Key Statistics
Key Takeaways
- Market growth: The global market reached USD 7,491.65 million in 2025 and is projected at USD 18,395.24 million in 2034, implying 10.5% compound growth. Semiconductor content rises as electrified vehicles adopt higher-voltage power conversion and conventional vehicles add more electronic loads.
- Leading type: Rectifiers account for an estimated ~46% of base-year revenue within the publisher’s functional type classification. Charging Systems semiconductor content is a faster-growing category at a modeled ~12.4% CAGR as onboard conversion and charging electronics become more sophisticated.
- Application mix: Automotive applications represent an estimated ~78% of 2025 sales. The publisher also includes Industrail and Others as application members; those labels refer to overlapping end uses of the same power-device families rather than to complete industrial equipment.
- Regional leadership: Asia-Pacific is the largest market with an estimated ~45% share in 2025, reflecting vehicle electronics and power semiconductor manufacturing across China, Japan and South Korea. North America contributes an estimated ~28% based partly on the historical US monetary reference.
- Device technology: Silicon MOSFETs and diodes remain important for cost-sensitive distribution and auxiliary functions, while silicon carbide MOSFETs and modules gain traction in higher-voltage electric drivetrains. Gallium nitride is an emerging option in selected compact power conversion applications.
- Commercial challenges: Automotive qualification, power-module thermal design, silicon carbide substrate cost and the need for multi-year supply continuity restrain adoption. Product-level customer design wins are stronger evidence of supplier relevance than total company revenue or broad EV unit sales.
Automotive Power Semiconductor Market Overview
Automotive power semiconductor market was valued at USD 7,491.65 million in 2025, is estimated at USD 8,277.99 million in 2026, and is forecast to reach USD 18,395.24 million by 2034, advancing at a 10.5% CAGR during 2025–2034. Asia-Pacific leads regional demand at an estimated ~45% of 2025 revenue, supported by its large vehicle production base and extensive automotive electronics supply chain.
Automotive power semiconductors switch, rectify, regulate or protect electrical power inside vehicle electronic systems. They range from silicon diodes and MOSFETs used in low-voltage distribution to insulated-gate bipolar transistors and silicon carbide devices that handle traction inverter power. A single vehicle can contain power switches in motor control, battery interfaces, onboard charging, DC/DC conversion, body electronics, braking, lighting and thermal management. Their commercial value is the semiconductor device or qualified module, not the full vehicle or the complete electrical subsystem.
The product boundary follows the functional mix in the publisher’s segmentation. Rectifiers and Voltage Suppressor devices represent semiconductor functions, while Charging Systems denotes the power semiconductor content supplied into onboard charging and related conversion circuits rather than a finished charger. The Application axis contains Automotive, Industrail and Others, so the modeled product family includes overlapping non-vehicle end uses where the same power devices are sold. Finished traction inverter assemblies, EV charging stations, complete battery packs, GPUs and general-purpose vehicle software are outside this revenue boundary.
The global monetary anchors are USD 6.78 billion for 2024 and USD 12.34 billion for 2030. They imply a six-year annualized rate of 10.4963%, consistent with the printed 10.5% after rounding. Extending the same trajectory produces USD 7,491.65 million in 2025 and USD 18,395.24 million by 2034. The forecast depends on both vehicle production and power-device value per vehicle; more EVs can increase the semiconductor opportunity even if total light-vehicle unit growth is modest.
Vehicle electrification changes the power architecture. A battery-electric drivetrain must convert DC battery energy into controlled AC motor power, manage regenerative energy and supply lower-voltage loads through DC/DC converters. Onboard chargers use additional switching and rectification stages, while high-voltage battery systems require protective and monitoring components. Silicon carbide can reduce losses at demanding voltage and switching conditions, although its value proposition depends on thermal design, manufacturing cost and the vehicle maker’s chosen architecture.
Global vehicle electrification provides a wider demand context for automotive switching and protection components, but vehicle registrations cannot be converted directly into semiconductor sales. Public supplier announcements reveal how SiC MOSFETs are being integrated into onboard conversion and electric drive systems, while platform architecture and actual manufacturing volumes determine the merchant device opportunity. Supplier partnerships also indicate the importance of system-level engineering in the automotive qualification cycle.
The competitive landscape is shaped by automotive-grade reliability and long design-in cycles. Infineon, STMicroelectronics, onsemi, Texas Instruments and Bosch provide direct device or module evidence, while NXP supplies broader vehicle electronics and acquired Freescale in 2015. A supplier listed in an automotive semiconductor company universe is not necessarily a direct merchant seller of high-voltage power switches; Intel, Nvidia and Trumpf have other roles that require careful separation from this narrow product market.
Segment Analysis: By Type
The publisher’s Type segmentation contains Rectifiers, Voltage Suppressor and Charging Systems. These are functional groupings rather than an exhaustive material-based list of silicon, SiC and GaN devices. Rectifiers lead at an estimated ~46% of 2025 revenue, followed by Charging Systems at ~35% and Voltage Suppressor at ~19%. Charging Systems power-device content has the fastest modeled growth at ~12.4% CAGR, reflecting rising onboard conversion complexity; the entire charger system is not counted.
| Publisher type | Principal semiconductor functions | Market positioning |
|---|---|---|
| Rectifiers | Rectifier diodes and associated power semiconductor functions convert alternating or transient electrical inputs into controlled DC supply paths. Automotive uses range from auxiliary converters and alternator-related circuitry to high-voltage charging stages, with device selection shaped by reverse recovery, conduction loss, voltage rating and thermal performance. A rectifier is a semiconductor function, so the category does not imply that every vehicle contains a discrete bridge of identical design. | Largest type at ~46% share in 2025, with modeled ~9.7% CAGR. Broad application across conventional and electrified vehicles supports volume, but price pressure remains significant for established silicon devices. Suppliers compete on low defect rates, compact packages and qualification over wide temperature ranges. Higher-efficiency devices can command premiums in demanding conversion stages, whereas commodity rectification faces persistent unit-price competition. |
| Voltage Suppressor | Transient voltage suppressors and related protection devices protect automotive electronic nodes from load dumps, electrostatic events and switching transients. As zonal architectures, battery interfaces and high-voltage converters proliferate, protection design becomes more distributed and application-specific. A component may be selected for pulse handling, clamping behavior, leakage and package reliability, with the exact qualification depending on whether the product is a discrete device or an integrated circuit. | Estimated ~19% of base-year revenue and ~8.5% modeled growth. The category benefits from the increasing number of sensitive power and control interfaces in modern vehicles, but its average device selling price is often lower than that of traction power modules. Purchasing emphasizes robust electrical ratings, failure-mode behavior and supply continuity. Suppliers that offer qualified protection families across multiple vehicle platforms can sustain repeat design wins. |
| Charging Systems | This functional class covers semiconductor switches, rectifiers and related power conversion devices supplied into onboard charging and vehicle-side battery conversion circuits. High-voltage architectures can use SiC MOSFETs, gate drivers and other power components to reduce losses and manage thermal constraints. Charging Systems is a publisher label for semiconductor content, not a count of finished charging stations, cables, complete onboard chargers or infrastructure projects. | Estimated ~35% share and fastest modeled ~12.4% CAGR. Electrification increases the need for efficient onboard power conversion and can raise semiconductor value per vehicle. Infineon’s Toyota bZ4X application provides direct evidence of SiC devices in onboard charging and DC/DC conversion. Customer acceptance still depends on system cost, reliability testing and the vehicle maker’s chosen battery voltage platform. |
Rectifiers: high-volume power conversion across vehicle platforms
Rectification remains necessary wherever a vehicle converts, conditions or routes electrical energy. Silicon devices continue to dominate many cost-sensitive positions because they combine established manufacturing with predictable reliability. In higher-voltage conversion stages, engineers evaluate losses and switching behavior against the total cost of the power circuit, including magnetics and cooling. The modeled ~46% share reflects the breadth of these functions, not a claim that rectifier revenue is independently audited across every automaker.
Design teams assess voltage margin, surge performance, package parasitics and heat dissipation before approving a replacement rectifier. A low-cost device may be unsuitable if it increases switching losses or creates electromagnetic interference in a tightly packaged converter. Suppliers that can deliver consistent automotive qualification and long product availability are favored, particularly where a platform must remain in production and service for many years after its original electrical design is frozen.
Voltage Suppressor: reliability protection for distributed electronics
Automotive electrical systems experience transient events from inductive loads, motor switching, battery connections and external interfaces. Suppression components protect downstream circuitry by limiting voltage excursions, with selection based on pulse energy, clamping voltage and response behavior. Electric vehicles add high-voltage domains, but low-voltage networks and body controllers still require protection. The modeled ~19% share recognizes a large installed function with relatively modest per-device pricing compared with traction power semiconductors.
Qualification depends on the actual electrical environment and the distinction between discrete protection devices and integrated circuits. AEC-Q101 is relevant to many discrete semiconductor components, while AEC-Q100 applies to integrated circuits; the standards are not interchangeable labels for all power products. Designers also consider package thermal behavior and long-term availability. A supplier can win protection positions through detailed application support rather than by offering the highest voltage rating alone.
Charging Systems: power devices within the vehicle conversion chain
Vehicle-side charging conversion uses semiconductor switches and rectifiers to manage energy transfer from the external supply to the battery and to downstream DC buses. Higher-voltage batteries can reduce current for a given power level but require devices and insulation systems matched to the operating envelope. Silicon carbide MOSFETs offer a potential efficiency advantage in selected stages, though thermal design, gate driving and electromagnetic compatibility remain essential. The modeled ~35% allocation refers to the semiconductor content of these circuits.
Vehicle-side converters increasingly integrate semiconductor switches with protective gate control and thermal management, so component selection involves more than an isolated efficiency comparison. A device supplier can gain multiple positions when its product family supports both charging and low-voltage conversion functions. Platform-specific qualification and converter design choices still determine actual shipments, making the modeled ~35% functional category distinct from a count of complete chargers or battery packs.
Segment Analysis: By Application
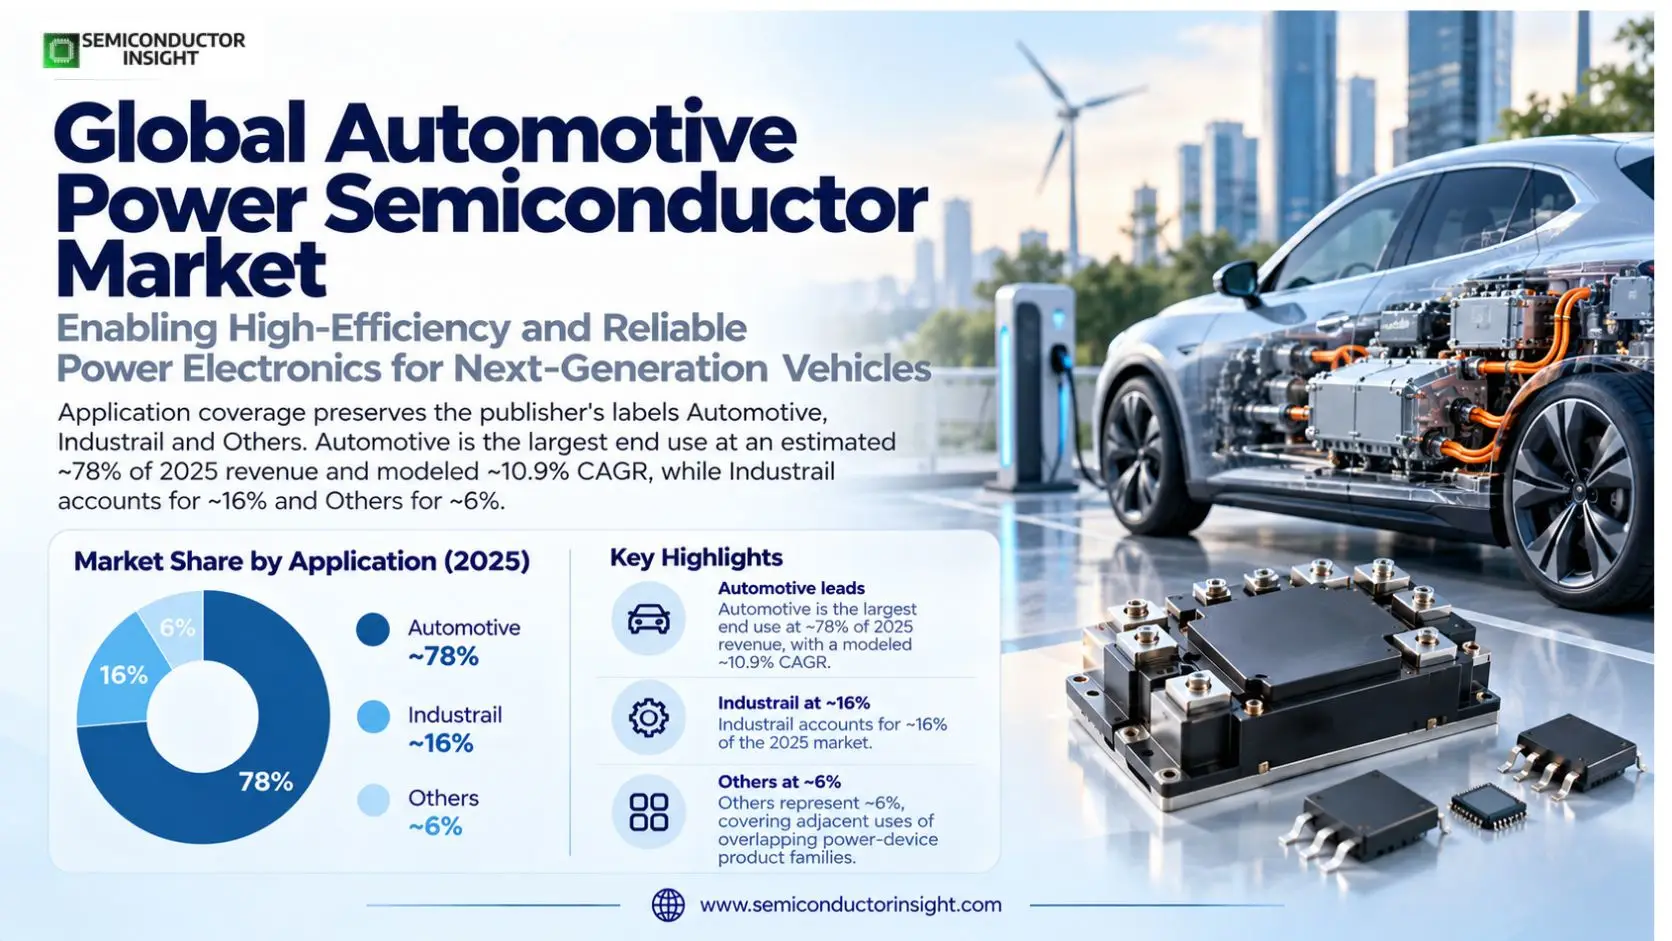
Application coverage preserves the publisher’s labels Automotive, Industrail and Others, including the spelling of Industrail. Automotive is the largest end use at an estimated ~78% of 2025 revenue and modeled ~10.9% CAGR, while Industrail accounts for ~16% and Others for ~6%. The latter two categories refer to adjacent uses of overlapping power-device product families, not to finished factories or infrastructure systems. This distinction prevents the automotive title from being broadened into all industrial electronics revenue.
| Application | Demand characteristics |
|---|---|
| Automotive | Dominant application at ~78% share and ~10.9% modeled CAGR. Traction inverters, battery conversion, onboard charging, electronic power steering, thermal management and distributed low-voltage loads require qualified semiconductor switches, rectifiers and protective devices. Electrification raises the average value of power electronics in many vehicles, while conventional powertrains still consume numerous silicon devices. Automakers impose extensive reliability and change-control requirements, making the commercial cycle longer than that of general-purpose industrial parts. |
| Industrail | Publisher label retained, with estimated ~16% share and ~8.7% modeled CAGR. This category represents industrial use of overlapping power semiconductor families, including drives, power supplies and energy conversion, rather than industrial machinery itself. The same supplier may qualify a silicon carbide switch for both automotive and industrial platforms, but specifications and purchasing channels differ. Industrial demand adds diversification without implying that a complete factory system is included in the automotive power-device market. |
| Others | Residual ~6% share and ~9.2% modeled CAGR. The group includes additional eligible end uses for the defined semiconductor device families where sales are not assigned to the automotive or Industrail categories. Examples can involve specialized power conversion and protection circuits, but the model does not count finished charging stations or unrelated electronic equipment. Its small share reflects the title’s automotive focus and the publisher’s broad but non-overlapping application classification. |
Application demand is affected by platform design decisions that are made well before vehicles reach dealerships. A power semiconductor may be selected during inverter or onboard charger development and then shipped across several model years after qualification. The same vehicle architecture can support multiple brands, allowing one device win to generate sustained production orders. However, model cancellations, changes in battery voltage or redesign of the thermal system can shift expected volumes without altering the overall direction of electrification.
Industrial applications follow different replacement and capital investment cycles from vehicle platforms. A power MOSFET or gate driver may be electrically similar across sectors but face different reliability, packaging and lifecycle requirements. For the modeled application split, revenue is assigned to the actual end use of the device sale, so a component shipped to an industrial inverter is not simultaneously counted as automotive demand. This preserves the publisher’s stated members while avoiding double counting across overlapping markets.
Regional Analysis
Asia-Pacific leads automotive power semiconductor demand with an estimated ~45% share in 2025 and modeled ~11.5% CAGR, followed by North America at ~28% and Europe at ~20%. South America contributes ~4%, while the Middle East and Africa account for ~3%. These regional allocations follow the destination of power semiconductor sales into vehicle and overlapping industrial electronics, not the location where every die is fabricated. The United States represented 26.25% of the publisher’s 2024 global anchor, supporting a substantial North American allocation.
How do vehicle electrification and semiconductor supply chains shape regional demand?
Regional patterns differ because the semiconductor content of a vehicle depends on powertrain mix, voltage architecture and local automotive production. China combines high electric-car penetration with a major vehicle manufacturing ecosystem, Europe is influenced by CO2 regulation and premium electrification, and North America mixes established light-vehicle demand with more uneven EV adoption. Emerging markets may increase EV sales quickly from small bases without immediately matching the power-device consumption of mature automotive production centers.
The International Energy Agency estimated more than 20 million electric cars sold worldwide in 2025 and forecast 23 million in 2026. That global vehicle count is not a regional semiconductor revenue table, so the share model also considers supplier design wins, powertrain production, module sourcing and the value of conversion electronics per vehicle. North America is calibrated to the publisher’s USD 1.78 billion US value in 2024, while remaining allocations are modeled from automotive electronics activity and end-use geography.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~45%) | Fastest (~11.5% CAGR) | Chinese EV production and Asian electronics | Automotive quality, SiC scaling and Tier 1 integration |
| North America | Second (~28%) | Moderate (~9.2% CAGR) | US vehicle electronics and supplier design-ins | Multi-year qualification and vehicle-platform stability |
| Europe | Third (~20%) | Steady (~10.0% CAGR) | EV inverter and premium vehicle programs | Efficiency, functional safety and qualified module supply |
| South America | Smaller (~4%) | Expanding (~10.3% CAGR) | Vehicle assembly and imported electronics | Localized platform cost and powertrain mix |
| Middle East & Africa | Emerging (~3%) | Developing (~10.6% CAGR) | Imported vehicles and selected manufacturing | Thermal durability, price and distribution access |
Automotive Power Semiconductor Manufacturers and Competitive Landscape
Automotive power semiconductor competition spans integrated device manufacturers, discrete device specialists and suppliers of gate-drive and protection circuits. Infineon, STMicroelectronics, onsemi, Texas Instruments and Bosch have documented automotive power-device technologies, while NXP contributes related automotive electronics and historical Freescale assets. Market positioning depends on actual qualified product sales rather than a company’s aggregate semiconductor revenue or its role in a finished vehicle electronics system.
Infineon participates in silicon and silicon carbide power devices and modules, with a 2026 announcement describing a 1300 V HybridPACK Drive SiC module rated for continuous operation at 205 degrees Celsius. The company also identified Toyota bZ4X applications for CoolSiC MOSFETs in onboard charging and DC/DC conversion. These examples establish direct product relevance but do not reveal the company’s exact share of the modeled global market, which includes lower-voltage rectifiers and protection functions as well.
STMicroelectronics markets STPOWER silicon carbide devices and has disclosed power module collaborations with automotive partners. Its fourth-generation SiC technology targets traction inverter voltage classes and improved device density, while long-term supply arrangements with European vehicle suppliers demonstrate the importance of predictable manufacturing capacity. onsemi offers EliteSiC power technologies and works with Geely on integrated electric drive platforms. The suppliers compete on device losses, packaging reliability, engineering support and production continuity.
Texas Instruments provides automotive-qualified gate drivers and other power management components that enable safe operation of high-voltage switches, while Bosch develops SiC MOSFET technology for electric drivetrains. NXP has a broader vehicle electronics portfolio and absorbed Freescale in December 2015, so Freescale should not be counted as an independent current competitor. Supplier comparisons need to distinguish a discrete MOSFET, an isolated gate driver, a power module and a complete inverter, which have different revenue boundaries.
Several names included in the publisher’s company universe do not automatically qualify as merchant automotive power semiconductor vendors. Nvidia and Intel have prominent computing and automotive ecosystem roles, but their broad processor businesses are not direct evidence of rectifier or traction power-device revenue. Trumpf is associated with industrial laser and manufacturing technologies rather than a clearly documented merchant automotive power-device portfolio. Such companies can be described as adjacent ecosystem participants without assigning unsupported market shares.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Core power-device suppliers | Infineon Technologies, STMicroelectronics, onsemi, Bosch | Direct automotive SiC and silicon power-device evidence, high-voltage traction or conversion applications, and long qualification cycles with vehicle makers. Competition centers on efficiency, reliability, packaging and sustained production at automotive volumes. |
| Power control and integration | Texas Instruments, NXP Semiconductors | Automotive-qualified gate drivers, protection and broader power-management electronics contribute to the functional device mix. Device content must be separated from finished ECUs, processors and complete power conversion assemblies when evaluating revenue. |
| Historical or adjacent names | Freescale Semiconductor, Nvidia, Intel, Trumpf | Freescale became part of NXP in 2015; the other names participate in related computing, industrial or manufacturing ecosystems. Their presence in an historical supplier list does not establish independent current sales of automotive rectifiers or SiC power devices. |
Key companies profiled
- Infineon Technologies
- STMicroelectronics
- onsemi
- Texas Instruments
- Robert Bosch GmbH
- NXP Semiconductors
- Freescale Semiconductor (historical, now NXP)
- Nvidia Corporation (adjacent)
- Intel Corporation (adjacent)
- Trumpf GmbH (adjacent)
Automotive Power Semiconductor Manufacturing and Capacity Analysis
Automotive power device production requires semiconductor wafer fabrication, device testing, assembly, thermal packaging and qualification under vehicle-specific reliability requirements. Silicon MOSFETs and diodes use mature manufacturing infrastructure, while silicon carbide devices require more specialized substrates, epitaxy and processing. Manufacturing geography spans Europe, Asia and North America, and supplier capacity cannot be inferred solely from the number of electric vehicles sold in a particular country.
Silicon carbide manufacturing economics depend on substrate diameter, defect control, device yield and the ability to scale qualified process flows. Infineon disclosed a 2026 supply agreement supporting its move to 200mm SiC production, with the aim of increasing manufacturing flexibility and reducing per-device cost. Larger wafers can improve die output, but automotive customers still require stable electrical characteristics and traceability. Substrate purchases and device sales occupy different positions in the value chain and must not be counted twice.
Automotive power module production adds interconnect, substrate, cooling and encapsulation requirements beyond wafer fabrication. Infineon’s 1300 V module announcement described operation at temperatures above conventional design benchmarks, illustrating the importance of package engineering as well as semiconductor die performance. A device that switches efficiently in laboratory conditions may still need extensive thermal cycling and fault testing before it can be designed into a traction inverter. These tests extend the commercial ramp of new device generations.
STMicroelectronics has described a vertically integrated silicon carbide strategy, including European and Asian manufacturing activities, while onsemi invests in system-level pairing of SiC switches and gate drivers. Suppliers also rely on contract manufacturing, materials partners and automotive Tier 1 integrators for different portions of the supply chain. A power semiconductor design win can support multiple vehicle model years, but capacity planning must account for yield, packaging throughput and customer-specific qualification rather than simple wafer starts.
The production mix is changing as automakers consider 400V and 800V battery architectures, higher-efficiency traction stages and compact onboard conversion. These shifts can increase demand for SiC in selected high-voltage positions while established silicon remains competitive for many auxiliary loads. Manufacturers therefore need portfolios spanning device ratings and packaging formats instead of assuming a single technology will replace all others. Price pressure can intensify when EV platforms consolidate suppliers or delay new model launches.
Automotive Power Semiconductor Market Dynamics: Drivers, Restraints and Opportunities
The market is driven by electric drivetrain penetration, rising semiconductor content per vehicle, higher-voltage conversion architectures, auxiliary electronic loads and supplier innovation in SiC devices. Offsetting forces include substrate and packaging costs, long automotive qualification programs, thermal reliability requirements and uncertain vehicle production schedules. The impact allocations express the modeled headline CAGR across the forecast window, with adjacent electric-car sales used as context rather than as direct semiconductor revenue.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2025–2027 | 2028–2030 | 2031–2034 |
|---|---|---|---|---|---|
| EV and hybrid drivetrain semiconductor demand | High | +4.40% | High | High | High |
| 800V conversion and SiC penetration | High | +3.30% | Medium | High | High |
| Growing onboard power electronics content | Medium-High | +2.60% | High | High | Medium |
| Automotive safety and power protection requirements | Medium | +2.00% | Medium | High | High |
| Power module integration and packaging innovation | Low-Medium | +1.60% | Medium | Medium | High |
| Others (auxiliary electrification, regional EV programs, industrial crossover) | Low | +1.10% | Low | Medium | Medium |
Electric and hybrid vehicle production expands device opportunities
Battery-electric and hybrid powertrains require switching and conversion functions beyond those used in conventional internal-combustion vehicles. The IEA reported global electric-car sales above 20 million in 2025 and projected 23 million in 2026, indicating a larger potential installed base of traction and charging electronics. The semiconductor effect depends on each model’s architecture and supplier design choices, but the shift supports sustained demand for qualified high-voltage power devices.
Higher battery voltage favors efficient wide-bandgap switches
Vehicle platforms designed around higher DC bus voltages can use silicon carbide MOSFETs to reduce losses and manage current in traction and charging conversion. Infineon’s 1300 V automotive SiC module shows how suppliers are extending operating envelopes, while STMicroelectronics has targeted 750V and 1200V device classes. A material advantage becomes commercially relevant only when the full inverter or converter delivers better efficiency, size or cost under real driving and thermal conditions.
More electronic loads raise semiconductor content per vehicle
Even vehicles without full electric traction contain power switches, rectifiers and transient protection components for body systems, lighting, steering, braking, climate control and electronic control units. New architectures may distribute power through zonal controllers and more sophisticated low-voltage networks. This broadens the device opportunity beyond the high-profile traction inverter. Suppliers with automotive-qualified portfolios can win multiple small positions whose combined value is meaningful across high-volume vehicle platforms.
Reliability requirements create demand for specialized protection
Vehicle electrical environments involve temperature variation, vibration, load transients and demanding fault conditions. Designers use voltage suppression, isolated gate drivers and protection functions to maintain safe operation when switches encounter overcurrent or abnormal voltage. Texas Instruments documents devices with desaturation detection and controlled turn-off for SiC and IGBT applications. Increasing power density can raise the importance of such functions, although safety-related features must be evaluated at the system level rather than assumed from a component label.
Module innovation improves efficiency and packaging density
Advances in substrate technology, thermal interfaces, interconnects and switch control can reduce the size or energy loss of automotive power electronics. onsemi’s 2026 embedded power platform and device-pairing tools illustrate investment in integrating semiconductor functions with packaging and system design. Customers evaluate whether these improvements lower total converter cost and support manufacturing reliability. The opportunity is not confined to the newest die process because packaging and gate control can improve established device families.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2025–2027 | 2028–2030 | 2031–2034 |
|---|---|---|---|---|---|
| SiC substrates and high-temperature packaging costs | High | -1.60% | High | Medium | Medium |
| Long vehicle qualification and design-in cycles | Medium-High | -1.30% | High | High | Medium |
| Thermal, fault and lifetime reliability requirements | Medium | -0.90% | Medium | High | High |
| Others (vehicle production volatility and pricing pressure) | Low | -0.70% | Medium | High | Medium |
Wide-bandgap manufacturing remains cost sensitive
Silicon carbide devices require specialized substrates and processing that can cost more than established silicon technologies, particularly when yields are still improving. Packaging for high-voltage traction applications adds thermal and insulation requirements, and the economic advantage must be evaluated at the full converter level. Vehicle makers may retain silicon devices where their performance is sufficient. This creates a selective adoption path rather than a uniform replacement of all automotive power semiconductor functions.
Automotive approval extends the time from design to revenue
A power semiconductor selected for a vehicle platform must satisfy electrical performance, reliability, production traceability and customer-specific change control. AEC-Q100 applies to many integrated circuits, while AEC-Q101 is relevant to discrete semiconductor components, so qualification cannot be reduced to one generic label. Once approved, the device may ship for years, but winning the initial position can require substantial engineering and testing before revenue scales with vehicle production.
Thermal and fault management add system complexity
High-power switching devices face losses, temperature gradients, electromagnetic interference and transient faults that can compromise vehicle reliability. Engineers must coordinate semiconductor selection with cooling, gate drive, protection and package design. A more efficient SiC switch may still be unattractive if its integration requires expensive supporting hardware or fails robustness targets. Suppliers therefore compete on validated system performance and field reliability, not solely on headline switching efficiency or voltage rating.
MARKET OPPORTUNITIES
Higher-voltage onboard charging and DC/DC conversion
Automakers are refining charging architectures to reduce energy loss and component volume while meeting safety requirements. The Toyota bZ4X use of CoolSiC MOSFETs in onboard charging and DC/DC conversion demonstrates an application beyond the traction inverter. Suppliers that offer matched switches, drivers and protection components can compete for multiple positions within a vehicle power network. The value opportunity depends on qualified semiconductor content, not the retail price of the complete charger.
Mid-market EV platforms seeking lower system cost
As electric vehicles expand beyond premium models, manufacturers seek converter designs that improve efficiency without excessive bill-of-materials cost. Smaller SiC die, optimized packages and simpler gate-driving solutions can help when their benefits are verified at system level. STMicroelectronics has described device improvements intended to make SiC attractive in mid-size and compact vehicles. A supplier that reduces total inverter cost may win more volume than one that optimizes a single laboratory parameter.
Vehicle electronics protection and zonal distribution
The move toward distributed vehicle electronics creates demand for compact protection, switching and monitoring functions throughout the electrical architecture. Transient suppressors, low-voltage MOSFETs and power management ICs can benefit even when the traction powertrain remains conventional. Suppliers with broad automotive-grade portfolios may gain multiple design wins per platform, while specialized providers can focus on difficult thermal or fault conditions. These opportunities diversify the market beyond a single SiC growth narrative.
Cross-sector technology transfer with controlled attribution
Power semiconductor suppliers can adapt manufacturing and packaging advances from industrial drives and energy conversion to automotive programs, subject to different qualification requirements. The publisher’s Industrail category recognizes overlapping product families, but a device sale should be assigned to its actual end use. Companies that reuse core technology while customizing reliability and package specifications can improve development economics. Revenue must remain separated from finished industrial systems and complete vehicle subsystems.
Automotive Power Semiconductor Supply Chain Analysis
The supply chain runs from silicon and silicon carbide substrates through wafer fabrication, device testing, packaging, module integration and vehicle-platform qualification. Tier 1 suppliers and automakers determine the electrical and thermal requirements that shape semiconductor demand, while materials and manufacturing partners influence cost and delivery resilience. The final market measures eligible semiconductor devices and modules, not the cumulative value of every upstream input and downstream converter assembly.
Upstream. Silicon and silicon carbide materials determine the starting economics of power device production, with SiC substrates requiring specialized crystal growth and processing. Infineon’s 2026 agreement for 200mm SiC wafer supply reflects the importance of larger substrate formats and secure sourcing. Materials availability affects device cost and production planning, but substrate revenue is an upstream input rather than a second sale of the finished automotive power semiconductor. Traceability and consistent defect levels are especially important for qualified vehicle components.
Manufacturing. Semiconductor factories create the electrical device structures, while downstream assembly determines how heat and current move through the package. Automotive testing screens electrical behavior across operating conditions and verifies compliance with product-specific qualification requirements. For high-voltage modules, thermal cycling and interconnect reliability are central to field performance. Manufacturing capacity must be evaluated at the level of usable, qualified devices, because wafer throughput alone does not guarantee finished module output.
Distribution. Many power semiconductors reach vehicle makers through Tier 1 suppliers that design inverters, onboard chargers, electronic control units and power distribution modules. A component maker can win a long-lived platform position through joint engineering and qualification before series production starts. Direct automotive supply agreements and authorized distribution provide additional channels. Customers expect change-control discipline and reliable multi-year availability, which can limit rapid supplier substitution even when nominally similar parts are available.
Downstream. Vehicle electrical architecture determines how many switching, rectification and protection functions are needed and what voltage and current ratings they must meet. Electric traction increases demand for high-power devices, while body and auxiliary systems sustain numerous smaller silicon components. Production schedules and platform launches influence semiconductor shipments, but the value of a complete vehicle is outside the market. Industrial crossover demand is counted separately under the publisher’s non-automotive application members.
Recent Developments in the Automotive Power Semiconductor Market
- 16 September 2026 Introduced
onsemi introduced an Embedded Power Platform that uses the silicon wafer as a packaging foundation and targets integrated power delivery across automotive, industrial and data-center applications. The company described potential power density improvements of three to five times compared with current approaches. The announcement demonstrates supplier investment in packaging and integration, but it does not disclose automotive shipments or justify assigning the entire platform revenue to vehicle power semiconductors. Source - 8 June 2026 Launched
onsemi launched Elite Pairing Studio, a design environment for matching SiC MOSFETs and gate drivers in demanding power electronics, including electric vehicles and industrial systems. The tool helps engineers examine device interactions and switching trade-offs before final hardware evaluation. It is evidence of system-design support around power semiconductors rather than a standalone semiconductor shipment or a measure of automotive market share. Source - 29 May 2026 Introduced
Infineon announced a 1300 V HybridPACK Drive silicon carbide power module designed for continuous operation at 205 degrees Celsius, above the 175-degree benchmark cited for existing designs. The higher thermal operating envelope can support greater output or simpler system cooling when vehicle engineers validate the complete inverter. This development is directly relevant to high-voltage automotive power modules but does not describe global market revenue or a supplier-wide sales share. Source - 20 May 2026 Published
The International Energy Agency reported more than 20 million electric cars sold worldwide in 2025 and projected 23 million sales in 2026, with EVs approaching 30% of global new-car sales. The data establishes a downstream demand context for traction and onboard conversion semiconductors. It should not be interpreted as a direct measurement of device revenue, since semiconductor content varies substantially by model, battery architecture and supplier design. Source - 28 April 2026 Expanded
onsemi and Geely Auto Group announced an expanded collaboration involving EliteSiC technologies in next-generation electric and hybrid vehicle power systems. The companies described system-level integration aimed at improving power density, efficiency and charging performance. The agreement demonstrates direct engagement between a semiconductor supplier and an automaker, while actual device sales depend on platform production and commercial deliveries. The broader Geely vehicle revenue is not part of the power semiconductor market. Source - 9 February 2026 Selected
Infineon reported that its CoolSiC MOSFETs were adopted in Toyota’s new bZ4X for the onboard charger and DC/DC converter. The design win demonstrates that SiC devices can support more than the traction inverter, helping manage efficiency and power conversion in the vehicle electrical system. The announcement provides product-level evidence but does not specify global market value, total semiconductor content per vehicle or an independently verified supplier share. Source - 24 September 2024 Unveiled
STMicroelectronics introduced its fourth-generation STPOWER silicon carbide MOSFET technology, targeting 750 V and 1200 V classes for traction inverters and related conversion applications. The company highlighted smaller die sizes and improved efficiency as ways to extend SiC adoption beyond premium electric cars. The product announcement provides a technology baseline for the forecast, although volume qualification and customer program timing determine when the devices contribute to merchant semiconductor revenue. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2020–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2025–2034 |
| Historical Period | 2020–2024 |
| Market Size 2025 | USD 7,491.65 million |
| Market Size 2026 | USD 8,277.99 million |
| Market Size 2034 | USD 18,395.24 million |
| Growth Rate | CAGR of 10.5% during 2025–2034 |
| Unit | Value in USD million |
| Segmentation | By Type, By Application, and By Region |
| By Type | Rectifiers · Voltage Suppressor · Charging Systems |
| By Application | Automotive · Industrail · Others |
| By Region | Regional review covers vehicle electronics, supplier design-ins and eligible semiconductor demand North AmericaUnited States, Canada, Mexico EuropeGermany, UK, France, Italy, Russia, Rest of Europe Asia-PacificChina, Japan, South Korea, India, Southeast Asia, Rest of Asia-Pacific South AmericaBrazil, Argentina, Colombia, Rest of South America Middle East & AfricaSaudi Arabia, UAE, Egypt, Nigeria, South Africa, Rest of Middle East & Africa |
| Key Companies Profiled | Infineon Technologies, STMicroelectronics, NXP Semiconductors, Texas Instruments, Robert Bosch GmbH, onsemi, Freescale Semiconductor (historical NXP), Nvidia Corporation (adjacent), Intel Corporation (adjacent), Trumpf GmbH (adjacent) |
| Customization Scope | Customization may cover device voltage classes, SiC versus silicon adoption, OEM powertrain architectures, country-level supplier relationships and the value of semiconductor content within vehicle charging and traction systems. |
Frequently Asked Questions
How large is the automotive power semiconductor market in 2025?
The market exceeded USD 7.49 billion in 2025, based on a publisher monetary series that starts at USD 6.78 billion in 2024 and reaches USD 12.34 billion in 2030. Eligible revenue covers automotive-oriented power devices, qualified modules and the related functional categories in the publisher’s segmentation. Finished electric vehicles, traction inverter assemblies and public charging stations are excluded from the semiconductor revenue total.
What market value is projected for 2034?
The global forecast exceeds USD 18.39 billion in 2034, representing the headline annualized growth over 2025–2034. This rate reconciles with the publisher’s two headline monetary anchors after rounding, rather than being inferred from total vehicle sales. Demand growth is associated with electrified drivetrains, higher-value onboard power conversion and electronic power management, with automotive qualification and cost pressures moderating adoption.
Which Type category is the largest?
Rectifiers are the largest functional type with an estimated ~46% share in 2025, supported by widespread power conversion and distribution applications. Voltage Suppressor devices protect circuits against electrical transients, while Charging Systems represents semiconductor content within vehicle charging and related conversion. These publisher categories are functional groupings, so they should not be confused with separate material classifications such as silicon, SiC and GaN.
Which Application category dominates demand?
Automotive is the leading application with an estimated ~78% of base-year revenue, followed by the publisher’s Industrail and Others categories. The label Industrail is retained as supplied in the source segmentation, referring to industrial uses of overlapping power semiconductor families. The application allocation follows the customer use of a semiconductor shipment, so overlapping product catalogues do not create a second sale when a device is designed into an industrial converter.
Which region is the largest automotive power semiconductor market?
Asia-Pacific leads at an estimated ~45% share in 2025 and a modeled ~11.5% CAGR, reflecting China’s electric vehicle production and the broader Japanese and Korean automotive electronics ecosystem. North America accounts for an estimated ~28%, supported by the publisher’s USD 1.78 billion United States figure in 2024. Europe follows with a substantial base of electrified powertrain design and manufacturing programs.
How do silicon carbide devices improve electric vehicle powertrains?
SiC MOSFETs can reduce conversion losses and support efficient switching at demanding voltages, allowing vehicle engineers to optimize traction inverters and onboard converters. The actual benefit depends on package temperature, gate-drive design, cooling and total system cost. Infineon’s 1300 V automotive module and STMicroelectronics’ 750 V and 1200 V device technology illustrate supplier investment, but SiC does not replace every low-voltage silicon component.
What are the main growth drivers?
Growth comes from increased electric and hybrid vehicle production, greater power-device content per vehicle, higher-voltage battery architectures and more sophisticated onboard charging and auxiliary electronics. The IEA’s 2026 outlook provides downstream evidence of EV adoption, while company design wins show specific semiconductor applications. Demand should be evaluated by the eligible device content of vehicles, not by multiplying total vehicle sales value by a broad semiconductor percentage.
What restrains adoption of advanced automotive power devices?
Silicon carbide substrates and high-temperature packaging can be costly, and automotive programs require extensive reliability and change-control work before new devices enter series production. Thermal management, fault protection and electromagnetic compatibility add system design complexity. Vehicle production volatility and price competition can also affect shipments. Suppliers must demonstrate measurable converter-level benefits and maintain consistent manufacturing output over multi-year vehicle platform lifecycles.
Which manufacturers are most relevant to the market?
Infineon, STMicroelectronics, onsemi, Texas Instruments and Bosch have documented power-device, module or gate-drive technologies relevant to automotive applications. NXP participates in automotive electronics and completed its merger with Freescale in December 2015, so Freescale is not an independent current supplier. Other publisher-listed names such as Nvidia, Intel and Trumpf have adjacent roles that should not be equated with verified merchant automotive power-device sales.
What does the study include and exclude?
The study tracks Rectifiers, Voltage Suppressor and Charging Systems semiconductor content across Automotive, Industrail and Others applications, with regional coverage of North America, Europe, Asia-Pacific, South America and the Middle East and Africa. The base year is 2025 and the forecast extends through 2034. It includes qualified power semiconductor devices and modules but excludes full vehicles, complete inverters, charging stations, unrelated processors and upstream materials sold separately.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF