Key Statistics
Key Takeaways
- Market size: The market is valued at USD 2.05 billion in 2025 and is projected to reach USD 4.33 billion by 2034, representing a 8.6% CAGR during 2026–2034.
- 6-inch epiwafers lead commercial demand, providing better manufacturing economics for RF, VCSEL and photonic applications than smaller legacy diameters.
- Optoelectronic devices are the largest application as VCSELs, laser diodes, sensing and optical interconnects increase compound-semiconductor wafer demand.
- Asia Pacific leads the market through Taiwan, China, Japan and South Korea, while North America and Europe remain important for high-value telecom, defense and photonics applications.
- AI data-center optics is creating a new growth vector, with 6-inch GaAs quantum-dot laser epitaxy moving toward customer sampling in 2026.
GaAs Epiwafer Market Overview
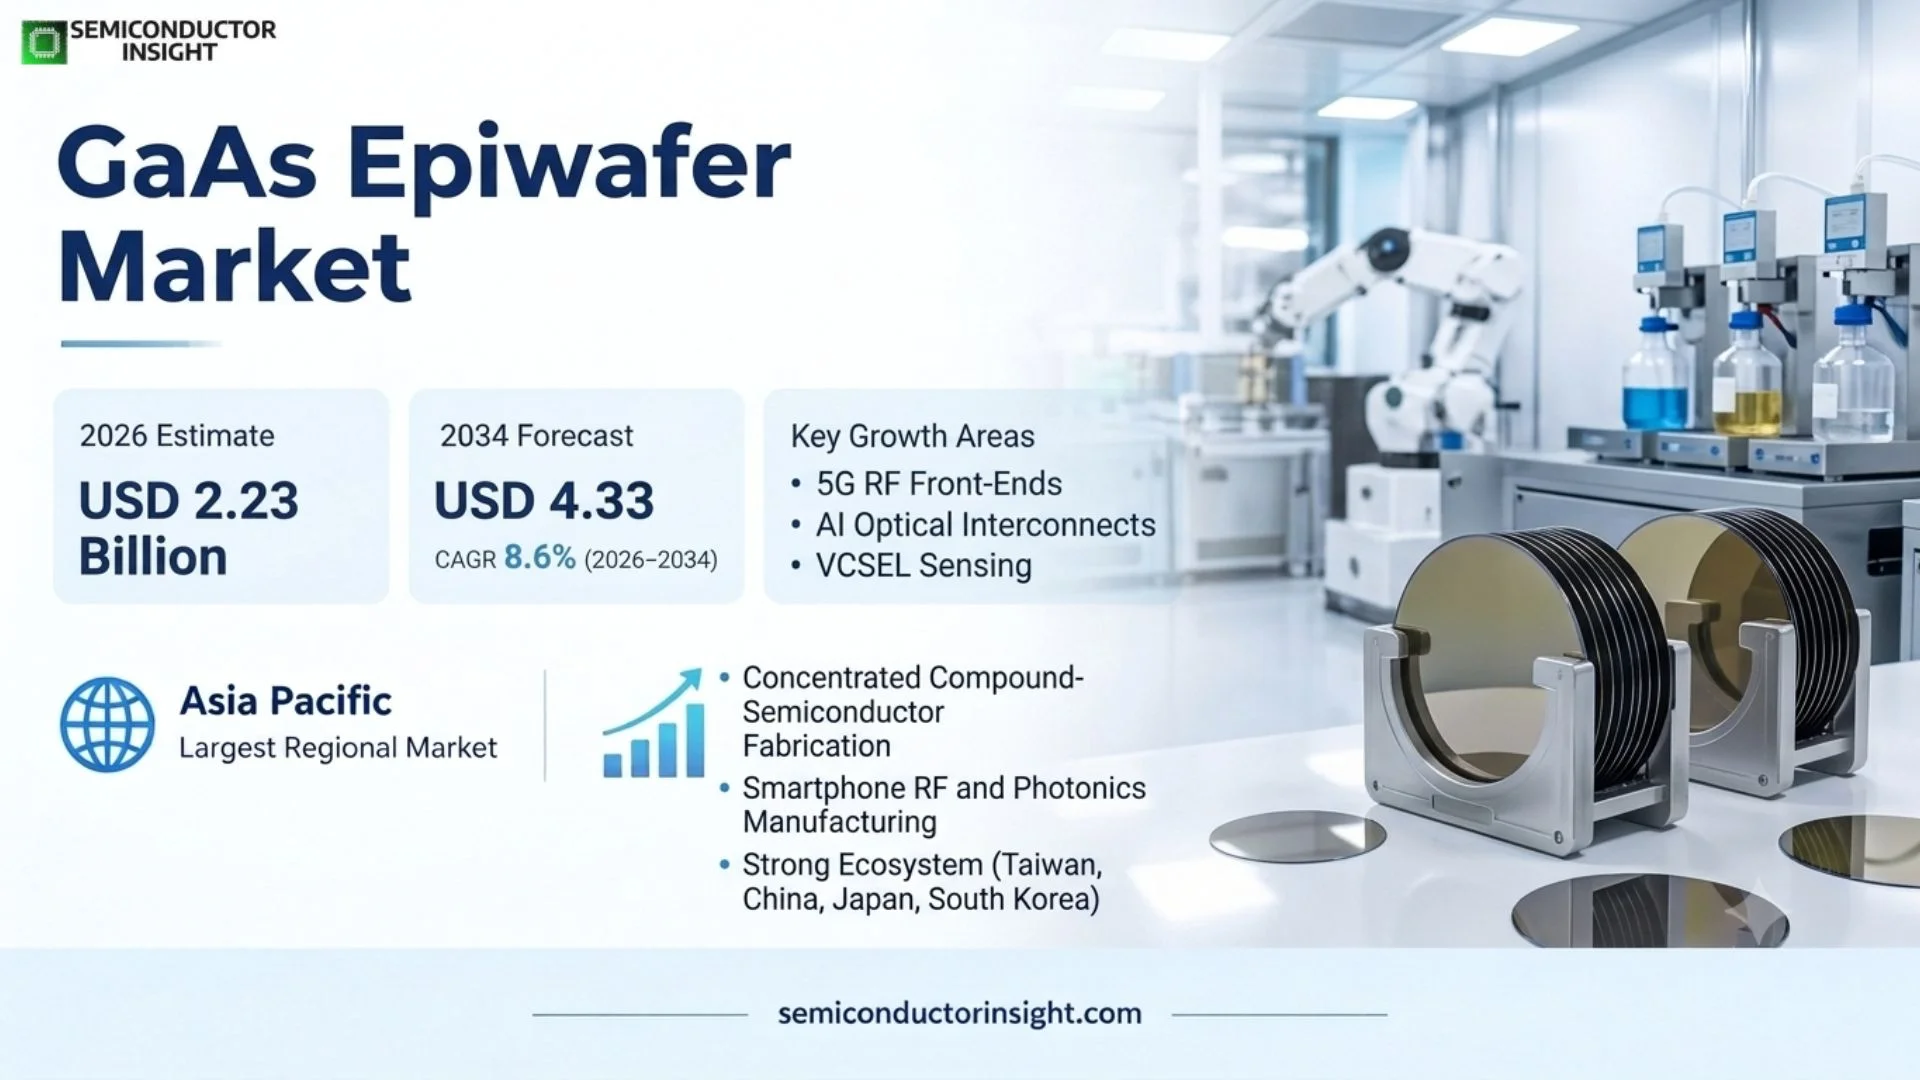
GaAs Epiwafer Market is valued at USD 2.05 billion in 2025 and is projected to reach USD 4.33 billion by 2034, expanding at a 8.6% CAGR during 2026–2034. The 2026 market level is USD 2.23 billion. Asia Pacific is the largest and fastest-growing regional market because compound-semiconductor fabrication, smartphone RF, optoelectronics and photonics manufacturing are concentrated across Taiwan, China, Japan and South Korea. Growth is being reinforced by 5G, VCSEL sensing and AI optical interconnects.
GaAs epiwafers are gallium-arsenide substrates with precisely engineered epitaxial layers used to fabricate RF power amplifiers, VCSELs, laser diodes, photodetectors and other compound-semiconductor devices. Commercial performance depends on substrate quality, epitaxial thickness, doping, interface control, defect density and within-wafer uniformity. The value chain is process-intensive because a wafer can contain many layers whose composition and thickness directly determine device frequency, optical wavelength and yield.
Six-inch substrates have become the preferred production format for many high-volume applications because they increase die output and fit more automated wafer-processing infrastructure than 4-inch wafers. MOCVD is widely used for high-volume VCSEL, laser and RF production, while MBE remains important for structures requiring exceptional interface and composition control. Larger diameters improve economics only when epitaxial uniformity and downstream device yield remain stable.
AI data-center connectivity is adding a new demand pathway alongside established smartphone RF and 3D sensing. IQE announced in September 2026 that it would supply 6-inch GaAs quantum-dot laser epitaxy to Quintessent for customer sampling, linking GaAs epiwafers directly to lower-power optical interconnects for AI infrastructure. The development broadens the market beyond mature handset and telecom demand.
Segment Analysis: By Type
By type, the market is segmented into 4-inch, 6-inch and other wafer diameters. Six-inch is the leading commercial segment because it supports higher-volume manufacturing and better cost per device for RF and optoelectronics. Four-inch remains important in legacy and specialty lines, while other diameters serve research, niche production and emerging process platforms.
| Type | Commercial role |
|---|---|
| 4 Inches | Established diameter for specialty RF, photonics and legacy production lines. |
| 6 Inches | Leading high-volume format for RF, VCSEL, laser and advanced photonics manufacturing. |
| Other | Research, pilot and application-specific diameters outside the principal 4-inch and 6-inch production formats. |
Additional Segmentation: By End User
End-user demand spans telecommunications, automotive, aerospace and defense, consumer electronics and healthcare. Telecom is a core market because GaAs remains important in RF front ends and optical communications. Consumer devices use GaAs in RF power amplifiers and 3D sensing, while automotive, defense and healthcare applications value high-frequency, optical and sensing performance that is difficult to reproduce with silicon alone.
| End User | Demand characteristics |
|---|---|
| Telecommunications | 5G RF, optical networking and high-speed laser applications. |
| Automotive | LiDAR, sensing, radar-adjacent optoelectronics and communications. |
| Aerospace & Defense | High-frequency RF, satellite communications and specialized photonics. |
| Consumer Electronics | Smartphone RF, VCSEL sensing and AR/VR optical functions. |
| Healthcare | Laser, imaging and sensing systems requiring compound-semiconductor emitters or detectors. |
Segment Analysis: By Application
By application, the market is divided into microelectronic and optoelectronic devices. Microelectronics includes RF power amplifiers, switches and high-frequency devices, while optoelectronics includes VCSELs, edge-emitting lasers and photodetectors. Optoelectronics is the larger growth opportunity because sensing, data-center optics and laser applications are increasing both wafer value and epitaxial complexity. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
| Application | Demand characteristics |
|---|---|
| Microelectronic Devices | RF power amplifiers, switches and high-frequency electronics for telecom, aerospace and wireless systems. |
| Optoelectronic Devices | VCSELs, laser diodes, photodetectors and optical components for sensing, datacom and industrial applications. |
Additional Segmentation: By Epitaxy Method
MOCVD and MBE are the principal epitaxial growth methods. MOCVD offers high throughput and strong suitability for volume production, while MBE provides exceptional layer and interface control for advanced RF, quantum and photonic structures. Supplier capability is often tied to specific reactor fleets, process recipes and customer-qualified material structures, which makes process transfer between vendors difficult.
| Epitaxy Method | Commercial relevance |
|---|---|
| MOCVD | High-volume growth for VCSELs, lasers, RF and mainstream compound-semiconductor production. |
| MBE | High-precision growth for specialized RF, quantum and advanced photonic structures. |
Regional Analysis
Asia Pacific leads the GaAs epiwafer market because Taiwan, China, Japan and South Korea combine device fabs, smartphone supply chains, photonics manufacturing and established substrate expertise. North America remains important in defense, telecom and AI optical interconnects, while Europe has strong automotive, sensing and compound-semiconductor R&D. Other regions remain smaller and import-dependent.
Why does regional demand differ across the GaAs Epiwafer market?
Regional demand follows compound-semiconductor device manufacturing rather than final electronics sales. Asia benefits from concentrated wafer and module production, North America provides high-value datacom, defense and research demand, and Europe contributes automotive and industrial photonics. As AI optical interconnects scale, regions with integrated epitaxy, wafer fabrication and packaging ecosystems will be best positioned to capture value.
| Region | Position | Demand profile | Key commercial factor |
|---|---|---|---|
| Asia Pacific | Largest / fastest growth | RF, VCSEL, photonics | Manufacturing scale and device ecosystem |
| North America | High-value | Defense, telecom, AI optics | Advanced design and qualification |
| Europe | Strategic | Automotive, industrial photonics | Specialty reliability and R&D |
| South America | Emerging | Telecom, limited photonics | Imported supply |
| Middle East & Africa | Emerging | Telecom, R&D | Project-led demand |
Competitive Landscape
IQE, Coherent, Sumitomo Chemical, IntelliEPI, VPEC, SCIOCS, LandMark Optoelectronics and Changelight form the principal competitive group. Suppliers differentiate through MOCVD or MBE process know-how, wafer diameter, defect density, application-specific layer design and the ability to scale from development wafers into qualified production. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Competition is moderately consolidated because epiwafer quality directly affects downstream device yield. IQE has strong positions in RF, sensing and photonics, while Coherent and Sumitomo Chemical benefit from broader materials and optoelectronics portfolios. Asian specialists compete through proximity to device manufacturers and faster customization. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
AI optical interconnects could reshape the market by adding a new high-growth photonics application. Quantum-dot lasers promise lower power and better temperature stability for data-center links, but commercial success depends on consistent 6-inch epitaxy and customer qualification. Suppliers with foundry-ready processes can capture this opportunity without waiting for entirely new substrate standards.
| Competitive tier | Representative companies | Primary differentiation |
|---|---|---|
| Global epitaxy leaders | IQE, Coherent, Sumitomo Chemical | Large-scale compound-semiconductor epitaxy and broad customer qualification. |
| Asian specialists | VPEC, IntelliEPI, SCIOCS | Regional proximity, customized epi structures and high-volume manufacturing. |
| Focused photonics suppliers | LandMark Optoelectronics, Changelight | Laser, sensing and application-specific photonic epiwafer capability. |
Key companies profiled
IQE plc, Coherent, Sumitomo Chemical, IntelliEPI, VPEC, SCIOCS, LandMark Optoelectronics and Changelight are included in the competitive scope. Their positions vary by wafer diameter, epitaxy method, RF versus photonic exposure and customer qualification history, so market share should be interpreted by application rather than as a single uniform GaAs product category.
Production Capacity Analysis
GaAs epiwafer capacity depends on substrate availability, reactor fleet, epitaxial recipe time, chamber matching, wafer handling and metrology. Six-inch capacity is strategically important because it improves device output per wafer, but maintaining uniform thickness and composition across the larger area requires mature process control. Effective capacity is therefore measured by qualified saleable wafers rather than reactor count alone.
Supplier scale is also constrained by application engineering. A new VCSEL, RF or quantum-dot laser stack can require multiple development iterations before production release. Once a structure is qualified, customers prefer stable recipes and controlled change management, which gives established suppliers recurring revenue but reduces flexibility to redirect reactors between unrelated product families.
Market Dynamics
The market is expanding through 5G RF, optical communications, sensing and AI datacenter photonics. The strongest value growth is moving toward 6-inch and application-specific photonic epiwafers, while mature smartphone RF demand still provides scale. High substrate cost, long qualification cycles and competition from alternative material platforms remain the principal restraints.
Market Drivers
| Driver | Impact | Commercial mechanism |
|---|---|---|
| AI optical interconnects | High | Quantum-dot and other GaAs lasers can reduce power in datacenter links. |
| 5G and RF front ends | High | GaAs remains important in high-frequency handset and infrastructure RF. |
| 3D sensing and VCSELs | Medium-High | Consumer and automotive sensing use high-volume GaAs emitters. |
| Larger wafer diameters | Medium | Six-inch wafers improve device output and manufacturing automation. |
AI optical interconnects
AI clusters require more optical links and lower energy per bit. GaAs-based quantum-dot lasers are attractive because they can offer temperature stability and efficient light generation. IQE’s 2026 6-inch GaAs supply agreement for Quintessent customer sampling demonstrates direct commercial development in this application. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
5G and RF front ends
GaAs power amplifiers retain strong performance in RF front ends, particularly where efficiency, linearity and frequency are critical. New 5G bands and more complex handset radios increase RF content even as competing technologies gain share. Epiwafer suppliers benefit when customers require additional layer structures or larger wafer formats. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
3D sensing and VCSELs
VCSEL arrays are used in facial recognition, time-of-flight sensing and in-cabin monitoring. IQE reported production ramp of second-generation 3D-sensing VCSEL products in 2025, demonstrating that sensing remains an important high-volume GaAs application outside communications. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Larger wafer diameters
Moving from 4-inch to 6-inch increases usable area and can reduce cost per die when epitaxial and device yields remain high. The transition rewards suppliers with large-wafer reactor capacity, strong uniformity control and established customer qualification. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Market Restraints
| Restraint | Impact | Commercial consequence |
|---|---|---|
| High manufacturing cost | High | GaAs substrates and epitaxy are more expensive than mainstream silicon. |
| Qualification cycles | Medium-High | Each epitaxial stack requires customer and device-level validation. |
| Alternative technologies | Medium-High | Silicon photonics, GaN and CMOS RF compete in some applications. |
| Demand cyclicality | Medium | Smartphone and consumer-electronics cycles affect wafer utilization. |
High manufacturing cost
Single-crystal GaAs substrates, long epitaxy cycles and strict defect control create a higher material cost base. Customers therefore use GaAs where RF or optical performance justifies the premium. Cost pressure is strongest in consumer applications where silicon-based alternatives continue to improve. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Qualification cycles
A small change in thickness, doping or composition can shift wavelength or RF behavior. Customers therefore validate wafers extensively before production. This slows supplier switching and makes development capacity a commercial bottleneck for new entrants. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Alternative technologies
GaAs is not the only route to high-frequency or optical functions. Silicon photonics can integrate modulators and waveguides at scale, while GaN offers higher power in selected RF applications. GaAs suppliers must focus on functions where direct-bandgap emission or mature RF performance provides a clear advantage. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Demand cyclicality
RF and sensing demand can change rapidly when handset or consumer-device inventories correct. Suppliers with exposure to datacom, defense and industrial photonics can reduce volatility, but capacity planning remains challenging when different end markets move asynchronously. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Market Opportunities
Quantum-dot lasers for AI datacenters
Customer sampling of 6-inch GaAs QDL epitaxy creates a new growth pathway. If the architecture enters high-volume production, it could add substantial demand beyond traditional telecom lasers and smartphone RF. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Automotive optical sensing
In-cabin monitoring, LiDAR-adjacent sensing and other optical functions can expand VCSEL and photodiode demand. Automotive qualification also creates longer product lifecycles than consumer electronics. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Six-inch foundry-ready epitaxy
Suppliers that offer qualified 6-inch wafers with fast development cycles can attract fabless photonics and RF customers that do not want to own epitaxy capacity. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Defense and space photonics
High-frequency RF, satellite communications and specialized lasers offer lower-volume but high-value demand where GaAs performance and controlled supply are important. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Supply Chain Analysis
Substrates. Semi-insulating and conductive GaAs wafers provide the crystalline base for epitaxy. Diameter, orientation, defect density and surface quality influence downstream growth. Reliable substrate supply is important because wafer variability can reduce epitaxial uniformity and device yield. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Epitaxy. MOCVD or MBE reactors grow multiple compound-semiconductor layers with precise composition and doping. Reactor conditioning, temperature control and gas purity determine repeatability. Larger 6-inch wafers require tighter within-wafer uniformity and chamber matching across production fleets. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Device fabrication. RF, VCSEL and laser manufacturers process epiwafers through lithography, etch, metallization and optical or electrical test. The epi structure is closely coupled to the device architecture, which is why customers qualify suppliers at the device-performance level rather than only by wafer specification. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Module integration. Finished die are packaged into RF modules, optical transceivers, sensors or laser assemblies. Yield and packaging cost can exceed the wafer value, so epiwafer consistency matters throughout the downstream chain. Long-term supply agreements help customers reduce the risk of material changes after qualification. For commercial buyers in the GaAs Epiwafer market, purchasing decisions also depend on qualification history, integration effort, supply continuity, lifecycle support, operating reliability and measurable system-level value.
Recent Developments in the GaAs Epiwafer Market
Developments tracked through September 2026 and limited to events that materially affect technology, capacity, adoption or competition.
- 3 September 2026
IQE announced a purchase agreement with Quintessent for 6-inch GaAs quantum-dot laser epitaxy supporting customer sampling for AI data-center connectivity, extending an earlier strategic relationship into a more advanced commercialization phase. Source - 2026 Full-Year 2025 Results
IQE reported new 5G handset power-amplifier design wins, production ramp of second-generation 3D-sensing VCSEL products and automotive-qualified VCSEL volume orders, demonstrating diversified GaAs and compound-semiconductor demand. Source - 2025 Interim Results
IQE highlighted continued development of 8-inch RGB epitaxy for silicon integration and expansion across advanced sensing and display applications, illustrating broader large-diameter compound-semiconductor manufacturing capability. Source
Report Scope & Segmentation
| Attribute | Scope |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| 2025 market size | USD 2.05 billion |
| 2026 estimated size | USD 2.23 billion |
| 2034 projected size | USD 4.33 billion |
| CAGR (2026–2034) | 8.6% |
| Largest market in 2025 | Asia Pacific |
| By Type | 4 Inches; 6 Inches; Other |
| By Application | Microelectronic Devices; Optoelectronic Devices |
| By End User | Telecommunications; Automotive; Aerospace & Defense; Consumer Electronics; Healthcare |
| By Epitaxy Method | MOCVD; MBE |
| Companies profiled | IQE; Coherent; Sumitomo Chemical; IntelliEPI; VPEC; SCIOCS; LandMark Optoelectronics; Changelight |
Frequently Asked Questions
What is the GaAs epiwafer market size in 2025?
The global GaAs epiwafer market is valued at USD 2.05 billion in 2025 across RF, optoelectronic, sensing and photonics applications.
What is the market forecast for 2034?
The market is projected to reach USD 4.33 billion by 2034, representing an 8.6% CAGR during 2026–2034. The corresponding 2026 market level is USD 2.23 billion.
Which region leads the market?
Asia Pacific leads because Taiwan, China, Japan and South Korea combine compound-semiconductor epitaxy, device fabrication and electronics manufacturing.
Which wafer size is most important?
Six-inch epiwafers are the leading commercial format because they improve manufacturing economics and support high-volume RF, VCSEL and photonics production.
Which application is largest?
Optoelectronic devices are the strongest growth area, including VCSELs, lasers, photodetectors and emerging AI optical-interconnect products.
What epitaxy methods are used?
MOCVD is widely used for high-volume production, while MBE is important for specialized structures requiring very precise interface and composition control.
How is AI affecting demand?
AI data centers need lower-power optical interconnects, creating new demand for GaAs laser epitaxy, including 6-inch quantum-dot laser wafers moving into customer sampling.
Who are the major companies?
Major suppliers include IQE, Coherent, Sumitomo Chemical, IntelliEPI, VPEC, SCIOCS, LandMark Optoelectronics and Changelight.
What limits market growth?
High substrate and epitaxy cost, long customer qualification and competition from alternative RF or photonic technologies are the main restraints.
What will drive growth through 2034?
5G RF, VCSEL sensing, automotive photonics, larger wafer diameters and AI optical interconnects will support market expansion.
Research Sources & Evidence Base
View research sources used in this market overview
- IQE – Quantum Dot Laser purchase agreement with Quintessent. 2026 6-inch GaAs QDL epitaxy for AI datacenter customer sampling.
- IQE – Full Year 2025 Results. 5G RF, VCSEL sensing and automotive compound-semiconductor demand evidence.
- IQE – 2025 Interim Results. Large-diameter epitaxy and sensing/display development evidence.

Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF