SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

CPU and GPU Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
MICROPROCESSORS Semiconductor Market Research

CPU and GPU Market

Size, Trends, Business Strategies 2026-2034

◷
UPDATED 23 September 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 06043a4c931e
▯
FORMATS PDF

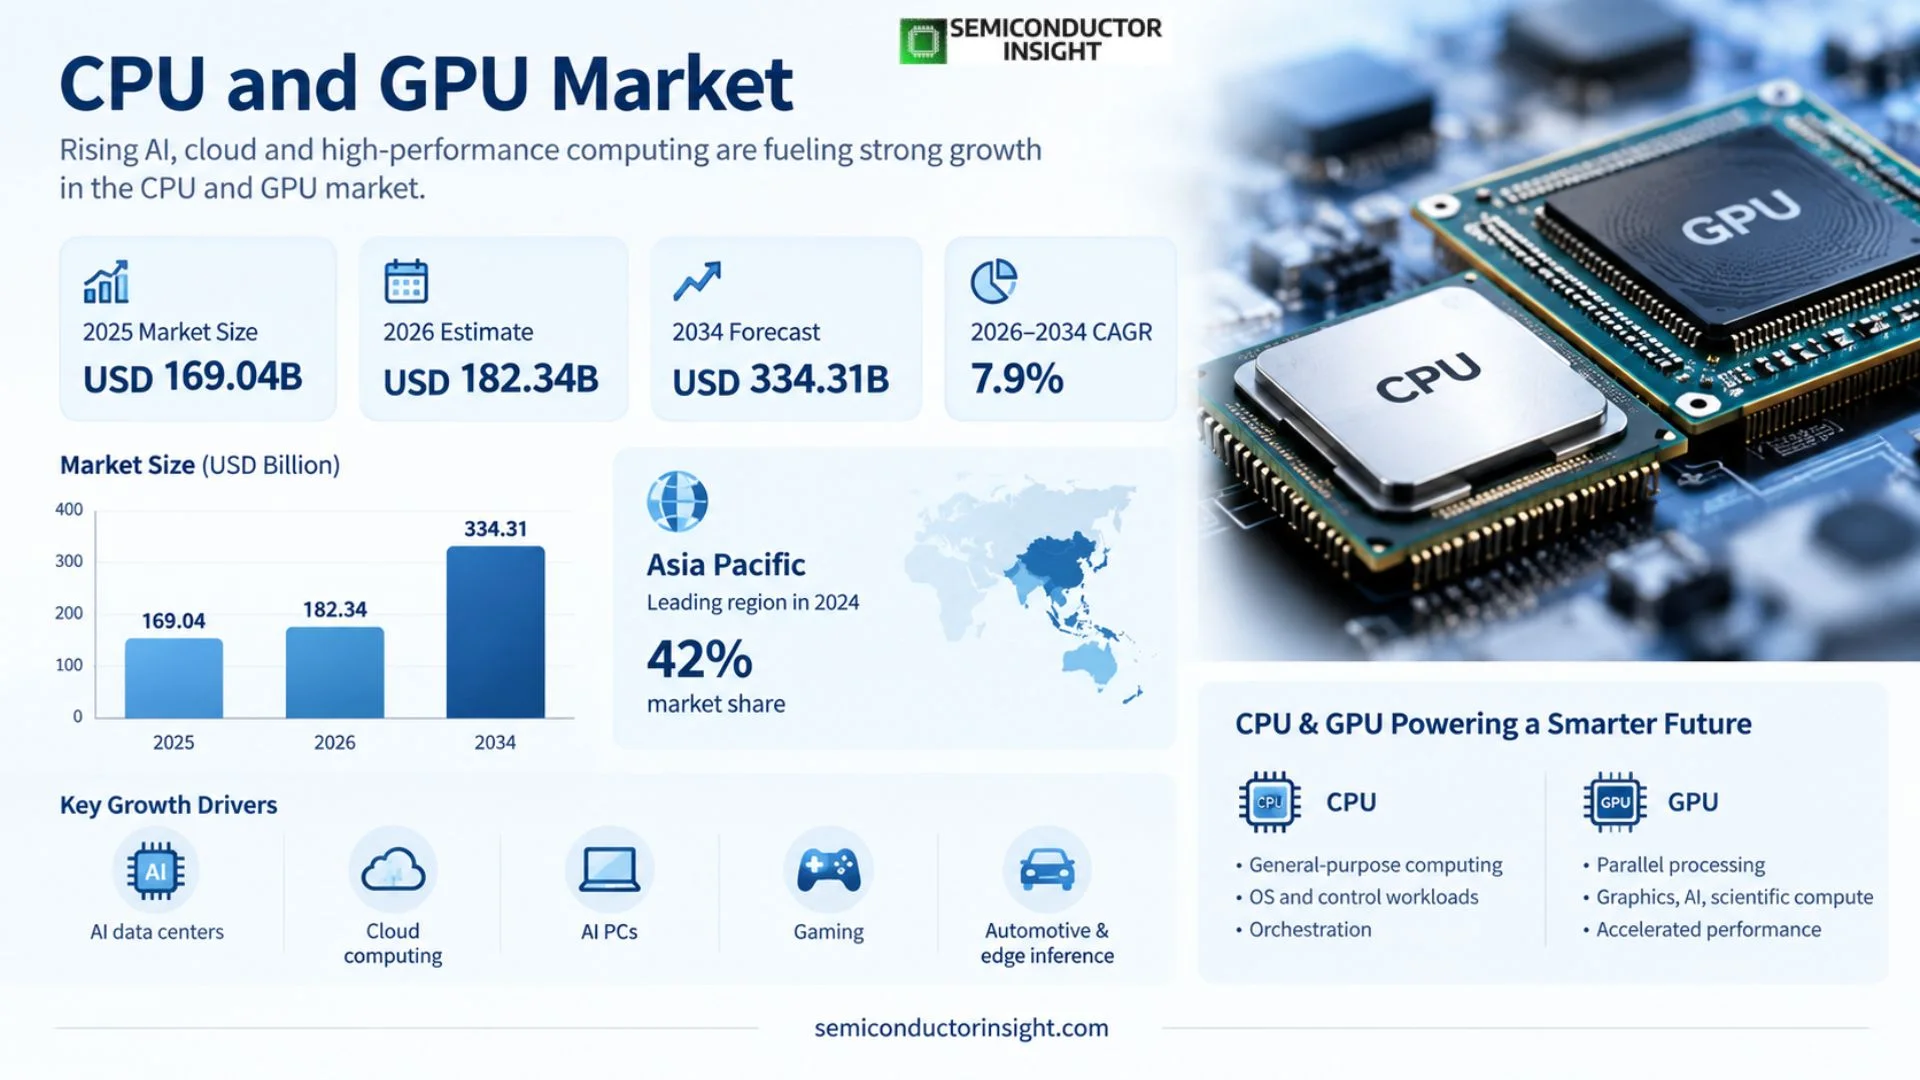
CPU and GPU market is projected to reach USD 334.31 billion by 2034, representing a 7.9% CAGR during 2026–2034. The 2026 estimated market size is USD 182.34 billion. Asia Pacific is the leading regional market with 42% share in 2024.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 169.04 billion
2034 Projected Size
USD 334.31 billion
CAGR (2026–2034)
7.9%
Largest Market in 2025
Asia Pacific (42% share in 2024)

Key Takeaways

  • GPU is the fastest-growing processor type because AI training, inference, graphics, HPC and simulation favor massively parallel compute architectures.
  • Industry is the leading application in the report structure, supported by automation, engineering, robotics, edge AI and high-performance workstation demand.
  • Asia Pacific held 42% of global market share in 2024, supported by large electronics markets, semiconductor manufacturing and processor demand in China, Japan, South Korea, Taiwan and India.
  • x86 remains the dominant general-computing architecture, while ARM is expanding across PCs, mobile, cloud and edge systems and RISC-V is gaining strategic interest in embedded and custom silicon.
  • 2026 is a major architecture transition year. AMD launched MI400-series GPUs and 6th Gen EPYC CPUs, NVIDIA expanded Vera Rubin deployments, Intel introduced Core Ultra Series 3 on 18A, and Apple launched M5 Pro and M5 Max.

CPU and GPU Market Overview

CPU and GPU market is valued at USD 169.04 billion in 2025 and is projected to reach USD 334.31 billion by 2034, representing a 7.9% CAGR during 2026–2034. The 2026 estimated market size is USD 182.34 billion. Asia Pacific is the leading regional market with 42% share in 2024.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Historical data: 2020–2025 · Values in USD

Central processing units execute general-purpose instruction streams, operating systems and control workloads, while graphics processing units execute large numbers of parallel arithmetic operations across graphics, AI and scientific-computing tasks. Modern systems increasingly combine CPU, GPU, NPU and high-speed memory into heterogeneous compute platforms rather than relying on one processor class alone.

Market expansion is being shaped by AI data centers, cloud computing, AI PCs, gaming, industrial automation, edge inference and software-defined vehicles. In data centers, CPUs orchestrate workloads, networking and storage while GPUs provide accelerated matrix and vector compute. In client devices, integrated graphics and AI accelerators are increasing the compute content per processor package.

Architecture differentiation now extends beyond core count. Memory bandwidth, chiplet interconnect, advanced packaging, power efficiency, software ecosystem, compiler support and system-scale networking increasingly determine performance. This favors vendors that can combine silicon, software and platform design across CPUs and GPUs.

Segment Analysis: By Type

By type, the market is segmented into CPU and GPU. CPUs remain fundamental across client, server and embedded systems, while GPUs are the faster-growing value segment because AI and HPC require large-scale parallel processing.

Processor type Technical role Market position
CPU General-purpose execution, operating systems, databases, control logic and sequential or lightly parallel workloads. Subtypes include desktop, mobile, server and embedded CPUs. Largest installed computing base. x86 remains important in PCs and servers, while ARM expands in mobile, client and cloud platforms.
GPU Highly parallel processors optimized for graphics, matrix arithmetic, AI training/inference, simulation and visualization. Includes integrated and discrete GPU architectures. Fastest-growing value segment. AI infrastructure and accelerated computing are increasing GPU content per server and per data-center rack.

Architecture and end-user segmentation

The market also segments by instruction-set architecture and end user. x86 dominates traditional PC and server computing, ARM is expanding through mobile, Apple silicon, Snapdragon PCs and cloud processors, while RISC-V is gaining adoption in embedded and custom compute. Enterprise and cloud-service providers account for the largest high-value infrastructure deployments.

Axis Segments Commercial implication
By Architecture x86 · ARM · RISC-V · Others x86 retains broad software compatibility; ARM emphasizes power efficiency and custom silicon; RISC-V enables open, configurable architectures for embedded and specialized processors.
By End User Consumer Electronics · Enterprise · Government · Cloud Service Providers · Others Consumer drives unit volume; cloud and enterprise create the highest accelerator intensity; governments support sovereign and scientific-computing deployments.

Segment Analysis: By Application

By application, the market includes Industry, Medical, Finance, Aerospace and Other Computing Applications. Industry leads through automation, engineering, robotics and digital transformation, while finance and medical applications are rapidly adopting accelerated AI compute.

Application Key market insight
Industry Factory automation, robotics, digital twins, engineering simulation and industrial edge AI require CPUs for control and GPUs for vision, simulation and inference.
Medical Imaging, genomics, diagnostics and AI-assisted clinical workflows use GPU acceleration alongside general-purpose server and workstation CPUs.
Finance Risk modeling, fraud detection, high-performance analytics and generative AI create demand for dense CPU/GPU infrastructure in data centers.
Aerospace Simulation, digital engineering, mission systems and research computing require high-performance CPU and GPU platforms with long lifecycle and reliability.
Gaming / Content / Other Gaming, media creation, visualization and scientific research sustain strong discrete GPU and high-performance CPU demand.

CPU and GPU Market Size & Share

Regional Analysis

Asia Pacific leads the CPU and GPU market with 42% share in 2024. China is a major consumption and semiconductor-development market, Taiwan is central to advanced manufacturing, South Korea and Japan maintain strong electronics ecosystems, and India is expanding AI and cloud infrastructure.

How do processor markets differ by region?

Asia Pacific combines electronics demand, advanced manufacturing and growing domestic processor programs. North America is the global center for many leading CPU/GPU vendors and hyperscale AI deployment. Europe has strong automotive, industrial and HPC demand. Emerging regions are expanding through cloud, AI infrastructure and digital transformation.

Region Market position Growth outlook Core demand Commercial priority
Asia Pacific 42% share in 2024 Very high Consumer, cloud & manufacturing Scale, supply chain and local ecosystems
North America Technology / AI hub Very high AI DC, enterprise & client Architecture, software and system scale
Europe Industrial / HPC High Auto, science & enterprise Energy efficiency and sovereign compute
South America Emerging Moderate Cloud, enterprise & gaming Affordability and infrastructure
Middle East & Africa Fast-emerging High AI, cloud & government Data-center capacity and sovereign AI
Asia Pacific42% GLOBAL SHARE IN 2024

Why does Asia Pacific lead CPU and GPU demand?

The region combines very large consumer-electronics markets, semiconductor manufacturing, AI infrastructure and domestic processor development. Taiwan anchors advanced foundry and packaging supply, China has large cloud and electronics demand, South Korea is strong in memory and systems, Japan invests in national AI infrastructure and India is expanding data-center and AI capacity.

Market position
Largest
Growth outlook
Very high
Demand profile
Consumer, AI & manufacturing
Commercial gate
Supply scale and software ecosystem
Country / cluster Role Market instance
China Large consumption / design market PC, cloud, gaming and domestic processor programs support demand.
Taiwan Manufacturing hub Advanced foundry and packaging supply supports global CPU/GPU production.
Japan AI / HPC market National and industrial AI infrastructure expands accelerator demand.
India Fast-growing cloud market AI services, enterprise digitization and data centers expand CPU/GPU deployment.
NVIDIA announced a Japan national AI infrastructure in July 2026 using 13,750 Vera CPUs and 27,500 Rubin GPUs.
AMD EPYC and Instinct platforms continue to expand in Asian cloud and enterprise deployments.
Advanced packaging and HBM availability remain strategic constraints for high-end GPU supply.
North AmericaGLOBAL CPU/GPU VENDOR & AI HUB

What drives North American market value?

The United States hosts Intel, NVIDIA, AMD, Qualcomm, Apple and major cloud-service providers. AI infrastructure, enterprise computing, gaming and client PCs create large demand, while the region also defines many software and architecture standards used globally.

Market position
Technology hub
Growth outlook
Very high
Demand profile
AI, cloud & enterprise
Commercial gate
Performance per watt and software
Country / cluster Role Market instance
United States Primary market Hyperscale AI, CPU/GPU vendors and enterprise IT create the largest regional value pool.
Canada AI / cloud niche AI research and data-center investment support accelerators.
Mexico Electronics manufacturing base Server, PC and electronics assembly create downstream processor demand.
AMD launched MI400-series GPUs, 6th Gen EPYC CPUs and Helios rack-scale systems in July 2026.
Intel launched Core Ultra Series 3 on Intel 18A in January 2026 and expanded client/workstation products in March.
Apple M5 Pro and M5 Max integrate up to an 18-core CPU and 40-core GPU with Neural Accelerators.
Europe

What differentiates Europe?

Europe has strong scientific computing, industrial automation, automotive electronics and sovereign-compute initiatives. ARM architecture expertise and major supercomputing programs broaden demand beyond conventional x86 infrastructure, while energy efficiency is a major selection criterion.

Market position
Industrial / HPC
Growth outlook
High
Demand profile
Science, auto & enterprise
Commercial gate
Efficiency and sovereign compute
Country / cluster Role Market instance
United Kingdom Architecture / design hub Arm and advanced chip design ecosystems influence processor platforms.
Germany Industrial / automotive market Engineering, simulation and enterprise AI create accelerator demand.
Finland / broader EU Supercomputing growth EuroHPC systems create large CPU/GPU procurement programs.
AMD announced LUMI-AI in August 2026 using MI430X GPUs and 6th Gen EPYC CPUs.
European industrial users increasingly deploy GPUs for simulation, digital twins and AI vision.
Energy cost and data sovereignty shape HPC and AI procurement.
South America

How does the market develop in South America?

Brazil is the largest regional market through cloud, gaming, enterprise and financial services. Processor demand is mostly imported, and growth depends on data-center investment, currency conditions and broader enterprise IT modernization.

Market position
Emerging
Growth outlook
Moderate
Demand profile
Cloud, gaming & finance
Commercial gate
Affordability and infrastructure
Country / cluster Role Market instance
Brazil Largest regional market Cloud, gaming and financial services support processor demand.
Argentina Software / research niche Technical computing and cloud services create selective demand.
Chile Data-center niche Cloud and digital infrastructure support server CPU/GPU growth.
Cloud providers concentrate high-end GPU access in regional data centers.
Gaming remains a major consumer discrete-GPU demand source.
Currency and import costs strongly influence refresh cycles.
Middle East & Africa

What supports rapid regional growth?

Gulf countries are investing heavily in sovereign AI, cloud and data centers, while Africa is expanding enterprise and telecom computing. The highest-value growth comes from large accelerator clusters rather than traditional PC shipments.

Market position
Fast-emerging
Growth outlook
High
Demand profile
AI, cloud & government
Commercial gate
Power, data centers and access to accelerators
Country / cluster Role Market instance
Saudi Arabia Sovereign AI growth market Large AI and cloud programs create high-end processor demand.
UAE Data-center / AI hub Cloud and national AI initiatives drive accelerators.
South Africa Regional enterprise market Cloud, telecom and financial services create broad CPU demand.
Qualcomm and HUMAIN launched an AI PC platform based on Snapdragon X2 Elite in August 2026.
Regional AI investment increases demand for data-center CPUs and GPUs together.
Power availability and cooling capacity are key constraints for accelerator clusters.

Competitive Landscape

Key participants include Intel Corporation, NVIDIA Corporation, Advanced Micro Devices, Qualcomm Technologies, Samsung Electronics, Apple, MediaTek, Arm, Imagination Technologies, UNISOC, HiSilicon and emerging accelerator developers. Competition spans architecture, software, foundry access, memory bandwidth and system-scale integration.

NVIDIA leads high-end accelerated computing and discrete AI GPUs through its CUDA software ecosystem and large-scale GPU systems. Its roadmap has moved from Hopper and Blackwell into Vera Rubin platforms that combine dedicated CPUs, GPUs, networking and rack-scale design.

AMD competes across both CPUs and GPUs with EPYC, Ryzen and Instinct. The 2026 launch of 6th Gen EPYC, MI400-series GPUs and Helios demonstrates a full-platform strategy spanning processors, accelerators, networking and ROCm software.

Intel remains a major CPU supplier and is increasing GPU and AI integration across client and workstation platforms. Apple, Qualcomm and MediaTek strengthen ARM-based competition in client and mobile computing, while Samsung, UNISOC and HiSilicon address regional and vertically integrated markets.

Competitive tier structure

Competitive tier Representative companies Competitive strengths
Global CPU/GPU platform leaders Intel; NVIDIA; AMD Data center, client, graphics, AI software and advanced packaging
ARM-based system leaders Apple; Qualcomm; MediaTek; Samsung Mobile, AI PC, integrated SoC and power-efficient compute
Architecture / regional challengers Arm; Imagination; UNISOC; HiSilicon; emerging accelerator vendors Licensable architecture, regional ecosystems and specialized compute

Key companies profiled

Intel CorporationNVIDIA CorporationAdvanced Micro Devices (AMD)Qualcomm TechnologiesSamsung ElectronicsAppleMediaTekArmImagination TechnologiesUNISOCHiSilicon

CPU/GPU Supply Capacity & Advanced Packaging Analysis

Processor supply depends on leading-edge wafer capacity, HBM availability, advanced packaging, substrate capacity and final system integration. Many leading CPU/GPU companies are fabless or use a mix of internal and external manufacturing, making foundry and packaging allocation central to effective market capacity.

AI GPUs have especially high packaging intensity because they combine large accelerator dies, HBM stacks and advanced interposers. Capacity therefore cannot be measured only in wafers; CoWoS-class packaging, HBM output and rack-level integration determine how many complete accelerator systems can ship.

Client CPUs and integrated GPUs have different economics. High-volume notebook and desktop products rely on large wafer volumes and mature package assembly, while premium workstation and AI parts use chiplets, high-speed interconnect and higher-value substrates.

Market Dynamics

Growth is driven by AI, cloud, gaming, AI PCs and industrial acceleration. Restraints include high capital intensity, power consumption, software lock-in and supply constraints in advanced packaging or HBM. Opportunities center on heterogeneous compute, chiplets, ARM PCs, RISC-V, sovereign AI and energy-efficient inference.

MARKET DRIVERS

AI requires more accelerated compute

Large models need massive matrix throughput, high memory bandwidth and specialized software stacks.

Cloud providers are designing around heterogeneous systems

CPUs, GPUs, DPUs and networking are co-optimized at rack scale.

Client devices are adding on-device AI

PC processors increasingly integrate stronger GPUs and NPUs to run models locally.

Industrial workloads need real-time inference

Robotics, vision and digital twins expand GPU and edge processor deployment.

Drivers Impact Analysis

Driver Impact Primary markets Time horizon
AI training and inference High Global data centers Short to long term
Cloud / HPC expansion High North America, Europe, Asia Persistent
AI PC refresh Medium to high Global client market Medium term
Industrial edge AI High Factories / robotics Persistent

MARKET RESTRAINTS

AI clusters consume very high power

GPU racks require dense electrical and cooling infrastructure.

High-end accelerators depend on constrained components

HBM and advanced packaging can limit shipments even when GPU wafers are available.

Software ecosystems create switching costs

Applications optimized for one GPU stack can require significant work to migrate.

Leading-edge manufacturing is expensive

Advanced nodes and packaging raise unit cost and require large capital commitments.

Restraints Impact Analysis

Restraint Impact Exposure Time horizon
Power and cooling High AI data centers Persistent
HBM / advanced packaging capacity High High-end GPUs Medium term
Software ecosystem lock-in High Accelerated computing Persistent
Capital / foundry constraints Medium to high Advanced nodes Persistent

MARKET OPPORTUNITIES

Expand rack-scale AI systems

Integrated CPU/GPU/networking platforms can capture more value than standalone chips.

Grow ARM-based PCs and servers

Energy efficiency and custom silicon are creating alternatives to traditional x86 systems.

Use chiplets to scale product families

Die disaggregation improves yield and allows reusable compute, I/O and accelerator tiles.

Build sovereign AI infrastructure

Countries and regulated industries are creating new demand for local accelerator capacity.

CPU and GPU Value Chain Analysis

Architecture / IP / chip design

CPU cores, GPU engines, memory controllers and interconnect define product capability.

Leading-edge wafer fabrication

Foundries manufacture compute dies using advanced process nodes.

Advanced packaging / HBM integration

Chiplets, interposers and stacked memory create high-performance packages.

Server / PC / device integration

OEMs deploy processors in data centers, PCs, industrial systems and consumer devices.

Architecture determines software compatibility

Instruction sets and programming environments strongly influence customer adoption.

Wafer technology determines density and efficiency

Advanced process nodes enable more transistors within power limits.

Packaging determines system bandwidth

Chiplets and HBM require short, high-density interconnect.

Software determines realized performance

Compilers, libraries and frameworks turn hardware capability into usable application performance.

Recent Developments in the CPU and GPU Market

31 August 2026

AMD EPYC CPUs and Instinct GPUs selected for LUMI-AI

The next-generation European supercomputer will use AMD Instinct MI430X GPUs and 6th Gen EPYC processors.

Primary source

31 August 2026

Qualcomm and HUMAIN unveil Snapdragon X2 Elite AI PC

The system combines an 18-core Oryon CPU, Adreno GPU and Hexagon NPU for on-device AI.

Primary source

23 July 2026

AMD launches MI400-series GPUs, 6th Gen EPYC and Helios

The 2026 platform expands AMD across CPU, GPU, networking and rack-scale AI infrastructure.

Primary source

16 July 2026

NVIDIA announces Vera Rubin national AI infrastructure in Japan

The project includes 13,750 Vera CPUs and 27,500 Rubin GPUs for a 140 MW AI factory.

Primary source

3 March 2026

Apple launches M5 Pro and M5 Max

The chips combine up to an 18-core CPU and 40-core GPU with Neural Accelerators and higher unified-memory bandwidth.

Primary source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2020–2034
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
Historical Period 2020–2025
Market Size 2025 USD 169.04 billion
Market Size 2034 USD 334.31 billion
Growth Rate 7.9% during 2026–2034
Unit Value (USD Million/Billion) and processor shipments
By Type CPU · GPU
By Application Industry · Medical · Finance · Aerospace · Others
By Architecture x86 · ARM · RISC-V · Others
By End User Consumer Electronics · Enterprise · Government · Cloud Service Providers · Others
By Region Each region analysed by processor type, application, architecture, end user and country compute ecosystem
North AmericaUnited States, Canada, Mexico
EuropeUnited Kingdom, Germany, France, Finland and other European markets
Asia PacificChina, Taiwan, Japan, South Korea, India and other Asian markets
South AmericaBrazil, Argentina, Chile and other South American markets
Middle East & AfricaSaudi Arabia, UAE, South Africa and other MEA markets
Key Companies Profiled Intel Corporation · NVIDIA Corporation · Advanced Micro Devices (AMD) · Qualcomm Technologies · Samsung Electronics · Apple · MediaTek · Arm · Imagination Technologies · UNISOC · HiSilicon
Customization Scope Free report customization equivalent to up to four analyst working days with purchase. Addition or alteration to country, regional and segment scope.

Frequently Asked Questions

What is the 2025 size of the CPU and GPU market?

The market is valued at USD 169.04 billion in 2025 and is projected to reach USD 334.31 billion by 2034. The 2026 estimate is USD 182.34 billion and the 2026–2034 CAGR is 7.9%.

Which processor type is growing fastest?

GPU is the faster-growing value segment because AI training, inference, graphics and HPC require large-scale parallel processing.

Which application leads the market?

Industry is the leading application in the report structure, supported by automation, engineering, robotics and digital transformation.

Which region leads the market?

Asia Pacific held 42% of global market share in 2024 and remains the leading regional market.

What is the estimated market size in 2026?

The 2026 estimated market size is USD 182.34 billion within the consistent long-term market series.

Which CPU architecture is most important?

x86 remains dominant in general computing, while ARM is expanding across mobile, PCs and cloud and RISC-V is gaining strategic interest.

What are the main market restraints?

Power and cooling, advanced-packaging and HBM constraints, software lock-in and leading-edge manufacturing cost are major restraints.

How is AI changing the processor market?

AI increases GPU demand, raises server CPU requirements and pushes rack-scale integration of compute, memory and networking.

Which companies are active in the market?

Major participants include Intel, NVIDIA, AMD, Qualcomm, Samsung, Apple, MediaTek, Arm, Imagination, UNISOC and HiSilicon.

What does the report cover?

The report covers CPUs and GPUs, application sectors, processor architectures, end users, five global regions, supply capacity, competition, dynamics, recent developments and value chain.

Research Sources & Evidence Base

View primary and authoritative evidence used in this overview
  1. AMD. Advancing AI 2026 – Primary evidence on MI400-series GPUs, 6th Gen EPYC and Helios rack-scale systems.
  2. NVIDIA. Japan Vera Rubin AI Infrastructure – July 2026 evidence on Vera CPUs and Rubin GPUs in national AI infrastructure.
  3. Intel. Core Ultra Series 3 on Intel 18A – January 2026 evidence on client CPU/GPU integration and 18A manufacturing.
  4. Apple. M5 Pro and M5 Max – March 2026 evidence on integrated CPU/GPU and AI compute architecture.
  5. Qualcomm. Snapdragon X2 Elite AI PC – August 2026 evidence on Oryon CPU, Adreno GPU and on-device AI.
CPU and GPU Market Size, Trends, Business Strategies 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...
Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 CPU and GPU Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global CPU and GPU Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global CPU and GPU Overall Market Size
2.1 Global CPU and GPU Market Size: 2024 VS 2032
2.2 Global CPU and GPU Market Size, Prospects & Forecasts: 2020-2032
2.3 Global CPU and GPU Sales: 2020-2032
3 Company Landscape
3.1 Top CPU and GPU Players in Global Market
3.2 Top Global CPU and GPU Companies Ranked by Revenue
3.3 Global CPU and GPU Revenue by Companies
3.4 Global CPU and GPU Sales by Companies
3.5 Global CPU and GPU Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 CPU and GPU Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers CPU and GPU Product Type
3.8 Tier 1, Tier 2, and Tier 3 CPU and GPU Players in Global Market
3.8.1 List of Global Tier 1 CPU and GPU Companies
3.8.2 List of Global Tier 2 and Tier 3 CPU and GPU Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global CPU and GPU Market Size Markets, 2024 & 2032
4.1.2 CPU
4.1.3 GPU
4.2 Segment by Type – Global CPU and GPU Revenue & Forecasts
4.2.1 Segment by Type – Global CPU and GPU Revenue, 2020-2025
4.2.2 Segment by Type – Global CPU and GPU Revenue, 2026-2032
4.2.3 Segment by Type – Global CPU and GPU Revenue Market Share, 2020-2032
4.3 Segment by Type – Global CPU and GPU Sales & Forecasts
4.3.1 Segment by Type – Global CPU and GPU Sales, 2020-2025
4.3.2 Segment by Type – Global CPU and GPU Sales, 2026-2032
4.3.3 Segment by Type – Global CPU and GPU Sales Market Share, 2020-2032
4.4 Segment by Type – Global CPU and GPU Price (Manufacturers Selling Prices), 2020-2032
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global CPU and GPU Market Size, 2024 & 2032
5.1.2 Industry
5.1.3 Medical
5.1.4 Finance
5.1.5 Aerospace
5.1.6 Others
5.2 Segment by Application – Global CPU and GPU Revenue & Forecasts
5.2.1 Segment by Application – Global CPU and GPU Revenue, 2020-2025
5.2.2 Segment by Application – Global CPU and GPU Revenue, 2026-2032
5.2.3 Segment by Application – Global CPU and GPU Revenue Market Share, 2020-2032
5.3 Segment by Application – Global CPU and GPU Sales & Forecasts
5.3.1 Segment by Application – Global CPU and GPU Sales, 2020-2025
5.3.2 Segment by Application – Global CPU and GPU Sales, 2026-2032
5.3.3 Segment by Application – Global CPU and GPU Sales Market Share, 2020-2032
5.4 Segment by Application – Global CPU and GPU Price (Manufacturers Selling Prices), 2020-2032
6 Sights by Region
6.1 By Region – Global CPU and GPU Market Size, 2024 & 2032
6.2 By Region – Global CPU and GPU Revenue & Forecasts
6.2.1 By Region – Global CPU and GPU Revenue, 2020-2025
6.2.2 By Region – Global CPU and GPU Revenue, 2026-2032
6.2.3 By Region – Global CPU and GPU Revenue Market Share, 2020-2032
6.3 By Region – Global CPU and GPU Sales & Forecasts
6.3.1 By Region – Global CPU and GPU Sales, 2020-2025
6.3.2 By Region – Global CPU and GPU Sales, 2026-2032
6.3.3 By Region – Global CPU and GPU Sales Market Share, 2020-2032
6.4 North America
6.4.1 By Country – North America CPU and GPU Revenue, 2020-2032
6.4.2 By Country – North America CPU and GPU Sales, 2020-2032
6.4.3 United States CPU and GPU Market Size, 2020-2032
6.4.4 Canada CPU and GPU Market Size, 2020-2032
6.4.5 Mexico CPU and GPU Market Size, 2020-2032
6.5 Europe
6.5.1 By Country – Europe CPU and GPU Revenue, 2020-2032
6.5.2 By Country – Europe CPU and GPU Sales, 2020-2032
6.5.3 Germany CPU and GPU Market Size, 2020-2032
6.5.4 France CPU and GPU Market Size, 2020-2032
6.5.5 U.K. CPU and GPU Market Size, 2020-2032
6.5.6 Italy CPU and GPU Market Size, 2020-2032
6.5.7 Russia CPU and GPU Market Size, 2020-2032
6.5.8 Nordic Countries CPU and GPU Market Size, 2020-2032
6.5.9 Benelux CPU and GPU Market Size, 2020-2032
6.6 Asia
6.6.1 By Region – Asia CPU and GPU Revenue, 2020-2032
6.6.2 By Region – Asia CPU and GPU Sales, 2020-2032
6.6.3 China CPU and GPU Market Size, 2020-2032
6.6.4 Japan CPU and GPU Market Size, 2020-2032
6.6.5 South Korea CPU and GPU Market Size, 2020-2032
6.6.6 Southeast Asia CPU and GPU Market Size, 2020-2032
6.6.7 India CPU and GPU Market Size, 2020-2032
6.7 South America
6.7.1 By Country – South America CPU and GPU Revenue, 2020-2032
6.7.2 By Country – South America CPU and GPU Sales, 2020-2032
6.7.3 Brazil CPU and GPU Market Size, 2020-2032
6.7.4 Argentina CPU and GPU Market Size, 2020-2032
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa CPU and GPU Revenue, 2020-2032
6.8.2 By Country – Middle East & Africa CPU and GPU Sales, 2020-2032
6.8.3 Turkey CPU and GPU Market Size, 2020-2032
6.8.4 Israel CPU and GPU Market Size, 2020-2032
6.8.5 Saudi Arabia CPU and GPU Market Size, 2020-2032
6.8.6 UAE CPU and GPU Market Size, 2020-2032
7 Manufacturers & Brands Profiles
7.1 Intel
7.1.1 Intel Company Summary
7.1.2 Intel Business Overview
7.1.3 Intel CPU and GPU Major Product Offerings
7.1.4 Intel CPU and GPU Sales and Revenue in Global (2020-2025)
7.1.5 Intel Key News & Latest Developments
7.2 Qualcomm Technologies
7.2.1 Qualcomm Technologies Company Summary
7.2.2 Qualcomm Technologies Business Overview
7.2.3 Qualcomm Technologies CPU and GPU Major Product Offerings
7.2.4 Qualcomm Technologies CPU and GPU Sales and Revenue in Global (2020-2025)
7.2.5 Qualcomm Technologies Key News & Latest Developments
7.3 NXP Semiconductors
7.3.1 NXP Semiconductors Company Summary
7.3.2 NXP Semiconductors Business Overview
7.3.3 NXP Semiconductors CPU and GPU Major Product Offerings
7.3.4 NXP Semiconductors CPU and GPU Sales and Revenue in Global (2020-2025)
7.3.5 NXP Semiconductors Key News & Latest Developments
7.4 Samsung Electronics
7.4.1 Samsung Electronics Company Summary
7.4.2 Samsung Electronics Business Overview
7.4.3 Samsung Electronics CPU and GPU Major Product Offerings
7.4.4 Samsung Electronics CPU and GPU Sales and Revenue in Global (2020-2025)
7.4.5 Samsung Electronics Key News & Latest Developments
7.5 Advanced Micro Devices
7.5.1 Advanced Micro Devices Company Summary
7.5.2 Advanced Micro Devices Business Overview
7.5.3 Advanced Micro Devices CPU and GPU Major Product Offerings
7.5.4 Advanced Micro Devices CPU and GPU Sales and Revenue in Global (2020-2025)
7.5.5 Advanced Micro Devices Key News & Latest Developments
7.6 Apple
7.6.1 Apple Company Summary
7.6.2 Apple Business Overview
7.6.3 Apple CPU and GPU Major Product Offerings
7.6.4 Apple CPU and GPU Sales and Revenue in Global (2020-2025)
7.6.5 Apple Key News & Latest Developments
7.7 MediaTek
7.7.1 MediaTek Company Summary
7.7.2 MediaTek Business Overview
7.7.3 MediaTek CPU and GPU Major Product Offerings
7.7.4 MediaTek CPU and GPU Sales and Revenue in Global (2020-2025)
7.7.5 MediaTek Key News & Latest Developments
7.8 Nvidia
7.8.1 Nvidia Company Summary
7.8.2 Nvidia Business Overview
7.8.3 Nvidia CPU and GPU Major Product Offerings
7.8.4 Nvidia CPU and GPU Sales and Revenue in Global (2020-2025)
7.8.5 Nvidia Key News & Latest Developments
7.9 UNISOC
7.9.1 UNISOC Company Summary
7.9.2 UNISOC Business Overview
7.9.3 UNISOC CPU and GPU Major Product Offerings
7.9.4 UNISOC CPU and GPU Sales and Revenue in Global (2020-2025)
7.9.5 UNISOC Key News & Latest Developments
7.10 Hisilicon
7.10.1 Hisilicon Company Summary
7.10.2 Hisilicon Business Overview
7.10.3 Hisilicon CPU and GPU Major Product Offerings
7.10.4 Hisilicon CPU and GPU Sales and Revenue in Global (2020-2025)
7.10.5 Hisilicon Key News & Latest Developments
7.11 ARM Limited
7.11.1 ARM Limited Company Summary
7.11.2 ARM Limited Business Overview
7.11.3 ARM Limited CPU and GPU Major Product Offerings
7.11.4 ARM Limited CPU and GPU Sales and Revenue in Global (2020-2025)
7.11.5 ARM Limited Key News & Latest Developments
7.12 Imagination Technologies Group
7.12.1 Imagination Technologies Group Company Summary
7.12.2 Imagination Technologies Group Business Overview
7.12.3 Imagination Technologies Group CPU and GPU Major Product Offerings
7.12.4 Imagination Technologies Group CPU and GPU Sales and Revenue in Global (2020-2025)
7.12.5 Imagination Technologies Group Key News & Latest Developments
7.13 VeriSilicon (Vivante)
7.13.1 VeriSilicon (Vivante) Company Summary
7.13.2 VeriSilicon (Vivante) Business Overview
7.13.3 VeriSilicon (Vivante) CPU and GPU Major Product Offerings
7.13.4 VeriSilicon (Vivante) CPU and GPU Sales and Revenue in Global (2020-2025)
7.13.5 VeriSilicon (Vivante) Key News & Latest Developments
7.14 Allwinner Technology
7.14.1 Allwinner Technology Company Summary
7.14.2 Allwinner Technology Business Overview
7.14.3 Allwinner Technology CPU and GPU Major Product Offerings
7.14.4 Allwinner Technology CPU and GPU Sales and Revenue in Global (2020-2025)
7.14.5 Allwinner Technology Key News & Latest Developments
7.15 Iluvatar CoreX
7.15.1 Iluvatar CoreX Company Summary
7.15.2 Iluvatar CoreX Business Overview
7.15.3 Iluvatar CoreX CPU and GPU Major Product Offerings
7.15.4 Iluvatar CoreX CPU and GPU Sales and Revenue in Global (2020-2025)
7.15.5 Iluvatar CoreX Key News & Latest Developments
7.16 Biren Technology
7.16.1 Biren Technology Company Summary
7.16.2 Biren Technology Business Overview
7.16.3 Biren Technology CPU and GPU Major Product Offerings
7.16.4 Biren Technology CPU and GPU Sales and Revenue in Global (2020-2025)
7.16.5 Biren Technology Key News & Latest Developments
8 Global CPU and GPU Production Capacity, Analysis
8.1 Global CPU and GPU Production Capacity, 2020-2032
8.2 CPU and GPU Production Capacity of Key Manufacturers in Global Market
8.3 Global CPU and GPU Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 CPU and GPU Supply Chain Analysis
10.1 CPU and GPU Industry Value Chain
10.2 CPU and GPU Upstream Market
10.3 CPU and GPU Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 CPU and GPU Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of CPU and GPU in Global Market
Table 2. Top CPU and GPU Players in Global Market, Ranking by Revenue (2024)
Table 3. Global CPU and GPU Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global CPU and GPU Revenue Share by Companies, 2020-2025
Table 5. Global CPU and GPU Sales by Companies, (K Units), 2020-2025
Table 6. Global CPU and GPU Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers CPU and GPU Price (2020-2025) & (US$/Unit)
Table 8. Global Manufacturers CPU and GPU Product Type
Table 9. List of Global Tier 1 CPU and GPU Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 CPU and GPU Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global CPU and GPU Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global CPU and GPU Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global CPU and GPU Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global CPU and GPU Sales (K Units), 2020-2025
Table 15. Segment by Type – Global CPU and GPU Sales (K Units), 2026-2032
Table 16. Segment by Application – Global CPU and GPU Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global CPU and GPU Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global CPU and GPU Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global CPU and GPU Sales, (K Units), 2020-2025
Table 20. Segment by Application – Global CPU and GPU Sales, (K Units), 2026-2032
Table 21. By Region – Global CPU and GPU Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global CPU and GPU Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global CPU and GPU Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global CPU and GPU Sales, (K Units), 2020-2025
Table 25. By Region – Global CPU and GPU Sales, (K Units), 2026-2032
Table 26. By Country – North America CPU and GPU Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America CPU and GPU Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America CPU and GPU Sales, (K Units), 2020-2025
Table 29. By Country – North America CPU and GPU Sales, (K Units), 2026-2032
Table 30. By Country – Europe CPU and GPU Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe CPU and GPU Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe CPU and GPU Sales, (K Units), 2020-2025
Table 33. By Country – Europe CPU and GPU Sales, (K Units), 2026-2032
Table 34. By Region – Asia CPU and GPU Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia CPU and GPU Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia CPU and GPU Sales, (K Units), 2020-2025
Table 37. By Region – Asia CPU and GPU Sales, (K Units), 2026-2032
Table 38. By Country – South America CPU and GPU Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America CPU and GPU Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America CPU and GPU Sales, (K Units), 2020-2025
Table 41. By Country – South America CPU and GPU Sales, (K Units), 2026-2032
Table 42. By Country – Middle East & Africa CPU and GPU Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa CPU and GPU Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa CPU and GPU Sales, (K Units), 2020-2025
Table 45. By Country – Middle East & Africa CPU and GPU Sales, (K Units), 2026-2032
Table 46. Intel Company Summary
Table 47. Intel CPU and GPU Product Offerings
Table 48. Intel CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 49. Intel Key News & Latest Developments
Table 50. Qualcomm Technologies Company Summary
Table 51. Qualcomm Technologies CPU and GPU Product Offerings
Table 52. Qualcomm Technologies CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 53. Qualcomm Technologies Key News & Latest Developments
Table 54. NXP Semiconductors Company Summary
Table 55. NXP Semiconductors CPU and GPU Product Offerings
Table 56. NXP Semiconductors CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 57. NXP Semiconductors Key News & Latest Developments
Table 58. Samsung Electronics Company Summary
Table 59. Samsung Electronics CPU and GPU Product Offerings
Table 60. Samsung Electronics CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 61. Samsung Electronics Key News & Latest Developments
Table 62. Advanced Micro Devices Company Summary
Table 63. Advanced Micro Devices CPU and GPU Product Offerings
Table 64. Advanced Micro Devices CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 65. Advanced Micro Devices Key News & Latest Developments
Table 66. Apple Company Summary
Table 67. Apple CPU and GPU Product Offerings
Table 68. Apple CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 69. Apple Key News & Latest Developments
Table 70. MediaTek Company Summary
Table 71. MediaTek CPU and GPU Product Offerings
Table 72. MediaTek CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 73. MediaTek Key News & Latest Developments
Table 74. Nvidia Company Summary
Table 75. Nvidia CPU and GPU Product Offerings
Table 76. Nvidia CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 77. Nvidia Key News & Latest Developments
Table 78. UNISOC Company Summary
Table 79. UNISOC CPU and GPU Product Offerings
Table 80. UNISOC CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 81. UNISOC Key News & Latest Developments
Table 82. Hisilicon Company Summary
Table 83. Hisilicon CPU and GPU Product Offerings
Table 84. Hisilicon CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 85. Hisilicon Key News & Latest Developments
Table 86. ARM Limited Company Summary
Table 87. ARM Limited CPU and GPU Product Offerings
Table 88. ARM Limited CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 89. ARM Limited Key News & Latest Developments
Table 90. Imagination Technologies Group Company Summary
Table 91. Imagination Technologies Group CPU and GPU Product Offerings
Table 92. Imagination Technologies Group CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 93. Imagination Technologies Group Key News & Latest Developments
Table 94. VeriSilicon (Vivante) Company Summary
Table 95. VeriSilicon (Vivante) CPU and GPU Product Offerings
Table 96. VeriSilicon (Vivante) CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 97. VeriSilicon (Vivante) Key News & Latest Developments
Table 98. Allwinner Technology Company Summary
Table 99. Allwinner Technology CPU and GPU Product Offerings
Table 100. Allwinner Technology CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 101. Allwinner Technology Key News & Latest Developments
Table 102. Iluvatar CoreX Company Summary
Table 103. Iluvatar CoreX CPU and GPU Product Offerings
Table 104. Iluvatar CoreX CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 105. Iluvatar CoreX Key News & Latest Developments
Table 106. Biren Technology Company Summary
Table 107. Biren Technology CPU and GPU Product Offerings
Table 108. Biren Technology CPU and GPU Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 109. Biren Technology Key News & Latest Developments
Table 110. CPU and GPU Capacity of Key Manufacturers in Global Market, 2023-2025 (K Units)
Table 111. Global CPU and GPU Capacity Market Share of Key Manufacturers, 2023-2025
Table 112. Global CPU and GPU Production by Region, 2020-2025 (K Units)
Table 113. Global CPU and GPU Production by Region, 2026-2032 (K Units)
Table 114. CPU and GPU Market Opportunities & Trends in Global Market
Table 115. CPU and GPU Market Drivers in Global Market
Table 116. CPU and GPU Market Restraints in Global Market
Table 117. CPU and GPU Raw Materials
Table 118. CPU and GPU Raw Materials Suppliers in Global Market
Table 119. Typical CPU and GPU Downstream
Table 120. CPU and GPU Downstream Clients in Global Market
Table 121. CPU and GPU Distributors and Sales Agents in Global Market

List of Figures
Figure 1. CPU and GPU Product Picture
Figure 2. CPU and GPU Segment by Type in 2024
Figure 3. CPU and GPU Segment by Application in 2024
Figure 4. Global CPU and GPU Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global CPU and GPU Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global CPU and GPU Revenue: 2020-2032 (US$, Mn)
Figure 8. CPU and GPU Sales in Global Market: 2020-2032 (K Units)
Figure 9. The Top 3 and 5 Players Market Share by CPU and GPU Revenue in 2024
Figure 10. Segment by Type – Global CPU and GPU Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global CPU and GPU Revenue Market Share, 2020-2032
Figure 12. Segment by Type – Global CPU and GPU Sales Market Share, 2020-2032
Figure 13. Segment by Type – Global CPU and GPU Price (US$/Unit), 2020-2032
Figure 14. Segment by Application – Global CPU and GPU Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global CPU and GPU Revenue Market Share, 2020-2032
Figure 16. Segment by Application – Global CPU and GPU Sales Market Share, 2020-2032
Figure 17. Segment by Application -Global CPU and GPU Price (US$/Unit), 2020-2032
Figure 18. By Region – Global CPU and GPU Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global CPU and GPU Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global CPU and GPU Revenue Market Share, 2020-2032
Figure 21. By Region – Global CPU and GPU Sales Market Share, 2020-2032
Figure 22. By Country – North America CPU and GPU Revenue Market Share, 2020-2032
Figure 23. By Country – North America CPU and GPU Sales Market Share, 2020-2032
Figure 24. United States CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 25. Canada CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 26. Mexico CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 27. By Country – Europe CPU and GPU Revenue Market Share, 2020-2032
Figure 28. By Country – Europe CPU and GPU Sales Market Share, 2020-2032
Figure 29. Germany CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 30. France CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 31. U.K. CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 32. Italy CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 33. Russia CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 34. Nordic Countries CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 35. Benelux CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 36. By Region – Asia CPU and GPU Revenue Market Share, 2020-2032
Figure 37. By Region – Asia CPU and GPU Sales Market Share, 2020-2032
Figure 38. China CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 39. Japan CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 40. South Korea CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 41. Southeast Asia CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 42. India CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 43. By Country – South America CPU and GPU Revenue Market Share, 2020-2032
Figure 44. By Country – South America CPU and GPU Sales, Market Share, 2020-2032
Figure 45. Brazil CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 46. Argentina CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 47. By Country – Middle East & Africa CPU and GPU Revenue, Market Share, 2020-2032
Figure 48. By Country – Middle East & Africa CPU and GPU Sales, Market Share, 2020-2032
Figure 49. Turkey CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 50. Israel CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 51. Saudi Arabia CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 52. UAE CPU and GPU Revenue, (US$, Mn), 2020-2032
Figure 53. Global CPU and GPU Production Capacity (K Units), 2020-2032
Figure 54. The Percentage of Production CPU and GPU by Region, 2024 VS 2032
Figure 55. CPU and GPU Industry Value Chain
Figure 56. Marketing Channels