Key Statistics
Key Takeaways
- Market size: the Control Allocation for Overactuated eVTOL Aircraft in Transition Flight market was valued at USD 180 million in 2025 and is projected to reach USD 1.05 billion by 2034, representing a 21.3% CAGR over 2026–2034.
- Model-Based Allocation has the strongest current type position because physics-based models remain easier to verify, tune and explain within safety-critical certification programs.
- Urban Air Mobility (UAM) Services is the most commercially important application because UAM and air-taxi programs are the primary commercial path for passenger eVTOL aircraft and require robust hover-to-cruise transition control.
- North America is the largest regional market in 2025; regional expansion depends on the local mix of installed infrastructure, regulation, manufacturing capability and customer investment.
- Competitive differentiation increasingly depends on application engineering, qualification support and lifecycle reliability rather than price alone.
Control Allocation for Overactuated eVTOL Aircraft in Transition Flight Market Overview
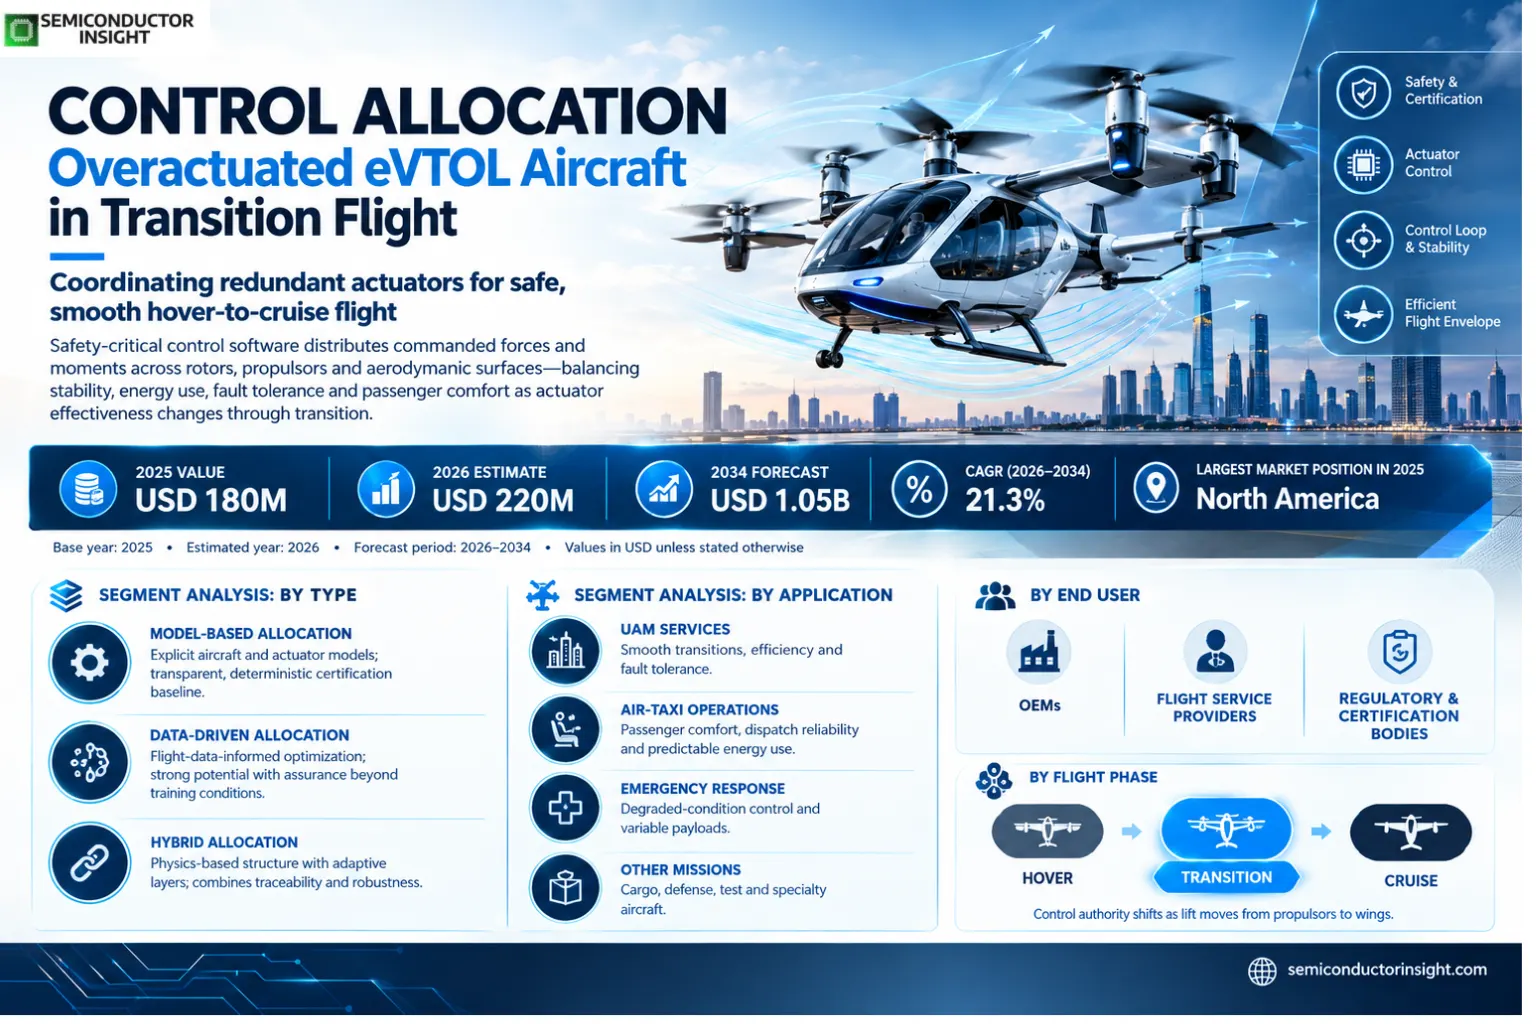
Control Allocation for Overactuated eVTOL Aircraft in Transition Flight market was valued at USD 180 million in 2025 and is estimated at USD 220 million in 2026. It is projected to reach USD 1.05 billion by 2034, registering a 21.3% CAGR over 2026–2034. North America held the largest market position in 2025.
Control allocation is the real-time distribution of commanded forces and moments across redundant rotors, propulsors and aerodynamic surfaces. In overactuated eVTOL aircraft, multiple combinations of actuator commands can produce the same vehicle response, so the allocation layer must choose a solution that respects actuator limits while balancing stability, energy use, failure tolerance and passenger comfort. Transition flight is especially demanding because control effectiveness changes as the aircraft moves from rotor-borne lift toward wing-borne forward flight.
The commercial market is therefore a safety-critical software and avionics engineering category rather than a standalone mass-produced component. Revenue can include embedded control software, model development, high-integrity computing integration, verification tools and certification engineering. The value of control allocation rises with propulsion complexity because distributed electric aircraft may have many independently controlled motors, tilt mechanisms and surfaces whose authority changes rapidly across the flight envelope.
Regulatory progress is converting technical research into commercial engineering work. The FAA issued a powered-lift integration final rule in October 2024, while EASA has continued to expand Special Condition VTOL means of compliance and operational guidance. These frameworks do not prescribe one allocation algorithm, but they increase the amount of evidence OEMs must generate around flight control, failures, simulation and operational safety, supporting demand for traceable and certifiable control architectures.
Segment Analysis: By Type
By type, the market is segmented into Model-Based Allocation, Data-Driven Allocation, Hybrid Allocation. Model-Based Allocation has the strongest current position, while the remaining categories compete on performance, integration effort, lifecycle economics and customer qualification requirements.
| Type | Function / role | Market position |
|---|---|---|
| Model-Based Allocation | Uses explicit aircraft and actuator models to solve allocation objectives. | Preferred baseline where transparency and deterministic behavior support certification. |
| Data-Driven Allocation | Uses learned models or optimization informed by flight data. | High innovation potential but requires careful assurance of behavior outside training conditions. |
| Hybrid Allocation | Combines physics-based structure with adaptive or learning layers. | Balances certifiability with improved robustness across uncertain aerodynamics and failures. |
Commercial implications by type
Model-based allocation is likely to remain the certification anchor because its behavior can be traced to known dynamics and actuator limits. Data-driven methods can add value in health estimation, disturbance prediction and adaptive tuning, while hybrid architectures offer a practical route to introduce learning without making the entire safety-critical chain opaque. Commercial suppliers therefore need strong model-validation, real-time optimization and verification capabilities rather than generic AI expertise.
Segment Analysis: By Application
By application, the market is segmented into Urban Air Mobility (UAM) Services, Air-Taxi Operations, Emergency Response Platforms, Others. Purchasing behavior differs materially by use case because performance thresholds, duty cycles, safety requirements and integration costs vary across end systems.
| Application | Demand characteristics |
|---|---|
| Urban Air Mobility (UAM) Services | High-frequency passenger operations demand smooth, efficient transitions and fault tolerance across many daily cycles. |
| Air-Taxi Operations | Air-taxi services place strong emphasis on passenger comfort, dispatch reliability and predictable energy use. |
| Emergency Response Platforms | Emergency platforms need robust control under degraded conditions, variable payload and demanding operating environments. |
| Others | Cargo, defense, test and specialty missions create smaller but technically diverse requirements. |
By End User
The by end user view is segmented into OEMs (Original Equipment Manufacturers), Flight Service Providers, Regulatory & Certification Bodies. OEMs dominate spending because control allocation is embedded during vehicle architecture and certification, while operators influence maintainability and fleet-performance requirements.
By Flight Phase
The by flight phase view is segmented into Hover, Transition (Hover-to-Cruise), Cruise. Transition is the defining engineering challenge because actuator effectiveness changes quickly as lift shifts between propulsors and aerodynamic surfaces.
Regional Analysis
North America leads the Control Allocation for Overactuated eVTOL Aircraft in Transition Flight market in 2025. The regional structure is not uniform: adoption reflects differences in end-market scale, qualification requirements, manufacturing ecosystems, regulation and customer access rather than one global purchasing pattern.
How does regional demand differ across the Control Allocation for Overactuated eVTOL Aircraft in Transition Flight market?
Regional demand should be read through the local deployment mechanism. Mature markets usually place more weight on qualification, regulation and replacement cycles, while faster-growing markets are shaped by new capacity, infrastructure build-out and rising local production. Supplier strategy therefore differs by region: channel depth and compliance may matter more than low price in mature markets, while local engineering and availability can decide share in expansion markets.
| Region | Position | Growth outlook | Demand profile | Supplier-selection factor |
|---|---|---|---|---|
| North America | Largest | Strong | OEM and certification led | FAA pathway, capital, flight testing |
| Europe | Large | Strong | Certification-led | EASA SC-VTOL, aerospace ecosystem |
| Asia Pacific | Fast-growing | High | OEM and urban-mobility pilots | Local certification, manufacturing |
| South America | Early | Emerging | Demonstration-led | Cost, infrastructure |
| Middle East & Africa | Early | Emerging | Premium mobility projects | Policy, vertiports, climate |
Competitive Landscape
Competition is dominated by eVTOL OEMs that treat control allocation as proprietary flight-control IP, supported by aerospace suppliers providing avionics, actuation, simulation and certification engineering. The market is therefore partnership-driven: specialist software vendors rarely sell a generic allocator without deep adaptation to a specific aircraft.
Joby, Archer, Beta, Vertical Aerospace and other OEMs integrate allocation logic with vehicle aerodynamics, propulsion and energy-management systems. Their advantage comes from proprietary flight-test data and direct ownership of certification artifacts.
Safran, Honeywell, Collins Aerospace, Thales and Rolls-Royce can participate through flight-control computers, actuators, electric propulsion and systems engineering. These suppliers bring established assurance processes and long aerospace qualification histories that reduce program risk.
Specialist algorithm providers can create value in optimization, digital twins and fault-tolerant control, but they must support deterministic execution, traceable requirements and verification. The strongest commercial model is co-development with OEMs rather than off-the-shelf software licensing.
| Company | Positioning | Competitive relevance |
|---|---|---|
| Joby Aviation | Established / platform leader | Vertical integration of aircraft, propulsion and flight testing provides proprietary data for control-law development. |
| Lilium GmbH | Established / specialist | Vehicle-specific architecture and certification ownership make allocation software tightly coupled to the OEM platform. |
| Archer Aviation | Established / specialist | A major U.S. eVTOL program with active certification work creates recurring demand for high-integrity control engineering. |
Companies Profiled
Joby Aviation, Lilium GmbH, Archer Aviation, Beta Technologies, Volocopter, EHang, Vertical Aerospace, Wisk Aero, Boeing Aurora, Airbus, Rolls-Royce, Safran, Honeywell Aerospace, Collins Aerospace, Thales Group.
Production Capacity Analysis
Capacity in this market is measured primarily in qualified engineering teams, simulation infrastructure and flight-test assets rather than physical factories. Bottlenecks include control engineers with both nonlinear flight-dynamics and embedded real-time expertise, certified software processes, high-fidelity digital models and access to aircraft for validation.
Hardware capacity still matters because allocation algorithms execute on high-integrity flight-control computers connected to sensors and distributed propulsion actuators. Suppliers must coordinate software releases with avionics hardware, actuator dynamics and vehicle configuration changes, making systems integration capacity a critical commercial resource.
Market Dynamics
The market is accelerated by eVTOL certification activity and increasing actuator complexity, but commercialization remains gated by aircraft program schedules, safety assurance and the scarcity of experienced flight-control engineers. Value concentrates in software and systems work that can survive certification scrutiny.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial implication |
|---|---|---|
| eVTOL certification programs | High | As OEMs move from prototypes toward type certification, transition-flight control must be documented, verified and flight-tested. This converts control allocation from research code into a funded safety-critical engineering workstream. |
| Distributed electric propulsion | High | Multiple independent rotors and tilt mechanisms create excess control authority that must be allocated in real time, increasing algorithmic complexity and the value of robust optimization. |
| Digital twins and HIL testing | High | High-fidelity simulation and hardware-in-the-loop environments let engineers test faults, gusts and actuator limits before flight, improving development efficiency and evidence quality. |
| Fleet economics | Medium-High | More efficient allocation can reduce energy waste and improve actuator usage, which matters for commercial operators sensitive to range, battery cycles and dispatch reliability. |
eVTOL certification programs
As OEMs move from prototypes toward type certification, transition-flight control must be documented, verified and flight-tested. This converts control allocation from research code into a funded safety-critical engineering workstream.
Distributed electric propulsion
Multiple independent rotors and tilt mechanisms create excess control authority that must be allocated in real time, increasing algorithmic complexity and the value of robust optimization.
Digital twins and HIL testing
High-fidelity simulation and hardware-in-the-loop environments let engineers test faults, gusts and actuator limits before flight, improving development efficiency and evidence quality.
Fleet economics
More efficient allocation can reduce energy waste and improve actuator usage, which matters for commercial operators sensitive to range, battery cycles and dispatch reliability.
Market Restraints
Restraints Impact Analysis
| Restraint | Impact | Commercial implication |
|---|---|---|
| Certification complexity | High | Safety-critical control software requires extensive requirements traceability, verification and flight evidence. Novel learning-based methods face additional assurance challenges. |
| OEM program delays | High | Revenue depends on aircraft certification and production schedules; slips in a small number of leading programs can materially delay market spending. |
| Specialist talent shortage | Medium-High | Engineers who combine nonlinear control, flight dynamics, embedded systems and certification knowledge are scarce, limiting development throughput. |
| Architecture specificity | Medium | Allocation logic is tightly coupled to each aircraft’s actuator layout and aerodynamics, limiting reuse and reducing pure software scalability. |
Certification complexity
Safety-critical control software requires extensive requirements traceability, verification and flight evidence. Novel learning-based methods face additional assurance challenges.
OEM program delays
Revenue depends on aircraft certification and production schedules; slips in a small number of leading programs can materially delay market spending.
Specialist talent shortage
Engineers who combine nonlinear control, flight dynamics, embedded systems and certification knowledge are scarce, limiting development throughput.
Architecture specificity
Allocation logic is tightly coupled to each aircraft’s actuator layout and aerodynamics, limiting reuse and reducing pure software scalability.
Market Opportunities
Hybrid model-plus-learning control
Using physics-based allocation with adaptive health estimation or disturbance prediction can improve robustness without making the full control chain opaque.
Certification-grade simulation toolchains
OEMs need repeatable evidence across Monte Carlo simulation, HIL and flight tests. Toolchains that automate traceability and failure-case coverage can capture significant engineering value.
Fault-tolerant allocation
Graceful redistribution after motor, actuator or sensor degradation is central to safety cases for overactuated aircraft and creates demand for specialized algorithms and verification.
Fleet performance optimization
Once aircraft enter service, operational data can refine models, maintenance thresholds and energy-management strategies, creating a recurring software and analytics layer.
Supply Chain Analysis
Vehicle physics
Control software
Avionics / actuation
Certification / operations
The highest-value layer is systems knowledge that links vehicle physics to certifiable software. Generic optimization algorithms are widely available, but implementing them with deterministic timing, actuator constraints, failure behavior and traceability requires specialized aerospace engineering.
Flight-test data and validated simulation models are strategic assets because they improve both controller performance and certification evidence. OEMs therefore retain strong control over the value chain, while suppliers differentiate through reusable tools and assurance experience.
Recent Developments
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | Control Allocation for Overactuated eVTOL Aircraft in Transition Flight |
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| Market size | USD 180 million (2025) to USD 1.05 billion (2034) |
| CAGR | 21.3% (2026–2034) |
| Largest market | North America |
| By Type | Model-Based Allocation, Data-Driven Allocation, Hybrid Allocation |
| By Application | Urban Air Mobility (UAM) Services, Air-Taxi Operations, Emergency Response Platforms, Others |
| By End User | OEMs (Original Equipment Manufacturers), Flight Service Providers, Regulatory & Certification Bodies |
| By Flight Phase | Hover, Transition (Hover-to-Cruise), Cruise |
| By Control Architecture | Centralized Allocation, Distributed Allocation, Hierarchical Allocation |
| Companies profiled | Joby Aviation, Lilium GmbH, Archer Aviation, Beta Technologies, Volocopter, EHang, Vertical Aerospace, Wisk Aero, Boeing Aurora, Airbus, Rolls-Royce, Safran, Honeywell Aerospace, Collins Aerospace, Thales Group |
Frequently Asked Questions
What is the Control Allocation for Overactuated eVTOL Aircraft in Transition Flight market size in 2025?
The market was valued at USD 180 million in 2025.
What is the projected Control Allocation for Overactuated eVTOL Aircraft in Transition Flight market size by 2034?
The market is projected to reach USD 1.05 billion by 2034.
What is the CAGR of the Control Allocation for Overactuated eVTOL Aircraft in Transition Flight market from 2026 to 2034?
The market is expected to expand at a 21.3% CAGR over 2026–2034.
Which region leads the Control Allocation for Overactuated eVTOL Aircraft in Transition Flight market?
North America holds the largest market position in 2025 based on the demand, supplier and adoption structure described in this analysis.
What are the main product or service types?
The main types are Model-Based Allocation, Data-Driven Allocation, Hybrid Allocation.
What are the key applications?
Key applications include Urban Air Mobility (UAM) Services, Air-Taxi Operations, Emergency Response Platforms, Others.
What is a major growth driver?
As OEMs move from prototypes toward type certification, transition-flight control must be documented, verified and flight-tested. This converts control allocation from research code into a funded safety-critical engineering workstream.
What is a major restraint?
Safety-critical control software requires extensive requirements traceability, verification and flight evidence. Novel learning-based methods face additional assurance challenges.
Where are the strongest opportunities?
Using physics-based allocation with adaptive health estimation or disturbance prediction can improve robustness without making the full control chain opaque.
Which companies are active in the market?
Companies profiled include Joby Aviation, Lilium GmbH, Archer Aviation, Beta Technologies, Volocopter, EHang, Vertical Aerospace, Wisk Aero.
Research Sources & Evidence Base
View supporting primary and technical sources
- Federal Aviation Administration: Integration of Powered-Lift final rule — U.S. powered-lift operating and certification framework.
- European Union Aviation Safety Agency: Special Condition for VTOL and Means of Compliance — VTOL certification requirements and means of compliance.
- European Union Aviation Safety Agency: Innovative Air Mobility regulatory framework — 2025 operational guidance for manned VTOL-capable aircraft.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF