Key Statistics
Key Takeaways
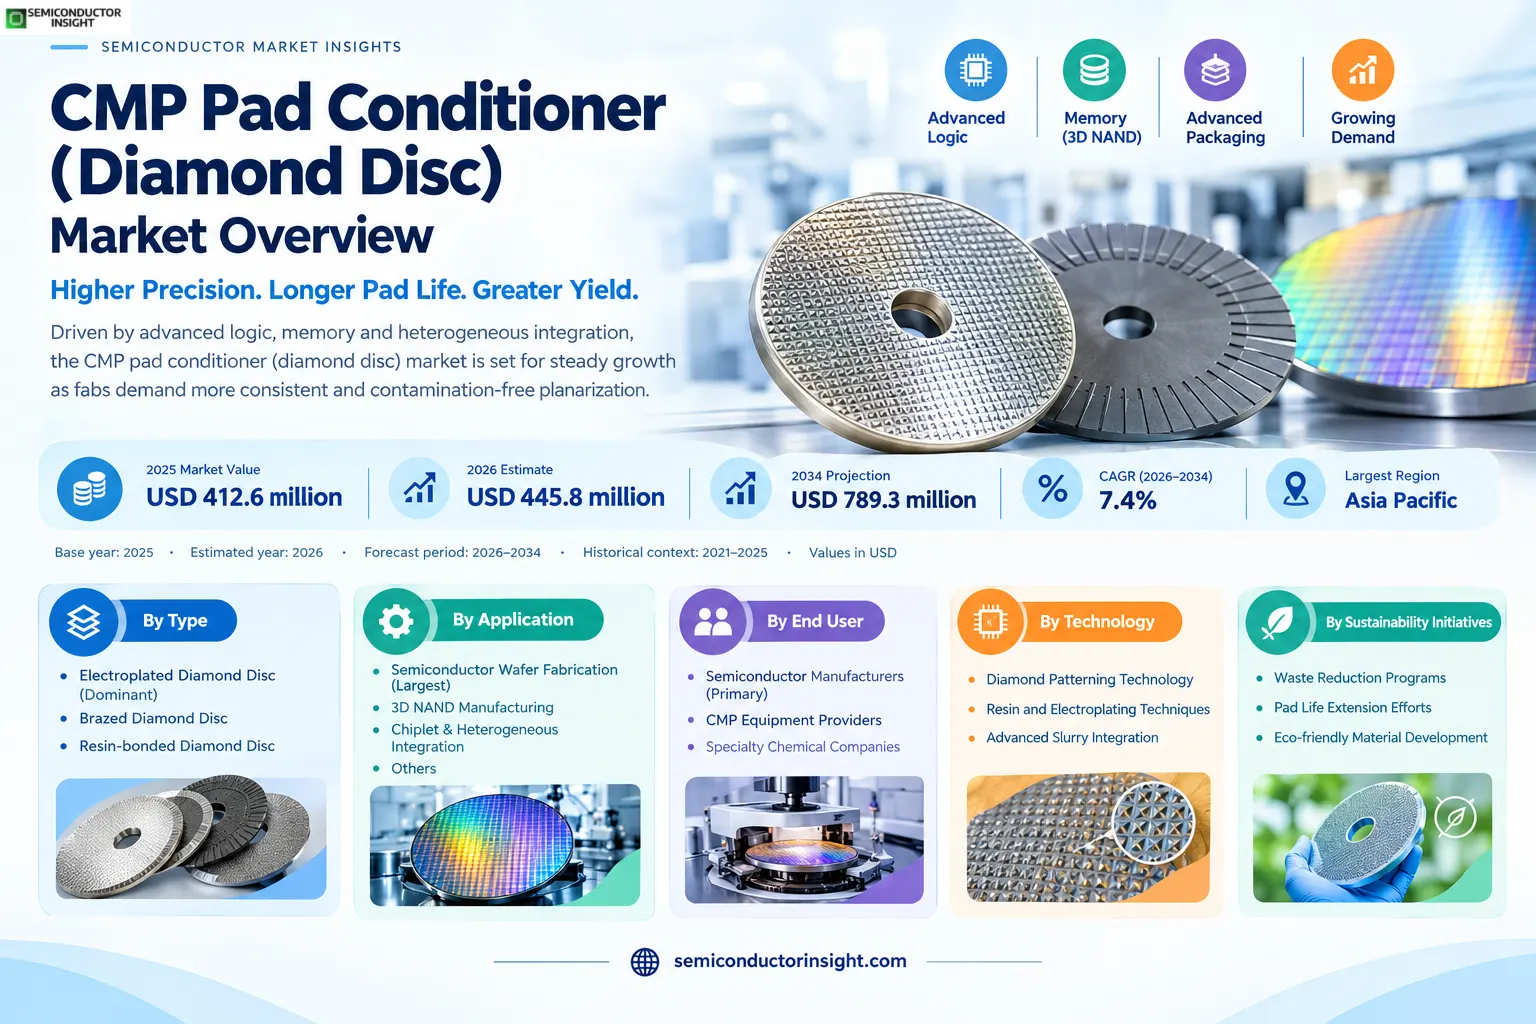
- Market value: revenue is estimated at USD 445.8 million in 2026 and is projected to reach USD 789.3 million by 2034, a CAGR of 7.4% over 2026–2034.
- Electroplated diamond discs remain the dominant type because they offer established manufacturing economics, controllable diamond exposure and broad compatibility across common CMP pad conditions.
- Chiplet, heterogeneous integration and advanced 3D NAND are the fastest-moving application drivers because they increase the number and diversity of planarization steps and tighten uniformity and defect-control requirements.
- Asia Pacific leads the market through its dense concentration of foundry, DRAM and NAND manufacturing, supported by continuing advanced-node and high-layer-count memory investment.
- Conditioner performance is increasingly measured through total CMP cost of ownership, including pad life, defectivity, metal contamination, conditioning consistency and maintenance downtime rather than disc price alone.
- Pad-life extension is both an opportunity and a restraint: longer-lasting, lower-defect conditioners can gain share, but better pads and slurries can reduce replacement frequency for conventional diamond discs.
CMP Pad Conditioner (Diamond Disc) Market Overview
CMP pad conditioner (diamond disc) market was valued at USD 412.6 million in 2025, is estimated at USD 445.8 million in 2026, and is projected to reach USD 789.3 million by 2034, representing a CAGR of 7.4% during 2026–2034. Asia Pacific is the largest regional market because Taiwan, South Korea, Japan and China contain the highest concentration of advanced logic and memory wafer fabrication requiring recurring CMP consumables.
A CMP pad conditioner is a precision consumable used to restore and control the surface texture of the polishing pad during chemical mechanical planarization. Diamond discs cut, open and refresh the pad asperities so slurry can distribute consistently and the wafer experiences a stable material-removal rate across repeated polishing cycles. The market covers electroplated, brazed and resin-bonded diamond configurations, along with related patterning and bonding approaches that tune diamond density, protrusion, orientation and retention for specific pad and slurry combinations.
Demand is driven by wafer starts and by CMP steps per wafer. Advanced logic, high-layer-count NAND and heterogeneous integration require repeated planarization of dielectric and metal films, and each step places different demands on pad texture, removal rate and defectivity. SK hynix began mass production of 321-layer NAND in 2024 and expanded to 321-layer QLC production in 2025, illustrating how memory architectures are becoming more vertically complex. The resulting process complexity supports demand for more controlled pad conditioning and application-specific disc designs.
The commercial decision is increasingly based on total process economics rather than disc purchase price. A conditioner that maintains stable cutting behavior can extend pad life, reduce process drift and lower the frequency of maintenance interventions. At the same time, contamination control is becoming more important. 3M states that its CMP pad-conditioner coatings can reduce metal leaching into slurry or wafers by up to 99% in sensitive processes. This shows how conditioner design is evolving from simple abrasion toward integrated defect and contamination management.
Segment Analysis: By Type
By type, the market is segmented into Electroplated Diamond Disc, Brazed Diamond Disc and Resin-bonded Diamond Disc. Electroplated discs remain the dominant type because the format is well established in semiconductor CMP and can provide controlled diamond distribution and aggressive pad cutting. Brazed and resin-bonded variants compete where diamond retention, corrosion behavior, pad compatibility or conditioning aggressiveness require a different bonding architecture.
| Type | Configuration | Market position |
|---|---|---|
| Electroplated Diamond Disc | Diamond abrasive is fixed to the carrier through an electroplated metal layer, allowing control of grit size, density and exposure. | Dominant type. Broad process familiarity and manufacturing scalability make electroplated discs a standard choice. Competitive differentiation comes from diamond placement, protrusion control, flatness and coating technologies that reduce contamination. |
| Brazed Diamond Disc | Diamond particles are metallurgically bonded at elevated temperature, supporting strong retention and durable cutting points. | Used where robust diamond retention and aggressive conditioning are valued. The format can support demanding pad applications but must be optimized carefully for cutting uniformity and defect risk. |
| Resin-bonded Diamond Disc | Diamond particles are held in a polymeric or resin matrix that can tune compliance and abrasive exposure. | A more application-specific segment. Resin systems can be engineered for gentler conditioning or specialized pad interactions, creating opportunities where defect reduction and controlled pad wear outweigh maximum aggressiveness. |
Conditioner economics are shifting toward process consistency
The conditioner is a small item within total fab cost, but its influence on pad performance and wafer defectivity can be much larger than its purchase price. Suppliers therefore compete on repeatability, diamond retention, flatness, contamination control and the stability of cut rate over disc life. 3M’s product portfolio illustrates this shift: the company markets controlled diamond placement, metal-free or coated surfaces, and designs intended to extend pad and disc life. These features are evaluated through lower downtime and more stable CMP rather than through abrasive cost alone.
Segment Analysis: By Application
By application, the market is segmented into Semiconductor Wafer Fabrication, 3D NAND Manufacturing, Chiplet and Heterogeneous Integration, and Others. Conventional wafer fabrication remains the largest demand base, while 3D NAND and heterogeneous integration are increasing conditioner intensity because they introduce more planarization steps, diverse materials and tighter local-uniformity requirements.
| Application | Demand characteristics |
|---|---|
| Semiconductor Wafer Fabrication | The core application covers CMP steps used in logic, memory and specialty-device manufacturing. Demand is recurring because conditioners are wear consumables and because pad performance must be maintained continuously during production. Purchasing criteria center on removal-rate stability, pad life, defectivity and compatibility with established slurry and pad sets. |
| 3D NAND Manufacturing | High layer counts increase structural complexity and can expand the number and difficulty of CMP operations. SK hynix has moved 321-layer NAND into mass production, highlighting the continued vertical scaling that drives more stringent control of planarization uniformity, pad texture and conditioner lifetime. |
| Chiplet and Heterogeneous Integration | Advanced packaging and integration involve multiple materials, fine topography and tight coplanarity requirements. Conditioner suppliers must support different dielectric and metal CMP steps while controlling scratching and contamination. This application is gaining strategic importance as AI and HPC systems adopt more complex integration architectures. |
| Others | Includes specialty wafer processing, hard-disk or substrate polishing and related precision planarization uses. Volumes are smaller than mainstream semiconductor CMP, but specialized pads and materials can support premium customized conditioner designs. |
Segment Analysis: By End User
| End User | Purchasing priorities |
|---|---|
| Semiconductor Manufacturers | Yield, defectivity, pad life, stable removal rate, contamination control and qualified multi-site supply. |
| CMP Equipment Providers | Integration compatibility, tool mechanics, process repeatability and joint customer qualification. |
| Specialty Chemical Companies | Co-optimization with slurry and pad chemistry, test access and application development. |
Segment Analysis: By Technology
| Technology | Commercial role |
|---|---|
| Diamond Patterning Technology | Controls abrasive spacing, protrusion and orientation so conditioning aggressiveness and uniformity can be tuned for the pad and process. |
| Resin and Electroplating Techniques | Determine how diamond is retained, how the disc interacts with slurry chemistry and how wear progresses through product life. |
| Advanced Slurry Integration | Co-optimization of conditioner, pad and slurry is becoming more important as harsh chemistries, metal sensitivity and new materials alter conditioning behavior. |
Segment Analysis: By Sustainability Initiatives
| Initiative | Market relevance |
|---|---|
| Waste Reduction Programs | Longer pad and conditioner life can reduce consumable waste and maintenance frequency without sacrificing process control. |
| Pad Life Extension Efforts | Suppliers increasingly design conditioners to preserve pad texture while reducing unnecessary pad removal, lowering total CMP operating cost. |
| Eco-friendly Material Development | Material selection and surface treatments are being refined to reduce contamination, improve durability and support semiconductor sustainability targets. |
Regional Analysis
Asia Pacific is the largest market because it contains the world’s deepest concentration of advanced logic, DRAM and NAND production. North America is a high-value technology and capacity-expansion market, Europe is driven by specialty semiconductors and equipment expertise, while South America and the Middle East & Africa remain smaller demand pools linked mainly to emerging electronics and semiconductor investment.
How does regional demand differ across the cmp pad conditioner (diamond disc) market?
CMP pad conditioner demand is more geographically concentrated than many electronic-component markets because it follows wafer fabrication rather than end-device consumption. A region can consume large numbers of smartphones without creating meaningful local conditioner demand if the wafers are fabricated elsewhere. Asia Pacific therefore dominates through production intensity. North America is gaining importance as new advanced fabs are built, and Europe supports a smaller but technologically demanding base of logic, power, analog and specialty semiconductor manufacturing.
| Region | Position | Growth outlook | Demand profile | Supplier selection factors |
|---|---|---|---|---|
| Asia Pacific | Largest | Strongest | Foundry + memory manufacturing | Fab qualification, local support, yield performance |
| North America | High-value | Strong | Advanced logic and new fab expansion | Performance, IP, domestic supply assurance |
| Europe | Established niche | Steady | Specialty and power semiconductors | Process compatibility, quality, technical service |
| South America | Small | Selective | Limited local wafer fabrication | Landed cost and service |
| Middle East & Africa | Nascent | Long-term opportunity | Emerging technology investment | Technical capability and project support |
Key CMP Pad Conditioner (Diamond Disc) Manufacturers and Competitive Landscape
The competitive landscape combines global materials companies with specialized diamond-tool and CMP-conditioner manufacturers. Product differentiation is increasingly based on abrasive placement, diamond retention, substrate flatness, corrosion resistance and contamination control. Because conditioner behavior can affect pad life and wafer defectivity, suppliers that can demonstrate stable process results and provide fab-side application engineering have a stronger position than suppliers competing only on disc price.
3M is a major global participant with a broad portfolio spanning diamond, microreplicated and flexible pad conditioners. Its published product information emphasizes controlled diamond placement, long pad and disc life and optional coatings intended to reduce metal leaching by up to 99% in sensitive processes. This illustrates the direction of competition: conditioner suppliers are adding surface engineering and contamination-control features that address yield risk, not just abrasion.
Specialized companies such as Shinhan Diamond, Brakey Industries, CPMC Global, Kado Diamond Technologies and other diamond-tool firms compete through custom disc geometries, bonding methods and responsiveness to specific pad or process requirements. These suppliers can be attractive where a fab or equipment partner needs rapid iteration, but qualification depth and global supply consistency determine whether a niche design can scale across multiple sites.
Entegris and other semiconductor-material platforms can compete through broader process relationships, especially when customers are optimizing pads, slurries, filtration and contamination control together. As CMP becomes more integrated with advanced packaging and new materials, cross-product application knowledge may become as important as abrasive manufacturing capability.
Tier structure
| Competitive tier | Representative participants | Basis of competition |
|---|---|---|
| Tier 1: Global CMP technology suppliers | 3M Company; Entegris Inc.; Sumitomo Electric | Global fab relationships, IP, qualification depth, product breadth |
| Tier 2: Diamond-conditioner specialists | Shinhan Diamond; Brakey Industries; CPMC Global; Kado Diamond Technologies; Meister Diamond | Custom patterning, bonding know-how, application flexibility |
| Regional / niche suppliers | Mearsk Abrasives; Carat Diamond Tools; NH Diamond Tech; Flashpad Solutions; other specialists | Price, responsiveness, niche process optimization |
Key companies profiled
3M Company, Entegris Inc., Shinhan Diamond Co., Ltd., Brakey Industries, CPMC Global, Mearsk Abrasives, Sumitomo Electric, Kado Diamond Technologies, Meister Diamond, Carat Diamond Tools, NH Diamond Tech, Flashpad Solutions, Diamond Innovations, TechniPad Systems, Premium Pads Inc..
CMP Pad Conditioner (Diamond Disc) Production Capacity Analysis
Pad-conditioner capacity is determined by precision manufacturing rather than bulk abrasive availability. Producers must prepare carriers with tight flatness, place or retain diamond within controlled protrusion ranges, apply bonding or plating layers, and inspect the finished surface for distribution and defects. A plant can have sufficient nominal disc output yet still be constrained by yield on advanced products where diamond placement, metal contamination or flatness specifications are more demanding. Metrology capacity and process-control discipline are therefore part of true usable capacity.
Demand-side capacity is closely tied to 300mm wafer manufacturing. SEMI’s Q3 2026 300mm Fab Outlook states that global 300mm front-end fab equipment spending is projected to reach USD 149 billion in 2026, while installed 300mm capacity is expected to increase. More installed wafer capacity creates recurring demand for pads, slurry and conditioners after fabs enter production. Advanced logic and memory are particularly important because they use many CMP steps and maintain tighter planarization and defect-control limits.
Upstream supply risk is concentrated in synthetic diamond quality, carrier materials, plating or brazing chemistry, precision machining and specialized coatings. The market is not primarily constrained by raw diamond tonnage; it is constrained by the ability to make consistent engineered abrasive surfaces and qualify them in production. This favors suppliers with vertically controlled manufacturing, strong metrology and redundant production sites, especially as fabs ask for business-continuity plans for critical consumables.
CMP Pad Conditioner (Diamond Disc) Market Dynamics: Drivers, Restraints and Opportunities
Market growth is anchored by semiconductor wafer-capacity expansion and by the increasing number of CMP-sensitive layers in advanced logic, memory and heterogeneous integration. At the same time, suppliers must offset a structural counterforce: better pads, slurries and conditioner designs can extend consumable life. The strongest commercial position comes from improving process stability enough that customers accept a premium based on lower defectivity and maintenance cost.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | Impact | Time horizon |
|---|---|---|
| Advanced logic and memory wafer capacity | High | 2026–2034 |
| Higher CMP step count in 3D NAND and heterogeneous integration | High | 2026–2034 |
| Fab focus on lower defectivity and contamination | Medium-High | 2026–2034 |
Advanced wafer-fab investment expands the recurring consumables base
SEMI’s 300mm outlook shows continued investment in wafer fabs, and TSMC is expanding 3nm and 2nm manufacturing across multiple regions. Once a fab enters production, CMP conditioners become recurring consumables tied to wafer starts and polishing-tool utilization. This makes the installed base of active CMP tools more important than one-time fab construction spending. Suppliers with qualified products on major tool platforms can benefit for years from replacement demand.
3D NAND layer growth increases planarization complexity
SK hynix has moved 321-layer NAND into mass production, demonstrating the industry’s continued vertical scaling. More complex structures require repeated deposition, etch and planarization operations, which increases the importance of controlled pad texture and stable conditioning. The commercial opportunity is not simply more discs per wafer; it is greater willingness to pay for conditioners that hold process performance across long runs and reduce excursions in complex memory flows.
Contamination and defect control raise the value of engineered conditioner surfaces
As device geometries and yield targets tighten, metal leaching, diamond shedding and scratch generation become more expensive. 3M markets pad-conditioner coatings that can reduce metal leaching by up to 99%, showing that contamination control has become a product differentiator. This supports premium designs that combine abrasive performance with protective coatings, improved carriers and more precise diamond placement.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | Impact | Time horizon |
|---|---|---|
| Longer pad and conditioner lifetimes reduce replacement frequency | Medium-High | Persistent |
| High qualification cost and fab-specific process dependence | High | Persistent |
| Alternative conditioning approaches and improved slurry chemistry | Medium | Long-term |
Consumable-life extension can moderate unit-volume growth
The same innovation that makes advanced conditioners attractive can reduce replacement frequency. Better diamond retention, slower cut-rate decay and longer pad life lower total fab cost but can also mean fewer discs consumed per tool-year. Suppliers therefore need to capture more value per unit through performance differentiation rather than relying only on rising wafer starts.
Fab qualification is slow and application-specific
A conditioner interacts with the pad, slurry, tool head and process recipe. Changing the abrasive pattern or bonding system can alter cut rate, pad texture, wafer defects and removal-rate stability. Customers therefore require extended qualification before changing suppliers or disc designs. This creates a barrier to entry and can delay adoption of new products even when laboratory results are attractive.
Improved pads, slurries and nontraditional conditioning create substitution risk
Advanced pad materials and slurry formulations can extend pad life or reduce the aggressiveness required from mechanical conditioning. Flexible or non-diamond conditioning concepts may also address specific defect issues. These technologies will not eliminate diamond discs across mainstream CMP, but they can reduce usage in selected steps and force conventional conditioner suppliers to keep improving total process economics.
MARKET OPPORTUNITIES
Metal-sensitive and low-defect CMP processes
Advanced nodes and new materials create applications where metal contamination and scratching are particularly costly. Protective coatings, metal-free cutting surfaces and improved diamond retention can command premium pricing if they demonstrate better wafer defectivity without sacrificing pad activation. This opportunity is strongest in processes using harsh slurries or sensitive metal and dielectric stacks.
Conditioners optimized for high-layer-count NAND
Memory manufacturers need stable conditioning across long, complex process flows. Suppliers can develop disc patterns and bonding systems tailored to specific pad and slurry combinations used in advanced 3D NAND. Co-development with memory fabs creates a defensible position because process knowledge and qualification history are difficult for competitors to replicate quickly.
Heterogeneous integration and advanced packaging CMP
Chiplets, hybrid bonding and advanced packaging introduce new topographies and material combinations that require tight coplanarity. Conditioner suppliers can expand beyond conventional front-end steps by supporting copper, dielectric and specialty CMP used in packaging flows. The opportunity favors vendors that can work across equipment, pad and slurry partners to tune the full process window.
Regional technical-service expansion near new fabs
New wafer fabs in the United States, Europe and Japan create demand for local qualification and rapid troubleshooting. Establishing regional application labs, refurbishment capability or dedicated inventory can reduce customer risk and shorten response times. For a consumable tied to yield, local support can become a meaningful differentiator even when the disc itself is manufactured elsewhere.
CMP Pad Conditioner (Diamond Disc) Supply Chain Analysis
Value capture concentrates in engineering and qualification. Synthetic diamond is essential, but raw abrasive alone does not determine performance. Diamond spacing, protrusion, carrier flatness, surface coatings and the stability of those features over product life determine how the conditioner changes pad texture. Suppliers that control these variables and support customer experiments can charge for process value rather than commodity abrasive content.
The supply chain is also sensitive to business-continuity requirements. Fabs prefer qualified backup sources, but dual-sourcing is difficult because two conditioners rarely behave identically without recipe adjustment. This makes supplier manufacturing redundancy, lot traceability and regional inventory important. A disruption in a qualified conditioner can force a customer to consume safety stock or requalify an alternate product under time pressure, creating incentives for long-term supply agreements.
Recent Developments in the CMP Pad Conditioner (Diamond Disc) Market
SEMI projects global 300mm front-end fab equipment spending of USD 149 billion in 2026 and continued capacity growth. New production capacity expands the installed base of CMP tools and supports recurring consumption of pads, slurries and conditioners once fabs ramp. Source: SEMI
SK hynix announced mass production of a 321-layer 2Tb QLC NAND device. Higher layer counts and denser memory architectures increase process complexity and reinforce the need for stable planarization and pad conditioning across advanced NAND manufacturing. Source: SK hynix
TSMC reported that its 2nm process entered high-volume manufacturing in 4Q25 and expects a fast ramp in 2026. Advanced logic scaling increases the process-control burden on CMP steps and raises the value of conditioners with tightly controlled abrasive behavior and contamination performance. Source: TSMC
SK hynix announced mass production of the first 321-high 4D TLC NAND, marking another step in vertical memory scaling. This supports the long-term demand case for CMP consumables used to maintain uniformity through increasingly complex memory process flows. Source: SK hynix
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| By Type | Electroplated Diamond Disc; Brazed Diamond Disc; Resin-bonded Diamond Disc |
| By Application | Semiconductor Wafer Fabrication; 3D NAND Manufacturing; Chiplet and Heterogeneous Integration; Others |
| By End User | Semiconductor Manufacturers; CMP Equipment Providers; Specialty Chemical Companies |
| By Technology | Diamond Patterning Technology; Resin and Electroplating Techniques; Advanced Slurry Integration |
| By Sustainability Initiatives | Waste Reduction Programs; Pad Life Extension Efforts; Eco-friendly Material Development |
| Regions | North America; Europe; Asia Pacific; South America; Middle East & Africa |
| Companies profiled | 3M Company; Entegris Inc.; Shinhan Diamond Co., Ltd.; Brakey Industries; CPMC Global; Mearsk Abrasives; Sumitomo Electric; Kado Diamond Technologies; Meister Diamond; Carat Diamond Tools; NH Diamond Tech; Flashpad Solutions; Diamond Innovations; TechniPad Systems; Premium Pads Inc. |
Frequently Asked Questions
What is the size of the CMP Pad Conditioner (Diamond Disc) market?
The market was valued at USD 412.6 million in 2025, is estimated at USD 445.8 million in 2026, and is projected to reach USD 789.3 million by 2034, representing a CAGR of 7.4% during 2026–2034.
Which region leads the market?
Asia Pacific leads because Taiwan, South Korea, Japan and China contain the highest concentration of foundry, DRAM and NAND wafer fabrication.
Which type is dominant?
Electroplated diamond discs remain the dominant type because they are widely used, scalable to manufacture and can provide controlled abrasive placement and cut behavior.
What does a CMP pad conditioner do?
It restores and controls polishing-pad surface texture so slurry distribution and material-removal rate remain stable through repeated CMP cycles.
Which applications are covered?
The report covers Semiconductor Wafer Fabrication, 3D NAND Manufacturing, Chiplet and Heterogeneous Integration, and Others.
Why does 3D NAND support market growth?
Higher NAND layer counts increase structural complexity and the number and difficulty of planarization operations, raising the need for stable pad conditioning and defect control.
What are the main purchasing criteria?
Fabs evaluate removal-rate stability, pad life, defectivity, diamond retention, contamination control, carrier flatness, qualification history and supply continuity.
What are the main restraints?
Key restraints include longer consumable lifetimes, slow fab qualification and substitution from improved pads, slurries or alternative conditioning approaches.
How is sustainability influencing product development?
Suppliers are working to extend pad and disc life, reduce material waste, lower contamination and improve process stability so fewer consumables and maintenance interventions are required.
Which companies are profiled?
The profiled list includes 3M Company, Entegris, Shinhan Diamond, Brakey Industries, CPMC Global, Sumitomo Electric, Kado Diamond Technologies and other specialized suppliers.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF