Key Statistics
Key Takeaways
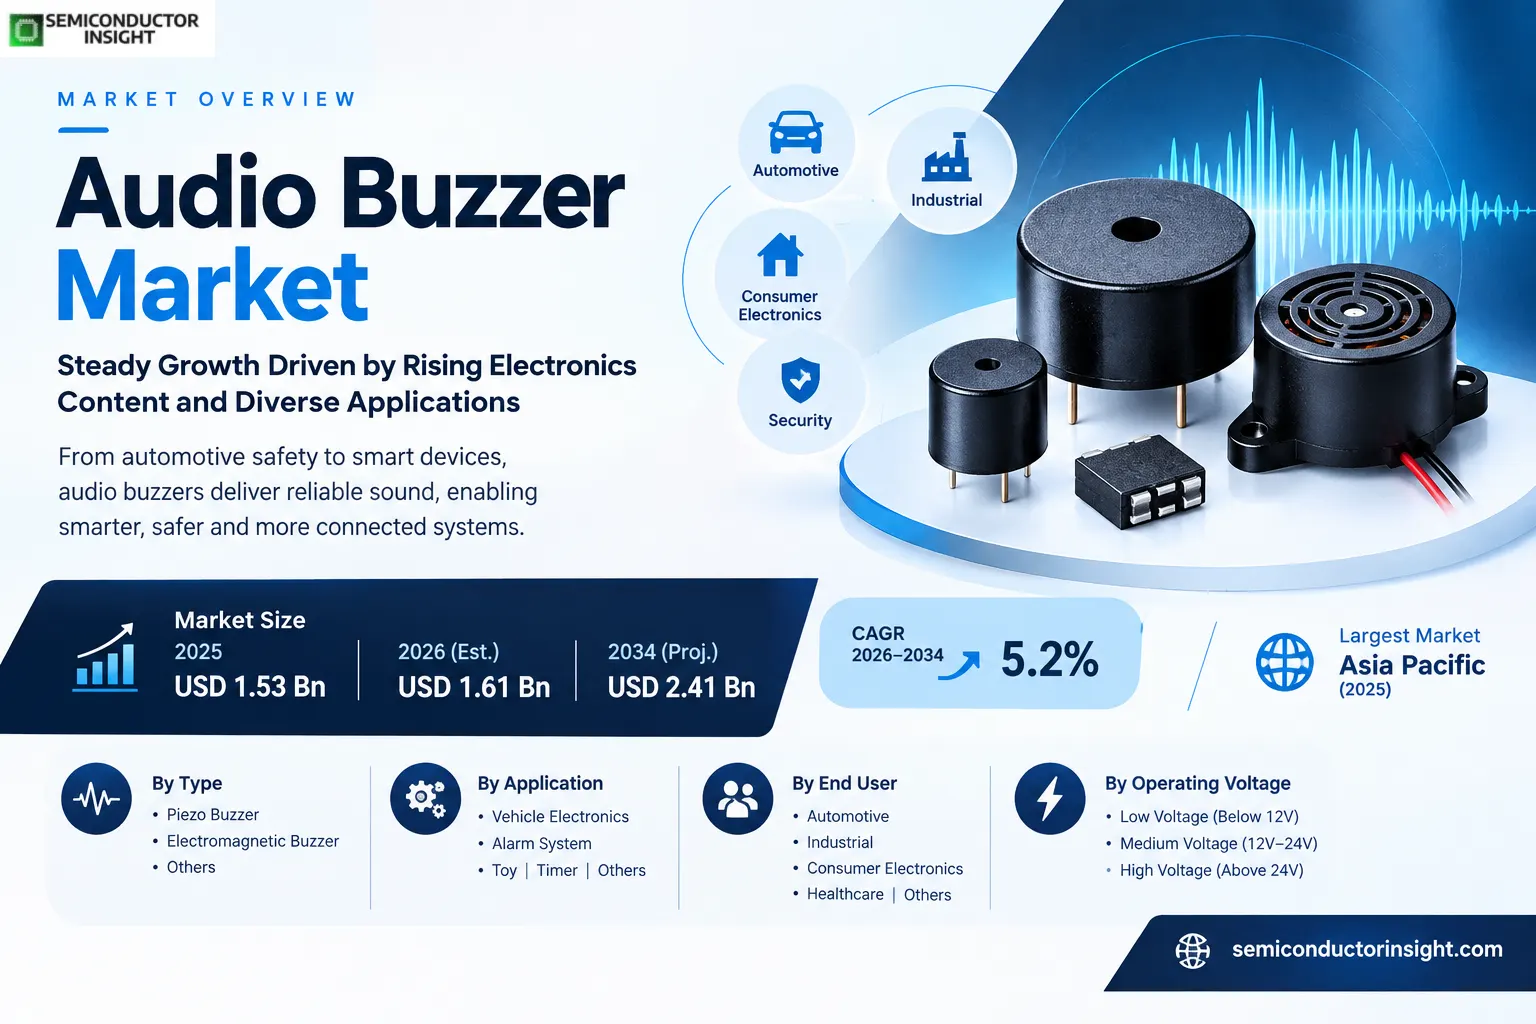
- Market size: the Audio Buzzer market was valued at USD 1.53 billion in 2025 and is projected to reach USD 2.41 billion by 2034, representing a 5.2% CAGR over 2026–2034.
- Piezo Buzzer has the strongest current type position because piezoelectric designs combine low power, compact size and compatibility with high-density electronics assembly.
- Vehicle Electronics is the most commercially important application because vehicle electronics use audible warnings across safety, convenience and driver-information systems, creating a broad and durable demand base.
- Asia Pacific is the largest regional market in 2025; regional expansion depends on the local mix of installed infrastructure, regulation, manufacturing capability and customer investment.
- Competitive differentiation increasingly depends on application engineering, qualification support and lifecycle reliability rather than price alone.
Audio Buzzer Market Overview
Audio Buzzer market was valued at USD 1.53 billion in 2025 and is estimated at USD 1.61 billion in 2026. It is projected to reach USD 2.41 billion by 2034, registering a 5.2% CAGR over 2026–2034. Asia Pacific held the largest market position in 2025.
Audio buzzers are compact electroacoustic signaling components that convert electrical input into audible tones for alarms, status indication and user feedback. Piezoelectric designs use a ceramic element and are favored for low power, thin profiles and high-frequency output, while electromagnetic designs use coils and diaphragms to deliver strong sound pressure in robust packages. The category spans pin-terminal and surface-mount formats, with selection governed by frequency, sound-pressure level, voltage, temperature range and mounting method.
Demand is broad rather than dependent on a single end market. Automotive electronics use buzzers for warnings and user notifications, industrial equipment requires audible machine-status and fault signals, and appliances, smart meters and security devices use low-cost sounders for local feedback. TDK and Murata product portfolios illustrate how manufacturers compete across package size, sound pressure, drive method and operating-temperature requirements rather than through one universal specification.
The market is mature but still expands as electronics content rises in vehicles, equipment and connected devices. Miniaturization and surface-mount assembly favor compact piezo solutions, while harsh-environment and high-sound-pressure applications sustain electromagnetic products. Lifecycle management is increasingly important because OEMs qualify specific acoustic behavior and package footprints; end-of-life notices can trigger redesign work even when replacement components appear technically similar.
Segment Analysis: By Type
By type, the market is segmented into Piezo Buzzer, Electromagnetic Buzzer, Others. Piezo Buzzer has the strongest current position, while the remaining categories compete on performance, integration effort, lifecycle economics and customer qualification requirements.
| Type | Function / role | Market position |
|---|---|---|
| Piezo Buzzer | Ceramic vibration element produces tone with low current draw. | Largest segment; strong fit for compact SMD and low-power products. |
| Electromagnetic Buzzer | Coil-driven diaphragm provides robust audible output. | Important in automotive and industrial products that value sound pressure and ruggedness. |
| Others | Mechanical or application-specific sounders. | Niche demand tied to legacy or specialized acoustic requirements. |
Commercial implications by type
Product economics depend on acoustic performance, package size and qualification. Piezo devices benefit from miniaturization and simpler power requirements, while electromagnetic units remain relevant where higher sound pressure, familiar drive circuits or rugged mechanical behavior matter. Suppliers must manage product lifecycles carefully because changing a buzzer can alter perceived tone, loudness, board layout and regulatory testing at the customer level.
Segment Analysis: By Application
By application, the market is segmented into Vehicle Electronics, Alarm System, Toy, Timer, Others. Purchasing behavior differs materially by use case because performance thresholds, duty cycles, safety requirements and integration costs vary across end systems.
| Application | Demand characteristics |
|---|---|
| Vehicle Electronics | Automotive warning functions require reliable sound output across temperature and vibration, making qualification and lifecycle support central. |
| Alarm System | Security and building alarms value audibility, reliability and low standby power, with demand spread across commercial and residential systems. |
| Toy | Toys use low-cost compact buzzers where simple tones and high-volume manufacturing dominate purchasing. |
| Timer | Timers and appliances favor established footprints, low cost and predictable acoustic output over feature complexity. |
| Others | Medical, metering and specialty products create smaller niches with stricter reliability or acoustic requirements. |
By End User
The by end user view is segmented into Automotive, Industrial, Consumer Electronics, Healthcare, Others. Automotive and industrial buyers place greater weight on qualification and temperature range, while consumer electronics emphasizes size, cost and automated assembly.
By Operating Voltage
The by operating voltage view is segmented into Low Voltage (Below 12V), Medium Voltage (12V–24V), High Voltage (Above 24V). Low-voltage devices dominate modern electronics because most embedded systems run from low-voltage DC rails; higher-voltage variants remain useful in industrial and legacy equipment.
Regional Analysis
Asia Pacific leads the Audio Buzzer market in 2025. The regional structure is not uniform: adoption reflects differences in end-market scale, qualification requirements, manufacturing ecosystems, regulation and customer access rather than one global purchasing pattern.
How does regional demand differ across the Audio Buzzer market?
Regional demand should be read through the local deployment mechanism. Mature markets usually place more weight on qualification, regulation and replacement cycles, while faster-growing markets are shaped by new capacity, infrastructure build-out and rising local production. Supplier strategy therefore differs by region: channel depth and compliance may matter more than low price in mature markets, while local engineering and availability can decide share in expansion markets.
| Region | Position | Growth outlook | Demand profile | Supplier-selection factor |
|---|---|---|---|---|
| Asia Pacific | Largest | Strong | Manufacturing-led | Cost, scale, supplier density |
| North America | Large | Moderate | Automotive and industrial | Qualification, distribution |
| Europe | Large | Moderate | Automotive and machinery | Compliance, reliability |
| South America | Emerging | Moderate | Imported components | Landed cost, availability |
| Middle East & Africa | Emerging | Moderate | Security and infrastructure | Distribution, durability |
Competitive Landscape
The market combines global component specialists, Japanese materials leaders and numerous Asian high-volume manufacturers. Competition is fragmented because application requirements differ by voltage, mounting method, tone and environmental rating, allowing both broad-line suppliers and niche acoustic specialists to maintain defensible positions.
TDK and Murata compete through materials expertise, detailed acoustic specifications and broad technical documentation. Their portfolios illustrate the shift toward compact SMD and carefully characterized piezoelectric sounders for dense electronics designs.
CUI Devices, Kingstate, BeStar and other specialists compete on catalog breadth, customization, lead time and distribution. For many OEMs, access to samples and consistent acoustic behavior across production lots are as important as nominal electrical specifications.
Lifecycle management is a growing strategic issue. TDK product records show several electromagnetic buzzer part numbers with end-of-life schedules extending into 2027, which can create replacement-design activity and opportunities for alternative suppliers.
| Company | Positioning | Competitive relevance |
|---|---|---|
| CUI Devices | Established / platform leader | Broad buzzer portfolio and distributor access support design-in activity across industrial and consumer electronics. |
| TDK Corporation | Established / specialist | Materials and component expertise supports compact piezo and electromagnetic technologies with detailed qualification data. |
| Murata Manufacturing | Established / specialist | Strong piezoelectric sounder portfolio and miniaturized SMD offerings support consumer and industrial applications. |
Companies Profiled
CUI Devices, TDK Corporation, Murata Manufacturing, BeStar Technologies, Kingstate Electronics, Digisound Group, EAO, RAFI GmbH & Co. KG, Seeed Technology, Adafruit Industries, NTE Electronics, Littelfuse, Omron.
Production Capacity Analysis
Buzzer production is concentrated in Asian electronics manufacturing clusters because the supply chain combines piezoelectric ceramics, magnets, copper windings, plastic housings, stamped terminals and high-volume automated assembly. Capacity is relatively scalable compared with semiconductors, but acoustical consistency, ceramic quality and stable assembly processes still differentiate suppliers.
The most important operational risk is product continuity rather than absolute industry capacity. Automotive and industrial customers may qualify a specific footprint and acoustic signature for years, so supplier end-of-life decisions can force redesigns. Manufacturers with flexible production lines and long-term component sourcing can use lifecycle stability as a competitive advantage.
Market Dynamics
The market expands with rising electronics content in vehicles, appliances and industrial equipment, while mature pricing, alternative haptic technologies and product-lifecycle transitions limit value growth. Suppliers win through compact form factors, dependable acoustic performance and reliable availability.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial implication |
|---|---|---|
| Rising electronics content | High | More electronic control functions create more opportunities for local audible feedback in vehicles, appliances, metering and industrial equipment. Each new control interface can require warning, status or confirmation tones. |
| Automotive safety and notification | Medium-High | Vehicles use audible signaling for warnings, parking systems, driver reminders and user interfaces. Automotive qualification requirements also raise the value of durable, traceable components. |
| Miniaturization and SMD assembly | Medium-High | Compact surface-mount piezoelectric sounders fit high-density boards and automated production, supporting adoption in smart devices and connected equipment. |
| Industrial automation | Medium | Machine status, alarms and operator feedback require reliable sounders that can operate across wider temperature and vibration ranges. |
Rising electronics content
More electronic control functions create more opportunities for local audible feedback in vehicles, appliances, metering and industrial equipment. Each new control interface can require warning, status or confirmation tones.
Automotive safety and notification
Vehicles use audible signaling for warnings, parking systems, driver reminders and user interfaces. Automotive qualification requirements also raise the value of durable, traceable components.
Miniaturization and SMD assembly
Compact surface-mount piezoelectric sounders fit high-density boards and automated production, supporting adoption in smart devices and connected equipment.
Industrial automation
Machine status, alarms and operator feedback require reliable sounders that can operate across wider temperature and vibration ranges.
Market Restraints
Restraints Impact Analysis
| Restraint | Impact | Commercial implication |
|---|---|---|
| Haptic and visual substitution | Medium | Some consumer products use vibration motors, speakers or visual indicators instead of dedicated buzzers, limiting demand in applications where multimodal interfaces are preferred. |
| Price competition | High | High-volume buzzers are relatively standardized, exposing suppliers to strong price pressure from regional manufacturers. |
| Acoustic performance trade-offs | Medium | Reducing size while preserving sound-pressure level and tone quality requires careful mechanical design and can constrain miniaturization. |
| Lifecycle discontinuations | Medium | Part end-of-life decisions can disrupt qualified OEM programs and force redesign or revalidation, which makes continuity a purchasing concern. |
Haptic and visual substitution
Some consumer products use vibration motors, speakers or visual indicators instead of dedicated buzzers, limiting demand in applications where multimodal interfaces are preferred.
Price competition
High-volume buzzers are relatively standardized, exposing suppliers to strong price pressure from regional manufacturers.
Acoustic performance trade-offs
Reducing size while preserving sound-pressure level and tone quality requires careful mechanical design and can constrain miniaturization.
Lifecycle discontinuations
Part end-of-life decisions can disrupt qualified OEM programs and force redesign or revalidation, which makes continuity a purchasing concern.
Market Opportunities
Automotive-grade compact buzzers
Electric and increasingly software-defined vehicles still require local audible warnings. Compact products with wide temperature ranges and long lifecycle support can capture value.
Smart meters and building controls
Connected meters and building devices use simple audible feedback while operating from low-voltage rails, favoring efficient piezo sounders.
Medical and safety equipment
Applications where alerts must remain audible and predictable support premium products with documented reliability and consistent sound output.
Application-specific acoustic design
Suppliers can differentiate through custom frequency response, housings and drive circuits for products where acoustic identity or harsh-environment performance matters.
Supply Chain Analysis
Materials
Component fabrication
Module assembly
Distribution / OEM
Piezoelectric materials and mechanical resonator design are the highest-value technical inputs because they determine efficiency, frequency response and size. In electromagnetic products, magnet, coil and diaphragm design drive sound pressure and operating range.
Distribution is strategically important because many design wins start with catalog selection and sampling. Suppliers with accurate online data, available inventory and stable lifecycle policies can win engineering mindshare before high-volume sourcing begins.
Recent Developments
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | Audio Buzzer |
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| Market size | USD 1.53 billion (2025) to USD 2.41 billion (2034) |
| CAGR | 5.2% (2026–2034) |
| Largest market | Asia Pacific |
| By Type | Piezo Buzzer, Electromagnetic Buzzer, Others |
| By Application | Vehicle Electronics, Alarm System, Toy, Timer, Others |
| By End User | Automotive, Industrial, Consumer Electronics, Healthcare, Others |
| By Operating Voltage | Low Voltage (Below 12V), Medium Voltage (12V–24V), High Voltage (Above 24V) |
| Companies profiled | CUI Devices, TDK Corporation, Murata Manufacturing, BeStar Technologies, Kingstate Electronics, Digisound Group, EAO, RAFI GmbH & Co. KG, Seeed Technology, Adafruit Industries, NTE Electronics, Littelfuse, Omron |
Frequently Asked Questions
What is the Audio Buzzer market size in 2025?
The market was valued at USD 1.53 billion in 2025.
What is the projected Audio Buzzer market size by 2034?
The market is projected to reach USD 2.41 billion by 2034.
What is the CAGR of the Audio Buzzer market from 2026 to 2034?
The market is expected to expand at a 5.2% CAGR over 2026–2034.
Which region leads the Audio Buzzer market?
Asia Pacific holds the largest market position in 2025 based on the demand, supplier and adoption structure described in this analysis.
What are the main product or service types?
The main types are Piezo Buzzer, Electromagnetic Buzzer, Others.
What are the key applications?
Key applications include Vehicle Electronics, Alarm System, Toy, Timer, Others.
What is a major growth driver?
More electronic control functions create more opportunities for local audible feedback in vehicles, appliances, metering and industrial equipment. Each new control interface can require warning, status or confirmation tones.
What is a major restraint?
Some consumer products use vibration motors, speakers or visual indicators instead of dedicated buzzers, limiting demand in applications where multimodal interfaces are preferred.
Where are the strongest opportunities?
Electric and increasingly software-defined vehicles still require local audible warnings. Compact products with wide temperature ranges and long lifecycle support can capture value.
Which companies are active in the market?
Companies profiled include CUI Devices, TDK Corporation, Murata Manufacturing, BeStar Technologies, Kingstate Electronics, Digisound Group, EAO, RAFI GmbH & Co. KG.
Research Sources & Evidence Base
View supporting primary and technical sources
- TDK: Piezoelectric Buzzer Selection Guide — product size, sound-pressure and frequency evidence.
- TDK: SD1209T3-A1 electromagnetic buzzer lifecycle record — automotive-grade specifications and lifecycle timing.
- Murata Manufacturing: Piezoelectric Sounders / Buzzers — SMD and pin-type product architecture and applications.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF