Key Statistics
Key Takeaways
- Polyurethane Wire Enamels is a leading product category because it addresses the largest current application base.
- Copper Wires is a major application, with demand shaped by performance, reliability and system integration.
- Asia Pacific leads current market value, while Asia Pacific provides the strongest growth profile.
- Higher-temperature insulation, corona resistance and cleaner high-speed enameling processes is the main technology direction influencing new design wins.
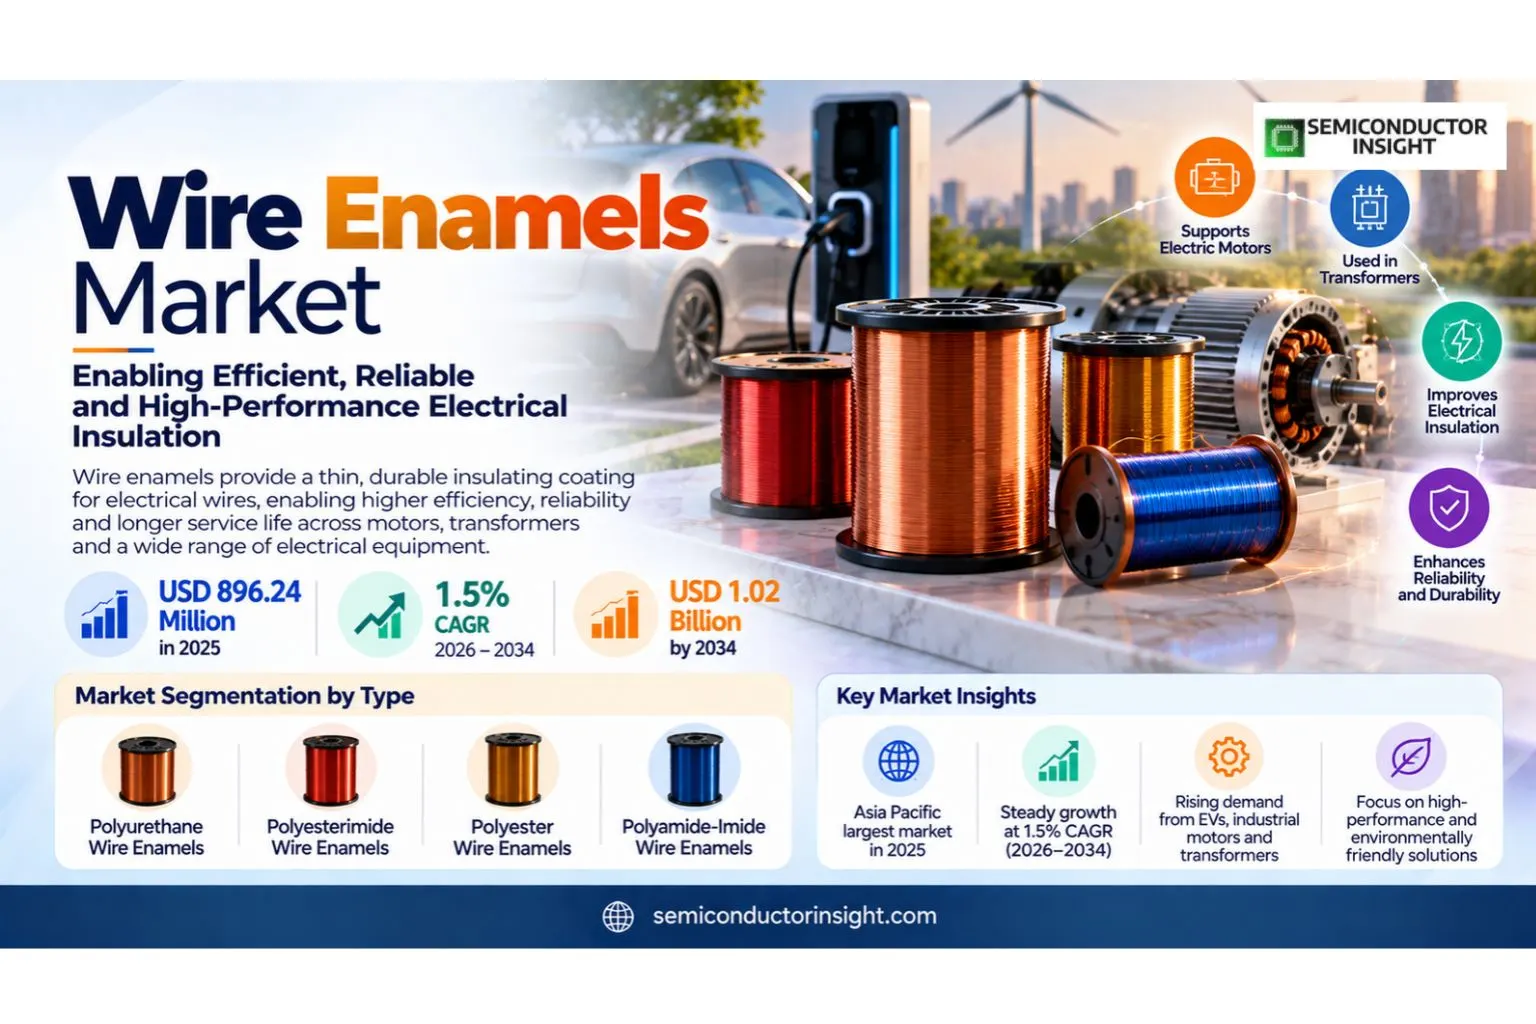
- Market size and growth: USD 896.24 million in 2025 is projected to reach USD 1.02 billion by 2034 at a 1.5% CAGR during 2026–2034.
Wire Enamels Market Overview
Wire enamels market was valued at USD 896.24 million in 2025 and is projected to reach USD 1.02 billion by 2034, growing at a CAGR of 1.5% over the 2026–2034 forecast period. Asia Pacific held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.
The wire enamels market wire enamels are thermally cured insulating varnishes applied directly to copper or aluminum magnet wire used in motors, transformers, generators and electrical equipment. Commercial decisions in the Wire Enamels market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
The market was valued at USD 883 million in 2024 and is projected to reach USD 979 million by 2032. Growth is steady because magnet wire is mature, but product mix is improving as e-mobility and high-efficiency motors require stronger thermal and electrical performance. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
ELANTAS lists polyester, polyesterimide, polyamide-imide, polyimide and polyurethane chemistries, with products designed for thermal resistance, abrasion, winding flexibility, chemical resistance and long service life. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Segment Analysis: By Type
By type, the wire enamels market is segmented into Polyurethane Wire Enamels, Polyesterimide Wire Enamels, Polyester Wire Enamels, Polyamide-Imide Wire Enamels. Each category has a distinct functional role and commercial position, so the analysis emphasizes use case, integration and competitive relevance rather than repeating a single market statistic across every row.
| Type | Function | Market position |
|---|---|---|
| Polyurethane Wire Enamels | Polyurethane Wire Enamels addresses a distinct architecture or performance requirement within the Wire Enamels market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Polyesterimide Wire Enamels | Polyesterimide Wire Enamels addresses a distinct architecture or performance requirement within the Wire Enamels market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Polyester Wire Enamels | Polyester Wire Enamels addresses a distinct architecture or performance requirement within the Wire Enamels market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Polyamide-Imide Wire Enamels | Polyamide-Imide Wire Enamels addresses a distinct architecture or performance requirement within the Wire Enamels market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
Pricing by type
Polyurethane and standard polyester systems compete strongly on price, while polyesterimide, polyamide-imide and specialty corona-resistant coatings command premiums through higher thermal and electrical performance. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Wire Enamels market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Segment Analysis: By Application
By application, the market is segmented into Copper Wires, Aluminum Wires. Application economics differ by qualification, lifecycle, reliability and system-level value, so each row below uses context specific to that application rather than mechanically repeating headline evidence. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
| Application | Demand characteristics |
|---|---|
| Copper Wires | Copper Wires creates demand where wire enamels improves integration, performance, reliability or system economics. |
| Aluminum Wires | Aluminum Wires creates demand where wire enamels improves integration, performance, reliability or system economics. |
Regional Analysis
Asia Pacific leads the wire enamels market because China, Japan, South Korea and Southeast Asia combine the largest magnet-wire production, electric-motor manufacturing and transformer demand. China alone accounts for about 45% of global demand. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
How does regional demand differ across the wire enamels market?
North America and Europe remain important for high-performance insulation systems used in motors, generators, transformers and e-mobility, while Asia Pacific leads both production and consumption volume. Emerging markets add demand through industrialization and grid investment. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Highest in market | Manufacturing led | Cost, thermal class and supply reliability |
| North America | High-value | Moderate | Specialty/e-mobility led | UL recognition and technical support |
| Europe | High-value | Moderate | Automotive/industrial led | REACH, thermal performance and qualification |
| South America | Smaller | Moderate | Industrial/import led | Cost and local distribution |
| Middle East & Africa | Smallest base | Emerging | Infrastructure led | Import availability |
Key Wire Enamels Manufacturers and Competitive Landscape
The competitive landscape includes ELANTAS, Superior Essex, Axalta, TOTOKU TORYO, Kyocera, Hubergroup, Hitachi Chemical heritage suppliers, Taihu, Xianda, regional specialty coating producers. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Wire Enamels market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Competition centers on higher-temperature insulation, corona resistance and cleaner high-speed enameling processes, customer qualification, manufacturing consistency and application support. Once a product is designed into a long-lifecycle system, switching costs can protect incumbent positions but also raise the importance of roadmap continuity. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | ELANTAS, Superior Essex, Axalta, TOTOKU TORYO | Global scale, broad customer qualification and advanced technology portfolios. |
| Tier 2 | Kyocera, Hubergroup, Hitachi Chemical heritage suppliers, Taihu | Strong specialist capability, regional design wins and application-focused portfolios. |
| Tier 3 | Regional and niche suppliers | Cost competition, customization and specialized customer support. |
Key companies profiled
- ELANTAS
- Superior Essex
- Axalta
- TOTOKU TORYO
- Kyocera
- Hubergroup
- Hitachi Chemical heritage suppliers
- Taihu
- Xianda
- regional specialty coating producers
Wire Enamels Production Capacity Analysis
Production capacity in the Wire Enamels market is shaped by the underlying manufacturing process, qualification burden and customer-specific configuration. Suppliers must balance equipment utilization with quality control because high-volume output only creates value when yield, reliability and traceability remain stable. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Capacity additions tend to follow customer program ramps rather than headline market growth alone. Regional supply resilience is becoming more important, particularly where customers require second-source planning, long product lifecycles or shorter engineering-response times. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
The practical bottleneck is often qualified output rather than nominal installed capacity. Manufacturing, assembly, test and application support must scale together to avoid creating capacity that cannot be used in production programs. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Wire Enamels Market Dynamics: Drivers, Restraints and Opportunities
The Wire Enamels market is shaped by growth is driven by energy-efficient motors, renewable-energy generators, transformer demand, industrial automation and electrified vehicle traction systems that require reliable magnet-wire insulation. At the same time, growth is constrained by raw-material and solvent volatility, environmental requirements, price pressure in mature applications and long qualification cycles for insulation-system changes. The strongest commercial opportunities are concentrated in corona-resistant enamels, higher thermal classes, e-mobility traction motors and lower-emission formulations create the strongest value-growth opportunities.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Technology upgrade cycle | +1.6% | Global; strongest in leading adopter markets | Near to medium term |
| End-market expansion | +1.2% | Application-specific | Near term |
| Higher value per system | +0.8% | Premium and advanced systems | Medium term |
Technology adoption expands addressable demand
Growth is driven by energy-efficient motors, renewable-energy generators, transformer demand, industrial automation and electrified vehicle traction systems that require reliable magnet-wire insulation. This demand is strongest where customers can measure a clear improvement in system performance, footprint, energy efficiency, reliability or operating cost. Commercial decisions in the Wire Enamels market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
End-market modernization increases content per system
The technology upgrade cycle supports replacement and redesign activity as OEMs move to higher-performance architectures. New designs typically create the best opportunity because suppliers can influence specifications before qualification is locked. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Higher-value architectures support premium mix
Expanding end markets also increase content per system, creating value growth even when unit shipments grow more slowly. Suppliers that combine engineering support with reliable supply are better positioned to capture those design transitions. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Qualification and integration burden | -0.7% | Global | Ongoing |
| Price and substitution pressure | -0.5% | Cost-sensitive applications | Ongoing |
| Supply-chain or process complexity | -0.4% | Global | Medium term |
Qualification burden slows supplier switching
Growth is constrained by raw-material and solvent volatility, environmental requirements, price pressure in mature applications and long qualification cycles for insulation-system changes. These constraints are most significant where customers have qualified alternatives or where the technology must prove a clear system-level advantage over lower-cost incumbent solutions. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Price competition limits margin expansion
Qualification and integration can extend sales cycles because customers must validate performance, reliability and compatibility in their own system environment. That makes early engineering engagement important for new suppliers. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Alternative technologies constrain selected use cases
Supply-chain complexity can also limit growth when specialized materials, tooling, test or regional support are required. Customers increasingly evaluate resilience alongside price when choosing long-lifecycle suppliers. Commercial decisions in the Wire Enamels market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
MARKET OPPORTUNITIES
Advanced integration creates premium opportunities
Corona-resistant enamels, higher thermal classes, e-mobility traction motors and lower-emission formulations create the strongest value-growth opportunities. The most attractive opportunities are where customers are redesigning systems rather than simply replacing like-for-like components. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Regional capacity and supply resilience
Higher-temperature insulation, corona resistance and cleaner high-speed enameling processes can create premium value when it lowers system complexity, improves performance or supports a new product architecture that is difficult to achieve with incumbent approaches. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Application engineering deepens customer value
Regional engineering support and application-specific customization provide another route to growth because customers increasingly expect suppliers to support qualification, transition planning and lifecycle management. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Wire Enamels Supply Chain Analysis
Upstream. Resins, solvents, additives and high-purity specialty polymers form the upstream material base, followed by formulation, quality testing and supply to magnet-wire producers. Supply quality at this stage directly affects downstream yield, reliability and cost. Commercial decisions in the Wire Enamels market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Manufacturing. Core production combines process control, assembly, inspection and test, with product-specific qualification used to verify performance before customer shipment. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Distribution. High-value programs are typically won through direct OEM, Tier-1 or design-house engagement, while distributors serve prototypes, regional customers and lower-volume applications. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Downstream. End users integrate the product into systems where switching costs rise after qualification, making lifecycle support and supply continuity commercially important. Commercial decisions in the Wire Enamels market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Downstream. Panel builders and machine OEMs are the primary specifying customers, followed by electrical contractors working on building services and by facility maintenance teams handling replacement. The specification decision is usually made once, at panel design, and then repeats for the life of the design — which makes design-in position considerably more valuable than any individual transaction.
Recent Developments in the Wire Enamels Market
Developments tracked through September 2026. Items are selected for direct relevance to product technology, deployment or standards. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
- 2026 Current
ELANTAS advanced wire enamels ELANTAS offers polyester, polyesterimide, polyamide-imide, polyimide and polyurethane wire enamels for motors, generators and transformers. Source - 2026 Current
High-temperature insulation ELANTAS highlights thermal resistance, abrasion strength and application-specific chemistry as core wire-enamel requirements. Source - 2026 Current
E-mobility insulation High-temperature and corona-resistant enamel systems are increasingly relevant in traction motors exposed to inverter-driven electrical stress. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2021–2025 |
| Market Size 2025 | USD 896.24 million |
| Market Size 2034 | USD 1.02 billion |
| Growth Rate | CAGR of 1.5% from 2026–2034 |
| Unit | Value (USD Million) |
| Segmentation | By Type, By Application, By Thermal Class, By End Use, and By Region |
| By Type | Polyurethane Wire Enamels · Polyesterimide Wire Enamels · Polyester Wire Enamels · Polyamide-Imide Wire Enamels |
| By Application | Copper Wires · Aluminum Wires |
| By End Use | Motors · Transformers · Generators · E-Mobility · Industrial Electronics |
| By Thermal Class | Class 130-155 · Class 180 · Class 200+ · Specialty |
| By Region | Each region analysed by Type, Application and Country North AmericaU.S., Canada, Mexico EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux AsiaChina, Japan, South Korea, India, Southeast Asia South AmericaBrazil, Argentina, Rest of South America Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA |
| Key Companies Profiled | ELANTAS, Superior Essex, Axalta, TOTOKU TORYO, Kyocera, Hubergroup, Hitachi Chemical heritage suppliers, Taihu, Xianda, regional specialty coating producers |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the current size of the Wire Enamels market?
The market is valued at USD 896.24 million in 2025 and is projected to reach USD 1.02 billion by 2034, expanding at a 1.5% CAGR during 2026–2034.
Which companies lead the Wire Enamels market?
Key participants include ELANTAS, Superior Essex, Axalta, TOTOKU TORYO, Kyocera, Hubergroup, Hitachi Chemical heritage suppliers, Taihu.
What is Wire Enamels?
Wire enamels are thermally cured insulating varnishes applied directly to copper or aluminum magnet wire used in motors, transformers, generators and electrical equipment.
What are the main product types?
The market includes Polyurethane Wire Enamels, Polyesterimide Wire Enamels, Polyester Wire Enamels, Polyamide-Imide Wire Enamels.
What are the key applications?
The principal applications are Copper Wires, Aluminum Wires.
Which region leads the market?
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile.
What drives market growth?
Growth is driven by energy-efficient motors, renewable-energy generators, transformer demand, industrial automation and electrified vehicle traction systems that require reliable magnet-wire insulation.
What are the main challenges?
Growth is constrained by raw-material and solvent volatility, environmental requirements, price pressure in mature applications and long qualification cycles for insulation-system changes.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF