SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

WiFi Chip Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
INTEGRATED CIRCUITS Semiconductor Market Research

WiFi Chip Market

Emerging Trends, Technological Advancements, and Business Strategies 2026-2034

◷
UPDATED 18 September 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 3651b08fc5b9
▯
FORMATS PDF

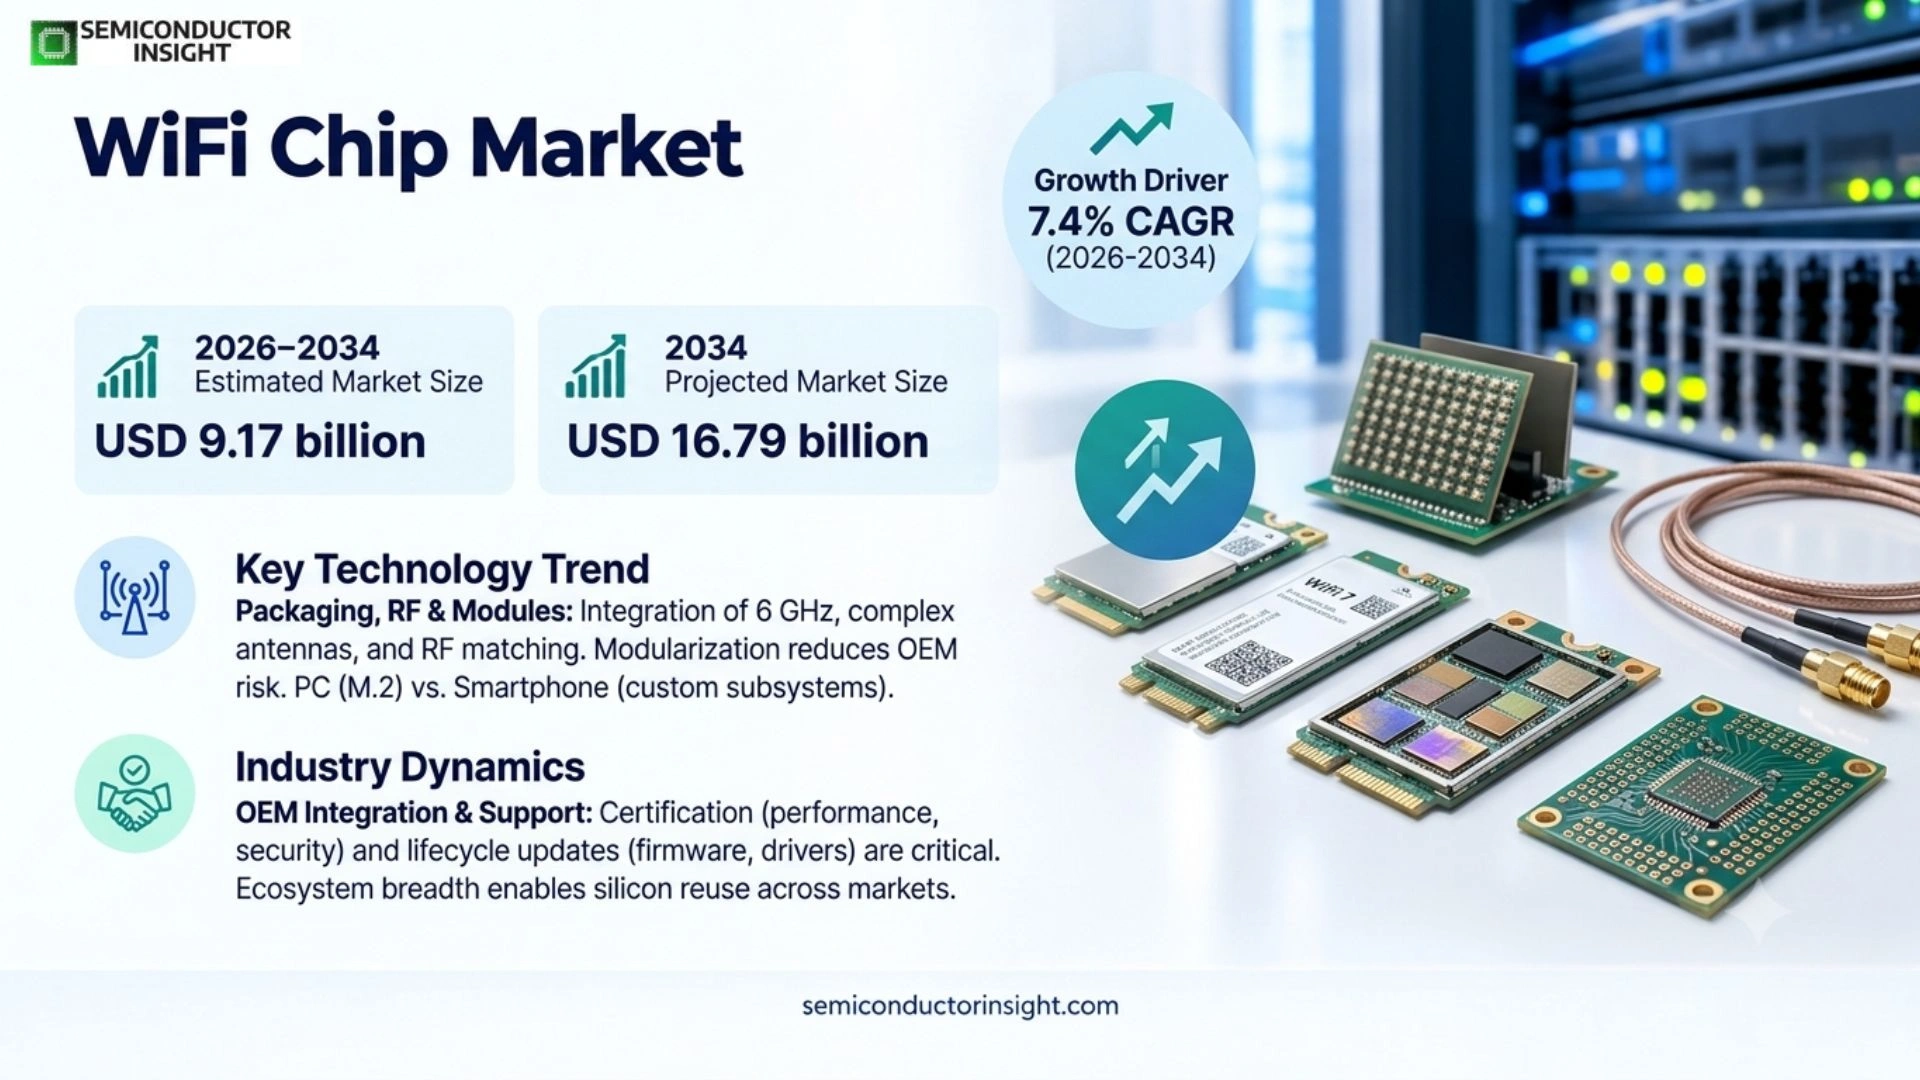
WiFi Chip Market is projected to reach USD 16.79 billion by 2034, representing a 7.4% CAGR during 2026–2034. The 2026 estimated market size is USD 9.49 billion. Asia Pacific is the largest demand region, with the source report assigning it 42% of global demand, while North America leads technology adoption and standards commercialization.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 8.84 billion
2034 Projected Size
USD 16.79 billion
CAGR (2026–2034)
7.4%
Largest Market in 2025
Asia Pacific — 42% of global demand

Key Takeaways

  • WiFi-6 chips are the leading type in the source segmentation, combining broad device qualification with OFDMA, multi-user efficiency and a cost structure that has moved the standard into mainstream routers, handsets and enterprise equipment.
  • Cell phones remain the largest application, but IoT creates a broader long-tail unit opportunity where power consumption, software support and multi-protocol integration can matter more than peak throughput.
  • Asia Pacific accounts for 42% of global demand in the source FAQ and is the fastest-growing region, while North America retains a distinct role as the technology-adoption and spectrum-policy leader.
  • WiFi-7 is the next value-upgrade cycle. Qualcomm, Intel and MediaTek already offer 6 nm or high-performance WiFi-7 platforms supporting 320 MHz channels, multi-link operation and 4K QAM for premium devices and networking equipment.
  • Spectrum regulation is a structural constraint. The value of 6 GHz-capable silicon depends on national rules, certification and device power limits, so one connectivity platform can require different feature configurations across regional markets.

WiFi Chip Market Overview

WiFi Chip Market was valued at USD 8.84 billion in 2025 and is projected to reach USD 16.79 billion by 2034, representing a 7.4% CAGR during 2026–2034. The 2026 estimated market size is USD 9.49 billion. Asia Pacific is the largest demand region, with the source report assigning it 42% of global demand, while North America leads technology adoption and standards commercialization.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD

A WiFi chip is a semiconductor connectivity device that implements IEEE 802.11 radio, baseband and medium-access functions so a host system can communicate over unlicensed wireless spectrum. Products range from low-power embedded controllers to multi-band PC modules and highly integrated mobile connectivity systems that combine WiFi with Bluetooth, UWB and coexistence logic.

The market’s commercial cycle is standards driven. Each generation adds radio features that require new silicon, RF front ends, antennas, firmware and certification, creating a design refresh even when the host device itself changes only modestly. WiFi-6 established OFDMA and dense-network efficiency; WiFi-6E opened 6 GHz operation; WiFi-7 adds 320 MHz channels, multi-link operation and higher-order modulation.

Demand therefore depends on both device volume and content per device. Smartphones, notebooks, routers and consumer electronics provide the largest recurring unit base, while IoT expands the addressable endpoint count. Premium connectivity raises silicon value when OEMs integrate multiple radios, advanced coexistence, location functions and low-latency features into one subsystem rather than buying a basic standalone WiFi device.

The supply structure is largely fabless at the chip-design level and depends on external wafer fabrication, advanced RF packaging and broad software ecosystems. Winning a socket requires more than protocol compliance: OEMs evaluate power, antenna performance, driver stability, platform interoperability, security updates and regional certification. That raises qualification costs and favors suppliers with established reference designs and long-standing device-maker relationships.

Segment Analysis: By Type

The source report segments the market into WiFi-4, WiFi-5, WiFi-6 and WiFi-6E chips. WiFi-6 is the leading segment because it delivers a strong performance and efficiency upgrade while already having broad ecosystem maturity, whereas WiFi-6E occupies a higher-value transition tier tied to 6 GHz availability and the early WiFi-7 cycle increasingly sits beyond the source page’s formal type split.

Type Technical / purchasing role Market position
WiFi-4 Chip 802.11n devices remain relevant where low bill-of-material cost, broad interoperability and moderate throughput matter more than peak performance. The technology is mature and widely integrated into cost-sensitive routers, appliances, embedded controllers and legacy IoT endpoints, so replacement demand persists even as premium consumer and enterprise systems migrate to newer standards. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market. This is a mature value segment with limited pricing power. Suppliers compete on cost, power consumption, long availability and software stability rather than leading-edge throughput. Its installed base keeps volumes meaningful in embedded products, but the revenue mix is pressured by migration toward WiFi-5, WiFi-6 and integrated multi-radio solutions. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
WiFi-5 Chip 802.11ac remains a practical mainstream option for many notebooks, televisions, gateways and embedded devices that operate mainly in the 5 GHz band. It offers sufficient throughput for ordinary streaming and enterprise access without the full complexity of OFDMA, 6 GHz support or multi-link operation, making it attractive in cost-controlled designs. The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer. WiFi-5 occupies the middle of the migration curve: larger and more capable than the legacy WiFi-4 base, but increasingly displaced in new premium platforms by WiFi-6 and WiFi-7. Suppliers can still win long-life industrial and consumer programs when certification, drivers and platform familiarity matter more than supporting the newest standard. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
WiFi-6 Chip 802.11ax adds OFDMA, improved multi-user operation, target wake time and better efficiency in dense networks. These features fit smartphones, enterprise access points, routers and IoT systems that must support many simultaneous clients, and they also improve power behavior for battery-powered endpoints without requiring access to the 6 GHz band. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market. Largest type in the source segmentation. WiFi-6 combines broad ecosystem maturity with meaningful performance gains and is therefore the revenue anchor across routers, handsets and enterprise equipment. It has moved beyond the premium tier into mainstream products, giving vendors a large qualified base even as WiFi-7 begins the next high-end replacement cycle.
WiFi-6E Chip WiFi-6E extends 802.11ax into the 6 GHz band, giving compatible devices access to cleaner spectrum and wider channels where regulators permit operation. That changes the radio front end, antenna requirements and certification burden, so the chip opportunity depends not only on protocol capability but also on regional spectrum rules and OEM design choices. WiFi-6E is the premium bridge between WiFi-6 and WiFi-7. It is strongest in high-end handsets, PCs, routers and enterprise access points that benefit from 6 GHz capacity, but the segment faces a shorter strategic window because WiFi-7 uses the same spectrum opportunity while adding 320 MHz channels and multi-link operation. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.

Technology transition beyond the source type split: WiFi-7

WiFi-7 is becoming the principal technology upgrade beyond the source page’s four formal type categories. Qualcomm’s FastConnect 7900 supports 320 MHz channels, 4K QAM and multi-link features in a 6 nm single-chip connectivity system, Intel’s BE200 reaches 5.8 Gbps in a 2×2 module, and MediaTek’s Filogic 860 targets routers and access points with up to 7.2 Gbps PHY performance. The shift increases chip value but also raises RF, software and certification complexity.

Segment Analysis: By Application

By application, the source report covers WiFi routers, cell phones, IoT devices and other consumer electronics. Cell phones are the largest application because connectivity is a standard function in every smartphone and flagship products refresh radio capability frequently, while IoT provides the broadest structural expansion opportunity through smart-home, industrial, healthcare and building devices with very different cost and power requirements.

Application Demand characteristics
WiFi Router Router and gateway demand is driven by broadband speed upgrades, mesh networking and the need to serve more concurrent devices per household or enterprise site. WiFi-7 products raise chip value through wider channels, multi-link operation and more complex radio configurations, while mainstream operators continue to deploy WiFi-6 for cost and ecosystem maturity.
Cell Phone Largest application in the source segmentation. Smartphone connectivity chips are refreshed with flagship and upper-midrange SoCs because WiFi performance affects cloud services, local media transfer, gaming and hotspot use. Integration of WiFi, Bluetooth and UWB into compact low-power connectivity systems increases silicon value even when handset unit growth is modest. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
IoT Devices IoT creates a broad unit opportunity across smart-home, industrial, medical and building-control endpoints. The purchasing priority differs from smartphones: power consumption, long software support, security, cost and coexistence with Bluetooth or Thread can matter more than peak data rate. This favors both highly integrated low-power chips and industrial-grade variants with longer lifecycles.
Other Consumer Electronics Televisions, gaming devices, cameras, appliances, XR products and personal computers create recurring connectivity design wins tied to product refresh cycles. Higher-bandwidth devices benefit from WiFi-6E and WiFi-7, while appliances often remain on mature standards. The diversity of requirements supports a wide portfolio rather than a single universally optimal chip architecture. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.

WiFi Chip Market Outlook

Regional Analysis

Asia Pacific is the largest WiFi chip demand region, with the source FAQ assigning 42% of global demand, and it also has the strongest growth profile. North America plays a different leadership role as the technology-adoption and regulatory center for advanced WiFi, while Europe emphasizes enterprise and industrial lifecycle requirements and emerging regions remain more sensitive to device affordability.

How does WiFi chip demand differ by region?

Regional differences are created by where devices are designed, where they are assembled, how quickly premium standards are adopted and whether 6 GHz operation is permitted. Asia Pacific converts manufacturing scale into chip volume, North America influences platform features and spectrum practice, Europe rewards long support cycles, and emerging markets extend the commercial life of mature standards because affordability and operator economics remain central to purchasing.

Region Position Growth outlook Demand profile What decides supplier selection
North America Technology-adoption leader Strong Premium devices, enterprise and standards led FCC spectrum compliance, OEM platform qualification, software support and supply assurance The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.
Europe Major established market Steady to strong Enterprise, industrial and automotive led Radio conformity, lifecycle support, security documentation and local module ecosystem For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
Asia Pacific Largest Highest in market Manufacturing and high-volume device led Price-performance, local OEM engineering, supply scale and multi-market certification The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.
South America Emerging Selective Broadband and value-device led Landed cost, operator qualification, distributor support and spectrum compliance In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
Middle East & Africa Emerging Selective to strong Gulf premium infrastructure plus affordable connectivity Project channels, device affordability, logistics and national radio rules For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.

Asia Pacific LARGEST & FASTEST-GROWING

Why does Asia Pacific lead the WiFi chip market?

Asia Pacific combines the report page’s 42% share of global demand with the world’s deepest concentration of consumer-electronics assembly, handset manufacturing, networking equipment and connected-device production. China, Taiwan, South Korea, Japan and Southeast Asia therefore generate both direct chip demand and the design activity that determines which connectivity platforms are qualified into global products.

Market positionLargest region
Growth outlookHighest in market
Demand profileElectronics manufacturing and device-volume led
Market access gateLocal OEM access, price-performance, certification support and supply continuity
Country / market Role in region What drives demand
China Largest manufacturing and device ecosystem China’s router, smartphone, appliance and IoT manufacturing base creates high-volume demand across mature and advanced WiFi generations. Domestic OEM programs reward vendors that provide local reference designs, firmware support and cost control, while export-oriented products also require certification for North American and European spectrum rules. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
Taiwan Chip-design and ODM hub Taiwan combines fabless semiconductor design with notebook, networking and electronics ODM capability. MediaTek and Realtek give the region local chipset depth, while contract manufacturers influence platform selection for global brands. That makes engineering support at the design stage commercially important even when final products ship to other regions. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.
South Korea Premium mobile and consumer electronics South Korea’s smartphone, television and appliance industries create demand for advanced WiFi generations that can be synchronized with premium product launches. High-end phones and connected devices adopt new standards early, making the market valuable for connectivity suppliers that can meet aggressive power, size and coexistence requirements. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
India High-growth device and broadband market India’s expanding smartphone, broadband-router and electronics-assembly base supports volume growth across mainstream WiFi standards. Cost remains important, but local production programs and rising fiber penetration create more opportunities for WiFi-6-class gateways and integrated IoT connectivity, especially where vendors can support domestic OEM and operator qualification. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
Southeast Asia Electronics production and connectivity expansion Vietnam, Malaysia and Thailand combine electronics manufacturing with growing broadband and smart-device demand. New production lines create fresh chipset qualification events, while regional consumer markets remain price sensitive. Suppliers with flexible portfolios can address premium export products and lower-cost domestic devices from the same local support structure. The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.

Market instances

  • The client report’s FAQ assigns Asia Pacific 42% of global demand, while its narrative separately describes North America as dominant in technology adoption. That distinction is commercially useful: Asia Pacific sets much of the volume and manufacturing pull, whereas North American platform launches can influence the features that Asian factories ultimately build at scale.
  • MediaTek’s Filogic 860 is a 6 nm WiFi-7 platform for routers, repeaters, gateways and access points, offering up to 7.2 Gbps PHY performance and multi-link operation. The product shows how Taiwanese suppliers are moving beyond value positioning into advanced networking silicon, increasing competitive pressure in a region already central to electronics manufacturing.
  • Asian handset and device makers are important launch customers for new connectivity generations because they refresh products frequently and operate global supply chains. A successful design win can therefore translate into unit demand across several export markets, making local engineering relationships in Taiwan, China and South Korea strategically valuable to global chip vendors.
In the full report: country-level revenue, segment mix, technology adoption, competitive position and forecast metrics for the wifi chip across the markets listed above through 2034.

North America TECHNOLOGY-ADOPTION LEADER

What makes North America strategically important in the WiFi chip market?

North America is the principal technology-adoption and platform-definition market in the source narrative. The United States combines leading connectivity-chip suppliers, premium device demand, cloud and enterprise networking, and regulatory control over 6 GHz spectrum. Those conditions make the region influential even when Asia Pacific carries the larger share of physical device manufacturing and global demand.

Market positionMajor established market
Growth outlookStrong
Demand profilePremium devices, enterprise networking and standards led
Market access gateFCC spectrum rules, OEM qualification, software support and channel relationships
Country / market Role in region What drives demand
United States Technology and regulatory anchor Qualcomm, Broadcom and Intel have major connectivity businesses serving US platform customers, while the FCC determines unlicensed spectrum conditions that shape 6 GHz product capability. Premium PCs, phones, routers and enterprise access points create an early market for advanced standards before features diffuse into lower-priced global devices. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
Canada Enterprise and broadband market Canadian demand is tied to enterprise networking, broadband gateways, PCs and connected consumer devices. Product selection closely follows North American certification and spectrum practice, so vendors can often leverage US platform qualifications while still needing local operator and enterprise-channel support for specific deployments. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.
Mexico Manufacturing-linked growth market Mexico’s electronics and appliance manufacturing base creates demand for connectivity modules and chips incorporated into products serving both domestic and US markets. Near-shoring can create new board and module design opportunities, but programs often inherit North American certification, security and supply-chain requirements from their end customers. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.

Market instances

  • The FCC’s October 2023 action authorized very-low-power devices in portions of the 6 GHz band and explicitly described 6 GHz as important for next-generation WiFi, including WiFi-7. Spectrum access is therefore not a background policy issue: it directly expands the addressable feature set for chip vendors designing 6 GHz radios. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.
  • Qualcomm’s FastConnect 7900 integrates WiFi-7, Bluetooth and UWB on a 6 nm single-chip platform, with 320 MHz channels, 4K QAM and peak WiFi speed of 5.8 Gbps. The product illustrates how North American suppliers compete by increasing radio integration rather than selling an isolated WiFi function. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.
  • Intel’s WiFi-7 BE200 supports 2.4, 5 and 6 GHz bands, 320 MHz channels and a 5.8 Gbps maximum speed. Its Q3 2023 launch positioned WiFi-7 inside the PC upgrade cycle, showing how the region’s compute ecosystem can accelerate adoption through standardized module interfaces and broad operating-system support. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
In the full report: country-level revenue, segment mix, technology adoption, competitive position and forecast metrics for the wifi chip across the markets listed above through 2034.

Europe ENTERPRISE & INDUSTRIAL MARKET

How does European WiFi chip demand differ from other regions?

Europe is shaped less by handset manufacturing volume and more by enterprise networking, industrial digitalization, connected vehicles, broadband gateways and energy-conscious device design. Germany, the United Kingdom, France and the Nordic markets create demand for robust WiFi solutions, while regional radio rules and privacy expectations encourage OEMs to prioritize documented compliance and long software support.

Market positionMajor established market
Growth outlookSteady to strong
Demand profileEnterprise, industrial and automotive led
Market access gateEU radio conformity, lifecycle support, cybersecurity and local module ecosystem
Country / market Role in region What drives demand
Germany Industrial and automotive anchor Germany’s industrial automation, automotive electronics and enterprise networking base favors chips with long availability, reliable drivers and documented compliance. Design cycles can be longer than in consumer products, but successful qualifications can persist across multiple equipment generations and therefore support durable supplier positions. The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.
United Kingdom Enterprise and consumer connectivity The UK market combines broadband gateways, enterprise WLAN, PCs and smart-home devices. Buyers follow rapid standards transitions at the premium end while mainstream operator equipment emphasizes cost and proven interoperability. Supplier support for certification and firmware maintenance is therefore important across both consumer and business channels. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.
France Telecom and connected-device market France’s telecom operators, enterprise customers and consumer-electronics channels create demand for broadband routers, connected appliances and mobile devices. WiFi chip selection is usually embedded in larger platform decisions, so vendors benefit from partnerships with module makers and gateway OEMs rather than relying solely on direct component sales. The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.
Nordic countries High-connectivity premium markets High broadband penetration and advanced digital services support premium routers, PCs and connected-home products in Nordic markets. Device volumes are smaller than in Asia, yet the willingness to adopt higher-performance networking can make the region useful for early commercialization of WiFi-6E and WiFi-7 products. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.

Market instances

  • European enterprise and industrial customers frequently keep networked equipment in service longer than consumer users, creating a different value equation from smartphone markets. Driver maintenance, security updates and long product availability can outweigh a small chip-price advantage, rewarding suppliers that support lifecycle requirements beyond the initial design win. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
  • The shift to 6 GHz and WiFi-7 increases the importance of regional radio compliance because available channels, power limits and deployment rules determine which performance claims are usable in each country. Chip suppliers therefore need flexible firmware and certification support rather than assuming that one global feature configuration can ship unchanged across every European market.
  • Automotive and industrial applications add another qualification layer through temperature, reliability and coexistence requirements. These segments can adopt new standards more slowly than smartphones, but the design wins are often longer-lived and higher value, giving diversified WiFi vendors a route to balance short consumer cycles with steadier embedded demand. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
In the full report: country-level revenue, segment mix, technology adoption, competitive position and forecast metrics for the wifi chip across the markets listed above through 2034.

South America VALUE-UPGRADE MARKET

What is driving WiFi chip demand in South America?

South American demand is driven by broadband expansion, smartphone replacement, operator gateways and connected consumer devices, with Brazil representing the largest regional opportunity. The market remains price sensitive, so mature WiFi-5 and WiFi-6 solutions can stay commercially relevant longer than in premium economies even while high-end routers and smartphones begin adopting newer standards.

Market positionEmerging market
Growth outlookSelective growth
Demand profileBroadband, smartphone and consumer-device led
Market access gateLanded cost, operator qualification, distributor support and spectrum compliance
Country / market Role in region What drives demand
Brazil Regional anchor Brazil’s large consumer base and broadband market create demand for smartphones, routers, televisions and connected appliances. Cost sensitivity supports mature chip generations, but fiber upgrades and premium device tiers also create opportunities for WiFi-6-class and newer connectivity where suppliers can manage local certification and distribution. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
Argentina Import-sensitive market Argentina’s device demand is strongly affected by exchange rates, import policy and consumer purchasing power. OEMs and distributors therefore value chips and modules that are already qualified in widely used platforms, because local redesign or a fragmented supplier base can increase inventory risk and slow product availability. The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.
Chile & Colombia Broadband and enterprise growth Fiber deployment, enterprise connectivity and rising use of cloud services support router and access-point upgrades in Chile and Colombia. Market scale is smaller than Brazil, but demand can favor proven WiFi-6 solutions that improve multi-device performance without requiring the highest-priced premium silicon. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.

Market instances

  • South America illustrates why the newest standard does not automatically capture the largest revenue pool. Fiber and device upgrades increase throughput requirements, yet OEMs must balance that performance against retail affordability and import cost, which can extend the commercial life of WiFi-5 and WiFi-6 chips after premium markets have moved further toward WiFi-7.
  • Operator-supplied gateways are an important demand mechanism because a broadband provider can standardize one hardware platform across a large subscriber base. Winning such a platform requires interoperability, firmware stability and supply continuity, so a successful chip qualification can produce more predictable volumes than fragmented retail-router demand. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
  • Local spectrum and equipment-approval rules determine whether 6 GHz capability can be used in practice. Vendors serving the region therefore need software-configurable products and certification support that let OEMs reuse core silicon while adjusting radio operation to each national market. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
In the full report: country-level revenue, segment mix, technology adoption, competitive position and forecast metrics for the wifi chip across the markets listed above through 2034.

Middle East & Africa EMERGING CONNECTIVITY MARKET

Where are the strongest WiFi chip opportunities in the Middle East and Africa?

The region is bifurcated between premium Gulf markets investing in high-speed fixed broadband, smart buildings and enterprise networking, and African markets where affordability and basic connectivity remain stronger purchasing drivers. This creates simultaneous demand for advanced WiFi-6 and WiFi-7 platforms in the Gulf and mature low-cost connectivity chips in broader mobile-first markets.

Market positionEmerging market
Growth outlookSelective to strong
Demand profileGulf premium infrastructure plus mass-market connectivity
Market access gateProject qualification, local channel support, device affordability and spectrum availability
Country / market Role in region What drives demand
Saudi Arabia Infrastructure and smart-city market Large infrastructure, hospitality, enterprise and smart-city projects create demand for high-capacity wireless networks. Premium access points and gateways can support advanced WiFi standards, but suppliers need project-channel relationships and reliable regional logistics because deployments are often tied to large construction or digital-infrastructure programs. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
United Arab Emirates Premium connectivity market High-income consumers, dense commercial development and advanced telecom infrastructure support premium smartphones, routers and enterprise WLAN equipment. The UAE can adopt new WiFi generations early, making it a useful regional market for flagship platforms even though total unit volumes remain below major Asian economies. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.
South Africa Enterprise and consumer anchor South Africa combines enterprise networking, broadband growth and a relatively developed consumer-electronics market. Cost remains important, so vendors benefit from portfolios spanning mainstream WiFi-5/6 devices and higher-performance business or premium consumer equipment rather than relying on one technology tier. The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.
Nigeria & Kenya Mobile-first emerging demand Large young populations and expanding digital services create long-run demand for connected devices, but affordability and infrastructure constraints favor lower-cost WiFi solutions. Integrated chips that combine WiFi with Bluetooth and other functions can reduce system cost and simplify local device designs. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.

Market instances

  • Gulf smart-building and hospitality projects create a different purchasing pattern from consumer retail: integrators specify access points, gateways and management systems as part of a complete network. Chip suppliers benefit indirectly through OEM platforms that have already been qualified for enterprise-scale deployments, so ecosystem partnerships can matter more than direct regional component sales.
  • In many African markets, the economic value of WiFi comes from extending fixed or mobile broadband to multiple household devices rather than from maximizing peak throughput. That favors cost-efficient connectivity chips with strong power performance and mature software, creating a long commercial tail for standards that have already moved down the cost curve.
  • As 6 GHz rules expand across more countries, vendors can reuse global WiFi-6E and WiFi-7 silicon more effectively. Until then, regional firmware variants and certification requirements can fragment product planning, giving larger suppliers an advantage because they can absorb validation costs across a broader worldwide shipment base. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
In the full report: country-level revenue, segment mix, technology adoption, competitive position and forecast metrics for the wifi chip across the markets listed above through 2034.

WiFi Chip Competitive Landscape

Competition is concentrated among diversified semiconductor companies with strong radio IP, platform relationships and access to advanced process nodes, but the market is not uniform. Qualcomm and MediaTek are strong in mobile connectivity, Broadcom has deep networking exposure, Intel serves PC platforms, and Realtek and Espressif address value and embedded segments. The competitive boundary increasingly includes multi-radio integration rather than WiFi performance alone.

The first competitive lever is integration. Qualcomm’s FastConnect 7900 combines WiFi-7, Bluetooth and UWB in a 6 nm device, demonstrating how suppliers can raise content and reduce board complexity simultaneously. For smartphone and XR OEMs, a tightly integrated connectivity subsystem can save power, antenna-management effort and PCB area, making platform-level functionality more defensible than a discrete WiFi chip sold on throughput alone.

The second lever is segment specialization. MediaTek’s Filogic family targets routers, gateways and access points, while Intel’s BE200 is a standardized PC connectivity module and Espressif is associated with embedded and IoT designs. Each category has different qualification cycles, software requirements and pricing, so a supplier can build a strong franchise without leading every end market. Portfolio breadth still matters because standards transitions occur at different speeds across device categories.

The third lever is regulatory execution. 6 GHz operation, automated frequency coordination and regional certification can determine whether a technically capable chip can use its full feature set in a specific country. Larger vendors spread those validation costs across many OEM programs and provide firmware variants for regional rules, while smaller entrants may need to focus on a narrower geography or device class where certification requirements are less fragmented.

Foundry access and RF supply continuity remain important because connectivity chips combine digital baseband, analog RF and external front-end elements. Advanced-node designs improve power and integration, but they also increase development expense and dependence on a limited set of manufacturing partners. Customers therefore evaluate roadmap continuity and component availability alongside benchmark performance, particularly for routers and industrial products with multi-year production lives.

Tier structure

Market instances

  • European enterprise and industrial customers frequently keep networked equipment in service longer than consumer users, creating a different value equation from smartphone markets. Driver maintenance, security updates and long product availability can outweigh a small chip-price advantage, rewarding suppliers that support lifecycle requirements beyond the initial design win. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
  • The shift to 6 GHz and WiFi-7 increases the importance of regional radio compliance because available channels, power limits and deployment rules determine which performance claims are usable in each country. Chip suppliers therefore need flexible firmware and certification support rather than assuming that one global feature configuration can ship unchanged across every European market.
  • Automotive and industrial applications add another qualification layer through temperature, reliability and coexistence requirements. These segments can adopt new standards more slowly than smartphones, but the design wins are often longer-lived and higher value, giving diversified WiFi vendors a route to balance short consumer cycles with steadier embedded demand. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
Competitive tier Representative participants How suppliers compete
Platform leaders Qualcomm Technologies; Broadcom; MediaTek These suppliers compete through leading radio architectures, early standards implementation, advanced process technology and broad OEM relationships. Their scale lets them support premium smartphones, access points and gateways while funding certification across many countries. Platform integration and reference designs create switching costs that extend beyond the individual WiFi die. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.
Compute and diversified semiconductor suppliers Intel; NXP Semiconductors; Texas Instruments; Infineon; onsemi These companies participate where WiFi is tied to PCs, industrial systems, automotive electronics or broader embedded portfolios. Their advantage is access to existing processor, MCU, power and system relationships, which can simplify customer sourcing. They compete less through one universal WiFi architecture and more through platform fit, lifecycle support and application-specific integration.
Value and embedded specialists
In the full report: country-level revenue, segment mix, technology adoption, competitive position and forecast metrics for the wifi chip across the markets listed above through 2034.

South America VALUE-UPGRADE MARKET

What is driving WiFi chip demand in South America?

South American demand is driven by broadband expansion, smartphone replacement, operator gateways and connected consumer devices, with Brazil representing the largest regional opportunity. The market remains price sensitive, so mature WiFi-5 and WiFi-6 solutions can stay commercially relevant longer than in premium economies even while high-end routers and smartphones begin adopting newer standards.

Market positionEmerging market
Growth outlookSelective growth
Demand profileBroadband, smartphone and consumer-device led
Market access gateLanded cost, operator qualification, distributor support and spectrum compliance
Country / market Role in region What drives demand
Brazil Regional anchor Brazil’s large consumer base and broadband market create demand for smartphones, routers, televisions and connected appliances. Cost sensitivity supports mature chip generations, but fiber upgrades and premium device tiers also create opportunities for WiFi-6-class and newer connectivity where suppliers can manage local certification and distribution. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
Argentina Import-sensitive market Argentina’s device demand is strongly affected by exchange rates, import policy and consumer purchasing power. OEMs and distributors therefore value chips and modules that are already qualified in widely used platforms, because local redesign or a fragmented supplier base can increase inventory risk and slow product availability. The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.
Chile & Colombia Broadband and enterprise growth Fiber deployment, enterprise connectivity and rising use of cloud services support router and access-point upgrades in Chile and Colombia. Market scale is smaller than Brazil, but demand can favor proven WiFi-6 solutions that improve multi-device performance without requiring the highest-priced premium silicon. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.

Market instances

  • South America illustrates why the newest standard does not automatically capture the largest revenue pool. Fiber and device upgrades increase throughput requirements, yet OEMs must balance that performance against retail affordability and import cost, which can extend the commercial life of WiFi-5 and WiFi-6 chips after premium markets have moved further toward WiFi-7.
  • Operator-supplied gateways are an important demand mechanism because a broadband provider can standardize one hardware platform across a large subscriber base. Winning such a platform requires interoperability, firmware stability and supply continuity, so a successful chip qualification can produce more predictable volumes than fragmented retail-router demand. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
  • Local spectrum and equipment-approval rules determine whether 6 GHz capability can be used in practice. Vendors serving the region therefore need software-configurable products and certification support that let OEMs reuse core silicon while adjusting radio operation to each national market. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.
In the full report: country-level revenue, segment mix, technology adoption, competitive position and forecast metrics for the wifi chip across the markets listed above through 2034.

Middle East & Africa EMERGING CONNECTIVITY MARKET

Where are the strongest WiFi chip opportunities in the Middle East and Africa?

The region is bifurcated between premium Gulf markets investing in high-speed fixed broadband, smart buildings and enterprise networking, and African markets where affordability and basic connectivity remain stronger purchasing drivers. This creates simultaneous demand for advanced WiFi-6 and WiFi-7 platforms in the Gulf and mature low-cost connectivity chips in broader mobile-first markets.

Market positionEmerging market
Growth outlookSelective to strong
Demand profileGulf premium infrastructure plus mass-market connectivity
Market access gateProject qualification, local channel support, device affordability and spectrum availability
Country / market Role in region What drives demand
Saudi Arabia Infrastructure and smart-city market Large infrastructure, hospitality, enterprise and smart-city projects create demand for high-capacity wireless networks. Premium access points and gateways can support advanced WiFi standards, but suppliers need project-channel relationships and reliable regional logistics because deployments are often tied to large construction or digital-infrastructure programs. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
United Arab Emirates Premium connectivity market High-income consumers, dense commercial development and advanced telecom infrastructure support premium smartphones, routers and enterprise WLAN equipment. The UAE can adopt new WiFi generations early, making it a useful regional market for flagship platforms even though total unit volumes remain below major Asian economies. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.
South Africa Enterprise and consumer anchor South Africa combines enterprise networking, broadband growth and a relatively developed consumer-electronics market. Cost remains important, so vendors benefit from portfolios spanning mainstream WiFi-5/6 devices and higher-performance business or premium consumer equipment rather than relying on one technology tier. The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.
Nigeria & Kenya Mobile-first emerging demand Large young populations and expanding digital services create long-run demand for connected devices, but affordability and infrastructure constraints favor lower-cost WiFi solutions. Integrated chips that combine WiFi with Bluetooth and other functions can reduce system cost and simplify local device designs. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.

Market instances

  • Gulf smart-building and hospitality projects create a different purchasing pattern from consumer retail: integrators specify access points, gateways and management systems as part of a complete network. Chip suppliers benefit indirectly through OEM platforms that have already been qualified for enterprise-scale deployments, so ecosystem partnerships can matter more than direct regional component sales.
  • In many African markets, the economic value of WiFi comes from extending fixed or mobile broadband to multiple household devices rather than from maximizing peak throughput. That favors cost-efficient connectivity chips with strong power performance and mature software, creating a long commercial tail for standards that have already moved down the cost curve.
  • As 6 GHz rules expand across more countries, vendors can reuse global WiFi-6E and WiFi-7 silicon more effectively. Until then, regional firmware variants and certification requirements can fragment product planning, giving larger suppliers an advantage because they can absorb validation costs across a broader worldwide shipment base. In the wifi chip market market, the practical consequence is a stronger link between engineering support and commercial conversion: customers need confidence that a device will remain compatible, available and supportable after launch. That favors suppliers able to pair technical differentiation with qualification data, ecosystem relationships and a credible production roadmap rather than treating the product as a stand-alone catalog part for the WiFi chip market.
In the full report: country-level revenue, segment mix, technology adoption, competitive position and forecast metrics for the wifi chip across the markets listed above through 2034.

WiFi Chip Competitive Landscape

Competition is concentrated among diversified semiconductor companies with strong radio IP, platform relationships and access to advanced process nodes, but the market is not uniform. Qualcomm and MediaTek are strong in mobile connectivity, Broadcom has deep networking exposure, Intel serves PC platforms, and Realtek and Espressif address value and embedded segments. The competitive boundary increasingly includes multi-radio integration rather than WiFi performance alone.

The first competitive lever is integration. Qualcomm’s FastConnect 7900 combines WiFi-7, Bluetooth and UWB in a 6 nm device, demonstrating how suppliers can raise content and reduce board complexity simultaneously. For smartphone and XR OEMs, a tightly integrated connectivity subsystem can save power, antenna-management effort and PCB area, making platform-level functionality more defensible than a discrete WiFi chip sold on throughput alone.

The second lever is segment specialization. MediaTek’s Filogic family targets routers, gateways and access points, while Intel’s BE200 is a standardized PC connectivity module and Espressif is associated with embedded and IoT designs. Each category has different qualification cycles, software requirements and pricing, so a supplier can build a strong franchise without leading every end market. Portfolio breadth still matters because standards transitions occur at different speeds across device categories.

The third lever is regulatory execution. 6 GHz operation, automated frequency coordination and regional certification can determine whether a technically capable chip can use its full feature set in a specific country. Larger vendors spread those validation costs across many OEM programs and provide firmware variants for regional rules, while smaller entrants may need to focus on a narrower geography or device class where certification requirements are less fragmented.

Foundry access and RF supply continuity remain important because connectivity chips combine digital baseband, analog RF and external front-end elements. Advanced-node designs improve power and integration, but they also increase development expense and dependence on a limited set of manufacturing partners. Customers therefore evaluate roadmap continuity and component availability alongside benchmark performance, particularly for routers and industrial products with multi-year production lives.

Tier structure

2023
FCC expands very-low-power use of the 6 GHz band

The FCC authorized very-low-power operations in portions of the 6 GHz band and stated that earlier unlicensed access helped usher in WiFi-6E and set the stage for WiFi-7. The decision expands the range of devices that can use 6 GHz spectrum in the United States, directly supporting chipsets designed for new wearable, XR and IoT operating modes.

Official source

Q3 2023
Intel launches the WiFi-7 BE200 PC connectivity module

Intel lists the BE200 as launched in Q3 2023 with 2×2 operation across 2.4, 5 and 6 GHz bands, 320 MHz channels and a maximum speed of 5.8 Gbps. Standardized M.2 formats help OEMs adopt the new generation inside PCs without redesigning the entire wireless subsystem, accelerating the transition through established compute platforms.

Official source

Competitive tier Representative participants How suppliers compete
Platform leaders Qualcomm Technologies; Broadcom; MediaTek These suppliers compete through leading radio architectures, early standards implementation, advanced process technology and broad OEM relationships. Their scale lets them support premium smartphones, access points and gateways while funding certification across many countries. Platform integration and reference designs create switching costs that extend beyond the individual WiFi die. This is commercially important in the wifi chip market market because the value of a design win is realized only after the device survives platform validation, software or system integration and supplier approval. The resulting qualification burden can lengthen sales cycles, but it also makes successful positions durable and raises the cost for customers to switch to an unproven alternative for the WiFi chip market.
Compute and diversified semiconductor suppliers Intel; NXP Semiconductors; Texas Instruments; Infineon; onsemi These companies participate where WiFi is tied to PCs, industrial systems, automotive electronics or broader embedded portfolios. Their advantage is access to existing processor, MCU, power and system relationships, which can simplify customer sourcing. They compete less through one universal WiFi architecture and more through platform fit, lifecycle support and application-specific integration.
Value and embedded specialists

REPORT SCOPE & SEGMENTATION

The report scope covers semiconductor devices that provide WiFi connectivity under the product, application and end-user categories published on the client page. The standardized financial series uses 2025 as the base year, 2026 as the estimated year and 2034 as the forecast endpoint. The formal type segmentation remains WiFi-4 through WiFi-6E, while WiFi-7 is analyzed as the principal technology transition beyond that published split.

Report attribute Coverage
Market WiFi Chip
Base year 2025
Estimated year 2026
Forecast period 2026–2034
2025 market size USD 8.84 billion
2034 forecast size USD 16.79 billion
CAGR 7.4% during 2026–2034
Largest market in 2025 Asia Pacific — 42% of global demand
By Type WiFi-4 Chip; WiFi-5 Chip; WiFi-6 Chip; WiFi-6E Chip
By Application WiFi Router; Cell Phone; IoT Devices; Other Consumer Electronics
Additional segmentation By End User: Consumer Electronics; Enterprise; Automotive; Industrial
Regions North America; Europe; Asia Pacific; South America; Middle East & Africa
Companies profiled Qualcomm Technologies, Inc.; Broadcom Inc.; Intel Corporation; MediaTek Inc.; NXP Semiconductors N.V.; Texas Instruments Incorporated; Infineon Technologies AG; ON Semiconductor Corp.; Realtek Semiconductor Corp.; Triductor Technology Inc.; Espressif Systems

Frequently Asked Questions

What is the wifi chip market size in 2025?

The global wifi chip market is valued at USD 8.84 billion in 2025 under the standardized series used in this overview. The same series places the estimated 2026 market at USD 9.49 billion, allowing the base year, estimate and forecast to be compared without changing scope. The figure is carried consistently through the statistics, overview and report-scope sections for the WiFi chip market.

What is the projected wifi chip market size by 2034?

The wifi chip market is projected to reach USD 16.79 billion by 2034. This endpoint follows the growth path implied by the published market-size anchors and is paired with the 2025 base value rather than an unrelated forecast for the WiFi chip market. That consistency is important when evaluating segment growth, regional opportunities and supplier strategies across the full 2026–2034 period for the WiFi chip market.

What CAGR is expected for the wifi chip market during 2026–2034?

The standardized outlook corresponds to a 7.4% CAGR during 2026–2034. The rate is the compound annual growth implied by the market-size anchors used for the 2025 and 2034 values, so the percentage and revenue series describe the same trajectory for the WiFi chip market. It provides the reference against which drivers, restraints and faster-moving subsegments are assessed for the WiFi chip market.

Which region is the largest wifi chip market in 2025?

Asia Pacific is identified as the largest market in 2025. Its position reflects the concentration of relevant device manufacturing, system demand, research activity or customer deployment described in the market evidence for the WiFi chip market. Suppliers still need local qualification and channel support to convert that structural demand into revenue, so geographic scale alone does not guarantee a durable competitive position for the WiFi chip market.

Which product type leads the wifi chip market?

WiFi-6 Chip is the leading product or technology type in the source segmentation. Its position reflects a combination of installed-base relevance, compatibility with current system architectures and breadth of addressable applications for the WiFi chip market. Newer technologies can grow faster, but the leading type retains a larger revenue base until customers complete qualification and platform migration across multiple product cycles for the WiFi chip market.

Which application is the most important for the wifi chip market?

Cell Phone is the principal application identified in the report scope. Demand is created by system-level performance requirements and the need for qualified components that can be integrated without disproportionate redesign, validation or support burden for the WiFi chip market. This makes application engineering and customer roadmaps important commercial variables alongside the underlying device specifications for the WiFi chip market. For the wifi chip market market, this changes purchasing economics because design qualification, integration effort, lifecycle support and supply continuity influence a customer’s decision alongside headline performance. Suppliers that reduce those risks can defend design wins for multiple product cycles, while vendors that compete only on component price face a narrower route into long-lived platforms for the WiFi chip market.

Which region has the strongest growth profile in the wifi chip market?

Asia Pacific has the strongest growth profile in this overview. Growth is tied to new manufacturing capacity, infrastructure, research programs or device adoption depending on the region for the WiFi chip market. Suppliers benefit most where they can shorten qualification cycles, support customers locally and align product roadmaps with the technical and regulatory conditions shaping deployments for the WiFi chip market. The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.

What is the main technology transition shaping the wifi chip market?

The most important transition is from WiFi-6/6E into WiFi-7. New platforms add 320 MHz channels, 4K QAM and multi-link operation while integrating Bluetooth, UWB and proximity functions. That raises performance and content per device, but it also increases RF design, certification and software complexity, making ecosystem execution a central competitive factor. The market implication is that performance gains matter most when they can be converted into lower system power, easier integration, higher throughput or reduced deployment risk for the WiFi chip market. In the wifi chip market market, those benefits determine whether OEMs and system builders accept a new supplier, making application engineering, reference designs and dependable manufacturing capacity important parts of the competitive offer.

What are the principal restraints on the wifi chip market?

The main restraints are mature unit growth in smartphones and PCs, fragmented 6 GHz spectrum rules, rising verification and security costs, and dependence on foundry and RF supply chains. These factors can delay standards adoption and favor established platform vendors with the engineering scale to maintain drivers, certifications and regional product variants over long device lifecycles.

Who are the key suppliers in the wifi chip market?

The competitive landscape includes the companies listed in the report scope together with the qualified ecosystem participants discussed in this overview for the WiFi chip market. Advantage depends on product performance, manufacturing quality, system integration, reliability evidence and customer support for the WiFi chip market. In markets with long qualification cycles, production continuity and roadmap credibility can be as important as a single generation’s peak technical specification for the WiFi chip market.

Research Sources & Evidence Base
View research sources used for this overview
  1. Federal Communications Commission. FCC Permits Very Low Power Device Operations in 6 GHz Band, October 19, 2023 decision describing 6 GHz unlicensed use, WiFi-6E and the foundation for WiFi-7.
  2. Qualcomm Technologies. FastConnect 7900, 6 nm WiFi-7, Bluetooth and UWB platform specifications including 320 MHz channels, 4K QAM and 5.8 Gbps peak speed.
  3. Intel. Intel WiFi 7 BE200 Specifications, Q3 2023 launch, tri-band 2×2 operation, 320 MHz channels and 5.8 Gbps maximum speed.
  4. MediaTek. MediaTek Filogic 860, 6 nm WiFi-7 router, gateway and access-point platform with multi-link operation and up to 7.2 Gbps PHY performance.
WiFi Chip Market, Emerging Trends, Technological Advancements, and Business Strategies 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 WiFi Chip Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global WiFi Chip Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global WiFi Chip Overall Market Size
2.1 Global WiFi Chip Market Size: 2024 VS 2032
2.2 Global WiFi Chip Market Size, Prospects & Forecasts: 2020-2032
2.3 Global WiFi Chip Sales: 2020-2032
3 Company Landscape
3.1 Top WiFi Chip Players in Global Market
3.2 Top Global WiFi Chip Companies Ranked by Revenue
3.3 Global WiFi Chip Revenue by Companies
3.4 Global WiFi Chip Sales by Companies
3.5 Global WiFi Chip Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 WiFi Chip Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers WiFi Chip Product Type
3.8 Tier 1, Tier 2, and Tier 3 WiFi Chip Players in Global Market
3.8.1 List of Global Tier 1 WiFi Chip Companies
3.8.2 List of Global Tier 2 and Tier 3 WiFi Chip Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global WiFi Chip Market Size Markets, 2024 & 2032
4.1.2 WiFi-4 Chip
4.1.3 WiFi-5 Chip
4.1.4 WiFi-6 Chip
4.1.5 WiFi-6E Chip
4.2 Segment by Type – Global WiFi Chip Revenue & Forecasts
4.2.1 Segment by Type – Global WiFi Chip Revenue, 2020-2025
4.2.2 Segment by Type – Global WiFi Chip Revenue, 2026-2032
4.2.3 Segment by Type – Global WiFi Chip Revenue Market Share, 2020-2032
4.3 Segment by Type – Global WiFi Chip Sales & Forecasts
4.3.1 Segment by Type – Global WiFi Chip Sales, 2020-2025
4.3.2 Segment by Type – Global WiFi Chip Sales, 2026-2032
4.3.3 Segment by Type – Global WiFi Chip Sales Market Share, 2020-2032
4.4 Segment by Type – Global WiFi Chip Price (Manufacturers Selling Prices), 2020-2032
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global WiFi Chip Market Size, 2024 & 2032
5.1.2 WiFi Router
5.1.3 Cell Phone
5.1.4 IoT
5.1.5 Other
5.2 Segment by Application – Global WiFi Chip Revenue & Forecasts
5.2.1 Segment by Application – Global WiFi Chip Revenue, 2020-2025
5.2.2 Segment by Application – Global WiFi Chip Revenue, 2026-2032
5.2.3 Segment by Application – Global WiFi Chip Revenue Market Share, 2020-2032
5.3 Segment by Application – Global WiFi Chip Sales & Forecasts
5.3.1 Segment by Application – Global WiFi Chip Sales, 2020-2025
5.3.2 Segment by Application – Global WiFi Chip Sales, 2026-2032
5.3.3 Segment by Application – Global WiFi Chip Sales Market Share, 2020-2032
5.4 Segment by Application – Global WiFi Chip Price (Manufacturers Selling Prices), 2020-2032
6 Sights by Region
6.1 By Region – Global WiFi Chip Market Size, 2024 & 2032
6.2 By Region – Global WiFi Chip Revenue & Forecasts
6.2.1 By Region – Global WiFi Chip Revenue, 2020-2025
6.2.2 By Region – Global WiFi Chip Revenue, 2026-2032
6.2.3 By Region – Global WiFi Chip Revenue Market Share, 2020-2032
6.3 By Region – Global WiFi Chip Sales & Forecasts
6.3.1 By Region – Global WiFi Chip Sales, 2020-2025
6.3.2 By Region – Global WiFi Chip Sales, 2026-2032
6.3.3 By Region – Global WiFi Chip Sales Market Share, 2020-2032
6.4 North America
6.4.1 By Country – North America WiFi Chip Revenue, 2020-2032
6.4.2 By Country – North America WiFi Chip Sales, 2020-2032
6.4.3 United States WiFi Chip Market Size, 2020-2032
6.4.4 Canada WiFi Chip Market Size, 2020-2032
6.4.5 Mexico WiFi Chip Market Size, 2020-2032
6.5 Europe
6.5.1 By Country – Europe WiFi Chip Revenue, 2020-2032
6.5.2 By Country – Europe WiFi Chip Sales, 2020-2032
6.5.3 Germany WiFi Chip Market Size, 2020-2032
6.5.4 France WiFi Chip Market Size, 2020-2032
6.5.5 U.K. WiFi Chip Market Size, 2020-2032
6.5.6 Italy WiFi Chip Market Size, 2020-2032
6.5.7 Russia WiFi Chip Market Size, 2020-2032
6.5.8 Nordic Countries WiFi Chip Market Size, 2020-2032
6.5.9 Benelux WiFi Chip Market Size, 2020-2032
6.6 Asia
6.6.1 By Region – Asia WiFi Chip Revenue, 2020-2032
6.6.2 By Region – Asia WiFi Chip Sales, 2020-2032
6.6.3 China WiFi Chip Market Size, 2020-2032
6.6.4 Japan WiFi Chip Market Size, 2020-2032
6.6.5 South Korea WiFi Chip Market Size, 2020-2032
6.6.6 Southeast Asia WiFi Chip Market Size, 2020-2032
6.6.7 India WiFi Chip Market Size, 2020-2032
6.7 South America
6.7.1 By Country – South America WiFi Chip Revenue, 2020-2032
6.7.2 By Country – South America WiFi Chip Sales, 2020-2032
6.7.3 Brazil WiFi Chip Market Size, 2020-2032
6.7.4 Argentina WiFi Chip Market Size, 2020-2032
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa WiFi Chip Revenue, 2020-2032
6.8.2 By Country – Middle East & Africa WiFi Chip Sales, 2020-2032
6.8.3 Turkey WiFi Chip Market Size, 2020-2032
6.8.4 Israel WiFi Chip Market Size, 2020-2032
6.8.5 Saudi Arabia WiFi Chip Market Size, 2020-2032
6.8.6 UAE WiFi Chip Market Size, 2020-2032
7 Manufacturers & Brands Profiles
7.1 Broadcomm
7.1.1 Broadcomm Company Summary
7.1.2 Broadcomm Business Overview
7.1.3 Broadcomm WiFi Chip Major Product Offerings
7.1.4 Broadcomm WiFi Chip Sales and Revenue in Global (2020-2025)
7.1.5 Broadcomm Key News & Latest Developments
7.2 Qualcomm
7.2.1 Qualcomm Company Summary
7.2.2 Qualcomm Business Overview
7.2.3 Qualcomm WiFi Chip Major Product Offerings
7.2.4 Qualcomm WiFi Chip Sales and Revenue in Global (2020-2025)
7.2.5 Qualcomm Key News & Latest Developments
7.3 Intel
7.3.1 Intel Company Summary
7.3.2 Intel Business Overview
7.3.3 Intel WiFi Chip Major Product Offerings
7.3.4 Intel WiFi Chip Sales and Revenue in Global (2020-2025)
7.3.5 Intel Key News & Latest Developments
7.4 MediaTek
7.4.1 MediaTek Company Summary
7.4.2 MediaTek Business Overview
7.4.3 MediaTek WiFi Chip Major Product Offerings
7.4.4 MediaTek WiFi Chip Sales and Revenue in Global (2020-2025)
7.4.5 MediaTek Key News & Latest Developments
7.5 NXP
7.5.1 NXP Company Summary
7.5.2 NXP Business Overview
7.5.3 NXP WiFi Chip Major Product Offerings
7.5.4 NXP WiFi Chip Sales and Revenue in Global (2020-2025)
7.5.5 NXP Key News & Latest Developments
7.6 TI
7.6.1 TI Company Summary
7.6.2 TI Business Overview
7.6.3 TI WiFi Chip Major Product Offerings
7.6.4 TI WiFi Chip Sales and Revenue in Global (2020-2025)
7.6.5 TI Key News & Latest Developments
7.7 Infineon
7.7.1 Infineon Company Summary
7.7.2 Infineon Business Overview
7.7.3 Infineon WiFi Chip Major Product Offerings
7.7.4 Infineon WiFi Chip Sales and Revenue in Global (2020-2025)
7.7.5 Infineon Key News & Latest Developments
7.8 ON Semiconductor
7.8.1 ON Semiconductor Company Summary
7.8.2 ON Semiconductor Business Overview
7.8.3 ON Semiconductor WiFi Chip Major Product Offerings
7.8.4 ON Semiconductor WiFi Chip Sales and Revenue in Global (2020-2025)
7.8.5 ON Semiconductor Key News & Latest Developments
7.9 Realtek
7.9.1 Realtek Company Summary
7.9.2 Realtek Business Overview
7.9.3 Realtek WiFi Chip Major Product Offerings
7.9.4 Realtek WiFi Chip Sales and Revenue in Global (2020-2025)
7.9.5 Realtek Key News & Latest Developments
7.10 Triductor Technology
7.10.1 Triductor Technology Company Summary
7.10.2 Triductor Technology Business Overview
7.10.3 Triductor Technology WiFi Chip Major Product Offerings
7.10.4 Triductor Technology WiFi Chip Sales and Revenue in Global (2020-2025)
7.10.5 Triductor Technology Key News & Latest Developments
7.11 Espressif Systems
7.11.1 Espressif Systems Company Summary
7.11.2 Espressif Systems Business Overview
7.11.3 Espressif Systems WiFi Chip Major Product Offerings
7.11.4 Espressif Systems WiFi Chip Sales and Revenue in Global (2020-2025)
7.11.5 Espressif Systems Key News & Latest Developments
7.12 Beken
7.12.1 Beken Company Summary
7.12.2 Beken Business Overview
7.12.3 Beken WiFi Chip Major Product Offerings
7.12.4 Beken WiFi Chip Sales and Revenue in Global (2020-2025)
7.12.5 Beken Key News & Latest Developments
7.13 ASR Microelectronics
7.13.1 ASR Microelectronics Company Summary
7.13.2 ASR Microelectronics Business Overview
7.13.3 ASR Microelectronics WiFi Chip Major Product Offerings
7.13.4 ASR Microelectronics WiFi Chip Sales and Revenue in Global (2020-2025)
7.13.5 ASR Microelectronics Key News & Latest Developments
8 Global WiFi Chip Production Capacity, Analysis
8.1 Global WiFi Chip Production Capacity, 2020-2032
8.2 WiFi Chip Production Capacity of Key Manufacturers in Global Market
8.3 Global WiFi Chip Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 WiFi Chip Supply Chain Analysis
10.1 WiFi Chip Industry Value Chain
10.2 WiFi Chip Upstream Market
10.3 WiFi Chip Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 WiFi Chip Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of WiFi Chip in Global Market
Table 2. Top WiFi Chip Players in Global Market, Ranking by Revenue (2024)
Table 3. Global WiFi Chip Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global WiFi Chip Revenue Share by Companies, 2020-2025
Table 5. Global WiFi Chip Sales by Companies, (M Units), 2020-2025
Table 6. Global WiFi Chip Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers WiFi Chip Price (2020-2025) & (US$/K Units)
Table 8. Global Manufacturers WiFi Chip Product Type
Table 9. List of Global Tier 1 WiFi Chip Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 WiFi Chip Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global WiFi Chip Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global WiFi Chip Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global WiFi Chip Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global WiFi Chip Sales (M Units), 2020-2025
Table 15. Segment by Type – Global WiFi Chip Sales (M Units), 2026-2032
Table 16. Segment by Application – Global WiFi Chip Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global WiFi Chip Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global WiFi Chip Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global WiFi Chip Sales, (M Units), 2020-2025
Table 20. Segment by Application – Global WiFi Chip Sales, (M Units), 2026-2032
Table 21. By Region – Global WiFi Chip Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global WiFi Chip Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global WiFi Chip Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global WiFi Chip Sales, (M Units), 2020-2025
Table 25. By Region – Global WiFi Chip Sales, (M Units), 2026-2032
Table 26. By Country – North America WiFi Chip Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America WiFi Chip Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America WiFi Chip Sales, (M Units), 2020-2025
Table 29. By Country – North America WiFi Chip Sales, (M Units), 2026-2032
Table 30. By Country – Europe WiFi Chip Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe WiFi Chip Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe WiFi Chip Sales, (M Units), 2020-2025
Table 33. By Country – Europe WiFi Chip Sales, (M Units), 2026-2032
Table 34. By Region – Asia WiFi Chip Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia WiFi Chip Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia WiFi Chip Sales, (M Units), 2020-2025
Table 37. By Region – Asia WiFi Chip Sales, (M Units), 2026-2032
Table 38. By Country – South America WiFi Chip Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America WiFi Chip Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America WiFi Chip Sales, (M Units), 2020-2025
Table 41. By Country – South America WiFi Chip Sales, (M Units), 2026-2032
Table 42. By Country – Middle East & Africa WiFi Chip Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa WiFi Chip Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa WiFi Chip Sales, (M Units), 2020-2025
Table 45. By Country – Middle East & Africa WiFi Chip Sales, (M Units), 2026-2032
Table 46. Broadcomm Company Summary
Table 47. Broadcomm WiFi Chip Product Offerings
Table 48. Broadcomm WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 49. Broadcomm Key News & Latest Developments
Table 50. Qualcomm Company Summary
Table 51. Qualcomm WiFi Chip Product Offerings
Table 52. Qualcomm WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 53. Qualcomm Key News & Latest Developments
Table 54. Intel Company Summary
Table 55. Intel WiFi Chip Product Offerings
Table 56. Intel WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 57. Intel Key News & Latest Developments
Table 58. MediaTek Company Summary
Table 59. MediaTek WiFi Chip Product Offerings
Table 60. MediaTek WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 61. MediaTek Key News & Latest Developments
Table 62. NXP Company Summary
Table 63. NXP WiFi Chip Product Offerings
Table 64. NXP WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 65. NXP Key News & Latest Developments
Table 66. TI Company Summary
Table 67. TI WiFi Chip Product Offerings
Table 68. TI WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 69. TI Key News & Latest Developments
Table 70. Infineon Company Summary
Table 71. Infineon WiFi Chip Product Offerings
Table 72. Infineon WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 73. Infineon Key News & Latest Developments
Table 74. ON Semiconductor Company Summary
Table 75. ON Semiconductor WiFi Chip Product Offerings
Table 76. ON Semiconductor WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 77. ON Semiconductor Key News & Latest Developments
Table 78. Realtek Company Summary
Table 79. Realtek WiFi Chip Product Offerings
Table 80. Realtek WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 81. Realtek Key News & Latest Developments
Table 82. Triductor Technology Company Summary
Table 83. Triductor Technology WiFi Chip Product Offerings
Table 84. Triductor Technology WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 85. Triductor Technology Key News & Latest Developments
Table 86. Espressif Systems Company Summary
Table 87. Espressif Systems WiFi Chip Product Offerings
Table 88. Espressif Systems WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 89. Espressif Systems Key News & Latest Developments
Table 90. Beken Company Summary
Table 91. Beken WiFi Chip Product Offerings
Table 92. Beken WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 93. Beken Key News & Latest Developments
Table 94. ASR Microelectronics Company Summary
Table 95. ASR Microelectronics WiFi Chip Product Offerings
Table 96. ASR Microelectronics WiFi Chip Sales (M Units), Revenue (US$, Mn) and Average Price (US$/K Units) & (2020-2025)
Table 97. ASR Microelectronics Key News & Latest Developments
Table 98. WiFi Chip Capacity of Key Manufacturers in Global Market, 2023-2025 (M Units)
Table 99. Global WiFi Chip Capacity Market Share of Key Manufacturers, 2023-2025
Table 100. Global WiFi Chip Production by Region, 2020-2025 (M Units)
Table 101. Global WiFi Chip Production by Region, 2026-2032 (M Units)
Table 102. WiFi Chip Market Opportunities & Trends in Global Market
Table 103. WiFi Chip Market Drivers in Global Market
Table 104. WiFi Chip Market Restraints in Global Market
Table 105. WiFi Chip Raw Materials
Table 106. WiFi Chip Raw Materials Suppliers in Global Market
Table 107. Typical WiFi Chip Downstream
Table 108. WiFi Chip Downstream Clients in Global Market
Table 109. WiFi Chip Distributors and Sales Agents in Global Market

List of Figures
Figure 1. WiFi Chip Product Picture
Figure 2. WiFi Chip Segment by Type in 2024
Figure 3. WiFi Chip Segment by Application in 2024
Figure 4. Global WiFi Chip Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global WiFi Chip Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global WiFi Chip Revenue: 2020-2032 (US$, Mn)
Figure 8. WiFi Chip Sales in Global Market: 2020-2032 (M Units)
Figure 9. The Top 3 and 5 Players Market Share by WiFi Chip Revenue in 2024
Figure 10. Segment by Type – Global WiFi Chip Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global WiFi Chip Revenue Market Share, 2020-2032
Figure 12. Segment by Type – Global WiFi Chip Sales Market Share, 2020-2032
Figure 13. Segment by Type – Global WiFi Chip Price (US$/K Units), 2020-2032
Figure 14. Segment by Application – Global WiFi Chip Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global WiFi Chip Revenue Market Share, 2020-2032
Figure 16. Segment by Application – Global WiFi Chip Sales Market Share, 2020-2032
Figure 17. Segment by Application -Global WiFi Chip Price (US$/K Units), 2020-2032
Figure 18. By Region – Global WiFi Chip Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global WiFi Chip Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global WiFi Chip Revenue Market Share, 2020-2032
Figure 21. By Region – Global WiFi Chip Sales Market Share, 2020-2032
Figure 22. By Country – North America WiFi Chip Revenue Market Share, 2020-2032
Figure 23. By Country – North America WiFi Chip Sales Market Share, 2020-2032
Figure 24. United States WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 25. Canada WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 26. Mexico WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 27. By Country – Europe WiFi Chip Revenue Market Share, 2020-2032
Figure 28. By Country – Europe WiFi Chip Sales Market Share, 2020-2032
Figure 29. Germany WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 30. France WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 31. U.K. WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 32. Italy WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 33. Russia WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 34. Nordic Countries WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 35. Benelux WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 36. By Region – Asia WiFi Chip Revenue Market Share, 2020-2032
Figure 37. By Region – Asia WiFi Chip Sales Market Share, 2020-2032
Figure 38. China WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 39. Japan WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 40. South Korea WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 41. Southeast Asia WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 42. India WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 43. By Country – South America WiFi Chip Revenue Market Share, 2020-2032
Figure 44. By Country – South America WiFi Chip Sales, Market Share, 2020-2032
Figure 45. Brazil WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 46. Argentina WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 47. By Country – Middle East & Africa WiFi Chip Revenue, Market Share, 2020-2032
Figure 48. By Country – Middle East & Africa WiFi Chip Sales, Market Share, 2020-2032
Figure 49. Turkey WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 50. Israel WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 51. Saudi Arabia WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 52. UAE WiFi Chip Revenue, (US$, Mn), 2020-2032
Figure 53. Global WiFi Chip Production Capacity (M Units), 2020-2032
Figure 54. The Percentage of Production WiFi Chip by Region, 2024 VS 2032
Figure 55. WiFi Chip Industry Value Chain
Figure 56. Marketing Channels