Key Statistics
Key Takeaways
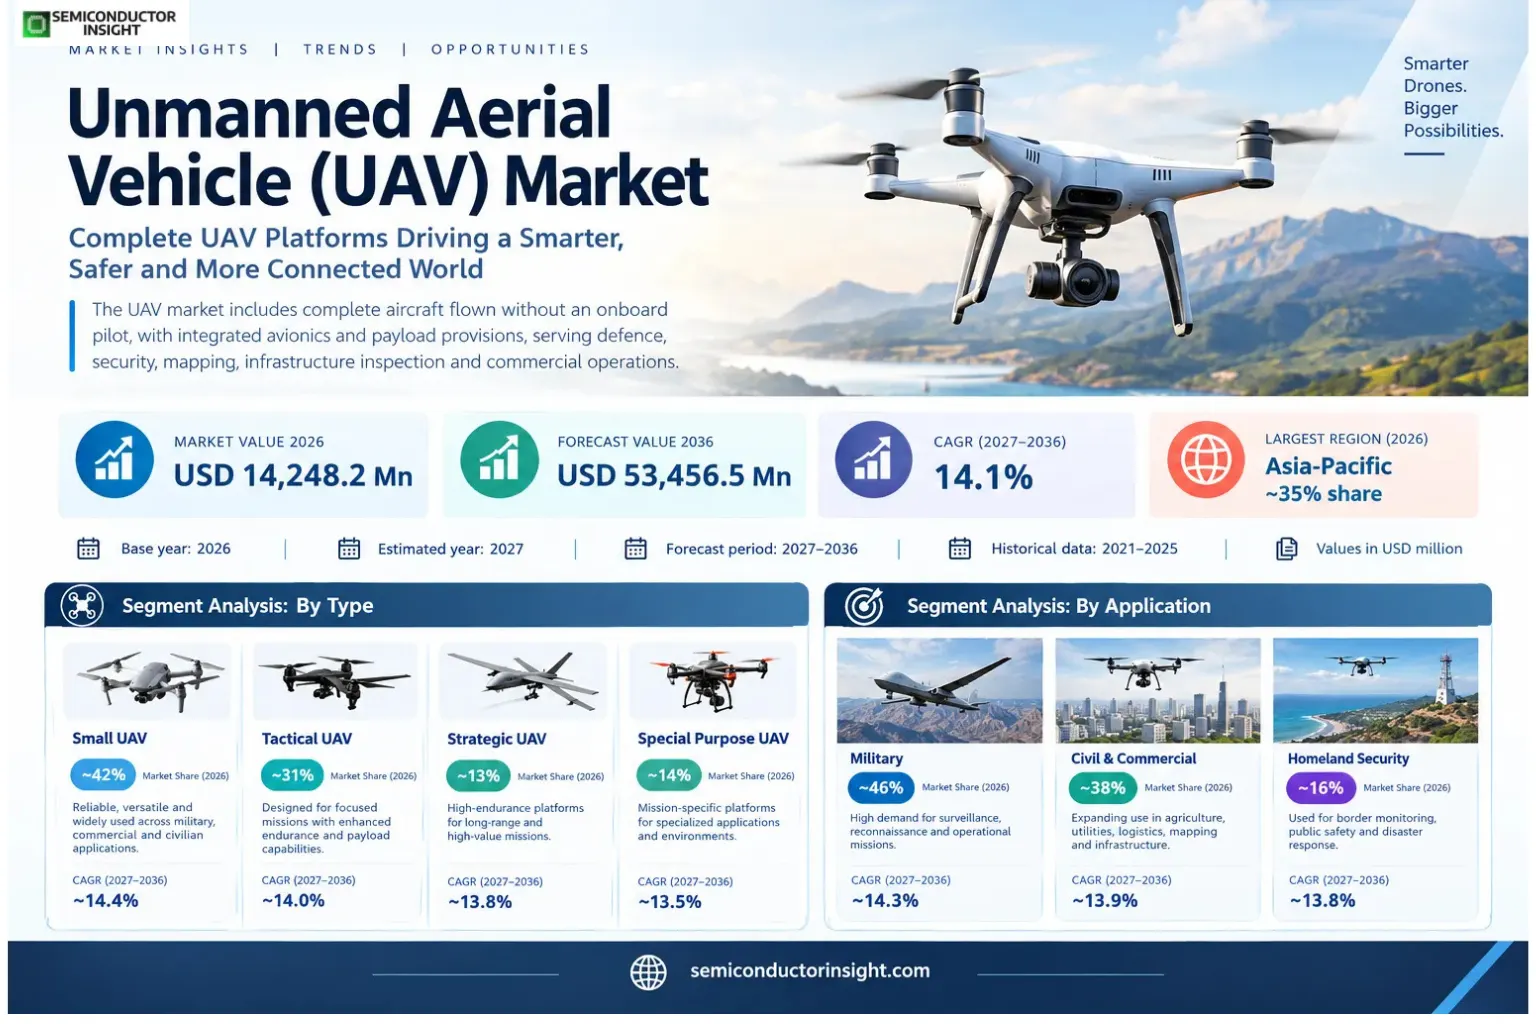
- Market value: The unmanned aerial vehicle (uav) market reached USD 14,248.2 million in 2026 and is projected to reach USD 53,456.5 million by 2036, representing a CAGR of 14.1% for 2027–2036 as customers adopt complete aircraft flown without an onboard pilot, including remotely piloted drones and aircraft capable of autonomous missions for defence, security, mapping, infrastructure inspection and commercial operations.
- Small UAV: The largest type category commands an estimated ~42% of 2026 revenue; its commercial significance arises from lower-cost remote observation and controlled unmanned missions without putting human pilots in hazardous environments. Adjacent designs compete on performance, qualification and total installed cost.
- Military: The leading application accounts for an estimated ~46% of 2026 sales, driven by end-user requirements for reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. Purchase decisions are typically channelled through defence procurement agencies, specialist aerospace distributors, enterprise drone dealers, public safety organisations and commercial flight operators.
- Asia-Pacific: Leading regional expenditure accounts for an estimated ~35% of 2026 revenue, with regional growth close to ~14.2% annually. Geography reflects China supplies major civil drone platforms while Japan, South Korea and India pursue inspection, agriculture, homeland security and local aerospace manufacturing.
- Commercial restraint: Flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links shape adoption. For drone-system suppliers, a strong customer pipeline does not automatically turn into processor or aircraft orders until qualification, safety and installation conditions are satisfied.
Unmanned Aerial Vehicle (UAV) Market Overview
Unmanned aerial vehicle (uav) market was valued at USD 14,248.2 million in 2026 and is projected to reach USD 53,456.5 million by 2036, at a CAGR of 14.1% during 2027–2036. Asia-Pacific is the largest regional market, with an estimated ~35% of 2026 expenditure. The market boundary covers whole UAV platform revenue including integrated avionics and payload provisions rather than the narrower semiconductor or remote sensing service revenue streams, rather than revenue from loosely connected service activities.
The unmanned aerial vehicle (uav) market covers complete aircraft flown without an onboard pilot, including remotely piloted drones and aircraft capable of autonomous missions for defence, security, mapping, infrastructure inspection and commercial operations. The accounting boundary is finished unmanned aircraft and integrated mission vehicles delivered to customers, excluding standalone chips, separately sold drone services, pilot training and counter-drone weapon systems. Customers evaluating a supplier measure reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. These selection criteria affect not only purchase price but also which parts of the value chain can earn recurring demand from military and homeland-security agencies, agricultural operators, utilities, engineering contractors, retailers and emergency responders.
Product scope should follow the transaction being priced: whole UAV platform revenue including integrated avionics and payload provisions rather than the narrower semiconductor or remote sensing service revenue streams. For that reason the analysis separates hardware purchases from wider economic activities such as inspected linear kilometres, mapped hectares, monitored borders, cargo flights and mission hours. Large end users generally specify delivery and support through defence procurement agencies, specialist aerospace distributors, enterprise drone dealers, public safety organisations and commercial flight operators. For uncrewed flight missions, this distinction prevents comparisons against adjacent markets that monetise the same deployments through different bills of materials and contracts.
Engineering advances focus on DJI Matrice enterprise drones, AeroVironment Switchblade systems and Parrot ANAFI professional micro-UAVs. Equipment designers are balancing flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links. Under aviation procurement, the most competitive solution is not necessarily the highest-throughput product: platform fit, environmental resilience and validation effort can dominate the field decision. In professional drone operations, the revenue mix therefore depends on deployment class, software release maturity and an ability to maintain technical service across successive equipment generations.
Demand originates in lower-cost remote observation and controlled unmanned missions without putting human pilots in hazardous environments. Across unmanned-aircraft fleets, as programmes move from test demonstrations to repeatable installation, operators must procure and qualify hardware at consistent volumes rather than ordering bespoke demonstration units. For uncrewed flight missions, this creates a larger role for standard modules, design-support documentation and distributors with verified configuration control. Across unmanned-aircraft fleets, commercial buyers also compare integration and maintenance expenditure over several years, which can outweigh the initial hardware invoice.
The immediate market transition is toward more practical and verifiable deployments of complete aircraft flown without an onboard pilot, including remotely piloted drones and aircraft capable of autonomous missions for defence, security, mapping, infrastructure inspection and commercial operations. For uncrewed flight missions, leading firms have begun to offer more integrated product families while buyers require evidence of operability under real workloads. The binding constraints are flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links. For UAV purchasers, product roadmaps are becoming closely aligned with certification milestones, installed asset cycles and the economics of reliable field operation rather than isolated engineering demonstrations.
Segment Analysis: By Type
By type, unmanned aerial vehicle (uav) is segmented into Small UAV, Tactical UAV, Strategic UAV, Special Purpose UAV. Small UAV leads with an estimated ~42% of 2026 revenue and demand across military and homeland-security agencies, agricultural operators, utilities, engineering contractors, retailers and emergency responders. In professional drone operations, the other types address alternative power, functional or mission requirements and are not interchangeable in system design. Each class has a different qualification pathway and unit-value profile.
| Type | Function | Market position |
|---|---|---|
| Small UAV | Small UAV addresses a defined performance and integration tier within unmanned aerial vehicle (uav). For Small UAV, the purchasing case depends on the customer’s target operating envelope and the integration tasks implied by reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. The Small UAV approval programme includes development-tool compatibility, power and thermal measurements and expected fault behaviour during normal service. Buyers of Small UAV additionally examine supplier continuity and whether the package can be substituted during future maintenance or design updates. | This type carries an estimated ~42% of 2026 market revenue and ~14.4% annual growth over the model window. For uncrewed flight missions, it is the largest type and provides the reference price point. The Small UAV procurement category competes on reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. A sustainable Small UAV supply programme depends on component availability, system-level qualification and repeat contracts won through defence procurement agencies, specialist aerospace distributors, enterprise drone dealers, public safety organisations and commercial flight operators. |
| Tactical UAV | Tactical UAV addresses a defined performance and integration tier within unmanned aerial vehicle (uav). For Tactical UAV, the purchasing case depends on the customer’s target operating envelope and the integration tasks implied by reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. The Tactical UAV approval programme includes development-tool compatibility, power and thermal measurements and expected fault behaviour during normal service. Buyers of Tactical UAV additionally examine supplier continuity and whether the package can be substituted during future maintenance or design updates. | This type carries an estimated ~31% of 2026 market revenue and ~14.0% annual growth over the model window. In professional drone operations, it addresses a narrower deployment profile with differentiated value per unit. The Tactical UAV procurement category competes on reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. A sustainable Tactical UAV supply programme depends on component availability, system-level qualification and repeat contracts won through defence procurement agencies, specialist aerospace distributors, enterprise drone dealers, public safety organisations and commercial flight operators. |
| Strategic UAV | Strategic UAV addresses a defined performance and integration tier within unmanned aerial vehicle (uav). For Strategic UAV, the purchasing case depends on the customer’s target operating envelope and the integration tasks implied by reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. The Strategic UAV approval programme includes development-tool compatibility, power and thermal measurements and expected fault behaviour during normal service. Buyers of Strategic UAV additionally examine supplier continuity and whether the package can be substituted during future maintenance or design updates. | This type carries an estimated ~13% of 2026 market revenue and ~13.8% annual growth over the model window. For customers assessing Strategic UAV market position, it addresses a narrower deployment profile with differentiated value per unit. The Strategic UAV procurement category competes on reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. A sustainable Strategic UAV supply programme depends on component availability, system-level qualification and repeat contracts won through defence procurement agencies, specialist aerospace distributors, enterprise drone dealers, public safety organisations and commercial flight operators. |
| Special Purpose UAV | Special Purpose UAV addresses a defined performance and integration tier within unmanned aerial vehicle (uav). For Special Purpose UAV, the purchasing case depends on the customer’s target operating envelope and the integration tasks implied by reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. The Special Purpose UAV approval programme includes development-tool compatibility, power and thermal measurements and expected fault behaviour during normal service. Buyers of Special Purpose UAV additionally examine supplier continuity and whether the package can be substituted during future maintenance or design updates. | This type carries an estimated ~14% of 2026 market revenue and ~13.5% annual growth over the model window. In procurement programmes centred on Special Purpose UAV market position, it addresses a narrower deployment profile with differentiated value per unit. The Special Purpose UAV procurement category competes on reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. A sustainable Special Purpose UAV supply programme depends on component availability, system-level qualification and repeat contracts won through defence procurement agencies, specialist aerospace distributors, enterprise drone dealers, public safety organisations and commercial flight operators. |
Segment Analysis: By Application
By application, unmanned aerial vehicle (uav) is divided among Military, Civil & Commercial, Homeland Security. Military has the largest estimated ~46% share in 2026. Customer requirements differ as strongly as military and homeland-security agencies, agricultural operators, utilities, engineering contractors, retailers and emergency responders differ from one another. Across unmanned-aircraft fleets, suppliers adapt their service, training and qualification plans to these individual purchasing environments.
| Application | Demand characteristics |
|---|---|
| Military | Military accounts for an estimated ~46% of 2026 market value and is modelled at roughly ~14.3% annual growth. Orders for Military are triggered by requirements for inspected linear kilometres, mapped hectares, monitored borders, cargo flights and mission hours, as well as reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. Before purchasing for Military, operators review operating conditions, application software, platform resilience and how field maintenance will be handled. The commercial success of Military follows actually deployed applications rather than broad technical specifications alone. |
| Civil & Commercial | Civil & Commercial accounts for an estimated ~38% of 2026 market value and is modelled at roughly ~13.9% annual growth. Orders for Civil & Commercial are triggered by requirements for inspected linear kilometres, mapped hectares, monitored borders, cargo flights and mission hours, as well as reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. Before purchasing for Civil & Commercial, operators review operating conditions, application software, platform resilience and how field maintenance will be handled. The commercial success of Civil & Commercial follows actually deployed applications rather than broad technical specifications alone. |
| Homeland Security | Homeland Security accounts for an estimated ~16% of 2026 market value and is modelled at roughly ~13.8% annual growth. Orders for Homeland Security are triggered by requirements for inspected linear kilometres, mapped hectares, monitored borders, cargo flights and mission hours, as well as reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. Before purchasing for Homeland Security, operators review operating conditions, application software, platform resilience and how field maintenance will be handled. The commercial success of Homeland Security follows actually deployed applications rather than broad technical specifications alone. |
The route to market usually passes through defence procurement agencies, specialist aerospace distributors, enterprise drone dealers, public safety organisations and commercial flight operators. Under aviation procurement, customer qualification can take longer than component or airframe production, especially where safety and interoperability are important. For uncrewed flight missions, a fast-growing end market does not always translate into a similar component-revenue growth rate because replacement cycles, configuration standards and negotiated prices vary. For UAV purchasers, the channel analysis therefore separates equipment demand from downstream service earnings and investigates which firms actually own the purchasing decision.
Regional Analysis
Asia-Pacific leads the global unmanned aerial vehicle (uav) market in 2026 with an estimated ~35% share. The three largest regions are Asia-Pacific (~35%), North America (~28%), Europe (~24%), while Middle East & Africa has the fastest modelled growth at ~14.5% CAGR. For uncrewed flight missions, regional supply and demand are concentrated in Asia-Pacific through local investment and distribution networks. Across unmanned-aircraft fleets, smaller regions have different adoption gates rather than simply representing scaled-down versions of leading markets.
How does the commercial logic differ by region in the unmanned aerial vehicle (uav) market?
Global demand varies because flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links. For drone-system suppliers, north America, Europe, Asia-Pacific, South America and the Middle East and Africa therefore differ in qualification practice, operating geography and available procurement channels. Under aviation procurement, local supplier support and customer experience can matter as much as technology capability when systems must be deployed and serviced at scale. Under aviation procurement, consequently the regional estimate is a distribution of equipment expenditure, not a count of every related downstream service transaction.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~35%) | Measured (~14.2% CAGR) | Manufacturing base and broad mission demand | Supplier selection in Asia-Pacific depends on manufacturing base and broad mission demand. China supplies major civil drone platforms while Japan, South Korea and India pursue inspection, agriculture, homeland security and local aerospace manufacturing. In Asia-Pacific, supply awards depend on reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility, performance under field workloads and dependable local technical support. Across unmanned-aircraft fleets, asia-Pacific procurement policies determine whether equipment purchases move directly from OEMs, via distributors or through larger system contracts. |
| North America | Second (~28%) | Measured (~14.4% CAGR) | Defense purchasing and commercial waivers | Supplier selection in North America depends on defense purchasing and commercial waivers. U.S. procurement includes tactical unmanned aircraft and loitering systems, while FAA rules and delivery partnerships influence civilian fleet growth. In North America, supply awards depend on reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility, performance under field workloads and dependable local technical support. For drone-system suppliers, north America procurement policies determine whether equipment purchases move directly from OEMs, via distributors or through larger system contracts. |
| Europe | Third (~24%) | Measured (~13.8% CAGR) | Regulated commercial airspace and defence readiness | Supplier selection in Europe depends on regulated commercial airspace and defence readiness. EASA U-space certification and European policy support more systematic airspace services, with continental OEMs supplying professional and defence UAV systems. In Europe, supply awards depend on reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility, performance under field workloads and dependable local technical support. For uncrewed flight missions, europe procurement policies determine whether equipment purchases move directly from OEMs, via distributors or through larger system contracts. |
| Middle East & Africa | Fourth (~8%) | Fastest (~14.5% CAGR) | Border surveillance and harsh-environment operations | Supplier selection in Middle East & Africa depends on border surveillance and harsh-environment operations. Regional buyers pursue long-range monitoring, mapping and inspection, with high temperatures and infrastructure coverage influencing endurance and maintainability. In Middle East & Africa, supply awards depend on reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility, performance under field workloads and dependable local technical support. For uncrewed flight missions, middle East & Africa procurement policies determine whether equipment purchases move directly from OEMs, via distributors or through larger system contracts. |
| South America | Fifth (~5%) | Measured (~13.7% CAGR) | Agricultural monitoring and geographic scale | Supplier selection in South America depends on agricultural monitoring and geographic scale. Brazilian farms and utilities provide inspection demand, while mountains, remote connectivity and import conditions affect deployment options in the wider region. In South America, supply awards depend on reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility, performance under field workloads and dependable local technical support. For uncrewed flight missions, south America procurement policies determine whether equipment purchases move directly from OEMs, via distributors or through larger system contracts. |
Competitive Landscape
Competitive dynamics in unmanned aerial vehicle (uav) span silicon or vehicle manufacturers, platform integrators and procurement intermediaries. Leading direct suppliers include DJI Innovations, AeroVironment, Parrot, Israel Aerospace Industries, while other profiled companies participate through adjacent platforms or customer programmes. Competition hinges on reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. Under aviation procurement, buyer access requires field validation, software support and a credible plan for spare parts and technical continuity.
For uncrewed flight missions, product leadership is defined by real implementation experience rather than company-wide revenue. DJI Innovations, AeroVironment, Parrot, Israel Aerospace Industries have portfolios relevant to the sector, although each operates across a broader collection of products. For uncrewed flight missions, it is important to assess only the relevant platform or device families when comparing supplier positions. Under aviation procurement, procurement wins also depend on reference designs, channel access and capability to fix deployment issues after installation.
Suppliers compete across multiple qualification thresholds. Buyers seek reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility and increasingly request integration toolchains, compliance records and known configurations. For UAV purchasers, continuous product revisions must be compatible with the customer’s service life and existing assets. In professional drone operations, as a result, early price discounts do not guarantee a design win unless a supplier can maintain support through complete deployment cycles.
Adjacent companies are influential without necessarily supplying the market-defining device. Cybaero can affect platform specifications, distribution or adoption economics, while other manufacturers supply supporting electronics. For UAV purchasers, including the entire revenue of a service platform or parent company would overstate the equipment market. In professional drone operations, tier comparisons distinguish direct hardware suppliers, niche specialists and system-level ecosystem participants.
For UAV purchasers, the most durable commercial advantage comes from repeatable delivery rather than isolated demonstrations. For drone-system suppliers, component traceability, repair logistics, manufacturing capacity and the ability to meet an OEM testing protocol are material competitive factors. When flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links, customers favour suppliers capable of maintaining stable product revisions. In professional drone operations, this favours vendors that combine technical capability with dependable field support and contract discipline.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | DJI Innovations, AeroVironment, Parrot, Israel Aerospace Industries | Direct hardware suppliers compete on a combination of validated product capability and timely deliveries. The relevant offering must satisfy reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. For drone-system suppliers, when evaluating the Tier 1 category, purchasers consider interoperability, component life and testing evidence, not simply the supplier’s brand. The Tier 1 business grows through repeated orders from established defence procurement agencies, specialist aerospace distributors, enterprise drone dealers, public safety organisations and commercial flight operators. |
| Tier 2 | Airbus Group, Microdrones, Boeing | Specialised vendors concentrate on narrower functional or customer niches. Their products may offer favourable trade-offs against flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links. For UAV purchasers, for the Tier 2 supplier group, sales opportunities depend on the buyer’s willingness to support additional integration and qualification work. For UAV purchasers, for Tier 2 providers, long-term service arrangements can offset their smaller sales organisations and manufacturing footprints. |
| Ecosystem | Cybaero | Systems and service participants influence the final design without always producing the market-defining hardware. The Ecosystem participants shape customer requirements, installation plans and acceptance criteria connected to inspected linear kilometres, mapped hectares, monitored borders, cargo flights and mission hours. For drone-system suppliers, including the full revenue of these Ecosystem participants as direct product-market sales would double-count adjacent activity. Across unmanned-aircraft fleets, the supplier model therefore treats these participants separately from manufacturers of the primary hardware. |
Key companies profiled
- DJI Innovations
- AeroVironment
- Cybaero
- Parrot
- Israel Aerospace Industries
- Airbus Group
- Microdrones
- Boeing
Production Capacity Analysis
Production in the unmanned aerial vehicle (uav) market combines product development, contracted manufacture, test and field qualification. Capacity must be evaluated for the equipment covered by finished unmanned aircraft and integrated mission vehicles delivered to customers, excluding standalone chips, separately sold drone services, pilot training and counter-drone weapon systems. In professional drone operations, supplier output depends on reliable upstream components and the availability of teams able to certify each platform generation. For UAV purchasers, installed production lines are not equivalent to saleable market output when customer acceptance testing and configuration restrictions remain binding.
Upstream manufacturing begins with specialised equipment and electronics matched to complete aircraft flown without an onboard pilot, including remotely piloted drones and aircraft capable of autonomous missions for defence, security, mapping, infrastructure inspection and commercial operations. For uncrewed flight missions, designs are converted into repeatable builds using supplier-qualified parts, automated verification and controlled firmware releases. For UAV purchasers, factories operating multiple programmes must schedule production batches according to expected customer acceptance and servicing demand. For UAV purchasers, the resulting throughput can differ substantially from nominal assembly capacity, especially during early qualification and engineering changes.
Diversified production and overseas service centres have a direct effect on the cost of unmanned aerial vehicle (uav). For uncrewed flight missions, for customers operating across continents, replacement units and regulatory documentation can be as important as local final assembly. Across unmanned-aircraft fleets, companies may therefore dual-source electronics or maintain additional field-stock hubs where import lead times are unpredictable. For uncrewed flight missions, this reduces the operational disruption that can result when equipment is repaired far from its initial manufacturing plant.
The practical bottlenecks include flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links. Across unmanned-aircraft fleets, manufacturers must control incoming components, update software securely and demonstrate consistent performance in representative operating conditions. In professional drone operations, a design sold into a regulated mission cannot be readily modified without further validation. For drone-system suppliers, the commercial effect is a preference for stable approved parts and a need to fund parallel product generations during technology transitions.
Market Dynamics
Market dynamics reflect customer demand for lower-cost remote observation and controlled unmanned missions without putting human pilots in hazardous environments, balanced against flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links. In professional drone operations, the drivers below describe directional factors on growth rather than independently measured contributions to the headline forecast. For uncrewed flight missions, technology choices are mediated by channel access and programme commissioning schedules. Across unmanned-aircraft fleets, projected market revenue therefore depends on actual procurement milestones, hardware qualification and completed operational rollouts.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Defence reconnaissance and tactical demand | +0.3% | Global / selected adopter markets | 2026–2036 |
| Enterprise inspection automation | +0.5% | Global / selected adopter markets | 2026–2036 |
| Safer low-altitude aviation rules | +0.6% | Global / selected adopter markets | 2026–2036 |
| Payload and flight-controller improvement | +0.8% | Global / selected adopter markets | 2026–2036 |
| Fleet or installed-base renewal | +0.9% | Global / selected adopter markets | 2026–2036 |
Defence reconnaissance and tactical demand
Defence reconnaissance and tactical demand supports demand for unmanned aerial vehicle (uav). The commercial effect of defence reconnaissance and tactical demand is observed when customers require inspected linear kilometres, mapped hectares, monitored borders, cargo flights and mission hours in a reliable operating environment. Purchasers affected by defence reconnaissance and tactical demand translate requirements into specifications for reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. In defence reconnaissance and tactical demand programmes, the sale depends on field-validation success and the supplier’s ability to sustain volume production rather than demand estimates alone.
Enterprise inspection automation
Enterprise inspection automation supports demand for unmanned aerial vehicle (uav). The commercial effect of enterprise inspection automation is observed when customers require inspected linear kilometres, mapped hectares, monitored borders, cargo flights and mission hours in a reliable operating environment. Purchasers affected by enterprise inspection automation translate requirements into specifications for reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. In enterprise inspection automation programmes, the sale depends on field-validation success and the supplier’s ability to sustain volume production rather than demand estimates alone.
Safer low-altitude aviation rules
Safer low-altitude aviation rules supports demand for unmanned aerial vehicle (uav). The commercial effect of safer low-altitude aviation rules is observed when customers require inspected linear kilometres, mapped hectares, monitored borders, cargo flights and mission hours in a reliable operating environment. Purchasers affected by safer low-altitude aviation rules translate requirements into specifications for reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. In safer low-altitude aviation rules programmes, the sale depends on field-validation success and the supplier’s ability to sustain volume production rather than demand estimates alone.
Payload and flight-controller improvement
Payload and flight-controller improvement supports demand for unmanned aerial vehicle (uav). The commercial effect of payload and flight-controller improvement is observed when customers require inspected linear kilometres, mapped hectares, monitored borders, cargo flights and mission hours in a reliable operating environment. Purchasers affected by payload and flight-controller improvement translate requirements into specifications for reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. In payload and flight-controller improvement programmes, the sale depends on field-validation success and the supplier’s ability to sustain volume production rather than demand estimates alone.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| BVLOS and airspace permission barriers | -0.2% | Selected end markets | 2026–2036 |
| Battery endurance and adverse weather | -0.3% | Selected end markets | 2026–2036 |
| Procurement controls and secure component sourcing | -0.4% | Selected end markets | 2026–2036 |
| Airworthiness, privacy and insurance burden | -0.6% | Selected end markets | 2026–2036 |
BVLOS and airspace permission barriers
BVLOS and airspace permission barriers can delay expenditure on unmanned aerial vehicle (uav). Buyers facing flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links may reduce fleet growth, defer system integration or select lower-cost equipment with longer lead times. The response to bvlos and airspace permission barriers requires suppliers to prove performance and offer maintainable lifecycle commitments to overcome these constraints. This specific restraint, bvlos and airspace permission barriers, extends procurement schedules despite the presence of a credible long-term requirement.
Battery endurance and adverse weather
Battery endurance and adverse weather can delay expenditure on unmanned aerial vehicle (uav). For commercial projects involving Battery endurance and adverse weather, buyers facing flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links may reduce fleet growth, defer system integration or select lower-cost equipment with longer lead times. The response to battery endurance and adverse weather requires suppliers to prove performance and offer maintainable lifecycle commitments to overcome these constraints. This specific restraint, battery endurance and adverse weather, extends procurement schedules despite the presence of a credible long-term requirement.
Procurement controls and secure component sourcing
Procurement controls and secure component sourcing can delay expenditure on unmanned aerial vehicle (uav). In service networks supporting Procurement controls and secure component sourcing, buyers facing flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links may reduce fleet growth, defer system integration or select lower-cost equipment with longer lead times. The response to procurement controls and secure component sourcing requires suppliers to prove performance and offer maintainable lifecycle commitments to overcome these constraints. This specific restraint, procurement controls and secure component sourcing, extends procurement schedules despite the presence of a credible long-term requirement.
Airworthiness, privacy and insurance burden
Airworthiness, privacy and insurance burden can delay expenditure on unmanned aerial vehicle (uav). When selecting equipment for Airworthiness, privacy and insurance burden, buyers facing flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links may reduce fleet growth, defer system integration or select lower-cost equipment with longer lead times. The response to airworthiness, privacy and insurance burden requires suppliers to prove performance and offer maintainable lifecycle commitments to overcome these constraints. This specific restraint, airworthiness, privacy and insurance burden, extends procurement schedules despite the presence of a credible long-term requirement.
MARKET OPPORTUNITIES
Critical infrastructure remote inspection
Critical infrastructure remote inspection provides a route into adjacent customer segments for unmanned aerial vehicle (uav). The commercial opportunity is to solve a specific deployment problem involving reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. New offerings targeting critical infrastructure remote inspection need documented interoperability, reliable suppliers and credible post-sale support. For critical infrastructure remote inspection, the strongest value proposition combines the desired capability with lower integration risk, not with technical novelty in isolation.
Automated retail and medical delivery
Automated retail and medical delivery provides a route into adjacent customer segments for unmanned aerial vehicle (uav). Across supply agreements concerning Automated retail and medical delivery, the commercial opportunity is to solve a specific deployment problem involving reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. New offerings targeting automated retail and medical delivery need documented interoperability, reliable suppliers and credible post-sale support. For automated retail and medical delivery, the strongest value proposition combines the desired capability with lower integration risk, not with technical novelty in isolation.
Interoperable low-altitude traffic services
Interoperable low-altitude traffic services provides a route into adjacent customer segments for unmanned aerial vehicle (uav). For customers assessing Interoperable low-altitude traffic services, the commercial opportunity is to solve a specific deployment problem involving reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. New offerings targeting interoperable low-altitude traffic services need documented interoperability, reliable suppliers and credible post-sale support. For interoperable low-altitude traffic services, the strongest value proposition combines the desired capability with lower integration risk, not with technical novelty in isolation.
Multi-sensor search and rescue missions
Multi-sensor search and rescue missions provides a route into adjacent customer segments for unmanned aerial vehicle (uav). In procurement programmes centred on Multi-sensor search and rescue missions, the commercial opportunity is to solve a specific deployment problem involving reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. New offerings targeting multi-sensor search and rescue missions need documented interoperability, reliable suppliers and credible post-sale support. For multi-sensor search and rescue missions, the strongest value proposition combines the desired capability with lower integration risk, not with technical novelty in isolation.
Supply Chain Analysis
The value chain for unmanned aerial vehicle (uav) links design and qualification to production, distribution and field support. Its revenue boundary remains whole UAV platform revenue including integrated avionics and payload provisions rather than the narrower semiconductor or remote sensing service revenue streams. Product sourcing is complicated by flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links. For drone-system suppliers, a dependable supply chain must therefore track revisions, validate suppliers and maintain spares for the actual operating life of deployed hardware.
Upstream. The upstream stage influences cost and reliability for unmanned aerial vehicle (uav). Upstream participants manage flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links while protecting availability of parts and validated software. Under aviation procurement, work at the upstream stage must support traceable revisions, acceptance documentation and the customer’s maintenance model. For uncrewed flight missions, the upstream performance record shapes which firms can secure long-lived supply commitments rather than one-time prototype orders.
Manufacturing. The manufacturing stage influences cost and reliability for unmanned aerial vehicle (uav). Manufacturing participants manage flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links while protecting availability of parts and validated software. In professional drone operations, work at the manufacturing stage must support traceable revisions, acceptance documentation and the customer’s maintenance model. Under aviation procurement, the manufacturing performance record shapes which firms can secure long-lived supply commitments rather than one-time prototype orders.
Channel. The channel stage influences cost and reliability for unmanned aerial vehicle (uav). Channel participants manage flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links while protecting availability of parts and validated software. Across unmanned-aircraft fleets, work at the channel stage must support traceable revisions, acceptance documentation and the customer’s maintenance model. Under aviation procurement, the channel performance record shapes which firms can secure long-lived supply commitments rather than one-time prototype orders.
Downstream. The downstream stage influences cost and reliability for unmanned aerial vehicle (uav). Downstream participants manage flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links while protecting availability of parts and validated software. In professional drone operations, work at the downstream stage must support traceable revisions, acceptance documentation and the customer’s maintenance model. In professional drone operations, the downstream performance record shapes which firms can secure long-lived supply commitments rather than one-time prototype orders.
Recent Developments
- 5 October 2026 Announced
Wing reported new retail delivery metros on 5 October 2026. In professional drone operations, the first-party statement identifies a concrete product line, commercial release or platform partnership, allowing procurement teams to inspect the named capability instead of relying on broad technology claims. For unmanned aerial vehicle (uav) customers, the significance is the relationship between new retail delivery metros and the choice of reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. Across unmanned-aircraft fleets, the announcement also helps buyers assess supplier capability, real deployments and which product generation can enter their purchasing process. For UAV purchasers, market impact depends on subsequent adoption, not the existence of a press announcement alone. Source - 26 August 2026 Announced
AeroVironment reported switchblade 600 order on 26 August 2026. Within field deployments associated with 26 August 2026 Announced release, the first-party statement identifies a concrete product line, commercial release or platform partnership, allowing procurement teams to inspect the named capability instead of relying on broad technology claims. For unmanned aerial vehicle (uav) customers, the significance is the relationship between switchblade 600 order and the choice of reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. From the perspective of operators using 26 August 2026 Announced release, the announcement also helps buyers assess supplier capability, real deployments and which product generation can enter their purchasing process. For manufacturers serving 26 August 2026 Announced release, market impact depends on subsequent adoption, not the existence of a press announcement alone. Source - 14 July 2026 Announced
European Commission reported drone strategy 2.0 review on 14 July 2026. For UAV purchasers, the official publication documents a specific product, programme or technical requirement, and its date helps distinguish an implemented milestone from a later vendor ambition. For unmanned aerial vehicle (uav) customers, the significance is the relationship between drone strategy 2.0 review and the choice of reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. During integration of 14 July 2026 Announced release, the announcement also helps buyers assess supplier capability, real deployments and which product generation can enter their purchasing process. In lifecycle planning for 14 July 2026 Announced release, market impact depends on subsequent adoption, not the existence of a press announcement alone. Source - 8 June 2026 Announced
Wing reported seven new delivery metros on 8 June 2026. Within qualification procedures for 8 June 2026 Announced release, the first-party statement identifies a concrete product line, commercial release or platform partnership, allowing procurement teams to inspect the named capability instead of relying on broad technology claims. For unmanned aerial vehicle (uav) customers, the significance is the relationship between seven new delivery metros and the choice of reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. For commercial projects involving 8 June 2026 Announced release, the announcement also helps buyers assess supplier capability, real deployments and which product generation can enter their purchasing process. In service networks supporting 8 June 2026 Announced release, market impact depends on subsequent adoption, not the existence of a press announcement alone. Source - 11 January 2026 Announced
Wing reported drone delivery expansion on 11 January 2026. In procurement programmes centred on 11 January 2026 Announced release, the first-party statement identifies a concrete product line, commercial release or platform partnership, allowing procurement teams to inspect the named capability instead of relying on broad technology claims. For unmanned aerial vehicle (uav) customers, the significance is the relationship between drone delivery expansion and the choice of reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. Within field deployments associated with 11 January 2026 Announced release, the announcement also helps buyers assess supplier capability, real deployments and which product generation can enter their purchasing process. From the perspective of operators using 11 January 2026 Announced release, market impact depends on subsequent adoption, not the existence of a press announcement alone. Source - 10 June 2025 Announced
DJI reported matrice 400 launch on 10 June 2025. When selecting equipment for 10 June 2025 Announced release, the first-party statement identifies a concrete product line, commercial release or platform partnership, allowing procurement teams to inspect the named capability instead of relying on broad technology claims. For unmanned aerial vehicle (uav) customers, the significance is the relationship between matrice 400 launch and the choice of reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. Across supply agreements concerning 10 June 2025 Announced release, the announcement also helps buyers assess supplier capability, real deployments and which product generation can enter their purchasing process. For customers assessing 10 June 2025 Announced release, market impact depends on subsequent adoption, not the existence of a press announcement alone. Source - 14 May 2025 Announced
EASA reported u-space certification on 14 May 2025. For manufacturers serving 14 May 2025 Announced release, the official publication documents a specific product, programme or technical requirement, and its date helps distinguish an implemented milestone from a later vendor ambition. For unmanned aerial vehicle (uav) customers, the significance is the relationship between u-space certification and the choice of reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. During integration of 14 May 2025 Announced release, the announcement also helps buyers assess supplier capability, real deployments and which product generation can enter their purchasing process. In lifecycle planning for 14 May 2025 Announced release, market impact depends on subsequent adoption, not the existence of a press announcement alone. Source - 8 January 2025 Announced
DJI reported matrice 4 launch on 8 January 2025. Within qualification procedures for 8 January 2025 Announced release, the first-party statement identifies a concrete product line, commercial release or platform partnership, allowing procurement teams to inspect the named capability instead of relying on broad technology claims. For unmanned aerial vehicle (uav) customers, the significance is the relationship between matrice 4 launch and the choice of reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. For commercial projects involving 8 January 2025 Announced release, the announcement also helps buyers assess supplier capability, real deployments and which product generation can enter their purchasing process. In service networks supporting 8 January 2025 Announced release, market impact depends on subsequent adoption, not the existence of a press announcement alone. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2036 |
| Historical Period | 2021–2025 |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2027–2036 |
| 2026 Market Size | USD 14,248.2 million |
| 2027 Estimated Size | USD 16,262.4 million |
| 2036 Forecast Size | USD 53,456.5 million |
| CAGR (2027–2036) | 14.1% |
| Unit | USD million; equipment and device sales |
| Market Definition | finished unmanned aircraft and integrated mission vehicles delivered to customers, excluding standalone chips, separately sold drone services, pilot training and counter-drone weapon systems |
| By Type | Small UAV · Tactical UAV · Strategic UAV · Special Purpose UAV |
| By Application | Military · Civil & Commercial · Homeland Security |
| By Region | Regional revenue values are attributed to the procurement geography; the estimate includes five global regions. Asia-PacificChina, Japan, South Korea, India North AmericaUnited States, Canada, Mexico EuropeGermany, France, United Kingdom, Italy Middle East & AfricaSaudi Arabia, United Arab Emirates, South Africa South AmericaBrazil, Argentina, Chile |
| Key Companies Profiled | DJI Innovations, AeroVironment, Cybaero, Parrot, Israel Aerospace Industries, Airbus Group, Microdrones, Boeing |
| Customization Scope | Country-level type and application revenue, manufacturer capability, buying-channel mapping, technical qualification, systems design and pricing for unmanned aerial vehicle (uav). |
Frequently Asked Questions
What is the size and forecast of the unmanned aerial vehicle (uav) market?
The market is valued at USD 14,248.2 million in 2026 and is projected to reach USD 53,456.5 million by 2036, representing CAGR of 14.1% over 2027–2036. The category covers complete aircraft flown without an onboard pilot, including remotely piloted drones and aircraft capable of autonomous missions for defence, security, mapping, infrastructure inspection and commercial operations. For uncrewed flight missions, buyers should compare these figures only with similarly bounded product revenue rather than service or system totals from adjacent categories.
Which type has the largest share in the unmanned aerial vehicle (uav) market?
Small UAV is the largest type with an estimated ~42% share of 2026 value. It is supported by lower-cost remote observation and controlled unmanned missions without putting human pilots in hazardous environments. In professional drone operations, the remaining categories meet different operating envelopes, so an equipment producer may need multiple solutions even when the leading class captures most of the market revenue.
Which application leads unmanned aerial vehicle (uav) demand?
Military leads with an estimated ~46% of 2026 revenue. This application values reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. In professional drone operations, demand is converted into sales when customers pass their engineering and acceptance tests, establish operating procedures and secure a source of spare devices or replacement airframes.
Which is the largest regional market for unmanned aerial vehicle (uav)?
Asia-Pacific leads with an estimated ~35% of 2026 revenue, while Middle East & Africa has the quickest modeled expansion. When selecting equipment for FAQ: Which is the largest regional market for unmanned aerial vehicle (uav)?, china supplies major civil drone platforms while Japan, South Korea and India pursue inspection, agriculture, homeland security and local aerospace manufacturing. For drone-system suppliers, regional share differences reflect purchasing and equipment deployment rather than counting every service enabled by the hardware.
What drives growth in the unmanned aerial vehicle (uav) market?
The strongest underlying driver is lower-cost remote observation and controlled unmanned missions without putting human pilots in hazardous environments. Equipment must still meet customer requirements for reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. For uncrewed flight missions, suppliers that can combine reliable performance with software and integration support are better positioned to convert demonstrations into repeatable procurement programmes.
What limits wider adoption of unmanned aerial vehicle (uav)?
Important restrictions include flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links. For uncrewed flight missions, these concerns affect schedules and the proportion of potential users ready to fund deployments. Under aviation procurement, vendors can mitigate part of the risk with documented validation, long-term maintenance agreements and multiple qualified sources, but they cannot remove all policy or operating constraints.
Which companies are profiled in the unmanned aerial vehicle (uav) market?
The company coverage includes DJI Innovations, AeroVironment, Cybaero, Parrot, Israel Aerospace Industries, Airbus Group. Across unmanned-aircraft fleets, some names are directly relevant equipment suppliers while others participate through adjacent technologies, platform procurement or integration partnerships. Under aviation procurement, commercial assessment should distinguish direct product revenue from other corporate sales to avoid false market-share comparisons. Operating choices are influenced by flight-authorisation restrictions, beyond-visual-line-of-sight oversight, endurance and payload trade-offs, airworthiness and secure command links. Under aviation procurement, customer evaluation extends beyond the upfront price and includes support across expected service life. Across unmanned-aircraft fleets, those considerations make a consistent market boundary essential for comparing suppliers.
How is unmanned aerial vehicle (uav) segmented?
Type segments comprise Small UAV, Tactical UAV, Strategic UAV, Special Purpose UAV. Application categories comprise Military, Civil & Commercial, Homeland Security. For drone-system suppliers, these dimensions describe the same global expenditure from different perspectives and should not be added together. For UAV purchasers, geographic coverage spans North America, Europe, Asia-Pacific, South America and Middle East and Africa.
How does innovation affect supplier choice in the unmanned aerial vehicle (uav) market?
Innovations centre on DJI Matrice enterprise drones, AeroVironment Switchblade systems and Parrot ANAFI professional micro-UAVs. Their commercial value depends on how effectively the customer can deploy them, including reliable flight endurance, sensor-to-airframe integration, hardened navigation, safe command links and mission-specific payload compatibility. Under aviation procurement, companies increasingly choose products with clear technical support, mature software or mission controls and predictable maintenance instead of paying solely for maximum specifications.
What does the unmanned aerial vehicle (uav) study include and exclude?
The scope includes finished unmanned aircraft and integrated mission vehicles delivered to customers, excluding standalone chips, separately sold drone services, pilot training and counter-drone weapon systems. For drone-system suppliers, it excludes unrelated revenues from surrounding services and infrastructure so that segment and regional comparisons remain meaningful. For UAV purchasers, the analysis covers production capability, competitive positioning, procurement practices, growth forces and leading product categories in a 2026 base-year and 2036 forecast framework.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF