Key Statistics
Key Takeaways
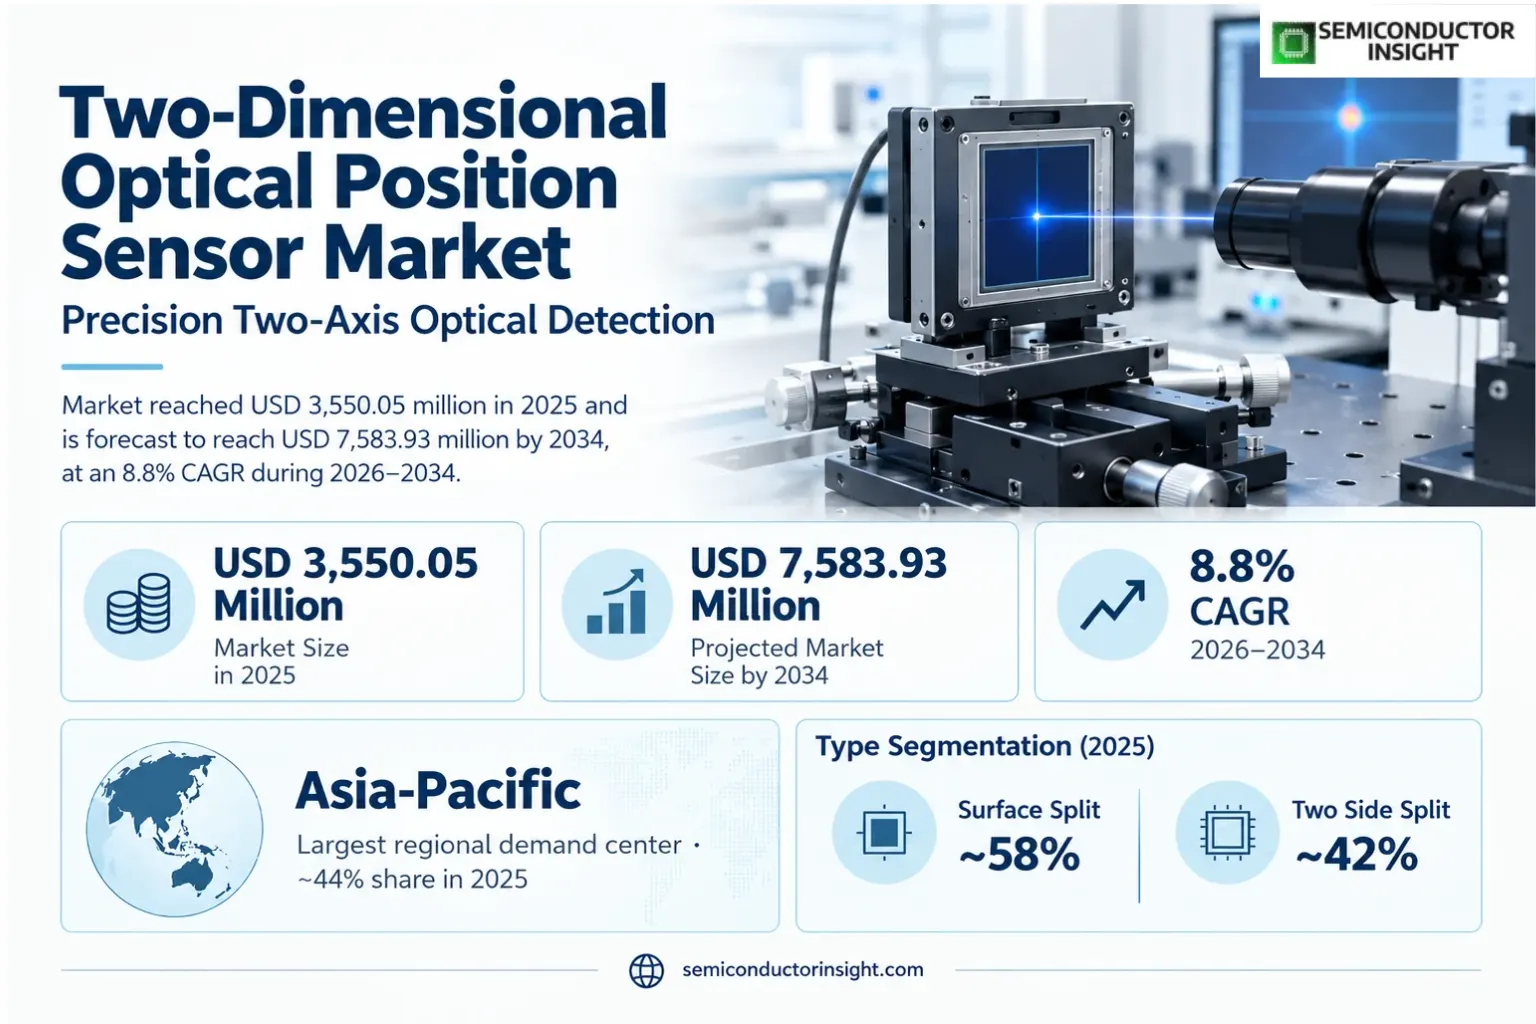
- Market value: Global revenue is modeled at USD 3,550.05 million in 2025, rising to USD 7,583.93 million by 2034 at a 8.8% CAGR during 2026–2034. The forecast extends the original 2023 and 2030 monetary observations without treating downstream instrument turnover as detector shipments.
- Two product geometries: Surface Split accounts for an estimated ~58% of base-year type revenue and Two Side Split for ~42%. Their respective 2034 modeled revenues of USD 4,185.1 million and USD 3,398.8 million reflect differing detector integration requirements and long-life equipment platforms.
- Four application groups: Electronic Product is the largest application at ~42%, followed by Car at ~25%, Aerospace at ~20% and Other at ~13%. The automotive category is modeled to grow at ~10.2% CAGR as calibration and optical testing become more demanding.
- Geographic pattern: Asia-Pacific holds an estimated ~44% of 2025 component demand, North America ~25%, Europe ~23%, South America ~5% and the Middle East and Africa ~3%. These allocations reconcile with the global model and are not claims of published company regional sales.
- Supplier qualification: Commercial product specifications establish Hamamatsu Photonics and SiTek as relevant direct PSD suppliers. LASER COMPONENTS provides distribution and supporting electronics, while optical encoders and complete laser displacement instruments remain alternative approaches rather than interchangeable detector components.
Two Dimensional Optical Position Sensor Market Overview
Two dimensional optical position sensor market reached USD 3,550.05 million in 2025 and is forecast at USD 7,583.93 million by 2034, an implied CAGR of 8.8% during 2026–2034. Asia-Pacific is the largest regional demand center with an estimated ~44% base-year share, driven by electronics production and optical equipment integration.
Two-axis optical position sensing is a specific form of photodetection in which the electrical response changes continuously as a focused light spot moves across a photosensitive surface. Four electrical contacts allow the horizontal and vertical coordinates to be calculated from relative photocurrents, making the device suitable for precise beam displacement rather than image formation. A detector of this kind can sit in an optical bench, alignment fixture, machine controller or laboratory apparatus. It differs from an array camera because it reports a centroid-related signal without providing a full scene or multiple independent image features.
The commercial boundary centers on position-sensitive semiconductor elements and qualifying detector assemblies, including units supplied with essential signal conditioning. Finished robots, industrial displacement meters, optical encoders and camera systems are excluded even when their positioning functions overlap. This separation matters when evaluating company lists that combine photodiode suppliers with broad automation businesses: a supplier may have substantial sales in metrology without selling the underlying two-dimensional PSD as a merchant component. Procurement value also varies according to whether the equipment maker purchases a discrete silicon chip, packaged detector or calibrated electronics module.
Two structural categories are retained for the product segmentation: Surface Split and Two Side Split. Their distinctions concern how electrical contacts and sensing surfaces are arranged, rather than whether the detector is installed in a car, laboratory or electronics plant. Technical catalogues also describe duo-lateral and tetra-lateral configurations, showing that engineering terminology can be more granular than a commercial segmentation table. The market model therefore follows the two named categories while discussing pin-cushion and other geometries as product-design choices within the wider detector family, not as additional revenue axes.
Hamamatsu’s position-sensitive detector range demonstrates how product characteristics can differ even when devices share a two-coordinate function. The S15535 is built for surface mounting and uses a 9 × 9 mm sensitive area, whereas other parts offer different dimensions and contact layouts. SiTek devices available through LASER COMPONENTS cover a broader range of optical apertures and can be paired with electronics that convert current signals into coordinate outputs. The choice between those offerings depends on optical spot size, noise floor, rise time, available board space and the stability of the instrument calibration.
Commercial adoption depends on the measurement task, not simply on the spread of electronics or automation. A PSD can be efficient when one luminous target must be followed rapidly, while an encoder is better for reading travel against a scale and a camera is preferable for identifying several objects. The opportunity for detector vendors lies in finding equipment designs where continuous two-axis feedback is a functional advantage and then retaining that design through repeated production. Qualification periods, lifecycle support and analog signal-processing knowledge influence purchasing alongside headline sensor specifications.
Segment Analysis: By Type
The two named types are Surface Split and Two Side Split. Surface Split contributes an estimated ~58% of 2025 revenue, equivalent to USD 2,059.0 million, and has a modeled ~8.2% CAGR. Two Side Split contributes ~42%, or USD 1,491.0 million, and is projected to expand at ~9.6% CAGR. The classifications are applied consistently to the global component total; other geometry terms are discussed as engineering variants without being added as separate market segments.
| Type | Functional profile and selection criteria | Estimated market trajectory |
|---|---|---|
| Surface Split | An arrangement intended for continuous lateral-position detection across a sensitive surface, suited to compact optical tracking and repeated alignment tasks. The choice of device depends on the available optical aperture, analog front-end compatibility, thermal stability and whether the assembly can be mounted by an automated process. | Estimated ~58% of 2025 revenue, USD 2,059.0 million. The modeled 2026 value is USD 2,227.9 million and the 2034 value USD 4,185.1 million, with ~8.2% annual growth. Established design wins support repeat purchases. |
| Two Side Split | A second commercial structural group for two-coordinate spot detection, selected where the equipment design favors its particular electrical and mechanical characteristics. Device engineers still need to characterize response linearity, incident beam geometry and the signal-conditioning circuit before approving the part. | Estimated ~42% base-year share and USD 1,491.0 million revenue. The 2026 modeled value is USD 1,634.0 million, with USD 3,398.8 million projected for 2034 and ~9.6% CAGR. Higher modeled growth reflects specialized integration demand. |
Structural details and modeled revenue by type
Commercial segmentation into two types should not obscure the diversity of detector construction. The SiTek range includes different active-area dimensions and optional wavelength treatments, while Hamamatsu markets tetra-lateral devices as well as newer compact packaging. These distinctions affect the position response, calibration method and mechanical mounting even when a market table groups the devices into only two classes. A supplier that wins a high-value specialized design may realize more revenue per unit than a producer of a simpler volume detector, so segment growth is not equivalent to shipment growth.
| Type | 2025 share | 2025 value, USD m | 2026 value, USD m | 2034 value, USD m | Growth |
|---|---|---|---|---|---|
| Surface Split | ~58% | 2,059.0 | 2,227.9 | 4,185.1 | ~8.2% |
| Two Side Split | ~42% | 1,491.0 | 1,634.0 | 3,398.8 | ~9.6% |
A two-dimensional detector is only one part of a position-measurement chain. Illumination optics, transimpedance amplification and coordinate calculation determine whether the instrument achieves its required repeatability. LASER COMPONENTS offers integrated SiTek electronics that shorten this engineering work, while Hamamatsu provides circuit products that can be paired with compatible PSDs. Buyers may consequently select a more expensive packaged module when it lowers commissioning risk. The type allocation is a modeled revenue distribution, not a statement that either structural group universally outperforms the other.
Segment Analysis: By Application
Four applications are tracked: Aerospace, Electronic Product, Car and Other. Electronic Product leads with an estimated ~42% of 2025 revenue and a modeled ~8.1% CAGR. Car follows at ~25% and is the fastest-growing named application at ~10.2%, while Aerospace represents ~20% with ~8.9% growth. Other accounts for ~13% and includes laboratory and specialized industrial equipment. These application classes are mutually exclusive revenue views, not separate markets to add on top of the global total.
| Application | Demand characteristics |
|---|---|
| Electronic Product | Estimated ~42% share, USD 1,491.0 million in 2025 and USD 3,005.5 million by 2034. Electronic equipment production, optical alignment and precision inspection create the broadest component opportunity. The modeled 2026 value is USD 1,611.8 million, with ~8.1% CAGR reflecting equipment upgrades and detector integration. |
| Car | Estimated ~25% of 2025 demand, or USD 887.5 million, increasing to USD 2,127.2 million by 2034. Automotive-related optical testing and assembly tools contribute more directly than claims of universal PSD adoption inside vehicles. The 2026 estimate is USD 978.0 million, with modeled ~10.2% CAGR. |
| Aerospace | Estimated ~20% share and USD 710.0 million base value, reaching USD 1,529.4 million by 2034. Specialized optical alignment and beam monitoring favor stable component specifications and extended qualification. The 2026 value is modeled at USD 773.2 million, and growth at ~8.9% CAGR. |
| Other | Estimated ~13% of 2025 revenue, USD 461.5 million, and a modeled 2034 value of USD 921.9 million. Research instruments, medical optics and industrial measurement are included where they use qualifying detector components. The 2026 estimate is USD 498.4 million, with ~8.0% CAGR. |
Application boundaries must be interpreted at the component level. A detector used in an optical fixture on an automotive production line belongs to the Car application even though the final vehicle may contain no such PSD. Likewise, a device built into a scientific beam tracker is part of the residual application group, not the entire laboratory equipment market. The buyer may purchase a ready-made module or discrete photodiode, and those choices alter the selling price while leaving the physical measurement function unchanged.
Growth prospects vary with the engineering alternatives available. In electronic product assembly, vision cameras can perform complex inspection, but a simple photodiode may be sufficient for tracking a known laser target. Aerospace equipment can justify longer component qualification when reliability is important, while automotive test fixtures face pressure to reduce cycle time and cost. These differences explain why the four applications carry distinct modeled growth rates instead of assuming that every position sensor expands at the same pace as its end industry.
Regional Analysis
Regional demand reflects where manufacturers deploy optical alignment and measurement systems, rather than the location where a silicon detector is fabricated. Asia-Pacific accounts for an estimated ~44% of 2025 revenue and is modeled at ~9.5% CAGR. North America follows at ~25%, Europe ~23%, South America ~5% and the Middle East and Africa ~3%. The global split reconciles to 100%, with a separate 2023 North American publisher anchor used only as historical calibration rather than an assumed current share.
Which regional manufacturing and research activities support two-axis photodiode purchases?
Regional component sales are difficult to infer from the headquarters of equipment vendors because detectors may be manufactured in one country, integrated into a machine in another and serviced in a third. The model places the greatest demand in Asian electronics production, while North America and Europe retain substantial specialized optical instrumentation markets. Smaller regions buy many sensors indirectly through imported machinery, so their component demand is not identical to local semiconductor fabrication. Procurement decisions also depend on access to engineering support, compatible analog electronics and replacement stock.
The modeled 2025 regional values are USD 1,562.0 million for Asia-Pacific, USD 887.5 million for North America, USD 816.5 million for Europe, USD 177.5 million for South America and USD 106.5 million for the Middle East and Africa. Their projected 2034 values are USD 3,535.2 million, USD 1,803.9 million, USD 1,673.5 million, USD 326.3 million and USD 245.0 million, respectively. These estimates describe the geographical distribution of the same global revenue pool and are not independent country-by-country supplier disclosures.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~44% share) | ~9.5% CAGR | High-volume optical equipment integration | Manufacturing consistency and component engineering |
| North America | Second (~25% share) | ~8.2% CAGR | Precision instruments and specialized optical systems | Calibration records and dependable part availability |
| Europe | Third (~23% share) | ~8.3% CAGR | Automotive test equipment and metrology | Distributor service and long-life qualification |
| South America | Smaller (~5% share) | ~7.0% CAGR | Imported industrial machinery and optical laboratories | Local maintenance capability and import cost |
| Middle East and Africa | Emerging (~3% share) | ~9.7% CAGR | Specialized scientific and industrial projects | System integration and environmental protection |
Two Dimensional Optical Position Sensor Competitive Landscape and Company Roles
Competition must be evaluated at the detector level because a long list of industrial sensor companies does not establish that every participant manufactures merchant two-axis photodiodes. Hamamatsu Photonics has directly documented PSD products, and SiTek supplies specialized silicon detectors distributed by LASER COMPONENTS. Broader industrial names can influence equipment architecture through encoders, laser displacement instruments and integrated control systems. Customers select a qualified component after testing optical response, analog compatibility, package stability and support across the equipment lifecycle.
Hamamatsu has several two-dimensional detector models with different package and electrode characteristics. The S5990-01 illustrates a smaller tetra-lateral configuration, while the S5991-01 provides a larger active area in the same broad technical family. The company also supplies signal-processing electronics that can simplify evaluation of photocurrent outputs. This product breadth allows an equipment maker to compare response and mounting options without switching the entire supplier relationship, but no cited product catalogue provides a separate audited revenue figure for this narrowly defined global component market.
SiTek addresses optical designers seeking continuous spot tracking over a wide range of sensitive areas. Its products are distributed by LASER COMPONENTS, which also provides evaluation and conditioning electronics. This arrangement supports customers needing samples, technical advice and a compatible analog front end, especially when the required detector is not a mass-market standard. The distributor’s international presence can expand access, but the manufacturer and sales intermediary should not be treated as two independent fabricators of the same silicon devices.
Companies such as Micro-Epsilon and Renishaw compete for some of the same industrial measurement budgets without necessarily supplying a directly substitutable PSD. A complete triangulation sensor measures displacement through an integrated optical system, whereas an optical encoder derives position from a scale. Either architecture may be more suitable than a continuous photodiode when the application demands a calibrated distance or absolute axis measurement. These adjacent offerings therefore matter to the competitive assessment while remaining outside the core detector revenue boundary.
The barriers to entry arise from design qualification and the total cost of changing an established sensing circuit. An apparently similar PSD can differ in current distribution, linearity, capacitance and mechanical dimensions, creating work for the instrument developer. Long-lived industrial systems reward reliable specifications and stable component availability. Custom suppliers can win applications with unusual optical apertures or coatings, but broad adoption requires evidence that the design can be produced consistently and supported for years after the initial engineering project.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Direct component specialists | Hamamatsu Photonics; SiTek | Two-dimensional position-sensitive detector families with technical specifications that permit component-level comparison. Compete on optical response, package geometry, noise behavior, linearly mapped coordinates and documented production support. |
| Distribution and conditioning | LASER COMPONENTS; specialized optical integrators | Access to detector variants, samples, amplifier boards and design assistance. Channel value is strongest where the customer needs a usable sensing assembly rather than only a bare silicon element. |
| Broader optical sensing ecosystem | Micro-Epsilon; Renishaw; OMRON; Panasonic; Honeywell; Siemens | Industrial sensing and positioning solutions that can influence the choice of measurement architecture. Participation in adjacent systems should not be converted into a fabricated share of direct two-axis PSD component sales. |
Key companies profiled
- Hamamatsu Photonics K.K. — verified two-dimensional PSD product range
- SiTek Electro Optics — verified detector portfolio
- LASER COMPONENTS — SiTek distribution and associated signal electronics
- Micro-Epsilon — adjacent laser displacement instruments
- Renishaw plc — adjacent encoder and motion systems
- First Sensor AG — historical sensor company identity, direct current PSD offering unverified
- Panasonic Corporation — broader electronic components
- OMRON Corporation — industrial sensing equipment
- Siemens — industrial automation ecosystem
- Honeywell International — industrial sensing ecosystem
- Melexis — semiconductor sensor ecosystem
- Bourns — electronic component supplier
Two Dimensional Optical Position Sensor Production and Design Qualification
A position-sensitive photodiode must be fabricated with controlled electrical uniformity and then characterized optically so that the relationship between light-spot displacement and output current is predictable. Packaging adds another engineering dimension because the sensing surface must remain aligned with the equipment optics. The production chain includes semiconductor processing, assembly, testing and optional signal-conditioning electronics. Device qualification is particularly important when the detector is incorporated into a machine that will remain in service for many years.
Silicon device manufacturing sets the underlying responsivity, dark current and contact resistance characteristics, but those specifications are only part of usable two-axis accuracy. The optical spot may move over a large fraction of the active surface, exposing non-linearity and sensitivity to beam shape. Manufacturers characterize these effects and provide data that guide the customer’s calibration process. Large-area detectors can offer more travel for beam tracking, while compact packages favor board integration; neither option is universally superior because the optimal geometry follows the instrument design.
Packaging and analog electronics determine the point at which the product is sold as a component or as a more integrated module. A bare detector requires the equipment maker to design amplification and position calculations, while an SPC-PSD-style assembly incorporates circuitry for current conversion. The latter may carry a higher price but reduce engineering hours and shorten validation. Production planning must therefore distinguish semiconductor die capacity from assembly and electronics capability, because a bottleneck in a specialized package can affect delivery even when wafers remain available.
The aftermarket rewards continuity of manufacturing. A sensor embedded in a calibrated optical fixture may be difficult to replace with a different product because the active-area dimensions and electrical transfer function influence system performance. Customers may maintain spare inventories or request lifecycle commitments from distributors. The supply risk is not limited to raw materials: discontinuation of a package, amplifier circuit or calibration procedure can make an apparently simple component substitution expensive. Suppliers that support long-running equipment programs can preserve demand beyond the original machine build.
Two Dimensional Optical Position Sensor Market Drivers, Restraints and Opportunities
Demand growth reflects the expanding number of optical measurement tasks in electronics, vehicle-related testing and specialized aerospace equipment. Better packaging and signal-processing options can make a continuous detector easier to adopt, but other sensor architectures remain powerful substitutes. The contribution estimates below assign percentage points to individual forces and sum to the forecast growth rate after restraints. They describe the relative direction of demand rather than a causal coefficient independently measured from a global sales census.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Electronic product alignment and optical testing | High | +3.20% | High | High | Medium |
| Automotive production and optical calibration | High | +2.70% | Medium | High | High |
| Aerospace beam monitoring and precision equipment | Medium-High | +2.20% | Medium | High | High |
| Smaller integrated detector and amplifier assemblies | Medium | +1.80% | High | Medium | Medium |
| Research instrumentation and replacement demand | Low-Medium | +1.40% | Medium | Medium | Medium |
| Others (specialized laboratory and industrial tracking) | Low | +1.00% | Low | Medium | Medium |
Electronic production adds controlled optical tracking tasks
Electronics manufacturing relies on optical alignment and testing at many points in a production process, creating opportunities for a detector that converts spot displacement into a continuous electrical signal. The Electronic Product application is modeled at ~42% of 2025 demand, reflecting its broad equipment base. This does not mean every smartphone or tablet contains a discrete PSD; component purchases can be concentrated in the machines that assemble and calibrate those devices. The estimated contribution from this driver is +3.20 percentage points.
Automotive equipment needs reproducible positioning feedback
Vehicle-component production and test fixtures can require optical measurement that remains stable across repeated cycles. A two-axis detector may be used for alignment of a controlled light source, while cameras and encoders handle other measurement functions. The Car application represents an estimated ~25% of base-year revenue and has a modeled ~10.2% CAGR. The +2.70-point contribution captures increasing use of qualifying components in precision equipment, not the entire automotive sensor market or a universal installation rate per vehicle.
Aerospace applications reward reliable optical instrumentation
Aerospace research and engineering employ beam-position monitoring, optical alignment and high-stability measurement equipment. Component orders can be smaller than consumer-oriented purchases, but qualification and lifecycle requirements create value for well-characterized detectors. The Aerospace application is modeled at ~20% of revenue with ~8.9% annual growth. This driver contributes an estimated +2.20 points as specialized optical systems expand, while the model excludes complete navigation systems and other downstream equipment whose revenues are not attributable to the detector alone.
Integrated modules reduce the analog engineering barrier
A discrete PSD requires multiple current channels and coordinate calculation before its output becomes useful to a controller. An integrated assembly can remove part of that design burden, which matters for laboratories and smaller equipment makers. SiTek signal-processing modules distributed by LASER COMPONENTS demonstrate the commercial logic of selling a more complete sensing function. The modeled +1.80-point contribution reflects easier adoption and potentially higher selling value per assembly, balanced against customers that prefer custom low-cost electronics for high-volume production.
Instrument maintenance creates recurring component purchases
Industrial and scientific systems may remain operational for many years after their original installation, generating demand for compatible replacement detectors and associated electronics. The value of a spare part can depend on avoiding recalibration or machine downtime rather than on its semiconductor fabrication cost. This recurring demand is distinct from new equipment installations and can help stabilize orders when capital spending slows. The estimated +1.40-point contribution reflects service-driven purchasing and upgrades to established optical measurement platforms.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Competing camera, encoder and triangulation architectures | High | -1.40% | High | High | High |
| Analog noise and calibration burden | Medium-High | -0.90% | High | Medium | Medium |
| Slow component substitution and qualification | Medium | -0.70% | Medium | Medium | High |
| Others (small runs and pricing competition) | Low | -0.50% | Medium | Low | Low |
The measurement requirement can favor a different sensor
Continuous two-axis PSDs excel at locating an illuminated centroid, but they do not provide a scene image, direct absolute travel against a scale or a finished distance measurement. Machine-vision cameras, optical encoders and integrated triangulation sensors can therefore win equipment designs that need those functions. The modeled restraint of −1.40 percentage points captures the opportunity lost to alternative architectures rather than an assumption that the overall optical measurement industry is contracting.
Photocurrent processing increases the true installed cost
The raw detector output is sensitive to optical power, electrical noise and the behavior of the current-conversion circuit. A customer may need several amplifier channels, filtering and calibration to achieve the desired coordinate accuracy. Integrated modules reduce this work but can increase the bill of materials, while custom boards require engineering resources. The estimated −0.90-point restraint reflects designs that select a turnkey sensor because a bare PSD cannot meet the project’s cost or integration timetable.
Changing a qualified component can disrupt a long-lived product
An instrument that was calibrated around one detector may not behave identically with a replacement from another manufacturer. Mechanical dimensions, active-area response and current distribution can require revised electronics or optical alignment. This raises the cost of supplier switching and can delay new projects when parts are difficult to obtain. The modeled −0.70-point restraint is most relevant to regulated or long-service equipment, where validation and continuity are weighted more heavily than short-term component price.
MARKET OPPORTUNITIES
Wavelength-specific detector designs support premium niches
Some optical systems operate outside the ideal response of a standard silicon detector or need coatings that improve their optical performance. SiTek product offerings include variants adapted to specialized wavelengths and aperture requirements. A supplier that matches these requirements can enter research, beam alignment and specialized industrial projects where a general-purpose device is unsuitable. The opportunity is concentrated in technically demanding designs rather than broad mass-market substitution, making application engineering a central commercial asset.
Small instrument makers can adopt ready-to-use electronics
A laboratory or custom machinery company may lack the resources to design and validate a low-noise multichannel amplifier. A packaged detector with integrated coordinate processing can reduce development time and simplify testing. This approach expands the addressable customer base beyond companies with dedicated photodiode engineering teams. The commercial challenge is to maintain performance and documentation while offering an interface that can be integrated into existing control software without extensive redesign.
Miniaturized assemblies create new optical feedback locations
As electronic and scientific instruments become more compact, designers may seek a sensing method that occupies less space than a camera and image-processing board. A surface-mount two-axis detector can be attractive where illumination and target geometry are already controlled. The opportunity requires careful optical design, because miniaturization can make alignment and stray-light effects more difficult. Suppliers that offer stable packaging and credible application data can win new equipment platforms with long replacement lifecycles.
Two Dimensional Optical Position Sensor Supply Chain and System Integration
The product chain begins with semiconductor photodetector processing and continues through packaging, electrical characterization, distribution and instrument integration. Specialized suppliers provide position-sensitive silicon devices, while distributors may add sampling support and compatible analog electronics. Original-equipment manufacturers then embed the sensor in optical tracking or alignment systems. The market boundary remains the qualifying detector component and its directly associated assembly, preventing double counting of the finished instrument, service contract and machine-control software.
Materials. The electrical behavior of a position-sensitive detector depends on the uniformity of its silicon sensing structure, the quality of contacts and the condition of the optical entrance surface. A package may include a protective window or a coating selected for the intended wavelength. These inputs must be controlled together because a detector can have adequate light sensitivity but poor coordinate accuracy if current distribution or stray illumination is not managed. Material cost is therefore only one part of the component value proposition.
Detector manufacturing. Manufacturers fabricate the photosensitive element and characterize its response as the illuminated spot moves across the active area. Test data can include dark current, response time, linearity and the effect of wavelength or spot size. Packaging must preserve the geometry that the instrument designer expects. Different device families suit different optical footprints, and the availability of a qualified model can matter more than the total number of nominally similar photodiodes produced by the supplier.
Engineering channel. Distributors and module specialists make specialized detector products accessible to smaller customers and can supply evaluation circuitry that reduces analog design work. The equipment maker still needs to validate the full measurement path, including illumination, optical alignment and coordinate processing. A conditioned module can shorten development, while a bare detector may be cheaper in a mature high-volume product. Channel revenue should not be counted twice when the same device passes from manufacturer through distributor to the final equipment builder.
End use. A detector may become a small component inside a large machine, where its failure can interrupt an expensive process. That encourages customers to preserve qualified parts and maintain replacement stock. A final user may see only a calibrated instrument rather than the semiconductor device itself, so downstream equipment prices are a poor proxy for PSD market size. Demand assessment must focus on the component content and the applications that actually use continuous two-axis optical spot feedback.
Recent Product Evidence and Optical Position Sensing Developments
- 30 June 2026 Product feature
Hamamatsu Photonics highlighted compact S15534 and S15535 two-dimensional PSD products intended for straightforward board integration. The devices use a glass-epoxy construction and support lead-free reflow processing, making them relevant to automated electronics assembly. Their technical significance lies in simplifying how a position-sensitive photodiode is mounted, while the equipment designer must still address illumination geometry and coordinate calibration. The feature does not disclose worldwide market sales. Source - 2026 catalogue Technical listing
The Hamamatsu S2044 documentation describes a two-axis position-sensitive detector for optical spot measurement. Its product information provides a concrete component-level reference for equipment designers comparing a continuous analog detector with a camera or encoder. A catalogue entry demonstrates that the device is offered commercially, but it should not be interpreted as evidence of a newly announced production contract or as a measure of the supplier’s market share. Source - 2026 catalogue Technical listing
LASER COMPONENTS presents SiTek detectors with sensitive areas extending to 45 × 45 mm and options for particular optical wavelengths. The range is important for instruments whose laser spot must move across a substantial field without losing continuous coordinate feedback. The offering also illustrates why the market cannot be represented by a single package size or one generic sensor specification. No shipment or revenue totals accompany the technical listing. Source - 2026 catalogue Engineering product
Hamamatsu provides the C4674-01 circuit as a compatible signal-processing solution for position-sensitive detectors, with selectable sensitivity arrangements. Such electronics are relevant because the photodiode produces current signals that require conversion before a controller can interpret the X and Y coordinates. The commercial implication is a choice between discrete detector procurement and more complete functional assemblies, with different engineering and calibration responsibilities for the equipment buyer. Source - 11 March 2013 Historical supplier notice
A LASER COMPONENTS communication documented SiTek two-dimensional PSDs and their suitability for alignment, motion measurement and vibration studies. The historical date shows that continuous spot-position technology was already established well before the current forecast horizon. Recent demand therefore arises from new integration contexts, product packaging and replacement cycles rather than from a first invention of two-axis photodiode sensing. Historical specifications should not be presented as current shipment evidence. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2019–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Context | 2019–2024 |
| Market Size 2025 | USD 3,550.05 million |
| Market Size 2026 | USD 3,862.45 million |
| Market Size 2034 | USD 7,583.93 million |
| Growth Rate | CAGR of 8.8% during 2026–2034 |
| Unit | Revenue in USD million; estimated component shares |
| Segmentation | By Type, By Application and By Region |
| By Type | Surface Split · Two Side Split |
| By Application | Aerospace · Electronic Product · Car · Other |
| By Region | Each region assessed by product structure and end application North AmericaUnited States, Canada, Mexico EuropeGermany, United Kingdom, France, Italy, Spain and Rest of Europe Asia-PacificChina, Japan, South Korea, Taiwan, India and Southeast Asia South AmericaBrazil, Argentina, Chile, Colombia and Rest of South America Middle East & AfricaUnited Arab Emirates, Saudi Arabia, Israel, South Africa and Rest of Region |
| Key Companies Profiled | Hamamatsu Photonics; SiTek; LASER COMPONENTS (distributor); First Sensor AG (historical company identity); Panasonic; OMRON; Siemens; Honeywell; Micro-Epsilon (adjacent displacement instruments); Renishaw (adjacent optical encoders); Bourns; Melexis; Celera Motion; Balluff; ifm electronic; Pilz |
| Customization Scope | Additional component-level segmentation, supplier qualification details, country demand estimates, application-specific calibration requirements and separate treatment of complete optical measurement equipment. |
Frequently Asked Questions
How large is the two dimensional optical position sensor market?
The global component market is modeled at USD 3,550.05 million in 2025 and is forecast to reach USD 7,583.93 million by 2034, advancing at a CAGR of 8.8% during 2026–2034. The estimate extends the original 2023 and 2030 revenue anchors and includes qualifying continuous two-coordinate photodiode detectors and directly associated sensing assemblies. Finished cameras, optical encoders and complete industrial displacement instruments are not counted at their full selling prices.
What does a continuous two-axis optical sensor measure?
A position-sensitive photodiode reports the location of an illuminated spot across a photosensitive surface by comparing currents collected at several electrical contacts. The signal can be converted into horizontal and vertical coordinates for alignment or feedback control. This is different from capturing an image or reading an encoder scale, so the device is especially useful when a machine needs to follow one controlled light target rather than identify many independent visual features.
Which structural type has the largest estimated share?
Surface Split is the leading category at an estimated ~58% of 2025 revenue, with Two Side Split accounting for ~42%. The first group benefits from broad optical alignment and equipment integration, while the second serves designs that favor its specific electrode and response characteristics. The two categories are the complete commercial type segmentation; pin-cushion and tetra-lateral terms describe engineering geometry and should not be added as new revenue categories in this particular model.
Which applications generate the most detector demand?
Electronic Product is the largest application with an estimated ~42% share, followed by Car at ~25%, Aerospace at ~20% and Other at ~13%. Electronic production generates recurring alignment and inspection needs, while vehicle-related testing and aerospace instrumentation create technically demanding orders. These percentages represent the detector content associated with each use case, not the full value of electronics, vehicles, aircraft or the machinery that contains optical sensors.
What is the largest regional market for two-axis PSD components?
Asia-Pacific leads with an estimated ~44% of 2025 revenue because of electronics manufacturing and optical equipment integration. North America accounts for ~25%, Europe ~23%, South America ~5% and the Middle East and Africa ~3%. The regional split is a modeled allocation; a separate 2023 North American publisher figure is historical context and does not establish the current share of every country or manufacturer.
Which companies supply commercial two-dimensional position detectors?
Hamamatsu Photonics has documented two-axis PSD products in multiple configurations, and SiTek offers silicon position-sensitive devices through the LASER COMPONENTS distribution channel. Other industrial sensing companies participate in adjacent optical measurement systems or broader electronic components, but a general sensor portfolio is not proof of direct merchant PSD fabrication. Buyers should verify the specific part number, sensitive area, analog interface and lifecycle support rather than relying on a broad company list.
Why might a machine builder choose a PSD instead of a camera?
A continuous photodiode can provide direct spot-centroid feedback without requiring a complete image-processing pipeline, which may simplify a tightly controlled laser alignment loop. A camera remains preferable when the application needs object recognition, several targets or a full scene. An encoder can be superior for travel measurement against a scale. The correct selection depends on the measurement objective, response time, optical geometry and total integration cost.
What slows the adoption of two-coordinate optical sensors?
Technical challenges include stray light, response non-linearity, electrical noise, amplifier offset and the need for reliable calibration. Equipment makers may also face a lengthy qualification process when changing detector geometry or supplier. A packaged module can reduce some engineering work but raises the assembly price. These trade-offs limit adoption where a turnkey displacement instrument or camera provides the required function with lower total project risk.
How are detector revenue and complete equipment revenue separated?
The detector market includes the qualifying photodiode or integrated sensing assembly that produces continuous two-axis position information. A complete machine may also contain a laser, lenses, mechanics, motion controller, software and maintenance services, each with its own economic value. Counting the entire machine as detector revenue would overstate the component opportunity. The same distinction applies to optical encoders and industrial triangulation sensors, which may compete for a measurement task but use different architectures.
What years and segment categories does the study cover?
The analysis uses a 2025 base, a 2026 estimate and a 2034 forecast, with historical context beginning in 2019. Two type categories and four application categories are examined across five regions, with modeled shares and growth rates that reconcile with the global market total. The coverage focuses on component-level positioning technology, company participation, supply considerations and application demand without attributing all adjacent optical equipment spending to position-sensitive photodiodes.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF