SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Transceivers for Optical Communication Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
COMMUNICATION SYSTEMS Semiconductor Market Research

Transceivers for Optical Communication Market

Size, Share & Industry Analysis, 2026–2034

◷
UPDATED 13 November 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 03f57338a05a
▯
FORMATS PDF

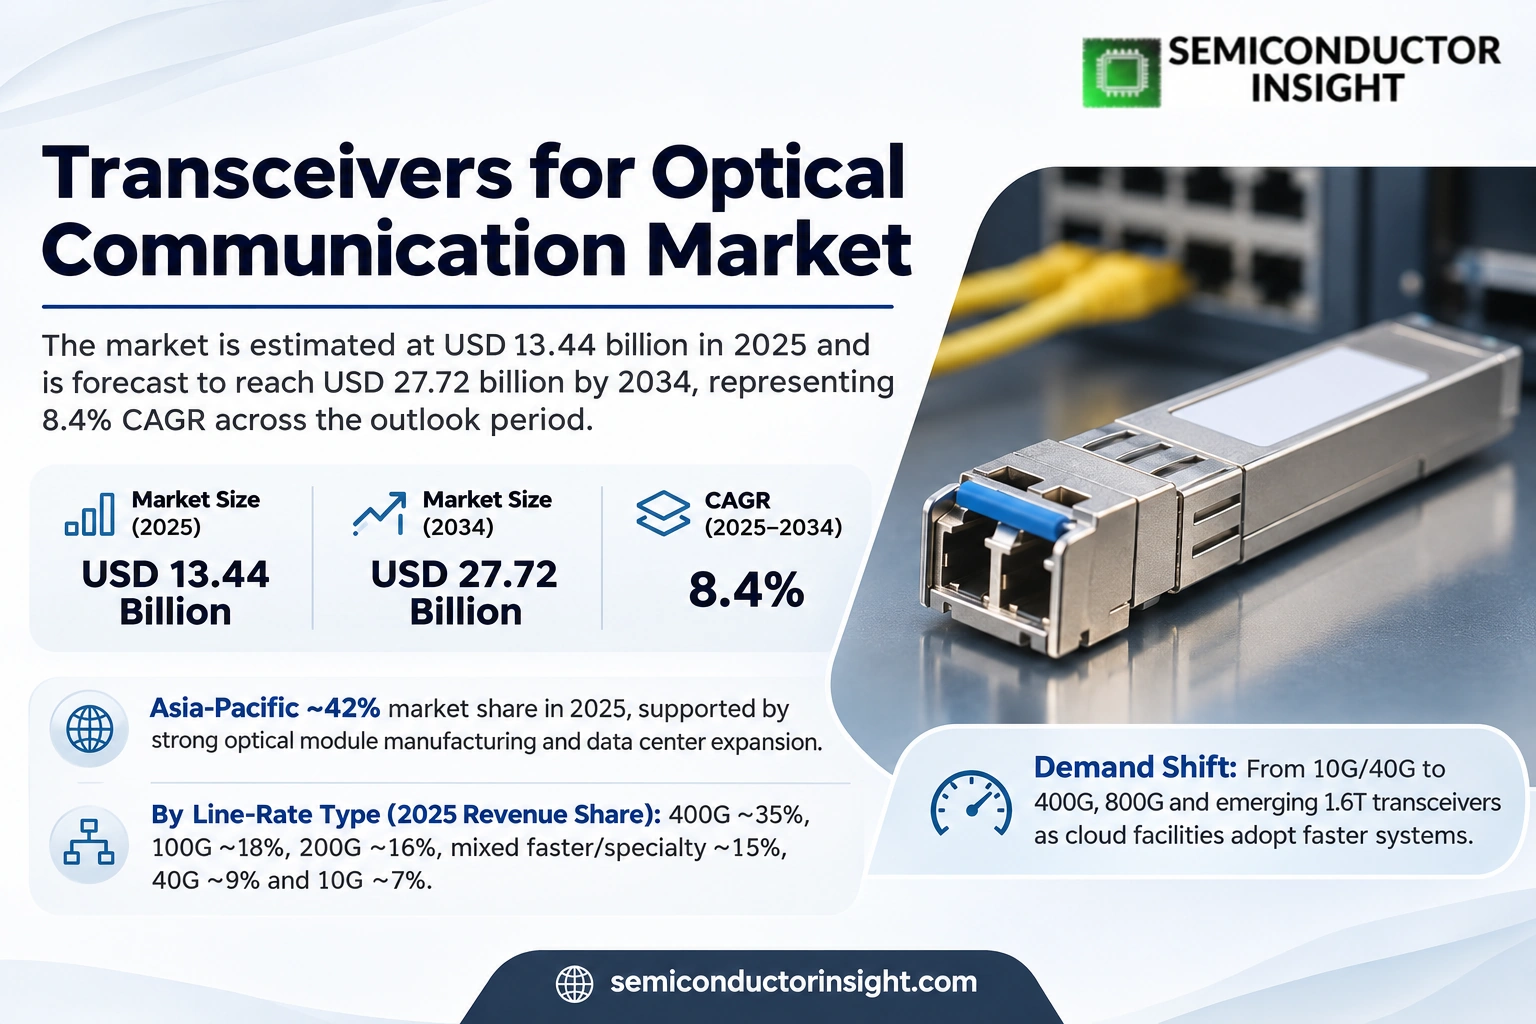
Transceivers for optical communication market is estimated at USD 13.44 billion in 2025 and is forecast to reach USD 27.72 billion by 2034, representing 8.4% CAGR across the outlook period. Optical modules combine laser transmitters, receiver photodiodes and signal-processing electronics in pluggable or embedded form factors, allowing switches, servers and carrier systems to move data through fiber; Asia-Pacific held the leading estimated 2025 market position of ~42%.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 13.44 billion
2034 Projected Size
USD 27.72 billion
CAGR (2026–2034)
8.4%
Largest Market in 2025
Asia-Pacific (~42%)

Key Takeaways

  • Market size: Optical communication transceiver revenue is estimated at USD 13.44 billion in 2025 and projected at USD 27.72 billion in 2034. The market includes complete optical modules converting electrical networking signals into fiber-optic transmission and receiving streams across data centers, carrier routes and enterprise infrastructure; revenue is distinct from the individual lasers, DSPs and receiver chips inside each assembly.
  • 400G and faster modules are changing purchasing priorities. The 400G type holds an estimated ~35% of 2025 market value while 100G products serve a substantial installed base and 800G or higher designs within the other category create increasing demand for power-efficient pluggable connectivity across AI computing clusters.
  • Data-center applications represent about ~55% of 2025 revenue, with telecommunications around ~36% and specialist or enterprise-related demand ~9%. Coherent 400ZR, 800ZR and emerging 1600ZR interfaces allow greater capacity between facilities, while direct-detection optics remain central within shorter-reach switching fabrics.
  • Asia-Pacific leadership reflects roughly ~42% of global 2025 transceiver demand, supported by module assembly ecosystems, optical component manufacturing and fiber-system procurement. North America contributes around ~30%, Europe ~21%, South America ~4% and the Middle East and Africa ~3%, with different mixes of cloud systems and transport-network projects.
  • Efficiency and interoperability shape competition: 800G QSFP-DD and OSFP modules must fit defined electrical interfaces, optical reach, thermal envelopes and vendor qualification rules. Supplier advantage depends on dependable high-speed packaging, laser sourcing, DSP integration and ability to satisfy customers migrating from 100G/400G to 800G/1.6T platforms.

Transceivers for Optical Communication Market Overview

Transceivers for optical communication market is estimated at USD 13.44 billion in 2025 and is forecast to reach USD 27.72 billion by 2034, representing 8.4% CAGR across the outlook period. Optical modules combine laser transmitters, receiver photodiodes and signal-processing electronics in pluggable or embedded form factors, allowing switches, servers and carrier systems to move data through fiber; Asia-Pacific held the leading estimated 2025 market position of ~42%.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Historical data: 2020–2024 · Values in USD billion

An optical transceiver is an integrated module containing both transmitter and receiver paths and their interface electronics. Depending on link distance and signaling method, the assembly can contain vertical-cavity surface-emitting lasers, indium-phosphide lasers, silicon-photonic circuits, driver circuits, photodiodes, transimpedance amplification and a digital signal processor. Products are sold in SFP, QSFP, OSFP or other physical packages that must match the host equipment and fiber plant. Manufacturers differentiate by achievable lane speed, optical reach, electrical power, reliability and system interoperability.

AI training clusters and growing cloud infrastructure place heavy demands on optical links between servers, switches and data-center buildings. The market transition includes 100G and 400G equipment alongside 800G and 1.6T systems, rather than one instantaneous replacement cycle. Marvell identifies optical DSP families serving 100G through 1.6T modules, while Coherent has demonstrated 1.6T transceiver technologies using silicon photonics, indium-phosphide components and VCSEL devices. A design win increasingly requires coordinated component availability and package-level thermal qualification.

Telecommunications networking presents a different physical challenge from short-reach data-center optics. Carrier networks often need amplification, dispersion management and tightly specified coherent receiver functions over hundreds or thousands of kilometers. Cisco describes 800ZR applications extending to around 120 km and 800G ZR+ transport beyond 1000 km, while the Optical Internetworking Forum has defined 400ZR, 800ZR and 1600ZR implementation agreements. Compatibility with line systems, wavelength plans and operational monitoring determines whether higher-rate pluggable modules can replace separate transponders.

Commercial forecasting must distinguish revenue recognized on the finished optical transceiver from the value of semiconductors and optical subassemblies it contains. The market includes both direct-detection and coherent modules used for data centers, telecommunications and other optical communication applications, but excludes the standalone value of network switches, fiber cables, lasers sold outside complete modules and service contracts. Customer spending depends on shipments by speed generation, average selling price, optical reach and module qualification. Established 10G and 40G lines continue at lower unit economics while 400G and 800G designs account for more demanding engineering programs.

Segment Analysis: By Type

By line-rate type, the 400 G segment leads 2025 revenue with an estimated ~35% share, followed by 100 G at ~18%, 200 G at ~16%, the mixed faster and specialty categories at ~15%, 40 G at ~9% and 10 G at ~7%. This segmentation follows marketed optical interface capacities rather than optical wavelengths or number of electrical lanes. As cloud facilities adopt faster systems, demand shifts from mature 10G/40G products to 400G, 800G and emerging 1.6T transceivers.

Type Function Market position
10 G Ten-gigabit optical links continue in access networks, enterprise switches, management interfaces and certain equipment interconnects. SFP+ modules may run over single-mode or multimode fiber depending on optical reach and transceiver wavelength. Their electrical power requirements and qualified host compatibility suit long installed equipment cycles, but replacement demand depends heavily on the maintenance and refresh timing of legacy network platforms. Mature segment (~7% share). 10 G modules provide a cost-effective option where switching infrastructure does not justify migration to 100 G or 400 G. Product variety remains broad and price competition is strong, so suppliers emphasize sourcing availability and verified equipment compatibility. Higher-rate module lines generate more growth value even while these older interfaces retain an important installed base.
40 G Forty-gigabit transceivers connect older QSFP+ switching systems and established enterprise or data-center network links. They often employ several parallel lower-speed optical lanes, linking historical 10 G systems to subsequent 100 G architectures. Operators choosing replacements must verify pin compatibility, fiber type, loss budgets and end-of-life policies. Upgrade projects may bypass this speed class if compatible higher-rate switch ports are already available. Established share (~9%). Demand is primarily tied to the installed base of QSFP+ platforms, redundancy inventory and selective upgrades. Market value is more sensitive to component price erosion than the latest optical modules. Vendors can retain orders through dependable quality assurance, while advanced data-center deployments increasingly favor 100 G, 400 G and 800 G rates instead.
100 G One-hundred-gigabit optical modules became a widely used building block of Ethernet and network transport. QSFP28 transceivers can support short-reach multimode and longer-reach single-mode fiber variants, with differing lane counts and wavelength plans. Interoperability with 100GE switch ports remains a major purchasing factor. Continued demand arises from existing infrastructure, regional carriers, campus links and server aggregation that does not immediately require 400 G interfaces. Estimated ~18% share. 100 G remains commercially significant because its broad equipment footprint supports replacements, spare modules and incremental capacity additions. The price-performance balance suits enterprise and telecommunications networks using established hardware. However, when operators refresh entire switching platforms, four-hundred-gigabit modules can offer better port-density economics and capture new-build demand.
200 G Two-hundred-gigabit modules fill intermediate requirements between 100 G and 400 G network classes and can support specific optical lane architectures. Their commercial adoption depends on available host electrical interfaces, qualified photonic components and port density constraints. Suppliers may use 200 G lanes as building blocks in 800 G and 1.6T optical assemblies, but lane speed should not be confused with the total end-to-end module throughput. Estimated ~16% share. 200 G products have a role in network modernization and in technology platforms that progressively raise per-lane capacity. Opportunities depend on how equipment makers partition switching interfaces and on power requirements for each supported optical reach. Some customers choose 400 G directly, making the category less uniform than broad 100 G or 400 G deployment.
400 G Four-hundred-gigabit transceivers combine high bandwidth with established pluggable ecosystems for contemporary data centers and coherent transport. QSFP-DD, OSFP and related form factors host optical designs for short, campus and metropolitan connections. Coherent 400ZR and related interface agreements support interoperable transport use cases, while direct-detection products address many switching and server interconnects. Final system suitability depends on lane encoding, optical reach, host support and thermal design. Largest segment (~35% share). 400 G is the commercial center of gravity for high-capacity optical upgrades. New installations benefit from its combination of platform availability and transmission performance, while interoperability and power compliance remain important. Suppliers compete over product qualification across 400GBASE variants, cost-effective laser supply and availability of both short-reach and coherent pluggable architectures.
Others This category contains emerging 800 G and 1.6T optical assemblies as well as less common speed and application configurations. Eight-hundred-gigabit products can use QSFP-DD800 or OSFP packages, and 1.6T devices move toward eight 200 G optical lanes. Coherent versions introduce additional DSP and tunable-laser demands. Their production economics differ sharply from the mature 10 G segment, with more difficult integration and thermal validation. Estimated ~15% share. The category has the fastest technology transition because 800 G and 1.6T are expanding into AI and cloud network designs. Coherent demonstrated multiple 1.6T transceiver technologies in 2026, while Marvell introduced supporting 3 nm DSP platforms. Commercial expansion requires manufacturing yields and host interoperability to catch up with higher headline rates.

Secondary segmentation: optical detection method and form factor

Direct-detection optical modules account for an estimated ~67% of 2025 market value and coherent designs account for ~33%. Direct detection is prevalent in short-reach Ethernet systems, while coherent links add DSP processing for greater reach and spectral efficiency. Form factors remain dependent on switch port density and thermal design, rather than only the signaling rate.

Axis Members Commercial role
Detection method Direct detection (~67%); coherent (~33%) Direct detection serves short-reach data center links; coherent technology serves high-capacity DCI and carrier routes.
Form factor QSFP/QSFP28 (~37%); SFP/SFP+ (~18%); CFP/CFP2 (~15%); other including OSFP and QSFP-DD (~30%) Higher-density formats support 800G and 1.6T growth, while legacy packages sustain replacement requirements.

Segment Analysis: By Application

By application, data-center optical systems account for an estimated ~55% of 2025 transceiver sales, telecommunications networks ~36% and other optical communication uses ~9%. A cloud operator purchasing thousands of 400G and 800G modules creates different demands from a carrier provisioning 400ZR or 800ZR wavelengths over an amplified line system. Product choices are constrained by supported fiber, host ports, monitoring software and total energy per delivered bit.

Application Demand characteristics
Data Center (Datacom) Largest application (~55% share). Cloud and AI compute networks use high-density optical transceivers for switch-to-switch, server and campus links, with 100 G and 400 G installed products alongside 800 G and newer 1.6T module programs. Purchasers prioritize power per bit, compatible connector formats, module telemetry, thermal efficiency and prompt supply. Marvell and Coherent announcements demonstrate active supplier investment in the photonic and DSP components needed for these deployments.
Telecommunication Estimated ~36% share. Metro, long-haul, mobile transport and carrier backbone systems use optical transceivers selected for link distance, bit error rate and interoperability with wavelength-division systems. Cisco offers 800G ZR and ZR+ coherent pluggables, while OIF technical agreements support vendor interoperability. Network operators balance optical power, dispersion, amplification requirements and service availability against equipment density and the cost of adding capacity.
Other Estimated ~9% share. Enterprise campuses, industrial optical networks, public-sector systems and specialized connectivity deployments use a broad range of SFP+, QSFP and higher-speed modules. Procurement may prioritize host-vendor approval and long-term replacement availability over leading-edge bandwidth. Different fiber types, connector arrangements and environmental specifications sustain multiple transceiver product families even as cloud data centers drive the fastest high-capacity platforms.

Applications set the effective economic value of a transceiver design. A 400G data-center optical module may have a short link budget and numerous parallel lanes, while an 800ZR coherent module must maintain suitable optical performance across a heavily managed network span. Enterprise installations may continue using 10G/100G links for years. Manufacturers must reconcile these differences through specific approved products rather than promoting every transceiver as interchangeable at the same advertised data rate.
Regional Analysis

Asia-Pacific represents the largest optical communication transceiver market with about ~42% of 2025 value. North America follows at an estimated ~30%, Europe at ~21%, South America ~4% and the Middle East and Africa ~3%. The distribution reflects manufacturing and module integration as well as purchases by operators that deploy transceivers in switching, mobile transport, fiber backbones and inter-data-center networks. Asia combines the largest production cluster with growing optical connectivity needs; North America has strong hyperscale demand and Europe retains an important carrier network base.

Which geographic areas shape optical transceiver manufacturing and adoption?

The regional mix links component supply locations to equipment procurement patterns. Chinese production and broader East Asian electronic manufacturing support high-volume optical assembly; US hyperscalers and networking equipment vendors influence demand for advanced 400G, 800G and 1.6T optics; and European fiber operators emphasize interoperability and wavelength efficiency. In South America and the Middle East and Africa, equipment is often imported for telecommunications and enterprise upgrades. Regional comparisons therefore combine direct purchases of modules with upstream value embedded in internationally shipped optical equipment.

Region Position Growth outlook Demand profile What decides supplier selection
Asia-Pacific Largest (~42%) Fast (~9.2% CAGR) Optical module manufacturing, cloud links and fiber networks Manufacturing yield and optical supply chain
North America Second (~30%) Growth (~8.6% CAGR) Cloud and AI switching networks 800G/1.6T power and port qualification
Europe Third (~21%) Growth (~7.8% CAGR) Metro and long-haul optical upgrades Coherent pluggable interoperability
South America Developing (~4%) Growth (~7.1% CAGR) Carrier backbone and enterprise optical links Import availability and network compatibility
Middle East & Africa Developing (~3%) Growth (~7.5% CAGR) Data-center interconnect and telecom fiber expansion Resilient field deployment

Asia-Pacific LARGEST · ~42% SHARE

Why does Asia-Pacific lead module supply and optical demand?

Asia-Pacific contributes approximately ~42% of 2025 revenue and an estimated ~9.2% CAGR. The region includes established transceiver assembly and photonic component manufacturers in China and Northeast Asia, together with expanding fiber projects and cloud capacity in India and Southeast Asia. Countries have different strengths: Chinese production scale, Japanese precision optics, South Korean optical components and Indian network construction. Competitive success relies on aligning 400G and 800G designs with production yield, optical testing capacity and internationally accepted host-module interfaces.

Market positionLargest region (~42%)
Growth outlookFast expansion (~9.2% CAGR)
Demand profileOptical module manufacturing
Market access gate400G/800G supplier qualification
Country Position in region What drives demand
China Module manufacturing center China is a major base for the manufacture and assembly of optical modules, lasers and associated components serving domestic and overseas networking markets. Suppliers compete at 10G, 100G, 400G and higher classes, with manufacturing economics shifting as newer devices require denser packaging and more advanced DSPs. Carrier upgrades and cloud deployment support domestic orders, but product design wins depend on the electrical and optical requirements of the final equipment customer.
Japan and South Korea High-performance optical devices Japan and South Korea contribute precision optoelectronic materials, laser technology, optical device engineering and demanding enterprise or carrier equipment programs. Manufacturers must qualify transmission performance and operating reliability at the interface level. The move from established 100G products toward 400G and 800G systems increases the value of specialist transmitters, detectors, package materials and high-frequency testing, creating opportunities beyond final module assembly.
India and Southeast Asia New fiber network capacity India and Southeast Asia add transport connectivity and data-center facilities that increase requirements for optical transceivers across 100G, 400G and longer-reach coherent interfaces. Large national fiber projects coexist with private cloud and enterprise networks, so procurement ranges from traditional SFP modules to higher-capacity pluggables. Suppliers typically address the market through equipment vendors and system integrators rather than selling identical devices across all network segments.

Market instances

  • Coherent displayed multiple 1.6T technologies at OFC 2026 In March 2026 Coherent announced demonstrations of 1.6T pluggable technologies using silicon photonics, indium phosphide, and gallium-arsenide VCSEL solutions. The portfolio also discussed 3.2T and more demanding interconnect architecture. The market significance is that East Asian device, packaging and assembly supply chains must qualify several optical implementations rather than depend on one universal 1.6T production design.
  • India tested 1.6 Tb/s optical transport as networks scale Ciena reported in March 2026 that Vodafone Idea tested 1.6 Tb/s channel performance between two Indian data centers using WaveLogic 6 technology. The program illustrates demand for capacity upgrades beyond 400G and 800G service interfaces, although a wavelength demonstration should not be interpreted as a volume shipment count for pluggable modules. It supports interest in higher-rate coherent optical infrastructure.
  • Asian factories balance 100G maturity with 800G production demands Many electronics producers can assemble mature 100G QSFP28 transceivers using established processes, while 800G devices require greater channel density and careful heat management. Coherent and Marvell optical component roadmaps show more photonics and DSP functions inside each module generation. The market implication is investment in thermal testing, optical alignment and automated yield inspection, with cost reductions developing through manufacturing learning.
In the full report: China, Japan, South Korea, India, Taiwan, Singapore and Southeast Asian networks, optical component manufacturing, module assembly and links from 100G to emerging 1.6T systems.

North America SECOND · ~30% SHARE

Why do North American cloud operators influence transceiver design?

North America represents approximately ~30% of market value and is expected to grow at roughly ~8.6% CAGR. Large US cloud and AI infrastructure buyers set demanding specifications for 400G, 800G and 1.6T Ethernet optics, while Canadian network operators and photonic engineers participate in optical development. Mexico contributes regional electronics integration. The central purchasing challenge is to expand optical port density without uncontrolled growth in power draw, heat and fiber management complexity.

Market positionShare (~30%)
Growth outlookGrowth (~8.6% CAGR)
Demand profileHyperscale optical networks
Market access gateLow-power 1.6T technology
Country Position in region What drives demand
United States Cloud optical demand United States data-center operators are influential buyers of optical transceivers for high-capacity switching fabrics, server networks and campus interconnects. Suppliers compete over 400G/800G pluggable deployment readiness and 1.6T module development. The purchase decision spans device functionality, qualified host support, power per port, error monitoring and delivery commitments, with products tested within complete networking platforms before volume orders are approved.
Canada Transport and photonics research Canadian carriers and photonic engineering firms contribute specialized optical communication expertise, including metropolitan transmission, coherent components and optical test systems. Enterprise data centers require dependable transceivers that match existing equipment, while more demanding networks explore 400ZR, 800ZR and wider optical reach. Orders are influenced by network construction cycles and certified components rather than isolated optical module technology announcements.
Mexico Regional equipment integration Mexico participates in North American electronics manufacturing and equipment distribution chains used by communications and computing businesses. Demand for optical transceivers is usually specified through OEM platforms and approved vendor lists. Short-reach interfaces may prioritize price and delivery, whereas 400G or 800G programs require qualified assembly practices and strict thermal specifications. Local system integration can benefit from cross-border networking equipment supply chains.

Market instances

  • Marvell expanded 1.6T DSP offerings in March 2026 Marvell announced an expanded 1.6T optical DSP portfolio in March 2026, reflecting demand for 200G-per-lane interfaces across cloud interconnect equipment. Its 3nm Ara platform targets high bandwidth with lower power per transferred bit. The market implication is a broader set of component choices for 800G and 1.6T module assemblers as hyperscale buyers evaluate interoperable optical engines.
  • Broadcom uses 200G-per-lane PHY technology for multimode links Broadcom describes a 5nm BCM85834 device with a 200G-per-lane PAM4 optical PHY and an integrated VCSEL driver intended to enable 1.6T multimode pluggables. The design shows how semiconductor integration can reduce separate components in module assemblies. Deployment still requires photonic quality control and compatibility with the host system, meaning PHY specifications alone do not establish finished transceiver market share.
  • North American equipment suppliers support 800G coherent modules Cisco specifies QSFP-DD and OSFP 800G ZR/ZR+ coherent optics for applications reaching roughly 120km and beyond 1000km with suitable line systems. The move allows some optical transport functions to be integrated into pluggable interfaces at router ports. For buyers, the relevant operational test includes forward error correction, optical channel planning and performance monitoring, not merely transceiver electrical signaling rate.
In the full report: United States, Canada and Mexico cloud infrastructure, network equipment procurement, optical DSP supply and advanced transceiver qualification programs.

Europe THIRD · ~21% SHARE

How does European optical network modernization affect module demand?

Europe accounts for an estimated ~21% of revenue and around ~7.8% CAGR, supported by metro networks, data-center corridors and long-reach carrier connectivity. Telecommunications companies are interested in coherent pluggables that permit higher rates on existing fiber and DWDM systems. Equipment makers and carriers in Germany, France and the United Kingdom value optical reach, wavelength interoperability and predictable service operations. European demand consequently spans both high-speed router interfaces and optical transport modules designed for longer spans.

Market positionShare (~21%)
Growth outlookGrowth (~7.8% CAGR)
Demand profileOptical transport networks
Market access gate400ZR/800ZR compatibility
Country Position in region What drives demand
Germany Network and industrial engineering Germany combines enterprise networking, carrier connectivity and electronics engineering ecosystems that purchase qualified transceiver products across several speed classes. Industrial sites may retain 10G or 40G equipment, whereas higher-capacity data-center environments require 100G/400G links and newer 800G solutions. Purchasers assess compliance with electrical interfaces, optical performance and service-life requirements before broad adoption, especially when upgrading existing fiber pathways.
France Optical networking expertise France has an established optical networking technology and telecommunications ecosystem with experience in coherent transport and photonic equipment. Interoperability initiatives encourage the use of standardized 400ZR and 800ZR modules for appropriate spans. Buyers examine operational monitoring, DSP power, laser tuning and the ability to integrate transceivers with installed routers and line systems. The same ecosystem also supports optical research beyond current commercial deployment.
United Kingdom Carrier and data-center networks The United Kingdom supports dense telecommunications routes and cloud interconnect needs, where higher-capacity optical pluggables can reduce rack usage and simplify port-level upgrades. Network planners distinguish short-reach Ethernet transceivers from coherent modules operating on amplified fiber routes. Component procurement depends on verified host support, optical reach and operating conditions, and some older interfaces remain essential for equipment still in service.

Market instances

  • OIF released the 1600ZR agreement in September 2026 The Optical Internetworking Forum published a 1600ZR implementation agreement defining a 1.6T coherent line interface for amplified links up to 120km. The agreement sets interoperability expectations for the next generation after 800ZR. European network equipment developers can use the technical framework when assessing pluggable solutions, but the existence of a standard is not itself confirmation of commercial shipment volume.
  • European routes can use Nokia coherent pluggables Nokia reported a Telxius deployment of 800G coherent pluggable optics in September 2026 covering European and other international network corridors. The project illustrates how carriers are testing and adopting denser coherent connections for cloud and international traffic. Transceiver suppliers must match line-system design, host interfaces and operational requirements before these modules can replace existing optical components on a route.
  • Optical compatibility matters across multiple module generations European operators may operate a mix of 100G enterprise interfaces, 400ZR metropolitan links and newer 800ZR equipment. The same chassis and fiber plant can have different optical budgets and software management capabilities across generations. As a result, replacement procurement requires device qualification and realistic system engineering rather than treating an advertised 800G rate as sufficient to ensure interoperability.
In the full report: Germany, France, the United Kingdom and regional European optical transport corridors, focusing on coherent equipment qualification, DWDM interfaces and cloud connectivity.

South America EMERGING · ~4% SHARE

Where do South American optical transceiver opportunities arise?

South America contributes approximately ~4% of 2025 market value and grows around ~7.1% CAGR. Brazil is a central telecommunications and enterprise networking market, while Chile and Argentina require transceiver capacity in carrier and data-center systems. Many modules arrive through imported switching and optical transport equipment. Procurement therefore concentrates on equipment compatibility, qualified replacements and improving the economics of regional backbone connectivity rather than a large domestic high-speed photonics production cluster.

Market positionShare (~4%)
Growth outlookGrowth (~7.1% CAGR)
Demand profileFiber backbone demand
Market access gateRegional import and integration
Country Position in region What drives demand
Brazil Largest regional market Brazil concentrates major telecommunications and commercial data infrastructure activities in South America. Networks may upgrade Ethernet transport from 100G toward 400G, with coherent optical modules improving fiber use on regional routes. Demand for standalone transceiver units usually comes through equipment vendors and authorized integrators. Import conditions, local service capability and warranty support influence purchases alongside optical reach and module price.
Chile Long-distance connectivity Chile relies on high-capacity fiber routes for enterprise services, cloud connectivity and access to international cable systems. Optical transceivers used in such networks must support the transmission distance, amplification plan and equipment interfaces already installed. Projects can create incremental demand for 100G and 400G modules, with 800G adoption depending on the capability of the surrounding routers and transport line systems.
Argentina Carrier and enterprise networks Argentina uses optical modules in metro fiber, enterprise switching and telecommunications networks where equipment upgrades are planned around budget cycles. Mature SFP and QSFP products remain relevant while higher throughput requirements support selective deployment of coherent interfaces. Buyers commonly compare supported vendor models, fiber type and optical margin, making interoperability and product availability more influential than the newest nominal line rate.

Market instances

  • Ciena presented 1.6Tb/s transport options at Futurecom 2026 Ciena’s September 2026 Futurecom announcement for São Paulo included WaveLogic 6 Extreme 1.6 Tb/s transport technology and data-center interconnect demonstrations. This illustrates the regional relevance of terabit optical network planning, even though transport platform capacity is not equivalent to transceiver module sales. The implications are growing equipment familiarity and a potential path for future coherent pluggable adoption.
  • Imported optical modules must match local installed systems A carrier may have 100G/400G connections from several equipment generations deployed across a regional fiber route. Ordering an 800G replacement without checking host support, wavelength compatibility and amplification performance risks a failed upgrade. The market implication is resilient demand for approved modules and detailed vendor certification, not only rapid shipments of the highest-rate new products.
  • Network operators balance capacity upgrades against funding The economics of a new optical transceiver include module price, labor, available switch ports, line-system investment and expected bandwidth utilization. A 400G deployment can be more practical than an 800G change if other equipment must also be replaced. Regional demand therefore progresses in platform-specific stages; suppliers with reliable long-life 100G and 400G inventory retain valuable customer relationships.
In the full report: Brazil, Chile, Argentina and neighboring South American countries, connecting regional carrier network upgrades to compatible optical modules and equipment finance.

Middle East & Africa EMERGING · ~3% SHARE

What role do Gulf and African connectivity projects play?

The Middle East and Africa represent an estimated ~3% market share and roughly ~7.5% CAGR. Gulf cloud and telecom infrastructure projects need high-bandwidth optical backbone links, while African markets expand network access and international fiber connectivity unevenly. Saudi Arabia and the United Arab Emirates drive data-center and high-capacity enterprise installations, with South Africa an established regional fiber and colocation center. Most sophisticated 400G/800G modules are imported from global suppliers and qualified against deployed equipment.

Market positionShare (~3%)
Growth outlookGrowth (~7.5% CAGR)
Demand profileCloud and backbone routes
Market access gateHigh-temperature field support
Country Position in region What drives demand
Saudi Arabia National digital infrastructure Saudi Arabian telecommunications and data-center projects require progressively denser fiber connectivity between network aggregation points and computing facilities. Optical transceiver purchases follow certified equipment platforms, with 100G/400G products serving many current routes and 800G options relevant to higher-throughput designs. Equipment owners consider electrical power, temperature tolerance, wavelength reach and long-term service contracts before qualifying replacements or new interface families.
United Arab Emirates Regional data-center hub The United Arab Emirates attracts enterprise networking and inter-data-center demand, generating need for optical pluggables spanning intra-building links and metropolitan fiber routes. The appropriate module may be a direct-detection Ethernet optic or a coherent device, depending on reach and transmission impairments. Procurement commonly relies on approved OEM modules and stable delivery channels, since systems are sensitive to incompatible or poorly tested third-party optics.
South Africa Southern African connectivity South African operators and data-center businesses maintain optical transport and switching infrastructure that connects regional facilities to wider international networks. Mature 10G and 100G modules coexist with plans for higher-speed backbones. Supplier opportunities depend on equipment compatibility, regional support and fiber-system economics, while faster coherent interfaces may become useful where network traffic and available optical line infrastructure justify their cost.

Market instances

  • Data-center clustering makes optical reach a planning variable Cloud facilities operating within one campus can use short-reach direct-detection modules, while sites separated by many kilometers often require different optical budgets or coherent technology. Cisco 800ZR specifications reference roughly 120km reach over amplified systems, and ZR+ products can target much longer routes. The market implication is a varied transceiver mix shaped by geography and facility placement.
  • Dense pluggables must satisfy thermal operating limits Higher speed modules integrate more signal-processing and optical functions in limited package space. Hot environmental conditions add constraints for equipment racks, particularly where cooling and maintenance capacity are uneven. Network buyers therefore evaluate 400G/800G module power and environmental ratings alongside fiber reach, instead of treating aggregate throughput as the only purchasing criterion for new optical equipment.
  • Carrier projects rely on long-term interoperable supply An operator extending metro or backbone capacity usually procures transceivers through a qualified optical equipment supply chain. The systems must be tested against router software, interface monitoring and the installed DWDM platform. This supports demand for proven products and spare inventory across several generations, while future 800ZR or 1600ZR adoption depends on supported equipment and service economics.
In the full report: Saudi Arabia, the United Arab Emirates, South Africa and adjacent African and Gulf optical networks, emphasizing data-center interconnect and qualified fiber transport equipment.

Key Transceivers for Optical Communication Manufacturers and Competitive Landscape

The optical transceiver market brings together vertically integrated photonics manufacturers, networking equipment companies, semiconductor component suppliers and regional module assemblers. Coherent, Lumentum, Cisco, Broadcom and suppliers serving 400G/800G optical connectivity compete or influence competition through different parts of this chain. Marvell and Broadcom provide high-speed electrical and optical processing devices, while Ciena and Nokia help define transport system requirements. Actual competitive positions vary across pluggable form factor, transmission reach and module bandwidth, so upstream supplier activity is not directly equal to finished module share.

Coherent supplies a broad photonics platform that spans indium-phosphide technology, silicon-photonic components, VCSEL devices and advanced optical module designs. Its March 2026 demonstrations included several 1.6T transceiver approaches and future optical interconnect paths. This breadth supports choices between short-reach multimode and high-speed single-mode designs. Yet each product still requires qualification at the host platform and optical link level, and a demonstration should not be interpreted as commercial unit shipments.

Lumentum participates in optical components and cloud networking markets, highlighting 1.6T adoption and optical circuit switching opportunities in 2026 financial communications. The company brings photonic device design and manufacturing experience to customer programs requiring demanding transmitter and receiver specifications. Suppliers are evaluated on wavelength stability, component availability, packaging quality and operating margin, with telecommunications and data-center customers assigning different priorities to transmission reach and module energy use.

Cisco and other networking equipment firms specify the electrical, thermal and optical requirements that individual transceiver products must satisfy. Cisco documentation for 800G ZR/ZR+ coherent modules details host form factors and route reach classes, allowing integrators to validate complete transmission platforms. Ciena and Nokia similarly provide evidence of operator transport requirements, through projects reaching 800G and 1.6 Tb/s wavelengths. These participants shape product roadmaps even when their core business is broader than selling a standardized merchant module.

Broadcom and Marvell compete at the high-speed DSP and optical PHY layer, affecting the bill of materials, energy budget and possible reach of finished optical transceivers. Broadcom highlights a 200G-per-lane VCSEL-oriented PHY, and Marvell markets PAM4 solutions addressing 100G through 1.6T modules. Equipment makers combine these semiconductor inputs with lasers, detectors, connectors and mechanical packaging. The result is competition based on an integrated supply chain rather than on a single interchangeable component.

Tier structure

Tier Companies Basis of competition
Optics specialists Coherent, Lumentum Photonic devices, laser technologies, high-speed optical assembly development and integration engineering serving carrier and data-center transceiver programs.
Optical processing and PHY Broadcom, Marvell Technology Optical PAM4 DSPs, integrated PHY capabilities, laser-driver support and electronics that enable 400G/800G/1.6T module designs.
Equipment and transport ecosystem Cisco Systems, Nokia, Ciena Optical system interfaces, coherent module certification, operator deployments and standards participation influencing the economics of complete optical networking devices.

Key companies profiled

  • Coherent Corp.
  • Lumentum Holdings
  • Broadcom
  • Marvell Technology
  • Cisco Systems
  • Nokia
  • Ciena
  • Sumitomo Electric
  • Accelink Technologies
  • InnoLight Technology
  • Eoptolink Technology

Transceivers for Optical Communication Production Capacity Analysis

Optical transceiver production combines semiconductor and photonic wafer fabrication, laser assembly, micro-optics, printed circuit manufacture, hermetic or non-hermetic packaging, precision fiber attachment and automated electrical testing. Manufacturing clusters in Asia serve much of the international market, while specialist optoelectronic devices and engineering capabilities are distributed across North America, Europe and Japan. Capacity differs by product generation: 10G and 100G modules have established process routes, whereas 800G and 1.6T programs rely on faster component test equipment and more stringent thermal validation.

Module manufacturing begins with optical device procurement and electronic PCB preparation. Laser chips, photodiodes and driver or DSP semiconductors must be matched to an optical design before assembly because tolerances accumulate across transmission and receiving paths. Higher-capacity products require better control of thermal dissipation, optical alignment and high-speed electrical routing. Yield can be constrained by a specific component or calibration process even when general factory floor space is available for additional units.

A QSFP28 100G module and an 800G QSFP-DD device have markedly different testing burdens. At the higher speed, manufacturers validate multiple 100G/200G lanes, electrical eye performance, optical receive margin and complex error-correction integration. Coherent products bring additional tunable components and DSP tests, while multi-mode short-reach modules depend on laser-array uniformity. Production capacity therefore should be measured in qualified units of a particular link class, not only an overall count of module packages.

Advanced manufacturing programs place growing weight on supplier diversification and repeatable high-speed inspection. A 1.6T optical engine may use an eight-lane 200G architecture requiring precision integration of detectors, lasers and electronic chips. If a qualified optical device or DSP becomes scarce, the final module line can slow even when other parts are readily available. Customers assess test records, quality returns and delivered power characteristics to select partners for multi-year networking rollouts.

Transceivers for Optical Communication Market Dynamics: Drivers, Restraints and Opportunities

Demand is rising as AI networking clusters increase optical lane counts, cloud operators refresh server fabrics and carriers migrate to coherent transmission at higher rates. Suppliers must move between 100G, 400G, 800G and 1.6T module families while controlling power draw and electrical compatibility. Optical component shortages, manufacturing yield and intense price competition can offset growth. The impact tables describe the relative contribution of these factors to the overall growth trajectory and are not independent product market-share estimates.

MARKET DRIVERS

Drivers Impact Analysis*

Market Drivers Impact Rank CAGR Contribution (%) 2026–2028 2029–2031 2032–2034
AI and hyperscale optical interconnect buildout High +4.20% High High High
400G to 800G and 1.6T platform migration Medium-High +2.70% High High High
Coherent pluggable 400ZR/800ZR adoption Medium +1.40% Medium High High
Backbone and 5G fiber capacity upgrades Low-Medium +1.10% Medium Medium Medium
Others (enterprise connectivity and specialty links) Low +0.80% Low Medium Medium

AI-network links expand the requirement for optical ports

Machine-learning computing clusters frequently exchange large volumes of data among accelerators, servers and network switching systems. Optical interfaces must handle this traffic within strict latency and energy requirements, prompting 400G and 800G module adoption and investment in 1.6T technology. Coherent demonstrated multiple advanced 1.6T optical approaches in March 2026, while Marvell described its evolving 3nm DSP platform. New design programs increase the commercial opportunity for qualified photonic and electronic components.

Module line rates move upward as switch density increases

Transitioning from 100G to 400G can reduce the number of physical ports required for a given aggregate throughput, while 800G QSFP-DD and OSFP modules extend the pattern in supported networking hardware. Cisco’s coherent module specifications illustrate the complexity of specifying reach and form factor at high rates. Suppliers can sell more capable modules with greater integration content, but the price premium must compensate for optical packaging and testing costs.

Coherent standards expand inter-data-center possibilities

OIF published implementation agreements for 400ZR and 800ZR and followed with a 1600ZR specification in September 2026. Common interface expectations allow optical system makers and module suppliers to target compatible deployments over amplified metropolitan routes. Cisco describes 800G coherent optics designed for distances around 120km and much longer with ZR+ line-system support. Standardization can reduce uncertainty for carrier operators evaluating whether coherent pluggables suit a particular fiber route.

Fiber upgrades increase the addressable transport market

Ciena cited Vodafone Idea testing a 1.6 Tb/s wavelength in India during 2026, while Nokia reported 800G coherent pluggable work with Telxius international transport networks. These programs show demand for new optical capacity from telecommunications and cloud customers. Module adoption depends on equipment interfaces and fiber routes, but rising traffic provides a practical reason for operators to evaluate additional transceiver generations and higher-capacity components.

MARKET RESTRAINTS

Restraints Impact Analysis*

Market Restraints Impact Rank CAGR Contribution (%) 2026–2028 2029–2031 2032–2034
High-speed optical assembly and qualification expenses Medium -0.90% High Medium Medium
Module power and thermal constraints Low-Medium -0.50% Medium High Medium
Others (pricing pressure and component concentration) Low -0.40% Medium Medium Low
*CAGR contribution shows the percentage points each factor adds to or removes from the forecast CAGR for 2026–2034; driver contributions less restraint contributions equal the market CAGR. Period columns rate the strength of each factor in that window.

Component packaging complexity can limit qualified yield

An 800G or 1.6T transceiver contains multiple high-speed optical and electronic paths that must perform together under operational temperature limits. Electrical parasitics, optical alignment and DSP behavior complicate assembly and production tests. A faulty laser, detector or receiver chip can prevent final qualification even when the module is otherwise complete. Manufacturers must invest in automation, high-frequency instrumentation and process repeatability before reliable commercial volume is achieved.

Thermal envelopes restrict dense pluggable integration

Higher aggregate throughput brings additional optical laser, driver and DSP power into a physically limited QSFP-DD or OSFP housing. Host switches have finite cooling capacity and defined allowable interface temperatures, creating design trade-offs among density, speed and reach. Even a technically functioning module can be unsuitable if the surrounding chassis cannot dissipate its heat. Equipment suppliers therefore evaluate full-system power and airflow before approving the next optical generation.

Mature optical products face continuing price erosion

Standardized 10G, 40G and 100G transceivers can be offered by many suppliers, creating strong pressure on average selling prices. Buyers often compare approved alternatives by cost, warranty and delivery time once electrical and optical requirements are met. The growth in 400G and 800G products may lift overall market value, yet manufacturers must keep developing differentiated performance to counter reduced margins on older product lines.

MARKET OPPORTUNITIES

Co-packaged optics could change the optical module boundary

Placing optical engines near switching or computing silicon can shorten high-speed electrical connections and improve system-level energy efficiency. Coherent demonstrated photonic platforms relevant to more integrated optical architectures, and Lumentum has discussed related photonic demand in financial communications. The opportunity for optical suppliers is substantial, but traditional pluggable module revenue should be distinguished from embedded engine sales as competing equipment architectures evolve.

1600ZR promises an interoperable 1.6T coherent class

The OIF September 2026 agreement for 1600ZR supports a single 1.6T coherent line interface on suitable amplified spans of up to approximately 120km. Such standards can create new design requirements for tunable lasers, coherent DSPs, optical assemblies and compact pluggable packages. The commercial prize is more optical capacity per host port, but adoption depends on the arrival of compatible routers, operational tools and production-qualified modules.

Optical telemetry and diagnostics create equipment differentiation

Fast pluggable transceivers increasingly include module-management and monitoring functions that help operators identify electrical and optical problems. DSP vendors and equipment makers can integrate performance counters, signal diagnostics and software control to reduce service disruptions. Suppliers that combine consistent optical performance with accessible monitoring can win customer confidence even where nominal bandwidth is similar to competing units, particularly in large 400G and 800G fleets.

Transceivers for Optical Communication Supply Chain Analysis

The value chain begins with compound-semiconductor wafers, silicon-photonic chips, VCSELs, laser diodes, photodiodes, optical fibers and high-speed signal-processing semiconductors. Module manufacturers combine these with circuit boards, optical alignment structures, connectors and thermal housings, then test finished products against equipment interfaces. Networking OEMs, cloud companies, telecom carriers and regional distributors are downstream customers. Production yield and qualified suppliers become especially important as module families move from 100G/400G toward 800G and 1.6T assemblies.

UpstreamOptical wafers and lasers, InP devices, VCSEL arrays, silicon-photonic PICs, photodiodes, PAM4 and coherent DSPs, driver semiconductors, connector materials
Module manufacturingPhotonic assembly, optical alignment, PCB fabrication, high-frequency electrical and optical testing, thermal screening, QSFP/OSFP mechanical packaging
Distribution and integrationOptical module vendors, switch and router manufacturers, transport system integrators, component distributors, network commissioning and qualification labs
End customersHyperscale data centers, carrier backbone operators, mobile-network providers, enterprises, public sector fiber systems and specialist industrial communication sites

Upstream. A high-speed transceiver draws on a mix of compound-semiconductor and CMOS inputs whose supply risks differ. Laser or photodetector wafer processes require specialized manufacturing control, while the digital signal processor depends on advanced semiconductor fabrication and software validation. Selecting the wrong optical source can prevent compliance with a specific reach or wavelength plan. Manufacturers therefore design qualified bill-of-material combinations rather than treating every optical or electronic device as interchangeable.

Module manufacturing. Assembly lines must mount the optical engines, electrical chips and connector interfaces within stringent mechanical tolerances. Product tests can include host-electrical signal compliance, transmit-eye quality, receiver sensitivity, optical launch power, wavelength stability and thermal operation. A single 800G module may demand testing across several 100G or 200G lanes, increasing test-equipment occupancy. Higher production throughput depends on automated calibration and low rework rates as much as labor and factory capacity.

Distribution and integration. A transceiver may be sold directly to a cloud platform buyer or through an equipment manufacturer whose switch or router software validates approved optical devices. Carriers often require interoperability with transport systems and monitoring tools before deploying coherent modules on live routes. Buyers look for multi-year availability, trackable serial data and predictable failure handling. A technically compatible module without the required qualification can remain commercially excluded from a large installed hardware platform.

End customers. Cloud operators typically concentrate purchases around new switch designs and AI network construction, making optical lane capacity and power per port critical. Telecom carriers balance route capacity with line-system support, operational alarms and wavelength interoperability. Enterprises often retain older 10G and 100G optics for established network equipment, so the channel needs diverse product inventories. The mix produces ongoing replacement demand alongside high-value deployments of 400G, 800G and coherent technologies.

Recent Developments in the Transceivers for Optical Communication Market

  • 9 September 2026 Interoperability agreement
    OIF published the Implementation Agreement for 1600ZR coherent interfaces, specifying a single 1.6T coherent wavelength over amplified links up to 120km. The milestone expands the interoperable roadmap beyond 800ZR and gives optical DSP, laser and module developers a common technical target. Network operators still need host platforms, wavelength compatibility and finished products before a published agreement becomes deployed transport capacity. Source
  • 17 March 2026 Next-generation pluggable optics
    Coherent announced an OFC 2026 technology showcase of 1.6T optical transceivers and architectures reaching 3.2T and beyond. Demonstrations included silicon photonics, indium-phosphide lasers and VCSEL-based technologies. This signals development activity across multiple physical transmission approaches; the company showcased solutions rather than reporting a unified commercial shipment count for all announced speed classes. Source
  • 12 March 2026 Optical DSP portfolio
    Marvell announced a broader 1.6T optical DSP platform family as hyperscale networks moved from 800G to more demanding interfaces. The company discussed its prior 5nm Nova and 3nm Ara developments and shipments to customers. For transceiver manufacturers, this broadens electronic component choices but does not eliminate optical assembly and power qualification requirements for commercially supported module products. Source
  • 13 July 2026 Coherent pluggable equipment documentation
    Cisco updated its specifications for 800G QSFP-DD and OSFP ZR/ZR+ coherent optical modules, covering 800ZR distances up to about 120km on amplified DWDM systems and ZR+ transport above 1000km under suitable conditions. The specifications help network planners match optical reach and host interfaces, although realized distance remains dependent on fiber, amplification and line-system design. Source
  • 15 September 2026 International optical transport deployment
    Nokia announced that Telxius was adopting 800G coherent pluggable technology across terrestrial transport routes spanning Europe, the United States and Latin America. The project supports growing demand for cloud and data-center network capacity. It demonstrates a concrete optical transport use case while requiring distinction between completed network integration and the broader worldwide market for merchant transceiver modules. Source
  • 11 August 2026 Cloud optical component investment
    Lumentum reported fiscal fourth-quarter 2026 revenue of about USD 1.01 billion and described momentum associated with cloud optical modules and 1.6T adoption. The disclosure supports continued investment in relevant photonics technologies, but the company-wide figure covers a range of product areas and should not be interpreted as revenue from the optical transceiver segment alone. Source
  • September 2026 Next-generation transport showcase
    Ciena described an ECOC 2026 showcase including 800G pluggable coherent optics, 1600ZR+ directions and technologies supporting AI data-center transport networks. The portfolio illustrates multiple approaches to increasing throughput and using existing fiber capacity. Commercial selection still depends on coherent line interfaces, module diagnostics, operator maintenance expectations and the power envelope of installed networking equipment. Source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2020–2034
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
Historical Period 2020–2024
Market Size 2025 USD 13.44 billion
Market Size 2026 USD 14.56 billion
Market Size 2034 USD 27.72 billion
Growth Rate CAGR of 8.4% from 2026–2034
Unit Revenue (USD Billion)
Segmentation By Data Rate, Application, Technology, Form Factor and Region
By Type 10 G · 40 G · 100 G · 200 G · 400 G · Others (800G and emerging higher rates)
By Application Telecommunication · Data Center (Datacom) · Other
By Technology Direct Detection · Coherent Optical
By Form Factor SFP/SFP+ · QSFP/QSFP28 · CFP/CFP2 · Others including QSFP-DD and OSFP
By Region Regional coverage analyses optical module use, supplier manufacturing and country-specific carrier and cloud demand
Asia-PacificChina, India, Japan, South Korea, Southeast Asia, Rest of Asia-Pacific
North AmericaUnited States, Canada, Mexico
EuropeGermany, France, United Kingdom, Rest of Europe
South AmericaBrazil, Chile, Argentina, Rest of South America
Middle East & AfricaSaudi Arabia, United Arab Emirates, South Africa, Rest of Middle East & Africa
Key Companies Profiled Coherent, Lumentum, Broadcom, Marvell Technology, Cisco Systems, Ciena, Nokia, Sumitomo Electric, Accelink Technologies, InnoLight Technology and Eoptolink Technology
Customization Scope Custom coverage may add optical module specifications, 800G and 1.6T platform adoption, vendor qualification, country-level interfaces and single-mode or multimode product breakdowns.

Frequently Asked Questions

How large is the transceivers for optical communication market?

Global optical communication transceiver revenue is estimated at USD 13.44 billion in 2025 and is expected to reach USD 27.72 billion by 2034. The scope covers complete transmit-and-receive optical modules used for data centers, telecommunications and other networks. Component-only sales and the wider values of switches, fiber and service contracts are outside that specific product boundary.

What is the expected compound growth rate?

The worldwide market is expected to grow at a 8.4% CAGR for the forecast horizon. Data-center optical port demand, migration from 100G to 400G/800G systems and the use of higher-capacity coherent pluggables support the outlook. Manufacturing costs, qualification cycles and module power limitations remain important constraints as buyers replace older equipment in phases.

Which speed category generates the largest revenue?

The 400 G type is the largest estimated category at ~35% of market value, followed by 100 G at ~18%, 200 G at ~16%, the other category including 800 G and emerging rates at ~15%, 40 G at ~9% and 10 G at ~7%. The speed categories refer to marketed module capability, not to independent laser or DSP sales.

Which application dominates transceiver purchases?

Data-center networking is the largest application with approximately ~55% share, followed by telecommunications at ~36% and other optical networking uses at ~9%. Cloud systems procure numerous dense Ethernet transceivers, whereas carrier operators require a mix of metro, coherent and longer-reach equipment. A specific 800G module may not be interchangeable between these applications because signaling and optical reach differ.

How does direct detection differ from coherent optics?

Direct-detection modules represent about ~67% of 2025 value and are widely used for short and medium optical links. Coherent optical transceivers account for an estimated ~33% and combine advanced modulation, DSP functions and wavelength control for longer or spectrally demanding routes. Technical requirements and component pricing are substantially different between these two categories, so data rates alone do not determine product suitability.

Which world region leads optical transceiver sales?

Asia-Pacific leads with approximately ~42% of market value, benefiting from optical component manufacturing, module integration and network investment. North America contributes around ~30% through cloud systems and high-speed switching demand, Europe ~21% through carrier and enterprise networks, South America ~4%, and the Middle East and Africa around ~3%. These estimates concern module market value, not solely physical shipment volume.

How are new optical modules changing form-factor demand?

SFP/SFP+ represents about ~18% of value, QSFP/QSFP28 around ~37%, CFP/CFP2 ~15%, and other designs including QSFP-DD and OSFP approximately ~30%. Higher bandwidth requirements favor dense pluggable formats that can contain 800G or emerging 1.6T optical engines. Customers must still check mechanical compatibility, electrical host interfaces, cooling constraints and the fiber connection type.

What do the 800ZR and 1600ZR standards address?

OIF implementation agreements describe interoperable coherent optical interfaces for high-capacity data-center interconnect applications. The 800ZR family addresses 800G-capable coherent links, while the September 2026 1600ZR agreement targets a 1.6T coherent wavelength over amplified spans up to approximately 120km. Such standards clarify technical interoperability but do not guarantee a finished product works with every host chassis or optical line system.

Which suppliers are relevant to the commercial ecosystem?

Coherent and Lumentum contribute optical component and photonic module technologies; Broadcom and Marvell supply high-speed signal-processing electronics; and Cisco, Ciena and Nokia shape optical equipment requirements and implementation. The market also includes dedicated module manufacturers and regional component specialists. Competitive comparisons must separate manufacturing of complete modules from sales of enabling semiconductors and networking equipment.

What constrains widespread 1.6T adoption?

Optical 1.6T designs require higher per-lane signaling rates, compatible switching hardware, careful thermal engineering and consistent optical assembly yield. Coherent and Marvell demonstrated 2026 technology progress, but buyers assess full-system power consumption, interoperability and maintenance cost before mass deployment. The global long-term outlook of 8.4% CAGR reflects many generations of products, not the immediate conversion of every installed 100G or 400G interface.

Research Sources & Evidence Base
View research sources used for this overview
  1. Coherent. OFC 2026 transceiver demonstration, 1.6T and future pluggable technologies, 17 March 2026.
  2. Marvell. Expanded 1.6T optical DSP portfolio, Optical DSP module architectures and 200G lanes, March 2026.
  3. Marvell. Ara DSP engineering recognition, 3nm 1.6T high-speed interface technology, February 2026.
  4. Broadcom. BCM85834 PAM4 optical PHY, 200G per lane VCSEL driver integration and 1.6T multimode architecture.
  5. Cisco. 800G ZR and ZR+ coherent pluggables, Optical reach, QSFP-DD and OSFP interfaces, July 2026.
  6. OIF. 1600ZR coherent implementation agreement, Interoperable 1.6T link standard announced 9 September 2026.
  7. OIF. Coherent interface agreements, 400ZR, 800ZR and 1600ZR standards history and approval.
  8. OIF. 800G coherent optical project, 800G applications over amplified and unamplified fiber links.
  9. Marvell. PAM4 optical DSP products, 100G to 1.6T signal processing portfolio.
  10. Lumentum. Fiscal fourth quarter 2026 results, Cloud optical product growth and 1.6T adoption commentary.
  11. Lumentum. Fiscal first quarter 2027 results, November 2026 optical networking business demand disclosure.
  12. Ciena. Vodafone Idea WaveLogic 6 Extreme, Indian 1.6Tbps optical transport test, March 2026.
  13. Ciena. Spark New Zealand DCI, Optical 10G to 800G data-center network links, September 2026.
  14. Nokia. Telxius 800G pluggable deployment, International coherent fiber network upgrade, September 2026.
  15. Ciena. ECOC 2026 optical showcase, 1600ZR and 800G coherent optical products.
  16. Ciena. ECHO subsea cable upgrade, 400GbE/800GbE transpacific transport capacity announcement, September 2026.
Transceivers for Optical Communication Market Size, Share & Industry Analysis, 2026–2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Transceivers for Optical Communication Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Transceivers for Optical Communication Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Transceivers for Optical Communication Overall Market Size
2.1 Global Transceivers for Optical Communication Market Size: 2024 VS 2032
2.2 Global Transceivers for Optical Communication Market Size, Prospects & Forecasts: 2026-2034
2.3 Global Transceivers for Optical Communication Sales: 2026-2034
3 Company Landscape
3.1 Top Transceivers for Optical Communication Players in Global Market
3.2 Top Global Transceivers for Optical Communication Companies Ranked by Revenue
3.3 Global Transceivers for Optical Communication Revenue by Companies
3.4 Global Transceivers for Optical Communication Sales by Companies
3.5 Global Transceivers for Optical Communication Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 Transceivers for Optical Communication Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers Transceivers for Optical Communication Product Type
3.8 Tier 1, Tier 2, and Tier 3 Transceivers for Optical Communication Players in Global Market
3.8.1 List of Global Tier 1 Transceivers for Optical Communication Companies
3.8.2 List of Global Tier 2 and Tier 3 Transceivers for Optical Communication Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global Transceivers for Optical Communication Market Size Markets, 2024 & 2032
4.1.2 10 G
4.1.3 40 G
4.1.4 100 G
4.1.5 200 G
4.1.6 400 G
4.1.7 Others
4.2 Segment by Type – Global Transceivers for Optical Communication Revenue & Forecasts
4.2.1 Segment by Type – Global Transceivers for Optical Communication Revenue, 2020-2025
4.2.2 Segment by Type – Global Transceivers for Optical Communication Revenue, 2026-2032
4.2.3 Segment by Type – Global Transceivers for Optical Communication Revenue Market Share, 2026-2034
4.3 Segment by Type – Global Transceivers for Optical Communication Sales & Forecasts
4.3.1 Segment by Type – Global Transceivers for Optical Communication Sales, 2020-2025
4.3.2 Segment by Type – Global Transceivers for Optical Communication Sales, 2026-2032
4.3.3 Segment by Type – Global Transceivers for Optical Communication Sales Market Share, 2026-2034
4.4 Segment by Type – Global Transceivers for Optical Communication Price (Manufacturers Selling Prices), 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global Transceivers for Optical Communication Market Size, 2024 & 2032
5.1.2 Telecommunication
5.1.3 Date Center (Datacom)
5.1.4 Other
5.2 Segment by Application – Global Transceivers for Optical Communication Revenue & Forecasts
5.2.1 Segment by Application – Global Transceivers for Optical Communication Revenue, 2020-2025
5.2.2 Segment by Application – Global Transceivers for Optical Communication Revenue, 2026-2032
5.2.3 Segment by Application – Global Transceivers for Optical Communication Revenue Market Share, 2026-2034
5.3 Segment by Application – Global Transceivers for Optical Communication Sales & Forecasts
5.3.1 Segment by Application – Global Transceivers for Optical Communication Sales, 2020-2025
5.3.2 Segment by Application – Global Transceivers for Optical Communication Sales, 2026-2032
5.3.3 Segment by Application – Global Transceivers for Optical Communication Sales Market Share, 2026-2034
5.4 Segment by Application – Global Transceivers for Optical Communication Price (Manufacturers Selling Prices), 2026-2034
6 Sights by Region
6.1 By Region – Global Transceivers for Optical Communication Market Size, 2024 & 2032
6.2 By Region – Global Transceivers for Optical Communication Revenue & Forecasts
6.2.1 By Region – Global Transceivers for Optical Communication Revenue, 2020-2025
6.2.2 By Region – Global Transceivers for Optical Communication Revenue, 2026-2032
6.2.3 By Region – Global Transceivers for Optical Communication Revenue Market Share, 2026-2034
6.3 By Region – Global Transceivers for Optical Communication Sales & Forecasts
6.3.1 By Region – Global Transceivers for Optical Communication Sales, 2020-2025
6.3.2 By Region – Global Transceivers for Optical Communication Sales, 2026-2032
6.3.3 By Region – Global Transceivers for Optical Communication Sales Market Share, 2026-2034
6.4 North America
6.4.1 By Country – North America Transceivers for Optical Communication Revenue, 2026-2034
6.4.2 By Country – North America Transceivers for Optical Communication Sales, 2026-2034
6.4.3 United States Transceivers for Optical Communication Market Size, 2026-2034
6.4.4 Canada Transceivers for Optical Communication Market Size, 2026-2034
6.4.5 Mexico Transceivers for Optical Communication Market Size, 2026-2034
6.5 Europe
6.5.1 By Country – Europe Transceivers for Optical Communication Revenue, 2026-2034
6.5.2 By Country – Europe Transceivers for Optical Communication Sales, 2026-2034
6.5.3 Germany Transceivers for Optical Communication Market Size, 2026-2034
6.5.4 France Transceivers for Optical Communication Market Size, 2026-2034
6.5.5 U.K. Transceivers for Optical Communication Market Size, 2026-2034
6.5.6 Italy Transceivers for Optical Communication Market Size, 2026-2034
6.5.7 Russia Transceivers for Optical Communication Market Size, 2026-2034
6.5.8 Nordic Countries Transceivers for Optical Communication Market Size, 2026-2034
6.5.9 Benelux Transceivers for Optical Communication Market Size, 2026-2034
6.6 Asia
6.6.1 By Region – Asia Transceivers for Optical Communication Revenue, 2026-2034
6.6.2 By Region – Asia Transceivers for Optical Communication Sales, 2026-2034
6.6.3 China Transceivers for Optical Communication Market Size, 2026-2034
6.6.4 Japan Transceivers for Optical Communication Market Size, 2026-2034
6.6.5 South Korea Transceivers for Optical Communication Market Size, 2026-2034
6.6.6 Southeast Asia Transceivers for Optical Communication Market Size, 2026-2034
6.6.7 India Transceivers for Optical Communication Market Size, 2026-2034
6.7 South America
6.7.1 By Country – South America Transceivers for Optical Communication Revenue, 2026-2034
6.7.2 By Country – South America Transceivers for Optical Communication Sales, 2026-2034
6.7.3 Brazil Transceivers for Optical Communication Market Size, 2026-2034
6.7.4 Argentina Transceivers for Optical Communication Market Size, 2026-2034
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa Transceivers for Optical Communication Revenue, 2026-2034
6.8.2 By Country – Middle East & Africa Transceivers for Optical Communication Sales, 2026-2034
6.8.3 Turkey Transceivers for Optical Communication Market Size, 2026-2034
6.8.4 Israel Transceivers for Optical Communication Market Size, 2026-2034
6.8.5 Saudi Arabia Transceivers for Optical Communication Market Size, 2026-2034
6.8.6 UAE Transceivers for Optical Communication Market Size, 2026-2034
7 Manufacturers & Brands Profiles
7.1 II-VI Incorporated
7.1.1 II-VI Incorporated Company Summary
7.1.2 II-VI Incorporated Business Overview
7.1.3 II-VI Incorporated Transceivers for Optical Communication Major Product Offerings
7.1.4 II-VI Incorporated Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.1.5 II-VI Incorporated Key News & Latest Developments
7.2 Broadcom(Avago)
7.2.1 Broadcom(Avago) Company Summary
7.2.2 Broadcom(Avago) Business Overview
7.2.3 Broadcom(Avago) Transceivers for Optical Communication Major Product Offerings
7.2.4 Broadcom(Avago) Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.2.5 Broadcom(Avago) Key News & Latest Developments
7.3 Lumentum (Oclaro)
7.3.1 Lumentum (Oclaro) Company Summary
7.3.2 Lumentum (Oclaro) Business Overview
7.3.3 Lumentum (Oclaro) Transceivers for Optical Communication Major Product Offerings
7.3.4 Lumentum (Oclaro) Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.3.5 Lumentum (Oclaro) Key News & Latest Developments
7.4 Sumitomo
7.4.1 Sumitomo Company Summary
7.4.2 Sumitomo Business Overview
7.4.3 Sumitomo Transceivers for Optical Communication Major Product Offerings
7.4.4 Sumitomo Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.4.5 Sumitomo Key News & Latest Developments
7.5 Accelink
7.5.1 Accelink Company Summary
7.5.2 Accelink Business Overview
7.5.3 Accelink Transceivers for Optical Communication Major Product Offerings
7.5.4 Accelink Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.5.5 Accelink Key News & Latest Developments
7.6 Fujitsu
7.6.1 Fujitsu Company Summary
7.6.2 Fujitsu Business Overview
7.6.3 Fujitsu Transceivers for Optical Communication Major Product Offerings
7.6.4 Fujitsu Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.6.5 Fujitsu Key News & Latest Developments
7.7 Cisco
7.7.1 Cisco Company Summary
7.7.2 Cisco Business Overview
7.7.3 Cisco Transceivers for Optical Communication Major Product Offerings
7.7.4 Cisco Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.7.5 Cisco Key News & Latest Developments
7.8 Alcatel-Lucent
7.8.1 Alcatel-Lucent Company Summary
7.8.2 Alcatel-Lucent Business Overview
7.8.3 Alcatel-Lucent Transceivers for Optical Communication Major Product Offerings
7.8.4 Alcatel-Lucent Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.8.5 Alcatel-Lucent Key News & Latest Developments
7.9 NeoPhotonics
7.9.1 NeoPhotonics Company Summary
7.9.2 NeoPhotonics Business Overview
7.9.3 NeoPhotonics Transceivers for Optical Communication Major Product Offerings
7.9.4 NeoPhotonics Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.9.5 NeoPhotonics Key News & Latest Developments
7.10 Source Photonics
7.10.1 Source Photonics Company Summary
7.10.2 Source Photonics Business Overview
7.10.3 Source Photonics Transceivers for Optical Communication Major Product Offerings
7.10.4 Source Photonics Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.10.5 Source Photonics Key News & Latest Developments
7.11 Ciena
7.11.1 Ciena Company Summary
7.11.2 Ciena Business Overview
7.11.3 Ciena Transceivers for Optical Communication Major Product Offerings
7.11.4 Ciena Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.11.5 Ciena Key News & Latest Developments
7.12 Molex(Oplink)
7.12.1 Molex(Oplink) Company Summary
7.12.2 Molex(Oplink) Business Overview
7.12.3 Molex(Oplink) Transceivers for Optical Communication Major Product Offerings
7.12.4 Molex(Oplink) Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.12.5 Molex(Oplink) Key News & Latest Developments
7.13 Huawei
7.13.1 Huawei Company Summary
7.13.2 Huawei Business Overview
7.13.3 Huawei Transceivers for Optical Communication Major Product Offerings
7.13.4 Huawei Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.13.5 Huawei Key News & Latest Developments
7.14 Infinera(Coriant)
7.14.1 Infinera(Coriant) Company Summary
7.14.2 Infinera(Coriant) Business Overview
7.14.3 Infinera(Coriant) Transceivers for Optical Communication Major Product Offerings
7.14.4 Infinera(Coriant) Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.14.5 Infinera(Coriant) Key News & Latest Developments
7.15 ACON
7.15.1 ACON Company Summary
7.15.2 ACON Business Overview
7.15.3 ACON Transceivers for Optical Communication Major Product Offerings
7.15.4 ACON Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.15.5 ACON Key News & Latest Developments
7.16 ATOP
7.16.1 ATOP Company Summary
7.16.2 ATOP Business Overview
7.16.3 ATOP Transceivers for Optical Communication Major Product Offerings
7.16.4 ATOP Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.16.5 ATOP Key News & Latest Developments
7.17 ColorChip
7.17.1 ColorChip Company Summary
7.17.2 ColorChip Business Overview
7.17.3 ColorChip Transceivers for Optical Communication Major Product Offerings
7.17.4 ColorChip Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.17.5 ColorChip Key News & Latest Developments
7.18 OE SOLUTION
7.18.1 OE SOLUTION Company Summary
7.18.2 OE SOLUTION Business Overview
7.18.3 OE SOLUTION Transceivers for Optical Communication Major Product Offerings
7.18.4 OE SOLUTION Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.18.5 OE SOLUTION Key News & Latest Developments
7.19 OPTICORE
7.19.1 OPTICORE Company Summary
7.19.2 OPTICORE Business Overview
7.19.3 OPTICORE Transceivers for Optical Communication Major Product Offerings
7.19.4 OPTICORE Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.19.5 OPTICORE Key News & Latest Developments
7.20 INTEC E&C
7.20.1 INTEC E&C Company Summary
7.20.2 INTEC E&C Business Overview
7.20.3 INTEC E&C Transceivers for Optical Communication Major Product Offerings
7.20.4 INTEC E&C Transceivers for Optical Communication Sales and Revenue in Global (2020-2025)
7.20.5 INTEC E&C Key News & Latest Developments
8 Global Transceivers for Optical Communication Production Capacity, Analysis
8.1 Global Transceivers for Optical Communication Production Capacity, 2026-2034
8.2 Transceivers for Optical Communication Production Capacity of Key Manufacturers in Global Market
8.3 Global Transceivers for Optical Communication Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 Transceivers for Optical Communication Supply Chain Analysis
10.1 Transceivers for Optical Communication Industry Value Chain
10.2 Transceivers for Optical Communication Upstream Market
10.3 Transceivers for Optical Communication Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 Transceivers for Optical Communication Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of Transceivers for Optical Communication in Global Market
Table 2. Top Transceivers for Optical Communication Players in Global Market, Ranking by Revenue (2024)
Table 3. Global Transceivers for Optical Communication Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global Transceivers for Optical Communication Revenue Share by Companies, 2020-2025
Table 5. Global Transceivers for Optical Communication Sales by Companies, (K Units), 2020-2025
Table 6. Global Transceivers for Optical Communication Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers Transceivers for Optical Communication Price (2020-2025) & (US$/Unit)
Table 8. Global Manufacturers Transceivers for Optical Communication Product Type
Table 9. List of Global Tier 1 Transceivers for Optical Communication Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Transceivers for Optical Communication Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global Transceivers for Optical Communication Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global Transceivers for Optical Communication Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global Transceivers for Optical Communication Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global Transceivers for Optical Communication Sales (K Units), 2020-2025
Table 15. Segment by Type – Global Transceivers for Optical Communication Sales (K Units), 2026-2032
Table 16. Segment by Application – Global Transceivers for Optical Communication Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global Transceivers for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global Transceivers for Optical Communication Sales, (K Units), 2020-2025
Table 20. Segment by Application – Global Transceivers for Optical Communication Sales, (K Units), 2026-2032
Table 21. By Region – Global Transceivers for Optical Communication Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global Transceivers for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global Transceivers for Optical Communication Sales, (K Units), 2020-2025
Table 25. By Region – Global Transceivers for Optical Communication Sales, (K Units), 2026-2032
Table 26. By Country – North America Transceivers for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America Transceivers for Optical Communication Sales, (K Units), 2020-2025
Table 29. By Country – North America Transceivers for Optical Communication Sales, (K Units), 2026-2032
Table 30. By Country – Europe Transceivers for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe Transceivers for Optical Communication Sales, (K Units), 2020-2025
Table 33. By Country – Europe Transceivers for Optical Communication Sales, (K Units), 2026-2032
Table 34. By Region – Asia Transceivers for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia Transceivers for Optical Communication Sales, (K Units), 2020-2025
Table 37. By Region – Asia Transceivers for Optical Communication Sales, (K Units), 2026-2032
Table 38. By Country – South America Transceivers for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America Transceivers for Optical Communication Sales, (K Units), 2020-2025
Table 41. By Country – South America Transceivers for Optical Communication Sales, (K Units), 2026-2032
Table 42. By Country – Middle East & Africa Transceivers for Optical Communication Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa Transceivers for Optical Communication Sales, (K Units), 2020-2025
Table 45. By Country – Middle East & Africa Transceivers for Optical Communication Sales, (K Units), 2026-2032
Table 46. II-VI Incorporated Company Summary
Table 47. II-VI Incorporated Transceivers for Optical Communication Product Offerings
Table 48. II-VI Incorporated Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 49. II-VI Incorporated Key News & Latest Developments
Table 50. Broadcom(Avago) Company Summary
Table 51. Broadcom(Avago) Transceivers for Optical Communication Product Offerings
Table 52. Broadcom(Avago) Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 53. Broadcom(Avago) Key News & Latest Developments
Table 54. Lumentum (Oclaro) Company Summary
Table 55. Lumentum (Oclaro) Transceivers for Optical Communication Product Offerings
Table 56. Lumentum (Oclaro) Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 57. Lumentum (Oclaro) Key News & Latest Developments
Table 58. Sumitomo Company Summary
Table 59. Sumitomo Transceivers for Optical Communication Product Offerings
Table 60. Sumitomo Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 61. Sumitomo Key News & Latest Developments
Table 62. Accelink Company Summary
Table 63. Accelink Transceivers for Optical Communication Product Offerings
Table 64. Accelink Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 65. Accelink Key News & Latest Developments
Table 66. Fujitsu Company Summary
Table 67. Fujitsu Transceivers for Optical Communication Product Offerings
Table 68. Fujitsu Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 69. Fujitsu Key News & Latest Developments
Table 70. Cisco Company Summary
Table 71. Cisco Transceivers for Optical Communication Product Offerings
Table 72. Cisco Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 73. Cisco Key News & Latest Developments
Table 74. Alcatel-Lucent Company Summary
Table 75. Alcatel-Lucent Transceivers for Optical Communication Product Offerings
Table 76. Alcatel-Lucent Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 77. Alcatel-Lucent Key News & Latest Developments
Table 78. NeoPhotonics Company Summary
Table 79. NeoPhotonics Transceivers for Optical Communication Product Offerings
Table 80. NeoPhotonics Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 81. NeoPhotonics Key News & Latest Developments
Table 82. Source Photonics Company Summary
Table 83. Source Photonics Transceivers for Optical Communication Product Offerings
Table 84. Source Photonics Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 85. Source Photonics Key News & Latest Developments
Table 86. Ciena Company Summary
Table 87. Ciena Transceivers for Optical Communication Product Offerings
Table 88. Ciena Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 89. Ciena Key News & Latest Developments
Table 90. Molex(Oplink) Company Summary
Table 91. Molex(Oplink) Transceivers for Optical Communication Product Offerings
Table 92. Molex(Oplink) Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 93. Molex(Oplink) Key News & Latest Developments
Table 94. Huawei Company Summary
Table 95. Huawei Transceivers for Optical Communication Product Offerings
Table 96. Huawei Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 97. Huawei Key News & Latest Developments
Table 98. Infinera(Coriant) Company Summary
Table 99. Infinera(Coriant) Transceivers for Optical Communication Product Offerings
Table 100. Infinera(Coriant) Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 101. Infinera(Coriant) Key News & Latest Developments
Table 102. ACON Company Summary
Table 103. ACON Transceivers for Optical Communication Product Offerings
Table 104. ACON Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 105. ACON Key News & Latest Developments
Table 106. ATOP Company Summary
Table 107. ATOP Transceivers for Optical Communication Product Offerings
Table 108. ATOP Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 109. ATOP Key News & Latest Developments
Table 110. ColorChip Company Summary
Table 111. ColorChip Transceivers for Optical Communication Product Offerings
Table 112. ColorChip Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 113. ColorChip Key News & Latest Developments
Table 114. OE SOLUTION Company Summary
Table 115. OE SOLUTION Transceivers for Optical Communication Product Offerings
Table 116. OE SOLUTION Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 117. OE SOLUTION Key News & Latest Developments
Table 118. OPTICORE Company Summary
Table 119. OPTICORE Transceivers for Optical Communication Product Offerings
Table 120. OPTICORE Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 121. OPTICORE Key News & Latest Developments
Table 122. INTEC E&C Company Summary
Table 123. INTEC E&C Transceivers for Optical Communication Product Offerings
Table 124. INTEC E&C Transceivers for Optical Communication Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 125. INTEC E&C Key News & Latest Developments
Table 126. Transceivers for Optical Communication Capacity of Key Manufacturers in Global Market, 2023-2025 (K Units)
Table 127. Global Transceivers for Optical Communication Capacity Market Share of Key Manufacturers, 2023-2025
Table 128. Global Transceivers for Optical Communication Production by Region, 2020-2025 (K Units)
Table 129. Global Transceivers for Optical Communication Production by Region, 2026-2032 (K Units)
Table 130. Transceivers for Optical Communication Market Opportunities & Trends in Global Market
Table 131. Transceivers for Optical Communication Market Drivers in Global Market
Table 132. Transceivers for Optical Communication Market Restraints in Global Market
Table 133. Transceivers for Optical Communication Raw Materials
Table 134. Transceivers for Optical Communication Raw Materials Suppliers in Global Market
Table 135. Typical Transceivers for Optical Communication Downstream
Table 136. Transceivers for Optical Communication Downstream Clients in Global Market
Table 137. Transceivers for Optical Communication Distributors and Sales Agents in Global Market

List of Figures
Figure 1. Transceivers for Optical Communication Product Picture
Figure 2. Transceivers for Optical Communication Segment by Type in 2024
Figure 3. Transceivers for Optical Communication Segment by Application in 2024
Figure 4. Global Transceivers for Optical Communication Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Transceivers for Optical Communication Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Transceivers for Optical Communication Revenue: 2026-2034 (US$, Mn)
Figure 8. Transceivers for Optical Communication Sales in Global Market: 2026-2034 (K Units)
Figure 9. The Top 3 and 5 Players Market Share by Transceivers for Optical Communication Revenue in 2024
Figure 10. Segment by Type – Global Transceivers for Optical Communication Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global Transceivers for Optical Communication Revenue Market Share, 2026-2034
Figure 12. Segment by Type – Global Transceivers for Optical Communication Sales Market Share, 2026-2034
Figure 13. Segment by Type – Global Transceivers for Optical Communication Price (US$/Unit), 2026-2034
Figure 14. Segment by Application – Global Transceivers for Optical Communication Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global Transceivers for Optical Communication Revenue Market Share, 2026-2034
Figure 16. Segment by Application – Global Transceivers for Optical Communication Sales Market Share, 2026-2034
Figure 17. Segment by Application -Global Transceivers for Optical Communication Price (US$/Unit), 2026-2034
Figure 18. By Region – Global Transceivers for Optical Communication Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global Transceivers for Optical Communication Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global Transceivers for Optical Communication Revenue Market Share, 2026-2034
Figure 21. By Region – Global Transceivers for Optical Communication Sales Market Share, 2026-2034
Figure 22. By Country – North America Transceivers for Optical Communication Revenue Market Share, 2026-2034
Figure 23. By Country – North America Transceivers for Optical Communication Sales Market Share, 2026-2034
Figure 24. United States Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 25. Canada Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 26. Mexico Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 27. By Country – Europe Transceivers for Optical Communication Revenue Market Share, 2026-2034
Figure 28. By Country – Europe Transceivers for Optical Communication Sales Market Share, 2026-2034
Figure 29. Germany Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 30. France Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 31. U.K. Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 32. Italy Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 33. Russia Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 34. Nordic Countries Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 35. Benelux Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 36. By Region – Asia Transceivers for Optical Communication Revenue Market Share, 2026-2034
Figure 37. By Region – Asia Transceivers for Optical Communication Sales Market Share, 2026-2034
Figure 38. China Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 39. Japan Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 40. South Korea Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 41. Southeast Asia Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 42. India Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 43. By Country – South America Transceivers for Optical Communication Revenue Market Share, 2026-2034
Figure 44. By Country – South America Transceivers for Optical Communication Sales, Market Share, 2026-2034
Figure 45. Brazil Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 46. Argentina Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 47. By Country – Middle East & Africa Transceivers for Optical Communication Revenue, Market Share, 2026-2034
Figure 48. By Country – Middle East & Africa Transceivers for Optical Communication Sales, Market Share, 2026-2034
Figure 49. Turkey Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 50. Israel Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 51. Saudi Arabia Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 52. UAE Transceivers for Optical Communication Revenue, (US$, Mn), 2026-2034
Figure 53. Global Transceivers for Optical Communication Production Capacity (K Units), 2026-2034
Figure 54. The Percentage of Production Transceivers for Optical Communication by Region, 2024 VS 2032
Figure 55. Transceivers for Optical Communication Industry Value Chain
Figure 56. Marketing Channels