Single Mode Optical Modules Market Trends, Technological Advancements and Business Strategies 2026–2034

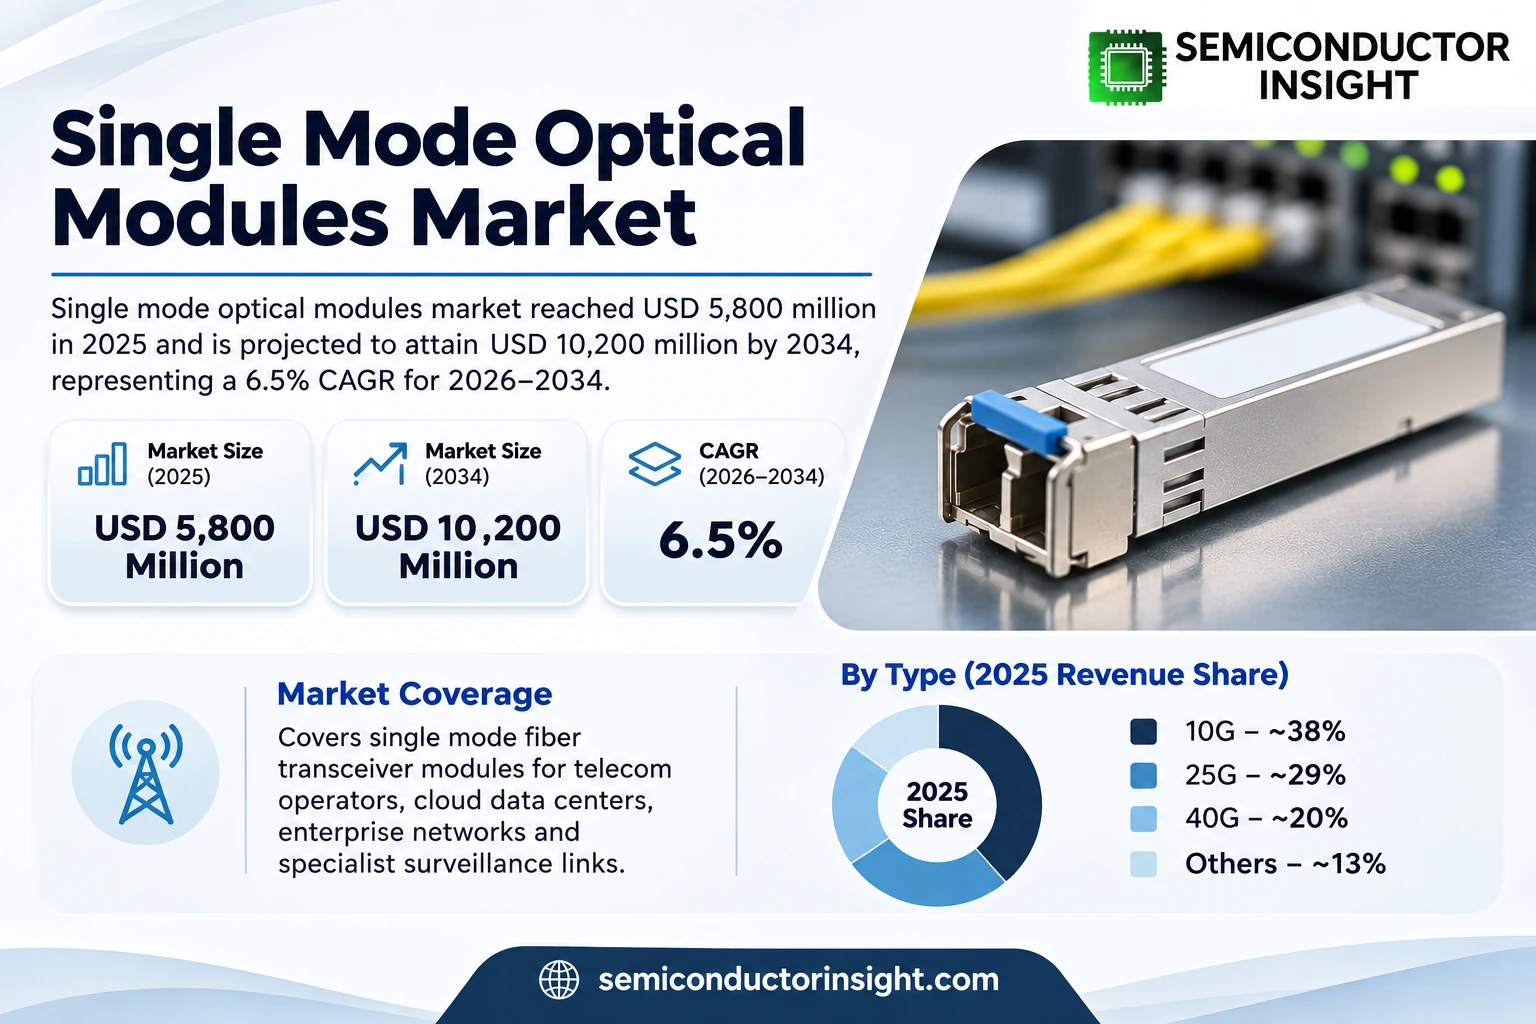
Single mode optical modules market reached USD 5,800 million in 2025 and is projected to attain USD 10,200 million by 2034, representing a 6.5% CAGR for the 2026–2034 period. This market covers single mode fiber transceiver modules serving telecom operators, cloud data centers, enterprise networks and specialist surveillance links. The latest supplier developments reinforce the role of higher-capacity optical links in both short-reach and metropolitan networks.

PDF Icon Download Sample Report PDF
  • Quick Dispatch

    All Orders

  • Secure Payment

    100% Secure Payment

Price range: $1,500.00 through $4,250.00

Clear

Key Statistics

2025 Market Size
USD 5,800 million
2034 Projected Size
USD 10,200 million
CAGR (2026–2034)
6.5%
Largest Market in 2025
Asia-Pacific (~40%)

Key Takeaways

  • Market trajectory The global single mode optical modules market is valued at USD 5,800 million in 2025, reaches an estimated USD 6,175 million in 2026 and is forecast at USD 10,200 million in 2034. The corresponding 6.5% CAGR reflects demand from both established carrier fiber networks and new high-capacity interconnects in cloud facilities.
  • Regional demand Asia-Pacific represents an estimated ~40% of the market in 2025, supported by module assembly and large fiber network deployments. North America accounts for approximately ~29%, driven by data center and telecommunications procurement, while Europe contributes around ~21% through metropolitan fiber and enterprise backbone refresh cycles.
  • Product mix Established 10G single mode products represent an estimated ~38% of revenue because carrier and enterprise equipment remains widely deployed. The 25G category contributes about ~29%, while 40G contributes ~20%; higher-speed products grouped in other categories are increasing as network operators pursue more capacity per fiber pair.
  • Data center upgrades Data centers represent an estimated ~32% of application revenue and are growing more quickly than mature operator networks. Suppliers are demonstrating 800G and 1.6T single mode modules, with 500-meter reach configurations for dense computing clusters and coherent modules for longer interconnection distances.
  • Commercial constraints Optical component supply, thermal management and link-budget verification influence adoption. Module buyers must qualify the optical reach, electrical interface, management firmware and power draw together; a higher nominal transmission rate alone cannot ensure compatibility with installed switches, routers or fiber routes.

Single Mode Optical Modules Market Overview

Single mode optical modules market reached USD 5,800 million in 2025 and is projected to attain USD 10,200 million by 2034, representing a 6.5% CAGR for the 2026–2034 period. This market covers single mode fiber transceiver modules serving telecom operators, cloud data centers, enterprise networks and specialist surveillance links. The latest supplier developments reinforce the role of higher-capacity optical links in both short-reach and metropolitan networks.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million · Estimated shares are indicative

Single mode optical modules convert electrical signals into optical signals for transmission over fiber with a narrow propagation mode. They serve links where attenuation, chromatic dispersion and available fiber capacity matter. Pluggable transceivers make it possible for network equipment to change reach or wavelength capability without replacing the entire switch or router, although the electrical host interface and thermal limits still determine which modules are supported.

The market includes established 10G, 25G and 40G products alongside emerging higher-rate optical modules used in data center interconnects. A module designed for 500 meters inside a computing campus is not interchangeable with a coherent wavelength-tunable device designed for a regional fiber route. These configurations have distinct optical architectures, costs, power envelopes and testing requirements, so purchasing decisions depend on network topology rather than bandwidth alone.

Network expansion is increasingly linked to cloud infrastructure, artificial intelligence workloads and migration to faster switch ports. Coherent announced general availability of an 800G ZR/ZR+ QSFP-DD transceiver in March 2025, demonstrating that compact coherent optics can serve metro and regional connections. Lumentum also documents an 800G OSFP single mode product operating across 500 meters with a typical power consumption below 15.2 watts.

A key difference between market growth and unit shipment growth is the value attached to advanced modules. Higher-speed transceivers can require more sophisticated lasers, drivers, receivers, photonic integration and qualification than mature lower-rate parts. As buyers move from established 10G and 25G links to 800G and 1.6T systems, suppliers compete on power per bit, interoperability, reach, reliability and delivery capability as well as headline port speed.

Segment Analysis: By Type

By type, single mode optical modules are segmented into 10G, 25G, 40G and Others. Mature 10G products remain the largest individual category with an estimated ~38% of 2025 revenue, followed by 25G at about ~29%, 40G at ~20% and higher-rate or specialist products grouped as Others at ~13%. Growth differs across the categories as established carrier access networks and new high-capacity optical fabrics have distinct refresh schedules.

Type Function Market position
10G Single mode SFP+ links serve established enterprise and carrier aggregation networks, often using duplex LC interfaces and wavelength selections appropriate to the installed fiber route. Replacement demand remains durable where switching hardware is not being upgraded to a faster interface. The 10G replacement market rewards proven SFP+ compatibility, consistent optical power and access to long-lived spare parts. Estimated ~38% revenue share in 2025, with ~4.4% CAGR. This remains the largest installed-speed segment because deployed networks contain many long-lived 10G access and aggregation ports. Price competition is pronounced, but certified optics and dependable supply remain important in maintenance procurement.
25G Single mode SFP28 products increase capacity without requiring a complete redesign of access equipment. Operators choose these links for mobile transport, enterprise uplinks and intermediate steps in bandwidth upgrades where 100G or 400G aggregation is not economically justified. A 25G deployment must align SFP28 electrical timing, link budget and operator-specific access network certification requirements. Estimated ~29% of revenue in 2025 and ~6.6% CAGR. Demand benefits from higher port density and network upgrades, although customer qualification and host-platform compatibility remain important because electrical interfaces and optics management vary by equipment family.
40G QSFP and related optical formats are used in established aggregation and data center connections. Some operators retain 40G hardware for installed workloads while others migrate to 100G or higher capacity as equipment reaches the end of its support cycle. The 40G segment depends on installed QSFP switch ports, cable topology and the economics of migrating to faster aggregation equipment. Estimated ~20% share in 2025 and ~7.7% CAGR for the represented category. Procurement is mixed between replacement of installed modules and demand from applications where the optical reach and port economics still favor this speed over higher-rate alternatives.
Others Higher-rate 100G, 400G, 800G and 1.6T optical module families are grouped here because the source market page presents its core legacy speed categories separately. Products range from short-reach parallel single mode links to coherent transceivers for metro interconnection. Newer high-rate modules must satisfy stringent thermal design limits, advanced signal integrity requirements and interoperability testing. Estimated ~13% share in 2025 and approximately ~8.5% CAGR. Although smaller in the base year, this grouping captures more advanced optical designs and is supported by AI cluster interconnects, hyperscale networking and the move toward higher bandwidth per fiber.

Segment Analysis: By Application

By application, the market comprises Telecommunication Operator Networks, Data Centers, Enterprise Networks, Security & Surveillance, and Others. Operator networks account for an estimated ~45% of 2025 value, while data centers represent ~32% and show faster expansion. Each application has different optical reach, redundancy, power and certification requirements, so modules are typically qualified against specific network equipment and deployment conditions.

Application Demand characteristics
Telecommunication Operator Networks Estimated ~45% share and ~5.8% CAGR. Operators use single mode optics for fiber access, mobile backhaul, metropolitan aggregation and long-distance links. Reliability, environmental operating range and support for existing router and transport platforms influence purchasing decisions, particularly where field service and downtime costs exceed the module price. Field replacement programs often require compatibility with existing transport cards and predictable spare availability.
Data Centers Estimated ~32% share and ~8.4% CAGR. Cloud and AI data centers increasingly require 400G, 800G and 1.6T single mode links to connect switch tiers and buildings. Buyers focus on energy per transmitted bit, reach and multi-vendor compatibility, with rapid technology qualification and high-volume delivery capacity shaping supplier selection. Cluster operators place particular emphasis on thermal headroom and the electrical host interface during rack qualification.
Enterprise Networks Estimated ~13% share and ~5.5% CAGR. Corporate campus and industrial operators deploy single mode modules across long building-to-building routes, aggregation rings and security-sensitive networks. Installed 10G and 25G switches remain relevant because equipment replacement budgets and maintenance cycles are often longer than those of hyperscale operators. Enterprise buyers often procure certified optics with multiyear support arrangements and predictable maintenance stock.
Security & Surveillance Estimated ~6% share and ~4.4% CAGR. Single mode links carry video and control traffic between distant monitoring sites, transport corridors and centralized command facilities. Network planners prioritize stable optical power, compatibility with rugged switches and manageable fiber distances rather than adopting the highest available bandwidth category. Surveillance installations favor stable optical budgets across outdoor cabinets and long fiber corridors.
Others Estimated ~4% share and ~7.5% CAGR. Specialist applications include research networks, utility communications and optical transport connections with unusual wavelength or reach requirements. Procurement is typically project-led, with environmental qualification, supply assurance and integration support influencing the choice of a module and vendor. Specialist networks often need custom wavelength selection and extensive acceptance testing before deployment.

Application mix changes the value of module features. A carrier-grade optic may need extended operating temperatures and long-term replacement availability, while an AI computing cluster prioritizes dense short-reach connectivity and low watts per bit. Lumentum and Coherent product disclosures illustrate the growing spread between compact 500-meter single mode modules and wavelength-tunable coherent transceivers that span hundreds of kilometers.
Regional Analysis

Asia-Pacific represents the largest estimated single mode optical modules market at ~40% of 2025 revenue, supported by manufacturing concentration and fiber network construction. North America follows at ~29%, with cloud data centers and AI infrastructure sustaining higher-speed demand, while Europe accounts for ~21% through telecom and enterprise fiber upgrades. South America contributes ~6% and the Middle East and Africa ~4%. Regional growth is expected to differ because local network investment, equipment qualification and availability of advanced optical components do not move together.

How does demand for single mode optical modules differ across regions?

Asia-Pacific combines large-scale optical component production with extensive telecom deployment and data center investment. North America has a high concentration of hyperscale customers purchasing faster links and demanding strict interoperability. European operators emphasize equipment life cycles and compatibility with existing fiber networks. Latin American carriers frequently expand metropolitan and national fiber backbones in stages. Middle Eastern and African deployments are shaped by new infrastructure, international connectivity and the economics of long-distance transport. These patterns affect the regional balance of 10G, 25G, 40G and newer coherent and parallel optical module products.

Region Position Growth outlook Demand profile What decides supplier selection
Asia-Pacific Largest (~40%) Fastest (~7.6% CAGR) Manufacturing, carriers, cloud networks Qualification and component supply
North America Second (~29%) Growing (~6.2% CAGR) Hyperscale AI and interconnect Power and interoperability
Europe Third (~21%) Steady (~5.5% CAGR) Operator upgrades and enterprise fiber Lifecycle and procurement
South America Fourth (~6%) Steady (~5.0% CAGR) Backbone and metro fiber Financing and import cost
Middle East & Africa Fifth (~4%) Emerging (~3.4% CAGR) New backbone and data center links Installation and support

Asia-Pacific LARGEST · ~40% SHARE

Why is Asia-Pacific the leading single mode optical modules region?

Asia-Pacific accounts for approximately ~40% of global 2025 demand, with estimated growth near ~7.6% CAGR. The region combines transceiver manufacturing, cloud infrastructure expansion and carrier optical transport investment. China provides scale in access and backbone deployments; Japan and South Korea demand advanced network reliability; and India and Southeast Asia contribute new fiber and data center builds. The product mix includes established 10G and 25G links alongside emerging 400G and 800G products.

Market positionLargest (~40%)
Growth outlookFastest (~7.6% CAGR)
Demand profileCloud and carrier investment
Market access gateProduction and supply
Country Position in region What drives demand
China Largest national base China represents the largest national demand center within Asia-Pacific because telecom operators deploy extensive fiber access and transport systems while domestic equipment makers assemble optical networking products. Established 10G and 25G modules remain important in installed infrastructure. Data center expansion creates demand for higher-rate optics, but actual product choices depend on reach, connector design and interoperability with existing switches.
Japan Reliability-led Japanese operators and enterprise customers place particular weight on network continuity, product qualification and long service lives. Single mode transceivers serve metropolitan fiber, campus interconnect and equipment rooms where links must remain compatible across refresh cycles. Higher-speed modules support modern computing environments, although purchasing decisions often require extensive testing of thermal behavior and vendor interoperability.
India & Southeast Asia Expansion markets Indian and Southeast Asian demand is supported by new fiber access routes, regional data centers and expanding enterprise networks. Equipment buyers balance affordable 10G and 25G connections with selected faster links at aggregation points. Project timing can depend on imported optical components, local installation capability and access to network power, creating uneven demand between large cities and secondary locations.

Market instances

  • 800G coherent products expand carrier options. Transport equipment purchasers in Asia-Pacific increasingly assess coherent connectivity when planning additional capacity on fiber routes already carrying significant traffic. The announcement establishes a concrete product reference for equipment selection rather than a regional shipment forecast or sales commitment. Asian equipment buyers can evaluate reach and interoperability as they modernize transport networks.
  • Optical link design differs across Asian deployments. Engineers in Asian cloud facilities must balance higher port density against the power available to optical transceivers and the length of installed fiber runs. The specification does not establish shipment volumes or a national market size. It does show how faster switch interfaces can raise requirements for optical power budgets, thermal design and installation quality.
  • Switch upgrades influence regional deployment schedules. Coherent demonstrated 1.6T DR8 and 800G DR4 optical transceiver modules in 2024, highlighting development beyond legacy 40G categories. These products address short-reach single mode fiber applications and are relevant to large data center projects across Asia-Pacific. Deployment still depends on host equipment availability and the commercial economics of upgrading a full network link across multiple switch generations.
In the full report: National revenue and shipment splits for China, Japan, South Korea, India and Southeast Asia, with module speed, fiber reach, data center demand and telecom network applications.

North America SECOND · ~29% SHARE

What drives North American demand for single mode optical modules?

North America contributes an estimated ~29% of global 2025 revenue and grows at approximately ~6.2% CAGR. Hyperscale computing, AI clusters and cloud interconnect projects increase interest in faster optical links. Carrier and enterprise networks retain substantial 10G and 25G installed bases, while advanced 800G and 1.6T products serve selected high-bandwidth requirements. Buyers emphasize module power, vendor qualification and stable supply rather than speed alone.

Market positionSecond (~29%)
Growth outlookGrowth (~6.2% CAGR)
Demand profileHyperscale infrastructure
Market access gateInteroperability testing
Country Position in region What drives demand
United States Largest national market The United States leads North American demand through cloud data centers, enterprise campuses and telecom network operators. Hyperscale customers are assessing higher-density optical interfaces while existing access and aggregation equipment continues to use slower single mode modules. Qualification programs test optical reach, power consumption, thermal performance and compatibility with switches before new products enter operational networks.
Canada Long-distance connectivity Canadian demand includes intercity fiber routes, regional data centers and enterprise connections across geographically dispersed sites. Single mode fiber is well suited to longer transmission paths, but the module selected depends on attenuation, distance and optical interface specifications. Carriers often preserve compatible legacy products alongside upgrades to higher-capacity backbone equipment and metropolitan interconnects.
Mexico Enterprise and carrier upgrades Mexican telecom operators and enterprise network integrators deploy single mode modules for metropolitan fiber and cross-building connections. Projects often emphasize procurement cost, service support and compatibility with existing equipment. Higher-capacity data center and cross-border connectivity requirements can encourage newer optical modules, but smaller installations may remain on established 10G and 25G technology.

Market instances

  • Coherent adds 800G metro transceiver availability. The 2025 announcement of 800G ZR and ZR+ QSFP-DD products provides a relevant benchmark for North American data center interconnect and metro transport upgrades. It does not imply every operator has deployed the new form factor. Buyers must still test coherent module performance, host compatibility and the total cost of the network connection.
  • Lumentum demonstrates faster optical platforms. Lumentum presented optical innovations at OFC 2025, including 800G and 1.6T connectivity and optical circuit switching concepts. The event illustrates the direction of cloud infrastructure development rather than an audited regional market share. Equipment customers compare the benefits of new modules against thermal constraints and the expense of upgrading switches.
  • Facility power planning shapes American optical purchasing. North American hyperscale procurement teams evaluate the physical port form factor, module cooling requirements and compatibility with their installed switches before selecting optical products. This specification helps data center engineers evaluate equipment density and cooling requirements. The power figure is a product characteristic, not a market growth statistic or evidence of annual sales or deliveries across individual customers.
In the full report: United States, Canada and Mexico demand by carrier, enterprise and cloud use, including transceiver speed, power class, reach and deployment environment.

Europe THIRD · ~21% SHARE

How does Europe purchase single mode optical modules?

Europe holds approximately ~21% of the 2025 market with estimated growth of ~5.5% CAGR. Demand comes from carrier modernization, national fiber networks, enterprise connections and data center expansion. Buyers often need interoperability with equipment already deployed across multiple generations. Energy consumption, component traceability and maintenance arrangements can be as important as peak optical speed when choosing among 10G, 25G, 40G and newer module families.

Market positionThird (~21%)
Growth outlookGrowth (~5.5% CAGR)
Demand profileCarrier modernization
Market access gateLong lifecycle
Country Position in region What drives demand
Germany Enterprise networks Germany has a broad base of industrial enterprises, telecom infrastructure and data center operators requiring reliable optical connections. Buyers deploy single mode modules for campus backbones and metropolitan transport where reach and maintenance continuity matter. Higher-speed interfaces are attractive in new data centers, but replacement programs must accommodate installed switches, optical distribution frames and fiber characteristics.
United Kingdom Cloud and connectivity The United Kingdom combines cloud infrastructure and carrier interconnection with enterprise demand for single mode fiber links. Data center customers assess higher-rate optical modules for dense interconnects, while telecom operators maintain a mix of legacy and newer equipment. Module certification, power draw and supply continuity are important procurement considerations for operators managing many sites.
France & Netherlands Interconnect hubs France and the Netherlands have important network exchange and data center locations where fiber interconnection capacity is commercially significant. Buyers specify optical modules based on distance, link budget and host equipment compatibility. The move toward faster optical links is uneven because an interconnection upgrade often requires coordinated changes to switching, cabling and monitoring systems.

Market instances

  • Coherent demonstrates 1.6T transceivers. Coherent showed advanced 1.6T DR8 and 800G DR4 modules in 2024. These specifications are relevant to European cloud operators assessing future network density. A demonstration is not equivalent to a shipment commitment or a regional adoption rate, and installation depends on switch interfaces, power availability, service arrangements and fiber plant suitability.
  • European wavelength planning governs transport upgrades. European carrier upgrades require careful planning of optical spectrum and the installed line system before higher-capacity coherent modules can be introduced. European operators may evaluate wavelength and reach flexibility when modernizing dense networks. Product availability does not establish how quickly individual carriers will approve, integrate or purchase the modules in practice.
  • New coherent modules address multiple distances. Lumentum announced transceiver products in 2025 designed to increase fiber capacity across a range of transmission distances, including C-band and L-band coherent connectivity. These developments matter to operators with varied network footprints. Commercial selection still depends on the optical line system, route engineering and compatibility testing across multiple installed equipment generations.
In the full report: Country and customer splits for Germany, United Kingdom, France, Netherlands and other European markets, including legacy compatibility, optical reach and power consumption.

South America FOURTH · ~6% SHARE

What determines optical module uptake in South America?

South America represents an estimated ~6% of 2025 revenue and grows at about ~5.0% CAGR. Carrier backbone construction and metropolitan fiber access upgrades provide a continuing market for single mode transceivers. Buyers frequently prioritize robust 10G and 25G products compatible with installed infrastructure, while higher-rate optical modules are introduced where traffic density and project budgets justify them. Currency movements and equipment import costs can influence purchasing schedules.

Market positionFourth (~6%)
Growth outlookGrowth (~5.0% CAGR)
Demand profileCarrier backbone
Market access gateImport economics
Country Position in region What drives demand
Brazil Largest national base Brazil leads regional optical networking demand through its extensive metropolitan areas, telecom operators and expanding cloud infrastructure. Single mode modules support carrier aggregation and longer fiber links across varied routes. Projects combine established module speeds with faster equipment in high-traffic locations, while procurement choices are influenced by local service support and the cost of imported components.
Argentina Metropolitan connectivity Argentine telecom and enterprise operators require single mode modules for metropolitan connections, interoffice fiber and national network upgrades. Budget and currency conditions can affect equipment replacement cycles, making compatibility with existing hardware valuable. Newer high-capacity optics are more likely to appear in heavily used backbone links than in smaller enterprise installations.
Chile & Colombia Network expansion Chile and Colombia support demand through urban fiber networks, data center connections and enterprise communications. The installed equipment base includes legacy optical interfaces that cannot all be replaced at once. Operators evaluate new single mode modules against route length, service reliability, financing and the availability of engineers who can test and maintain optical links.

Market instances

  • Coherent 800G product offers a capacity benchmark. The 2025 800G ZR and ZR+ QSFP-DD announcement provides a product reference for South American backbone operators planning high-capacity upgrades. It does not document regional sales, deployment volumes or carrier purchasing commitments. Operators would need to confirm coherent reach, wavelength planning and compatibility with their optical line systems before introducing the transceiver.
  • Short-reach 800G links suit dense facilities. New South American cloud facilities can use short-reach single mode fiber to connect switch tiers while keeping longer carrier routes on different optical technologies. Such a design is relevant to new data center installations where high port density and limited rack space are important. It does not replace the longer-reach coherent optics used on national backbone routes, so the two products serve different purchasing decisions.
  • South American network budgets shape equipment replacement. Cloud operators in South America must coordinate transceiver replacement with the availability of host switches, qualified technicians and sufficient network cooling. South American cloud and interconnection operators may consider such interfaces as switch platforms evolve. Adoption depends on equipment refresh cycles, energy budgets and the price of complete links and facility operating costs, rather than the existence of a product specification alone.
In the full report: National demand for Brazil, Argentina, Chile, Colombia and other markets by backbone, metro fiber, enterprise and data center application.

Middle East & Africa FIFTH · ~4% SHARE

How is single mode optical module demand developing in the Middle East and Africa?

The Middle East and Africa contribute an estimated ~4% of 2025 revenue, with estimated growth of about ~3.4% CAGR. Fiber backbone projects, telecom network densification and selected data center investments underpin demand. Longer-distance optical connections are important where networks span wide geographic areas. Operators typically balance reliability and replacement availability with advanced speed requirements, and projects can be constrained by financing, installation resources and network power.

Market positionFifth (~4%)
Growth outlookGrowth (~3.4% CAGR)
Demand profileFiber backbone links
Market access gateInstallation support
Country Position in region What drives demand
Saudi Arabia & UAE Data center investment Saudi Arabia and the United Arab Emirates are developing cloud and telecommunications infrastructure that requires fiber interconnection. Buyers assess single mode transceivers for both established network routes and high-capacity data center links. Equipment specifications must account for temperature, power and long-term support, while project timing depends on network construction and facility readiness.
South Africa Regional connectivity South Africa has established telecom and enterprise networks that use single mode modules for metropolitan fiber, long-distance transport and data center connectivity. Operators weigh replacement compatibility and service continuity alongside higher-rate upgrades. New optical interfaces can improve capacity at selected network nodes, but the existing installed base continues to generate demand for familiar module formats.
Kenya & Nigeria Emerging fiber demand Kenya and Nigeria are examples of markets where metro fiber and regional backbone investment support demand for single mode optical modules. Operators must plan for route length, equipment power and field maintenance. Cost-effective 10G and 25G links can remain practical for access and aggregation even when selected core routes require faster transport technology.

Market instances

  • Coherent 800G coherent module targets transport networks. Coherent announced availability of 800G ZR and ZR+ QSFP-DD products in 2025, a useful reference for operators planning more capacity on selected backbone and metro routes. This does not establish deployment in a particular African or Gulf network. Each operator must evaluate fiber reach, link budgets and the existing optical line system.
  • 800G transceiver reach affects site planning. New Gulf data centers must engineer optical port power, fiber routes and heat dissipation together because high-density network cabinets face demanding operating conditions. Such a module is designed for short data center connections rather than national fiber routes. Local infrastructure developers must match the optical design to the intended distance and ensure sufficient cooling, reliable maintenance and compatible switch ports.
  • African fiber engineering requires detailed loss analysis. Data center optical circuit switching introduces extra optical loss that must be included in the engineering budget for any proposed module and switching architecture. The product demonstrates how link budgets change with network architecture. Buyers in new data centers should verify optical loss and switching requirements rather than assume all single mode modules are interchangeable across architectures.
In the full report: National demand across Gulf states, South Africa, Kenya and Nigeria, including fiber transport, cloud infrastructure, access networks and installation constraints.

Key Single Mode Optical Modules Manufacturers and Competitive Landscape

Competition in single mode optical modules spans integrated photonics suppliers, transceiver assemblers and networking equipment companies. Coherent and Lumentum have public portfolios that demonstrate the move from established telecom optics toward 800G and 1.6T products. Customers select suppliers on reach, module form factor, electrical compatibility, power consumption and consistent manufacturing quality. Large-volume data center purchasing differs from carrier procurement, where long service cycles and network qualification are especially important.

Coherent offers optical transceiver technologies for telecommunications and data center interconnect. Its announced 800G ZR and ZR+ QSFP-DD products address coherent transmission, while DR4 and DR8 developments target parallel optical links. The different architectures require distinct host interfaces and fiber plant designs. The company competes on optical integration, engineering support and the ability to supply components across multiple module families.

Lumentum provides lasers and transceiver technologies for high-bandwidth optical networks. Its published 800G 2DR4 OSFP and 1.6T products illustrate the performance and thermal challenges associated with faster single mode links. Buyers compare electrical interfaces, reach and power specifications rather than assuming all modules at a given nominal data rate can replace one another. Product documentation supports technical comparison but not estimates of supplier revenue share.

Equipment makers and network integrators influence competitive outcomes because host switch qualification determines which optics customers can deploy. Approved module lists, monitoring support and warranty requirements can narrow the effective supplier choice. Telecom buyers may favor stable product lifecycles, whereas cloud customers can prioritize density and rapid platform refreshes. These purchasing differences help explain why module speed alone does not define competitive advantage.

Component availability remains central to price and delivery. Lasers, optical receivers, drivers, packaging and high-speed electronics must meet demanding optical and electrical tolerances. Manufacturers must control test yields and maintain repeatability across production batches. A lower quoted module price may be offset by installation labor, power use, replacement inventory or the risk of link downtime during a network migration.

Tier structure

Tier Companies Basis of competition
Integrated photonics and optical modules Coherent, Lumentum These companies develop high-speed optical technologies and publish module specifications covering coherent transport and short-reach single mode data center applications. They compete on integration, optical performance and product qualification across different transmission environments.
Networking equipment ecosystem Arista Networks and compatible optical module suppliers Switch platforms and their approved optical interfaces shape module procurement. Customers compare port speed, physical form factor, optical reach and support arrangements before introducing alternative transceivers into production networks.
Specialist assembly and supply chain Optical module assemblers and component vendors Specialist firms integrate laser sources, receiver devices, driver electronics and mechanical packages into qualified modules. Supply continuity, testing and warranty performance are essential for customers purchasing large quantities over several equipment generations.

Key companies profiled

  • Coherent
  • Lumentum
  • Arista Networks

Single Mode Optical Modules Production Capacity Analysis

Production of single mode optical modules depends on precision photonic components, high-speed electronic integration and final optical testing. Asia-Pacific has an important role in assembly and component manufacturing, while suppliers serving North American and European customers also invest in design, qualification and commercial support. The industry cannot be assessed through factory floor area alone because yield, equipment throughput and access to critical optical parts determine usable output.

A typical module combines laser and detector components, driver and receiver electronics, optical coupling, a mechanical enclosure and firmware. Each stage requires controlled alignment and testing. Faster optical links increase the importance of signal integrity, heat dissipation and consistent optical power. A manufacturer with sufficient assembly equipment may still face delivery constraints if high-performance laser devices or qualified electronic components are unavailable.

Product formats create distinct production requirements. A 10G SFP+ transceiver and an 800G OSFP module are not interchangeable manufacturing products, even when both use single mode fiber. Higher-rate modules require more complex electrical interfaces and optical packaging. The qualification process includes reach, temperature, bit error performance and interoperability testing, which can lengthen the transition from engineering samples to large customer orders.

The 500-meter 800G and 1.6T single mode products described by Lumentum illustrate how suppliers specify reach and thermal performance. Coherent coherent-optics products address different transport distances and wavelength planning needs. Capacity analysis therefore separates short-reach data center modules from coherent telecom products instead of combining all nominal optical speeds into one production category.

Single Mode Optical Modules Market Dynamics: Drivers, Restraints and Opportunities

Demand for single mode optical modules is supported by cloud infrastructure, telecom network modernization, increasing port speeds and fiber interconnection requirements. Faster optics create higher revenue opportunities but also impose thermal and qualification costs. The forecast incorporates expansion of installed fiber networks alongside the slower replacement cycle of existing carrier equipment. Restraints include component constraints, equipment compatibility and capital expenditure timing. These factors differ across customer types and network distances.

MARKET DRIVERS

Drivers Impact Analysis*

Market Drivers Impact Rank CAGR Contribution (%) 2026–2028 2029–2031 2032–2034
Cloud and AI data center optical links High +2.80% High High High
Telecom fiber backbone and metro upgrades High +2.00% High High Medium
Higher-speed switch port adoption Medium-High +1.50% Medium High High
Enterprise campus and interbuilding fiber Medium +1.00% High Medium Medium
Coherent transport module availability Medium +0.70% Medium High Medium
Others (network resilience and replacement) Low +0.50% Medium Medium Low

Cloud workloads require faster optical links

AI computing and cloud facilities place more traffic between switches and equipment rooms, increasing interest in 400G, 800G and 1.6T single mode optics. Lumentum publishes a 500-meter 800G OSFP module with specified for high-density operation, showing how data rate, reach and thermal requirements are evaluated together. Adoption depends on compatible host ports and the economics of upgrading complete connections.

Telecom operators modernize fiber transport

Operators require optical modules for metro aggregation, data center interconnect and longer transport routes. Coherent announced 800G ZR and ZR+ QSFP-DD products in 2025, adding a coherent option for higher-capacity links. Installed 10G and 25G infrastructure remains important because carriers replace equipment in stages rather than exchanging every link simultaneously. Network engineering and interoperability therefore shape the timing of revenue growth.

Switch interface speeds create product transitions

A higher-speed network port can change the optical module format, connector and fiber requirement. Coherent demonstrated 1.6T DR8 and 800G DR4 transceivers in 2024, while Lumentum has described 1.6T single mode products for 500-meter links. These developments expand engineering options but require careful qualification of thermal performance, optical loss and host equipment compatibility.

Enterprise and regional fiber expansion sustains legacy demand

Many enterprises and regional carriers rely on single mode fiber for interbuilding connections and aggregation routes. Established 10G and 25G modules offer familiar deployment and maintenance characteristics. Replacement demand persists as equipment ages, even when high-profile data centers adopt much faster interfaces. Buyers consider fiber reach, local service availability and product lifecycle before choosing a transceiver family.

MARKET RESTRAINTS

Restraints Impact Analysis*

Market Restraints Impact Rank CAGR Contribution (%) 2026–2028 2029–2031 2032–2034
Optical component availability and manufacturing yield Medium -0.80% High Medium Medium
Power, thermal and interface qualification Medium -0.50% Medium High High
Carrier and cloud capital expenditure timing Low-Medium -0.40% High Medium Medium
Others (import costs and price competition) Low -0.30% Medium Low Medium
*CAGR contribution shows the percentage points each factor adds to or removes from the forecast CAGR for 2026–2034; driver contributions less restraint contributions equal the market CAGR. Period columns rate the strength of each factor in that window.

Component supply limits delivery flexibility

Optical module production requires lasers, detectors, electronic drivers and precision packaging. Higher-rate products place additional demands on alignment and testing. A supplier may have assembly capacity yet lack qualified components for a particular module design. Customers consequently assess alternative suppliers, delivery lead times and qualification costs when planning large purchases.

Thermal and interoperability limits complicate upgrades

Moving from established 10G links to 800G or 1.6T changes electrical interfaces, optical reach requirements and heat dissipation. The 500-meter and power specifications in published Lumentum products illustrate why module selection cannot rely on headline data rate alone. Engineers must validate switch compatibility, fiber attenuation and cooling before equipment enters service.

Capital expenditure cycles influence order timing

Cloud and telecom customers approve major network investments according to traffic needs and financing conditions. A coherent transport upgrade can involve optical line systems and multiple network nodes, while a data center port refresh may require new switches and cabling. Delays in any of these investments can shift transceiver orders without changing the long-term need for fiber connectivity.

Pricing and procurement create margin pressure

Optical module buyers compare price, warranty and reliability among products that appear similar on paper. Established lower-speed formats face competition from multiple supply channels, while newer products incur development and testing expense. Manufacturers must balance competitive quotations with quality control and technical support because a low-cost module that causes link outages can be expensive to operate.

MARKET OPPORTUNITIES

Higher-density data center interconnect

Higher-density cloud connectivity creates opportunities for manufacturers able to qualify transceivers across different equipment generations and challenging deployment environments. Customers may gain higher capacity per port, but successful installations require compatible switches, power budgets and optical cabling. Suppliers that provide reliable qualification and lifecycle support can compete for these upgrades.

Coherent transport across metro networks

Coherent transport is increasingly considered for metro routes where existing fiber assets need to carry additional traffic without extensive civil construction. Such products create opportunities where network operators need additional capacity on existing fiber routes. Actual adoption depends on line-system compatibility, optical reach, wavelength planning and the cost of the complete transport solution.

Optical circuit switching applications

Specialized data center architectures create opportunities for modules that tolerate additional optical loss from switching components and complex fiber routing. These designs illustrate how new network architectures can create specialized requirements for single mode optics. Vendors able to meet link budgets and switching compatibility may serve applications beyond conventional fixed optical connections.

Single Mode Optical Modules Supply Chain Analysis

The single mode optical module supply chain begins with lasers, detectors, photonic chips, electronic drivers and packaging materials. Module manufacturers integrate these parts into tested assemblies before networking equipment makers and operators qualify them for particular interfaces. Finished products reach telecom carriers, cloud infrastructure operators, enterprises and specialist network integrators. The complexity of a module increases with data rate, coherent functionality and optical reach, so upstream supply quality and downstream interoperability are closely linked.

UpstreamLaser diodes, optical receivers, photonic devices, driver chips, fiber connectors and thermal components
ManufacturingOptical assembly, electronic integration, firmware, thermal verification, link-budget and interoperability testing
ChannelNetwork equipment makers, direct hyperscale contracts, authorized distributors and systems integrators
DownstreamTelecom carriers, cloud data centers, enterprise fiber networks, security and research applications

Upstream. Lasers, detectors, photonic integrated devices and high-speed electronic components establish the performance ceiling of a transceiver. Coherent and Lumentum publish technical information about products operating at 800G and 1.6T, showing how higher data rates increase demands on optical and electronic integration. Component availability, yield and consistent specifications influence finished module delivery, particularly during equipment transitions.

Manufacturing. Optical module manufacturing involves precise assembly, electrical connections, fiber coupling, firmware configuration and repeated testing. A 500-meter short-reach single mode module has different optical requirements from a coherent product designed for metro transport. Suppliers must verify optical output, error performance, power and temperature operation. Production volume without reliable test yield does not necessarily translate into available commercial inventory.

Distribution. Cloud operators may procure qualified transceivers through direct supply agreements, while telecom operators often obtain modules with network equipment or through approved distribution channels. Enterprise buyers rely more heavily on integrators and stocked replacement parts. The sales route affects warranty terms, installation assistance and how quickly a buyer can replace an incompatible or failed optical module.

Downstream. Customers evaluate total link performance rather than nominal module speed alone. Telecom networks prioritize reach, compatibility and service continuity, while cloud data centers often place greater weight on density, energy use and rapid equipment upgrades. Enterprises need reliable links over existing fiber infrastructure. The diversity of downstream needs sustains both established 10G and 25G products and higher-rate module families.

Recent Developments in the Single Mode Optical Modules Market

  • 2025 Product
    Coherent announced general availability of 800G ZR and ZR+ QSFP-DD coherent optical transceivers for metro and data center interconnect use. The announcement provides evidence of product availability rather than market shipment totals. These designs give operators an additional option for increasing fiber capacity where host equipment and optical line systems can support the required transmission conditions. Source
  • 2025 Product
    Lumentum announced transceiver developments intended to double fiber capacity across different transmission distances, including 400G and 800G coherent connectivity. The products illustrate the range of optical architectures needed for different routes. Operators still need to test wavelength compatibility, power budgets and total link economics before adding modules to their production networks. Source
  • 2025 Industry event
    Lumentum highlighted optical innovations for cloud AI and networking infrastructure at OFC 2025, including faster transceivers and optical circuit switching. The event demonstrates a technology direction but does not establish revenue, market share or deployment volumes. Cloud operators evaluate the ability of these designs to support high-density switch connections within thermal and operational limits. Source
  • 2025 Product
    Coherent announced 400G optical transceivers for optical circuit switching applications with an additional 3 dB insertion-loss allowance. This design addresses a specific optical network requirement rather than a universal improvement to every module. Equipment engineers must verify the loss budget and switching architecture before selecting an optical transceiver for such installations. Source
  • 2024 Demonstration
    Coherent demonstrated 1.6T DR8 and 800G DR4 optical module technologies in 2024. The demonstration highlights the move toward faster single mode links used in data centers. Commercial adoption depends on host interfaces, fiber configuration, thermal design and customer qualification, so a demonstration should not be treated as proof of large-scale shipment volumes. Source
  • 2024 Product
    Coherent introduced an 800G L-band QSFP-DD coherent optical transceiver, illustrating an approach to capacity expansion in wavelength-managed transport systems. This type of product addresses a different engineering problem from a 500-meter parallel data center module. Network operators consider route reach, line-system compatibility and wavelength planning when assessing its potential deployment. Source
  • Product documentation Specification
    Lumentum documents an 800G 2DR4 OSFP single mode module with a 500-meter reach and power consumption below 15.2 watts. These are technical product specifications rather than a dated launch announcement. The details help network designers compare port density, thermal needs and optical reach for short connections in cloud facilities. Source
  • Product documentation Specification
    Lumentum describes a 1.6T single mode OSFP transceiver designed for a 500-meter link. The published specification illustrates the technical demands of faster data center connections. It should not be interpreted as a forecast of adoption or a claim that every cloud operator has equipment capable of using the module in production networks. Source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2020–2034
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
Historical Period 2020–2024
Market Size 2025 USD 5,800 million
Market Size 2026 USD 6,175 million
Market Size 2034 USD 10,200 million
Growth Rate CAGR of 6.5% from 2026–2034
Unit Value (USD Million)
Segmentation By Type, By Application and By Region
By Type 10G · 25G · 40G · Others
By Application Telecommunication Operator Networks · Data Centers · Enterprise Networks · Security & Surveillance · Others
By Region Each region analysed by type, application and country
Asia-PacificChina, Japan, India, South Korea, Southeast Asia
North AmericaUnited States, Canada, Mexico
EuropeGermany, United Kingdom, France, Netherlands, Rest of Europe
South AmericaBrazil, Argentina, Chile, Colombia, Rest of South America
Middle East & AfricaSaudi Arabia, UAE, South Africa, Kenya, Nigeria, Rest of Middle East & Africa
Key Companies Profiled Coherent, Lumentum, Arista Networks and other qualified optical module suppliers
Customization Scope Report customization may include additional country analysis, transceiver form factors, transmission reach, interface speeds and application-specific supplier comparisons, subject to data availability.

Frequently Asked Questions

What is the size of the single mode optical modules market?

The global single mode optical modules market is valued at USD 5,800 million in 2025 and is projected to reach USD 10,200 million by 2034. The forecast corresponds to a 6.5% CAGR over the 2025–2034 interval. Telecom network upgrades and demand for higher-capacity data center connections support growth, while component supply and equipment compatibility affect purchasing schedules.

Which region leads the market?

Asia-Pacific is the largest regional market with an estimated ~40% share of 2025 revenue and approximately ~7.6% CAGR. China contributes extensive telecom deployment and optical equipment production, while Japan, India and other regional markets have different purchasing patterns. North America follows with ~29% share, supported by cloud and AI infrastructure investment.

Which product type has the largest share?

Established 10G single mode modules represent the largest listed type with an estimated ~38% share in 2025, followed by 25G at ~29% and 40G at ~20%. Other products account for ~13% and include higher-rate optical module families. These shares describe the market value mix rather than the installed number of fiber connections.

What applications drive growth?

Telecommunication operator networks account for an estimated ~45% of revenue, supported by fiber access, aggregation and backbone links. Data centers represent about ~32% and are expected to grow faster as high-density computing increases demand for 400G, 800G and 1.6T connectivity. Enterprise networks and specialized applications continue to purchase established optical module formats.

What is the difference between 10G and 800G single mode optics?

The headline speed indicates nominal data throughput but does not specify reach, wavelength, electrical interface or fiber arrangement. A 10G module can serve established carrier or enterprise connections, while 800G designs address higher-bandwidth applications and may require different switch ports and cooling. Engineers must check optical link budgets and interoperability before replacing an installed transceiver.

Who supplies high-speed single mode optical technologies?

Coherent and Lumentum publish technical portfolios covering advanced optical transceivers and supporting photonic technologies. Networking equipment makers and their qualified supplier ecosystems influence which products reach customers. Supplier leadership varies by coherent transport, short-reach data center links and legacy module formats, so a single ranking cannot be assumed across every optical architecture.

Why are 800G and 1.6T modules important?

High-speed optical interfaces can increase the capacity of each compatible network port and reduce the need for additional physical connections in dense computing facilities. Coherent demonstrated 1.6T DR8 and 800G DR4 technologies in 2024, while Lumentum documents 500-meter single mode products. Adoption still requires compatible switching equipment, suitable fiber, thermal capacity and successful qualification.

What limits market expansion?

Constraints include availability of qualified optical components, high-speed signal integrity, power consumption and the cost of replacing networking equipment. Telecom operators often maintain existing 10G and 25G systems for long periods. Even when a faster module is commercially available, an installation may need new switches, additional cooling or changes to optical line systems.

How do coherent and parallel optical modules differ?

Coherent transceivers use sophisticated optical modulation and receiver processing to support particular transport requirements, while parallel optical modules commonly address shorter high-capacity connections in data centers. The appropriate design depends on reach, fiber layout and network architecture. Coherent 800G ZR and ZR+ products therefore serve different use cases from 500-meter 800G OSFP modules.

What does the market study cover?

The study presents 2025 revenue, a 2026 estimate and forecasts through 2034, with historical context from 2020–2024. It segments the market by 10G, 25G, 40G and other module types; telecom, data center, enterprise and specialized applications; and five global regions. Market shares are indicative estimates and product claims are distinguished from verified source specifications.

Research Sources & Evidence Base
View research sources used for this overview
  1. Coherent. 800G ZR and ZR+ QSFP-DD transceivers, Product availability and coherent transport applications.
  2. Coherent. 100G transimpedance amplifiers, High-speed optical receiver component development.
  3. Lumentum. 1.6T single mode transceiver, Technical reach and product specifications.
  4. Lumentum. OFC 2024 optical technologies, Optical component and transmission developments.
  5. Lumentum. New coherent transceiver products, 2025 product portfolio expansion.
  6. Coherent. 800G L-band coherent transceiver, Transport module wavelength and capacity.
  7. Coherent. Coherent QSFP-DD transceiver, Product specifications for telecom transport.
  8. Coherent. C-band coherent optical module, Coherent module optical reach and specifications.
  9. Coherent. Optical circuit switch transceivers, 400G product design and additional insertion loss.
  10. Coherent. Advanced transceiver demonstrations, 1.6T and 800G technology demonstrations.
  11. Lumentum. 800G 2DR4 OSFP transceiver, 500-meter reach and power specification.
  12. Lumentum. 1.6T 2DR4 OSFP transceiver, 500-meter reach and high-speed connectivity.
  13. Lumentum. OFC 2025 optical innovations, 800G and 1.6T data center optical technologies.
  14. Lumentum. Electro-absorption modulated lasers, 100G and 200G photonic components.
  15. Arista Networks. Optical product migration notice, Product lifecycle and network equipment compatibility.
Single Mode Optical Modules Market Trends, Technological Advancements and Business Strategies 2026–2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF
SKU: 8b911628df73
Category:
License Type

Corporate License, Excel License, PDF and Excel Databook License

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Single Mode Optical Modules Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Single Mode Optical Modules Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Single Mode Optical Modules Overall Market Size
2.1 Global Single Mode Optical Modules Market Size: 2025 VS 2034
2.2 Global Single Mode Optical Modules Market Size, Prospects & Forecasts: 2026-2034
2.3 Global Single Mode Optical Modules Sales: 2026-2034
3 Company Landscape
3.1 Top Single Mode Optical Modules Players in Global Market
3.2 Top Global Single Mode Optical Modules Companies Ranked by Revenue
3.3 Global Single Mode Optical Modules Revenue by Companies
3.4 Global Single Mode Optical Modules Sales by Companies
3.5 Global Single Mode Optical Modules Price by Manufacturer (2021-2026)
3.6 Top 3 and Top 5 Single Mode Optical Modules Companies in Global Market, by Revenue in 2025
3.7 Global Manufacturers Single Mode Optical Modules Product Type
3.8 Tier 1, Tier 2, and Tier 3 Single Mode Optical Modules Players in Global Market
3.8.1 List of Global Tier 1 Single Mode Optical Modules Companies
3.8.2 List of Global Tier 2 and Tier 3 Single Mode Optical Modules Companies
4 Sights by Type
4.1 Overview
4.1.1 Segment by Type – Global Single Mode Optical Modules Market Size Markets, 2025 & 2034
4.1.2 10G
4.1.3 25G
4.1.4 40G
4.1.5 Others
4.2 Segment by Type – Global Single Mode Optical Modules Revenue & Forecasts
4.2.1 Segment by Type – Global Single Mode Optical Modules Revenue, 2021-2026
4.2.2 Segment by Type – Global Single Mode Optical Modules Revenue, 2027-2034
4.2.3 Segment by Type – Global Single Mode Optical Modules Revenue Market Share, 2026-2034
4.3 Segment by Type – Global Single Mode Optical Modules Sales & Forecasts
4.3.1 Segment by Type – Global Single Mode Optical Modules Sales, 2021-2026
4.3.2 Segment by Type – Global Single Mode Optical Modules Sales, 2027-2034
4.3.3 Segment by Type – Global Single Mode Optical Modules Sales Market Share, 2026-2034
4.4 Segment by Type – Global Single Mode Optical Modules Price (Manufacturers Selling Prices), 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global Single Mode Optical Modules Market Size, 2025 & 2034
5.1.2 Telecommunication Operator Networks
5.1.3 Data Centers
5.1.4 Enterprise Networks
5.1.5 Security & Surveillance
5.1.6 Others
5.2 Segment by Application – Global Single Mode Optical Modules Revenue & Forecasts
5.2.1 Segment by Application – Global Single Mode Optical Modules Revenue, 2021-2026
5.2.2 Segment by Application – Global Single Mode Optical Modules Revenue, 2027-2034
5.2.3 Segment by Application – Global Single Mode Optical Modules Revenue Market Share, 2026-2034
5.3 Segment by Application – Global Single Mode Optical Modules Sales & Forecasts
5.3.1 Segment by Application – Global Single Mode Optical Modules Sales, 2021-2026
5.3.2 Segment by Application – Global Single Mode Optical Modules Sales, 2027-2034
5.3.3 Segment by Application – Global Single Mode Optical Modules Sales Market Share, 2026-2034
5.4 Segment by Application – Global Single Mode Optical Modules Price (Manufacturers Selling Prices), 2026-2034
6 Sights Region
6.1 By Region – Global Single Mode Optical Modules Market Size, 2025 & 2034
6.2 By Region – Global Single Mode Optical Modules Revenue & Forecasts
6.2.1 By Region – Global Single Mode Optical Modules Revenue, 2021-2026
6.2.2 By Region – Global Single Mode Optical Modules Revenue, 2027-2034
6.2.3 By Region – Global Single Mode Optical Modules Revenue Market Share, 2026-2034
6.3 By Region – Global Single Mode Optical Modules Sales & Forecasts
6.3.1 By Region – Global Single Mode Optical Modules Sales, 2021-2026
6.3.2 By Region – Global Single Mode Optical Modules Sales, 2027-2034
6.3.3 By Region – Global Single Mode Optical Modules Sales Market Share, 2026-2034
6.4 North America
6.4.1 By Country – North America Single Mode Optical Modules Revenue, 2026-2034
6.4.2 By Country – North America Single Mode Optical Modules Sales, 2026-2034
6.4.3 United States Single Mode Optical Modules Market Size, 2026-2034
6.4.4 Canada Single Mode Optical Modules Market Size, 2026-2034
6.4.5 Mexico Single Mode Optical Modules Market Size, 2026-2034
6.5 Europe
6.5.1 By Country – Europe Single Mode Optical Modules Revenue, 2026-2034
6.5.2 By Country – Europe Single Mode Optical Modules Sales, 2026-2034
6.5.3 Germany Single Mode Optical Modules Market Size, 2026-2034
6.5.4 France Single Mode Optical Modules Market Size, 2026-2034
6.5.5 U.K. Single Mode Optical Modules Market Size, 2026-2034
6.5.6 Italy Single Mode Optical Modules Market Size, 2026-2034
6.5.7 Russia Single Mode Optical Modules Market Size, 2026-2034
6.5.8 Nordic Countries Single Mode Optical Modules Market Size, 2026-2034
6.5.9 Benelux Single Mode Optical Modules Market Size, 2026-2034
6.6 Asia
6.6.1 By Region – Asia Single Mode Optical Modules Revenue, 2026-2034
6.6.2 By Region – Asia Single Mode Optical Modules Sales, 2026-2034
6.6.3 China Single Mode Optical Modules Market Size, 2026-2034
6.6.4 Japan Single Mode Optical Modules Market Size, 2026-2034
6.6.5 South Korea Single Mode Optical Modules Market Size, 2026-2034
6.6.6 Southeast Asia Single Mode Optical Modules Market Size, 2026-2034
6.6.7 India Single Mode Optical Modules Market Size, 2026-2034
6.7 South America
6.7.1 By Country – South America Single Mode Optical Modules Revenue, 2026-2034
6.7.2 By Country – South America Single Mode Optical Modules Sales, 2026-2034
6.7.3 Brazil Single Mode Optical Modules Market Size, 2026-2034
6.7.4 Argentina Single Mode Optical Modules Market Size, 2026-2034
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa Single Mode Optical Modules Revenue, 2026-2034
6.8.2 By Country – Middle East & Africa Single Mode Optical Modules Sales, 2026-2034
6.8.3 Turkey Single Mode Optical Modules Market Size, 2026-2034
6.8.4 Israel Single Mode Optical Modules Market Size, 2026-2034
6.8.5 Saudi Arabia Single Mode Optical Modules Market Size, 2026-2034
6.8.6 UAE Single Mode Optical Modules Market Size, 2026-2034
7 Manufacturers & Brands Profiles
7.1 Cisco
7.1.1 Cisco Company Summary
7.1.2 Cisco Business Overview
7.1.3 Cisco Single Mode Optical Modules Major Product Offerings
7.1.4 Cisco Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.1.5 Cisco Key News & Latest Developments
7.2 II-VI Incorporated
7.2.1 II-VI Incorporated Company Summary
7.2.2 II-VI Incorporated Business Overview
7.2.3 II-VI Incorporated Single Mode Optical Modules Major Product Offerings
7.2.4 II-VI Incorporated Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.2.5 II-VI Incorporated Key News & Latest Developments
7.3 E.C.I. Networks
7.3.1 E.C.I. Networks Company Summary
7.3.2 E.C.I. Networks Business Overview
7.3.3 E.C.I. Networks Single Mode Optical Modules Major Product Offerings
7.3.4 E.C.I. Networks Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.3.5 E.C.I. Networks Key News & Latest Developments
7.4 Amphenol
7.4.1 Amphenol Company Summary
7.4.2 Amphenol Business Overview
7.4.3 Amphenol Single Mode Optical Modules Major Product Offerings
7.4.4 Amphenol Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.4.5 Amphenol Key News & Latest Developments
7.5 Molex
7.5.1 Molex Company Summary
7.5.2 Molex Business Overview
7.5.3 Molex Single Mode Optical Modules Major Product Offerings
7.5.4 Molex Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.5.5 Molex Key News & Latest Developments
7.6 NEC
7.6.1 NEC Company Summary
7.6.2 NEC Business Overview
7.6.3 NEC Single Mode Optical Modules Major Product Offerings
7.6.4 NEC Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.6.5 NEC Key News & Latest Developments
7.7 Broadcom
7.7.1 Broadcom Company Summary
7.7.2 Broadcom Business Overview
7.7.3 Broadcom Single Mode Optical Modules Major Product Offerings
7.7.4 Broadcom Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.7.5 Broadcom Key News & Latest Developments
7.8 Approved Networks
7.8.1 Approved Networks Company Summary
7.8.2 Approved Networks Business Overview
7.8.3 Approved Networks Single Mode Optical Modules Major Product Offerings
7.8.4 Approved Networks Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.8.5 Approved Networks Key News & Latest Developments
7.9 Vitex
7.9.1 Vitex Company Summary
7.9.2 Vitex Business Overview
7.9.3 Vitex Single Mode Optical Modules Major Product Offerings
7.9.4 Vitex Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.9.5 Vitex Key News & Latest Developments
7.10 Nokia
7.10.1 Nokia Company Summary
7.10.2 Nokia Business Overview
7.10.3 Nokia Single Mode Optical Modules Major Product Offerings
7.10.4 Nokia Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.10.5 Nokia Key News & Latest Developments
7.11 InnoLight Technology
7.11.1 InnoLight Technology Company Summary
7.11.2 InnoLight Technology Business Overview
7.11.3 InnoLight Technology Single Mode Optical Modules Major Product Offerings
7.11.4 InnoLight Technology Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.11.5 InnoLight Technology Key News & Latest Developments
7.12 HiSilicon Optoelectronics
7.12.1 HiSilicon Optoelectronics Company Summary
7.12.2 HiSilicon Optoelectronics Business Overview
7.12.3 HiSilicon Optoelectronics Single Mode Optical Modules Major Product Offerings
7.12.4 HiSilicon Optoelectronics Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.12.5 HiSilicon Optoelectronics Key News & Latest Developments
7.13 Hisense Broadband
7.13.1 Hisense Broadband Company Summary
7.13.2 Hisense Broadband Business Overview
7.13.3 Hisense Broadband Single Mode Optical Modules Major Product Offerings
7.13.4 Hisense Broadband Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.13.5 Hisense Broadband Key News & Latest Developments
7.14 Eoptolink
7.14.1 Eoptolink Company Summary
7.14.2 Eoptolink Business Overview
7.14.3 Eoptolink Single Mode Optical Modules Major Product Offerings
7.14.4 Eoptolink Single Mode Optical Modules Sales and Revenue in Global (2021-2026)
7.14.5 Eoptolink Key News & Latest Developments
8 Global Single Mode Optical Modules Production Capacity, Analysis
8.1 Global Single Mode Optical Modules Production Capacity, 2026-2034
8.2 Single Mode Optical Modules Production Capacity of Key Manufacturers in Global Market
8.3 Global Single Mode Optical Modules Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 Single Mode Optical Modules Supply Chain Analysis
10.1 Single Mode Optical Modules Industry Value Chain
10.2 Single Mode Optical Modules Upstream Market
10.3 Single Mode Optical Modules Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 Single Mode Optical Modules Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of Single Mode Optical Modules in Global Market
Table 2. Top Single Mode Optical Modules Players in Global Market, Ranking by Revenue (2025)
Table 3. Global Single Mode Optical Modules Revenue by Companies, (US$, Mn), 2021-2026
Table 4. Global Single Mode Optical Modules Revenue Share by Companies, 2021-2026
Table 5. Global Single Mode Optical Modules Sales by Companies, (K Units), 2021-2026
Table 6. Global Single Mode Optical Modules Sales Share by Companies, 2021-2026
Table 7. Key Manufacturers Single Mode Optical Modules Price (2021-2026) & (US$/Unit)
Table 8. Global Manufacturers Single Mode Optical Modules Product Type
Table 9. List of Global Tier 1 Single Mode Optical Modules Companies, Revenue (US$, Mn) in 2025 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Single Mode Optical Modules Companies, Revenue (US$, Mn) in 2025 and Market Share
Table 11. Segment by Type – Global Single Mode Optical Modules Revenue, (US$, Mn), 2025 & 2034
Table 12. Segment by Type – Global Single Mode Optical Modules Revenue (US$, Mn), 2021-2026
Table 13. Segment by Type – Global Single Mode Optical Modules Revenue (US$, Mn), 2027-2034
Table 14. Segment by Type – Global Single Mode Optical Modules Sales (K Units), 2021-2026
Table 15. Segment by Type – Global Single Mode Optical Modules Sales (K Units), 2027-2034
Table 16. Segment by Application – Global Single Mode Optical Modules Revenue, (US$, Mn), 2025 & 2034
Table 17. Segment by Application – Global Single Mode Optical Modules Revenue, (US$, Mn), 2021-2026
Table 18. Segment by Application – Global Single Mode Optical Modules Revenue, (US$, Mn), 2027-2034
Table 19. Segment by Application – Global Single Mode Optical Modules Sales, (K Units), 2021-2026
Table 20. Segment by Application – Global Single Mode Optical Modules Sales, (K Units), 2027-2034
Table 21. By Region – Global Single Mode Optical Modules Revenue, (US$, Mn), 2025 & 2034
Table 22. By Region – Global Single Mode Optical Modules Revenue, (US$, Mn), 2021-2026
Table 23. By Region – Global Single Mode Optical Modules Revenue, (US$, Mn), 2027-2034
Table 24. By Region – Global Single Mode Optical Modules Sales, (K Units), 2021-2026
Table 25. By Region – Global Single Mode Optical Modules Sales, (K Units), 2027-2034
Table 26. By Country – North America Single Mode Optical Modules Revenue, (US$, Mn), 2021-2026
Table 27. By Country – North America Single Mode Optical Modules Revenue, (US$, Mn), 2027-2034
Table 28. By Country – North America Single Mode Optical Modules Sales, (K Units), 2021-2026
Table 29. By Country – North America Single Mode Optical Modules Sales, (K Units), 2027-2034
Table 30. By Country – Europe Single Mode Optical Modules Revenue, (US$, Mn), 2021-2026
Table 31. By Country – Europe Single Mode Optical Modules Revenue, (US$, Mn), 2027-2034
Table 32. By Country – Europe Single Mode Optical Modules Sales, (K Units), 2021-2026
Table 33. By Country – Europe Single Mode Optical Modules Sales, (K Units), 2027-2034
Table 34. By Region – Asia Single Mode Optical Modules Revenue, (US$, Mn), 2021-2026
Table 35. By Region – Asia Single Mode Optical Modules Revenue, (US$, Mn), 2027-2034
Table 36. By Region – Asia Single Mode Optical Modules Sales, (K Units), 2021-2026
Table 37. By Region – Asia Single Mode Optical Modules Sales, (K Units), 2027-2034
Table 38. By Country – South America Single Mode Optical Modules Revenue, (US$, Mn), 2021-2026
Table 39. By Country – South America Single Mode Optical Modules Revenue, (US$, Mn), 2027-2034
Table 40. By Country – South America Single Mode Optical Modules Sales, (K Units), 2021-2026
Table 41. By Country – South America Single Mode Optical Modules Sales, (K Units), 2027-2034
Table 42. By Country – Middle East & Africa Single Mode Optical Modules Revenue, (US$, Mn), 2021-2026
Table 43. By Country – Middle East & Africa Single Mode Optical Modules Revenue, (US$, Mn), 2027-2034
Table 44. By Country – Middle East & Africa Single Mode Optical Modules Sales, (K Units), 2021-2026
Table 45. By Country – Middle East & Africa Single Mode Optical Modules Sales, (K Units), 2027-2034
Table 46. Cisco Company Summary
Table 47. Cisco Single Mode Optical Modules Product Offerings
Table 48. Cisco Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 49. Cisco Key News & Latest Developments
Table 50. II-VI Incorporated Company Summary
Table 51. II-VI Incorporated Single Mode Optical Modules Product Offerings
Table 52. II-VI Incorporated Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 53. II-VI Incorporated Key News & Latest Developments
Table 54. E.C.I. Networks Company Summary
Table 55. E.C.I. Networks Single Mode Optical Modules Product Offerings
Table 56. E.C.I. Networks Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 57. E.C.I. Networks Key News & Latest Developments
Table 58. Amphenol Company Summary
Table 59. Amphenol Single Mode Optical Modules Product Offerings
Table 60. Amphenol Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 61. Amphenol Key News & Latest Developments
Table 62. Molex Company Summary
Table 63. Molex Single Mode Optical Modules Product Offerings
Table 64. Molex Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 65. Molex Key News & Latest Developments
Table 66. NEC Company Summary
Table 67. NEC Single Mode Optical Modules Product Offerings
Table 68. NEC Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 69. NEC Key News & Latest Developments
Table 70. Broadcom Company Summary
Table 71. Broadcom Single Mode Optical Modules Product Offerings
Table 72. Broadcom Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 73. Broadcom Key News & Latest Developments
Table 74. Approved Networks Company Summary
Table 75. Approved Networks Single Mode Optical Modules Product Offerings
Table 76. Approved Networks Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 77. Approved Networks Key News & Latest Developments
Table 78. Vitex Company Summary
Table 79. Vitex Single Mode Optical Modules Product Offerings
Table 80. Vitex Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 81. Vitex Key News & Latest Developments
Table 82. Nokia Company Summary
Table 83. Nokia Single Mode Optical Modules Product Offerings
Table 84. Nokia Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 85. Nokia Key News & Latest Developments
Table 86. InnoLight Technology Company Summary
Table 87. InnoLight Technology Single Mode Optical Modules Product Offerings
Table 88. InnoLight Technology Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 89. InnoLight Technology Key News & Latest Developments
Table 90. HiSilicon Optoelectronics Company Summary
Table 91. HiSilicon Optoelectronics Single Mode Optical Modules Product Offerings
Table 92. HiSilicon Optoelectronics Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 93. HiSilicon Optoelectronics Key News & Latest Developments
Table 94. Hisense Broadband Company Summary
Table 95. Hisense Broadband Single Mode Optical Modules Product Offerings
Table 96. Hisense Broadband Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 97. Hisense Broadband Key News & Latest Developments
Table 98. Eoptolink Company Summary
Table 99. Eoptolink Single Mode Optical Modules Product Offerings
Table 100. Eoptolink Single Mode Optical Modules Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2021-2026)
Table 101. Eoptolink Key News & Latest Developments
Table 102. Single Mode Optical Modules Capacity of Key Manufacturers in Global Market, 2024-2026 (K Units)
Table 103. Global Single Mode Optical Modules Capacity Market Share of Key Manufacturers, 2024-2026
Table 104. Global Single Mode Optical Modules Production by Region, 2021-2026 (K Units)
Table 105. Global Single Mode Optical Modules Production by Region, 2027-2034 (K Units)
Table 106. Single Mode Optical Modules Market Opportunities & Trends in Global Market
Table 107. Single Mode Optical Modules Market Drivers in Global Market
Table 108. Single Mode Optical Modules Market Restraints in Global Market
Table 109. Single Mode Optical Modules Raw Materials
Table 110. Single Mode Optical Modules Raw Materials Suppliers in Global Market
Table 111. Typical Single Mode Optical Modules Downstream
Table 112. Single Mode Optical Modules Downstream Clients in Global Market
Table 113. Single Mode Optical Modules Distributors and Sales Agents in Global Market

List of Figures
Figure 1. Single Mode Optical Modules Product Picture
Figure 2. Single Mode Optical Modules Segment by Type in 2025
Figure 3. Single Mode Optical Modules Segment by Application in 2025
Figure 4. Global Single Mode Optical Modules Market Overview: 2025
Figure 5. Key Caveats
Figure 6. Global Single Mode Optical Modules Market Size: 2025 VS 2034 (US$, Mn)
Figure 7. Global Single Mode Optical Modules Revenue: 2026-2034 (US$, Mn)
Figure 8. Single Mode Optical Modules Sales in Global Market: 2026-2034 (K Units)
Figure 9. The Top 3 and 5 Players Market Share by Single Mode Optical Modules Revenue in 2025
Figure 10. Segment by Type – Global Single Mode Optical Modules Revenue, (US$, Mn), 2025 & 2034
Figure 11. Segment by Type – Global Single Mode Optical Modules Revenue Market Share, 2026-2034
Figure 12. Segment by Type – Global Single Mode Optical Modules Sales Market Share, 2026-2034
Figure 13. Segment by Type – Global Single Mode Optical Modules Price (US$/Unit), 2026-2034
Figure 14. Segment by Application – Global Single Mode Optical Modules Revenue, (US$, Mn), 2025 & 2034
Figure 15. Segment by Application – Global Single Mode Optical Modules Revenue Market Share, 2026-2034
Figure 16. Segment by Application – Global Single Mode Optical Modules Sales Market Share, 2026-2034
Figure 17. Segment by Application -Global Single Mode Optical Modules Price (US$/Unit), 2026-2034
Figure 18. By Region – Global Single Mode Optical Modules Revenue, (US$, Mn), 2025 & 2034
Figure 19. By Region – Global Single Mode Optical Modules Revenue Market Share, 2021 VS 2025 VS 2034
Figure 20. By Region – Global Single Mode Optical Modules Revenue Market Share, 2026-2034
Figure 21. By Region – Global Single Mode Optical Modules Sales Market Share, 2026-2034
Figure 22. By Country – North America Single Mode Optical Modules Revenue Market Share, 2026-2034
Figure 23. By Country – North America Single Mode Optical Modules Sales Market Share, 2026-2034
Figure 24. United States Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 25. Canada Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 26. Mexico Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 27. By Country – Europe Single Mode Optical Modules Revenue Market Share, 2026-2034
Figure 28. By Country – Europe Single Mode Optical Modules Sales Market Share, 2026-2034
Figure 29. Germany Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 30. France Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 31. U.K. Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 32. Italy Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 33. Russia Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 34. Nordic Countries Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 35. Benelux Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 36. By Region – Asia Single Mode Optical Modules Revenue Market Share, 2026-2034
Figure 37. By Region – Asia Single Mode Optical Modules Sales Market Share, 2026-2034
Figure 38. China Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 39. Japan Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 40. South Korea Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 41. Southeast Asia Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 42. India Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 43. By Country – South America Single Mode Optical Modules Revenue Market Share, 2026-2034
Figure 44. By Country – South America Single Mode Optical Modules Sales, Market Share, 2026-2034
Figure 45. Brazil Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 46. Argentina Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 47. By Country – Middle East & Africa Single Mode Optical Modules Revenue, Market Share, 2026-2034
Figure 48. By Country – Middle East & Africa Single Mode Optical Modules Sales, Market Share, 2026-2034
Figure 49. Turkey Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 50. Israel Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 51. Saudi Arabia Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 52. UAE Single Mode Optical Modules Revenue, (US$, Mn), 2026-2034
Figure 53. Global Single Mode Optical Modules Production Capacity (K Units), 2026-2034
Figure 54. The Percentage of Production Single Mode Optical Modules by Region, 2025 VS 2034
Figure 55. Single Mode Optical Modules Industry Value Chain
Figure 56. Marketing Channels