Key Statistics
Key Takeaways
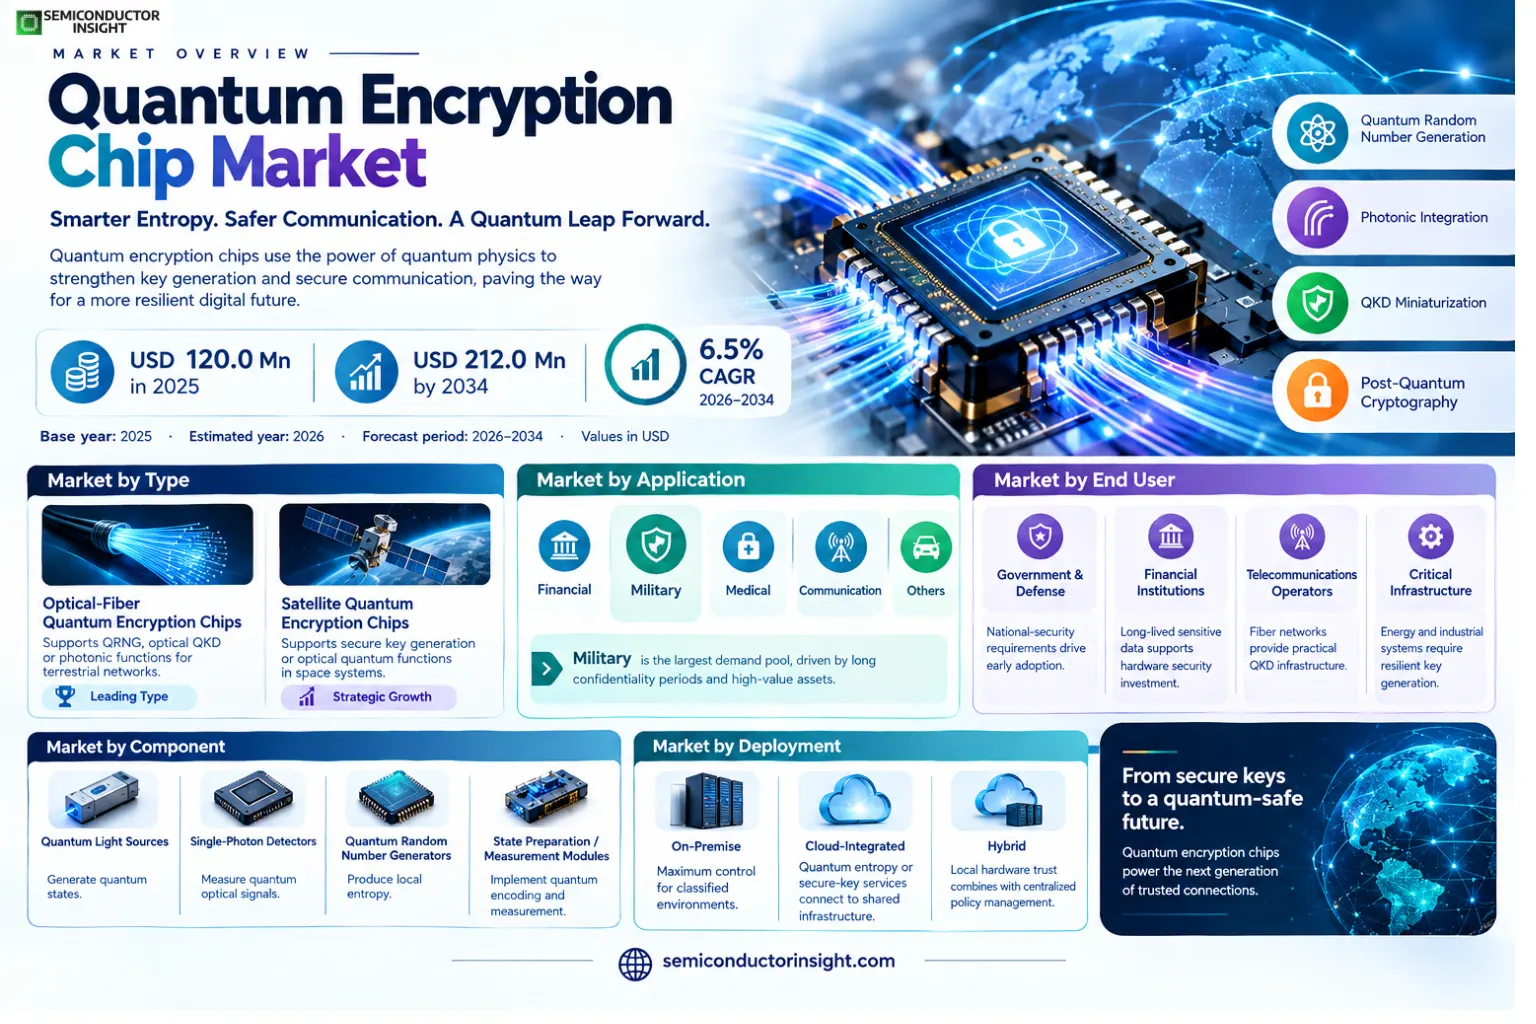
- Market size and growth: the market is valued at USD 120.0 million in 2025 and is projected to reach USD 212.0 million by 2034, with a 6.5% CAGR over 2026–2034.
- Optical-Fiber Quantum Encryption Chips leads by type because fiber infrastructure is the most mature terrestrial path for quantum key distribution and secure metropolitan networks.
- Military is the principal application because defense communications place high value on trusted key generation, sovereign control and resistance to future cryptanalytic threats.
- North America is the largest regional market, while Asia Pacific has the strongest incremental growth profile.
- Primary driver: rising concern about long-lived data security is increasing demand for quantum-safe key generation and secure communications hardware
- Principal restraint: QKD infrastructure, photonic integration and certification remain expensive and technically complex
Market Overview
The quantum encryption chip market was valued at USD 120.0 million in 2025 and is projected to reach USD 212.0 million by 2034, expanding at a 6.5% CAGR over 2026–2034. North America leads in 2025, while market structure is being reshaped by quantum random number generation, photonic integration, QKD miniaturization and migration toward post-quantum cryptography..
Quantum encryption chips integrate hardware functions that strengthen cryptographic key generation or quantum-secure communication. Commercial implementations include quantum random-number generator chips, photonic components used in quantum key distribution and specialized security ICs that embed trusted entropy directly at the endpoint. The category overlaps with, but is distinct from, post-quantum cryptography: QRNG and QKD use quantum physical processes, while PQC uses classical algorithms designed to resist quantum attacks.
ID Quantique’s current Quantis QRNG chips show how quantum security is moving into semiconductor form factors. The devices use quantum shot noise from a light source and CMOS image sensor to generate entropy and are offered for automotive, computing, critical infrastructure, IoT, mobile, space and security applications. Several models carry NIST entropy-source validation, making certification an increasingly important differentiator.
The cybersecurity environment is accelerating demand for quantum-safe hardware. NIST published FIPS 203, 204 and 205 in 2024 and continues migration guidance. This does not make every quantum encryption chip mandatory, but it increases attention on crypto-agility, secure key generation and hardware roots of trust that can support both current cryptographic systems and future quantum-resistant algorithms.
Segment Analysis: By Type
By type, the market is segmented into Optical-Fiber Quantum Encryption Chips, Satellite Quantum Encryption Chips. Optical-Fiber Quantum Encryption Chips holds the leading position.
| Type | Role | Commercial position |
|---|---|---|
| Optical-Fiber Quantum Encryption Chips | Support QRNG, optical QKD or photonic functions for terrestrial networks. | Leading type because fiber provides the most practical deployment route. |
| Satellite Quantum Encryption Chips | Support secure key generation or optical quantum functions in space systems. | Strategic growth segment for sovereign long-distance communications. |
Commercial implications by type
Fiber and satellite products have different commercialization paths. Fiber-based systems can leverage existing telecom networks, while satellite designs face radiation, power and optical-link constraints. QRNG chips can serve both categories because local high-quality entropy is useful even when full QKD infrastructure is not available.
Segment Analysis: By Application
By application, the market includes Financial, Military, Medical, Communication, Others. Military is the largest demand pool.
| Application | Demand characteristics |
|---|---|
| Financial | Banks and payment systems value strong entropy and crypto-agility. |
| Military | Leading application because long confidentiality periods justify premium secure hardware. |
| Medical | Protected health data and connected devices create demand for stronger security. |
| Communication | Telecom networks provide natural infrastructure for QKD and secure key management. |
| Others | Automotive, IoT, cloud and critical infrastructure broaden demand. |
By End User
| End User | Commercial relevance |
|---|---|
| Government & Defense | National-security requirements drive early adoption. |
| Financial Institutions | Long-lived sensitive data supports hardware security investment. |
| Telecommunications Operators | Fiber networks provide practical QKD infrastructure. |
| Critical Infrastructure | Energy and industrial systems require resilient key generation. |
By Component
| Component | Commercial relevance |
|---|---|
| Quantum Light Sources | Generate quantum states. |
| Single-Photon Detectors | Measure quantum optical signals. |
| Quantum Random Number Generators | Produce local entropy. |
| State Preparation / Measurement Modules | Implement quantum encoding and measurement. |
By Deployment
| Deployment | Commercial relevance |
|---|---|
| On-Premise | Maximum control for classified environments. |
| Cloud-Integrated | Quantum entropy or secure-key services connect to shared infrastructure. |
| Hybrid | Local hardware trust combines with centralized policy management. |
Regional Analysis
North America leads the market because the source analysis identifies North America as the leading innovation and adoption region, supported by cybersecurity investment and strategic government demand. Asia Pacific has the strongest growth profile through national quantum programs and telecom investment in China, Japan and South Korea.
How does regional demand differ across this market?
North America leads commercial and strategic development, Europe has strong research and regulatory momentum, and Asia Pacific is expanding fastest through national quantum programs. South America and the Middle East & Africa are earlier-stage markets where adoption centers on government, finance and critical infrastructure.
| Region | Position | Growth outlook | Demand profile | Supplier selection |
|---|---|---|---|---|
| North America | Largest | Strong | Quantum-safe cybersecurity and secure communications | Technology, support, lifecycle |
| Europe | Second | Moderate | Quantum-safe cybersecurity and secure communications | Compliance, efficiency, reliability |
| Asia Pacific | Third | Fastest | Quantum-safe cybersecurity and secure communications | Cost, scale, local supply |
| South America | Smaller | Moderate | Quantum-safe cybersecurity and secure communications | Cost and availability |
| Middle East & Africa | Emerging | Moderate | Quantum-safe cybersecurity and secure communications | Ruggedness, service, availability |
Competitive Landscape
Competition spans quantum-security specialists, photonics companies and semiconductor vendors integrating stronger entropy and security into conventional products.
ID Quantique is a visible commercial QRNG supplier, while Toshiba and telecom-oriented companies pursue QKD systems and photonic integration. Crypto Quantique and PQShield address adjacent hardware and post-quantum security layers.
Certification is becoming a competitive moat. ID Quantique’s current portfolio includes NIST entropy-source validated models, and customers in automotive, space and critical infrastructure increasingly require evidence that the entropy source behaves as claimed.
The market will likely converge around hybrid security. Quantum-generated entropy can strengthen keys today, while post-quantum algorithms protect public-key operations. Vendors supporting both approaches within manageable hardware footprints are well positioned.
| Competitive tier | Representative participants | Competitive focus |
|---|---|---|
| Quantum security specialists | ID Quantique, Toshiba | QRNG, QKD and photonic security hardware |
| Embedded-security specialists | Crypto Quantique, PQShield | Device security and post-quantum implementations |
| Telecom / semiconductor participants | SK Telecom, Infineon | Integration with communications and mass-market devices |
Companies Profiled
ID Quantique, Toshiba, Infineon Technologies, SK Telecom, PQShield, Crypto Quantique, OCTATCO, RED Semiconductor
Production Capacity Analysis
Capacity depends on photonic components, CMOS integration, secure packaging, optical test and certification rather than conventional logic-node scaling alone.
QRNG chips can use mainstream CMOS image-sensor and mixed-signal processes, but the quantum entropy source and health-monitoring logic require additional calibration and validation. QKD components impose more demanding photonic alignment and detector requirements.
Commercial scale is also limited by qualification. Security products must demonstrate entropy quality, environmental stability and resistance to tampering, so certification laboratories and standards work can become a longer bottleneck than wafer supply.
Market Dynamics
The market is moving from laboratory quantum communications toward deployable endpoint chips and hybrid quantum-safe architectures.
Near-term demand is strongest for hardware that improves security without requiring a complete quantum network, especially QRNG and crypto-agile secure elements. Full QKD remains valuable for the most sensitive links but carries higher deployment cost. This creates a layered market rather than one universal architecture.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Quantum threat awareness | High | Organizations are preparing for future attacks against current public-key cryptography. |
| NIST PQC migration | High | Standardized algorithms accelerate hardware and software transition planning. |
| Critical infrastructure security | High | Long-lived systems need stronger key generation and crypto-agility. |
| Photonic integration | Medium | Smaller optical components improve deployment practicality. |
Quantum threat awareness
Organizations are preparing for future attacks against current public-key cryptography.
NIST PQC migration
Standardized algorithms accelerate hardware and software transition planning.
Critical infrastructure security
Long-lived systems need stronger key generation and crypto-agility.
Photonic integration
Smaller optical components improve deployment practicality.
Market Restraints
Restraints Impact Analysis
| Restraint | Impact | Commercial mechanism |
|---|---|---|
| Infrastructure cost | High | QKD networks require specialized optical equipment. |
| Certification burden | High | Security hardware must prove entropy quality and robustness. |
| Technology fragmentation | Medium | QRNG, QKD and PQC address different layers. |
| Limited specialist skills | Medium | Quantum optical deployment requires scarce expertise. |
Infrastructure cost
QKD networks require specialized optical equipment.
Certification burden
Security hardware must prove entropy quality and robustness.
Technology fragmentation
QRNG, QKD and PQC address different layers.
Limited specialist skills
Quantum optical deployment requires scarce expertise.
Market Opportunities
Embedded QRNG
Local quantum entropy can strengthen phones, vehicles, HSMs and IoT.
Hybrid PQC hardware
Secure chips can accelerate standardized PQC algorithms while using strong entropy.
Quantum-secure telecom
Fiber and satellite links offer premium QKD applications.
Space and defense security
Long mission lifetimes justify premium hardware.
Supply Chain Analysis
Light sources, detectors, image sensors
Entropy extraction, health tests, crypto logic
Secure packaging, optical test, validation
HSMs, telecom, finance, defense, IoT
Quantum components
Optical or noise sources create physical entropy or quantum states.
Security IC
Extraction and health-test logic convert raw physical behavior into usable cryptographic data.
Packaging and certification
Environmental effects and tamper resistance must be characterized.
System integration
Keys, protocols and lifecycle management must be engineered into a complete architecture.
Recent Developments
2026 — ID Quantique expands current Quantis QRNG chip portfolio
Current chips address automotive, computing, critical infrastructure, IoT, mobile, space and security. Source
2026 — NIST continues PQC standardization and migration guidance
NIST has finalized FIPS 203, 204 and 205 and continues work on additional standards. Source
2025 — NIST selects HQC for additional standardization
The selection broadens future quantum-resistant key-establishment options. Source
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | Quantum Encryption Chip |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 120.0 million |
| 2026 Estimated Size | USD 127.8 million |
| 2034 Forecast Size | USD 212.0 million |
| CAGR | 6.5% (2026–2034) |
| By Type | Optical-Fiber Quantum Encryption Chips, Satellite Quantum Encryption Chips |
| By Application | Financial, Military, Medical, Communication, Others |
| By End User | Government & Defense, Financial Institutions, Telecommunications Operators, Critical Infrastructure |
| By Component | Quantum Light Sources, Single-Photon Detectors, Quantum Random Number Generators, State Preparation / Measurement Modules |
| By Deployment | On-Premise, Cloud-Integrated, Hybrid |
| Regions | North America, Europe, Asia Pacific, South America, Middle East & Africa |
| Companies Profiled | ID Quantique, Toshiba, Infineon Technologies, SK Telecom, PQShield, Crypto Quantique, OCTATCO, RED Semiconductor |
Frequently Asked Questions
What is the quantum encryption chip market size in 2025?
The market is valued at USD 120.0 million in 2025.
What is the projected market size by 2034?
The market is projected to reach USD 212.0 million by 2034.
What is the CAGR from 2026 to 2034?
The market is expected to expand at a 6.5% CAGR.
Which region leads the market?
North America is the largest regional market in 2025.
Which type leads the market?
Optical-Fiber Quantum Encryption Chips is the leading type.
Which application leads demand?
Military is the leading application.
What is the primary growth driver?
rising concern about long-lived data security is increasing demand for quantum-safe key generation and secure communications hardware.
What is the principal restraint?
QKD infrastructure, photonic integration and certification remain expensive and technically complex.
Where are the strongest opportunities?
embedded QRNG, fiber QKD, satellite links and hybrid hardware supporting PQC migration.
Which companies are active in the market?
ID Quantique, Toshiba, Infineon Technologies, SK Telecom, PQShield, Crypto Quantique, OCTATCO, RED Semiconductor.
Research Sources & Evidence Base
View primary and official evidence used in this overview
- ID Quantique: Quantis QRNG Chips — Current quantum entropy chip portfolio and certifications.
- NIST: Post-Quantum Cryptography Standardization — Current PQC standards and migration context.
- NIST: FIPS 203, 204 and 205 approval — Federal standards for quantum-resistant cryptography.

Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF