Key Statistics
Key Takeaways
- Market size: The market is valued at USD 853.58 million in 2025 and is projected to reach USD 2.46 billion by 2034, representing a 12.5% CAGR during 2026–2034.
- Multimode connectors dominate current unit demand, supported by short-reach data-center links where parallel fiber offers attractive cost and density.
- Data centers are the largest application, accounting for more than 44% of demand in the underlying market evidence as AI and cloud fabrics add dense optical interconnect.
- Asia Pacific leads the market, supported by data-center expansion and a large optical-component manufacturing base.
- 800G and 1.6T transceivers are increasing connector density requirements, accelerating adoption of compact MPO and next-generation multi-fiber interfaces.
Multi-Fiber Connector Market Overview
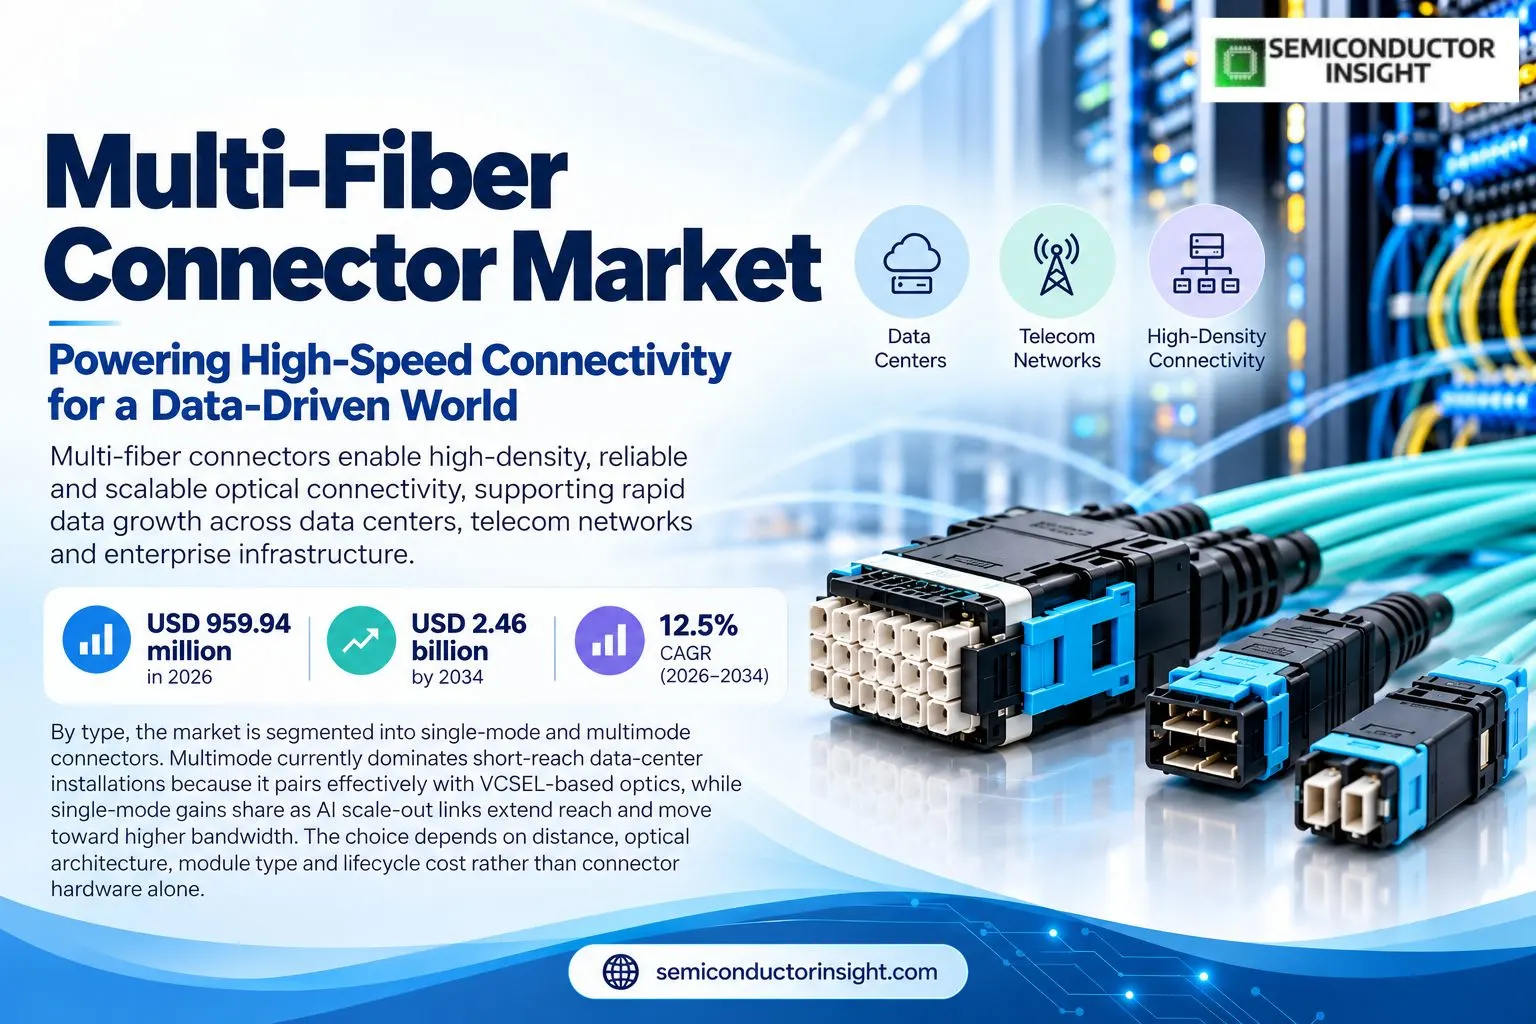
Multi-fiber connector market is valued at USD 853.58 million in 2025 and is projected to reach USD 2.46 billion by 2034, expanding at a 12.5% CAGR during 2026–2034. The 2026 market level is USD 959.94 million. Asia Pacific leads through rapid digital infrastructure investment and a dense optical-component supply chain. The market is increasingly shaped by AI data centers, 400G/800G migration and higher fiber counts per switch port.
Multi-fiber connectors terminate several optical fibers in one ferrule, allowing a single mating interface to carry multiple transmit and receive channels. MPO and MTP-style connectors are widely used in data centers, telecom equipment and high-density trunk cabling because they reduce panel space and installation time compared with individual duplex connectors. Performance depends on ferrule precision, fiber geometry, insertion loss, polarity control, end-face cleanliness and repeatable mating.
Technology development is focused on higher fiber counts, lower insertion loss and smaller footprints. SENKO’s MPO-PLUS EZ-Way connector supports 16-, 24- and 32-fiber versions and is positioned for 800G dual-MPO transceivers, while its SN-MT16 architecture targets still higher density. These changes reflect the transition from 100G and 400G networks toward 800G and 1.6T optical links in AI clusters.
Commercial value extends beyond the connector body because customers need trunks, cassettes, adapters, polarity management, inspection tools and field-cleaning processes. Data-center operators favor solutions that minimize installation errors and speed moves, adds and changes. Suppliers therefore compete through complete high-density connectivity platforms, low-loss ferrules, factory-terminated cabling and interoperability with standardized transceiver interfaces.
Segment Analysis: By Type
By type, the market is segmented into single-mode and multimode connectors. Multimode currently dominates short-reach data-center installations because it pairs effectively with VCSEL-based optics, while single-mode gains share as AI scale-out links extend reach and move toward higher bandwidth. The choice depends on distance, optical architecture, module type and lifecycle cost rather than connector hardware alone.
| Type | Commercial role |
|---|---|
| Single-Mode | Longer-reach data-center, telecom and high-bandwidth interconnect using low-loss single-mode fiber. |
| Multimode | High-volume short-reach connectivity for data centers and enterprise networks. |
Additional Segmentation: By Connector Type
Connector architecture separates MPO, MTP and emerging compact multi-fiber interfaces. MPO remains the broad standards base, MTP represents a high-performance implementation used in many hyperscale deployments, and newer interfaces reduce footprint for AI transceivers. Buyers balance compatibility with installed infrastructure against the density advantages of newer ferrule formats. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Connector Type | Demand characteristics |
|---|---|
| MPO | Industry-standard multi-fiber push-on interface used across data centers and telecom. |
| MTP | High-performance MPO-compatible implementation with precision ferrule and housing features. |
| Other Multi-Fiber Interfaces | Compact formats such as SN-MT and specialized transceiver interfaces. |
Segment Analysis: By Application
By application, data centers are the largest market because leaf-spine fabrics and AI clusters require dense parallel optical links. Telecommunications uses multi-fiber connectivity in transport, access and mobile infrastructure, while aerospace and military systems value compact high-fiber-count interconnect. Other uses include enterprise, medical and industrial optical systems. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Application | Demand characteristics |
|---|---|
| Data Centers | High-density trunks, switch fabrics and 400G/800G/1.6T connectivity. |
| Telecommunications | Metro, access, central office and mobile-network optical infrastructure. |
| Aerospace & Military | Compact rugged multi-channel optical connections. |
| Others | Enterprise, medical, industrial and research networks. |
Additional Segmentation: By End User
End-user segmentation highlights how IT and telecom dominate deployment volume, while healthcare, manufacturing and BFSI use multi-fiber systems in data centers or specialized optical networks. Requirements differ by uptime, cleanliness, ruggedness and installation skill, making pre-terminated solutions especially attractive in large enterprise and hyperscale projects. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| End User | Commercial relevance |
|---|---|
| IT & Telecom | Largest user group across cloud, carrier and enterprise network infrastructure. |
| Healthcare | Hospital data centers, imaging and specialized optical systems. |
| Manufacturing | Industrial networks and automation backbones. |
| BFSI | High-availability data centers and low-latency enterprise connectivity. |
| Others | Government, research, education and specialized facilities. |
Regional Analysis
Asia Pacific leads with roughly 42% of current demand in the underlying market evidence, while North America remains a major high-value user of AI and hyperscale connectivity. Europe has mature cloud and telecom infrastructure, and other regions expand through fiber and data-center investment. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Why does regional demand differ across the Multi-Fiber Connector market?
Regional demand depends on data-center construction, optical-module production and telecom fiber deployment. Asia Pacific combines all three, North America drives early high-speed adoption, and Europe emphasizes standards and energy-efficient data centers. South America and the Middle East & Africa remain smaller but benefit from new cloud regions and backbone projects. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Region | Position | Demand profile | Supplier-selection factor |
|---|---|---|---|
| Asia Pacific | Largest / fastest | Data centers, telecom, manufacturing | Scale and local optical supply |
| North America | High-value | AI and hyperscale data centers | Early 800G adoption |
| Europe | Mature | Cloud, telecom, enterprise | Standards and reliability |
| South America | Emerging | Cloud and telecom | Fiber expansion |
| Middle East & Africa | Emerging | Data centers and telecom | Greenfield digital infrastructure |
Competitive Landscape
US Conec, SENKO Advanced Components, Amphenol, Sumitomo Electric, Siemon and T&S Communications compete through ferrule precision, insertion loss, connector density and ecosystem breadth. Large customers increasingly require complete pre-terminated systems rather than stand-alone connectors, favoring vendors with cable assembly, adapter and inspection portfolios. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
SENKO’s 2026 OFC portfolio highlights the market’s shift toward 800G and 1.6T, with EZ-Way MPO products for dual-transceiver interfaces and SN-MT16 for higher-density AI clusters. The competitive frontier is moving from basic MPO compatibility toward lower loss and smaller footprints. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Chinese and other Asian suppliers remain important in high-volume assembly, while established U.S., Japanese and European vendors retain strength in premium ferrules, standards participation and hyperscale qualification. Supplier choice therefore combines price, optical loss, capacity and field-installation reliability. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Competitive tier | Representative companies | Primary differentiation |
|---|---|---|
| Global high-performance leaders | US Conec, SENKO, Amphenol | Low-loss ferrules, dense interfaces and hyperscale qualification. |
| Integrated fiber suppliers | Sumitomo Electric, Siemon | Connector, cable and structured-cabling portfolios. |
| Regional high-volume suppliers | T&S Communications and Asian specialists | Cost-competitive MPO assemblies and local manufacturing. |
Key companies profiled
US Conec, SENKO Advanced Components, Amphenol, Sumitomo Electric, Siemon, T&S Communications, Suzhou Agix Optical and other multi-fiber connectivity suppliers are included in the competitive scope. Their positions differ by ferrule technology, connector family, fiber count and regional manufacturing scale. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Production Capacity Analysis
Capacity depends on precision ferrule molding, fiber-array assembly, polishing, inspection and cable termination. Low-loss multi-fiber products require tight hole geometry and end-face control across every fiber, so yield can fall sharply as fiber count rises. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Factory-terminated cable assemblies are increasingly important because hyperscale deployments demand repeatable loss and polarity at large scale. Suppliers therefore invest in automated polishing, interferometry and optical test as much as in connector-body molding. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Dynamics
The market is driven by hyperscale data centers, AI clusters, 5G transport and the need for higher fiber density. Growth is restrained by contamination sensitivity, polarity complexity and competition from new connector formats. High-density AI fabrics and 1.6T transceivers provide the strongest opportunity for premium low-loss products. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Drivers
| Driver | Impact | Commercial mechanism |
|---|---|---|
| AI data centers | High | More optical links per rack require dense multi-fiber connectivity. |
| 800G and 1.6T migration | High | Higher-speed transceivers use more parallel optical lanes. |
| 5G and telecom modernization | Medium-High | Dense fiber is needed in transport and central-office systems. |
| Pre-terminated deployment | Medium | Factory-tested assemblies reduce field labor and polarity errors. |
AI data centers
AI clusters connect thousands of accelerators and switches, sharply increasing fiber counts. Multi-fiber connectors reduce rack space and installation time compared with individual duplex links. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
800G and 1.6T migration
New pluggables increasingly use dual-MPO or related multi-fiber interfaces. This raises demand for precision ferrules and lower insertion loss. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
5G and telecom modernization
Carrier upgrades add parallel fiber trunks and higher port density, supporting standardized MPO assemblies. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Pre-terminated deployment
Hyperscale operators favor factory-built trunks and cassettes because they can be installed quickly and tested before shipment. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Market Restraints
| Restraint | Impact | Commercial consequence |
|---|---|---|
| Contamination sensitivity | High | Dust on one ferrule can affect several optical channels. |
| Polarity complexity | Medium-High | Multiple fiber maps can create installation errors. |
| Standards fragmentation | Medium | New formats compete with established MPO ecosystems. |
| Price pressure | Medium | High-volume assemblies face aggressive cost reduction. |
Contamination sensitivity
Multi-fiber end faces have many closely spaced fibers, making inspection and cleaning essential. Field handling can therefore affect reliability. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Polarity complexity
MPO systems use different polarity methods and key orientations. Incorrect planning can delay commissioning and require rework. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Standards fragmentation
Compact alternatives improve density but create interoperability and inventory questions for network operators. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Price pressure
As 400G and 800G become mainstream, connector suppliers must improve automation and yield to defend margins. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Market Opportunities
AI cluster trunks
High-fiber-count low-loss trunks can capture premium demand in dense accelerator fabrics. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
1.6T transceiver interfaces
Dual-MPO and next-generation ferrules create new high-density connector opportunities. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Compact multi-fiber formats
Smaller interfaces such as SN-MT can reduce panel footprint beyond conventional MPO. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Automated inspection
Machine-vision inspection and cleaning systems can improve deployment reliability and reduce field failures. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Supply Chain Analysis
Components. Ceramic or polymer ferrules, optical fiber, springs, housings and alignment hardware form the connector platform. Precision hole geometry determines fiber alignment and insertion loss. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Assembly. Fibers are inserted, bonded, cleaved and polished as an array. End-face geometry is inspected using interferometry, and insertion loss is measured before shipment. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
System integration. Connectors are incorporated into trunks, cassettes, transceivers and patch panels with defined polarity. Factory pre-termination reduces field labor and error risk. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Deployment. Network teams inspect and clean end faces before mating. Monitoring and disciplined handling are essential because contamination can affect multiple fibers simultaneously. Commercial decisions in the Multi-Fiber Connector market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Recent Developments in the Multi-Fiber Connector Market
Developments tracked through September 2026 and limited to events that materially affect technology, capacity, adoption or competition.
- OFC 2026
SENKO highlighted SN-MT16 and optimized MPO solutions for AI clusters, including connectors designed for 800G dual-transceiver configurations and higher-density unified-mesh architectures. Source - 2026 Product Portfolio
SENKO’s MPO-PLUS EZ-Way connector supports low-loss 12-, 16-, 24- and 32-fiber options and is positioned for 800G dual-MPO transceivers. Source - 2026 High-Density Adapter
SENKO’s MT-MPO low-profile adapter supports 400G, 800G and 1.6T transceiver applications in QSFP-DD, OSFP and OSFP-XD interfaces. Source
Report Scope & Segmentation
| Attribute | Scope |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| 2025 market size | USD 853.58 million |
| 2026 estimated size | USD 959.94 million |
| 2034 projected size | USD 2.46 billion |
| CAGR (2026–2034) | 12.5% |
| Largest market in 2025 | Asia Pacific |
| By Type | Single-Mode; Multimode |
| By Application | Data Centers; Telecommunications; Aerospace & Military; Others |
| By Connector Type | MPO; MTP; Other Multi-Fiber Interfaces |
| By End User | IT & Telecom; Healthcare; Manufacturing; BFSI; Others |
| Companies profiled | US Conec; SENKO; Amphenol; Sumitomo Electric; Siemon; T&S Communications; Suzhou Agix Optical |
Frequently Asked Questions
What is the multi-fiber connector market size in 2025?
The global market is valued at USD 853.58 million in 2025.
What is the market forecast for 2034?
The market is projected to reach USD 2.46 billion by 2034, representing a 12.5% CAGR during 2026–2034. The 2026 level is USD 959.94 million.
Which region leads the market?
Asia Pacific is the largest and fastest-growth region, supported by data-center expansion and optical-component manufacturing.
Which fiber type is largest?
Multimode remains the largest current type for short-reach data-center connectivity, while single-mode gains with longer-reach AI fabrics.
Which application is largest?
Data centers are the largest application and account for more than 44% of demand in the underlying market evidence.
What connector types are most important?
MPO and MTP dominate, while compact next-generation multi-fiber formats are emerging for higher-density AI systems.
Who are the major suppliers?
US Conec, SENKO, Amphenol, Sumitomo Electric, Siemon and T&S Communications are important suppliers.
What drives growth?
AI data centers, 800G and 1.6T migration, 5G transport and pre-terminated fiber deployments drive growth.
What limits adoption?
Contamination sensitivity, polarity complexity, standards fragmentation and pricing pressure are the main restraints.
What will shape the market through 2034?
Higher fiber counts, lower-loss ferrules and compact interfaces for AI clusters will shape the market.
Research Sources & Evidence Base
View research sources used in this market overview
- SENKO Advanced Components — OFC 2026 Multi-Fiber Solutions. Current AI-cluster, 800G and SN-MT multi-fiber connectivity evidence.
- SENKO Advanced Components — MPO-PLUS EZ-Way Connector. Fiber-count, insertion-loss and 800G interface evidence.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF