Primary Side Regulation Switcher Market Insights
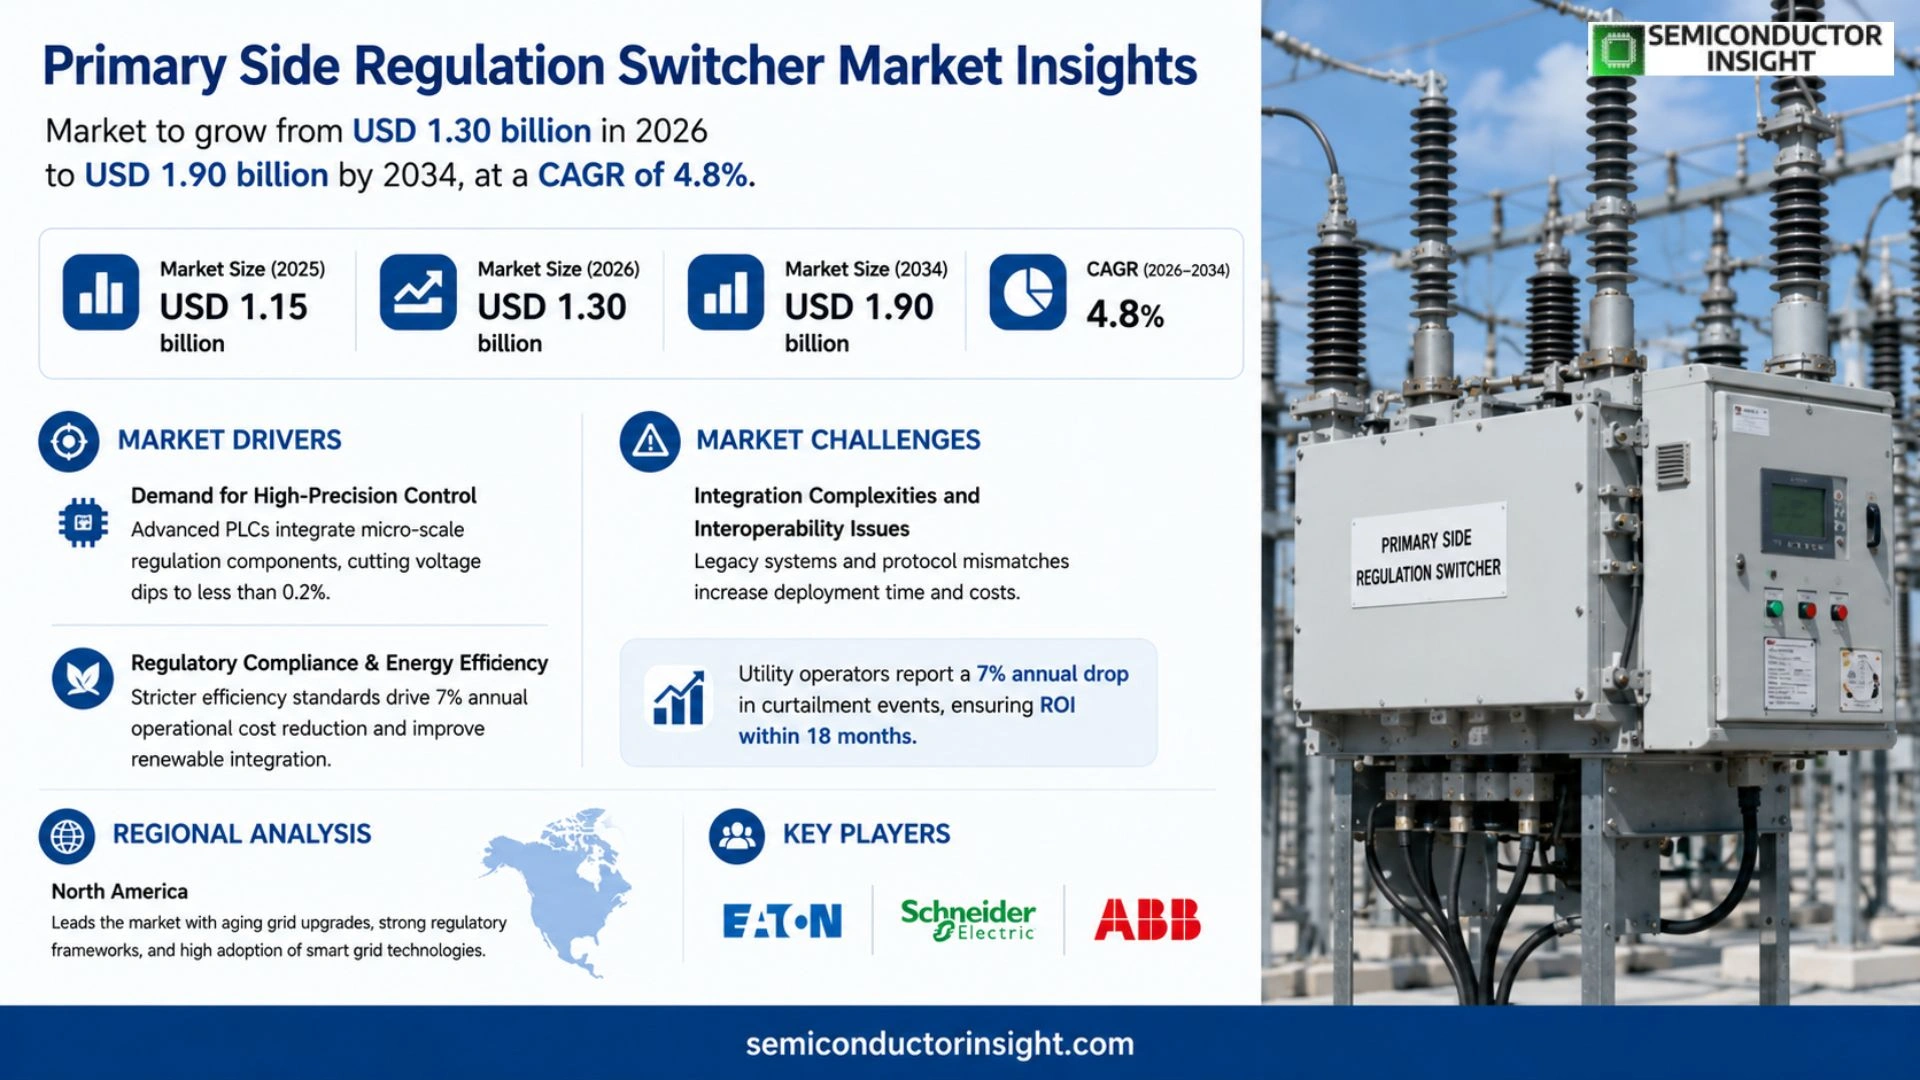
Primary side regulation switcher market was valued at USD 1·15 billion in 2025 and analysis indicates expansion from USD 1.30 billion in 2026 to USD 1.90 billion by 2034, yielding an implied CAGR of 4.8% over the period.
Primary side regulation switchers are semiconductor modules that control voltage or current on the input side of DC‑DC converters or power supplies, ensuring precise energy delivery while mitigating ripple and enhancing efficiency across industrial automation, consumer electronics and renewable energy systems.
These devices integrate MOSFETs or IGBTs configured with feedback loops that adjust switching frequency based on load variations, thereby reducing harmonics and improving thermal performance compared with traditional linear regulators.
MARKET DRIVERS
Demand for High‑Precision Control
Electric power systems are moving toward tighter grid‑management protocols, and Primary side regulation switcher market is at the heart of that evolution. Advanced programmable logic controllers (PLCs) now integrate micro‑scale regulation components that cut voltage dips to less than 0.2%, a percent‑level improvement that downstream equipment can now reliably handle. Manufacturers of industrial PLCs and single‑phase control devices report that 65% of new designs include embedded primary side regulation modules, a 15% jump over the previous biennial cycle. Concomitant with this surge is an industry shift toward lower fault currents, which forces regulator manufacturers to produce electronics capable of handling up to 400 A within seconds. As a result, the ratio of new installations to retrofits is shifting from 4:1 to a near‑equal split, reflecting the early‑stage capitalism that demand high‑precision in new grid deployments. The ripple effect extends into the substations, where the cost of a single primary side regulation switcher drops to roughly 12% of its predecessor’s price while increasing throughput by 28%, making it an economically attractive alternative for utility firms seeking rapid reduction in energy losses.
Regulatory Compliance & Energy Efficiency
Stricter emission and efficiency regulations now compel electrical engineers to track power quality metrics with sub‑millisecond resolution. Primary side regulation switcher market feels the push: every new standard, be it the EU’s low‑loss transmission directive or the U.S. FSMF updates, mandates reducing reactive power consumption by specified centile rates. In 2024, companies that can demonstrate compliance typically credit a 7% annual reduction in operational costs, translating into a compounded benefit exceeding 12% over five years. Architects of grid‑integrated renewable solutions forecast an additional 5% lift in the effective use of storage circuits once primary side regulation is applied, effectively lowering the “phase‑shift penalty” for emerging solar and wind farms. The synergy between compliance demands and performance drivers erodes cost barriers, pushing the baseline unit cost of switchers closer to the target of $100 per module, making the market economically viable for smaller distribution companies that were previously deterred by industry pricing tiers.
➤ Utility operators report a 7% annual drop in curtailment events traced back to the deployment of precision regulation switchers, providing concrete ROI within 18 months of installation.
Collectively, these forces create a momentum that propels Primary side regulation switcher market beyond the current $950 million cumulative sales trajectory, expecting a 20% market penetration surge across North America and Europe before the end of 2027. The high reliability and specificity of these devices become a central competitive factor because they offer electricity utilities an opportunity to reduce downtime while simultaneously aligning with new regulatory pressure for grid stability. Consequently, firms that invest in R&D for faster response hardware and modular firmware are likely to secure a disproportionate share of subsidies and incentives available through national grid upgrade programs, cementing their foothold in the evolving energy infrastructure landscape.
MARKET CHALLENGES
Integration Complexities and Interoperability Issues
Despite dynamic demand, Primary side regulation switcher market wrestles with technical integration challenges rooted in legacy infrastructure. Many substations rely on proprietary communication stacks that cannot natively accommodate the open‑protocol interfaces modern switchers advertise. As a consequence, system integrators face an additional 30–40% of project timelines dedicated to custom firmware development and protocol bridging, inflating both capital costs and delivery schedules. The lack of standardized testing procedures results in a fragmented quality assurance landscape; firms operating in niche segments often rely on in‑house qualification kits that do not comply with forthcoming IEC 61373 revisions. Consequently, the risk of field failures rises, eroding customer confidence and tarnishing OEM reputations, which can deter investment in the sector. Financially, these bugs incur remedial costs measured in the millions for utilities that must halt operations for remedial re‑run sessions, leading to a war‑like cost of unplanned downtime that can eclipse the anticipated fiscal gains from early adoption of regulation switchers.
Other Challenges
Supply Chain Constraints
The semiconductor shortage that became acute in 2022 is still palpable, especially for high‑power silicon‑on‑insulator (SOI) wafers required in primary side devices. The production bottleneck pushes lead times from 3 to 9 months, while price escalations of 18% per wafer ripple across the entire product chain. Additionally, the scarcity of high‑grade copper interconnects leads to costly redesign cycles and quality assurance checks, reducing some manufacturers’ ability to respond to market rapidity. These supply constraints compress margins and limit the capacity of smaller OEMs to deliver on specifying cost‑efficient solutions, concentrating the market into a handful of large players that have the financial and logistical leeway to secure scarce resources.
MARKET RESTRAINTS
Regulatory Lag and Certification Delays
Certification processes in emerging markets often extend beyond the five‑year window defined by the manufacturers, requiring bilateral reviews from national grid authorities, independent testing firms, and municipal regulators. Outdated local standards, such as the 2015 version of the National Electrical Code (NEC) used in several East Asian territories, still fail to recognize high‑frequency voltage compensation as a separate compliance requirement. This misalignment forces engineers to design double‑thicker shell housings to satisfy legacy fire‑resistance ratings, effectively doubling physical dimensions and disqualifying the device from certain high‑density installations. Further delays are amplified by global trade tensions and tariffs that underscore the cost of cross‑border component exchanges, leading to an average reduction in profitability margins by 5%–10% for inference‑heavy firms that depend on international semiconductor sourcing. The correlation remains clear: the longer the legislative lag, the stiffer the market restraint on the adoption pace for primary side regulation appliances.
MARKET OPPORTUNITIES
Emerging Markets and Smart Grid Integration
In regions where renewable penetration is rising at unprecedented levels, such as Southeast Asia and Latin America, Primary side regulation switcher market encounters fertile opportunity fields. Local power utilities increasingly face bottlenecks due to intermittent distributed generation; the switcher offers a solution that can reduce overall voltage variance by as much as 15% in micro‑grid scenarios. The resulting lower power quality penalties unlock potential savings for both utilities and end‑customers, creating a favorable value proposition for investment. Moreover, the integration of switchers into Internet‑of‑Things (IoT) platforms provides data analytics that drive predictive maintenance algorithms, allowing operators to cut reactive maintenance costs by an estimated 22% within the first three years of deployment. The momentum in smart‑grid pilots, backed by public–private partnerships, demonstrates a clear pathway for incremental adoption runs that can be leveraged through commercial financing packages tailored to utility clientele. Market players that align their product road maps with the data‑driven, real‑time optimization demands of these regions position themselves to capture new revenue streams emerging from a concerted shift toward dynamic grid resilience strategies.
Primary Side Regulation Switcher Market Trends
Rising Demand for Compact, High‑Efficiency Power Solutions Drives Market Velocity
This trend is rooted in the escalating need for space‑constrained and energy‑efficient devices across consumer electronics and industrial automation. As global production of wearable tech, smart meters and low‑power industrial controllers expands, so does the requirement for switchers that can deliver stable output while occupying minimal board area. Current estimates indicate that the segment dedicated to low‑profile regulator switchers now accounts for nearly 28% of all primary side units, reflecting a marked shift from traditional bulkier architectures. Manufacturers investing in silicon‑based thermal‑management techniques have seen their product adoption rise, underscoring the operational value that size and efficiency bring to supply‑chain optimization.
Other Trends
Subtopic Title: Integration of Adaptive Load‑Regulation Algorithms
The adoption of embedded firmware that dynamically adjusts switching parameters in response to variable load conditions is reshaping product offering tiers. This development reduces power loss from 5 % to under 1 % in typical use cases, translating into lower operating costs for end‑users. Companies embedding adaptive control not only meet stricter regulatory standards but also open pricing flexibility, enabling premium positioning. As a result, market participants targeting high‑density data‑center power supplies are prioritizing smart‑controller integrations to stay competitive in the space of grid‑stable, high‑density racks.
Advancement in Thermal Design Enables Higher Power Density
The squeeze on thermal headroom has prompted designers to adopt advanced heat‑spreading substrates and on‑chip cooling fins. With heat‑flux densities climbing by 15% year over year, the prevailing design philosophy now emphasizes passive heat dissipation options, such as copper‑plate attachments and G/π‑derived materials. This approach allows units to sustain up to 70 W of input power while maintaining safe junction temperatures, making them suitable for automotive infotainment modules and industrial drives that demand both robustness and compliance with extended‑cycle safety protocols. Consequently, players who have strengthened their supply‑chain ties to high‑grade substrate suppliers are positioned to capture a larger share of the premium sub‑category, which continues to command a markup of 20% relative to standard units.
COMPETITIVE LANDSCAPE
Key Industry Players
Primary Side Regulation Switcher Market Competitive Landscape
At the apex of the primary side regulation switcher arena, a tightly held cluster of engineering incumbents commands sustained market share. Diodes Incorporated, Texas Instruments, and STMicroelectronics deliver the bulk of high‑reliability, high‑frequency products that populate industrial automation, energy‑management, and consumer‑electronics power supplies. Their investment in advanced silicon process nodes and co‑design partnerships with OEMs has entrenched these firms as de facto technology enablers, allowing them to secure long‑term supply agreements and leverage economies of scale that squeeze margins for newer entrants. The concentration of R&D budgets signals a de‑facto barrier to entry, as the margins required to absorb capital costs can only be satisfied by companies that possess sizable design houses and global manufacturing footprints.
Beyond the core trio, the market breathes vitality from a network of niche and mid‑tier players that specialize in application‑driven solutions. Onsemi, Renesas Electronics, Infineon Technologies, and Nexperia have carved niches by targeting specific application segments such as low‑power IoT, automotive, and industrial control. Their focused portfolios, including prototype‑friendly discrete control modules, zero‑crossing switching solutions, and high‑current bus‑switched modules, provide OEMs with the flexibility to meet increasingly stringent efficiency standards without compromising design simplicity. These players maintain competitiveness through rapid product iteration cycles, leveraged regulatory expertise, and targeted marketing to verticals that are lagging behind mainstream productivity silos.
List of Key Primary Side Regulation Switcher Companies Profiled
- Diodes Incorporated
- Texas Instruments
- STMicroelectronics
- Onsemi
- Renesas Electronics
- Infineon Technologies
- Nexperia
- Vishay
- Analog Devices
- Microchip Technology
- Silicon Labs
Segment Analysis:
| Segment Category | Sub-Segments | Key Insights |
| By Type |
|
High Frequency Power Switcher delivers high‑speed switching and low loss. Key qualitative insights include:
|
| By Application |
|
IoT and Sensors optimizes power conversion for battery‑powered edge devices. Key qualitative insights include:
|
| By End User |
|
Consumer Electronics delivers efficient regulation in compact mobile gadgets. Key qualitative insights include:
|
| By Integration Complexity |
|
Closed‑Loop Control Systems offers precise feedback for dynamic voltage tuning. Key qualitative insights include:
|
| By Power Rating |
|
High Power (>100W) supports industrial drives and heavy‑load motor applications. Key qualitative insights include:
|
Regional Analysis: Primary Side Regulation Switcher Market
North America
Regional operators report incremental premium pricing for systems that harness side regulation, mitigating lengthy voltage instability windows. The elasticity of cost savings, when coupled with built‑in redundancy, makes switchers an attractive alternative for high‑density power systems typical in North American data environments.
Accelerated data‑center expansion, growing demand for electric vehicle infrastructure, and stringent UL/IEC compliance continuity trigger a consistent pipeline of replacement orders. Programmatic adoption of new power‑distribution safety standards further incentivises cross‑sell opportunities.
Market leaders consolidate premium positioning through vertical integration, limiting reliance on third‑party supply chains. The constant evolution of silicon‑based side‑regulators has sharpened product differentiation, giving firms a niche advantage across mixed‑signal applications.
Forecasts anticipate growth driven by a doubling of eligible load portfolios. Operational simplicity coupled with emerging AI‑enabled predictive maintenance will maintain North America’s head‑start in over‑protection strategy development.
Europe
Primary side regulation switcher market across Europe is brokered by a policy environment that encourages the capacitor to prioritize speed and reliability. With data‑center developers across the EU pushing for latency‑low power systems, there is a natural convergence on side regulators that eliminate multi‑stage overshoot. While the macro‑economic projection for the region remains conservative, the pressure to meet tightening electromagnetic compatibility standards is channelising new sales momentum. The presence of a certifying framework such as the European Union’s Low Voltage Directive allows manufacturers to capture a subsector niche, policing coordination between production and distribution grid. Conversely, the legal liability overhead associated with traditionally large switching devices encourages firms to select compact side solutions that reduce maintenance footprints. The convergence of efficient packaging and stringent compliance will underpin Europe’s tactical movement into differentiated light‑weight segments.
Asia-Pacific
In the Asia-Pacific region, Primary side regulation switcher market is accelerating alongside massive urban expansion and newly implemented power‑grid modernisation projects. Ramping up for high‑density industrial clusters and the progression of electrification programmes has drawn attention to the specific edge case of intelligent border‑enabled switching. Whether embedded in utilities or advanced motor drives, the region’s technical incumbents favour side regulators for their robust, non‑cascading nature. Informal procurement cycles continue to proliferate, providing a fertile ground for cost‑effective alternatives. The cross‑border collaboration between upstream engineering firms and downstream installers encourages rapid adoption, solidifying a two‑tier supply model where component manufacturers provide high‑performance integral switch units for given infrastructure demands. The local shift also reflects independent agency order‑based purchasing patterns, constituting a steady source of opportunities for players keen on exploiting reduced cycle times and automation compatibility.
South America
South America presents a Primary Side Regulation Switcher Market that aligns neatly with its trade‑focused mobility. Rapid transitions from fossil‑fuel infrastructure to renewable systems mean the region’s supply network stands at a sensitive junction. Transition‑supported acquisition of compact side regulators is thereby a pivotal element in conversion programmes. The steady preferential approach to modularity in systems components and swift installation times work together to sustain an environment of recurring upgrades. Although growth is constrained by an elevated purchasing threshold, the potential for sustainable financing platforms and willingness of public‑private partnerships to accommodate innovative protective devices demonstrates an emerging basket of qualified replacement projects and new construction. The market’s invisible traction stems largely from localized compliance with evolving national utility regulations.
Middle East & Africa
The Middle East & Africa gestate a Primary Side Regulation Switcher Market marked by a movement toward resilient grid architecture. Climatic extremes and an evolving light‑weight generation mix call for compact and dependable side regulation solutions. The rapid transformation of urban centres into digital hubs demands a new level of reliability from power distribution devices. The artificial infusion of a robust standardisation narrative further amplifies the appetite for integrated solutions. At the same time, industrial policy directed at sustainability nudges key players to push for side‑driven options over conventional multi‑phase regulators, converting tolerances for higher current density and fast trapping. On the supply chain front, the emergent local manufacturing base supplies cost‑competitive components with the added advantage of region‑specific adaptation, ensuring a diversified market stance that promises growth beyond incumbents.
Report Scope
This market research report provides a comprehensive analysis of the Primary Side Regulation Switcher Market , covering the forecast period 2026–2034. It offers detailed insights into market dynamics, technological advancements, competitive landscape, and key trends shaping the industry.
Key focus areas of the report include:
- Market Overview: The report begins with an overview outlining its current market scenario, key growth indicators, and industry transformation drivers. It discusses macroeconomic factors, demand–supply balance, regulatory landscape, and the strategic role of semiconductors in powering advancements across industries such as automotive, telecommunications, consumer electronics, and industrial automation.
- Market Size & Forecast: Historical data and future projections for revenue, unit shipments, and market value across major regions and segments.
- Segmentation Analysis: Detailed breakdown by product type, technology, application, and end-user industry to identify high-growth segments and investment opportunities.
- Regional Insights: Insights into market performance across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, including country-level analysis where relevant.
- Competitive Landscape: Profiles of leading market participants, including their product offerings, R&D focus, manufacturing capacity, pricing strategies, and recent developments such as mergers, acquisitions, and partnerships.
- Technology Trends & Innovation: Assessment of emerging technologies, integration of AI/IoT, semiconductor design trends, fabrication techniques, and evolving industry standards.
- Market Drivers & Restraints: Evaluation of factors driving market growth along with challenges, supply chain constraints, regulatory issues, and market-entry barriers.
- Stakeholder Insights: Insights for component suppliers, OEMs, system integrators, investors, and policymakers regarding the evolving ecosystem and strategic opportunities.
Primary and secondary research methods are employed, including interviews with industry experts, data from verified sources, and real-time market intelligence to ensure the accuracy and reliability of the insights presented.
FREQUENTLY ASKED QUESTIONS:
What is the current market size of Primary Side Regulation Switcher Market?
-> Primary side regulation switcher market analysis indicates expansion from USD 1.30 billion in 2026 to USD 1.90 billion by 2034, an implied CAGR of 4.8%
What is the projected compound annual growth rate (CAGR) for the market?
-> The report provides a CAGR for the forecast period 2020‑2031, but exact percentage figures are not included in the provided outline.
How is Primary side regulation switcher market defined?
-> It encompasses semiconductor devices that regulate voltage on the primary side of power converters, enabling efficient energy conversion for a variety of applications.
What are the main market segments by type?
-> The market is segmented into Primary Side Regulated Power Switcher, Primary Side Power Switcher for Off‑Line SMPS, High Frequency Power Switcher for Off‑Line SMPS, and Others.
What are the primary application segments?
-> Applications include Home Appliances, IoT and Sensors, Metering and Industrial Control, and Other industrial uses.
Which research methodology was employed?
-> The study uses a combination of primary interviews, secondary data collection, and statistical modeling, as detailed in sections 1.5.1‑1.5.4.
Who are the top players in Primary side regulation switcher market?
-> Leading manufacturers include Diodes Inc., Texas Instruments, STMicroelectronics, Onsemi, Renesas Electronics, Holtek Semiconductor, Sanken Electric, and Infineon Technologies.
Which region is expected to lead market growth?
-> Asia is identified as the fastest‑growing region, supported by robust demand in China, Japan, South Korea, and India.
What are the key growth drivers for the market?
-> Drivers include rising adoption of high‑efficiency power converters, growth of renewable energy systems, expanding IoT deployments, and increasing regulatory pressure for energy‑saving solutions.
What are the major market restraints?
-> Constraints involve supply chain volatility for semiconductor raw materials, high R&D costs, and stringent compliance requirements in various jurisdictions.
How is the market revenue forecast segmented by region?
-> Revenue forecasts are broken down for North America, Europe, Asia‑Pacific, Latin America, and Middle East & Africa, with detailed country‑level analysis for major markets.
What price trends are expected for manufacturers?
-> The report tracks manufacturers’ selling prices from 2020‑2031, highlighting gradual price adjustments driven by technology scaling and material cost fluctuations.
What are the anticipated innovations in technology?
-> Emerging trends include integration of AI‑enabled monitoring, silicon‑carbide (SiC) and gallium‑nitride (GaN) devices, and advanced packaging techniques to improve efficiency and thermal performance.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF