
Key Statistics
Key Takeaways
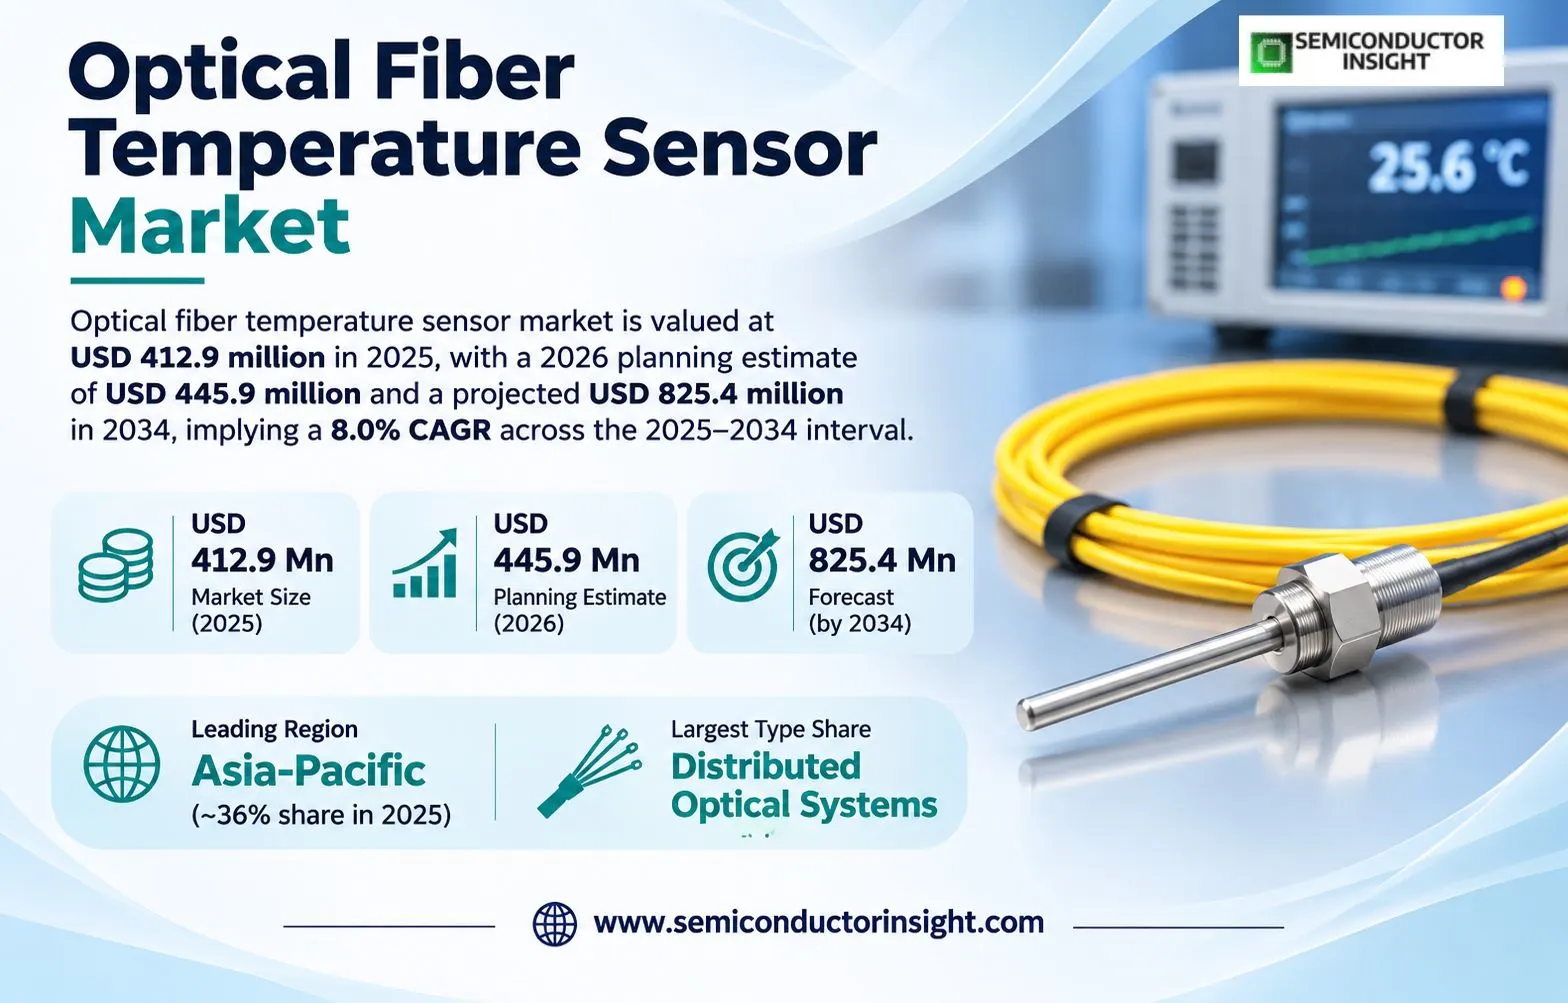
- Market trajectory: USD 412.9 million in 2025 is projected to become USD 825.4 million in 2034 at 8.0% annual growth; the 2026 planning value is USD 445.9 million. These values follow a consistent extrapolation from the publisher’s earlier dated endpoints, rather than being separately measured annual sales.
- Distributed instruments: A modeled ~55% of 2025 value comes from distributed systems because a single interrogator can read continuous cable routes; the point-sensor group retains ~45% through electrically isolated probes for machines, transformers and laboratory installations.
- Oilfield monitoring: The Oil Industry represents a modeled ~31% of 2025 revenue and has the strongest application growth at ~9.2% annually; wellbore profiles, pipeline surveillance and integrity analysis require durable sensing across locations where electrical instrumentation is difficult.
- Regional concentration: Asia-Pacific has a modeled ~36% revenue share, ahead of North America at ~29.8% and Europe at ~24%; industrial equipment production, electrical networks and new energy infrastructure create different equipment-buying cycles across these markets.
- Adoption barriers: Installation engineering, interrogator cost, calibration and system-integration requirements limit rapid substitution for inexpensive thermocouples; high-value deployments nevertheless justify optical systems when thousands of locations or hazardous electromagnetic conditions must be monitored.
Optical Fiber Temperature Sensor Market Overview
Optical fiber temperature sensor market is valued at USD 412.9 million in 2025, with a 2026 planning estimate of USD 445.9 million and a projected USD 825.4 million in 2034, implying a 8.0% CAGR across the 2025–2034 interval. Asia-Pacific leads with an estimated ~36% of base-year value, while distributed optical systems hold the largest type share.
An optical-fiber temperature sensor measures heat by interpreting changes in light travelling through or returning from a sensing fiber. Point systems read selected probes at a motor winding, transformer, furnace or research instrument; distributed systems reconstruct temperature continuously along long cables, pipelines and industrial corridors. Both approaches keep the sensing element electrically passive, an important distinction in high-voltage, high-electromagnetic-interference and explosive environments. The commercial value includes probes, interrogators, purpose-built fiber cables and equipment supplied as integrated thermal monitoring assemblies.
The revenue boundary excludes conventional thermocouples, infrared imaging cameras, generic network fiber, acoustic-only interrogators and the value of an entire power cable or oil well. A combined optical instrument is counted only to the extent that temperature monitoring is its principal marketed function, rather than treating every sensing modality or supervisory software licence as part of the same addressable market. This prevents comparisons with adjacent industrial automation revenue from overstating the demand attributable to fiber-based temperature measurement hardware.
Distributed temperature sensing, commonly called DTS, typically interrogates Raman backscatter along a sensing route, whereas fiber Bragg grating and fluorescence approaches can serve selected points or multiplexed arrays. The optical fiber may be installed during construction or retrofitted to existing assets, but mechanical protection, connector quality and calibration determine whether a laboratory capability becomes a reliable industrial system. Equipment suppliers therefore compete on field engineering, environmental certification, channel count, alarm integration and lifetime support rather than optical sensitivity alone.
The demand structure differs sharply by installation. Electricity networks need hotspot identification along buried or subsea cables and inside switchgear; oilfield operators require a continuous profile that reveals changes in flow and thermal integrity; factories monitor heat around machinery where radio-frequency interference or high voltage can distort electrical instruments. In each case, the purchasing decision compares the avoided cost of an undetected failure with the full installed price of interrogators, fiber, enclosures and commissioning.
Product specifications illustrate the variety of commercial offerings without establishing market-wide averages. Luna describes an HD6T temperature fiber available in 1–5 metre lengths with an operating range of minus 40 to 200 degrees Celsius, designed for dense thermal mapping with its ODiSI platform. At the opposite scale, Yokogawa describes DTSX3000 configurations measuring routes as long as 50 kilometres. These devices address different procurement problems, so their technical performance should not be aggregated into a single representative selling price.
The headline forecast applies the nine-interval growth rate implicit in the publisher’s 2023 value of USD 354 million and 2032 value of USD 707.65 million to the 2025–2034 framework. The resulting 2025, 2026 and 2034 values are modeled time-window conversions rather than newly published year-specific survey findings. Type, application and geographic percentages below are transparent value-weighted allocations informed by identifiable products and end uses; they should not be interpreted as audited vendor market shares.
Segment Analysis: By Type
The publisher distinguishes Dot Type Temperature Sensor and Distributed Type Temperature Sensor. The distributed class has an estimated ~55% share of 2025 revenue and an ~8.9% growth path, reflecting long routes that require costly interrogation electronics and cable integration. Dot-type instruments account for ~45% and grow at ~6.8%, with demand concentrated in equipment-level hotspots where optical isolation and repeatability outweigh the need for continuous coverage.
| Type | Technical and commercial scope | Modeled revenue trajectory and purchase logic |
|---|---|---|
| Distributed Type Temperature Sensor | DTS interrogators interpret backscatter or optical spectral changes across an installed sensing cable. Systems can cover cable routes, tunnels, process pipelines and wellbores, with software assigning thermal alarms to physical locations. Their value includes multi-channel optical equipment and ruggedized sensing cable rather than the length of unrelated telecom fiber. | Estimated ~55% in 2025 and ~8.9% CAGR. Modeled USD million path: 2025 227.1; 2026 247.3; 2027 269.3; 2028 293.3; 2029 319.4; 2030 347.8; 2031 378.8; 2032 412.5; 2033 449.2; 2034 489.2. The larger project value reflects coverage length, channel configuration, commissioning and control integration. |
| Dot Type Temperature Sensor | Fiber Bragg grating, fluorescent and other localized optical probes monitor selected hotspots in switchgear, transformer windings, electrical machines and specialist industrial test fixtures. Several probes may share an interrogator, but the thermal reading remains associated with discrete locations rather than every metre of a route. | Estimated ~45% in 2025 and ~6.81% CAGR. Modeled USD million path: 2025 185.8; 2026 198.5; 2027 212.0; 2028 226.4; 2029 241.8; 2030 258.3; 2031 275.9; 2032 294.7; 2033 314.7; 2034 336.2. Equipment designers value small probe size, galvanic isolation and qualification inside electrically noisy assemblies. |
Distributed temperature sensing for continuous assets
The distributed category captures projects where temperature must be located as well as measured. AP Sensing markets real-time thermal rating that combines DTS observations with power-cable loading history, allowing grid operators to evaluate available current capacity against thermal constraints. Bandweaver positions its T-Laser product for routes reaching 40 kilometres per channel at one-metre spatial resolution. Such specifications are product-level examples, but they explain why a utility can justify a multi-channel interrogator rather than hundreds of isolated electrical probes.
In underground infrastructure, a distributed fiber becomes a spatial coordinate system: the interrogator assigns readings to route positions, operators define alarms for cable joints or ducts, and maintenance crews investigate the segment displaying abnormal thermal behaviour. The benefit is particularly strong where access is difficult or where a failure could interrupt a high-value electrical corridor. Installation conditions, fiber splices and local heat transfer still affect measurement quality, so vendor demonstrations require application-specific acceptance tests.
Point probes for confined high-voltage equipment
Point-based optical sensors address a different design problem: one or several critical components may need accurate temperatures without placing conductive wiring in a hazardous electric field. Osensa lists a six-channel FTX-610-PWR interrogator with a ten-hertz update rate for industrial electrical monitoring, while its PRB-G20 probe covers a broader thermal range for specialized test conditions. These product examples show the value of optical isolation, not an industry-wide unit-volume ranking.
OEM adoption often begins in a new transformer, generator or switchgear platform because routing a thin fiber through insulation and protective housings is easier before equipment is sealed. Retrofit demand can still be significant at high-risk joints and busbars, but labor and outage scheduling constrain adoption. Consequently, the dot segment grows through repeat design wins and targeted replacements rather than by replacing every conventional temperature measurement on a production line.
Segment Analysis: By Application
The six publisher application categories span process industries and energy assets. The Oil Industry leads with a modeled ~31% of 2025 revenue and ~9.2% growth, followed by Metal Industry at ~19%, Glass Industry and Other at ~14% each, Food And Beverage Industry at ~12%, and Plastic Industry at ~10%. Shares describe modeled revenue from sensing equipment rather than each industry’s installed temperature sensor count.
| Application | Demand characteristics |
|---|---|
| Oil Industry | Estimated ~31% of 2025 value; USD million trajectory: 2025 128.0, 2026 139.8, 2027 152.6, 2028 166.7, 2029 182.0, 2030 198.8, 2031 217.0, 2032 237.0, 2033 258.8, 2034 282.6. Wellbores and pipelines favor ruggedized optical lines and multipoint thermal profiling; ~9.2% modeled CAGR reflects long-asset monitoring and integrity requirements. |
| Metal Industry | Estimated ~19% of base-year revenue; modeled USD million: 2025 78.5, 2026 84.0, 2027 90.0, 2028 96.4, 2029 103.2, 2030 110.5, 2031 118.4, 2032 126.8, 2033 135.8, 2034 145.4. Furnaces, casting lines and electrically intense machinery value remote readout and probe durability; the segment follows ~7.1% annual growth. |
| Glass Industry | Estimated ~14% share; modeled USD million: 2025 57.8, 2026 62.3, 2027 67.2, 2028 72.4, 2029 78.1, 2030 84.2, 2031 90.7, 2032 97.8, 2033 105.4, 2034 113.6. Continuous furnaces and heat-treatment stations require consistent thermal surveillance, with ~7.8% modeled growth tied to safety and quality investment. |
| Other | Estimated ~14% share; modeled USD million: 2025 57.8, 2026 62.2, 2027 66.9, 2028 72.0, 2029 77.5, 2030 83.3, 2031 89.7, 2032 96.5, 2033 103.8, 2034 111.7. This residual category includes power networks, transport infrastructure, laboratory thermal mapping and fire detection, but excludes purely acoustic or strain-only systems; ~7.59% annual growth. |
| Food And Beverage Industry | Estimated ~12% of 2025 value; modeled USD million: 2025 49.5, 2026 53.2, 2027 57.2, 2028 61.4, 2029 65.9, 2030 70.8, 2031 76.0, 2032 81.7, 2033 87.7, 2034 94.2. Processing plants adopt optical temperature monitoring at selected electrically challenging assets and bus ducts, producing a ~7.4% modeled CAGR. |
| Plastic Industry | Estimated ~10% share; modeled USD million: 2025 41.3, 2026 44.3, 2027 47.5, 2028 51.0, 2029 54.7, 2030 58.7, 2031 63.0, 2032 67.6, 2033 72.6, 2034 77.8. Extrusion and molding applications prioritize stable heating profiles and electrical isolation around drives; ~7.3% annual expansion is slower than energy-related applications. |
Oilfield installations use temperature as a diagnostic variable rather than merely a control input. Weatherford describes optical sensors multiplexed along a wellbore to observe production conditions, while Silixa documents combined distributed acoustic and temperature measurements for well integrity and flow profiling. The optical hardware can remain installed for extended periods in locations where conventional electronics face harsh conditions. Project revenue depends on completion design, available fiber, data interpretation requirements and whether the sensor is supplied with a broader well monitoring package.
Food processing and other manufacturing uses require careful boundary interpretation. A fiber sensor attached to a plant’s bus duct or critical motor is counted as temperature sensing equipment, even when the host plant makes beverages or packaged food. By contrast, the revenue from the factory’s process automation suite, electric drive or food product is outside the scope. This distinction matters because the technical benefit of optical measurement is often reliability in an electrical subassembly rather than direct control of the food temperature itself.
Regional Analysis
Asia-Pacific is the modeled largest regional market at ~36% of 2025 revenue, followed by North America at ~29.8%, Europe at ~24%, South America at ~6% and Middle East & Africa at ~4.2%. Differences arise from industrial asset density, power network investment, access to specialist integrators and the installed base of long pipelines and high-voltage cables. Regional forecasts are analytical allocations of the global total, not independently reported national sales figures.
How does the regional opportunity change from 2025 to 2034?
The modeled 2025 regional revenue distribution is USD 148.6 million in Asia-Pacific, USD 123.0 million in North America, USD 99.1 million in Europe, USD 24.8 million in South America and USD 17.3 million in Middle East & Africa. These values sum to the global base after rounding and correspond to shares of ~36%, ~29.8%, ~24%, ~6% and ~4.2%. The allocation weights the presence of thermal-intensive industrial assets, power infrastructure, supplier access and the ability to fund predictive maintenance.
By 2034 the same region-specific growth assumptions yield USD 322.8 million for Asia-Pacific, USD 233.9 million for North America, USD 183.7 million for Europe, USD 50.8 million for South America and USD 34.1 million for Middle East & Africa. The respective modeled growth paths are ~9.0%, ~7.4%, ~7.1%, ~8.3% and ~7.81% annually. A country with major electrical equipment manufacturing does not necessarily purchase the largest number of distributed systems, since a single long-route project can outweigh many point-probe installations.
Regional market access is shaped by engineering service coverage as much as sensor specification. Utilities may demand interoperability with existing SCADA alarms, oilfield operators require wellhead-rated deployment procedures, and industrial OEMs prioritize repeatable qualification of probes inside their machines. Buyers also evaluate whether the vendor can support fiber repair, calibration, software updates and spare interrogators locally. These practical constraints explain why nominal optical measurement performance does not automatically translate into equivalent adoption rates across countries.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest, ~36% share | ~9.0% CAGR | USD M model: 2025 148.6; 2026 162.0; 2027 176.6; 2028 192.5; 2029 209.8; 2030 228.7; 2031 249.3; 2032 271.7; 2033 296.2; 2034 322.8. | Local service networks for grid cable monitoring, industrial equipment qualification, field commissioning and high-density thermal mapping. |
| North America | Second, ~29.8% share | ~7.4% CAGR | USD M model: 2025 123.0; 2026 132.2; 2027 141.9; 2028 152.4; 2029 163.7; 2030 175.8; 2031 188.8; 2032 202.8; 2033 217.8; 2034 233.9. | Utility reliability contracts, wellbore data integration, safety standards and qualification of high-voltage instrumentation. |
| Europe | Third, ~24% share | ~7.1% CAGR | USD M model: 2025 99.1; 2026 106.1; 2027 113.7; 2028 121.7; 2029 130.4; 2030 139.6; 2031 149.6; 2032 160.2; 2033 171.5; 2034 183.7. | Industrial safety certification, retrofit compatibility, transmission corridor access and reliable maintenance arrangements. |
| South America | Emerging, ~6% share | ~8.3% CAGR | USD M model: 2025 24.8; 2026 26.8; 2027 29.1; 2028 31.5; 2029 34.1; 2030 36.9; 2031 40.0; 2032 43.3; 2033 46.9; 2034 50.8. | Mining process monitoring, pipeline operators, hydropower and cable-route economics under constrained capital budgets. |
| Middle East & Africa | Developing, ~4.2% share | ~7.81% CAGR | USD M model: 2025 17.3; 2026 18.7; 2027 20.2; 2028 21.7; 2029 23.4; 2030 25.3; 2031 27.2; 2032 29.4; 2033 31.6; 2034 34.1. | Oil and gas thermal surveillance, refinery protection, long-distance utility assets and service availability in remote environments. |
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF





