Key Statistics
Key Takeaways
- Single Channel Acquisition Module is a leading product category because it addresses the largest current application base.
- Industrial Automation is a major application, with demand shaped by performance, reliability and system integration.
- Asia Pacific leads current market value, while Asia Pacific provides the strongest growth profile.
- Edge processing, industrial ethernet and more wireless acquisition is the main technology direction influencing new design wins.
- Market size and growth: USD 111.78 million in 2025 is projected to reach USD 152.34 million by 2034 at a 3.5% CAGR during 2026–2034.
Module Acquisition Transmission Components Market Overview
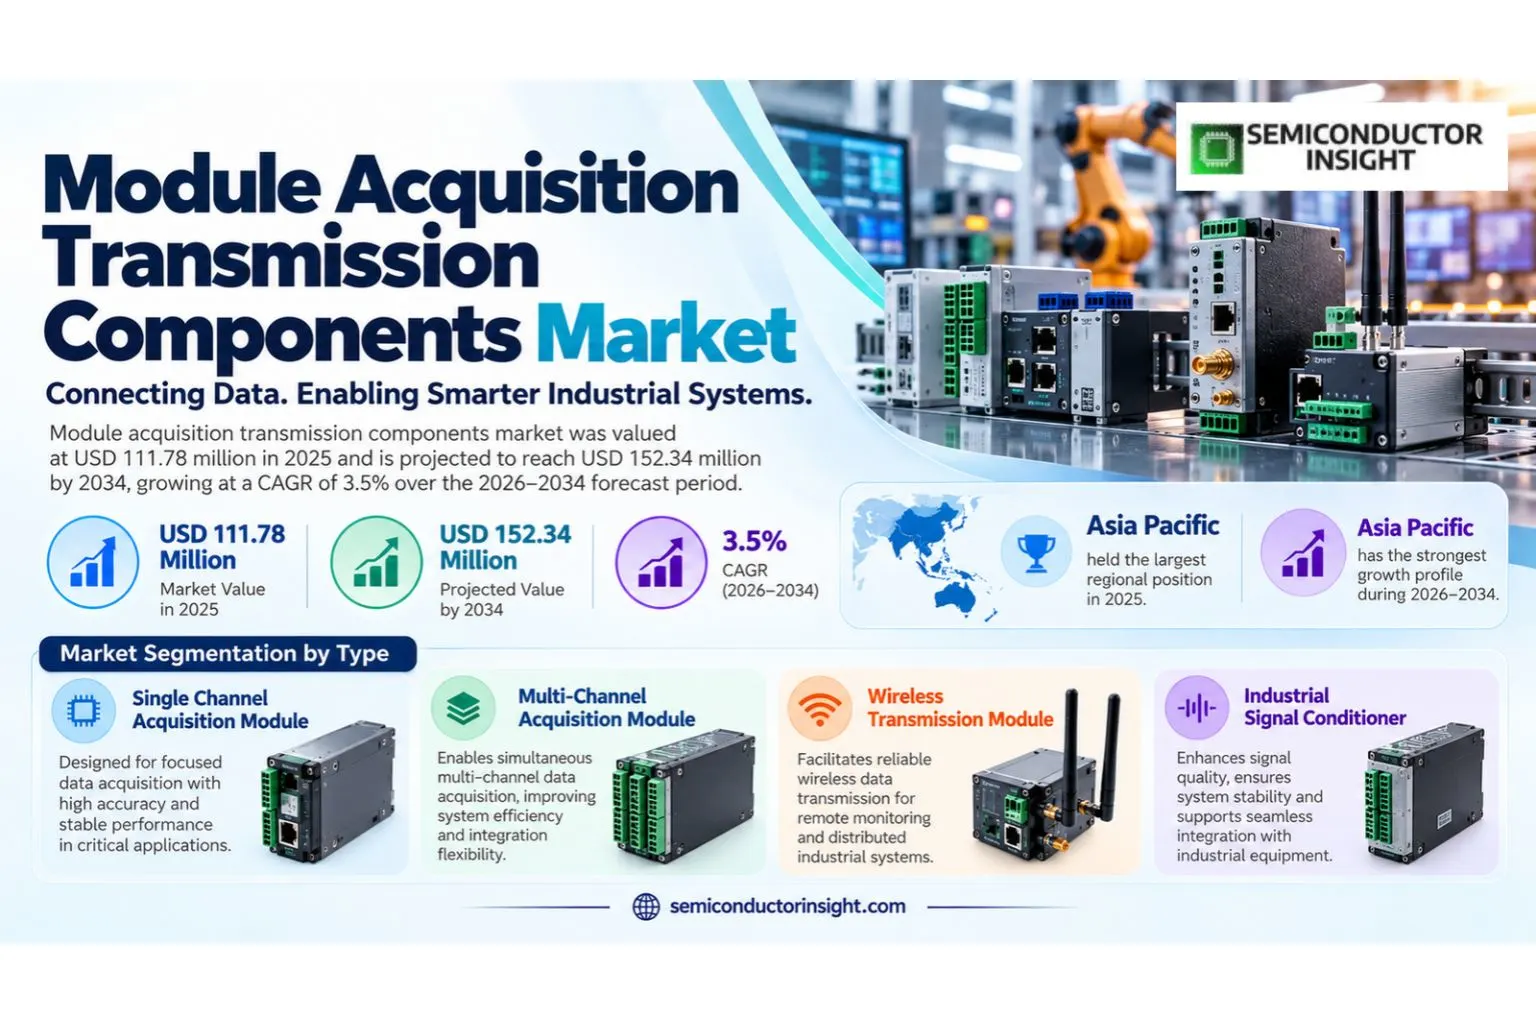
Module acquisition transmission components market was valued at USD 111.78 million in 2025 and is projected to reach USD 152.34 million by 2034, growing at a CAGR of 3.5% over the 2026–2034 forecast period. Asia Pacific held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.
Module acquisition transmission components integrate sensing, signal conditioning, conversion, processing and communications so physical measurements can be captured and sent to control or analytics systems. Commercial decisions in the Module Acquisition Transmission Components market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
The client evidence values the market at USD 108 million in 2024 and projects USD 140 million by 2032 at a 3.5% CAGR. Asia Pacific leads revenue, while industrial automation is the largest application and multi-channel acquisition modules are the leading product category. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Advantech’s current ADAM and iDAQ module families span RS-485, Ethernet, analog I/O and high-resolution isolated acquisition, illustrating the market’s shift toward remote I/O, edge connectivity and rugged industrial measurement. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Segment Analysis: By Type
By type, the module acquisition transmission components market is segmented into Single Channel Acquisition Module, Multi-Channel Acquisition Module, Wireless Transmission Module, Industrial Signal Conditioner. Each category has a distinct functional role and commercial position, so the analysis emphasizes use case, integration and competitive relevance rather than repeating a single market statistic across every row.
| Type | Function | Market position |
|---|---|---|
| Single Channel Acquisition Module | Single Channel Acquisition Module addresses a distinct architecture or performance requirement within the Module Acquisition Transmission Components market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Multi-Channel Acquisition Module | Multi-Channel Acquisition Module addresses a distinct architecture or performance requirement within the Module Acquisition Transmission Components market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Wireless Transmission Module | Wireless Transmission Module addresses a distinct architecture or performance requirement within the Module Acquisition Transmission Components market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Industrial Signal Conditioner | Industrial Signal Conditioner addresses a distinct architecture or performance requirement within the Module Acquisition Transmission Components market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
Pricing by type
Multi-channel and isolated modules command premiums through ADC performance, synchronization, isolation and embedded processing. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Segment Analysis: By Application
By application, the market is segmented into Industrial Automation, Environmental Monitoring, Medical Diagnostics, Automotive Systems. Application economics differ by qualification, lifecycle, reliability and system-level value, so each row below uses context specific to that application rather than mechanically repeating headline evidence. Commercial decisions in the Module Acquisition Transmission Components market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
| Application | Demand characteristics |
|---|---|
| Industrial Automation | Industrial Automation creates demand where module acquisition transmission components improves integration, performance, reliability or system economics. |
| Environmental Monitoring | Environmental Monitoring creates demand where module acquisition transmission components improves integration, performance, reliability or system economics. |
| Medical Diagnostics | Medical Diagnostics creates demand where module acquisition transmission components improves integration, performance, reliability or system economics. |
| Automotive Systems | Automotive Systems creates demand where module acquisition transmission components improves integration, performance, reliability or system economics. |
Regional Analysis
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile. Regional demand is shaped by manufacturing concentration, technology adoption, customer investment cycles and local supplier ecosystems. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
How does regional demand differ across the module acquisition transmission components market?
Asia Pacific provides the deepest manufacturing scale, North America contributes high-value technology and enterprise demand, and Europe remains important in industrial, automotive and regulated applications. South America and the Middle East & Africa are smaller but developing markets. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Highest | smart factories, electronics manufacturing and IIoT | Supply scale and qualification |
| North America | High | Moderate-high | industrial IoT, aerospace and advanced data acquisition | Technology capability and service |
| Europe | Moderate-high | Moderate | factory automation, energy monitoring and EMC-sensitive industrial systems | Compliance and lifecycle |
| South America | Smaller | Moderate | Import/industrial led | Cost and distribution |
| Middle East & Africa | Smallest base | Emerging | Infrastructure led | Project support |
Key Module Acquisition Transmission Components Manufacturers and Competitive Landscape
The competitive landscape includes Bosch, Infineon Technologies, STMicroelectronics, TE Connectivity, NXP Semiconductors, Advantech, Omega Engineering, Broadcom, LCM Systems, ThinkWill. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Competition centers on edge processing, industrial Ethernet and more wireless acquisition, customer qualification, manufacturing consistency and application support. Once a product is designed into a long-lifecycle system, switching costs can protect incumbent positions but also raise the importance of roadmap continuity. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Bosch, Infineon Technologies, STMicroelectronics, TE Connectivity | Global scale, broad customer qualification and advanced technology portfolios. |
| Tier 2 | NXP Semiconductors, Advantech, Omega Engineering, Broadcom | Strong specialist capability, regional design wins and application-focused portfolios. |
| Tier 3 | Regional and niche suppliers | Cost competition, customization and specialized customer support. |
Key companies profiled
- Bosch
- Infineon Technologies
- STMicroelectronics
- TE Connectivity
- NXP Semiconductors
- Advantech
- Omega Engineering
- Broadcom
- LCM Systems
- ThinkWill
Module Acquisition Transmission Components Production Capacity Analysis
Production capacity in the Module Acquisition Transmission Components market is shaped by the underlying manufacturing process, qualification burden and customer-specific configuration. Suppliers must balance equipment utilization with quality control because high-volume output only creates value when yield, reliability and traceability remain stable. Commercial decisions in the Module Acquisition Transmission Components market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Capacity additions tend to follow customer program ramps rather than headline market growth alone. Regional supply resilience is becoming more important, particularly where customers require second-source planning, long product lifecycles or shorter engineering-response times. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
The practical bottleneck is often qualified output rather than nominal installed capacity. Manufacturing, assembly, test and application support must scale together to avoid creating capacity that cannot be used in production programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Module Acquisition Transmission Components Market Dynamics: Drivers, Restraints and Opportunities
The Module Acquisition Transmission Components market is shaped by growth is driven by industry 4.0, predictive maintenance, vehicle testing, environmental sensing and medical monitoring. At the same time, growth is constrained by integration complexity, protocol fragmentation, cybersecurity requirements and component availability. The strongest commercial opportunities are concentrated in edge analytics, wireless industrial monitoring and compact multi-channel acquisition create the strongest opportunities.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Technology upgrade cycle | +1.6% | Global; strongest in leading adopter markets | Near to medium term |
| End-market expansion | +1.2% | Application-specific | Near term |
| Higher value per system | +0.8% | Premium and advanced systems | Medium term |
Technology adoption expands addressable demand
Growth is driven by Industry 4.0, predictive maintenance, vehicle testing, environmental sensing and medical monitoring. This demand is strongest where customers can measure a clear improvement in system performance, footprint, energy efficiency, reliability or operating cost. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
End-market modernization increases content per system
The technology upgrade cycle supports replacement and redesign activity as OEMs move to higher-performance architectures. New designs typically create the best opportunity because suppliers can influence specifications before qualification is locked. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Higher-value architectures support premium mix
Expanding end markets also increase content per system, creating value growth even when unit shipments grow more slowly. Suppliers that combine engineering support with reliable supply are better positioned to capture those design transitions. Commercial decisions in the Module Acquisition Transmission Components market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Qualification and integration burden | -0.7% | Global | Ongoing |
| Price and substitution pressure | -0.5% | Cost-sensitive applications | Ongoing |
| Supply-chain or process complexity | -0.4% | Global | Medium term |
Qualification burden slows supplier switching
Growth is constrained by integration complexity, protocol fragmentation, cybersecurity requirements and component availability. These constraints are most significant where customers have qualified alternatives or where the technology must prove a clear system-level advantage over lower-cost incumbent solutions. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Price competition limits margin expansion
Qualification and integration can extend sales cycles because customers must validate performance, reliability and compatibility in their own system environment. That makes early engineering engagement important for new suppliers. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Alternative technologies constrain selected use cases
Supply-chain complexity can also limit growth when specialized materials, tooling, test or regional support are required. Customers increasingly evaluate resilience alongside price when choosing long-lifecycle suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
MARKET OPPORTUNITIES
Advanced integration creates premium opportunities
Edge analytics, wireless industrial monitoring and compact multi-channel acquisition create the strongest opportunities. The most attractive opportunities are where customers are redesigning systems rather than simply replacing like-for-like components. Commercial decisions in the Module Acquisition Transmission Components market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Regional capacity and supply resilience
Edge processing, industrial ethernet and more wireless acquisition can create premium value when it lowers system complexity, improves performance or supports a new product architecture that is difficult to achieve with incumbent approaches. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Application engineering deepens customer value
Regional engineering support and application-specific customization provide another route to growth because customers increasingly expect suppliers to support qualification, transition planning and lifecycle management. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Module Acquisition Transmission Components Supply Chain Analysis
Upstream. ADCs, signal conditioners, MCUs, communication ICs, isolation devices, connectors and industrial enclosures form the supply chain. Supply quality at this stage directly affects downstream yield, reliability and cost. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Manufacturing. Core production combines process control, assembly, inspection and test, with product-specific qualification used to verify performance before customer shipment. Commercial decisions in the Module Acquisition Transmission Components market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Distribution. High-value programs are typically won through direct OEM, Tier-1 or design-house engagement, while distributors serve prototypes, regional customers and lower-volume applications. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Downstream. End users integrate the product into systems where switching costs rise after qualification, making lifecycle support and supply continuity commercially important. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Module Acquisition Transmission Components market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Downstream. Panel builders and machine OEMs are the primary specifying customers, followed by electrical contractors working on building services and by facility maintenance teams handling replacement. The specification decision is usually made once, at panel design, and then repeats for the life of the design — which makes design-in position considerably more valuable than any individual transaction.
Recent Developments in the Module Acquisition Transmission Components Market
Developments tracked through September 2026. Items are selected for direct relevance to product technology, deployment or standards. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
- 2026 Current
Advantech ADAM remote I/O Advantech’s ADAM modules provide Ethernet and RS-485 data acquisition and monitoring for harsh industrial environments. Source - 2026 Current
Advantech high-resolution iDAQ modules Advantech’s iDAQ portfolio includes isolated analog modules with up to 24-bit resolution and high-speed sampling for industrial measurements. Source - 2026 Current
DAQ interface breadth expands Modern DAQ platforms combine PCIe, USB, Ethernet and modular I/O to support industrial and laboratory systems. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2021–2025 |
| Market Size 2025 | USD 111.78 million |
| Market Size 2034 | USD 152.34 million |
| Growth Rate | CAGR of 3.5% from 2026–2034 |
| Unit | Value (USD Million) |
| Segmentation | By Type, By Application, By Component, By Connectivity, and By Region |
| By Type | Single Channel Acquisition Module · Multi-Channel Acquisition Module · Wireless Transmission Module · Industrial Signal Conditioner |
| By Application | Industrial Automation · Environmental Monitoring · Medical Diagnostics · Automotive Systems |
| By Connectivity | Ethernet · Wi-Fi · Bluetooth · Zigbee · CAN |
| By Component | ADC · Signal Conditioning · Microcontroller · Communication Interface |
| By Region | Each region analysed by Type, Application and Country North AmericaU.S., Canada, Mexico EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux AsiaChina, Japan, South Korea, India, Southeast Asia South AmericaBrazil, Argentina, Rest of South America Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA |
| Key Companies Profiled | Bosch, Infineon Technologies, STMicroelectronics, TE Connectivity, NXP Semiconductors, Advantech, Omega Engineering, Broadcom, LCM Systems, ThinkWill |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the current size of the Module Acquisition Transmission Components market?
The market is valued at USD 111.78 million in 2025 and is projected to reach USD 152.34 million by 2034, expanding at a 3.5% CAGR during 2026–2034.
Which companies lead the Module Acquisition Transmission Components market?
Key participants include Bosch, Infineon Technologies, STMicroelectronics, TE Connectivity, NXP Semiconductors, Advantech, Omega Engineering, Broadcom.
What is Module Acquisition Transmission Components?
Module acquisition transmission components integrate sensing, signal conditioning, conversion, processing and communications so physical measurements can be captured and sent to control or analytics systems.
What are the main product types?
The market includes Single Channel Acquisition Module, Multi-Channel Acquisition Module, Wireless Transmission Module, Industrial Signal Conditioner.
What are the key applications?
The principal applications are Industrial Automation, Environmental Monitoring, Medical Diagnostics, Automotive Systems.
Which region leads the market?
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile.
What drives market growth?
Growth is driven by Industry 4.0, predictive maintenance, vehicle testing, environmental sensing and medical monitoring.
What are the main challenges?
Growth is constrained by integration complexity, protocol fragmentation, cybersecurity requirements and component availability.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...