Key Statistics
Key Takeaways
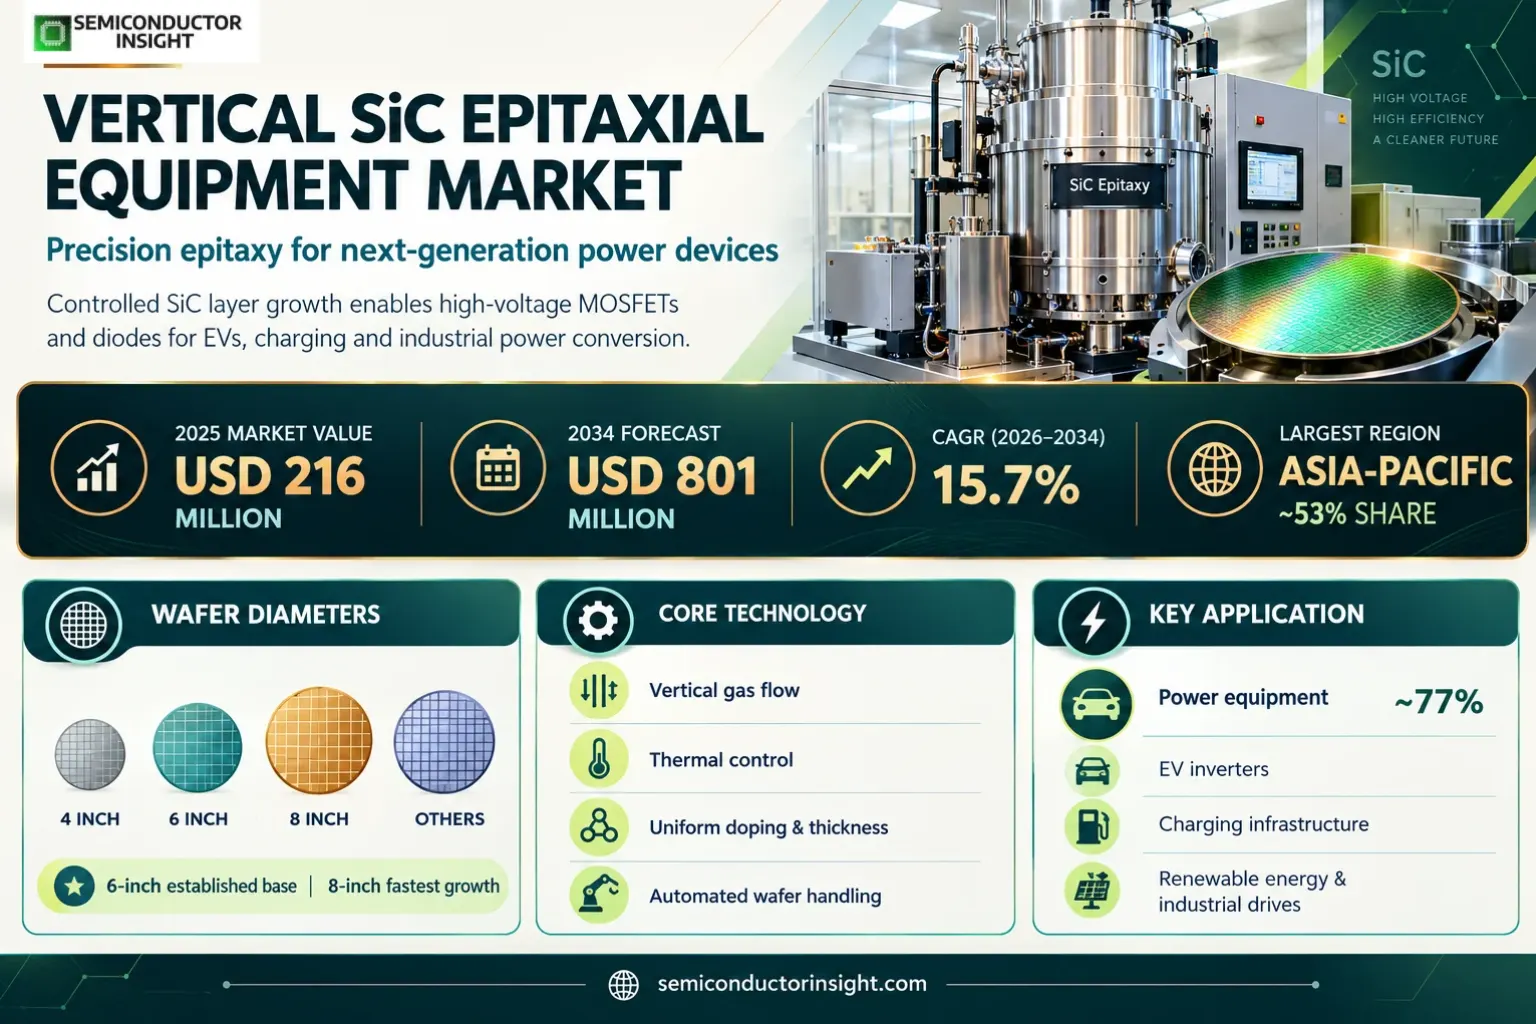
- Global value: the vertical SiC epitaxial equipment market is valued at USD 216 million in 2025 and is projected to reach USD 801 million in 2034 at a CAGR of 15.7% through 2026–2034. Capital spending follows power-semiconductor wafer capacity and the migration from established 150 millimetre platforms toward 200 millimetre production.
- 6 Inch systems account for an estimated ~43% of equipment value in 2025 because qualified six-inch wafer lines remain the most widespread commercial conversion route; eight-inch machines represent an estimated ~40% and a faster upgrading opportunity as factories weigh throughput against yield.
- Power Equipment generates an estimated ~77% of application demand because traction inverters, charging networks, solar conversion and industrial drives require thick, uniform and low-defect SiC epitaxial layers before power-device fabrication.
- Asia-Pacific represents an estimated ~53% of 2025 demand, followed by North America (~24%) and Europe (~17%). Domestic tooling suppliers in China and established Japanese equipment manufacturers influence purchasing specifications and after-sales response times.
- Qualification and capital intensity restrain new orders where high-temperature process uniformity, chamber uptime, precursor consumption and customer acceptance tests delay purchases; competition from planetary and cross-flow epitaxy configurations also complicates purchasing decisions.
Vertical SiC Epitaxial Equipment Market Overview
Vertical SiC epitaxial equipment market was valued at USD 216 million in 2025 and is forecast to reach USD 801 million by 2034, growing at a CAGR of 15.7% during 2026–2034. Asia-Pacific was the largest regional market in 2025 with an estimated ~53% share, supported by compound-semiconductor equipment production and expanding power-device manufacturing.
Vertical silicon carbide epitaxial equipment grows crystalline SiC layers on prepared substrates using controlled vertical introduction of process gases at elevated temperatures. These epitaxial films form the drift and device-active structures required for high-voltage SiC transistors and diodes. The commercial product comprises the reaction chamber, gas distribution, thermal-control, wafer-handling and machine-control subsystems needed to deliver repeatable device-grade layers, rather than merely a hot furnace or a finished wafer.
This market covers complete vertical-flow SiC epitaxial reactor systems as described by the production equipment suppliers, including integrated and split chamber configurations and tools capable of processing multiple wafer diameters. It excludes finished SiC wafers, crystal-growth furnaces, unrelated sintering or heat-treatment systems, silicon or gallium-nitride epitaxy tools, and service-only transactions. NuFlare EPIREVO equipment, SiCentury SiCCESS vertical-airflow tools and the JSG vertical SiC epitaxial furnace illustrate the product category.
Equipment economics depend on film-growth rate, within-wafer thickness and doping variation, defects, automation reliability, gas consumption and scheduled maintenance. NuFlare specifies growth above 50 micrometres per hour for its EPIREVO S6 and S8 systems, while SiCentury describes vertically distributed gases, automated wafer transfer and dual-chamber operation. Such performance attributes determine both the number of reactors a wafer factory needs and the value of process qualification and field service.
Six-inch production remains important because mature device fabs have an installed base of 150 millimetre process equipment, defect metrology and downstream fabrication recipes. Eight-inch platforms may lower the cost of acceptable epitaxial area when higher raw substrate cost, temperature gradients and yield challenges are controlled. A purchase therefore depends on factory economics rather than diameter alone, and dual-size-compatible machines must be classified by the primary process configuration bought.
Demand responds to investment in SiC MOSFETs, Schottky diodes, high-temperature devices and power modules used in vehicle inverters, charging, renewable energy conversion and industrial motor drives. The adoption of vertical-flow reactors reflects attempts to improve precursor utilisation and achieve uniform growth at commercial scale. Customer qualification and factory ramp schedules make orders uneven, even when medium-term growth in electrical efficiency applications strengthens the equipment opportunity.
Segment Analysis: By Type
By type, equipment is categorized as 4 Inch, 6 Inch, 8 Inch and Others. Six-inch equipment has an estimated ~43% of 2025 revenue, while eight-inch machines hold ~40% and expand fastest as 200 mm SiC wafer programs pursue larger production economies. Diameter reflects the principal qualifying wafer configuration at shipment, so a reactor advertised as compatible with both 6 and 8 inches is assigned to one primary class.
| Type | Function | Market position |
|---|---|---|
| 4 Inch | Legacy pilot and specialty SiC lines typically value flexibility and process transfer more than the largest wafer area. Lower capital commitments help customers trial doping profiles, new high-temperature materials and device structures before committing to wider wafers. The 4 inch configuration influences hot-zone design, substrate edge exclusion, wafer-temperature monitoring and maintenance requirements. | Estimated ~12% of 2025 revenue and ~9.0% CAGR. Legacy pilot and specialty SiC lines typically value flexibility and process transfer more than the largest wafer area. Lower capital commitments help customers trial doping profiles, new high-temperature materials and device structures before committing to wider wafers. This commercial position reflects the installed wafer diameter mix, upgrade cadence and the difficulty of achieving uniform epitaxial thickness and doping at full customer throughput. |
| 6 Inch | Six-inch epitaxy supports the established 150 mm power-device production base and multi-year qualified recipes. NuFlare S6 capability and JSG four/six-inch tools indicate continued demand for mature diameters alongside transitions toward newer eight-inch offerings. The 6 inch configuration influences hot-zone design, substrate edge exclusion, wafer-temperature monitoring and maintenance requirements. In the commercial setting of six-inch epitaxy supports the established 150 mm, nominal type-class share is an estimated ~43% in 2025. For six-inch epitaxy supports the established 150 mm, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving six-inch epitaxy supports the established 150 mm balances chamber configuration against process transfer, factory integration and longer-run upkeep. | Estimated ~43% of 2025 revenue and ~14.2% CAGR. Six-inch epitaxy supports the established 150 mm power-device production base and multi-year qualified recipes. NuFlare S6 capability and JSG four/six-inch tools indicate continued demand for mature diameters alongside transitions toward newer eight-inch offerings. This commercial position reflects the installed wafer diameter mix, upgrade cadence and the difficulty of achieving uniform epitaxial thickness and doping at full customer throughput. |
| 8 Inch | Eight-inch reactors are positioned for 200 mm cost-of-ownership improvements through higher sellable area per wafer. NuFlare S8 and SiCentury compatible vertical-airflow platforms make wafer uniformity, stable high-temperature loading and factory automation pivotal purchasing requirements. The 8 inch configuration influences hot-zone design, substrate edge exclusion, wafer-temperature monitoring and maintenance requirements. In the commercial setting of eight-inch reactors are positioned for 200 mm, nominal type-class share is an estimated ~40% in 2025. For eight-inch reactors are positioned for 200 mm, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving eight-inch reactors are positioned for 200 mm balances chamber configuration against process transfer, factory integration and longer-run upkeep. | Estimated ~40% of 2025 revenue and ~19.1% CAGR. Eight-inch reactors are positioned for 200 mm cost-of-ownership improvements through higher sellable area per wafer. NuFlare S8 and SiCentury compatible vertical-airflow platforms make wafer uniformity, stable high-temperature loading and factory automation pivotal purchasing requirements. This commercial position reflects the installed wafer diameter mix, upgrade cadence and the difficulty of achieving uniform epitaxial thickness and doping at full customer throughput. |
| Others | Other nominal configurations are associated with development platforms, nonstandard substrate diameters and conversion lines. These small-volume systems serve evaluation and specialized power-electronics research where chamber geometry and flexibility may matter more than total wafer starts. The others configuration influences hot-zone design, substrate edge exclusion, wafer-temperature monitoring and maintenance requirements. In the commercial setting of other nominal configurations are associated with development, nominal type-class share is an estimated ~5% in 2025. For other nominal configurations are associated with development, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving other nominal configurations are associated with development balances chamber configuration against process transfer, factory integration and longer-run upkeep. | Estimated ~5% of 2025 revenue and ~11.0% CAGR. Other nominal configurations are associated with development platforms, nonstandard substrate diameters and conversion lines. These small-volume systems serve evaluation and specialized power-electronics research where chamber geometry and flexibility may matter more than total wafer starts. This commercial position reflects the installed wafer diameter mix, upgrade cadence and the difficulty of achieving uniform epitaxial thickness and doping at full customer throughput. |
Segment Analysis: By Application
By application, Power Equipment leads with an estimated ~77% of 2025 value, followed by Electronics and Optoelectronics (~13%), Wireless Infrastructure (~6%) and Others (~4%). Application assignments follow the commissioning fab’s principal qualified end use, not every possible downstream use of a multipurpose substrate. In the commercial setting of by application, power equipment leads with an, commercial application decisions depend on process maturity and traceable production qualifications. For by application, power equipment leads with an, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving by application, power equipment leads with an balances chamber configuration against process transfer, factory integration and longer-run upkeep.
| Application | Demand characteristics |
|---|---|
| Power Equipment | Estimated ~77% application share. Electric-vehicle powertrains, charging infrastructure, solar inverters, grid conversion and industrial drives increase the need for reproducible SiC epitaxial wafers used in MOSFETs and diodes. Equipment value follows reactor qualification standards, process yield and production schedules rather than the shipment counts of finished systems alone. In the commercial setting of estimated ~77% application share. electric-vehicle powertrains, charging, for power equipment, customers compare substrate size, defect performance and throughput. For estimated ~77% application share. electric-vehicle powertrains, charging, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving estimated ~77% application share. electric-vehicle powertrains, charging balances chamber configuration against process transfer, factory integration and longer-run upkeep. |
| Electronics and Optoelectronics | Estimated ~13% application share. Specialty electronics and optoelectronic structures can require tailored epitaxial layer thickness, impurity control and substrate material quality rather than maximum automotive production volume. Equipment value follows reactor qualification standards, process yield and production schedules rather than the shipment counts of finished systems alone. In the commercial setting of estimated ~13% application share. specialty electronics and, for electronics and optoelectronics, customers compare substrate size, defect performance and throughput. For estimated ~13% application share. specialty electronics and, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving estimated ~13% application share. specialty electronics and balances chamber configuration against process transfer, factory integration and longer-run upkeep. |
| Wireless Infrastructure | Estimated ~6% application share. Radio and wireless electrical subsystems contain power conversion assemblies that can incorporate SiC devices, although the breadth of direct epitaxy equipment demand is smaller than automotive or industrial categories. Equipment value follows reactor qualification standards, process yield and production schedules rather than the shipment counts of finished systems alone. |
| Others | Estimated ~4% application share. Research, aerospace and niche high-temperature applications can motivate specialized SiC epitaxy tooling, including smaller lot sizes and unusual device reliability requirements. Equipment value follows reactor qualification standards, process yield and production schedules rather than the shipment counts of finished systems alone. In the commercial setting of estimated ~4% application share. research, aerospace and, for others, customers compare substrate size, defect performance and throughput. For estimated ~4% application share. research, aerospace and, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving estimated ~4% application share. research, aerospace and balances chamber configuration against process transfer, factory integration and longer-run upkeep. |
Commercial distribution remains concentrated around supplier-to-fab qualification and factory acceptance, with device manufacturers evaluating sample epitaxial wafers before releasing high-volume tool orders. System qualification can require long operating trials, wafer metrology comparisons and documented chamber-to-chamber reproducibility. In the commercial setting of commercial distribution remains concentrated around supplier-to-fab qualification, different fab maturity levels lead to staggered procurement and commissioning dates. For commercial distribution remains concentrated around supplier-to-fab qualification, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving commercial distribution remains concentrated around supplier-to-fab qualification balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Regional Analysis
Asia-Pacific is the largest regional market with an estimated ~53% share in 2025, ahead of North America at ~24% and Europe at ~17%. South America and the Middle East and Africa account for smaller estimated shares near ~3% each. The strongest growth is linked to large-volume fabrication concentration, domestic equipment programs and the conversion of SiC power device capacity to eight-inch processing.
Which regions drive investment in vertical silicon-carbide epitaxial reactors?
Regional demand depends on where power-semiconductor wafer plants commission new epitaxy process capacity, where tool suppliers provide field support, and how quickly device designs move from small-batch qualification to stable commercial output. Differences in equipment localisation and factory financing lead to materially different buying cycles. In the commercial setting of regional demand depends on where power-semiconductor wafer, the regional shares are analytical estimates calibrated against the publisher market series. For regional demand depends on where power-semiconductor wafer, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving regional demand depends on where power-semiconductor wafer balances chamber configuration against process transfer, factory integration and longer-run upkeep.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~53%) | Estimated ~17.6% CAGR | Domestic equipment portfolios and growing SiC fabricati | Process uniformity, field maintenance and localisation requirements across the Asia-Pacific fab ecosystem |
| North America | Second largest (~24%) | Estimated ~13.3% CAGR | United States power-semiconductor projects and high-rel | Process uniformity, field maintenance and localisation requirements across the North America fab ecosystem |
| Europe | Third largest (~17%) | Estimated ~13.4% CAGR | Automotive power electronics and advanced industrial ma | Process uniformity, field maintenance and localisation requirements across the Europe fab ecosystem |
| South America | Emerging (~3%) | Estimated ~12.0% CAGR | Most near-term activity relates to imported devices and | Process uniformity, field maintenance and localisation requirements across the South America fab ecosystem |
| Middle East & Africa | Early-stage (~3%) | Estimated ~12.2% CAGR | Early industrial diversification, semiconductor ecosyst | Process uniformity, field maintenance and localisation requirements across the Middle East & Africa fab ecosystem |
Competitive Landscape
NuFlare Technology, SiCentury and Jingsheng Mechanical & Electrical have product materials describing SiC epitaxial equipment with vertical-flow characteristics. Competition is shaped by reactor geometry, qualified layer uniformity, cost of ownership, service geography and the readiness of six- and eight-inch process offerings; adjacent epitaxy suppliers compete through alternative flow configurations. In the commercial setting of nuflare technology, sicentury and jingsheng mechanical &, the distinction matters because sales coverage alone cannot establish qualified installation capacity. For nuflare technology, sicentury and jingsheng mechanical &, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving nuflare technology, sicentury and jingsheng mechanical & balances chamber configuration against process transfer, factory integration and longer-run upkeep.
NuFlare markets EPIREVO S6 and S8 single-wafer SiC reactor platforms and publishes technical criteria for growth rate, film thickness uniformity and wafer-temperature performance. Demonstrated production characteristics and a clear wafer-size path are central to commercial differentiation. In the commercial setting of nuflare markets epirevo s6 and s8 single-wafer, supplier performance specifications are useful for screening but customer acceptance tests determine order placement. For nuflare markets epirevo s6 and s8 single-wafer, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving nuflare markets epirevo s6 and s8 single-wafer balances chamber configuration against process transfer, factory integration and longer-run upkeep.
SiCentury describes integrated and split SiCCESS reactors using vertical gas distribution, robotic wafer logistics and 6/8-inch compatibility. Its public specifications make throughput and process-control design differentiators, although manufacturer figures should be compared using a common production recipe and metrology standard. In the commercial setting of sicentury describes integrated and split siccess reactors, the cost of ownership depends on both acceptance yield and routine maintenance. For sicentury describes integrated and split siccess reactors, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving sicentury describes integrated and split siccess reactors balances chamber configuration against process transfer, factory integration and longer-run upkeep.
JSG includes a vertical SiC epitaxial furnace in its power-semiconductor equipment portfolio, providing an additional industrial option. Its broad materials and crystal-growth activities are separate products, so competitive positioning within the vertical epitaxy category must be confined to genuine reactor offerings. In the commercial setting of jsg includes a vertical sic epitaxial furnace, equipment breadth is not the same as market share within a specialized process tool segment. For jsg includes a vertical sic epitaxial furnace, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving jsg includes a vertical sic epitaxial furnace balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Hunan ACME appears in the market company list, while the inspected company materials primarily document sintering and thermal processing equipment. It is retained in the complete roster but excluded from the primary proven vertical-reactor supplier tier. Planetary AIXTRON and cross-flow ASM systems are technologically relevant alternatives, not direct vertical-flow examples without product-level confirmation.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | NuFlare Technology; SiCentury | Official catalogs document production-class vertical SiC epitaxial reactors, six/eight-inch technology, high-temperature process operation and wafer automation. In the commercial setting of official catalogs document production-class vertical sic epitaxial, proven product geometry is the threshold for this specialist competitive tier. For official catalogs document production-class vertical sic epitaxial, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving official catalogs document production-class vertical sic epitaxial balances chamber configuration against process transfer, factory integration and longer-run upkeep. |
| Tier 2 | JSG | Official Jingsheng equipment documentation includes a vertical SiC epitaxial furnace, with four/six-inch capability and a wider semiconductor tool portfolio. In the commercial setting of official jingsheng equipment documentation includes a vertical, qualified installation base and relative revenue allocation are separate competitive questions. For official jingsheng equipment documentation includes a vertical, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving official jingsheng equipment documentation includes a vertical balances chamber configuration against process transfer, factory integration and longer-run upkeep. |
| Tier 3 | Hunan ACME; adjacent reactor technology suppliers | The listed Hunan ACME products require confirmation of vertical SiC epitaxial configuration; planetary or cross-flow reactor suppliers provide competitive technology benchmarks. In the commercial setting of the listed hunan acme products require confirmation, this tier does not imply verified direct reactor shipments from every listed company. For the listed hunan acme products require confirmation, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving the listed hunan acme products require confirmation balances chamber configuration against process transfer, factory integration and longer-run upkeep. |
Key companies profiled
- NuFlare Technology
- SiCentury
- Hunan ACME
- JSG
Production Capacity Analysis
Installed wafer-fab throughput, reactor hot-zone reliability and growth cycle time govern output capacity in vertical SiC epitaxy. The capital-equipment production chain also requires specialist hot-wall components, precise thermal management and gas-distribution engineering, meaning nominal tool output alone cannot define economic wafer capacity. In the commercial setting of installed wafer-fab throughput, reactor hot-zone reliability and, laboratory process speeds need to translate into qualified high-volume results. For installed wafer-fab throughput, reactor hot-zone reliability and, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving installed wafer-fab throughput, reactor hot-zone reliability and balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Manufacturing capabilities are concentrated among specialist equipment companies with SiC process know-how and the ability to build stable high-temperature chambers. Japanese and Chinese suppliers participate through distinct engineering and customer qualification approaches. Buyers typically compare system uptime, measured wafer quality and the installation resources available at their own fabs. In the commercial setting of manufacturing capabilities are concentrated among specialist equipment, these factors create manufacturing scale advantages beyond the number of chambers assembled. For manufacturing capabilities are concentrated among specialist equipment, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving manufacturing capabilities are concentrated among specialist equipment balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Diversifying tool supply may shorten delivery exposure and give wafer fabs flexibility across 150 and 200 millimetre capacity. However, substituting platforms requires moving epitaxial recipes, validating film uniformity and documenting electrical performance through downstream device fabrication. The expense of qualification creates switching costs after a reactor has entered stable production. In the commercial setting of diversifying tool supply may shorten delivery exposure, this encourages multi-tool purchase patterns within already qualified platforms. For diversifying tool supply may shorten delivery exposure, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving diversifying tool supply may shorten delivery exposure balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Critical upstream constraints include corrosion-resistant process components, high-temperature heaters, precision sensors, clean gas controls, robotics and chamber materials that do not introduce contamination. Maintenance consumables, cleaning cycles and long-term dimensional stability influence usable uptime. Semiconductor customers will often favor proven yields over a marginal nominal deposition-speed advantage. In the commercial setting of critical upstream constraints include corrosion-resistant process components, field process specialists and metrology engineers are important capacity resources. For critical upstream constraints include corrosion-resistant process components, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving critical upstream constraints include corrosion-resistant process components balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Market Dynamics
The market is influenced by SiC device adoption, renewable power electronics and larger wafer fabrication capacity on one side, and substrate availability, high-temperature process qualification and capital spending cycles on the other. Growth is therefore uneven between established six-inch production lines and newer eight-inch ramps. In the commercial setting of the market is influenced by sic device, equipment adoption requires multi-disciplinary acceptance across process and device-engineering teams. For the market is influenced by sic device, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving the market is influenced by sic device balances chamber configuration against process transfer, factory integration and longer-run upkeep.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Electric-vehicle SiC inverter and powertrain applications | High | +5.20% | High | High | Medium |
| Eight-inch SiC wafer capacity transitions | High | +4.60% | Medium | High | High |
| Industrial and renewable-energy inverter requirements | Medium-High | +3.60% | High | Medium | Medium |
| Vertical-flow reactor throughput and defect reduction | Medium | +2.70% | Medium | High | High |
| Localisation of SiC fabrication equipment supply | Low-Medium | +2.00% | High | Medium | Medium |
| Others (grid storage, aerospace power, specialty diodes, process replacement) | Low | +1.40% | Low | Medium | Medium |
Vehicle electrification
SiC power devices reduce switching losses in traction inverters and onboard charging, creating demand for device-quality epitaxial layers. Epitaxial capacity is ordered only after manufacturers have established suitable substrate supply and device yields. In the commercial setting of sic power devices reduce switching losses in, automotive qualification makes process reproducibility particularly valuable. For sic power devices reduce switching losses in, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving sic power devices reduce switching losses in balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Eight-inch wafer economics
Moving from 150 millimetre to 200 millimetre substrates increases potential wafer area but can expose new temperature-uniformity and defect challenges. The EPIREVO S8 and compatible SiCCESS configurations address this migration with specialized control. In the commercial setting of moving from 150 millimetre to 200 millimetre, fab procurement decisions weigh usable die output rather than wafer diameter by itself. For moving from 150 millimetre to 200 millimetre, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving moving from 150 millimetre to 200 millimetre balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Energy conversion and industrial drives
Solar and storage inverters, wind-energy electrical systems and industrial motor control benefit from high-voltage power conversion. Their performance requirements motivate SiC MOSFET and diode fabrication, which eventually adds epitaxy reactor demand when device makers expand wafer starts. In the commercial setting of solar and storage inverters, wind-energy electrical systems, industrial cycles differ from vehicle platform launches. For solar and storage inverters, wind-energy electrical systems, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving solar and storage inverters, wind-energy electrical systems balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Process productivity
Uniform vertical gas distribution and high-temperature wafer rotation can improve precursor usage and film quality. NuFlare and SiCentury specifications emphasize growth rate, wafer temperature and thickness consistency because these measurements shape the annual qualified throughput per tool. In the commercial setting of uniform vertical gas distribution and high-temperature wafer, performance trials distinguish useful production efficiency from headline equipment speed. For uniform vertical gas distribution and high-temperature wafer, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving uniform vertical gas distribution and high-temperature wafer balances chamber configuration against process transfer, factory integration and longer-run upkeep.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| SiC wafer and epitaxy qualification delays | High | -1.70% | High | High | Medium |
| High-temperature reactor maintenance and process cost | Medium-High | -1.00% | High | Medium | Medium |
| Capital expenditure deferrals during device price pressure | Medium | -0.70% | Medium | High | Medium |
| Others (precursor supply, geometry competition, technology integration) | Low | -0.40% | Medium | Low | Medium |
Epitaxial layer qualification
Highly controlled doping and low defects are necessary for breakdown voltage and yield, so switching reactor supplier can require repeated test wafers, electrical verification and reliability characterization. These cycles can postpone equipment booking and delay conversion from pilot runs to commercial capacity. In the commercial setting of highly controlled doping and low defects are, failure analysis and acceptance criteria are central to tool procurement. For highly controlled doping and low defects are, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving highly controlled doping and low defects are balances chamber configuration against process transfer, factory integration and longer-run upkeep.
High ownership cost
A SiC epitaxy reactor needs expensive high-temperature parts, clean precursor delivery, automated wafer transfer, gas safety and field maintenance. A tool with high nominal deposition rate may still have inferior output economics if chamber cleaning and scrap are excessive. In the commercial setting of a sic epitaxy reactor needs expensive high-temperature, buyers pay attention to annual wafer cost across a full maintenance cycle. For a sic epitaxy reactor needs expensive high-temperature, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving a sic epitaxy reactor needs expensive high-temperature balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Industry capital-spending cycles
The timing of equipment orders changes as power-device manufacturers reassess automotive demand, existing inventory and wafer cost targets. A project may have attractive long-term economics while individual reactor purchases are deferred across commissioning phases. In the commercial setting of the timing of equipment orders changes as, equipment makers are exposed to timing differences between project announcements and cash orders. For the timing of equipment orders changes as, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving the timing of equipment orders changes as balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Competing reactor geometries
Planar cross-flow and planetary SiC epitaxial reactors offer alternative ways of controlling temperature, deposition uniformity and wafer throughput. NuFlare, SiCentury and JSG must differentiate vertical-flow features without treating all other reactor designs as direct comparable equipment value. In the commercial setting of planar cross-flow and planetary sic epitaxial reactors, the competitive choice depends on production recipe and installed plant infrastructure. For planar cross-flow and planetary sic epitaxial reactors, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving planar cross-flow and planetary sic epitaxial reactors balances chamber configuration against process transfer, factory integration and longer-run upkeep.
MARKET OPPORTUNITIES
200 millimetre process conversion
The opportunity to install eight-inch SiC reactors depends on maturing substrate quality and maintaining thickness and doping consistency over larger areas. Tool suppliers capable of transferring customer recipes with low scrap can expand their installed base. In the commercial setting of the opportunity to install eight-inch sic reactors, eight-inch systems can change fab floor space and automation economics. For the opportunity to install eight-inch sic reactors, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving the opportunity to install eight-inch sic reactors balances chamber configuration against process transfer, factory integration and longer-run upkeep.
After-sales engineering partnerships
Semiconductor fabs value local process specialists who can diagnose growth defects, calibrate temperature zones and coordinate spare chamber parts. New equipment wins can create longer-term qualification relationships and recurring maintenance work alongside capital tool deliveries. In the commercial setting of semiconductor fabs value local process specialists who, reliable commissioning can shorten time to usable high-volume capacity. For semiconductor fabs value local process specialists who, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving semiconductor fabs value local process specialists who balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Integrated automation
Factory interface design, cassette-to-cassette transfer and automated high-temperature wafer logistics reduce handling defects. NuFlare and SiCentury product materials indicate that automation and uptime can be differentiators independent of nominal growth rate. In the commercial setting of factory interface design, cassette-to-cassette transfer and automated, automation qualification becomes more important for multiple chambers operating without manual intervention. For factory interface design, cassette-to-cassette transfer and automated, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving factory interface design, cassette-to-cassette transfer and automated balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Domestic SiC tool ecosystems
Regional equipment programs can develop local supplier qualification, gas systems, chamber machining and maintenance skills. Such ecosystems can reduce import dependence where fabs have sufficient scale to sustain supplier development, while demanding rigorous device yield performance. In the commercial setting of regional equipment programs can develop local supplier, local supplier access can influence commercial terms after technical acceptance. For regional equipment programs can develop local supplier, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving regional equipment programs can develop local supplier balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Supply Chain Analysis
The vertical SiC epitaxy supply chain runs from chamber materials and high-purity process gas controls through specialized reactor manufacture and process integration, then to power-semiconductor wafer fabs and electrical-device customers. Unlike commodity equipment, process qualification and field engineering create substantial value at the customer interface. In the commercial setting of the vertical sic epitaxy supply chain runs, the stages have different cost structures and different technical validation requirements. For the vertical sic epitaxy supply chain runs, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving the vertical sic epitaxy supply chain runs balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Upstream. Specialist thermal and gas-control inputs must operate reproducibly at epitaxial growth temperatures without contaminating wafer surfaces. Gas purity and heated chamber stability govern downstream layer defects, making suppliers of heaters, chamber internals, metrology and transfer robotics important to equipment consistency. In the commercial setting of specialist thermal and gas-control inputs must operate, procurement teams manage spare parts and high-temperature materials together. For specialist thermal and gas-control inputs must operate, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving specialist thermal and gas-control inputs must operate balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Manufacturing. Equipment makers integrate reactor geometry, automated handling, sensors, process software and exhaust systems, then demonstrate wafer uniformity with repeatable recipes. A production-ready vertical gas-flow system needs more than nominal hot-zone capability; clean maintenance access and traceable process controls affect fab acceptance. In the commercial setting of equipment makers integrate reactor geometry, automated handling, factory testing should use representative customer substrate diameters. For equipment makers integrate reactor geometry, automated handling, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving equipment makers integrate reactor geometry, automated handling balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Distribution. Reactor systems are sold through specialist technical channels rather than broad wholesale distribution. Applications teams participate in wafer tests, qualification protocol development, commissioning and process transfer when manufacturing expands to another fab site. Supplier field-service reach can determine whether a technically acceptable product is commercially practical. In the commercial setting of reactor systems are sold through specialist technical, contract timing follows acceptance and commissioning milestones. For reactor systems are sold through specialist technical, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving reactor systems are sold through specialist technical balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Downstream. Manufacturers of SiC MOSFETs, Schottky diodes and power modules need epitaxial layers with controlled thickness, doping and defects. Their device yield and lifetime targets set the tool performance requirements passed upstream, while automotive and industrial customer qualification influences production speed and capacity expansion. In the commercial setting of manufacturers of sic mosfets, schottky diodes and, wafer fabs are the main buyers of complete epitaxial equipment. For manufacturers of sic mosfets, schottky diodes and, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving manufacturers of sic mosfets, schottky diodes and balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Vertical SiC Epitaxial Equipment Technology Developments
- Technical portfolio Published
NuFlare describes its EPIREVO S8 single-wafer reactor for eight-inch SiC wafers, with more than 50 micrometres per hour growth and two-point wafer temperature control. The larger-wafer offering matters because suppliers must combine deposition uniformity and maintainability as customers examine 200 millimetre manufacturing economics. In the commercial setting of nuflare describes its epirevo s8 single-wafer reactor, the product is documented in a manufacturer specification rather than a claimed new launch. For nuflare describes its epirevo s8 single-wafer reactor, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving nuflare describes its epirevo s8 single-wafer reactor balances chamber configuration against process transfer, factory integration and longer-run upkeep. Source - Technical portfolio Published
NuFlare specifies its EPIREVO S6 six-inch reactor with high-temperature wafer transfer, growth above 50 micrometres per hour and sub-two-percent thickness variation under stated measurement conditions. This establishes a performance reference for mature six-inch SiC production and explains continued spending on qualified 150 millimetre lines. In the commercial setting of nuflare specifies its epirevo s6 six-inch reactor, the product page documents current capabilities without assigning an unverified announcement date. For nuflare specifies its epirevo s6 six-inch reactor, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving nuflare specifies its epirevo s6 six-inch reactor balances chamber configuration against process transfer, factory integration and longer-run upkeep. Source - Technical portfolio Published
SiCentury documents an integrated SiCCESS vertical-airflow epitaxy tool compatible with six- and eight-inch SiC wafers. Its product material describes automated transfer, multi-zone gas-flow control and high growth rates, indicating a competitive emphasis on automation and stable process characteristics. In the commercial setting of sicentury documents an integrated siccess vertical-airflow epitaxy, the manufacturer specifications support a technology comparison, not a dated purchase-order claim. For sicentury documents an integrated siccess vertical-airflow epitaxy, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving sicentury documents an integrated siccess vertical-airflow epitaxy balances chamber configuration against process transfer, factory integration and longer-run upkeep. Source - Technical portfolio Published
SiCentury also presents a split vertical-flow SiC epitaxy equipment configuration, separating system functions while retaining compatibility with advanced wafer-size requirements. A split architecture can influence plant utility design, tool footprint and maintainability, especially during factory expansion or additional chamber integration. In the commercial setting of sicentury also presents a split vertical-flow sic, this documented product configuration is not described as a newly launched platform. For sicentury also presents a split vertical-flow sic, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving sicentury also presents a split vertical-flow sic balances chamber configuration against process transfer, factory integration and longer-run upkeep. Source - Technical portfolio Published
Jingsheng Mechanical and Electrical lists a vertical SiC epitaxial furnace among its power-semiconductor equipment products. The official product portfolio demonstrates an additional potential source of vertically configured reactors and provides an alternative to importing every system. In the commercial setting of jingsheng mechanical and electrical lists a vertical, the material establishes manufacturer participation without implying sales volumes or a date of commercial launch. For jingsheng mechanical and electrical lists a vertical, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving jingsheng mechanical and electrical lists a vertical balances chamber configuration against process transfer, factory integration and longer-run upkeep. Source - Technical comparison Published
ASM provides PE2O8 SiC epitaxy equipment featuring cross-flow reactor geometry. This matters for vertical-reactor positioning because competing methods target similar wafer quality and capacity objectives but should not be merged into the vertical gas-flow equipment category. In the commercial setting of asm provides pe2o8 sic epitaxy equipment featuring, the official product document supports a distinction between reactor designs rather than market-share claims. For asm provides pe2o8 sic epitaxy equipment featuring, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving asm provides pe2o8 sic epitaxy equipment featuring balances chamber configuration against process transfer, factory integration and longer-run upkeep. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2020–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2020–2024 |
| Market Size 2025 | USD 216 million |
| Market Size 2026 | USD 249 million |
| Market Size 2034 | USD 801 million |
| Growth Rate | CAGR of 15.7% from 2026–2034 |
| Unit | Value (USD Million), production capacity and wafer diameter |
| Segmentation | By Type, By Application, and By Region |
| By Type | 4 Inch · 6 Inch · 8 Inch · Others |
| By Application | Power Equipment · Electronics and Optoelectronics · Wireless Infrastructure · Others |
| By Region | Each region analysed by Type, Application and Country Asia-PacificChina, Japan, South Korea, India North AmericaUnited States, Canada, Mexico EuropeGermany, France, United Kingdom, Italy South AmericaBrazil, Argentina, Chile Middle East & AfricaSaudi Arabia, United Arab Emirates, South Africa |
| Key Companies Profiled | NuFlare Technology, SiCentury, Hunan ACME, JSG |
| Customization Scope | Company competitive analysis, qualified fabrication capacity, wafer diameter transition, demand scenarios, supply chain and regional equipment investment analysis. |
Frequently Asked Questions
How large is the vertical SiC epitaxial equipment market?
The market stands at USD 216 million in 2025 and is projected to reach USD 801 million by 2034, growing at a CAGR of 15.7% during 2026–2034. The series covers reactor systems used to grow SiC epitaxial layers and tracks investment in power-semiconductor manufacturing. In the commercial setting of the market stands at usd 216 million, the question concerns how large is the vertical sic epitaxial equipment market, which is evaluated through the equipment boundary and documented supplier technology. For the market stands at usd 216 million, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving the market stands at usd 216 million balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Which reactor size leads equipment demand?
Six-inch SiC epitaxial reactors lead with an estimated ~43% of 2025 revenue, reflecting installed 150 millimetre wafer process lines. Eight-inch systems represent ~40% and an expanding opportunity as substrate, equipment and device manufacturers move toward 200 millimetre processing, provided acceptable device yields and plant economics are achieved. In the commercial setting of six-inch sic epitaxial reactors lead with an, the question concerns which reactor size leads equipment demand, which is evaluated through the equipment boundary and documented supplier technology. For six-inch sic epitaxial reactors lead with an, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving six-inch sic epitaxial reactors lead with an balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Which end-use application is largest?
Power Equipment accounts for an estimated ~77% of 2025 demand, including reactor capacity serving vehicle traction inverters, charging, solar inverters and industrial power conversion. Electronics and Optoelectronics hold an estimated ~13%, Wireless Infrastructure ~6%, and other technical end uses ~4%, according to the analyst share allocation. In the commercial setting of power equipment accounts for an estimated ~77%, the question concerns which end-use application is largest, which is evaluated through the equipment boundary and documented supplier technology. For power equipment accounts for an estimated ~77%, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving power equipment accounts for an estimated ~77% balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Which region has the largest market share?
Asia-Pacific has an estimated ~53% of 2025 equipment sales, reflecting its toolmaker base, semiconductor fabrication projects and regional substrate supply relationships. North America follows with ~24%, Europe with ~17%, and South America and the Middle East and Africa with ~3% each. These regional figures are modeled shares, not reported manufacturer shipments. In the commercial setting of asia-pacific has an estimated ~53% of 2025, the question concerns which region has the largest market share, which is evaluated through the equipment boundary and documented supplier technology. For asia-pacific has an estimated ~53% of 2025, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving asia-pacific has an estimated ~53% of 2025 balances chamber configuration against process transfer, factory integration and longer-run upkeep.
What is vertical SiC epitaxy?
Vertical epitaxy uses a controlled predominantly vertical process-gas flow to deposit crystalline SiC layers on a substrate under precisely maintained temperature and gas composition. Epitaxial layer thickness, impurity doping and crystallographic defects affect the subsequent power device characteristics, making both reactor configuration and process-control stability important equipment selection parameters. In the commercial setting of vertical epitaxy uses a controlled predominantly vertical, the question concerns what is vertical sic epitaxy, which is evaluated through the equipment boundary and documented supplier technology. For vertical epitaxy uses a controlled predominantly vertical, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving vertical epitaxy uses a controlled predominantly vertical balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Why are eight-inch systems important?
Eight-inch tools process larger 200 millimetre SiC substrates and potentially spread fixed wafer processing cost across more device area. The advantage depends on substrate availability, wafer bow, defect control, reactor uniformity and downstream yield. Qualified six-inch systems therefore remain commercially relevant even while new eight-inch production programs gain attention. In the commercial setting of eight-inch tools process larger 200 millimetre sic, the question concerns why are eight-inch systems important, which is evaluated through the equipment boundary and documented supplier technology. For eight-inch tools process larger 200 millimetre sic, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving eight-inch tools process larger 200 millimetre sic balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Which manufacturers are active?
NuFlare Technology markets the EPIREVO SiC line, SiCentury supplies vertical-airflow SiCCESS reactors, and JSG identifies a vertical SiC epitaxial furnace in its equipment portfolio. Hunan ACME is also profiled in the market source roster, though the inspected materials describe thermal processing products and require specific epitaxy reactor verification. In the commercial setting of nuflare technology markets the epirevo sic line, the question concerns which manufacturers are active, which is evaluated through the equipment boundary and documented supplier technology. For nuflare technology markets the epirevo sic line, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving nuflare technology markets the epirevo sic line balances chamber configuration against process transfer, factory integration and longer-run upkeep.
What restrains equipment adoption?
The main restraints are long process qualification cycles, high-temperature chamber maintenance, cost of ownership and the uneven timing of semiconductor capacity projects. Different reactor gas-flow configurations also compete, so buyers compare process yield and throughput against planetary and cross-flow alternatives rather than purchasing solely on vertical-flow claims. In the commercial setting of the main restraints are long process qualification, the question concerns what restrains equipment adoption, which is evaluated through the equipment boundary and documented supplier technology. For the main restraints are long process qualification, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving the main restraints are long process qualification balances chamber configuration against process transfer, factory integration and longer-run upkeep.
How does reactor growth rate affect economics?
Nominal growth rate influences potential wafer output, but a higher film deposition speed does not automatically lower manufacturing cost. Thickness and doping uniformity, defect density, automation reliability and maintenance downtime determine how many qualified wafers leave the system. NuFlare and SiCentury technical sheets illustrate the performance criteria prospective customers assess. In the commercial setting of nominal growth rate influences potential wafer output, the question concerns how does reactor growth rate affect economics, which is evaluated through the equipment boundary and documented supplier technology. For nominal growth rate influences potential wafer output, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving nominal growth rate influences potential wafer output balances chamber configuration against process transfer, factory integration and longer-run upkeep.
What is the study scope and forecast period?
The study covers complete vertical gas-flow SiC epitaxial equipment and segments revenue by 4 Inch, 6 Inch, 8 Inch and Others; Power Equipment, Electronics and Optoelectronics, Wireless Infrastructure and Others; and five geographic regions. The base year is 2025, estimated year is 2026 and market forecast runs through 2034. In the commercial setting of the study covers complete vertical gas-flow sic, the question concerns what is the study scope and forecast period, which is evaluated through the equipment boundary and documented supplier technology. For the study covers complete vertical gas-flow sic, customer acceptance depends on epitaxial wafer quality, service arrangements and qualified tool throughput for this particular use case. Equipment selection involving the study covers complete vertical gas-flow sic balances chamber configuration against process transfer, factory integration and longer-run upkeep.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF