Key Statistics
Key Takeaways
- Market trajectory: The SiC Schottky barrier diode market reaches USD 530 million in 2025 and USD 1,625 million by 2034, implying 13.3% annual growth during 2026–2034. The modeled revenue curve reflects wider use of fast-recovery rectification in high-voltage converters rather than sales of finished charging or photovoltaic systems.
- Voltage mix: The publisher 600V family, encompassing common commercial 650V products, holds an estimated ~52% of 2025 sales; 1200V variants account for ~42%, with other ratings at ~6%. Engineers trade forward drop, junction capacitance and thermal resistance against blocking voltage.
- Applications: New energy vehicles are the leading outlet at an estimated ~28% of revenue, followed by power supplies at ~25%, photovoltaics at ~19%, consumer electronics at ~12%, industrial systems at ~12% and other uses at ~4%. Those are modeled allocations, not manufacturer shipment disclosures.
- Geography: Asia-Pacific represents an estimated ~48% of 2025 diode revenue, North America ~27%, Europe ~18%, South America ~4% and the Middle East and Africa ~3%. Power electronics production and electrified transport explain the first region’s advantage.
- Competitive priorities: Infineon, STMicroelectronics, Vishay, ROHM and Microchip sell distinct Schottky products; historical names such as Microsemi and GeneSiC must be interpreted within their acquiring companies. Reliability documentation and packaging compatibility frequently determine design wins.
SiC-SBD Market Overview
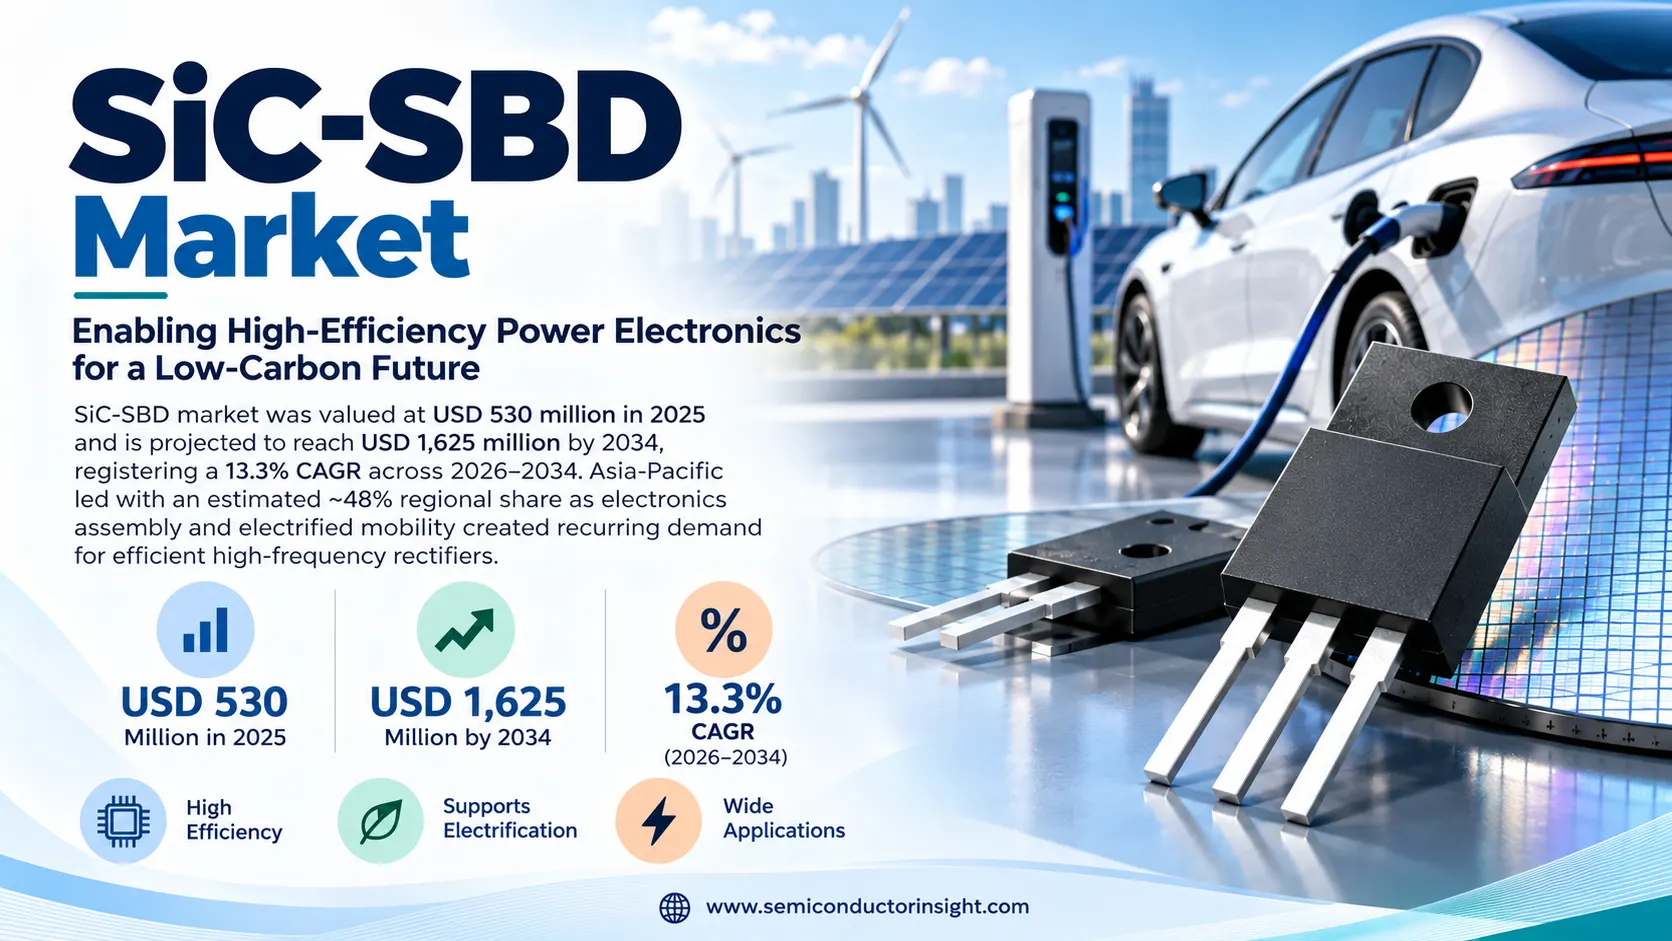
SiC-SBD market was valued at USD 530 million in 2025 and is projected to reach USD 1,625 million by 2034, registering a 13.3% CAGR across 2026–2034. Asia-Pacific led with an estimated ~48% regional share as electronics assembly and electrified mobility created recurring demand for efficient high-frequency rectifiers.
A silicon carbide Schottky barrier diode conducts through a metal-semiconductor junction instead of the minority-carrier storage mechanism associated with conventional silicon fast-recovery rectifiers. In power factor correction, the benefit is particularly visible when a switching transistor commutates current away from the diode: lower stored charge reduces the loss and noise burden on the companion switch. Designers still need to evaluate forward voltage at operating temperature, surge-current withstand and package parasitics rather than assuming that every SiC part is interchangeable.
The commercial boundary covers finished discrete silicon carbide Schottky barrier diodes, packaged diode bridges and standalone die sold for integration into converters. It includes the publisher’s 600V, 1200V and other voltage classes, and its six named end uses. It does not include raw SiC crystals, polished substrates, epitaxial wafer sales, MOSFET-only components, complete traction inverters, photovoltaic panels or battery charging installations. Where a module contains a diode alongside transistors, only independently identifiable Schottky product revenue belongs within the boundary.
The market is increasingly shaped by topology selection. A 650V rectifier can serve a 400V-class DC bus with appropriate transient margin, whereas 1200V devices are considered in higher-voltage energy conversion and industrial power stages. A merged PIN Schottky design adds a junction structure intended to improve surge behavior under abnormal currents, and high-creepage packages address insulation requirements that become more demanding as power density rises. Engineers evaluate device behavior under 25°C, 125°C and 175°C test conditions before committing to an automotive or industrial design.
Sales are not proportional to the number of electric vehicles or solar panels alone. Each 2-level, 3-level or resonant converter architecture has a different rectifier bill of materials, and a shift from a silicon diode to a synchronous transistor can eliminate one component while raising efficiency. This is why application growth is translated into semiconductor demand only after accounting for circuit topology, voltage rating, qualification and average selling price; adjacent deployment statistics serve as direction indicators rather than as direct diode revenue.
Supplier competition has moved beyond bare blocking-voltage claims. Procurement teams compare JEDEC qualification, thermal-cycling endurance, 1A through 240A current options, available 650V and 1200V packages, and the cost of retesting when a package footprint changes. New product announcements during 2025 show both low-current surface-mount devices and higher-current SOT-227 assemblies being developed, indicating that manufacturers pursue several converter power bands rather than a single mass-market device class.
Segment Analysis: By Type
The type classification follows the three publisher voltage categories: 600V, 1200V and Other. The 600V group is the largest, with an estimated ~52% share in 2025, because commercial 650V-class Schottky products are common in 400V-bus AC/DC power-factor-correction circuits. The 1200V class represents an estimated ~42% and tends to carry higher value per qualified part in industrial, transport and energy systems.
| Type | Electrical role and examples | Revenue position and buying criteria |
|---|---|---|
| 600V | This publisher category covers the commercially widespread 650V device family used in boost PFC, high-frequency power conversion and compact power adapters. Designers commonly compare a 1A or 2A surface-mount part with larger TO-247 packages when switching from 25kHz toward 100kHz or higher, while checking leakage current and creepage. | Estimated ~52% share in 2025. High shipment frequency comes from server and telecom supplies, consumer conversion stages and auxiliary vehicle charging electronics. Procurement favors package continuity, low capacitive charge, consistent 125°C performance and a reliable second source. The label is retained as 600V even though many manufacturer catalogues say 650V. |
| 1200V | Higher-voltage SiC Schottky devices are considered where DC-link excursions, insulation coordination and industrial fault transients exceed the comfort margin of the 650V class. A 1200V, 50A die can enter custom rectifier assemblies; packaged options span smaller currents and bridge arrangements. These parts face demanding reverse leakage and surge-current screening. | Estimated ~42% share in 2025. Applications include renewable-energy converters, selected industrial drives, high-voltage charging subsystems and power infrastructure. Design-in cycles can exceed 12 months because the diode must be qualified with the complete thermal stack and gate-drive environment. Higher prices can offset lower unit shipments than the 600V family. |
| Other | The residual voltage segment covers grades outside the two main publisher categories, including specialized lower-voltage and higher-voltage parts whose use is tied to particular equipment designs. Component buyers may require custom creepage, surge rating or wafer-level die supply rather than catalogue packages. Production volumes are typically smaller and qualification is more project-specific. | Estimated ~6% share in 2025. Revenue is limited by narrower converter socket availability and fewer interchangeable suppliers. The economic case is strongest when an unusual voltage specification removes an external snubber or reduces a converter stage. No separate product-grade shipment totals are assumed for this modeled residual class. |
600V and commercial 650V SiC-SBD devices
The 600V classification remains dominant because most single-phase mains power supplies rectify into a DC bus near 400V and require switching diodes that withstand operating spikes. A designer selecting a 650V part weighs 1.2V–1.5V forward-drop examples against capacitance, cooling cost and reliability over a 10-year product life. Infineon’s CoolSiC 650V G5 and G6 families illustrate the depth of catalogue choices, although a catalogue listing alone does not reveal market revenue.
1200V rectifiers for higher-voltage equipment
The 1200V segment is differentiated by insulation, junction temperature and fault behavior rather than by a simple doubling of voltage. ROHM’s S6305 1200V 50A bare die shows why power-system manufacturers sometimes buy unpackaged parts for their own assemblies. The route from bare die to qualified inverter can involve 3 stages of electrical screening, thermal attachment trials and high-voltage system testing, so qualification expense can outweigh a small purchase-price difference.
Other ratings and application-specific designs
Special voltage grades remain relevant when a converter has an unusual bus range or requires insulation distances unavailable in mainstream outlines. Their estimated ~6% allocation is deliberately limited: most catalogued demand is concentrated in 650V and 1200V devices, while project-specific variants often need custom assembly and limited production runs. Buyers evaluate availability across a 5- to 10-year service interval because redesigns can be costly after certification.
Segment Analysis: By Application
By application, New Energy Vehicles lead with an estimated ~28% of 2025 revenue. Power Supplies follow at ~25%, Photovoltaics at ~19%, Consumer Electronics and Industrial each at ~12%, and Others at ~4%. These estimates reflect different device counts, voltage ratings and qualification premiums, not a conversion of vehicle or solar installation values into semiconductor revenue.
| Application | Demand characteristics |
|---|---|
| New Energy Vehicles | The largest modeled outlet, ~28%, comprises on-board chargers, DC/DC converters and selected charging electronics where low switching loss helps reduce cooling requirements. A 400V or 800V vehicle platform can use different diode counts, and the rectifier content depends on whether a stage employs synchronous switching or a dedicated Schottky path. Automotive-grade qualification and long support commitments influence price more than headline vehicle sales alone. |
| Power Supplies | An estimated ~25% of revenue comes from power-factor-correction front ends, telecom rectifiers, industrial UPS and high-efficiency server supplies. These applications place value on switching at 50kHz, 100kHz or higher while keeping electromagnetic interference manageable. The chosen package must handle thermal stress and current ripple during 24-hour operation, making forward voltage and capacitive charge practical purchasing criteria. |
| Photovoltaics | An estimated ~19% share is tied to solar inverter conversion stages, auxiliary supplies and related storage interfaces, not to photovoltaic module manufacturing. The IEA PVPS recorded 698GW of new solar installations in 2025, a useful demand indicator but not a semiconductor sales figure. System designers increasingly pair SiC devices with high-frequency magnetics and bidirectional stages, changing the number of standalone diodes per kilowatt. |
| Consumer Electronics | An estimated ~12% of market value reflects premium adapters, higher-wattage appliances and compact power products where efficiency certification and enclosure temperature matter. The use case is narrower than total consumer electronics output because low-cost chargers can remain on silicon or GaN designs. Component choices balance board area, 650V blocking requirements, acoustic noise and a product cycle of roughly 2 to 5 years. |
| Industrial | Industrial converters and automation equipment account for an estimated ~12% of diode demand, including motor-drive auxiliaries, welding supplies, UPS equipment and selected rail-related power stages. Service continuity, replacement part availability and electrical isolation can outweigh a few percentage points of initial cost. Engineering teams may retain the same qualified 1200V outline across several equipment revisions to avoid repeat environmental testing. |
| Others | The residual ~4% covers specialized grid interfaces, energy-storage auxiliaries, test equipment and niche transport power systems. Buyers may require unusually high surge ratings or traceability at lot level, and the design quantity can be small relative to mainstream power-factor-correction markets. Revenue assumptions remain conservative because the publisher provides no standalone totals for these additional uses. |
Application economics differ sharply by power rating. A 2kW power supply with a high-frequency boost stage may justify a 650V Schottky because lower recovery charge improves switching efficiency, whereas a low-wattage consumer adapter might use a different semiconductor topology altogether. At 11kW or 22kW charging levels, thermal design, electrical isolation and component redundancy take greater weight in the engineering decision. These distinctions make direct multiplication of installation counts by diode prices unreliable.
Photovoltaic and electric-vehicle deployment provide overlapping but distinct sales channels. Solar inverters typically have grid-interconnection and long-field-life requirements, while automotive electronics must withstand vibration and broad ambient temperatures under vehicle qualification regimes. A single diode family can appear in both markets, yet approval, packaging and customer documentation may differ enough that suppliers treat them as separate commercial programmes. This separation matters when interpreting the estimated ~19% solar allocation and ~28% vehicle allocation.
Regional Analysis
The regional model assigns Asia-Pacific ~48% of 2025 SiC-SBD revenue, North America ~27%, Europe ~18%, South America ~4% and Middle East & Africa ~3%. Shares describe the modeled market allocation rather than official regional sales disclosures; manufacturing location, converter design ownership and end-equipment deployment are distinct measures.
Where are SiC Schottky rectifier design wins concentrated?
Power-electronics production in China, Japan and South Korea anchors Asia-Pacific demand, with Taiwan and Southeast Asia participating in component assembly and supply-chain integration. A product can be designed in Europe, packaged in Asia and installed in North America, so regional sales should be interpreted as estimated semiconductor demand rather than an assertion about where every die is fabricated. The modeled Asia-Pacific lead is consistent with the scale of electric mobility and power conversion manufacturing.
North America and Europe remain important specification-setting markets because converter suppliers serving automotive, energy and industrial customers require detailed reliability evidence. South America and the Middle East and Africa account for smaller shares but can grow quickly from a modest installed base as photovoltaic and storage equipment adoption broadens. Regional CAGRs are scenarios derived from application mixes and are not publisher-provided forecasts for each geography.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest ~48% | ~14.2% CAGR | Power-device manufacturing, electric mobility and solar inverter assembly | Supplier qualification in China, Japan and Korea; package availability for 650V and 1200V |
| North America | Second ~27% | ~12.0% CAGR | Power supplies, vehicle electronics and industrial energy conversion | Automotive traceability, distributor inventory, high-temperature reliability and application engineering |
| Europe | Third ~18% | ~12.5% CAGR | Industrial drives, renewable conversion and premium automotive electronics | Electrical insulation, thermal lifetime, regional engineering support and compliance documentation |
| South America | Emerging ~4% | ~14.0% CAGR | Solar deployment, charging networks and imported industrial converters | Import logistics, replacement-part lead time and local integration partners |
| Middle East & Africa | Emerging ~3% | ~14.5% CAGR | Utility solar, data infrastructure and selective charging projects | Thermal derating, grid conditions and supplier after-sales support |
Key SiC-SBD Manufacturers and Competitive Landscape
Competition spans integrated power-semiconductor producers, discrete-device specialists and suppliers of packaged bare die. The market does not support a defensible public ranking by standalone SiC-SBD revenue because most companies report wider power-device businesses. Product breadth, wafer supply, 650V and 1200V packaging, automotive qualification and customer engineering are more useful competitive differentiators than assigning unsupported company shares.
Infineon’s CoolSiC diode families serve power-factor-correction and industrial conversion markets, while STMicroelectronics offers packaged 650V Schottky rectifiers such as the STPSC6H065. Vishay competes through a wide range of surface-mount and SOT-227 configurations, and ROHM offers bare-die formats that can be integrated into customized power assemblies. Those portfolios address different current and packaging requirements, so a comparison of catalogue part numbers does not by itself identify the largest seller.
Corporate history changes how the publisher’s company list should be read. Microsemi became part of Microchip in 2018; GeneSiC was acquired by Navitas in 2022; and Qorvo acquired UnitedSiC in 2021 before onsemi purchased its silicon carbide JFET business in 2025. These names remain useful for product lineage, but counting them alongside their owners as independent present-day competitors would inflate the supplier universe.
Automotive qualification creates a durable barrier. A supplier may offer 650V parts at a competitive price but still lack the lot traceability, surge-current documentation or long-term product change control demanded by a vehicle platform. Industrial customers face different constraints, including 24-hour operation, repairability and a requirement for equivalent parts after 7 to 10 years. The winning supplier therefore depends on the customer’s converter duty cycle rather than only on nominal blocking voltage.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Broad power-semiconductor portfolios | Infineon, STMicroelectronics, ROHM, onsemi, Mitsubishi Electric, Fuji Electric, Toshiba | These companies operate across multiple power-device categories and can provide application engineering, long-life product support and access to several voltage families. Inclusion reflects verified power-electronics capabilities; no standalone SiC-SBD sales ranking is asserted because segment reporting does not isolate diode revenue. |
| Discrete rectifier and design-in specialists | Vishay, Microchip, Navitas/GeneSiC, Yangzhou Yangjie, InventChip | These suppliers compete through diode-specific packages, current ratings, price, distribution or niche customer engineering. Some historical labels now sit within acquiring groups, and a company’s broader SiC portfolio should not be interpreted as proof that every listed product is a currently shipped Schottky diode. |
| Additional publisher-listed ecosystem names | Wolfspeed (Cree), Global Power Technology, BASiC, United Silicon Carbide (Qorvo), Microsemi (Microchip) | The names indicate relevant SiC material, device or historical capabilities, but not all represent independent current sellers of finished SiC Schottky rectifiers. Wolfspeed is prominent in SiC materials and power devices, while acquired brands must be reconciled with current ownership and business transfers. |
Key companies profiled
- Infineon
- Mitsubishi Electric
- STMicroelectronics
- Fuji Electric
- Toshiba
- onsemi
- Vishay
- Wolfspeed (Cree)
- ROHM
- Microsemi (Microchip)
- United Silicon Carbide (Qorvo)
- GeneSiC (Navitas)
- Global Power Technology
- BASiC
- Yangzhou Yangjie
- InventChip
SiC-SBD Production Capacity and Technology Analysis
A finished Schottky diode passes through substrate preparation, epitaxial growth, junction formation, metallization, wafer test, die separation and packaging. Capacity for any one stage cannot be equated with saleable diode output because yield, wafer diameter, die area, voltage grade and product qualification determine the number of approved components. Manufacturers balance 650V and 1200V production against demand for other SiC devices on related fabrication assets.
Substrate defects and epitaxial uniformity influence reverse leakage, blocking capability and eventual die yield. A 1200V design often needs different epitaxial thickness and doping than a 650V design, so manufacturing throughput is not interchangeable simply because both use silicon carbide wafers. Wafer diameter affects potential die count, but edge exclusion, defect density and electrical binning must be considered before projecting the number of sellable rectifiers from a nominal 150mm or 200mm substrate.
Merged PIN Schottky structures can improve surge behavior by providing an alternative conduction path during abnormal current events. They require additional junction design and process control compared with a simple Schottky contact, and their advantages must be balanced against forward voltage and capacitance. High-temperature operation adds another challenge: the die attachment, bond wires, molding compound and terminal insulation can limit assembly lifetime even if the semiconductor junction itself meets the desired blocking specification.
Packaging is a separate capacity constraint. Small 1A and 2A surface-mount devices serve compact converter boards, while 40A to 240A SOT-227 arrangements require larger current paths and heat extraction. Automated optical inspection, electrical screening and traceability records add cost but support the reliability commitments needed for industrial and automotive supply. Suppliers therefore compete on qualified output rather than theoretical wafer starts, and an announced wafer investment should not be treated as immediate Schottky sales.
SiC-SBD Market Dynamics: Drivers, Restraints and Opportunities
Growth is supported by vehicle electrification, higher-efficiency power-factor-correction supplies, photovoltaic conversion and demanding industrial power stages. Those drivers are offset by SiC wafer yield and price constraints, competition from silicon and gallium nitride, and the long qualification cycle for automotive electronics. Contributions in the impact tables are scenario allocations that reconcile to the headline growth rate, not separately measured causal percentages.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Vehicle electrification and charging conversion | High | +4.80% | High | High | Medium |
| Efficient PFC, UPS and telecom rectifiers | High | +3.60% | High | High | Medium |
| Photovoltaic inverter and storage deployment | Medium-High | +2.70% | High | Medium | Medium |
| Industrial high-voltage power conversion | Medium | +2.10% | Medium | High | High |
| High-frequency switching and cooling reduction | Low-Medium | +1.80% | Medium | High | High |
| Others (rail, grid auxiliaries and specialty power) | Low | +1.00% | Low | Medium | Medium |
Vehicle power electronics create premium rectifier sockets
On-board chargers and DC/DC converters can benefit from low reverse-recovery charge, especially when power density and thermal efficiency are central to the design. An 800V vehicle platform does not automatically double diode content relative to a 400V vehicle because the circuit topology may change. The 4.80-point modeled contribution reflects the interaction of electrified vehicle production, charging conversion and semiconductor content per approved design rather than a fixed device count per vehicle.
Power-factor correction rewards switching efficiency
Server, telecom and UPS power supplies are often evaluated at 50kHz, 100kHz and higher switching frequencies where diode recovery can increase loss in the companion transistor. A Schottky rectifier with appropriate capacitive charge may allow smaller magnetics or reduced cooling, but the value depends on the complete converter stage. The 3.60-point contribution recognizes these engineering trade-offs and the continuing demand for high-uptime power infrastructure.
Solar conversion broadens industrial demand
New photovoltaic capacity expands the installed base of inverters and related power electronics, but a given inverter can use different rectifier topologies and diode voltage grades. IEA PVPS recorded 698GW of additions in 2025, showing the scale of deployment across utility and distributed projects. The modeled 2.70-point driver is therefore assigned to potential component opportunities in conversion and maintenance rather than to the gross value of solar modules or installations.
Industrial systems value voltage margin and lifetime
Factory power supplies, welding equipment and motor-drive auxiliaries use rectifiers under widely varying surge and ambient-temperature conditions. A 1200V device may be selected to provide blocking margin, while a 650V part can be preferred in a compact lower-voltage stage. Long service periods and the cost of equipment downtime support qualified component demand, with a modeled 2.10-point contribution spread across several equipment categories.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| SiC wafer yield, packaging and device cost | High | -1.10% | High | Medium | Medium |
| Silicon and GaN circuit substitution | Medium-High | -0.80% | Medium | High | High |
| Automotive design and qualification cycles | Medium | -0.50% | High | Medium | Low |
| Others (trade friction and reliability screening) | Low | -0.30% | Medium | Medium | Low |
Manufacturing cost and defects limit price reductions
Silicon carbide substrates, epitaxial processing and electrical screening remain costly relative to mature silicon rectifiers. Yield losses are particularly important for higher-voltage die that need stringent leakage control, and a defective wafer can affect many packaged parts. The modeled negative 1.10-point effect reflects the difficulty of passing lower manufacturing costs through to customers while maintaining traceability and reliability across automotive and industrial qualifications.
Alternative technologies can remove the diode socket
A converter using synchronous rectification may replace a dedicated diode with an actively controlled transistor, while a GaN-based architecture may shift the optimal switching frequency and passive-component design. These changes can improve system efficiency but reduce standalone SiC-SBD content in a particular power stage. The negative 0.80-point scenario allocation captures design substitution rather than predicting a uniform decline in demand across all voltage ratings.
Qualification and procurement slow new designs
Automotive and industrial customers test components under thermal cycling, surge-current and long-duration electrical stress before authorizing production. A product introduced in 2025 might not reach full platform volumes until a later vehicle or equipment revision, and changing package footprint can restart approval work. The negative 0.50-point effect reflects this lag between device availability and revenue realization, especially for high-reliability 1200V parts.
Trade exposure complicates specialist sourcing
A customer that depends on a single qualified package can be vulnerable to changes in export rules, distributor availability or production location. The resulting response may be inventory buffering, alternate supplier qualification or redesign, each of which raises total ownership cost. A smaller negative 0.30-point contribution covers these frictions without assuming that all regional buyers face identical regulatory or supply-chain constraints.
MARKET OPPORTUNITIES
High-density supplies create room for differentiated packages
Designers of data-center and telecom power supplies seek lower losses while reducing magnetics and heat-sink volume. A 650V diode that offers a suitable forward-drop and capacitive-charge balance can win a socket even when the converter manufacturer is reluctant to redesign the entire stage. Package compatibility and test evidence are important because a high-volume 2kW or 3kW platform can run for several product generations.
Higher-voltage energy systems broaden the design space
Industrial energy storage, solar conversion and fast charging create use cases for 1200V blocking capability, but the best solution depends on DC-link voltage, fault behavior and the number of switching stages. Suppliers offering both bare die and packaged parts can serve custom assemblies as well as standard printed circuit boards. The opportunity is strongest where a diode reduces total converter losses enough to justify qualification and integration expense.
Repair channels reward long-term product availability
Many UPS and industrial power systems operate well beyond a typical consumer product cycle, creating a need for qualified replacement rectifiers. A manufacturer that maintains the same 650V or 1200V footprint and publishes reliable derating curves can gain aftermarket business through authorized distributors. This opportunity is less visible in new-build statistics because it follows installed equipment age, field failure rates and service inventories.
SiC-SBD Value Chain and Procurement Analysis
The value chain begins with SiC crystal growth and epitaxial wafer supply, then moves through device fabrication, electrical test, packaging, distribution and integration into a converter. Only finished Schottky diode component sales are counted in the market boundary; upstream wafer revenue and downstream inverter value are separate economic activities. Procurement teams assess the entire chain because a weak link in wafer yield or package availability can delay an approved product.
Materials and wafer quality. A finished diode’s reverse leakage depends on epitaxial uniformity and defects inherited from crystal growth. High-voltage grades demand tighter control over blocking performance, while large-area high-current devices have more die area exposed to possible defects. The transition from 150mm to 200mm processing may increase potential die output, but it also requires qualified equipment, process control and packaging capacity before it changes saleable device volumes.
Fabrication and test. Schottky contact metallurgy, edge termination and merged PIN structures determine the electrical characteristics that appear in a data sheet. Production testing must verify leakage and forward voltage at relevant conditions rather than relying on a nominal 650V or 1200V label. Manufacturers also need repeatable wafer-probe and final-test flows, since an attractive laboratory sample is not equivalent to a stable commercial yield across many lots.
Distribution and end use. Converter manufacturers usually buy through direct supply agreements or authorized distribution channels, with demand linked to approved bills of materials. When a 50A diode is replaced by a different package, engineers may need to reassess heat sinking, clearance and electromagnetic behavior. This creates switching costs that reward product continuity, although large customers can use dual-source qualification to improve resilience and negotiate price.
Recent Developments in the SiC-SBD Market
- 29 January 2025 Launched
Vishay introduced 16 new 650V and 1200V SiC Schottky diode variants in the SOT-227 package, including 40A–240A parallel arrangements and 50A/90A bridge devices. The launch targets higher-current rectification in charging, UPS and photovoltaic converters, with low capacitive charge and high-temperature operation. Its importance is the extension of SiC-SBD selection into package formats familiar to industrial designers, reducing mechanical redesign risk for certain power stages. Source - 9 June 2025 Technology
Toshiba described a 650V superjunction Schottky barrier diode prototype with about 35% lower high-temperature on-resistance at 175°C than a conventional comparison device. This research points to potential improvements in conduction losses and power density, but a prototype result should not be treated as evidence of immediate production shipments or realized revenue. Commercial impact depends on later qualification, manufacturability and converter adoption. Source - 9 July 2025 Product
Vishay released three Gen 3 SiC Schottky diodes in SlimSMA HV packaging, offering 650V and 1200V options with 1A or 2A current ratings and a minimum 3.2mm creepage distance. The compact format addresses low-current high-frequency designs where board area and insulation are important. The product range demonstrates how suppliers target specialized circuit positions rather than relying solely on larger high-current packages. Source - 15 January 2025 Ownership
onsemi completed its purchase of Qorvo’s silicon carbide JFET business, historically associated with the UnitedSiC portfolio. The transaction is adjacent to SiC-SBD competition rather than a disclosed diode revenue event, but it changes the interpretation of former supplier names in power-semiconductor comparisons. Customers examining older component documentation need to verify current product ownership, support channels and availability rather than assuming historical brand independence. Source - April 2026 Demand context
IEA PVPS reported 698GW of global photovoltaic additions during 2025, bringing cumulative installations close to 3TW. These figures signal a broadening installed base for solar inverters, storage interfaces and auxiliary power conversion, but they measure power-system deployment rather than SiC Schottky component sales. The market implication is a larger potential equipment population for efficient rectifier designs and future maintenance demand. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2020–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2020–2024 |
| Market Size 2025 | USD 530 million |
| Market Size 2026 | USD 600 million |
| Market Size 2034 | USD 1,625 million |
| Growth Rate | CAGR of 13.3% from 2026–2034 |
| Unit | Revenue in USD million; device count and current ratings used only for context |
| Segmentation | By Type, By Application and By Region |
| By Type | 600V · 1200V · Other |
| By Application | New Energy Vehicles · Power Supplies · Photovoltaics · Consumer Electronics · Industrial · Others |
| By Region | Five-region model, with 2025 share estimates and indicative 2026–2034 growth rates North AmericaUnited States, Canada, Mexico EuropeGermany, France, Italy, United Kingdom, Spain, Nordics, Rest of Europe Asia-PacificChina, Japan, India, South Korea, Taiwan, Southeast Asia, Rest of Asia-Pacific South AmericaBrazil, Chile, Argentina, Colombia, Rest of South America Middle East & AfricaSaudi Arabia, UAE, Morocco, Egypt, South Africa, Rest of Middle East & Africa |
| Key Companies Profiled | Infineon, Mitsubishi Electric, STMicroelectronics, Fuji Electric, Toshiba, onsemi, Vishay, Wolfspeed (Cree), ROHM, Microsemi (Microchip), United Silicon Carbide (Qorvo), GeneSiC (Navitas), Global Power Technology, BASiC, Yangzhou Yangjie, InventChip |
| Customization Scope | Custom country, voltage class and converter application breakouts can be specified to align analysis with particular equipment platforms and procurement requirements. |
Frequently Asked Questions
How large is the global SiC-SBD market?
The global SiC-SBD market was valued at USD 530 million in 2025 and is forecast to reach USD 1,625 million by 2034, representing 13.3% CAGR during 2026–2034. The forecast includes discrete Schottky rectifiers used in vehicle power electronics, power supplies, photovoltaic converters and industrial equipment. It excludes finished inverters, standalone wafer materials and MOSFET-only components, which are economically different products.
What is the practical advantage of a SiC Schottky diode?
Its junction mechanism avoids the minority-carrier recovery behavior of conventional silicon fast-recovery rectifiers, reducing switching loss in appropriate converter stages. Engineers still evaluate forward voltage, leakage, junction capacitance and thermal performance because lower recovery charge is not the only determinant of efficiency. A 650V device selected for a compact PFC stage may be unsuitable for a 1200V industrial design despite similar packaging.
Which voltage category holds the largest share?
The publisher’s 600V type category is the largest with an estimated ~52% of 2025 revenue, including widely used commercial 650V-class products. The 1200V class follows at an estimated ~42%, with Other ratings contributing ~6%. These allocations reflect modeled converter socket demand and component value; manufacturers do not disclose a complete worldwide revenue split by the publisher’s exact voltage labels.
Which application leads demand for SiC-SBD components?
New Energy Vehicles account for an estimated ~28% of market revenue, driven by on-board charging and selected DC/DC power stages. Power Supplies are close behind at ~25%, while Photovoltaics contribute ~19%. The opportunity within any end market depends on circuit architecture: a synchronous topology can reduce the number of standalone diodes even as system efficiency improves, so equipment growth does not translate mechanically into rectifier sales.
Why is Asia-Pacific the largest regional market?
Asia-Pacific combines a large electronics manufacturing base with vehicle electrification and high-frequency power conversion engineering. Its estimated ~48% revenue share reflects demand and supplier concentration across China, Japan, South Korea and other production centers. The regional growth scenario of ~14.2% CAGR is higher than the global rate, although individual company production sites and customer locations may differ from the region where the final equipment is installed.
Which companies offer relevant SiC Schottky diode products?
Confirmed product examples include Infineon CoolSiC diode families, STMicroelectronics packaged 650V devices, Vishay 650V and 1200V parts, ROHM 1200V bare die and Microchip discrete rectifiers. Other publisher-listed names participate in related SiC materials or power electronics. GeneSiC is associated with Navitas, Microsemi with Microchip and UnitedSiC with a history of Qorvo ownership, so the supplier universe should not double-count acquired brands.
What limits adoption in price-sensitive power supplies?
A SiC diode can offer lower switching loss, but its purchase cost, forward drop and available package must be justified against mature silicon rectifiers and alternative transistor-based circuits. Some consumer designs prioritize the lowest total bill of materials rather than maximum switching frequency. Production yield, second-source availability and the cost of qualifying a different footprint can also delay adoption despite technically favorable data-sheet characteristics.
How do photovoltaic installations affect the opportunity?
New solar projects create demand for inverters, auxiliary converters and storage interfaces, some of which use SiC Schottky rectifiers. However, installation data are measured in gigawatts and cannot be treated as diode revenue. Circuit topologies vary by power rating, grid requirements and semiconductor generation, so the installed photovoltaic base is best used as a demand-direction indicator rather than a fixed semiconductor-content multiplier.
Why are current rating and package choice important?
The same nominal blocking voltage can be offered in a small surface-mount package, a TO-247 discrete outline or a higher-current SOT-227 arrangement. Heat removal, creepage distance, surge current and board assembly rules differ among these formats. A converter maker may choose a 2A component for an auxiliary stage and a 50A part for a high-power path, making price comparisons without package context misleading.
What is included in the market segmentation?
The study uses 2025 as its base year, 2026 as the estimate and 2034 as the forecast horizon. It separates the voltage categories 600V, 1200V and Other; six applications from New Energy Vehicles through Industrial and Others; and North America, Europe, Asia-Pacific, South America and Middle East and Africa. Regional shares and segment mixes are analytical estimates supported by device and application evidence.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF