Key Statistics
Key Takeaways
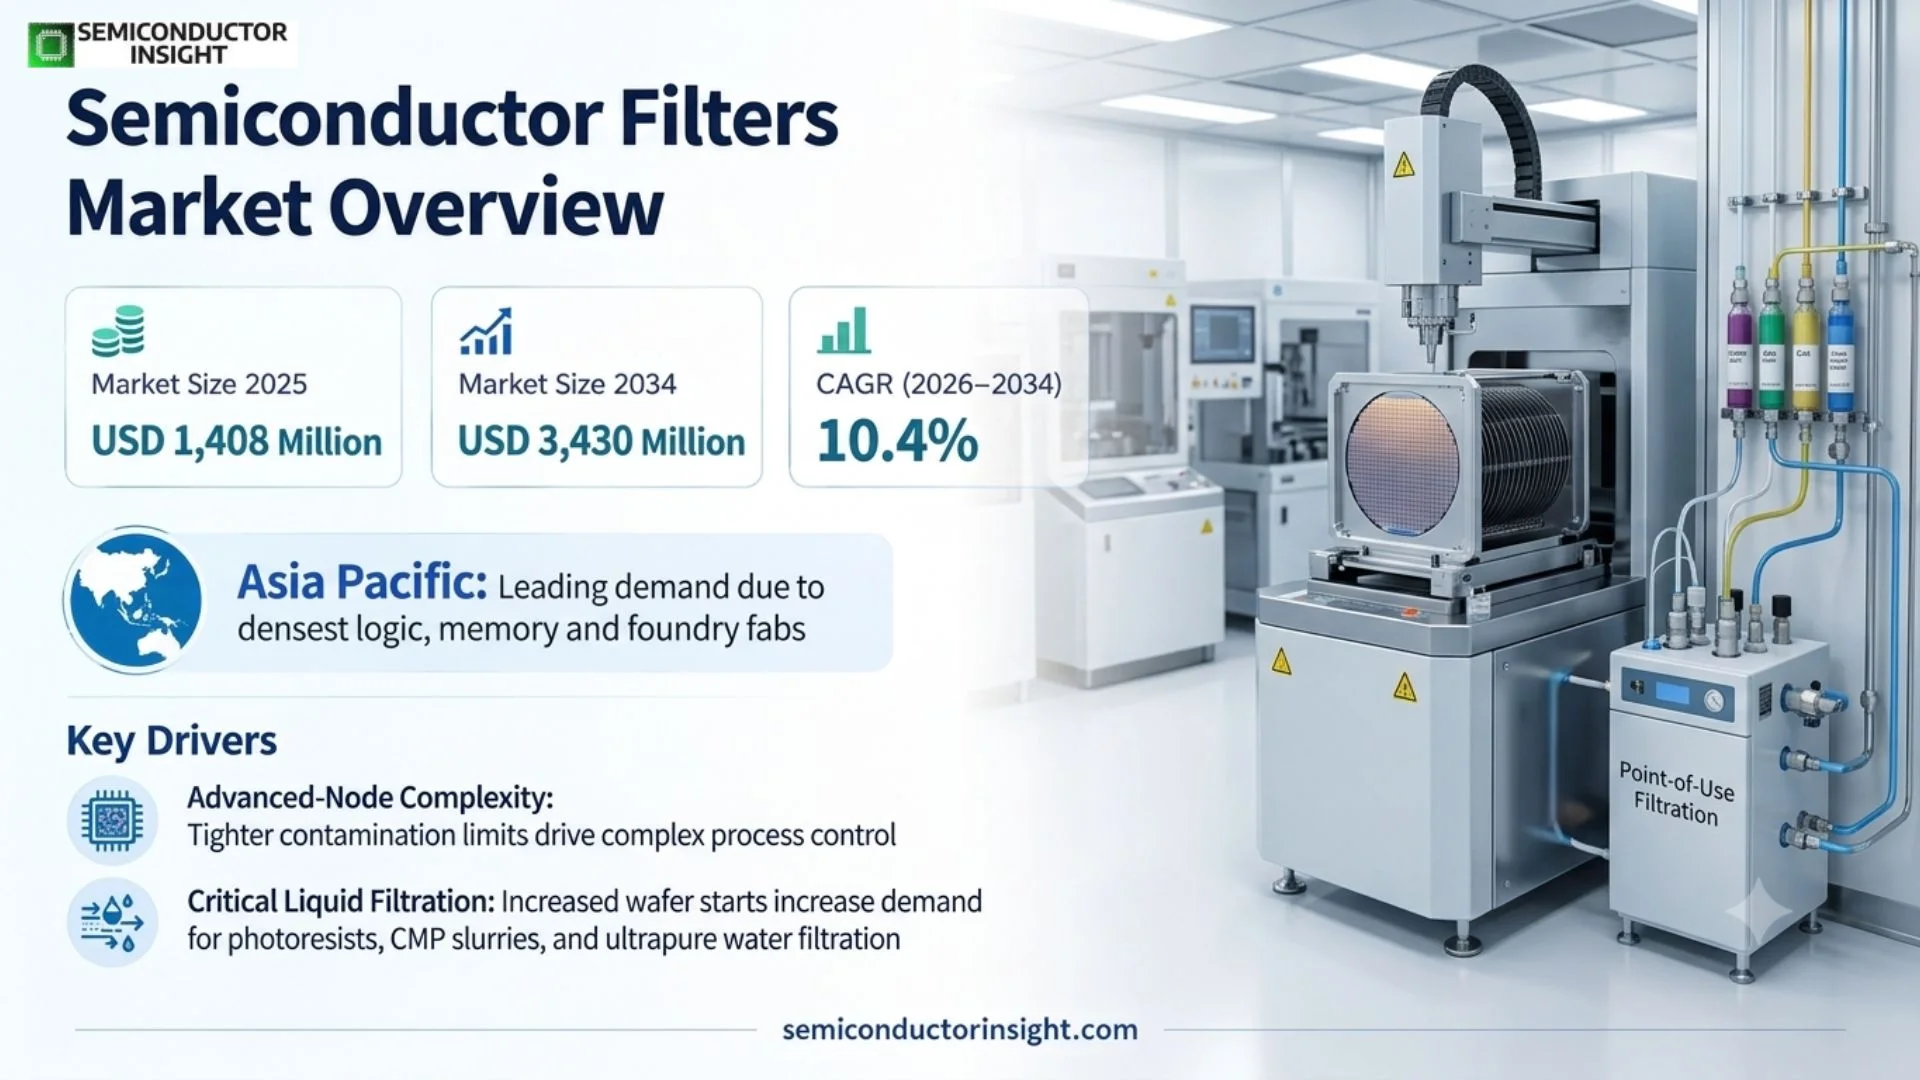
- Market size: The market stands at USD 1,408 million in 2025 and is projected to reach USD 3,430 million by 2034, representing a 10.4% CAGR across 2026–2034.
- Liquid filtration represents a large value pool because lithography, wet cleans, CMP and electronic-grade chemicals require aggressive particle and metal control at multiple points in the fab.
- Asia Pacific is the largest demand region because the region contains the highest concentration of semiconductor wafer-fabrication capacity and new fab investment.
- Advanced-node contamination control is tightening, with filtration requirements moving toward nanometer-scale retention, lower extractables and reduced pressure drop to protect yield.
- Process qualification creates high switching costs; once a filter is validated for a chemical, slurry or gas stream, fabs are cautious about substitution because changes can affect defectivity and tool uptime.
Semiconductor Filters Market Overview
Semiconductor Filters Market is valued at USD 1,408 million in 2025 and is projected to reach USD 3,430 million by 2034, expanding at a 10.4% CAGR during 2026–2034. The 2026 market level is USD 1,554 million. Asia Pacific leads demand because it contains the densest concentration of logic, memory and foundry fabs. Growth is linked to more wafer starts, advanced-node process complexity, tighter contamination limits and rising use of point-of-use filtration across chemicals, gases, photoresists, CMP slurries and ultrapure water.
Semiconductor filters remove particles, gels, agglomerates, metals and other contaminants from process gases, chemicals, slurries, photoresists and ultrapure water used in wafer fabrication. The market includes gas and liquid filter elements rather than large membrane modules. Product performance is evaluated through retention efficiency, extractables, chemical compatibility, pressure drop, flow stability and lifetime under extremely pure process conditions, making qualification and materials selection central to product value.
Filtration intensity rises as device geometries shrink because a contaminant that was tolerable at a mature node can become a killer defect at an advanced node. Fabs therefore deploy filtration at bulk delivery, recirculation and point-of-use locations. Lithography and wet cleaning require low particle and metal levels, CMP requires control of agglomerates without removing useful slurry particles, and process-gas systems require filters that do not shed particles or outgas impurities.
The market is highly qualification-driven. A filter can affect chemistry, flow and defectivity, so customers validate media, housing materials and pore structure for each process. Once approved, switching is deliberately slow because a lower-cost filter is unattractive if it increases wafer defects or tool downtime. This creates recurring replacement demand and favors suppliers with strong application engineering, global clean manufacturing, controlled change management and traceable quality systems.
Segment Analysis: By Type
By type, the market is segmented into semiconductor gas filters and semiconductor liquid filters. Gas filters protect ultra-high-purity process streams used in deposition, etch and related tools, while liquid filters serve photoresists, wet chemicals, CMP slurries and ultrapure water. Both categories become more demanding as contamination budgets tighten and process windows narrow.
| Type | Technical / commercial role | Market position |
|---|---|---|
| Semiconductor Gas Filter | Removes particles and selected contaminants from bulk and point-of-use process gas streams. | Critical for deposition, etch and gas delivery; supplier selection emphasizes low outgassing, particle shedding and pressure drop. |
| Semiconductor Liquid Filter | Filters photoresists, chemicals, slurries and ultrapure water through polymer or other high-purity media. | Large and diverse segment with multiple process-specific retention, compatibility and flow requirements. |
Additional Segmentation: By Process Stage
Process-stage segmentation includes lithography, wet etch and clean, deposition and etch gas delivery, chemical mechanical planarization, electronic-grade chemicals and ultrapure water. Each stage presents different contaminants and fluid properties, so filters cannot be standardized around a single pore rating. Application engineering and validation are therefore central to commercial differentiation across these process steps.
| Process Stage | Demand characteristics |
|---|---|
| Lithography | Photoresist and developer filtration targets particles, gels, metals and microbubble-related defects. |
| Wet Etch & Clean | Aggressive acids and bases require chemically compatible media with nanometer-scale retention and stable flow. |
| Deposition & Etch Gas | Ultra-high-purity gases require low-shedding filters and purification close to the process tool. |
| CMP | Slurry filters must remove harmful large particles without stripping useful slurry distribution. |
| Chemical & UPW | Bulk chemicals and ultrapure water need consistent contamination control throughout fab distribution. |
Segment Analysis: By Application
By application, foundry manufacturing is the largest demand pool because leading-edge logic combines high wafer volumes with stringent contamination requirements. Memory manufacturing also uses extensive chemical, gas and slurry filtration, while solar semiconductor production applies related contamination-control principles at different cost and purity targets. Replacement demand is recurring because filters load over time and are changed under preventive-maintenance or process-control schedules.
| Application | Demand characteristics |
|---|---|
| Semiconductor Foundry Manufacturing | Leading-edge and mature-node logic fabs use filters across lithography, cleans, CMP, gas delivery and chemical systems; largest demand base. |
| Memory Manufacturing | DRAM and NAND fabs have high process-step counts and large wafer volumes, creating recurring filter replacement demand. |
| Solar Semiconductor Manufacturing | Photovoltaic manufacturing uses chemical and water filtration, though specifications and economics differ from advanced IC fabs. |
Additional Segmentation: By Filter Media
Filter-media selection depends on chemistry, temperature, extractables, mechanical strength and required retention. PTFE is widely used where chemical resistance is critical, while UPE or polyethylene, PES and nylon serve specific liquid applications. Metal-fiber or sintered-metal media are relevant to ultra-high-purity gas streams. The commercial market therefore rewards suppliers that can match media properties to specific process fluids without adding contamination.
| Filter Media | Commercial relevance |
|---|---|
| PTFE | Excellent chemical resistance for aggressive semiconductor chemicals and process applications. |
| UPE / PE | High-purity polymer media used in selected liquid chemical and photolithography applications. |
| PES | Hydrophilic media suited to selected aqueous and chemical filtration requirements. |
| Nylon | Used in lithography and other liquid applications where wettability and retention characteristics fit process needs. |
| Metal Media | High-purity gas filtration and harsh environments where low shedding and thermal stability are required. |
Regional Analysis
Asia Pacific leads semiconductor filter demand because Taiwan, South Korea, China, Japan and Singapore contain a large share of global wafer-fabrication capacity. North America is expanding advanced logic and memory capacity, while Europe is adding automotive, power and advanced-node fabs. Regional filter demand follows installed wafer capacity and process complexity more closely than end-device consumption because filters are consumed where wafers are processed.
Why does semiconductor filter demand track fab capacity more closely than chip sales?
Filters are consumed inside wafer fabs, so regional demand follows cleanroom process capacity, tool utilization and the number of filtration points per wafer process. A smartphone sold in Europe can contain chips fabricated in Taiwan, Korea or the United States; the filter demand occurs where the wafer is processed. New fabs therefore create a direct local market for qualification, initial fill and recurring replacement across process gases, liquids and water.
| Region | Position | Growth outlook | Demand profile | Supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | High | Foundry + memory fabs | Fab qualification and local support |
| North America | Expanding | High | Advanced logic, memory, analog | Application engineering and supply security |
| Europe | Strategic growth | Steady-high | Automotive, power, logic | Process compatibility and local support |
| South America | Small | Moderate | Downstream / limited fabs | Imported supply |
| Middle East & Africa | Emerging | Selective | New semiconductor projects | Project qualification and logistics |
Competitive Landscape
Competition is led by contamination-control specialists with deep semiconductor application expertise. Pall and Entegris are prominent global suppliers, while Nippon Seisen, Exyte Technology, Camfil, Donaldson, AAF, Porvair, Mott, Cobetter and others participate across gas, liquid, cleanroom and process-specific filtration. Commercial differentiation depends on process qualification, media science, low extractables, retention performance and support inside customer fabs.
Semiconductor filters are recurring consumables, but replacement is not purely price-driven. A filter validated in a photoresist, CMP slurry or high-purity gas system can remain specified for years because customers avoid changes that may alter defectivity. This creates attractive installed-base economics but also raises the cost of winning new design-ins, since suppliers need extensive test data and application engineering.
Advanced nodes increase value per filtration point. Pall publicly describes retention down to 2nm in selected wet-clean chemistry and very fine PTFE filtration for high-purity chemicals, illustrating how particle-control requirements continue to tighten. Suppliers that maintain low pressure drop, cleanliness and chemical compatibility at these ratings can support higher flow without sacrificing contamination control.
| Competitive tier | Representative companies | Primary differentiation |
|---|---|---|
| Global semiconductor filtration leaders | Pall, Entegris | Broad process coverage, materials science, fab qualification and global application support. |
| Process and cleanroom specialists | Nippon Seisen, Exyte Technology, Camfil, Donaldson, AAF | Gas, liquid, air and contamination-control products across semiconductor facilities. |
| Specialized filter manufacturers | Porvair, Mott, Cobetter, Critical Process Filtration, Advantec | Niche media, metal filtration, regional supply and process-specific solutions. |
Key companies profiled
Pall, Entegris, Nippon Seisen, Exyte Technology, Camfil, Ecopro, CoorsTek, YESIANG Enterprise, Donaldson Company, AAF International, Purafil, Porvair, Dan-Takuma Technologies, Cobetter Filtration Group, Critical Process Filtration, Mott Corporation, SV Techsol and Advantec Group are included in the competitive scope. Their product coverage varies across process filters, cleanroom systems and broader contamination control.
Production Capacity Analysis
Filter production capacity includes high-purity membrane formation, cartridge assembly, metal-fiber fabrication, housing manufacturing, cleanroom assembly and final integrity testing. Semiconductor-grade capacity is more demanding than general industrial filtration because extractables, particle shedding and contamination introduced during assembly must be tightly controlled. Effective capacity therefore depends on qualified clean manufacturing and test capability, not only gross factory output.
Demand expands alongside fab capacity. SEMI projected advanced process capacity of 7nm and below to reach 1.4 million wafers per month by 2028, up 69% from 2024. More wafer starts and more complex process flows increase the number of filters in bulk chemical, point-of-use, CMP, lithography and gas systems. Suppliers need regional inventory and technical teams near fab clusters because filter failures or delayed qualification can affect tool uptime.
Market Dynamics
The market grows with semiconductor fab capacity, advanced-node complexity and tighter contamination budgets. Filter demand benefits from recurring replacement cycles, but suppliers face long qualification periods and strong pressure to prove defect reduction without disrupting flow. The most attractive opportunities are in advanced lithography, wet cleans, CMP and ultra-high-purity gas or chemical streams where process sensitivity is highest.
Market Drivers
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Fab capacity expansion | High | New wafer capacity creates initial and recurring demand across gas, chemical, slurry and water filtration. |
| Advanced-node contamination control | High | Smaller features require lower particle and metal levels, raising filter performance requirements. |
| Recurring replacement | Medium-High | Qualified filters are consumables with scheduled and condition-based replacement cycles. |
| Advanced packaging | Medium | New chemistries and fine interconnect processes create additional contamination-control steps. |
Fab construction directly expands the installed base
Each new fab includes bulk chemical systems, ultrapure water, process-gas delivery, lithography tracks, wet benches and CMP tools that require multiple filtration points. Once a fab begins production, filters become recurring consumables. This creates a durable link between semiconductor capital investment and filter demand.
Smaller nodes tighten contamination budgets
As features shrink, particles and metals that previously had little effect can cause bridging, opens or pattern defects. Fabs therefore move toward finer retention, lower extractables and more point-of-use filtration. The value of a filter is measured by avoided defects and stable process conditions, not simply by replacement price.
Recurring consumables support attractive aftermarket economics
Filters are replaced because of pressure drop, contamination loading, maintenance schedules or chemistry changes. Once a product is qualified, fabs often retain the same specification for long periods. This creates repeat revenue and gives suppliers a strong incentive to win initial process qualification early in a tool or fab ramp.
Advanced packaging adds new high-purity workflows
Hybrid bonding, fine-pitch redistribution and advanced interconnect processing use sensitive cleans, slurries and chemicals. These steps add contamination-control requirements outside traditional front-end wafer processing. Filter suppliers can therefore grow with advanced packaging even when front-end node scaling slows.
Market Restraints
| Restraint | Impact | Commercial consequence |
|---|---|---|
| Qualification cycles | High | New filters require process testing before adoption, slowing share gains. |
| High-performance filter cost | Medium | Finer retention and high-purity materials increase unit cost. |
| Process-specific complexity | Medium-High | Different chemistries need different media and ratings, limiting standardization. |
| Customer concentration | Medium | Large fabs and chemical suppliers can exert purchasing leverage. |
Qualification protects incumbents and slows new entrants
A filter change can affect chemistry, flow and defectivity, so fabs test new products carefully. Suppliers may need months of data before approval, especially in lithography or critical cleans. This raises sales costs and makes it difficult for smaller vendors to displace established products solely with lower pricing.
Advanced filters are expensive to manufacture
Nanometer-scale retention, ultra-low extractables, high-purity housings and clean assembly increase material and process cost. Customers will pay for measurable yield benefit, but mature-node fabs may resist premium products where contamination margins are wider. Suppliers must therefore align performance with process economics.
There is no single universal semiconductor filter
Photoresist, HF, CMP slurry, ammonia gas and ultrapure water have very different chemical and physical characteristics. Media that performs well in one stream may be unsuitable in another. This fragmentation raises R&D, inventory and qualification complexity across a broad product portfolio.
Large customers have significant negotiating power
Leading foundries, memory manufacturers and chemical suppliers buy large filter volumes and maintain rigorous approved-vendor lists. Their scale can pressure pricing and demand local technical support. Suppliers offset this through differentiated performance, long qualifications and products that reduce chemical use or tool downtime.
Market Opportunities
EUV and advanced lithography filtration
EUV photoresists and associated chemistries require extremely low defectivity. Advanced membrane designs that remove fine particles and gels without harming chemical performance can capture premium value because lithography defects are costly.
2nm-class wet-clean filtration
Pall’s published 2nm retention capability for selected wet-clean chemistry illustrates the direction of process requirements. Similar high-retention products can expand as nodes shrink and surface preparation becomes more sensitive.
Advanced packaging contamination control
Hybrid bonding, wafer-level packaging and fine redistribution layers add new chemical and slurry filtration steps. Suppliers can extend existing front-end expertise into packaging fabs and OSAT environments.
Regional fab localization
New fabs in the United States, Europe and other regions create opportunities for local stocking, service and application labs. Suppliers able to support qualification near customer sites can shorten response times and strengthen long-term relationships.
Supply Chain Analysis
Materials. PTFE, polyethylene, nylon, PES, metal fibers and high-purity housing materials form the upstream base. Material purity matters because a filter must remove contaminants without introducing extractables, metals or particles of its own. Semiconductor-grade resin and metal supply therefore has stricter specifications than general industrial filtration.
Manufacturing. Membrane formation, pleating, bonding, cartridge assembly and clean packaging determine retention and integrity. Advanced filters require controlled environments and extensive testing. Product consistency is critical because fabs expect every replacement cartridge to reproduce the qualified performance of the original.
Qualification and distribution. Suppliers work with chemical companies, equipment OEMs and wafer fabs to validate media and housings. Once approved, filters are stocked near fab clusters and replaced on scheduled or condition-based cycles. Local inventory reduces downtime risk and strengthens account retention.
End use. Foundries, memory fabs, IDMs, advanced packaging plants and solar semiconductor manufacturers consume filters across gases, chemicals, slurries and water. The highest-value applications are those where a small contamination excursion can scrap expensive wafers or interrupt high-utilization tools.
Recent Developments in the Semiconductor Filters Market
Developments tracked through September 2026. Entries are limited to events that materially affect product capability, manufacturing capacity, customer adoption, channel access or the competitive structure of the market.
- 25 June 2025
SEMI forecast global 7nm-and-below capacity to rise 69% from 850,000 wafers per month in 2024 to 1.4 million in 2028. The expansion directly increases demand for high-purity filtration in advanced lithography, cleans, gases and CMP. Source - 2025–2026
Pall highlighted semiconductor filtration across lithography, wet etch, CMP, process gases, chemicals and ultrapure water, emphasizing tighter contamination control as device geometries shrink. The portfolio illustrates the growing number of filtration points inside advanced fabs. Source - 2025–2026
Pall’s wet-clean filtration portfolio describes 2nm retention in critical HF and BOE surface-preparation chemistry, demonstrating the direction of advanced-node particle control and the premium placed on retention with manageable pressure drop. Source
Report Scope & Segmentation
| Attribute | Scope |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| 2025 market size | USD 1,408 million |
| 2026 estimated size | USD 1,554 million |
| 2034 projected size | USD 3,430 million |
| CAGR (2026–2034) | 10.4% |
| Largest market in 2025 | Asia Pacific |
| By Type | Semiconductor Gas Filter; Semiconductor Liquid Filter |
| By Application | Semiconductor Foundry Manufacturing; Memory Manufacturing; Solar Semiconductor Manufacturing |
| By Process Stage | Lithography; Wet Etch & Clean; Deposition & Etch Gas; CMP; Chemical & Ultrapure Water |
| By Filter Media | PTFE; UPE/PE; PES; Nylon; Metal |
| Companies profiled | Pall; Entegris; Nippon Seisen; Exyte Technology; Camfil; Ecopro; CoorsTek; YESIANG; Donaldson; AAF; Purafil; Porvair; Dan-Takuma; Cobetter; Critical Process Filtration; Mott; SV Techsol; Advantec |
Frequently Asked Questions
What is the semiconductor filters market size in 2025?
The global semiconductor filters market is valued at USD 1,408 million in 2025. The market includes gas and liquid filter elements used across semiconductor wafer fabrication, memory manufacturing and related high-purity production processes.
What is the semiconductor filters market forecast for 2034?
The market is projected to reach USD 3,430 million by 2034, representing a 10.4% CAGR during 2026–2034. The corresponding 2026 market level is USD 1,554 million.
Which region leads semiconductor filter demand?
Asia Pacific leads because it contains the largest concentration of semiconductor foundry and memory fabrication capacity across Taiwan, South Korea, China, Japan and Southeast Asia.
What are the main types of semiconductor filters?
The market is divided into semiconductor gas filters and semiconductor liquid filters. Gas filters protect ultra-high-purity process streams, while liquid filters serve photoresists, wet chemicals, CMP slurries and ultrapure water.
Why are filters important in semiconductor manufacturing?
Filters remove particles, gels, metals and other contaminants that can create wafer defects, damage equipment or destabilize process chemistry. Their importance increases as feature sizes shrink and contamination budgets become tighter.
Which applications consume the most filters?
Foundry and memory fabs consume large filter volumes because they run many chemical, gas, lithography, CMP and cleaning steps at high wafer throughput. Advanced packaging is also adding contamination-control demand.
What makes a semiconductor filter difficult to replace?
Fabs validate filters within specific chemistries and tools. A replacement can alter flow, extractables or defectivity, so customers require qualification data before switching. This creates high technical switching costs.
Which filter media are commonly used?
PTFE, polyethylene or UPE, PES, nylon and metal media are used depending on chemistry, gas type, temperature and retention requirements. No single material is optimal for every semiconductor process.
Who are the major semiconductor filter suppliers?
Major suppliers include Pall and Entegris, alongside Nippon Seisen, Camfil, Donaldson, AAF, Porvair, Mott, Cobetter, Advantec and other specialized contamination-control companies.
What will drive market growth through 2034?
Growth will come from more wafer-fab capacity, advanced-node contamination requirements, recurring replacement cycles, EUV lithography, advanced cleans and expanding advanced packaging. Qualification time and product cost will remain the main barriers.
Research Sources & Evidence Base
View research sources used in this market overview
- SEMI – Advanced chipmaking capacity forecast through 2028. Advanced-node fab capacity and investment context, June 2025.
- Pall Corporation – Semiconductor Filtration & Purification Solutions. Process coverage and contamination-control evidence.
- Pall Corporation – Wet Etch & Cleans. 2nm retention and wet-clean application evidence.
- Pall Corporation – Process Gas Filtration. Ultra-high-purity gas filtration and low-shedding requirements.

Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF