Key Statistics
Key Takeaways
- Equipment is a leading product category because it addresses the largest current application base.
- Communication & Network Equipment is a major application, with demand shaped by performance, reliability and system integration.
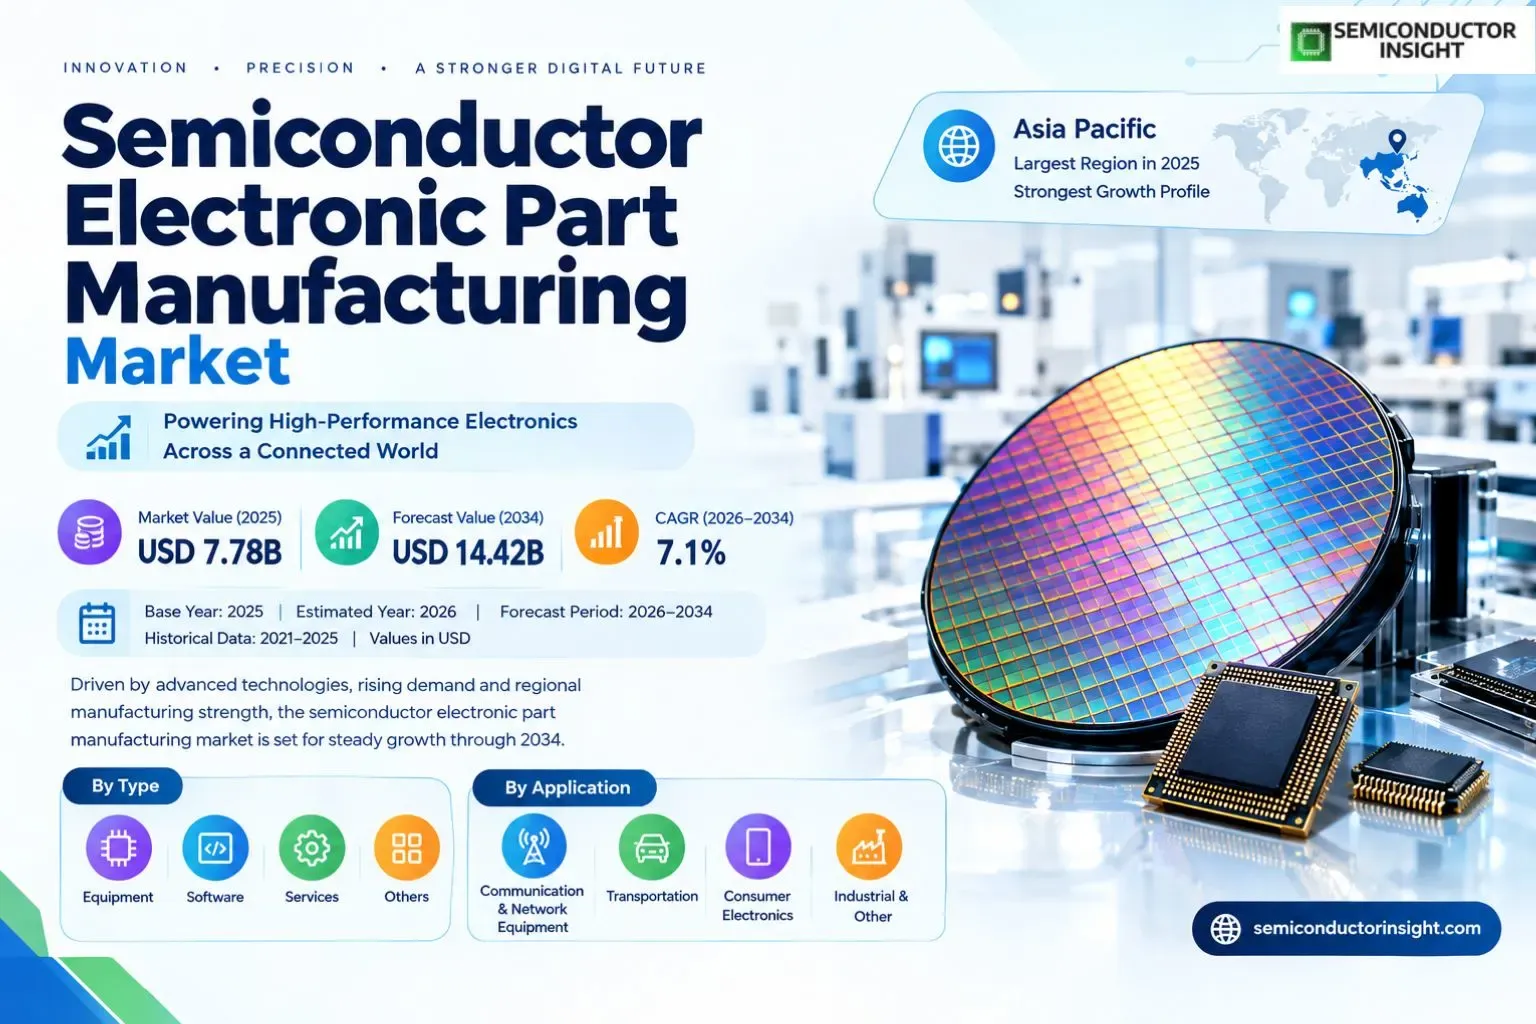
- Asia Pacific leads current market value, while Asia Pacific provides the strongest growth profile.
- Leading-edge process scaling, advanced packaging and regional manufacturing diversification is the main technology direction influencing new design wins.
- Market size and growth: USD 7.78 billion in 2025 is projected to reach USD 14.42 billion by 2034 at a 7.1% CAGR during 2026–2034.
Semiconductor Electronic Part Manufacturing Market Overview
Semiconductor electronic part manufacturing market was valued at USD 7.78 billion in 2025 and is projected to reach USD 14.42 billion by 2034, growing at a CAGR of 7.1% over the 2026–2034 forecast period. Asia Pacific held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.
Semiconductor electronic part manufacturing covers the fabrication, assembly, packaging, testing and supporting production services used to turn semiconductor designs into qualified electronic components and modules. Commercial decisions in the Semiconductor Electronic Part Manufacturing market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
The client evidence values the market at USD 6.78 billion in 2023 and projects USD 10.95862 billion by 2030 at a 7.1% CAGR. North America represented USD 1.76667 billion in 2023, while Asia Pacific is the largest manufacturing region. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
TSMC’s 2025 annual report and Intel’s 2026 foundry updates show continued investment in leading-edge wafer fabrication and advanced packaging. Intel reported 18A production in 2025 and 18A-P risk production in 2026, while expanding packaging and European manufacturing capacity. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Segment Analysis: By Type
By type, the semiconductor electronic part manufacturing market is segmented into Equipment, Software, Services, Others. Each category has a distinct functional role and commercial position, so the analysis emphasizes use case, integration and competitive relevance rather than repeating a single market statistic across every row. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
| Type | Function | Market position |
|---|---|---|
| Equipment | Equipment addresses a distinct architecture or performance requirement within the Semiconductor Electronic Part Manufacturing market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Software | Software addresses a distinct architecture or performance requirement within the Semiconductor Electronic Part Manufacturing market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Services | Services addresses a distinct architecture or performance requirement within the Semiconductor Electronic Part Manufacturing market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
| Others | Others addresses a distinct architecture or performance requirement within the Semiconductor Electronic Part Manufacturing market. | Commercial demand depends on application fit, qualification, cost and lifecycle requirements rather than a single headline statistic. |
Pricing by type
Wafer-fabrication and advanced-packaging services command premium economics where leading-edge process capability, yield and customer qualification are scarce. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Semiconductor Electronic Part Manufacturing market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Segment Analysis: By Application
By application, the market is segmented into Communication & Network Equipment, Transportation, Consumer Electronics, Industrial & Other. Application economics differ by qualification, lifecycle, reliability and system-level value, so each row below uses context specific to that application rather than mechanically repeating headline evidence. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
| Application | Demand characteristics |
|---|---|
| Communication & Network Equipment | Communication & Network Equipment creates demand where semiconductor electronic part manufacturing improves integration, performance, reliability or system economics. |
| Transportation | Transportation creates demand where semiconductor electronic part manufacturing improves integration, performance, reliability or system economics. |
| Consumer Electronics | Consumer Electronics creates demand where semiconductor electronic part manufacturing improves integration, performance, reliability or system economics. |
| Industrial & Other | Industrial & Other creates demand where semiconductor electronic part manufacturing improves integration, performance, reliability or system economics. |
Regional Analysis
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile. Regional demand is shaped by manufacturing concentration, technology adoption, customer investment cycles and local supplier ecosystems. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
How does regional demand differ across the semiconductor electronic part manufacturing market?
Asia Pacific provides the deepest manufacturing scale, North America contributes high-value technology and enterprise demand, and Europe remains important in industrial, automotive and regulated applications. South America and the Middle East & Africa are smaller but developing markets. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Highest | wafer fabs, OSATs and electronics manufacturing | Supply scale and qualification |
| North America | High | Moderate-high | advanced-node logic, AI chips and domestic manufacturing | Technology capability and service |
| Europe | Moderate-high | Moderate | automotive semiconductors, industrial electronics and advanced packaging | Compliance and lifecycle |
| South America | Smaller | Moderate | Import/industrial led | Cost and distribution |
| Middle East & Africa | Smallest base | Emerging | Infrastructure led | Project support |
Key Semiconductor Electronic Part Manufacturing Manufacturers and Competitive Landscape
The competitive landscape includes TSMC, Samsung Electronics, Intel, SK hynix, Micron Technology, Qualcomm, Broadcom, Texas Instruments, Jabil, Flex. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Semiconductor Electronic Part Manufacturing market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Competition centers on leading-edge process scaling, advanced packaging and regional manufacturing diversification, customer qualification, manufacturing consistency and application support. Once a product is designed into a long-lifecycle system, switching costs can protect incumbent positions but also raise the importance of roadmap continuity. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | TSMC, Samsung Electronics, Intel, SK hynix | Global scale, broad customer qualification and advanced technology portfolios. |
| Tier 2 | Micron Technology, Qualcomm, Broadcom, Texas Instruments | Strong specialist capability, regional design wins and application-focused portfolios. |
| Tier 3 | Regional and niche suppliers | Cost competition, customization and specialized customer support. |
Key companies profiled
- TSMC
- Samsung Electronics
- Intel
- SK hynix
- Micron Technology
- Qualcomm
- Broadcom
- Texas Instruments
- Jabil
- Flex
Semiconductor Electronic Part Manufacturing Production Capacity Analysis
Production capacity in the Semiconductor Electronic Part Manufacturing market is shaped by the underlying manufacturing process, qualification burden and customer-specific configuration. Suppliers must balance equipment utilization with quality control because high-volume output only creates value when yield, reliability and traceability remain stable. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Capacity additions tend to follow customer program ramps rather than headline market growth alone. Regional supply resilience is becoming more important, particularly where customers require second-source planning, long product lifecycles or shorter engineering-response times. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
The practical bottleneck is often qualified output rather than nominal installed capacity. Manufacturing, assembly, test and application support must scale together to avoid creating capacity that cannot be used in production programs. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Semiconductor Electronic Part Manufacturing Market Dynamics: Drivers, Restraints and Opportunities
The Semiconductor Electronic Part Manufacturing market is shaped by growth is driven by ai, 5g, automotive electronics, consumer devices and industrial automation, all of which require more semiconductor content and manufacturing capacity. At the same time, growth is constrained by capital intensity, long fab construction cycles, advanced-equipment availability, skilled labor and cyclical inventory corrections. The strongest commercial opportunities are concentrated in leading-edge logic, advanced packaging, trusted regional manufacturing and ai-oriented semiconductor production create the strongest opportunities.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Technology upgrade cycle | +1.6% | Global; strongest in leading adopter markets | Near to medium term |
| End-market expansion | +1.2% | Application-specific | Near term |
| Higher value per system | +0.8% | Premium and advanced systems | Medium term |
Technology adoption expands addressable demand
Growth is driven by AI, 5G, automotive electronics, consumer devices and industrial automation, all of which require more semiconductor content and manufacturing capacity. This demand is strongest where customers can measure a clear improvement in system performance, footprint, energy efficiency, reliability or operating cost. Commercial decisions in the Semiconductor Electronic Part Manufacturing market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
End-market modernization increases content per system
The technology upgrade cycle supports replacement and redesign activity as OEMs move to higher-performance architectures. New designs typically create the best opportunity because suppliers can influence specifications before qualification is locked. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Higher-value architectures support premium mix
Expanding end markets also increase content per system, creating value growth even when unit shipments grow more slowly. Suppliers that combine engineering support with reliable supply are better positioned to capture those design transitions. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Qualification and integration burden | -0.7% | Global | Ongoing |
| Price and substitution pressure | -0.5% | Cost-sensitive applications | Ongoing |
| Supply-chain or process complexity | -0.4% | Global | Medium term |
Qualification burden slows supplier switching
Growth is constrained by capital intensity, long fab construction cycles, advanced-equipment availability, skilled labor and cyclical inventory corrections. These constraints are most significant where customers have qualified alternatives or where the technology must prove a clear system-level advantage over lower-cost incumbent solutions. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Price competition limits margin expansion
Qualification and integration can extend sales cycles because customers must validate performance, reliability and compatibility in their own system environment. That makes early engineering engagement important for new suppliers. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Alternative technologies constrain selected use cases
Supply-chain complexity can also limit growth when specialized materials, tooling, test or regional support are required. Customers increasingly evaluate resilience alongside price when choosing long-lifecycle suppliers. Commercial decisions in the Semiconductor Electronic Part Manufacturing market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
MARKET OPPORTUNITIES
Advanced integration creates premium opportunities
Leading-edge logic, advanced packaging, trusted regional manufacturing and AI-oriented semiconductor production create the strongest opportunities. The most attractive opportunities are where customers are redesigning systems rather than simply replacing like-for-like components. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Regional capacity and supply resilience
Leading-edge process scaling, advanced packaging and regional manufacturing diversification can create premium value when it lowers system complexity, improves performance or supports a new product architecture that is difficult to achieve with incumbent approaches. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Application engineering deepens customer value
Regional engineering support and application-specific customization provide another route to growth because customers increasingly expect suppliers to support qualification, transition planning and lifecycle management. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Semiconductor Electronic Part Manufacturing Supply Chain Analysis
Upstream. Silicon wafers, chemicals, gases, lithography and process equipment, packaging substrates, test equipment, cleanroom infrastructure and manufacturing software form the supply chain. Supply quality at this stage directly affects downstream yield, reliability and cost. Commercial decisions in the Semiconductor Electronic Part Manufacturing market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Manufacturing. Core production combines process control, assembly, inspection and test, with product-specific qualification used to verify performance before customer shipment. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Distribution. High-value programs are typically won through direct OEM, Tier-1 or design-house engagement, while distributors serve prototypes, regional customers and lower-volume applications. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Downstream. End users integrate the product into systems where switching costs rise after qualification, making lifecycle support and supply continuity commercially important. Commercial decisions in the Semiconductor Electronic Part Manufacturing market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Downstream. Panel builders and machine OEMs are the primary specifying customers, followed by electrical contractors working on building services and by facility maintenance teams handling replacement. The specification decision is usually made once, at panel design, and then repeats for the life of the design — which makes design-in position considerably more valuable than any individual transaction.
Recent Developments in the Semiconductor Electronic Part Manufacturing Market
Developments tracked through September 2026. Items are selected for direct relevance to product technology, deployment or standards. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
- 2026 Manufacturing
Intel 18A-P enters risk production Intel Foundry reported that 18A-P entered risk production in 2026 after 18A entered production in 2025. Source - 2026 Investment
Intel expands European manufacturing Intel announced a €5 billion investment to expand manufacturing capacity at its Leixlip, Ireland campus. Source - 2026 Current
TSMC publishes 2025 annual report TSMC’s 2025 annual report and 20-F provide current manufacturing, capacity and technology roadmap context. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2021–2025 |
| Market Size 2025 | USD 7.78 billion |
| Market Size 2034 | USD 14.42 billion |
| Growth Rate | CAGR of 7.1% from 2026–2034 |
| Unit | Value (USD Million) |
| Segmentation | By Type, By Application, By Manufacturing Stage, By Technology Focus, and By Region |
| By Type | Equipment · Software · Services · Others |
| By Application | Communication & Network Equipment · Transportation · Consumer Electronics · Industrial & Other |
| By Technology Focus | Logic / Compute · Memory · Analog / Power · RF / Connectivity |
| By Manufacturing Stage | Wafer Fabrication · Assembly & Packaging · Testing · Electronics Manufacturing Services |
| By Region | Each region analysed by Type, Application and Country North AmericaU.S., Canada, Mexico EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux AsiaChina, Japan, South Korea, India, Southeast Asia South AmericaBrazil, Argentina, Rest of South America Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA |
| Key Companies Profiled | TSMC, Samsung Electronics, Intel, SK hynix, Micron Technology, Qualcomm, Broadcom, Texas Instruments, Jabil, Flex |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the current size of the Semiconductor Electronic Part Manufacturing market?
The market is valued at USD 7.78 billion in 2025 and is projected to reach USD 14.42 billion by 2034, expanding at a 7.1% CAGR during 2026–2034.
Which companies lead the Semiconductor Electronic Part Manufacturing market?
Key participants include TSMC, Samsung Electronics, Intel, SK hynix, Micron Technology, Qualcomm, Broadcom, Texas Instruments.
What is Semiconductor Electronic Part Manufacturing?
Semiconductor electronic part manufacturing covers the fabrication, assembly, packaging, testing and supporting production services used to turn semiconductor designs into qualified electronic components and modules.
What are the main product types?
The market includes Equipment, Software, Services, Others.
What are the key applications?
The principal applications are Communication & Network Equipment, Transportation, Consumer Electronics, Industrial & Other.
Which region leads the market?
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile.
What drives market growth?
Growth is driven by AI, 5G, automotive electronics, consumer devices and industrial automation, all of which require more semiconductor content and manufacturing capacity.
What are the main challenges?
Growth is constrained by capital intensity, long fab construction cycles, advanced-equipment availability, skilled labor and cyclical inventory corrections.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF