
Key Statistics
Key Takeaways
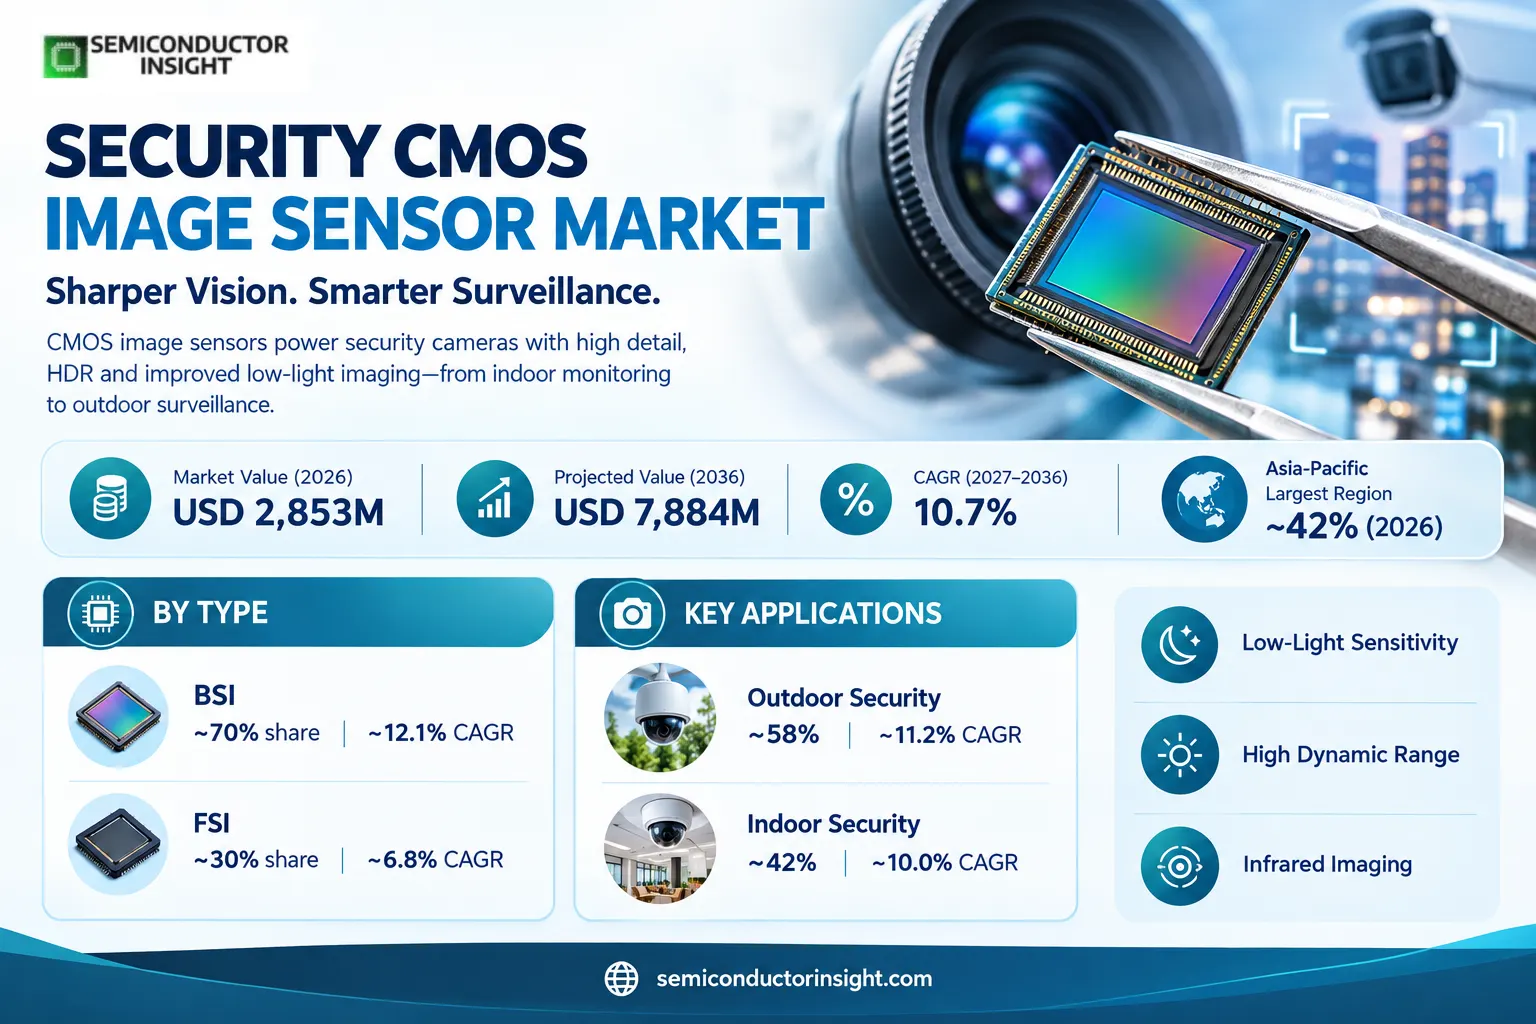
- Market trajectory: the global security CMOS image sensor market is valued at USD 2,853 million in 2026 and is projected to reach USD 7,884 million by 2036, expanding at 10.7% during the forecast window. These values measure sensor-chip revenue rather than camera systems, recorders, cloud video services or installation spending.
- Backside illumination: BSI devices hold an estimated ~70% of 2026 sensor revenue and grow near ~12.1% CAGR because low-light performance, near-infrared sensitivity and high dynamic range matter for 4MP and 8MP surveillance designs; FSI remains relevant in cost-sensitive and mature designs with an estimated ~30% share.
- Outdoor security: Outdoor deployments account for an estimated ~58% of revenue and grow near ~11.2% CAGR as traffic, industrial perimeter and municipal cameras require 24-hour capture; indoor security represents ~42%, driven by business facilities, smart homes and battery-powered video doorbells.
- Regional pattern: Asia-Pacific leads at an estimated ~42% of 2026 revenue and ~11.1% CAGR, supported by image-sensor supply chains in Japan, China and South Korea and broad surveillance camera assembly; North America contributes ~25%, and Europe ~20% with more procurement emphasis on privacy and cybersecurity.
- Technology and constraints: Sony IMX908 combines 8.4 megapixels with 96 dB single-exposure HDR and 1.45 µm pixels, while OMNIVISION offers 4MP Nyxel sensors with 850 nm and 940 nm near-infrared capability. Competition centres on image quality per watt, yield, device qualification and surveillance privacy safeguards.
Security CMOS Image Sensor Market Overview
The security CMOS image sensor market reached USD 2,853 million in 2026 and is projected to grow to USD 7,884 million by 2036, representing a CAGR of 10.7% across 2027–2036. Asia-Pacific accounts for the largest estimated regional share at ~42% in 2026, while BSI sensors contribute an estimated ~70% of product revenue.
Security CMOS image sensors convert incident photons into digital image signals inside surveillance cameras, video doorbells, traffic-monitoring devices and industrial safety cameras. They are purchased as semiconductor devices and integrated with lenses, infrared illumination, image-signal processors and network video software. The relevant revenue boundary therefore includes sensor dies and packaged sensor chips sold for security imaging, but excludes complete cameras, storage hardware, video management subscriptions and system installation services.
Security design requirements differ sharply from smartphone imaging because many cameras operate continuously through daylight, backlighting and darkness. Sony markets its STARVIS, STARVIS 2 and STARVIS 3 back-illuminated pixel technologies specifically for security cameras, with sensitivity and HDR characteristics designed for low-light surveillance. OMNIVISION separately offers PureCel Plus and Nyxel near-infrared sensor families that target home security and commercial surveillance rather than treating all mobile-image-sensor shipments as addressable security demand.
Image-sensor value is affected by resolution, pixel size, optical format and interface speed rather than camera count alone. Sony introduced the IMX908 in March 2026 with 8.4 effective megapixels, 1.45 µm LOFIC pixels and 96 dB HDR. OMNIVISION OS08C10 provides 8MP resolution in a 1/2.8-inch format and can output 4K video at 60 fps. These capabilities support premium surveillance camera designs but do not imply that every installed camera uses the newest sensor generation.
The market spans frontside-illuminated and backside-illuminated architectures, with BSI gaining value where photons must be collected through smaller pixels or where cameras use 850 nm or 940 nm illumination. The application split distinguishes indoor monitoring from outdoor security, although some sensor models are qualified for both. A separate resolution lens helps explain mix: 2MP products still serve budget installations, 4MP devices balance detail and bandwidth, and 8MP products raise value per camera in critical environments.
Regional demand and manufacturing should not be conflated. Japanese and Chinese semiconductor suppliers may ship chips to camera factories that subsequently export finished products to Europe or North America; the chip manufacturing location is not necessarily the final sensor demand location. Regional estimates use a demand-side allocation, with North America’s published 2023 value of USD 547.98 million providing a historical check rather than a direct 2026 percentage. Surveillance regulation and privacy design also influence customer purchasing decisions.
Segment Analysis: By Type
By type, security CMOS image sensors are classified into frontside-illuminated (FSI) and backside-illuminated (BSI) devices. BSI represents an estimated ~70% of 2026 revenue and expands near ~12.1% CAGR because high-resolution and night-vision cameras increasingly require strong photon collection, while FSI holds ~30% and grows near ~6.8% CAGR in legacy and lower-cost designs.
| Type | Sensor architecture and security use | Market position |
|---|---|---|
| BSI | Backside illumination places the light-receiving side above much of the interconnect structure, improving sensitivity in compact 2.0 µm and 1.45 µm pixel arrays. Sony STARVIS generations and OMNIVISION PureCel Plus-S and Nyxel products apply these principles to 4MP and 8MP security cameras where nighttime evidence, 850 nm or 940 nm illumination and 60 fps output are relevant. | Largest share (~70%, ~12.1% CAGR). BSI sensors earn a premium where buyers value usable detail in poor illumination rather than nominal pixel count. A 4MP BSI device with strong infrared response can outperform a higher-resolution older device at night; however, added process complexity and supply qualification still matter for high-volume low-price surveillance tenders. |
| FSI | Frontside illumination collects light through the side containing pixel wiring, a structure that remains serviceable when pixels are larger, resolution is moderate and the camera has adequate lighting. FSI products are most relevant to price-led 2MP or 4MP replacement installations and certain analog security channels that prioritize continuity, simple readout and stable component supply over premium night-vision performance. | Estimated ~30% share, ~6.8% CAGR. FSI remains an addressable part of the installed security camera supply chain but loses revenue mix as vendors redesign platforms around backside illumination. It is not technically obsolete for every use case: controlled indoor lighting, low frame rates and a constrained bill of materials can still favor mature architectures over advanced HDR features. |
Backside-Illuminated Sensors
BSI adoption is driven by measurable imaging outcomes rather than the label alone. Sony IMX908 uses a 1/2.8-type optical format and 1.45 µm LOFIC pixels to combine 4K imaging with 96 dB HDR, while the OMNIVISION OS04J10 uses 2.9 µm BSI pixels in a 4MP format for demanding low-light scenes. These devices illustrate distinct performance routes: compact pixels and charge handling versus larger pixels with near-infrared sensitivity.
Security integrators evaluate BSI devices using SNR1, near-infrared quantum efficiency, dynamic range and motion artifacts. OMNIVISION OS04A10 reports quantum efficiency of 60% at 850 nm and 40% at 940 nm, helping reduce the infrared illuminator power needed at night. The commercial benefit appears in camera power, thermal design and recognition reliability, not only in the semiconductor component price.
Frontside-Illuminated Sensors
FSI remains relevant to legacy cameras with modest pixel densities and predictable illumination. Many buyers replace failed 2MP or 4MP cameras without upgrading every network switch, recorder and cable, so sensor suppliers can continue shipping mature designs through established OEM platforms. The opportunity is narrower than premium BSI because competing products offer higher night sensitivity at similar optical formats, which puts pressure on FSI pricing.
For procurement, the choice between FSI and BSI depends on lens quality, exposure time, infrared power and the amount of motion in the scene. A lower-cost frontside sensor may satisfy a well-lit corridor but can struggle with moving subjects against headlights outdoors. System integrators should compare complete imaging performance and life-cycle availability instead of assuming that an architecture label guarantees a particular resolution or security outcome.
Segment Analysis: By Application
By application, outdoor security is the larger market at an estimated ~58% of 2026 revenue and grows near ~11.2% CAGR; indoor security contributes ~42% and expands near ~10.0% CAGR. The split reflects chip revenue in cameras deployed for the respective use case, not the revenue of completed surveillance systems or associated cloud services.
| Application | Demand characteristics |
|---|---|
| Outdoor Security | Estimated ~58% share, ~11.2% CAGR. Outdoor sensors serve traffic intersections, transport hubs, perimeter fences, parking areas and municipal surveillance. They require 4MP or 8MP detail, strong 850 nm near-infrared response, 60 fps options and reliable operation under street lighting or direct sunlight. Sony’s IMX908 96 dB HDR and OMNIVISION’s OS08E10 8MP Nyxel capabilities illustrate the image-quality requirements, while camera weatherproofing remains outside sensor revenue. |
| Indoor Security | Estimated ~42% share, ~10.0% CAGR. Indoor sensors support offices, retail aisles, apartment entrances, warehouses, baby monitors and video doorbells. Power and compact packaging matter for battery-powered cameras; OMNIVISION OS04D10 targets 2K security and smart-home designs, while OS04E10 uses a 2K-by-2K square array for fisheye and wide-field-of-view formats. Cloud recording and analytics may influence purchasing but are not counted as sensor sales. |
The outdoor mix has a higher average sensor value because recognition at distance benefits from resolution, optical size and HDR. An 8MP sensor with 3840 × 2160 output can preserve more detail than a 2MP design at the same field of view, but it also increases data rates and system storage requirements. These trade-offs affect the pace of adoption in traffic and critical-infrastructure installations.
Indoor adoption is more diverse: battery video doorbells emphasize milliwatt-level power and wake-up behavior, whereas office security emphasizes network reliability and long-term firmware support. OMNIVISION OS04C10 explicitly targets low-power home monitoring and 940 nm infrared illumination, showing how the semiconductor specification can be optimized for residential use even when the same supplier serves professional outdoor cameras.
Regional Analysis
Asia-Pacific is the largest security CMOS image sensor demand region at an estimated ~42% of 2026 revenue, followed by North America at ~25%, Europe at ~20%, South America at ~7% and the Middle East and Africa at ~6%. These are modeled demand allocations, distinct from the geographic location of wafer fabrication or camera assembly. Regional growth varies from ~9.8% CAGR in Europe to ~12.5% in the Middle East and Africa.
Where are security image sensors used and purchased?
Asia-Pacific combines several parts of the security imaging value chain: Japanese and Chinese sensor design, semiconductor manufacturing, camera electronics assembly and large domestic video-surveillance markets. Sony’s March 2026 IMX908 launch and OMNIVISION’s security product portfolio demonstrate the technology investment supporting this region. Camera makers may export assembled devices to other continents, so production volume is not a direct proxy for local sensor consumption.
North American demand is supported by commercial security retrofits, municipal infrastructure and smart-home cameras. The published historical market reference of USD 547.98 million in 2023 provides a useful check on the region’s size, but it does not directly establish a 2026 share. Europe places particular weight on video privacy and retention safeguards under EDPB guidance, while Latin America and the Middle East and Africa combine targeted public infrastructure installations with budget-sensitive replacement demand.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | LARGEST (~42%) | ~11.1% CAGR | Japan’s 8.4MP IMX908 engineering and Chinese 4MP camera integration both influence product selection; the ~42% estimated component-demand share reflects final sensor use, not all cameras exported from regional factories. The allocation distinguishes wafer design and fabrication from local chip consumption and avoids treating export camera shipments as separate regional sensor sales. | Regional OEMs qualify 1.45 µm and 2.9 µm pixel devices for different optics, compare 850 nm and 940 nm night sensitivity and evaluate 60 fps MIPI interfaces. A supplier with stable 4MP and 8MP designs can serve domestic and export camera platforms. Japanese STARVIS and Chinese camera platform choices also affect long-term component availability, price negotiation and the pace of sensor qualification across the supply chain. |
| North America | SECOND LARGEST (~25%) | ~10.2% CAGR | Commercial 8MP 4K upgrades and 4MP smart-home devices create distinct demand streams, while the historical 2023 regional figure of USD 547.98 million helps check the ~25% 2026 modeled allocation. Premium sensor purchases are concentrated in systems where better recognition and low-light performance justify additional network and recording expenditure rather than in every replacement camera. | North American camera buyers emphasize reliable HDR, power efficiency, privacy configuration and compatibility with installed 2MP or 4MP systems. An 8MP upgrade can require additional storage, so low-light gains and cost of ownership matter as much as sensor specifications. Procurement teams often retain existing switches and recorder software, so sensors that fit proven camera platforms have a commercial advantage over incompatible 4K upgrades. |
| Europe | THIRD LARGEST (~20%) | ~9.8% CAGR | Industrial, transit and property monitoring drive 4MP and 8MP sensor demand, with a modeled ~20% regional share and privacy safeguards under EDPB video-device guidance influencing camera deployment decisions. Public and private operators must assess the purpose and retention of recorded images, which can change the number and placement of cameras without changing semiconductor specifications. | European integrators evaluate HDR artifacts, 850 nm or 940 nm infrared performance, long-term supply and secure video processing. The 96 dB HDR IMX908 is a useful high-end benchmark, but camera operators must separately meet data-protection obligations. Security integrators should validate the complete optical path and recording architecture under local requirements, since a high-performing chip is not a substitute for lawful deployment. |
| South America | FOURTH (~7%) | ~11.0% CAGR | Brazilian commercial security and urban monitoring lead a price-sensitive regional opportunity, where 2MP replacement systems coexist with 4MP mainstream upgrades and selective 8MP adoption; the modeled share is ~7%. The gap between a low-cost replacement and a premium night camera can be substantial when financing, local service and import taxes are included in the buyer’s decision. | Distributors and camera OEMs weigh import pricing, power, warranty support and 4MP optical compatibility. Sensor revenue is distinct from network recorders, camera enclosures and installation, and currency movements can delay adoption of premium 8MP BSI designs. For outdoor sites, the interaction of infrared emitter power, lens quality and 4MP sensor sensitivity can matter more than advertised pixel counts or a newer sensor-generation label. |
| Middle East & Africa | FIFTH · FASTEST GROWTH (~6%) | ~12.5% CAGR | Industrial perimeter and transport security create demand for 4MP and 8MP night-capable imaging, with a smaller ~6% modeled base but ~12.5% growth in infrastructure-led deployments. Large projects may require supplier continuity for several years, particularly where camera access is difficult and outdoor temperatures put pressure on housings and electronics. Serviceability and lens contamination also affect operating costs. | Procurement places weight on heat tolerance, 96 dB HDR capture in harsh sunlight, 850 nm and 940 nm infrared illumination and reliable replacement supply. Camera-integrator capability matters because the sensor alone cannot deliver complete site surveillance. The most valuable opportunities combine robust imaging silicon with locally supported camera integration, stable procurement channels and practical testing under the actual installation conditions. |
Security CMOS Image Sensor Manufacturers and Competitive Landscape
The security CMOS sensor supply base includes specialist imaging companies and diversified semiconductor suppliers. Sony Semiconductor Solutions, OMNIVISION, onsemi and PIXELPLUS have identifiable security imaging portfolios; other firms listed in industry directories may participate in adjacent mobile, automotive or camera electronics categories rather than sell equivalent security sensor chips. Competition centers on pixel architecture, 4MP and 8MP image quality, low-light sensitivity, power, package compatibility and OEM qualification.
Sony’s STARVIS product family focuses on high sensitivity, HDR and near-infrared capture for surveillance cameras. The IMX908 announced on 17 March 2026 combines 8.4 effective megapixels with 1.45 µm LOFIC pixels and 96 dB HDR; the earlier IMX675 provides approximately 5.12MP and dual-speed streaming. This range illustrates how sensor suppliers differentiate through imaging architecture rather than simply supplying one interchangeable camera component.
OMNIVISION serves multiple security price points through OS08C10, OS08E10, OS04A10, OS04C10, OS04D10, OS04E10, OS04F10 and OS04J10. The portfolio spans 4MP and 8MP resolutions, 1.45 µm to 2.9 µm pixels, near-infrared sensitivity and low-power options. Breadth helps camera OEMs reuse a supplier relationship while changing optical format, lens design, frame rate or night-vision performance across different camera product tiers.
PIXELPLUS presents CMOS image sensors and video-processing semiconductor products, including 2MP RGB-IR devices and HDR-oriented designs. onsemi publishes security and surveillance image-sensor application architecture. These companies demonstrate alternatives to the largest portfolios, although published catalog availability does not reveal the proportion of total revenue earned specifically from security sensor chips or the number of qualified camera designs in each geography.
Commercial qualification involves pixel defect limits, SNR1 testing, HDR artifacts, temperature performance, interface timing and supply continuity. A 4MP sensor with 60 fps output and 850 nm sensitivity may win a night camera even if a competing 8MP device has a higher nominal resolution. Camera makers also weigh image-signal processor compatibility, lens cost, firmware support and second-source risk before changing a sensor in an established surveillance platform.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Broad security portfolios | Sony Semiconductor Solutions; OMNIVISION | These vendors offer multiple security-targeted image sensor generations covering 4MP, 5MP and 8MP classes, BSI pixels, 850 nm or 940 nm near-infrared sensitivity and advanced HDR. Camera manufacturers can select across optical formats and price tiers, but device-level qualification and supply commitments still determine whether a product enters a volume surveillance camera line. |
| Specialist and diversified suppliers | PIXELPLUS; onsemi | PIXELPLUS markets CMOS sensors and image-processing semiconductors with security applications, while onsemi provides imaging architectures for security and industrial surveillance. Their commercial positions differ by product and design win; neither a corporate name nor a broad imaging catalog should be equated with a verified security-chip market share without segment-specific revenue disclosures. |
Key companies profiled
- Sony Semiconductor Solutions
- OMNIVISION
- onsemi
- PIXELPLUS
Security CMOS Sensor Production and Technology Outlook
Security CMOS sensor production depends on wafer fabrication, pixel-stack processing, color-filter and microlens integration, wafer probing, packaging and camera-OEM qualification. BSI designs add specialized wafer processing and bonding considerations, while FSI devices use more mature architectures. Product-level specifications show technology differentiation, but neither supplier capacity nor camera assembly volume can be directly converted into the global security sensor revenue total.
A security sensor wafer contains pixel arrays, readout circuits and interfaces that must remain consistent across thousands of dies. For an 8.4MP array, pixel uniformity and dark-current performance affect whether the camera can produce usable night video; for a 4MP battery camera, active power and standby leakage are also critical. Wafer yield, test time and package quality therefore influence both selling price and delivery reliability.
Backside illumination shifts the optical collection path to improve photon access in dense pixel arrays. Sony’s STARVIS 3 technology combines a deep photodiode structure with LOFIC charge storage to address both dark and bright scenes, while OMNIVISION PureCel Plus-S uses stacked-die technology in compact packages. These are different technology implementations, and the manufacturing complexity must be weighed against the performance and selling-price premium available in surveillance cameras.
Product families must be qualified at the camera system level, including 10-bit and 12-bit output, MIPI lane count, HDR readout modes, lens shading and infrared illumination. OMNIVISION OS08C10 supports 3840 × 2160 output at 60 fps; Sony IMX908 supports 90 fps at 10-bit and 60 fps at 12-bit. Those rates require compatible processors and power budgets, making the sensor only one part of the final camera design. The OMNIVISION OV04C10 also specifies a 4MP RAW RGB output path with up to four MIPI lanes, giving designers an example of the interface trade-offs that accompany sensor resolution and frame-rate selection.
Long product lives and predictable replacement supply matter because installed surveillance networks are often upgraded gradually. A camera OEM may retain a 2MP or 4MP platform while adding an 8MP premium tier, and a sensor supplier that offers pin-compatible upgrades can reduce engineering effort. Production capacity is therefore valuable when matched with actual qualified demand; unsold inventory or broad semiconductor factory output is not a measure of security imaging market revenue.
Security CMOS Image Sensor Market Dynamics and Growth Opportunities
Growth comes from higher-value 4MP and 8MP imaging, migration toward BSI, stronger 850 nm and 940 nm night performance and the spread of video monitoring across commercial and residential settings. Restraints include price erosion, privacy requirements and the cost of upgrading storage and networking when resolution increases. Opportunity concentrates in sensors that improve usable evidence quality without proportionally increasing system power or data traffic.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| 4K security camera upgrades | +1.5% | North America, Europe, Asia-Pacific | Medium term (2027–2031) |
| BSI and HDR night performance | +1.3% | Global outdoor security | Long term (2027–2036) |
| Smart-home monitoring | +0.8% | North America and Asia-Pacific | Medium term (2027–2032) |
Higher resolution improves evidence detail
Moving from 2MP to 4MP and 8MP sensors increases the number of usable pixels across wide surveillance scenes, particularly when a camera covers an entrance, intersection or industrial perimeter. Sony’s IMX908 offers 8.4MP in a 1/2.8-type format, while OMNIVISION OS08C10 supports 3840 × 2160 output at 60 fps. The value uplift depends on the lens and image processing, but better detail is a consistent reason for premium camera redesigns.
Near-infrared performance expands night use
Many security installations operate after dark with 850 nm or 940 nm infrared illumination, so sensor quantum efficiency directly affects image quality and power requirements. OMNIVISION OS04A10 quotes 60% QE at 850 nm and 40% at 940 nm; its OS04J10 adds a 2.9 µm BSI pixel for low-light surveillance. Improved sensitivity can lower illuminator power and help camera makers offer night-capable products in more compact housings.
Dynamic range supports automated recognition
High-contrast scenes contain dark interiors and bright doorways, vehicle headlights and street lighting. Sony’s 96 dB single-exposure IMX908 HDR design aims to preserve information without some artifacts of multi-exposure merging, which can help downstream video analytics on moving objects. Buyers do not pay for dynamic range in isolation; they pay for a more reliable image stream that reduces missed or unusable events in practical installations.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Price competition in 2MP and 4MP platforms | −0.9% | Global budget camera channel | Short term (2027–2029) |
| Privacy and retention restrictions | −0.5% | Europe, North America | Long term (2027–2036) |
| Storage and network upgrade costs | −0.4% | All 8MP deployments | Medium term (2027–2031) |
Camera-system economics limit premium sensor uptake
A higher-resolution sensor increases potential detail but can also raise image processor requirements, storage volume and network bandwidth. An 8MP camera producing 3840 × 2160 video at 60 fps has different infrastructure needs from a 2MP replacement camera, and not every customer will fund the full upgrade. Suppliers therefore face pricing pressure in mainstream 4MP products and must demonstrate measurable operating benefits before charging more for advanced BSI or HDR features.
Privacy rules constrain surveillance deployment
Video devices can process personal data even when the sensor chip has no identification software. The European Data Protection Board’s Guidelines 3/2019 emphasize purpose, transparency and proportionality for video processing, creating obligations for operators and system integrators. These requirements can delay or reshape deployments, particularly public-space monitoring, although they also create demand for better-controlled systems and privacy-aware video analytics rather than automatically reducing every camera purchase.
Long qualification cycles slow component substitution
Camera makers validate sensor timing, optics, HDR algorithms, near-infrared response and package compatibility before committing to a new device. A 4MP sensor with different 2-lane or 4-lane MIPI behavior may require processor and firmware changes, while an 8MP product can affect thermal and power budgets. This reduces rapid switching between suppliers and can make established devices more durable in procurement despite the availability of technically superior alternatives.
MARKET OPPORTUNITIES
Single-exposure HDR for difficult scenes
Sensors that capture bright and dark areas with fewer motion artifacts can improve traffic and facility security video, where subjects cross between sunlight and shadow. Sony’s IMX908 uses LOFIC pixels to achieve 96 dB HDR and 8.4MP resolution with a single-exposure approach. Camera OEMs can translate this capability into premium products for entrance monitoring and moving-object recognition, provided lenses and processors preserve the sensor’s advantage.
Lower-power always-on residential monitoring
Smart-home cameras and video doorbells value long battery life and fast wake-up capture. OMNIVISION OS04C10 and OS04F10 provide low-power operating modes, while OS04D10 reports a 40% active-power improvement versus its predecessor. Suppliers that reduce energy consumption without losing 4MP detail or night sensitivity can compete for compact consumer security designs where enclosure size and maintenance frequency are major constraints.
Near-infrared optimization across wavelengths
The difference between 850 nm and 940 nm illumination creates room for tailored sensor offerings. OMNIVISION OS04A10 reports 60% quantum efficiency at 850 nm and 40% at 940 nm, allowing camera designers to trade invisible illumination against power and reach. Suppliers with documented spectral response and stable HDR behavior can win outdoor perimeter or indoor discreet-monitoring designs without relying solely on megapixel counts.
Security CMOS Image Sensor Supply Chain Analysis
The value chain starts with pixel architecture and semiconductor fabrication, moves through packaging and testing, and reaches camera OEMs through direct design wins or distribution. Security-camera integrators then combine the chip with optics, processors, infrared emitters, housings and network software. The distinction matters because chip sales are a fraction of complete camera revenue and are often geographically separated from camera assembly and installation.
Upstream. Pixel architecture is a major source of value because sensitivity, dark current and HDR behavior depend on semiconductor structures that cannot be corrected entirely by software. Sony STARVIS 3 uses deep photodiode and LOFIC features, while OMNIVISION offers PureCel Plus-S and Nyxel implementations. The chosen wafer process affects yield and package cost, especially as 1.45 µm pixels are pushed into compact 8MP optical formats.
Manufacturing. Sensors undergo wafer-level tests for defective pixels, read noise and response uniformity, then packaging and final characterization. A security camera must operate under varied lighting for long periods, so temperature behavior and interface timing matter as much as headline resolution. Device specifications such as 10-bit and 12-bit output, 60 fps and MIPI lane count determine the downstream processor and board design that can use a particular sensor.
Distribution. Image sensors usually reach the market through OEM qualification programs rather than anonymous spot transactions. A camera maker evaluates samples, optics and firmware before placing repeat orders, and distributors support smaller manufacturers or repair channels. Suppliers that maintain stable 2MP, 4MP and 8MP product families can retain designs for years, while frequent package or interface changes may increase switching costs and reduce customer willingness to adopt new devices.
Downstream. The sensor is only one part of a security camera. A 4MP outdoor system also includes a lens, enclosure, infrared illumination, processor, power supply, network interface and software, and the total installed system may include recorders or cloud services. Regional chip-demand estimates should therefore exclude finished-camera resale value and the recurring software revenue earned after installation; otherwise the same hardware value would be counted more than once. Axis Communications’ P1518-LE camera demonstrates downstream integration in a finished security product, whose sale price includes far more than the underlying image sensor.
Recent Developments in the Security CMOS Image Sensor Market
- 17 March 2026 Announced
Sony Semiconductor Solutions announced the IMX908 security sensor with 8.4 effective megapixels, 1.45 µm LOFIC pixels and 96 dB HDR. Planned sample shipment at the end of March 2026 marked a new premium design option for camera OEMs seeking 4K detail and single-exposure performance in difficult lighting, although production ramp and customer design wins depend on later qualification. Source - 3 June 2024 Announced
OMNIVISION introduced the OS04J10 for industrial and consumer security surveillance, combining 4MP resolution with 2.9 µm BSI pixels, Nyxel near-infrared technology and active power below 200 mW. The device illustrates competition on night sensitivity and energy use in the mainstream 4MP class rather than a simple shift toward maximum resolution. Source - 24 October 2023 Announced
OMNIVISION introduced the OS08C10 for home and professional security cameras, offering 8MP output, 1.45 µm BSI pixels and 4K2K capture at 60 fps. The device expands high-resolution options in a compact 1/2.8-inch optical format, creating opportunities for OEMs that can manage higher video throughput and maintain adequate low-light image quality. Source - 20 July 2022 Announced
Sony introduced the IMX675 security CMOS image sensor, which supports approximately 5.12MP imaging and high-speed region-of-interest output alongside full-pixel capture. Its dual-speed streaming design is relevant to surveillance cameras combining broad scene recording with targeted image processing, and the product highlights how readout architecture can differentiate security chips beyond nominal megapixel counts. Source - 2022 Product introduced
OMNIVISION’s OS04E10 applied a square 2048 × 2048 pixel array to security wide-field-of-view cameras and added digital watermarking for video authenticity. The 1:1 aspect ratio is useful for fisheye, dome and doorbell optics, while authenticity features address a different customer requirement from HDR or near-infrared sensitivity. The sensor shows continuing specialization within the 4MP class. Source - 2021 Product portfolio
OMNIVISION’s OS04D10 targeted 2K security, doorbell and baby-monitoring cameras with 4MP BSI imaging and a claimed 40% power reduction versus its predecessor. The design illustrates the commercial importance of low energy use in residential security products, where battery changes, thermal constraints and enclosure size can matter more than premium 8MP image resolution. Source - 2019 Product introduced
OMNIVISION introduced the OS04A10 4MP Nyxel sensor with 2.9 µm pixels and reported quantum efficiency of 60% at 850 nm and 40% at 940 nm. The technology supports infrared-assisted security imaging and demonstrates how sensor suppliers compete on usable nighttime video, an attribute not captured by megapixel counts alone. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Market | Global Security CMOS Image Sensor Market |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2027–2036 |
| Historical Data | 2021–2025 |
| Currency | USD million |
| Revenue Boundary | Security-use CMOS image sensor chips and packaged devices; excludes complete cameras, network recorders, cloud software, optics and installation. |
| Market valuation | USD 2,853 million (2026 base), USD 7,884 million (2036 forecast) and 10.7% compound annual growth; sensor-chip revenue only. |
| By Type | FSI (Frontside-Illuminated) · BSI (Backside-Illuminated) |
| By Application | Indoor Security · Outdoor Security |
| By Resolution | 2MP and below · 4MP–5MP · 8MP and above |
| By Region | Regional chip revenue estimated by end-use demand, not wafer fabrication or finished-camera assembly location. North AmericaUnited States, Canada, Mexico EuropeGermany, United Kingdom, France, Italy, Rest of Europe Asia-PacificChina, Japan, South Korea, India, Southeast Asia, Rest of Asia-Pacific South AmericaBrazil, Argentina, Chile, Colombia, Rest of South America Middle East & AfricaSaudi Arabia, UAE, South Africa, North Africa, Rest of Middle East & Africa |
| Key Companies Profiled | Sony Semiconductor Solutions, OMNIVISION, onsemi, PIXELPLUS |
| Customization Scope | Country, camera resolution and image-sensor architecture breakouts can be tailored to the buyer’s component-revenue boundary, including supplier qualification, HDR, near-infrared performance and application requirements. |
Frequently Asked Questions
How large is the global security CMOS image sensor market?
The global security CMOS image sensor market stands at USD 2,853 million in 2026 and is projected to reach USD 7,884 million by 2036, representing 10.7% CAGR over 2027–2036. The valuation concerns semiconductor sensor chips used in security cameras, not the much larger market for complete cameras, recorders, cloud subscriptions or installation services.
Which sensor type has the largest share?
Backside-illuminated CMOS sensors lead with an estimated ~70% of 2026 revenue and grow near ~12.1% CAGR, while frontside-illuminated devices account for ~30% and grow near ~6.8%. BSI is favored in premium 4MP and 8MP security cameras because low-light sensitivity, HDR and near-infrared response improve usable nighttime images, although mature FSI designs remain cost-effective in well-lit installations.
What are the main applications?
Outdoor security contributes an estimated ~58% of 2026 chip revenue and grows near ~11.2% CAGR; indoor security accounts for ~42% and grows near ~10.0%. Outdoor installations include traffic, industrial perimeter and transport monitoring, while indoor cameras cover commercial premises, residential entrances and smart-home applications. Both categories include several resolution tiers, so application share should not be confused with total camera-system spending.
Which region leads security CMOS sensor demand?
Asia-Pacific leads with an estimated ~42% of 2026 sensor revenue and ~11.1% CAGR, followed by North America at ~25% and Europe at ~20%. South America contributes ~7%, while the Middle East and Africa represent ~6% with the fastest modeled regional growth at ~12.5%. The regional figures represent final sensor demand rather than the location of camera assembly or wafer fabrication.
What is the difference between FSI and BSI?
FSI places pixel wiring on the light-entry side, while BSI collects light from the opposite side after specialized wafer processing. BSI can improve sensitivity in small pixels and is widely used for 4MP and 8MP security cameras that require low-light capture. The final result still depends on lens transmission, image-signal processing, infrared illumination and the specific sensor implementation.
Why are 850 nm and 940 nm important?
Security cameras often use near-infrared illumination at 850 nm or 940 nm for dark scenes. OMNIVISION OS04A10 reports quantum efficiency of 60% at 850 nm and 40% at 940 nm, illustrating the sensitivity differences designers must consider. The 940 nm option is less visible to people, while 850 nm can offer stronger illumination efficiency; camera range also depends on optics and emitter power.
Which companies manufacture security CMOS image sensors?
Sony Semiconductor Solutions and OMNIVISION offer extensive security-specific CMOS image sensor portfolios. PIXELPLUS supplies imaging semiconductors with security applications, and onsemi publishes security and surveillance image-sensor architectures. Product families range from 2MP and 4MP devices to 8MP 4K sensors. A supplier’s total image-sensor revenue should not be treated as its security-only market share without product-level disclosures.
What are the main technology trends?
Important trends include 8MP 4K capture, BSI migration, higher dynamic range, improved 850 nm and 940 nm sensitivity, lower active power and specialized sensor readout. Sony IMX908 uses 1.45 µm LOFIC pixels to support 96 dB HDR, while OMNIVISION OS04J10 uses larger 2.9 µm BSI pixels for 4MP low-light surveillance. The technologies solve different design problems rather than replacing each other universally.
What challenges constrain growth?
The main challenges are price competition in mainstream 2MP and 4MP cameras, longer OEM qualification cycles, the storage and network costs of 8MP video, and privacy restrictions on surveillance deployments. The European Data Protection Board provides guidance on personal-data processing through video devices, making operator governance a consideration in purchasing. Sensor makers must demonstrate reliable imaging improvements without forcing uneconomic system upgrades.
What period and segmentation does the study cover?
The study uses 2026 as its base year, 2027 as its estimated year and 2027–2036 as the forecast period, with historical coverage from 2021 through 2025. It segments sensor-chip revenue by FSI versus BSI, indoor versus outdoor security, resolution tiers and five world regions. Values are in USD million and exclude camera hardware and surveillance software sold downstream.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF


