Key Statistics
Key Takeaways
- Market trajectory: The global photonic infrared sensors market reached USD 1,011 million in 2026 and is projected to reach USD 1,887 million by 2036 at 6.4% CAGR over 2027–2036. Demand follows the actual sale of SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output, rather than the full revenue of adjacent digital infrastructure.
- Mid Wave Infrared (MWIR) leadership: Mid Wave Infrared (MWIR) has the largest estimated type share at ~43% in 2026. The fastest-growing type is Short Wave Infrared (SWIR), at ~7.3% CAGR from an estimated ~30% share. MWIR detectors are optimized for approximately 3–5 µm radiation and include cooled photon detectors used in defense, gas detection and high-precision thermal imaging. Readout and cryogenic packaging costs influence buyer selection.
- Military & Defense demand: Military & Defense leads application revenue at an estimated ~40% in 2026, while Automotive grows most rapidly near ~7.2% CAGR. Defense buyers procure integrated infrared sensing elements for target detection, border monitoring, threat warning and airborne payloads. Procurement involves long qualification, environmental test records and stringent supplier controls. For end-use systems in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
- Asia-Pacific position: Asia-Pacific represents the largest regional revenue pool at an estimated ~38% in 2026. Asia-Pacific has the highest regional modeled growth at ~7.1% CAGR. China produces significant volumes of imaging electronics while Japan manufactures high-performance photodiodes and sensors. Procurement is split between industrial vision, scientific instrumentation and local sensing-device production. In the regional competition setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
- Principal constraint: Cooled-detector manufacturing expense is a fundamental restraint. Purchase decisions are also affected by thermal-sensor and photon-sensor price disparity. Both conditions limit the speed at which a promising optical product can move into enduring installations; careful lifecycle support remains vital. This matters for adoption barriers, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Photonic Infrared Sensors Market Overview
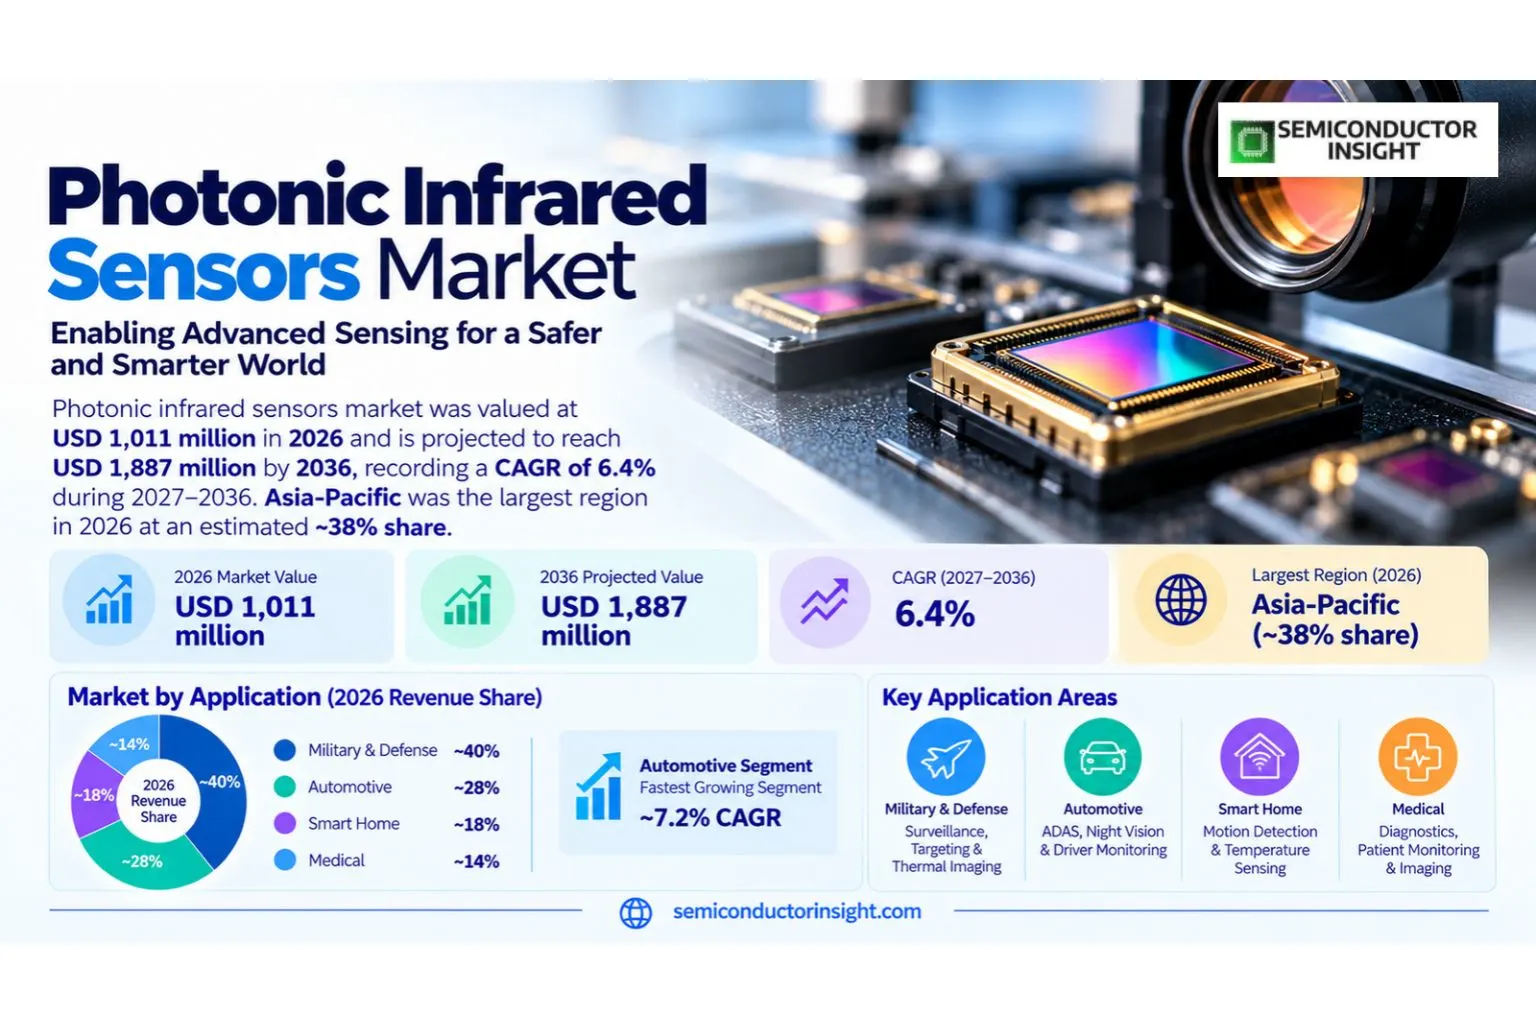
Photonic infrared sensors market was valued at USD 1,011 million in 2026 and is projected to reach USD 1,887 million by 2036, recording a CAGR of 6.4% during 2027–2036. Asia-Pacific was the largest region in 2026 at an estimated ~38% share. The market centers on SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output.
Photonic Infrared Sensors encompasses SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output. The optical interaction carries or secures the functional payload, but the device must also include appropriately designed mechanical, electronic and service interfaces. Customers primarily pay for a qualified system that performs consistently in field conditions, rather than a technical principle demonstrated only at prototype level.
The defined commercial boundary includes sales of infrared photoelectric and thermal sensing detector elements, assemblies and closely integrated sensor modules operating in SWIR, MWIR and LWIR; excludes complete cameras, remote-sensing satellite programmes, full military platforms and unrelated radar equipment. This distinction prevents a finished datacenter, networking service or unrelated electronic product from being mistaken for direct sales of the specialized component. Supplier comparisons are meaningful only when the invoiced product and its value contribution fall within the stated market boundary.
At the engineering level, SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output. Designing this technology for 2026 production requires material and mechanical stability, test coverage, procurement planning and the ability to identify a component that has begun to fail. Qualification routines can be more costly than the core material in demanding installations.
Demand develops through defense and surveillance equipment OEMs, industrial machine-vision assemblers, automotive safety system suppliers, medical instrument builders and facility sensor integrators. Those purchasers differ in the volumes they order, the length of their evaluation cycle and the documentation they require. The leading applications are Military & Defense, Automotive, Smart Home, Medical; their spending patterns cannot simply be extrapolated from wider electronics or digital-storage demand.
Technology priorities are evolving toward more reliable and serviceable optical architectures. MWIR detectors are optimized for approximately 3–5 µm radiation and include cooled photon detectors used in defense, gas detection and high-precision thermal imaging; for ov_paras/4, procurement is particularly sensitive to spectral response and cutoff. Readout and cryogenic packaging costs influence buyer selection. The commercial challenge is to turn those technical characteristics into repeat purchasing, while addressing loss of compatibility, changing interfaces and the long-term economics of support.
Segment Analysis: By Type
By type, the photonic infrared sensors market comprises Short Wave Infrared (SWIR), Mid Wave Infrared (MWIR), Long Wave Infrared (LWIR). Mid Wave Infrared (MWIR) leads with an estimated ~43% revenue share in 2026; Short Wave Infrared (SWIR) expands most rapidly at about ~7.3% CAGR from a ~30% share. Different physical designs lead to different suppliers, levels of qualification and possible expansion rates.
| Type | Function | Market position |
|---|---|---|
| Short Wave Infrared (SWIR) | SWIR sensors employ InGaAs and related photon-absorbing semiconductors for reflectance imaging, spectroscopy and low-light sensing. Device specifications include wavelength cutoff, cooling, dark current and low-noise electrical readout. Each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Short Wave Infrared (SWIR) variant affects installation requirements and ongoing service. | Estimated ~30% of 2026 revenue and ~7.3% CAGR. Short Wave Infrared (SWIR) is a distinct product category, with demand linked to the particular requirements of its buyers. SWIR sensors employ InGaAs and related photon-absorbing semiconductors for reflectance imaging, spectroscopy and low-light sensing; for Short Wave Infrared (SWIR), procurement is particularly sensitive to spectral response and cutoff. Device specifications include wavelength cutoff, cooling, dark current and low-noise electrical readout; for Short Wave Infrared (SWIR), procurement is particularly sensitive to spectral response and cutoff. Procurement teams evaluate component availability, unit cost and the necessary test records. |
| Mid Wave Infrared (MWIR) | MWIR detectors are optimized for approximately 3–5 µm radiation and include cooled photon detectors used in defense, gas detection and high-precision thermal imaging; for Mid Wave Infrared (MWIR), procurement is particularly sensitive to readout electronics noise. Readout and cryogenic packaging costs influence buyer selection. Each product specification maps to a different material bill, operating environment and qualification procedure; for Mid Wave Infrared (MWIR), procurement is particularly sensitive to spectral response and cutoff. Suppliers therefore need to establish how the Mid Wave Infrared (MWIR) variant affects installation requirements and ongoing service. | Estimated ~43% of 2026 revenue and ~6.5% CAGR. Mid Wave Infrared (MWIR) is the largest type by value, with demand linked to the particular requirements of its buyers. MWIR detectors are optimized for approximately 3–5 µm radiation and include cooled photon detectors used in defense, gas detection and high-precision thermal imaging; for Mid Wave Infrared (MWIR), procurement is particularly sensitive to dark-current and detector yield. Readout and cryogenic packaging costs influence buyer selection. Procurement teams evaluate component availability, unit cost and the necessary test records; for Mid Wave Infrared (MWIR), procurement is particularly sensitive to readout electronics noise. |
| Long Wave Infrared (LWIR) | LWIR sensors address thermal signatures around 8–14 µm through microbolometer arrays and other detector designs. Depending on architecture, uncooled thermal detection and cooled photon detection have distinct pricing and performance. Each product specification maps to a different material bill, operating environment and qualification procedure; for Long Wave Infrared (LWIR), procurement is particularly sensitive to cryogenic system integration. Suppliers therefore need to establish how the Long Wave Infrared (LWIR) variant affects installation requirements and ongoing service. | Estimated ~27% of 2026 revenue and ~5.5% CAGR. Long Wave Infrared (LWIR) is a distinct product category, with demand linked to the particular requirements of its buyers. LWIR sensors address thermal signatures around 8–14 µm through microbolometer arrays and other detector designs; for Long Wave Infrared (LWIR), procurement is particularly sensitive to cryogenic system integration. Depending on architecture, uncooled thermal detection and cooled photon detection have distinct pricing and performance; for Long Wave Infrared (LWIR), procurement is particularly sensitive to cryogenic system integration. Procurement teams evaluate component availability, unit cost and the necessary test records; for Long Wave Infrared (LWIR), procurement is particularly sensitive to dark-current and detector yield. |
Secondary segmentation: By Technology
The By Technology classification distinguishes Thermal Detection, Photon Detection. Photon Detection leads this separate estimated 2026 allocation at ~59%. Classifications are parallel descriptions of the same sold hardware; they are not additive product revenue pools. The choice among materials and assembly routes affects cost, thermal tolerance, signal characteristics and reliability. A commercial evaluation of By Technology segmentation therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
| Axis | Members | Commercial role |
|---|---|---|
| By Technology | Thermal Detection; Photon Detection | Photon Detection accounts for an estimated ~59% of by technology revenue in 2026. Other members address different procurement specifications. The underlying technology involves SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output. The best material or process choice is conditional on the actual optical device, thermal cycle, qualification plan and customer integration cost. |
Secondary segmentation: By End User
The By End User classification distinguishes Government & Defense, Industrial, Commercial, Healthcare. Government & Defense leads this separate estimated 2026 allocation at ~39%. Classifications are parallel descriptions of the same sold hardware; they are not additive product revenue pools; for type/subs, procurement is particularly sensitive to readout electronics noise. The choice among materials and assembly routes affects cost, thermal tolerance, signal characteristics and reliability; for type/subs, procurement is particularly sensitive to readout electronics noise.
| Axis | Members | Commercial role |
|---|---|---|
| By End User | Government & Defense; Industrial; Commercial; Healthcare | Government & Defense accounts for an estimated ~39% of by end user revenue in 2026. Other members address different procurement specifications. Detector technology groups differ in carrier generation, heat response, focal-plane integration and thermal stabilization, affecting how manufacturers qualify integrated sensing hardware. For the end-user classification, government and industrial purchasing are influenced by specialized environmental reliability testing, traceability and instrument-specific integration cost. |
Segment Analysis: By Application
Application segments are Military & Defense, Automotive, Smart Home, Medical. Military & Defense takes the largest estimated 2026 revenue share at ~40%, whereas Automotive is the fastest-growing application at ~7.2% CAGR. Channel structure, end-user servicing needs and purchasing cadence create distinct addressable opportunities despite shared underlying optical technologies. The 2027–2036 opportunity in application overview is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
| Application | Demand characteristics |
|---|---|
| Military & Defense | Estimated ~40% of 2026 revenue and ~6.6% CAGR. Military imaging programmes buy selected MWIR, LWIR and SWIR detector assemblies for target acquisition, border surveillance and airborne imaging payloads. Procurement involves long qualification, environmental test records and stringent supplier controls. Purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. |
| Automotive | Estimated ~26% of 2026 revenue and ~7.2% CAGR. Automotive suppliers evaluate uncooled long-wave imagers and compact infrared detector arrays for pedestrian recognition, cabin monitoring and low-light safety systems. Validation involves weather exposure, automotive qualification and integration with camera or lidar systems. Purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times; for Automotive, procurement is particularly sensitive to readout electronics noise. |
| Smart Home | Estimated ~15% of 2026 revenue and ~5.2% CAGR. Occupancy, intrusion and gas/temperature applications adopt pyroelectric or thermopile IR devices. Volume is driven by appliance and building-control design wins rather than military camera spending. Purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times; for Smart Home, procurement is particularly sensitive to dark-current and detector yield. |
| Medical | Estimated ~19% of 2026 revenue and ~5.8% CAGR. Medical instruments use shortwave absorption sensing and thermal detector components for monitoring, non-contact thermometry and optical spectroscopy; regulatory and calibration demands shape pricing. Purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times; for Medical, procurement is particularly sensitive to spectral response and cutoff. For Medical application in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. |
The commercial channel is shaped by defense and surveillance equipment OEMs, industrial machine-vision assemblers, automotive safety system suppliers, medical instrument builders and facility sensor integrators. Direct equipment purchase, specialist distributor supply and OEM qualification have different order economics. Volume can be won through stable specifications and documented reliability, while replacement sales depend on spare availability and retained interface compatibility over the 2027–2036 period.
Regional Analysis
Asia-Pacific leads global revenue with an estimated ~38% share in 2026. North America follows at ~29% and Europe at ~21%. Asia-Pacific has the fastest growth at ~7.1% CAGR. Regional purchases and supplier manufacturing footprints must be distinguished for market comparisons. In the regional lead setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
How do regional purchasing patterns differ in photonic infrared sensors?
Asia-Pacific: China produces significant volumes of imaging electronics while Japan manufactures high-performance photodiodes and sensors. Procurement is split between industrial vision, scientific instrumentation and local sensing-device production; for regional/paras, procurement is particularly sensitive to dark-current and detector yield. North America: American industrial and defense programs buy high-sensitivity SWIR and MWIR detectors, with radiation, response-time and export-control requirements shaping qualification. Equipment integrators seek documented wavelength response and temperature stability. Europe has distinct qualification and network compliance requirements; South America and the Middle East and Africa rely more heavily on imported products and local distribution service. This matters for regional comparison, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~38%) | ~7.1% CAGR | China produces significant volumes of imaging electronics while Japan manufactures high-performance photodiodes and sensors; for Asia-Pacific, procurement is particularly sensitive to readout electronics noise. Procurement is split between industrial vision, scientific instrumentation and local sensing-device production; for Asia-Pacific, procurement is particularly sensitive to cryogenic system integration. Within Asia-Pacific, design wins may be awarded to chip producers offshore even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. | Buyers in Asia-Pacific require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. For SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
| North America | Second (~29%) | ~6.2% CAGR | American industrial and defense programs buy high-sensitivity SWIR and MWIR detectors, with radiation, response-time and export-control requirements shaping qualification. Equipment integrators seek documented wavelength response and temperature stability. Within North America, design wins may be awarded to chip producers offshore even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. | Buyers in North America require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. For SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation; for North America, procurement is particularly sensitive to dark-current and detector yield. |
| Europe | Third (~21%) | ~5.8% CAGR | France and Germany maintain infrared detector development and production capabilities. European security, industrial process and environmental instruments create demand for calibrated long-wave and mid-wave detectors. Within Europe, design wins may be awarded to chip producers offshore even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. | Buyers in Europe require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. For SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation; for Europe, procurement is particularly sensitive to spectral response and cutoff. |
| South America | Fifth (~5%) | ~5.5% CAGR | Brazilian processing, mining and agricultural installations purchase infrared instruments for temperature, composition and condition measurements. Long service life and distributor stocking weigh heavily in device selection. Within South America, design wins may be awarded to chip producers offshore even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. | Buyers in South America require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. For SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation; for South America, procurement is particularly sensitive to cryogenic system integration. |
| Middle East & Africa | Fourth (~7%) | ~5.7% CAGR | Middle Eastern operators use mid-wave and long-wave sensing for infrastructure inspection, thermal security and process-control systems. African mining and energy sites value rugged devices and access to replacement modules. Within Middle East & Africa, design wins may be awarded to chip producers offshore even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. | Buyers in Middle East & Africa require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. For SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation; for Middle East & Africa, procurement is particularly sensitive to optical window transmission. |
Competitive Landscape
Competition is led by firms with relevant SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output. The competitive field includes established manufacturers, original equipment suppliers and historical product brands whose present scope differs. Buyers compare product-specific technical evidence and order terms instead of total corporate turnover, because an optical component represents only part of a finished digital system.
Sofradir and Excelitas Technologies Corp. illustrate different capabilities within the sector. Their product portfolios, production locations and support arrangements cannot be assumed identical. Procurement departments typically request specification sheets, samples, aging or thermal data and a long-term sourcing plan before designating a manufacturing source for a multi-year contract. A commercial evaluation of manufacturer capability therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Hamamatsu Photonics, Nippon Ceramic Co., Ltd., Senba Sensing Technology Co., Ltd., Yantai Raytron Technology Co., Ltd., InfraTEC GmbH appear in the wider manufacturer and distributor field. The roles of those entities require separation: media production, component housing manufacture, systems integration and distribution do not produce the same category of invoice. Market rivalry occurs at the level of the particular sold device, not across unrelated corporate divisions.
Other suppliers and historical business names include Yantai Raytron Technology Co., Ltd., InfraTEC GmbH, Panasonic Holdings Corporation, Omron Corporation. Legacy corporate names and regional branches may persist in industry directories, while actual current production must be checked against updated company disclosures. Product-life-cycle changes can alter sourcing qualification even if an installed system continues to function with existing spare inventories.
For 2027–2036, vendor differentiation will depend on manufacturing yield, documentation, reliable delivery and compatibility with demanding optical interfaces. Price competition may intensify in mature configurations, whereas new package geometries or archival media offer specialized margins. A customer switching supplier must weigh requalification, sample validation and operational interruption against lower unit costs. The 2027–2036 opportunity in competitive economics is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Sofradir; Excelitas Technologies Corp.; Hamamatsu Photonics | Direct manufacturers with published optical product or packaging activities differentiate through established process control and established technical catalogs. The first technical gate is the ability to supply SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output in a documented, reproducible format, followed by customer qualification and reliable lead times. |
| Tier 2 | Nippon Ceramic Co., Ltd.; Senba Sensing Technology Co., Ltd.; Yantai Raytron Technology Co., Ltd.; InfraTEC GmbH | Regional producers and equipment suppliers compete through specialized configurations, responsive design assistance and local service. Customers generally request traceable quality records and samples in the exact form factor they need. Lower production scale can be balanced by shorter engineering response times or customization of critical interfaces. For tier 2 in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. |
| Tier 3 | Panasonic Holdings Corporation; Omron Corporation | The broader value chain includes historical participants, distributors, integrators and component companies with adjacent expertise. Their names may appear in sector coverage without establishing that each currently sells an identical qualified device. Product applicability is determined by specific device families, production status and customer approvals. In the tier 3 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. |
Key companies profiled
- Sofradir
- Excelitas Technologies Corp.
- Hamamatsu Photonics
- Nippon Ceramic Co., Ltd.
- Senba Sensing Technology Co., Ltd.
- Yantai Raytron Technology Co., Ltd.
- InfraTEC GmbH
- Panasonic Holdings Corporation
- Omron Corporation
Production Capacity Analysis
Production capacity relies on specialized manufacturing and testing for SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output. Effective output is constrained by qualified material lots, process yield, equipment availability and completion of electrical, optical and environmental tests. Announced industrial capability should not be equated automatically with installed sales or usable nameplate capacity.
Initial manufacturing operations include SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output. Yield is influenced by each fabrication and assembly stage, while changes in materials or process equipment can require formal requalification. Japan, China and other Asia-Pacific manufacturing centers support considerable supplier capacity, although customer purchasing decisions may originate elsewhere.
Diversified capacity can reduce country-of-origin exposure and help supply different qualification requirements. However, transferring tooling and process knowledge between plants takes time, and products made in new locations may require fresh qualification. Strong inventory controls and component traceability are important during a period of changing designs and volatile customer orders. This matters for capacity diversification, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Upstream constraints include materials, specialized assembly equipment and trained optical manufacturing staff. For photonic infrared sensors, packaging, testing and maintenance infrastructure shape the ability to convert a technical design into reproducible revenue. Companies should distinguish capacity for direct in-scope products from headline capacity for the much larger adjacent electronics manufacturing market. A commercial evaluation of capacity bottlenecks therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Market Dynamics
Demand is driven by defense thermal-imaging qualification and machine vision and industrial swir. Growth depends on matching the optical product to qualification requirements, logistics and total ownership cost. Supplier economics also reflect the negative impact of cooled-detector manufacturing expense, particularly when customers require long operational support. The 2027–2036 opportunity in dynamics lead is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Defense thermal-imaging qualification | +1.8% | Asia-Pacific | 2027–2036 |
| Machine vision and industrial SWIR | +1.4% | Global | 2028–2034 |
| Automotive night-safety sensors | +1.1% | North America | 2027–2031 |
| Gas detection and environmental monitoring | +0.9% | Europe | 2029–2036 |
| Compact medical photonic instruments | +0.7% | Global | 2028–2035 |
Defense thermal-imaging qualification
Defense thermal-imaging qualification supports specialized purchases for photonic infrared sensors. SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output must be integrated into customer processes, inspected and supported. The growth effect is directional, not a separate addition to the headline CAGR. Actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
Machine vision and industrial SWIR
Machine vision and industrial SWIR supports specialized purchases for photonic infrared sensors. SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output must be integrated into customer processes, inspected and supported; for Machine vision and industrial SWIR, procurement is particularly sensitive to optical window transmission. The growth effect is directional, not a separate addition to the headline CAGR; for Machine vision and industrial SWIR, procurement is particularly sensitive to optical window transmission. Actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed; for Machine vision and industrial SWIR, procurement is particularly sensitive to optical window transmission.
Automotive night-safety sensors
Automotive night-safety sensors supports specialized purchases for photonic infrared sensors. SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output must be integrated into customer processes, inspected and supported; for Automotive night-safety sensors, procurement is particularly sensitive to readout electronics noise. The growth effect is directional, not a separate addition to the headline CAGR; for Automotive night-safety sensors, procurement is particularly sensitive to readout electronics noise. Actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed; for Automotive night-safety sensors, procurement is particularly sensitive to readout electronics noise.
Gas detection and environmental monitoring
Gas detection and environmental monitoring supports specialized purchases for photonic infrared sensors. SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output must be integrated into customer processes, inspected and supported; for Gas detection and environmental monitoring, procurement is particularly sensitive to dark-current and detector yield. The growth effect is directional, not a separate addition to the headline CAGR; for Gas detection and environmental monitoring, procurement is particularly sensitive to dark-current and detector yield. Actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed; for Gas detection and environmental monitoring, procurement is particularly sensitive to dark-current and detector yield.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Cooled-detector manufacturing expense | −1.5% | Global | 2027–2036 |
| Thermal-sensor and photon-sensor price disparity | −1.1% | Europe and North America | 2027–2034 |
| Dual-use export licensing | −0.8% | Asia-Pacific | 2028–2035 |
| Performance drift under harsh conditions | −0.6% | Global | 2029–2036 |
Cooled-detector manufacturing expense
Cooled-detector manufacturing expense increases the effort required to qualify or replace photonic infrared sensors. A technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. Suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. For Cooled-detector manufacturing expense restraint in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
Thermal-sensor and photon-sensor price disparity
Thermal-sensor and photon-sensor price disparity increases the effort required to qualify or replace photonic infrared sensors. A technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user; for Thermal-sensor and photon-sensor price disparity, procurement is particularly sensitive to spectral response and cutoff. Suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts; for Thermal-sensor and photon-sensor price disparity, procurement is particularly sensitive to spectral response and cutoff. In the Thermal-sensor and photon-sensor price disparity restraint setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Dual-use export licensing
Dual-use export licensing increases the effort required to qualify or replace photonic infrared sensors. A technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user; for Dual-use export licensing, procurement is particularly sensitive to cryogenic system integration. Suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts; for Dual-use export licensing, procurement is particularly sensitive to cryogenic system integration. This matters for Dual-use export licensing restraint, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Performance drift under harsh conditions
Performance drift under harsh conditions increases the effort required to qualify or replace photonic infrared sensors. A technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user; for Performance drift under harsh conditions, procurement is particularly sensitive to optical window transmission. Suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts; for Performance drift under harsh conditions, procurement is particularly sensitive to optical window transmission. A commercial evaluation of Performance drift under harsh conditions restraint therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
MARKET OPPORTUNITIES
Uncooled automotive thermal sensors
Uncooled automotive thermal sensors creates an opportunity to improve deployment or the supplier value proposition. The relevant engineering work concerns SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output. Buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. The commercial impact is strongest where those requirements can be standardized across several customers.
Integrated digital SWIR modules
Integrated digital SWIR modules creates an opportunity to improve deployment or the supplier value proposition. The relevant engineering work concerns SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output; for Integrated digital SWIR modules, procurement is particularly sensitive to cryogenic system integration. Buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule; for Integrated digital SWIR modules, procurement is particularly sensitive to cryogenic system integration. The commercial impact is strongest where those requirements can be standardized across several customers; for Integrated digital SWIR modules, procurement is particularly sensitive to cryogenic system integration.
Higher-sensitivity gas detection
Higher-sensitivity gas detection creates an opportunity to improve deployment or the supplier value proposition. The relevant engineering work concerns SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output; for Higher-sensitivity gas detection, procurement is particularly sensitive to optical window transmission. Buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule; for Higher-sensitivity gas detection, procurement is particularly sensitive to optical window transmission. The commercial impact is strongest where those requirements can be standardized across several customers; for Higher-sensitivity gas detection, procurement is particularly sensitive to optical window transmission.
Miniaturized medical IR instruments
Miniaturized medical IR instruments creates an opportunity to improve deployment or the supplier value proposition. The relevant engineering work concerns SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output; for Miniaturized medical IR instruments, procurement is particularly sensitive to readout electronics noise. Buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule; for Miniaturized medical IR instruments, procurement is particularly sensitive to readout electronics noise. The commercial impact is strongest where those requirements can be standardized across several customers; for Miniaturized medical IR instruments, procurement is particularly sensitive to readout electronics noise.
Supply Chain Analysis
The supply chain links specialized raw materials, device fabrication, verification, system integration and servicing for photonic infrared sensors. A failure at any stage can invalidate the qualified end product. Vendor selection is therefore affected by more than selling price: replacement-component availability, inspection data, lead time and the ability to support legacy interfaces are commercially significant.
Upstream materials. Materials and optical substrates required for SWIR InGaAs detectors, cooled MWIR semiconductor detectors, LWIR imagers and associated infrared sensor/readout structures that convert incoming infrared radiation into electric output; inspection before assembly; for Upstream materials, procurement is particularly sensitive to spectral response and cutoff. For photonic infrared sensors, controlling change across this stage enables traceability, reliability and repeatable delivery. Purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment.
Manufacturing. Fabrication, alignment, sealing or recording operations matched to the market boundary. For photonic infrared sensors, controlling change across this stage enables traceability, reliability and repeatable delivery; for Manufacturing, procurement is particularly sensitive to readout electronics noise. Purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment; for Manufacturing, procurement is particularly sensitive to readout electronics noise. In the Manufacturing chain setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Channels. OEM engineering contracts, technical distributors and integrated storage or optical equipment vendors; for Channels, procurement is particularly sensitive to cryogenic system integration. For photonic infrared sensors, controlling change across this stage enables traceability, reliability and repeatable delivery; for Channels, procurement is particularly sensitive to dark-current and detector yield. Purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment; for Channels, procurement is particularly sensitive to dark-current and detector yield. This matters for Channels chain, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Downstream users. defense and surveillance equipment OEMs, industrial machine-vision assemblers, automotive safety system suppliers, medical instrument builders and facility sensor integrators; qualification, deployment and lifecycle support; for Downstream users, procurement is particularly sensitive to dark-current and detector yield. For photonic infrared sensors, controlling change across this stage enables traceability, reliability and repeatable delivery; for Downstream users, procurement is particularly sensitive to spectral response and cutoff. Purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment; for Downstream users, procurement is particularly sensitive to spectral response and cutoff.
Recent Developments
- 21 September 2026 Announced
LYNRED disclosed its CAPT640 automotive thermal imaging sensor, positioning infrared sensing for active safety functions. The market consequence is an expanded qualification opportunity in automotive applications, which requires high reliability, cost control and compatibility with electronic safety systems. Automotive thermal detection is not technologically identical to cooled MWIR photon-counting sensors. A commercial evaluation of Photonic Infrared Sensors development 21 September 2026 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. Source - 9 September 2026 Announced
LYNRED and constellr announced work on next-generation infrared detection technologies. Satellite and terrestrial environmental applications demand spectral performance and stable operation under demanding conditions. Those engineering needs create opportunities for specialized focal-plane products while entire satellite mission costs remain outside the photonic infrared detector revenue boundary. The 2027–2036 opportunity in Photonic Infrared Sensors development 9 September 2026 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. Source - 15 June 2026 Announced
LYNRED introduced the DRACO MW SL detector optimized for land and counter-UAV missions. The product highlights demanding MWIR performance and processing requirements. Revenue implications relate to detector orders and supported sensor assemblies rather than complete military platforms, and higher device specifications can lengthen qualification and procurement cycles. For Photonic Infrared Sensors development 15 June 2026 in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. Source - 10 June 2026 Announced
LYNRED described production expansion to meet growing drone-market infrared detector demand. Increasing output matters where system makers require reliable volume and traceability. A capacity announcement, however, does not prove a corresponding increase in recognized sensor revenue until qualified detectors reach equipment manufacturers and customer systems are delivered. In the Photonic Infrared Sensors development 10 June 2026 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. Source - 20 April 2026 Announced
LYNRED introduced ARGO SL, a compact infrared detector aimed at drone applications. Smaller packages can reduce weight and thermal integration requirements, allowing infrared functionality in portable platforms. Buyers still have to validate optical sensitivity, thermal drift and operating-life stability before replacing incumbent detector designs. This matters for Photonic Infrared Sensors development 20 April 2026, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. Source - 19 January 2026 Announced
LYNRED announced YOCTO, an 8-micron-pitch microbolometer supporting compact thermal imaging. Its pixel-size reduction indicates continued progress in uncooled LWIR sensing, while the underlying thermal detection mechanism differs from direct photon conversion used by some SWIR and cooled MWIR detectors. Product miniaturization can increase system design opportunities. A commercial evaluation of Photonic Infrared Sensors development 19 January 2026 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. Source - 21 January 2025 Announced
LYNRED announced Eyesential SW for shortwave infrared machine vision. The development serves inspection and optical contrast tasks beyond visible cameras, with wavelength response and readout speed driving qualification. Product adoption depends on unit cost and customer integration rather than assuming that all infrared imaging expenditure becomes sensor-element sales. The 2027–2036 opportunity in Photonic Infrared Sensors development 21 January 2025 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2036 |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2027–2036 |
| Historical Period | 2021–2025 |
| Base Year Market Size | USD 1,011 million |
| Estimated Year Market Size | USD 1,076 million |
| Forecast Year Market Size | USD 1,887 million |
| CAGR | 6.4% |
| Unit | USD million |
| Market Definition | sales of infrared photoelectric and thermal sensing detector elements, assemblies and closely integrated sensor modules operating in SWIR, MWIR and LWIR; excludes complete cameras, remote-sensing satellite programmes, full military platforms and unrelated radar equipment |
| By Type | Short Wave Infrared (SWIR) · Mid Wave Infrared (MWIR) · Long Wave Infrared (LWIR) |
| By Application | Military & Defense · Automotive · Smart Home · Medical |
| By Technology | Thermal Detection · Photon Detection |
| By End User | Government & Defense · Industrial · Commercial · Healthcare |
| By Region | Five region market segmentation is based on where the final specialized optical equipment is sold, not the location of raw-material fabrication. Asia-PacificChina · Japan · India · South Korea North AmericaUnited States · Canada · Mexico EuropeGermany · United Kingdom · France South AmericaBrazil · Chile · Argentina Middle East & AfricaSaudi Arabia · United Arab Emirates · South Africa |
| Key Companies Profiled | Sofradir; Excelitas Technologies Corp.; Hamamatsu Photonics; Nippon Ceramic Co., Ltd.; Senba Sensing Technology Co., Ltd.; Yantai Raytron Technology Co., Ltd.; InfraTEC GmbH; Panasonic Holdings Corporation; Omron Corporation |
| Customization Scope | Supplier, type, application and regional price analysis for photonic infrared sensors; estimated market shares in 2026 and differentiated growth paths for 2027–2036. |
Frequently Asked Questions
What is the global photonic infrared sensors market size?
The global photonic infrared sensors market is valued at USD 1,011 million in 2026 and is forecast to reach USD 1,887 million by 2036, with 6.4% CAGR during 2027–2036. The demand boundary is specific to the optical equipment and technology defined here rather than the full revenue of all data-center, media, automotive or electronics systems.
Which geographic region is the largest market?
Asia-Pacific is the leading 2026 regional market with an estimated ~38% of revenue. North America and Europe follow at ~29% and ~21%, respectively. Differences in OEM manufacturing locations and customer purchasing geography can otherwise distort region comparisons. For FAQ 2 in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
Which region has the fastest growth rate?
Asia-Pacific has the highest estimated regional expansion at ~7.1% CAGR through 2036. China produces significant volumes of imaging electronics while Japan manufactures high-performance photodiodes and sensors; for faq/2, procurement is particularly sensitive to optical window transmission. Procurement is split between industrial vision, scientific instrumentation and local sensing-device production; for faq/2, procurement is particularly sensitive to spectral response and cutoff. The rate is linked to equipment deployment, supplier qualification and the technology mix, rather than broad GDP growth alone.
Which type holds the largest revenue share?
Mid Wave Infrared (MWIR) represents an estimated ~43% of the 2026 market. MWIR detectors are optimized for approximately 3–5 µm radiation and include cooled photon detectors used in defense, gas detection and high-precision thermal imaging; for faq/3, procurement is particularly sensitive to readout electronics noise. Readout and cryogenic packaging costs influence buyer selection. Buyers need to verify its performance, equipment compatibility and the available delivery chain before treating it as an interchangeable substitute for another optical format.
Which type is projected to expand fastest?
Short Wave Infrared (SWIR) carries the strongest estimated type growth at ~7.3% CAGR, from around ~30% of 2026 revenue. The product mix changes as users adopt performance-enhancing configurations, but engineering qualification and lifecycle servicing determine how quickly that potential converts into orders. In the FAQ 5 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
What is the leading application?
Military & Defense is the largest application at approximately ~40% of 2026 revenue. Defense buyers procure integrated infrared sensing elements for target detection, border monitoring, threat warning and airborne payloads; for faq/5, procurement is particularly sensitive to spectral response and cutoff. Procurement involves long qualification, environmental test records and stringent supplier controls. Procurement specifications depend on actual operating conditions; total revenue in the wider user industry is not a direct proxy for the value of optical equipment purchased.
Which application grows fastest?
Automotive is projected to grow at ~7.2% CAGR from approximately ~26% of 2026 revenue. Vehicle suppliers use infrared sensing for night-time pedestrian detection, cabin observation and emerging active safety architectures. Validation involves weather exposure, automotive qualification and integration with camera or lidar systems; for faq/6, procurement is particularly sensitive to readout electronics noise. Growth is affected by price changes and supplier qualification as well as physical unit demand.
Which companies are included?
The profiled market participants include Sofradir, Excelitas Technologies Corp., Hamamatsu Photonics, Nippon Ceramic Co., Ltd., Senba Sensing Technology Co., Ltd., Yantai Raytron Technology Co., Ltd.. These companies may operate in different parts of the value chain and in some cases retain historical naming. Comparisons need to distinguish direct in-scope equipment manufacturing from distribution, materials and wider group revenues.
What restrains adoption?
Cooled-detector manufacturing expense is a notable limitation, alongside thermal-sensor and photon-sensor price disparity. Customers must also examine service cost, quality-control requirements and purchasing terms. Technical improvement will not necessarily produce corresponding annual revenue growth without reproducible production and access to qualified buyers. This matters for FAQ 9, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
What is the study period and segmentation scope?
The base year is 2026, the estimated year is 2027, and the forecast runs through 2036 with historical context from 2021–2025. Segmentation by type covers Short Wave Infrared (SWIR), Mid Wave Infrared (MWIR), Long Wave Infrared (LWIR) and by application covers Military & Defense, Automotive, Smart Home, Medical. Five geographic regions are included. A commercial evaluation of FAQ 10 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF