SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Fiber Optic Cables Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
OPTOELECTRONICS Semiconductor Market Research

Fiber Optic Cables Market, Trends, Business Strategies 2026-2034

◷
UPDATED 17 September 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE f1337544a281
▯
FORMATS PDF

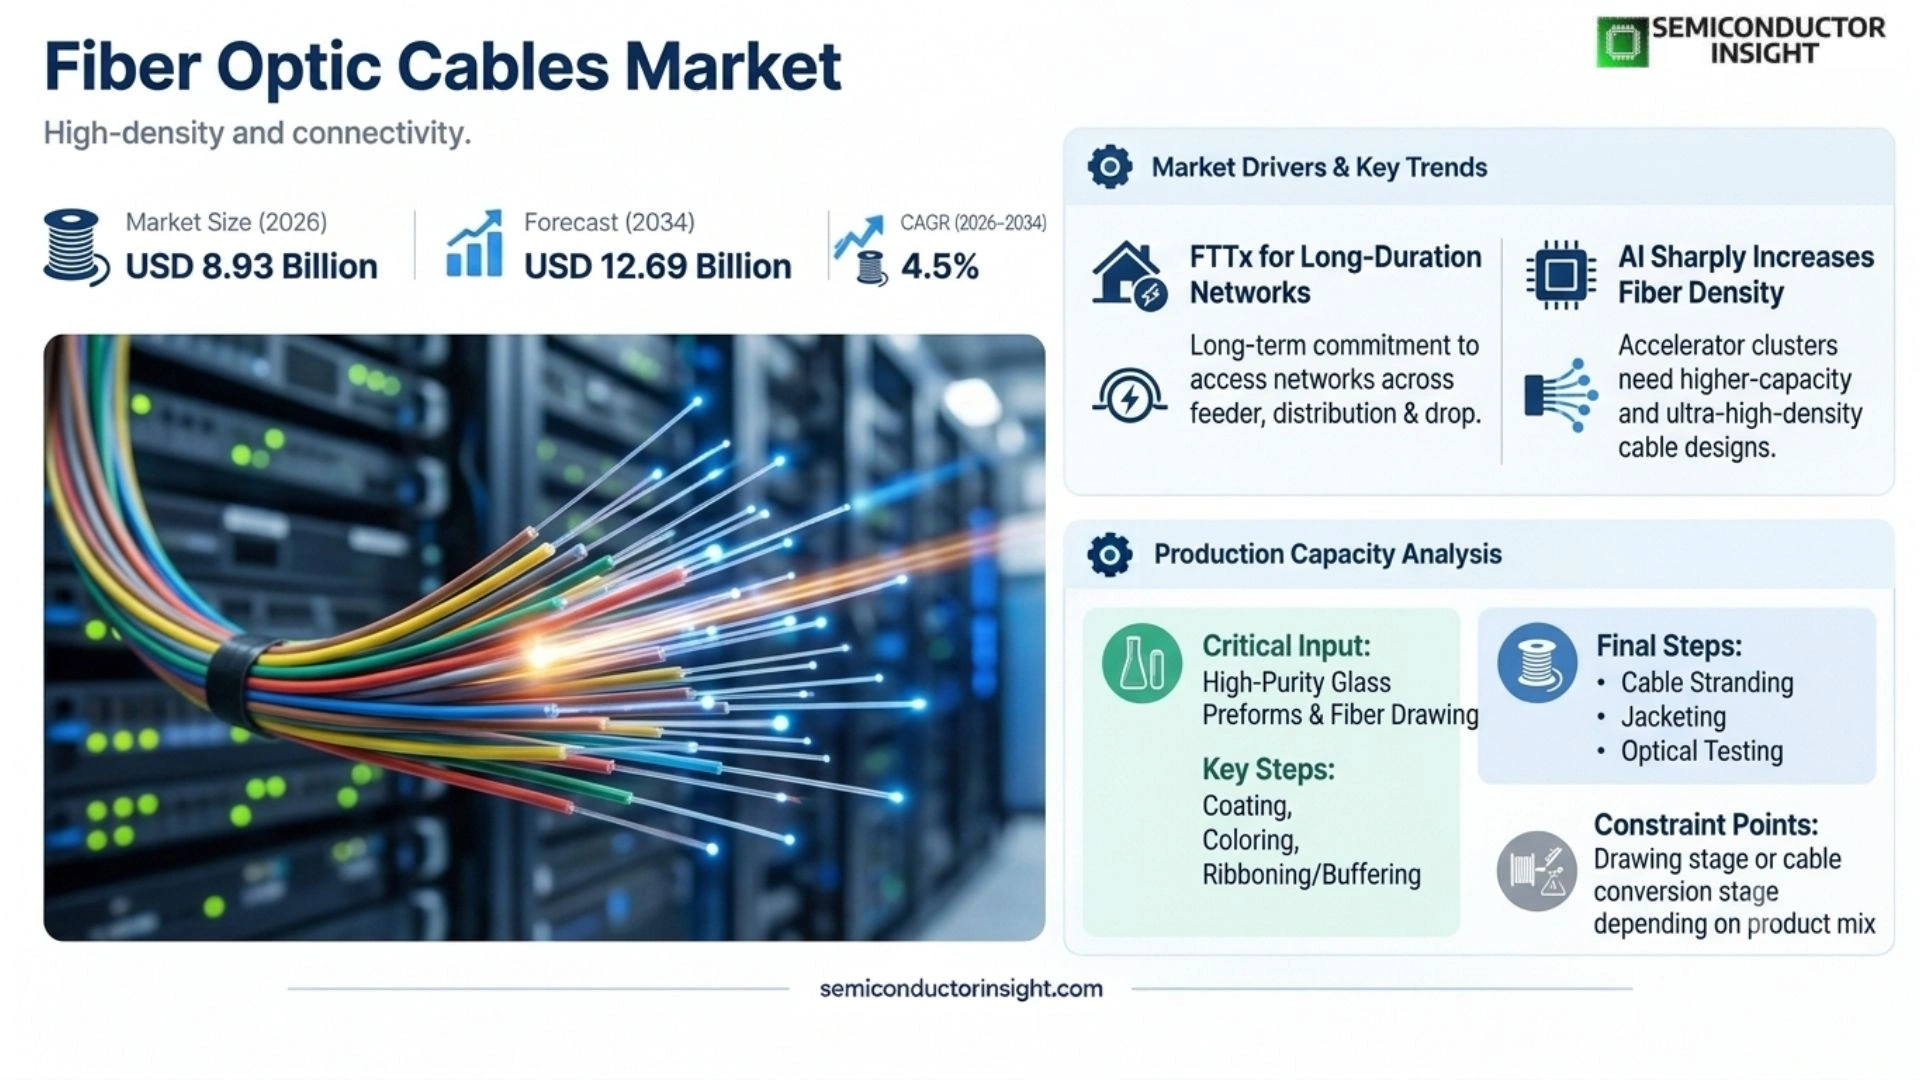
Fiber Optic Cables Market is estimated at USD 8,930.3 million in 2026, and is projected to reach USD 12,685.8 million by 2034, representing a CAGR of 4.5% during 2026–2034. Asia Pacific is the largest regional market in 2025, while the commercial growth mechanism is increasingly shaped by FTTx broadband, AI data centers, long-haul backbones, 5G transport, rural broadband programs, higher-density cable designs, and hyperscaler supply agreements.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 8,546.9 million
2026 Estimated Size
USD 8,930.3 million
2034 Projected Size
USD 12,685.8 million
CAGR (2026–2034)
4.5%
Largest Market in 2025
Asia Pacific

Key Takeaways

  • Single-Mode Fiber Optic Cable is the dominant product type, holding more than 97% share in the report scope because long-distance, FTTx and high-bandwidth backbone networks rely primarily on single-mode transmission.
  • FTTx is the largest application as operators and governments extend fiber closer to homes, buildings, campuses and businesses to deliver higher fixed-broadband capacity.
  • Asia Pacific is the largest region with more than 60% share in the report scope, driven by large-scale fiber deployment and manufacturing in China, India, Japan and other Asian markets.
  • North America is the second-largest region with about 16% share and is entering a major investment cycle tied to rural broadband, AI data centers and long-haul AI corridors.
  • AI infrastructure is creating a second major demand engine. Corning, Prysmian and network operators are adding cable and fiber capacity specifically for hyperscale data centers and AI interconnect.
  • High-density cable design is becoming strategic because the number of fibers per rack, conduit and long-haul route is rising sharply as AI clusters and converged broadband networks expand.

Fiber Optic Cables Market Overview

Fiber Optic Cables Market was valued at USD 8,546.9 million in 2025, is estimated at USD 8,930.3 million in 2026, and is projected to reach USD 12,685.8 million by 2034, representing a CAGR of 4.5% during 2026–2034. Asia Pacific is the largest regional market in 2025, while the commercial growth mechanism is increasingly shaped by FTTx broadband, AI data centers, long-haul backbones, 5G transport, rural broadband programs, higher-density cable designs, and hyperscaler supply agreements.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless otherwise stated

Fiber optic cables contain one or more glass or plastic optical fibers protected by coatings, buffer tubes, strength members and outer jackets suited to the deployment environment. They transmit data as light with far lower attenuation and much greater bandwidth than copper over long distances. Products range from single-fiber drop cables through high-count ribbon and loose-tube cables used in FTTx, metro, long-haul, mobile backhaul, cable television and data-center networks.

The market is being driven by two large infrastructure cycles. The first is continued broadband fiber deployment, especially FTTx and rural network expansion. The second is AI infrastructure, where data centers need much denser internal cabling and long-haul networks must connect new hyperscale campuses with very high capacity and low latency. These two demand pools increasingly share the same upstream fiber, cable and connectivity supply base.

Technology development is focused on higher fiber counts, smaller cable diameter, bend-insensitive fiber, ribbon structures and faster installation. Corning’s Contour Flow and other high-density architectures seek to place more fiber into existing duct, while Prysmian is expanding fiber and optical-cable capacity in the United States and Europe to serve data-center and hyperscaler demand.

Segment Analysis: By Type

By type, the market is segmented into Single-Mode and Multi-Mode. Single-Mode Fiber Optic Cable is the leading segment by a very wide margin because FTTx, long-haul and metro networks need low attenuation and high bandwidth over longer distances.

Type Technical role Market position
Single-Mode Uses a small optical core to propagate a single spatial mode, minimizing modal dispersion and supporting long-distance, high-bandwidth transmission. The dominant type with more than 97% share in the report scope. It is the standard choice for telecom backbones, FTTx, metro transport and most external data-center interconnect.
Multi-Mode Uses a larger core that supports multiple optical modes and is suited to shorter links using lower-cost transceivers in buildings and data centers. A smaller but durable segment for short-reach LAN, campus and selected data-center connections where reach requirements are limited.

Why does single-mode fiber dominate modern network buildouts?

Single-mode fiber can support much longer reach and higher aggregate capacity than multimode fiber, allowing operators to reuse the same installed cable as transceiver technology advances. FTTx and long-haul networks are therefore built primarily on single-mode infrastructure. The cable can remain in place for decades while electronics at each end are upgraded, which improves lifecycle economics and makes fiber a long-duration infrastructure asset rather than a short technology cycle.

Segment Analysis: By Application

By application, the market covers FTTx, Long-Distance Communication, Local Mobile Metro Network, CATV, Other Local Access Network, Multimode Fiber Applications, and Others. FTTx is the largest segment, followed by long-distance communication.

Application Demand characteristics
FTTx Fiber-to-the-home, building, curb and enterprise architectures extend optical access closer to end users and replace bandwidth-limited copper links. The largest application. Government broadband programs, operator upgrades and rising household data demand create sustained cable deployment.
Long-Distance Communication Long-haul and inter-city fiber routes connect carrier networks, cloud regions and data-center campuses over hundreds or thousands of kilometers. The second-largest application and a major AI-growth area as hyperscalers require new inter-data-center corridors.
Local Mobile Metro Network Metro rings and mobile transport networks connect cell sites, aggregation nodes, edge facilities and urban data centers. A major demand pool linked to 5G densification, cloud edge and enterprise connectivity.
CATV Cable operators deploy fiber deeper into hybrid fiber-coax and converged broadband networks. A mature but important application as operators increase fiber penetration and reduce amplifier/copper dependence.
Other Local Access Network Enterprise, campus, municipal and utility networks use fiber for reliable high-capacity access. Steady demand supported by business digitization and smart infrastructure.
Multimode Fiber Applications Short-reach data-center, building and campus networks use multimode fiber where transceiver cost and simplified optics are advantageous. A specialized short-distance segment that remains relevant despite single-mode dominance.
Others Includes industrial, defense, sensing, transport and specialized communications. A diversified niche that benefits from fiber immunity to electromagnetic interference and long reach.

Why are AI data centers changing cable density requirements?

AI clusters connect far more accelerators and switches than conventional enterprise data centers, and optical links are moving closer to the compute fabric. Corning has stated that scale-up and scale-out AI designs can drive thousands of fibers per rack and switch rack. This increases demand not only for more cable but for smaller-diameter, higher-density routing systems that fit within constrained trays, conduits and equipment spaces.
Fiber Optic Cables market Size 2026

Regional Analysis

Asia Pacific leads the Fiber Optic Cables market with more than 60% share, supported by large-scale broadband deployment and cable manufacturing. North America follows with about 16% share and is accelerating investment through AI infrastructure and broadband expansion.

Why does regional fiber demand increasingly combine broadband and AI infrastructure?

Traditional fiber demand came mainly from telecom access and backbone networks. AI adds a new layer: dense intra-data-center connectivity and new long-haul routes between hyperscale campuses. Asia Pacific remains the largest broadband and manufacturing region, while North America is seeing major hyperscaler agreements and route expansion. Europe continues shifting fixed broadband toward FTTP, and emerging regions are expanding backbone and mobile transport.

Region Position Growth outlook Demand profile What decides supplier selection
Asia Pacific Largest >60% Strong FTTx, mobile transport, long-haul and manufacturing Scale, cost, fiber count and deployment speed
North America Second-largest ~16% Strong Broadband, AI data centers and long-haul corridors Domestic supply, high-density cable and route expansion
Europe Large mature growth market Moderate to strong FTTP, data centers and copper retirement Deployment efficiency, VHCN targets and sustainability
South America Emerging infrastructure market Selective Backbone, metro, FTTx and cloud regions Capital cost, rights-of-way and imported supply
Middle East & Africa Emerging high-capacity market Selective Data centers, telecom backbones and smart infrastructure Long-distance economics, local installation and supply
Asia Pacific LARGEST MARKET

Why does Asia Pacific lead fiber-optic cable demand?

China, India, Japan and Southeast Asia combine large populations, continued broadband rollout, mobile-network expansion and major cable-manufacturing capacity. Regional suppliers such as YOFC, Hengtong, ZTT, FiberHome, Futong and Sumitomo Electric support both domestic projects and export markets.

Market positionLargest >60%
Growth outlookStrong
Demand profileFTTx and telecom scale
Market access gateCost, deployment speed and local supply
Country / market Position in region Evidence-led demand logic
China Largest regional manufacturing and deployment base Massive FTTx, 5G transport, data-center and backbone networks support high single-mode cable consumption and a large domestic supplier ecosystem.
India High-growth broadband market Fiber-to-home, 5G backhaul and national digital-infrastructure expansion create rising demand for access and long-haul cable.
Japan High-quality telecom market Dense fiber networks and advanced manufacturing support premium cable, bend-insensitive fiber and data-center applications.
Southeast Asia Growing network and data-center cluster New cloud regions, mobile networks and cross-border connectivity support metro and long-haul fiber demand.
2025–2026 – FTTx and mobile transport continue expanding across Asia

Operators increase fiber penetration in access and metro networks as data consumption rises.

Market relevance: Single-mode cable demand remains anchored by large physical network buildouts rather than only electronics upgrades.

2025–2026 – Asian data-center clusters add fiber density

Singapore, Malaysia, Japan and India continue adding cloud and AI infrastructure.

Market relevance: Higher rack and campus bandwidth expands demand for high-count cable and structured fiber systems.

2026 – major Asian manufacturers maintain broad global supply

YOFC, Hengtong, ZTT, FiberHome and Sumitomo Electric remain major producers in the report competitive set.

Market relevance: Regional scale supports both local infrastructure and export availability.

Full-report coverage: Country-level revenue, sales, supplier positioning and forecast detail are retained in the full study; this overview highlights the countries with the clearest, independently supportable demand mechanisms.
North America SECOND-LARGEST & AI-ACCELERATING MARKET

Why is North American fiber demand accelerating?

The United States is simultaneously expanding broadband access and building very large AI data-center campuses. Corning has announced multibillion-dollar agreements with Meta, Amazon and Verizon, while Zayo plans thousands of new long-haul route miles. These programs require both external long-haul cable and dense internal connectivity.

Market positionSecond-largest region
Growth outlookStrong
Demand profileBroadband plus AI infrastructure
Market access gateDomestic capacity, route scale and cable density
Country / market Position in region Evidence-led demand logic
United States Primary regional market Hyperscale data centers, rural broadband, long-haul AI corridors and large enterprise networks create broad fiber-cable demand.
Canada Backbone and rural-connectivity market Long distances and dispersed populations support fiber transport, metro networks and data-center connectivity.
Mexico Telecom and data-center growth market Broadband expansion and cloud investment create rising access and backbone demand.
8 Sep 2026 – Verizon and Corning announce multibillion-dollar fiber agreement

The agreement covers more than 80 million miles of high-density optical fiber and connectivity solutions for 2027–2032.

Market relevance: The same infrastructure supports consumer broadband and long-haul AI data-center corridors, demonstrating converged demand.

20 Aug 2026 – Zayo expands long-term Corning supply agreement

Zayo secured cable supply for a plan to add 15,000 route miles through 2030.

Market relevance: Long-haul AI infrastructure is becoming a direct driver of physical fiber-cable procurement.

8 Jun 2026 – Amazon signs multibillion-dollar Corning agreement

Amazon contracted for U.S.-made fiber, cable and connectivity to support expanding data-center infrastructure.

Market relevance: Hyperscaler demand is translating into new domestic manufacturing jobs and cable capacity.

Full-report coverage: Country-level revenue, sales, supplier positioning and forecast detail are retained in the full study; this overview highlights the countries with the clearest, independently supportable demand mechanisms.
Europe FTTP & DATA-CENTER EXPANSION MARKET

What supports European fiber-optic cable demand?

Europe continues replacing copper access networks with FTTP while expanding cloud and AI data-center infrastructure. The European Commission reported FTTP coverage of 74.1% across the EU27 in mid-2025, making fiber the most widespread individual fixed technology. Corning and Prysmian are also adding regional capacity for data-center connectivity.

Market positionLarge mature region
Growth outlookModerate to strong
Demand profileFTTP and data centers
Market access gateVHCN targets, deployment speed and local capacity
Country / market Position in region Evidence-led demand logic
Germany Large upgrade opportunity Legacy copper/cable networks create substantial remaining FTTP build potential, while data-center clusters add enterprise and AI demand.
France Advanced FTTP market High fiber-to-premises coverage supports ongoing network completion, densification and enterprise connectivity.
Poland Manufacturing and data-center supply hub Corning is expanding optical-connectivity manufacturing capacity in Stryków to serve Europe, the Middle East and Africa.
United Kingdom Active fiber-alternative market Multiple fiber operators and data-center investment support continued access and backbone construction.
20 Jul 2026 – Prysmian announces major optical capacity expansion

Prysmian signed a long-term data-center cable agreement and plans to expand optical fiber and cable production in the U.S. and Europe.

Market relevance: Hyperscaler contracts are supporting multi-year manufacturing investment beyond traditional telecom access.

17 Jun 2026 – EU publishes 2025 connectivity coverage

The European Commission reported EU27 FTTP coverage of 74.1% and VHCN coverage of 85.6%.

Market relevance: Continued gap-to-target creates remaining cable demand as copper networks are retired.

9 Apr 2026 – Corning expands Poland optical-connectivity capacity

Corning announced a new Stryków facility to serve AI data-center and micro-optics demand across EMEA.

Market relevance: Regional manufacturing reduces lead time and supports higher fiber density in European data centers.

Full-report coverage: Country-level revenue, sales, supplier positioning and forecast detail are retained in the full study; this overview highlights the countries with the clearest, independently supportable demand mechanisms.
South America EMERGING FIBER INFRASTRUCTURE MARKET

Where does fiber-cable demand develop in South America?

Brazil is the largest regional telecom and data-center market, while Chile has become an important cloud and submarine-cable location. Fiber rollout is driven by urban broadband, mobile backhaul, enterprise connectivity and long-distance routes between major cities. Upfront civil works remain a major constraint.

Market positionEmerging market
Growth outlookSelective
Demand profileFTTx, metro and data centers
Market access gateCivil cost, rights-of-way and financing
Country / market Position in region Evidence-led demand logic
Brazil Largest regional market FTTx, mobile networks, cloud regions and a large enterprise base create the broadest fiber demand.
Chile Data-center and submarine-cable hub International connectivity and cloud infrastructure support long-haul and metro fiber requirements.
Argentina Urban broadband market Fiber-to-home and carrier network upgrades create selective single-mode cable demand.
2025–2026 – regional cloud capacity expands

More cloud and colocation facilities increase metro and long-haul connectivity needs.

Market relevance: Data-center growth creates fiber demand beyond residential broadband.

2025–2026 – FTTx rollout continues in major cities

Operators continue replacing copper and wireless last-mile links with fiber.

Market relevance: Access-network construction remains the largest physical-cable opportunity.

2026 – submarine and cross-border connectivity stays strategic

International routes support cloud, content and enterprise traffic.

Market relevance: Landing stations and terrestrial backhaul create additional long-distance cable demand.

Full-report coverage: Country-level revenue, sales, supplier positioning and forecast detail are retained in the full study; this overview highlights the countries with the clearest, independently supportable demand mechanisms.
Middle East & Africa SMART INFRASTRUCTURE & BACKBONE MARKET

What drives fiber demand in the Middle East and Africa?

Gulf countries are building AI data centers, smart cities and national fiber backbones, while African markets expand mobile transport, metro rings and international connectivity. Long distances and uneven fixed infrastructure make fiber economics highly project-specific, but large digital-infrastructure programs can create substantial cable orders.

Market positionEmerging market
Growth outlookSelective
Demand profileData centers, telecom backbone and smart cities
Market access gateProject finance, installation and imported supply
Country / market Position in region Evidence-led demand logic
United Arab Emirates AI and cloud hub Data-center and smart-city investment creates dense metro and campus fiber demand.
Saudi Arabia Large infrastructure growth market Cloud, telecom and giga-projects require backbone, metro and access fiber networks.
South Africa Regional telecom and data-center anchor Enterprise, cloud and carrier networks create steady metro and long-haul demand.
East Africa International connectivity growth corridor Submarine landings and mobile broadband expansion increase backbone and metro fiber requirements.
2026 – Corning expands EMEA-serving capacity in Poland

The Stryków expansion is designed to meet data-center connectivity demand across Europe, the Middle East and Africa.

Market relevance: Regional supply investment reflects growing EMEA demand for high-density fiber infrastructure.

2025–2026 – Gulf AI infrastructure expands

Large AI and cloud projects require dense optical connectivity inside campuses and between facilities.

Market relevance: Fiber demand grows alongside compute investment and high-capacity network buildout.

2025–2026 – African backbone expansion continues

Mobile operators and wholesale carriers extend national and cross-border fiber routes.

Market relevance: Single-mode cable remains central to lowering unit bandwidth cost over long distances.

Full-report coverage: Country-level revenue, sales, supplier positioning and forecast detail are retained in the full study; this overview highlights the countries with the clearest, independently supportable demand mechanisms.

Competitive Landscape

Key companies include Prysmian, Hengtong Group, Furukawa Electric, Corning, YOFC, Futong, Fujikura, Sumitomo Electric, Tongding, CommScope, Sterlite Technologies, FiberHome, Jiangsu Etern, ZTT, Belden, Nexans, Kaile and LS Cable & System.

Prysmian and Corning compete through global fiber and cable manufacturing, high-density product design and long-term relationships with telecom and hyperscale customers. Both are expanding capacity specifically for AI data-center demand, showing a shift from traditional telecom-only growth toward a broader digital-infrastructure market.

Chinese suppliers including YOFC, Hengtong, ZTT, FiberHome and Futong have major scale advantages in Asia Pacific and participate in large domestic and export infrastructure programs. Japanese companies Furukawa, Fujikura and Sumitomo Electric maintain strong technology positions in specialty fiber, telecom and high-quality cable.

CommScope, Sterlite, Belden, Nexans and regional suppliers compete in access, enterprise, data-center and specialty cable segments. Differentiation increasingly depends on fiber density, deployment speed, bend performance, connector systems and the ability to guarantee large multi-year supply.

Competitive tier Representative companies Commercial basis
Global integrated fiber leaders Prysmian; Corning; Furukawa Electric; Sumitomo Electric Fiber preform, drawing, cable engineering, global manufacturing and hyperscaler/telecom relationships.
China scale manufacturers YOFC; Hengtong Group; ZTT Group; FiberHome; Futong; Tongding Large domestic demand, vertically integrated production and cost-competitive high-volume supply.
Network & specialty cable suppliers CommScope; Sterlite Technologies; Fujikura; Belden; Nexans; LS Cable & System FTTx, enterprise, data center, specialty cable and regional installation ecosystems.

Key Market Participants

Prysmian Group, Hengtong Group, Furukawa Electric, Corning Incorporated, Yangtze Optical Fibre and Cable (YOFC), Futong Group, Fujikura, Sumitomo Electric Industries, Tongding Group, CommScope, Sterlite Technologies, FiberHome Technologies, Jiangsu Etern, ZTT Group, Belden, Nexans, LS Cable & System.

Production Capacity Analysis

Fiber-optic cable capacity begins with high-purity glass preforms and fiber drawing, followed by coating, coloring, ribboning or buffering, cable stranding, armoring, jacketing and final optical testing. Capacity can be constrained at either the fiber-drawing stage or cable-conversion stage depending on product mix.

Optical fiber production starts with silica preforms engineered for precise refractive-index profiles. The preform is heated and drawn into thin glass fiber, coated and tested for attenuation, geometry and strength. This stage requires significant capital and materials expertise.

Cable plants convert fiber into loose-tube, ribbon, drop, armored, aerial or indoor products. High-density data-center and conduit-constrained applications favor smaller outer diameters and more efficient fiber organization.

Large infrastructure customers increasingly use multi-year supply agreements to secure capacity. Corning’s agreements with Verizon, Amazon, Meta and Zayo and Prysmian’s 2026 hyperscaler initiatives show that physical fiber and cable availability can become a strategic constraint during rapid AI-network expansion.

Capacity layer Where it concentrates Commercial constraint
Preform & fiber drawing United States, China, Japan, Europe and India Glass purity, draw-tower capacity, attenuation and bend performance.
Fiber coating / ribboning Integrated fiber plants Coating durability, ribbon density, identification and splice compatibility.
Cable manufacturing Global telecom manufacturing hubs Fiber count, diameter, armoring, fire rating and production throughput.
Installation & test Local operator and contractor ecosystems Splicing skill, civil works, OTDR testing, rights-of-way and project scheduling.

Market Dynamics

Fiber-cable demand is supported by persistent broadband and a new AI-driven infrastructure cycle. The main barriers are civil-construction cost, installation labor, rights-of-way and the capital required to expand glass and cable manufacturing before demand is fully contracted.

Market Drivers

Factor Directional impact Why it matters
FTTx broadband expansion High Fiber is replacing copper in access networks and extending to more homes and businesses.
AI data centers High Larger clusters require far more internal and inter-campus optical connectivity.
Long-haul network expansion High Hyperscalers and carriers are adding new routes between data-center regions.
5G / metro transport Medium-High Cell-site and edge aggregation depend on high-capacity fiber backhaul.

FTTx creates long-duration access-network demand

Fiber access networks are infrastructure assets designed for decades of use. Once operators commit to a region, cable demand continues across feeder, distribution and drop networks.

AI sharply increases fiber density

Large accelerator clusters use many more optical connections per rack and need higher-capacity interconnect between campuses. This raises both total fiber mileage and the value of high-density cable designs.

Long-haul routes become part of AI strategy

Cloud and network operators are building new corridors directly between AI campuses. Zayo’s planned route expansion and Verizon’s AI backbone strategy show that fiber cable is now a physical input to compute scaling.

5G keeps metro fiber investment active

Mobile networks need fiber from cell sites to aggregation and core facilities. More radios and edge sites increase route diversity and fiber-count requirements.

Market Restraints

Factor Directional impact Why it matters
Civil construction cost High Trenching, conduit and permitting can exceed the cost of the cable itself.
Skilled labor shortage Medium-High Splicing and field installation require trained technicians.
Rights-of-way and permitting Medium-High Urban and rural deployment can be delayed by access approvals.
Manufacturing capacity timing Medium Fiber and cable plants require capital before long-term demand is fully known.

Civil works dominate many project budgets

Digging streets, installing conduit and restoring surfaces can cost far more than the fiber. Operators therefore favor aerial deployment, existing ducts and smaller cables where possible.

Installation labor can limit project pace

Fiber networks require trained crews for pulling, splicing, termination and testing. Rapid national broadband programs can strain local contractor capacity.

Rights-of-way create schedule uncertainty

Railways, highways, municipalities and private landowners can each require separate permissions. Delays can leave purchased cable inventory idle and reduce project returns.

Capacity expansion carries forecasting risk

A fiber draw tower or cable plant represents a long-lived capital asset. Suppliers increasingly prefer multi-year customer agreements before committing to major expansions.

Market Opportunities

AI-ready long-haul corridors

New routes connecting hyperscale data centers create large, multi-year single-mode cable demand.

High-density data-center cable

Smaller-diameter and high-fiber-count designs can reduce rack, tray and conduit congestion.

Rural and national broadband

Public funding and operator expansion continue opening FTTx opportunities outside dense urban areas.

Fiber manufacturing localization

Hyperscaler and telecom contracts can justify new regional drawing and cable plants for supply resilience.

Supply Chain Analysis

Preform & GlassHigh-purity silica is engineered into optical preforms.
Fiber DrawingPreforms are drawn into coated single-mode or multimode optical fiber.
Cable ConversionFibers are buffered, ribboned, stranded, armored and jacketed for specific environments.
Network DeploymentOperators, data centers and contractors install, splice and test the cable.

Preform & Glass. Vertical integration into preforms can improve control over fiber quality and capacity. Refractive-index precision determines attenuation and transmission performance.

Fiber Drawing. Draw towers turn preforms into continuous fiber at high speed. Coating, geometry and proof testing must remain stable across long production runs.

Cable Conversion. Cable plants adapt fiber for aerial, duct, buried, indoor or data-center use. Fiber count, ribbon design, armor and jacket materials vary by deployment.

Network Deployment. Field installation requires ducts, poles, splicing hardware, skilled labor and test equipment. Deployment speed is therefore determined by a local ecosystem rather than cable manufacturing alone.

Recent Developments in the Fiber Optic Cables Market

Developments tracked to September 2026. Entries are dated to the official publication date where available.

  • 8 September 2026 Supply agreement
    Verizon and Corning announced a multiyear, multibillion-dollar agreement covering more than 80 million miles of high-density optical fiber and connectivity solutions from 2027 to 2032. The network will support broadband expansion and long-haul AI infrastructure. Source
  • 20 August 2026 Long-haul
    Zayo expanded its strategic supply agreement with Corning to secure cable for a plan to add 15,000 route miles through 2030. AI infrastructure is increasing demand for new long-haul physical routes. Source
  • 20 July 2026 Capacity
    Prysmian announced a major optical-fiber and cable capacity increase tied to hyperscaler and data-center agreements. The company plans to more than double U.S. fiber capacity and expand optical production in the U.S. and Europe. Source
  • 8 June 2026 Hyperscaler agreement
    Amazon signed a multibillion-dollar agreement with Corning for U.S.-made fiber, cable and connectivity for data-center infrastructure. The deal also supports expanded manufacturing in North Carolina. Source
  • 31 March 2026 Manufacturing
    Corning and Meta began construction on an expansion of optical-cable manufacturing capacity in Hickory, North Carolina. The project supports a multiyear agreement for advanced AI data-center connectivity. Source

Report Scope & Segmentation

Attribute Coverage
Report title Fiber Optic Cables Market, Global Business Strategies 2025-2032
Base / estimate / forecast 2025 base year; 2026 estimated year; 2034 forecast end year; CAGR measured for 2026–2034.
By Type Single-Mode; Multi-Mode
By Application FTTx; Long-Distance Communication; Local Mobile Metro Network; CATV; Other Local Access Network; Multimode Fiber Applications; Others
Regions North America, Europe, Asia-Pacific, South America, and Middle East & Africa, with country-level analysis across the principal national markets.
Companies Prysmian Group, Hengtong Group, Furukawa Electric, Corning Incorporated, Yangtze Optical Fibre and Cable (YOFC), Futong Group, Fujikura, Sumitomo Electric Industries, Tongding Group, CommScope, Sterlite Technologies, FiberHome Technologies, Jiangsu Etern, ZTT Group, Belden, Nexans, LS Cable & System
Customization Scope Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope.

Frequently Asked Questions

What is the size of the Fiber Optic Cables market?

The global Fiber Optic Cables market is valued at USD 8,546.9 million in 2025, is estimated at USD 8,930.3 million in 2026, and is projected to reach USD 12,685.8 million by 2034, representing a 4.5% CAGR during 2026–2034.

Which region leads the Fiber Optic Cables market?

Asia Pacific leads with more than 60% share in the report scope, supported by large-scale broadband deployment and manufacturing.

Which cable type leads the market?

Single-Mode Fiber Optic Cable leads with more than 97% share because FTTx, metro and long-haul networks rely on its low attenuation and high bandwidth.

Which application is largest?

FTTx is the largest application, followed by long-distance communication, as operators continue extending fiber closer to homes and businesses.

Why is AI increasing fiber-cable demand?

AI data centers require more optical connections inside racks and campuses and also need new long-haul routes between compute clusters, raising both cable density and total route mileage.

What are the main market restraints?

Civil-construction cost, skilled-labor shortages, rights-of-way and permitting, and the capital required to expand fiber/cable manufacturing are the main restraints.

Who are the major fiber-optic cable companies?

Major companies include Prysmian, Hengtong, Furukawa, Corning, YOFC, Fujikura, Sumitomo Electric, CommScope, Sterlite, FiberHome, ZTT, Belden and Nexans.

Why is single-mode fiber future-proof?

Operators can increase network capacity by upgrading optical transceivers while retaining the installed single-mode cable, giving fiber infrastructure a long useful life.

How is Europe progressing on FTTP?

The European Commission reported EU27 FTTP coverage of 74.1% as of mid-2025, with fiber becoming the most widespread individual fixed-access technology.

Where are the strongest opportunities?

The strongest opportunities are in AI-ready long-haul corridors, high-density data-center cable, rural broadband and localized fiber manufacturing.

Research Sources & Evidence Base
View research sources used for this overview
  1. Corning. Verizon High-Density Fiber Agreement, 2026 broadband and long-haul AI fiber demand..
  2. Corning. Zayo Long-Term Fiber Supply Agreement, 15,000 route-mile expansion plan and AI-ready network demand..
  3. Prysmian. Data Center Optical Capacity Expansion, 2026 hyperscaler agreements and fiber/cable capacity expansion..
  4. Corning. Amazon U.S. Fiber Optics Agreement, Data-center cable demand and U.S. manufacturing expansion..
  5. European Commission. Digital Decade 2026 Connectivity Coverage, EU FTTP and VHCN coverage statistics..
  6. CommScope. From AI to the Edge: Why Fiber Networks Matter More Than Ever, Fiber bandwidth, latency and access-network relevance to AI..
  7. Corning. PRIZM TMT High-Density Connectivity, Higher fiber density inside AI racks and data centers..
Fiber Optic Cables Market, Trends, Business Strategies 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Fiber Optic Cables Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Fiber Optic Cables Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Fiber Optic Cables Overall Market Size
2.1 Global Fiber Optic Cables Market Size: 2024 VS 2032
2.2 Global Fiber Optic Cables Market Size, Prospects & Forecasts: 2020-2032
2.3 Global Fiber Optic Cables Sales: 2020-2032
3 Company Landscape
3.1 Top Fiber Optic Cables Players in Global Market
3.2 Top Global Fiber Optic Cables Companies Ranked by Revenue
3.3 Global Fiber Optic Cables Revenue by Companies
3.4 Global Fiber Optic Cables Sales by Companies
3.5 Global Fiber Optic Cables Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 Fiber Optic Cables Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers Fiber Optic Cables Product Type
3.8 Tier 1, Tier 2, and Tier 3 Fiber Optic Cables Players in Global Market
3.8.1 List of Global Tier 1 Fiber Optic Cables Companies
3.8.2 List of Global Tier 2 and Tier 3 Fiber Optic Cables Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global Fiber Optic Cables Market Size Markets, 2024 & 2032
4.1.2 Single-Mode
4.1.3 Multi-Mode
4.2 Segment by Type – Global Fiber Optic Cables Revenue & Forecasts
4.2.1 Segment by Type – Global Fiber Optic Cables Revenue, 2020-2025
4.2.2 Segment by Type – Global Fiber Optic Cables Revenue, 2026-2032
4.2.3 Segment by Type – Global Fiber Optic Cables Revenue Market Share, 2020-2032
4.3 Segment by Type – Global Fiber Optic Cables Sales & Forecasts
4.3.1 Segment by Type – Global Fiber Optic Cables Sales, 2020-2025
4.3.2 Segment by Type – Global Fiber Optic Cables Sales, 2026-2032
4.3.3 Segment by Type – Global Fiber Optic Cables Sales Market Share, 2020-2032
4.4 Segment by Type – Global Fiber Optic Cables Price (Manufacturers Selling Prices), 2020-2032
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global Fiber Optic Cables Market Size, 2024 & 2032
5.1.2 Long-Distance Communication
5.1.3 FTTx
5.1.4 Local Mobile Metro Network
5.1.5 Other Local Access Network
5.1.6 CATV
5.1.7 Multimode Fiber Applications
5.1.8 Others
5.2 Segment by Application – Global Fiber Optic Cables Revenue & Forecasts
5.2.1 Segment by Application – Global Fiber Optic Cables Revenue, 2020-2025
5.2.2 Segment by Application – Global Fiber Optic Cables Revenue, 2026-2032
5.2.3 Segment by Application – Global Fiber Optic Cables Revenue Market Share, 2020-2032
5.3 Segment by Application – Global Fiber Optic Cables Sales & Forecasts
5.3.1 Segment by Application – Global Fiber Optic Cables Sales, 2020-2025
5.3.2 Segment by Application – Global Fiber Optic Cables Sales, 2026-2032
5.3.3 Segment by Application – Global Fiber Optic Cables Sales Market Share, 2020-2032
5.4 Segment by Application – Global Fiber Optic Cables Price (Manufacturers Selling Prices), 2020-2032
6 Sights by Region
6.1 By Region – Global Fiber Optic Cables Market Size, 2024 & 2032
6.2 By Region – Global Fiber Optic Cables Revenue & Forecasts
6.2.1 By Region – Global Fiber Optic Cables Revenue, 2020-2025
6.2.2 By Region – Global Fiber Optic Cables Revenue, 2026-2032
6.2.3 By Region – Global Fiber Optic Cables Revenue Market Share, 2020-2032
6.3 By Region – Global Fiber Optic Cables Sales & Forecasts
6.3.1 By Region – Global Fiber Optic Cables Sales, 2020-2025
6.3.2 By Region – Global Fiber Optic Cables Sales, 2026-2032
6.3.3 By Region – Global Fiber Optic Cables Sales Market Share, 2020-2032
6.4 North America
6.4.1 By Country – North America Fiber Optic Cables Revenue, 2020-2032
6.4.2 By Country – North America Fiber Optic Cables Sales, 2020-2032
6.4.3 United States Fiber Optic Cables Market Size, 2020-2032
6.4.4 Canada Fiber Optic Cables Market Size, 2020-2032
6.4.5 Mexico Fiber Optic Cables Market Size, 2020-2032
6.5 Europe
6.5.1 By Country – Europe Fiber Optic Cables Revenue, 2020-2032
6.5.2 By Country – Europe Fiber Optic Cables Sales, 2020-2032
6.5.3 Germany Fiber Optic Cables Market Size, 2020-2032
6.5.4 France Fiber Optic Cables Market Size, 2020-2032
6.5.5 U.K. Fiber Optic Cables Market Size, 2020-2032
6.5.6 Italy Fiber Optic Cables Market Size, 2020-2032
6.5.7 Russia Fiber Optic Cables Market Size, 2020-2032
6.5.8 Nordic Countries Fiber Optic Cables Market Size, 2020-2032
6.5.9 Benelux Fiber Optic Cables Market Size, 2020-2032
6.6 Asia
6.6.1 By Region – Asia Fiber Optic Cables Revenue, 2020-2032
6.6.2 By Region – Asia Fiber Optic Cables Sales, 2020-2032
6.6.3 China Fiber Optic Cables Market Size, 2020-2032
6.6.4 Japan Fiber Optic Cables Market Size, 2020-2032
6.6.5 South Korea Fiber Optic Cables Market Size, 2020-2032
6.6.6 Southeast Asia Fiber Optic Cables Market Size, 2020-2032
6.6.7 India Fiber Optic Cables Market Size, 2020-2032
6.7 South America
6.7.1 By Country – South America Fiber Optic Cables Revenue, 2020-2032
6.7.2 By Country – South America Fiber Optic Cables Sales, 2020-2032
6.7.3 Brazil Fiber Optic Cables Market Size, 2020-2032
6.7.4 Argentina Fiber Optic Cables Market Size, 2020-2032
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa Fiber Optic Cables Revenue, 2020-2032
6.8.2 By Country – Middle East & Africa Fiber Optic Cables Sales, 2020-2032
6.8.3 Turkey Fiber Optic Cables Market Size, 2020-2032
6.8.4 Israel Fiber Optic Cables Market Size, 2020-2032
6.8.5 Saudi Arabia Fiber Optic Cables Market Size, 2020-2032
6.8.6 UAE Fiber Optic Cables Market Size, 2020-2032
7 Manufacturers & Brands Profiles
7.1 Prysmian
7.1.1 Prysmian Company Summary
7.1.2 Prysmian Business Overview
7.1.3 Prysmian Fiber Optic Cables Major Product Offerings
7.1.4 Prysmian Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.1.5 Prysmian Key News & Latest Developments
7.2 HTGD
7.2.1 HTGD Company Summary
7.2.2 HTGD Business Overview
7.2.3 HTGD Fiber Optic Cables Major Product Offerings
7.2.4 HTGD Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.2.5 HTGD Key News & Latest Developments
7.3 Furukawa
7.3.1 Furukawa Company Summary
7.3.2 Furukawa Business Overview
7.3.3 Furukawa Fiber Optic Cables Major Product Offerings
7.3.4 Furukawa Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.3.5 Furukawa Key News & Latest Developments
7.4 Corning
7.4.1 Corning Company Summary
7.4.2 Corning Business Overview
7.4.3 Corning Fiber Optic Cables Major Product Offerings
7.4.4 Corning Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.4.5 Corning Key News & Latest Developments
7.5 YOFC
7.5.1 YOFC Company Summary
7.5.2 YOFC Business Overview
7.5.3 YOFC Fiber Optic Cables Major Product Offerings
7.5.4 YOFC Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.5.5 YOFC Key News & Latest Developments
7.6 Futong
7.6.1 Futong Company Summary
7.6.2 Futong Business Overview
7.6.3 Futong Fiber Optic Cables Major Product Offerings
7.6.4 Futong Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.6.5 Futong Key News & Latest Developments
7.7 Fujikura
7.7.1 Fujikura Company Summary
7.7.2 Fujikura Business Overview
7.7.3 Fujikura Fiber Optic Cables Major Product Offerings
7.7.4 Fujikura Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.7.5 Fujikura Key News & Latest Developments
7.8 Sumitomo
7.8.1 Sumitomo Company Summary
7.8.2 Sumitomo Business Overview
7.8.3 Sumitomo Fiber Optic Cables Major Product Offerings
7.8.4 Sumitomo Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.8.5 Sumitomo Key News & Latest Developments
7.9 Tongding
7.9.1 Tongding Company Summary
7.9.2 Tongding Business Overview
7.9.3 Tongding Fiber Optic Cables Major Product Offerings
7.9.4 Tongding Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.9.5 Tongding Key News & Latest Developments
7.10 CommScope
7.10.1 CommScope Company Summary
7.10.2 CommScope Business Overview
7.10.3 CommScope Fiber Optic Cables Major Product Offerings
7.10.4 CommScope Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.10.5 CommScope Key News & Latest Developments
7.11 Sterlite
7.11.1 Sterlite Company Summary
7.11.2 Sterlite Business Overview
7.11.3 Sterlite Fiber Optic Cables Major Product Offerings
7.11.4 Sterlite Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.11.5 Sterlite Key News & Latest Developments
7.12 FiberHome
7.12.1 FiberHome Company Summary
7.12.2 FiberHome Business Overview
7.12.3 FiberHome Fiber Optic Cables Major Product Offerings
7.12.4 FiberHome Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.12.5 FiberHome Key News & Latest Developments
7.13 Jiangsu Etern
7.13.1 Jiangsu Etern Company Summary
7.13.2 Jiangsu Etern Business Overview
7.13.3 Jiangsu Etern Fiber Optic Cables Major Product Offerings
7.13.4 Jiangsu Etern Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.13.5 Jiangsu Etern Key News & Latest Developments
7.14 ZTT
7.14.1 ZTT Company Summary
7.14.2 ZTT Business Overview
7.14.3 ZTT Fiber Optic Cables Major Product Offerings
7.14.4 ZTT Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.14.5 ZTT Key News & Latest Developments
7.15 Belden
7.15.1 Belden Company Summary
7.15.2 Belden Business Overview
7.15.3 Belden Fiber Optic Cables Major Product Offerings
7.15.4 Belden Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.15.5 Belden Key News & Latest Developments
7.16 Nexans
7.16.1 Nexans Company Summary
7.16.2 Nexans Business Overview
7.16.3 Nexans Fiber Optic Cables Major Product Offerings
7.16.4 Nexans Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.16.5 Nexans Key News & Latest Developments
7.17 Kaile
7.17.1 Kaile Company Summary
7.17.2 Kaile Business Overview
7.17.3 Kaile Fiber Optic Cables Major Product Offerings
7.17.4 Kaile Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.17.5 Kaile Key News & Latest Developments
7.18 LS Cable?System
7.18.1 LS Cable?System Company Summary
7.18.2 LS Cable?System Business Overview
7.18.3 LS Cable?System Fiber Optic Cables Major Product Offerings
7.18.4 LS Cable?System Fiber Optic Cables Sales and Revenue in Global (2020-2025)
7.18.5 LS Cable?System Key News & Latest Developments
8 Global Fiber Optic Cables Production Capacity, Analysis
8.1 Global Fiber Optic Cables Production Capacity, 2020-2032
8.2 Fiber Optic Cables Production Capacity of Key Manufacturers in Global Market
8.3 Global Fiber Optic Cables Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 Fiber Optic Cables Supply Chain Analysis
10.1 Fiber Optic Cables Industry Value Chain
10.2 Fiber Optic Cables Upstream Market
10.3 Fiber Optic Cables Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 Fiber Optic Cables Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of Fiber Optic Cables in Global Market
Table 2. Top Fiber Optic Cables Players in Global Market, Ranking by Revenue (2024)
Table 3. Global Fiber Optic Cables Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global Fiber Optic Cables Revenue Share by Companies, 2020-2025
Table 5. Global Fiber Optic Cables Sales by Companies, (M Fiber-Km), 2020-2025
Table 6. Global Fiber Optic Cables Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers Fiber Optic Cables Price (2020-2025) & (USD/Fiber-Km)
Table 8. Global Manufacturers Fiber Optic Cables Product Type
Table 9. List of Global Tier 1 Fiber Optic Cables Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Fiber Optic Cables Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global Fiber Optic Cables Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global Fiber Optic Cables Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global Fiber Optic Cables Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global Fiber Optic Cables Sales (M Fiber-Km), 2020-2025
Table 15. Segment by Type – Global Fiber Optic Cables Sales (M Fiber-Km), 2026-2032
Table 16. Segment by Application – Global Fiber Optic Cables Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global Fiber Optic Cables Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global Fiber Optic Cables Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global Fiber Optic Cables Sales, (M Fiber-Km), 2020-2025
Table 20. Segment by Application – Global Fiber Optic Cables Sales, (M Fiber-Km), 2026-2032
Table 21. By Region – Global Fiber Optic Cables Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global Fiber Optic Cables Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global Fiber Optic Cables Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global Fiber Optic Cables Sales, (M Fiber-Km), 2020-2025
Table 25. By Region – Global Fiber Optic Cables Sales, (M Fiber-Km), 2026-2032
Table 26. By Country – North America Fiber Optic Cables Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America Fiber Optic Cables Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America Fiber Optic Cables Sales, (M Fiber-Km), 2020-2025
Table 29. By Country – North America Fiber Optic Cables Sales, (M Fiber-Km), 2026-2032
Table 30. By Country – Europe Fiber Optic Cables Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe Fiber Optic Cables Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe Fiber Optic Cables Sales, (M Fiber-Km), 2020-2025
Table 33. By Country – Europe Fiber Optic Cables Sales, (M Fiber-Km), 2026-2032
Table 34. By Region – Asia Fiber Optic Cables Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia Fiber Optic Cables Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia Fiber Optic Cables Sales, (M Fiber-Km), 2020-2025
Table 37. By Region – Asia Fiber Optic Cables Sales, (M Fiber-Km), 2026-2032
Table 38. By Country – South America Fiber Optic Cables Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America Fiber Optic Cables Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America Fiber Optic Cables Sales, (M Fiber-Km), 2020-2025
Table 41. By Country – South America Fiber Optic Cables Sales, (M Fiber-Km), 2026-2032
Table 42. By Country – Middle East & Africa Fiber Optic Cables Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa Fiber Optic Cables Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa Fiber Optic Cables Sales, (M Fiber-Km), 2020-2025
Table 45. By Country – Middle East & Africa Fiber Optic Cables Sales, (M Fiber-Km), 2026-2032
Table 46. Prysmian Company Summary
Table 47. Prysmian Fiber Optic Cables Product Offerings
Table 48. Prysmian Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 49. Prysmian Key News & Latest Developments
Table 50. HTGD Company Summary
Table 51. HTGD Fiber Optic Cables Product Offerings
Table 52. HTGD Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 53. HTGD Key News & Latest Developments
Table 54. Furukawa Company Summary
Table 55. Furukawa Fiber Optic Cables Product Offerings
Table 56. Furukawa Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 57. Furukawa Key News & Latest Developments
Table 58. Corning Company Summary
Table 59. Corning Fiber Optic Cables Product Offerings
Table 60. Corning Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 61. Corning Key News & Latest Developments
Table 62. YOFC Company Summary
Table 63. YOFC Fiber Optic Cables Product Offerings
Table 64. YOFC Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 65. YOFC Key News & Latest Developments
Table 66. Futong Company Summary
Table 67. Futong Fiber Optic Cables Product Offerings
Table 68. Futong Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 69. Futong Key News & Latest Developments
Table 70. Fujikura Company Summary
Table 71. Fujikura Fiber Optic Cables Product Offerings
Table 72. Fujikura Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 73. Fujikura Key News & Latest Developments
Table 74. Sumitomo Company Summary
Table 75. Sumitomo Fiber Optic Cables Product Offerings
Table 76. Sumitomo Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 77. Sumitomo Key News & Latest Developments
Table 78. Tongding Company Summary
Table 79. Tongding Fiber Optic Cables Product Offerings
Table 80. Tongding Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 81. Tongding Key News & Latest Developments
Table 82. CommScope Company Summary
Table 83. CommScope Fiber Optic Cables Product Offerings
Table 84. CommScope Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 85. CommScope Key News & Latest Developments
Table 86. Sterlite Company Summary
Table 87. Sterlite Fiber Optic Cables Product Offerings
Table 88. Sterlite Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 89. Sterlite Key News & Latest Developments
Table 90. FiberHome Company Summary
Table 91. FiberHome Fiber Optic Cables Product Offerings
Table 92. FiberHome Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 93. FiberHome Key News & Latest Developments
Table 94. Jiangsu Etern Company Summary
Table 95. Jiangsu Etern Fiber Optic Cables Product Offerings
Table 96. Jiangsu Etern Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 97. Jiangsu Etern Key News & Latest Developments
Table 98. ZTT Company Summary
Table 99. ZTT Fiber Optic Cables Product Offerings
Table 100. ZTT Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 101. ZTT Key News & Latest Developments
Table 102. Belden Company Summary
Table 103. Belden Fiber Optic Cables Product Offerings
Table 104. Belden Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 105. Belden Key News & Latest Developments
Table 106. Nexans Company Summary
Table 107. Nexans Fiber Optic Cables Product Offerings
Table 108. Nexans Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 109. Nexans Key News & Latest Developments
Table 110. Kaile Company Summary
Table 111. Kaile Fiber Optic Cables Product Offerings
Table 112. Kaile Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 113. Kaile Key News & Latest Developments
Table 114. LS Cable?System Company Summary
Table 115. LS Cable?System Fiber Optic Cables Product Offerings
Table 116. LS Cable?System Fiber Optic Cables Sales (M Fiber-Km), Revenue (US$, Mn) and Average Price (USD/Fiber-Km) & (2020-2025)
Table 117. LS Cable?System Key News & Latest Developments
Table 118. Fiber Optic Cables Capacity of Key Manufacturers in Global Market, 2023-2025 (M Fiber-Km)
Table 119. Global Fiber Optic Cables Capacity Market Share of Key Manufacturers, 2023-2025
Table 120. Global Fiber Optic Cables Production by Region, 2020-2025 (M Fiber-Km)
Table 121. Global Fiber Optic Cables Production by Region, 2026-2032 (M Fiber-Km)
Table 122. Fiber Optic Cables Market Opportunities & Trends in Global Market
Table 123. Fiber Optic Cables Market Drivers in Global Market
Table 124. Fiber Optic Cables Market Restraints in Global Market
Table 125. Fiber Optic Cables Raw Materials
Table 126. Fiber Optic Cables Raw Materials Suppliers in Global Market
Table 127. Typical Fiber Optic Cables Downstream
Table 128. Fiber Optic Cables Downstream Clients in Global Market
Table 129. Fiber Optic Cables Distributors and Sales Agents in Global Market

List of Figures
Figure 1. Fiber Optic Cables Product Picture
Figure 2. Fiber Optic Cables Segment by Type in 2024
Figure 3. Fiber Optic Cables Segment by Application in 2024
Figure 4. Global Fiber Optic Cables Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Fiber Optic Cables Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Fiber Optic Cables Revenue: 2020-2032 (US$, Mn)
Figure 8. Fiber Optic Cables Sales in Global Market: 2020-2032 (M Fiber-Km)
Figure 9. The Top 3 and 5 Players Market Share by Fiber Optic Cables Revenue in 2024
Figure 10. Segment by Type – Global Fiber Optic Cables Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global Fiber Optic Cables Revenue Market Share, 2020-2032
Figure 12. Segment by Type – Global Fiber Optic Cables Sales Market Share, 2020-2032
Figure 13. Segment by Type – Global Fiber Optic Cables Price (USD/Fiber-Km), 2020-2032
Figure 14. Segment by Application – Global Fiber Optic Cables Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global Fiber Optic Cables Revenue Market Share, 2020-2032
Figure 16. Segment by Application – Global Fiber Optic Cables Sales Market Share, 2020-2032
Figure 17. Segment by Application -Global Fiber Optic Cables Price (USD/Fiber-Km), 2020-2032
Figure 18. By Region – Global Fiber Optic Cables Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global Fiber Optic Cables Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global Fiber Optic Cables Revenue Market Share, 2020-2032
Figure 21. By Region – Global Fiber Optic Cables Sales Market Share, 2020-2032
Figure 22. By Country – North America Fiber Optic Cables Revenue Market Share, 2020-2032
Figure 23. By Country – North America Fiber Optic Cables Sales Market Share, 2020-2032
Figure 24. United States Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 25. Canada Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 26. Mexico Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 27. By Country – Europe Fiber Optic Cables Revenue Market Share, 2020-2032
Figure 28. By Country – Europe Fiber Optic Cables Sales Market Share, 2020-2032
Figure 29. Germany Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 30. France Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 31. U.K. Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 32. Italy Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 33. Russia Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 34. Nordic Countries Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 35. Benelux Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 36. By Region – Asia Fiber Optic Cables Revenue Market Share, 2020-2032
Figure 37. By Region – Asia Fiber Optic Cables Sales Market Share, 2020-2032
Figure 38. China Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 39. Japan Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 40. South Korea Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 41. Southeast Asia Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 42. India Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 43. By Country – South America Fiber Optic Cables Revenue Market Share, 2020-2032
Figure 44. By Country – South America Fiber Optic Cables Sales, Market Share, 2020-2032
Figure 45. Brazil Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 46. Argentina Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 47. By Country – Middle East & Africa Fiber Optic Cables Revenue, Market Share, 2020-2032
Figure 48. By Country – Middle East & Africa Fiber Optic Cables Sales, Market Share, 2020-2032
Figure 49. Turkey Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 50. Israel Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 51. Saudi Arabia Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 52. UAE Fiber Optic Cables Revenue, (US$, Mn), 2020-2032
Figure 53. Global Fiber Optic Cables Production Capacity (M Fiber-Km), 2020-2032
Figure 54. The Percentage of Production Fiber Optic Cables by Region, 2024 VS 2032
Figure 55. Fiber Optic Cables Industry Value Chain
Figure 56. Marketing Channels