Key Statistics
Key Takeaways
- Market trajectory: The global optical fiber development tools market reached USD 1,471 million in 2026 and is projected to reach USD 2,834 million by 2036 at 6.8% CAGR over 2027–2036. Demand follows the actual sale of OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning, rather than the full revenue of adjacent digital infrastructure.
- Evaluation Kits leadership: Evaluation Kits has the largest estimated type share at ~27% in 2026. The fastest-growing type is Evaluation Kits, at ~7.4% CAGR from an estimated ~27% share. In optical fiber development tools revenue structure, configurable evaluation kits combine transceiver support circuits, firmware and connection interfaces for laboratory proof-of-concept and qualification. For product categories in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
- Communication demand: Communication leads application revenue at an estimated ~63% in 2026, while Communication grows most rapidly near ~7.1% CAGR. In optical fiber development tools revenue structure, communication procurement requires equipment-level validation, careful technical selection and documented support. In optical fiber development tools revenue structure, the buying decision reflects device performance under field loads and recognized sales of the specified optical hardware, not all expenditure across the wider customer industry.
- North America position: North America represents the largest regional revenue pool at an estimated ~36% in 2026. Asia-Pacific has the highest regional modeled growth at ~7.7% CAGR. U.S. In optical fiber development tools revenue structure, bEAD fiber buildout and data-center certification create recurring purchases of traceable OTDR, inspection and optical-loss equipment for contractors and network OEMs. In the regional competition setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
- Principal constraint: High calibration and ownership cost is a fundamental restraint. Purchase decisions are also affected by shortage of trained optical test technicians. In the optical fiber development tools market, both conditions limit the speed at which a promising optical product can move into enduring installations; careful lifecycle support remains vital. This matters for adoption barriers, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Optical Fiber Development Tools Market Overview
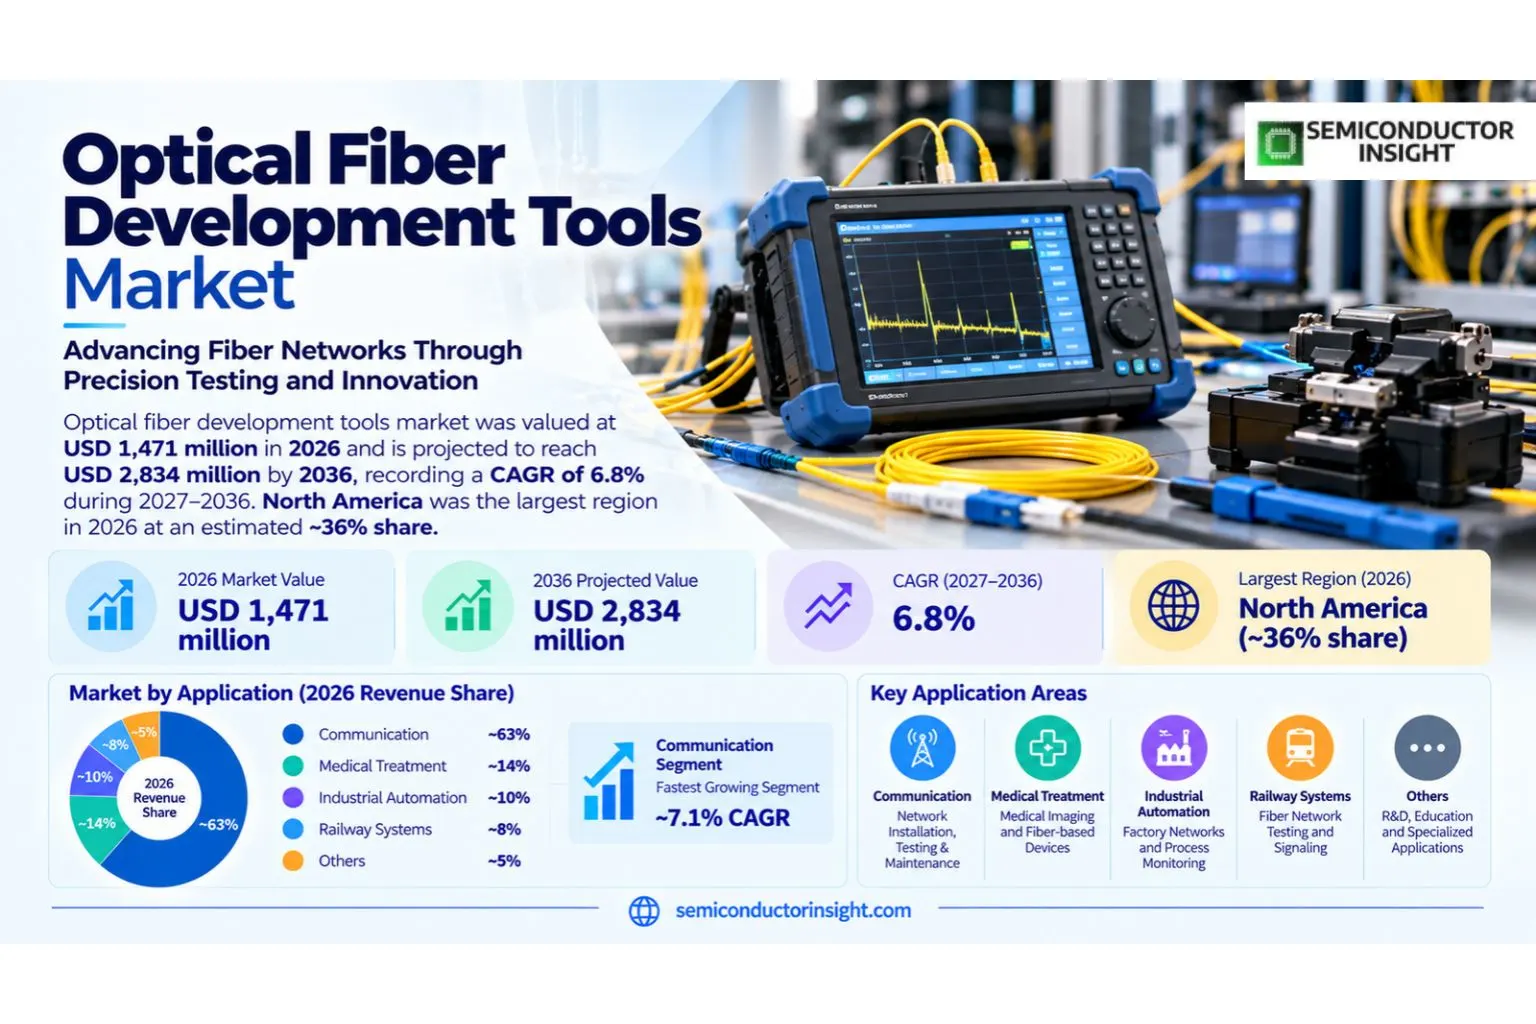
Optical fiber development tools market was valued at USD 1,471 million in 2026 and is projected to reach USD 2,834 million by 2036, recording a CAGR of 6.8% during 2027–2036. North America was the largest region in 2026 at an estimated ~36% share. The market centers on OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning.
Optical Fiber Development Tools encompasses OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning. For optical fiber development tools, the optical interaction carries or secures the functional payload, but the device must also include appropriately designed mechanical, electronic and service interfaces. In the optical fiber development tools market, customers primarily pay for a qualified system that performs consistently in field conditions, rather than a technical principle demonstrated only at prototype level.
The defined commercial boundary includes recognised revenue from fibre optic development tools including evaluation boards and kits, optical power meters, optical time-domain reflectometers, fibre-link characterisation hardware and bundled diagnostic software; excludes installed cable and connector sales, network operator service revenue, unrelated analogue semiconductor sales and complete routers. In the optical fiber development tools market, this distinction prevents a finished datacenter, networking service or unrelated electronic product from being mistaken for direct sales of the specialized component. In the optical fiber development tools market, supplier comparisons are meaningful only when the invoiced product and its value contribution fall within the stated market boundary.
At the engineering level, OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning. In the optical fiber development tools market, designing this technology for 2026 production requires material and mechanical stability, test coverage, procurement planning and the ability to identify a component that has begun to fail. In the optical fiber development tools market, qualification routines can be more costly than the core material in demanding installations.
Demand develops through telecom network testing firms, equipment manufacturers, fibre installation contractors, university photonics labs, railway system integrators and data-centre technicians. In the optical fiber development tools market, those purchasers differ in the volumes they order, the length of their evaluation cycle and the documentation they require. The leading applications are Communication, Medical Treatment, Industrial Automation, Railway Systems, Others; their spending patterns cannot simply be extrapolated from wider electronics or digital-storage demand.
In the optical fiber development tools market, technology priorities are evolving toward more reliable and serviceable optical architectures. In optical fiber development tools commercial scope, configurable evaluation kits combine transceiver support circuits, firmware and connection interfaces for laboratory proof-of-concept and qualification. For optical fiber development tools, the commercial challenge is to turn those technical characteristics into repeat purchasing, while addressing loss of compatibility, changing interfaces and the long-term economics of support. A commercial evaluation of current market transformation therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Segment Analysis: By Type
By type, the optical fiber development tools market comprises Evaluation Boards, Evaluation Kits, Optical Power Meters, Optical Time Domain Reflectometers (OTDR), Others. Evaluation Kits leads with an estimated ~27% revenue share in 2026; Evaluation Kits expands most rapidly at about ~7.4% CAGR from a ~27% share. In the optical fiber development tools market, different physical designs lead to different suppliers, levels of qualification and possible expansion rates.
| Type | Function | Market position |
|---|---|---|
| Evaluation Boards | In Evaluation Boards product design, high-speed transceiver test boards help design engineers evaluate electrical and optical front-end behaviour before authorizing network equipment production. In Evaluation Boards product design, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Evaluation Boards variant affects installation requirements and ongoing service. The 2027–2036 opportunity in Evaluation Boards technical function is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. | Estimated ~24% of 2026 revenue and ~6.2% CAGR. Evaluation Boards is a distinct product category, with demand linked to the particular requirements of its buyers. In Evaluation Boards product design, high-speed transceiver test boards help design engineers evaluate electrical and optical front-end behaviour before authorizing network equipment production at this specific optical fiber development tools purchasing stage. In Evaluation Boards product design, procurement teams evaluate component availability, unit cost and the necessary test records. |
| Evaluation Kits | In Evaluation Kits product design, configurable evaluation kits combine transceiver support circuits, firmware and connection interfaces for laboratory proof-of-concept and qualification. In Evaluation Kits product design, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Evaluation Kits variant affects installation requirements and ongoing service. For Evaluation Kits technical function in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. | Estimated ~27% of 2026 revenue and ~7.4% CAGR. Evaluation Kits is the largest type by value, with demand linked to the particular requirements of its buyers. In Evaluation Kits product design, configurable evaluation kits combine transceiver support circuits, firmware and connection interfaces for laboratory proof-of-concept and qualification at this specific optical fiber development tools purchasing stage. In Evaluation Kits product design, procurement teams evaluate component availability, unit cost and the necessary test records. |
| Optical Power Meters | In Optical Power Meters product design, optical power meters quantify link loss and reference level during connector acceptance and repair, making calibration vital to trustworthy results. In Optical Power Meters product design, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Optical Power Meters variant affects installation requirements and ongoing service. In the Optical Power Meters technical function setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. | Estimated ~15% of 2026 revenue and ~6.3% CAGR. Optical Power Meters is a distinct product category, with demand linked to the particular requirements of its buyers. In Optical Power Meters product design, optical power meters quantify link loss and reference level during connector acceptance and repair, making calibration vital to trustworthy results at this specific optical fiber development tools purchasing stage. In Optical Power Meters product design, procurement teams evaluate component availability, unit cost and the necessary test records. |
| Optical Time Domain Reflectometers (OTDR) | In Optical Time Domain Reflectometers (OTDR) product design, oTDR pulse analysis localizes splice losses, bends and broken fiber along installed spans; access and PON testing creates recurring field demand. In Optical Time Domain Reflectometers (OTDR) product design, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Optical Time Domain Reflectometers (OTDR) variant affects installation requirements and ongoing service. | Estimated ~26% of 2026 revenue and ~7.4% CAGR. Optical Time Domain Reflectometers (OTDR) is a distinct product category, with demand linked to the particular requirements of its buyers. In Optical Time Domain Reflectometers (OTDR) product design, oTDR pulse analysis localizes splice losses, bends and broken fiber along installed spans; access and PON testing creates recurring field demand at this specific optical fiber development tools purchasing stage. In Optical Time Domain Reflectometers (OTDR) product design, procurement teams evaluate component availability, unit cost and the necessary test records. |
| Others | In Others product design, spectrum analyzers, fiber inspection scopes, light sources and configurable test software cover specialized use cases not included in the major listed classes. In Others product design, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Others variant affects installation requirements and ongoing service. This matters for Others technical function, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. | Estimated ~8% of 2026 revenue and ~5.7% CAGR. Others is a distinct product category, with demand linked to the particular requirements of its buyers. In Others product design, spectrum analyzers, fiber inspection scopes, light sources and configurable test software cover specialized use cases not included in the major listed classes at this specific optical fiber development tools purchasing stage. In Others product design, procurement teams evaluate component availability, unit cost and the necessary test records. |
Secondary segmentation: By End User
The By End User classification distinguishes Network Equipment Manufacturers, Telecom Service Providers, Research Institutions, System Integrators, Others. Network Equipment Manufacturers leads this separate estimated 2026 allocation at ~34%. Classifications are parallel descriptions of the same sold hardware; they are not additive product revenue pools. The choice among materials and assembly routes affects cost, thermal tolerance, signal characteristics and reliability.
| Axis | Members | Commercial role |
|---|---|---|
| By End User | Network Equipment Manufacturers; Telecom Service Providers; Research Institutions; System Integrators; Others | Network Equipment Manufacturers accounts for an estimated ~34% of by end user revenue in 2026. Other members address different procurement specifications. The underlying technology involves OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning. The best material or process choice is conditional on the actual optical device, thermal cycle, qualification plan and customer integration cost. |
Segment Analysis: By Application
Application segments are Communication, Medical Treatment, Industrial Automation, Railway Systems, Others. Communication takes the largest estimated 2026 revenue share at ~63%, whereas Communication is the fastest-growing application at ~7.1% CAGR. In the optical fiber development tools market, channel structure, end-user servicing needs and purchasing cadence create distinct addressable opportunities despite shared underlying optical technologies. For optical fiber development tools, a commercial evaluation of application overview therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
| Application | Demand characteristics |
|---|---|
| Communication | Estimated ~63% of 2026 revenue and ~7.1% CAGR. Communication procurement requires equipment-level validation, careful technical selection and documented support. In Communication end-use demand, the buying decision reflects device performance under field loads and recognized sales of the specified optical hardware, not all expenditure across the wider customer industry. For Communication end-use demand, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. |
| Medical Treatment | Estimated ~8% of 2026 revenue and ~6.5% CAGR. Medical Treatment procurement requires equipment-level validation, careful technical selection and documented support. In Medical Treatment end-use demand, the buying decision reflects device performance under field loads and recognized sales of the specified optical hardware, not all expenditure across the wider customer industry. For Medical Treatment end-use demand, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. |
| Industrial Automation | Estimated ~13% of 2026 revenue and ~6.7% CAGR. Industrial Automation procurement requires equipment-level validation, careful technical selection and documented support. In Industrial Automation end-use demand, the buying decision reflects device performance under field loads and recognized sales of the specified optical hardware, not all expenditure across the wider customer industry. For Industrial Automation end-use demand, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. |
| Railway Systems | Estimated ~10% of 2026 revenue and ~5.9% CAGR. Railway Systems procurement requires equipment-level validation, careful technical selection and documented support. In Railway Systems end-use demand, the buying decision reflects device performance under field loads and recognized sales of the specified optical hardware, not all expenditure across the wider customer industry. For Railway Systems end-use demand, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. |
| Others | Estimated ~6% of 2026 revenue and ~6.1% CAGR. Others procurement requires equipment-level validation, careful technical selection and documented support. In Others end-use demand, the buying decision reflects device performance under field loads and recognized sales of the specified optical hardware, not all expenditure across the wider customer industry. For Others end-use demand, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. |
The commercial channel is shaped by telecom network testing firms, equipment manufacturers, fibre installation contractors, university photonics labs, railway system integrators and data-centre technicians. In the optical fiber development tools market, direct equipment purchase, specialist distributor supply and OEM qualification have different order economics. In the optical fiber development tools market, volume can be won through stable specifications and documented reliability, while replacement sales depend on spare availability and retained interface compatibility over the 2027–2036 period.
Regional Analysis
North America leads global revenue with an estimated ~36% share in 2026. Asia-Pacific follows at ~34% and Europe at ~19%. Asia-Pacific has the fastest growth at ~7.7% CAGR. In the optical fiber development tools market, regional purchases and supplier manufacturing footprints must be distinguished for market comparisons. For regional lead in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
How do regional purchasing patterns differ in optical fiber development tools?
Asia-Pacific: Chinese broadband deployment, India optical backhaul and Japanese precision-laboratory equipment provide separate channels for rugged OTDRs and protocol-specific evaluation systems. North America: U.S. In optical fiber development tools regional comparison, bEAD fiber buildout and data-center certification create recurring purchases of traceable OTDR, inspection and optical-loss equipment for contractors and network OEMs. In the optical fiber development tools market, europe has distinct qualification and network compliance requirements; South America and the Middle East and Africa rely more heavily on imported products and local distribution service. In the regional comparison setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Second (~34%) | ~7.7% CAGR | In Asia-Pacific optical fiber development tools market analysis, chinese broadband deployment, India optical backhaul and Japanese precision-laboratory equipment provide separate channels for rugged OTDRs and protocol-specific evaluation systems. Within Asia-Pacific, design wins may be awarded to test-instrument manufacturers outside the installation country even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. For optical fiber development tools, the 2027–2036 opportunity in Asia-Pacific regional demand is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. | For optical fiber development tools, buyers in Asia-Pacific require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Within Asia-Pacific optical fiber development tools market analysis, oTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. For Asia-Pacific purchasing rules in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. |
| North America | Largest (~36%) | ~6.3% CAGR | U.S. In North America optical fiber development tools market analysis, bEAD fiber buildout and data-center certification create recurring purchases of traceable OTDR, inspection and optical-loss equipment for contractors and network OEMs. Within North America, design wins may be awarded to test-instrument manufacturers outside the installation country even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. A commercial evaluation of North America regional demand therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. | For optical fiber development tools, buyers in North America require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Within North America optical fiber development tools market analysis, oTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
| Europe | Third (~19%) | ~6.1% CAGR | In Europe optical fiber development tools market analysis, eU gigabit infrastructure programmes and metrology-focused suppliers reward calibrated testing, connector cleanliness verification and digital reporting across diverse fibre networks. Within Europe, design wins may be awarded to test-instrument manufacturers outside the installation country even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. In the optical fiber development tools market, in the Europe regional demand setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. | For optical fiber development tools, buyers in Europe require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Within Europe optical fiber development tools market analysis, oTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. This matters for Europe purchasing rules, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. |
| South America | Fourth (~7%) | ~6.5% CAGR | In South America optical fiber development tools market analysis, brazilian telecom infrastructure and broadband access projects support portable fiber testers, but equipment exchange rates and training costs affect contractor purchasing. Within South America, design wins may be awarded to test-instrument manufacturers outside the installation country even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. This matters for South America regional demand, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. | For optical fiber development tools, buyers in South America require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Within South America optical fiber development tools market analysis, oTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
| Middle East & Africa | Fifth (~4%) | ~5.7% CAGR | In Middle East & Africa optical fiber development tools market analysis, gulf datacentre investment and African fibre backbone extensions create field deployment demand where environmental ruggedness, calibration support and technician skills are decisive. Within Middle East & Africa, design wins may be awarded to test-instrument manufacturers outside the installation country even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. | For optical fiber development tools, buyers in Middle East & Africa require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. Within Middle East & Africa optical fiber development tools market analysis, oTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
Competitive Landscape
Competition is led by firms with relevant OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning. For optical fiber development tools, the competitive field includes established manufacturers, original equipment suppliers and historical product brands whose present scope differs. For optical fiber development tools, buyers compare product-specific technical evidence and order terms instead of total corporate turnover, because an optical component represents only part of a finished digital system.
Analog Devices, Inc. and Broadcom Inc. illustrate different capabilities within the sector. In the optical fiber development tools market, their product portfolios, production locations and support arrangements cannot be assumed identical. In the optical fiber development tools market, procurement departments typically request specification sheets, samples, aging or thermal data and a long-term sourcing plan before designating a manufacturing source for a multi-year contract. This matters for manufacturer capability, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
II-VI Incorporated/Coherent Corp., Glenair, Inc., Maxim Integrated (now part of Analog Devices), Mikroelektronika, Hodiall S.A. (Radiall) appear in the wider manufacturer and distributor field. For optical fiber development tools, the roles of those entities require separation: media production, component housing manufacture, systems integration and distribution do not produce the same category of invoice. In the optical fiber development tools market, market rivalry occurs at the level of the particular sold device, not across unrelated corporate divisions.
Other suppliers and historical business names include Mikroelektronika, Hodiall S.A. (Radiall), Semtech Corporation, Texas Instruments Incorporated. In the optical fiber development tools market, legacy corporate names and regional branches may persist in industry directories, while actual current production must be checked against updated company disclosures. In the optical fiber development tools market, product-life-cycle changes can alter sourcing qualification even if an installed system continues to function with existing spare inventories.
In the optical fiber development tools sector, 2027–2036, vendor differentiation will depend on manufacturing yield, documentation, reliable delivery and compatibility with demanding optical interfaces. Price competition may intensify in mature configurations, whereas new package geometries or fiber diagnostics equipment offer specialized margins. For optical fiber development tools, a customer switching supplier must weigh requalification, sample validation and operational interruption against lower unit costs. A commercial evaluation of competitive economics therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Analog Devices, Inc.; Broadcom Inc.; II-VI Incorporated/Coherent Corp. | In the optical fiber development tools market, direct manufacturers with published optical product or packaging activities differentiate through established process control and established technical catalogs. The first technical gate is the ability to supply OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning in a documented, reproducible format, followed by customer qualification and reliable lead times. |
| Tier 2 | Glenair, Inc.; Maxim Integrated (now part of Analog Devices); Mikroelektronika; Hodiall S.A. (Radiall) | In the optical fiber development tools market, regional producers and equipment suppliers compete through specialized configurations, responsive design assistance and local service. In the optical fiber development tools market, customers generally request traceable quality records and samples in the exact form factor they need. In the optical fiber development tools market, lower production scale can be balanced by shorter engineering response times or customization of critical interfaces. The 2027–2036 opportunity in tier 2 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. |
| Tier 3 | Semtech Corporation; Texas Instruments Incorporated | For optical fiber development tools, the broader value chain includes historical participants, distributors, integrators and component companies with adjacent expertise. In the optical fiber development tools market, their names may appear in sector coverage without establishing that each currently sells an identical qualified device. In the optical fiber development tools market, product applicability is determined by specific device families, production status and customer approvals. For tier 3 in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. |
Key companies profiled
- Analog Devices, Inc.
- Broadcom Inc.
- II-VI Incorporated/Coherent Corp.
- Glenair, Inc.
- Maxim Integrated (now part of Analog Devices)
- Mikroelektronika
- Hodiall S.A. (Radiall)
- Semtech Corporation
- Texas Instruments Incorporated
Production Capacity Analysis
Production capacity relies on specialized manufacturing and testing for OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning. In the optical fiber development tools market, effective output is constrained by qualified material lots, process yield, equipment availability and completion of electrical, optical and environmental tests. In the optical fiber development tools market, announced industrial capability should not be equated automatically with installed sales or usable nameplate capacity.
Initial manufacturing operations include OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning. In the optical fiber development tools market, yield is influenced by each fabrication and assembly stage, while changes in materials or process equipment can require formal requalification. In the optical fiber development tools market, japan, China and other Asia-Pacific manufacturing centers support considerable supplier capacity, although customer purchasing decisions may originate elsewhere.
In the optical fiber development tools market, diversified capacity can reduce country-of-origin exposure and help supply different qualification requirements. In the optical fiber development tools market, however, transferring tooling and process knowledge between plants takes time, and products made in new locations may require fresh qualification. In the optical fiber development tools market, strong inventory controls and component traceability are important during a period of changing designs and volatile customer orders. In the capacity diversification setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
In the optical fiber development tools market, upstream constraints include materials, specialized assembly equipment and trained optical manufacturing staff. For optical fiber development tools, packaging, testing and maintenance infrastructure shape the ability to convert a technical design into reproducible revenue. In the optical fiber development tools market, companies should distinguish capacity for direct in-scope products from headline capacity for the much larger adjacent electronics manufacturing market. This matters for capacity bottlenecks, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Market Dynamics
Demand is driven by expansion of fibre-to-the-premises networks and rising otdr acceptance testing for gigabit transport. In the optical fiber development tools market, growth depends on matching the optical product to qualification requirements, logistics and total ownership cost. Supplier economics also reflect the negative impact of high calibration and ownership cost, particularly when customers require long operational support. A commercial evaluation of dynamics lead therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Expansion of fibre-to-the-premises networks | +1.8% | Asia-Pacific | 2027–2036 |
| Rising OTDR acceptance testing for gigabit transport | +1.4% | Global | 2028–2034 |
| Data-centre connector inspection and certification | +1.1% | North America | 2027–2031 |
| Automated multiwavelength link analysis | +0.9% | Europe | 2029–2036 |
| 5G fronthaul commissioning and troubleshooting | +0.7% | Global | 2028–2035 |
Expansion of fibre-to-the-premises networks
Expansion of fibre-to-the-premises networks supports specialized purchases for optical fiber development tools. In expansion of fibre-to-the-premises networks in optical fiber development tools, oTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning must be integrated into customer processes, inspected and supported. The growth effect is directional, not a separate addition to the headline CAGR. In expansion of fibre-to-the-premises networks in optical fiber development tools, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
Rising OTDR acceptance testing for gigabit transport
Rising OTDR acceptance testing for gigabit transport supports specialized purchases for optical fiber development tools. In rising otdr acceptance testing for gigabit transport in optical fiber development tools, oTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning must be integrated into customer processes, inspected and supported. The growth effect is directional, not a separate addition to the headline CAGR. In rising otdr acceptance testing for gigabit transport in optical fiber development tools, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
Data-centre connector inspection and certification
Data-centre connector inspection and certification supports specialized purchases for optical fiber development tools. In data-centre connector inspection and certification in optical fiber development tools, oTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning must be integrated into customer processes, inspected and supported. The growth effect is directional, not a separate addition to the headline CAGR. In data-centre connector inspection and certification in optical fiber development tools, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
Automated multiwavelength link analysis
Automated multiwavelength link analysis supports specialized purchases for optical fiber development tools. In automated multiwavelength link analysis in optical fiber development tools, oTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning must be integrated into customer processes, inspected and supported. The growth effect is directional, not a separate addition to the headline CAGR. In automated multiwavelength link analysis in optical fiber development tools, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| High calibration and ownership cost | −1.5% | Global | 2027–2036 |
| Shortage of trained optical test technicians | −1.1% | Europe and North America | 2027–2034 |
| Vendor-specific protocols and test configuration | −0.8% | Asia-Pacific | 2028–2035 |
| Legacy test instrument interoperability | −0.6% | Global | 2029–2036 |
High calibration and ownership cost
High calibration and ownership cost increases the effort required to qualify or replace optical fiber development tools. In high calibration and ownership cost in optical fiber development tools, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. For high calibration and ownership cost in optical fiber development tools, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. The 2027–2036 opportunity in High calibration and ownership cost restraint is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
Shortage of trained optical test technicians
Shortage of trained optical test technicians increases the effort required to qualify or replace optical fiber development tools. In shortage of trained optical test technicians in optical fiber development tools, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. For shortage of trained optical test technicians in optical fiber development tools, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. For Shortage of trained optical test technicians restraint in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
Vendor-specific protocols and test configuration
Vendor-specific protocols and test configuration increases the effort required to qualify or replace optical fiber development tools. In vendor-specific protocols and test configuration in optical fiber development tools, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. For vendor-specific protocols and test configuration in optical fiber development tools, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. In the Vendor-specific protocols and test configuration restraint setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Legacy test instrument interoperability
Legacy test instrument interoperability increases the effort required to qualify or replace optical fiber development tools. In legacy test instrument interoperability in optical fiber development tools, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. For legacy test instrument interoperability in optical fiber development tools, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. This matters for Legacy test instrument interoperability restraint, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
MARKET OPPORTUNITIES
Automated OTDR and iOLM workflows
Automated OTDR and iOLM workflows creates an opportunity to improve deployment or the supplier value proposition. In automated otdr and iolm workflows in optical fiber development tools, the relevant engineering work concerns OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning. For automated otdr and iolm workflows in optical fiber development tools, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. In automated otdr and iolm workflows in optical fiber development tools, the commercial impact is strongest where those requirements can be standardized across several customers.
Portable optical spectrum and power instrumentation
Portable optical spectrum and power instrumentation creates an opportunity to improve deployment or the supplier value proposition. In portable optical spectrum and power instrumentation in optical fiber development tools, the relevant engineering work concerns OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning. For portable optical spectrum and power instrumentation in optical fiber development tools, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. In portable optical spectrum and power instrumentation in optical fiber development tools, the commercial impact is strongest where those requirements can be standardized across several customers.
High-port-count data-centre test automation
High-port-count data-centre test automation creates an opportunity to improve deployment or the supplier value proposition. In high-port-count data-centre test automation in optical fiber development tools, the relevant engineering work concerns OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning. For high-port-count data-centre test automation in optical fiber development tools, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. In high-port-count data-centre test automation in optical fiber development tools, the commercial impact is strongest where those requirements can be standardized across several customers.
Remote fibre monitoring in access networks
Remote fibre monitoring in access networks creates an opportunity to improve deployment or the supplier value proposition. In remote fibre monitoring in access networks in optical fiber development tools, the relevant engineering work concerns OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning. For remote fibre monitoring in access networks in optical fiber development tools, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. In remote fibre monitoring in access networks in optical fiber development tools, the commercial impact is strongest where those requirements can be standardized across several customers.
Supply Chain Analysis
The supply chain links specialized raw materials, device fabrication, verification, system integration and servicing for optical fiber development tools. A failure at any stage can invalidate the qualified end product. In the optical fiber development tools market, vendor selection is therefore affected by more than selling price: replacement-component availability, inspection data, lead time and the ability to support legacy interfaces are commercially significant.
Upstream materials. In upstream materials in optical fiber development tools, materials and optical substrates required for OTDR pulse reflectometry, optical link power loss instrumentation, transceiver evaluation boards and software-driven fibre commissioning; inspection before assembly. Within upstream materials in optical fiber development tools, optical fiber development tools, controlling change across this stage enables traceability, reliability and repeatable delivery. In upstream materials in optical fiber development tools, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment.
Manufacturing. In manufacturing in optical fiber development tools, fabrication, alignment, sealing or recording operations matched to the market boundary. Within manufacturing in optical fiber development tools, optical fiber development tools, controlling change across this stage enables traceability, reliability and repeatable delivery. In manufacturing in optical fiber development tools, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment. In the Manufacturing chain setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Channels. In channels in optical fiber development tools, oEM engineering contracts, technical distributors and integrated storage or optical equipment vendors. Within channels in optical fiber development tools, optical fiber development tools, controlling change across this stage enables traceability, reliability and repeatable delivery. In channels in optical fiber development tools, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment. This matters for Channels chain, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Downstream users. In downstream users in optical fiber development tools, telecom network testing firms, equipment manufacturers, fibre installation contractors, university photonics labs, railway system integrators and data-centre technicians; qualification, deployment and lifecycle support. Within downstream users in optical fiber development tools, optical fiber development tools, controlling change across this stage enables traceability, reliability and repeatable delivery. In downstream users in optical fiber development tools, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment.
Recent Developments
- 18 August 2026 Published
VIAVI presented 4100-series OTDR modules for modular test platforms used in metro, FTTP and long-haul commissioning. Interchangeable hardware can improve the installed test-instrument base, but acquisition decisions still require calibration traceability and compatible software reporting. A commercial evaluation of Optical Fiber Development Tools development 18 August 2026 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. Source - 13 April 2026 Published
Anritsu issued new 2026 OTDR and 10G/100G testing documentation for its MT1000A Network Master Pro platform. These modules combine fiber event detection and data-plane tests, encouraging engineering buyers to evaluate one modular instrument rather than ordering unrelated single-purpose meters. The 2027–2036 opportunity in Optical Fiber Development Tools development 13 April 2026 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. Source - 9 February 2026 Announced
NTIA reported approvals for 50 BEAD final broadband proposals, providing a route to fiber access construction across multiple states and territories. Field qualification teams require optical loss tests and reproducible OTDR records; the total value of broadband infrastructure grants is not equivalent to test device revenue. For Optical Fiber Development Tools development 9 February 2026 in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. Source - 17 June 2026 Published
The European Commission published its 2026 Digital Decade assessment, examining fibre and gigabit coverage and the remaining gaps across the EU. Additional commissioning and network maintenance create demand for standards-based portable optical test equipment and consistent technician reporting. In the Optical Fiber Development Tools development 17 June 2026 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. Source - 15 October 2025 Published
ITU Facts and Figures 2025 detailed global internet adoption and remaining connectivity gaps. Expansion in user connectivity supports infrastructure investments in optical access, but the instrument market responds to construction, certification and fault-repair purchases, not directly to subscriber revenue. This matters for Optical Fiber Development Tools development 15 October 2025, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. Source - 29 July 2025 Published
Anritsu described optical transport network test methods and service activation measurement tools on its MT1000A product platform. Maintaining bit error rate and traffic performance alongside physical fiber diagnostics expands the scope of optical development instruments. A commercial evaluation of Optical Fiber Development Tools development 29 July 2025 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. Source - 30 July 2025 Published
The Ethernet Alliance published evolving link-speed roadmaps used by optical equipment engineers to plan more demanding test configurations. Increasing serial lane speed and optics density heighten the importance of device qualification, connector inspection and measured optical margins. The 2027–2036 opportunity in Optical Fiber Development Tools development 30 July 2025 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2036 |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2027–2036 |
| Historical Period | 2021–2025 |
| Base Year Market Size | USD 1,471 million |
| Estimated Year Market Size | USD 1,571 million |
| Forecast Year Market Size | USD 2,834 million |
| CAGR | 6.8% |
| Unit | USD million |
| Market Definition | recognised revenue from fibre optic development tools including evaluation boards and kits, optical power meters, optical time-domain reflectometers, fibre-link characterisation hardware and bundled diagnostic software; excludes installed cable and connector sales, network operator service revenue, unrelated analogue semiconductor sales and complete routers |
| By Type | Evaluation Boards · Evaluation Kits · Optical Power Meters · Optical Time Domain Reflectometers (OTDR) · Others |
| By Application | Communication · Medical Treatment · Industrial Automation · Railway Systems · Others |
| By End User | Network Equipment Manufacturers · Telecom Service Providers · Research Institutions · System Integrators · Others |
| By Region | Asia-Pacific, North America, Europe, South America, and Middle East & Africa allocated by location of equipment purchase or component consumption. Asia-PacificChina · Japan · India · South Korea North AmericaUnited States · Canada · Mexico EuropeGermany · United Kingdom · France South AmericaBrazil · Chile · Argentina Middle East & AfricaSaudi Arabia · United Arab Emirates · South Africa |
| Key Companies Profiled | Analog Devices, Inc.; Broadcom Inc.; II-VI Incorporated/Coherent Corp.; Glenair, Inc.; Maxim Integrated (now part of Analog Devices); Mikroelektronika; Hodiall S.A. (Radiall); Semtech Corporation; Texas Instruments Incorporated |
| Customization Scope | Supplier, type, application and regional price analysis for optical fiber development tools; estimated market shares in 2026 and differentiated growth paths for 2027–2036. |
Frequently Asked Questions
What is the global optical fiber development tools market size?
The global optical fiber development tools market is valued at USD 1,471 million in 2026 and is forecast to reach USD 2,834 million by 2036, with 6.8% CAGR during 2027–2036. For optical fiber development tools, the demand boundary is specific to the optical equipment and technology defined here rather than the full revenue of all data-center, media, automotive or electronics systems.
Which geographic region is the largest market?
North America is the leading 2026 regional market with an estimated ~36% of revenue. Asia-Pacific and Europe follow at ~34% and ~19%, respectively. In the optical fiber development tools market, differences in OEM manufacturing locations and customer purchasing geography can otherwise distort region comparisons. For FAQ 2 in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
Which region has the fastest growth rate?
Asia-Pacific has the highest estimated regional expansion at ~7.7% CAGR through 2036. In optical fiber development tools buyer demand, chinese broadband deployment, India optical backhaul and Japanese precision-laboratory equipment provide separate channels for rugged OTDRs and protocol-specific evaluation systems. For optical fiber development tools, the rate is linked to equipment deployment, supplier qualification and the technology mix, rather than broad GDP growth alone. In the FAQ 3 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Which type holds the largest revenue share?
Evaluation Kits represents an estimated ~27% of the 2026 market. In optical fiber development tools buyer demand, configurable evaluation kits combine transceiver support circuits, firmware and connection interfaces for laboratory proof-of-concept and qualification. For optical fiber development tools, buyers need to verify its performance, equipment compatibility and the available delivery chain before treating it as an interchangeable substitute for another optical format. This matters for FAQ 4, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Which type is projected to expand fastest?
Evaluation Kits carries the strongest estimated type growth at ~7.4% CAGR, from around ~27% of 2026 revenue. For optical fiber development tools, the product mix changes as users adopt performance-enhancing configurations, but engineering qualification and lifecycle servicing determine how quickly that potential converts into orders. A commercial evaluation of FAQ 5 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
What is the leading application?
Communication is the largest application at approximately ~63% of 2026 revenue. In optical fiber development tools buyer demand, communication procurement requires equipment-level validation, careful technical selection and documented support. In optical fiber development tools buyer demand, the buying decision reflects device performance under field loads and recognized sales of the specified optical hardware, not all expenditure across the wider customer industry. In the optical fiber development tools market, procurement specifications depend on actual operating conditions; total revenue in the wider user industry is not a direct proxy for the value of optical equipment purchased.
Which application grows fastest?
Communication is projected to grow at ~7.1% CAGR from approximately ~63% of 2026 revenue. In optical fiber development tools buyer demand, communication procurement requires equipment-level validation, careful technical selection and documented support at this specific optical fiber development tools purchasing stage. In optical fiber development tools buyer demand, the buying decision reflects device performance under field loads and recognized sales of the specified optical hardware, not all expenditure across the wider customer industry at this specific optical fiber development tools purchasing stage. In the optical fiber development tools market, growth is affected by price changes and supplier qualification as well as physical unit demand.
Which companies are included?
The profiled market participants include Analog Devices, Inc., Broadcom Inc., II-VI Incorporated/Coherent Corp., Glenair, Inc., Maxim Integrated (now part of Analog Devices), Mikroelektronika. In the optical fiber development tools market, these companies may operate in different parts of the value chain and in some cases retain historical naming. In the optical fiber development tools market, comparisons need to distinguish direct in-scope equipment manufacturing from distribution, materials and wider group revenues.
What restrains adoption?
High calibration and ownership cost is a notable limitation, alongside shortage of trained optical test technicians. In the optical fiber development tools market, customers must also examine service cost, quality-control requirements and purchasing terms. In the optical fiber development tools market, technical improvement will not necessarily produce corresponding annual revenue growth without reproducible production and access to qualified buyers. The 2027–2036 opportunity in FAQ 9 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
What is the study period and segmentation scope?
For optical fiber development tools, the base year is 2026, the estimated year is 2027, and the forecast runs through 2036 with historical context from 2021–2025. Segmentation by type covers Evaluation Boards, Evaluation Kits, Optical Power Meters, Optical Time Domain Reflectometers (OTDR), Others and by application covers Communication, Medical Treatment, Industrial Automation, Railway Systems, Others. Five geographic regions are included.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF