Key Statistics
Key Takeaways
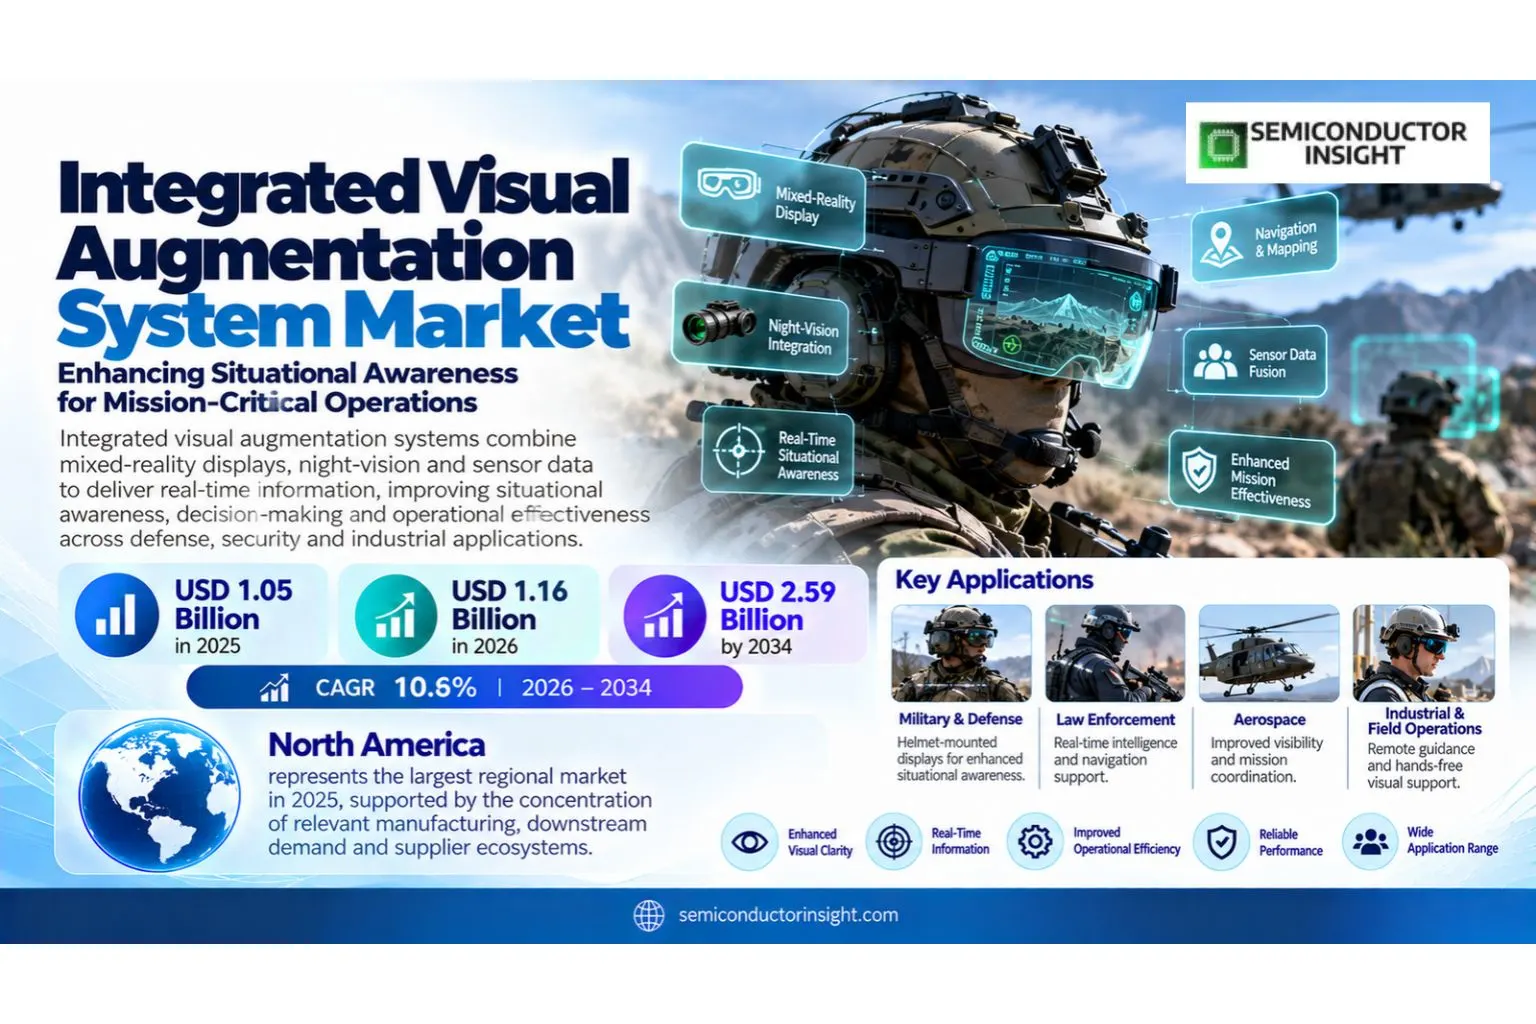
- The market is valued at USD 1.05 billion in 2025 and is projected to reach USD 2.59 billion by 2034, representing a 10.6% CAGR over 2026–2034.
- Helmet Mounted Display is a major product segment, while adjacent variants are expanding as performance, integration and cost requirements evolve.
- Army is a leading application area, supported by demand across Air Force, Navy.
- North America is the largest market in 2025 based on the current concentration of demand, manufacturing capacity and ecosystem maturity.
Integrated Visual Augmentation System Market Overview
Integrated Visual Augmentation System products combine head-mounted displays, night vision, augmented or mixed reality, navigation, targeting and tactical networking into a wearable soldier system. The objective is to place relevant mission information directly in the user’s field of view while maintaining hands-free mobility and access to low-light or thermal imagery.
The market is moving from a single hardware program toward broader soldier-borne mission-command architectures. Current development emphasizes lower weight, better comfort, improved battery life, open software integration and AI-enabled sensor fusion. This increases the value of compute, networking and software alongside the optical headset itself. Suppliers that translate technical improvements into measurable gains in efficiency, uptime, cost, ergonomics or workflow simplicity are better positioned to win long-duration programs and repeat purchases.
Segment Analysis: By Type
Helmet-mounted mixed-reality displays capture the highest system value because they combine digital overlays, navigation and sensor imagery in the soldier’s field of view. Night-vision components remain essential for low-light operation and increasingly fuse with digital imagery rather than operating as standalone optics. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Type | Market relevance |
|---|---|
| Helmet Mounted Display | Core mixed-reality visualization platform. |
| Night Vision Device | Low-light and thermal sensing layer. |
Segment Analysis: By Application
Army use dominates because dismounted soldiers have the clearest requirement for hands-free navigation, targeting and tactical awareness. Air Force and Navy applications extend to maintenance, training and mission-support contexts where wearable visualization can reduce task time. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Application | Market relevance |
|---|---|
| Army | Largest dismounted soldier deployment. |
| Air Force | Flight-line, maintenance and mission applications. |
| Navy | Shipboard and expeditionary mission support. |
Segment Analysis: By Capability
Situational awareness is the broadest capability layer, while thermal fusion and AI-assisted threat cueing add higher-value functions. Training and simulation are important because the same wearable platform can support rehearsal and operational modes. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Capability | Market relevance |
|---|---|
| Situational Awareness | Real-time overlays and team awareness. |
| Night Vision & Thermal Fusion | Low-light and thermal fusion. |
| Navigation & Targeting | Mission guidance and weapon cueing. |
| Training & Simulation | Synthetic rehearsal on common hardware. |
Segment Analysis: By Component
Head-worn displays and optical systems account for large hardware value, while software, AI, edge compute and networking are becoming increasingly important because military utility depends on timely fusion of sensor and mission data. Within this segment, customers increasingly compare lifecycle support, qualification requirements, integration effort and total ownership cost rather than relying on a single specification or upfront price.
| Component | Market relevance |
|---|---|
| Head-Worn Display | Optics, waveguides and display. |
| Sensors & Cameras | Thermal, low-light and spatial sensing. |
| Compute & Networking | Edge processing and secure links. |
| Software / AI | Applications, AI and tactical data fusion. |
Regional Analysis
North America leads because the U.S. Army has funded the largest visible program and is transitioning IVAS-related work into Soldier Borne Mission Command, while Europe and Asia Pacific pursue parallel digital-soldier and augmented-reality modernization efforts. Regional share also reflects supplier depth, engineering support, manufacturing concentration and the speed at which new Integrated Visual Augmentation System designs can move from evaluation into repeat deployment.
| Region | 2025 Position | Growth Outlook | Demand Profile |
|---|---|---|---|
| North America | Largest | Very strong | U.S. Army modernization led |
| Europe | High-value modernization market | Strong | Digital soldier and NATO interoperability led |
| Asia Pacific | Growing | Strong | Defense modernization and electronics led |
| Middle East | High-value niche | Strong | Defense procurement led |
| Rest of World | Selective | Moderate | Special forces and modernization led |
Detailed Regional Blocks
Why is North America important to this market?
North America leads through U.S. Army investment in IVAS and its follow-on Soldier Borne Mission Command effort. Procurement is centered on rugged mixed-reality systems integrated with tactical networks, night vision and edge computing. In North America, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| United States | Largest program market | Army modernization drives prototype and production demand. |
| Canada | Allied soldier-modernization niche | Interoperable wearable systems create future opportunity. |
- The U.S. Army FY2026 budget identifies Soldier Borne Mission Command as the program previously named IVAS and includes USD 85.5 million for the IVAS Middle Tier of Acquisition effort.
- Anduril announced a USD 159 million Army contract in September 2025 for an initial prototyping period under Soldier Borne Mission Command.
- The program increasingly emphasizes integration of sensing, compute and tactical data rather than a headset-only architecture.
Why is Europe important to this market?
Europe is a strong modernization market because NATO-aligned forces are investing in digital soldier systems, thermal imaging and networked situational awareness. Programs tend to emphasize modularity and interoperability with existing radios and command systems. In Europe, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| United Kingdom | Soldier modernization | Digital integration and night-vision capability support demand. |
| France | Dismounted systems | Networked soldier programs create mixed-reality opportunities. |
| Germany | Defense electronics | Modernization and NATO interoperability support adoption. |
- European programs often favor modular components that can integrate with existing helmet, radio and weapon ecosystems.
- Thermal and night-vision fusion provides an incremental path toward broader augmented reality.
- Open interfaces reduce dependence on a single proprietary system across long procurement cycles.
Why is Asia Pacific important to this market?
Asia Pacific demand is growing through defense modernization in South Korea, Japan, Australia and India. Local electronics and display capabilities support indigenous development of soldier-worn sensing and visualization. In Asia Pacific, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| South Korea | Advanced defense electronics | Hanwha and local suppliers support wearable systems. |
| Australia | Allied modernization | Interoperability with U.S. systems creates opportunity. |
| India | Large defense modernization market | Domestic electronics programs broaden long-term demand. |
- Regional programs increasingly combine digital maps, navigation and night vision at the soldier level.
- Local manufacturing can reduce lifecycle cost for optics, batteries and rugged compute.
- Training applications provide a lower-risk route to deploy mixed-reality hardware before operational use.
Why is Middle East important to this market?
Gulf defense customers are a high-value niche for advanced night vision, helmet displays and tactical networking. Procurement tends to favor proven systems with strong supplier support and integration into existing command networks. In Middle East, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| Saudi Arabia | Large defense buyer | Modernization supports advanced soldier electronics. |
| United Arab Emirates | Technology-focused procurement | Wearable situational awareness fits digital-force initiatives. |
- Thermal fusion is especially valuable for night operations and harsh environmental conditions.
- Training and simulation can be deployed alongside operational wearable systems.
- Lifecycle support and secure software integration are central procurement considerations.
Why is Rest of World important to this market?
Outside major procurement regions, adoption is selective and concentrated in special forces, training and specific modernization programs. High system cost and network integration requirements limit broad deployment. In Rest of World, procurement decisions also depend on service coverage, qualification resources, logistics and long-term availability, so ecosystem maturity can materially influence adoption even when core technology performance is similar.
| Country / Subregion | Role | Market Context |
|---|---|---|
| Selected allied forces | Specialized deployment | High-value units adopt advanced head-worn systems first. |
| Training organizations | Simulation use | Mixed-reality systems can reduce live-training cost. |
- Battery endurance and ergonomic load remain key barriers to wider soldier deployment.
- Systems must work with existing radios and mission software to deliver operational value.
- Training versions can build user familiarity before combat deployment.
Competitive Landscape
Anduril, Microsoft, Lockheed Martin, BAE Systems, Elbit Systems, RTX, Thales, Vuzix and other defense-electronics suppliers compete across headsets, software, sensing and tactical integration. Competitive advantage depends on ergonomics, night-vision performance, open software architecture, secure networking and successful military qualification.
| Company | Position | Relevant capability |
|---|---|---|
| Anduril Industries | Key participant | Current prime development role in Soldier Borne Mission Command prototyping and Lattice tactical-software integration. |
| Microsoft | Key participant | Developed the original IVAS mixed-reality hardware/software platform and remains an important technology participant. |
| Lockheed Martin | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| BAE Systems | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Elbit Systems | Key participant | Long-standing supplier of helmet-mounted displays and soldier vision systems. |
| RTX | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Thales | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Vuzix | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Hanwha Systems | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
| Honeywell | Key participant | Competes through product breadth, integration capability, qualification and customer support. |
Production Capacity Analysis
Production capacity depends on ruggedized displays, waveguides, thermal sensors, low-light cameras, edge compute, batteries, radios and secure software integration. Unlike commercial AR, defense systems require environmental, cybersecurity and mission testing before fielding. Scaling output without degrading consistency requires stable upstream materials, disciplined process control and final testing that catches drift before products reach high-value customer systems.
The U.S. program is currently prototype-intensive, so engineering and qualification capacity matter as much as factory throughput. Broader volume depends on successful user testing, weight reduction, reliability and alignment with future soldier-network architectures. Second-source planning and regional technical support therefore become increasingly important as deployments expand and buyers seek supply continuity without repeating lengthy qualification work.
Market Dynamics
The market is transitioning from hardware-led augmented reality toward networked soldier mission systems. Visual overlays are useful only when connected to reliable position, sensor, weapon and tactical-network data, making software integration increasingly central. This is changing competitive behavior because vendors increasingly sell system-level value, workflow integration and lifecycle economics rather than an isolated component specification.
Program risk remains high because wearable military systems must balance display performance, battery life, weight, comfort and ruggedness. These constraints can change procurement schedules even when core augmented-reality technology improves quickly. Buyers consequently evaluate total ownership cost, qualification effort and roadmap stability across the life of a program instead of focusing only on initial purchase price.
Market Drivers
| Factor | Analyst Interpretation |
|---|---|
| Defense modernization | Military forces are investing in digital soldier systems and real-time situational awareness. |
| Night-vision integration | Fusing thermal and low-light imagery increases operational value. |
| Tactical networking | Wearable displays can present team, sensor and mission data without handheld devices. |
| Training reuse | Common hardware can support both operational missions and synthetic training. |
Market Restraints
| Factor | Analyst Interpretation |
|---|---|
| Weight and ergonomics | Head-worn systems must remain comfortable during extended missions. |
| Battery endurance | Displays, sensors and compute create high portable power demand. |
| High development cost | Military qualification and software integration are expensive. |
| Cybersecurity and network dependence | Compromised or unavailable tactical data can reduce effectiveness. |
Market Opportunities
| Factor | Analyst Interpretation |
|---|---|
| AI threat cueing | Edge analytics can highlight relevant objects and alerts in the user’s field of view. |
| Open-architecture soldier systems | Modular software and sensors can shorten upgrade cycles. |
| Mounted and aircrew variants | Related technology can extend beyond dismounted infantry. |
| Training and simulation | Mixed reality can reduce live-training cost and increase rehearsal frequency. |
Supply Chain Analysis
The value chain combines microdisplays, optics, thermal and low-light sensors, rugged compute, batteries, communications hardware, mission software and military systems integration. Qualification and secure software are essential because the product operates as part of a broader tactical network. Traceability and coordination between component suppliers, integrators and end users are important because failures found late in the chain can be far more expensive than the underlying part itself.
| Supply Chain Stage | Role in the Market |
|---|---|
| Displays, optics and sensors | Waveguides, cameras and thermal sensors create the visual layer. |
| Edge compute and power | Processors, batteries and thermal management support wearable operation. |
| Secure networking and software | Mission applications fuse location, sensor and tactical data. |
| Military integration and support | Prime contractors qualify systems, train users and sustain deployed equipment. |
Recent Developments
| Date | Development | Source |
|---|---|---|
| September 2025 | Anduril announced a USD 159 million U.S. Army contract for an initial prototyping period under Soldier Borne Mission Command, previously IVAS Next. | Anduril Industries |
| 2026 | The U.S. Army FY2026 budget identifies Soldier Borne Mission Command as the program previously named IVAS and includes USD 85.5 million for the IVAS Middle Tier of Acquisition effort. | U.S. Army |
| September 2024 | Anduril and Microsoft announced integration of the Lattice software platform into the IVAS ecosystem to provide real-time threat information to soldiers. | Anduril Industries |
Report Scope & Segmentation
| Scope Item | Coverage |
|---|---|
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 1.05 billion |
| 2026 Estimated Size | USD 1.16 billion |
| 2034 Forecast Size | USD 2.59 billion |
| CAGR (2026–2034) | 10.6% |
| Largest Market in 2025 | North America |
| Category | Defense Electronics / Augmented Reality / Soldier Systems |
| By Type | Helmet Mounted Display, Night Vision Device |
| By Application | Army, Air Force, Navy |
| By Capability | Situational Awareness, Night Vision & Thermal Fusion, Navigation & Targeting, Training & Simulation |
| By Component | Head-Worn Display, Sensors & Cameras, Compute & Networking, Software / AI |
Frequently Asked Questions
What is the 2025 market size of the Integrated Visual Augmentation System market?
The market is valued at USD 1.05 billion in 2025.
What is the projected 2034 market size of the Integrated Visual Augmentation System market?
The market is projected to reach USD 2.59 billion by 2034.
What is the CAGR of the Integrated Visual Augmentation System market from 2026 to 2034?
The market is expected to expand at a CAGR of 10.6% during 2026–2034.
Which region leads the Integrated Visual Augmentation System market?
North America is the largest market in 2025 based on the current demand, manufacturing and deployment structure.
Which type segment is important in the Integrated Visual Augmentation System market?
Helmet Mounted Display is a major segment, while adjacent product variants are gaining share as performance and integration requirements evolve.
What is the main application for Integrated Visual Augmentation System products?
Army is a leading application, with additional growth coming from Air Force, Navy.
What drives growth in the Integrated Visual Augmentation System market?
Military forces are investing in digital soldier systems and real-time situational awareness.
What is a key restraint for the Integrated Visual Augmentation System market?
Head-worn systems must remain comfortable during extended missions.
Which companies participate in the Integrated Visual Augmentation System market?
Key participants include Anduril Industries, Microsoft, Lockheed Martin, BAE Systems, Elbit Systems, alongside other specialized suppliers and system companies.
What technology trend is shaping the Integrated Visual Augmentation System market?
Edge analytics can highlight relevant objects and alerts in the user’s field of view.
Research Sources & Evidence Base
View research sources used for this overview.
- U.S. Army — FY2026 RDT&E Budget – Soldier Borne Mission Command: Program status, nomenclature and FY2026 IVAS funding context. Source
- Anduril Industries — Soldier Borne Mission Command Contract: 2025 USD 159 million prototype contract and program transition. Source
- Anduril Industries — Lattice Integration with IVAS: 2024 integration of tactical software into the IVAS ecosystem. Source
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF