Key Statistics
Key Takeaways
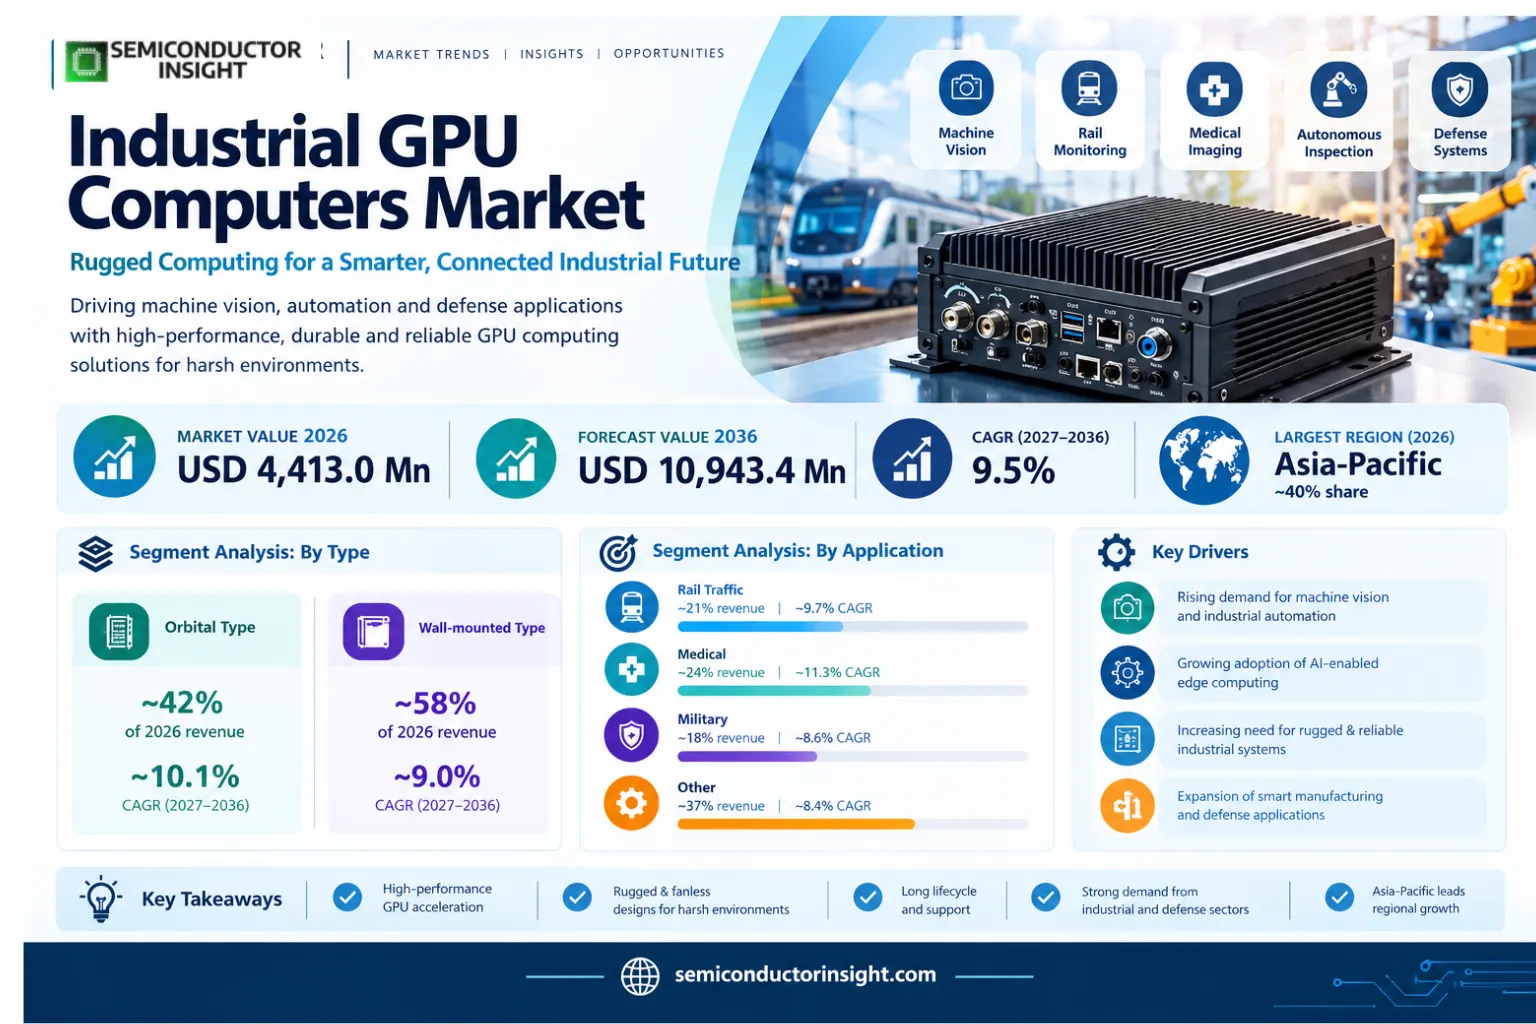
- Market value: The industrial gpu computers market stands at USD 4,413.0 million in 2026 and is projected to reach USD 10,943.4 million by 2036 at a CAGR of 9.5% during 2027–2036. The buying environment is shaped by machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems and the need to reconcile performance with availability, qualification and ownership costs.
- Wall-mounted Type: leads the type classification with an estimated ~58% of 2026 revenue; industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute define why this offering reaches the largest customer base, while differently configured products compete on cost, deployment restrictions and future upgrade paths.
- Other: accounts for an estimated ~37% of 2026 revenue, reflecting machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems; purchasing tends to follow equipment approval, system design and long-term service arrangements instead of isolated chip or hardware demonstrations.
- Asia-Pacific: holds an estimated ~40% of global market revenue in 2026. The regional growth pattern is uneven: Asia-Pacific has an estimated ~10.8% annual growth outlook, and access to product qualification routes differs by geography.
- Key constraint: Heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement limit conversion of planned technology spend into deliveries. Customers purchasing rugged industrial GPU computer systems need supplier evidence that parts remain supported, compatible and serviceable over extended deployments, particularly when a product becomes part of critical infrastructure.
Industrial GPU Computers Market Overview
Industrial GPU computers market was valued at USD 4,413.0 million in 2026 and is projected to reach USD 10,943.4 million by 2036, expanding at a CAGR of 9.5% during 2027–2036. Asia-Pacific represented the largest regional revenue share in 2026, estimated at ~40%, reflecting its central role in the supply or procurement of rugged industrial GPU computer systems.
Industrial GPU Computers is shaped by the design and deployment of industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity. For industrial gpu computers, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. For industrial gpu computers, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
Purchasing industrial gpu computers revenue boundary depends on the sale of rugged industrial GPU computer systems rather than all equipment or cloud services that incorporate them. When selecting industrial gpu computers revenue boundary, system architects compare sales eligibility, product configuration and exclusion of adjacent system revenue for Industrial GPU Computers against long-term integration cost and readiness. For industrial gpu computers revenue boundary, challenges involving double counting the same component through suppliers and system integrators remain adoption hurdles, affecting pricing, validation and repeat orders.
Within technology architecture, industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity; inputs include industrial motherboards, CPUs, GPU modules, rugged enclosures, heat spreaders and industrial I/O affects supplier qualification for technology architecture. When qualifying technology architecture, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. For technology architecture, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
A defining feature of industrial gpu computers end-customer demand is machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems. For industrial gpu computers end-customer demand, engineers balance long-term availability and qualified performance from suppliers of rugged industrial GPU computer systems with lifecycle support and deployment reliability. For industrial gpu computers end-customer demand, challenges involving deployment timing and the availability of compatible infrastructure remain adoption hurdles, affecting pricing, validation and repeat orders.
Current industry transition is shaped by consolidation of visual inspection and industrial robotics inference into rugged edge workstations. For current industry transition, buyers evaluate cost per deployed workload and the maturity of accompanying software and supply contracts for Industrial GPU Computers during qualification rather than in isolated benchmarks. In the market for current industry transition, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
Segment Analysis: By Type
Type segmentation is shaped by 2 published type categories: Orbital Type, Wall-mounted Type; Wall-mounted Type leads at an estimated ~58%. For type segmentation, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. In type segmentation, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site.
| Type | Function | Market position |
|---|---|---|
| Orbital Type | Purchasing orbital type type depends on its use within industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity for machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems. When selecting orbital type type, system architects compare operating limits, interoperability and technical qualification specific to Orbital Type in Industrial GPU Computers against long-term integration cost and readiness. In the market for orbital type type, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. | A defining feature of orbital type commercial position is an estimated ~42% of 2026 category revenue and ~10.1% annual growth to 2036. For orbital type commercial position, engineers balance commercial selection of Orbital Type on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. Buyers of orbital type commercial position must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment. |
| Wall-mounted Type | Within wall-mounted type type, its use within industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity for machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems affects supplier qualification for wall-mounted type type. When qualifying wall-mounted type type, customers place particular weight on operating limits, interoperability and technical qualification specific to Wall-mounted Type in Industrial GPU Computers, because deployment performance matters more than peak specifications. In the market for wall-mounted type type, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. | Wall-mounted Type commercial position is shaped by an estimated ~58% of 2026 category revenue and ~9.0% annual growth to 2036. For wall-mounted type commercial position, buyers evaluate commercial selection of Wall-mounted Type on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. In wall-mounted type commercial position, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site. |
Segment Analysis: By Application
A defining feature of application segmentation is Other is the leading end use at an estimated ~37% of 2026 revenue among 4 application classes. For application segmentation, engineers balance machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems with lifecycle support and deployment reliability. For application segmentation, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
| Application | Demand characteristics |
|---|---|
| Rail Traffic | Purchasing rail traffic application depends on an estimated ~21% of 2026 application revenue and a modeled ~9.7% CAGR, with demand from machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems. When selecting rail traffic application, system architects compare integration testing, operational reliability and buying cycles for Rail Traffic uses of rugged industrial GPU computer systems against long-term integration cost and readiness. In the market for rail traffic application, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. |
| Medical | Within medical application, an estimated ~24% of 2026 application revenue and a modeled ~11.3% CAGR, with demand from machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems affects supplier qualification for medical application. When qualifying medical application, customers place particular weight on integration testing, operational reliability and buying cycles for Medical uses of rugged industrial GPU computer systems, because deployment performance matters more than peak specifications. In the market for medical application, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. |
| Military | A defining feature of military application is an estimated ~18% of 2026 application revenue and a modeled ~8.6% CAGR, with demand from machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems. For military application, engineers balance integration testing, operational reliability and buying cycles for Military uses of rugged industrial GPU computer systems with lifecycle support and deployment reliability. In the market for military application, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. |
| Other | Other application is shaped by an estimated ~37% of 2026 application revenue and a modeled ~8.4% CAGR, with demand from machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems. For other application, buyers evaluate integration testing, operational reliability and buying cycles for Other uses of rugged industrial GPU computer systems during qualification rather than in isolated benchmarks. Buyers of other application must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment. |
Application purchasing channels is shaped by most deployments depend on the larger system integrator which qualifies rugged industrial GPU computer systems within an end product. For application purchasing channels, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. In the market for application purchasing channels, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
Regional Analysis
Within global regional markets, Asia-Pacific leads with ~40% estimated share, followed by North America (~25%) and Europe (~24%), while Asia-Pacific has ~10.8% annual growth affects supplier qualification for global regional markets. When qualifying global regional markets, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. Buyers of global regional markets must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment.
How do regional requirements differ for rugged industrial GPU computer systems?
A defining feature of regional differences is five market geographies have different roles in machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems, with qualification and manufacturing centers separated across borders. For regional differences, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. Buyers of regional differences must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| North America | Rank 2 (~25%) | ~9.3% CAGR | North America demand profile is shaped by factory systems integrators, autonomous mobile equipment and defence test facilities buy certified rugged GPU PCs with support contracts. For north america demand profile, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. In north america demand profile, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site. | Within north america vendor access, factory systems integrators, autonomous mobile equipment and defence test facilities buy certified rugged GPU PCs with support contracts affects supplier qualification for north america vendor access. When qualifying north america vendor access, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. For north america vendor access, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders. |
| Europe | Rank 3 (~24%) | ~8.4% CAGR | Purchasing europe demand profile depends on automation OEMs and rail integrators emphasize industrial software compatibility and long service life. When selecting europe demand profile, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. In europe demand profile, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site. | A defining feature of europe vendor access is automation OEMs and rail integrators emphasize industrial software compatibility and long service life. For europe vendor access, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. For europe vendor access, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders. |
| Asia-Pacific | Largest (~40%) | ~10.8% CAGR | Within asia-pacific demand profile, electronics factories, machine builders and industrial computer manufacturers combine large production capacity with extensive vision inspection demand affects supplier qualification for asia-pacific demand profile. When qualifying asia-pacific demand profile, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. In asia-pacific demand profile, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site. | Asia-Pacific vendor access is shaped by electronics factories, machine builders and industrial computer manufacturers combine large production capacity with extensive vision inspection demand. For asia-pacific vendor access, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. In the market for asia-pacific vendor access, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. |
| South America | Rank 4 (~6%) | ~6.3% CAGR | A defining feature of south america demand profile is mining, utilities and transportation pilots favor serviceable imported rugged computers matched to limited site power and maintenance. For south america demand profile, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. In south america demand profile, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site. | Purchasing south america vendor access depends on mining, utilities and transportation pilots favor serviceable imported rugged computers matched to limited site power and maintenance. When selecting south america vendor access, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. In the market for south america vendor access, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. |
| Middle East & Africa | Rank 5 (~5%) | ~7.8% CAGR | Middle East & Africa demand profile is shaped by critical infrastructure, oilfield remote monitoring and transport surveillance require dust-tolerant and wide-temperature computers. For middle east & africa demand profile, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. For middle east & africa demand profile, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders. | Within middle east & africa vendor access, critical infrastructure, oilfield remote monitoring and transport surveillance require dust-tolerant and wide-temperature computers affects supplier qualification for middle east & africa vendor access. When qualifying middle east & africa vendor access, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. In the market for middle east & africa vendor access, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. |
Competitive Landscape
Within competition and supplier positioning, ADLINK Technology; Advantech; Neousys Technology; OnLogic participate in the supply chain for rugged industrial GPU computer systems affects supplier qualification for competition and supplier positioning. When qualifying competition and supplier positioning, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. In the market for competition and supplier positioning, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
A defining feature of principal direct suppliers is qualified commercial offerings from ADLINK Technology; Advantech; Neousys Technology; OnLogic. For principal direct suppliers, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. In the market for principal direct suppliers, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
Specialist supplier channel is shaped by Premio; SINTRONES; Rugged Science; C&T Solution participate in the wider competitive environment. For specialist supplier channel, buyers evaluate traceable product capabilities and fulfilment of Industrial GPU Computers specifications during qualification rather than in isolated benchmarks. Buyers of specialist supplier channel must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment.
Purchasing industrial gpu computers integration ecosystem depends on Intel; NVIDIA; AMD (component technology, not complete rugged-computer sales) can influence integration while not automatically counting toward the same revenue boundary. When selecting industrial gpu computers integration ecosystem, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. Buyers of industrial gpu computers integration ecosystem must also account for confusing component and complete-system revenues, which shapes design margins and lifetime costs after the first shipment.
Within procurement competition, consolidation of visual inspection and industrial robotics inference into rugged edge workstations affects both established and challenger suppliers affects supplier qualification for procurement competition. When qualifying procurement competition, customers place particular weight on secure lead time and technical support in the Industrial GPU Computers supply chain, because deployment performance matters more than peak specifications. Buyers of procurement competition must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | ADLINK Technology; Advantech; Neousys Technology; OnLogic | A defining feature of tier-one competition is complete supplier offerings for machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems. For tier-one competition, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. Buyers of tier-one competition must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment. |
| Tier 2 | Premio; SINTRONES; Rugged Science; C&T Solution | Tier-two competition is shaped by focus on selected applications and specific integration pathways for rugged industrial GPU computer systems. For tier-two competition, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. In tier-two competition, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site. |
| Tier 3 | Intel; NVIDIA; AMD (component technology, not complete rugged-computer sales) | Purchasing industrial gpu computers ecosystem support depends on component technology or downstream integration that shapes industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity. When selecting industrial gpu computers ecosystem support, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. In industrial gpu computers ecosystem support, risks tied to misclassification of underlying revenue shift the configurations that win volume and determine whether deployments expand beyond the initial site. |
Key companies profiled
- Adlinktech
- Premio
- Advanced
- OnLogic
- Industrial PC
- Neousys Technology
- Advantech
- Assured Systems
- Rugged Science
- SINTRONES
- C&T Solution
Production Capacity Analysis
Within production and capacity, systems design and integration concentrated in Taiwan and specialized manufacturing partners serving North America and Europe affects supplier qualification for production and capacity. When qualifying production and capacity, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. In production and capacity, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site.
A defining feature of production concentration is systems design and integration concentrated in Taiwan and specialized manufacturing partners serving North America and Europe; output requires industrial motherboards, CPUs, GPU modules, rugged enclosures, heat spreaders and industrial I/O. For production concentration, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. In production concentration, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site.
Cross-border sourcing is shaped by subsystem integration for industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity frequently spans foundries, board makers, and qualified manufacturers. For cross-border sourcing, buyers evaluate configuration control and qualified alternatives for Industrial GPU Computers during qualification rather than in isolated benchmarks. For cross-border sourcing, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
Purchasing upstream bottlenecks depends on industrial motherboards, CPUs, GPU modules, rugged enclosures, heat spreaders and industrial I/O can become constrained when accelerator or embedded-system demand accelerates. When selecting upstream bottlenecks, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. For upstream bottlenecks, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
Market Dynamics
Within market drivers, restraints and opportunities, consolidation of visual inspection and industrial robotics inference into rugged edge workstations; the market must still manage heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement affects supplier qualification for market drivers, restraints and opportunities. When qualifying market drivers, restraints and opportunities, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. For market drivers, restraints and opportunities, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| AI workload localization | +1.5% | North America and Asia-Pacific | 2026–2029 |
| Product performance upgrades | +1.1% | Global AI and compute centers | 2027–2032 |
| Industrial deployment scale | +0.8% | Europe and Asia-Pacific | 2026–2034 |
| Integration ecosystem investment | +0.7% | Cross-region system deployment | 2028–2036 |
| Channel expansion | +0.4% | Regional industrial customers | 2026–2036 |
AI workload localization
AI workload localization is shaped by consolidation of visual inspection and industrial robotics inference into rugged edge workstations, raising the need for rugged industrial GPU computer systems. For ai workload localization, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. In the market for ai workload localization, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
Product performance upgrades
Purchasing product performance upgrades depends on consolidation of visual inspection and industrial robotics inference into rugged edge workstations, raising the need for rugged industrial GPU computer systems. When selecting product performance upgrades, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. In the market for product performance upgrades, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
Industrial deployment scale
Within industrial deployment scale, consolidation of visual inspection and industrial robotics inference into rugged edge workstations, raising the need for rugged industrial GPU computer systems affects supplier qualification for industrial deployment scale. When qualifying industrial deployment scale, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. In the market for industrial deployment scale, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
Integration ecosystem investment
A defining feature of integration ecosystem investment is consolidation of visual inspection and industrial robotics inference into rugged edge workstations, raising the need for rugged industrial GPU computer systems. For integration ecosystem investment, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. In the market for integration ecosystem investment, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Integration qualification costs | −0.9% | All regions | 2026–2030 |
| Power and thermal envelope | −0.8% | Asia-Pacific | 2027–2034 |
| Supply and software fragmentation | −0.6% | Industrial projects | 2026–2036 |
| Long-lifecycle replacement risk | −0.5% | Global procurement | 2028–2036 |
Integration qualification costs
Integration qualification costs is shaped by heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement change the level of attainable installation and supply. For integration qualification costs, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. Buyers of integration qualification costs must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment.
Power and thermal envelope
Purchasing power and thermal envelope depends on heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement change the level of attainable installation and supply. When selecting power and thermal envelope, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. Buyers of power and thermal envelope must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment.
Supply and software fragmentation
Within supply and software fragmentation, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement change the level of attainable installation and supply affects supplier qualification for supply and software fragmentation. When qualifying supply and software fragmentation, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. Buyers of supply and software fragmentation must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment.
Long-lifecycle replacement risk
A defining feature of long-lifecycle replacement risk is heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement change the level of attainable installation and supply. For long-lifecycle replacement risk, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. Buyers of long-lifecycle replacement risk must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment.
MARKET OPPORTUNITIES
System design wins in underserved verticals
System design wins in underserved verticals is shaped by customer priorities around machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems shift toward new configurations of industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity. For system design wins in underserved verticals, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. In system design wins in underserved verticals, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site.
Infrastructure retrofits and upgrades
Purchasing infrastructure retrofits and upgrades depends on customer priorities around machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems shift toward new configurations of industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity. When selecting infrastructure retrofits and upgrades, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. In infrastructure retrofits and upgrades, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site.
Local processing in privacy-sensitive sites
Within local processing in privacy-sensitive sites, customer priorities around machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems shift toward new configurations of industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity affects supplier qualification for local processing in privacy-sensitive sites. When qualifying local processing in privacy-sensitive sites, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. In local processing in privacy-sensitive sites, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site.
Supplier partnerships for qualified new products
A defining feature of supplier partnerships for qualified new products is customer priorities around machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems shift toward new configurations of industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity. For supplier partnerships for qualified new products, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. In supplier partnerships for qualified new products, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site.
Supply Chain Analysis
Supply chain structure is shaped by industrial motherboards, CPUs, GPU modules, rugged enclosures, heat spreaders and industrial I/O enter a chain of systems design and integration concentrated in Taiwan and specialized manufacturing partners serving North America and Europe. For supply chain structure, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. For supply chain structure, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
Upstream inputs. Purchasing upstream inputs depends on industrial motherboards, CPUs, GPU modules, rugged enclosures, heat spreaders and industrial I/O serve a defined position in the supply of rugged industrial GPU computer systems. When selecting upstream inputs, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. For upstream inputs, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
Fabrication and assembly. Within fabrication and assembly, systems design and integration concentrated in Taiwan and specialized manufacturing partners serving North America and Europe serve a defined position in the supply of rugged industrial GPU computer systems affects supplier qualification for fabrication and assembly. When qualifying fabrication and assembly, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. For fabrication and assembly, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
System integration. A defining feature of system integration is industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity serve a defined position in the supply of rugged industrial GPU computer systems. For system integration, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. For system integration, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
Deployment channel. Deployment channel is shaped by machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems serve a defined position in the supply of rugged industrial GPU computer systems. For deployment channel, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. In the market for deployment channel, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
Recent Developments
- 2026-08-20 Published
Purchasing qualcomm 2026-08-20 development depends on the industrial edge-ai processors announcement; Dragonwing industrial devices demonstrate another supplier approach to local AI compute.. When selecting qualcomm 2026-08-20 development, system architects compare qualified procurement and integration of rugged industrial GPU computer systems against long-term integration cost and readiness. In the market for qualcomm 2026-08-20 development, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. Source - 2026-07-15 Announced
Within nvidia 2026-07-15 development, the updated jetson thor systems announcement; A compact computer portfolio links GPU performance to on-device autonomous applications. affects supplier qualification for nvidia 2026-07-15 development. When qualifying nvidia 2026-07-15 development, customers place particular weight on qualified procurement and integration of rugged industrial GPU computer systems, because deployment performance matters more than peak specifications. In the market for nvidia 2026-07-15 development, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. Source - 2026-07-14 Published
A defining feature of semi 2026-07-14 development is the semiconductor equipment investment outlook announcement; Manufacturing investment provides context for processor and accelerator component supply.. For semi 2026-07-14 development, engineers balance qualified procurement and integration of rugged industrial GPU computer systems with lifecycle support and deployment reliability. In the market for semi 2026-07-14 development, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support. Source - 2026-06-01 Announced
Qualcomm 2026-06-01 development is shaped by the robotics reference design announcement; The reference design combines perception, deterministic control and industrial edge interfaces.. For qualcomm 2026-06-01 development, buyers evaluate qualified procurement and integration of rugged industrial GPU computer systems during qualification rather than in isolated benchmarks. Buyers of qualcomm 2026-06-01 development must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment. Source - 2026-04-21 Published
Purchasing onlogic 2026-04-21 development depends on the siemens industrial edge partnership announcement; The partnership places ruggedized fanless hardware into Siemens industrial-edge environments.. When selecting onlogic 2026-04-21 development, system architects compare qualified procurement and integration of rugged industrial GPU computer systems against long-term integration cost and readiness. Buyers of onlogic 2026-04-21 development must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment. Source - 2026-03-17 Announced
Within adlink 2026-03-17 development, the industrial jetson thor and igx thor systems announcement; Industrial-grade DLAP platforms bring Thor AI compute to robotics and image-processing systems. affects supplier qualification for adlink 2026-03-17 development. When qualifying adlink 2026-03-17 development, customers place particular weight on qualified procurement and integration of rugged industrial GPU computer systems, because deployment performance matters more than peak specifications. Buyers of adlink 2026-03-17 development must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment. Source - 2026-03-12 Published
A defining feature of adlink 2026-03-12 development is the medical and robotics gpu platforms announcement; The manufacturer GTC demonstration connects GPU computing to medical-imaging and robotic deployments.. For adlink 2026-03-12 development, engineers balance qualified procurement and integration of rugged industrial GPU computer systems with lifecycle support and deployment reliability. Buyers of adlink 2026-03-12 development must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment. Source - 2026-03-05 Announced
ADLINK 2026-03-05 development is shaped by the edge ai platforms at embedded world announcement; Industrial embedded systems, MXM graphics and GPU servers were demonstrated for real deployment environments.. For adlink 2026-03-05 development, buyers evaluate qualified procurement and integration of rugged industrial GPU computer systems during qualification rather than in isolated benchmarks. In adlink 2026-03-05 development, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Report Title | Industrial GPU Computers Market |
| Study Period | 2021–2036 |
| Historical Period | 2021–2025 |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2027–2036 |
| Base Year Market Size | USD 4,413.0 million |
| Estimated Market Size | USD 4,832.5 million |
| Forecast Market Size | USD 10,943.4 million |
| CAGR (2027–2036) | 9.5% |
| Market Revenue Unit | USD million |
| Market Boundary | Commercial revenues attributable to rugged industrial GPU computer systems; downstream service revenue and unrelated systems are excluded. |
| By Type | Orbital Type · Wall-mounted Type |
| By Application | Rail Traffic · Medical · Military · Other |
| By Region | Global geographic analysis across five regions, with base-year revenue shares shown as estimates. North AmericaUnited States · Canada · Mexico EuropeGermany · France · United Kingdom · Netherlands Asia-PacificChina · Japan · South Korea · India South AmericaBrazil · Argentina · Chile Middle East & AfricaSaudi Arabia · United Arab Emirates · South Africa · Egypt |
| Key Companies Profiled | Adlinktech · Premio · Advanced · OnLogic · Industrial PC · Neousys Technology · Advantech · Assured Systems · Rugged Science · SINTRONES · C&T Solution |
| Customization Scope | Country-level procurement patterns, industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, equipment qualification, capacity assumptions and buyer-specific industry segmentation. |
Frequently Asked Questions
What is the industrial gpu computers market size and forecast?
The global industrial gpu computers market was valued at USD 4,413.0 million in 2026 and is projected to reach USD 10,943.4 million in 2036, expanding at a CAGR of 9.5% over 2027–2036. A defining feature of forecast demand is consolidation of visual inspection and industrial robotics inference into rugged edge workstations. For forecast demand, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. In forecast demand, risks tied to heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement shift the configurations that win volume and determine whether deployments expand beyond the initial site.
Which product type leads the industrial gpu computers market?
Wall-mounted Type leadership is shaped by an estimated ~58% of 2026 revenues and continuing demand from machine vision, rail monitoring, medical imaging, autonomous inspection and defence systems. For wall-mounted type leadership, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. For wall-mounted type leadership, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
What is the leading industrial gpu computers application?
Purchasing other demand depends on an estimated ~37% of 2026 application revenues. When selecting other demand, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. For other demand, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
Which region has the largest industrial gpu computers market?
Within regional market leader, Asia-Pacific represented an estimated ~40% in 2026 and electronics factories, machine builders and industrial computer manufacturers combine large production capacity with extensive vision inspection demand affects supplier qualification for regional market leader. When qualifying regional market leader, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. For regional market leader, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
Which region is expanding fastest for industrial gpu computers?
A defining feature of fastest regional growth is Asia-Pacific has modeled annual expansion near ~10.8% and electronics factories, machine builders and industrial computer manufacturers combine large production capacity with extensive vision inspection demand. For fastest regional growth, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. For fastest regional growth, challenges involving heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement remain adoption hurdles, affecting pricing, validation and repeat orders.
What determines product selection in industrial gpu computers?
Selection requirements is shaped by industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute are decisive when implementing industrial chassis integrating CPU host, graphics accelerator, SSD storage and field connectivity. For selection requirements, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. In the market for selection requirements, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
Which firms participate in the industrial gpu computers market?
Purchasing supplier structure depends on ADLINK Technology; Advantech; Neousys Technology; OnLogic represent a major part of the commercial supply environment. When selecting supplier structure, system architects compare industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute against long-term integration cost and readiness. In the market for supplier structure, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
What are the key constraints on industrial gpu computers growth?
Within principal restraints, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement add cost and schedule uncertainty affects supplier qualification for principal restraints. When qualifying principal restraints, customers place particular weight on industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute, because deployment performance matters more than peak specifications. In the market for principal restraints, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
How do manufacturing and supply affect industrial gpu computers?
A defining feature of manufacturing availability is systems design and integration concentrated in Taiwan and specialized manufacturing partners serving North America and Europe and the sourcing of industrial motherboards, CPUs, GPU modules, rugged enclosures, heat spreaders and industrial I/O. For manufacturing availability, engineers balance industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute with lifecycle support and deployment reliability. In the market for manufacturing availability, heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement can delay conversion of an engineering prototype into a purchased production system with assured support.
What does the industrial gpu computers study cover?
Report scope is shaped by the 2021–2036 study span covers 2026 market revenues across 2 type and 4 application categories with five geographic regions. For report scope, buyers evaluate industrial I/O, shock qualification, thermal design, lifecycle support and deployable GPU compute during qualification rather than in isolated benchmarks. Buyers of report scope must also account for heat dissipation, lifecycle mismatch, cybersecurity hardening and project-dependent procurement, which shapes design margins and lifetime costs after the first shipment.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF