Key Statistics
Key Takeaways
- Metering DCUs are the largest type because smart-metering networks need local aggregation between field meters and head-end systems.
- Smart metering is the primary application, while distribution automation and DER integration are broadening functionality beyond meter collection.
- Asia Pacific is used as the largest and fastest-growth region because China and India are deploying smart meters and grid digitalization at very large scale.
- Multi-protocol connectivity is becoming essential as utilities combine PLC, cellular, Ethernet and RF networks.
- Cybersecurity and remote management increasingly influence procurement because DCUs sit between thousands of field devices and utility IT systems.
Data Concentrator Units (DCUs) Market Overview
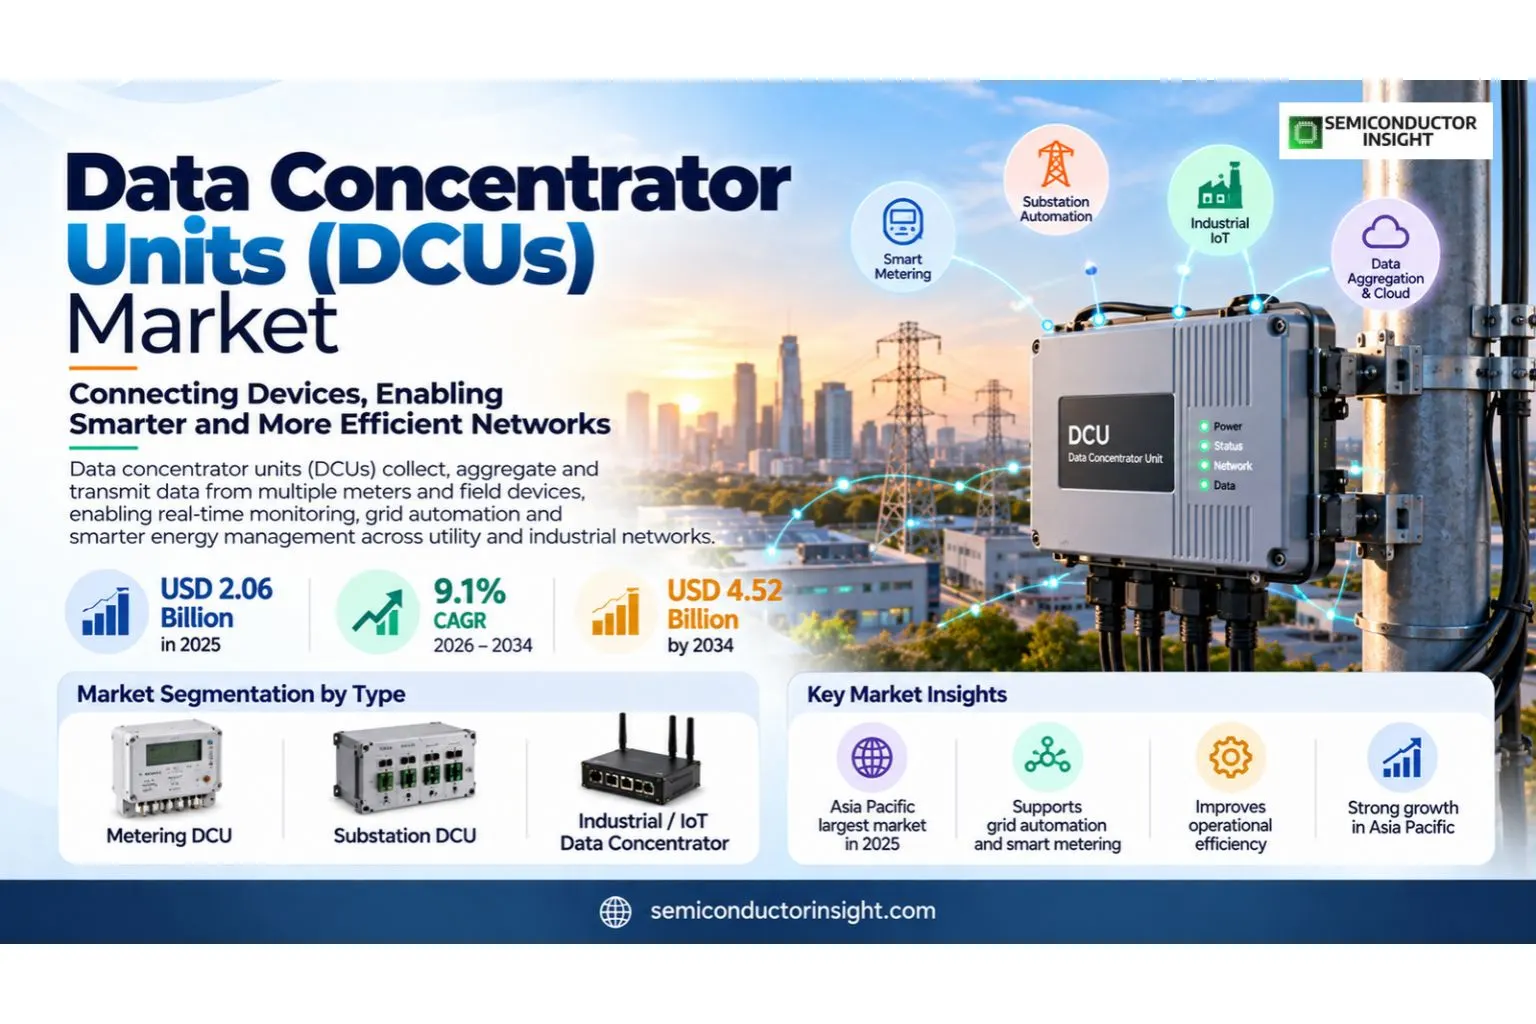
Data concentrator units DCUs market was valued at USD 2.06 billion in 2025 and is projected to reach USD 4.52 billion by 2034, growing at a CAGR of 9.1% over the 2026–2034 forecast period. Asia Pacific held the largest regional position in 2025, while Asia Pacific has the strongest growth profile.
The data concentrator units DCUs market data concentrator units aggregate data from smart meters, sensors or field devices, perform local processing and forward information to utility or industrial head-end systems. They reduce backhaul traffic and provide a control point for device management, firmware updates, time synchronization and network diagnostics. Commercial decisions in the Data Concentrator Units (DCUs) market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
The client URL reports a market value of USD 1.89 billion in 2024 and a forecast of USD 3.47 billion by 2032 at a 9.1% CAGR. Growth is linked to AMI rollouts, distribution automation, remote meter management and the need to connect large fleets of field devices securely.
ZIV’s current 4DCT data concentrator illustrates the modern feature set: PRIME PLC support, remote smart-meter management, Ethernet, DLMS/COSEM, TLS, SFTP and SNMP. This shows how the product has evolved from a simple data collector into a secure edge gateway for grid operations. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Segment Analysis: By Type
By type, the data concentrator units DCUs market is segmented into Metering DCU, Substation DCU, Industrial / IoT Data Concentrator. Each category has a distinct functional role and commercial position, so the analysis emphasizes use case, integration and competitive relevance rather than repeating a single market statistic across every row. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
| Type | Function | Market position |
|---|---|---|
| Metering DCU | Aggregates smart-meter data and manages field devices in AMI networks. | Largest installed base because smart metering is the core commercial application. |
| Substation DCU | Collects data from protection, metering and automation devices in substations. | Higher-value segment with more protocols, control and reliability requirements. |
| Industrial / IoT Data Concentrator | Aggregates sensors and controllers in industrial or infrastructure networks. | Broadening use as edge processing and protocol conversion become more important. |
Pricing by type
Metering DCUs are price-sensitive at scale because utilities deploy thousands of units, but secure multi-protocol devices can command higher value when they combine network supervision, firmware management and edge analytics. Substation units typically carry the highest ASP because of redundancy, ruggedness and protocol breadth. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Segment Analysis: By Application
By application, the market is segmented into Smart Metering, Distribution Automation, Industrial Automation, Microgrids & DER, Building / Infrastructure Monitoring. Application economics differ by qualification, lifecycle, reliability and system-level value, so each row below uses context specific to that application rather than mechanically repeating headline evidence. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
| Application | Demand characteristics |
|---|---|
| Smart Metering | Largest application connecting meter fleets to AMI head-end systems. |
| Distribution Automation | Combines field-device data and supports feeder or substation monitoring. |
| Industrial Automation | Aggregates PLC, sensor and process data across heterogeneous networks. |
| Microgrids & DER | Connects distributed generation, storage and load assets for local monitoring. |
| Building / Infrastructure Monitoring | Collects energy, environmental and equipment data across distributed sites. |
Regional Analysis
Asia Pacific is used as the largest and fastest-growth region because of large-scale smart-meter deployments, distribution modernization and domestic grid-equipment manufacturing in China, India, Japan and South Korea. Europe remains a mature AMI market with strong interoperability requirements. Commercial decisions in the Data Concentrator Units (DCUs) market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
How does regional demand differ across the data concentrator units DCUs market?
Regional demand differs according to smart-meter rollout stage, communication standards and utility regulation. Europe emphasizes standards-based interoperability, Asia Pacific emphasizes deployment scale, and North America has mature AMI networks with growing interest in edge intelligence and grid resilience. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia Pacific | Largest | Highest in market | Mass AMI deployment | Protocol interoperability and local service |
| Europe | Second | Moderate-high | Standards/interoperability led | DLMS/COSEM, PRIME and utility certification |
| North America | Third | Moderate | Grid modernization led | Cybersecurity and utility integration |
| South America | Emerging | High from smaller base | Smart-meter rollout led | Cost and telecom availability |
| Middle East & Africa | Emerging | High from smaller base | Utility modernization led | Project delivery and communications coverage |
Key Data Concentrator Units (DCUs) Manufacturers and Competitive Landscape
The competitive landscape combines utility automation specialists, meter vendors, smart-grid platform companies and industrial gateway suppliers. ZIV Automation is a notable DCU specialist, while larger metering and grid vendors compete through complete AMI platforms and utility relationships. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Competition is driven by protocol support, cybersecurity, meter scalability, remote firmware management, edge analytics and head-end integration. Utilities favor vendors able to guarantee long lifecycle support because AMI deployments operate for many years. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | ZIV Automation, Landis+Gyr, Itron and major AMI platform vendors | Large utility deployments, broad software integration and global support. |
| Tier 2 | Ami Tech India, Lekha and regional smart-grid suppliers | Cost-competitive solutions, local protocols and regional utility relationships. |
| Tier 3 | Industrial gateway and niche DCU suppliers | Protocol conversion, custom projects and specialized infrastructure applications. |
Key companies profiled
- ZIV Automation
- Landis+Gyr
- Itron
- Ami Tech India
- Lekha
- STMicroelectronics ecosystem partners
- regional AMI and gateway suppliers
Data Concentrator Units (DCUs) Production Capacity Analysis
DCU manufacturing uses embedded processors, communications modules, secure memory, industrial power supplies and rugged enclosures. Capacity is not usually constrained by leading-edge semiconductor supply; the greater challenge is utility qualification and software integration. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Large AMI rollouts require consistent field configuration, remote provisioning and service infrastructure. Vendors therefore scale not only hardware production but also firmware, device-management and commissioning resources. Commercial decisions in the Data Concentrator Units (DCUs) market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Regional assembly can be valuable where utilities impose local-content requirements or where installation support must be close to field operations. Long deployment cycles also favor suppliers with stable component sourcing. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Data Concentrator Units (DCUs) Market Dynamics: Drivers, Restraints and Opportunities
Growth is driven by smart-meter rollouts, distribution automation and the shift toward grid edge intelligence. Restraints include long utility procurement, cybersecurity requirements and protocol fragmentation. The strongest opportunity is multi-protocol DCUs that combine data aggregation with secure edge processing. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Industrial automation and machine-building investment | +1.3% | Asia Pacific, North America, Europe | Medium term (2–4 years) |
| Building energy codes mandating scheduled HVAC and lighting operation | +1.1% | Europe, North America, developed Asia Pacific | Medium term (2–4 years) |
| Mix shift to multifunction devices lifting average selling price | +0.9% | Global, distributor-led markets first | Short term (≤ 2 years) |
| Commercial HVAC retrofit and control panel rebuild cycle | +0.8% | North America, Europe | Short term (≤ 2 years) |
| Municipal water and wastewater infrastructure investment | +0.6% | Asia Pacific, Middle East and Africa, South America | Long term (≥ 4 years) |
| New panel-build demand from manufacturing relocation | +0.5% | India, Vietnam, Thailand, Mexico | Long term (≥ 4 years) |
| Smart-meter deployment | +1.8% | Asia Pacific, Europe, Middle East | Near term |
| Distribution automation | +1.2% | Global utilities | Medium term |
| Edge intelligence | +0.8% | North America, Europe, Asia Pacific | Medium term |
Industrial automation investment sustains baseline demand
AMI deployments create the largest direct demand because concentrators sit between meter networks and utility head-end systems. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
Building energy regulation drives HVAC and lighting demand
Distribution automation expands the role of the DCU beyond billing data into feeder monitoring, outage visibility and remote control support. Commercial decisions in the Data Concentrator Units (DCUs) market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Inventory consolidation favours multifunction devices
Edge processing can reduce upstream data traffic and enable faster local diagnostics, improving the value of more capable DCUs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| PLC substitution of discrete timing functions | −1.4% | Global, developed markets first | Long term (≥ 4 years) |
| Price competition from value-segment suppliers | −0.9% | Europe, North America, South America | Short term (≤ 2 years) |
| Networked lighting control absorbing discrete timing | −0.5% | Developed markets, new construction | Medium term (2–4 years) |
| VFD and soft-starter adoption reducing star-delta demand | −0.4% | Global, new installations | Long term (≥ 4 years) |
| Microcontroller supply disruption extending lead times | −0.2% | Global, programmable device tier only | Short term (≤ 2 years) |
| Long utility procurement | -0.7% | Global | Ongoing |
| Cybersecurity burden | -0.6% | Global | Ongoing |
| Protocol fragmentation | -0.5% | Regional | Medium term |
Substitution by programmable logic controllers
Utility tenders and field trials can take years, delaying revenue even after technical selection. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Data Concentrator Units (DCUs) market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Price competition in the commodity tier
DCUs are exposed to field networks and head-end systems, so secure boot, encrypted communications and credential management add engineering and certification burden. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Displacement by networked control in lighting
Different PLC, RF, cellular and application protocols make one universal product difficult without modular software and hardware architectures. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
MARKET OPPORTUNITIES
Communication-enabled devices
Multi-protocol DCUs can replace several gateways and simplify field networks, creating a premium segment around software flexibility. Commercial decisions in the Data Concentrator Units (DCUs) market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Water and wastewater infrastructure
Grid-edge analytics creates an opportunity to detect outages, power-quality issues and communication faults locally rather than forwarding every raw event. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Emerging-market panel building
Smart-meter replacement cycles can generate upgrade demand even in mature markets as utilities add stronger cybersecurity and newer communications standards. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Data Concentrator Units (DCUs) market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
Data Concentrator Units (DCUs) Supply Chain Analysis
Upstream. Embedded processors, communication chipsets, secure elements, industrial power supplies and enclosures form the hardware base. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers.
Manufacturing. Hardware assembly is combined with firmware loading, protocol configuration and environmental test. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment.
System integration. DCUs connect meters or field devices to head-end software using utility-specific protocols, certificates and network settings. Commercial decisions in the Data Concentrator Units (DCUs) market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone. Supplier selection also reflects manufacturing consistency, regional technical support, product availability and the ability to sustain qualified designs through multi-year customer programs.
Downstream. Electric, water and gas utilities deploy DCUs in substations, cabinets and field networks and maintain them over long operating lifecycles. Buyers increasingly compare total system impact, implementation complexity and long-term service requirements alongside component price, which creates room for technically differentiated suppliers. Adoption varies by customer architecture and replacement cycle, so demand is strongest where the technology solves a clear performance, reliability or integration problem.
Downstream. Panel builders and machine OEMs are the primary specifying customers, followed by electrical contractors working on building services and by facility maintenance teams handling replacement. The specification decision is usually made once, at panel design, and then repeats for the life of the design — which makes design-in position considerably more valuable than any individual transaction.
Recent Developments in the Data Concentrator Units (DCUs) Market
Developments tracked through September 2026. Items are selected for direct relevance to product technology, deployment or standards. That market structure favors suppliers able to combine product performance with stable supply, application engineering and documented quality across the intended operating environment. Commercial decisions in the Data Concentrator Units (DCUs) market therefore depend on system integration, qualification effort, reliability, lifecycle support and measurable operating value rather than on one specification alone.
- 2026 Current
ZIV 4DCT data concentrator ZIV’s current 4DCT combines PRIME PLC, smart-meter management, Ethernet, DLMS/COSEM, TLS, SFTP and SNMP functions. Source - 2026 Current
AMI platform integration ZIV positions DCUs and gateways as part of a standards-based metering and AMI portfolio. Source - 2026 Current
Distribution automation convergence Modern data concentrators increasingly overlap with gateway, monitoring and substation-controller functions. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2021–2025 |
| Market Size 2025 | USD 2.06 billion |
| Market Size 2034 | USD 4.52 billion |
| Growth Rate | CAGR of 9.1% from 2026–2034 |
| Unit | Value (USD Million) |
| Segmentation | By Type, By Application, By Communication, By End User, and By Region |
| By Type | Metering DCU · Substation DCU · Industrial / IoT Data Concentrator |
| By Application | Smart Metering · Distribution Automation · Industrial Automation · Microgrids & DER · Building / Infrastructure Monitoring |
| By End User | Electric Utilities · Water/Gas Utilities · Industrial Facilities · Infrastructure Operators |
| By Communication | PLC · RF Mesh · Cellular / Ethernet · Multi-Protocol |
| By Region | Each region analysed by Type, Application and Country North AmericaU.S., Canada, Mexico EuropeGermany, France, U.K., Italy, Russia, Nordic Countries, Benelux AsiaChina, Japan, South Korea, India, Southeast Asia South AmericaBrazil, Argentina, Rest of South America Middle East & AfricaTurkey, Israel, Saudi Arabia, UAE, Rest of MEA |
| Key Companies Profiled | ZIV Automation, Landis+Gyr, Itron, Ami Tech India, Lekha, STMicroelectronics ecosystem partners, regional AMI and gateway suppliers |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the current size of the Data Concentrator Units market?
The market is valued at USD 2.06 billion in 2025 and is projected to reach USD 4.52 billion by 2034, expanding at a 9.1% CAGR during 2026–2034.
Which companies lead the DCU market?
The market includes ZIV Automation, Landis+Gyr, Itron, Ami Tech India, Lekha and other AMI or utility-gateway suppliers.
What is a data concentrator unit?
A DCU aggregates data from smart meters or field devices, performs local processing and forwards information to utility or industrial head-end systems.
What are the main types?
Metering DCUs, substation DCUs and industrial or IoT data concentrators are the main categories.
What are the key applications?
Smart metering, distribution automation, industrial automation, microgrids and infrastructure monitoring are the principal applications.
Which region leads the market?
Asia Pacific is used as the largest and fastest-growth region because of large-scale smart-meter and grid-digitalization programs.
What drives market growth?
Smart-meter deployment, distribution automation and growing grid-edge processing requirements are the main growth drivers.
What are the main challenges?
Long utility procurement, cybersecurity requirements, protocol fragmentation and multi-year lifecycle support are the principal challenges.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...