
Key Statistics
Key Takeaways
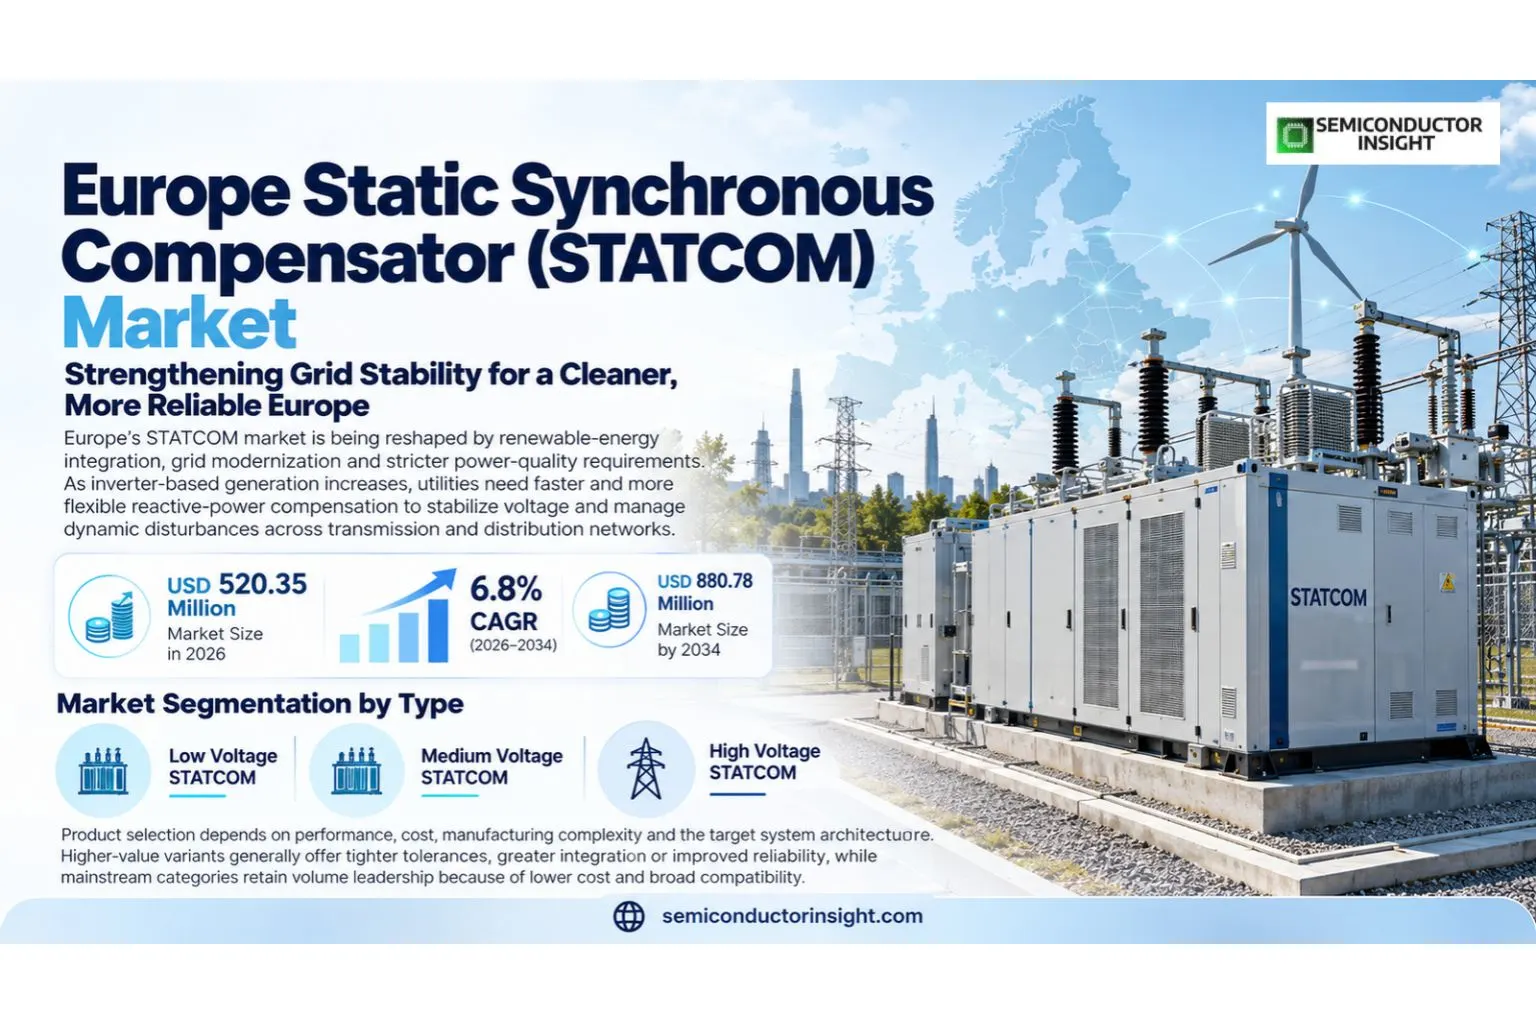
- Market size: The market is valued at USD 487.22 million in 2025 and is projected to reach USD 880.78 million by 2034, representing a 6.8% CAGR during 2026–2034.
- Low Voltage STATCOM is a leading segment, reflecting established use across major applications.
- Europe leads the market, while Europe provides the strongest growth profile.
- Renewable Integration is a major application, supported by rising performance and reliability requirements.
- modular converter architectures, advanced digital controls and higher-efficiency grid-support systems is becoming a central competitive differentiator as customers seek higher performance and lower system-level cost.
Europe Static Synchronous Compensator (STATCOM) Market Overview
Europe static synchronous compensator STATCOM market is valued at USD 487.22 million in 2025 and is projected to reach USD 880.78 million by 2034, expanding at a 6.8% CAGR during 2026–2034. The 2026 market level is USD 520.35 million. Europe’s STATCOM market is being reshaped by renewable-energy integration, grid modernization and stricter power-quality requirements. As inverter-based generation increases, utilities need faster and more flexible reactive-power compensation to stabilize voltage and manage dynamic disturbances across transmission and distribution networks.
Demand is strongest where renewable penetration, weak-grid conditions or rapidly changing industrial loads create voltage-control challenges. STATCOMs provide sub-cycle reactive-power support, making them attractive for wind and solar interconnections, steel and mining loads, data centers and high-capacity transport infrastructure. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Technology competition is shifting toward modular converter architectures, digital controls and higher-efficiency semiconductor platforms. Vendors that combine power electronics, grid modeling, control software and field-service capability are better positioned for complex utility tenders than suppliers competing on converter hardware alone. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Segment Analysis: By Type
By type, the market is segmented into Low Voltage STATCOM, Medium Voltage STATCOM, High Voltage STATCOM. Product selection depends on performance, cost, manufacturing complexity and the target system architecture. Higher-value variants generally offer tighter tolerances, greater integration or improved reliability, while mainstream categories retain volume leadership because of lower cost and broad compatibility.
| Type | Commercial role |
|---|---|
| Low Voltage STATCOM | Low Voltage STATCOM addresses a distinct requirement set within the Europe Static Synchronous Compensator (STATCOM) market, with purchasing decisions shaped by performance, qualification, integration and cost. |
| Medium Voltage STATCOM | Medium Voltage STATCOM addresses a distinct requirement set within the Europe Static Synchronous Compensator (STATCOM) market, with purchasing decisions shaped by performance, qualification, integration and cost. |
| High Voltage STATCOM | High Voltage STATCOM addresses a distinct requirement set within the Europe Static Synchronous Compensator (STATCOM) market, with purchasing decisions shaped by performance, qualification, integration and cost. |
Additional Segmentation: By Technology
Technology segmentation highlights important technical and commercial differences inside the Europe Static Synchronous Compensator (STATCOM) market. These categories affect pricing, qualification, process requirements and customer fit, making them useful for evaluating where value growth differs from simple unit growth. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Technology | Demand characteristics |
|---|---|
| Voltage Source Converter | Mainstream architecture for dynamic reactive-power compensation and voltage control. |
| Modular Multilevel Converter | Scalable high-voltage topology for transmission and large grid projects. |
| Hybrid STATCOM | Combines converter and passive elements to optimize cost and dynamic response. |
Segment Analysis: By Application
By application, the market covers Renewable Integration, Industrial Power Quality, Transmission & Distribution, Data Centers, Rail & Infrastructure. Demand varies by reliability, performance, budget and product lifecycle. Premium applications usually require stricter qualification and long-term supply support, while higher-volume applications place more emphasis on cost, manufacturing scale and rapid technology migration. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Application | Demand characteristics |
|---|---|
| Renewable Integration | Renewable Integration is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Industrial Power Quality | Industrial Power Quality is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Transmission & Distribution | Transmission & Distribution is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Data Centers | Data Centers is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Rail & Infrastructure | Rail & Infrastructure is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
Additional Segmentation: By End User
End User segmentation clarifies how system architecture and customer requirements reshape product selection. Growth is strongest where the technology delivers a clear performance, cost, reliability or integration advantage relative to incumbent solutions. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| End User | Commercial role |
|---|---|
| Utilities | Transmission and distribution voltage support and grid-stability projects. |
| Renewable Energy Developers | Grid-code compliance and reactive-power support for wind and solar. |
| Industrial Facilities | Power-quality correction for sensitive and high-load manufacturing. |
| Infrastructure Operators | Rail, data-center and critical infrastructure power stabilization. |
Regional Analysis
Europe is the market by definition, with the strongest activity across Germany, the United Kingdom, France, Spain, Italy and the Nordic countries. Renewable integration, cross-border transmission upgrades and industrial electrification are the main sources of project demand. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Why does regional demand differ across the Europe Static Synchronous Compensator (STATCOM) market?
Country-level demand differs according to renewable penetration, grid topology, interconnection requirements and industrial load patterns. Germany and the UK combine high renewable shares with major grid reinforcement programs, while Spain and Italy benefit from solar and wind integration needs and large transmission networks. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
How does Asia Pacific participate in the Europe Static Synchronous Compensator (STATCOM) market?
Asia Pacific demand is anchored by manufacturing scale, electronics production and growing investment in advanced infrastructure. China, Japan, South Korea, Taiwan and India contribute different mixes of production, end-market demand and technical capability, making the region central to both volume growth and supply-chain development. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
How does North America participate in the Europe Static Synchronous Compensator (STATCOM) market?
North America remains a high-value market with strong technology development, enterprise spending and specialized industrial demand. The United States is the principal contributor, supported by leading technology companies, research institutions and high-value end markets that adopt premium solutions early. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
How does Europe participate in the Europe Static Synchronous Compensator (STATCOM) market?
Europe combines advanced manufacturing, healthcare, aerospace, automotive and research demand. Germany, France, the United Kingdom, Italy and other markets emphasize reliability, energy efficiency and regulatory compliance, supporting demand for technically differentiated products with strong lifecycle support. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
How does South America participate in the Europe Static Synchronous Compensator (STATCOM) market?
South America is a smaller but developing market led by Brazil and selected industrial economies. Demand is concentrated in infrastructure, healthcare, electronics, research and industrial modernization, with import dependence making distributor support, service coverage and pricing important commercial factors. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
How does Middle East & Africa participate in the Europe Static Synchronous Compensator (STATCOM) market?
Middle East & Africa remains an emerging market where demand is concentrated in infrastructure, healthcare, energy, defense and research projects. Gulf countries account for much of the premium investment, while wider adoption depends on local technical capability, procurement cycles and access to qualified suppliers. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Competitive Landscape
The competitive landscape includes Hitachi Energy, Siemens Energy, GE Vernova, Mitsubishi Electric, Schneider Electric, Ingeteam, AMSC and regional grid-solution integrators. Market position is shaped by technical performance, qualification depth, customer support, manufacturing scale and the ability to support product transitions without disrupting customer operations. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Competition is increasingly centered on modular converter architectures, advanced digital controls and higher-efficiency grid-support systems. Larger suppliers benefit from global engineering resources and purchasing scale, while specialized vendors can defend attractive niches through process expertise, customization and faster technical support. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Competitive dimension | What matters |
|---|---|
| Technology | Performance, reliability and roadmap credibility. |
| Qualification | Customer validation, compliance and field history. |
| Supply | Capacity, lead time and regional resilience. |
| Commercial support | Application engineering, service and lifecycle support. |
Production Capacity Analysis
Capacity strategy in the Europe Static Synchronous Compensator (STATCOM) market is closely linked to demand visibility, qualification cycles and customer concentration. Suppliers add capacity carefully because advanced production often requires specialized equipment, process know-how and extended validation before new lines can serve demanding applications. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Regional capacity decisions increasingly balance cost with resilience. Customers are asking suppliers to diversify critical steps, maintain qualified backup capacity and support shorter lead times. That trend favors manufacturers able to combine scale with consistent process control and regional technical support. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Dynamics
The Europe Static Synchronous Compensator (STATCOM) market is shaped by simultaneous changes in end-market demand, product architecture, manufacturing economics and qualification requirements. Technology improvements create new use cases, but commercialization depends on whether performance gains translate into measurable system value. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Supply-chain conditions also influence purchasing behavior. Customers increasingly evaluate continuity, regional sourcing and lifecycle support alongside unit price. This shifts competition toward suppliers that can deliver stable quality and technical service through multiple product generations. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Drivers
Growth is driven by renewable-energy integration, transmission modernization, industrial electrification and rising sensitivity to voltage disturbances. STATCOMs are particularly valuable where grid-code compliance requires fast reactive-power support and where conventional mechanical compensation cannot respond quickly enough. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Driver | CAGR impact |
|---|---|
| Technology upgrade cycle | +1.8 percentage points |
| End-market expansion | +1.3 percentage points |
| Higher content per system | +0.9 percentage points |
Market Restraints
High capital cost, project-specific engineering and long utility procurement cycles restrain faster adoption. Grid connection studies, harmonic design and control coordination can add significant engineering complexity, while cheaper passive compensation may remain adequate for less dynamic applications. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Restraint | CAGR impact |
|---|---|
| Qualification and replacement cost | -0.8 percentage points |
| Price pressure | -0.6 percentage points |
| Supply or integration complexity | -0.5 percentage points |
Market Opportunities
Opportunities are strongest in offshore wind connections, weak-grid renewable zones, data-center clusters, rail electrification and aging transmission networks. Compact modular STATCOM systems and digital control platforms can reduce deployment time and improve lifecycle economics. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Opportunity | Commercial significance |
|---|---|
| modular converter architectures, advanced digital controls and higher-efficiency grid-support systems | Supports premium product mix and new design wins. |
| Regional capacity | Improves lead times and customer resilience. |
| Application engineering | Raises switching costs and deepens customer relationships. |
Supply Chain Analysis
The Europe Static Synchronous Compensator (STATCOM) supply chain spans upstream materials and components, specialized manufacturing, qualification and integration, distribution or direct sales, and end-use deployment. Value is not distributed evenly: the highest margins generally accrue where process know-how, IP, qualification or application engineering create defensible differentiation. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Stage | Role |
|---|---|
| Upstream inputs | Materials, components, software or specialized process equipment. |
| Manufacturing | Core fabrication, assembly and process control. |
| Qualification & integration | Validation, reliability testing and customer-specific adaptation. |
| End-market deployment | System integration, service and lifecycle support. |
Supply continuity has become strategically important because qualified alternatives may require lengthy validation. Buyers therefore monitor second-source readiness, geographic concentration and supplier financial stability, especially where a single component can delay a high-value system. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Recent Developments in the Europe Static Synchronous Compensator (STATCOM) Market
Report Scope & Segmentation
This analysis covers the Europe Static Synchronous Compensator (STATCOM) market from a 2025 base year through the 2026–2034 forecast period. It evaluates demand by product type, application and two additional segmentation axes, with regional coverage spanning Asia Pacific, North America, Europe, South America, and the Middle East & Africa. Commercial decisions in the Europe Static Synchronous Compensator (STATCOM) market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Scope item | Coverage |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| By Type | Low Voltage STATCOM, Medium Voltage STATCOM, High Voltage STATCOM |
| By Application | Renewable Integration, Industrial Power Quality, Transmission & Distribution, Data Centers, Rail & Infrastructure |
| By Technology | Voltage Source Converter, Modular Multilevel Converter, Hybrid STATCOM |
| By End User | Utilities, Renewable Energy Developers, Industrial Facilities, Infrastructure Operators |
| Key participants | Hitachi Energy, Siemens Energy, GE Vernova, Mitsubishi Electric, Schneider Electric, Ingeteam, AMSC and regional grid-solution integrators |
Frequently Asked Questions
What is the Europe Static Synchronous Compensator (STATCOM) market size in 2025?
The market is valued at USD 487.22 million in 2025.
What is the market forecast for 2034?
The market is projected to reach USD 880.78 million by 2034, with a 6.8% CAGR during 2026–2034.
Which region leads the market?
Europe leads current market value, while Europe has the strongest growth profile.
Which type is most important?
Low Voltage STATCOM is a leading category, although mix varies by application and performance requirement.
Which applications matter most?
Renewable Integration is a major demand segment, alongside Industrial Power Quality, Transmission & Distribution.
What technology trend matters most?
modular converter architectures, advanced digital controls and higher-efficiency grid-support systems is a central technology and commercialization trend.
Who are the major suppliers?
Major participants include Hitachi Energy, Siemens Energy, GE Vernova, Mitsubishi Electric, Schneider Electric, Ingeteam, AMSC and regional grid-solution integrators.
What drives market growth?
Growth is driven by renewable-energy integration, transmission modernization, industrial electrification and rising sensitivity to voltage disturbances. STATCOMs are particularly valuable where grid-code compliance requi
What limits growth?
High capital cost, project-specific engineering and long utility procurement cycles restrain faster adoption. Grid connection studies, harmonic design and control coordination can add significant engineering complexity,
What will shape the market through 2034?
Technology roadmaps, qualification, supply continuity and modular converter architectures, advanced digital controls and higher-efficiency grid-support systems will shape competitive outcomes.
Research Sources & Evidence Base
View selected external research sources
- Hitachi Energy — FACTS Solutions: Current STATCOM and grid-stability solution context. Open source
- Siemens Energy — FACTS: Current dynamic reactive-power and grid-support context. Open source
- ENTSO-E — European Transmission System Operators: European grid and renewable-integration context. Open source
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF


