Key Statistics
Key Takeaways
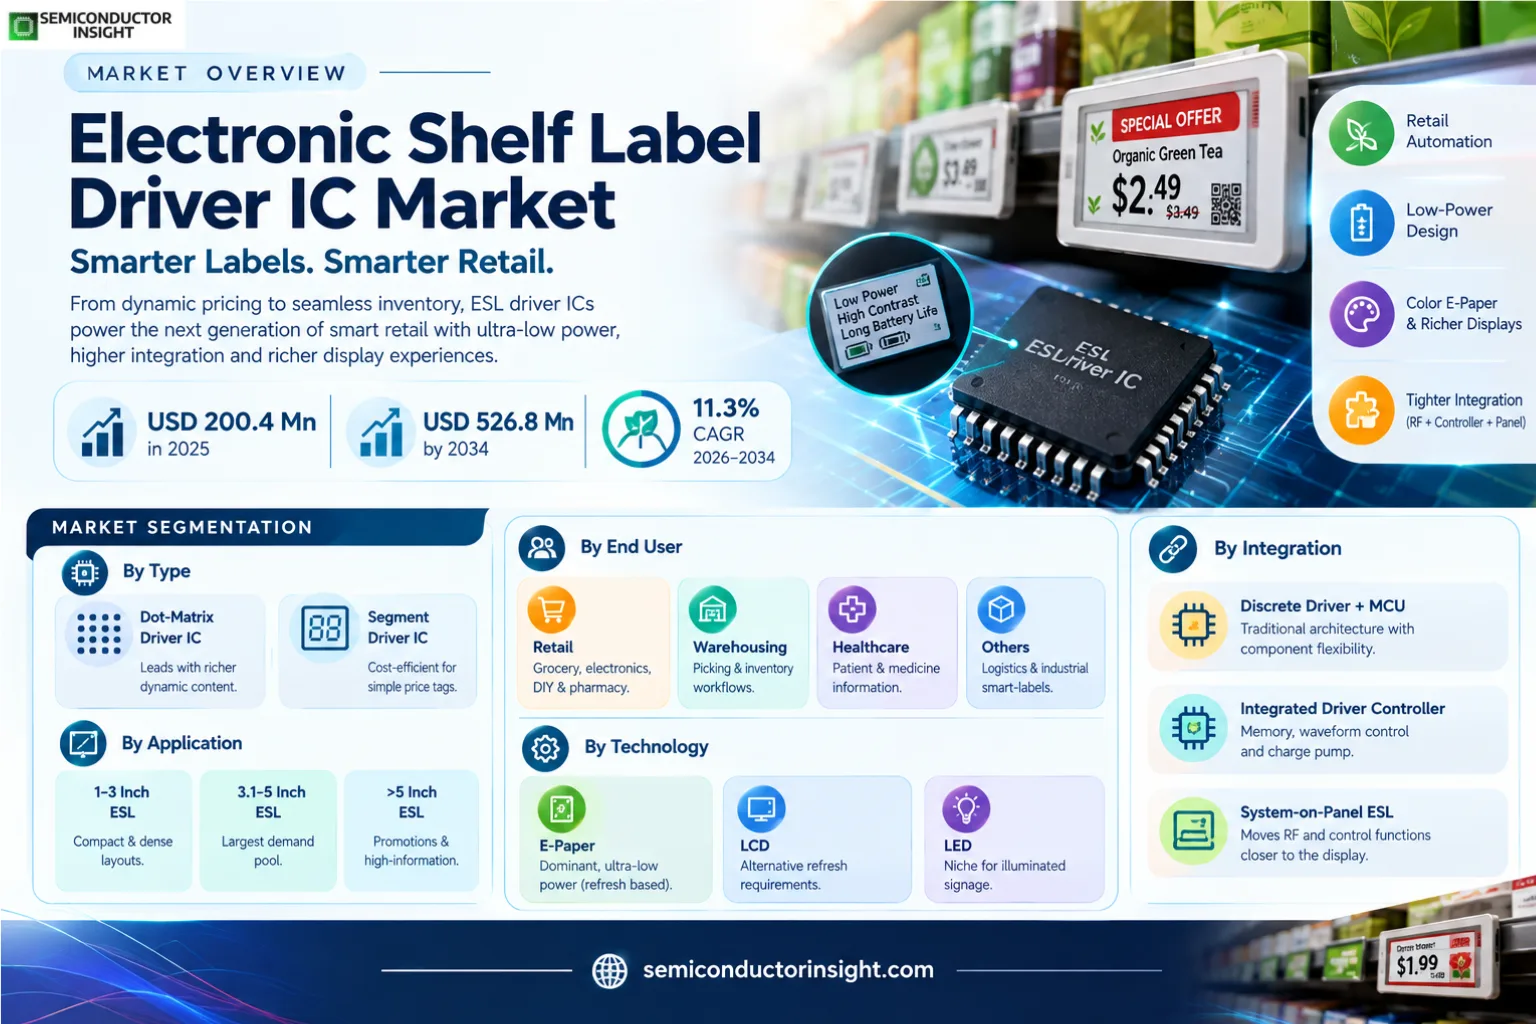
- Market size and growth: the market is valued at USD 200.4 million in 2025 and is projected to reach USD 526.8 million by 2034, with a 11.3% CAGR over 2026–2034.
- Dot-Matrix Driver IC leads by type because graphic e-paper labels can show prices, QR codes, inventory cues and promotional content beyond fixed numeric segments.
- 3.1–5 Inch ESL is the principal application because mid-sized labels balance readability, information density and shelf-space efficiency for mainstream retail.
- Asia Pacific is the largest regional market, while Asia Pacific has the strongest incremental growth profile.
- Primary driver: retailers are automating price updates and shelf-edge information to reduce labor cost and improve pricing accuracy
- Principal restraint: large storewide deployments require substantial upfront investment and extremely low-cost, long-life electronics
Market Overview
The electronic shelf label driver IC market was valued at USD 200.4 million in 2025 and is projected to reach USD 526.8 million by 2034, expanding at a 11.3% CAGR over 2026–2034. Asia Pacific leads in 2025, while market structure is being reshaped by retail automation, color e-paper, lower-power display driving and tighter integration of RF, controller and panel functions..
ESL driver ICs generate the high-voltage waveforms and pixel or segment control needed to update electronic paper and other bistable retail displays. These devices are optimized for extremely low standby power because e-paper consumes energy mainly when content changes. Modern drivers increasingly integrate charge pumps, waveform control, memory and timing so label manufacturers can reduce component count and extend battery life.
Solomon Systech’s current bistable display drivers illustrate the architecture. Its segment devices integrate high-voltage DC/DC conversion and waveform control for electrophoretic and cholesteric displays, while dot-matrix devices combine controller and driver functions for active-matrix e-paper. Such integration matters because large retailers can deploy tens of thousands of labels per store and require consistent battery life across every unit.
Retail adoption continues to deepen. E Ink states that ESLs allow wireless price updates, reduce manual shelf-label work and can operate for years on batteries. In 2025 E Ink and Realtek introduced a second-generation system-on-panel reference design that embeds an RF IC directly on glass, reducing component area and illustrating the move toward tighter electronics-panel integration.
Segment Analysis: By Type
By type, the market is segmented into Dot-Matrix Driver IC, Segment Driver IC. Dot-Matrix Driver IC holds the leading position.
| Type | Role | Commercial position |
|---|---|---|
| Dot-Matrix Driver IC | Controls graphic pixel arrays for text, images and promotional content. | Leading type as labels move toward richer dynamic content. |
| Segment Driver IC | Drives fixed numeric or icon segments. | Cost-efficient for simple price tags and constrained displays. |
Commercial implications by type
Dot-matrix devices create more software and hardware value because they manage larger pixel arrays, waveform tables and memory. Segment drivers remain attractive where retailers only need basic price information. The market therefore spans low-cost fixed-function ICs and more integrated controllers that enable color, graphics and faster updates.
Segment Analysis: By Application
By application, the market includes 1–3 Inch ESL, 3.1–5 Inch ESL, >5 Inch ESL. 3.1–5 Inch ESL is the largest demand pool.
| Application | Demand characteristics |
|---|---|
| 1–3 Inch ESL | Compact labels fit small packages, pharmacy shelves and dense layouts. |
| 3.1–5 Inch ESL | Largest application because the size balances readability and information density. |
| >5 Inch ESL | Larger displays support promotions, signage and high-information categories. |
By End User
| End User | Commercial relevance |
|---|---|
| Retail | Largest end-user market across grocery, electronics, DIY and pharmacy. |
| Warehousing | Dynamic labels support picking and inventory workflows. |
| Healthcare | Low-power labels can display patient or medicine information. |
| Others | Logistics and industrial smart-label uses broaden demand. |
By Technology
| Technology | Commercial relevance |
|---|---|
| E-Paper | Dominant technology because it uses power mainly during refresh. |
| LCD | Used where alternative refresh characteristics are required. |
| LED | Niche for illuminated shelf and signage applications. |
By Integration
| Integration | Commercial relevance |
|---|---|
| Discrete Driver + MCU | Traditional architecture with component flexibility. |
| Integrated Driver Controller | Combines memory, waveform control and charge pump. |
| System-on-Panel ESL | Moves RF and control functions closer to the display. |
Regional Analysis
Asia Pacific leads the market because the source analysis identifies Asia Pacific as the largest consumer and production region, supported by display-driver suppliers and fast retail digitization. Asia Pacific has the strongest growth profile through smart-store investment, e-paper manufacturing and local display-driver supply.
How does regional demand differ across this market?
Asia Pacific leads both production and demand, Europe has deep grocery and discount-retail adoption, and North America is accelerating as large chains digitize shelf-edge operations. South America and the Middle East & Africa remain smaller but offer growth as modern retail expands. Driver-IC demand follows installed ESL volumes, so retailer rollout schedules directly affect semiconductor shipments.
| Region | Position | Growth outlook | Demand profile | Supplier selection |
|---|---|---|---|---|
| North America | Second | Strong | Retail digitalization and electronic shelf labels | Technology, support, lifecycle |
| Europe | Third | Moderate | Retail digitalization and electronic shelf labels | Compliance, efficiency, reliability |
| Asia Pacific | Largest | Fastest | Retail digitalization and electronic shelf labels | Cost, scale, local supply |
| South America | Smaller | Moderate | Retail digitalization and electronic shelf labels | Cost and availability |
| Middle East & Africa | Emerging | Moderate | Retail digitalization and electronic shelf labels | Ruggedness, service, availability |
Competitive Landscape
Competition is concentrated among display-driver specialists and adjacent semiconductor suppliers with low-power analog, high-voltage waveform and e-paper expertise.
UltraChip, Solomon Systech, Jadard, DAVICOM and other Asian IC vendors compete on power, channel count, waveform flexibility and cost. Dot-matrix products capture more value as shelf-edge graphics become richer.
Solomon Systech’s mass-production bistable display portfolio integrates charge pumps and waveform control for electrophoretic displays, reducing external components for ESL manufacturers.
System integration is moving closer to the panel. E Ink’s collaboration with Realtek embeds an RF IC directly on glass, showing that future designs may be judged on mechanical footprint and assembly simplification as much as electrical performance.
| Competitive tier | Representative participants | Competitive focus |
|---|---|---|
| Driver IC specialists | UltraChip, Solomon Systech, Jadard | E-paper waveform control and low power |
| Connectivity / controller suppliers | Realtek, DAVICOM, ITE | Wireless and controller integration |
| Display ecosystem leaders | E Ink and module partners | E-paper materials and panel integration |
Companies Profiled
UltraChip, Jadard Technology, Solomon Systech, DAVICOM Semiconductor, ITE Tech, Integrated Solutions Technology, Realtek, E Ink ecosystem partners
Production Capacity Analysis
Driver-IC capacity relies mainly on mature mixed-signal foundry nodes, high-voltage analog design, packaging and high-volume test.
The main semiconductor challenge is consistent low-power and high-voltage performance at very low die cost. Mature processes are economical, but large ESL rollouts can create sharp demand swings for specialized analog capacity.
Module capacity depends on the full display stack. Driver ICs, e-paper films, TFT backplanes, batteries, antennas and housings must be available together. A bottleneck in any one component can delay a retailer’s rollout even when driver wafers are available.
Market Dynamics
The market is expanding as ESLs move from basic digital price tags toward richer shelf-edge information platforms.
The driver IC is a small portion of tag cost but has an outsized effect on battery life, refresh behavior and display quality. As retailers demand color, larger screens and promotional graphics, driver sophistication rises, creating room for higher-value controllers while unit prices remain under pressure.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Retail automation | High | Wireless updates reduce manual label changes. |
| E-paper battery life | High | Bistable displays allow multi-year operation. |
| Dynamic pricing | High | Retailers can update thousands of labels rapidly. |
| Color and graphics | Medium | Richer displays require more capable drivers. |
Retail automation
Wireless updates reduce manual label changes.
E-paper battery life
Bistable displays allow multi-year operation.
Dynamic pricing
Retailers can update thousands of labels rapidly.
Color and graphics
Richer displays require more capable drivers.
Market Restraints
Restraints Impact Analysis
| Restraint | Impact | Commercial mechanism |
|---|---|---|
| Upfront deployment cost | High | Large stores require thousands of labels plus network infrastructure. |
| IC price pressure | High | High-volume projects demand very low component cost. |
| Mature-node capacity | Medium | Specialized analog capacity can tighten. |
| Environmental requirements | Medium | Freezer and hot environments require wider margins. |
Upfront deployment cost
Large stores require thousands of labels plus network infrastructure.
IC price pressure
High-volume projects demand very low component cost.
Mature-node capacity
Specialized analog capacity can tighten.
Environmental requirements
Freezer and hot environments require wider margins.
Market Opportunities
System-on-panel integration
Embedding RF and control closer to the panel reduces size and assembly complexity.
Color ESLs
Promotional colors increase driver complexity and value.
Cold-chain retail
Freezer-capable e-paper expands addressable locations.
Warehouse labels
The same architecture can support logistics workflows.
Supply Chain Analysis
Mixed-signal and high-voltage CMOS
Waveform engine, memory, charge pump
E-paper, RF, battery, antenna
Gateways, cloud, POS integration
Foundry
Mature process economics support high-voltage analog at low cost.
Driver IC
Waveform quality and power design determine refresh and battery life.
ESL module
Battery, radio and display are optimized as one system.
Retail system
Labels create value when synchronized with pricing and inventory software.
Recent Developments
2025 — E Ink and Realtek unveil second-generation system-on-panel ESL
The design embeds an RF IC directly on glass and reduces TFT and FPC dimensions. Source
2026 — Solomon Systech maintains mass-production bistable drivers
Current drivers integrate charge pumps and waveform control for e-paper applications. Source
2026 — E Ink continues broad ESL platform support
Current ESL technology supports mono and multi-color retail labels with multi-year battery operation. Source
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | Electronic Shelf Label (ESL) Driver IC |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 200.4 million |
| 2026 Estimated Size | USD 223.1 million |
| 2034 Forecast Size | USD 526.8 million |
| CAGR | 11.3% (2026–2034) |
| By Type | Dot-Matrix Driver IC, Segment Driver IC |
| By Application | 1–3 Inch ESL, 3.1–5 Inch ESL, >5 Inch ESL |
| By End User | Retail, Warehousing, Healthcare, Others |
| By Technology | E-Paper, LCD, LED |
| By Integration | Discrete Driver + MCU, Integrated Driver Controller, System-on-Panel ESL |
| Regions | North America, Europe, Asia Pacific, South America, Middle East & Africa |
| Companies Profiled | UltraChip, Jadard Technology, Solomon Systech, DAVICOM Semiconductor, ITE Tech, Integrated Solutions Technology, Realtek, E Ink ecosystem partners |
Frequently Asked Questions
What is the electronic shelf label driver IC market size in 2025?
The market is valued at USD 200.4 million in 2025.
What is the projected market size by 2034?
The market is projected to reach USD 526.8 million by 2034.
What is the CAGR from 2026 to 2034?
The market is expected to expand at a 11.3% CAGR.
Which region leads the market?
Asia Pacific is the largest regional market in 2025.
Which type leads the market?
Dot-Matrix Driver IC is the leading type.
Which application leads demand?
3.1–5 Inch ESL is the leading application.
What is the primary growth driver?
retailers are automating price updates and shelf-edge information to reduce labor cost and improve pricing accuracy.
What is the principal restraint?
large storewide deployments require substantial upfront investment and extremely low-cost, long-life electronics.
Where are the strongest opportunities?
color e-paper, system-on-panel integration, freezer-capable labels and omnichannel retail synchronization.
Which companies are active in the market?
UltraChip, Jadard Technology, Solomon Systech, DAVICOM Semiconductor, ITE Tech, Integrated Solutions Technology, Realtek, E Ink ecosystem partners.
Research Sources & Evidence Base
View primary and official evidence used in this overview
- E Ink: Electronic Shelf Label applications — ESL operating model and retail benefits.
- E Ink: Second-generation System-on-Panel ESL — 2025 integration development.
- Solomon Systech: Bistable display driver ICs — Mass-production ESL-capable driver architecture.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF