Key Statistics
Key Takeaways
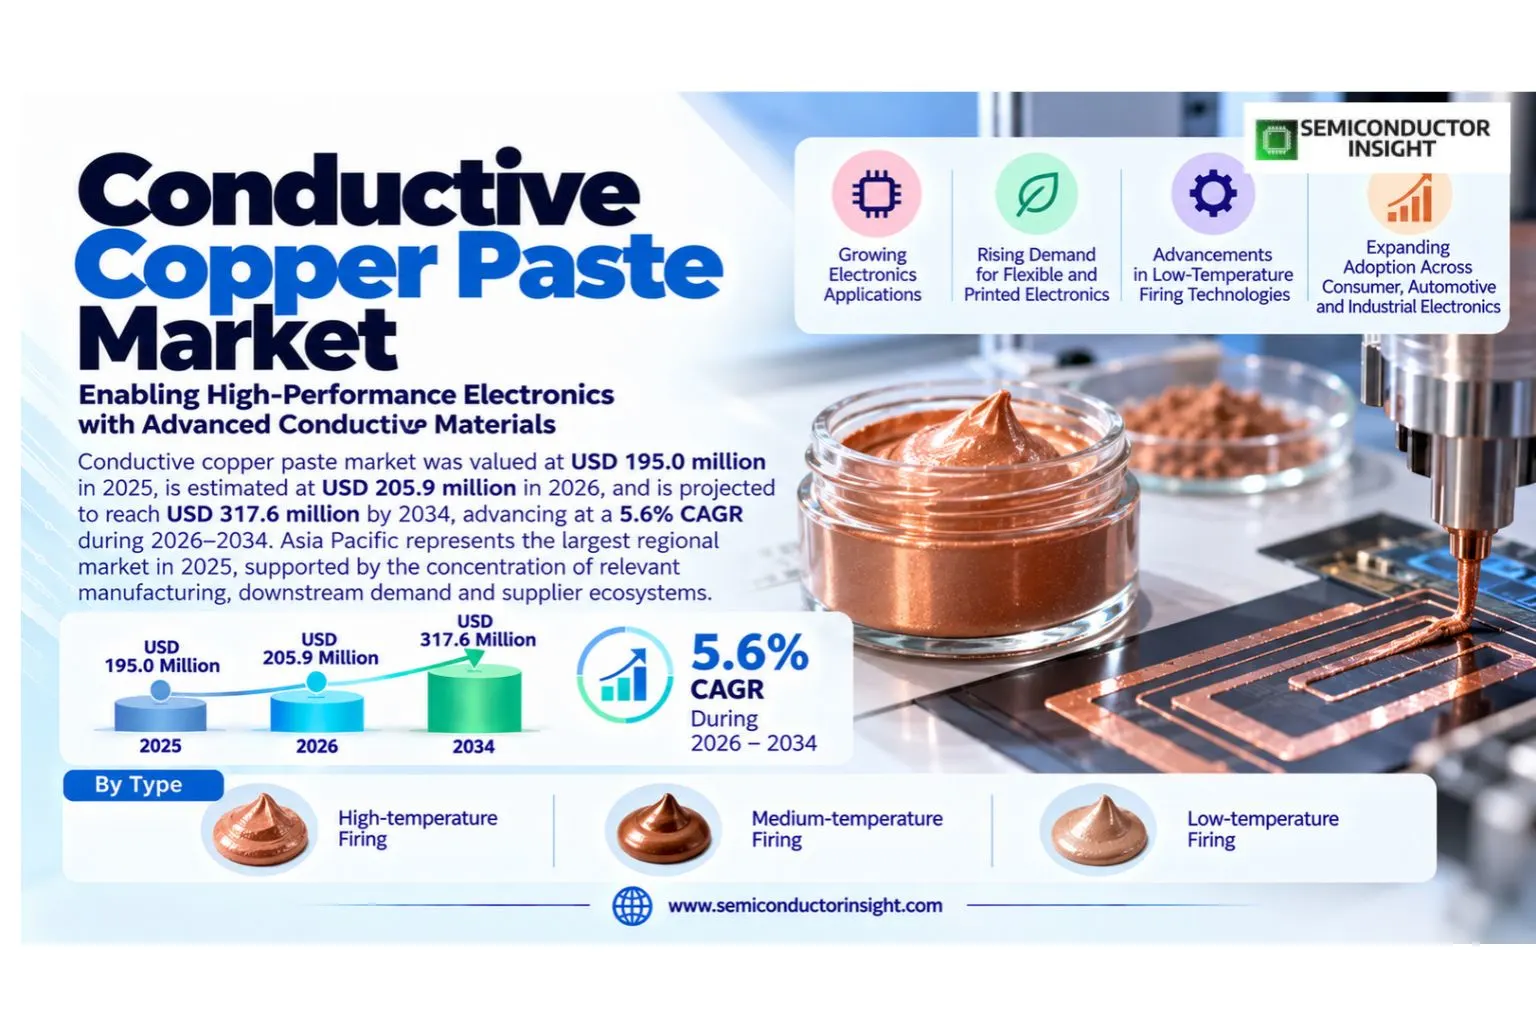
- Conductive copper paste market was valued at USD 195.0 million in 2025 and is projected to reach USD 317.6 million by 2034, representing a 5.6% CAGR over 2026–2034.
- Low-temperature firing formulations are commercially important because they enable conductive patterning on polymer films and other temperature-sensitive substrates while reducing thermal-process intensity.
- Electronics manufacturing remains the broadest consumption base, while automotive and power-electronics applications are raising reliability, thermal-cycling and bonding-performance requirements.
- Asia Pacific leads demand because copper-paste formulation, printed-electronics manufacturing, PCB production, MLCC supply and downstream electronics assembly are concentrated across China, Japan, South Korea and Taiwan.
- Copper oxidation control is the central technical restraint; successful formulations must preserve low resistivity through printing, drying, sintering and field exposure without eroding copper’s cost advantage.
Conductive Copper Paste Market Overview
Conductive copper paste market was valued at USD 195.0 million in 2025, is estimated at USD 205.9 million in 2026, and is projected to reach USD 317.6 million by 2034, advancing at a 5.6% CAGR during 2026–2034. Asia Pacific represents the largest regional market in 2025, supported by the concentration of relevant manufacturing, downstream demand and supplier ecosystems.
Conductive copper paste is a printable functional material that combines copper powder or copper nanoparticles with organic binders, solvents and additives to create conductive traces, electrodes, vias or bonding layers after curing or sintering. Its commercial appeal comes from copper’s strong electrical and thermal conductivity together with a raw-material cost profile that is structurally lower than silver. The main engineering challenge is controlling oxidation while maintaining printability, adhesion, conductivity and process compatibility.
The market spans conventional thick-film pastes, low-temperature printed-electronics formulations, copper bonding materials for power devices and emerging nano-copper systems. End users choose between screen printing, dispensing, coating and additive manufacturing according to line width, deposit thickness, substrate temperature tolerance and production throughput. These choices make formulation know-how and particle engineering critical sources of differentiation.
The commercial structure of the conductive copper paste market is shaped by design qualification, production economics and the interaction between component performance and downstream system requirements. Suppliers that can combine consistent manufacturing, application engineering and supply assurance are better positioned to convert technical eligibility into repeat business. Customer decisions increasingly account for lifecycle continuity, geographic resilience and integration cost, which makes proven process control and ecosystem compatibility as important as nominal product capability.
Segment Analysis: By Type
By type, the Conductive Copper Paste market is segmented into High-temperature Firing, Medium-temperature Firing, Low-temperature Firing. Low-temperature firing products are gaining relevance where flexible substrates, printed electronics and lower-energy processing limit conventional high-temperature cycles. High-temperature products remain important in thick-film electronics where ceramic substrates and proven firing profiles support durable conductivity. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Type | Role in the market | Demand characteristics |
|---|---|---|
| High-temperature Firing | High-temperature Firing addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
| Medium-temperature Firing | Medium-temperature Firing addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
| Low-temperature Firing | Low-temperature Firing addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. | Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins. |
Segment Analysis: By End User
By end user, the Conductive Copper Paste market is segmented into Electronics Manufacturers, Automotive OEMs, Energy Sector, Research Institutes. Electronics manufacturers account for the broadest demand base, while automotive OEM programs impose longer qualification cycles and stricter reliability targets. Energy applications add demand for power modules and metallization where copper can displace more expensive conductive materials. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| End User | Role in the market | Demand characteristics |
|---|---|---|
| Electronics Manufacturers | Electronics Manufacturers represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Automotive OEMs | Automotive OEMs represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Energy Sector | Energy Sector represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Research Institutes | Research Institutes represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Segment Analysis: By Application
By application, the Conductive Copper Paste market is segmented into PCB Manufacturing, MLCC, Flexible Electronics, Automotive Electronics, Others. PCB, MLCC and flexible-electronics demand is volume driven, while automotive electronics increasingly emphasizes thermal cycling, long-term reliability and power-module performance. The application mix is therefore shifting from purely cost-led selection toward more explicit qualification of conductivity, oxidation resistance and bonding integrity. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Application | Role in the market | Demand characteristics |
|---|---|---|
| PCB Manufacturing | PCB Manufacturing creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| MLCC | MLCC creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Flexible Electronics | Flexible Electronics creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Automotive Electronics | Automotive Electronics creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
| Others | Others creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. | Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk. |
Segment Analysis: By Technology
By technology, the Conductive Copper Paste market is segmented into Screen Printing, Dispensing, Coating, 3D Printing. Screen printing remains the workhorse for high-volume patterning because it combines repeatability, throughput and established equipment. Dispensing and 3D printing are more attractive when designers need selective deposition, thicker deposits or geometries that are difficult to realize with conventional screens. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Technology | Role in the market | Demand characteristics |
|---|---|---|
| Screen Printing | Screen Printing represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Dispensing | Dispensing represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Coating | Coating represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| 3D Printing | 3D Printing represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Segment Analysis: By Formulation
By formulation, the Conductive Copper Paste market is segmented into Flake-based, Spherical Powder, Nano-particle, Hybrid. Nano-particle and hybrid formulations are attracting attention because smaller particles can support lower-temperature sintering and finer features. Their commercial value depends on oxidation control, dispersion stability, paste rheology and the ability to retain copper-like conductivity after processing. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.
| Formulation | Role in the market | Demand characteristics |
|---|---|---|
| Flake-based | Flake-based represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Spherical Powder | Spherical Powder represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Nano-particle | Nano-particle represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
| Hybrid | Hybrid represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. | Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle. |
Regional Analysis
Asia Pacific leads the conductive copper paste market in 2025, while regional growth patterns differ according to manufacturing concentration, customer investment cycles, regulation, product mix and supply-chain access. The most important regional distinction is not simply market size; it is the mechanism that converts local investment and end-market demand into qualified purchases.
How does regional demand differ across the conductive copper paste market?
Regional demand for conductive copper paste is structurally uneven because manufacturing assets, design centers, downstream customers and qualification ecosystems are not distributed evenly. Asia Pacific typically has the deepest electronics manufacturing base, North America combines technology development with capital investment, Europe emphasizes reliability and industrial requirements, and emerging regions are more dependent on imported systems. These differences influence vendor selection, inventory policy, service expectations and the pace at which new technologies are adopted.
| Region | Market position | Growth outlook | Demand profile | Supplier-selection gate |
|---|---|---|---|---|
| Asia Pacific | Largest | Strong | Electronics-manufacturing led | Qualification, price and oxidation control |
| North America | Specialty demand | Moderate | R&D, aerospace and power-electronics led | Performance validation and application support |
| Europe | High-reliability niche | Moderate | Automotive and power-electronics led | Environmental compliance and reliability |
| South America | Emerging | Selective | Industrial and renewable-energy led | Landed cost and distributor support |
| Middle East & Africa | Developing | Selective | Project and imported-electronics led | Channel access and application support |
Detailed Regional Blocks
Competitive Landscape
Competition in the conductive copper paste market is determined by technical qualification, manufacturing consistency, customer relationships and the ability to support product lifecycles. Price matters, but it rarely overrides reliability, integration effort or switching cost once a supplier has been designed into a production platform.
The competitive field includes Shoei Chemical, Sumitomo Metal Mining, NAMICS, Kyoto Elex, Tatsuta, Chang Sung Corporation, alongside other specialized suppliers. Market share can shift when a vendor gains access to a new platform, expands qualified capacity or introduces a technology that materially improves system performance. Because customer validation can be lengthy, incumbent suppliers often benefit from continuity, while challengers need a clear technical or supply-chain advantage to displace an approved source.
Competitive strategy is increasingly multi-dimensional. Leading suppliers invest in process or product development, application engineering and regional support at the same time, while customers seek second-source options where technically feasible. This creates a market in which differentiation is sustained through documented performance, manufacturing yield, quality systems, responsiveness and the ability to support future roadmap transitions without forcing unnecessary redesigns.
| Company | Competitive position | Primary basis of competition |
|---|---|---|
| Shoei Chemical | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Sumitomo Metal Mining | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| NAMICS | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Kyoto Elex | Established global / strategic supplier | Competes through product capability, qualification, account access and supply execution. |
| Tatsuta | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Chang Sung Corporation | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Mitsuboshi Belting | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Heraeus | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Asahi Solder | Specialist / regional competitor | Competes through product capability, qualification, account access and supply execution. |
| Ampletec | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| Yuhon Enterprise Corporation | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| Asahi Chemical | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| Resonac | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
| Sinocera | Focused challenger / niche participant | Competes through product capability, qualification, account access and supply execution. |
Production Capacity Analysis
Conductive copper paste capacity is constrained less by gross mixing volume than by qualified powder supply, dispersion know-how, controlled-atmosphere processing and customer-specific validation. High-performance products often require narrow particle-size distributions, oxidation-resistant surface chemistry and repeatable rheology, so a nominal paste line cannot automatically switch among electronics, power-module and flexible-substrate applications without reformulation and validation.
Asia Pacific holds the deepest production ecosystem because copper powder suppliers, electronic-material formulators, PCB producers and downstream electronics manufacturers are clustered in Japan, China, South Korea and Taiwan. That proximity supports faster iteration during printability, curing and reliability qualification, while also intensifying price competition in mainstream formulations.
Capacity should therefore be evaluated on a qualified-output basis rather than as nominal installed capability. A supplier may possess equipment or production lines that appear suitable but still require customer-specific validation, process tuning, test correlation or upstream material qualification. This distinction becomes especially important during demand spikes, when headline capacity can overstate the volume that is immediately available for a particular application, technology generation or reliability class.
Market Dynamics
The conductive copper paste market is being shaped by rising performance requirements and technology transitions on the demand side, while qualification complexity, supply concentration and cost discipline constrain the pace of adoption. The balance of these forces favors suppliers that can solve a measurable system problem without increasing integration risk.
Demand expansion is not uniform across all product variants or customer groups. New technology creates attractive design opportunities, but buyers typically require a clear economic or performance case before changing a qualified architecture. At the same time, supply-chain localization, capacity investment and tighter quality requirements are changing procurement behavior. As a result, growth is likely to concentrate around applications where performance upgrades, manufacturing scale and lifecycle value reinforce one another.
Market Drivers
Four forces provide the strongest support for demand in the conductive copper paste market: performance-driven technology upgrades, expansion of relevant downstream applications, investment in manufacturing or infrastructure, and the need for more resilient supply. Their importance varies by segment, but each creates a direct reason for customers to qualify or purchase additional solutions.
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Copper’s cost advantage versus silver supports substitution | High | Copper provides strong conductivity at a substantially lower raw-material cost than silver, giving formulators a clear economic incentive to solve oxidation and processing challenges. The savings are most valuable in large-area or thick-deposit applications where metal loading is high. |
| Flexible electronics and additive patterning expand addressable uses | High | Printed sensors, flexible circuits and wearable electronics require conductive materials that can be deposited selectively on temperature-sensitive substrates. Low-temperature copper systems broaden design freedom while reducing subtractive processing and material waste. |
| EV and power-electronics growth raises demand for copper-based bonding | Medium-High | Power modules increasingly require conductive bonding materials with strong thermal performance and durability. Sintered copper is being developed for SiC module attachment and other high-temperature applications where silver systems are expensive. |
| Electronics miniaturization increases demand for finer, controlled deposits | Medium-High | Smaller features, tighter spacing and higher current density raise requirements for particle size distribution, rheology and sintering behavior. Suppliers that can deliver fine lines with low resistivity and stable adhesion can gain higher-value design positions. |
Copper’s cost advantage versus silver supports substitution
Copper provides strong conductivity at a substantially lower raw-material cost than silver, giving formulators a clear economic incentive to solve oxidation and processing challenges. The savings are most valuable in large-area or thick-deposit applications where metal loading is high. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Flexible electronics and additive patterning expand addressable uses
Printed sensors, flexible circuits and wearable electronics require conductive materials that can be deposited selectively on temperature-sensitive substrates. Low-temperature copper systems broaden design freedom while reducing subtractive processing and material waste. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
EV and power-electronics growth raises demand for copper-based bonding
Power modules increasingly require conductive bonding materials with strong thermal performance and durability. Sintered copper is being developed for SiC module attachment and other high-temperature applications where silver systems are expensive. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Electronics miniaturization increases demand for finer, controlled deposits
Smaller features, tighter spacing and higher current density raise requirements for particle size distribution, rheology and sintering behavior. Suppliers that can deliver fine lines with low resistivity and stable adhesion can gain higher-value design positions. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.
Market Restraints
Growth is moderated by qualification burden, cyclical purchasing, technology substitution and supply-chain risk. These restraints do not eliminate demand, but they can extend sales cycles, limit supplier switching and reduce the speed at which technically superior solutions convert into production revenue.
| Restraint | Impact | Commercial consequence |
|---|---|---|
| Copper oxidation complicates processing and long-term reliability | High | Copper oxidizes readily, particularly at elevated temperature, which can raise resistance and weaken sintering. Paste formulators must use protective chemistries, controlled atmospheres or particle engineering, adding complexity to manufacturing and customer qualification. |
| Process conversion from silver-based systems can require requalification | High | Many production lines are tuned for silver or other established pastes. Moving to copper can change firing atmosphere, curing temperature, screen parameters and reliability behavior, so customers may need new equipment settings and extended validation. |
| Copper and chemical input prices remain cyclical | Medium | Although copper is cheaper than silver, its price still fluctuates and paste economics are also affected by solvents, binders, specialty powders and energy. Smaller suppliers have less ability to hedge those inputs. |
| Fine-particle copper formulations can be difficult to stabilize | Medium | Nano-copper improves low-temperature sintering but increases surface area, oxidation sensitivity and dispersion complexity. Shelf life, viscosity drift and batch-to-batch consistency can become commercial barriers if formulation control is weak. |
Copper oxidation complicates processing and long-term reliability
Copper oxidizes readily, particularly at elevated temperature, which can raise resistance and weaken sintering. Paste formulators must use protective chemistries, controlled atmospheres or particle engineering, adding complexity to manufacturing and customer qualification. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Process conversion from silver-based systems can require requalification
Many production lines are tuned for silver or other established pastes. Moving to copper can change firing atmosphere, curing temperature, screen parameters and reliability behavior, so customers may need new equipment settings and extended validation. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Copper and chemical input prices remain cyclical
Although copper is cheaper than silver, its price still fluctuates and paste economics are also affected by solvents, binders, specialty powders and energy. Smaller suppliers have less ability to hedge those inputs. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Fine-particle copper formulations can be difficult to stabilize
Nano-copper improves low-temperature sintering but increases surface area, oxidation sensitivity and dispersion complexity. Shelf life, viscosity drift and batch-to-batch consistency can become commercial barriers if formulation control is weak. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.
Market Opportunities
The most attractive opportunities in the conductive copper paste market occur where a technology transition creates measurable value and where suppliers can enter before the customer architecture is locked. Early engagement, application-specific engineering and credible supply planning can convert these windows into durable design positions.
Low-temperature printed electronics
Oxidation-resistant nano-copper and metal-complex chemistries can open flexible circuits, wearable sensors and polymer-substrate applications that cannot tolerate conventional high-temperature firing. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Power-semiconductor die attach
Sintered copper can address high-temperature SiC and GaN modules where thermal conductivity, reliability and cost are critical, creating a premium materials niche beyond conventional printed conductors. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Solar-cell metallization
Copper-based metallization can reduce dependence on silver in photovoltaic manufacturing if diffusion control, contact resistance and module reliability are proven at scale. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Large-area additive electronics
Screen printing, dispensing and digital deposition allow copper paste to serve antennas, heaters, sensors and industrial circuits where material efficiency and scalable patterning matter. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.
Supply Chain Analysis
Copper powders and chemical inputs
Copper flake, spherical powder, nano-copper, binders, solvents and glass or inorganic additives determine conductivity, rheology and firing behavior. Powder morphology and surface treatment are especially important for oxidation control. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Paste formulation and dispersion
Manufacturers mix, mill and disperse conductive and organic phases to create a stable paste with application-specific viscosity, print resolution, adhesion and cure profile. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Printing, curing and sintering
Customers deposit paste by screen printing, dispensing, coating or additive methods before drying and sintering under air, nitrogen or other controlled conditions according to formulation requirements. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Electronics and power-device integration
Finished conductors, electrodes, vias or bonding layers are integrated into PCBs, MLCCs, flexible circuits, sensors, automotive electronics, solar devices and power modules. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.
Recent Developments
Recent developments show how technology roadmaps, manufacturing investment and standards are changing the competitive requirements of the conductive copper paste market. The entries below are selected for their direct relevance to product capability, capacity, qualification or downstream adoption rather than for general corporate activity.
Sumitomo Metal Mining announced development of 100 nm oxidation-resistant nano copper powder intended for power-semiconductor bonding and said it was preparing for mass production targeted for the fiscal year ending March 2027. The development directly addresses one of the main barriers to wider copper-paste use: maintaining conductivity and reliability despite copper’s tendency to oxidize. Source
Resonac continued commercial promotion of sintered copper paste for semiconductor power-module bonding, emphasizing heat resistance, heat dissipation and reliability for SiC devices. The product expands copper paste from printed conductors into higher-value die-attach and package-to-cooler bonding applications. Source
NREL’s Silicon PV workshop included work on copper fire-through paste metallization, underscoring active efforts to reduce silver intensity in crystalline-silicon solar manufacturing while solving copper diffusion, oxidation and contact-formation challenges. Source
Report Scope & Segmentation
| Report attribute | Coverage |
|---|---|
| Market | Conductive Copper Paste |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 195.0 million |
| 2026 Estimated Size | USD 205.9 million |
| 2034 Forecast Size | USD 317.6 million |
| CAGR (2026–2034) | 5.6% |
| Largest Market in 2025 | Asia Pacific |
| By Type | High-temperature Firing, Medium-temperature Firing, Low-temperature Firing |
| By Application | PCB Manufacturing, MLCC, Flexible Electronics, Automotive Electronics, Others |
| By End User | Electronics Manufacturers, Automotive OEMs, Energy Sector, Research Institutes |
| By Technology | Screen Printing, Dispensing, Coating, 3D Printing |
| By Formulation | Flake-based, Spherical Powder, Nano-particle, Hybrid |
| Companies Profiled | Shoei Chemical, Sumitomo Metal Mining, NAMICS, Kyoto Elex, Tatsuta, Chang Sung Corporation, Mitsuboshi Belting, Heraeus, Asahi Solder, Ampletec, Yuhon Enterprise Corporation, Asahi Chemical, Resonac, Sinocera |
Frequently Asked Questions
What was the conductive copper paste market size in 2025?
The global conductive copper paste market was valued at USD 195.0 million in 2025. The 2025 value is the base-year reference used throughout this overview and provides the starting point for comparing the 2026 estimate and the 2034 forecast.
What is the projected conductive copper paste market size in 2034?
The global market is projected to reach USD 317.6 million by 2034. The forecast reflects the interaction of downstream adoption, technology transitions, production investment and the qualification requirements that shape commercial conversion across the market.
What is the CAGR of the conductive copper paste market from 2026 to 2034?
The conductive copper paste market is expected to expand at a 5.6% CAGR during 2026–2034. Growth will not be uniform across every product or region because customer qualification, capital cycles, supply constraints and application-specific performance requirements differ materially.
Which region is the largest conductive copper paste market?
Asia Pacific is the largest regional market in 2025. Its position is supported by the concentration of relevant manufacturing, customers, technology ecosystems and downstream demand, although the precise commercial mechanism differs by country and application.
How is the conductive copper paste market segmented by type?
By type, the market is segmented into High-temperature Firing, Medium-temperature Firing, Low-temperature Firing. These categories address different performance, cost and integration requirements, so supplier selection depends on application fit, qualification history and lifecycle economics rather than a single specification.
What are the main applications for conductive copper paste?
By application, the market covers PCB Manufacturing, MLCC, Flexible Electronics, Automotive Electronics, Others. Demand in each application is linked to platform launches, capacity expansion, equipment replacement and the degree to which the technology improves system performance or manufacturing economics.
What are the principal growth drivers for the conductive copper paste market?
Key drivers include copper’s cost advantage versus silver supports substitution and flexible electronics and additive patterning expand addressable uses. These forces increase demand when customers can translate technical improvements into higher performance, lower cost, greater reliability or access to new applications.
What are the main restraints in the conductive copper paste market?
Important restraints include copper oxidation complicates processing and long-term reliability and process conversion from silver-based systems can require requalification. The resulting qualification burden, purchasing cyclicality and technology risk can extend sales cycles and limit rapid supplier substitution even when new solutions offer clear technical advantages.
Which companies participate in the conductive copper paste market?
Companies profiled in this market include Shoei Chemical, Sumitomo Metal Mining, NAMICS, Kyoto Elex, Tatsuta, Chang Sung Corporation, Mitsuboshi Belting, Heraeus. Competition centers on qualification, product or process performance, manufacturing consistency, customer support and the ability to maintain supply across the required product lifecycle.
What should buyers evaluate when selecting a conductive copper paste supplier?
Buyers should evaluate demonstrated performance, qualification history, manufacturing consistency, lifecycle support, supply resilience and integration cost. A technically strong product can still face adoption barriers if it increases redesign risk, lacks regional support or cannot meet the customer’s production and quality requirements.
Research Sources & Evidence Base
View research sources used for this overview.
- Sumitomo Metal Mining. Metal-complex conductive paste — Product characteristics, oxidation resistance, low-temperature sintering and printed-electronics applications.
- Sumitomo Metal Mining. 100 nm oxidation-resistant nano copper powder announcement — 2025 development milestone and planned mass-production timing for power-semiconductor bonding.
- Heraeus. C7462 copper conductor technical data sheet — Screen-printing, firing and conductivity requirements for thick-film copper conductors.
- Resonac. Sintered copper paste — Power-module bonding use case and reliability positioning for SiC semiconductor modules.
- NREL. Copper paste metallization workshop material — Solar-cell copper metallization research and process challenges.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF