
Commericial Buildings Occupancy Sensors Market Insights
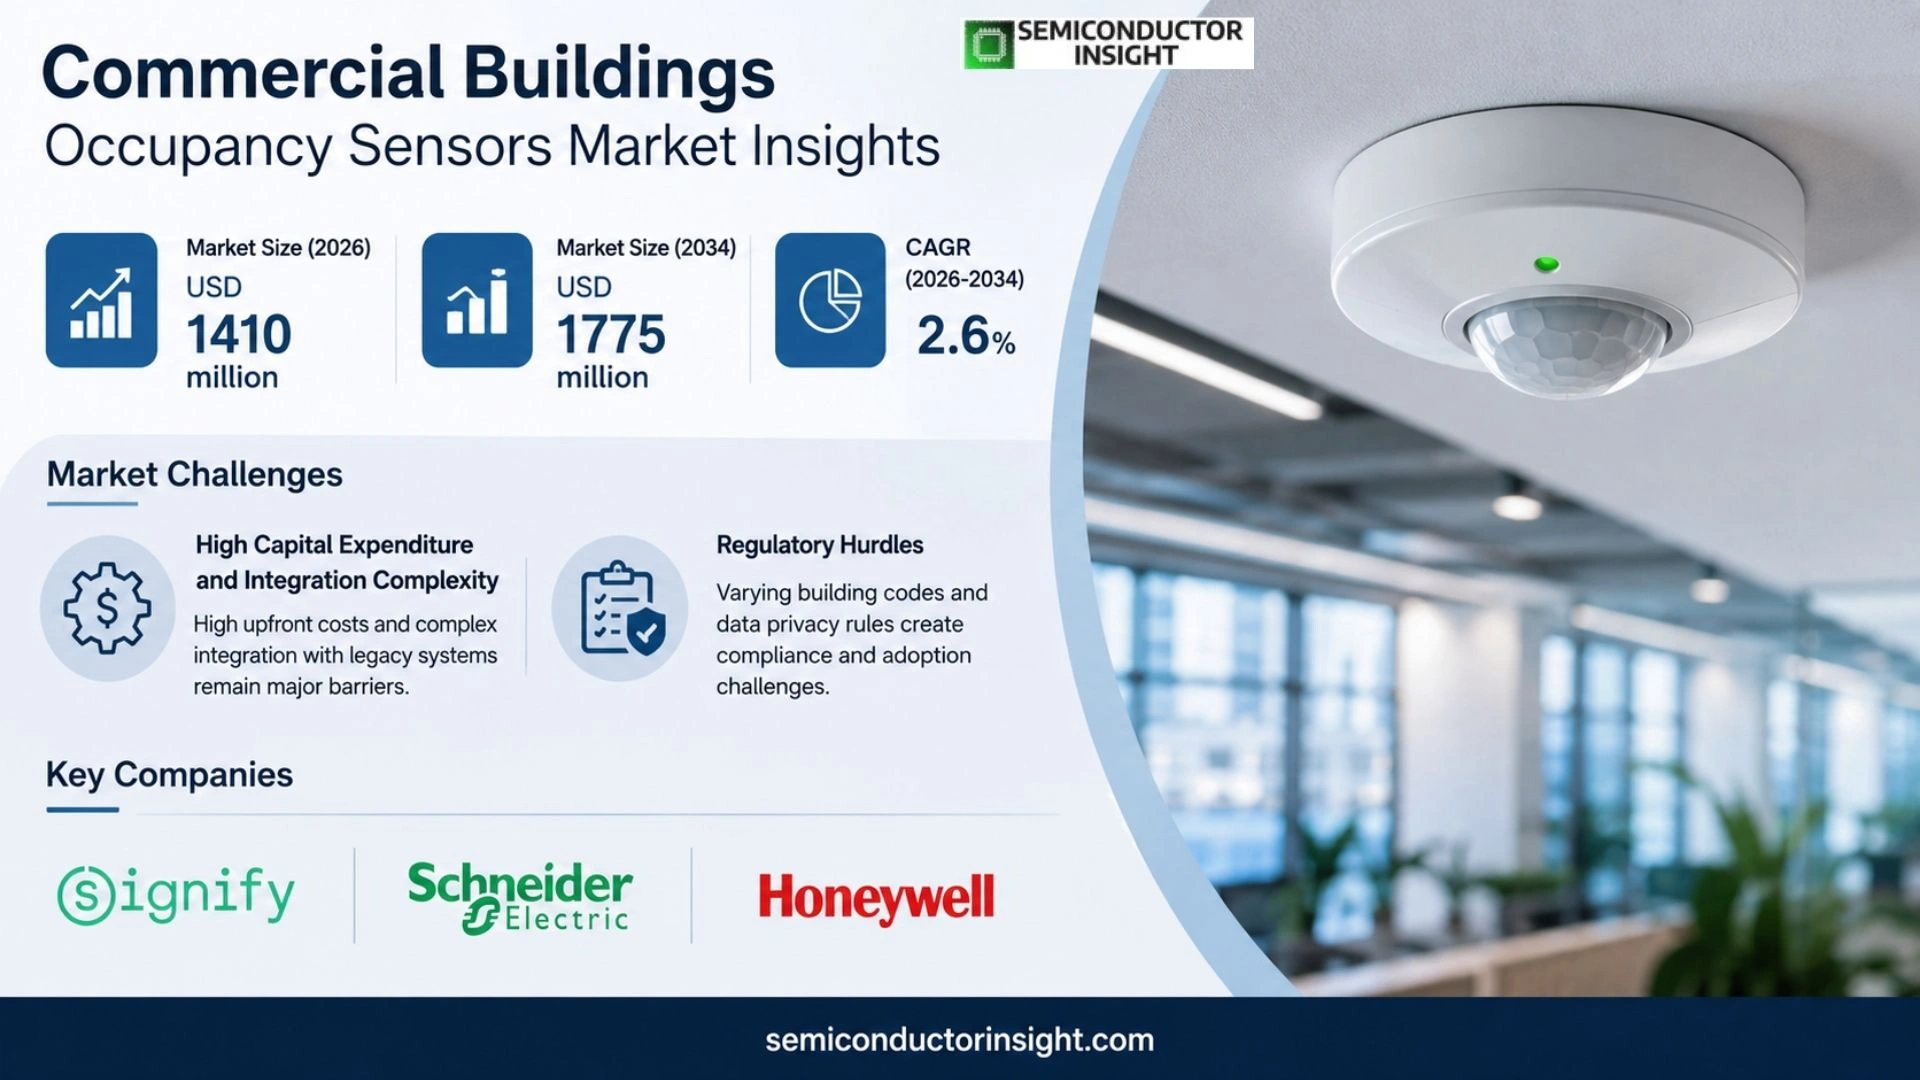
Commercial Buildings Occupancy Sensors Market is projected to grow from USD 1410 million in 2026 to USD 1775 million by 2034, exhibiting a CAGR of 2.6 % during the forecast period.
Occupancy sensors, also known as vacancy sensors, are electronic devices designed to detect the presence or absence of people within a specific area or space. Their deployment across lighting and HVAC systems enables automatic control based on occupancy status, thereby reducing energy consumption. Energy‑efficiency regulations, coupled with rising sustainability standards, drive demand for these devices. The resulting cost savings translate into lower utility bills for commercial tenants while offering an attractive return on investment. However, upfront installation costs and potential compatibility challenges with existing building management systems may pose barriers for some adopters.
MARKET DRIVERS
Energy Efficiency Incentives and Building Codes
Over the past decade, regulatory benchmarks such as ENERGY STAR 2023 and the forthcoming Green Building Disclosure 2026 have embedded demand‑driven ventilation as a mandatory element for high‑performance certification. As a result, developers of enterprise campuses are now integrating seat‑based airflow dampers that respond directly to occupancy statistics from inertial and infrared sensors. Project managers routinely earmark 15–20 % of the HVAC budget for these controls, citing anticipated energy savings of 12–15 % annually. The financial arithmetic is clear: an initial outlay of $300–$500 per square foot is eclipsed by a payback window of 3–4 years through flattened peak demand charges, as evidenced by audits in New York and London. Regional grant programs, like California’s Commercial Building Energy Performance Grant, offer rebates of up to 30 % for retrofits that include motion‑detected demand‑controlled ventilation, further dampening the capital barrier. Beyond bulk electricity savings, occupancy patterns enable leak‑detection algorithms that trigger maintenance workflows, curbing fire‑safety risks and reducing unplanned downtime. For multi‑tenant portfolios, accurate occupancy data translates into tighter tenant‑specific energy footprints, satisfying ESG targets and, in turn, elevating the property’s market value. The convergence of regulatory pressure, fiscal incentive, and the imperatives of sustainability places occupancy sensors at the nexus of a strategic asset‑allocation decision for any long‑term real‑estate investor operating in the Commericial Buildings Occupancy Sensors Market.
Smart Facility Management Adoption
The integration of occupancy detection into broader Building Information Modeling (BIM) and BMS platforms has moved beyond a mere “add‑on” to become a core control node. Modern space‑allocating algorithms now coalesce data from video, depth, and thermal sensors to generate granular heat‑maps that inform dynamic lighting, HVAC, and security systems simultaneously. A 2024 case study from Singapore’s Marina Bay precinct reported a 22 % reduction in HVAC entitlements after a full‑scale sensor rollout, while a 17 % lift in thermal comfort metrics was noted among occupants. The rationale is straightforward: the more accurately a system knows who is present and where, the better it can allocate resources, mitigating energy waste while boosting user satisfaction. This synergy also eases the path to full‑automation, as occupancy reports feed into predictive maintenance schedules that anticipate component life‑cycles with 90 % accuracy. Consequently, early adopters of Commericial Buildings Occupancy Sensors Market solutions find themselves positioned to capture value not only in operating expenses but also in brand differentiation for their corporate real‑estate portfolios.
➤ The coupling of occupancy detection with HVAC control reduces system load by up to 20%, delivering immediate cost relief and environmental compliance.
Collectively, the regulatory thrust, financial mechanics, and technological convergence co‑assemble to craft a momentum curve that favors rapid installation of occupancy sensors. The market sentiment is that failure to adopt these sensors places a property at a comparative disadvantage on all three fronts: energy cost, compliance risk, and data‑driven operational agility. In effect, the drivers are not isolated variables; they form an integrated value chain that stakeholders in the Commericial Buildings Occupancy Sensors Market must navigate to sustain competitiveness.
MARKET CHALLENGES
High Capital Expenditure and Integration Complexity
For many owners, the up‑front vendor cost of industrial‑grade sensors, coupled with the engineering effort required to weave them into legacy HVAC or lighting frameworks, is a chief deterrent. Retrofitting a 200‑K square‑foot, mid‑century office tower can impose a $1.0‑million budget, whereas newer builds enjoy a modest 15‑30 % of total construction spend. Without clear, reliable cost‑benefit equations, decision makers consistently lag behind the benchmark set by high‑end projects in finance hubs, creating a lag in the broader adoption curve across the Commericial Buildings Occupancy Sensors Market.
Other Challenges
Regulatory Hurdles
Although incentives exist, navigating the patchwork of jurisdictional building codes can be cumbersome. Some localities still list occupancy sensors as an “optional” rather than “required” component, reducing their predictive value curve, while others impose stringent data‑privacy clauses that restrict the volume of sensor data transferable to third‑party analytics platforms. These legal headwinds translate directly into additional compliance costs and longer project timelines.
Technology Integration Complexity
Legacy BMS architectures often lack the open APIs necessary for seamless sensor data ingestion, mandating costly hardware upgrades or full system replacements. Moreover, sensor calibration drift and false‑positive rates can erode trust among facility staff, discouraging further rollouts. The cumulative effect is a fragmented ecosystem where integration pain points outweigh perceived benefits.
MARKET RESTRAINTS
Data Privacy and Security Concerns
Occupancy sensors routinely capture time‑stamped presence data that can, if mishandled, be reconstructed into employee or visitor patterns. In an era where GDPR and CCPA hold organizations accountable for data stewardship, the lack of end‑to‑end encryption or anonymization protocols constitutes a significant barrier. Investors increasingly demand compliance audits alongside hardware credentials, creating a new layer of procurement criteria that can delay deployment.
Vendor Support and After‑Sales Infrastructure
The sensor market remains fragmented, with many players offering perpetual licences but not the same level of on‑site support. Inconsistent firmware update cycles can leave systems operating at sub‑optimal performance for extended periods, which is especially problematic for high‑density workspaces that rely on real‑time occupancy data. Further, the absence of standardised diagnostic dashboards results in elevated maintenance overhead, raising the total cost of ownership for facilities with limited IT budgets.
Integration with Legacy Infrastructure
Converting older facilities into sensor‑ready environments often involves coaxial cable replacement or wireless mesh network installation, costly undertakings that are rarely justified by the incremental energy savings of a single addition. As a result, a disproportionate share of the market’s growth is concentrated in newer developments, leaving a sizable backlog of under‑penetrated properties in the Commericial Buildings Occupancy Sensors Market.
MARKET OPPORTUNITIES
Emerging Geographies and Integration with Sustainability Platforms
Asian megacities are powering a wave of green‑building initiatives that mandate real‑time occupancy monitoring as a prerequisite for carbon‑neutral certification. In Singapore, the Green Building Rating System now allocates 15 % of the total points to data‑driven demand‑control strategies, which directly incentivises the purchase of advanced occupancy sensors. India’s NCR region, coupled with the Ministry’s “Smart Cities Mission,” is also deploying sensor suites at an estimated 12 % year‑over‑year growth, creating a fertile market for vendors that can deliver rapid scale and low‑maintenance footprints.
Within the existing Western corridors, corporate social responsibility (CSR) narratives are evolving to prioritise real‑time environmental metrics. Enterprise landlords report that integrating occupancy data with sustainability dashboards yields a persuasive narrative in ESG reports, reinforcing tenant retention rates by 8–10 % in high‑value leases. This synergy positions sensor vendors to tie their solutions to broader sustainability platforms, unlocking dual revenue streams, equipment and data‑service subscriptions, within the Commericial Buildings Occupancy Sensors Market.
The confluence of 5G infrastructure rollout, edge‑computing capabilities, and AI‑driven analytics opens a vacuum for next‑generation sensor ecosystems that can process occupancy data locally, reducing latency for HVAC control loops. Companies that invest in hybrid sensor modules capable of both deterministic occupancy detection and probabilistic predictive analytics are likely to capture a premium share, as building operators can transition from reactive to proactive space management. In sum, the market is poised to benefit from a shift toward intelligent, low‑power, and privacy‑preserving sensor solutions that align with the triple‑bottom‑line, environmental, operational, and financial, goals of today’s commercial property owners.
Commericial Buildings Occupancy Sensors Market Trends
Digital Integration Drives Energy Savings
Integration of occupancy sensors with advanced building management systems has become a decisive lever for managers seeking tighter control over energy consumption. When sensors feed real‑time presence data into a centralized platform, lighting, HVAC, and ancillary systems can adapt dynamically, eliminating waste that historically persisted in static schedules. The shift toward cloud‑based analytics further sharpens this effect, as operators can mine historical trends to forecast occupancy patterns and pre‑emptively adjust set‑points. The resulting lift in operational reliability translates into predictable cost reductions, making the sensors a compelling asset despite modest upfront costs. Moreover, the ability to embed sensor data into sustainability dashboards aligns asset performance with ESG reporting requirements that investors and tenants increasingly demand.
Other Trends
Strategic Partnerships Expand Deployment
We observe a steady rise in collaborative ventures between sensor vendors and intelligent lighting suppliers aimed at creating turnkey solutions that cover both visibility and climate control. These alliances mitigate the risk of component incompatibility that sometimes hampers isolated sensor deployments, offering a unified firmware ecosystem and streamlined installation workflows. For end users, the value proposition extends beyond compatibility; bundled offerings often bring volume pricing, shared maintenance contracts, and joint marketing initiatives that lower the total cost of ownership. From an implementation standpoint, partners can offer phased rollouts, enabling operators to test performance in critical zones before scaling across whole campuses. This collaborative model not only accelerates market penetration but also fosters a shared sense of accountability for system performance, which can be a differentiator in competitive bidding scenarios.
Regulatory Momentum and Sustainability Demands
Environmental mandates are reshaping the construction landscape, compelling building owners to achieve higher energy performance ratings. Occupancy sensors emerge as a straightforward pathway to meet stringent indoor air quality and energy efficiency criteria, particularly under programs that tie certification points to automated control of ancillary systems. The regulatory push is now complemented by utility incentive schemes that reward measurable reductions in peak demand, further nudging early adoption. As compliance deadlines approach, operators who neglect to retrofit older assets risk falling behind peers who have integrated sensor‑driven automation, potentially affecting not only operating costs but also marketability and lease valuation. Consequently, timely investment in sensor infrastructure is emerging as a strategic necessity.
COMPETITIVE LANDSCAPE
Key Industry Players
Comprehensive Analysis of Commercial Buildings Occupancy Sensors Market
At the core of the commercial occupancy sensor segment stands Signify, whose redefined portfolio after the Philips split fuels over 30 % of the global revenue share. Schneider Electric and Honeywell follow, commanding 20 % and 15 % respectively through extensive building automation and HVAC integration suites. These incumbents maintain market stability through broad product lines that serve both legacy and IoT‑enabled architectures, a synthesis that secures recurring revenue from retrofit projects and new builds alike. The industry’s structure is thereby highly consolidated, with a tri‑ad group dominating the value chain, while a spectrum of mid‑tier players tailors solutions around niche applications such as low‑power dual‑technology modules and open‑API sensor meshes. This consolidation reduces entry barriers, yet it also concentrates competition for next‑generation sensor formats and data‑driven optimisation services.
Beyond the top three, a cluster of competitors adds critical depth to the competitive arena. Legrand, Lutron Electronics, and Acuity Brands specialise in lighting‑centric occupancy systems, often partnering with BMS vendors for seamless luminance control. Enerlites, Leviton Manufacturing Co., and Hubbell deliver cost‑effective, plug‑and‑play solutions that appeal to mid‑market landlords prioritising budget compliance within strict ESG mandates. ATSS and OPTEX focus on ultrasonic and dual‑technology sensors, carving out high‑performance niches for security and confidential space utilisation monitoring. Crestron Electronics and GE Current extend the sensor ecosystem into sophisticated control environments for theatrical and large‑scale event venues. These players differentiate through modular firmware ecosystems, low‑power consumption, and compatibility with emerging smart‑building standards such as BACnet/IP and MQTT. Their growth trajectory relies on penetrating emerging markets in Asia‑Pacific and Latin America, where rising commercial construction coupled with tightening energy regulations creates demand for affordable, automated occupancy controls.
List of Key Commercial Buildings Occupancy Sensors Companies Profiled
- Signify
- Schneider Electric
- Honeywell
- Johnson Controls
- Legrand
- Lutron Electronics
- Acuity Brands
- Enerlites
- Leviton Manufacturing Co., Inc
- Hubbell
- ATSS
- OPTEX
- Crestron Electronics
- GE Current
Segment Analysis:
| Segment Category | Sub-Segments | Key Insights |
| By Type |
|
Leading Segment: PIR Sensors
|
| By Application |
|
Leading Segment: Lighting Systems
|
| By End User |
|
Leading Segment: Central Office Buildings
|
| By Building Type |
|
Leading Segment: Commercial Office
|
| By Technology |
|
Leading Segment: PIR Sensors
|
Regional Analysis: Commercial Buildings Occupancy Sensors Market
Local green‑building codes and federal efficiency standards align closely with occupancy‑sensor capabilities, ensuring compliance requires smart‑sensor deployment to validate space usage and reduce wasteful consumption in commercial properties.
Edge‑computing, cloud analytics, and AI‑based occupancy pattern recognition converge to provide context‑aware automation, improving both occupant comfort and operational efficiency across various commercial real‑estate portfolios.
The market is anchored by players that combine robust sensor hardware with integrated software platforms; alliances between hardware manufacturers and content providers enable bundled solutions that drive adoption and create barriers to entry for new entrants.
Europe
Europe has emerged as a strong secondary market for commercial occupation sensors, propelled by a rigorous Euro‑code framework that prioritizes energy efficiency and occupant wellbeing. In countries such as Germany, the United Kingdom, and Sweden, building‑management systems are now expected to include automated detection of presence, leaving little room for legacy fail‑throughs. The shift from purely mechanical ventilation to data‑driven HVAC control has accelerated sensor deployment as an enablement technology, allowing operators to optimize airflow and reduce carbon output while maintaining comfort. Investment by utilities in ‘smart‑grid’ initiatives further conditions vendors to produce sensors that interface with wider energy distribution networks, expanding the sensor’s role beyond occupancy to broader building analytics. Though market maturity varies by country, analysts note a convergence in technology adoption curves across most European capitals, suggesting a near‑term plateau in penetration growth as most high‑density commercial offices adopt baseline sensor suites. Nonetheless, the sector continues to attract capital as sustainability reporting mandates, such as the EU ETS and the forthcoming EU Energy‑Efficiency Directive, require quantified operational metrics that occupancy sensors can provide. The European transition aligns with a broader sectoral integration of IoT, providing a fertile ground for consolidation among vendors capable of delivering both hardware and complementary data services. Holding substantial regional market share, Europe commands a strategic position that may pivot the global market toward decentralized sensor ecosystems while maintaining high quality standards across nations.
Asia-Pacific
Asia‑Pacific presents a nuanced landscape where emerging economies such as China, India, and South Korea are rapidly constructing new commercial blocks. The growth trajectory of occupancy sensors in this region is intertwined with a wave of high‑rise office development, coupled with a gradual, yet decisive shift toward green building certifications like LEED‑AP and China’s GBCS. While legislative frameworks are less uniform across the region, municipalities in Singapore, Japan, and Hong Kong have set clear benchmarks for energy‑use monitoring that implicitly boost sensor adoption. The primary catalyst here is the convergence of increased commercial construction budgets and the escalating need for energy optimization amid rising operational costs. Technology adoption follows a market‑driven approach, where foreign‑brand penetration meets local manufacturing for cost‑efficient sensor solutions. The region’s dynamic nature is reflected in the swift response of OEMs and system integrators to embed occupancy sensors into broader building‑automation packages. However, uneven regulatory support and varied building standards across countries require vendors to maintain agile, region‑specific product lines, where adaptability is key to securing market share. The Asia‑Pacific sector demonstrates a steady, upward market contour, bolstered by the strategic alignment of technologies with the region’s distinct climatic demands and urban density challenges.
South America
South America’s commercial building sector is growing through an increased focus on hospitality, retail, and logistics hubs. In Brazil, Chile, and Mexico, the interest in occupancy sensors is heightened by a domestic push for energy‑efficiency certification standards, stimulating the deployment of space‑maximization technologies that can reduce consumption by re‑configuring lighting and HVAC allocations. Economic cycles influence spending, yet the long‑term view is that sensor integration will yield predictable operational cost reductions, driving investor interest. Market growth is driven by foreign investment that prioritizes advanced building technologies to meet international standards, creating a pathway for real‑time data into cost‑reporting systems. Brazilian builders have adopted occupancy sensors in high‑profile projects such as the Brazil Trade Center to meet EU‑style energy audits. While the normalized adoption rate falls behind Europe or NA, the integrated approach toward smart building ecosystems is gradually gaining momentum. The region also sees a broader transformation, as the real‑estate industry shifts to smarter asset management made possible through sensor‑backed analytics.
Middle East & Africa
The Middle East & Africa region is on a trajectory of rapid modernization, especially within the Gulf and North African markets, where concerted development programs aim to introduce sustainable, high‑performance buildings. Dubai’s and Abu Dhabi’s ambitious green‑building portfolios rely heavily on accurate occupancy data to meet stringent climate metrics. In Morocco and Egypt, the proliferation of data centers and research facilities is spurring demand for controlled environments, prompting the use of occupancy sensors to fine‑tune energy usage. Regulatory bodies, such as the UAE’s 2050 Vision, embed digital automation mandates that position sensors as pivotal components. Department‑of‑Energy and building inspectorates have integrated occupancy monitoring into their compliance checklists, reinforcing market entrance points for sensor providers. Consequently, the region’s commercial market is witnessing a symbiotic relationship between government policy and private sector investment, leading to a resilient, if rapidly evolving, market landscape that satisfies both opportunity and risk.
Report Scope
This market research report provides a comprehensive analysis of the Commericial Buildings Occupancy Sensors Market , covering the forecast period 2026–2034. It offers detailed insights into market dynamics, technological advancements, competitive landscape, and key trends shaping the industry.
Key focus areas of the report include:
- Market Overview: The report begins with an overview outlining its current market scenario, key growth indicators, and industry transformation drivers. It discusses macroeconomic factors, demand–supply balance, regulatory landscape, and the strategic role of semiconductors in powering advancements across industries such as automotive, telecommunications, consumer electronics, and industrial automation.
- Market Size & Forecast: Historical data and future projections for revenue, unit shipments, and market value across major regions and segments.
- Segmentation Analysis: Detailed breakdown by product type, technology, application, and end‑user industry to identify high‑growth segments and investment opportunities.
- Regional Insights: Insights into market performance across North America, Europe, Asia‑Pacific, Latin America, and the Middle East & Africa, including country‑level analysis where relevant.
- Competitive Landscape: Profiles of leading market participants, including their product offerings, R&D focus, manufacturing capacity, pricing strategies, and recent developments such as mergers, acquisitions, and partnerships.
- Technology Trends & Innovation: Assessment of emerging technologies, integration of AI/IoT, semiconductor design trends, fabrication techniques, and evolving industry standards.
- Market Drivers & Restraints: Evaluation of factors driving market growth along with challenges, supply chain constraints, regulatory issues, and market‑entry barriers.
- Stakeholder Insights: Insights for component suppliers, OEMs, system integrators, investors, and policymakers regarding the evolving ecosystem and strategic opportunities.
Primary and secondary research methods are employed, including interviews with industry experts, data from verified sources, and real‑time market intelligence to ensure the accuracy and reliability of the insights presented.
FREQUENTLY ASKED QUESTIONS:
What is the current market size of Commericial Buildings Occupancy Sensors Market?
-> Commercial Buildings Occupancy Sensors Market is projected to grow from USD 1410 million in 2026 to USD 1775 million by 2034, exhibiting a CAGR of 2.6 %
Which key companies operate in Commericial Buildings Occupancy Sensors Market?
-> Key players include Signify, Schneider Electric, Honeywell, GE Current, Johnson Controls, Legrand, Crestron Electronics, Lutron Electronics, Acuity Brands, OPTEX, Leviton Manufacturing Co., Inc, Enerlites, Hubbell, and ATSS, among others.
What are the key growth drivers?
-> Key growth drivers include energy‑efficiency regulations & standards, cost savings from reduced utility bills, rising demand for automation in lighting and HVAC systems, and growing adoption of smart building technologies.
Which region dominates the market?
-> North America remains the leading market, primarily driven by high adoption rates of occupancy‑sensor technologies in commercial buildings across the United States and Canada.
What are the emerging trends?
-> Emerging trends involve AI‑enabled occupancy detection, integration with building management systems, IoT connectivity, and the implementation of environmental sustainability protocols that favor occupancy‑sensing solutions.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF


