SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Coated Busbar Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
POWER ELECTRONICS Semiconductor Market Research

Coated Busbar Market

Size, Share & Industry Analysis, By Type (Copper Conductor, Aluminum Conductor), By Application (Switchgear, Smart Grid, Energy, Power Supply, Communication Connection, Others), By End User (Utilities, Industrial, Commercial Buildings), By Coating Type (Polymer Insulation, Anti-Corrosion, Heat Dissipation), By Voltage Rating (Low Voltage, Medium Voltage, High Voltage), and Regional Forecast, 2026-2034

◷
UPDATED 12 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 050a412b9998
▯
FORMATS PDF

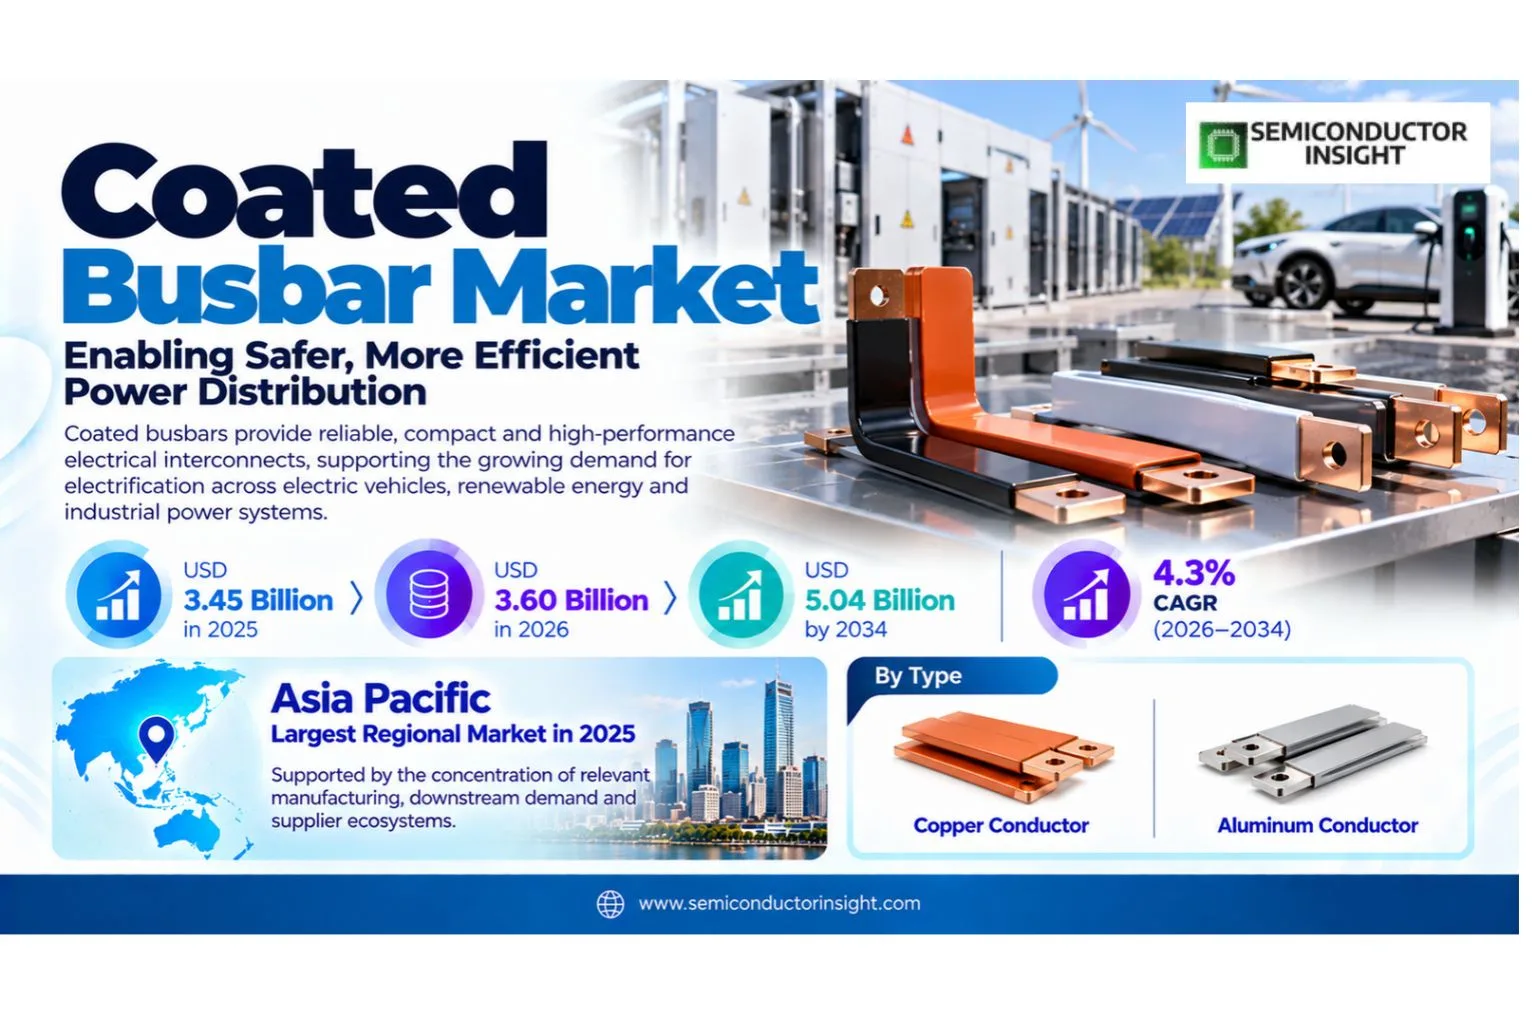
Coated busbar market was valued at USD 3.45 billion in 2025, is estimated at USD 3.60 billion in 2026, and is projected to reach USD 5.04 billion by 2034, advancing at a 4.3% CAGR during 2026–2034. Asia Pacific represents the largest regional market in 2025, supported by the concentration of relevant manufacturing, downstream demand and supplier ecosystems.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 3.45 billion
2034 Projected Market Size
USD 5.04 billion
CAGR (2026–2034)
4.3%
Largest Market in 2025
Asia Pacific

Key Takeaways

  • Coated busbar market was valued at USD 3.45 billion in 2025 and is projected to reach USD 5.04 billion by 2034, representing a 4.3% CAGR over 2026–2034.
  • Copper conductors remain the leading material choice where current density and thermal performance are critical, while aluminum gains share in weight-sensitive and cost-sensitive power distribution.
  • Switchgear, smart-grid and renewable-energy applications form the largest demand base because coated busbars combine high current carrying capability with compact insulated power routing.
  • Asia Pacific leads through concentrated electrical-equipment manufacturing, EV production, renewable-energy investment and major grid modernization programs in China, India, Japan and Southeast Asia.
  • Powder-coated and laminated constructions are gaining value as higher-voltage SiC-based power electronics increase demands for low inductance, insulation integrity and thermal durability.

Coated Busbar Market Overview

Coated busbar market was valued at USD 3.45 billion in 2025, is estimated at USD 3.60 billion in 2026, and is projected to reach USD 5.04 billion by 2034, advancing at a 4.3% CAGR during 2026–2034. Asia Pacific represents the largest regional market in 2025, supported by the concentration of relevant manufacturing, downstream demand and supplier ecosystems.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless otherwise stated

Coated busbars are copper or aluminum conductors protected by dielectric, anti-corrosion or thermally engineered coatings. They replace bulky cable assemblies in power conversion and distribution systems by carrying high current through compact, mechanically stable paths while maintaining electrical isolation and controlled spacing between conductors.

Market growth is increasingly linked to EV powertrains, renewable-energy inverters, data centers and smart-grid hardware. These applications need lower inductance, reduced wiring complexity and higher power density, which makes insulation chemistry, partial-discharge control and thermal endurance central product-selection criteria rather than simple conductor dimensions.

The commercial structure of the coated busbar market is shaped by design qualification, production economics and the interaction between component performance and downstream system requirements. Suppliers that can combine consistent manufacturing, application engineering and supply assurance are better positioned to convert technical eligibility into repeat business. Customer decisions increasingly account for lifecycle continuity, geographic resilience and integration cost, which makes proven process control and ecosystem compatibility as important as nominal product capability.

Segment Analysis: By Type

By type, the Coated Busbar market is segmented into Copper Conductor, Aluminum Conductor. Copper dominates high-power applications because of its conductivity and thermal performance, while aluminum offers lower weight and material cost. Suppliers increasingly combine conductor choice with plating, welding and coating technologies to optimize system economics rather than treating the base metal as the only design variable. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.

Type Role in the market Demand characteristics
Copper Conductor Copper Conductor addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins.
Aluminum Conductor Aluminum Conductor addresses a distinct part of the product and process mix. Its commercial position depends on technical fit, manufacturing maturity, integration requirements and customer qualification rather than on headline specifications alone. Demand is strongest where the segment aligns with established customer designs, predictable supply, and measurable system-level performance. Suppliers that can document repeatability, compatibility and lifecycle support are better placed to defend design wins.

Segment Analysis: By End User

By end user, the Coated Busbar market is segmented into Utilities, Industrial, Commercial Buildings. Utilities prioritize lifetime and electrical safety, industrial users focus on compact high-current distribution and maintainability, and commercial-building customers value installation efficiency and footprint reduction. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.

End User Role in the market Demand characteristics
Utilities Utilities represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle.
Industrial Industrial represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle.
Commercial Buildings Commercial Buildings represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle.

Segment Analysis: By Application

By application, the Coated Busbar market is segmented into Switchgear, Smart Grid, Energy, Power Supply, Communication Connection, Others. Switchgear and energy applications lead broad demand, while EV, data-center and renewable-energy converters provide faster growth because power density and installation space are more constrained. Smart-grid equipment adds long-lifecycle demand where insulation and corrosion resistance affect field reliability. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.

Application Role in the market Demand characteristics
Switchgear Switchgear creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk.
Smart Grid Smart Grid creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk.
Energy Energy creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk.
Power Supply Power Supply creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk.
Communication Connection Communication Connection creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk.
Others Others creates demand when the underlying system requires the market’s core function at production scale. Procurement is normally tied to platform launches, equipment upgrades, capacity expansion or replacement cycles. Buyers evaluate reliability, qualification time, integration cost and vendor support alongside unit economics. Adoption accelerates when the solution removes a system bottleneck or supports a new performance tier without creating disproportionate redesign risk.

Segment Analysis: By Coating Type

By coating type, the Coated Busbar market is segmented into Polymer Insulation, Anti-Corrosion, Heat Dissipation. Polymer insulation is the largest coating class because it prevents shorts and enables compact spacing. Anti-corrosion and high-temperature coatings create premium niches in harsh industrial, marine and high-power environments. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.

Coating Type Role in the market Demand characteristics
Polymer Insulation Polymer Insulation represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle.
Anti-Corrosion Anti-Corrosion represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle.
Heat Dissipation Heat Dissipation represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle.

Segment Analysis: By Voltage Rating

By voltage rating, the Coated Busbar market is segmented into Low Voltage, Medium Voltage, High Voltage. Medium-voltage products offer broad opportunity across industrial power distribution and smart-grid systems, while high-voltage coated busbars require tighter partial-discharge control and more demanding insulation validation. Purchasing decisions vary by performance requirement, qualification burden, integration complexity and lifecycle economics, so suppliers compete on application fit rather than on a single technical specification.

Voltage Rating Role in the market Demand characteristics
Low Voltage Low Voltage represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle.
Medium Voltage Medium Voltage represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle.
High Voltage High Voltage represents a relevant purchasing and deployment pathway within this market. Commercial attractiveness depends on how well it aligns with customer architecture, supply-chain constraints and required performance. Growth is linked to design-in activity, installed-base transitions and the ability of suppliers to meet qualification, cost and availability requirements over the full product lifecycle.

Regional Analysis

Asia Pacific leads the coated busbar market in 2025, while regional growth patterns differ according to manufacturing concentration, customer investment cycles, regulation, product mix and supply-chain access. The most important regional distinction is not simply market size; it is the mechanism that converts local investment and end-market demand into qualified purchases.

How does regional demand differ across the coated busbar market?

Regional demand for coated busbar is structurally uneven because manufacturing assets, design centers, downstream customers and qualification ecosystems are not distributed evenly. Asia Pacific typically has the deepest electronics manufacturing base, North America combines technology development with capital investment, Europe emphasizes reliability and industrial requirements, and emerging regions are more dependent on imported systems. These differences influence vendor selection, inventory policy, service expectations and the pace at which new technologies are adopted.

Region Market position Growth outlook Demand profile Supplier-selection gate
Asia Pacific Largest Strong Grid, EV and manufacturing led Cost, insulation quality and local capacity
North America Established high-value market Moderate-strong Data-center, EV and grid led Reliability and design integration
Europe Mature technology market Moderate Automotive, rail and renewable led Safety standards and lifecycle support
South America Emerging Moderate Industrial and renewable led Import cost and project timing
Middle East & Africa Developing Moderate-strong Infrastructure, energy and industrial led Project specification and durability

Detailed Regional Blocks

Asia Pacific LARGEST MARKET

What defines the Asia Pacific coated busbar market?

Asia Pacific leads because China, India, Japan and South Korea combine electrical-equipment manufacturing, EV production, renewable-energy expansion and grid investment. Regional suppliers benefit from high local demand for switchgear, inverters and compact power-distribution assemblies, while customers increasingly require stronger insulation and thermal performance for higher-power electronics. Supplier strategies therefore need to reflect local qualification practices, channel structure, end-market priorities and the availability of technically comparable alternatives rather than treating the region as a uniform extension of global demand.

Market positionLargest
Growth outlookStrong
Demand profileGrid, EV and manufacturing led
Market access gateCost, insulation quality and local capacity
Country / subregion Role Demand logic
China Largest manufacturing base EVs, inverters, switchgear and grid investment support very high coated-busbar demand.
India Grid and industrial expansion Electrification, renewables and industrial power distribution create strong demand.
Japan High-reliability electronics Automotive and industrial applications support premium coated and laminated designs.
South Korea EV and electronics demand Battery, automotive and power electronics support compact high-current solutions.

Market instances

Rogers’ ROLINX portfolio includes laminated, powder-coated, flexible and integrated busbar designs for EV/HEV, renewable energy, rail, industrial drives and smart-grid systems, illustrating the breadth of end-use demand. For suppliers in Asia Pacific, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Rogers states that ROLINX Performance busbars can support working voltages up to 12 kV DC and power levels of several megawatts, showing how coated and laminated busbars are moving into demanding high-power systems. For suppliers in Asia Pacific, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Regional EV and renewable-energy manufacturing creates strong co-development demand for busbars that match specific inverter layouts, current density and thermal environments rather than standardized cable assemblies. For suppliers in Asia Pacific, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Full-report coverage for Asia Pacific examines country-level demand, customer concentration, supplier positioning and the technical or commercial requirements that influence qualification. The regional view is designed to distinguish structural demand drivers from short-lived purchasing cycles and to show where market access depends on local manufacturing, distribution, standards, service capability or long-term customer relationships.

North America ESTABLISHED HIGH-VALUE MARKET

What defines the North America coated busbar market?

North America is a high-value market supported by data-center growth, vehicle electrification, grid modernization and industrial power conversion. Buyers place strong weight on low-inductance design, UL-recognized insulation systems, thermal performance and supplier engineering support during converter or battery-pack design. Supplier strategies therefore need to reflect local qualification practices, channel structure, end-market priorities and the availability of technically comparable alternatives rather than treating the region as a uniform extension of global demand.

Market positionEstablished high-value market
Growth outlookModerate-strong
Demand profileData-center, EV and grid led
Market access gateReliability and design integration
Country / subregion Role Demand logic
United States Largest regional market Data centers, EVs, charging and grid projects drive coated-busbar demand.
Canada Energy and mining demand Harsh industrial environments favor corrosion-resistant power distribution.
Mexico Automotive manufacturing Vehicle and electronics production support downstream demand.

Market instances

Rogers’ PowerCircuit platform carries currents above 100 A and is positioned between conventional PCBs and laminated busbars for EV, DC/DC converter, motor-drive and clean-energy systems. For suppliers in North America, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Data-center power architectures increasingly use busways and laminated conductors to reduce cable volume and improve power density as rack power levels rise. For suppliers in North America, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

EV battery packs and inverters create strong demand for customized coated conductors that combine electrical insulation with vibration and thermal-cycling durability. For suppliers in North America, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Full-report coverage for North America examines country-level demand, customer concentration, supplier positioning and the technical or commercial requirements that influence qualification. The regional view is designed to distinguish structural demand drivers from short-lived purchasing cycles and to show where market access depends on local manufacturing, distribution, standards, service capability or long-term customer relationships.

Europe MATURE TECHNOLOGY MARKET

What defines the Europe coated busbar market?

Europe is a mature coated-busbar market shaped by automotive electrification, rail traction, renewable-energy conversion and industrial automation. Strong safety standards and long equipment lifetimes favor suppliers able to document insulation, partial-discharge performance and thermal endurance. Supplier strategies therefore need to reflect local qualification practices, channel structure, end-market priorities and the availability of technically comparable alternatives rather than treating the region as a uniform extension of global demand.

Market positionMature technology market
Growth outlookModerate
Demand profileAutomotive, rail and renewable led
Market access gateSafety standards and lifecycle support
Country / subregion Role Demand logic
Germany Automotive and industrial hub EV powertrains and industrial converters support advanced busbar demand.
France Rail and energy demand Transport and renewable projects create high-reliability applications.
Nordic countries Renewable and grid focus High renewable penetration supports converter and grid applications.

Market instances

Rogers’ ROLINX Thermal platform is rated for operation up to 130°C, illustrating the higher-temperature requirements created by compact industrial and traction power electronics. For suppliers in Europe, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Rail and industrial converters use laminated busbars to reduce inductance and simplify assembly compared with cable harnesses, improving both switching performance and maintainability. For suppliers in Europe, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

European EV qualification cycles create durable supplier positions once coated conductor geometry, insulation and thermal cycling have been validated for a vehicle platform. For suppliers in Europe, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Full-report coverage for Europe examines country-level demand, customer concentration, supplier positioning and the technical or commercial requirements that influence qualification. The regional view is designed to distinguish structural demand drivers from short-lived purchasing cycles and to show where market access depends on local manufacturing, distribution, standards, service capability or long-term customer relationships.

South America EMERGING

What defines the South America coated busbar market?

South America is an emerging market led by Brazil, with demand tied to industrial power systems, mining, renewable energy and grid upgrades. Most advanced coated busbars are supplied through global electrical-equipment companies or specialized import channels, making landed cost and engineering support important. Supplier strategies therefore need to reflect local qualification practices, channel structure, end-market priorities and the availability of technically comparable alternatives rather than treating the region as a uniform extension of global demand.

Market positionEmerging
Growth outlookModerate
Demand profileIndustrial and renewable led
Market access gateImport cost and project timing
Country / subregion Role Demand logic
Brazil Largest regional market Industrial, grid and renewable-energy projects support demand.
Chile Mining and renewables Harsh environments create demand for corrosion-resistant power distribution.
Argentina Industrial niche Drives, switchgear and energy projects create selective demand.

Market instances

Mining equipment uses coated conductors where dust, vibration and corrosive environments make exposed high-current connections undesirable. For suppliers in South America, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Solar and wind projects increase demand for compact power-distribution assemblies inside inverters and balance-of-system equipment. For suppliers in South America, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Regional buyers often source complete power-electronic assemblies rather than bare busbars, so supplier access depends strongly on inverter and switchgear OEM channels. For suppliers in South America, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Full-report coverage for South America examines country-level demand, customer concentration, supplier positioning and the technical or commercial requirements that influence qualification. The regional view is designed to distinguish structural demand drivers from short-lived purchasing cycles and to show where market access depends on local manufacturing, distribution, standards, service capability or long-term customer relationships.

Middle East & Africa DEVELOPING

What defines the Middle East & Africa coated busbar market?

Middle East and Africa demand is growing through large infrastructure, renewable-energy, data-center and industrial projects. Gulf markets favor compact, high-reliability power-distribution systems, while African demand is concentrated in mining, utilities and urban electrification. Supplier strategies therefore need to reflect local qualification practices, channel structure, end-market priorities and the availability of technically comparable alternatives rather than treating the region as a uniform extension of global demand.

Market positionDeveloping
Growth outlookModerate-strong
Demand profileInfrastructure, energy and industrial led
Market access gateProject specification and durability
Country / subregion Role Demand logic
Saudi Arabia Infrastructure and energy demand Large industrial and data projects support high-current power systems.
United Arab Emirates Data-center and renewable demand Compact high-efficiency power distribution is increasingly important.
South Africa Mining and utility demand Industrial systems create durable high-current applications.

Market instances

Gulf data centers require high-current distribution in compact electrical rooms, creating opportunities for insulated busbars that reduce installation complexity. For suppliers in Middle East & Africa, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Solar and energy-storage projects use high-current DC paths where corrosion resistance and dielectric integrity affect long-term field performance. For suppliers in Middle East & Africa, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Mining and heavy industry create specialized demand for robust coated conductors that can withstand vibration, contamination and harsh ambient conditions. For suppliers in Middle East & Africa, the commercial implication is a stronger need to align product qualification, account coverage and inventory planning with the local demand mechanism rather than relying on broad global growth assumptions.

Full-report coverage for Middle East & Africa examines country-level demand, customer concentration, supplier positioning and the technical or commercial requirements that influence qualification. The regional view is designed to distinguish structural demand drivers from short-lived purchasing cycles and to show where market access depends on local manufacturing, distribution, standards, service capability or long-term customer relationships.

Competitive Landscape

Competition in the coated busbar market is determined by technical qualification, manufacturing consistency, customer relationships and the ability to support product lifecycles. Price matters, but it rarely overrides reliability, integration effort or switching cost once a supplier has been designed into a production platform.

The competitive field includes Rogers Corporation, Mersen, Electropak, EMS Elektro Metall Schwanenmühle, Amphenol, Methode Power Solutions, alongside other specialized suppliers. Market share can shift when a vendor gains access to a new platform, expands qualified capacity or introduces a technology that materially improves system performance. Because customer validation can be lengthy, incumbent suppliers often benefit from continuity, while challengers need a clear technical or supply-chain advantage to displace an approved source.

Competitive strategy is increasingly multi-dimensional. Leading suppliers invest in process or product development, application engineering and regional support at the same time, while customers seek second-source options where technically feasible. This creates a market in which differentiation is sustained through documented performance, manufacturing yield, quality systems, responsiveness and the ability to support future roadmap transitions without forcing unnecessary redesigns.

Company Competitive position Primary basis of competition
Rogers Corporation Established global / strategic supplier Competes through product capability, qualification, account access and supply execution.
Mersen Established global / strategic supplier Competes through product capability, qualification, account access and supply execution.
Electropak Established global / strategic supplier Competes through product capability, qualification, account access and supply execution.
EMS Elektro Metall Schwanenmühle Specialist / regional competitor Competes through product capability, qualification, account access and supply execution.
Amphenol Specialist / regional competitor Competes through product capability, qualification, account access and supply execution.
Methode Power Solutions Specialist / regional competitor Competes through product capability, qualification, account access and supply execution.
Storm Power Components Specialist / regional competitor Competes through product capability, qualification, account access and supply execution.
SVM Focused challenger / niche participant Competes through product capability, qualification, account access and supply execution.
Suzhou West Code Electrical Focused challenger / niche participant Competes through product capability, qualification, account access and supply execution.
RHI Electronic Focused challenger / niche participant Competes through product capability, qualification, account access and supply execution.
Southwire Focused challenger / niche participant Competes through product capability, qualification, account access and supply execution.

Production Capacity Analysis

Coated-busbar capacity depends on conductor rolling and forming, plating, lamination or powder coating, precision punching, welding and high-voltage inspection. Qualified output is more important than nominal metal-processing capacity because insulation defects or dimensional variation can compromise an entire power assembly.

Asia Pacific has the largest manufacturing base, while North American and European suppliers compete through engineering-intensive customized designs. Automation is increasing because high-volume EV and data-center programs require tighter repeatability than traditional industrial busbars.

Capacity should therefore be evaluated on a qualified-output basis rather than as nominal installed capability. A supplier may possess equipment or production lines that appear suitable but still require customer-specific validation, process tuning, test correlation or upstream material qualification. This distinction becomes especially important during demand spikes, when headline capacity can overstate the volume that is immediately available for a particular application, technology generation or reliability class.

Market Dynamics

The coated busbar market is being shaped by rising performance requirements and technology transitions on the demand side, while qualification complexity, supply concentration and cost discipline constrain the pace of adoption. The balance of these forces favors suppliers that can solve a measurable system problem without increasing integration risk.

Demand expansion is not uniform across all product variants or customer groups. New technology creates attractive design opportunities, but buyers typically require a clear economic or performance case before changing a qualified architecture. At the same time, supply-chain localization, capacity investment and tighter quality requirements are changing procurement behavior. As a result, growth is likely to concentrate around applications where performance upgrades, manufacturing scale and lifecycle value reinforce one another.

Market Drivers

Four forces provide the strongest support for demand in the coated busbar market: performance-driven technology upgrades, expansion of relevant downstream applications, investment in manufacturing or infrastructure, and the need for more resilient supply. Their importance varies by segment, but each creates a direct reason for customers to qualify or purchase additional solutions.

Driver Impact Commercial mechanism
Vehicle electrification increases compact high-current distribution High EV batteries, inverters and chargers need low-inductance conductors that fit constrained packaging and tolerate thermal cycling.
Data centers raise power density High Higher rack power and AI infrastructure increase current levels, favoring compact busbar-based distribution over large cable bundles.
Renewable-energy conversion expands inverter demand Medium-High Solar, wind and storage systems use high-current DC and AC connections where coating improves safety and corrosion resistance.
Wide-bandgap semiconductors increase switching performance Medium-High SiC and GaN devices switch faster and at higher power density, increasing the value of low-inductance busbar layouts and heat-resistant insulation.

Vehicle electrification increases compact high-current distribution

EV batteries, inverters and chargers need low-inductance conductors that fit constrained packaging and tolerate thermal cycling. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.

Data centers raise power density

Higher rack power and AI infrastructure increase current levels, favoring compact busbar-based distribution over large cable bundles. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.

Renewable-energy conversion expands inverter demand

Solar, wind and storage systems use high-current DC and AC connections where coating improves safety and corrosion resistance. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.

Wide-bandgap semiconductors increase switching performance

SiC and GaN devices switch faster and at higher power density, increasing the value of low-inductance busbar layouts and heat-resistant insulation. The commercial effect is strongest where customers can link the technology change to higher throughput, lower power, improved reliability, reduced lifecycle cost or access to a new end-market requirement.

Market Restraints

Growth is moderated by qualification burden, cyclical purchasing, technology substitution and supply-chain risk. These restraints do not eliminate demand, but they can extend sales cycles, limit supplier switching and reduce the speed at which technically superior solutions convert into production revenue.

Restraint Impact Commercial consequence
Copper price volatility pressures margins High Raw conductor cost can represent a large share of total busbar cost, making pricing sensitive to commodity cycles.
Custom designs reduce interchangeability High Busbars are often shaped for a specific converter or battery layout, limiting reuse across customer programs.
Coating defects can create critical reliability failures Medium Pinholes, delamination or poor edge coverage can reduce dielectric strength and trigger partial discharge or corrosion.
Specialized tooling raises entry barriers Medium Lamination, powder coating, plating, forming and high-voltage test equipment require significant capital and process expertise.

Copper price volatility pressures margins

Raw conductor cost can represent a large share of total busbar cost, making pricing sensitive to commodity cycles. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.

Custom designs reduce interchangeability

Busbars are often shaped for a specific converter or battery layout, limiting reuse across customer programs. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.

Coating defects can create critical reliability failures

Pinholes, delamination or poor edge coverage can reduce dielectric strength and trigger partial discharge or corrosion. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.

Specialized tooling raises entry barriers

Lamination, powder coating, plating, forming and high-voltage test equipment require significant capital and process expertise. Suppliers can mitigate part of this pressure through stronger qualification support, transparent lifecycle planning, dual-source strategies and better alignment between product roadmaps and customer production schedules.

Market Opportunities

The most attractive opportunities in the coated busbar market occur where a technology transition creates measurable value and where suppliers can enter before the customer architecture is locked. Early engagement, application-specific engineering and credible supply planning can convert these windows into durable design positions.

800V EV powertrains

Higher vehicle voltage raises insulation and partial-discharge requirements, increasing value per busbar assembly. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.

AI data-center power systems

High-current busbars can reduce cabling volume and improve power-distribution density inside racks and power shelves. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.

Integrated busbar-capacitor assemblies

Combining DC-link capacitors and busbars reduces inductance, assembly steps and system footprint. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.

High-temperature coatings

Insulation capable of operating above conventional temperature limits supports compact SiC-based converters and harsh industrial systems. The opportunity is strongest for suppliers that can demonstrate performance with production-relevant data, provide engineering support during qualification and maintain a roadmap that gives customers confidence in long-term availability.

Supply Chain Analysis

Stage 1
Copper, aluminum and coating materials
Stage 2
Busbar forming and insulation
Stage 3
Electrical and mechanical validation
Stage 4
Power-system integration

Copper, aluminum and coating materials

Conductive metal, dielectric films, polymers, plating metals and adhesives determine electrical and environmental performance. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.

Busbar forming and insulation

Conductors are punched, bent, welded and coated or laminated to customer-specific geometry. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.

Electrical and mechanical validation

Manufacturers test insulation resistance, partial discharge, current capacity, temperature rise and dimensional tolerances. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.

Power-system integration

Finished busbars are installed in switchgear, batteries, inverters, data centers, rail systems and renewable-energy equipment. Value capture at this stage depends on quality consistency, technical differentiation and the difficulty of substitution. Bottlenecks can propagate downstream when qualification or material compatibility prevents customers from shifting quickly to an alternative supplier.

Recent Developments

Recent developments show how technology roadmaps, manufacturing investment and standards are changing the competitive requirements of the coated busbar market. The entries below are selected for their direct relevance to product capability, capacity, qualification or downstream adoption rather than for general corporate activity.

2026 · Rogers Corporation

Rogers continues to market ROLINX busbars as a full range of laminated and powder-coated solutions for EV/HEV, renewable energy, rail, industrial drives and data servers. The portfolio emphasizes low inductance, high current capability and compact integration. Source

2026 · Rogers Corporation

Rogers’ ROLINX Compact uses epoxy powder coating as outer insulation to create tighter power-distribution assemblies where installation space is limited. The design directly addresses the market shift toward compact high-power converters. Source

2026 · Rogers Corporation

Rogers’ ROLINX Thermal platform supports working temperatures up to 130°C, expanding coated-busbar applicability in traction, clean-energy and industrial converters that operate at elevated power density. Source

Report Scope & Segmentation

Report attribute Coverage
Market Coated Busbar
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
2025 Market Size USD 3.45 billion
2026 Estimated Size USD 3.60 billion
2034 Forecast Size USD 5.04 billion
CAGR (2026–2034) 4.3%
Largest Market in 2025 Asia Pacific
By Type Copper Conductor, Aluminum Conductor
By Application Switchgear, Smart Grid, Energy, Power Supply, Communication Connection, Others
By End User Utilities, Industrial, Commercial Buildings
By Coating Type Polymer Insulation, Anti-Corrosion, Heat Dissipation
By Voltage Rating Low Voltage, Medium Voltage, High Voltage
Companies Profiled Rogers Corporation, Mersen, Electropak, EMS Elektro Metall Schwanenmühle, Amphenol, Methode Power Solutions, Storm Power Components, SVM, Suzhou West Code Electrical, RHI Electronic, Southwire

Frequently Asked Questions

What was the coated busbar market size in 2025?

The global coated busbar market was valued at USD 3.45 billion in 2025. The 2025 value is the base-year reference used throughout this overview and provides the starting point for comparing the 2026 estimate and the 2034 forecast.

What is the projected coated busbar market size in 2034?

The global market is projected to reach USD 5.04 billion by 2034. The forecast reflects the interaction of downstream adoption, technology transitions, production investment and the qualification requirements that shape commercial conversion across the market.

What is the CAGR of the coated busbar market from 2026 to 2034?

The coated busbar market is expected to expand at a 4.3% CAGR during 2026–2034. Growth will not be uniform across every product or region because customer qualification, capital cycles, supply constraints and application-specific performance requirements differ materially.

Which region is the largest coated busbar market?

Asia Pacific is the largest regional market in 2025. Its position is supported by the concentration of relevant manufacturing, customers, technology ecosystems and downstream demand, although the precise commercial mechanism differs by country and application.

How is the coated busbar market segmented by type?

By type, the market is segmented into Copper Conductor, Aluminum Conductor. These categories address different performance, cost and integration requirements, so supplier selection depends on application fit, qualification history and lifecycle economics rather than a single specification.

What are the main applications for coated busbar?

By application, the market covers Switchgear, Smart Grid, Energy, Power Supply, Communication Connection, Others. Demand in each application is linked to platform launches, capacity expansion, equipment replacement and the degree to which the technology improves system performance or manufacturing economics.

What are the principal growth drivers for the coated busbar market?

Key drivers include vehicle electrification increases compact high-current distribution and data centers raise power density. These forces increase demand when customers can translate technical improvements into higher performance, lower cost, greater reliability or access to new applications.

What are the main restraints in the coated busbar market?

Important restraints include copper price volatility pressures margins and custom designs reduce interchangeability. The resulting qualification burden, purchasing cyclicality and technology risk can extend sales cycles and limit rapid supplier substitution even when new solutions offer clear technical advantages.

Which companies participate in the coated busbar market?

Companies profiled in this market include Rogers Corporation, Mersen, Electropak, EMS Elektro Metall Schwanenmühle, Amphenol, Methode Power Solutions, Storm Power Components, SVM. Competition centers on qualification, product or process performance, manufacturing consistency, customer support and the ability to maintain supply across the required product lifecycle.

What should buyers evaluate when selecting a coated busbar supplier?

Buyers should evaluate demonstrated performance, qualification history, manufacturing consistency, lifecycle support, supply resilience and integration cost. A technically strong product can still face adoption barriers if it increases redesign risk, lacks regional support or cannot meet the customer’s production and quality requirements.

Research Sources & Evidence Base

View research sources used for this overview.
  1. Rogers Corporation. ROLINX Busbars — Laminated and powder-coated busbar technologies, applications and performance characteristics.
  2. Rogers Corporation. ROLINX Performance — High-voltage and high-current laminated busbar performance specifications.
  3. Rogers Corporation. ROLINX PowerCircuit — Busbar/PCB hybrid architecture for EV, converters and industrial systems.
  4. Rogers Corporation. ROLINX Thermal — High-temperature laminated busbar technology for traction and clean-energy applications.
Coated Busbar Market Size, Share & Industry Analysis, By Type (Copper Conductor, Aluminum Conductor), By Application (Switchgear, Smart Grid, Energy, Power Supply, Communication Connection, Others), By End User (Utilities, Industrial, Commercial Buildings), By Coating Type (Polymer Insulation, Anti-Corrosion, Heat Dissipation), By Voltage Rating (Low Voltage, Medium Voltage, High Voltage), and Regional Forecast, 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF
SKU: 050a412b9998
Category:
License Type

Corporate License, Excel License, PDF and Excel Databook License

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Coated Busbar Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Coated Busbar Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Coated Busbar Overall Market Size
2.1 Global Coated Busbar Market Size: 2025 VS 2034
2.2 Global Coated Busbar Market Size, Prospects & Forecasts: 2026-2034
2.3 Global Coated Busbar Sales: 2026-2034
3 Company Landscape
3.1 Top Coated Busbar Players in Global Market
3.2 Top Global Coated Busbar Companies Ranked by Revenue
3.3 Global Coated Busbar Revenue by Companies
3.4 Global Coated Busbar Sales by Companies
3.5 Global Coated Busbar Price by Manufacturer (2020-2026)
3.6 Top 3 and Top 5 Coated Busbar Companies in Global Market, by Revenue in 2025
3.7 Global Manufacturers Coated Busbar Product Type
3.8 Tier 1, Tier 2, and Tier 3 Coated Busbar Players in Global Market
3.8.1 List of Global Tier 1 Coated Busbar Companies
3.8.2 List of Global Tier 2 and Tier 3 Coated Busbar Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global Coated Busbar Market Size Markets, 2025 & 2034
4.1.2 Copper Conductor
4.1.3 Aluminum Conductor
4.2 Segment by Type – Global Coated Busbar Revenue & Forecasts
4.2.1 Segment by Type – Global Coated Busbar Revenue, 2020-2026
4.2.2 Segment by Type – Global Coated Busbar Revenue, 2026-2034
4.2.3 Segment by Type – Global Coated Busbar Revenue Market Share, 2026-2034
4.3 Segment by Type – Global Coated Busbar Sales & Forecasts
4.3.1 Segment by Type – Global Coated Busbar Sales, 2020-2026
4.3.2 Segment by Type – Global Coated Busbar Sales, 2026-2034
4.3.3 Segment by Type – Global Coated Busbar Sales Market Share, 2026-2034
4.4 Segment by Type – Global Coated Busbar Price (Manufacturers Selling Prices), 2026-2034
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global Coated Busbar Market Size, 2025 & 2034
5.1.2 Switchgear
5.1.3 Smart Grid
5.1.4 Energy
5.1.5 Power Supply
5.1.6 Communication Connection
5.1.7 Others
5.2 Segment by Application – Global Coated Busbar Revenue & Forecasts
5.2.1 Segment by Application – Global Coated Busbar Revenue, 2020-2026
5.2.2 Segment by Application – Global Coated Busbar Revenue, 2026-2034
5.2.3 Segment by Application – Global Coated Busbar Revenue Market Share, 2026-2034
5.3 Segment by Application – Global Coated Busbar Sales & Forecasts
5.3.1 Segment by Application – Global Coated Busbar Sales, 2020-2026
5.3.2 Segment by Application – Global Coated Busbar Sales, 2026-2034
5.3.3 Segment by Application – Global Coated Busbar Sales Market Share, 2026-2034
5.4 Segment by Application – Global Coated Busbar Price (Manufacturers Selling Prices), 2026-2034
6 Sights by Region
6.1 By Region – Global Coated Busbar Market Size, 2025 & 2034
6.2 By Region – Global Coated Busbar Revenue & Forecasts
6.2.1 By Region – Global Coated Busbar Revenue, 2020-2026
6.2.2 By Region – Global Coated Busbar Revenue, 2026-2034
6.2.3 By Region – Global Coated Busbar Revenue Market Share, 2026-2034
6.3 By Region – Global Coated Busbar Sales & Forecasts
6.3.1 By Region – Global Coated Busbar Sales, 2020-2026
6.3.2 By Region – Global Coated Busbar Sales, 2026-2034
6.3.3 By Region – Global Coated Busbar Sales Market Share, 2026-2034
6.4 North America
6.4.1 By Country – North America Coated Busbar Revenue, 2026-2034
6.4.2 By Country – North America Coated Busbar Sales, 2026-2034
6.4.3 United States Coated Busbar Market Size, 2026-2034
6.4.4 Canada Coated Busbar Market Size, 2026-2034
6.4.5 Mexico Coated Busbar Market Size, 2026-2034
6.5 Europe
6.5.1 By Country – Europe Coated Busbar Revenue, 2026-2034
6.5.2 By Country – Europe Coated Busbar Sales, 2026-2034
6.5.3 Germany Coated Busbar Market Size, 2026-2034
6.5.4 France Coated Busbar Market Size, 2026-2034
6.5.5 U.K. Coated Busbar Market Size, 2026-2034
6.5.6 Italy Coated Busbar Market Size, 2026-2034
6.5.7 Russia Coated Busbar Market Size, 2026-2034
6.5.8 Nordic Countries Coated Busbar Market Size, 2026-2034
6.5.9 Benelux Coated Busbar Market Size, 2026-2034
6.6 Asia
6.6.1 By Region – Asia Coated Busbar Revenue, 2026-2034
6.6.2 By Region – Asia Coated Busbar Sales, 2026-2034
6.6.3 China Coated Busbar Market Size, 2026-2034
6.6.4 Japan Coated Busbar Market Size, 2026-2034
6.6.5 South Korea Coated Busbar Market Size, 2026-2034
6.6.6 Southeast Asia Coated Busbar Market Size, 2026-2034
6.6.7 India Coated Busbar Market Size, 2026-2034
6.7 South America
6.7.1 By Country – South America Coated Busbar Revenue, 2026-2034
6.7.2 By Country – South America Coated Busbar Sales, 2026-2034
6.7.3 Brazil Coated Busbar Market Size, 2026-2034
6.7.4 Argentina Coated Busbar Market Size, 2026-2034
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa Coated Busbar Revenue, 2026-2034
6.8.2 By Country – Middle East & Africa Coated Busbar Sales, 2026-2034
6.8.3 Turkey Coated Busbar Market Size, 2026-2034
6.8.4 Israel Coated Busbar Market Size, 2026-2034
6.8.5 Saudi Arabia Coated Busbar Market Size, 2026-2034
6.8.6 UAE Coated Busbar Market Size, 2026-2034
7 Manufacturers & Brands Profiles
7.1 Rogers Corporation
7.1.1 Rogers Corporation Company Summary
7.1.2 Rogers Corporation Business Overview
7.1.3 Rogers Corporation Coated Busbar Major Product Offerings
7.1.4 Rogers Corporation Coated Busbar Sales and Revenue in Global (2020-2026)
7.1.5 Rogers Corporation Key News & Latest Developments
7.2 Mersen
7.2.1 Mersen Company Summary
7.2.2 Mersen Business Overview
7.2.3 Mersen Coated Busbar Major Product Offerings
7.2.4 Mersen Coated Busbar Sales and Revenue in Global (2020-2026)
7.2.5 Mersen Key News & Latest Developments
7.3 Electropak
7.3.1 Electropak Company Summary
7.3.2 Electropak Business Overview
7.3.3 Electropak Coated Busbar Major Product Offerings
7.3.4 Electropak Coated Busbar Sales and Revenue in Global (2020-2026)
7.3.5 Electropak Key News & Latest Developments
7.4 EMS Elektro Metall Schwanenmühle GmbH
7.4.1 EMS Elektro Metall Schwanenmühle GmbH Company Summary
7.4.2 EMS Elektro Metall Schwanenmühle GmbH Business Overview
7.4.3 EMS Elektro Metall Schwanenmühle GmbH Coated Busbar Major Product Offerings
7.4.4 EMS Elektro Metall Schwanenmühle GmbH Coated Busbar Sales and Revenue in Global (2020-2026)
7.4.5 EMS Elektro Metall Schwanenmühle GmbH Key News & Latest Developments
7.5 Amphenol
7.5.1 Amphenol Company Summary
7.5.2 Amphenol Business Overview
7.5.3 Amphenol Coated Busbar Major Product Offerings
7.5.4 Amphenol Coated Busbar Sales and Revenue in Global (2020-2026)
7.5.5 Amphenol Key News & Latest Developments
7.6 Methode Power Solutions
7.6.1 Methode Power Solutions Company Summary
7.6.2 Methode Power Solutions Business Overview
7.6.3 Methode Power Solutions Coated Busbar Major Product Offerings
7.6.4 Methode Power Solutions Coated Busbar Sales and Revenue in Global (2020-2026)
7.6.5 Methode Power Solutions Key News & Latest Developments
7.7 Storm Power Components
7.7.1 Storm Power Components Company Summary
7.7.2 Storm Power Components Business Overview
7.7.3 Storm Power Components Coated Busbar Major Product Offerings
7.7.4 Storm Power Components Coated Busbar Sales and Revenue in Global (2020-2026)
7.7.5 Storm Power Components Key News & Latest Developments
7.8 SVM
7.8.1 SVM Company Summary
7.8.2 SVM Business Overview
7.8.3 SVM Coated Busbar Major Product Offerings
7.8.4 SVM Coated Busbar Sales and Revenue in Global (2020-2026)
7.8.5 SVM Key News & Latest Developments
7.9 Suzhou West Code Electrical
7.9.1 Suzhou West Code Electrical Company Summary
7.9.2 Suzhou West Code Electrical Business Overview
7.9.3 Suzhou West Code Electrical Coated Busbar Major Product Offerings
7.9.4 Suzhou West Code Electrical Coated Busbar Sales and Revenue in Global (2020-2026)
7.9.5 Suzhou West Code Electrical Key News & Latest Developments
7.10 RHI Electronic
7.10.1 RHI Electronic Company Summary
7.10.2 RHI Electronic Business Overview
7.10.3 RHI Electronic Coated Busbar Major Product Offerings
7.10.4 RHI Electronic Coated Busbar Sales and Revenue in Global (2020-2026)
7.10.5 RHI Electronic Key News & Latest Developments
7.11 Suzhou Nicola Corrent Power Technology
7.11.1 Suzhou Nicola Corrent Power Technology Company Summary
7.11.2 Suzhou Nicola Corrent Power Technology Business Overview
7.11.3 Suzhou Nicola Corrent Power Technology Coated Busbar Major Product Offerings
7.11.4 Suzhou Nicola Corrent Power Technology Coated Busbar Sales and Revenue in Global (2020-2026)
7.11.5 Suzhou Nicola Corrent Power Technology Key News & Latest Developments
8 Global Coated Busbar Production Capacity, Analysis
8.1 Global Coated Busbar Production Capacity, 2026-2034
8.2 Coated Busbar Production Capacity of Key Manufacturers in Global Market
8.3 Global Coated Busbar Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 Coated Busbar Supply Chain Analysis
10.1 Coated Busbar Industry Value Chain
10.2 Coated Busbar Upstream Market
10.3 Coated Busbar Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 Coated Busbar Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of Coated Busbar in Global Market
Table 2. Top Coated Busbar Players in Global Market, Ranking by Revenue (2025)
Table 3. Global Coated Busbar Revenue by Companies, (US$, Mn), 2020-2026
Table 4. Global Coated Busbar Revenue Share by Companies, 2020-2026
Table 5. Global Coated Busbar Sales by Companies, (K Units), 2020-2026
Table 6. Global Coated Busbar Sales Share by Companies, 2020-2026
Table 7. Key Manufacturers Coated Busbar Price (2020-2026) & (US$/Unit)
Table 8. Global Manufacturers Coated Busbar Product Type
Table 9. List of Global Tier 1 Coated Busbar Companies, Revenue (US$, Mn) in 2025 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Coated Busbar Companies, Revenue (US$, Mn) in 2025 and Market Share
Table 11. Segment by Type – Global Coated Busbar Revenue, (US$, Mn), 2025 & 2034
Table 12. Segment by Type – Global Coated Busbar Revenue (US$, Mn), 2020-2026
Table 13. Segment by Type – Global Coated Busbar Revenue (US$, Mn), 2026-2034
Table 14. Segment by Type – Global Coated Busbar Sales (K Units), 2020-2026
Table 15. Segment by Type – Global Coated Busbar Sales (K Units), 2026-2034
Table 16. Segment by Application – Global Coated Busbar Revenue, (US$, Mn), 2025 & 2034
Table 17. Segment by Application – Global Coated Busbar Revenue, (US$, Mn), 2020-2026
Table 18. Segment by Application – Global Coated Busbar Revenue, (US$, Mn), 2026-2034
Table 19. Segment by Application – Global Coated Busbar Sales, (K Units), 2020-2026
Table 20. Segment by Application – Global Coated Busbar Sales, (K Units), 2026-2034
Table 21. By Region – Global Coated Busbar Revenue, (US$, Mn), 2026-2034
Table 22. By Region – Global Coated Busbar Revenue, (US$, Mn), 2020-2026
Table 23. By Region – Global Coated Busbar Revenue, (US$, Mn), 2026-2034
Table 24. By Region – Global Coated Busbar Sales, (K Units), 2020-2026
Table 25. By Region – Global Coated Busbar Sales, (K Units), 2026-2034
Table 26. By Country – North America Coated Busbar Revenue, (US$, Mn), 2020-2026
Table 27. By Country – North America Coated Busbar Revenue, (US$, Mn), 2026-2034
Table 28. By Country – North America Coated Busbar Sales, (K Units), 2020-2026
Table 29. By Country – North America Coated Busbar Sales, (K Units), 2026-2034
Table 30. By Country – Europe Coated Busbar Revenue, (US$, Mn), 2020-2026
Table 31. By Country – Europe Coated Busbar Revenue, (US$, Mn), 2026-2034
Table 32. By Country – Europe Coated Busbar Sales, (K Units), 2020-2026
Table 33. By Country – Europe Coated Busbar Sales, (K Units), 2026-2034
Table 34. By Region – Asia Coated Busbar Revenue, (US$, Mn), 2020-2026
Table 35. By Region – Asia Coated Busbar Revenue, (US$, Mn), 2026-2034
Table 36. By Region – Asia Coated Busbar Sales, (K Units), 2020-2026
Table 37. By Region – Asia Coated Busbar Sales, (K Units), 2026-2034
Table 38. By Country – South America Coated Busbar Revenue, (US$, Mn), 2020-2026
Table 39. By Country – South America Coated Busbar Revenue, (US$, Mn), 2026-2034
Table 40. By Country – South America Coated Busbar Sales, (K Units), 2020-2026
Table 41. By Country – South America Coated Busbar Sales, (K Units), 2026-2034
Table 42. By Country – Middle East & Africa Coated Busbar Revenue, (US$, Mn), 2020-2026
Table 43. By Country – Middle East & Africa Coated Busbar Revenue, (US$, Mn), 2026-2034
Table 44. By Country – Middle East & Africa Coated Busbar Sales, (K Units), 2020-2026
Table 45. By Country – Middle East & Africa Coated Busbar Sales, (K Units), 2026-2034
Table 46. Rogers Corporation Company Summary
Table 47. Rogers Corporation Coated Busbar Product Offerings
Table 48. Rogers Corporation Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 49. Rogers Corporation Key News & Latest Developments
Table 50. Mersen Company Summary
Table 51. Mersen Coated Busbar Product Offerings
Table 52. Mersen Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 53. Mersen Key News & Latest Developments
Table 54. Electropak Company Summary
Table 55. Electropak Coated Busbar Product Offerings
Table 56. Electropak Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 57. Electropak Key News & Latest Developments
Table 58. EMS Elektro Metall Schwanenmühle GmbH Company Summary
Table 59. EMS Elektro Metall Schwanenmühle GmbH Coated Busbar Product Offerings
Table 60. EMS Elektro Metall Schwanenmühle GmbH Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 61. EMS Elektro Metall Schwanenmühle GmbH Key News & Latest Developments
Table 62. Amphenol Company Summary
Table 63. Amphenol Coated Busbar Product Offerings
Table 64. Amphenol Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 65. Amphenol Key News & Latest Developments
Table 66. Methode Power Solutions Company Summary
Table 67. Methode Power Solutions Coated Busbar Product Offerings
Table 68. Methode Power Solutions Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 69. Methode Power Solutions Key News & Latest Developments
Table 70. Storm Power Components Company Summary
Table 71. Storm Power Components Coated Busbar Product Offerings
Table 72. Storm Power Components Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 73. Storm Power Components Key News & Latest Developments
Table 74. SVM Company Summary
Table 75. SVM Coated Busbar Product Offerings
Table 76. SVM Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 77. SVM Key News & Latest Developments
Table 78. Suzhou West Code Electrical Company Summary
Table 79. Suzhou West Code Electrical Coated Busbar Product Offerings
Table 80. Suzhou West Code Electrical Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 81. Suzhou West Code Electrical Key News & Latest Developments
Table 82. RHI Electronic Company Summary
Table 83. RHI Electronic Coated Busbar Product Offerings
Table 84. RHI Electronic Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 85. RHI Electronic Key News & Latest Developments
Table 86. Suzhou Nicola Corrent Power Technology Company Summary
Table 87. Suzhou Nicola Corrent Power Technology Coated Busbar Product Offerings
Table 88. Suzhou Nicola Corrent Power Technology Coated Busbar Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2026)
Table 89. Suzhou Nicola Corrent Power Technology Key News & Latest Developments
Table 90. Coated Busbar Capacity of Key Manufacturers in Global Market, 2023-2026 (K Units)
Table 91. Global Coated Busbar Capacity Market Share of Key Manufacturers, 2023-2026
Table 92. Global Coated Busbar Production by Region, 2020-2026 (K Units)
Table 93. Global Coated Busbar Production by Region, 2026-2034 (K Units)
Table 94. Coated Busbar Market Opportunities & Trends in Global Market
Table 95. Coated Busbar Market Drivers in Global Market
Table 96. Coated Busbar Market Restraints in Global Market
Table 97. Coated Busbar Raw Materials
Table 98. Coated Busbar Raw Materials Suppliers in Global Market
Table 99. Typical Coated Busbar Downstream
Table 100. Coated Busbar Downstream Clients in Global Market
Table 101. Coated Busbar Distributors and Sales Agents in Global Market

List of Figures
Figure 1. Coated Busbar Product Picture
Figure 2. Coated Busbar Segment by Type in 2025
Figure 3. Coated Busbar Segment by Application in 2025
Figure 4. Global Coated Busbar Market Overview: 2025
Figure 5. Key Caveats
Figure 6. Global Coated Busbar Market Size: 2025 VS 2034 (US$, Mn)
Figure 7. Global Coated Busbar Revenue: 2026-2034 (US$, Mn)
Figure 8. Coated Busbar Sales in Global Market: 2026-2034 (K Units)
Figure 9. The Top 3 and 5 Players Market Share by Coated Busbar Revenue in 2025
Figure 10. Segment by Type – Global Coated Busbar Revenue, (US$, Mn), 2025 & 2034
Figure 11. Segment by Type – Global Coated Busbar Revenue Market Share, 2026-2034
Figure 12. Segment by Type – Global Coated Busbar Sales Market Share, 2026-2034
Figure 13. Segment by Type – Global Coated Busbar Price (US$/Unit), 2026-2034
Figure 14. Segment by Application – Global Coated Busbar Revenue, (US$, Mn), 2025 & 2034
Figure 15. Segment by Application – Global Coated Busbar Revenue Market Share, 2026-2034
Figure 16. Segment by Application – Global Coated Busbar Sales Market Share, 2026-2034
Figure 17. Segment by Application -Global Coated Busbar Price (US$/Unit), 2026-2034
Figure 18. By Region – Global Coated Busbar Revenue, (US$, Mn), 2026 & 2034
Figure 19. By Region – Global Coated Busbar Revenue Market Share, 2020 VS 2025 VS 2034
Figure 20. By Region – Global Coated Busbar Revenue Market Share, 2026-2034
Figure 21. By Region – Global Coated Busbar Sales Market Share, 2026-2034
Figure 22. By Country – North America Coated Busbar Revenue Market Share, 2026-2034
Figure 23. By Country – North America Coated Busbar Sales Market Share, 2026-2034
Figure 24. United States Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 25. Canada Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 26. Mexico Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 27. By Country – Europe Coated Busbar Revenue Market Share, 2026-2034
Figure 28. By Country – Europe Coated Busbar Sales Market Share, 2026-2034
Figure 29. Germany Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 30. France Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 31. U.K. Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 32. Italy Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 33. Russia Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 34. Nordic Countries Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 35. Benelux Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 36. By Region – Asia Coated Busbar Revenue Market Share, 2026-2034
Figure 37. By Region – Asia Coated Busbar Sales Market Share, 2026-2034
Figure 38. China Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 39. Japan Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 40. South Korea Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 41. Southeast Asia Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 42. India Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 43. By Country – South America Coated Busbar Revenue Market Share, 2026-2034
Figure 44. By Country – South America Coated Busbar Sales, Market Share, 2026-2034
Figure 45. Brazil Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 46. Argentina Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 47. By Country – Middle East & Africa Coated Busbar Revenue, Market Share, 2026-2034
Figure 48. By Country – Middle East & Africa Coated Busbar Sales, Market Share, 2026-2034
Figure 49. Turkey Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 50. Israel Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 51. Saudi Arabia Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 52. UAE Coated Busbar Revenue, (US$, Mn), 2026-2034
Figure 53. Global Coated Busbar Production Capacity (K Units), 2026-2034
Figure 54. The Percentage of Production Coated Busbar by Region, 2025 VS 2034
Figure 55. Coated Busbar Industry Value Chain
Figure 56. Marketing Channels