SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Automotive Center Stack Display (CSD) Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
DISPLAY AND VISUALIZATION Semiconductor Market Research

Automotive Center Stack Display (CSD) Market

Trends, Business Strategies 2026-2034

◷
UPDATED 23 September 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 3fed55b5487e
▯
FORMATS PDF

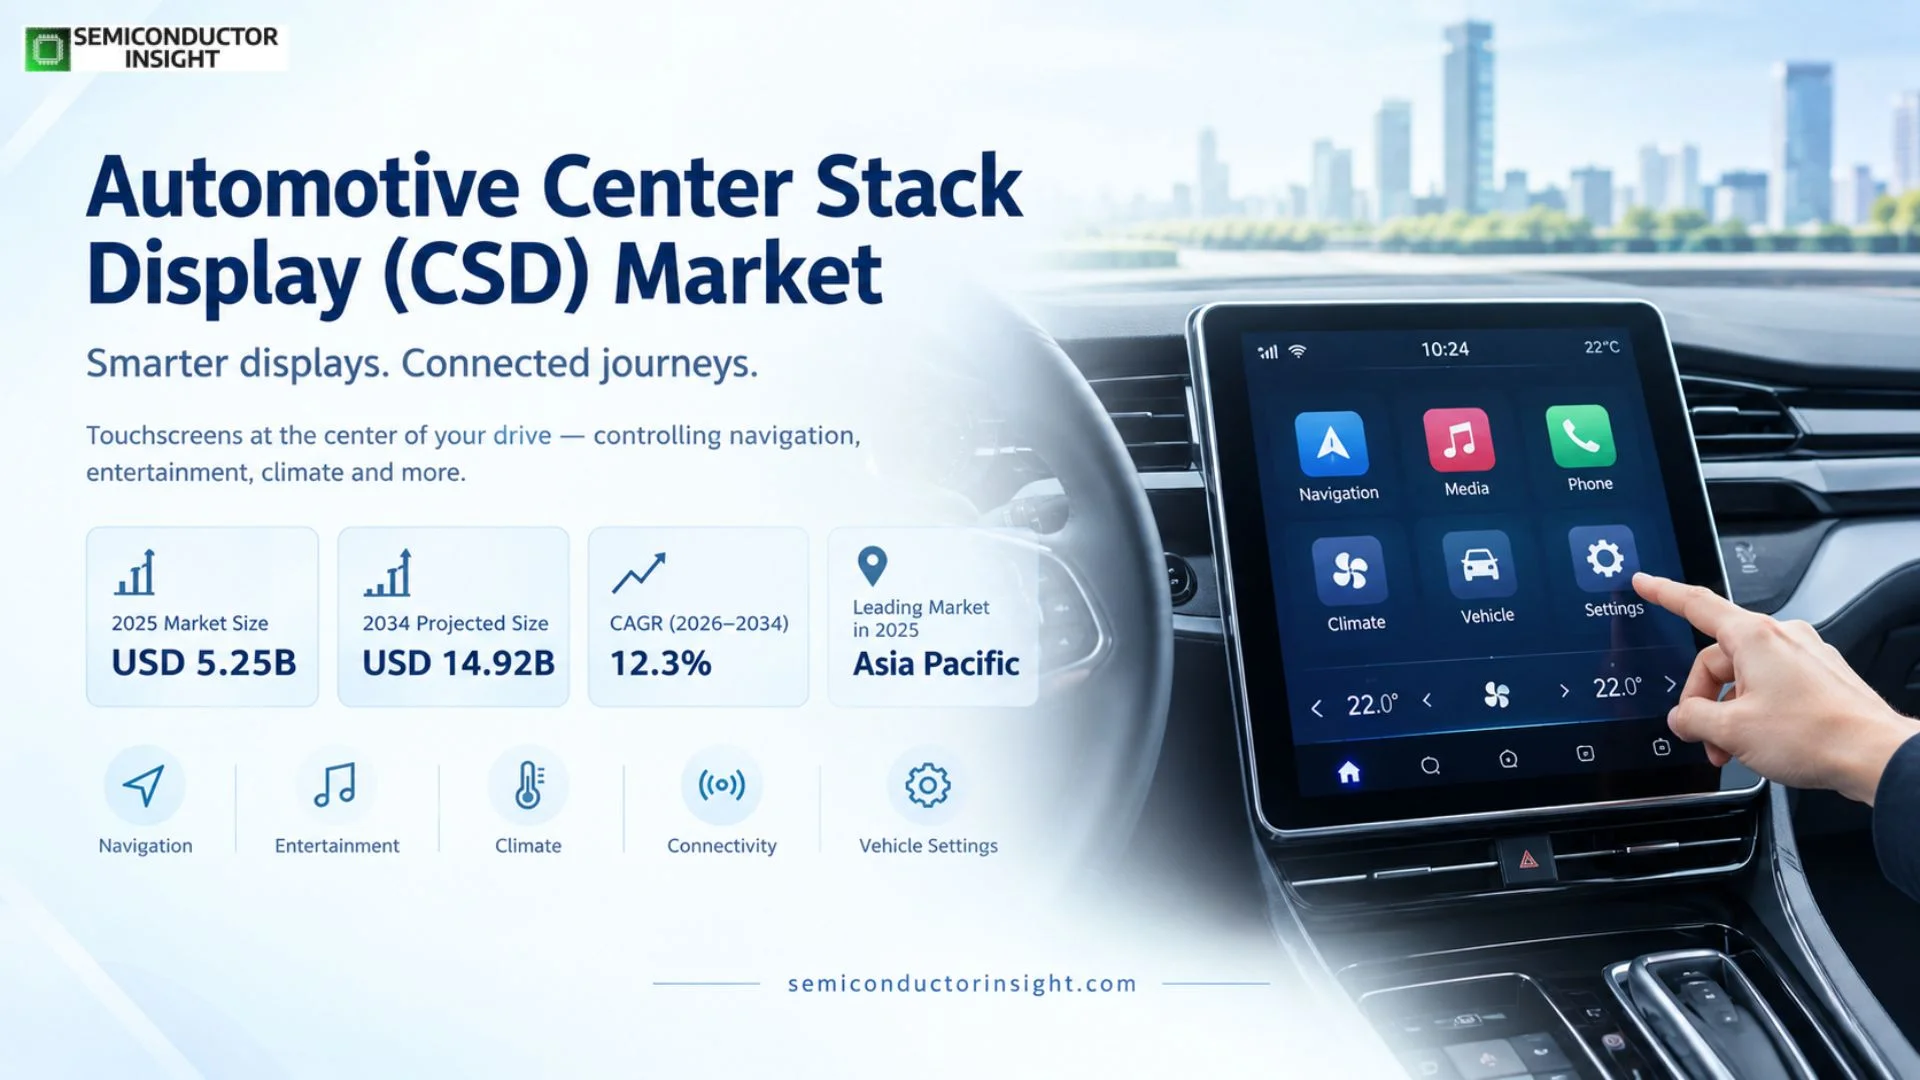
Automotive Center Stack Display (CSD) market is projected to reach USD 14.92 billion by 2034, representing a 12.3% CAGR during 2026–2034. The 2026 estimated market size is USD 5.89 billion. Asia Pacific is the leading regional market, supported by high vehicle production, rapid EV adoption and a dense automotive-display supply chain.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 5.25 billion
2034 Projected Size
USD 14.92 billion
CAGR (2026–2034)
12.3%
Largest Market in 2025
Asia Pacific

Key Takeaways

  • LCD remains the largest installed display technology because of cost, automotive qualification maturity and broad availability, while OLED is the fastest-moving premium technology.
  • Passenger cars dominate application demand, with electric and software-defined vehicles accelerating larger, integrated center displays and multi-screen cockpit architectures.
  • The 7–10 inch range remains the largest mainstream display-size band, but screens above 10 inches are gaining value share through premium vehicles, EVs and wide integrated dashboards.
  • Asia Pacific is the leading regional market through the scale of vehicle production in China, Japan, South Korea and India and the concentration of major automotive display suppliers.
  • 2026 innovation is moving beyond a single center screen. LG Display, Tianma, Visteon, Hyundai Mobis and Bosch are commercializing pillar-to-pillar displays, multi-screen domain controllers, slidable OLED and AI-enabled cockpit systems.

Automotive Center Stack Display (CSD) Market Overview

Automotive Center Stack Display (CSD) market is valued at USD 5.25 billion in 2025 and is projected to reach USD 14.92 billion by 2034, representing a 12.3% CAGR during 2026–2034. The 2026 estimated market size is USD 5.89 billion. Asia Pacific is the leading regional market, supported by high vehicle production, rapid EV adoption and a dense automotive-display supply chain.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Historical data: 2020–2025 · Values in USD

Center stack displays are the primary touchscreen interfaces in the central dashboard area of modern vehicles. They combine display panels, touch sensors, cover glass, optical bonding, display electronics and software interfaces to control navigation, entertainment, climate, connectivity and increasingly vehicle settings. The hardware is becoming part of a broader cockpit domain rather than a standalone infotainment screen.

Automotive displays must meet requirements that differ sharply from consumer tablets. Bright sunlight readability, low reflectance, wide temperature operation, vibration resistance, long product life, automotive EMC, touch performance with gloves or moisture and functional-safety considerations all influence product design and qualification.

Display architecture is also evolving from separate cluster and center screens toward integrated multi-display systems. OEMs are adopting panoramic and pillar-to-pillar concepts, privacy-controlled passenger zones, driver-monitoring integration and centralized cockpit computing. This transition increases the software, thermal and optical value of each installed display system.

Segment Analysis: By Type

By display technology, the market is segmented into LCD, OLED and Other Technologies. LCD remains the largest segment because TFT-LCD and IPS-LCD provide proven automotive reliability and competitive cost, while OLED is gaining share in premium and flexible cockpit designs.

Display technology Technical profile Market position
LCD TFT-LCD and IPS-LCD support high brightness, wide viewing angles and mature automotive qualification. Advanced backlights, local dimming and oxide or LTPS backplanes extend performance into larger integrated cockpits. Largest current segment. Broad supplier capacity and proven reliability make LCD the mainstream choice from value vehicles through premium systems.
OLED Self-emissive OLED delivers deep black, fast response, thinner form factors and flexible or curved geometries. Tandem and P-OLED architectures improve brightness, lifetime and durability for automotive use. Fast-growing premium segment. OLED is expanding in center displays, integrated dashboards and slidable or curved concepts.
Other / Emerging Includes MicroLED, transparent displays, holographic or projection-linked systems and specialized e-paper or dual-view technologies. Smaller innovation segment focused on premium HMI, low-power secondary interfaces and future cockpit differentiation.

Display-size and touch-technology segmentation

The market is also segmented by screen size and touch technology. The 7–10 inch range remains the largest mainstream band, while above-10-inch displays gain share as OEMs consolidate physical controls into digital interfaces. Capacitive touch is the principal interaction technology in modern vehicles because it supports multi-touch, gesture-like interaction and thin integrated display stacks.

Axis Segments Commercial implication
By Display Size Below 5 in · 5–7 in · 7–10 in · Above 10 in 7–10 inches remains the mainstream band; above 10 inches captures faster value growth through EVs, premium models and integrated cockpit architectures.
By Touch Technology Capacitive Touch · Resistive Touch · Infrared / Optical · Other Capacitive touch is the preferred modern architecture; haptic feedback and pressure/gesture sensing are being added to improve eyes-on-road usability.

Segment Analysis: By Application

By application, Passenger Cars dominate the market, while commercial vehicles are increasing adoption through fleet management, navigation, telematics and driver-assistance interfaces.

Application Key market insight
Passenger Cars The largest application. Sedans, SUVs and hatchbacks increasingly use center displays as the primary HMI for infotainment, navigation, climate and vehicle configuration. EVs generally adopt larger screen formats and more software-controlled functions.
Commercial Vehicles Light and heavy commercial vehicles use displays for navigation, fleet data, camera views and vehicle diagnostics. Durability, glove operation and anti-glare performance are particularly important.
Electric Vehicles EV cockpits emphasize battery range, charging, energy flows and software-defined features. Large displays and OTA-updated interfaces are common, increasing display and compute content per vehicle.
Premium / Luxury Vehicles Premium models lead OLED, curved, pillar-to-pillar, passenger privacy and integrated multi-screen adoption. Higher brightness, local dimming and advanced optical bonding support differentiated HMI.
Connected / Software-Defined Vehicles Cockpit domain controllers coordinate center displays, clusters, HUDs and cameras. Centralized software platforms reduce ECU count while increasing display rendering and communication requirements.

Automotive Center Stack Display (CSD) Market Outlook

Regional Analysis

Asia Pacific is the leading Automotive CSD market, supported by China’s large vehicle and EV production base, Japan and South Korea’s display and automotive electronics ecosystems, and expanding digital-cockpit adoption in India and Southeast Asia. North America and Europe remain high-value markets because premium vehicles and software-defined cockpit platforms are adopted quickly.

How do regional automotive-display markets differ?

Asia Pacific combines the highest production scale with strong local panel supply. North America emphasizes premium digital cockpits, EVs and software integration. Europe focuses on safety, high-end HMI and integrated cockpit electronics. Emerging regions remain more price sensitive but benefit from rising infotainment penetration.

Region Market position Growth outlook Core demand Commercial priority
Asia Pacific Leading Very high EV, passenger car & panel manufacturing Cost, scale and rapid feature adoption
North America Premium demand High EV, SUV & connected cockpit Large screens, software and premium UX
Europe Premium / regulated market High Luxury, safety & digital cockpit Driver distraction, quality and integration
South America Emerging Moderate Passenger cars & pickups Affordability and local assembly
Middle East & Africa Emerging Moderate Premium imports & connected vehicles Heat, durability and price
Asia PacificLEADING REGIONAL MARKET

Why does Asia Pacific lead automotive center display demand?

The region combines very large vehicle output, rapid EV adoption and several of the world’s major display manufacturers. China is particularly important through domestic EV brands and local panel supply, while Japan and South Korea contribute display, electronics and automotive Tier-1 capabilities. India is becoming an important cockpit-electronics manufacturing and software market.

Market position
Leading
Growth outlook
Very high
Demand profile
EV & passenger cars
Commercial gate
Cost and integration
Country / cluster Role Market instance
China Largest production market EV and intelligent-cockpit adoption support large LCD and OLED volumes.
South Korea Display technology hub LG Display and Hyundai Mobis advance OLED, pillar-to-pillar and next-generation cockpit solutions.
Japan Automotive electronics hub JDI, Alps Alpine and OEM ecosystems support high-reliability displays.
India Fast-growing cockpit market Connected SUVs and local vehicle production expand multi-screen and infotainment demand.
Visteon and Mahindra introduced SmartCore Pro for the 2026 XUV7X0. The system powers a three-display cockpit with ADAS visualization, surround view and telematics.
LG Display is commercializing automotive P2P, OLED and slidable display concepts. Its 2026 portfolio includes 48–51 inch dashboard-spanning systems.
Tianma’s 2026 Smart Cockpit 7.0 combines a 49.6-inch curved display with slidable AMOLED.
North AmericaPREMIUM DIGITAL COCKPIT MARKET

What drives North American demand?

The United States has high penetration of large SUVs, pickups, premium vehicles and EVs, all of which support larger center displays and connected services. OEMs increasingly consolidate infotainment and vehicle controls into central screens and cockpit domain controllers, while safety and driver-distraction requirements influence interface design.

Market position
Premium demand
Growth outlook
High
Demand profile
EV, SUV & connected cockpit
Commercial gate
UX and software integration
Country / cluster Role Market instance
United States Primary regional market Large-screen EV and premium vehicle adoption supports high display content per vehicle.
Canada Mature premium market Connected SUVs and premium models support center-display replacement and new-platform demand.
Mexico Vehicle manufacturing base Assembly plants integrate display systems supplied through global Tier-1 networks.
Bosch presented an AI extension platform for cockpit systems at CES 2026. The platform adds AI capability to existing and new cockpit architectures.
Visteon’s 2026 SmartCore HPC targets centralized premium cockpit systems. It supports multi-display experiences and substantial in-cabin compute.
Large integrated screens increasingly combine infotainment, ADAS visualization and vehicle settings.
Europe

What differentiates the European market?

Europe combines premium OEMs, strong Tier-1 cockpit suppliers and regulatory focus on safety. BMW, Mercedes-Benz, Volkswagen and other manufacturers use large central screens, integrated dashboards and advanced passenger displays. Human-machine interface design must balance richer digital functions with distraction management and functional safety.

Market position
Premium / regulated
Growth outlook
High
Demand profile
Luxury & SDV cockpit
Commercial gate
Safety and validation
Country / cluster Role Market instance
Germany Premium OEM / Tier-1 hub Bosch, Continental/Aumovio and German OEMs drive integrated cockpit architectures.
France Automotive electronics market Connected-car and EV programs support digital displays.
Central Europe Vehicle assembly cluster Display modules are integrated into large-volume European vehicle platforms.
Continental demonstrated microLED and crystal center-display concepts for premium vehicles.
European cockpit programs increasingly integrate privacy, haptics and multi-display rendering.
Optical bonding and sunlight readability remain essential for safety-critical information.
South America

How does the CSD market develop in South America?

Brazil is the largest regional vehicle market, with center displays increasingly standard in mid-range SUVs and pickups. Local vehicle assembly supports OEM integration, but premium OLED and wide-screen systems remain limited by vehicle price and imported component cost.

Market position
Emerging
Growth outlook
Moderate
Demand profile
SUV & passenger car
Commercial gate
Affordability
Country / cluster Role Market instance
Brazil Largest regional market Mid-range SUVs and pickups support mainstream center displays.
Argentina Assembly / value market Infotainment adoption grows with locally assembled vehicles.
Chile Import-led premium niche Imported EVs and premium vehicles introduce larger displays.
Mainstream LCD remains the practical technology for regional high-volume vehicles.
Smartphone projection lowers software cost while preserving connected functionality.
Premium displays enter first through imported EVs and luxury models.
Middle East & Africa

What supports demand in the Middle East and Africa?

Gulf countries have strong premium-vehicle demand and fast EV adoption, while Africa is more value sensitive. Automotive displays must tolerate high cabin temperatures, glare and dust. The market is driven mostly by imported vehicles and aftermarket infotainment rather than local panel manufacturing.

Market position
Emerging
Growth outlook
Moderate
Demand profile
Premium imports & infotainment
Commercial gate
Heat and durability
Country / cluster Role Market instance
UAE Premium vehicle hub Luxury and EV imports support large high-resolution displays.
Saudi Arabia Growing mobility market Digital cockpits expand with premium and locally planned vehicle programs.
South Africa Largest sub-Saharan vehicle market Mainstream infotainment and connected-car adoption create steady demand.
High-brightness and thermal stability are central design requirements.
Premium imported vehicles introduce OLED and wide cockpit displays.
Aftermarket infotainment remains important in older vehicle fleets.

Competitive Landscape

Key participants include LG Display, BOE Technology, Japan Display, Continental/Aumovio, Tianma, Visteon, Innolux, Robert Bosch, Hyundai Mobis, Garmin, Alps Alpine and Preh. Competition spans panel manufacturing, optical integration, cockpit electronics and software-defined HMI.

LG Display and BOE compete at the panel level with automotive LCD, OLED and wide integrated-display technologies. LG’s tandem automotive OLED improves brightness and lifetime, while BOE supplies center displays from conventional formats through large integrated cockpit systems and flexible AMOLED.

Visteon, Bosch, Continental/Aumovio and Hyundai Mobis compete higher in the system stack through cockpit domain controllers, multi-display integration, vehicle software and advanced HMI. Their position is strengthened as OEMs consolidate cluster, center, passenger and camera functions under centralized compute.

Tianma, JDI and Innolux provide additional panel and module competition across LCD and emerging OLED/MicroLED technologies. Competitive advantage depends on automotive qualification, optical performance, long product life, software integration and the ability to support global OEM platforms.

Competitive tier structure

Competitive tier Representative companies Competitive strengths
Automotive display-panel leaders LG Display; BOE; Tianma; JDI; Innolux LCD/OLED panel technology, wide formats, optical performance and automotive qualification
Cockpit system leaders Visteon; Bosch; Continental/Aumovio; Hyundai Mobis Domain controllers, multi-display rendering, software, HMI and system integration
Specialist / interface suppliers Garmin; Alps Alpine; Preh and others Navigation, controls, HMI modules and OEM-specific integration

Key companies profiled

LG DisplayBOE Technology GroupJapan Display Inc.Continental / AumovioTianma MicroelectronicsVisteon CorporationInnolux CorporationRobert Bosch GmbHHyundai MobisGarmin Ltd.Alps Alpine Co., Ltd.Preh GmbH

Automotive Display Capacity & Qualification Analysis

Capacity depends on automotive-grade LCD and OLED panel output, touch-sensor production, cover glass, optical bonding, module assembly, electronics integration and long-duration qualification. Automotive programs ramp more slowly than consumer devices but remain in production much longer.

Panel capacity is not automatically automotive capacity. Each design requires qualification for temperature, vibration, EMC, optical uniformity, lifetime and customer-specific reliability. Automotive-qualified OLED and large curved LCD therefore command more value than standard consumer panels.

System integration adds another capacity layer. Cockpit domain controllers must be validated with graphics processors, operating systems, cameras, touch interfaces and vehicle networks. This favors suppliers that can combine panel, module, software and compute expertise.

Market Dynamics

Growth is driven by vehicle digitization, EVs, software-defined vehicles, connected infotainment and larger displays. Restraints include qualification cost, thermal management, driver-distraction risk and display-semiconductor supply. Opportunities center on OLED, pillar-to-pillar displays, privacy modes, integrated cameras and AI-enabled cockpit platforms.

MARKET DRIVERS

Physical controls are moving into digital HMI

Navigation, climate and vehicle settings increasingly share one central interface, raising display content per vehicle.

EVs use digital screens as a brand differentiator

Battery status, charging, route planning and software features encourage larger and more integrated displays.

Centralized cockpit compute supports more screens

Domain controllers render content across center, cluster, passenger and HUD displays while reducing separate ECUs.

OLED and advanced LCD improve premium experience

Higher contrast, thinner form factors, wide color gamut and curved shapes allow new dashboard designs.

Drivers Impact Analysis

Driver Impact Primary markets Time horizon
Vehicle digitization High Global passenger vehicles Persistent
EV adoption High China, Europe, North America Medium to long term
Software-defined cockpit High Premium / connected vehicles Medium to long term
Display-size expansion High Premium and mid-range vehicles Persistent

MARKET RESTRAINTS

Qualification is lengthy and expensive

Displays must survive years of temperature cycling, sunlight, vibration and electrical stress before an OEM approves them.

Large high-brightness screens generate heat

More pixels, brighter backlights and powerful graphics increase thermal load inside confined dashboards.

More screen content can distract drivers

OEMs must manage glance time, touch depth and information hierarchy to meet safety expectations.

Automotive supply chains require long continuity

OEMs need stable panels and driver ICs for many years, which can be difficult when consumer-display technology changes rapidly.

Restraints Impact Analysis

Restraint Impact Exposure Time horizon
Automotive qualification cost High All suppliers Persistent
Thermal / brightness management High Large displays Persistent
Driver-distraction regulation Medium to high Global OEMs Persistent
Display IC / panel supply risk Medium Global supply chain Recurring

MARKET OPPORTUNITIES

Scale automotive OLED

Tandem and P-OLED architectures improve lifetime and brightness enough for more center displays and integrated dashboards.

Develop pillar-to-pillar cockpits

One wide display can replace several separate modules and support personalized driver/passenger zones.

Integrate cameras behind displays

Under-panel driver-monitoring and cabin cameras can reduce visible hardware and improve cockpit aesthetics.

Add AI and adaptive HMI

Voice, contextual recommendations, driver monitoring and predictive controls can make the display interface safer and more useful.

Automotive CSD Value Chain Analysis

Panel / touch materials

LCD/OLED panels, touch sensors, driver ICs and cover glass determine core display performance.

Module & optical integration

Optical bonding, backlight, cover lens, haptics and thermal structures form the automotive display module.

Cockpit electronics / software

Domain controllers, graphics, operating systems and vehicle networks drive the display.

OEM vehicle integration

Automakers validate HMI, safety, reliability and lifecycle across vehicle platforms.

Panel technology determines image and packaging options

LCD provides cost and brightness advantages; OLED provides contrast, thinness and flexible geometry.

Optical bonding improves readability

Reducing internal reflections improves contrast in sunlight and can increase mechanical robustness.

Cockpit software determines real user value

Display area only creates value when navigation, ADAS and vehicle functions are organized intuitively.

OEM qualification creates long supplier relationships

Once a display system is validated into a vehicle platform, suppliers can ship for many model years.

Recent Developments in the Automotive Center Stack Display (CSD) Market

August 2026

LG Display showcases 48-inch pillar-to-pillar mobility display

At K-Display 2026, LG Display demonstrated a 48-inch dashboard-spanning automotive display together with slidable OLED mobility concepts.

Primary source

3 June 2026

Visteon expands premium cockpit display portfolio

Visteon announced a 12.3-inch narrow-border display for the Lexus ES using full optical bonding and high-brightness LCD technology.

Primary source

4 May 2026

Tianma presents next-generation automotive displays

Tianma’s Display Week 2026 portfolio includes Smart Cockpit 7.0, large curved displays, MicroLED HUDs and AMOLED technologies for intelligent vehicles.

Primary source

3 February 2026

Hyundai Mobis forms alliance for holographic windshield display

Hyundai Mobis partnered with ZEISS, tesa and Sekurit to develop windshield-scale display technology targeting mass production from 2029.

Primary source

7 January 2026

Visteon and Mahindra unveil three-display SmartCore Pro cockpit

The 2026 Mahindra XUV7X0 platform uses Visteon SmartCore Pro to integrate multi-display infotainment, ADAS visualization, telematics and surround view.

Primary source

REPORT SCOPE & SEGMENTATION

Attribute Details
Study Period 2020–2034
Base Year 2025
Estimated Year 2026
Forecast Period 2026–2034
Historical Period 2020–2025
Market Size 2025 USD 5.25 billion
Market Size 2034 USD 14.92 billion
Growth Rate 12.3% during 2026–2034
Unit Value (USD Million/Billion) and display-system shipments
By Type LCD · OLED · Others
By Application Passenger Cars · Commercial Vehicles
By Display Size Less than 5 inches · 5–7 inches · 7–10 inches · Above 10 inches
By Touch Technology Resistive Touch · Capacitive Touch · Infrared / Optical Touch · Others
By Region Each region analysed by display technology, vehicle application, screen size, touch technology and country automotive ecosystem
North AmericaUnited States, Canada, Mexico
EuropeGermany, France, United Kingdom, Italy and other European markets
Asia PacificChina, South Korea, Japan, India, Southeast Asia and other Asian markets
South AmericaBrazil, Argentina, Chile and other South American markets
Middle East & AfricaUAE, Saudi Arabia, South Africa and other MEA markets
Key Companies Profiled LG Display · BOE Technology Group · Japan Display Inc. · Continental / Aumovio · Tianma Microelectronics · Visteon Corporation · Innolux Corporation · Robert Bosch GmbH · Hyundai Mobis · Garmin Ltd. · Alps Alpine Co., Ltd. · Preh GmbH
Customization Scope Free report customization equivalent to up to four analyst working days with purchase. Addition or alteration to country, regional and segment scope.

Frequently Asked Questions

What is the 2025 size of the Automotive Center Stack Display market?

The market is valued at USD 5.25 billion in 2025 and is projected to reach USD 14.92 billion by 2034. The 2026 estimate is USD 5.89 billion and the 2026–2034 CAGR is 12.3%.

Which display technology leads the market?

LCD remains the largest installed technology because of cost, automotive qualification maturity and broad supply, while OLED is the fastest-growing premium technology.

Which vehicle segment is the largest?

Passenger cars dominate because center displays are now standard across a large share of sedans, SUVs and EVs, while commercial-vehicle adoption is also rising.

Which region leads the market?

Asia Pacific is the leading region through its large vehicle-production base, rapid EV adoption and strong automotive display supply chain.

What is the estimated market size in 2026?

The 2026 estimated market size is USD 5.89 billion within the consistent long-term market-growth series.

Which screen size is most important?

The 7–10 inch range remains the largest mainstream size band, while displays above 10 inches are gaining value share through premium, EV and integrated cockpit programs.

What are the main market restraints?

Long automotive qualification, thermal management, driver-distraction risk and display-semiconductor supply constraints are the main restraints.

How is OLED changing automotive displays?

OLED enables thinner, curved and flexible cockpit designs with high contrast and fast response. Tandem OLED improves brightness and lifetime for automotive conditions.

Which companies are active in the market?

Major participants include LG Display, BOE, Tianma, Visteon, Bosch, Continental/Aumovio, Hyundai Mobis, JDI, Innolux, Garmin, Alps Alpine and Preh.

What does the report cover?

The report covers LCD and OLED center displays, passenger and commercial vehicles, display sizes, touch technologies, five global regions, competitive landscape, capacity, market dynamics, developments and value chain.

Research Sources & Evidence Base

View primary and authoritative evidence used in this overview
  1. BOE. Automotive Display – Official portfolio evidence on center stack, curved, integrated touch and automotive display technologies.
  2. LG Display. Automotive OLED – Official evidence on tandem OLED, slidable OLED, dual-view and embedded-camera automotive displays.
  3. LG Display. Automotive LCD – Official evidence on high-brightness automotive LCD and screenification.
  4. Visteon. SmartCore Pro for Mahindra – January 2026 evidence on three-display centralized cockpit architecture.
  5. Hyundai Mobis. Next-Generation Display Alliance – February 2026 evidence on holographic windshield display and cockpit display strategy.
  6. Bosch Mobility. AI Cockpit at CES 2026 – Official evidence on AI-enabled cockpit platforms and software-defined in-cabin experience.
Automotive Center Stack Display (CSD) Market, Trends, Business Strategies 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Automotive Center Stack Display (CSD) Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Automotive Center Stack Display (CSD) Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Automotive Center Stack Display (CSD) Overall Market Size
2.1 Global Automotive Center Stack Display (CSD) Market Size: 2024 VS 2032
2.2 Global Automotive Center Stack Display (CSD) Market Size, Prospects & Forecasts: 2020-2032
2.3 Global Automotive Center Stack Display (CSD) Sales: 2020-2032
3 Company Landscape
3.1 Top Automotive Center Stack Display (CSD) Players in Global Market
3.2 Top Global Automotive Center Stack Display (CSD) Companies Ranked by Revenue
3.3 Global Automotive Center Stack Display (CSD) Revenue by Companies
3.4 Global Automotive Center Stack Display (CSD) Sales by Companies
3.5 Global Automotive Center Stack Display (CSD) Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 Automotive Center Stack Display (CSD) Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers Automotive Center Stack Display (CSD) Product Type
3.8 Tier 1, Tier 2, and Tier 3 Automotive Center Stack Display (CSD) Players in Global Market
3.8.1 List of Global Tier 1 Automotive Center Stack Display (CSD) Companies
3.8.2 List of Global Tier 2 and Tier 3 Automotive Center Stack Display (CSD) Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global Automotive Center Stack Display (CSD) Market Size Markets, 2024 & 2032
4.1.2 LCD
4.1.3 OLED
4.2 Segment by Type – Global Automotive Center Stack Display (CSD) Revenue & Forecasts
4.2.1 Segment by Type – Global Automotive Center Stack Display (CSD) Revenue, 2020-2025
4.2.2 Segment by Type – Global Automotive Center Stack Display (CSD) Revenue, 2026-2032
4.2.3 Segment by Type – Global Automotive Center Stack Display (CSD) Revenue Market Share, 2020-2032
4.3 Segment by Type – Global Automotive Center Stack Display (CSD) Sales & Forecasts
4.3.1 Segment by Type – Global Automotive Center Stack Display (CSD) Sales, 2020-2025
4.3.2 Segment by Type – Global Automotive Center Stack Display (CSD) Sales, 2026-2032
4.3.3 Segment by Type – Global Automotive Center Stack Display (CSD) Sales Market Share, 2020-2032
4.4 Segment by Type – Global Automotive Center Stack Display (CSD) Price (Manufacturers Selling Prices), 2020-2032
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global Automotive Center Stack Display (CSD) Market Size, 2024 & 2032
5.1.2 Passenger Car
5.1.3 Commercial Vehicle
5.2 Segment by Application – Global Automotive Center Stack Display (CSD) Revenue & Forecasts
5.2.1 Segment by Application – Global Automotive Center Stack Display (CSD) Revenue, 2020-2025
5.2.2 Segment by Application – Global Automotive Center Stack Display (CSD) Revenue, 2026-2032
5.2.3 Segment by Application – Global Automotive Center Stack Display (CSD) Revenue Market Share, 2020-2032
5.3 Segment by Application – Global Automotive Center Stack Display (CSD) Sales & Forecasts
5.3.1 Segment by Application – Global Automotive Center Stack Display (CSD) Sales, 2020-2025
5.3.2 Segment by Application – Global Automotive Center Stack Display (CSD) Sales, 2026-2032
5.3.3 Segment by Application – Global Automotive Center Stack Display (CSD) Sales Market Share, 2020-2032
5.4 Segment by Application – Global Automotive Center Stack Display (CSD) Price (Manufacturers Selling Prices), 2020-2032
6 Sights by Region
6.1 By Region – Global Automotive Center Stack Display (CSD) Market Size, 2024 & 2032
6.2 By Region – Global Automotive Center Stack Display (CSD) Revenue & Forecasts
6.2.1 By Region – Global Automotive Center Stack Display (CSD) Revenue, 2020-2025
6.2.2 By Region – Global Automotive Center Stack Display (CSD) Revenue, 2026-2032
6.2.3 By Region – Global Automotive Center Stack Display (CSD) Revenue Market Share, 2020-2032
6.3 By Region – Global Automotive Center Stack Display (CSD) Sales & Forecasts
6.3.1 By Region – Global Automotive Center Stack Display (CSD) Sales, 2020-2025
6.3.2 By Region – Global Automotive Center Stack Display (CSD) Sales, 2026-2032
6.3.3 By Region – Global Automotive Center Stack Display (CSD) Sales Market Share, 2020-2032
6.4 North America
6.4.1 By Country – North America Automotive Center Stack Display (CSD) Revenue, 2020-2032
6.4.2 By Country – North America Automotive Center Stack Display (CSD) Sales, 2020-2032
6.4.3 United States Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.4.4 Canada Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.4.5 Mexico Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.5 Europe
6.5.1 By Country – Europe Automotive Center Stack Display (CSD) Revenue, 2020-2032
6.5.2 By Country – Europe Automotive Center Stack Display (CSD) Sales, 2020-2032
6.5.3 Germany Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.5.4 France Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.5.5 U.K. Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.5.6 Italy Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.5.7 Russia Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.5.8 Nordic Countries Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.5.9 Benelux Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.6 Asia
6.6.1 By Region – Asia Automotive Center Stack Display (CSD) Revenue, 2020-2032
6.6.2 By Region – Asia Automotive Center Stack Display (CSD) Sales, 2020-2032
6.6.3 China Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.6.4 Japan Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.6.5 South Korea Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.6.6 Southeast Asia Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.6.7 India Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.7 South America
6.7.1 By Country – South America Automotive Center Stack Display (CSD) Revenue, 2020-2032
6.7.2 By Country – South America Automotive Center Stack Display (CSD) Sales, 2020-2032
6.7.3 Brazil Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.7.4 Argentina Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa Automotive Center Stack Display (CSD) Revenue, 2020-2032
6.8.2 By Country – Middle East & Africa Automotive Center Stack Display (CSD) Sales, 2020-2032
6.8.3 Turkey Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.8.4 Israel Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.8.5 Saudi Arabia Automotive Center Stack Display (CSD) Market Size, 2020-2032
6.8.6 UAE Automotive Center Stack Display (CSD) Market Size, 2020-2032
7 Manufacturers & Brands Profiles
7.1 Tianma
7.1.1 Tianma Company Summary
7.1.2 Tianma Business Overview
7.1.3 Tianma Automotive Center Stack Display (CSD) Major Product Offerings
7.1.4 Tianma Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.1.5 Tianma Key News & Latest Developments
7.2 BOE
7.2.1 BOE Company Summary
7.2.2 BOE Business Overview
7.2.3 BOE Automotive Center Stack Display (CSD) Major Product Offerings
7.2.4 BOE Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.2.5 BOE Key News & Latest Developments
7.3 JDI
7.3.1 JDI Company Summary
7.3.2 JDI Business Overview
7.3.3 JDI Automotive Center Stack Display (CSD) Major Product Offerings
7.3.4 JDI Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.3.5 JDI Key News & Latest Developments
7.4 LG Display
7.4.1 LG Display Company Summary
7.4.2 LG Display Business Overview
7.4.3 LG Display Automotive Center Stack Display (CSD) Major Product Offerings
7.4.4 LG Display Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.4.5 LG Display Key News & Latest Developments
7.5 Continental
7.5.1 Continental Company Summary
7.5.2 Continental Business Overview
7.5.3 Continental Automotive Center Stack Display (CSD) Major Product Offerings
7.5.4 Continental Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.5.5 Continental Key News & Latest Developments
7.6 Truly Semi
7.6.1 Truly Semi Company Summary
7.6.2 Truly Semi Business Overview
7.6.3 Truly Semi Automotive Center Stack Display (CSD) Major Product Offerings
7.6.4 Truly Semi Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.6.5 Truly Semi Key News & Latest Developments
7.7 Robert Bosch
7.7.1 Robert Bosch Company Summary
7.7.2 Robert Bosch Business Overview
7.7.3 Robert Bosch Automotive Center Stack Display (CSD) Major Product Offerings
7.7.4 Robert Bosch Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.7.5 Robert Bosch Key News & Latest Developments
7.8 Innolux Corporation
7.8.1 Innolux Corporation Company Summary
7.8.2 Innolux Corporation Business Overview
7.8.3 Innolux Corporation Automotive Center Stack Display (CSD) Major Product Offerings
7.8.4 Innolux Corporation Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.8.5 Innolux Corporation Key News & Latest Developments
7.9 Hyundai Mobis
7.9.1 Hyundai Mobis Company Summary
7.9.2 Hyundai Mobis Business Overview
7.9.3 Hyundai Mobis Automotive Center Stack Display (CSD) Major Product Offerings
7.9.4 Hyundai Mobis Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.9.5 Hyundai Mobis Key News & Latest Developments
7.10 Visteon Corporation
7.10.1 Visteon Corporation Company Summary
7.10.2 Visteon Corporation Business Overview
7.10.3 Visteon Corporation Automotive Center Stack Display (CSD) Major Product Offerings
7.10.4 Visteon Corporation Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.10.5 Visteon Corporation Key News & Latest Developments
7.11 MTA S.p.A
7.11.1 MTA S.p.A Company Summary
7.11.2 MTA S.p.A Business Overview
7.11.3 MTA S.p.A Automotive Center Stack Display (CSD) Major Product Offerings
7.11.4 MTA S.p.A Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.11.5 MTA S.p.A Key News & Latest Developments
7.12 Alps Alpine
7.12.1 Alps Alpine Company Summary
7.12.2 Alps Alpine Business Overview
7.12.3 Alps Alpine Automotive Center Stack Display (CSD) Major Product Offerings
7.12.4 Alps Alpine Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.12.5 Alps Alpine Key News & Latest Developments
7.13 Garmin Ltd
7.13.1 Garmin Ltd Company Summary
7.13.2 Garmin Ltd Business Overview
7.13.3 Garmin Ltd Automotive Center Stack Display (CSD) Major Product Offerings
7.13.4 Garmin Ltd Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.13.5 Garmin Ltd Key News & Latest Developments
7.14 Preh GmbH
7.14.1 Preh GmbH Company Summary
7.14.2 Preh GmbH Business Overview
7.14.3 Preh GmbH Automotive Center Stack Display (CSD) Major Product Offerings
7.14.4 Preh GmbH Automotive Center Stack Display (CSD) Sales and Revenue in Global (2020-2025)
7.14.5 Preh GmbH Key News & Latest Developments
8 Global Automotive Center Stack Display (CSD) Production Capacity, Analysis
8.1 Global Automotive Center Stack Display (CSD) Production Capacity, 2020-2032
8.2 Automotive Center Stack Display (CSD) Production Capacity of Key Manufacturers in Global Market
8.3 Global Automotive Center Stack Display (CSD) Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 Automotive Center Stack Display (CSD) Supply Chain Analysis
10.1 Automotive Center Stack Display (CSD) Industry Value Chain
10.2 Automotive Center Stack Display (CSD) Upstream Market
10.3 Automotive Center Stack Display (CSD) Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 Automotive Center Stack Display (CSD) Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of Automotive Center Stack Display (CSD) in Global Market
Table 2. Top Automotive Center Stack Display (CSD) Players in Global Market, Ranking by Revenue (2024)
Table 3. Global Automotive Center Stack Display (CSD) Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global Automotive Center Stack Display (CSD) Revenue Share by Companies, 2020-2025
Table 5. Global Automotive Center Stack Display (CSD) Sales by Companies, (K Units), 2020-2025
Table 6. Global Automotive Center Stack Display (CSD) Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers Automotive Center Stack Display (CSD) Price (2020-2025) & (US$/Unit)
Table 8. Global Manufacturers Automotive Center Stack Display (CSD) Product Type
Table 9. List of Global Tier 1 Automotive Center Stack Display (CSD) Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Automotive Center Stack Display (CSD) Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global Automotive Center Stack Display (CSD) Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global Automotive Center Stack Display (CSD) Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global Automotive Center Stack Display (CSD) Sales (K Units), 2020-2025
Table 15. Segment by Type – Global Automotive Center Stack Display (CSD) Sales (K Units), 2026-2032
Table 16. Segment by Application – Global Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global Automotive Center Stack Display (CSD) Sales, (K Units), 2020-2025
Table 20. Segment by Application – Global Automotive Center Stack Display (CSD) Sales, (K Units), 2026-2032
Table 21. By Region – Global Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global Automotive Center Stack Display (CSD) Sales, (K Units), 2020-2025
Table 25. By Region – Global Automotive Center Stack Display (CSD) Sales, (K Units), 2026-2032
Table 26. By Country – North America Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America Automotive Center Stack Display (CSD) Sales, (K Units), 2020-2025
Table 29. By Country – North America Automotive Center Stack Display (CSD) Sales, (K Units), 2026-2032
Table 30. By Country – Europe Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe Automotive Center Stack Display (CSD) Sales, (K Units), 2020-2025
Table 33. By Country – Europe Automotive Center Stack Display (CSD) Sales, (K Units), 2026-2032
Table 34. By Region – Asia Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia Automotive Center Stack Display (CSD) Sales, (K Units), 2020-2025
Table 37. By Region – Asia Automotive Center Stack Display (CSD) Sales, (K Units), 2026-2032
Table 38. By Country – South America Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America Automotive Center Stack Display (CSD) Sales, (K Units), 2020-2025
Table 41. By Country – South America Automotive Center Stack Display (CSD) Sales, (K Units), 2026-2032
Table 42. By Country – Middle East & Africa Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa Automotive Center Stack Display (CSD) Sales, (K Units), 2020-2025
Table 45. By Country – Middle East & Africa Automotive Center Stack Display (CSD) Sales, (K Units), 2026-2032
Table 46. Tianma Company Summary
Table 47. Tianma Automotive Center Stack Display (CSD) Product Offerings
Table 48. Tianma Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 49. Tianma Key News & Latest Developments
Table 50. BOE Company Summary
Table 51. BOE Automotive Center Stack Display (CSD) Product Offerings
Table 52. BOE Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 53. BOE Key News & Latest Developments
Table 54. JDI Company Summary
Table 55. JDI Automotive Center Stack Display (CSD) Product Offerings
Table 56. JDI Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 57. JDI Key News & Latest Developments
Table 58. LG Display Company Summary
Table 59. LG Display Automotive Center Stack Display (CSD) Product Offerings
Table 60. LG Display Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 61. LG Display Key News & Latest Developments
Table 62. Continental Company Summary
Table 63. Continental Automotive Center Stack Display (CSD) Product Offerings
Table 64. Continental Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 65. Continental Key News & Latest Developments
Table 66. Truly Semi Company Summary
Table 67. Truly Semi Automotive Center Stack Display (CSD) Product Offerings
Table 68. Truly Semi Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 69. Truly Semi Key News & Latest Developments
Table 70. Robert Bosch Company Summary
Table 71. Robert Bosch Automotive Center Stack Display (CSD) Product Offerings
Table 72. Robert Bosch Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 73. Robert Bosch Key News & Latest Developments
Table 74. Innolux Corporation Company Summary
Table 75. Innolux Corporation Automotive Center Stack Display (CSD) Product Offerings
Table 76. Innolux Corporation Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 77. Innolux Corporation Key News & Latest Developments
Table 78. Hyundai Mobis Company Summary
Table 79. Hyundai Mobis Automotive Center Stack Display (CSD) Product Offerings
Table 80. Hyundai Mobis Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 81. Hyundai Mobis Key News & Latest Developments
Table 82. Visteon Corporation Company Summary
Table 83. Visteon Corporation Automotive Center Stack Display (CSD) Product Offerings
Table 84. Visteon Corporation Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 85. Visteon Corporation Key News & Latest Developments
Table 86. MTA S.p.A Company Summary
Table 87. MTA S.p.A Automotive Center Stack Display (CSD) Product Offerings
Table 88. MTA S.p.A Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 89. MTA S.p.A Key News & Latest Developments
Table 90. Alps Alpine Company Summary
Table 91. Alps Alpine Automotive Center Stack Display (CSD) Product Offerings
Table 92. Alps Alpine Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 93. Alps Alpine Key News & Latest Developments
Table 94. Garmin Ltd Company Summary
Table 95. Garmin Ltd Automotive Center Stack Display (CSD) Product Offerings
Table 96. Garmin Ltd Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 97. Garmin Ltd Key News & Latest Developments
Table 98. Preh GmbH Company Summary
Table 99. Preh GmbH Automotive Center Stack Display (CSD) Product Offerings
Table 100. Preh GmbH Automotive Center Stack Display (CSD) Sales (K Units), Revenue (US$, Mn) and Average Price (US$/Unit) & (2020-2025)
Table 101. Preh GmbH Key News & Latest Developments
Table 102. Automotive Center Stack Display (CSD) Capacity of Key Manufacturers in Global Market, 2023-2025 (K Units)
Table 103. Global Automotive Center Stack Display (CSD) Capacity Market Share of Key Manufacturers, 2023-2025
Table 104. Global Automotive Center Stack Display (CSD) Production by Region, 2020-2025 (K Units)
Table 105. Global Automotive Center Stack Display (CSD) Production by Region, 2026-2032 (K Units)
Table 106. Automotive Center Stack Display (CSD) Market Opportunities & Trends in Global Market
Table 107. Automotive Center Stack Display (CSD) Market Drivers in Global Market
Table 108. Automotive Center Stack Display (CSD) Market Restraints in Global Market
Table 109. Automotive Center Stack Display (CSD) Raw Materials
Table 110. Automotive Center Stack Display (CSD) Raw Materials Suppliers in Global Market
Table 111. Typical Automotive Center Stack Display (CSD) Downstream
Table 112. Automotive Center Stack Display (CSD) Downstream Clients in Global Market
Table 113. Automotive Center Stack Display (CSD) Distributors and Sales Agents in Global Market

List of Figures
Figure 1. Automotive Center Stack Display (CSD) Product Picture
Figure 2. Automotive Center Stack Display (CSD) Segment by Type in 2024
Figure 3. Automotive Center Stack Display (CSD) Segment by Application in 2024
Figure 4. Global Automotive Center Stack Display (CSD) Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Automotive Center Stack Display (CSD) Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Automotive Center Stack Display (CSD) Revenue: 2020-2032 (US$, Mn)
Figure 8. Automotive Center Stack Display (CSD) Sales in Global Market: 2020-2032 (K Units)
Figure 9. The Top 3 and 5 Players Market Share by Automotive Center Stack Display (CSD) Revenue in 2024
Figure 10. Segment by Type – Global Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global Automotive Center Stack Display (CSD) Revenue Market Share, 2020-2032
Figure 12. Segment by Type – Global Automotive Center Stack Display (CSD) Sales Market Share, 2020-2032
Figure 13. Segment by Type – Global Automotive Center Stack Display (CSD) Price (US$/Unit), 2020-2032
Figure 14. Segment by Application – Global Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global Automotive Center Stack Display (CSD) Revenue Market Share, 2020-2032
Figure 16. Segment by Application – Global Automotive Center Stack Display (CSD) Sales Market Share, 2020-2032
Figure 17. Segment by Application -Global Automotive Center Stack Display (CSD) Price (US$/Unit), 2020-2032
Figure 18. By Region – Global Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global Automotive Center Stack Display (CSD) Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global Automotive Center Stack Display (CSD) Revenue Market Share, 2020-2032
Figure 21. By Region – Global Automotive Center Stack Display (CSD) Sales Market Share, 2020-2032
Figure 22. By Country – North America Automotive Center Stack Display (CSD) Revenue Market Share, 2020-2032
Figure 23. By Country – North America Automotive Center Stack Display (CSD) Sales Market Share, 2020-2032
Figure 24. United States Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 25. Canada Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 26. Mexico Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 27. By Country – Europe Automotive Center Stack Display (CSD) Revenue Market Share, 2020-2032
Figure 28. By Country – Europe Automotive Center Stack Display (CSD) Sales Market Share, 2020-2032
Figure 29. Germany Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 30. France Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 31. U.K. Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 32. Italy Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 33. Russia Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 34. Nordic Countries Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 35. Benelux Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 36. By Region – Asia Automotive Center Stack Display (CSD) Revenue Market Share, 2020-2032
Figure 37. By Region – Asia Automotive Center Stack Display (CSD) Sales Market Share, 2020-2032
Figure 38. China Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 39. Japan Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 40. South Korea Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 41. Southeast Asia Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 42. India Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 43. By Country – South America Automotive Center Stack Display (CSD) Revenue Market Share, 2020-2032
Figure 44. By Country – South America Automotive Center Stack Display (CSD) Sales, Market Share, 2020-2032
Figure 45. Brazil Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 46. Argentina Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 47. By Country – Middle East & Africa Automotive Center Stack Display (CSD) Revenue, Market Share, 2020-2032
Figure 48. By Country – Middle East & Africa Automotive Center Stack Display (CSD) Sales, Market Share, 2020-2032
Figure 49. Turkey Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 50. Israel Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 51. Saudi Arabia Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 52. UAE Automotive Center Stack Display (CSD) Revenue, (US$, Mn), 2020-2032
Figure 53. Global Automotive Center Stack Display (CSD) Production Capacity (K Units), 2020-2032
Figure 54. The Percentage of Production Automotive Center Stack Display (CSD) by Region, 2024 VS 2032
Figure 55. Automotive Center Stack Display (CSD) Industry Value Chain
Figure 56. Marketing Channels