Key Statistics
Key Takeaways
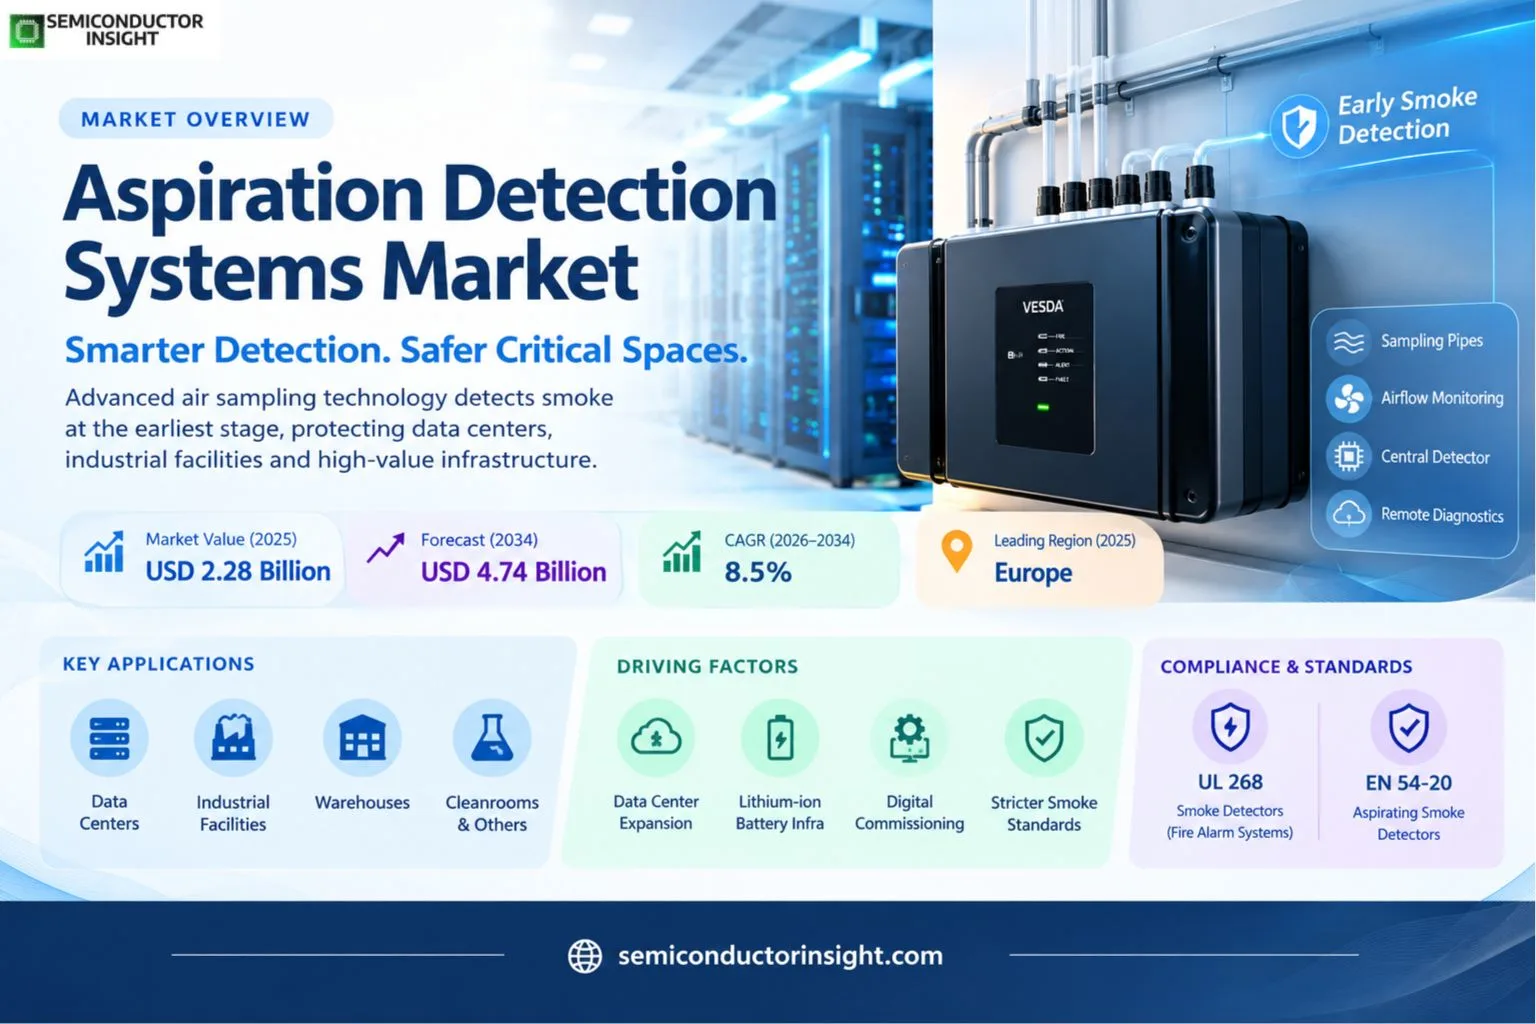
- Market size and growth: the market is valued at USD 2.28 billion in 2025 and is projected to reach USD 4.74 billion by 2034, with a 8.5% CAGR over 2026–2034.
- High Sensitivity Aspiration Detection Systems is the leading type because critical environments value the earliest possible warning, where very low smoke concentrations must be detected before visible smoke develops.
- Data or Comms Rooms is the leading application because high airflow and the financial cost of downtime make very early smoke detection especially valuable in data centers and communications facilities.
- Europe leads regionally, while Asia Pacific offers the strongest incremental growth.
- Primary driver: data-center growth, critical-infrastructure protection and stricter fire-safety requirements are increasing demand for very early warning detection
- Principal restraint: higher installed cost, pipe-network design complexity and shortage of experienced installers can slow adoption
Market Overview
Aspiration detection systems market was valued at USD 2.28 billion in 2025 and is projected to reach USD 4.74 billion by 2034, expanding at a 8.5% CAGR over 2026–2034. Europe leads in 2025, while the market is being reshaped by data-center expansion, lithium-ion battery infrastructure, digital commissioning and tighter smoke-detection standards..
Aspirating smoke detection systems actively draw air through a network of sampling pipes into a centralized detector, allowing smoke to be identified at concentrations below those typically detected by passive point devices. The architecture is especially useful in data centers, cleanrooms, high-bay warehouses, cable spaces and heritage facilities where high airflow, access restrictions or environmental conditions can reduce the effectiveness of conventional detectors.
Critical infrastructure is the strongest demand driver. Honeywell positions VESDA continuous air sampling as an early-warning solution for data centers, while Siemens notes that aspirating detectors can be placed where strong air currents direct smoke. These deployment practices are commercially important because server-room cooling can dilute smoke and delay passive detection, increasing the value of engineered sampling networks.
Regulatory compliance shapes product design and market access. UL Solutions identifies UL 268 for smoke detectors in fire alarm systems and EN 54-20 for aspirating smoke detectors. Suppliers therefore compete not only on sensitivity but also on false-alarm performance, airflow monitoring, network design software, remote diagnostics and certification across major regional standards.
Segment Analysis: By Type
By type, the market is segmented into Normal Aspiration Detection Systems, High Sensitivity Aspiration Detection Systems. High Sensitivity Aspiration Detection Systems holds the leading position based on current application breadth and purchasing economics.
| Type | Function / role | Market position |
|---|---|---|
| Normal Aspiration Detection Systems | Active sampling systems for general early-warning detection across moderate-risk environments. | Used where access or airflow makes point detection difficult but ultra-high sensitivity is not required. |
| High Sensitivity Aspiration Detection Systems | Very early warning systems capable of detecting extremely low smoke concentrations. | Leading type for data centers, cleanrooms and other mission-critical environments where intervention time is valuable. |
Commercial implications by type
High-sensitivity systems justify higher installed cost when downtime, equipment damage or process contamination is expensive. Normal systems address broader commercial and industrial spaces. The economic comparison therefore depends on risk rather than detector price alone: operators of mission-critical sites often value additional warning time more than the upfront premium.
Segment Analysis: By Application
By application, demand is segmented into Private Houses, Data or Comms Rooms, Warehouses, Others. Data or Comms Rooms is the leading use case because it directly connects the technology to measurable operating, safety or performance benefits.
| Application | Demand characteristics |
|---|---|
| Private Houses | A smaller niche where early warning or concealed installations are required. |
| Data or Comms Rooms | Leading application because high airflow and costly electronic assets make early warning critical. |
| Warehouses | High ceilings and large open volumes favor pipe networks that can sample across difficult spaces. |
| Others | Cleanrooms, transport, heritage buildings, cold storage and industrial production create specialized demand. |
By End User
| End User | Commercial relevance |
|---|---|
| Residential | Limited but useful for premium or architecturally sensitive installations. |
| Commercial | Largest end-user base across data centers, offices, retail and public buildings. |
| Industrial | Factories, logistics, cleanrooms and process facilities value harsh-environment capability. |
By Sensitivity Class
| Sensitivity Class | Commercial relevance |
|---|---|
| Very High Sensitivity | Designed for ultra-early warning in high-value or high-airflow environments. |
| Enhanced Sensitivity | Balances early warning with nuisance-alarm control in commercial facilities. |
| Standard Early Warning | Targets broader applications where active sampling is needed without extreme sensitivity. |
By Connectivity
| Connectivity | Commercial relevance |
|---|---|
| Standalone | Local relay outputs and direct alarm-panel integration. |
| Networked | Central monitoring across multiple detectors and zones. |
| Cloud-Connected | Remote diagnostics, event history and service analytics support distributed facilities. |
Regional Analysis
Europe leads the market because Western Europe has mature fire-safety regulation, strong EN 54-20 adoption and widespread use of very early warning systems in data centers, logistics and industrial facilities. Asia Pacific is positioned for the fastest expansion as adoption increases in new data centers, logistics facilities, electronics manufacturing and smart-building infrastructure across China, India and Southeast Asia.
How does regional demand differ across this market?
Europe leads on installed base and standards-driven adoption, while Asia Pacific is expanding fastest as data centers and modern logistics facilities are built at scale. North America is a mature high-value market where UL 268 certification and critical-infrastructure protection are central. South America and the Middle East & Africa are more project-driven, with adoption strongest in data centers, airports, mining, oil and gas and large commercial facilities.
| Region | Position | Growth outlook | Demand profile | Supplier selection |
|---|---|---|---|---|
| Europe | Largest | Strong | Standards and retrofit | EN 54-20 compliance, reliability |
| North America | Second | Strong | Critical infrastructure | UL 268, service and reliability |
| Asia Pacific | Third | Fastest | New data centers and logistics | Cost, scalability and local support |
| South America | Smaller | Moderate | Industrial and commercial projects | Price and technical support |
| Middle East & Africa | Emerging | Strong | Data centers and infrastructure | Ruggedness and integrator support |
Competitive Landscape
Competition includes multinational fire-system companies and specialist aspirating-detection vendors, with sensitivity, false-alarm control, networking and installer support differentiating platforms.
Honeywell’s VESDA platform is one of the best-known very-early-warning systems, while Siemens competes with modular ASD products designed for data centers, high-bay storage and challenging environments. Minimax, Protec, Zeta, WAGNER and other specialists serve regional and application-specific niches.
Digital commissioning is becoming a competitive feature. Siemens promotes app-guided commissioning for its ASD+ family, while Honeywell integrates event logging, network connectivity and adaptive threshold features. These capabilities reduce installer time and support remote service, which can lower lifecycle cost even if hardware prices remain premium.
Certification and installation expertise create durable market barriers. The same detector can perform poorly if pipe routing, hole sizing or airflow calculations are incorrect, so manufacturers with design tools, training and established integrator networks can defend share beyond the hardware itself.
| Competitive tier | Representative participants | Competitive focus |
|---|---|---|
| Global fire-safety leaders | Honeywell / Xtralis, Siemens, Minimax | High-sensitivity platforms, certifications and global support |
| Regional specialists | Protec, Zeta Alarms, WAGNER, Eurofyre | Application-specific systems and local installer networks |
| Local / niche suppliers | Cofem, Saval, Pertronic | Cost-effective and regionally adapted solutions |
Companies Profiled
Xtralis (Honeywell), Siemens AG, Minimax GmbH, Zeta Alarms Limited, Protec Fire and Security Group, Eurofyre Ltd, Saval, Scutum London, Bryland Fire, Zettler Group, Pertronic Industries, WAGNER Group, Cofem
Production Capacity Analysis
Production capacity depends on optical smoke chambers, aspirators, airflow sensors, control electronics, pipe accessories, certified software and regional commissioning support.
The detector itself combines laser or optical sensing, aspirator hardware, filters, electronics and communications. Production is more complex than a basic point detector because airflow measurement and sampling integrity must be verified across a wider operating range. Certification testing also adds time when new platforms or firmware revisions are introduced.
Field capacity is equally important. A large project requires pipe design, installation, commissioning and maintenance expertise. Manufacturers can therefore ship hardware faster than the market can absorb it if trained integrators are scarce. Digital design tools and app-guided commissioning are practical ways to expand effective deployment capacity.
Market Dynamics
The market is moving from specialist fire-detection hardware toward connected, serviceable safety infrastructure with stronger diagnostics and remote visibility.
Data centers and logistics facilities are driving this shift because operators need early warning without excessive nuisance alarms and want systems that can be monitored centrally. Modular detectors, event logs, network connectivity and automated commissioning reduce maintenance burden. At the same time, system design remains site-specific, so software does not eliminate the need for competent fire engineering.
Market Drivers
Drivers Impact Analysis
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Data-center expansion | High | High airflow and expensive electronic assets make early warning economically valuable. |
| Fire-safety standards | High | UL 268 and EN 54-20 create defined performance expectations and encourage certified products. |
| Critical infrastructure protection | High | Hospitals, telecom, transport and industrial facilities value additional response time. |
| Digital commissioning | Medium | Apps, design tools and remote diagnostics reduce lifecycle service effort. |
Data-center expansion
High airflow and expensive electronic assets make early warning economically valuable.
Fire-safety standards
UL 268 and EN 54-20 create defined performance expectations and encourage certified products.
Critical infrastructure protection
Hospitals, telecom, transport and industrial facilities value additional response time.
Digital commissioning
Apps, design tools and remote diagnostics reduce lifecycle service effort.
Market Restraints
Restraints Impact Analysis
| Restraint | Impact | Commercial mechanism |
|---|---|---|
| Higher installed cost | High | Pipe networks, commissioning and premium detectors cost more than conventional point systems. |
| Design complexity | High | Sampling-hole layout and airflow calculations require specialist expertise. |
| Nuisance management | Medium | High sensitivity can increase unwanted alarms if filtration and thresholds are poorly configured. |
| Installer availability | Medium | Limited regional expertise can delay projects and maintenance. |
Higher installed cost
Pipe networks, commissioning and premium detectors cost more than conventional point systems.
Design complexity
Sampling-hole layout and airflow calculations require specialist expertise.
Nuisance management
High sensitivity can increase unwanted alarms if filtration and thresholds are poorly configured.
Installer availability
Limited regional expertise can delay projects and maintenance.
Market Opportunities
Data centers and AI infrastructure
Growing compute density and high airflow make very early warning an increasingly strategic requirement.
Battery energy storage
Off-gas and smoke detection can be integrated into layered thermal-runaway risk management.
Cloud-based monitoring
Remote event history, diagnostics and service analytics can support large distributed portfolios.
Modular retrofit systems
Compact, serviceable detectors can expand adoption in existing buildings where access is difficult.
Supply Chain Analysis
Laser optics, fans, airflow sensors, filters
Electronics, enclosures, firmware
Tubing, sampling points, design software
Panels, commissioning, monitoring, maintenance
Detection components
Optical sensitivity and airflow stability determine early-warning performance and false-alarm control.
Detector assembly
Manufacturers integrate sensing, aspiration, power and communications into certified units.
Pipe network
Sampling design governs how quickly smoke reaches the detector, making software and engineering part of the product value.
Integration and service
Fire panels, remote monitoring and periodic maintenance determine long-term reliability in the field.
Recent Developments
2026 — Siemens expands ASD+ digital commissioning
The ASD+ portfolio uses guided app-based commissioning and modular service components for critical facilities. Source
2026 — Honeywell emphasizes VESDA in data centers
Honeywell positions continuous air sampling as a way to gain earlier warning in high-airflow data-center environments. Source
2026 — UL highlights standards for aspirating smoke detection
UL identifies UL 268 and EN 54-20 among key smoke-detection standards and notes the role of aspiration in data centers. Source
Report Scope & Segmentation
| Attribute | Coverage |
|---|---|
| Market | Aspiration Detection Systems |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| 2025 Market Size | USD 2.28 billion |
| 2026 Estimated Size | USD 2.47 billion |
| 2034 Forecast Size | USD 4.74 billion |
| CAGR | 8.5% (2026–2034) |
| By Type | Normal Aspiration Detection Systems, High Sensitivity Aspiration Detection Systems |
| By Application | Private Houses, Data or Comms Rooms, Warehouses, Others |
| By End User | Residential, Commercial, Industrial |
| By Sensitivity Class | Very High Sensitivity, Enhanced Sensitivity, Standard Early Warning |
| By Connectivity | Standalone, Networked, Cloud-Connected |
| Regions | Europe, North America, Asia Pacific, South America, Middle East & Africa |
| Companies Profiled | Xtralis (Honeywell), Siemens AG, Minimax GmbH, Zeta Alarms Limited, Protec Fire and Security Group, Eurofyre Ltd, Saval, Scutum London, Bryland Fire, Zettler Group, Pertronic Industries, WAGNER Group, Cofem |
Frequently Asked Questions
What is the aspiration detection systems market size in 2025?
The market is valued at USD 2.28 billion in 2025.
What is the projected market size by 2034?
The market is projected to reach USD 4.74 billion by 2034.
What is the CAGR from 2026 to 2034?
The market is expected to expand at a 8.5% CAGR.
Which region leads the market?
Europe is the largest region in 2025.
Which type leads the market?
High Sensitivity Aspiration Detection Systems is the leading type.
Which application leads demand?
Data or Comms Rooms is the leading application.
What is the primary growth driver?
data-center growth, critical-infrastructure protection and stricter fire-safety requirements are increasing demand for very early warning detection.
What is the principal restraint?
higher installed cost, pipe-network design complexity and shortage of experienced installers can slow adoption.
Where are the strongest opportunities?
data centers, battery-energy-storage facilities, cloud monitoring and modular digital commissioning.
Which companies are active in the market?
Xtralis (Honeywell), Siemens AG, Minimax GmbH, Zeta Alarms Limited, Protec Fire and Security Group, Eurofyre Ltd, Saval, Scutum London.
Research Sources & Evidence Base
View primary and industry evidence used in this overview
- Siemens: ASD+ aspirating smoke detector — Critical-infrastructure applications, coverage and digital commissioning.
- Honeywell Building Technologies: Data center fire detection — VESDA early warning and high-airflow data-center context.
- UL Solutions: Fire, smoke and gas device certification — UL 268, EN 54-20 and aspirating smoke detection standards context.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF