SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Yttria-Based Semiconductor Coatings Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
DIELECTRIC MATERIALS Semiconductor Market Research

Yttria-Based Semiconductor Coatings Market

Size, Share & Industry Analysis, By Type (Y2O3 Coating, YOF Coating, YF3 Coating, Composite/Other Yttria Coatings), By Application (Etch Chambers, CVD/PECVD, Ion Implant & Other Process Equipment, Wafer Handling), By Deposition Method (Plasma Spray, Aerosol Deposition, PVD/CVD/ALD, Other), By Component (Chamber Liners, Focus/Edge Rings, Showerheads, Electrostatic Chuck & Handling Parts), and Regional Forecast, 2026-2034

◷
UPDATED 07 October 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE 9b1f345fcc39
▯
FORMATS PDF

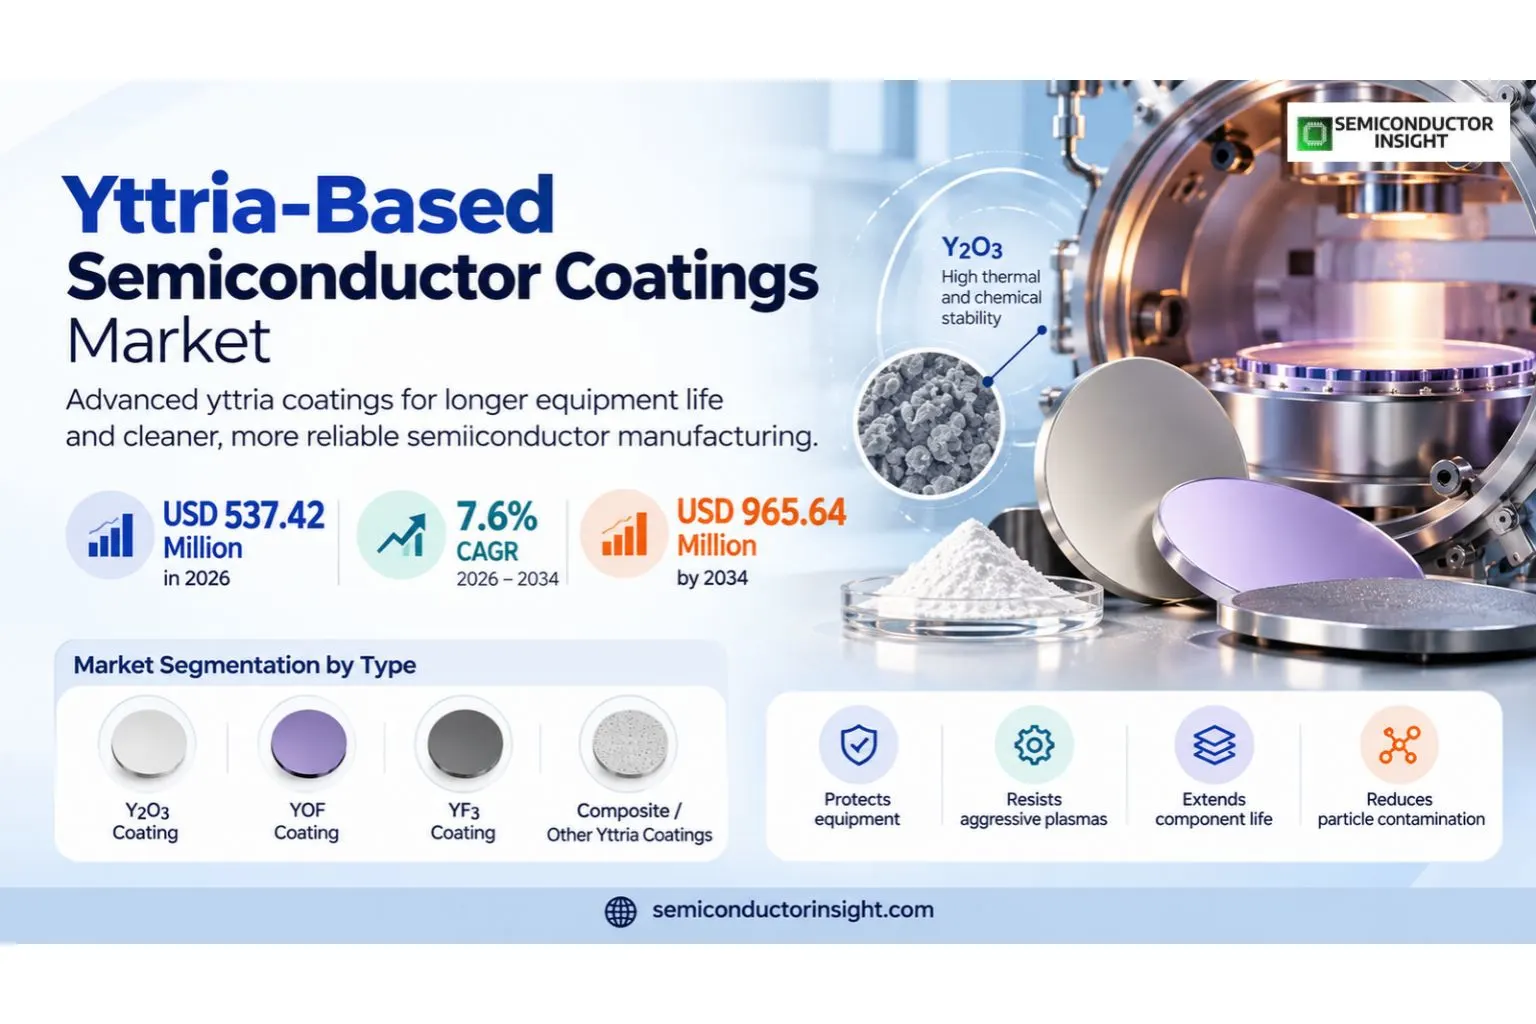
Yttria-based semiconductor coatings market is valued at USD 499.46 million in 2025 and is projected to reach USD 965.64 million by 2034, expanding at a 7.6% CAGR during 2026–2034. The 2026 market level is USD 537.42 million. Yttria-based coatings protect semiconductor process equipment from aggressive halogen plasmas, corrosive gases and erosion. Yttrium oxide and related fluorinated ceramics combine chemical stability, electrical insulation and plasma resistance, helping fabs extend chamber-component life and reduce particle contamination.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 499.46 million
2034 Projected Market Size
USD 965.64 million
CAGR (2026–2034)
7.6%
Largest Market in 2025
Asia Pacific

Key Takeaways

  • Market size: The market is valued at USD 499.46 million in 2025 and is projected to reach USD 965.64 million by 2034, representing a 7.6% CAGR during 2026–2034.
  • Y2O3 Coating remains commercially important because of its established use in core applications.
  • Asia Pacific leads current market value, while Asia Pacific offers a strong growth profile.
  • Etch Chambers is a major demand segment, with purchasing shaped by reliability, performance and system integration.
  • higher-purity YOF/YF3 coatings, denser deposition and lower particle generation is a central competitive theme through 2034.

Yttria-Based Semiconductor Coatings Market Overview

Yttria-based semiconductor coatings market is valued at USD 499.46 million in 2025 and is projected to reach USD 965.64 million by 2034, expanding at a 7.6% CAGR during 2026–2034. The 2026 market level is USD 537.42 million. Yttria-based coatings protect semiconductor process equipment from aggressive halogen plasmas, corrosive gases and erosion. Yttrium oxide and related fluorinated ceramics combine chemical stability, electrical insulation and plasma resistance, helping fabs extend chamber-component life and reduce particle contamination.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values stated in U.S. dollars

The client evidence places the market at USD 431.40 million in 2023 and USD 720.39 million in 2030, with a 7.6% CAGR. Demand is closely tied to etch intensity, deposition complexity and the number of plasma-exposed chamber components in advanced logic and memory manufacturing. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

The market is evolving beyond conventional Y2O3 toward oxyfluoride, fluoride and composite coatings designed for specific plasma chemistries. Performance is evaluated through erosion rate, particle generation, adhesion, purity and coating lifetime rather than one material property. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Segment Analysis: By Type

By type, the market is segmented into Y2O3 Coating, YOF Coating, YF3 Coating, Composite / Other Yttria Coatings. Each category serves a distinct performance, cost or integration requirement, so competitive positioning depends on more than shipment volume. Higher-value variants usually command premium pricing when they reduce system complexity, improve efficiency or satisfy stricter qualification requirements.

Type Commercial role
Y2O3 Coating Established plasma-resistant ceramic coating with high chemical stability and electrical insulation.
YOF Coating Oxyfluoride composition designed to improve resistance and reduce fluorine-related particle generation.
YF3 Coating Fluoride-rich coating used where resistance to aggressive fluorine plasma is critical.
Composite / Other Yttria Coatings Engineered multilayer or mixed ceramic systems targeting specific chamber chemistries and lifetime.

Additional Segmentation: By Deposition Method

Deposition method strongly influences coating density, porosity, adhesion, thickness and particle behavior. Plasma spray offers thick economical layers, while aerosol and vapor-based approaches can provide denser or more conformal coatings for advanced chamber components. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Deposition Method Demand characteristics
Plasma Spray Thick protective coatings widely used on chamber parts.
Aerosol Deposition Dense room-temperature ceramic coatings with fine microstructure.
PVD / CVD / ALD Higher-control thin films and conformal coatings for selected components.
Other Specialized slurry, sintered and hybrid coating approaches.

Segment Analysis: By Application

By application, demand spans Etch Chambers, CVD / PECVD, Ion Implant & Other Process Equipment, Wafer Handling. The mix changes according to performance needs, system value, reliability requirements, regulatory exposure and product lifecycle. This makes application-level analysis more useful than mechanically repeating one market statistic across every segment. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Application Demand characteristics
Etch Chambers Largest technical requirement because halogen plasmas can aggressively erode exposed chamber surfaces.
CVD / PECVD Protects chamber components from corrosive process gases and particle generation.
Ion Implant & Other Process Equipment Specialized use where contamination control and chemical resistance matter.
Wafer Handling Coated ceramic parts can reduce contamination and extend component life in selected handling environments.

Additional Segmentation: By Component

Component-level demand varies with direct plasma exposure, replacement cycle and contamination sensitivity. Parts closest to the active plasma generally justify higher-value coatings because erosion can affect particle counts, chamber stability and yield. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Component Commercial role
Chamber Liners Large-area protection against plasma and reactive gases.
Focus / Edge Rings High-exposure components where erosion can alter process uniformity.
Showerheads Gas-distribution parts requiring clean surfaces and controlled wear.
Electrostatic Chuck & Handling Parts Precision ceramic components where contamination and electrical properties matter.

Regional Analysis

Asia Pacific is expected to dominate because China, Taiwan, South Korea and Japan host the largest concentration of semiconductor fabs and process-equipment supply chains. North America also remains important, with the client evidence placing its 2023 market at USD 112.41 million. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Demand follows plasma-process tool installations, wafer starts and chamber-maintenance cycles. Asia Pacific leads volume, North America contributes advanced logic and memory capacity, and Europe supports specialty semiconductor production and materials technology. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Asia Pacific

Asia Pacific demand is supported by high-volume electronics manufacturing, semiconductor fabrication, automotive production and digital-infrastructure investment. China, Japan, South Korea, Taiwan, India and Southeast Asia contribute different mixes of production, consumption and technical capability, making the region central to both scale and supply-chain development. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

North America

North America remains a high-value market because of strong semiconductor design, aerospace, cloud, enterprise and advanced-manufacturing activity. The United States is the principal contributor, supported by leading technology companies, research institutions and early adoption of premium systems with demanding performance requirements. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Europe

Europe combines advanced automotive, aerospace, industrial, energy and research demand. Germany, France, the United Kingdom, Italy and the Nordic markets emphasize reliability, energy efficiency, safety and regulatory compliance, supporting demand for technically differentiated products with strong lifecycle support. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

South America

South America is a smaller but developing market led by Brazil and selected industrial economies. Demand is concentrated in telecom, infrastructure, industrial modernization, healthcare and consumer electronics, while import dependence makes distributor support, local certification and pricing important commercial factors. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Middle East & Africa

Middle East & Africa remains an emerging market where demand is concentrated in infrastructure, telecom, aviation, defense, energy and data-center projects. Gulf countries account for much of the premium investment, while wider adoption depends on local technical capability, procurement cycles and access to qualified suppliers. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Competitive Landscape

The competitive landscape includes Fujimi, Entegris, Saint-Gobain, Oerlikon, Hansol IONES, Treibacher Industrie, CoorsTek and specialized ceramic-coating suppliers. Supplier position is shaped by technical performance, qualification depth, customer relationships, manufacturing scale, software or application support and the ability to sustain product roadmaps across long customer lifecycles. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

The market rewards suppliers that combine ultra-high-purity feedstock with repeatable deposition, component refurbishment and low-particle performance. Fabs qualify coating processes carefully because a change in surface chemistry can alter chamber condition and wafer defectivity. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Competitive dimension What matters
Technology Performance, integration, roadmap credibility and IP differentiation.
Qualification Customer validation, compliance and field history.
Supply Capacity, lead time, quality consistency and resilience.
Support Application engineering, service and lifecycle management.

Production Capacity Analysis

Capacity includes high-purity yttria powder processing, coating deposition, machining, cleaning and component refurbishment. Because chamber parts often cycle through recoating, regional service centers near major fab clusters can improve turnaround and reduce inventory. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Advanced coating capacity is not fully interchangeable. Plasma-spray, aerosol and vapor-deposition systems produce different microstructures and thicknesses, so suppliers must align equipment capability with customer-specific chamber parts and plasma chemistries. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Market Dynamics

Advanced semiconductor nodes use increasingly aggressive and repeated plasma processes, raising the economic value of chamber protection. Longer component life can reduce maintenance downtime, but coating performance must be balanced against particle generation and contamination risk. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Fabs increasingly evaluate coatings through lifetime cost rather than coating price alone. A more expensive coating can be attractive if it extends chamber uptime, stabilizes process conditions or reduces particle-related wafer loss. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Market Drivers

Growth is driven by new fab capacity, more intensive plasma etch and deposition steps, 3D NAND layer growth and tighter contamination limits. High-purity yttria-based coatings can extend component lifetime in fluorine- and chlorine-rich environments. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Driver Directional impact on CAGR
Technology upgrade cycle +1.8 percentage points
End-market expansion +1.3 percentage points
Higher content per system +0.9 percentage points

Market Restraints

High-purity ceramic materials, specialized deposition equipment and lengthy fab qualification raise cost and entry barriers. Coating defects, adhesion failure or particles can affect wafer yield, so semiconductor customers are conservative when changing qualified suppliers. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Restraint Directional impact on CAGR
Qualification / integration burden -0.8 percentage points
Price pressure -0.6 percentage points
Supply complexity -0.5 percentage points

Market Opportunities

Opportunities include YOF and YF3 coatings, denser aerosol-deposited layers, advanced chamber-part refurbishment and coating solutions optimized for new plasma chemistries. Local service capacity near major fabs can also improve turnaround and customer retention. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Opportunity Commercial significance
higher-purity YOF/YF3 coatings, denser deposition and lower particle generation Supports premium product mix and new design wins.
Regional capacity Improves lead time and supply resilience.
Application engineering Deepens customer integration and raises switching costs.

Supply Chain Analysis

The supply chain starts with high-purity yttrium compounds and ceramic powders, moves through formulation and deposition, then into coated semiconductor process components. After fab use, many components return to specialized service providers for stripping, cleaning, recoating and requalification. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Stage Role
Raw materials High-purity yttria, fluorinated yttrium powders and ceramic feedstock.
Coating deposition Plasma spray, aerosol deposition and controlled thin-film processes.
Component finishing Machining, cleaning, inspection and contamination control.
Fab service loop Installed chamber parts, preventive maintenance and recoating.

The recurring refurbishment loop creates a service-intensive market structure. Supplier quality systems must control not only initial coating performance but also repeated stripping and recoating cycles over the component’s usable life. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Recent Developments in the Yttria-Based Semiconductor Coatings Market

2026 Contamination Control
Entegris continues supplying advanced materials and chamber components focused on contamination control in semiconductor manufacturing.
This development is relevant to lower particle generation, longer chamber life and plasma-resistant ceramic surfaces. Source
2026 Ceramic Materials
CoorsTek continues offering high-purity ceramics for semiconductor process equipment where plasma resistance and cleanliness are required.
This development is relevant to lower particle generation, longer chamber life and plasma-resistant ceramic surfaces. Source
2026 Specialty Ceramics
Saint-Gobain continues developing technical ceramics and coatings for harsh plasma and semiconductor-process environments.
This development is relevant to lower particle generation, longer chamber life and plasma-resistant ceramic surfaces. Source

Report Scope & Segmentation

This analysis covers the Yttria-Based Semiconductor Coatings market from a 2025 base year through the 2026–2034 forecast period. It evaluates demand by product type, application and two additional segmentation axes, with regional coverage spanning Asia Pacific, North America, Europe, South America, and the Middle East & Africa. Commercial decisions in the Yttria-Based Semiconductor Coatings market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.

Scope item Coverage
Base year 2025
Estimated year 2026
Forecast period 2026–2034
By Type Y2O3 Coating, YOF Coating, YF3 Coating, Composite / Other Yttria Coatings
By Application Etch Chambers, CVD / PECVD, Ion Implant & Other Process Equipment, Wafer Handling
By Deposition Method Plasma Spray, Aerosol Deposition, PVD / CVD / ALD, Other
By Component Chamber Liners, Focus / Edge Rings, Showerheads, Electrostatic Chuck & Handling Parts
Key participants Fujimi, Entegris, Saint-Gobain, Oerlikon, Hansol IONES, Treibacher Industrie, CoorsTek and specialized ceramic-coating suppliers

Frequently Asked Questions

What is the Yttria-Based Semiconductor Coatings market size in 2025?

The market is valued at USD 499.46 million in 2025.

What is the market forecast for 2034?

The market is projected to reach USD 965.64 million by 2034, with a 7.6% CAGR during 2026–2034.

Which region leads the market?

Asia Pacific leads current market value, while Asia Pacific has a strong growth profile.

Which type is most important?

Y2O3 Coating is a leading category, although mix varies by application.

Which applications matter most?

Etch Chambers is a major demand segment, alongside CVD / PECVD, Ion Implant & Other Process Equipment.

What technology trend matters most?

higher-purity YOF/YF3 coatings, denser deposition and lower particle generation is a central technology and commercialization trend.

Who are the major suppliers?

Major participants include Fujimi, Entegris, Saint-Gobain, Oerlikon, Hansol IONES, Treibacher Industrie, CoorsTek and specialized ceramic-coating suppliers.

What drives market growth?

Growth is driven by new fab capacity, more intensive plasma etch and deposition steps, 3D NAND layer growth and tighter contamination limits. High-purity yttria-based coatings can extend component lifetime in fluorine- a

What limits growth?

High-purity ceramic materials, specialized deposition equipment and lengthy fab qualification raise cost and entry barriers. Coating defects, adhesion failure or particles can affect wafer yield, so semiconductor custome

What will shape the market through 2034?

Technology roadmaps, qualification, supply continuity and higher-purity YOF/YF3 coatings, denser deposition and lower particle generation will shape competitive outcomes.

Research Sources & Evidence Base

View selected external research sources
  1. Entegris — Semiconductor Materials: Current contamination-control and semiconductor materials context. Open source
  2. CoorsTek — Semiconductor Ceramics: Current high-purity ceramic component context. Open source
  3. Saint-Gobain — Technical Ceramics: Current advanced ceramic materials and coating context. Open source
Yttria-Based Semiconductor Coatings Market Size, Share & Industry Analysis, By Type (Y2O3 Coating, YOF Coating, YF3 Coating, Composite/Other Yttria Coatings), By Application (Etch Chambers, CVD/PECVD, Ion Implant & Other Process Equipment, Wafer Handling), By Deposition Method (Plasma Spray, Aerosol Deposition, PVD/CVD/ALD, Other), By Component (Chamber Liners, Focus/Edge Rings, Showerheads, Electrostatic Chuck & Handling Parts), and Regional Forecast, 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

Table of Contents
1 Research Methodology and Statistical Scope
1.1 Market Definition and Statistical Scope of Yttria-Based Semiconductor Coatings
1.2 Key Market Segments
1.2.1 Yttria-Based Semiconductor Coatings Segment by Type
1.2.2 Yttria-Based Semiconductor Coatings Segment by Application
1.3 Methodology & Sources of Information
1.3.1 Research Methodology
1.3.2 Research Process
1.3.3 Market Breakdown and Data Triangulation
1.3.4 Base Year
1.3.5 Report Assumptions & Caveats
2 Yttria-Based Semiconductor Coatings Market Overview
2.1 Global Market Overview
2.1.1 Global Yttria-Based Semiconductor Coatings Market Size (M USD) Estimates and Forecasts (2026-2034)
2.1.2 Global Yttria-Based Semiconductor Coatings Sales Estimates and Forecasts (2026-2034)
2.2 Market Segment Executive Summary
2.3 Global Market Size by Region
3 Yttria-Based Semiconductor Coatings Market Competitive Landscape
3.1 Global Yttria-Based Semiconductor Coatings Sales by Manufacturers (2019-2025)
3.2 Global Yttria-Based Semiconductor Coatings Revenue Market Share by Manufacturers (2019-2025)
3.3 Yttria-Based Semiconductor Coatings Market Share by Company Type (Tier 1, Tier 2, and Tier 3)
3.4 Global Yttria-Based Semiconductor Coatings Average Price by Manufacturers (2019-2025)
3.5 Manufacturers Yttria-Based Semiconductor Coatings Sales Sites, Area Served, Product Type
3.6 Yttria-Based Semiconductor Coatings Market Competitive Situation and Trends
3.6.1 Yttria-Based Semiconductor Coatings Market Concentration Rate
3.6.2 Global 5 and 10 Largest Yttria-Based Semiconductor Coatings Players Market Share by Revenue
3.6.3 Mergers & Acquisitions, Expansion
4 Yttria-Based Semiconductor Coatings Industry Chain Analysis
4.1 Yttria-Based Semiconductor Coatings Industry Chain Analysis
4.2 Market Overview of Key Raw Materials
4.3 Midstream Market Analysis
4.4 Downstream Customer Analysis
5 The Development and Dynamics of Yttria-Based Semiconductor Coatings Market
5.1 Key Development Trends
5.2 Driving Factors
5.3 Market Challenges
5.4 Market Restraints
5.5 Industry News
5.5.1 New Product Developments
5.5.2 Mergers & Acquisitions
5.5.3 Expansions
5.5.4 Collaboration/Supply Contracts
5.6 Industry Policies
6 Yttria-Based Semiconductor Coatings Market Segmentation by Type
6.1 Evaluation Matrix of Segment Market Development Potential (Type)
6.2 Global Yttria-Based Semiconductor Coatings Sales Market Share by Type (2019-2025)
6.3 Global Yttria-Based Semiconductor Coatings Market Size Market Share by Type (2019-2025)
6.4 Global Yttria-Based Semiconductor Coatings Price by Type (2019-2025)
7 Yttria-Based Semiconductor Coatings Market Segmentation by Application
7.1 Evaluation Matrix of Segment Market Development Potential (Application)
7.2 Global Yttria-Based Semiconductor Coatings Market Sales by Application (2019-2025)
7.3 Global Yttria-Based Semiconductor Coatings Market Size (M USD) by Application (2019-2025)
7.4 Global Yttria-Based Semiconductor Coatings Sales Growth Rate by Application (2019-2025)
8 Yttria-Based Semiconductor Coatings Market Segmentation by Region
8.1 Global Yttria-Based Semiconductor Coatings Sales by Region
8.1.1 Global Yttria-Based Semiconductor Coatings Sales by Region
8.1.2 Global Yttria-Based Semiconductor Coatings Sales Market Share by Region
8.2 North America
8.2.1 North America Yttria-Based Semiconductor Coatings Sales by Country
8.2.2 U.S.
8.2.3 Canada
8.2.4 Mexico
8.3 Europe
8.3.1 Europe Yttria-Based Semiconductor Coatings Sales by Country
8.3.2 Germany
8.3.3 France
8.3.4 U.K.
8.3.5 Italy
8.3.6 Russia
8.4 Asia Pacific
8.4.1 Asia Pacific Yttria-Based Semiconductor Coatings Sales by Region
8.4.2 China
8.4.3 Japan
8.4.4 South Korea
8.4.5 India
8.4.6 Southeast Asia
8.5 South America
8.5.1 South America Yttria-Based Semiconductor Coatings Sales by Country
8.5.2 Brazil
8.5.3 Argentina
8.5.4 Columbia
8.6 Middle East and Africa
8.6.1 Middle East and Africa Yttria-Based Semiconductor Coatings Sales by Region
8.6.2 Saudi Arabia
8.6.3 UAE
8.6.4 Egypt
8.6.5 Nigeria
8.6.6 South Africa
9 Key Companies Profile
9.1 FUJIMI INCORPORATED
9.1.1 FUJIMI INCORPORATED Yttria-Based Semiconductor Coatings Basic Information
9.1.2 FUJIMI INCORPORATED Yttria-Based Semiconductor Coatings Product Overview
9.1.3 FUJIMI INCORPORATED Yttria-Based Semiconductor Coatings Product Market Performance
9.1.4 FUJIMI INCORPORATED Business Overview
9.1.5 FUJIMI INCORPORATED Yttria-Based Semiconductor Coatings SWOT Analysis
9.1.6 FUJIMI INCORPORATED Recent Developments
9.2 Entegris
9.2.1 Entegris Yttria-Based Semiconductor Coatings Basic Information
9.2.2 Entegris Yttria-Based Semiconductor Coatings Product Overview
9.2.3 Entegris Yttria-Based Semiconductor Coatings Product Market Performance
9.2.4 Entegris Business Overview
9.2.5 Entegris Yttria-Based Semiconductor Coatings SWOT Analysis
9.2.6 Entegris Recent Developments
9.3 Hansol IONES
9.3.1 Hansol IONES Yttria-Based Semiconductor Coatings Basic Information
9.3.2 Hansol IONES Yttria-Based Semiconductor Coatings Product Overview
9.3.3 Hansol IONES Yttria-Based Semiconductor Coatings Product Market Performance
9.3.4 Hansol IONES Yttria-Based Semiconductor Coatings SWOT Analysis
9.3.5 Hansol IONES Business Overview
9.3.6 Hansol IONES Recent Developments
9.4 SEWON HARDFACING CO.,LTD
9.4.1 SEWON HARDFACING CO.,LTD Yttria-Based Semiconductor Coatings Basic Information
9.4.2 SEWON HARDFACING CO.,LTD Yttria-Based Semiconductor Coatings Product Overview
9.4.3 SEWON HARDFACING CO.,LTD Yttria-Based Semiconductor Coatings Product Market Performance
9.4.4 SEWON HARDFACING CO.,LTD Business Overview
9.4.5 SEWON HARDFACING CO.,LTD Recent Developments
9.5 Saint-Gobain
9.5.1 Saint-Gobain Yttria-Based Semiconductor Coatings Basic Information
9.5.2 Saint-Gobain Yttria-Based Semiconductor Coatings Product Overview
9.5.3 Saint-Gobain Yttria-Based Semiconductor Coatings Product Market Performance
9.5.4 Saint-Gobain Business Overview
9.5.5 Saint-Gobain Recent Developments
9.6 Oerlikon Balzers
9.6.1 Oerlikon Balzers Yttria-Based Semiconductor Coatings Basic Information
9.6.2 Oerlikon Balzers Yttria-Based Semiconductor Coatings Product Overview
9.6.3 Oerlikon Balzers Yttria-Based Semiconductor Coatings Product Market Performance
9.6.4 Oerlikon Balzers Business Overview
9.6.5 Oerlikon Balzers Recent Developments
9.7 APS Materials
9.7.1 APS Materials Yttria-Based Semiconductor Coatings Basic Information
9.7.2 APS Materials Yttria-Based Semiconductor Coatings Product Overview
9.7.3 APS Materials Yttria-Based Semiconductor Coatings Product Market Performance
9.7.4 APS Materials Business Overview
9.7.5 APS Materials Recent Developments
9.8 Inc.
9.8.1 Inc. Yttria-Based Semiconductor Coatings Basic Information
9.8.2 Inc. Yttria-Based Semiconductor Coatings Product Overview
9.8.3 Inc. Yttria-Based Semiconductor Coatings Product Market Performance
9.8.4 Inc. Business Overview
9.8.5 Inc. Recent Developments
9.9 NGK (NTK CERATE)
9.9.1 NGK (NTK CERATE) Yttria-Based Semiconductor Coatings Basic Information
9.9.2 NGK (NTK CERATE) Yttria-Based Semiconductor Coatings Product Overview
9.9.3 NGK (NTK CERATE) Yttria-Based Semiconductor Coatings Product Market Performance
9.9.4 NGK (NTK CERATE) Business Overview
9.9.5 NGK (NTK CERATE) Recent Developments
9.10 Hansol IONES
9.10.1 Hansol IONES Yttria-Based Semiconductor Coatings Basic Information
9.10.2 Hansol IONES Yttria-Based Semiconductor Coatings Product Overview
9.10.3 Hansol IONES Yttria-Based Semiconductor Coatings Product Market Performance
9.10.4 Hansol IONES Business Overview
9.10.5 Hansol IONES Recent Developments
9.11 FEMVIX CORP.
9.11.1 FEMVIX CORP. Yttria-Based Semiconductor Coatings Basic Information
9.11.2 FEMVIX CORP. Yttria-Based Semiconductor Coatings Product Overview
9.11.3 FEMVIX CORP. Yttria-Based Semiconductor Coatings Product Market Performance
9.11.4 FEMVIX CORP. Business Overview
9.11.5 FEMVIX CORP. Recent Developments
9.12 CINOS
9.12.1 CINOS Yttria-Based Semiconductor Coatings Basic Information
9.12.2 CINOS Yttria-Based Semiconductor Coatings Product Overview
9.12.3 CINOS Yttria-Based Semiconductor Coatings Product Market Performance
9.12.4 CINOS Business Overview
9.12.5 CINOS Recent Developments
9.13 Yeedex
9.13.1 Yeedex Yttria-Based Semiconductor Coatings Basic Information
9.13.2 Yeedex Yttria-Based Semiconductor Coatings Product Overview
9.13.3 Yeedex Yttria-Based Semiconductor Coatings Product Market Performance
9.13.4 Yeedex Business Overview
9.13.5 Yeedex Recent Developments
9.14 YMC Co.
9.14.1 YMC Co. Yttria-Based Semiconductor Coatings Basic Information
9.14.2 YMC Co. Yttria-Based Semiconductor Coatings Product Overview
9.14.3 YMC Co. Yttria-Based Semiconductor Coatings Product Market Performance
9.14.4 YMC Co. Business Overview
9.14.5 YMC Co. Recent Developments
9.15 Ltd.
9.15.1 Ltd. Yttria-Based Semiconductor Coatings Basic Information
9.15.2 Ltd. Yttria-Based Semiconductor Coatings Product Overview
9.15.3 Ltd. Yttria-Based Semiconductor Coatings Product Market Performance
9.15.4 Ltd. Business Overview
9.15.5 Ltd. Recent Developments
9.16 Treibacher Industrie AG
9.16.1 Treibacher Industrie AG Yttria-Based Semiconductor Coatings Basic Information
9.16.2 Treibacher Industrie AG Yttria-Based Semiconductor Coatings Product Overview
9.16.3 Treibacher Industrie AG Yttria-Based Semiconductor Coatings Product Market Performance
9.16.4 Treibacher Industrie AG Business Overview
9.16.5 Treibacher Industrie AG Recent Developments
9.17 Nano Research Elements
9.17.1 Nano Research Elements Yttria-Based Semiconductor Coatings Basic Information
9.17.2 Nano Research Elements Yttria-Based Semiconductor Coatings Product Overview
9.17.3 Nano Research Elements Yttria-Based Semiconductor Coatings Product Market Performance
9.17.4 Nano Research Elements Business Overview
9.17.5 Nano Research Elements Recent Developments
9.18 Coorstek
9.18.1 Coorstek Yttria-Based Semiconductor Coatings Basic Information
9.18.2 Coorstek Yttria-Based Semiconductor Coatings Product Overview
9.18.3 Coorstek Yttria-Based Semiconductor Coatings Product Market Performance
9.18.4 Coorstek Business Overview
9.18.5 Coorstek Recent Developments
9.19 Shin-Etsu Rare Earths
9.19.1 Shin-Etsu Rare Earths Yttria-Based Semiconductor Coatings Basic Information
9.19.2 Shin-Etsu Rare Earths Yttria-Based Semiconductor Coatings Product Overview
9.19.3 Shin-Etsu Rare Earths Yttria-Based Semiconductor Coatings Product Market Performance
9.19.4 Shin-Etsu Rare Earths Business Overview
9.19.5 Shin-Etsu Rare Earths Recent Developments
10 Yttria-Based Semiconductor Coatings Market Forecast by Region
10.1 Global Yttria-Based Semiconductor Coatings Market Size Forecast
10.2 Global Yttria-Based Semiconductor Coatings Market Forecast by Region
10.2.1 North America Market Size Forecast by Country
10.2.2 Europe Yttria-Based Semiconductor Coatings Market Size Forecast by Country
10.2.3 Asia Pacific Yttria-Based Semiconductor Coatings Market Size Forecast by Region
10.2.4 South America Yttria-Based Semiconductor Coatings Market Size Forecast by Country
10.2.5 Middle East and Africa Forecasted Consumption of Yttria-Based Semiconductor Coatings by Country
11 Forecast Market by Type and by Application (2025-2030)
11.1 Global Yttria-Based Semiconductor Coatings Market Forecast by Type (2025-2030)
11.1.1 Global Forecasted Sales of Yttria-Based Semiconductor Coatings by Type (2025-2030)
11.1.2 Global Yttria-Based Semiconductor Coatings Market Size Forecast by Type (2025-2030)
11.1.3 Global Forecasted Price of Yttria-Based Semiconductor Coatings by Type (2025-2030)
11.2 Global Yttria-Based Semiconductor Coatings Market Forecast by Application (2025-2030)
11.2.1 Global Yttria-Based Semiconductor Coatings Sales (K Units) Forecast by Application
11.2.2 Global Yttria-Based Semiconductor Coatings Market Size (M USD) Forecast by Application (2025-2030)
12 Conclusion and Key FindingsList of Tables
Table 1. Introduction of the Type
Table 2. Introduction of the Application
Table 3. Market Size (M USD) Segment Executive Summary
Table 4. Yttria-Based Semiconductor Coatings Market Size Comparison by Region (M USD)
Table 5. Global Yttria-Based Semiconductor Coatings Sales (K Units) by Manufacturers (2019-2025)
Table 6. Global Yttria-Based Semiconductor Coatings Sales Market Share by Manufacturers (2019-2025)
Table 7. Global Yttria-Based Semiconductor Coatings Revenue (M USD) by Manufacturers (2019-2025)
Table 8. Global Yttria-Based Semiconductor Coatings Revenue Share by Manufacturers (2019-2025)
Table 9. Company Type (Tier 1, Tier 2, and Tier 3) & (based on the Revenue in Yttria-Based Semiconductor Coatings as of 2022)
Table 10. Global Market Yttria-Based Semiconductor Coatings Average Price (USD/Unit) of Key Manufacturers (2019-2025)
Table 11. Manufacturers Yttria-Based Semiconductor Coatings Sales Sites and Area Served
Table 12. Manufacturers Yttria-Based Semiconductor Coatings Product Type
Table 13. Global Yttria-Based Semiconductor Coatings Manufacturers Market Concentration Ratio (CR5 and HHI)
Table 14. Mergers & Acquisitions, Expansion Plans
Table 15. Industry Chain Map of Yttria-Based Semiconductor Coatings
Table 16. Market Overview of Key Raw Materials
Table 17. Midstream Market Analysis
Table 18. Downstream Customer Analysis
Table 19. Key Development Trends
Table 20. Driving Factors
Table 21. Yttria-Based Semiconductor Coatings Market Challenges
Table 22. Global Yttria-Based Semiconductor Coatings Sales by Type (K Units)
Table 23. Global Yttria-Based Semiconductor Coatings Market Size by Type (M USD)
Table 24. Global Yttria-Based Semiconductor Coatings Sales (K Units) by Type (2019-2025)
Table 25. Global Yttria-Based Semiconductor Coatings Sales Market Share by Type (2019-2025)
Table 26. Global Yttria-Based Semiconductor Coatings Market Size (M USD) by Type (2019-2025)
Table 27. Global Yttria-Based Semiconductor Coatings Market Size Share by Type (2019-2025)
Table 28. Global Yttria-Based Semiconductor Coatings Price (USD/Unit) by Type (2019-2025)
Table 29. Global Yttria-Based Semiconductor Coatings Sales (K Units) by Application
Table 30. Global Yttria-Based Semiconductor Coatings Market Size by Application
Table 31. Global Yttria-Based Semiconductor Coatings Sales by Application (2019-2025) & (K Units)
Table 32. Global Yttria-Based Semiconductor Coatings Sales Market Share by Application (2019-2025)
Table 33. Global Yttria-Based Semiconductor Coatings Sales by Application (2019-2025) & (M USD)
Table 34. Global Yttria-Based Semiconductor Coatings Market Share by Application (2019-2025)
Table 35. Global Yttria-Based Semiconductor Coatings Sales Growth Rate by Application (2019-2025)
Table 36. Global Yttria-Based Semiconductor Coatings Sales by Region (2019-2025) & (K Units)
Table 37. Global Yttria-Based Semiconductor Coatings Sales Market Share by Region (2019-2025)
Table 38. North America Yttria-Based Semiconductor Coatings Sales by Country (2019-2025) & (K Units)
Table 39. Europe Yttria-Based Semiconductor Coatings Sales by Country (2019-2025) & (K Units)
Table 40. Asia Pacific Yttria-Based Semiconductor Coatings Sales by Region (2019-2025) & (K Units)
Table 41. South America Yttria-Based Semiconductor Coatings Sales by Country (2019-2025) & (K Units)
Table 42. Middle East and Africa Yttria-Based Semiconductor Coatings Sales by Region (2019-2025) & (K Units)
Table 43. FUJIMI INCORPORATED Yttria-Based Semiconductor Coatings Basic Information
Table 44. FUJIMI INCORPORATED Yttria-Based Semiconductor Coatings Product Overview
Table 45. FUJIMI INCORPORATED Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 46. FUJIMI INCORPORATED Business Overview
Table 47. FUJIMI INCORPORATED Yttria-Based Semiconductor Coatings SWOT Analysis
Table 48. FUJIMI INCORPORATED Recent Developments
Table 49. Entegris Yttria-Based Semiconductor Coatings Basic Information
Table 50. Entegris Yttria-Based Semiconductor Coatings Product Overview
Table 51. Entegris Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 52. Entegris Business Overview
Table 53. Entegris Yttria-Based Semiconductor Coatings SWOT Analysis
Table 54. Entegris Recent Developments
Table 55. Hansol IONES Yttria-Based Semiconductor Coatings Basic Information
Table 56. Hansol IONES Yttria-Based Semiconductor Coatings Product Overview
Table 57. Hansol IONES Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 58. Hansol IONES Yttria-Based Semiconductor Coatings SWOT Analysis
Table 59. Hansol IONES Business Overview
Table 60. Hansol IONES Recent Developments
Table 61. SEWON HARDFACING CO.,LTD Yttria-Based Semiconductor Coatings Basic Information
Table 62. SEWON HARDFACING CO.,LTD Yttria-Based Semiconductor Coatings Product Overview
Table 63. SEWON HARDFACING CO.,LTD Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 64. SEWON HARDFACING CO.,LTD Business Overview
Table 65. SEWON HARDFACING CO.,LTD Recent Developments
Table 66. Saint-Gobain Yttria-Based Semiconductor Coatings Basic Information
Table 67. Saint-Gobain Yttria-Based Semiconductor Coatings Product Overview
Table 68. Saint-Gobain Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 69. Saint-Gobain Business Overview
Table 70. Saint-Gobain Recent Developments
Table 71. Oerlikon Balzers Yttria-Based Semiconductor Coatings Basic Information
Table 72. Oerlikon Balzers Yttria-Based Semiconductor Coatings Product Overview
Table 73. Oerlikon Balzers Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 74. Oerlikon Balzers Business Overview
Table 75. Oerlikon Balzers Recent Developments
Table 76. APS Materials Yttria-Based Semiconductor Coatings Basic Information
Table 77. APS Materials Yttria-Based Semiconductor Coatings Product Overview
Table 78. APS Materials Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 79. APS Materials Business Overview
Table 80. APS Materials Recent Developments
Table 81. Inc. Yttria-Based Semiconductor Coatings Basic Information
Table 82. Inc. Yttria-Based Semiconductor Coatings Product Overview
Table 83. Inc. Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 84. Inc. Business Overview
Table 85. Inc. Recent Developments
Table 86. NGK (NTK CERATE) Yttria-Based Semiconductor Coatings Basic Information
Table 87. NGK (NTK CERATE) Yttria-Based Semiconductor Coatings Product Overview
Table 88. NGK (NTK CERATE) Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 89. NGK (NTK CERATE) Business Overview
Table 90. NGK (NTK CERATE) Recent Developments
Table 91. Hansol IONES Yttria-Based Semiconductor Coatings Basic Information
Table 92. Hansol IONES Yttria-Based Semiconductor Coatings Product Overview
Table 93. Hansol IONES Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 94. Hansol IONES Business Overview
Table 95. Hansol IONES Recent Developments
Table 96. FEMVIX CORP. Yttria-Based Semiconductor Coatings Basic Information
Table 97. FEMVIX CORP. Yttria-Based Semiconductor Coatings Product Overview
Table 98. FEMVIX CORP. Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 99. FEMVIX CORP. Business Overview
Table 100. FEMVIX CORP. Recent Developments
Table 101. CINOS Yttria-Based Semiconductor Coatings Basic Information
Table 102. CINOS Yttria-Based Semiconductor Coatings Product Overview
Table 103. CINOS Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 104. CINOS Business Overview
Table 105. CINOS Recent Developments
Table 106. Yeedex Yttria-Based Semiconductor Coatings Basic Information
Table 107. Yeedex Yttria-Based Semiconductor Coatings Product Overview
Table 108. Yeedex Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 109. Yeedex Business Overview
Table 110. Yeedex Recent Developments
Table 111. YMC Co. Yttria-Based Semiconductor Coatings Basic Information
Table 112. YMC Co. Yttria-Based Semiconductor Coatings Product Overview
Table 113. YMC Co. Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 114. YMC Co. Business Overview
Table 115. YMC Co. Recent Developments
Table 116. Ltd. Yttria-Based Semiconductor Coatings Basic Information
Table 117. Ltd. Yttria-Based Semiconductor Coatings Product Overview
Table 118. Ltd. Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 119. Ltd. Business Overview
Table 120. Ltd. Recent Developments
Table 121. Treibacher Industrie AG Yttria-Based Semiconductor Coatings Basic Information
Table 122. Treibacher Industrie AG Yttria-Based Semiconductor Coatings Product Overview
Table 123. Treibacher Industrie AG Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 124. Treibacher Industrie AG Business Overview
Table 125. Treibacher Industrie AG Recent Developments
Table 126. Nano Research Elements Yttria-Based Semiconductor Coatings Basic Information
Table 127. Nano Research Elements Yttria-Based Semiconductor Coatings Product Overview
Table 128. Nano Research Elements Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 129. Nano Research Elements Business Overview
Table 130. Nano Research Elements Recent Developments
Table 131. Coorstek Yttria-Based Semiconductor Coatings Basic Information
Table 132. Coorstek Yttria-Based Semiconductor Coatings Product Overview
Table 133. Coorstek Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 134. Coorstek Business Overview
Table 135. Coorstek Recent Developments
Table 136. Shin-Etsu Rare Earths Yttria-Based Semiconductor Coatings Basic Information
Table 137. Shin-Etsu Rare Earths Yttria-Based Semiconductor Coatings Product Overview
Table 138. Shin-Etsu Rare Earths Yttria-Based Semiconductor Coatings Sales (K Units), Revenue (M USD), Price (USD/Unit) and Gross Margin (2019-2025)
Table 139. Shin-Etsu Rare Earths Business Overview
Table 140. Shin-Etsu Rare Earths Recent Developments
Table 141. Global Yttria-Based Semiconductor Coatings Sales Forecast by Region (2025-2030) & (K Units)
Table 142. Global Yttria-Based Semiconductor Coatings Market Size Forecast by Region (2025-2030) & (M USD)
Table 143. North America Yttria-Based Semiconductor Coatings Sales Forecast by Country (2025-2030) & (K Units)
Table 144. North America Yttria-Based Semiconductor Coatings Market Size Forecast by Country (2025-2030) & (M USD)
Table 145. Europe Yttria-Based Semiconductor Coatings Sales Forecast by Country (2025-2030) & (K Units)
Table 146. Europe Yttria-Based Semiconductor Coatings Market Size Forecast by Country (2025-2030) & (M USD)
Table 147. Asia Pacific Yttria-Based Semiconductor Coatings Sales Forecast by Region (2025-2030) & (K Units)
Table 148. Asia Pacific Yttria-Based Semiconductor Coatings Market Size Forecast by Region (2025-2030) & (M USD)
Table 149. South America Yttria-Based Semiconductor Coatings Sales Forecast by Country (2025-2030) & (K Units)
Table 150. South America Yttria-Based Semiconductor Coatings Market Size Forecast by Country (2025-2030) & (M USD)
Table 151. Middle East and Africa Yttria-Based Semiconductor Coatings Consumption Forecast by Country (2025-2030) & (Units)
Table 152. Middle East and Africa Yttria-Based Semiconductor Coatings Market Size Forecast by Country (2025-2030) & (M USD)
Table 153. Global Yttria-Based Semiconductor Coatings Sales Forecast by Type (2025-2030) & (K Units)
Table 154. Global Yttria-Based Semiconductor Coatings Market Size Forecast by Type (2025-2030) & (M USD)
Table 155. Global Yttria-Based Semiconductor Coatings Price Forecast by Type (2025-2030) & (USD/Unit)
Table 156. Global Yttria-Based Semiconductor Coatings Sales (K Units) Forecast by Application (2025-2030)
Table 157. Global Yttria-Based Semiconductor Coatings Market Size Forecast by Application (2025-2030) & (M USD)
List of Figures
Figure 1. Product Picture of Yttria-Based Semiconductor Coatings
Figure 2. Data Triangulation
Figure 3. Key Caveats
Figure 4. Global Yttria-Based Semiconductor Coatings Market Size (M USD), 2026-2034
Figure 5. Global Yttria-Based Semiconductor Coatings Market Size (M USD) (2026-2034)
Figure 6. Global Yttria-Based Semiconductor Coatings Sales (K Units) & (2026-2034)
Figure 7. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 8. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 9. Evaluation Matrix of Regional Market Development Potential
Figure 10. Yttria-Based Semiconductor Coatings Market Size by Country (M USD)
Figure 11. Yttria-Based Semiconductor Coatings Sales Share by Manufacturers in 2023
Figure 12. Global Yttria-Based Semiconductor Coatings Revenue Share by Manufacturers in 2023
Figure 13. Yttria-Based Semiconductor Coatings Market Share by Company Type (Tier 1, Tier 2 and Tier 3): 2023
Figure 14. Global Market Yttria-Based Semiconductor Coatings Average Price (USD/Unit) of Key Manufacturers in 2023
Figure 15. The Global 5 and 10 Largest Players: Market Share by Yttria-Based Semiconductor Coatings Revenue in 2023
Figure 16. Evaluation Matrix of Segment Market Development Potential (Type)
Figure 17. Global Yttria-Based Semiconductor Coatings Market Share by Type
Figure 18. Sales Market Share of Yttria-Based Semiconductor Coatings by Type (2019-2025)
Figure 19. Sales Market Share of Yttria-Based Semiconductor Coatings by Type in 2023
Figure 20. Market Size Share of Yttria-Based Semiconductor Coatings by Type (2019-2025)
Figure 21. Market Size Market Share of Yttria-Based Semiconductor Coatings by Type in 2023
Figure 22. Evaluation Matrix of Segment Market Development Potential (Application)
Figure 23. Global Yttria-Based Semiconductor Coatings Market Share by Application
Figure 24. Global Yttria-Based Semiconductor Coatings Sales Market Share by Application (2019-2025)
Figure 25. Global Yttria-Based Semiconductor Coatings Sales Market Share by Application in 2023
Figure 26. Global Yttria-Based Semiconductor Coatings Market Share by Application (2019-2025)
Figure 27. Global Yttria-Based Semiconductor Coatings Market Share by Application in 2023
Figure 28. Global Yttria-Based Semiconductor Coatings Sales Growth Rate by Application (2019-2025)
Figure 29. Global Yttria-Based Semiconductor Coatings Sales Market Share by Region (2019-2025)
Figure 30. North America Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 31. North America Yttria-Based Semiconductor Coatings Sales Market Share by Country in 2023
Figure 32. U.S. Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 33. Canada Yttria-Based Semiconductor Coatings Sales (K Units) and Growth Rate (2019-2025)
Figure 34. Mexico Yttria-Based Semiconductor Coatings Sales (Units) and Growth Rate (2019-2025)
Figure 35. Europe Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 36. Europe Yttria-Based Semiconductor Coatings Sales Market Share by Country in 2023
Figure 37. Germany Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 38. France Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 39. U.K. Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 40. Italy Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 41. Russia Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 42. Asia Pacific Yttria-Based Semiconductor Coatings Sales and Growth Rate (K Units)
Figure 43. Asia Pacific Yttria-Based Semiconductor Coatings Sales Market Share by Region in 2023
Figure 44. China Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 45. Japan Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 46. South Korea Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 47. India Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 48. Southeast Asia Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 49. South America Yttria-Based Semiconductor Coatings Sales and Growth Rate (K Units)
Figure 50. South America Yttria-Based Semiconductor Coatings Sales Market Share by Country in 2023
Figure 51. Brazil Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 52. Argentina Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 53. Columbia Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 54. Middle East and Africa Yttria-Based Semiconductor Coatings Sales and Growth Rate (K Units)
Figure 55. Middle East and Africa Yttria-Based Semiconductor Coatings Sales Market Share by Region in 2023
Figure 56. Saudi Arabia Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 57. UAE Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 58. Egypt Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 59. Nigeria Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 60. South Africa Yttria-Based Semiconductor Coatings Sales and Growth Rate (2019-2025) & (K Units)
Figure 61. Global Yttria-Based Semiconductor Coatings Sales Forecast by Volume (2026-2034) & (K Units)
Figure 62. Global Yttria-Based Semiconductor Coatings Market Size Forecast by Value (2026-2034) & (M USD)
Figure 63. Global Yttria-Based Semiconductor Coatings Sales Market Share Forecast by Type (2025-2030)
Figure 64. Global Yttria-Based Semiconductor Coatings Market Share Forecast by Type (2025-2030)
Figure 65. Global Yttria-Based Semiconductor Coatings Sales Forecast by Application (2025-2030)
Figure 66. Global Yttria-Based Semiconductor Coatings Market Share Forecast by Application (2025-2030)