Key Statistics
Key Takeaways
- Power banks below 20,000 mAh form the mainstream product tier because they balance portability, airline travel limits, smartphone charging needs and manageable device weight. Higher-capacity products serve longer-duration travel and multi-device use, but the commercial center of gravity remains around compact 5,000–10,000 mAh magnetic and Qi-compatible designs that can be carried easily with a phone.
- Household and personal use is the largest application because wireless power banks are purchased primarily as consumer accessories for smartphones, earbuds and related devices. Commercial demand from hospitality, events, rental services and shared charging environments adds a secondary opportunity, but it is more fragmented and places greater emphasis on durability, asset management and charging-cycle reliability.
- Qi has become the dominant technology framework as the Wireless Power Consortium expanded Qi certification and introduced magnetic alignment through Qi2. Qi2 delivers up to 15 W in its first generation, while Qi2 25W was introduced in July 2025, raising wireless charging speed and giving accessory brands a clearer standards-based path for premium magnetic power-bank products.
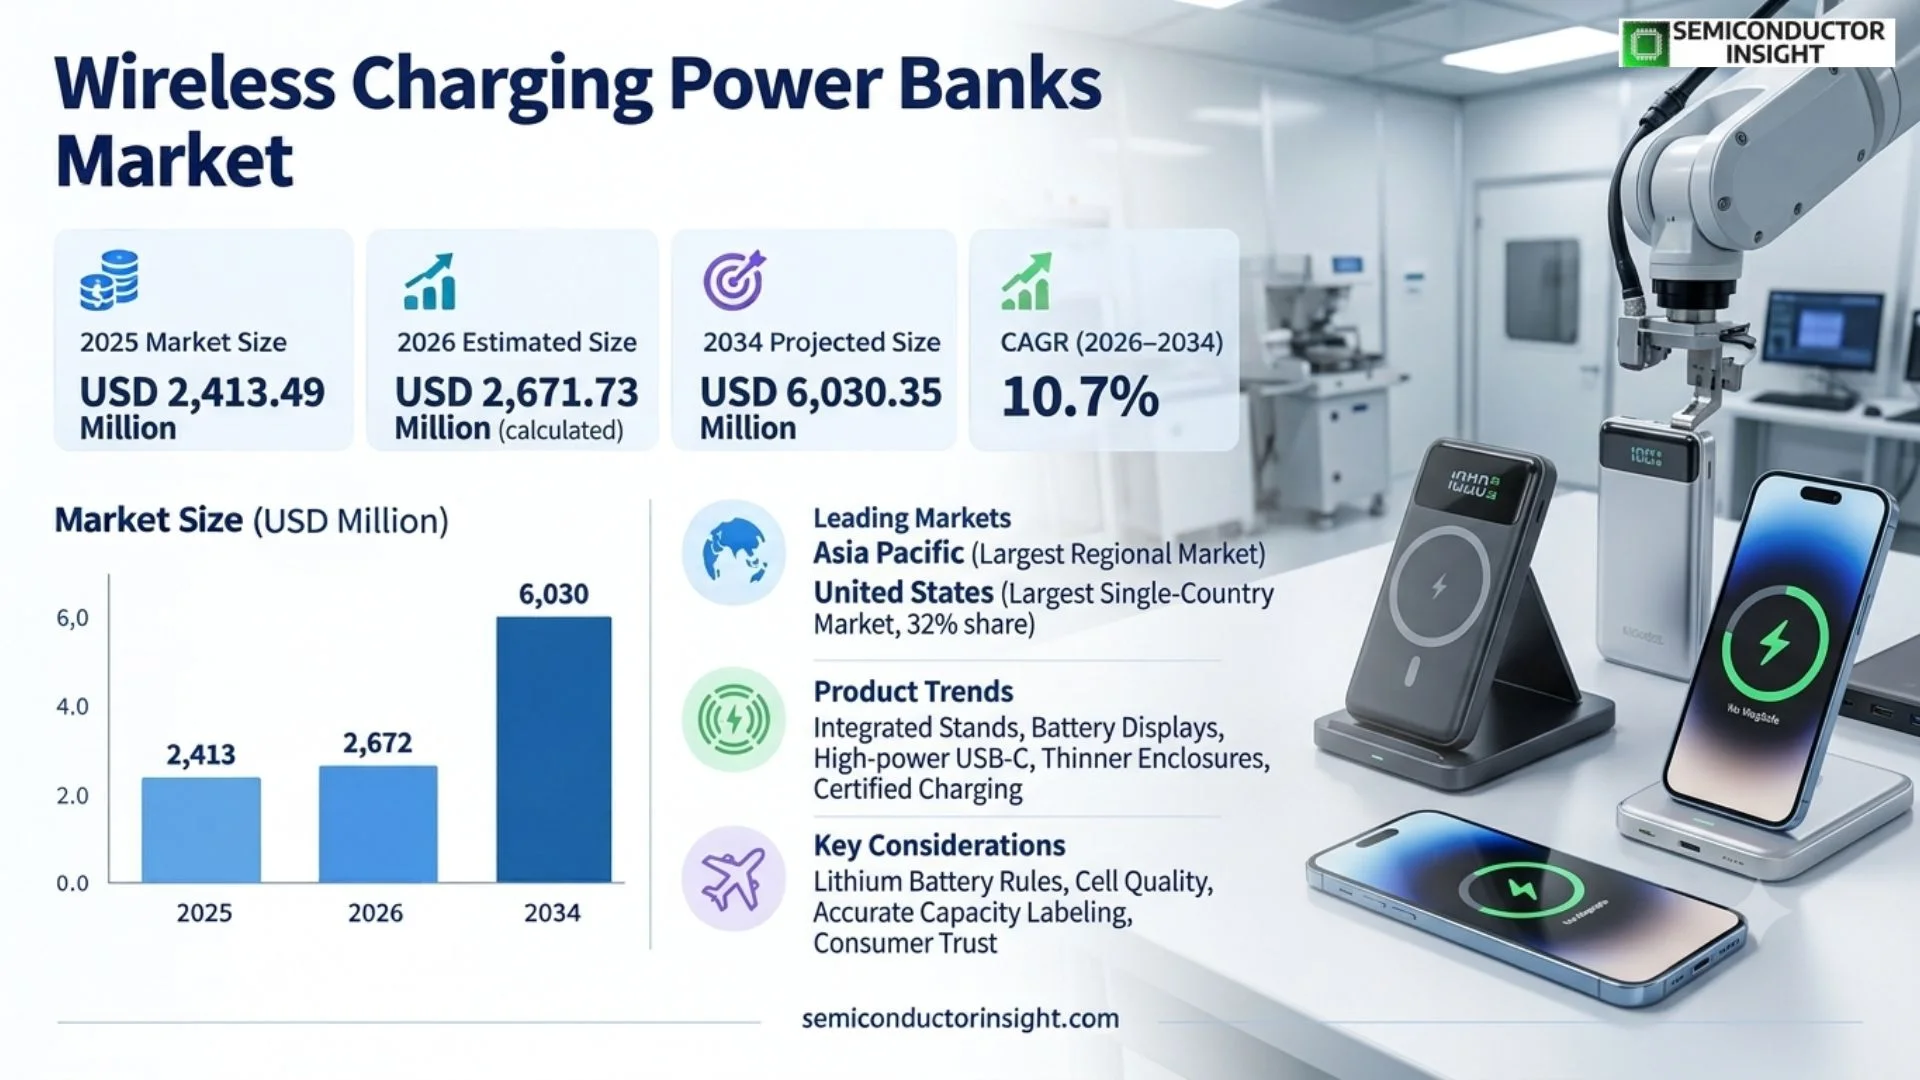
- Asia Pacific is the largest regional market because the region combines the world’s largest consumer-electronics manufacturing ecosystem, a dense accessory-brand base and rapid smartphone adoption. The United States remains the largest single-country market in the source scope with a 32% share, supported by strong iPhone penetration, premium accessory spending and widespread magnetic wireless-charging adoption.
- Safety, thermal performance and travel regulation are the main constraints. Power banks contain lithium-ion batteries and must comply with transport rules, protection requirements and airline carry-on restrictions. IATA guidance treats power banks as spare batteries that belong in carry-on baggage, so cell quality, protection electronics, accurate capacity labeling and thermal management are central to brand trust.
Wireless Charging Power Banks Market Overview
Wireless Charging Power Banks Market was valued at USD 2,413.49 million in 2025 and is projected to reach USD 6,030.35 million by 2034, expanding at a 10.7% CAGR during 2026–2034. Asia Pacific is the largest regional market, while the United States is the largest single-country market in the source scope with a reported 32% share.
Wireless charging power banks combine a rechargeable lithium-ion battery pack with an inductive charging transmitter so a compatible smartphone or accessory can receive power without a cable. Most products also include USB-C input and output, which allows the same pack to provide higher-efficiency wired charging when speed or device power requirements exceed the wireless path. The category therefore competes on convenience, portability, safety, charging standards, thermal behavior and industrial design rather than stored energy alone.
Magnetic alignment has changed the category by making a power bank easier to use while attached to a phone. Qi2, administered by the Wireless Power Consortium, provides a standards-based magnetic charging framework and reduces the alignment uncertainty that limited earlier generic Qi accessories. First-generation Qi2 products support up to 15 W, while Qi2 25W was introduced in July 2025, giving brands a new performance tier that can support premium product refreshes if thermal performance remains controlled.
The market is unusually fast-moving because electronics supply chains can copy successful form factors quickly. Once magnets, coils, charging controllers and high-density cells are widely available, basic designs become commoditized and price competition intensifies. Leading brands respond by integrating stands, battery-percentage displays, higher-power USB-C ports, thinner enclosures and certified charging behavior. Safety and travel rules also matter because the product contains lithium batteries and is routinely carried on aircraft, making cell quality and accurate capacity labeling central to consumer trust.
Segment Analysis: By Type
By capacity type, the market is segmented into Less than 20000 mAh and Above 20000 mAh. The below-20,000 mAh segment represents the mainstream market because smartphone users prioritize portability and travel convenience, with 5,000–10,000 mAh magnetic products forming a particularly active premium tier. Higher-capacity products target extended travel, multi-device charging and users who value autonomy over compact size.
| Capacity type | Product role | Market position |
|---|---|---|
| Less than 20000 mAh | This segment covers the mainstream portable range used for smartphone and earbud charging, including thin magnetic packs and common 5,000–10,000 mAh products. The value proposition is mobility: users want enough stored energy for daily travel or one to two phone recharges without carrying a heavy battery. The format also aligns well with airline travel because most products remain far below the 100 Wh threshold used in passenger battery rules. | Largest product tier. Compact Qi2-compatible 10,000 mAh products from brands such as Anker, Belkin and Samsung show where premium development is concentrated. The segment benefits from frequent consumer replacement cycles, new smartphone launches and strong online merchandising. Competition is intense, so brands differentiate through magnetic alignment, charging speed, device thickness, thermal behavior, displays, integrated stands and USB-C output power. |
| Above 20000 mAh | Higher-capacity products target travelers, field workers and users charging multiple devices over longer periods. The larger cell pack can support more wired energy delivery and longer autonomy, but it increases weight, thermal-management requirements and transport considerations. Product design must balance wireless convenience with the efficiency losses inherent in inductive transfer because a large nominal battery does not translate directly into equivalent energy delivered to the phone. | Smaller but higher-ticket segment. Growth is supported by multi-device lifestyles and travel, but the segment faces stronger regulatory and portability trade-offs. Larger-capacity units can approach airline watt-hour limits depending on cell configuration, making accurate labeling and travel guidance important. Vendors increasingly combine wireless charging with high-power USB-C ports so the product can serve both phones and larger electronics without relying on wireless transfer for every device. |
Charging speed and product architecture
Product differentiation increasingly depends on the combination of wireless and wired power rather than on battery capacity alone. Anker’s 10,000 mAh MagGo design, for example, combines Qi2-certified 15 W wireless charging with 27 W USB-C output. This architecture reflects how the category is evolving: wireless charging handles convenient phone use, while USB-C provides a faster and more efficient path for top-ups, tablets or other devices. Integrated stands, displays and cables create additional value without materially increasing stored energy.
Segment Analysis: By Application
By application, the market is segmented into Household and Commercial. Household use is the dominant application because most purchases are personal smartphone accessories for commuting, travel and backup power. Commercial demand includes hospitality, shared charging, events, workplaces and rental fleets, where durability, multi-device compatibility, cycle life and asset management become more important than minimal size or fashion-oriented design.
| Application | Demand characteristics |
|---|---|
| Household | Largest application. Consumers buy wireless power banks as personal smartphone accessories for commuting, travel, events and everyday backup. Purchasing is influenced by phone compatibility, magnetic alignment, size, charging speed, design and brand reputation. The household channel also responds quickly to smartphone launches because new device generations can change magnetic alignment, supported wireless power levels or USB-C charging behavior, encouraging accessory replacement. |
| Commercial | Commercial demand includes hospitality, shared charging services, promotional products, event venues, workplaces and rental environments. These buyers emphasize durability, cycle life, asset control and the ability to serve many phone models rather than a single user’s preferred device. Although the segment is smaller, it can support recurring fleet purchases and centralized procurement. Qi compatibility is valuable because it reduces connector dependence and supports a broad installed base of smartphones. |
Regional Analysis
Asia Pacific is the largest regional wireless charging power banks market in 2025 because it combines a vast smartphone user base with the world’s principal battery-pack and accessory manufacturing ecosystem. North America is a major premium region and contains the United States, the largest single-country market in the source scope with a 32% share. Europe is regulation-led, while South America and Middle East & Africa present more value- and travel-driven demand profiles.
How does regional demand differ across the wireless charging power banks market?
The regional market is shaped by different combinations of manufacturing scale, smartphone ecosystems, travel patterns and regulation. Asia Pacific leads in supply-chain depth and rapid product iteration; North America emphasizes premium magnetic accessories and strong brand distribution; Europe places greater weight on battery regulation and product documentation. South America is more price sensitive, while parts of the Middle East and Africa value travel convenience, heat tolerance and backup power reliability. Those differences affect both product design and channel strategy.
| Region | Position | Growth outlook | Demand profile | Supplier-selection logic |
|---|---|---|---|---|
| Asia Pacific | Largest region | Highest | Manufacturing and mass consumer adoption | Scale of accessory manufacturing, e-commerce and smartphone users creates intense competition and fast product iteration. |
| North America | Largest single-country market in U.S. | High | Premium magnetic accessories and iPhone ecosystem | Qi2 compatibility, brand trust, retail distribution and safety certifications strongly influence purchasing. |
| Europe | Large mature market | Moderate to high | Premium accessories and regulatory compliance | Battery regulation, consumer safety, USB-C adoption and sustainability requirements shape product design and labeling. |
| South America | Growth market | Moderate | Value-focused mobile accessory demand | Price, local retail availability and compatibility across Android and iPhone devices are central to adoption. |
| Middle East & Africa | Emerging | Moderate | Travel, premium retail and mobile-first demand | Charging availability, heat conditions, travel use and distributor coverage create country-specific opportunities. |
Key Wireless Charging Power Bank Manufacturers and Competitive Landscape
Competition is fragmented across global accessory brands, smartphone manufacturers and high-volume Asian suppliers. Brands such as Anker and Belkin compete through Qi2 certification, industrial design, charging speed and global retail reach, while Samsung can bundle accessories into a broader handset ecosystem. Value suppliers compete aggressively on capacity and price, which makes safety reputation, certification, warranty and real-world thermal performance important defenses against commoditization.
The technical barrier to entry is moderate because cells, wireless-charging controllers, coils, magnets and USB-C components are widely available. The commercial barrier is higher. A successful product must coordinate magnetic force, coil alignment, enclosure thickness, thermal dissipation, cell protection and firmware power negotiation while passing channel and safety requirements. A design that overheats, disconnects intermittently or performs poorly through common phone cases can generate negative reviews quickly, making quality control and compatibility testing central to brand economics.
Standards are redistributing competitive advantage. Qi2 allows multiple brands to offer similar magnetic charging functionality, which reduces the exclusivity of proprietary alignment systems but increases the value of certified interoperability. As common performance levels spread, suppliers need other differentiation such as thinner packaging, stronger USB-C output, better battery displays, integrated stands or longer warranties. Qi2 25W creates a new premium cycle, yet higher power also raises thermal challenges that can separate well-engineered products from specification-led copies.
Distribution is another major competitive layer. Online marketplaces provide rapid global reach and make technical specifications highly visible, but they also intensify price comparison. Established companies use direct websites, electronics retailers and recognized warranties to sustain premium positioning. Smartphone-OEM accessories such as Samsung’s wireless battery pack benefit from ecosystem trust, while specialist brands can move faster on form factor and charging features. Private-label and unbranded suppliers remain important at the low end, particularly in price-sensitive regions.
Tier structure
| Competitive tier | Representative companies | How they compete |
|---|---|---|
| Premium global accessory leaders | Anker Innovations; Belkin International; Scosche Industries; ZAGG Inc. | Compete through Qi2 certification, product design, thermal management, strong USB-C capability, warranties and global retail or direct-to-consumer distribution. They target users willing to pay for predictable compatibility and safety. |
| Device and electronics ecosystem brands | Samsung Electronics; Panasonic Corporation | Leverage broader electronics brands, channel relationships and consumer trust. Their advantage is strongest when accessories are marketed as a natural extension of phones and other devices rather than as stand-alone battery products. |
| Value and specialist accessory brands | AUKEY; Kenu; Nillkin; Mipow; HOCO Technology | Compete on price, rapid product iteration and broad e-commerce distribution. Their challenge is defending margin once common Qi2 features are widely available, which increases the importance of design, channel reputation and after-sales support. |
Key companies profiled
The report profiles Anker Innovations, Belkin International, AUKEY, Scosche Industries, Kenu, ZAGG Inc., Nillkin, Samsung Electronics, Mipow, Panasonic Corporation, and HOCO Technology. The group spans premium accessory brands, smartphone and electronics companies, and value-focused suppliers. This mix reflects a market where battery-pack engineering is only one part of competition; standards certification, industrial design, retail trust, digital marketing, safety performance and speed of product refresh can be equally important to commercial success.
Wireless Charging Power Banks Production Capacity Analysis
Production capacity is concentrated in the Asian consumer-electronics supply chain, particularly China, where battery-pack assembly, PCB manufacturing, magnets, coils, charging controllers, enclosures and contract manufacturing can be sourced in close proximity. This ecosystem allows rapid scale-up when a new smartphone or Qi standard creates demand, but it also makes basic designs easy to replicate and intensifies price competition.
Cell supply and quality are the most important upstream capacity variables because battery energy density, cycle life and safety determine the product’s core performance. Power-bank assemblers can source cells from multiple manufacturers, but changing a cell can affect thermal behavior, capacity accuracy and certification. Premium brands therefore use tighter incoming quality control and protection-system validation than low-cost sellers. The strongest manufacturers also coordinate cell selection with enclosure design because compact magnetic products have limited room to dissipate wireless charging heat.
Assembly capacity itself is comparatively scalable. Surface-mount PCB assembly, battery-pack welding, coil placement, magnet installation and enclosure assembly can be expanded through contract manufacturers, especially in China and Southeast Asia. The more difficult capacity constraint is quality consistency during fast product ramps. Misaligned coils, weak magnetic arrays, poor thermal interfaces or inconsistent firmware can create high return rates even when the factory can produce large unit volumes, so process control and end-of-line testing are essential.
Regulation and transport create an additional capacity gate because lithium-battery products must be documented and shipped under dangerous-goods requirements. A manufacturer may have physical production capacity yet still face constraints in certified cells, packaging, freight or channel acceptance. This favors established suppliers with mature compliance teams and logistics partners. As Qi2 25W products emerge, thermal validation capacity will become more important because higher wireless power can expose weak designs before mass production.
Wireless Charging Power Banks Market Dynamics: Drivers, Restraints and Opportunities
Wireless charging power-bank growth is driven by Qi2 standardization, premium smartphone accessory demand, mobile travel use and e-commerce. The market is restrained by inductive efficiency losses, heat, lithium-battery safety requirements, rapid commoditization and compatibility variability. The most attractive opportunities are Qi2 25W premium products, integrated multi-function designs, commercial charging fleets and compliance-led premium positioning.
MARKET DRIVERS
| Driver | Impact | Commercial implication |
|---|---|---|
| Qi2 standardization and magnetic alignment | High | A common magnetic wireless-charging standard reduces compatibility uncertainty and enables accessory brands to build products around a defined performance and alignment framework. |
| Growth of premium smartphone accessories | High | Consumers increasingly treat portable power as part of the phone accessory ecosystem, supporting frequent product refreshes tied to new handset launches and travel behavior. |
| Travel and mobile-work demand | Medium to High | Commuting, air travel, events and mobile work create demand for power that can be attached and used without a cable while the phone remains in hand. |
| Expansion of online retail | Medium | E-commerce lets accessory brands launch new products quickly, compare features visibly and reach global customers without depending entirely on carrier or electronics-store shelf space. |
Qi2 standardization and magnetic alignment
Qi2 is the most important technology driver because it turns magnetic wireless charging from a largely ecosystem-specific experience into a broader standard administered by the Wireless Power Consortium. Magnetic alignment improves coil positioning, which supports more consistent power transfer and user convenience. Qi2’s initial 15 W profile and the introduction of Qi2 25W in July 2025 give brands a clear upgrade path. As compatible phones expand, certified power banks can address a wider installed base without relying on proprietary accessory programs.
Growth of premium smartphone accessories
Wireless power banks benefit from the same replacement and upgrade cycle that supports cases, chargers and cables. A new smartphone can introduce different magnetic alignment, charging speed or USB-C behavior, encouraging users to update accessories even when an older battery pack still functions. Premium brands reinforce this cycle through thinner designs, integrated stands, displays and higher wired output. The result is a market where design and convenience can support pricing above basic wired power banks.
Travel and mobile-work demand
The strongest use case is not maximum energy efficiency; it is convenient charging while moving. Magnetic wireless power banks can stay attached to a smartphone during transit, reducing cable clutter and allowing users to continue using the device. IATA data highlights the widespread carriage of power banks by travelers, while airline rules reinforce the need for clearly labeled, travel-compliant products. Brands that combine compact size with useful wired output can serve both travel convenience and higher-power charging needs.
Expansion of online retail
Wireless power banks are well suited to online merchandising because capacity, charging wattage, device thickness and certification can be compared directly. Brands can launch quickly in response to new phone cycles and gather reviews that validate real-world performance. The same transparency intensifies price competition, however, so established brands use certification, warranties, safety systems and product ecosystems to justify premiums over visually similar low-cost alternatives.
MARKET RESTRAINTS
| Restraint | Impact | Commercial implication |
|---|---|---|
| Wireless efficiency and heat | High | Inductive charging loses more energy than a wired connection and can generate additional heat, reducing effective delivered capacity and complicating compact battery-pack design. |
| Lithium-battery safety and travel rules | High | Power banks are regulated as spare lithium batteries for air travel, making cell quality, protection electronics, capacity labeling and passenger guidance essential product requirements. |
| Fast commoditization and price competition | Medium to High | Manufacturing scale and common component platforms allow many brands to launch similar-looking products, compressing margins once a new charging feature becomes widely available. |
| Device compatibility and case interaction | Medium | Real-world charging depends on phone model, case thickness, magnetic alignment and software power negotiation, so headline wattage may not be achieved in every configuration. |
Wireless efficiency and heat
A power bank’s nominal milliamp-hour rating does not equal the energy ultimately delivered wirelessly to a phone because conversion, coil coupling and thermal losses occur at several stages. Magnetic alignment helps, but wireless charging still imposes an efficiency penalty compared with a direct cable. Heat also accelerates battery stress and can force the charging controller to reduce power. Vendors must therefore balance thin form factors and high wattage against safe cell temperatures and realistic runtime expectations.
Lithium-battery safety and travel rules
IATA guidance requires power banks to be carried in cabin baggage rather than checked baggage, and common passenger rules use watt-hour thresholds to determine when airline approval is needed. These constraints do not prevent market growth, but they raise compliance and quality requirements. Low-quality cells, inaccurate capacity claims or weak thermal protection can damage brand trust quickly. Established suppliers benefit from documented safety systems and clear product labeling, while unbranded sellers face greater retailer and regulatory scrutiny.
Fast commoditization and price competition
The physical architecture of a wireless power bank can be replicated quickly once controllers, coils and magnets are available at scale. As Qi2 becomes common, certification and charging speed alone will not protect a brand premium. Companies must differentiate through industrial design, thermal performance, warranty, software displays, compact packaging or retail presence. This dynamic favors firms with brand trust and channel strength but creates constant pressure to refresh products before older designs become commodity items.
Device compatibility and case interaction
Consumers often interpret a charging label as a guaranteed experience, yet actual performance can vary by handset and case. Thick or poorly aligned cases increase coil distance and heat, while some devices support lower wireless power levels than the bank can provide. Returns and negative reviews can result even when the accessory operates within specification. Brands reduce this risk through broad compatibility testing, clear certified-device claims and magnetic designs that stabilize alignment.
MARKET OPPORTUNITIES
Qi2 25W premium product cycle
The Wireless Power Consortium introduced Qi2 25W in July 2025, creating a new premium performance tier. Power-bank makers can use the higher power level to refresh product lines, improve charging speed and create visible differentiation from first-generation Qi2 products. The opportunity is strongest for brands able to manage the extra thermal load in compact magnetic packs and communicate device compatibility clearly, because sustained charging performance matters more than a short peak wattage claim.
Integrated multi-function designs
Power banks can capture more value by combining wireless charging with high-power USB-C ports, integrated stands, battery-percentage displays, retractable cables or desktop charging functions. Anker’s 10,000 mAh Qi2 product already pairs 15 W wireless charging with 27 W USB-C output. Multi-function designs reduce the need for consumers to carry separate accessories and can defend higher average selling prices in a category where basic capacity is increasingly commoditized.
Commercial fleets and shared charging
Hospitality, events, workplaces and rental services can use wireless power banks to support diverse smartphone fleets without managing multiple connector types. The commercial opportunity requires different product attributes from household use: durable housings, cycle-life monitoring, charging racks and asset control become more important than minimal thickness. Vendors that adapt consumer wireless technology into managed fleets can create recurring institutional sales rather than relying solely on one-time retail purchases.
Compliance-led premiumization
European battery regulation and airline safety requirements can raise the value of traceable cells, accurate labeling and mature quality systems. Compliance costs are a burden for low-cost sellers, but they also create an opportunity for established brands to differentiate through documented safety, warranty and responsible battery management. Retailers and airlines are increasingly sensitive to lithium-battery risk, so trusted compliance can become a channel-access advantage rather than only a back-office requirement.
Wireless Charging Power Banks Supply Chain Analysis
Cells & charging components
Pack engineering
Assembly & certification
Distribution & lifecycle
Upstream value begins with lithium-ion cells, charging controllers, power-management ICs, wireless coils, magnets and protection components. Cell quality determines the available energy and much of the safety profile, while the wireless controller and coil set the charging protocol and power capability. Qi2 has increased the importance of precise magnetic and coil alignment. Component commoditization lowers entry barriers, but premium products still require carefully matched parts to control heat, maintain charging stability and deliver realistic usable capacity.
Pack engineering integrates the battery, protection circuit, USB-C power path, wireless transmitter, thermal interfaces and mechanical enclosure. This stage creates much of the user experience because a few millimeters of thickness, magnet strength or coil position can determine whether the bank feels secure and charges consistently through a phone case. Engineering teams must also manage heat without making the product too bulky, which becomes harder as wireless power rises from 15 W toward the Qi2 25W tier.
Assembly and certification convert the design into a channel-ready product. Factories weld cells, assemble PCBs, place magnets and coils, close housings and run electrical and charging tests. Qi certification provides standards assurance, while battery transport and safety documentation support retailer and logistics acceptance. Because lithium products can be costly to recall or ship back, premium brands invest in end-of-line testing and lot traceability to catch capacity, charging and thermal defects before products leave the factory.
Distribution and lifecycle economics are dominated by e-commerce, consumer-electronics retail, warranties and increasingly battery end-of-life obligations. Online channels enable rapid global launches but also expose brands to public review scores and return data. European battery regulation raises the importance of labeling and responsible battery management, while airline rules influence travel marketing. Strong suppliers treat compliance, warranty and recycling as part of product value rather than as administrative costs after the hardware is designed.
Recent Developments in the Wireless Charging Power Banks Market
July 2025 — Wireless Power Consortium introduced Qi2 25W
The Wireless Power Consortium introduced Qi2 25W as a higher-power extension of the Qi2 ecosystem. The change creates a fresh premium product cycle for wireless power banks because brands can offer materially faster magnetic charging while remaining within an interoperable certification framework. The commercial challenge shifts toward thermal engineering and compatibility, since sustaining higher power in a thin battery pack is more difficult than briefly advertising a peak wattage.
Qi2 15 W products became mainstream in 10,000 mAh magnetic packs
Anker and Belkin both market 10,000 mAh Qi2 power banks with 15 W wireless charging, demonstrating that Qi2 has moved from specification to mainstream branded products. The form factor balances portability with useful stored energy and illustrates how the market is converging around magnetic alignment plus a higher-power USB-C port for devices or situations where wired charging is more efficient.
Ongoing — IATA guidance keeps power banks in carry-on baggage
IATA passenger guidance treats power banks as spare lithium batteries that must be carried in cabin baggage rather than checked baggage. For manufacturers and retailers, travel rules make watt-hour labeling, protection electronics and clear consumer instructions essential. Products positioned for frequent travelers need to communicate capacity in a way that passengers and airline staff can evaluate without ambiguity.
EU battery regulation increases compliance requirements
Regulation (EU) 2023/1542 establishes a broad framework covering battery sustainability, safety, labeling and end-of-life responsibilities. Wireless power banks sold in Europe are therefore affected not only by consumer-electronics standards but also by evolving battery obligations. The regulation raises compliance costs, but it can also favor established brands that already maintain traceable supply chains, documented specifications and structured warranty or recycling processes.
REPORT SCOPE & SEGMENTATION
| Attribute | Coverage |
|---|---|
| Market definition | Portable rechargeable battery packs that provide wireless inductive charging for compatible devices and typically also include wired USB input or output. |
| Base / estimate / forecast | 2025 base year; 2026 estimated year; forecast through 2034. |
| Market size | USD 2,413.49 million in 2025; USD 6,030.35 million in 2034; 10.7% CAGR during 2026–2034. |
| By Type | Less than 20000 mAh; Above 20000 mAh. |
| By Application | Household; Commercial. |
| By Technology | Qi Standard; PMA Standard; Others. |
| By Distribution Channel | Online Retail; Offline Retail. |
| Regions | North America; Europe; Asia Pacific; South America; Middle East & Africa. |
| Companies profiled | Anker Innovations, Belkin International, AUKEY, Scosche Industries, Kenu, ZAGG Inc., Nillkin, Samsung Electronics, Mipow, Panasonic Corporation, HOCO Technology |
Frequently Asked Questions
What is the 2025 size of the wireless charging power banks market?
The global wireless charging power banks market is valued at USD 2,413.49 million in 2025. Demand is driven by magnetic smartphone charging, the broader Qi ecosystem, frequent mobile use and consumer preference for cable-free backup power. The market sits between the traditional power-bank category and premium smartphone accessories, so product cycles are influenced by both battery economics and new handset features such as magnetic alignment, supported wireless wattage and USB-C power delivery.
What is the projected market size in 2034?
The market is projected to reach USD 6,030.35 million by 2034, representing a 10.7% CAGR during 2026–2034. Growth is supported by Qi2 standardization, expansion of magnetic charging across compatible smartphones, premium accessory spending and new commercial use cases. The opportunity is not limited to higher unit volumes; faster wireless standards and multi-function designs can also lift average selling prices when brands deliver reliable thermal performance and certified compatibility.
Which region leads the wireless charging power banks market?
Asia Pacific is the largest regional market because it combines a vast smartphone user base with the global center of power-bank and consumer-electronics accessory manufacturing. China provides dense battery-pack, magnet, controller and assembly supply chains, while South Korea and Japan add major electronics capabilities. The United States remains the largest single-country market in the report scope with a 32% share, driven by premium smartphone and accessory demand.
Which capacity segment is largest?
Power banks below 20,000 mAh form the largest capacity segment because they provide the best balance of portability, useful smartphone backup and travel convenience. Compact 5,000–10,000 mAh magnetic products are particularly important because they can attach directly to a phone without making the combined device too heavy. Higher-capacity units serve multi-device and extended-travel needs but face stronger size, weight and airline watt-hour considerations.
What technology standard is most important?
Qi is the central interoperability standard, and Qi2 is the most important current product-development framework because it adds magnetic alignment and a defined certification path. The Wireless Power Consortium states that Qi2 supports magnetic charging, with first-generation products reaching 15 W and Qi2 25W introduced in July 2025. Standardization helps accessory brands address multiple compatible devices while reducing the uncertainty associated with proprietary magnetic charging implementations.
Why is Qi2 important for power banks?
Qi2 improves the user experience by aligning the phone and charging coil magnetically, which reduces positioning errors and supports more consistent power transfer. It also gives accessory makers a common certification framework rather than requiring separate proprietary programs. For power banks, alignment is particularly valuable because the device is used while moving. A secure magnetic connection lets the user charge without managing a cable, which is the category’s primary convenience advantage.
Who are the major companies in the market?
The profiled competitive group includes Anker Innovations, Belkin International, AUKEY, Scosche Industries, Kenu, ZAGG Inc., Nillkin, Samsung Electronics, Mipow, Panasonic Corporation and HOCO Technology. Competition spans premium global accessory brands, smartphone manufacturers and value-oriented Asian suppliers. The strongest differentiators are standards certification, cell quality, magnetic design, thermal control, industrial design, online reputation and distribution rather than battery capacity alone.
What are the main safety and travel constraints?
Wireless power banks contain lithium-ion batteries and are subject to transport and passenger-safety requirements. IATA guidance treats power banks as spare batteries that belong in cabin baggage, and battery capacity is commonly expressed in watt-hours for travel rules. Beyond transport, the product must manage cell overcharge, short-circuit, temperature and wireless-charging heat. Clear labeling, quality cells and robust protection electronics are therefore essential to retailer and consumer trust.
What are the main growth restraints?
The main restraints are wireless energy losses, heat generation, battery-safety requirements, intense price competition and device-compatibility variability. A high nominal battery capacity can deliver less usable phone energy when charging wirelessly, and compact magnetic packs have limited surface area for heat dissipation. Meanwhile, many brands can source similar controllers and cells, so products become commoditized quickly unless the supplier differentiates through design, certification, warranty and reliable real-world charging behavior.
How is the market changing through 2034?
The market is moving from basic Qi-enabled battery packs toward magnetic, standards-certified accessory platforms that combine faster wireless charging with high-power USB-C output and additional functions. Qi2 25W creates a new premium speed tier, while regulation and airline safety expectations increase the value of traceable battery quality. Competitive advantage will increasingly come from thermal engineering, compact mechanical design, multi-device utility, channel trust and rapid alignment with new smartphone charging specifications.
Research Sources & Evidence Base
View research sources used for this overview.
- Wireless Power Consortium. Qi Wireless Charging, evidence for the Qi ecosystem, Qi2 magnetic alignment, 15 W Qi2 operation and the July 2025 introduction of Qi2 25W.
- Apple. How to wirelessly charge your iPhone, evidence for Qi-certified wireless charging support across compatible iPhone models.
- Anker Innovations. Anker MagGo Power Bank (10K), technical evidence for a 10,000 mAh Qi2-certified magnetic power bank with 15 W wireless charging and 27 W USB-C output.
- Belkin. Magnetic Power Bank with Qi2 15W 10K, technical evidence for branded Qi2 15 W magnetic power-bank design and capacity.
- Samsung Electronics. Wireless Battery Pack 10,000mAh, evidence for smartphone-OEM participation in wireless power banks and mainstream 10,000 mAh product positioning.
- International Air Transport Association. Passenger baggage information for batteries and power banks, evidence for carry-on treatment of power banks and passenger lithium-battery travel requirements.
- European Union. Regulation (EU) 2023/1542 concerning batteries and waste batteries, regulatory evidence for battery sustainability, safety, labeling and end-of-life obligations in the European market.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF