Key Statistics
Key Takeaways
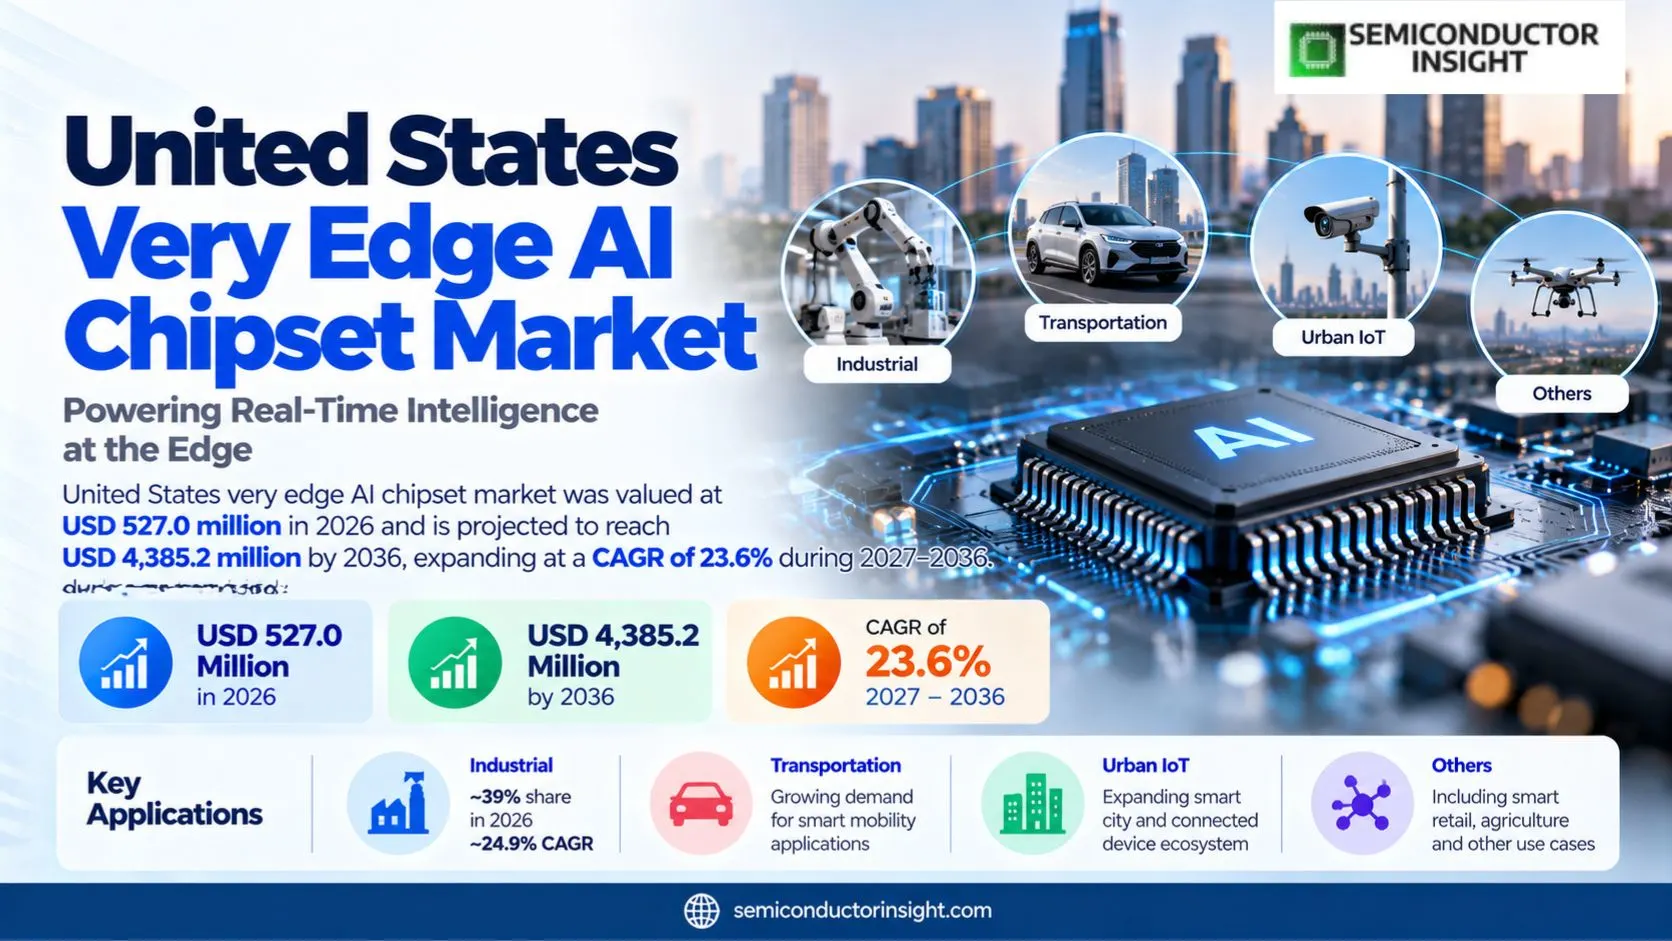
- Market outlook: united states very edge ai chipset is valued at USD 527.0 million in 2026 and is projected to reach USD 4,385.2 million in 2036, implying a 23.6% compound annual rate for the 2027–2036 forecast period as buyers qualify more production-ready systems rather than prototypes.
- ASIC leads: The leading Type accounts for an estimated ~48% of 2026 revenue. ASIC is the fastest-growing Type at ~25.8% CAGR, reflecting product design choices, application power budgets and the economics of qualified manufacturing.
- Industrial application: This application represents an estimated ~39% of the 2026 market, while Industrial shows the strongest long-term growth at ~24.9% CAGR because deployment decisions directly affect supplier production orders.
- South leads: At an estimated ~32% of 2026 revenue, South has the leading market position; Mountain grows fastest at ~28.5% CAGR as spending shifts to commercially deployable technology.
- Principal restraint: The largest commercial obstacle is turning engineering performance into repeatable field-qualified shipments. Buyers still assess yield, thermal and power characteristics, integration expense, service commitments and the lifetime reliability of industrial vision cameras.
United States Very Edge AI Chipset Market Overview
United States united states very edge ai chipset market was valued at USD 527.0 million in 2026 and is projected to reach USD 4,385.2 million by 2036, expanding at a CAGR of 23.6% during 2027–2036. South is the largest modeled buying region at an estimated ~32% of 2026 revenue. The forecast reflects demand for qualified hardware, channel commitments and recurring production orders, rather than counting every adjacent technology program.
Very-edge AI inference moves machine-learning decisions into the endpoint, not simply closer to a centralized cloud. A traffic camera, factory sensor or equipment controller can detect anomalies without uploading its raw data for every decision. This lower-latency execution requires optimized instruction sets, accelerator memory and stringent power management. The chipset cost must remain economical relative to the intelligence it adds to the installed hardware. The US market is therefore a deployment market, not the full addressable global revenue of US-headquartered chip vendors.
The US-only revenue boundary comprises GPUs, ASIC accelerators and FPGA devices sold for very-edge inference hardware applications. It excludes cloud training accelerators, generic server GPUs, subscription software revenue and foreign market shipments; corporate revenue totals are not proxies for chipsets sold into these uses. GPU, ASIC and FPGA are kept as distinct Type classes, as the scope requires. ASIC products compete on efficient fixed-function inference; GPUs emphasize programmability while FPGAs offer reconfigurable sensor interfaces. Some devices include several compute blocks, but commercial counting treats the sold chipset by its primary quoted type. This avoids multiplying revenues merely because more than one silicon accelerator appears in a finished product.
Design constraints vary sharply between battery-operated microphones and mains-powered industrial cameras. An MCU-class NPU can process local time-series signals at substantially lower energy than a graphics-class platform; embedded GPU modules handle richer multimodal workloads. Texas Instruments introduced TinyEngine-enabled MCU families in March 2026, while NVIDIA released Jetson Thor robotics modules in 2025. Quoted performance metrics are architecture-specific and should not be compared as if system power, latency or model precision were identical. Supplier selection turns on the complete application benchmark.
Software compatibility now influences semiconductor choices as strongly as the raw arithmetic throughput. Qualcomm’s acquisition agreement for Edge Impulse in March 2025 and Intel’s AI Edge Systems initiative demonstrate investment in development and lifecycle support. OEMs want validated models, quantization tools, security updates and a reproducible path from evaluation board to production hardware. When software migration cost is high, an otherwise more efficient chip can lose to an established device with a proven toolchain. Platform lock-in becomes part of lifetime economics.
North American automotive and industrial deployment schedules provide identifiable purchase triggers. Factories install cameras on inspection lines, transport fleets integrate safety processing, and utilities deploy sensors in systems that need reliable local reaction. Each application imposes different security, temperature, service and certification conditions; attractive benchmark performance alone does not unlock a design win. Industrial orders also depend on machine upgrades, whereas consumer design cycles can replace chip platforms more often. These divergent demand mechanisms explain why segment growth should not be inferred from one high-profile processor release.
Segment Analysis: By Type
By Type, united states very edge ai chipset is divided into GPU, ASIC, FPGA. ASIC has the largest modeled share, an estimated ~48% in 2026; ASIC grows fastest at ~25.8% CAGR. Each category is counted once on the primary product specification, so overlapping design functions are not added as independent revenue streams.
| Type | Function | Market position |
|---|---|---|
| GPU | Programmable parallel inference engine deployed in near-device vision and robotics. This design is relevant to industrial vision cameras and adjacent qualified uses where measurable performance is critical. The GPU qualification program tests integration tolerances, supply-chain dependency and reliability before volume manufacture. For united states very edge ai chipset, the practical commercial question is whether GPU can be sustained at the purchase volumes implied by the specified product category. Qualification for GPU requires an executable order forecast as well as suitable testing capacity and lifecycle support. The GPU purchase decision for GPU therefore affects supplier selection, unit economics and deployment timing rather than just the volume of demonstrations. | An estimated ~36% of US 2026 revenue; graphics-derived ecosystems simplify model development but cooling, memory and power limit tiny endpoints. Estimated 2026 type share is ~36%, with modeled growth of ~22.8% CAGR. For GPU sourcing, buyers compare the full device bill of materials, operating constraints and vendor software or optics support before awarding high-volume orders. |
| ASIC | Dedicated low-power neural signal processing and fixed-function inference. This design is relevant to transportation safety systems and adjacent qualified uses where measurable performance is critical. The ASIC qualification program tests integration tolerances, supply-chain dependency and reliability before volume manufacture. For united states very edge ai chipset, the practical commercial question is whether ASIC can be sustained at the purchase volumes implied by the specified product category. Qualification for ASIC requires an executable order forecast as well as suitable testing capacity and lifecycle support. The ASIC purchase decision for ASIC therefore affects supplier selection, unit economics and deployment timing rather than just the volume of demonstrations. | Largest estimated 2026 type at ~48%; optimized power per inference and deployment volume make tailored accelerators attractive for cameras and control devices. Estimated 2026 type share is ~48%, with modeled growth of ~25.8% CAGR. For ASIC sourcing, buyers compare the full device bill of materials, operating constraints and vendor software or optics support before awarding high-volume orders. |
| FPGA | Reconfigurable inference hardware integrating sensor preprocessing and programmable logic. This design is relevant to urban IoT sensors and adjacent qualified uses where measurable performance is critical. The FPGA qualification program tests integration tolerances, supply-chain dependency and reliability before volume manufacture. For united states very edge ai chipset, the practical commercial question is whether FPGA can be sustained at the purchase volumes implied by the specified product category. Qualification for FPGA requires an executable order forecast as well as suitable testing capacity and lifecycle support. The FPGA purchase decision for FPGA therefore affects supplier selection, unit economics and deployment timing rather than just the volume of demonstrations. | An estimated ~16% share; industrial lifetime, adaptable interfaces and deterministic data paths support premium deployments. Estimated 2026 type share is ~16%, with modeled growth of ~16.3% CAGR. For FPGA sourcing, buyers compare the full device bill of materials, operating constraints and vendor software or optics support before awarding high-volume orders. |
Segment Analysis: By Application
By Application, the market includes Industrial, Transportation, Urban IoT, Others. Industrial represents the largest estimated 2026 share at ~39%; Industrial is modeled to rise at ~24.9% CAGR. Differences in application certification, sales cycle and installation economics produce distinct buying patterns even where suppliers use a common device family. For united states very edge ai chipset, the practical commercial question is whether Industrial can be sustained at the purchase volumes implied by the specified product category. Qualification for Industrial requires an executable order forecast as well as suitable testing capacity and lifecycle support. The procurement purchase decision for Industrial therefore affects supplier selection, unit economics and deployment timing rather than just the volume of demonstrations.
| Application | Demand characteristics |
|---|---|
| Industrial | Estimated ~39% of 2026 market revenue; ~24.9% CAGR. Industrial buyers use industrial vision cameras to meet operational objectives that must be converted into equipment specifications. Engineering teams evaluate device lifetime, local power, image or inference quality and available integrators, then qualify the component before placing a production order. Industrial production calendars differ from the prototype stage because volume procurement depends on budget approval, field reliability and long-term supplier commitments. |
| Transportation | Estimated ~26% of 2026 market revenue; ~23.9% CAGR. Transportation buyers use transportation safety systems to meet operational objectives that must be converted into equipment specifications. For factory-ramp planning in the united states very edge ai chipset market, engineering teams evaluate device lifetime, local power, image or inference quality and available integrators, then qualify the component before placing a production order. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. Transportation production calendars differ from the prototype stage because volume procurement depends on budget approval, field reliability and long-term supplier commitments. |
| Urban IoT | Estimated ~25% of 2026 market revenue; ~23.4% CAGR. Urban IoT buyers use urban IoT sensors to meet operational objectives that must be converted into equipment specifications. For OEM sourcing negotiations in the united states very edge ai chipset market, engineering teams evaluate device lifetime, local power, image or inference quality and available integrators, then qualify the component before placing a production order. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. Urban IoT production calendars differ from the prototype stage because volume procurement depends on budget approval, field reliability and long-term supplier commitments. |
| Others | Estimated ~10% of 2026 market revenue; ~16.9% CAGR. Others buyers use medical and retail endpoints to meet operational objectives that must be converted into equipment specifications. For product lifecycle qualification in the united states very edge ai chipset market, engineering teams evaluate device lifetime, local power, image or inference quality and available integrators, then qualify the component before placing a production order. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. Others production calendars differ from the prototype stage because volume procurement depends on budget approval, field reliability and long-term supplier commitments. |
Application mix governs distribution strategy as much as production engineering. Professional buyers frequently procure through specialist OEMs, equipment makers and trained system integrators rather than from component manufacturers directly. Consumer device vendors negotiate consolidated volume terms, whereas industrial and regulated applications demand documentation and spare-part assurances. Consequently, a supplier may win a lucrative design without recording shipments until the downstream device launches. Qualified channels provide the link from the published addressable market to actual hardware purchases.
Regional Analysis
South leads the united states very edge ai chipset market with an estimated ~32% of 2026 revenue, followed by Pacific (~29%) and Northeast (~17%). Mountain has the highest modeled regional growth at ~28.5% CAGR. Regional economic logic reflects where the relevant devices are bought or installed, and it does not equate the geographic location of a corporate headquarters with consumption.
Why does united states very edge ai chipset demand vary between regional buying centers?
Geographic purchase behavior is driven by the location of finished-device orders, local application ecosystems and supplier qualification routes. A sophisticated prototype designed in one country may be manufactured in another and installed in a third; these activities are not three independent sales of the same module or chipset. Therefore the regional revenue split reflects purchasing and deployment assumptions rather than allocating the whole corporate sales of firms operating internationally. Fast-growing regions can also start from much smaller installation bases. Comparisons should examine procurement triggers alongside the stated estimated share and growth.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| South | #1 (~32%) | ~24.5% CAGR | High-volume industrial deployments, semiconductors and data infrastructure | Texas: qualification and buyer access |
| Pacific | #2 (~29%) | ~22.5% CAGR | Edge ai chip design, platform software and industrial robotics r&d | California: qualification and buyer access |
| Northeast | #3 (~17%) | ~20.5% CAGR | Healthcare electronics and research-driven system design | New York: qualification and buyer access |
| Midwest | #4 (~15%) | ~23.9% CAGR | Automotive, manufacturing inspection and connected machinery | Michigan: qualification and buyer access |
| Mountain | #5 (~7%) | ~28.5% CAGR | Industrial electronics, semiconductor expansion and smart infrastructure | Arizona: qualification and buyer access |
Competitive Landscape
Competitive intensity rests on technology ownership, manufacturing process control, system-integration evidence and contract qualification. A company can be important as a platform architect, materials supplier or downstream OEM without being a direct producer of the exact revenue-defined component. The profiled ecosystem therefore needs tier separation to prevent conflating chip designers with memory vendors or glass makers with optical module assemblers. Where ownership has changed, acquired brands are retained for scope continuity but not automatically treated as independent revenue companies. The durable advantages are production yield, customer qualification and a credible replacement-product roadmap.
Direct competitors are measured by repeatable procurement wins for an identified optical or semiconductor component, not by how often their names appear in technology demonstrations. Purchase decisions require verified product specifications, quality systems, customer access and sustained sourcing options. This separates a credible prototype supplier from an established revenue-producing participant, especially where the business depends on a single demanding device platform. NVIDIA represents one of the named commercial roles. The industrial vision cameras channel has distinct evaluation criteria. Product-market adoption also requires application-specific certification, post-sale support and resilience through component redesigns. This creates a measurable distinction between technology readiness and recognized component sales.
Design wins form the leading indicator of future component shipments, although a design win does not guarantee a product will launch. Buyers can abandon a platform after reliability problems, shifts in silicon architecture or changes in optical-engine configuration. Suppliers that demonstrate stable performance during engineering validation and maintain inventory continuity can earn stronger negotiating leverage when device makers reach commercial volumes. Intel Corporation represents one of the named commercial roles. The transportation safety systems channel has distinct evaluation criteria. This creates a measurable distinction between technology readiness and recognized component sales.
Vertical integration changes bargaining power because some companies control material processing, device architectures, proprietary tools and final qualification. It can reduce coordination costs and improve manufacturing learning, but also concentrate supply-chain risk. Buyers therefore evaluate alternative manufacturing locations, secondary suppliers, design portability and intellectual-property restrictions before accepting a volume contract, especially for public-sector and industrial devices. Qualcomm Technologies, Inc. represents one of the named commercial roles. The urban IoT sensors channel has distinct evaluation criteria. This creates a measurable distinction between technology readiness and recognized component sales.
Adjacent ecosystem participants require separate treatment in revenue analysis. Product enablers may be named in the competitive set because they supply essential materials, accelerators, memory, tools or integration capability, but this does not establish their portion of finished-module or very-edge-chipset sales. OEM customers commonly purchase combinations of hardware and software, so careful scoping remains central to market comparisons and pricing assessments. Apple Inc. represents one of the named commercial roles. The medical and retail endpoints channel has distinct evaluation criteria. This creates a measurable distinction between technology readiness and recognized component sales.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 — processor IP | NVIDIA; Qualcomm Technologies; AMD; Texas Instruments | End-device inference architectures, reference SDKs, efficient accelerated execution and established OEM engagement. Suppliers in this classification are evaluated by whether product certifications, design controls and service arrangements support recurring business under this specific market definition. For united states very edge ai chipset, the practical commercial question is whether Tier 1 — processor IP can be sustained at the purchase volumes implied by the specified product category. Qualification for Tier 1 — processor IP requires an executable order forecast as well as suitable testing capacity and lifecycle support. The tier purchase decision for Tier 1 — processor IP therefore affects supplier selection, unit economics and deployment timing rather than just the volume of demonstrations. |
| Tier 2 — specialist systems | Intel; Apple; Google; IBM | Software platforms, integrated AI silicon, selected embedded solutions and product-specific deployment channels. For united states very edge ai chipset, the practical commercial question is whether Tier 2 — specialist systems can be sustained at the purchase volumes implied by the specified product category. Qualification for Tier 2 — specialist systems requires an executable order forecast as well as suitable testing capacity and lifecycle support. The tier purchase decision for Tier 2 — specialist systems therefore affects supplier selection, unit economics and deployment timing rather than just the volume of demonstrations. |
| Adjacent suppliers | Micron Technology; Xilinx (AMD business) | Memory enabling local inference and historic adaptive-chip branding; neither should be treated as a separately verified pure-play share holder. For united states very edge ai chipset, the practical commercial question is whether Adjacent suppliers can be sustained at the purchase volumes implied by the specified product category. Qualification for Adjacent suppliers requires an executable order forecast as well as suitable testing capacity and lifecycle support. The tier purchase decision for Adjacent suppliers therefore affects supplier selection, unit economics and deployment timing rather than just the volume of demonstrations. |
Key companies profiled
- NVIDIA
- Intel Corporation
- Qualcomm Technologies, Inc.
- Apple Inc.
- Advanced Micro Devices (AMD)
- Texas Instruments
- Google LLC
- Xilinx
- Micron Technology
- IBM
Production Capacity Analysis
Capacity should be understood as qualified, saleable units rather than nominal wafer, substrate or assembled-board throughput. Prototype line availability can overstate capacity when testing yield, packaging or customer-acceptance requirements are excluded. The production constraint moves across process steps as designs mature: upstream materials, chip fabrication or optical processing, final assembly and system qualification. An announced factory expansion is an indicator of potential supply rather than proof of sales. Supply decisions require both process capability and downstream purchase orders.
The most valuable production step for united states very edge ai chipset is the operation that controls product-specific yield. The process may involve precision reflection surfaces, module alignment or inference-silicon packaging; inspection before shipment is essential. Engineering change control becomes especially important once a consumer or industrial OEM certifies a part number. Localized capacity can support shorter lead times, but the location of development labs does not prove where saleable units are produced. Buyers assess traceability and process control across all manufacturing partners.
Manufacturing diversification is gaining significance as downstream companies ask for dependable supply under changing logistics conditions. SCHOTT has expanded precision optics operations in Malaysia, while US chip developers work with global fabrication and packaging supply chains, illustrating distinct business models. A second-site strategy can lower disruption risk only after equivalent product testing and documentation have been completed. Dual-sourcing commonly incurs extra qualification expense and may not be possible for unique optical IP or complex processor software. These costs influence near-term profitability before they strengthen longer-term delivery assurance.
Upstream bottlenecks can determine output even when final assembly lines have headroom. Waveguide suppliers depend on surface quality, coatings and optical tools; AI processor suppliers depend on advanced wafer fabrication, memory components, substrates and testing. A defect or shortage at one specialized stage can interrupt many downstream products because redesign affects mechanical, software and electromagnetic compatibility. Commercial contracts increasingly require transparent lead times, revision tracking and long-term materials management. The economic issue is qualified throughput, not installed machine count.
Market Dynamics
Growth is being shaped by a chain of events, from application requirements through device architecture and manufacturing availability to procurement. Drivers increase the probability that a buyer approves a qualified hardware platform, whereas restraints lower the attainable deployment rate or the price achieved per shipped component. Opportunities arise where a technical capability solves a measurable task at a competitive total cost. Impact figures below are directional scenario sensitivities, not independent published market statistics. They are assessed individually and are not additive to the headline CAGR.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Real-time local decision cycles | +1.9% | industrial plants and robotics | 2027–2032 |
| Power-efficient neural processors | +1.5% | wearables and instrumented equipment | 2027–2036 |
| Developer SDK integration | +1.2% | software and chip suppliers | 2027–2032 |
| Safety and privacy requirements | +0.9% | transportation and medical endpoints | 2027–2036 |
Real-time local decision cycles
Real-time local decision cycles influence purchasing behavior by changing the usable economics of the end application. Inspection cameras and industrial controllers benefit when classification runs next to the physical process rather than in a remote cloud; latency and connectivity become operational constraints. Demand is visible in industrial plants and robotics; this is not equivalent to the total number of announced products. To obtain orders, a supplier must convert the advantage into repeatable test results and support the intended sales channel. When qualification lengthens, installation or device-launch timing can lag engineering progress. The contribution to the market therefore depends on the speed of customer adoption.
Power-efficient neural processors
Power-efficient neural processors influence purchasing behavior by changing the usable economics of the end application. The integration of a low-power neural processing unit with an MCU can expand feasible inference into battery-powered hardware where an embedded GPU would be impractical. Demand is visible in wearables and instrumented equipment; this is not equivalent to the total number of announced products. When qualification lengthens, installation or device-launch timing can lag engineering progress. The contribution to the market therefore depends on the speed of customer adoption.
Developer SDK integration
Developer SDK integration influence purchasing behavior by changing the usable economics of the end application. Framework support, model quantization and production-ready libraries reduce the time needed to integrate inference into an embedded product, which helps smaller OEM engineering teams. Demand is visible in software and chip suppliers; this is not equivalent to the total number of announced products. When qualification lengthens, installation or device-launch timing can lag engineering progress. The contribution to the market therefore depends on the speed of customer adoption.
Safety and privacy requirements
Safety and privacy requirements influence purchasing behavior by changing the usable economics of the end application. Local processing can keep raw images or sensitive sensor data inside the device, but model updates and security controls must still satisfy deployment requirements. Demand is visible in transportation and medical endpoints; this is not equivalent to the total number of announced products. When qualification lengthens, installation or device-launch timing can lag engineering progress. The contribution to the market therefore depends on the speed of customer adoption.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Model and memory limits | −1.6% | camera and vision applications | Short–medium term |
| Qualification and cost | −1.3% | regulated deployments | Short–medium term |
| Software fragmentation | −1.1% | embedded engineering | 2027–2036 |
| Security and lifecycle | −0.8% | operational technology | 2027–2036 |
Model and memory limits
Model and memory limits limits scaling where manufacturing and operational requirements exceed the available component capability. Small-memory endpoints cannot execute every computer-vision or language model at acceptable latency; quantization can reduce memory but may change accuracy. The consequence is strongest in camera and vision applications, where engineering failures can interrupt deployment schedules. OEMs commonly respond through redesign, supplier changes, additional validation work or reduced first-run production volume. Those remedies create costs that may not be recovered by higher unit prices. Commercial forecasts should therefore treat product maturity and qualified throughput separately from stated market interest.
Qualification and cost
Qualification and cost limits scaling where manufacturing and operational requirements exceed the available component capability. Automotive, industrial and medical engineering programs impose long testing cycles and require extended hardware availability before production commitment. The consequence is strongest in regulated deployments, where engineering failures can interrupt deployment schedules. Those remedies create costs that may not be recovered by higher unit prices. For multi-year supply agreements in the united states very edge ai chipset market, commercial forecasts should therefore treat product maturity and qualified throughput separately from stated market interest. This consideration continues to affect customer decisions across the 2026–2036 planning horizon.
Software fragmentation
Software fragmentation limits scaling where manufacturing and operational requirements exceed the available component capability. Compiler differences, unsupported operators and version drift make porting AI models expensive and can obstruct customer switching even where processors are cheaper. The consequence is strongest in embedded engineering, where engineering failures can interrupt deployment schedules. Those remedies create costs that may not be recovered by higher unit prices. For component yield verification in the united states very edge ai chipset market, commercial forecasts should therefore treat product maturity and qualified throughput separately from stated market interest. This consideration continues to affect customer decisions across the 2026–2036 planning horizon.
Security and lifecycle
Security and lifecycle limits scaling where manufacturing and operational requirements exceed the available component capability. Installed sensors and connected controllers may remain in service longer than a vendor software release cycle, raising vulnerability management and update burdens. The consequence is strongest in operational technology, where engineering failures can interrupt deployment schedules. Those remedies create costs that may not be recovered by higher unit prices. For deployment risk assessment in the united states very edge ai chipset market, commercial forecasts should therefore treat product maturity and qualified throughput separately from stated market interest. This consideration continues to affect customer decisions across the 2026–2036 planning horizon.
MARKET OPPORTUNITIES
Smart industrial inspection
Defect-detection cameras at assembly stations are a direct route to repeatable very-edge AI chipset purchases when their false-positive performance and total equipment cost justify adoption. The procurement trigger is a reproducible improvement in industrial vision cameras rather than a technology demonstration. Hardware suppliers can accelerate adoption through customer-specific reference designs and dependable distribution arrangements. However, device makers must still qualify the solution against user, safety and lifetime conditions. Successful OEM collaboration can move the opportunity from design activity into recurring order volumes.
Distributed transport safety
Vehicles and infrastructure sensors increasingly combine camera processing with deterministic local decisions, creating demand for specialized accelerators that handle varied operating conditions. The procurement trigger is a reproducible improvement in transportation safety systems rather than a technology demonstration. For regional distribution planning in the united states very edge ai chipset market, hardware suppliers can accelerate adoption through customer-specific reference designs and dependable distribution arrangements. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. However, device makers must still qualify the solution against user, safety and lifetime conditions. Successful OEM collaboration can move the opportunity from design activity into recurring order volumes.
Compact medical monitoring
On-device signal classification can reduce energy and bandwidth costs for healthcare instrumentation, provided the manufacturer completes safety and data-protection validation. The procurement trigger is a reproducible improvement in urban IoT sensors rather than a technology demonstration. For technical product validation in the united states very edge ai chipset market, hardware suppliers can accelerate adoption through customer-specific reference designs and dependable distribution arrangements. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. However, device makers must still qualify the solution against user, safety and lifetime conditions. Successful OEM collaboration can move the opportunity from design activity into recurring order volumes.
Edge AI software portability
Reference designs and portable development stacks can widen the chip supplier pool by reducing integration cost for device makers, even when processor hardware changes between generations. The procurement trigger is a reproducible improvement in medical and retail endpoints rather than a technology demonstration. For factory-ramp planning in the united states very edge ai chipset market, hardware suppliers can accelerate adoption through customer-specific reference designs and dependable distribution arrangements. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. However, device makers must still qualify the solution against user, safety and lifetime conditions. Successful OEM collaboration can move the opportunity from design activity into recurring order volumes.
Supply Chain Analysis
Supply-chain economics are determined by where technical performance is created and who certifies the assembly for delivery. Upstream inputs cannot automatically be added to finished chip or optical-module revenue as separate demand. Production processes and sales channels differ, but in every case a hardware vendor must link specifications to an approved customer design. The chain below distinguishes material or silicon preparation from manufacturing, distribution and final application. Quality records and revision management connect each stage to field reliability.
Upstream. Upstream: Semiconductor IP, wafer fabrication, memory and embedded sensor interfaces. The industrial vision cameras application defines the performance threshold expected at this point in the supply chain. Supplier qualification establishes traceability, minimum operational performance and predictable logistics before scaled production. An interruption at this stage can require revalidation at the downstream stage and may delay recognized sales. This is why upstream performance influences component pricing as well as availability.
Manufacturing. Manufacturing: Processor packaging, accelerator test, firmware and board-level validation. The transportation safety systems application defines the performance threshold expected at this point in the supply chain. For OEM sourcing negotiations in the united states very edge ai chipset market, supplier qualification establishes traceability, minimum operational performance and predictable logistics before scaled production. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. This is why manufacturing performance influences component pricing as well as availability.
Channel. Channel: OEM distribution, industrial integrators, embedded systems companies and reference design providers. The urban IoT sensors application defines the performance threshold expected at this point in the supply chain. For product lifecycle qualification in the united states very edge ai chipset market, supplier qualification establishes traceability, minimum operational performance and predictable logistics before scaled production. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. This is why channel performance influences component pricing as well as availability.
Downstream. Downstream: Local AI in factory vision, transportation safety, municipal sensors and specialized equipment. The medical and retail endpoints application defines the performance threshold expected at this point in the supply chain. For near-term purchasing cycles in the united states very edge ai chipset market, supplier qualification establishes traceability, minimum operational performance and predictable logistics before scaled production. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. This is why downstream performance influences component pricing as well as availability.
Recent Developments
- 8 September 2026 Announced
Arm: Arm AI Portal development platform. Arm documented this development in its 8 September 2026 company announcement. For united states very edge ai chipset, the significance is the movement of device engineering, manufacturing processes or software capabilities toward deployable customer products. The event should be interpreted within its actual technical scope: a material, device or platform disclosure is evidence of progress but does not independently establish annual market revenue. Commercial impact depends on integration with medical and retail endpoints and sustained manufacturer qualification, not on the announcement alone. Source - 15 July 2026 Announced
NVIDIA: T3000 and T2000 edge AI modules. NVIDIA documented this development in its 15 July 2026 company announcement. For field reliability evaluation in the united states very edge ai chipset market, for united states very edge ai chipset, the significance is the movement of device engineering, manufacturing processes or software capabilities toward deployable customer products. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. Commercial impact depends on integration with urban IoT sensors and sustained manufacturer qualification, not on the announcement alone. Source - 10 March 2026 Announced
Texas Instruments: TinyEngine integrated NPU MCU families. Texas Instruments documented this development in its 10 March 2026 company announcement. For device cost-down programs in the united states very edge ai chipset market, for united states very edge ai chipset, the significance is the movement of device engineering, manufacturing processes or software capabilities toward deployable customer products. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. Commercial impact depends on integration with industrial vision cameras and sustained manufacturer qualification, not on the announcement alone. Source - 30 October 2025 Announced
Alif Semiconductor: ExecuTorch model deployment on MCUs. Alif Semiconductor documented this development in its 30 October 2025 company announcement. For contract manufacturing qualification in the united states very edge ai chipset market, for united states very edge ai chipset, the significance is the movement of device engineering, manufacturing processes or software capabilities toward deployable customer products. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. For multi-year supply agreements in the united states very edge ai chipset market, commercial impact depends on integration with medical and retail endpoints and sustained manufacturer qualification, not on the announcement alone. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. Source - 25 August 2025 Announced
NVIDIA: Jetson AGX Thor release. NVIDIA documented this development in its 25 August 2025 company announcement. For component yield verification in the united states very edge ai chipset market, for united states very edge ai chipset, the significance is the movement of device engineering, manufacturing processes or software capabilities toward deployable customer products. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. Commercial impact depends on integration with transportation safety systems and sustained manufacturer qualification, not on the announcement alone. Source - 5 June 2025 Published
AMD: Versal Gen 2 sampling milestones. AMD documented this development in its 5 June 2025 technical update. For deployment risk assessment in the united states very edge ai chipset market, for united states very edge ai chipset, the significance is the movement of device engineering, manufacturing processes or software capabilities toward deployable customer products. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. For regional distribution planning in the united states very edge ai chipset market, commercial impact depends on integration with medical and retail endpoints and sustained manufacturer qualification, not on the announcement alone. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. Source - 13 March 2025 Announced
Qualcomm: Industrial edge-AI collaboration. Qualcomm documented this development in its 13 March 2025 Qualcomm announcement. For technical product validation in the united states very edge ai chipset market, for united states very edge ai chipset, the significance is the movement of device engineering, manufacturing processes or software capabilities toward deployable customer products. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. For factory-ramp planning in the united states very edge ai chipset market, commercial impact depends on integration with medical and retail endpoints and sustained manufacturer qualification, not on the announcement alone. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2036 |
| Historical Period | 2021–2025 |
| Base Year | 2026 |
| Base Year Market Size | USD 527.0 million |
| Estimated Year | 2027 |
| Estimated Year Market Size | USD 651.4 million |
| Forecast Year | 2036 |
| Forecast Market Size | USD 4,385.2 million |
| Forecast CAGR (2027–2036) | 23.6% |
| Currency / Measurement | USD million; revenue of included hardware |
| Market Boundary | For OEM sourcing negotiations in the united states very edge ai chipset market, the US-only revenue boundary comprises GPUs, ASIC accelerators and FPGA devices sold for very-edge inference hardware applications. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. For product lifecycle qualification in the united states very edge ai chipset market, it excludes cloud training accelerators, generic server GPUs, subscription software revenue and foreign market shipments; corporate revenue totals are not proxies for chipsets sold into these uses. This consideration continues to affect customer decisions across the 2026–2036 planning horizon. |
| By Type | GPU · ASIC · FPGA |
| By Application | Industrial · Transportation · Urban IoT · Others |
| By Region | 2026 regional market shares are estimates; the United States revenue total is allocated once across the non-overlapping buying regions below. SouthTexas, North Carolina, Virginia, Georgia PacificCalifornia, Washington, Oregon, Hawaii NortheastNew York, Massachusetts, Pennsylvania, New Jersey MidwestMichigan, Ohio, Illinois, Indiana MountainArizona, Colorado, Utah, Nevada |
| Key Companies Profiled | NVIDIA, Intel Corporation, Qualcomm Technologies, Inc., Apple Inc., Advanced Micro Devices (AMD), Texas Instruments, Google LLC, Xilinx, Micron Technology, IBM |
| Customization Scope | Available detail includes region and customer-type splits, component specification coverage, supplier qualification criteria and country or state-level analysis within the defined market boundary. |
Frequently Asked Questions
What is the size and forecast for the united states very edge ai chipset market?
The united states very edge ai chipset market is valued at USD 527.0 million in 2026 and is projected to reach USD 4,385.2 million in 2036, representing 23.6% CAGR for the 2027–2036 forecast period. The revenue basis covers qualified hardware within the named technology scope and geographic boundary, rather than sales of all devices using AI or augmented reality. The forecast assumes gradual transition from engineering trials to repeat purchases.
Which Type has the largest estimated 2026 share of united states very edge ai chipset?
ASIC is the largest Type at an estimated ~48% of 2026 market revenue. This category represents dedicated low-power neural signal processing and fixed-function inference. Procurement often depends on long-term operational stability, the economics of a qualified bill of materials and service availability. Product classes remain distinct, and the estimated share should not be interpreted as a published audited company-revenue statistic.
Which Type is projected to expand fastest in united states very edge ai chipset?
ASIC shows the highest modeled Type growth at ~25.8% CAGR over the ten-year base-to-forecast calculation window. Its path reflects a combination of technical differentiation and potential adoption in industrial vision cameras. The apparent advantage depends on qualification, price erosion and application mix, so the outlook refers to revenue within the Type category rather than production units or total hardware shipments.
Which applications lead demand for united states very edge ai chipset?
Industrial accounts for an estimated ~39% of the 2026 market, while Industrial has modeled growth of ~24.9% CAGR. Hardware buying patterns differ because transportation safety systems can be funded by industrial budgets while industrial vision cameras may depend on a retail device launch. Demand estimates refer to the original application categories and are not additive across separate end-user lenses.
Which geographical market leads united states very edge ai chipset?
South has the largest estimated 2026 share at ~32%, with Pacific at ~29% and Northeast at ~17%. These are allocations of purchases and use, not the worldwide revenue of companies headquartered in those places. The highest modeled growth occurs in Mountain at ~28.5% CAGR, reflecting different manufacturing and installation timelines.
What distinguishes the included technology from adjacent devices?
The core definition is chipsets executing local machine-learning inference within sensors, cameras, automation controllers, mobile endpoints and other power-constrained devices at the United States point of data capture. This distinction is important because a cloud accelerator, optical glass wafer, camera-only eyewear product or system-integration contract may be commercially relevant without representing the hardware sale counted here. When comparing suppliers, the finished deliverable and revenue ownership must be established before including a shipment.
What are the most important commercialization constraints?
Commercialization is limited by manufacturing yield, qualification expense, device power and thermal constraints and the risk that technical advances outpace compatible products. For urban IoT sensors, buyers also need documentation, field support and a dependable spare-part strategy. These hurdles can push procurement beyond the original demonstration schedule even when an experimental technology already performs well in controlled conditions.
How do manufacturers compete in the united states very edge ai chipset market?
Suppliers compete through component performance, production yield, available development tools, intellectual property and the ability to support a customer through several design revisions. Companies such as NVIDIA and Intel Corporation can serve distinct roles in the broader ecosystem. A company named as a platform provider, material supplier or historic brand is not necessarily a separate revenue-leading hardware producer.
Why does the forecast depend on qualification timing?
Customers do not typically pay for full-production quantities at the initial design phase. Evaluation samples are followed by application tests, manufacturing reviews, revised optics or firmware and finally recurring orders. Delays at any stage change the 2027–2036 revenue profile even when long-run demand remains attractive. The estimated shares and growth rates represent a coherent market scenario rather than guaranteed execution by individual OEMs.
What is included in the geographic and product scope?
The analysis covers 2026 as the base, 2027 as the estimated year and 2036 as the forecast, with historical context from 2021 to 2025. Type members are GPU, ASIC, FPGA; application members are Industrial, Transportation, Urban IoT, Others. Five non-overlapping US regional groupings divide the United States only, excluding international demand. Companies are profiled according to their actual commercial role.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF