Key Statistics
Key Takeaways
- 2026 base: The United States market for dedicated organ-on-chip microfluidic devices and eligible single-use chips is valued at an estimated USD 125.28 million in 2026, with installed platform capital expenditure separated from recurring chip consumable purchases to avoid counting an instrument twice.
- 2036 outlook: The forecast reaches USD 753.67 million by 2036, equivalent to a reconciled 19.7% CAGR across ten years; this is a modeled extension of the publisher’s 2030 endpoint, not an independently audited supplier revenue projection.
- Liver-on-chip: Liver systems represent an estimated ~26% of 2026 device revenue, supported by pharmaceutical interest in drug-induced liver injury screening and the progression of an FDA qualification package for a human liver chip.
- Pharma and biotech: Drug developers form the largest application with an estimated ~63% share, while academic laboratories account for an estimated ~27%; NIH translational awards support research demand but are not equivalent to commercial chip sales.
- Northeast leadership: The Northeast holds an estimated ~34% of U.S. demand through Boston and New York research and pharmaceutical clusters; the South, Pacific, Midwest and Mountain subregions make up the rest of the domestic geographic model.
- Technology architecture: Actively perfused systems are estimated at ~68% of device demand, gravity-driven systems at ~19%, and static or intermittent-flow systems at ~13%, with technical selection depending on shear stress, barrier stability and experimental throughput.
- Regulatory transition: The FDA issued NAM validation draft guidance in March 2026 and updated non-animal testing terminology in September 2026; neither development automatically qualifies any specific chip assay for a regulatory submission.
- Revenue boundary: Only factory-gate device and eligible consumable chip sales into the United States are counted; outsourced assays, CRO studies, drug development budgets, computational modeling and generic laboratory automation are outside the defined commercial scope.
United States Organ-on-Chip (OOC) Market Overview
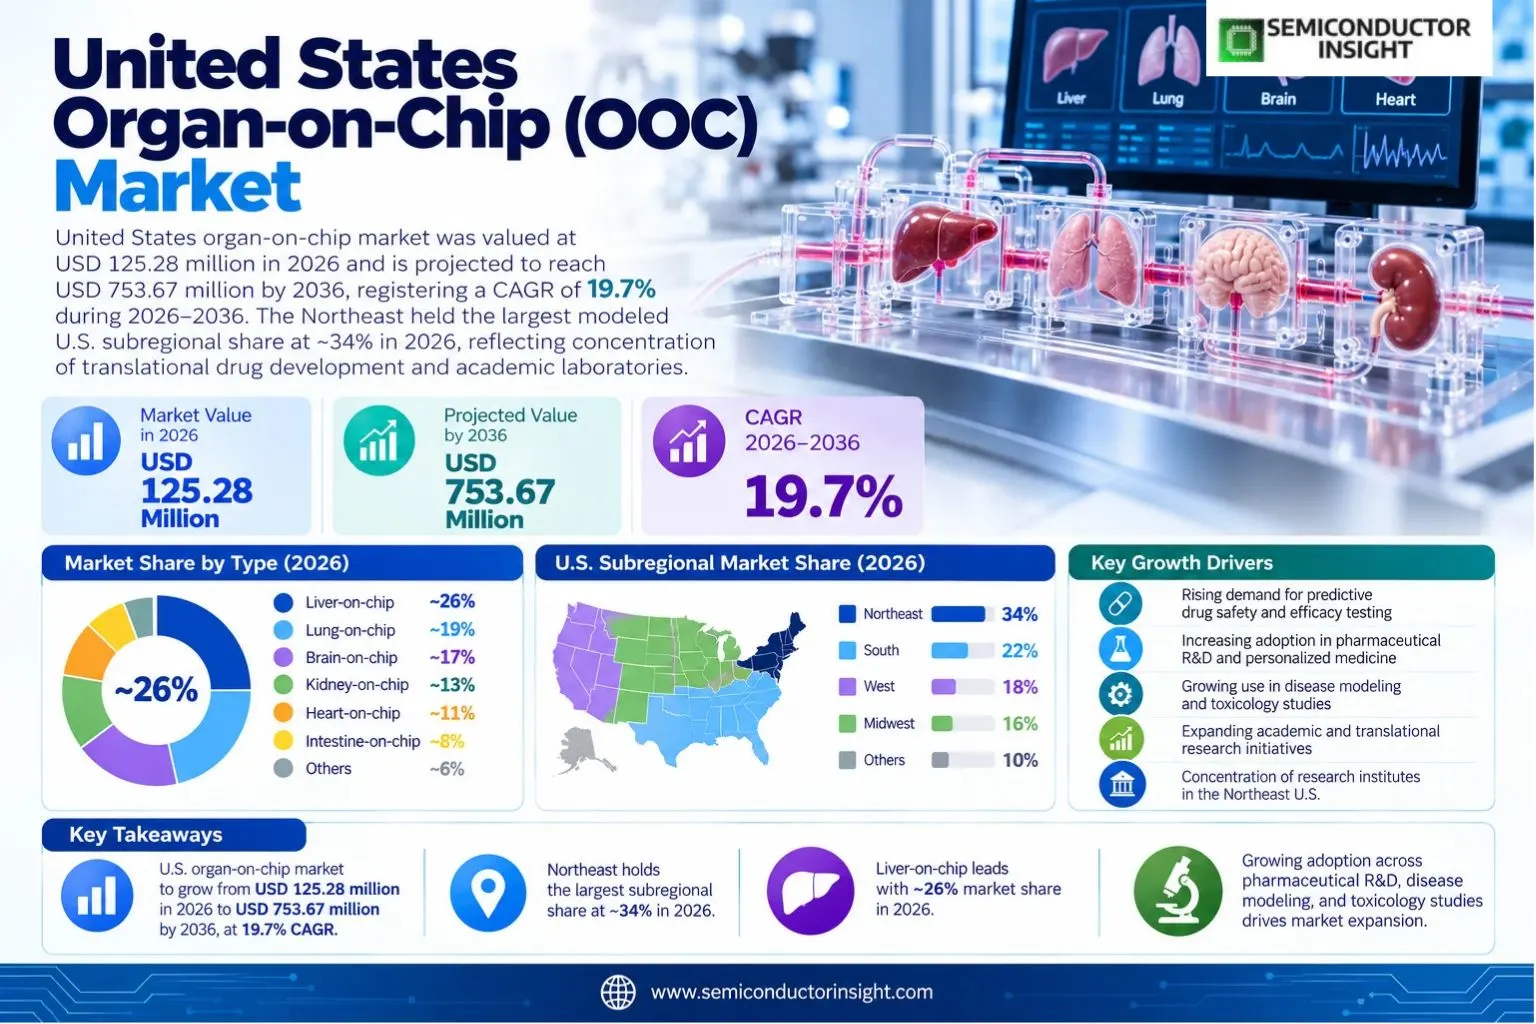
United States organ-on-chip market was valued at USD 125.28 million in 2026 and is projected to reach USD 753.67 million by 2036, registering a CAGR of 19.7% during 2026–2036. The Northeast held the largest modeled U.S. subregional share at ~34% in 2026, reflecting concentration of translational drug development and academic laboratories.
An organ-on-chip device is a microengineered cell-culture platform in which human tissue experiences controlled fluid flow, mechanical forces and biochemical exposure. A liver model may reproduce drug metabolism and toxicity signatures, whereas a lung or intestinal barrier chip emphasizes transport and epithelial responses. NIH NCATS describes tissue chips as human-cell systems designed to improve predictions of drug safety. The device is not a miniature whole organ, and different organ types require distinct validation endpoints. Manufacturers therefore compete on reproducible tissue function, ease of operation and compatibility with established laboratory workflows.
Commercial demand is concentrated in pharmaceutical discovery and preclinical safety research rather than clinical implantation. A customer buys an instrument, consumable chips and sometimes specialized reagents; this model counts only qualifying device hardware and dedicated microfluidic chips. Emulate launched its AVA platform in June 2025 for high-throughput organ-chip studies, while MIMETAS offers gravity-driven OrganoPlate formats. Service fees for experiments performed by a supplier do not become factory-gate chip sales merely because the supplier uses its own platform. Separating these revenue streams is essential when comparing product catalogues and published market estimates.
The United States benefits from a dense network of university research programs, biotechnology start-ups and large drug developers. The NIH NCATS TraCe MPS initiative announced four translational centers and roughly $31 million over five years in July 2024. Those awards support validation capacity in locations including Washington, New York, Rochester, Pittsburgh and Texas. Research grants may purchase chips, but their entire grant value is not device-market revenue. Demand estimates therefore reflect eligible procurement rather than a direct conversion of research budgets into sales.
Regulatory acceptance is an important demand catalyst but should not be described as automatic substitution for animal testing. In March 2026 the FDA issued draft guidance on validation of new approach methodologies, and a September 2026 rule addressed terminology for non-animal testing methods. Emulate submitted a Human Liver-Chip qualification package to the FDA ISTAND program in September 2026. A qualification submission is not a final FDA determination that all organ-chip assays can replace animal evidence. Customers still need fit-for-purpose analytical performance, reproducibility and documented relevance to the intended safety question.
The numerical forecast uses the publisher’s 2024 and 2030 United States endpoints to derive a consistent ten-year growth path. An endpoint-implied annual rate of 19.655% produces a 2026 modeled base of $125.28 million and a 2036 scenario of $753.67 million. The 2036 endpoint is six years beyond the original published forecast and assumes continued adoption without a verified manufacturer shipment schedule. The model also divides demand among five nonoverlapping domestic subregions, not five global continents. Each geographic percentage is explicitly an analyst allocation and is not represented as an audited Census or supplier revenue share.
Segmentation should be interpreted as six independent views of the same domestic device market. The type allocation assigns ~26% to liver, ~18% to lung, ~16% to brain, ~13% to kidney, ~11% to heart, ~9% to intestine and ~7% to other organ models. Application demand assigns ~63% to pharmaceutical and biotechnology users, ~27% to academia, ~6% to cosmetics and ~4% to other purposes. These are analytical estimates based on product availability and institutional demand, not disclosed vendor revenue. Adding the type and application allocations would double count the same physical chip purchases.
Segment Analysis: By Type
By type, the U.S. market is divided into liver, lung, brain, kidney, heart, intestine and other organ-on-chip devices. Liver-on-chip holds the largest modeled 2026 share at ~26%, reflecting established pharmaceutical safety workflows; the other types are distinct organ-specific assay categories, not overlapping drug-development service revenues. All reported percentages are modeled allocations within a device-only revenue boundary and should not be mistaken for audited supplier shipments.
| Organ model | Scientific purpose | Commercial assessment |
|---|---|---|
| Liver-on-a-chip | Liver-on-a-chip serves a modeled ~26% share of domestic device demand in 2026. Drug-induced liver injury, metabolic clearance and hepatocyte co-culture are major workflows. Purchasers evaluate human tissue performance under repeated runs and the stability of cell culture across different laboratories. The experimental format may require dedicated fluidic control and imaging, so device purchase decisions are linked to total operating burden. Reported company-wide research revenue cannot be used as a substitute for sales of the specific chip format. | Emulate’s liver chip qualification work provides a direct commercial example, although submission status does not establish broad regulatory acceptance. The estimated 2026 allocation is ~26% and the scenario CAGR is ~19.0%. Supplier differentiation depends on the tissue source, assay readout and ability to preserve the desired phenotype over multi-day exposure. Academic publication activity supports scientific interest but is not equivalent to paid procurement. Revenue is limited to qualifying chips and associated dedicated hardware sold into U.S. laboratories. |
| Lung-on-a-chip | Lung-on-a-chip serves a modeled ~18% share of domestic device demand in 2026. Air-liquid interface culture and respiratory barrier responses drive lung model design. Purchasers evaluate human tissue performance under repeated runs and the stability of cell culture across different laboratories for liver injury assays. The experimental format may require dedicated fluidic control and imaging, so device purchase decisions are linked to total operating burden for liver injury assays. Reported company-wide research revenue cannot be used as a substitute for sales of the specific chip format for liver injury assays. | Academic disease modeling and pharmaceutical respiratory toxicity create demand, with sample handling and tissue viability as qualification constraints. The estimated 2026 allocation is ~18% and the scenario CAGR is ~18.9%. Supplier differentiation depends on the tissue source, assay readout and ability to preserve the desired phenotype over multi-day exposure for liver injury assays. Academic publication activity supports scientific interest but is not equivalent to paid procurement for liver injury assays. Revenue is limited to qualifying chips and associated dedicated hardware sold into U.S for liver injury assays. laboratories. |
| Brain-on-a-chip | Brain-on-a-chip serves a modeled ~16% share of domestic device demand in 2026. Neurovascular barrier permeability and central nervous system inflammation motivate brain-chip adoption. Purchasers evaluate human tissue performance under repeated runs and the stability of cell culture across different laboratories for lung barrier tests. The experimental format may require dedicated fluidic control and imaging, so device purchase decisions are linked to total operating burden for lung barrier tests. Reported company-wide research revenue cannot be used as a substitute for sales of the specific chip format for lung barrier tests. | MIMETAS published a perfused blood–brain barrier model in February 2026, illustrating the technical complexity of multi-cell brain systems. The estimated 2026 allocation is ~16% and the scenario CAGR is ~21.4%. Supplier differentiation depends on the tissue source, assay readout and ability to preserve the desired phenotype over multi-day exposure for lung barrier tests. Academic publication activity supports scientific interest but is not equivalent to paid procurement for lung barrier tests. Revenue is limited to qualifying chips and associated dedicated hardware sold into U.S for lung barrier tests. laboratories. |
| Kidney-on-a-chip | Kidney-on-a-chip serves a modeled ~13% share of domestic device demand in 2026. Renal proximal tubule transport and nephrotoxicity endpoints are relevant for candidate selection. Purchasers evaluate human tissue performance under repeated runs and the stability of cell culture across different laboratories for kidney transport studies. The experimental format may require dedicated fluidic control and imaging, so device purchase decisions are linked to total operating burden for kidney transport studies. Reported company-wide research revenue cannot be used as a substitute for sales of the specific chip format for kidney transport studies. | Kidney models need controlled shear stress and transporter expression, making assay reproducibility a decisive purchasing factor. The estimated 2026 allocation is ~13% and the scenario CAGR is ~19.4%. Supplier differentiation depends on the tissue source, assay readout and ability to preserve the desired phenotype over multi-day exposure for kidney transport studies. Academic publication activity supports scientific interest but is not equivalent to paid procurement for kidney transport studies. Revenue is limited to qualifying chips and associated dedicated hardware sold into U.S for kidney transport studies. laboratories. |
| Heart-on-a-chip | Heart-on-a-chip serves a modeled ~11% share of domestic device demand in 2026. Cardiotoxicity and contractile response models complement traditional cellular electrophysiology. Purchasers evaluate human tissue performance under repeated runs and the stability of cell culture across different laboratories for brain vascular models. The experimental format may require dedicated fluidic control and imaging, so device purchase decisions are linked to total operating burden for brain vascular models. Reported company-wide research revenue cannot be used as a substitute for sales of the specific chip format for brain vascular models. | The value proposition depends on stable beating tissues, quantitative force measurement and translation to human exposure. The estimated 2026 allocation is ~11% and the scenario CAGR is ~18.1%. Supplier differentiation depends on the tissue source, assay readout and ability to preserve the desired phenotype over multi-day exposure for brain vascular models. Academic publication activity supports scientific interest but is not equivalent to paid procurement for brain vascular models. Revenue is limited to qualifying chips and associated dedicated hardware sold into U.S for brain vascular models. laboratories. |
| Intestine-on-a-chip | Intestine-on-a-chip serves a modeled ~9% share of domestic device demand in 2026. Intestinal absorption and gut-barrier integrity models support oral drug screening. Purchasers evaluate human tissue performance under repeated runs and the stability of cell culture across different laboratories for cardiac safety screens. The experimental format may require dedicated fluidic control and imaging, so device purchase decisions are linked to total operating burden for cardiac safety screens. Reported company-wide research revenue cannot be used as a substitute for sales of the specific chip format for cardiac safety screens. | Perfusion and epithelial co-culture may improve physiological realism but add training and operating costs. The estimated 2026 allocation is ~9% and the scenario CAGR is ~21.2%. Supplier differentiation depends on the tissue source, assay readout and ability to preserve the desired phenotype over multi-day exposure for cardiac safety screens. Academic publication activity supports scientific interest but is not equivalent to paid procurement for cardiac safety screens. Revenue is limited to qualifying chips and associated dedicated hardware sold into U.S for cardiac safety screens. laboratories. |
| Other organ models | Other organ models serves a modeled ~7% share of domestic device demand in 2026. Vascular, tumor, skin and multi-tissue microfluidic systems broaden experimental use cases. Purchasers evaluate human tissue performance under repeated runs and the stability of cell culture across different laboratories for intestinal uptake studies. The experimental format may require dedicated fluidic control and imaging, so device purchase decisions are linked to total operating burden for intestinal uptake studies. Reported company-wide research revenue cannot be used as a substitute for sales of the specific chip format for intestinal uptake studies. | Specialized disease programs generate small batches, so revenue depends on custom chip designs and reproducible workflows. The estimated 2026 allocation is ~7% and the scenario CAGR is ~20.3%. Supplier differentiation depends on the tissue source, assay readout and ability to preserve the desired phenotype over multi-day exposure for intestinal uptake studies. Academic publication activity supports scientific interest but is not equivalent to paid procurement for intestinal uptake studies. Revenue is limited to qualifying chips and associated dedicated hardware sold into U.S for intestinal uptake studies. laboratories. |
Liver-on-a-chip
The Liver-on-a-chip segment has a modeled ~26% share of 2026 sales and a scenario growth rate of ~19.0% per year. Drug-induced liver injury, metabolic clearance and hepatocyte co-culture are major workflows. Emulate’s liver chip qualification work provides a direct commercial example, although submission status does not establish broad regulatory acceptance for liver injury assays. Laboratories compare throughput, readout sensitivity, device lifetime and the complexity of integrating human cells with microfluidic components. Adoption is constrained by assay-specific qualification rather than by a universal approval that covers every tissue model. This segment is tracked separately from assay outsourcing and drug discovery services.
Lung-on-a-chip
The Lung-on-a-chip segment has a modeled ~18% share of 2026 sales and a scenario growth rate of ~18.9% per year. Air-liquid interface culture and respiratory barrier responses drive lung model design. Academic disease modeling and pharmaceutical respiratory toxicity create demand, with sample handling and tissue viability as qualification constraints for liver injury assays. Laboratories compare throughput, readout sensitivity, device lifetime and the complexity of integrating human cells with microfluidic components for liver injury assays. Adoption is constrained by assay-specific qualification rather than by a universal approval that covers every tissue model for liver injury assays. This segment is tracked separately from assay outsourcing and drug discovery services for liver injury assays.
Brain-on-a-chip
The Brain-on-a-chip segment has a modeled ~16% share of 2026 sales and a scenario growth rate of ~21.4% per year. Neurovascular barrier permeability and central nervous system inflammation motivate brain-chip adoption. MIMETAS published a perfused blood–brain barrier model in February 2026, illustrating the technical complexity of multi-cell brain systems for liver injury assays. Laboratories compare throughput, readout sensitivity, device lifetime and the complexity of integrating human cells with microfluidic components for lung barrier tests. Adoption is constrained by assay-specific qualification rather than by a universal approval that covers every tissue model for lung barrier tests. This segment is tracked separately from assay outsourcing and drug discovery services for lung barrier tests.
Kidney-on-a-chip
The Kidney-on-a-chip segment has a modeled ~13% share of 2026 sales and a scenario growth rate of ~19.4% per year. Renal proximal tubule transport and nephrotoxicity endpoints are relevant for candidate selection for liver injury assays. Kidney models need controlled shear stress and transporter expression, making assay reproducibility a decisive purchasing factor for liver injury assays. Laboratories compare throughput, readout sensitivity, device lifetime and the complexity of integrating human cells with microfluidic components for kidney transport studies. Adoption is constrained by assay-specific qualification rather than by a universal approval that covers every tissue model for kidney transport studies. This segment is tracked separately from assay outsourcing and drug discovery services for kidney transport studies.
Heart-on-a-chip
The Heart-on-a-chip segment has a modeled ~11% share of 2026 sales and a scenario growth rate of ~18.1% per year. Cardiotoxicity and contractile response models complement traditional cellular electrophysiology. The value proposition depends on stable beating tissues, quantitative force measurement and translation to human exposure for liver injury assays. Laboratories compare throughput, readout sensitivity, device lifetime and the complexity of integrating human cells with microfluidic components for brain vascular models. Adoption is constrained by assay-specific qualification rather than by a universal approval that covers every tissue model for brain vascular models. This segment is tracked separately from assay outsourcing and drug discovery services for brain vascular models.
Intestine-on-a-chip
The Intestine-on-a-chip segment has a modeled ~9% share of 2026 sales and a scenario growth rate of ~21.2% per year. Intestinal absorption and gut-barrier integrity models support oral drug screening. Perfusion and epithelial co-culture may improve physiological realism but add training and operating costs for liver injury assays. Laboratories compare throughput, readout sensitivity, device lifetime and the complexity of integrating human cells with microfluidic components for cardiac safety screens. Adoption is constrained by assay-specific qualification rather than by a universal approval that covers every tissue model for cardiac safety screens. This segment is tracked separately from assay outsourcing and drug discovery services for cardiac safety screens.
Other organ models
The Other organ models segment has a modeled ~7% share of 2026 sales and a scenario growth rate of ~20.3% per year. Vascular, tumor, skin and multi-tissue microfluidic systems broaden experimental use cases. Specialized disease programs generate small batches, so revenue depends on custom chip designs and reproducible workflows for liver injury assays. Laboratories compare throughput, readout sensitivity, device lifetime and the complexity of integrating human cells with microfluidic components for intestinal uptake studies. Adoption is constrained by assay-specific qualification rather than by a universal approval that covers every tissue model for intestinal uptake studies. This segment is tracked separately from assay outsourcing and drug discovery services for intestinal uptake studies.
U.S. modeled segmentation schedules
Modeled Region allocation, U.S. device revenue (USD million; analyst scenario)
| Segment | 2026 share | Scenario CAGR | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 | 2035 | 2036 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Northeast | ~34% | ~19.1% | 42.60 | 50.73 | 60.42 | 71.96 | 85.71 | 102.08 | 121.57 | 144.79 | 172.45 | 205.38 | 244.61 |
| South | ~28% | ~21.4% | 35.08 | 42.59 | 51.70 | 62.76 | 76.19 | 92.50 | 112.29 | 136.32 | 165.50 | 200.91 | 243.91 |
| Pacific | ~22% | ~19.6% | 27.56 | 32.96 | 39.42 | 47.15 | 56.39 | 67.45 | 80.67 | 96.48 | 115.39 | 138.00 | 165.05 |
| Midwest | ~10% | ~17.7% | 12.53 | 14.75 | 17.36 | 20.43 | 24.04 | 28.30 | 33.31 | 39.20 | 46.14 | 54.31 | 63.92 |
| Mountain | ~6% | ~17.0% | 7.52 | 8.80 | 10.29 | 12.04 | 14.09 | 16.49 | 19.30 | 22.58 | 26.42 | 30.92 | 36.18 |
These values allocate the same national device-market total across one independent analytical axis. Each axis sums to ~100% in 2026, and no separate axis should be added to another. All future entries are scenario calculations rather than supplier-reported state or product revenues. Their intended use is transparent sensitivity analysis, not claims of observed shipment quantities or verified transaction prices.
Modeled Type allocation, U.S. device revenue (USD million; analyst scenario)
| Segment | 2026 share | Scenario CAGR | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 | 2035 | 2036 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Liver-on-a-chip | ~26% | ~19.0% | 32.57 | 38.76 | 46.13 | 54.89 | 65.32 | 77.73 | 92.50 | 110.07 | 130.99 | 155.88 | 185.49 |
| Lung-on-a-chip | ~18% | ~18.9% | 22.55 | 26.81 | 31.88 | 37.91 | 45.07 | 53.59 | 63.72 | 75.76 | 90.08 | 107.10 | 127.34 |
| Brain-on-a-chip | ~16% | ~21.4% | 20.04 | 24.33 | 29.54 | 35.86 | 43.54 | 52.86 | 64.17 | 77.90 | 94.57 | 114.81 | 139.38 |
| Kidney-on-a-chip | ~13% | ~19.4% | 16.29 | 19.45 | 23.22 | 27.72 | 33.10 | 39.52 | 47.19 | 56.35 | 67.28 | 80.33 | 95.91 |
| Heart-on-a-chip | ~11% | ~18.1% | 13.78 | 16.28 | 19.22 | 22.70 | 26.81 | 31.66 | 37.39 | 44.16 | 52.15 | 61.59 | 72.74 |
| Intestine-on-a-chip | ~9% | ~21.2% | 11.28 | 13.67 | 16.56 | 20.07 | 24.33 | 29.49 | 35.74 | 43.32 | 52.50 | 63.63 | 77.12 |
| Other organ models | ~7% | ~20.3% | 8.77 | 10.55 | 12.69 | 15.27 | 18.37 | 22.10 | 26.59 | 31.99 | 38.48 | 46.29 | 55.69 |
These values allocate the same national device-market total across one independent analytical axis. Each axis sums to ~100% in 2026, and no separate axis should be added to another for liver injury assays. All future entries are scenario calculations rather than supplier-reported state or product revenues for liver injury assays. Their intended use is transparent sensitivity analysis, not claims of observed shipment quantities or verified transaction prices for liver injury assays.
Modeled Application allocation, U.S. device revenue (USD million; analyst scenario)
| Segment | 2026 share | Scenario CAGR | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 | 2035 | 2036 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Pharmaceutical & Biotechnology Companies | ~63% | ~20.2% | 78.93 | 94.87 | 114.03 | 137.07 | 164.76 | 198.04 | 238.04 | 286.12 | 343.92 | 413.39 | 496.90 |
| Academic & Research Institutes | ~27% | ~18.7% | 33.83 | 40.15 | 47.66 | 56.57 | 67.15 | 79.71 | 94.61 | 112.31 | 133.31 | 158.23 | 187.82 |
| Cosmetics Industry | ~6% | ~17.2% | 7.52 | 8.81 | 10.32 | 12.10 | 14.18 | 16.62 | 19.48 | 22.83 | 26.76 | 31.36 | 36.75 |
| Other applications | ~4% | ~20.4% | 5.01 | 6.04 | 7.27 | 8.76 | 10.55 | 12.70 | 15.30 | 18.43 | 22.19 | 26.73 | 32.19 |
These values allocate the same national device-market total across one independent analytical axis. Each axis sums to ~100% in 2026, and no separate axis should be added to another for lung barrier tests. All future entries are scenario calculations rather than supplier-reported state or product revenues for lung barrier tests. Their intended use is transparent sensitivity analysis, not claims of observed shipment quantities or verified transaction prices for lung barrier tests.
Modeled Chip Format allocation, U.S. device revenue (USD million; analyst scenario)
| Segment | 2026 share | Scenario CAGR | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 | 2035 | 2036 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Single-organ microphysiological chips | ~67% | ~18.8% | 83.94 | 99.72 | 118.46 | 140.74 | 167.19 | 198.63 | 235.97 | 280.33 | 333.03 | 395.64 | 470.02 |
| Multi-organ linked systems | ~21% | ~22.5% | 26.31 | 32.23 | 39.48 | 48.36 | 59.24 | 72.57 | 88.90 | 108.91 | 133.41 | 163.43 | 200.20 |
| Specialized barrier-interface chips | ~12% | ~18.7% | 15.03 | 17.84 | 21.18 | 25.14 | 29.84 | 35.42 | 42.04 | 49.90 | 59.23 | 70.30 | 83.45 |
These values allocate the same national device-market total across one independent analytical axis. Each axis sums to ~100% in 2026, and no separate axis should be added to another for kidney transport studies. All future entries are scenario calculations rather than supplier-reported state or product revenues for kidney transport studies. Their intended use is transparent sensitivity analysis, not claims of observed shipment quantities or verified transaction prices for kidney transport studies.
Modeled Sales Channel allocation, U.S. device revenue (USD million; analyst scenario)
| Segment | 2026 share | Scenario CAGR | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 | 2035 | 2036 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Direct manufacturer contracts | ~59% | ~20.1% | 73.92 | 88.77 | 106.62 | 128.05 | 153.78 | 184.69 | 221.82 | 266.40 | 319.95 | 384.26 | 461.49 |
| Specialist laboratory distributors | ~22% | ~17.9% | 27.56 | 32.50 | 38.31 | 45.17 | 53.25 | 62.79 | 74.03 | 87.28 | 102.90 | 121.32 | 143.04 |
| Institutional framework agreements | ~14% | ~19.3% | 17.54 | 20.92 | 24.96 | 29.78 | 35.53 | 42.38 | 50.57 | 60.32 | 71.97 | 85.86 | 102.43 |
| Other channels | ~5% | ~22.3% | 6.26 | 7.66 | 9.36 | 11.45 | 13.99 | 17.11 | 20.91 | 25.57 | 31.26 | 38.21 | 46.72 |
These values allocate the same national device-market total across one independent analytical axis. Each axis sums to ~100% in 2026, and no separate axis should be added to another for brain vascular models. All future entries are scenario calculations rather than supplier-reported state or product revenues for brain vascular models. Their intended use is transparent sensitivity analysis, not claims of observed shipment quantities or verified transaction prices for brain vascular models.
Modeled Flow Architecture allocation, U.S. device revenue (USD million; analyst scenario)
| Segment | 2026 share | Scenario CAGR | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 | 2035 | 2036 |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Actively perfused platforms | ~68% | ~20.0% | 85.19 | 102.23 | 122.67 | 147.21 | 176.65 | 211.98 | 254.38 | 305.25 | 366.30 | 439.56 | 527.48 |
| Gravity-driven perfusion | ~19% | ~19.1% | 23.80 | 28.35 | 33.76 | 40.21 | 47.89 | 57.04 | 67.94 | 80.91 | 96.37 | 114.77 | 136.70 |
| Static or intermittent-flow chips | ~13% | ~18.6% | 16.29 | 19.31 | 22.90 | 27.15 | 32.20 | 38.18 | 45.27 | 53.68 | 63.65 | 75.48 | 89.50 |
These values allocate the same national device-market total across one independent analytical axis. Each axis sums to ~100% in 2026, and no separate axis should be added to another for cardiac safety screens. All future entries are scenario calculations rather than supplier-reported state or product revenues for cardiac safety screens. Their intended use is transparent sensitivity analysis, not claims of observed shipment quantities or verified transaction prices for cardiac safety screens.
Segment Analysis: By Application
Pharmaceutical and biotechnology customers account for an estimated ~63% of 2026 U.S. organ-chip device sales, followed by academic and research institutes at ~27%. Cosmetics and other research buyers contribute smaller shares, and outsourced screening fees remain excluded even when a service provider uses qualifying microfluidic devices. All reported percentages are modeled allocations within a device-only revenue boundary and should not be mistaken for audited supplier shipments for liver injury assays.
| Application | Demand characteristics |
|---|---|
| Pharmaceutical & Biotechnology Companies | These buyers test candidate safety, metabolism, barrier permeability and disease mechanisms before clinical programs advance. The modeled share is ~63% in 2026, with a projected category CAGR of ~20.2% through 2036. Budget approval depends on evidence that the chip readout addresses a specific experimental question rather than simply replacing a conventional culture plate. Procurement contracts may bundle instrumentation, disposable chips and training, so only attributable hardware and eligible consumables enter the market boundary. Customers also weigh validation documentation, operator training and assay transfer between laboratories. |
| Academic & Research Institutes | University laboratories investigate fundamental physiology and benchmark new chip configurations using NIH-funded translational research networks. The modeled share is ~27% in 2026, with a projected category CAGR of ~18.7% through 2036. Budget approval depends on evidence that the chip readout addresses a specific experimental question rather than simply replacing a conventional culture plate for liver injury assays. Procurement contracts may bundle instrumentation, disposable chips and training, so only attributable hardware and eligible consumables enter the market boundary for liver injury assays. Customers also weigh validation documentation, operator training and assay transfer between laboratories for liver injury assays. |
| Cosmetics Industry | Cosmetics research uses human-relevant skin and barrier systems where regulatory and ethical considerations favor non-animal evidence. The modeled share is ~6% in 2026, with a projected category CAGR of ~17.2% through 2036. Budget approval depends on evidence that the chip readout addresses a specific experimental question rather than simply replacing a conventional culture plate for lung barrier tests. Procurement contracts may bundle instrumentation, disposable chips and training, so only attributable hardware and eligible consumables enter the market boundary for lung barrier tests. Customers also weigh validation documentation, operator training and assay transfer between laboratories for lung barrier tests. |
| Other applications | Environmental toxicology, specialized diagnostics research and food-safety testing generate smaller procurement programs with distinct assay requirements. The modeled share is ~4% in 2026, with a projected category CAGR of ~20.4% through 2036. Budget approval depends on evidence that the chip readout addresses a specific experimental question rather than simply replacing a conventional culture plate for kidney transport studies. Procurement contracts may bundle instrumentation, disposable chips and training, so only attributable hardware and eligible consumables enter the market boundary for kidney transport studies. Customers also weigh validation documentation, operator training and assay transfer between laboratories for kidney transport studies. |
Pharmaceutical & Biotechnology Companies represents a separate end-use procurement pool with an estimated ~63% share in the base year. These buyers test candidate safety, metabolism, barrier permeability and disease mechanisms before clinical programs advance. The scenario assigns a ~20.2% annual increase to this application based on evolving demand for more human-relevant laboratory models. The commercial opportunity is sensitive to cost per experiment and to whether the user operates the platform in-house. Sales through contract research organizations are recorded only when the organization purchases devices, not when it invoices customers for test results.
Academic & Research Institutes represents a separate end-use procurement pool with an estimated ~27% share in the base year. University laboratories investigate fundamental physiology and benchmark new chip configurations using NIH-funded translational research networks. The scenario assigns a ~18.7% annual increase to this application based on evolving demand for more human-relevant laboratory models. The commercial opportunity is sensitive to cost per experiment and to whether the user operates the platform in-house for liver injury assays. Sales through contract research organizations are recorded only when the organization purchases devices, not when it invoices customers for test results for liver injury assays.
Cosmetics Industry represents a separate end-use procurement pool with an estimated ~6% share in the base year. Cosmetics research uses human-relevant skin and barrier systems where regulatory and ethical considerations favor non-animal evidence. The scenario assigns a ~17.2% annual increase to this application based on evolving demand for more human-relevant laboratory models. The commercial opportunity is sensitive to cost per experiment and to whether the user operates the platform in-house for lung barrier tests. Sales through contract research organizations are recorded only when the organization purchases devices, not when it invoices customers for test results for lung barrier tests.
Other applications represents a separate end-use procurement pool with an estimated ~4% share in the base year. Environmental toxicology, specialized diagnostics research and food-safety testing generate smaller procurement programs with distinct assay requirements. The scenario assigns a ~20.4% annual increase to this application based on evolving demand for more human-relevant laboratory models. The commercial opportunity is sensitive to cost per experiment and to whether the user operates the platform in-house for kidney transport studies. Sales through contract research organizations are recorded only when the organization purchases devices, not when it invoices customers for test results for kidney transport studies.
Regional Analysis
The United States is modeled through five nonoverlapping domestic subregions: Northeast, South, Pacific, Midwest and Mountain. The Northeast leads with an estimated ~34% of 2026 demand; the West is split into Pacific and Mountain states to preserve five geographic blocks without importing foreign regions or inventing territory revenues. Regional placement follows the laboratory destination of a device sale and does not include Canadian, European or Asian markets.
Where is United States organ-on-chip demand concentrated?
Domestic sales are assigned to the location of the U.S. laboratory or purchasing entity rather than to the headquarters of a multinational supplier. The five subregions cover all fifty states and the District of Columbia exactly once; U.S. territories are excluded from this state-based model. Northeast biopharma clusters lead, while the South and Pacific contain significant translational centers and academic buyers. No public source provides a verified revenue distribution by these exact five subregions, so every regional share and CAGR is explicitly modeled. This geographic structure prevents the United States total from being mislabeled as a global market.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Northeast | Estimated ~34% share | Modeled ~19.1% CAGR | Boston/Cambridge, New York, Philadelphia | Device validation, procurement process and reproducibility |
| South | Estimated ~28% share | Modeled ~21.4% CAGR | Texas, North Carolina, Maryland, Florida | Device validation, procurement process and reproducibility |
| Pacific | Estimated ~22% share | Modeled ~19.6% CAGR | California, Washington, Oregon, Alaska, Hawaii | Device validation, procurement process and reproducibility |
| Midwest | Estimated ~10% share | Modeled ~17.7% CAGR | Illinois, Ohio, Michigan, Indiana, Minnesota | Device validation, procurement process and reproducibility |
| Mountain | Estimated ~6% share | Modeled ~17.0% CAGR | Colorado, Utah, Arizona, New Mexico, Nevada, Idaho, Montana, Wyoming | Device validation, procurement process and reproducibility |
Organ-on-Chip Manufacturers and U.S. Competitive Landscape
Commercial competition spans dedicated organ-chip developers, platform providers and adjacent 3D tissue-model companies. Emulate, MIMETAS and CN Bio provide directly documented microphysiological products; some names on the publisher roster have broader tissue-engineering or contract-research businesses and cannot be treated as audited U.S. chip manufacturers solely because they appear in a company list.
Emulate is a direct platform competitor in perfused human tissue chips. Its AVA launch in June 2025 introduced an instrument capable of running up to 96 independent organ-chip samples, and its September 2026 liver-chip qualification package highlighted the importance of regulatory-grade data. The instrument and consumable business should be separated from services performed using the instrument. Large pharmaceutical buyers value validated protocols and high sample throughput more than a generic device count. The company is relevant to U.S. device competition without assuming that its overall revenue equals this market.
MIMETAS approaches the market through OrganoPlate microfluidic arrays and gravity-driven perfusion. The January 2025 UniFlow launch and February 2026 blood–brain barrier work demonstrate a product strategy emphasizing compatibility with standard imaging and high-throughput research. Bruker announced a majority investment in August 2026, which may strengthen commercialization and distribution. MIMETAS also launched OrganoServices in September 2026; that service revenue is excluded from this hardware-only boundary. U.S. purchases of its eligible chips count regardless of the supplier’s Netherlands headquarters.
CN Bio markets PhysioMimix organ-on-chip systems for drug metabolism and toxicity studies. Its September 2025 announcement added computational modeling to contract research capabilities, illustrating how manufacturers increasingly combine physical platforms with analytical services. Only device and eligible dedicated consumable revenue belongs in this market, not the entire value of a modeling project. Smaller providers and academic spinouts may compete in organ-specific niches but often lack broad catalogues or validated multi-site protocols. Competitive rankings should therefore be based on product fit rather than unverified consolidated company turnover.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Dedicated device platforms | Emulate; MIMETAS; CN Bio | Directly documented microfluidic organ-chip products, repeat-use platforms and dedicated consumables. |
| Specialized research suppliers | Nortis; Hesperos; AxoSim; TissUse | Organ-specific or multi-organ scientific offerings; verify current commercial product and service split before assigning merchant revenue. |
| Adjacent tissue-model ecosystem | Organovo; Draper; other tissue engineering groups | Broader 3D tissue, research engineering or service activity should not automatically be counted as organ-chip sales. |
Key companies profiled
- Emulate
- MIMETAS
- CN Bio
- Nortis
- Hesperos
- AxoSim
- TissUse
- Draper
- Organovo (adjacent 3D tissue)
- Tara Biosystems (legacy roster; corporate status requires review)
United States Organ-on-Chip Device Manufacturing and Supply
The supply chain combines polymer microfabrication, surface chemistry, microchannel design, human cell sourcing and instrument control. Device yield depends on fluidic sealing, low adsorption, sterility and repeatable cell seeding; the critical commercial output is a reproducible assay-ready chip rather than a semiconductor integrated circuit. All reported percentages are modeled allocations within a device-only revenue boundary and should not be mistaken for audited supplier shipments for lung barrier tests.
Microfluidic chip fabrication starts with polymer or glass substrates, patterned channels and bonding operations. Manufacturers need precise control of channel geometry, membrane permeability and surface treatment so cells experience reproducible fluid shear and nutrient delivery. A failed seal or high drug adsorption can invalidate an entire multi-day toxicology run, making production yield and quality assurance central to margins. Consumable devices may be single-use, while pumps and imaging modules remain durable equipment. Commercial contracts often combine hardware qualification with cell protocols and training.
Human cell sourcing is a separate bottleneck from plastic chip manufacturing. Primary cells and induced pluripotent stem cell-derived tissues vary by donor, batch and differentiation protocol, so standardized chip geometry alone does not guarantee reproducible biology. MIMETAS reported a blood–brain barrier model incorporating endothelial cells, pericytes and astrocytes under unidirectional flow. The commercial challenge is maintaining physiologically relevant readouts over the exposure window without excessive operator intervention. Vendors that support standardized assays can reduce customer validation time and improve recurring chip utilization.
Instrument capacity influences the economics of a disposable chip platform. Emulate’s AVA system supports up to 96 independent organ-chip samples in a run, illustrating why high-throughput operation matters to pharmaceutical laboratories. MIMETAS UniFlow takes a different approach with gravity-driven flow and reduced external pump complexity. Neither instrument specification can be converted directly into annual sales without utilization, pricing and shipment evidence. The modeled market therefore distinguishes capital equipment from eligible consumable chip units and excludes contract research charges.
United States Organ-on-Chip Market Dynamics: Drivers, Restraints and Opportunities
Growth is supported by pharmaceutical demand for human-relevant preclinical evidence, NIH-backed translational centers, platform throughput improvements and clearer regulatory discussion of NAM validation. It is constrained by high per-assay costs, biological variability, slow cross-site qualification and competition from conventional organoids or other laboratory models. All reported percentages are modeled allocations within a device-only revenue boundary and should not be mistaken for audited supplier shipments for kidney transport studies.
MARKET DRIVERS
Drivers Impact Analysis
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2027–2029 | 2030–2032 | 2033–2036 |
|---|---|---|---|---|---|
| FDA NAM validation framework and industry adoption | High | +9.10% | High | High | High |
| Pharmaceutical liver toxicity and ADME programs | High | +5.60% | High | High | Medium |
| Higher-throughput disposable chip platforms | Medium-High | +4.30% | Medium | High | High |
| NIH and university translational centers | Medium | +3.50% | High | Medium | Medium |
| Multi-organ disease and barrier research | Low-Medium | +2.50% | Medium | Medium | High |
| Others (training, contract renewals and academic expansion) | Low | +1.60% | Low | Medium | Medium |
Regulatory discussion increases willingness to validate human-relevant assays
The FDA’s March 2026 draft guidance addresses principles for validating new approach methodologies in drug development. Its September 2026 terminology update also recognizes that appropriate non-animal methods can support nonclinical evaluation. These steps encourage laboratories to examine human-cell models with defined performance criteria. The regulatory changes do not create a universal authorization for every chip, so product-specific qualification remains necessary. Vendors benefit most when they provide reproducible data and documentation suitable for a specific safety question.
Liver safety screening anchors commercial demand
Drug-induced liver injury remains an important reason to adopt organ-chip models. Emulate’s September 2026 FDA ISTAND qualification-package submission demonstrates supplier investment in regulatory-grade liver-chip evidence. Pharmaceutical companies can use such systems to explore human-specific toxicity mechanisms before committing to expensive development stages. The qualification process requires a defined context of use and cannot be generalized to unrelated organs or compounds. Recurring disposable chip purchases may expand as protocols move from pilot experiments into routine screening.
Higher throughput improves cost per experiment
Platform automation addresses the staffing burden of manual microfluidic experiments. Emulate introduced AVA in June 2025 with capacity for up to 96 independent organ-chip samples, while MIMETAS UniFlow supports high-density gravity-driven experiments. Laboratories can compare conditions and replicates more efficiently when incubation, perfusion and imaging are standardized. The instrument purchase may be episodic, but dedicated chip consumables generate recurring revenue if assay utilization increases. Commercial value depends on usable results per experiment rather than headline chip capacity alone.
Public research networks strengthen scientific validation
NIH NCATS awarded roughly $31 million across four translational tissue-chip centers in July 2024. These programs aim to establish more predictive human-cell platforms and advance cross-laboratory performance. Universities can become early reference sites for specific liver, kidney, lung or neurovascular models. Grant budgets also pay salaries, research operations and many non-device expenses, so they cannot be equated with chip sales. Validated research protocols can nonetheless reduce perceived risk for later pharmaceutical purchasing decisions.
MARKET RESTRAINTS
Restraints Impact Analysis
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2027–2029 | 2030–2032 | 2033–2036 |
|---|---|---|---|---|---|
| High device and validation cost | High | -3.00% | High | High | Medium |
| Biological variability and interlaboratory reproducibility | Medium-High | -2.10% | High | Medium | Medium |
| Competing organoids and established assays | Medium | -1.30% | Medium | Medium | High |
| Others (procurement delays and platform lock-in) | Low | -0.50% | Medium | Low | Low |
Assay economics remain challenging for smaller laboratories
An organ-chip experiment may require a dedicated instrument, disposable chips, qualified human cells, media and trained personnel. These costs can be difficult to justify for laboratories with irregular sample volumes or limited technical support. High-throughput platforms reduce cost per usable result only when utilization is sufficient and protocols are stable. Procurement teams also consider the cost of repeating failed experiments, not merely the sticker price of a chip. A clear economic case is essential for moving beyond proof-of-concept adoption.
Biological repeatability is harder than microfabrication repeatability
Two devices with identical channel dimensions can produce different biological responses when cell sources, differentiation or seeding protocols vary. Regulatory-grade work requires assay precision, appropriate controls and a defined context of use. The FDA’s March 2026 NAM guidance emphasizes validation principles rather than granting blanket acceptance to particular platforms. Long-term tissue viability and quantitative endpoint stability are especially demanding in multi-organ experiments. Supplier support and standardized protocols can therefore determine whether customers renew device purchases.
Alternative human models compete for the same research budget
Organoids, conventional 3D cell cultures, tissue slices and computational approaches all address parts of the preclinical evidence problem. Some assays need only a simple cellular endpoint and gain little from complex perfusion hardware. Organ-chip vendors must demonstrate incremental value in transport, metabolism, mechanical signaling or cell interaction. Purchasing decisions often compare data quality, sample throughput, staffing needs and historical validation evidence. A successful application-specific comparison matters more than claiming that one platform replaces all existing models.
MARKET OPPORTUNITIES
Cross-organ linked models
Linking liver, intestine and kidney chips could improve the study of absorption, metabolism and excretion across tissue compartments. Commercial systems must control fluid volumes and residence times without introducing unrealistic dilution or adsorption. Research users value experiments that clarify mechanistic pathways difficult to reproduce in isolated cell culture. Multi-organ adoption remains dependent on standard protocols and data interpretation, not just additional microchannels. Suppliers with interoperable chip formats and transparent assay specifications could capture specialized development programs.
Barrier models for neurovascular and pulmonary research
Blood–brain barrier and lung-on-chip systems address transport and inflammatory mechanisms relevant to difficult therapeutic targets. MIMETAS reported a perfused blood–brain barrier model in February 2026 with multiple human cell types. Academic and pharmaceutical buyers may use these platforms for permeability screening and disease mechanism studies. The highest-value opportunity is a reproducible endpoint with a clearly defined predictive purpose. Device demand will depend on whether laboratories can reproduce results across independent batches and sites.
Consumable chip repeat purchasing
Disposable organ-chip cartridges create a different revenue pattern from one-time instrument installations. A laboratory that qualifies a specific microfluidic platform may purchase chips repeatedly for dose-response and replicate studies. Suppliers can improve retention by offering reliable logistics, validated cell protocols and compatibility with existing imaging systems. A service contract is excluded from device revenue, but a separately priced eligible chip is included. This distinction supports clearer forecasting of installed-base utilization and recurring hardware sales.
Organ-on-Chip Supply Chain and Commercial Delivery
The value chain begins with microfabricated chips, membranes and human-cell preparation, then moves through assay qualification, platform distribution and research laboratory procurement. Consumable devices are purchased repeatedly when an experiment is standardized, whereas outsourced study fees and software-only services are not part of factory-gate hardware revenue. All reported percentages are modeled allocations within a device-only revenue boundary and should not be mistaken for audited supplier shipments for brain vascular models.
Upstream materials. Polymer properties and membrane chemistry determine whether a chip can sustain physiologically relevant flow and drug exposure. Adsorption to channel walls can distort measured compound concentration, especially in studies of lipophilic molecules. Suppliers therefore select materials and surface treatments with assay requirements in mind rather than treating all microfluidic plastics as interchangeable. A change in substrate formulation may require renewed qualification for sensitive endpoints. Reliable component sourcing supports consistent consumable performance and helps customers compare results across experiments.
Chip assembly. Microchannel fabrication must maintain precise geometry, leak-free bonding and stable surfaces for cell attachment. High-throughput arrays reduce handling steps but increase the importance of consistent perfusion and imaging access across many wells. Quality systems must document dimensions, flow characteristics and lot release criteria. Manufacturing yield affects chip cost, while experimental failure can create additional hidden cost for customers. Vendors that provide reproducible consumables can support repeat purchasing after the initial platform is installed.
Commercial distribution. Large pharmaceutical companies often procure directly from platform developers and negotiate technical support alongside device supply. Universities may use framework agreements, centralized procurement or specialist laboratory distributors. Sales into the United States count in the domestic model even when the manufacturer is headquartered overseas. Contract research services remain outside the device revenue boundary unless a separately priced qualifying chip is actually sold. This distinction also prevents a supplier’s analytical service turnover from being misclassified as chip production.
Downstream use. Drug developers evaluate liver toxicity, barrier transport and disease mechanisms with controlled human-cell microenvironments. Academic groups use chips to test physiological hypotheses and develop assay standards that can later inform commercial adoption. The FDA’s NAM framework encourages fit-for-purpose validation rather than assuming every chip is suitable for every drug. Users therefore purchase not only a physical device but confidence in cell performance and experimental reproducibility. Demand depends on repeatable scientific utility and an operating cost compatible with the laboratory’s workflow.
Recent Developments in the United States Organ-on-Chip Market
- 1 October 2026 Announced
CN Bio published the program for a December 2026 organ-on-chip symposium with pharmaceutical and regulatory participants. The announcement reflects continuing industry focus on practical adoption and study design; it is a knowledge-exchange event rather than evidence of audited device sales. The development is relevant to device selection because purchasers increasingly compare physiological relevance, operating complexity and the evidence needed to support repeatable assay outcomes. It should be interpreted within the United States device-and-consumables revenue boundary rather than as a measure of total pharmaceutical research spending. Commercial demand depends on independent customer procurement and validated workflows. Source - 21 September 2026 Regulatory
The FDA issued a direct final rule updating nonclinical testing terminology to recognize scientifically appropriate non-animal methods. The rule does not waive existing evidence standards or automatically validate a particular commercial organ chip, but it reduces terminology barriers to considering NAMs. The development is relevant to device selection because purchasers increasingly compare physiological relevance, operating complexity and the evidence needed to support repeatable assay outcomes for liver injury assays. It should be interpreted within the United States device-and-consumables revenue boundary rather than as a measure of total pharmaceutical research spending for liver injury assays. Commercial demand depends on independent customer procurement and validated workflows. Source - 14 September 2026 Launched
MIMETAS announced OrganoServices, a standardized contract research offering using OrganoPlate platforms for gastrointestinal toxicity and vascular injury. The development demonstrates demand for organ-chip-derived data while highlighting the accounting distinction between service revenue and the sale of a physical chip. The development is relevant to device selection because purchasers increasingly compare physiological relevance, operating complexity and the evidence needed to support repeatable assay outcomes for lung barrier tests. It should be interpreted within the United States device-and-consumables revenue boundary rather than as a measure of total pharmaceutical research spending for lung barrier tests. Commercial demand depends on independent customer procurement and validated workflows. Source - 9 September 2026 Submitted
Emulate submitted a full qualification package for its Human Liver-Chip under the FDA ISTAND program, covering Zoë and AVA platforms. The milestone advances regulatory evaluation of a defined drug-induced liver injury use case but is not equivalent to an FDA approval of all liver-chip assays. The development is relevant to device selection because purchasers increasingly compare physiological relevance, operating complexity and the evidence needed to support repeatable assay outcomes for kidney transport studies. It should be interpreted within the United States device-and-consumables revenue boundary rather than as a measure of total pharmaceutical research spending for kidney transport studies. Commercial demand depends on independent customer procurement and validated workflows. Source - 10 August 2026 Investment
Bruker announced a majority investment in MIMETAS, whose OrganoPlate supports scalable human tissue models. The investment may support commercialization and distribution; the transaction itself is not evidence of the number of chips sold to United States laboratories. The development is relevant to device selection because purchasers increasingly compare physiological relevance, operating complexity and the evidence needed to support repeatable assay outcomes for brain vascular models. It should be interpreted within the United States device-and-consumables revenue boundary rather than as a measure of total pharmaceutical research spending for brain vascular models. Commercial demand depends on independent customer procurement and validated workflows. Source - 20 April 2026 Updated
The FDA reported first-year progress on its roadmap to reduce animal testing in drug development and promote human-relevant alternatives. The program supports regulatory dialogue around NAMs, while validation remains tied to specific nonclinical questions and documented assay performance. The development is relevant to device selection because purchasers increasingly compare physiological relevance, operating complexity and the evidence needed to support repeatable assay outcomes for cardiac safety screens. It should be interpreted within the United States device-and-consumables revenue boundary rather than as a measure of total pharmaceutical research spending for cardiac safety screens. Commercial demand depends on independent customer procurement and validated workflows. Source - 18 March 2026 Guidance
The FDA issued draft guidance on general considerations for validation of new approach methodologies in drug development. The document provides nonbinding principles for study design and reporting rather than mandatory organ-chip adoption, so commercial uptake remains application-specific. The development is relevant to device selection because purchasers increasingly compare physiological relevance, operating complexity and the evidence needed to support repeatable assay outcomes for intestinal uptake studies. It should be interpreted within the United States device-and-consumables revenue boundary rather than as a measure of total pharmaceutical research spending for intestinal uptake studies. Commercial demand depends on independent customer procurement and validated workflows. Source - 17 February 2026 Published
MIMETAS described a three-dimensional human blood–brain barrier model using unidirectional perfusion and multiple human cell types. The study supports technical development of brain-chip applications but does not establish a commercial market share for any vendor or U.S. state. The development is relevant to device selection because purchasers increasingly compare physiological relevance, operating complexity and the evidence needed to support repeatable assay outcomes for tumor vascular systems. It should be interpreted within the United States device-and-consumables revenue boundary rather than as a measure of total pharmaceutical research spending for tumor vascular systems. Commercial demand depends on independent customer procurement and validated workflows. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2036 |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2026–2036 |
| Historical Context | 2021–2025 |
| 2026 Market Size | USD 125.28 million |
| 2027 Market Size | USD 149.90 million |
| 2036 Market Size | USD 753.67 million |
| Growth Rate | CAGR of 19.7% during 2026–2036 |
| Unit | Value in USD million; eligible devices and dedicated consumable chips |
| Revenue Boundary | Factory-gate U.S. sales; exclude outsourced assay and CRO services |
| By Type | Liver-on-a-chip · Lung-on-a-chip · Brain-on-a-chip · Kidney-on-a-chip · Heart-on-a-chip · Intestine-on-a-chip · Other organ models |
| By Application | Pharmaceutical & Biotechnology Companies · Academic & Research Institutes · Cosmetics Industry · Other applications |
| By Chip Format | Single-organ microphysiological chips · Multi-organ linked systems · Specialized barrier-interface chips |
| By Sales Channel | Direct manufacturer contracts · Specialist laboratory distributors · Institutional framework agreements · Other channels |
| By Flow Architecture | Actively perfused platforms · Gravity-driven perfusion · Static or intermittent-flow chips |
| By Region | U.S.-only five-region model: Northeast, South, Pacific, Midwest and Mountain; Pacific and Mountain are disjoint subdivisions of the Census West, all 50 states plus DC included, territories excluded. NortheastMassachusetts, New York, Pennsylvania and the remaining Northeast states SouthSouth Atlantic and south-central states plus the District of Columbia PacificPacific states, with Alaska and Hawaii included MidwestEast North Central and West North Central states MountainMountain states only |
| Key Companies Profiled | Emulate; MIMETAS; CN Bio; Nortis; Hesperos; AxoSim; TissUse; Draper; Organovo (adjacent 3D tissue activity); Tara Biosystems (legacy roster, review required) |
| Customization Scope | Optional detailed state-level procurement and chip format splits, subject to supporting commercial evidence and scope confirmation. |
Frequently Asked Questions
What is the size of the U.S. organ-on-chip device market?
The modeled U.S. market is USD 125.28 million in 2026 and is projected at USD 753.67 million by 2036, representing a 19.7% CAGR. The scope counts dedicated microfluidic organ-chip devices and eligible consumable chips purchased for U.S. laboratory use. The forecast extends beyond the publisher’s original 2030 endpoint, so it is a scenario rather than audited manufacturer shipment guidance.
Which organ model is the largest segment?
Liver-on-chip is the largest modeled type, accounting for ~26% of 2026 U.S. revenue. Pharmaceutical interest in drug-induced liver injury and metabolism testing provides the central demand case. Emulate’s September 2026 FDA ISTAND submission for a Human Liver-Chip demonstrates a defined qualification effort, but a submission is not a universal authorization for all liver models.
Why are pharmaceutical companies the main customers?
Pharmaceutical and biotechnology companies hold an estimated ~63% application share because they need human-relevant models for toxicity, metabolism and disease research. Organ chips may supplement conventional cellular or animal studies where a specific microphysiological readout adds predictive value. Procurement decisions still require repeatable assay results, staff training and an acceptable cost per usable experiment.
Which U.S. subregion has the largest modeled share?
The Northeast leads with an estimated ~34% of 2026 domestic device demand, reflecting Boston and New York biotechnology and academic research concentration. The model also includes South, Pacific, Midwest and Mountain as nonoverlapping U.S. subdivisions. These percentages are scenario allocations, not audited sales by Census division, and no foreign country is included in the geographic total.
Does the market include research services and CRO contracts?
No. The revenue boundary includes factory-gate devices and eligible dedicated consumable chips sold for U.S. use. Contract research fees, outsourced drug screening, computational modeling, general laboratory automation and pharmaceutical R&D budgets are excluded. A supplier offering both physical platforms and assay services must separate the qualifying product revenue from the value of work performed for customers.
What changed in FDA policy during 2026?
The FDA issued draft NAM validation guidance in March 2026 and updated nonclinical testing terminology in September 2026 to recognize scientifically appropriate non-animal approaches. These actions can encourage development and validation of organ-chip assays. They do not mean every commercial chip is qualified or that drug developers can omit evidence required for a particular submission.
How do perfused chips differ from static systems?
Actively perfused chips circulate media through microchannels and can reproduce flow-related signals, while gravity-driven systems reduce the need for external pumps. Static or intermittent-flow designs may be simpler for some assays but may not capture the same shear or transport conditions. The modeled mix assigns ~68% to actively perfused, ~19% to gravity-driven and ~13% to static or intermittent formats.
Which companies supply relevant organ-chip technologies?
Emulate, MIMETAS and CN Bio have directly documented commercial microphysiological systems. Specialized groups such as Nortis, Hesperos, AxoSim and TissUse are relevant to organ-specific or multi-organ research, but product and service revenue must be distinguished. Organovo and certain legacy names on older company lists should not automatically be counted as current merchant organ-chip device manufacturers.
How was the 2036 projection developed?
The publisher’s U.S. endpoints of $87.5 million in 2024 and $256.8 million in 2030 imply about 19.655% annual growth. Applying that rate gives the 2026 modeled base and the 2036 scenario. The extra six years are extrapolated beyond the publisher’s original forecast, so the result is sensitive to adoption, assay validation and device utilization assumptions.
What are the biggest commercialization obstacles?
The leading obstacles are device and cell-culture cost, biological variability, reproducibility between laboratories and competition from simpler human-cell models. Validation must match the intended drug-development context rather than relying on a generic technology claim. High-throughput instruments and standardized protocols may lower cost per result, but adoption still depends on technical support and credible experimental performance.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF