Key Statistics
Key Takeaways
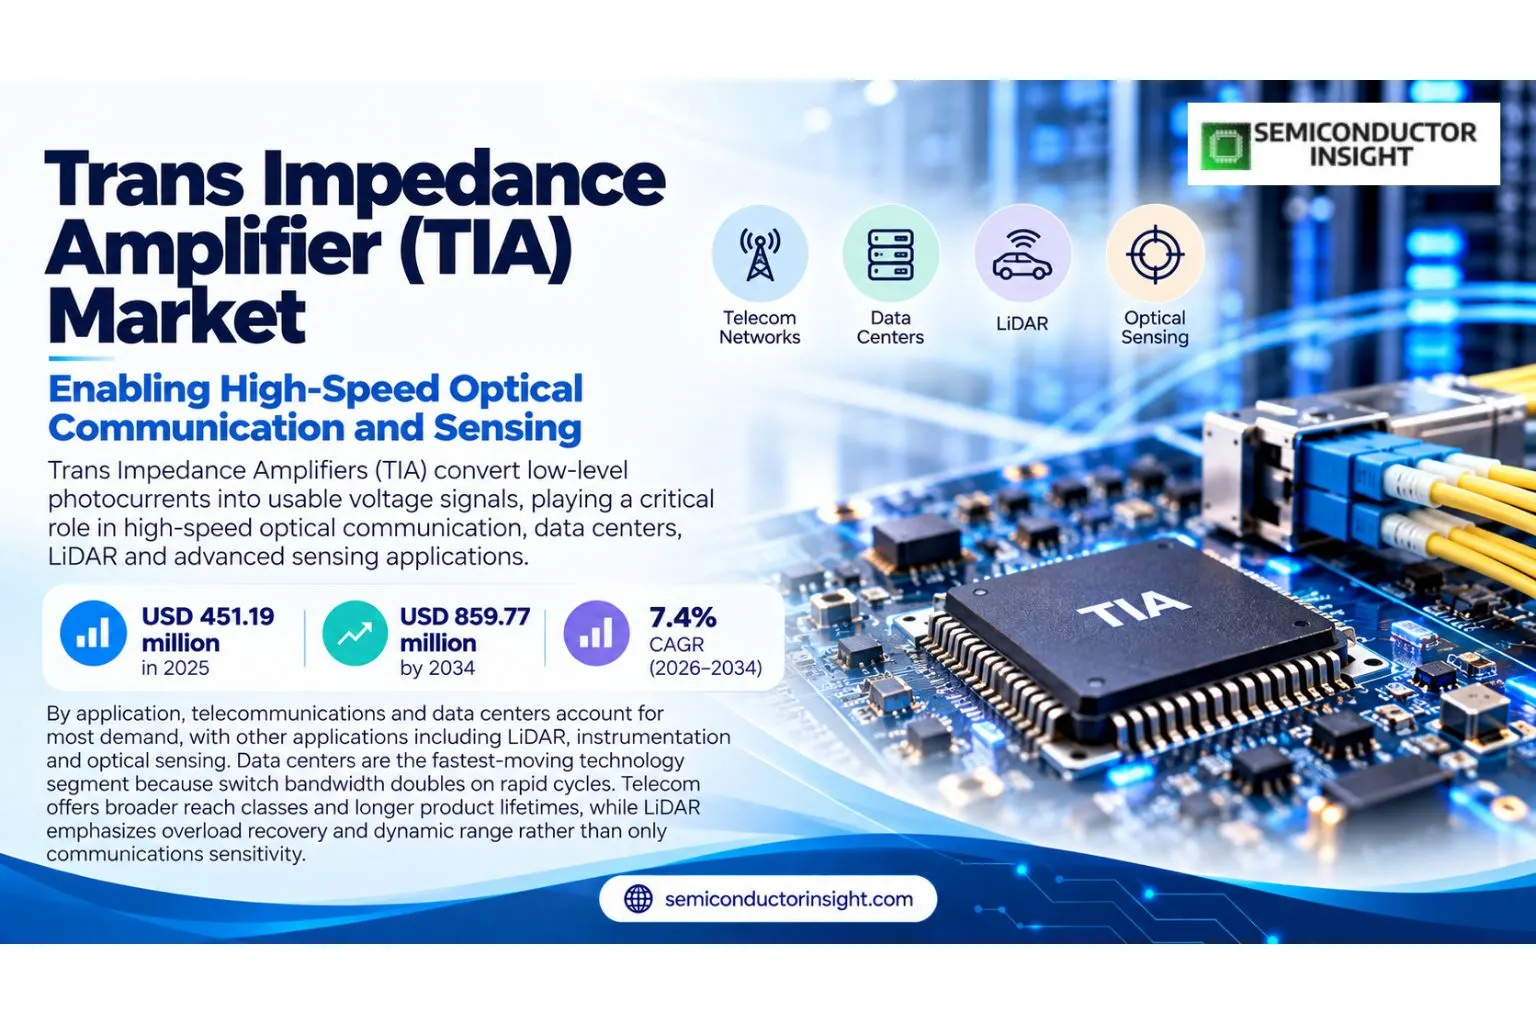
- Market size: The market is valued at USD 451.19 million in 2025 and is projected to reach USD 859.77 million by 2034, representing a 7.4% CAGR during 2026–2034.
- High-speed optical communication is the largest growth engine, with ≥40Gbps and next-generation receiver front ends benefiting from 400G, 800G and emerging 1.6T networks.
- North America leads current revenue, supported by hyperscale data centers, optical networking and semiconductor design, while Asia Pacific has the fastest demand growth.
- Telecommunications and data centers dominate applications, as TIAs are fundamental receiver components that convert photodiode current into low-noise voltage signals.
- Integration is increasing, with TIAs moving closer to photodiodes and optical engines to reduce parasitics, power and footprint.
Trans Impedance Amplifier (TIA) Market Overview
Trans impedance amplifier TIA market is valued at USD 451.19 million in 2025 and is projected to reach USD 859.77 million by 2034, expanding at a 7.4% CAGR during 2026–2034. The 2026 market level is USD 484.70 million. North America leads current revenue, while Asia Pacific grows fastest through optical-module manufacturing and network buildout. Market growth follows the bandwidth transition from legacy optical links toward 400G, 800G and higher-speed data-center and telecom receivers.
Transimpedance amplifiers convert very small photodiode currents into usable voltage signals while preserving bandwidth and minimizing added noise. They are fundamental receiver components in optical communication, LiDAR and sensing. Key design parameters include transimpedance gain, input-referred noise, bandwidth, overload recovery, dynamic range, power consumption and output interface. Higher data rates make parasitic capacitance and package design increasingly important.
Commercial TIAs span low-speed precision devices through multi-tens-of-gigabit optical receiver ICs. Analog Devices’ current product portfolio includes precision and optical TIAs, while legacy 43Gbps devices illustrate the architecture used in high-speed fiber receivers. Newer optical modules increasingly integrate TIAs with photodiodes or receiver optical subassemblies to shorten electrical paths and improve power efficiency.
The market is closely linked to transceiver architecture. Data-center modules require low-power wideband TIAs with good sensitivity, while telecom and coherent systems may use more specialized receiver chains. Automotive and industrial LiDAR create a second growth path for fast-recovery TIAs that must handle large input pulses and wide dynamic range, expanding the technology beyond communications.
Segment Analysis: By Type
By type, the market is segmented by supported data rate from ≤1.25Gbps through ≥40Gbps. Lower-speed devices remain widely installed in access and sensing applications, but value growth is concentrated in 25-40Gbps and ≥40Gbps categories as optical modules increase lane rates. Device architecture becomes more demanding at each step because bandwidth, noise and power must improve simultaneously.
| Type | Commercial role |
|---|---|
| ≤1.25Gbps | Legacy optical access, sensing and lower-speed communication. |
| 1.25-10Gbps | Enterprise, access and installed telecom links. |
| 10-25Gbps | 25G-class optical lanes and intermediate-speed receiver applications. |
| 25-40Gbps | High-speed telecom and early 100G parallel receiver channels. |
| ≥40Gbps | 400G/800G-class receiver front ends and emerging higher-speed links. |
Additional Segmentation: By Technology
Semiconductor technology affects bandwidth, noise, power and integration. CMOS provides cost and integration advantages, SiGe/BiCMOS supports very high analog bandwidth with mature mixed-signal integration, and GaAs or InP remains relevant in premium ultra-high-speed front ends. The optimal technology depends on target lane rate, power budget, package and photodiode interface.
| Technology | Demand characteristics |
|---|---|
| CMOS | High integration and cost efficiency for optical and sensing receiver ICs. |
| SiGe / BiCMOS | Very high bandwidth with strong analog performance and mixed-signal integration. |
| GaAs / InP | Premium high-frequency implementations for demanding optical receivers. |
Segment Analysis: By Application
By application, telecommunications and data centers account for most demand, with other applications including LiDAR, instrumentation and optical sensing. Data centers are the fastest-moving technology segment because switch bandwidth doubles on rapid cycles. Telecom offers broader reach classes and longer product lifetimes, while LiDAR emphasizes overload recovery and dynamic range rather than only communications sensitivity.
| Application | Demand characteristics |
|---|---|
| Telecommunications | Access, metro, long-haul and mobile transport optical receivers. |
| Data Centers | High-speed Ethernet and InfiniBand receiver modules for cloud and AI. |
| Others | LiDAR, test and measurement, industrial sensing and specialized optical receivers. |
Additional Segmentation: By Integration Level
Integration level ranges from discrete TIAs to TIA-photodiode combinations and more complete receiver front ends. Closer integration reduces input capacitance and package parasitics, improving bandwidth and noise at lower power. Highly integrated optical engines also simplify module assembly but create tighter supplier qualification and thermal constraints. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Integration Level | Commercial relevance |
|---|---|
| Discrete TIA | Standalone receiver amplifier IC or die paired with an external photodiode. |
| TIA with Photodiode | Co-packaged receiver front end reducing parasitic capacitance. |
| Receiver Front-End / Optical Engine | Higher integration with detector arrays, limiting amplifiers or optical subassemblies. |
Regional Analysis
North America leads current market revenue with around 32% share in the underlying market evidence, while Asia Pacific is the fastest-growing region. Europe remains important in telecom and industrial sensing, and emerging regions expand through data-center and mobile-network investment. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Why does regional demand differ across the Trans Impedance Amplifier (TIA) market?
Regional demand reflects where optical modules are designed, assembled and deployed. North America leads hyperscale and semiconductor design, Asia Pacific combines module manufacturing with fast network growth, and Europe contributes telecom, industrial and automotive sensing. High-speed receiver supply is global, so customers also evaluate geographic manufacturing resilience. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Region | Position | Demand profile | Supplier-selection factor |
|---|---|---|---|
| North America | Largest | Hyperscale, telecom, semiconductor design | Early high-speed adoption |
| Asia Pacific | Fastest growth | Module manufacturing, telecom, cloud | Scale and supply chain |
| Europe | Strategic | Telecom, industrial, automotive | Reliability and qualification |
| South America | Emerging | Telecom and cloud | Network expansion |
| Middle East & Africa | Emerging | Data centers, telecom | Greenfield infrastructure |
Competitive Landscape
Texas Instruments, Analog Devices, Semtech, Qorvo, MACOM, Marvell, Renesas and HiLight Semiconductor are among the principal participants in the broader TIA market. Competition depends on bandwidth, noise, power, overload behavior, package format and customer qualification within optical-module platforms. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
The underlying market evidence identifies a concentrated leading group, while specialized vendors retain opportunities in high-speed optical and LiDAR niches. Device suppliers increasingly collaborate with photodiode and module companies because package parasitics strongly affect real-world receiver performance. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Integration is shifting competitive advantage from a standalone amplifier specification toward complete receiver performance. Vendors that can support co-packaged photodiodes, low-power front ends and high-volume optical packaging are well positioned for 800G and future modules. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Competitive tier | Representative companies | Primary differentiation |
|---|---|---|
| Large analog / mixed-signal suppliers | Texas Instruments, Analog Devices, Renesas | Broad analog portfolios and global customer support. |
| Optical / RF specialists | Semtech, Qorvo, MACOM, HiLight | High-speed receiver ICs and photonics expertise. |
| Networking silicon suppliers | Marvell and integrated optical ecosystems | System-level networking and optical interconnect integration. |
Key companies profiled
Texas Instruments, Analog Devices, Semtech, Qorvo, MACOM, Marvell, Renesas, HiLight Semiconductor and other analog or optical semiconductor suppliers are included in the competitive scope. Their positions differ by data rate, process technology, package and target optical architecture. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Production Capacity Analysis
TIA capacity depends on semiconductor wafer fabrication, analog design, wafer probe, packaging and high-frequency test. High-speed products require specialized process nodes and RF test capability, making effective capacity more constrained than simple analog IC output. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Optical-module qualification can be a larger bottleneck than wafer supply. Receiver front ends must be validated with specific photodiodes, packages, fibers and DSPs, and high-speed performance can change with small parasitic differences. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Dynamics
The market is driven by 5G, hyperscale data centers, optical-network upgrades and LiDAR. Growth is restrained by high-frequency design complexity, packaging parasitics and rapid price erosion. Co-packaged optics, integrated receiver front ends and lower-power ≥40Gbps TIAs offer the strongest opportunities. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Drivers
| Driver | Impact | Commercial mechanism |
|---|---|---|
| AI and cloud data centers | High | Higher switch bandwidth requires faster optical receivers. |
| 5G and telecom | High | Fiber transport and mobile infrastructure use large numbers of optical receivers. |
| LiDAR | Medium-High | Fast optical pulses require low-noise, fast-recovery TIAs. |
| Photonic integration | Medium | Closer detector-amplifier integration improves bandwidth and power. |
AI and cloud data centers
400G, 800G and emerging 1.6T links raise lane rates and therefore TIA bandwidth requirements. Each optical receive channel needs low-noise current-to-voltage conversion. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
5G and telecom
Network upgrades increase optical port count and speed, supporting TIA demand across access, metro and long-haul systems. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
LiDAR
Automotive and industrial ranging applications create demand for amplifiers that can recover quickly from large input currents while detecting weak returns. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Photonic integration
Reducing input capacitance and interconnect length can improve sensitivity and energy efficiency, creating value for co-packaged receiver designs. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Market Restraints
| Restraint | Impact | Commercial consequence |
|---|---|---|
| High-frequency design complexity | High | Bandwidth, gain and noise trade off directly. |
| Packaging parasitics | Medium-High | Bond wires and interconnect capacitance can limit real performance. |
| Price erosion | Medium | Mature optical generations become highly competitive. |
| Supply concentration | Medium | High-speed analog processes and specialized test are limited. |
High-frequency design complexity
At high data rates, designers must balance sensitivity against stability, power and process variation. This raises development cost and qualification effort. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Packaging parasitics
A strong die design can underperform if the optical package adds too much capacitance or inductance. Co-design with the module becomes essential. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Price erosion
As a data-rate generation scales, module and component prices decline. Suppliers must improve yield and integration to protect margins. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Supply concentration
Some products depend on foundry processes with fewer qualified alternatives, increasing supply-chain risk for optical customers. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Market Opportunities
800G and 1.6T receivers
Higher lane rates create premium opportunities for low-power wideband TIAs. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Co-packaged optics
Placing TIAs close to photodiodes and switch silicon can reduce electrical reach and power. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Automotive LiDAR
Fast-recovery TIAs can expand in high-resolution ranging and sensing systems. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Integrated optical engines
Multi-channel receiver front ends can capture more value than discrete amplifier die. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Supply Chain Analysis
Fabrication. TIAs are manufactured in CMOS, BiCMOS or compound-semiconductor processes selected for bandwidth and noise. Wafer probe screens DC and RF characteristics. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Packaging. High-speed die are assembled in packages or optical subassemblies with very short connections to photodiodes. Parasitic control is critical to preserve bandwidth. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Receiver integration. TIAs are combined with photodiodes, limiting amplifiers and optical elements and then tested for sensitivity, overload and bit-error performance. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Deployment. Finished receivers are integrated into transceivers, LiDAR modules and optical instruments. Qualification is closely linked to the final optical system. Commercial decisions in the Trans Impedance Amplifier (TIA) market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Recent Developments in the Trans Impedance Amplifier (TIA) Market
Developments tracked through September 2026 and limited to events that materially affect technology, capacity, adoption or competition.
- 2026 Current Portfolio
Analog Devices maintains a current TIA product category spanning precision and optical transimpedance amplifiers, including production devices for sensing and photodiode receiver applications. Source - 2026 LiDAR Receiver Portfolio
Analog Devices’ MAX40658/MAX40659 production TIAs provide 360MHz minimum bandwidth and fast overload recovery for automotive and industrial LiDAR receivers. Source - 2025–2026 High-Speed Architecture
High-speed optical receiver designs continue moving toward tighter TIA-photodiode integration as data-center modules increase lane rates and reduce allowable power per bit. Source
Report Scope & Segmentation
| Attribute | Scope |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| 2025 market size | USD 451.19 million |
| 2026 estimated size | USD 484.70 million |
| 2034 projected size | USD 859.77 million |
| CAGR (2026–2034) | 7.4% |
| Largest market in 2025 | North America |
| By Type | ≤1.25Gbps; 1.25-10Gbps; 10-25Gbps; 25-40Gbps; ≥40Gbps |
| By Application | Telecommunications; Data Centers; Others |
| By Technology | CMOS; SiGe/BiCMOS; GaAs/InP |
| By Integration Level | Discrete TIA; TIA with Photodiode; Receiver Front-End/Integrated Optical Engine |
| Companies profiled | Texas Instruments; Analog Devices; Semtech; Qorvo; MACOM; Marvell; Renesas; HiLight Semiconductor |
Frequently Asked Questions
What is the TIA market size in 2025?
The global trans impedance amplifier market is valued at USD 451.19 million in 2025.
What is the market forecast for 2034?
The market is projected to reach USD 859.77 million by 2034, representing a 7.4% CAGR during 2026–2034. The 2026 market level is USD 484.70 million.
Which region leads the market?
North America leads current revenue, while Asia Pacific has the fastest growth profile.
Which applications are largest?
Telecommunications and data centers are the principal applications, with LiDAR and sensing included in other uses.
Why are high-speed TIAs important?
They convert weak photodiode currents into low-noise voltage signals at the bandwidth required by modern optical links.
Which technologies are used?
CMOS, SiGe/BiCMOS and compound-semiconductor technologies such as GaAs or InP are used depending on bandwidth and integration needs.
Who are the major suppliers?
Texas Instruments, Analog Devices, Semtech, Qorvo, MACOM, Marvell and Renesas are important participants.
How does LiDAR affect demand?
LiDAR creates demand for fast-recovery TIAs with wide dynamic range and low noise.
What limits market growth?
High-frequency design complexity, packaging parasitics, price erosion and specialized process supply are the main restraints.
What will drive growth through 2034?
800G and 1.6T optical links, 5G, co-packaged optics and LiDAR will support expansion.
Research Sources & Evidence Base
View research sources used in this market overview
- Analog Devices — Transimpedance Amplifiers. Current portfolio and receiver-amplifier product evidence.
- Analog Devices — MAX40658. Production LiDAR TIA bandwidth, current-clamp and power evidence.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF