SEMICONDUCTOR INSIGHT
MARKET RESEARCH REPORT

Smart Card Market

2026 to 2034
MARKET INTELLIGENCE
ACROSS KEY REGIONS
2026 EDITION
EMBEDDED SYSTEMS Semiconductor Market Research

Smart Card Market

Size, Trends, Business Strategies 2026-2034

◷
UPDATED 28 September 2026
▤
REPORT LENGTH Detailed Report
▣
REPORT CODE b0d68711a744
▯
FORMATS PDF

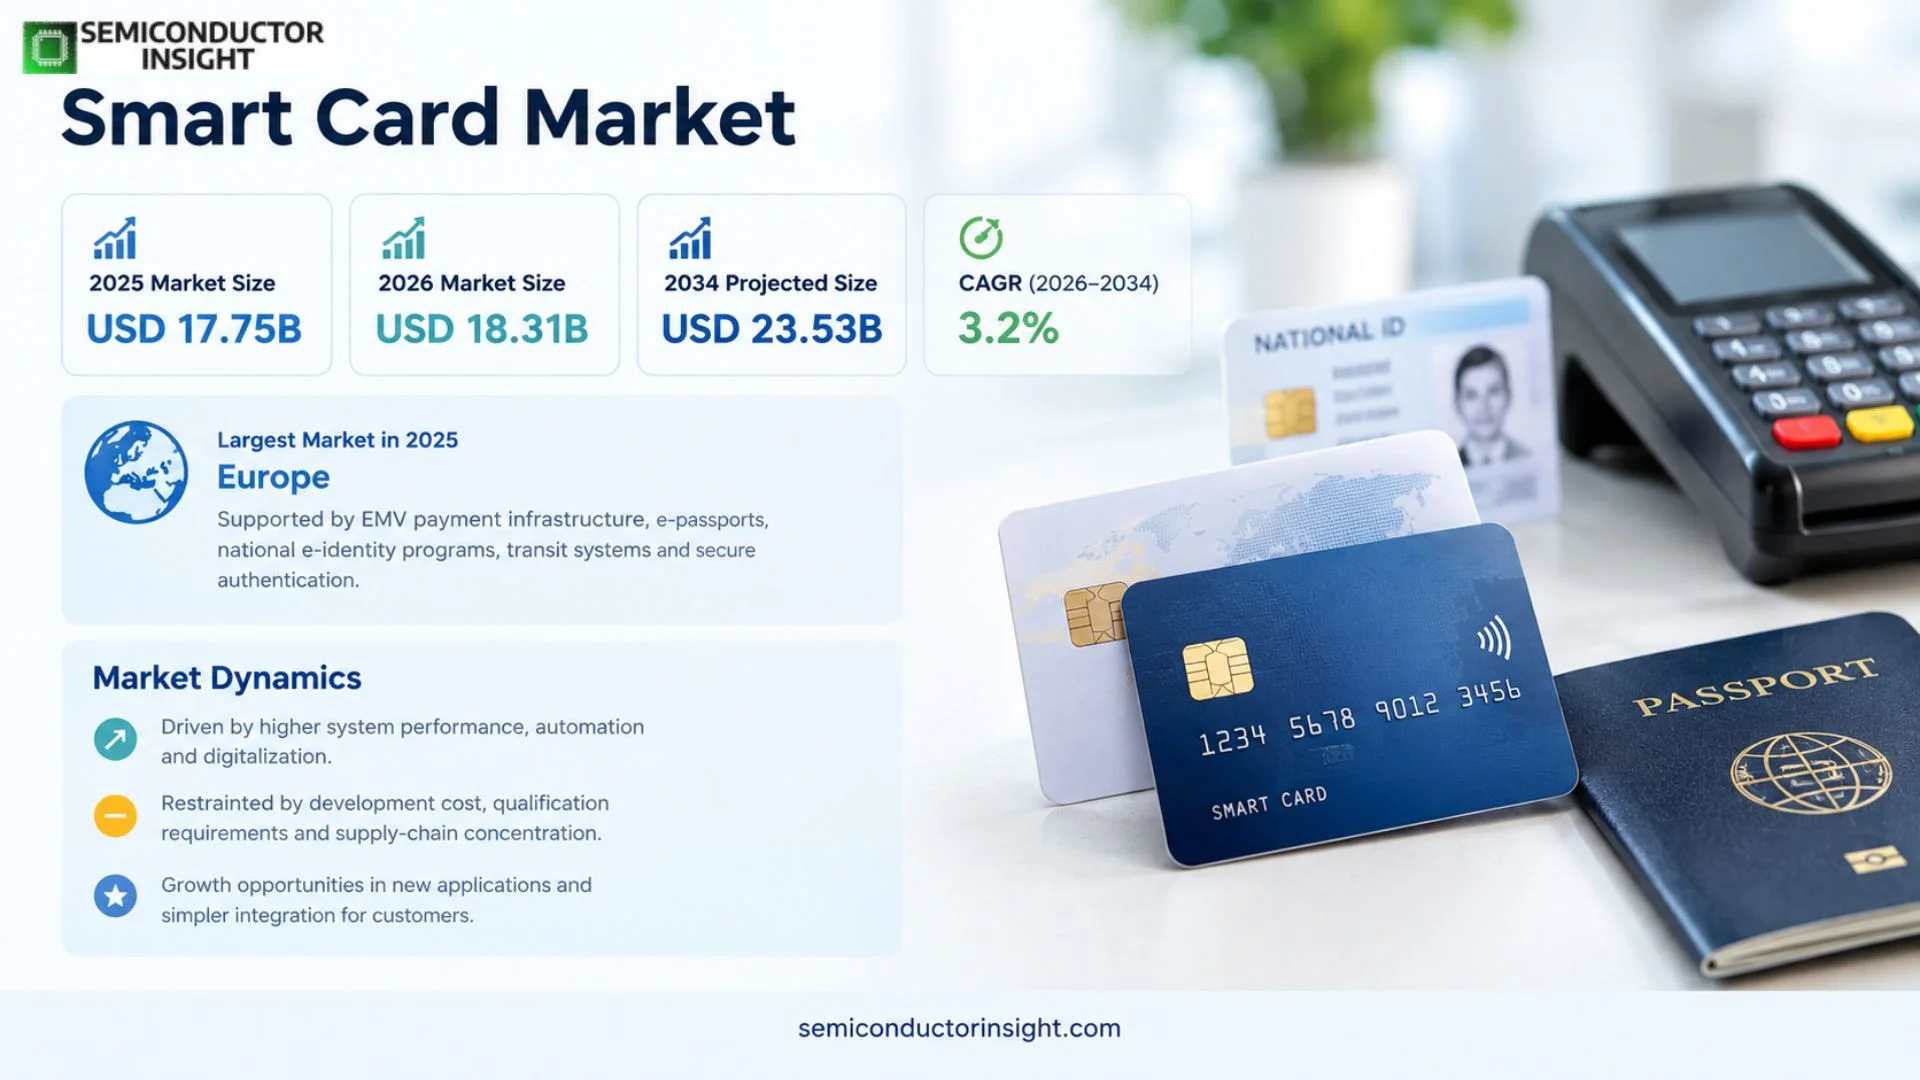
Smart Card Market is estimated at USD 18.31 billion in 2026. The market is projected to reach USD 23.53 billion by 2034, representing a CAGR of 3.2% during 2026–2034. Europe is the largest consumer market, supported by mature EMV payment infrastructure, national electronic-identity programs, e-passports, transit systems and widespread secure authentication.

Get the sample PDF with study scope, segmentation and methodology details.

Key Statistics

2025 Market Size
USD 17.75 billion
2026 Estimated Market Size
USD 18.31 billion
2034 Projected Market Size
USD 23.53 billion
CAGR (2026–2034)
3.2%

Key Takeaways

  • Market size and growth: the market is estimated at USD 18.31 billion in 2026 and is projected to reach USD 23.53 billion by 2034, representing a 3.2% CAGR during 2026–2034.
  • Contactless and dual-interface cards are the strongest technology trend because payment, transit and access-control systems increasingly prioritize tap speed, convenience and compatibility with NFC infrastructure.
  • Finance remains the largest application through EMV debit, credit and prepaid cards, while government identity, transportation and secure enterprise access provide long product cycles and recurring replacement demand.
  • Europe is the largest consumer market, while China is the largest production base in the underlying market scope, illustrating a supply chain where manufacturing and end-market leadership are geographically different.
  • EMV is effectively universal in card-present payments: EMVCo reported that 97% of global card-based transactions were EMV chip transactions as of Q4 2025, reinforcing the durable installed base for secure smart-card technology.

Smart Card Market Overview

Smart Card market was valued at USD 17.75 billion in 2025 and is estimated at USD 18.31 billion in 2026. The market is projected to reach USD 23.53 billion by 2034, representing a CAGR of 3.2% during 2026–2034. Europe is the largest consumer market, supported by mature EMV payment infrastructure, national electronic-identity programs, e-passports, transit systems and widespread secure authentication.

Base year: 2025 · Estimated year: 2026 · Forecast period: 2026–2034 · Values in USD million unless otherwise stated

Smart cards are portable secure devices that embed an integrated circuit inside a plastic, composite or metal card body. The chip can store credentials or execute cryptographic functions, allowing the card to authenticate a user, protect payment data or hold digital identity information. Contact cards communicate through physical terminals, contactless cards use radio-frequency interfaces, and dual-interface cards support both methods. Smart cards are deployed at large scale in banking, government identification, public transportation, telecommunications, healthcare and enterprise access control.

Payment remains the largest commercial use because EMV chip technology is deeply embedded in the global card ecosystem. EMVCo reported that 97% of card-based transactions worldwide were EMV chip transactions in the twelve-month period through Q4 2025. This installed base sustains card issuance and replacement, while contactless migration raises the value of dual-interface products. The market is therefore driven less by first-time EMV conversion in mature regions and more by replacement cycles, contactless upgrades, higher-security chips and new identity applications.

Government identity and transportation add long-duration demand that differs from banking. National ID cards, e-passports, driver credentials and healthcare cards typically use secure microprocessor chips and require rigorous personalization. Transit systems prioritize rapid contactless transactions and high card durability. Telecom SIM cards remain important even as eSIM adoption grows because many global mobile markets still issue physical SIMs at very large scale. These diverse use cases create a resilient market despite slow growth in mature payment-card volumes.

Segment Analysis: By Type

By type, the market is segmented into contact smart cards, contactless smart cards and dual-interface cards. Contactless and dual-interface products have the strongest momentum because they support faster transactions and broader acceptance in payment, transit and access-control systems. Contact cards remain important in government, telecom and legacy banking applications where installed readers or security procedures still rely on physical interfaces.

Type Technical / commercial role Market position
Contact Smart Card Physical-contact interface for payment, SIM, identity and secure authentication. Large installed base; mature replacement market.
Contactless Smart Card RF interface for tap payments, transit and access control. Fast adoption where transaction speed and convenience are primary.
Dual Interface Card Single secure chip supporting both contact and contactless communication. Strategic growth segment for payments and identity programs requiring compatibility with both infrastructures.

Segment Analysis: By Application

Applications include finance, transportation, government, communication, medical and other secure credential uses. Finance remains the largest because banks issue very large numbers of EMV debit and credit cards. Government programs create high-value multi-year contracts for identity and travel documents, while transit authorities use contactless cards for fare collection. Telecom demand remains substantial through SIM cards, although form-factor migration toward embedded SIM technologies changes the long-term mix.

Application Demand characteristics
Finance Largest application through EMV payment cards, debit, credit and prepaid programs.
Transportation Contactless fare cards and account-linked transit credentials require fast reliable transactions.
Government National ID, e-passports, driver credentials and social-security programs use secure microprocessor cards.
Communication Physical SIM cards remain a major installed application in global mobile markets.
Medical Patient identity, insurance and secure health-record access in selected systems.
Others Enterprise access, campus cards, loyalty, entertainment and specialty credentials.

Segment Analysis: By End User

End users include individual consumers, government institutions and enterprises. Individual consumers represent the largest installed base through payment, SIM and transit cards. Government institutions drive some of the highest-security projects because national identity and passport programs require secure chips, personalization and document lifecycle management. Enterprises use smart cards for physical access, logical authentication and employee identity, where integration with security software and credential-management systems is often more important than card unit cost.

End User Demand logic
Individual Consumers Largest installed base through banking, mobile, transit and access credentials.
Government Institutions High-security identity, passport, benefit and citizen-service programs.
Enterprises & Corporations Employee access, authentication and corporate identity systems.

Segment Analysis: By Technology

Technology segmentation separates simple memory-based cards from microprocessor-based secure cards. Memory cards store limited data and fit lower-complexity prepaid or identification uses. Microprocessor cards dominate high-security banking and government applications because they can execute cryptography, manage multiple applications and support stronger authentication. The market direction remains toward more capable secure elements as payment networks, identity issuers and enterprise security systems increase requirements for on-card processing and tamper resistance.

Technology Commercial role
Memory-based Cards Lower-complexity storage applications and selected prepaid use cases.
Microprocessor-based Cards Dominant high-security platform for banking, identity, SIM and multi-application credentials.

Smart Card Market Size & Share

Regional Analysis

Europe is the largest consumer market, supported by long-established EMV payments, government identity, e-passports and secure public-sector credentials. Asia Pacific is the largest production region, with China playing a major role in card manufacturing and a large domestic payments and telecom base. North America remains a major replacement market after EMV migration, while emerging regions continue to expand financial inclusion, national ID and contactless transportation systems.

Smart-card geography differs between manufacturing and consumption. Europe captures strong end-market value through secure payment and identity programs, while Asia Pacific has extensive card-body, chip-module and personalization capacity. North America has a large banking market and enterprise-security demand, while Latin America uses smart cards heavily in banking and government programs. Regional competition therefore depends on issuer relationships, security certification, personalization infrastructure and the ability to deliver millions of cards reliably under tight project schedules.

Region Position Growth outlook Demand profile Supplier-selection factor
Europe Largest consumer market Steady Payments, government ID, transit Security certification and lifecycle support
Asia Pacific Largest production base Moderate-High Payments, telecom, manufacturing Scale, cost and local issuance
North America Major replacement market Steady Payments and enterprise security EMV/contactless and personalization
South America Established growth Moderate Banking, ID and telecom Regional issuer relationships
Middle East & Africa Growth market Moderate-High Identity, payments and telecom Government programs and financial inclusion
EuropeLARGEST

What defines demand in Europe?

Europe is the largest consumer market because EMV payments, national electronic identity, e-passports and transit systems are deeply established. Issuers increasingly migrate toward contactless and dual-interface credentials rather than replacing secure cards with entirely different form factors. The region also hosts major suppliers such as Thales, IDEMIA and Giesecke+Devrient, giving it a strong combination of demand, security technology and personalization infrastructure.

PositionLargest consumer market
Demand basePayments + eID
Commercial focusSecurity and lifecycle
Key hubsFrance, Germany, UK
Country / subregion Role Demand logic
France Identity / payments Government and banking programs support high-security cards.
Germany Identity / enterprise eID, banking and secure access create long-cycle demand.
United Kingdom Payments Large contactless payment base supports dual-interface issuance.

Regional demand is shaped by the local concentration of customers, supplier service capability and the availability of qualified technical support. Companies that can shorten lead times, maintain local application engineering and support product changes during the customer lifecycle are better positioned to convert market growth into durable share. These factors matter most in technically demanding markets where a design change can affect validation, uptime or manufacturing yield.

Asia PacificPRODUCTION LEADER

What defines demand in Asia Pacific?

Asia Pacific is the largest production base and one of the fastest-growing demand regions. China has a major share of global card manufacturing, while India and Southeast Asia continue expanding banking, telecom and digital-identity programs. Japan and South Korea have mature secure-payment and transit systems. Regional manufacturers benefit from scale, lower production cost and proximity to chip-module and electronics supply chains.

PositionProduction leader
Demand basePayments + telecom + ID
Commercial focusScale and cost
Key hubsChina, India, Japan, Korea
Country / subregion Role Demand logic
China Largest production base Large manufacturing and domestic financial/telecom demand.
India Fast-growing issuance Payments, national identity and telecom create large card volumes.
Japan / Korea Mature contactless markets Transit and payments support high-value secure-card use.

Regional demand is shaped by the local concentration of customers, supplier service capability and the availability of qualified technical support. Companies that can shorten lead times, maintain local application engineering and support product changes during the customer lifecycle are better positioned to convert market growth into durable share. These factors matter most in technically demanding markets where a design change can affect validation, uptime or manufacturing yield.

North AmericaESTABLISHED

What defines demand in North America?

North America is a mature payment and enterprise-security market. The United States completed its major EMV migration later than Europe, creating a large installed base that now cycles through contactless and dual-interface replacements. Enterprise access, healthcare and government credentials add diversified demand. Card suppliers compete through personalization capacity, issuer relationships and rapid delivery because large financial institutions manage frequent card replacement and portfolio refresh programs.

PositionMajor mature market
Demand basePayments + enterprise
Commercial focusContactless replacement
Primary hubUnited States
Country / subregion Role Demand logic
United States Primary market Large payment-card and enterprise-security installed base.
Canada Mature contactless High contactless adoption supports ongoing card replacement.
Mexico Banking / telecom growth Financial inclusion and telecom create additional issuance.

Regional demand is shaped by the local concentration of customers, supplier service capability and the availability of qualified technical support. Companies that can shorten lead times, maintain local application engineering and support product changes during the customer lifecycle are better positioned to convert market growth into durable share. These factors matter most in technically demanding markets where a design change can affect validation, uptime or manufacturing yield.

South AmericaGROWTH MARKET

What defines demand in South America?

South America has an established smart-card market led by banking, telecom, government identity and transportation. Brazil is the largest regional opportunity and hosts both card issuance and supplier activity. Financial institutions continue modernizing contactless portfolios, while government and transit projects create high-volume tenders. Economic volatility can affect replacement timing, but secure card credentials remain embedded in critical payment and identity infrastructure.

PositionEstablished growth
Demand baseBanking + government
Commercial focusIssuer relationships
Primary hubBrazil
Country / subregion Role Demand logic
Brazil Largest regional market Banking, telecom and government programs support demand.
Argentina Payments / transit Contactless and secure ID create recurring demand.
Chile / Colombia Digital payments Banking modernization supports card upgrades.

Regional demand is shaped by the local concentration of customers, supplier service capability and the availability of qualified technical support. Companies that can shorten lead times, maintain local application engineering and support product changes during the customer lifecycle are better positioned to convert market growth into durable share. These factors matter most in technically demanding markets where a design change can affect validation, uptime or manufacturing yield.

Middle East & AfricaGROWTH MARKET

What defines demand in Middle East & Africa?

Middle East & Africa offers strong growth through national identity, banking expansion, telecom and public-sector digitalization. Gulf countries use high-security credentials for government and banking, while African markets expand chip-based payments and SIM issuance as financial inclusion improves. Suppliers with secure personalization, local partners and the ability to manage large government tenders are best positioned to capture regional growth.

PositionGrowth market
Demand baseID + payments + telecom
Commercial focusGovernment programs
Key hubsGulf, South Africa, Nigeria
Country / subregion Role Demand logic
Gulf states High-security ID Government identity and banking support premium cards.
South Africa Payments / banking Established financial infrastructure supports EMV replacement.
Nigeria / East Africa Financial inclusion Banking and telecom expansion drive secure-card issuance.

Regional demand is shaped by the local concentration of customers, supplier service capability and the availability of qualified technical support. Companies that can shorten lead times, maintain local application engineering and support product changes during the customer lifecycle are better positioned to convert market growth into durable share. These factors matter most in technically demanding markets where a design change can affect validation, uptime or manufacturing yield.

Competitive Landscape

Competition in the Smart Card market is shaped by technology performance, customer qualification, application engineering and continuity of supply. Leading companies use product breadth and global support to win large programs, while specialist suppliers can defend attractive niches through deeper technical performance in specific applications. As the market expands, customers increasingly evaluate total system value and lifecycle support rather than relying only on initial component price.

The leading suppliers compete through a combination of proprietary technology, manufacturing scale and customer relationships. In the Smart Card market, design wins can remain in place for several product generations because switching suppliers often requires requalification, software changes or manufacturing adjustments. This creates durable revenue positions for vendors that deliver reliable performance and responsive technical support.

Regional suppliers can still gain share where local availability, cost and fast engineering response matter. Their strongest opportunities are generally in standardized or mature applications, while the highest-performance segments remain concentrated among companies with deeper intellectual property, process control and qualification histories. This creates a market structure with both global platform leaders and specialized regional competitors.

Competitive strategy is increasingly moving toward integrated solutions. Customers prefer suppliers that can combine the core product with software, interface components, testing, support or adjacent technologies because integration reduces project risk and development time. Companies able to solve a broader customer problem therefore have more pricing power than vendors competing only on a single specification.

Competitive tier Representative companies Competitive basis
Global technology leaders Thales Group, IDEMIA, Giesecke+Devrient, CPI Card Group Scale, broad product portfolios, strong R&D and global customer support.
Established specialists Eastcompeace, Valid, Watchdata, Hengbao Application-specific engineering and strong qualification in selected segments.
Regional / emerging suppliers HID Global, Chutian Dragon, Kona I, Wuhan Tianyu, Inteligensa Local service, competitive pricing and focused customer relationships.

Key Participants

The profiled competitive set includes Thales Group, IDEMIA, Giesecke+Devrient, CPI Card Group, Eastcompeace, Valid, Watchdata, Hengbao, HID Global, Chutian Dragon, Kona I, Wuhan Tianyu, Inteligensa. Supplier position depends on engineering performance, customer qualification, manufacturing continuity and the ability to support design changes over long product cycles. Larger vendors benefit from broad portfolios and application teams, while specialists can retain strong positions in narrow, technically demanding subsegments where historical qualification and process know-how create meaningful switching costs.

Production Capacity Analysis

Production capacity for Smart Card is constrained by the combination of specialized equipment, qualified materials, process know-how and customer-specific validation. Nominal factory output can overstate commercial supply because a new line or material source must often demonstrate consistent performance before it can serve high-value customers. This makes qualified capacity more important than raw nameplate capacity.

Regional manufacturing and service capacity influence lead time and resilience. Customers increasingly prefer suppliers that can support major production clusters from more than one site, reducing exposure to logistics disruption and single-factory events. At the same time, duplicating specialized processes can be difficult because equipment recipes, trained engineers and quality systems must be transferred without changing product performance.

The strongest capacity investments are aligned with structural demand drivers rather than short-term cycles. Suppliers expanding around AI, advanced semiconductor manufacturing, automotive electronics or industrial automation seek to secure positions before customer volumes scale. Effective capacity therefore includes engineering resources, test capability and local technical support in addition to physical manufacturing equipment.

Capacity factor Market implication
Specialized manufacturing Determines qualified output and technical performance.
Critical materials / components Can constrain supply despite available factory floor space.
Qualification and test Controls how quickly new capacity becomes usable by customers.
Regional support Improves lead time, resilience and customer retention.

Market Dynamics

The Smart Card market is driven by higher system performance, automation, digitalization and expanding use in high-value applications. Growth is moderated by development cost, qualification requirements and supply-chain concentration. The strongest opportunities occur where new architectures or applications create a clear performance advantage and where suppliers can reduce integration complexity for customers.

MARKET DRIVERS

Driver Relative impact Commercial mechanism
Structural end-market growth High Expanding deployments increase unit demand and installed-base requirements.
Technology upgrade cycle High Higher performance raises value per product and accelerates replacement.
Customer integration needs Medium-High Validated solutions reduce engineering time and project risk.
Regional capacity expansion Medium New manufacturing clusters create local supplier demand.

Structural end-market expansion

Growth in the Smart Card market is supported by rising deployment across its principal applications. Customers are investing because the technology improves performance, efficiency, automation or product capability in ways that are difficult to replicate with older approaches. This expands both new-system demand and the installed base that later requires replacement, upgrades or related services.

Higher technical requirements increase value per system

New product generations demand tighter performance, greater integration and better reliability. These requirements can increase selling prices even when unit volumes grow more slowly, because customers are willing to pay for solutions that protect yield, uptime or user experience. Suppliers with stronger engineering capability therefore benefit disproportionately from technology transitions.

Regional investment broadens customer access

Manufacturing and infrastructure investment in North America, Europe and Asia is creating additional customer clusters outside traditional centers. Local engineering support and shorter supply chains help suppliers qualify products earlier in new projects, creating an opportunity to win design positions before production reaches full scale.

MARKET RESTRAINTS

Restraint Relative impact Commercial mechanism
Development and qualification cost High Raises barriers to entry and lengthens customer adoption.
Supply-chain concentration Medium-High Critical components or materials can limit output.
Price pressure Medium Customers seek lower total system cost as volumes increase.
Technology substitution Medium Alternative architectures can replace incumbent solutions in selected uses.

Qualification slows supplier switching

Customers in technical markets cannot change suppliers based only on purchase price. New products must demonstrate performance, reliability and compatibility in the actual application, which can require months of engineering work. This limits the pace at which new entrants gain share and can delay commercialization of technically promising products.

Specialized inputs can constrain supply

Advanced products depend on a limited number of qualified materials, components or manufacturing tools. Shortages or long lead times at one upstream stage can restrict finished-product output even when downstream assembly capacity is available. Suppliers therefore carry strategic inventory or qualify alternate sources, but those actions increase cost.

Customer cost pressure remains persistent

As a technology becomes more widely adopted, customers expect lower unit costs and may redesign systems to use standardized components. Suppliers must offset this pressure through better performance, lower manufacturing cost and additional software or service value. Vendors that cannot maintain differentiation can face margin erosion even in a growing market.

MARKET OPPORTUNITIES

Dual-interface replacement cycle

Large payment-card portfolios are steadily replacing older contact-only cards with dual-interface products that preserve chip-and-PIN compatibility while enabling tap transactions. This creates a recurring upgrade opportunity even in mature markets where total card counts are stable. Suppliers that combine secure chips, antenna modules, personalization and sustainable card bodies can increase value per issued card.

Government digital identity

National eID, residence, health and travel credentials require long-term secure issuance and personalization infrastructure. Many programs combine physical smart cards with mobile or online identity services rather than eliminating the card. Vendors that provide both secure documents and digital-identity platforms can capture larger multi-year government contracts.

Sustainable card materials

Banks and governments are seeking lower-impact card bodies made from recycled PVC, bio-sourced materials or alternative substrates. Security and durability cannot be compromised, so certified sustainable materials create a premium niche rather than a simple packaging substitution. Large issuers can reduce portfolio emissions when sustainable materials are deployed across millions of replacement cards.

Multi-application secure credentials

Microprocessor cards can support payment, access, identity and loyalty functions on one credential. Universities, corporations and public agencies can reduce the number of physical credentials while maintaining strong cryptographic authentication. The opportunity is strongest where the issuer controls both the card lifecycle and the digital services linked to it.

Supply Chain Analysis

Stage 1
Specialized materials and components
Stage 2
Core product manufacturing
Stage 3
Qualification and system integration
Stage 4
End-user deployment, service and replacement

The upstream supply chain provides the specialized materials, semiconductor devices, mechanical components or substrates that determine baseline product performance. Qualified inputs are important because changes in composition or manufacturing source can alter reliability, electrical behavior or process compatibility. Suppliers therefore maintain close technical relationships with upstream partners and often approve alternate sources before a disruption occurs.

Manufacturing converts these inputs into finished products using process-specific equipment, inspection and test. Quality systems are central because customers expect lot-to-lot consistency and traceability, particularly in semiconductor, automotive and industrial applications. High-value suppliers differentiate through process control rather than simple assembly scale, and they invest heavily in metrology or validation to protect yield.

Downstream value is created when the product is integrated into the customer system and validated under real operating conditions. Application engineers support installation, software, calibration or process optimization, while service teams maintain the installed base. This lifecycle relationship creates recurring revenue through replacement, updates, refurbishment or expansion and makes customer support an important part of the market structure.

Recent Developments

Q4 2025 – EMVCo reports 97% of global card-based transactions are EMV chip

EMVCo’s worldwide deployment statistics show that EMV chip is now used in 97% of global card-based transactions, confirming the depth of the secure-chip installed base that underpins payment-card replacement and contactless upgrades. Source

2026 – Contactless and dual-interface migration continues across payment portfolios

Issuers continue replacing older contact-only cards with contactless or dual-interface products to improve user experience while preserving EMV security and terminal compatibility. Source

2026 – Smart-card suppliers expand multi-application secure credentials

Leading identity and payment suppliers continue integrating payment, identity, access and digital-service functions into secure chip credentials, increasing value per issued card in government and enterprise programs. Source

REPORT SCOPE & SEGMENTATION

Base Year 2025
Estimated Year 2026
Forecast Year 2034
2025 Market Size USD 17.75 billion
2026 Market Size USD 18.31 billion
2034 Market Size USD 23.53 billion
CAGR 3.2% during 2026–2034
Largest Market / Leading Geography Europe
By Type Contact Smart Card; Contactless Smart Card; Dual Interface Card
By Application Finance; Transportation; Government; Communication; Medical; Others
By End User Enterprises & Corporations; Government Institutions; Individual Consumers
By Technology Memory-based Cards; Microprocessor-based Cards

Frequently Asked Questions

What is the size of the smart card market?

The market is estimated at USD 18.31 billion in 2026 and is projected to reach USD 23.53 billion by 2034, representing a 3.2% CAGR during 2026–2034. The 2025 market size is USD 17.75 billion.

Which smart-card type is growing fastest?

Contactless and dual-interface cards have the strongest momentum because payments, transit and access systems increasingly require fast tap transactions while retaining secure chip functionality.

Which application is largest?

Finance is the largest application through EMV debit, credit and prepaid cards, while government identity and transportation remain important high-security markets.

Which region leads the market?

Europe is the largest consumer market, while Asia Pacific has the largest production base and strong growth in payments, telecom and digital-identity programs.

How widespread is EMV chip technology?

EMVCo reported that 97% of global card-based transactions were EMV chip transactions in the twelve months through Q4 2025.

What are the main market constraints?

Mature payment-card volumes, eSIM migration, mobile wallets, card-replacement pricing pressure and long government procurement cycles can restrain growth.

Research Sources & Evidence Base
View research sources used for this overview
  1. EMVCo. Worldwide EMV Deployment Statistics, Q4 2025 global chip-transaction penetration.
  2. EMVCo. EMV Contact Chip, global payment-chip technology and security context.
  3. Thales. Digital Identity and Security – Banking & Payment, secure payment and smart-card product context.
Smart Card Market, Size, Trends, Business Strategies 2026-2034

Get Sample Report PDF for Exclusive Insights

Report Sample Includes

  • Table of Contents
  • List of Tables & Figures
  • Charts, Research Methodology, and more...

PDF Icon Download Sample Report PDF

Download Sample Report

Table of Content

1 Introduction to Research & Analysis Reports
1.1 Smart Card Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Smart Card Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Smart Card Overall Market Size
2.1 Global Smart Card Market Size: 2024 VS 2032
2.2 Global Smart Card Market Size, Prospects & Forecasts: 2020-2032
2.3 Global Smart Card Sales: 2020-2032
3 Company Landscape
3.1 Top Smart Card Players in Global Market
3.2 Top Global Smart Card Companies Ranked by Revenue
3.3 Global Smart Card Revenue by Companies
3.4 Global Smart Card Sales by Companies
3.5 Global Smart Card Price by Manufacturer (2020-2025)
3.6 Top 3 and Top 5 Smart Card Companies in Global Market, by Revenue in 2024
3.7 Global Manufacturers Smart Card Product Type
3.8 Tier 1, Tier 2, and Tier 3 Smart Card Players in Global Market
3.8.1 List of Global Tier 1 Smart Card Companies
3.8.2 List of Global Tier 2 and Tier 3 Smart Card Companies
4 Sights by Product
4.1 Overview
4.1.1 Segment by Type – Global Smart Card Market Size Markets, 2024 & 2032
4.1.2 Contact Smart Card
4.1.3 Contactless Smart Card
4.1.4 Dual Interface Card
4.2 Segment by Type – Global Smart Card Revenue & Forecasts
4.2.1 Segment by Type – Global Smart Card Revenue, 2020-2025
4.2.2 Segment by Type – Global Smart Card Revenue, 2026-2032
4.2.3 Segment by Type – Global Smart Card Revenue Market Share, 2020-2032
4.3 Segment by Type – Global Smart Card Sales & Forecasts
4.3.1 Segment by Type – Global Smart Card Sales, 2020-2025
4.3.2 Segment by Type – Global Smart Card Sales, 2026-2032
4.3.3 Segment by Type – Global Smart Card Sales Market Share, 2020-2032
4.4 Segment by Type – Global Smart Card Price (Manufacturers Selling Prices), 2020-2032
5 Sights by Application
5.1 Overview
5.1.1 Segment by Application – Global Smart Card Market Size, 2024 & 2032
5.1.2 Communication
5.1.3 Finance
5.1.4 Transportation
5.1.5 Government
5.1.6 Medical
5.1.7 Others
5.2 Segment by Application – Global Smart Card Revenue & Forecasts
5.2.1 Segment by Application – Global Smart Card Revenue, 2020-2025
5.2.2 Segment by Application – Global Smart Card Revenue, 2026-2032
5.2.3 Segment by Application – Global Smart Card Revenue Market Share, 2020-2032
5.3 Segment by Application – Global Smart Card Sales & Forecasts
5.3.1 Segment by Application – Global Smart Card Sales, 2020-2025
5.3.2 Segment by Application – Global Smart Card Sales, 2026-2032
5.3.3 Segment by Application – Global Smart Card Sales Market Share, 2020-2032
5.4 Segment by Application – Global Smart Card Price (Manufacturers Selling Prices), 2020-2032
6 Sights by Region
6.1 By Region – Global Smart Card Market Size, 2024 & 2032
6.2 By Region – Global Smart Card Revenue & Forecasts
6.2.1 By Region – Global Smart Card Revenue, 2020-2025
6.2.2 By Region – Global Smart Card Revenue, 2026-2032
6.2.3 By Region – Global Smart Card Revenue Market Share, 2020-2032
6.3 By Region – Global Smart Card Sales & Forecasts
6.3.1 By Region – Global Smart Card Sales, 2020-2025
6.3.2 By Region – Global Smart Card Sales, 2026-2032
6.3.3 By Region – Global Smart Card Sales Market Share, 2020-2032
6.4 North America
6.4.1 By Country – North America Smart Card Revenue, 2020-2032
6.4.2 By Country – North America Smart Card Sales, 2020-2032
6.4.3 United States Smart Card Market Size, 2020-2032
6.4.4 Canada Smart Card Market Size, 2020-2032
6.4.5 Mexico Smart Card Market Size, 2020-2032
6.5 Europe
6.5.1 By Country – Europe Smart Card Revenue, 2020-2032
6.5.2 By Country – Europe Smart Card Sales, 2020-2032
6.5.3 Germany Smart Card Market Size, 2020-2032
6.5.4 France Smart Card Market Size, 2020-2032
6.5.5 U.K. Smart Card Market Size, 2020-2032
6.5.6 Italy Smart Card Market Size, 2020-2032
6.5.7 Russia Smart Card Market Size, 2020-2032
6.5.8 Nordic Countries Smart Card Market Size, 2020-2032
6.5.9 Benelux Smart Card Market Size, 2020-2032
6.6 Asia
6.6.1 By Region – Asia Smart Card Revenue, 2020-2032
6.6.2 By Region – Asia Smart Card Sales, 2020-2032
6.6.3 China Smart Card Market Size, 2020-2032
6.6.4 Japan Smart Card Market Size, 2020-2032
6.6.5 South Korea Smart Card Market Size, 2020-2032
6.6.6 Southeast Asia Smart Card Market Size, 2020-2032
6.6.7 India Smart Card Market Size, 2020-2032
6.7 South America
6.7.1 By Country – South America Smart Card Revenue, 2020-2032
6.7.2 By Country – South America Smart Card Sales, 2020-2032
6.7.3 Brazil Smart Card Market Size, 2020-2032
6.7.4 Argentina Smart Card Market Size, 2020-2032
6.8 Middle East & Africa
6.8.1 By Country – Middle East & Africa Smart Card Revenue, 2020-2032
6.8.2 By Country – Middle East & Africa Smart Card Sales, 2020-2032
6.8.3 Turkey Smart Card Market Size, 2020-2032
6.8.4 Israel Smart Card Market Size, 2020-2032
6.8.5 Saudi Arabia Smart Card Market Size, 2020-2032
6.8.6 UAE Smart Card Market Size, 2020-2032
7 Manufacturers & Brands Profiles
7.1 Thales Group
7.1.1 Thales Group Company Summary
7.1.2 Thales Group Business Overview
7.1.3 Thales Group Smart Card Major Product Offerings
7.1.4 Thales Group Smart Card Sales and Revenue in Global (2020-2025)
7.1.5 Thales Group Key News & Latest Developments
7.2 IDEMIA
7.2.1 IDEMIA Company Summary
7.2.2 IDEMIA Business Overview
7.2.3 IDEMIA Smart Card Major Product Offerings
7.2.4 IDEMIA Smart Card Sales and Revenue in Global (2020-2025)
7.2.5 IDEMIA Key News & Latest Developments
7.3 Giesecke & Devrient
7.3.1 Giesecke & Devrient Company Summary
7.3.2 Giesecke & Devrient Business Overview
7.3.3 Giesecke & Devrient Smart Card Major Product Offerings
7.3.4 Giesecke & Devrient Smart Card Sales and Revenue in Global (2020-2025)
7.3.5 Giesecke & Devrient Key News & Latest Developments
7.4 CPI Card Group
7.4.1 CPI Card Group Company Summary
7.4.2 CPI Card Group Business Overview
7.4.3 CPI Card Group Smart Card Major Product Offerings
7.4.4 CPI Card Group Smart Card Sales and Revenue in Global (2020-2025)
7.4.5 CPI Card Group Key News & Latest Developments
7.5 Eastcompeace
7.5.1 Eastcompeace Company Summary
7.5.2 Eastcompeace Business Overview
7.5.3 Eastcompeace Smart Card Major Product Offerings
7.5.4 Eastcompeace Smart Card Sales and Revenue in Global (2020-2025)
7.5.5 Eastcompeace Key News & Latest Developments
7.6 Valid
7.6.1 Valid Company Summary
7.6.2 Valid Business Overview
7.6.3 Valid Smart Card Major Product Offerings
7.6.4 Valid Smart Card Sales and Revenue in Global (2020-2025)
7.6.5 Valid Key News & Latest Developments
7.7 Watchdata
7.7.1 Watchdata Company Summary
7.7.2 Watchdata Business Overview
7.7.3 Watchdata Smart Card Major Product Offerings
7.7.4 Watchdata Smart Card Sales and Revenue in Global (2020-2025)
7.7.5 Watchdata Key News & Latest Developments
7.8 Hengbao
7.8.1 Hengbao Company Summary
7.8.2 Hengbao Business Overview
7.8.3 Hengbao Smart Card Major Product Offerings
7.8.4 Hengbao Smart Card Sales and Revenue in Global (2020-2025)
7.8.5 Hengbao Key News & Latest Developments
7.9 HID Global
7.9.1 HID Global Company Summary
7.9.2 HID Global Business Overview
7.9.3 HID Global Smart Card Major Product Offerings
7.9.4 HID Global Smart Card Sales and Revenue in Global (2020-2025)
7.9.5 HID Global Key News & Latest Developments
7.10 Chutian Dragon
7.10.1 Chutian Dragon Company Summary
7.10.2 Chutian Dragon Business Overview
7.10.3 Chutian Dragon Smart Card Major Product Offerings
7.10.4 Chutian Dragon Smart Card Sales and Revenue in Global (2020-2025)
7.10.5 Chutian Dragon Key News & Latest Developments
7.11 Kona I
7.11.1 Kona I Company Summary
7.11.2 Kona I Business Overview
7.11.3 Kona I Smart Card Major Product Offerings
7.11.4 Kona I Smart Card Sales and Revenue in Global (2020-2025)
7.11.5 Kona I Key News & Latest Developments
7.12 Wuhan Tianyu
7.12.1 Wuhan Tianyu Company Summary
7.12.2 Wuhan Tianyu Business Overview
7.12.3 Wuhan Tianyu Smart Card Major Product Offerings
7.12.4 Wuhan Tianyu Smart Card Sales and Revenue in Global (2020-2025)
7.12.5 Wuhan Tianyu Key News & Latest Developments
7.13 Inteligensa
7.13.1 Inteligensa Company Summary
7.13.2 Inteligensa Business Overview
7.13.3 Inteligensa Smart Card Major Product Offerings
7.13.4 Inteligensa Smart Card Sales and Revenue in Global (2020-2025)
7.13.5 Inteligensa Key News & Latest Developments
8 Global Smart Card Production Capacity, Analysis
8.1 Global Smart Card Production Capacity, 2020-2032
8.2 Smart Card Production Capacity of Key Manufacturers in Global Market
8.3 Global Smart Card Production by Region
9 Key Market Trends, Opportunity, Drivers and Restraints
9.1 Market Opportunities & Trends
9.2 Market Drivers
9.3 Market Restraints
10 Smart Card Supply Chain Analysis
10.1 Smart Card Industry Value Chain
10.2 Smart Card Upstream Market
10.3 Smart Card Downstream and Clients
10.4 Marketing Channels Analysis
10.4.1 Marketing Channels
10.4.2 Smart Card Distributors and Sales Agents in Global
11 Conclusion
12 Appendix
12.1 Note
12.2 Examples of Clients
12.3 DisclaimerList of Tables
Table 1. Key Players of Smart Card in Global Market
Table 2. Top Smart Card Players in Global Market, Ranking by Revenue (2024)
Table 3. Global Smart Card Revenue by Companies, (US$, Mn), 2020-2025
Table 4. Global Smart Card Revenue Share by Companies, 2020-2025
Table 5. Global Smart Card Sales by Companies, (B Units), 2020-2025
Table 6. Global Smart Card Sales Share by Companies, 2020-2025
Table 7. Key Manufacturers Smart Card Price (2020-2025) & (USD/K Units)
Table 8. Global Manufacturers Smart Card Product Type
Table 9. List of Global Tier 1 Smart Card Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Smart Card Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segment by Type – Global Smart Card Revenue, (US$, Mn), 2024 & 2032
Table 12. Segment by Type – Global Smart Card Revenue (US$, Mn), 2020-2025
Table 13. Segment by Type – Global Smart Card Revenue (US$, Mn), 2026-2032
Table 14. Segment by Type – Global Smart Card Sales (B Units), 2020-2025
Table 15. Segment by Type – Global Smart Card Sales (B Units), 2026-2032
Table 16. Segment by Application – Global Smart Card Revenue, (US$, Mn), 2024 & 2032
Table 17. Segment by Application – Global Smart Card Revenue, (US$, Mn), 2020-2025
Table 18. Segment by Application – Global Smart Card Revenue, (US$, Mn), 2026-2032
Table 19. Segment by Application – Global Smart Card Sales, (B Units), 2020-2025
Table 20. Segment by Application – Global Smart Card Sales, (B Units), 2026-2032
Table 21. By Region – Global Smart Card Revenue, (US$, Mn), 2025-2032
Table 22. By Region – Global Smart Card Revenue, (US$, Mn), 2020-2025
Table 23. By Region – Global Smart Card Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Global Smart Card Sales, (B Units), 2020-2025
Table 25. By Region – Global Smart Card Sales, (B Units), 2026-2032
Table 26. By Country – North America Smart Card Revenue, (US$, Mn), 2020-2025
Table 27. By Country – North America Smart Card Revenue, (US$, Mn), 2026-2032
Table 28. By Country – North America Smart Card Sales, (B Units), 2020-2025
Table 29. By Country – North America Smart Card Sales, (B Units), 2026-2032
Table 30. By Country – Europe Smart Card Revenue, (US$, Mn), 2020-2025
Table 31. By Country – Europe Smart Card Revenue, (US$, Mn), 2026-2032
Table 32. By Country – Europe Smart Card Sales, (B Units), 2020-2025
Table 33. By Country – Europe Smart Card Sales, (B Units), 2026-2032
Table 34. By Region – Asia Smart Card Revenue, (US$, Mn), 2020-2025
Table 35. By Region – Asia Smart Card Revenue, (US$, Mn), 2026-2032
Table 36. By Region – Asia Smart Card Sales, (B Units), 2020-2025
Table 37. By Region – Asia Smart Card Sales, (B Units), 2026-2032
Table 38. By Country – South America Smart Card Revenue, (US$, Mn), 2020-2025
Table 39. By Country – South America Smart Card Revenue, (US$, Mn), 2026-2032
Table 40. By Country – South America Smart Card Sales, (B Units), 2020-2025
Table 41. By Country – South America Smart Card Sales, (B Units), 2026-2032
Table 42. By Country – Middle East & Africa Smart Card Revenue, (US$, Mn), 2020-2025
Table 43. By Country – Middle East & Africa Smart Card Revenue, (US$, Mn), 2026-2032
Table 44. By Country – Middle East & Africa Smart Card Sales, (B Units), 2020-2025
Table 45. By Country – Middle East & Africa Smart Card Sales, (B Units), 2026-2032
Table 46. Thales Group Company Summary
Table 47. Thales Group Smart Card Product Offerings
Table 48. Thales Group Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 49. Thales Group Key News & Latest Developments
Table 50. IDEMIA Company Summary
Table 51. IDEMIA Smart Card Product Offerings
Table 52. IDEMIA Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 53. IDEMIA Key News & Latest Developments
Table 54. Giesecke & Devrient Company Summary
Table 55. Giesecke & Devrient Smart Card Product Offerings
Table 56. Giesecke & Devrient Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 57. Giesecke & Devrient Key News & Latest Developments
Table 58. CPI Card Group Company Summary
Table 59. CPI Card Group Smart Card Product Offerings
Table 60. CPI Card Group Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 61. CPI Card Group Key News & Latest Developments
Table 62. Eastcompeace Company Summary
Table 63. Eastcompeace Smart Card Product Offerings
Table 64. Eastcompeace Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 65. Eastcompeace Key News & Latest Developments
Table 66. Valid Company Summary
Table 67. Valid Smart Card Product Offerings
Table 68. Valid Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 69. Valid Key News & Latest Developments
Table 70. Watchdata Company Summary
Table 71. Watchdata Smart Card Product Offerings
Table 72. Watchdata Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 73. Watchdata Key News & Latest Developments
Table 74. Hengbao Company Summary
Table 75. Hengbao Smart Card Product Offerings
Table 76. Hengbao Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 77. Hengbao Key News & Latest Developments
Table 78. HID Global Company Summary
Table 79. HID Global Smart Card Product Offerings
Table 80. HID Global Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 81. HID Global Key News & Latest Developments
Table 82. Chutian Dragon Company Summary
Table 83. Chutian Dragon Smart Card Product Offerings
Table 84. Chutian Dragon Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 85. Chutian Dragon Key News & Latest Developments
Table 86. Kona I Company Summary
Table 87. Kona I Smart Card Product Offerings
Table 88. Kona I Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 89. Kona I Key News & Latest Developments
Table 90. Wuhan Tianyu Company Summary
Table 91. Wuhan Tianyu Smart Card Product Offerings
Table 92. Wuhan Tianyu Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 93. Wuhan Tianyu Key News & Latest Developments
Table 94. Inteligensa Company Summary
Table 95. Inteligensa Smart Card Product Offerings
Table 96. Inteligensa Smart Card Sales (B Units), Revenue (US$, Mn) and Average Price (USD/K Units) & (2020-2025)
Table 97. Inteligensa Key News & Latest Developments
Table 98. Smart Card Capacity of Key Manufacturers in Global Market, 2023-2025 (B Units)
Table 99. Global Smart Card Capacity Market Share of Key Manufacturers, 2023-2025
Table 100. Global Smart Card Production by Region, 2020-2025 (B Units)
Table 101. Global Smart Card Production by Region, 2026-2032 (B Units)
Table 102. Smart Card Market Opportunities & Trends in Global Market
Table 103. Smart Card Market Drivers in Global Market
Table 104. Smart Card Market Restraints in Global Market
Table 105. Smart Card Raw Materials
Table 106. Smart Card Raw Materials Suppliers in Global Market
Table 107. Typical Smart Card Downstream
Table 108. Smart Card Downstream Clients in Global Market
Table 109. Smart Card Distributors and Sales Agents in Global Market

List of Figures
Figure 1. Smart Card Product Picture
Figure 2. Smart Card Segment by Type in 2024
Figure 3. Smart Card Segment by Application in 2024
Figure 4. Global Smart Card Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Smart Card Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Smart Card Revenue: 2020-2032 (US$, Mn)
Figure 8. Smart Card Sales in Global Market: 2020-2032 (B Units)
Figure 9. The Top 3 and 5 Players Market Share by Smart Card Revenue in 2024
Figure 10. Segment by Type – Global Smart Card Revenue, (US$, Mn), 2024 & 2032
Figure 11. Segment by Type – Global Smart Card Revenue Market Share, 2020-2032
Figure 12. Segment by Type – Global Smart Card Sales Market Share, 2020-2032
Figure 13. Segment by Type – Global Smart Card Price (USD/K Units), 2020-2032
Figure 14. Segment by Application – Global Smart Card Revenue, (US$, Mn), 2024 & 2032
Figure 15. Segment by Application – Global Smart Card Revenue Market Share, 2020-2032
Figure 16. Segment by Application – Global Smart Card Sales Market Share, 2020-2032
Figure 17. Segment by Application -Global Smart Card Price (USD/K Units), 2020-2032
Figure 18. By Region – Global Smart Card Revenue, (US$, Mn), 2025 & 2032
Figure 19. By Region – Global Smart Card Revenue Market Share, 2020 VS 2024 VS 2032
Figure 20. By Region – Global Smart Card Revenue Market Share, 2020-2032
Figure 21. By Region – Global Smart Card Sales Market Share, 2020-2032
Figure 22. By Country – North America Smart Card Revenue Market Share, 2020-2032
Figure 23. By Country – North America Smart Card Sales Market Share, 2020-2032
Figure 24. United States Smart Card Revenue, (US$, Mn), 2020-2032
Figure 25. Canada Smart Card Revenue, (US$, Mn), 2020-2032
Figure 26. Mexico Smart Card Revenue, (US$, Mn), 2020-2032
Figure 27. By Country – Europe Smart Card Revenue Market Share, 2020-2032
Figure 28. By Country – Europe Smart Card Sales Market Share, 2020-2032
Figure 29. Germany Smart Card Revenue, (US$, Mn), 2020-2032
Figure 30. France Smart Card Revenue, (US$, Mn), 2020-2032
Figure 31. U.K. Smart Card Revenue, (US$, Mn), 2020-2032
Figure 32. Italy Smart Card Revenue, (US$, Mn), 2020-2032
Figure 33. Russia Smart Card Revenue, (US$, Mn), 2020-2032
Figure 34. Nordic Countries Smart Card Revenue, (US$, Mn), 2020-2032
Figure 35. Benelux Smart Card Revenue, (US$, Mn), 2020-2032
Figure 36. By Region – Asia Smart Card Revenue Market Share, 2020-2032
Figure 37. By Region – Asia Smart Card Sales Market Share, 2020-2032
Figure 38. China Smart Card Revenue, (US$, Mn), 2020-2032
Figure 39. Japan Smart Card Revenue, (US$, Mn), 2020-2032
Figure 40. South Korea Smart Card Revenue, (US$, Mn), 2020-2032
Figure 41. Southeast Asia Smart Card Revenue, (US$, Mn), 2020-2032
Figure 42. India Smart Card Revenue, (US$, Mn), 2020-2032
Figure 43. By Country – South America Smart Card Revenue Market Share, 2020-2032
Figure 44. By Country – South America Smart Card Sales, Market Share, 2020-2032
Figure 45. Brazil Smart Card Revenue, (US$, Mn), 2020-2032
Figure 46. Argentina Smart Card Revenue, (US$, Mn), 2020-2032
Figure 47. By Country – Middle East & Africa Smart Card Revenue, Market Share, 2020-2032
Figure 48. By Country – Middle East & Africa Smart Card Sales, Market Share, 2020-2032
Figure 49. Turkey Smart Card Revenue, (US$, Mn), 2020-2032
Figure 50. Israel Smart Card Revenue, (US$, Mn), 2020-2032
Figure 51. Saudi Arabia Smart Card Revenue, (US$, Mn), 2020-2032
Figure 52. UAE Smart Card Revenue, (US$, Mn), 2020-2032
Figure 53. Global Smart Card Production Capacity (B Units), 2020-2032
Figure 54. The Percentage of Production Smart Card by Region, 2024 VS 2032
Figure 55. Smart Card Industry Value Chain
Figure 56. Marketing Channels