1 Introduction to Research & Analysis Reports
1.1 Semiconductor Fine Ceramics Market Definition
1.2 Market Segments
1.2.1 Segment by Type
1.2.2 Segment by Application
1.3 Global Semiconductor Fine Ceramics Market Overview
1.4 Features & Benefits of This Report
1.5 Methodology & Sources of Information
1.5.1 Research Methodology
1.5.2 Research Process
1.5.3 Base Year
1.5.4 Report Assumptions & Caveats
2 Global Semiconductor Fine Ceramics Overall Market Size
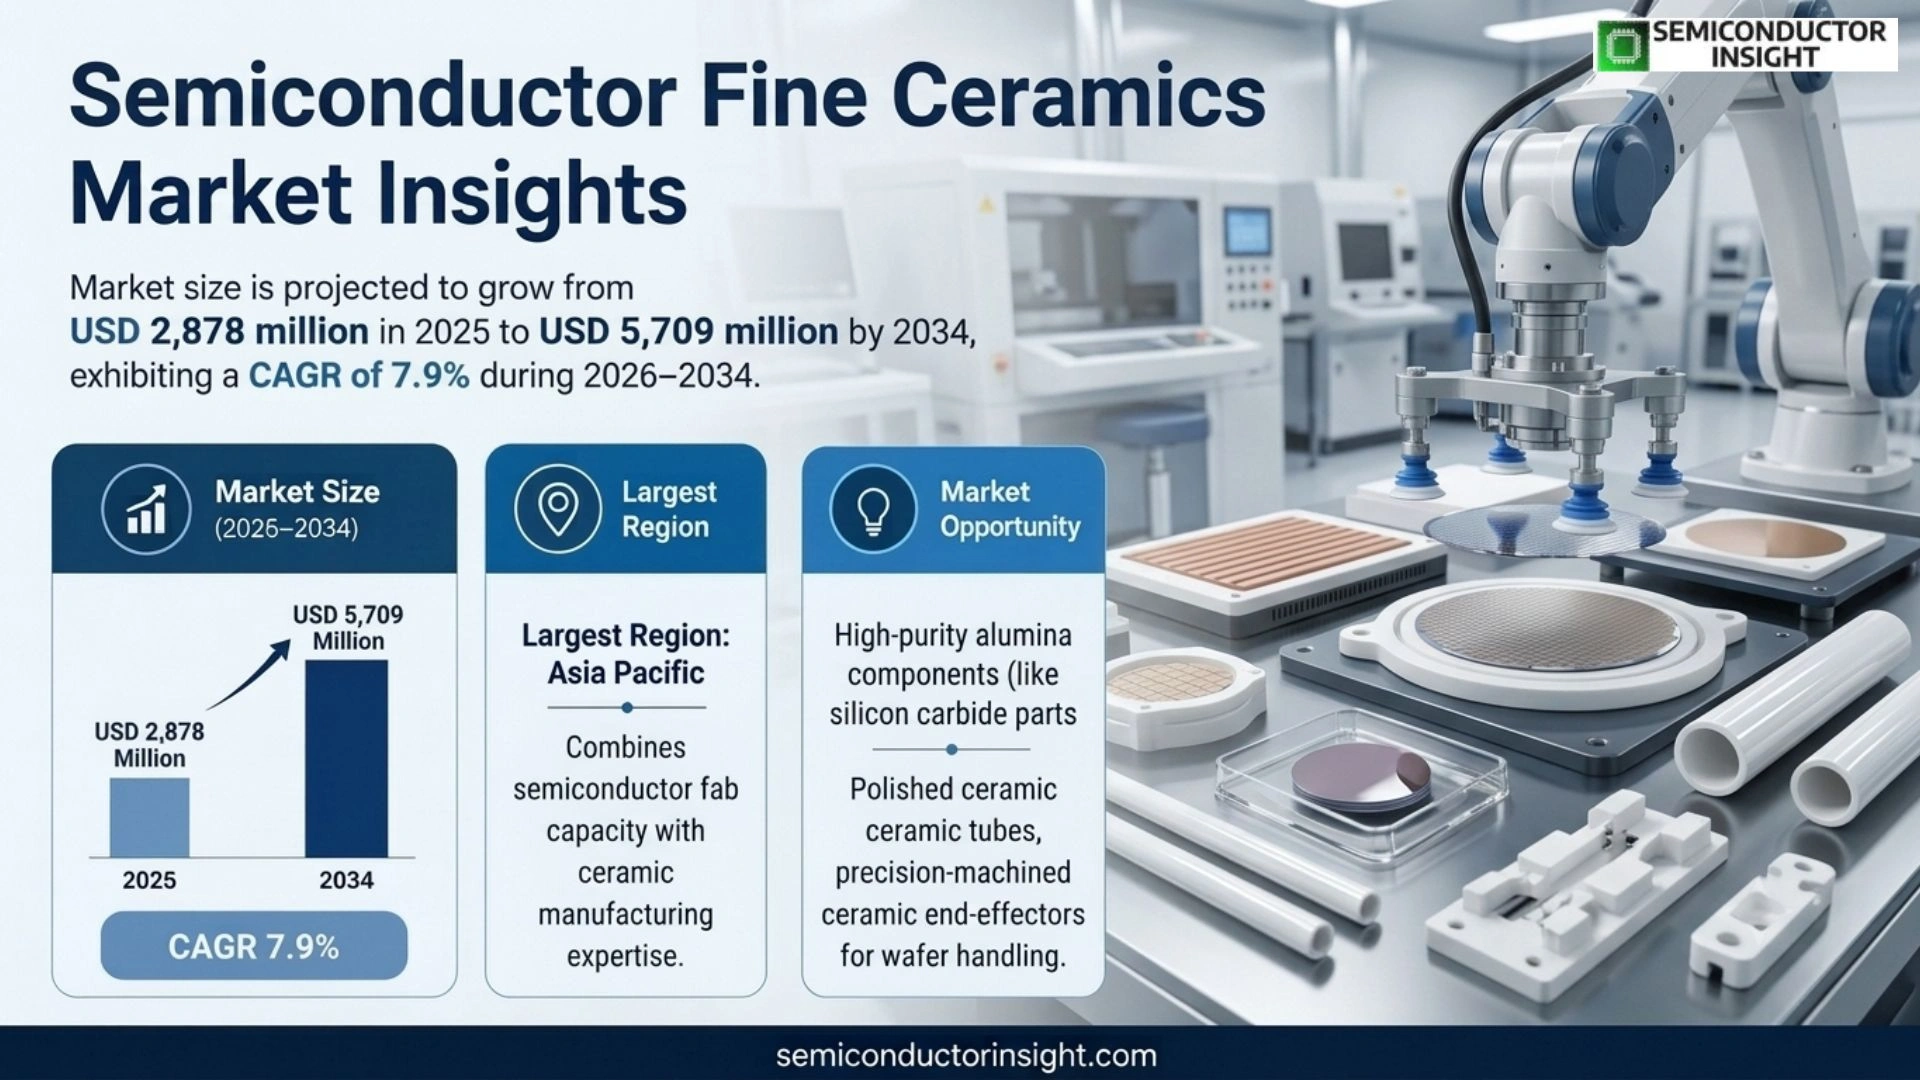
2.1 Global Semiconductor Fine Ceramics Market Size: 2024 VS 2032
2.2 Global Semiconductor Fine Ceramics Market Size, Prospects & Forecasts: 2020-2032
2.3 Key Market Trends, Opportunity, Drivers and Restraints
2.3.1 Market Opportunities & Trends
2.3.2 Market Drivers
2.3.3 Market Restraints
3 Company Landscape
3.1 Top Semiconductor Fine Ceramics Players in Global Market
3.2 Top Global Semiconductor Fine Ceramics Companies Ranked by Revenue
3.3 Global Semiconductor Fine Ceramics Revenue by Companies
3.4 Top 3 and Top 5 Semiconductor Fine Ceramics Companies in Global Market, by Revenue in 2024
3.5 Global Companies Semiconductor Fine Ceramics Product Type
3.6 Tier 1, Tier 2, and Tier 3 Semiconductor Fine Ceramics Players in Global Market
3.6.1 List of Global Tier 1 Semiconductor Fine Ceramics Companies
3.6.2 List of Global Tier 2 and Tier 3 Semiconductor Fine Ceramics Companies
4 Sights by Product
4.1 Overview
4.1.1 Segmentation by Type – Global Semiconductor Fine Ceramics Market Size Markets, 2024 & 2032
4.1.2 Aluminas (Al2O3)
4.1.3 Aluminum Nitride (AlN)
4.1.4 Silicon Carbide (SiC)
4.1.5 Silicon Nitride (Si3N4)
4.1.6 Others
4.2 Segmentation by Type – Global Semiconductor Fine Ceramics Revenue & Forecasts
4.2.1 Segmentation by Type – Global Semiconductor Fine Ceramics Revenue, 2020-2025
4.2.2 Segmentation by Type – Global Semiconductor Fine Ceramics Revenue, 2026-2032
4.2.3 Segmentation by Type – Global Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
5 Sights by Application
5.1 Overview
5.1.1 Segmentation by Application – Global Semiconductor Fine Ceramics Market Size, 2024 & 2032
5.1.2 Semiconductor Wafer Processing
5.1.3 Semiconductor Fabrication (Front End)
5.1.4 Semiconductor Manufacturing Process (Back-End Process)
5.2 Segmentation by Application – Global Semiconductor Fine Ceramics Revenue & Forecasts
5.2.1 Segmentation by Application – Global Semiconductor Fine Ceramics Revenue, 2020-2025
5.2.2 Segmentation by Application – Global Semiconductor Fine Ceramics Revenue, 2026-2032
5.2.3 Segmentation by Application – Global Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
6 Sights by Region
6.1 By Region – Global Semiconductor Fine Ceramics Market Size, 2024 & 2032
6.2 By Region – Global Semiconductor Fine Ceramics Revenue & Forecasts
6.2.1 By Region – Global Semiconductor Fine Ceramics Revenue, 2020-2025
6.2.2 By Region – Global Semiconductor Fine Ceramics Revenue, 2026-2032
6.2.3 By Region – Global Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
6.3 North America
6.3.1 By Country – North America Semiconductor Fine Ceramics Revenue, 2020-2032
6.3.2 United States Semiconductor Fine Ceramics Market Size, 2020-2032
6.3.3 Canada Semiconductor Fine Ceramics Market Size, 2020-2032
6.3.4 Mexico Semiconductor Fine Ceramics Market Size, 2020-2032
6.4 Europe
6.4.1 By Country – Europe Semiconductor Fine Ceramics Revenue, 2020-2032
6.4.2 Germany Semiconductor Fine Ceramics Market Size, 2020-2032
6.4.3 France Semiconductor Fine Ceramics Market Size, 2020-2032
6.4.4 U.K. Semiconductor Fine Ceramics Market Size, 2020-2032
6.4.5 Italy Semiconductor Fine Ceramics Market Size, 2020-2032
6.4.6 Russia Semiconductor Fine Ceramics Market Size, 2020-2032
6.4.7 Nordic Countries Semiconductor Fine Ceramics Market Size, 2020-2032
6.4.8 Benelux Semiconductor Fine Ceramics Market Size, 2020-2032
6.5 Asia
6.5.1 By Region – Asia Semiconductor Fine Ceramics Revenue, 2020-2032
6.5.2 China Semiconductor Fine Ceramics Market Size, 2020-2032
6.5.3 Japan Semiconductor Fine Ceramics Market Size, 2020-2032
6.5.4 South Korea Semiconductor Fine Ceramics Market Size, 2020-2032
6.5.5 Southeast Asia Semiconductor Fine Ceramics Market Size, 2020-2032
6.5.6 India Semiconductor Fine Ceramics Market Size, 2020-2032
6.6 South America
6.6.1 By Country – South America Semiconductor Fine Ceramics Revenue, 2020-2032
6.6.2 Brazil Semiconductor Fine Ceramics Market Size, 2020-2032
6.6.3 Argentina Semiconductor Fine Ceramics Market Size, 2020-2032
6.7 Middle East & Africa
6.7.1 By Country – Middle East & Africa Semiconductor Fine Ceramics Revenue, 2020-2032
6.7.2 Turkey Semiconductor Fine Ceramics Market Size, 2020-2032
6.7.3 Israel Semiconductor Fine Ceramics Market Size, 2020-2032
6.7.4 Saudi Arabia Semiconductor Fine Ceramics Market Size, 2020-2032
6.7.5 UAE Semiconductor Fine Ceramics Market Size, 2020-2032
7 Companies Profiles
7.1 NGK Insulators
7.1.1 NGK Insulators Corporate Summary
7.1.2 NGK Insulators Business Overview
7.1.3 NGK Insulators Semiconductor Fine Ceramics Major Product Offerings
7.1.4 NGK Insulators Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.1.5 NGK Insulators Key News & Latest Developments
7.2 Kyocera
7.2.1 Kyocera Corporate Summary
7.2.2 Kyocera Business Overview
7.2.3 Kyocera Semiconductor Fine Ceramics Major Product Offerings
7.2.4 Kyocera Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.2.5 Kyocera Key News & Latest Developments
7.3 Ferrotec
7.3.1 Ferrotec Corporate Summary
7.3.2 Ferrotec Business Overview
7.3.3 Ferrotec Semiconductor Fine Ceramics Major Product Offerings
7.3.4 Ferrotec Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.3.5 Ferrotec Key News & Latest Developments
7.4 TOTO Advanced Ceramics
7.4.1 TOTO Advanced Ceramics Corporate Summary
7.4.2 TOTO Advanced Ceramics Business Overview
7.4.3 TOTO Advanced Ceramics Semiconductor Fine Ceramics Major Product Offerings
7.4.4 TOTO Advanced Ceramics Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.4.5 TOTO Advanced Ceramics Key News & Latest Developments
7.5 Niterra Co., Ltd.
7.5.1 Niterra Co., Ltd. Corporate Summary
7.5.2 Niterra Co., Ltd. Business Overview
7.5.3 Niterra Co., Ltd. Semiconductor Fine Ceramics Major Product Offerings
7.5.4 Niterra Co., Ltd. Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.5.5 Niterra Co., Ltd. Key News & Latest Developments
7.6 ASUZAC Fine Ceramics
7.6.1 ASUZAC Fine Ceramics Corporate Summary
7.6.2 ASUZAC Fine Ceramics Business Overview
7.6.3 ASUZAC Fine Ceramics Semiconductor Fine Ceramics Major Product Offerings
7.6.4 ASUZAC Fine Ceramics Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.6.5 ASUZAC Fine Ceramics Key News & Latest Developments
7.7 Japan Fine Ceramics Co., Ltd. (JFC)
7.7.1 Japan Fine Ceramics Co., Ltd. (JFC) Corporate Summary
7.7.2 Japan Fine Ceramics Co., Ltd. (JFC) Business Overview
7.7.3 Japan Fine Ceramics Co., Ltd. (JFC) Semiconductor Fine Ceramics Major Product Offerings
7.7.4 Japan Fine Ceramics Co., Ltd. (JFC) Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.7.5 Japan Fine Ceramics Co., Ltd. (JFC) Key News & Latest Developments
7.8 Maruwa
7.8.1 Maruwa Corporate Summary
7.8.2 Maruwa Business Overview
7.8.3 Maruwa Semiconductor Fine Ceramics Major Product Offerings
7.8.4 Maruwa Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.8.5 Maruwa Key News & Latest Developments
7.9 Nishimura Advanced Ceramics
7.9.1 Nishimura Advanced Ceramics Corporate Summary
7.9.2 Nishimura Advanced Ceramics Business Overview
7.9.3 Nishimura Advanced Ceramics Semiconductor Fine Ceramics Major Product Offerings
7.9.4 Nishimura Advanced Ceramics Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.9.5 Nishimura Advanced Ceramics Key News & Latest Developments
7.10 Repton Co., Ltd.
7.10.1 Repton Co., Ltd. Corporate Summary
7.10.2 Repton Co., Ltd. Business Overview
7.10.3 Repton Co., Ltd. Semiconductor Fine Ceramics Major Product Offerings
7.10.4 Repton Co., Ltd. Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.10.5 Repton Co., Ltd. Key News & Latest Developments
7.11 Pacific Rundum
7.11.1 Pacific Rundum Corporate Summary
7.11.2 Pacific Rundum Business Overview
7.11.3 Pacific Rundum Semiconductor Fine Ceramics Major Product Offerings
7.11.4 Pacific Rundum Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.11.5 Pacific Rundum Key News & Latest Developments
7.12 Coorstek
7.12.1 Coorstek Corporate Summary
7.12.2 Coorstek Business Overview
7.12.3 Coorstek Semiconductor Fine Ceramics Major Product Offerings
7.12.4 Coorstek Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.12.5 Coorstek Key News & Latest Developments
7.13 3M
7.13.1 3M Corporate Summary
7.13.2 3M Business Overview
7.13.3 3M Semiconductor Fine Ceramics Major Product Offerings
7.13.4 3M Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.13.5 3M Key News & Latest Developments
7.14 Bullen Ultrasonics
7.14.1 Bullen Ultrasonics Corporate Summary
7.14.2 Bullen Ultrasonics Business Overview
7.14.3 Bullen Ultrasonics Semiconductor Fine Ceramics Major Product Offerings
7.14.4 Bullen Ultrasonics Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.14.5 Bullen Ultrasonics Key News & Latest Developments
7.15 STC Material Solutions
7.15.1 STC Material Solutions Corporate Summary
7.15.2 STC Material Solutions Business Overview
7.15.3 STC Material Solutions Semiconductor Fine Ceramics Major Product Offerings
7.15.4 STC Material Solutions Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.15.5 STC Material Solutions Key News & Latest Developments
7.16 Precision Ferrites & Ceramics (PFC)
7.16.1 Precision Ferrites & Ceramics (PFC) Corporate Summary
7.16.2 Precision Ferrites & Ceramics (PFC) Business Overview
7.16.3 Precision Ferrites & Ceramics (PFC) Semiconductor Fine Ceramics Major Product Offerings
7.16.4 Precision Ferrites & Ceramics (PFC) Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.16.5 Precision Ferrites & Ceramics (PFC) Key News & Latest Developments
7.17 Ortech Ceramics
7.17.1 Ortech Ceramics Corporate Summary
7.17.2 Ortech Ceramics Business Overview
7.17.3 Ortech Ceramics Semiconductor Fine Ceramics Major Product Offerings
7.17.4 Ortech Ceramics Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.17.5 Ortech Ceramics Key News & Latest Developments
7.18 Morgan Advanced Materials
7.18.1 Morgan Advanced Materials Corporate Summary
7.18.2 Morgan Advanced Materials Business Overview
7.18.3 Morgan Advanced Materials Semiconductor Fine Ceramics Major Product Offerings
7.18.4 Morgan Advanced Materials Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.18.5 Morgan Advanced Materials Key News & Latest Developments
7.19 CeramTec
7.19.1 CeramTec Corporate Summary
7.19.2 CeramTec Business Overview
7.19.3 CeramTec Semiconductor Fine Ceramics Major Product Offerings
7.19.4 CeramTec Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.19.5 CeramTec Key News & Latest Developments
7.20 Saint-Gobain
7.20.1 Saint-Gobain Corporate Summary
7.20.2 Saint-Gobain Business Overview
7.20.3 Saint-Gobain Semiconductor Fine Ceramics Major Product Offerings
7.20.4 Saint-Gobain Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.20.5 Saint-Gobain Key News & Latest Developments
7.21 Schunk Xycarb Technology
7.21.1 Schunk Xycarb Technology Corporate Summary
7.21.2 Schunk Xycarb Technology Business Overview
7.21.3 Schunk Xycarb Technology Semiconductor Fine Ceramics Major Product Offerings
7.21.4 Schunk Xycarb Technology Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.21.5 Schunk Xycarb Technology Key News & Latest Developments
7.22 Advanced Special Tools (AST)
7.22.1 Advanced Special Tools (AST) Corporate Summary
7.22.2 Advanced Special Tools (AST) Business Overview
7.22.3 Advanced Special Tools (AST) Semiconductor Fine Ceramics Major Product Offerings
7.22.4 Advanced Special Tools (AST) Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.22.5 Advanced Special Tools (AST) Key News & Latest Developments
7.23 MiCo Ceramics Co., Ltd.
7.23.1 MiCo Ceramics Co., Ltd. Corporate Summary
7.23.2 MiCo Ceramics Co., Ltd. Business Overview
7.23.3 MiCo Ceramics Co., Ltd. Semiconductor Fine Ceramics Major Product Offerings
7.23.4 MiCo Ceramics Co., Ltd. Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.23.5 MiCo Ceramics Co., Ltd. Key News & Latest Developments
7.24 WONIK QnC
7.24.1 WONIK QnC Corporate Summary
7.24.2 WONIK QnC Business Overview
7.24.3 WONIK QnC Semiconductor Fine Ceramics Major Product Offerings
7.24.4 WONIK QnC Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.24.5 WONIK QnC Key News & Latest Developments
7.25 Micro Ceramics Ltd
7.25.1 Micro Ceramics Ltd Corporate Summary
7.25.2 Micro Ceramics Ltd Business Overview
7.25.3 Micro Ceramics Ltd Semiconductor Fine Ceramics Major Product Offerings
7.25.4 Micro Ceramics Ltd Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.25.5 Micro Ceramics Ltd Key News & Latest Developments
7.26 Suzhou KemaTek, Inc.
7.26.1 Suzhou KemaTek, Inc. Corporate Summary
7.26.2 Suzhou KemaTek, Inc. Business Overview
7.26.3 Suzhou KemaTek, Inc. Semiconductor Fine Ceramics Major Product Offerings
7.26.4 Suzhou KemaTek, Inc. Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.26.5 Suzhou KemaTek, Inc. Key News & Latest Developments
7.27 Shanghai Companion
7.27.1 Shanghai Companion Corporate Summary
7.27.2 Shanghai Companion Business Overview
7.27.3 Shanghai Companion Semiconductor Fine Ceramics Major Product Offerings
7.27.4 Shanghai Companion Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.27.5 Shanghai Companion Key News & Latest Developments
7.28 Sanzer (Shanghai) New Materials Technology
7.28.1 Sanzer (Shanghai) New Materials Technology Corporate Summary
7.28.2 Sanzer (Shanghai) New Materials Technology Business Overview
7.28.3 Sanzer (Shanghai) New Materials Technology Semiconductor Fine Ceramics Major Product Offerings
7.28.4 Sanzer (Shanghai) New Materials Technology Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.28.5 Sanzer (Shanghai) New Materials Technology Key News & Latest Developments
7.29 St.Cera Co., Ltd
7.29.1 St.Cera Co., Ltd Corporate Summary
7.29.2 St.Cera Co., Ltd Business Overview
7.29.3 St.Cera Co., Ltd Semiconductor Fine Ceramics Major Product Offerings
7.29.4 St.Cera Co., Ltd Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.29.5 St.Cera Co., Ltd Key News & Latest Developments
7.30 Fountyl
7.30.1 Fountyl Corporate Summary
7.30.2 Fountyl Business Overview
7.30.3 Fountyl Semiconductor Fine Ceramics Major Product Offerings
7.30.4 Fountyl Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.30.5 Fountyl Key News & Latest Developments
7.31 Hebei Sinopack Electronic Technology
7.31.1 Hebei Sinopack Electronic Technology Corporate Summary
7.31.2 Hebei Sinopack Electronic Technology Business Overview
7.31.3 Hebei Sinopack Electronic Technology Semiconductor Fine Ceramics Major Product Offerings
7.31.4 Hebei Sinopack Electronic Technology Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.31.5 Hebei Sinopack Electronic Technology Key News & Latest Developments
7.32 ChaoZhou Three-circle
7.32.1 ChaoZhou Three-circle Corporate Summary
7.32.2 ChaoZhou Three-circle Business Overview
7.32.3 ChaoZhou Three-circle Semiconductor Fine Ceramics Major Product Offerings
7.32.4 ChaoZhou Three-circle Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.32.5 ChaoZhou Three-circle Key News & Latest Developments
7.33 Fujian Huaqing Electronic Material Technology
7.33.1 Fujian Huaqing Electronic Material Technology Corporate Summary
7.33.2 Fujian Huaqing Electronic Material Technology Business Overview
7.33.3 Fujian Huaqing Electronic Material Technology Semiconductor Fine Ceramics Major Product Offerings
7.33.4 Fujian Huaqing Electronic Material Technology Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.33.5 Fujian Huaqing Electronic Material Technology Key News & Latest Developments
7.34 3X Ceramic Parts Company
7.34.1 3X Ceramic Parts Company Corporate Summary
7.34.2 3X Ceramic Parts Company Business Overview
7.34.3 3X Ceramic Parts Company Semiconductor Fine Ceramics Major Product Offerings
7.34.4 3X Ceramic Parts Company Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.34.5 3X Ceramic Parts Company Key News & Latest Developments
7.35 Krosaki Harima Corporation
7.35.1 Krosaki Harima Corporation Corporate Summary
7.35.2 Krosaki Harima Corporation Business Overview
7.35.3 Krosaki Harima Corporation Semiconductor Fine Ceramics Major Product Offerings
7.35.4 Krosaki Harima Corporation Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.35.5 Krosaki Harima Corporation Key News & Latest Developments
7.36 Kallex Company,Ltd
7.36.1 Kallex Company,Ltd Corporate Summary
7.36.2 Kallex Company,Ltd Business Overview
7.36.3 Kallex Company,Ltd Semiconductor Fine Ceramics Major Product Offerings
7.36.4 Kallex Company,Ltd Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.36.5 Kallex Company,Ltd Key News & Latest Developments
7.37 Shaanxi UDC Materials Technology
7.37.1 Shaanxi UDC Materials Technology Corporate Summary
7.37.2 Shaanxi UDC Materials Technology Business Overview
7.37.3 Shaanxi UDC Materials Technology Semiconductor Fine Ceramics Major Product Offerings
7.37.4 Shaanxi UDC Materials Technology Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.37.5 Shaanxi UDC Materials Technology Key News & Latest Developments
7.38 AGC
7.38.1 AGC Corporate Summary
7.38.2 AGC Business Overview
7.38.3 AGC Semiconductor Fine Ceramics Major Product Offerings
7.38.4 AGC Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.38.5 AGC Key News & Latest Developments
7.39 Coalition Technology
7.39.1 Coalition Technology Corporate Summary
7.39.2 Coalition Technology Business Overview
7.39.3 Coalition Technology Semiconductor Fine Ceramics Major Product Offerings
7.39.4 Coalition Technology Semiconductor Fine Ceramics Revenue in Global Market (2020-2025)
7.39.5 Coalition Technology Key News & Latest Developments
8 Conclusion
9 Appendix
9.1 Note
9.2 Examples of Clients
9.3 DisclaimerList of Tables
Table 1. Semiconductor Fine Ceramics Market Opportunities & Trends in Global Market
Table 2. Semiconductor Fine Ceramics Market Drivers in Global Market
Table 3. Semiconductor Fine Ceramics Market Restraints in Global Market
Table 4. Key Players of Semiconductor Fine Ceramics in Global Market
Table 5. Top Semiconductor Fine Ceramics Players in Global Market, Ranking by Revenue (2024)
Table 6. Global Semiconductor Fine Ceramics Revenue by Companies, (US$, Mn), 2020-2025
Table 7. Global Semiconductor Fine Ceramics Revenue Share by Companies, 2020-2025
Table 8. Global Companies Semiconductor Fine Ceramics Product Type
Table 9. List of Global Tier 1 Semiconductor Fine Ceramics Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 10. List of Global Tier 2 and Tier 3 Semiconductor Fine Ceramics Companies, Revenue (US$, Mn) in 2024 and Market Share
Table 11. Segmentation by Type Global Semiconductor Fine Ceramics Revenue, (US$, Mn), 2024 & 2032
Table 12. Segmentation by Type – Global Semiconductor Fine Ceramics Revenue (US$, Mn), 2020-2025
Table 13. Segmentation by Type – Global Semiconductor Fine Ceramics Revenue (US$, Mn), 2026-2032
Table 14. Segmentation by Application Global Semiconductor Fine Ceramics Revenue, (US$, Mn), 2024 & 2032
Table 15. Segmentation by Application – Global Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2025
Table 16. Segmentation by Application – Global Semiconductor Fine Ceramics Revenue, (US$, Mn), 2026-2032
Table 17. By Region Global Semiconductor Fine Ceramics Revenue, (US$, Mn), 2024 & 2032
Table 18. By Region – Global Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2025
Table 19. By Region – Global Semiconductor Fine Ceramics Revenue, (US$, Mn), 2026-2032
Table 20. By Country – North America Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2025
Table 21. By Country – North America Semiconductor Fine Ceramics Revenue, (US$, Mn), 2026-2032
Table 22. By Country – Europe Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2025
Table 23. By Country – Europe Semiconductor Fine Ceramics Revenue, (US$, Mn), 2026-2032
Table 24. By Region – Asia Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2025
Table 25. By Region – Asia Semiconductor Fine Ceramics Revenue, (US$, Mn), 2026-2032
Table 26. By Country – South America Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2025
Table 27. By Country – South America Semiconductor Fine Ceramics Revenue, (US$, Mn), 2026-2032
Table 28. By Country – Middle East & Africa Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2025
Table 29. By Country – Middle East & Africa Semiconductor Fine Ceramics Revenue, (US$, Mn), 2026-2032
Table 30. NGK Insulators Corporate Summary
Table 31. NGK Insulators Semiconductor Fine Ceramics Product Offerings
Table 32. NGK Insulators Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 33. NGK Insulators Key News & Latest Developments
Table 34. Kyocera Corporate Summary
Table 35. Kyocera Semiconductor Fine Ceramics Product Offerings
Table 36. Kyocera Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 37. Kyocera Key News & Latest Developments
Table 38. Ferrotec Corporate Summary
Table 39. Ferrotec Semiconductor Fine Ceramics Product Offerings
Table 40. Ferrotec Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 41. Ferrotec Key News & Latest Developments
Table 42. TOTO Advanced Ceramics Corporate Summary
Table 43. TOTO Advanced Ceramics Semiconductor Fine Ceramics Product Offerings
Table 44. TOTO Advanced Ceramics Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 45. TOTO Advanced Ceramics Key News & Latest Developments
Table 46. Niterra Co., Ltd. Corporate Summary
Table 47. Niterra Co., Ltd. Semiconductor Fine Ceramics Product Offerings
Table 48. Niterra Co., Ltd. Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 49. Niterra Co., Ltd. Key News & Latest Developments
Table 50. ASUZAC Fine Ceramics Corporate Summary
Table 51. ASUZAC Fine Ceramics Semiconductor Fine Ceramics Product Offerings
Table 52. ASUZAC Fine Ceramics Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 53. ASUZAC Fine Ceramics Key News & Latest Developments
Table 54. Japan Fine Ceramics Co., Ltd. (JFC) Corporate Summary
Table 55. Japan Fine Ceramics Co., Ltd. (JFC) Semiconductor Fine Ceramics Product Offerings
Table 56. Japan Fine Ceramics Co., Ltd. (JFC) Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 57. Japan Fine Ceramics Co., Ltd. (JFC) Key News & Latest Developments
Table 58. Maruwa Corporate Summary
Table 59. Maruwa Semiconductor Fine Ceramics Product Offerings
Table 60. Maruwa Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 61. Maruwa Key News & Latest Developments
Table 62. Nishimura Advanced Ceramics Corporate Summary
Table 63. Nishimura Advanced Ceramics Semiconductor Fine Ceramics Product Offerings
Table 64. Nishimura Advanced Ceramics Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 65. Nishimura Advanced Ceramics Key News & Latest Developments
Table 66. Repton Co., Ltd. Corporate Summary
Table 67. Repton Co., Ltd. Semiconductor Fine Ceramics Product Offerings
Table 68. Repton Co., Ltd. Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 69. Repton Co., Ltd. Key News & Latest Developments
Table 70. Pacific Rundum Corporate Summary
Table 71. Pacific Rundum Semiconductor Fine Ceramics Product Offerings
Table 72. Pacific Rundum Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 73. Pacific Rundum Key News & Latest Developments
Table 74. Coorstek Corporate Summary
Table 75. Coorstek Semiconductor Fine Ceramics Product Offerings
Table 76. Coorstek Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 77. Coorstek Key News & Latest Developments
Table 78. 3M Corporate Summary
Table 79. 3M Semiconductor Fine Ceramics Product Offerings
Table 80. 3M Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 81. 3M Key News & Latest Developments
Table 82. Bullen Ultrasonics Corporate Summary
Table 83. Bullen Ultrasonics Semiconductor Fine Ceramics Product Offerings
Table 84. Bullen Ultrasonics Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 85. Bullen Ultrasonics Key News & Latest Developments
Table 86. STC Material Solutions Corporate Summary
Table 87. STC Material Solutions Semiconductor Fine Ceramics Product Offerings
Table 88. STC Material Solutions Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 89. STC Material Solutions Key News & Latest Developments
Table 90. Precision Ferrites & Ceramics (PFC) Corporate Summary
Table 91. Precision Ferrites & Ceramics (PFC) Semiconductor Fine Ceramics Product Offerings
Table 92. Precision Ferrites & Ceramics (PFC) Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 93. Precision Ferrites & Ceramics (PFC) Key News & Latest Developments
Table 94. Ortech Ceramics Corporate Summary
Table 95. Ortech Ceramics Semiconductor Fine Ceramics Product Offerings
Table 96. Ortech Ceramics Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 97. Ortech Ceramics Key News & Latest Developments
Table 98. Morgan Advanced Materials Corporate Summary
Table 99. Morgan Advanced Materials Semiconductor Fine Ceramics Product Offerings
Table 100. Morgan Advanced Materials Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 101. Morgan Advanced Materials Key News & Latest Developments
Table 102. CeramTec Corporate Summary
Table 103. CeramTec Semiconductor Fine Ceramics Product Offerings
Table 104. CeramTec Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 105. CeramTec Key News & Latest Developments
Table 106. Saint-Gobain Corporate Summary
Table 107. Saint-Gobain Semiconductor Fine Ceramics Product Offerings
Table 108. Saint-Gobain Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 109. Saint-Gobain Key News & Latest Developments
Table 110. Schunk Xycarb Technology Corporate Summary
Table 111. Schunk Xycarb Technology Semiconductor Fine Ceramics Product Offerings
Table 112. Schunk Xycarb Technology Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 113. Schunk Xycarb Technology Key News & Latest Developments
Table 114. Advanced Special Tools (AST) Corporate Summary
Table 115. Advanced Special Tools (AST) Semiconductor Fine Ceramics Product Offerings
Table 116. Advanced Special Tools (AST) Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 117. Advanced Special Tools (AST) Key News & Latest Developments
Table 118. MiCo Ceramics Co., Ltd. Corporate Summary
Table 119. MiCo Ceramics Co., Ltd. Semiconductor Fine Ceramics Product Offerings
Table 120. MiCo Ceramics Co., Ltd. Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 121. MiCo Ceramics Co., Ltd. Key News & Latest Developments
Table 122. WONIK QnC Corporate Summary
Table 123. WONIK QnC Semiconductor Fine Ceramics Product Offerings
Table 124. WONIK QnC Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 125. WONIK QnC Key News & Latest Developments
Table 126. Micro Ceramics Ltd Corporate Summary
Table 127. Micro Ceramics Ltd Semiconductor Fine Ceramics Product Offerings
Table 128. Micro Ceramics Ltd Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 129. Micro Ceramics Ltd Key News & Latest Developments
Table 130. Suzhou KemaTek, Inc. Corporate Summary
Table 131. Suzhou KemaTek, Inc. Semiconductor Fine Ceramics Product Offerings
Table 132. Suzhou KemaTek, Inc. Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 133. Suzhou KemaTek, Inc. Key News & Latest Developments
Table 134. Shanghai Companion Corporate Summary
Table 135. Shanghai Companion Semiconductor Fine Ceramics Product Offerings
Table 136. Shanghai Companion Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 137. Shanghai Companion Key News & Latest Developments
Table 138. Sanzer (Shanghai) New Materials Technology Corporate Summary
Table 139. Sanzer (Shanghai) New Materials Technology Semiconductor Fine Ceramics Product Offerings
Table 140. Sanzer (Shanghai) New Materials Technology Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 141. Sanzer (Shanghai) New Materials Technology Key News & Latest Developments
Table 142. St.Cera Co., Ltd Corporate Summary
Table 143. St.Cera Co., Ltd Semiconductor Fine Ceramics Product Offerings
Table 144. St.Cera Co., Ltd Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 145. St.Cera Co., Ltd Key News & Latest Developments
Table 146. Fountyl Corporate Summary
Table 147. Fountyl Semiconductor Fine Ceramics Product Offerings
Table 148. Fountyl Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 149. Fountyl Key News & Latest Developments
Table 150. Hebei Sinopack Electronic Technology Corporate Summary
Table 151. Hebei Sinopack Electronic Technology Semiconductor Fine Ceramics Product Offerings
Table 152. Hebei Sinopack Electronic Technology Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 153. Hebei Sinopack Electronic Technology Key News & Latest Developments
Table 154. ChaoZhou Three-circle Corporate Summary
Table 155. ChaoZhou Three-circle Semiconductor Fine Ceramics Product Offerings
Table 156. ChaoZhou Three-circle Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 157. ChaoZhou Three-circle Key News & Latest Developments
Table 158. Fujian Huaqing Electronic Material Technology Corporate Summary
Table 159. Fujian Huaqing Electronic Material Technology Semiconductor Fine Ceramics Product Offerings
Table 160. Fujian Huaqing Electronic Material Technology Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 161. Fujian Huaqing Electronic Material Technology Key News & Latest Developments
Table 162. 3X Ceramic Parts Company Corporate Summary
Table 163. 3X Ceramic Parts Company Semiconductor Fine Ceramics Product Offerings
Table 164. 3X Ceramic Parts Company Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 165. 3X Ceramic Parts Company Key News & Latest Developments
Table 166. Krosaki Harima Corporation Corporate Summary
Table 167. Krosaki Harima Corporation Semiconductor Fine Ceramics Product Offerings
Table 168. Krosaki Harima Corporation Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 169. Krosaki Harima Corporation Key News & Latest Developments
Table 170. Kallex Company,Ltd Corporate Summary
Table 171. Kallex Company,Ltd Semiconductor Fine Ceramics Product Offerings
Table 172. Kallex Company,Ltd Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 173. Kallex Company,Ltd Key News & Latest Developments
Table 174. Shaanxi UDC Materials Technology Corporate Summary
Table 175. Shaanxi UDC Materials Technology Semiconductor Fine Ceramics Product Offerings
Table 176. Shaanxi UDC Materials Technology Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 177. Shaanxi UDC Materials Technology Key News & Latest Developments
Table 178. AGC Corporate Summary
Table 179. AGC Semiconductor Fine Ceramics Product Offerings
Table 180. AGC Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 181. AGC Key News & Latest Developments
Table 182. Coalition Technology Corporate Summary
Table 183. Coalition Technology Semiconductor Fine Ceramics Product Offerings
Table 184. Coalition Technology Semiconductor Fine Ceramics Revenue (US$, Mn) & (2020-2025)
Table 185. Coalition Technology Key News & Latest Developments
List of Figures
Figure 1. Semiconductor Fine Ceramics Product Picture
Figure 2. Semiconductor Fine Ceramics Segment by Type in 2024
Figure 3. Semiconductor Fine Ceramics Segment by Application in 2024
Figure 4. Global Semiconductor Fine Ceramics Market Overview: 2024
Figure 5. Key Caveats
Figure 6. Global Semiconductor Fine Ceramics Market Size: 2024 VS 2032 (US$, Mn)
Figure 7. Global Semiconductor Fine Ceramics Revenue: 2020-2032 (US$, Mn)
Figure 8. The Top 3 and 5 Players Market Share by Semiconductor Fine Ceramics Revenue in 2024
Figure 9. Segmentation by Type Global Semiconductor Fine Ceramics Revenue, (US$, Mn), 2024 & 2032
Figure 10. Segmentation by Type – Global Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
Figure 11. Segmentation by Application Global Semiconductor Fine Ceramics Revenue, (US$, Mn), 2024 & 2032
Figure 12. Segmentation by Application – Global Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
Figure 13. By Region – Global Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
Figure 14. By Country – North America Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
Figure 15. United States Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 16. Canada Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 17. Mexico Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 18. By Country – Europe Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
Figure 19. Germany Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 20. France Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 21. U.K. Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 22. Italy Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 23. Russia Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 24. Nordic Countries Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 25. Benelux Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 26. By Region – Asia Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
Figure 27. China Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 28. Japan Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 29. South Korea Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 30. Southeast Asia Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 31. India Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 32. By Country – South America Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
Figure 33. Brazil Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 34. Argentina Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 35. By Country – Middle East & Africa Semiconductor Fine Ceramics Revenue Market Share, 2020-2032
Figure 36. Turkey Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 37. Israel Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 38. Saudi Arabia Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 39. UAE Semiconductor Fine Ceramics Revenue, (US$, Mn), 2020-2032
Figure 40. NGK Insulators Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 41. Kyocera Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 42. Ferrotec Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 43. TOTO Advanced Ceramics Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 44. Niterra Co., Ltd. Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 45. ASUZAC Fine Ceramics Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 46. Japan Fine Ceramics Co., Ltd. (JFC) Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 47. Maruwa Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 48. Nishimura Advanced Ceramics Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 49. Repton Co., Ltd. Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 50. Pacific Rundum Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 51. Coorstek Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 52. 3M Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 53. Bullen Ultrasonics Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 54. STC Material Solutions Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 55. Precision Ferrites & Ceramics (PFC) Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 56. Ortech Ceramics Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 57. Morgan Advanced Materials Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 58. CeramTec Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 59. Saint-Gobain Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 60. Schunk Xycarb Technology Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 61. Advanced Special Tools (AST) Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 62. MiCo Ceramics Co., Ltd. Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 63. WONIK QnC Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 64. Micro Ceramics Ltd Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 65. Suzhou KemaTek, Inc. Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 66. Shanghai Companion Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 67. Sanzer (Shanghai) New Materials Technology Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 68. St.Cera Co., Ltd Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 69. Fountyl Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 70. Hebei Sinopack Electronic Technology Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 71. ChaoZhou Three-circle Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 72. Fujian Huaqing Electronic Material Technology Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 73. 3X Ceramic Parts Company Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 74. Krosaki Harima Corporation Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 75. Kallex Company,Ltd Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 76. Shaanxi UDC Materials Technology Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 77. AGC Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)
Figure 78. Coalition Technology Semiconductor Fine Ceramics Revenue Year Over Year Growth (US$, Mn) & (2020-2025)