Key Statistics
Key Takeaways
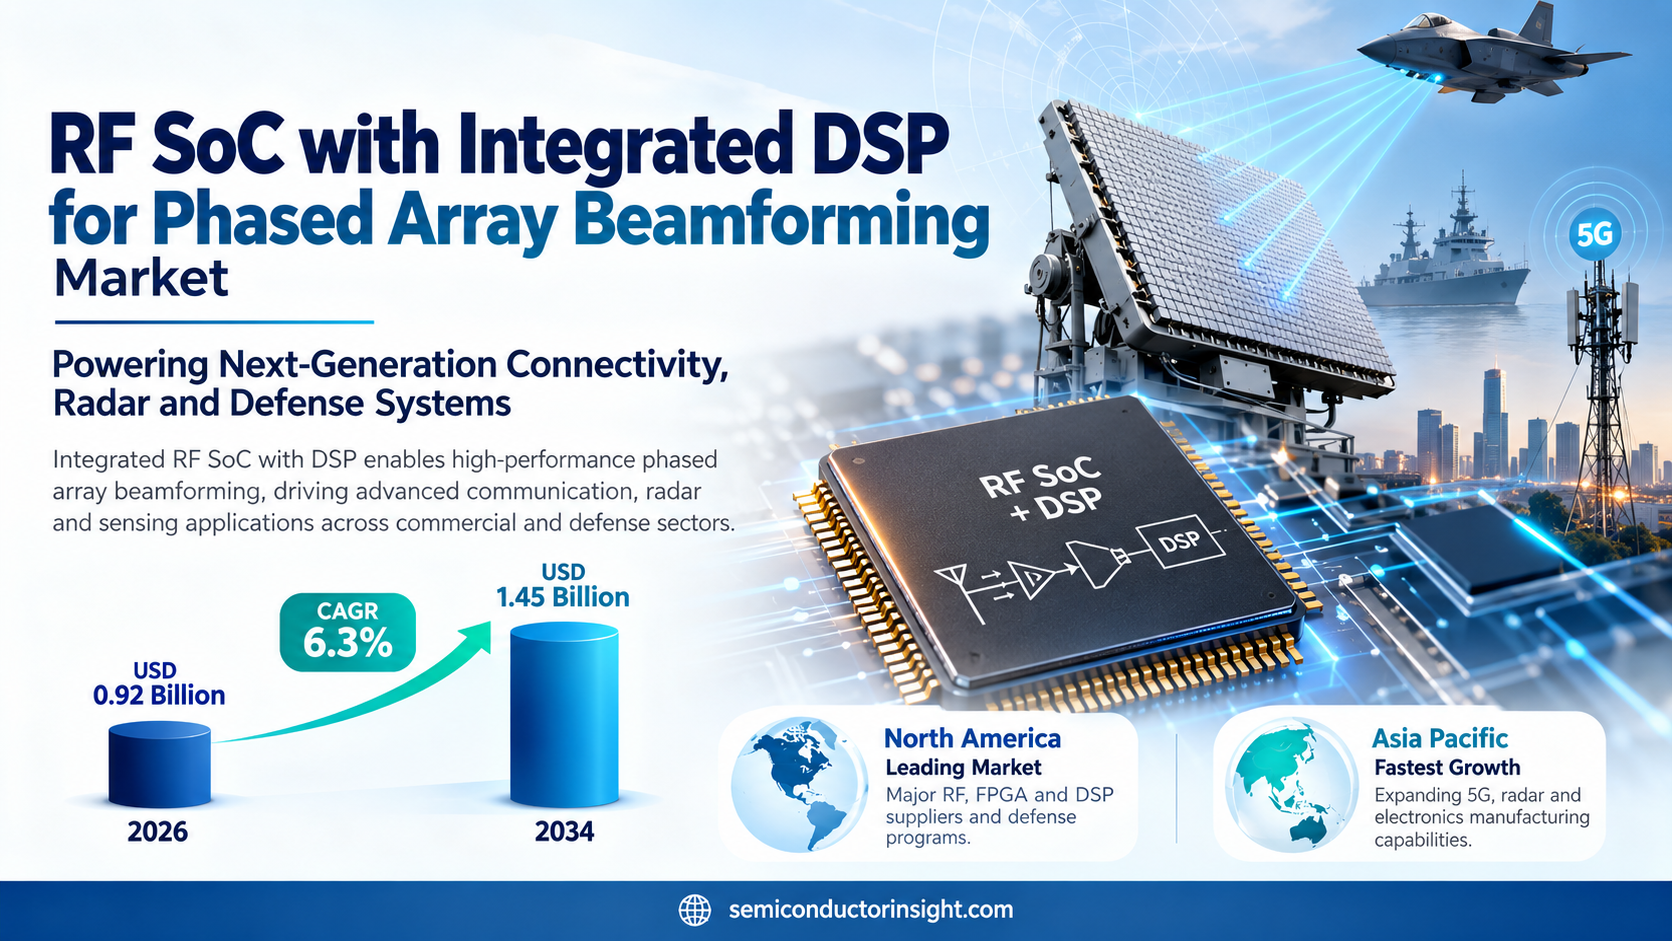
- Market size: The market is valued at USD 0.85 billion in 2025 and is projected to reach USD 1.45 billion by 2034, representing a 6.3% CAGR during 2026–2034.
- Sub-6 GHz RF SoC is a leading segment, reflecting broad use across the largest volume applications.
- North America leads the market, while Asia Pacific provides the strongest growth profile.
- 5G/6G Infrastructure is a major application, supported by rising performance and reliability requirements.
- real-time digital beamforming, RF-data-converter integration and mmWave arrays is becoming a central competitive differentiator as customers seek higher performance and lower system-level cost.
RF SoC with Integrated DSP for Phased Array Beamforming Market Overview
RF SoC with integrated DSP for phased array beamforming market is valued at USD 0.85 billion in 2025 and is projected to reach USD 1.45 billion by 2034, expanding at a 6.3% CAGR during 2026–2034. The 2026 market level is USD 0.92 billion. North America is used as the leading current market because major RF, FPGA and DSP suppliers and defense programs are concentrated there, while Asia Pacific provides the fastest growth through 5G, radar and electronics manufacturing.
RF SoC with Integrated DSP for Phased Array Beamforming products provide a critical functional layer inside modern electronic and industrial systems. Their commercial value depends on performance, reliability, manufacturability, qualification and compatibility with the broader hardware architecture. Customers increasingly assess total system impact rather than component price alone, which favors suppliers that combine proven technology with consistent global support.
Technology development is focused on real-time digital beamforming, rf-data-converter integration and mmwave arrays, tighter integration and more automated manufacturing. These trends raise the value of precision process control and application engineering because smaller geometries, higher data rates or greater power density leave less margin for variation. Qualification therefore becomes a major barrier to entry in premium applications.
Commercial competition combines scale with specialization. Large suppliers benefit from purchasing power, engineering resources and global manufacturing, while specialist vendors can win through process expertise or application-specific performance. Design wins are often durable because changing suppliers can require requalification of electrical, thermal, mechanical or reliability performance. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Segment Analysis: By Type
By type, the market is segmented into Sub-6 GHz RF SoC, mmWave RF SoC, Multi-Band RF SoC. Product selection depends on performance, cost, manufacturing complexity and the target system architecture. Higher-value variants generally offer tighter tolerances, greater integration or improved reliability, while mainstream categories retain volume leadership because of lower cost and broad compatibility.
| Type | Commercial role |
|---|---|
| Sub-6 GHz RF SoC | Sub-6 GHz RF SoC serves a distinct portion of the RF SoC with Integrated DSP for Phased Array Beamforming market based on performance, cost and integration requirements. |
| mmWave RF SoC | mmWave RF SoC serves a distinct portion of the RF SoC with Integrated DSP for Phased Array Beamforming market based on performance, cost and integration requirements. |
| Multi-Band RF SoC | Multi-Band RF SoC serves a distinct portion of the RF SoC with Integrated DSP for Phased Array Beamforming market based on performance, cost and integration requirements. |
Additional Segmentation: By Array Size
Array Size segmentation highlights important technical or commercial differences inside the RF SoC with Integrated DSP for Phased Array Beamforming market. These categories affect pricing, qualification, process requirements and customer fit, making them useful for evaluating where value growth differs from simple unit growth. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Array Size | Demand characteristics |
|---|---|
| Small Array | Compact beamforming for automotive, industrial and point-to-point links. |
| Medium Array | 5G radio and phased-array sensing platforms. |
| Large Array | Defense radar, satellite and high-capacity mmWave systems. |
Segment Analysis: By Application
By application, the market covers 5G/6G Infrastructure, Radar & Defense, Automotive Radar, Satellite Communications, Industrial Sensing. Demand varies by reliability, performance and product lifecycle. Premium applications usually require stricter qualification and long-term supply support, while higher-volume applications place more emphasis on cost, manufacturing scale and rapid technology migration. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Application | Demand characteristics |
|---|---|
| 5G/6G Infrastructure | 5G/6G Infrastructure is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Radar & Defense | Radar & Defense is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Automotive Radar | Automotive Radar is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Satellite Communications | Satellite Communications is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Industrial Sensing | Industrial Sensing is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
Additional Segmentation: By Integration Level
Integration Level provides a second analytical view of the RF SoC with Integrated DSP for Phased Array Beamforming market. It captures how product architecture and end-use requirements change supplier economics, qualification effort and technology roadmaps across the forecast period. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Integration Level | Commercial relevance |
|---|---|
| RF + DSP SoC | Integrated RF conversion and real-time beamforming computation. |
| RF + Beamformer IC | Dedicated RF and phase-control integration around a host processor. |
| Fully Integrated Antenna-in-Package Platform | Highest integration for compact mmWave and satellite terminals. |
Regional Analysis
North America is the largest regional market, while Asia Pacific is the fastest-growth region. Regional positioning reflects manufacturing concentration, downstream electronics demand, capital investment and the availability of qualified suppliers. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Why does regional demand differ across the RF SoC with Integrated DSP for Phased Array Beamforming market?
Regional demand varies with electronics manufacturing, technology adoption and local investment. North America leads design and defense demand, while Asia Pacific combines 5G infrastructure, automotive electronics and large-volume manufacturing. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Region | Position | Demand profile | Supplier-selection factor |
|---|---|---|---|
| Asia Pacific | Fastest growth | Technology and end-market demand | Qualification, cost and local support |
| North America | Largest / strategic | Technology and end-market demand | Qualification, cost and local support |
| Europe | Strategic | Technology and end-market demand | Qualification, cost and local support |
| South America | Strategic | Technology and end-market demand | Qualification, cost and local support |
| Middle East & Africa | Strategic | Technology and end-market demand | Qualification, cost and local support |
Competitive Landscape
AMD/Xilinx, Intel/Altera, NXP Semiconductors, Texas Instruments, Analog Devices, Qualcomm and specialized RF beamforming vendors form the core competitive landscape. Suppliers differentiate through process capability, product breadth, qualification history, manufacturing scale and technical support. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
The competitive frontier is shifting toward real-time digital beamforming, rf-data-converter integration and mmwave arrays, which raises the value of engineering integration and reduces the importance of price alone in premium segments. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Customer relationships are durable because qualified products become embedded inside longer-lived systems. This creates switching costs but also requires suppliers to maintain lifecycle support and predictable quality. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Competitive tier | Representative companies | Primary differentiation |
|---|---|---|
| Global leaders | AMD/Xilinx, Intel/Altera, NXP Semiconductors, Texas Instruments, Analog Devices, Qualcomm and specialized RF beamforming vendors | Scale, technology and customer qualification. |
| Specialists | Regional and application-focused vendors | Process expertise and niche performance. |
| Emerging suppliers | New regional entrants | Cost, local capacity and diversification. |
Key companies profiled
AMD/Xilinx, Intel/Altera, NXP Semiconductors, Texas Instruments, Analog Devices, Qualcomm and specialized RF beamforming vendors are included in the competitive scope. Their positions differ by product mix, technology capability, geographic manufacturing footprint and customer qualification. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Production Capacity Analysis
Capacity depends on specialized materials, precision manufacturing, automated inspection and qualified final test. Effective output is determined by saleable yield and customer-approved capacity rather than nominal equipment throughput alone. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Supply expansion increasingly requires duplicated qualification across several factories. This is strategically important because customers want resilience without sacrificing consistency, particularly in automotive, data-center, industrial and high-reliability applications. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Dynamics
The market is driven by electronics content growth, system performance requirements and supply-chain modernization. Growth is restrained by capital intensity, qualification cycles and pricing pressure. real-time digital beamforming, RF-data-converter integration and mmWave arrays creates the strongest opportunity for premium value growth. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Drivers
| Driver | Impact | Commercial mechanism |
|---|---|---|
| Technology migration | High | real-time digital beamforming, RF-data-converter integration and mmWave arrays increases product value and complexity. |
| Electronics demand | High | More electronic content increases component consumption. |
| Supply diversification | Medium-High | Customers want qualified capacity across several regions. |
| Automation | Medium | Higher automation improves yield and throughput. |
Technology migration
Customers are adopting more advanced architectures to improve performance, density or efficiency. This raises qualification and process-control requirements and supports premium pricing for technically differentiated suppliers. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Electronics demand
Growth in automotive, data centers, industrial automation and connected devices expands the installed base requiring RF SoC with Integrated DSP for Phased Array Beamforming products. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Supply diversification
Geopolitical and logistics risk encourage multi-site sourcing, creating opportunities for suppliers that can replicate quality across factories. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Automation
Automated process control, inspection and material handling can reduce variation and support larger production volumes. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Market Restraints
| Restraint | Impact | Commercial consequence |
|---|---|---|
| Capital intensity | High | Advanced manufacturing requires specialized equipment. |
| Qualification cycles | Medium-High | Customer approval can take many months. |
| Price pressure | Medium | High-volume segments face continuing cost reduction. |
| Supply-chain risk | Medium | Specialized materials or equipment can be concentrated. |
Capital intensity
New RF SoC with Integrated DSP for Phased Array Beamforming capacity can require significant equipment and qualification investment before revenue scales. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Qualification cycles
Reliability validation and system integration slow supplier switching and delay new-factory ramps. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Price pressure
Suppliers must offset lower average selling prices with yield, automation and differentiated technology. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Supply-chain risk
Dependence on limited upstream suppliers can affect lead times and create the need for strategic inventory or second sourcing. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Market Opportunities
real-time digital beamforming, RF-data-converter integration and mmWave arrays
real-time digital beamforming, RF-data-converter integration and mmWave arrays can expand value per unit and improve system performance. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Regional manufacturing
New qualified capacity can support customers seeking geographic diversification. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Automation and inspection
Better process control can raise yield and reduce lifecycle cost. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Application-specific products
Tailored designs can capture premium niches with stronger qualification barriers. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Supply Chain Analysis
Upstream. Specialized materials, wafers, laminates, metals or process equipment provide the technical foundation. Quality at this stage influences downstream yield and reliability. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Manufacturing. Suppliers use precision process control and automated inspection to produce RF SoC with Integrated DSP for Phased Array Beamforming products within tight tolerances. Yield improvement is a major economic lever. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Integration. Products are qualified inside customer systems where electrical, thermal or mechanical behavior is validated. Design changes can trigger additional testing. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Deployment. Finished products enter electronics, industrial, automotive, data-center or aerospace systems. Lifecycle support and supply continuity determine long-term customer value. Commercial decisions in the RF SoC with Integrated DSP for Phased Array Beamforming market also depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value. Buyers therefore evaluate technical performance together with manufacturability, supply continuity and the cost of maintaining the solution across its intended service life.
Recent Developments in the RF SoC with Integrated DSP for Phased Array Beamforming Market
Developments tracked through September 2026 and limited to events that materially affect technology, capacity, adoption or competition.
- 2026 Beamforming Platform
Analog Devices continues offering highly integrated beamformer ICs and phased-array signal-chain platforms for radar, satellite and mmWave communications. Source - 2026 RFSoC Platform
AMD RFSoC platforms continue combining high-speed RF data converters with programmable logic and DSP resources for radar, communications and phased-array systems. Source - 2026 5G/6G Development
Integrated RF and DSP platforms are increasingly used to reduce latency and power in real-time beam steering for mmWave communications and electronically steered arrays. Source
Report Scope & Segmentation
| Attribute | Scope |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| 2025 market size | USD 0.85 billion |
| 2026 estimated size | USD 0.92 billion |
| 2034 projected size | USD 1.45 billion |
| CAGR (2026–2034) | 6.3% |
| Largest market in 2025 | North America |
| By Type | Sub-6 GHz RF SoC; mmWave RF SoC; Multi-Band RF SoC |
| By Application | 5G/6G Infrastructure; Radar & Defense; Automotive Radar; Satellite Communications; Industrial Sensing |
| By Array Size | Small Array; Medium Array; Large Array |
| By Integration Level | RF + DSP SoC; RF + Beamformer IC; Fully Integrated Antenna-in-Package Platform |
| Companies profiled | AMD/Xilinx, Intel/Altera, NXP Semiconductors, Texas Instruments, Analog Devices, Qualcomm and specialized RF beamforming vendors |
Frequently Asked Questions
What is the RF SoC with Integrated DSP for Phased Array Beamforming market size in 2025?
The global market is valued at USD 0.85 billion in 2025.
What is the market forecast for 2034?
The market is projected to reach USD 1.45 billion by 2034, representing a 6.3% CAGR during 2026–2034. The 2026 market level is USD 0.92 billion.
Which region leads the market?
North America is the largest market, while Asia Pacific has the strongest growth profile.
Which type is most important?
Sub-6 GHz RF SoC is a leading category within the current market structure.
Which applications matter most?
5G/6G Infrastructure and other listed applications are the principal demand segments.
What technology trend matters most?
real-time digital beamforming, RF-data-converter integration and mmWave arrays is a major technology and competitive trend.
Who are the major suppliers?
Major participants include AMD/Xilinx, Intel/Altera, NXP Semiconductors, Texas Instruments, Analog Devices, Qualcomm and specialized RF beamforming vendors.
What drives market growth?
Electronics content, technology upgrades, automation and supply-chain modernization are the main growth drivers.
What limits growth?
Capital intensity, qualification cycles, price pressure and supply-chain concentration are the main restraints.
What will shape the market through 2034?
real-time digital beamforming, RF-data-converter integration and mmWave arrays, regional manufacturing diversification and more automated production will shape the market through 2034.
Research Sources & Evidence Base
View research sources used in this market overview
- AMD — Zynq UltraScale+ RFSoC. Integrated RF data-converter and DSP platform evidence.
- Analog Devices — Beamformer ICs. Current phased-array beamformer and RF integration evidence.
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...