Key Statistics
Key Takeaways
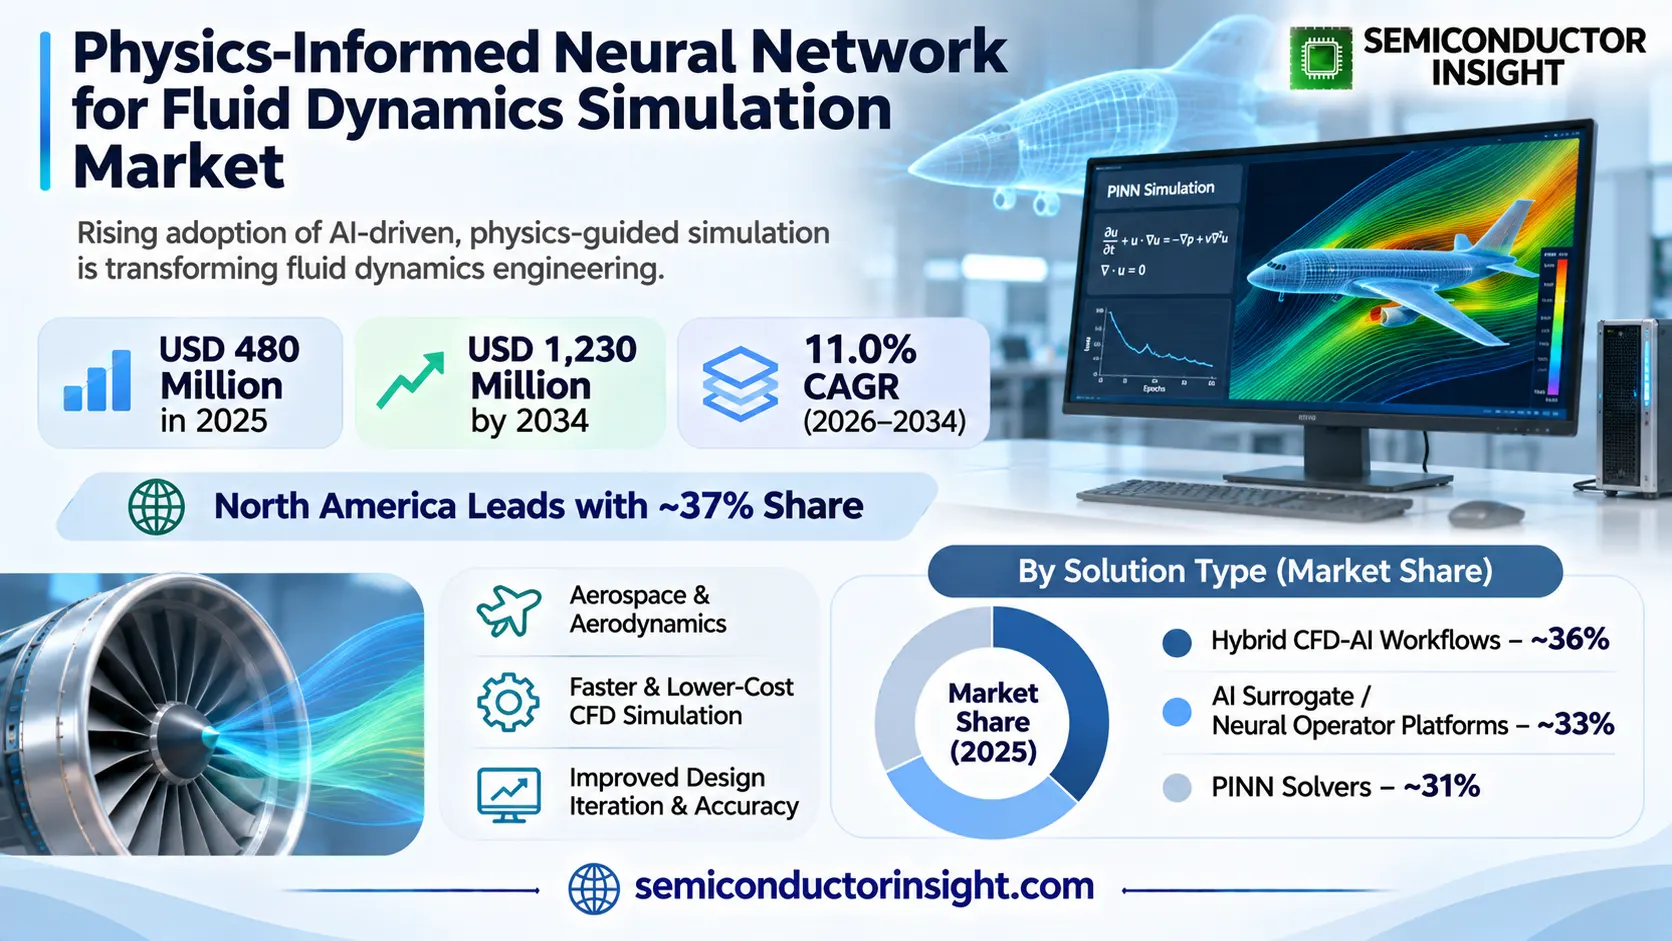
- Market trajectory: The worldwide commercial opportunity reached USD 480 million in 2025 and is forecast to expand to USD 1,230 million in 2034, equivalent to 11.0% compounded annual growth. High-cost computational fluid dynamics workflows give engineering teams an incentive to accelerate parameter sweeps and complex design optimization.
- Software mix: Hybrid CFD-AI workflows account for an estimated ~36% of product revenue because industrial buyers typically retain established solvers as the verification authority. AI surrogate and neural-operator platforms contribute an estimated ~33%, followed by direct PINN solvers at ~31% in specialized physics-constrained computations.
- Demand sectors: Aerospace and defense contribute an estimated ~34% of applications, supported by extensive aerodynamic qualification and expensive simulation campaigns. Automotive demand accounts for an estimated ~24%, while energy and turbomachinery represent ~20% through rotating machinery, combustion and thermal-flow assessment.
- Deployment landscape: Cloud installations capture an estimated ~44% of platform value owing to elastic accelerator access and collaborative engineering. On-premises systems hold about ~30% where intellectual property and controlled data govern deployment; hybrid configurations provide an estimated ~26% of revenue.
- Commercial distinction: A physics-informed solver constrains optimization with physical governing equations or boundary conditions. A purely data-trained CFD emulator may be useful in the same project but should not be represented as a verified equation-constrained PINN. Predictive accuracy, conservation behavior and certification requirements remain decisive purchasing considerations.
Physics-Informed Neural Network for Fluid Dynamics Simulation Market Overview
Physics-informed neural network for fluid dynamics simulation market generated USD 480 million in 2025 and is projected to reach USD 1,230 million by 2034, advancing at 11.0% CAGR over 2026–2034. North America leads with an estimated ~37% share, reflecting aerospace engineering, accelerated-computing resources and demand for simulation automation.
Physics-informed neural networks represent a class of machine-learning methods that train predictive models while imposing selected physical equations, conservation relationships or boundary conditions. In fluid dynamics they can infer pressure or velocity fields, estimate unknown boundary parameters and support inverse problems where direct observations are incomplete. They complement conventional computational fluid dynamics, whose numerical discretization remains central to high-fidelity engineering validation. Model suitability depends on the flow regime, dimensionality and the quality of physical constraints.
The commercial boundary encompasses PINN solver software and associated engineering implementation, AI neural-operator or surrogate platforms marketed for fluid-flow simulation, and hybrid CFD-AI toolchains that combine physical simulation with learned acceleration. Deployment subscriptions, specialist integration and supported platform use belong within this product mix. The scope excludes general-purpose GPU chip sales, unrelated generative AI, physical wind tunnels and CFD-only licensing when no physics-informed AI capability is supplied. Research code without commercial support can influence adoption without creating direct software revenue.
Industrial procurement follows demonstrable engineering value rather than neural-network architecture alone. A useful accelerated workflow must reduce the cost of a repeated design question while preserving checks on mass, momentum, energy and boundary behavior. NVIDIA PhysicsNeMo includes physics-informed and neural-operator methods; Siemens Simcenter PhysicsAI and Ansys SimAI broaden the market for trained simulation surrogates. Buyers need to verify whether an offered product contains explicit equation constraints or primarily learns from examples.
Technical limitations make the transition to production uneven. High-Reynolds-number turbulence, complex moving meshes and irregular boundary conditions can challenge learning stability or transfer across geometries. Academic toolkits such as DeepXDE and MATLAB examples lower prototyping barriers, yet regulated aerospace or industrial programs require test cases, repeatable validation records and accountable software maintenance. Commercial acceptance improves when an engineering team can compare AI outputs directly with measured data and a trusted baseline CFD solver.
Segment Analysis: By Type
The market divides into PINN Solvers, AI Surrogate / Neural Operator Platforms, and Hybrid CFD-AI Workflows. Hybrid workflows represent an estimated ~36% of current value because they integrate learned approximations with existing computational fluid dynamics validation. Standalone neural-operator and surrogate platforms capture about ~33%; specialist PINN solvers contribute approximately ~31%. The boundaries reflect supported commercial offerings rather than a claim that every learned surrogate enforces physics equations.
| Type | Function | Market position |
|---|---|---|
| PINN Solvers | PINN solvers optimize a neural representation of a flow field against governing differential equations, initial conditions and observed or prescribed boundaries. They can infer coefficients, estimate internal states from sparse sensors and address inverse questions that are difficult to formulate as an ordinary numerical calculation. Performance depends on loss weighting, sampling, optimizer selection and treatment of sharp gradients or turbulent structures. | Estimated ~31% share. Specialist use is strongest where an identifiable physical model and sparse observations provide useful constraints. Adoption can be constrained by optimization cost and poor convergence on stiff, multiscale problems. Engineering buyers therefore pay for tested workflows, solver integration and documented uncertainty instead of assuming that open research libraries automatically satisfy reliability or runtime requirements. |
| AI Surrogate / Neural Operator Platforms | Neural operators and data-driven surrogates approximate relationships between flow parameters, shapes and response fields after training across a family of simulations. They can accelerate repeated scenario evaluations and enable interactive engineering exploration. Physical laws may be incorporated during training or through coupling, but a model trained solely to imitate data is not automatically a physics-informed neural network. | Estimated ~33% share. Strong commercial demand stems from design-space exploration where the same engineering discipline repeatedly evaluates related geometries and operating points. Neural operator training often requires a high-quality simulation database and careful control over extrapolation. Customers value a clear operating envelope, error monitoring and rapid inference more than a generic claim of replacing full CFD for every configuration. |
| Hybrid CFD-AI Workflows | Hybrid workflows keep conventional finite-volume or other established numerical solvers in the engineering loop while using AI for initial conditions, turbulence closures, rapid surrogates or optimization decisions. This design can route difficult geometries or out-of-domain results back to full CFD. Physical residual screening and automated validation can mitigate some risks of a fully learned approach. | Largest type at an estimated ~36% share. Engineering enterprises favor transitional deployments compatible with existing simulation investments, certification processes and compute environments. Repeatable acceleration rather than wholesale solver replacement shapes purchasing. Hybrid solutions typically require connector maintenance, domain-specific training data and controls that preserve access to validated physics results for design approval. |
Secondary segmentation: delivery environment and customer group
Deployment architecture and buyer organization alter both software economics and validation requirements. Cloud systems facilitate accelerator access for large training jobs, while on-premises installations address protected design data and export restrictions. Engineering enterprises generally commission the largest production workloads, followed by simulation software vendors embedding AI in their platforms. Research institutions expand algorithm capability, whereas digital-twin operators prioritize recurrent updates from real-world sensors.
| Axis | Members | Commercial role |
|---|---|---|
| Deployment | Cloud · On-Premises · Hybrid | Cloud accounts for an estimated ~44% of commercial value as training and repeated inference use scalable processing capacity. On-premises represents approximately ~30% where regulated design assets demand direct control. Hybrid deployments contribute an estimated ~26%, allowing a controlled engineering environment to connect with burst computing. |
| End User | Engineering Enterprises · Simulation Software Vendors · Research Institutions · Digital Twin Platforms | Engineering enterprises contribute an estimated ~43% because they own substantial product design and qualification workloads. Simulation software vendors account for roughly ~22%, with research institutions near ~21%. Digital-twin platforms represent about ~14% where sensor-informed flow predictions need repeated operational updates. |
Segment Analysis: By Application
Major applications are Aerospace & Defense, Automotive, Energy & Turbomachinery, HVAC & Built Environment, and Marine & Process Industries. Aerospace and defense represent an estimated ~34% of revenue, followed by automotive at ~24%. Energy and turbomachinery contribute ~20%; HVAC has an estimated ~13%, and marine and process operations comprise the remaining ~9%. Physical testing expense and repeat-design frequency affect the pace of purchasing in each field.
| Application | Demand characteristics |
|---|---|
| Aerospace & Defense | Estimated ~34% share. Airframe drag, thermal management, propulsion flows and operational envelope studies require many high-cost simulations. Physics-constrained reduced-order predictions can shorten early concept screening, but flight qualification continues to need validated numerical analysis, ground testing and rigorous documentation. Restricted project data and geometry sensitivity favor carefully controlled training pipelines. Buyers invest where repeatable acceleration can reduce iteration time without weakening aerodynamic verification. The 2026–2034 forecast hinges on repeat design-analysis workloads. |
| Automotive | Estimated ~24% share. Vehicle development calls for aerodynamic drag studies, cabin airflow, underhood cooling and battery thermal control. Related platform variants can reuse trained representations if the geometry and operating conditions remain sufficiently similar. A design team must still test performance on unseen body shapes and flow regimes, particularly when separation or transient thermal effects are influential. Integration into established product lifecycle workflows helps translate faster evaluation into engineering value. Over 2026–2034, product variant analysis offers continued commercial potential. |
| Energy & Turbomachinery | Estimated ~20% share. Turbine blade passages, pumps, compressors, heat exchangers and energy infrastructure require complex rotating and turbulent flow assessments. A trained prediction system can support condition screening or repeated operating-point selection, yet must respect boundary conditions and conservation behavior in high-stakes equipment. Commercial benefit is strongest when repeated evaluations use similar physical configurations and sound reference data are available for validation. For 2026–2034, operating-point optimization is one plausible route to paid adoption. |
| HVAC & Built Environment | Estimated ~13% share. Buildings, ventilation systems and data-center cooling create repeated questions about air movement, heat transfer and equipment placement. Physics-constrained surrogates can support rapid analysis of operating schedules or layout changes while conventional CFD handles difficult geometry or rare events. Data availability and computing budgets vary significantly between commercial facilities, making deployment simplicity and transparent error reporting important sales considerations. During 2026–2034, cooling reliability could sharpen buyer interest. |
| Marine & Process Industries | Estimated ~9% share. Naval hydrodynamics, mixing systems, chemical process equipment and marine propulsion introduce multiphase or highly constrained flow regimes. These applications can offer strong value from accelerated parameter studies, but some governing phenomena are particularly difficult to approximate with trained networks. Users often prioritize integration with trusted process or hydrodynamic models and require explicit out-of-range alerts rather than relying solely on low inference latency. Through 2026–2034, specialist projects will likely favor careful physical verification. |
Physics-informed methods can have different levels of maturity within an application label. An aerodynamic engineer may use a rapid surrogate to screen variants and a separate physics-residual network to estimate poorly observed boundary states. A process engineer may instead require a coupled model for flow and heat transfer. Commercial assessment should distinguish the mathematical constraint, the training dataset, the allowable operating domain and the documented downstream verification step.
Regional Analysis
North America is the leading regional market with an estimated ~37% of 2025 spending on physics-informed fluid simulation. Europe contributes approximately ~28%, Asia-Pacific ~23%, the Middle East and Africa ~7%, and South and Central America ~5%. Aerospace, industrial software procurement and access to high-performance computing explain differences in commercial activity. Training and inference may be hosted remotely, so the contracting customer location does not necessarily reveal the physical location of the computing cluster.
Where is physics-informed fluid dynamics technology finding repeatable commercial workflows?
The geography of adoption depends on engineering simulation budgets, available specialist talent, access to validated CFD reference data and willingness to deploy experimental AI methods in production. North American accelerator and aerospace ecosystems support platform development, while European software and manufacturing firms emphasize integration with established engineering tools. Asia-Pacific combines a large industrial design base with growing AI infrastructure. Emerging regions often begin with universities, external simulation services or specific energy and infrastructure projects rather than a full local software ecosystem.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Third (~23%) | Strong (~11.3% CAGR; 2026–2034) | Automotive electronics and industrial AI engineering | Training talent and validated CFD integration |
| North America | Largest (~37%) | Strong (~10.6% CAGR; 2026–2034) | Aerospace, GPU platforms and simulation software | Benchmark validation and secure project data |
| Europe | Second (~28%) | Fast (~11.6% CAGR; 2026–2034) | Industrial CFD, digital engineering and mobility | Integration with installed solver workflows |
| Middle East & Africa | Developing (~7%) | Positive (~10.1% CAGR; 2026–2034) | Energy operations and advanced research projects | Qualified staff and deployment support |
| South & Central America | Developing (~5%) | Measured (~10.5% CAGR; 2026–2034) | Energy, industrial design and academic CFD | Cloud access and implementation economics |
Key Physics-Informed Neural Network for Fluid Dynamics Simulation Manufacturers and Competitive Landscape
Competition in physics-informed fluid dynamics software spans specialist machine-learning toolchains, established computer-aided engineering vendors, accelerator ecosystem providers and simulation implementation partners. NVIDIA PhysicsNeMo and open frameworks supply important model-building tools; Siemens Simcenter and Ansys offer industrial AI-accelerated simulation products. MathWorks provides engineering tools and documented PINN methods. Commercial overlap varies: some platforms train explicitly against governing equations, while others use simulation-generated examples to create rapid surrogates. Customers should compare actual product capabilities rather than treating all engineering AI as identical.
NVIDIA positions PhysicsNeMo as an open framework for physics-based machine learning, with examples covering fluid problems and neural-operator applications. It broadens developer access to accelerator-backed training infrastructure, but open framework usage does not necessarily represent standalone licensed solver revenue. Engineering firms may incur costs for GPUs, hosting, integration and maintained commercial software. The supply ecosystem also includes university-developed code, which often advances numerical methods faster than a traditional software product cycle.
Siemens expands the industrial distribution channel through Simcenter CFD and PhysicsAI, while Ansys supports learned prediction workflows through SimAI. These suppliers benefit from established industrial accounts and integration points with verified solvers. The distinction between a data-trained surrogate and a PINN with explicit equation residuals is technically meaningful; an industrial package may offer one, the other or a hybrid pipeline. Buying decisions hinge on whether the model can be validated over the intended geometry and operating envelope.
MathWorks provides differentiable computing, numerical PDE workflows and practical tutorials for physics-informed neural network experiments, reducing the cost of adoption within engineering teams already using its environment. Open projects such as DeepXDE influence developer practice but should not be treated as directly comparable to fully supported enterprise software subscriptions. Dassault Systèmes, COMSOL and other multiphysics providers are important adjacent competitors where AI acceleration interfaces with established numerical engineering, subject to confirmation of the specific physics-learning function on offer.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Engineering platform vendors | Siemens Digital Industries Software; Ansys (Synopsys); MathWorks; Dassault Systèmes | Enterprise vendors compete through maintained solver integration, engineering data connections, account support and validation pipelines. The most attractive customers already operate high-value simulation workflows that can be accelerated by a carefully bounded learned model. A product feature marketed as AI acceleration must be assessed for actual equation constraints and support levels before it is compared with a specialist PINN solver. |
| Physics-machine-learning frameworks | NVIDIA PhysicsNeMo; DeepXDE; specialist neural-operator developers | Toolkits allow teams to construct PINN or operator-learning models with custom governing equations and accelerator execution. They support research and the creation of specialized commercial offerings, but availability of source code does not equal a standard enterprise support commitment. Commercial differentiation comes from validated industry workflows, stable numerical optimization and integration services layered around model training. |
| Implementation and CFD ecosystem | CFD consulting firms; multiphysics application engineers; cloud HPC providers | Service providers translate engineering objectives into workable training domains, reference simulations and deployment controls. Cloud and on-premises compute operators support intensive training but sell different underlying products. A buyer evaluating this category needs evidence of conservation testing, operating-range coverage and handoff to a trusted high-fidelity method when predictions become uncertain. |
Key companies profiled
- NVIDIA Corporation (PhysicsNeMo framework)
- Siemens Digital Industries Software (Simcenter PhysicsAI)
- Ansys / Synopsys (SimAI software)
- MathWorks (PINN engineering workflows)
- Dassault Systèmes (adjacent simulation ecosystem)
- COMSOL (multiphysics simulation ecosystem)
- DeepXDE development community (open-source toolkit)
- Specialist CFD and physics-ML integration providers
Physics-Informed Neural Network for Fluid Dynamics Simulation Production Capacity Analysis
Production capacity in physics-informed fluid dynamics simulation means the ability to prepare reference datasets, train numerical representations, validate physical behavior, maintain solver integrations and deliver reliable inference for industrial workloads. Unlike a fabricated electronic component, the scarce production resources are expert researchers, CFD computational capacity, accelerators, high-quality validation data and engineering software support. Commercial scalability depends on how often a trained model can be reused across design variations without violating its verified operating limits.
A production workflow begins with a well-defined fluid problem, physical equations, geometry, boundary conditions and the range of parameters that the customer expects to explore. Teams either create a physics-residual loss, collect validated CFD examples for surrogate training or combine both approaches. Training requires optimization stability and repeated checks on conservation errors. For incompressible and compressible applications, important quality targets can include mass balance, wall behavior and correct pressure or velocity trends under changed operating conditions.
Capacity constraints differ between stages. A large GPU cluster can accelerate some neural training workloads, while high-fidelity CFD reference generation may remain limited by conventional solver scaling and license capacity. A short inference time does not ensure useful throughput if every new design needs extensive retraining. Platform vendors therefore build reusable APIs, standard data conversions and automated benchmark suites, so engineering customers can move from a successful pilot to repeatable design studies without manually rebuilding the model each time.
Commercial deployment must preserve engineering accountability. Versioned training data, model configuration, benchmark results and secure access are essential when predictions inform expensive machinery or safety-sensitive products. A purely neural prediction outside its learning domain may look smooth even when physically incorrect. Mature offerings mitigate this through confidence checks, periodic recalibration, reference CFD spot checks and workflows that escalate difficult cases for full numerical treatment. These operational features can be as valuable as a lower computational time per prediction.
Physics-Informed Neural Network for Fluid Dynamics Simulation Market Dynamics: Drivers, Restraints and Opportunities
The key growth forces are the economics of repeated numerical simulation, development of GPU-oriented physics learning and the spread of AI within mainstream engineering platforms. However, numerical instability, difficulty generalizing to unseen flow regimes and limited validated data can hold back adoption. The contributions below describe opposing forces shaping the net growth forecast; their importance changes as users move from exploratory engineering to repeatable industrial deployment. A successful product must combine computational speed with measurable physical reliability.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Cost pressure on repeated CFD design sweeps | High | +4.20% | High | High | High |
| GPU and physics-ML software maturation | Medium-High | +3.50% | High | High | Medium |
| AI integration within engineering platforms | Medium-High | +2.90% | Medium | High | High |
| Aerospace and automotive optimization needs | Medium | +2.50% | Medium | High | High |
| Sensor-informed digital twin requirements | Low-Medium | +1.80% | Medium | Medium | High |
| Others (cloud access and research tools) | Low | +0.60% | Low | Medium | Medium |
High-cost CFD iteration creates strong productivity incentives
A detailed flow simulation can take substantial computing time, particularly when engineers repeat the calculation for many geometric or operating choices. A trained physics-aware model may screen alternatives much faster after up-front training expense. The economic advantage is largest when the same learning domain supports many similar evaluations. Buyers still need to budget for reference results and uncertainty checks so that accelerated exploration does not compromise later engineering approval.
Specialized acceleration software lowers development barriers
Frameworks such as PhysicsNeMo and documented PINN training examples allow research and engineering teams to experiment with conservation losses, neural operators and different optimizers. Accelerator access increases the size of models and datasets that can be explored. This makes commercial pilots more accessible, although trained-model quality still depends on numerical insight. A useful support ecosystem turns a technical demonstration into an maintainable application with clear boundaries, logs and reproducible validation.
Simulation vendors bring AI to existing industrial customers
Established CAD and CFD suppliers can incorporate learned predictions into workflows familiar to engineering organizations. Siemens PhysicsAI and Ansys SimAI show how neural acceleration can be distributed alongside conventional engineering software. This shortens procurement and integration friction for enterprises already holding simulation data and licenses. Industry adoption should nevertheless distinguish physics-constrained optimization from surrogate inference, especially when safety reviews depend on explicit governing-equation satisfaction.
Operational flow models extend the value beyond design offices
Monitoring airflow, fluid circulation and thermal behavior in operating equipment offers potential recurring use for learned physical representations. Sensor measurements can update boundary information, while a constrained model estimates conditions that are difficult to measure directly. This can support digital twins for industrial facilities or rotating machinery. Deployment remains attractive only when maintenance teams can detect drift, refresh the model and compare inferred states against reliable reference data.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Training stability and turbulent flow complexity | High | -1.70% | High | High | Medium |
| Unverified extrapolation and certification limits | Medium-High | -1.20% | High | High | Medium |
| Reference-data and specialist talent requirements | Medium | -0.90% | High | Medium | Medium |
| Others (legacy integration and switching cost) | Low | -0.70% | Medium | Medium | Low |
Turbulence can defeat otherwise efficient network optimization
Strong gradients, boundary layers and complex three-dimensional turbulent structures can be difficult for a learned model to represent accurately. Physics-residual losses do not guarantee convergence, especially when different equations or regions contribute gradients on very different scales. Adding more collocation points or network parameters may increase training expense without solving the underlying optimization problem. These limitations restrict commercial usefulness for the most demanding flows and motivate hybrid solvers.
Extrapolation risk slows acceptance in consequential engineering
A neural prediction can provide a plausible field far outside the range on which the model was trained or checked. If an organization treats that output as a certified high-fidelity result, design errors could follow. Aerospace, energy and industrial safety programs therefore need reproducible tests, clear physical acceptance criteria and routes back to conventional numerical solutions. Such controls take time and can reduce near-term software adoption even when early demonstrations appear impressive.
Engineering expertise and reliable reference cases remain scarce
Building a successful physics-informed flow system requires proficiency in numerical fluid mechanics, machine-learning optimization and engineering data management. Industrial reference datasets may contain proprietary geometry or limited sensor coverage, complicating model training and independent validation. Small users can face high implementation costs before any inference benefit is realized. Open research libraries help with prototypes, but do not eliminate the need for specialized domain staff and production software maintenance.
MARKET OPPORTUNITIES
Physics-guided inverse estimation for sparse sensor systems
Industrial operators often know governing relationships but can only observe selected points within a fluid system. Equation-constrained learning may infer missing boundary states, effective coefficients or internal conditions when observations and model assumptions are sufficiently informative. This creates an opportunity beyond conventional design optimization, particularly for asset monitoring. The commercial product must expose uncertainty and identify cases where sparse measurements cannot uniquely determine the desired physical quantities.
Validated hybrid pipelines for established CFD customers
Numerical software customers may be more willing to buy a learning component that works alongside their trusted solver than an entirely new simulation stack. A hybrid pipeline can use fast predictions for broad screening, then reserve conventional CFD for unusual or certification-sensitive candidates. Vendors that automate the switching criterion and preserve engineering audit trails can compete on total workflow efficiency rather than raw neural inference speed alone.
Targeted accelerator cloud services for specialist teams
Smaller engineering groups may avoid purchasing permanent high-performance computing capacity if a cloud service provides the training environment and secure data workflow required for occasional projects. Subscription and professional-service products can package solver preparation, reference benchmarks and managed model deployment. The opportunity depends on data governance, budget predictability and the ability to rerun validated models economically when a product design changes.
Physics-Informed Neural Network for Fluid Dynamics Simulation Supply Chain Analysis
The value chain begins with physical equations and trusted engineering inputs, then passes through CFD reference simulation, neural architecture selection, accelerated training, validation and deployment into industrial design environments. Revenue may be realized through specialist software licenses, cloud platform subscriptions, engineering services and supported integrations. Semiconductor accelerators and conventional CFD tools remain essential enabling inputs, but their entire sales values are not identical to the revenue of physics-informed flow-simulation products.
Physics definitions and observed inputs. An engineering team establishes equations, fluid properties and prescribed boundary conditions before selecting the learning method. For inverse studies it must also decide which coefficients are identifiable from available measurements. Poorly specified physics can produce convincing but misleading learned fields. This first stage is often carried out by domain experts or consultants and creates the technical requirements for later model licensing and integration.
Reference data and compute infrastructure. Conventional solvers and physical observations provide test cases for training and verification, while GPUs and optimized software support demanding neural optimization. The mix differs between equation-residual PINNs and neural-operator platforms that rely on a large generated simulation library. Cloud providers enable variable capacity and on-premises systems support confidential research. These infrastructure purchases are inputs to a software workflow rather than interchangeable measures of market revenue.
Model quality assurance and reproducibility. Developers evaluate residual conservation errors, prediction deviations, boundary behavior and sensitivity to operating variables. A model that succeeds on a familiar benchmark may perform poorly on a different geometry or turbulent regime. Product teams must preserve training versions, test datasets and acceptance thresholds, so customers can understand exactly where acceleration is warranted. Independent comparison with established CFD remains valuable for consequential design decisions.
Enterprise delivery and long-term maintenance. Simulation vendors, integrators and internal engineering software groups connect trained representations to CAD data, project management, access controls and production pipelines. A valuable commercial service supports customer changes, new solver releases and model refreshes as physical conditions evolve. Procurement teams assess service continuity and support responsibilities, which can favor suppliers with existing industrial relationships even when an open research project has strong raw numerical performance.
Recent Developments in the Physics-Informed Neural Network for Fluid Dynamics Simulation Market
- November 2026 OPEN SOURCE
DeepXDE released an updated version of its scientific machine-learning framework, maintaining access to physics-informed and differential-equation learning utilities. Research and engineering users can use the project to prototype constrained models, but they must separately verify performance on their industrial flow cases. Framework updates can help maintain developer tooling without establishing direct license sales for a particular end-market region. Source - August 2026 SOFTWARE
NVIDIA issued PhysicsNeMo release documentation covering enhancements to its physics-machine-learning toolchain. The update supports a developer ecosystem working with accelerated numerical models and fluid-related learning tasks. Commercialization depends on the fit of these capabilities with verified engineering workflows and on the software or services adopted by paying customers, rather than the number of publicly accessible sample notebooks. Source - July 2026 SIMULATION
Siemens highlighted summer 2026 Simcenter engineering software developments, including AI-related workflow updates and faster simulation capabilities. This illustrates the investment of established industrial suppliers in connecting learned and numerical analysis methods. Companies still need to establish whether a specific AI feature enforces governing flow equations or instead provides a data-trained approximation within a broader verified toolchain. Source - May 2026 AI PLATFORM
Siemens announced Simcenter PhysicsAI improvements for AI-based simulation acceleration. The release emphasized leveraging engineering models and GPU-enabled workflows to shorten repetitive design evaluations. The value proposition is relevant to hybrid CFD-AI commercialization, although a learned response representation must be evaluated separately from a PINN trained explicitly on differential-equation residuals. Source - 2026 PRODUCT
Ansys detailed its AI simulation capabilities, including the SimAI portfolio for rapid physics prediction from training examples. The software offers an example of industrial distribution for neural surrogates. Engineering buyers should verify data needs and trust boundaries before using its output in design sign-off; a fast generated field is not by itself evidence of physical conservation compliance. Source - 2025 RESEARCH
A published scientific study examined challenges in applying learned approaches to difficult three-dimensional turbulent-flow problems. Turbulence remains an important test of robustness for physical learning systems and an obstacle to universal replacement of standard CFD. Progress in this area could ultimately expand the range of commercially useful tasks, but validation requirements remain substantial. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2020–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2020–2024 |
| Market Size 2025 | USD 480 million |
| Market Size 2026 | USD 532.9 million |
| Market Size 2034 | USD 1,230 million |
| Growth Rate | CAGR of 11.0% from 2026–2034 |
| Unit | Value (USD Million) |
| Segmentation | By Type, By Application, By Deployment, By End User, and By Region |
| By Type | PINN Solvers · AI Surrogate / Neural Operator Platforms · Hybrid CFD-AI Workflows |
| By Application | Aerospace & Defense · Automotive · Energy & Turbomachinery · HVAC & Built Environment · Marine & Process Industries |
| By Deployment | Cloud · On-Premises · Hybrid |
| By End User | Engineering Enterprises · Simulation Software Vendors · Research Institutions · Digital Twin Platforms |
| By Region | Each region analysed by Type, Application and Country Asia-PacificChina, Japan, South Korea, India, Taiwan and Rest of Asia-Pacific North AmericaUnited States, Canada and Mexico EuropeGermany, France, United Kingdom, Netherlands and Rest of Europe Middle East & AfricaUnited Arab Emirates, Saudi Arabia, South Africa, Israel and Rest of MEA South & Central AmericaBrazil, Argentina, Chile, Colombia and Rest of South & Central America |
| Key Companies Profiled | NVIDIA PhysicsNeMo, Siemens Simcenter PhysicsAI, Ansys SimAI, MathWorks, Dassault Systèmes, COMSOL, DeepXDE, engineering implementation providers |
| Customization Scope | Free report customization (equivalent to up to 4 analyst working days) with purchase. Addition or alteration to country, regional and segment scope. |
Frequently Asked Questions
What is the size and growth rate of this market?
The worldwide product and service opportunity amounted to USD 480 million in 2025 and is expected to reach USD 1,230 million in 2034, a 11.0% CAGR across 2026–2034. The market addresses software and technical services that apply physics-informed or closely integrated learned methods to fluid-flow simulation. Demand reflects the cost of conventional CFD campaigns, growing AI tool availability and the requirement for documented engineering performance.
What makes a fluid dynamics neural network physics-informed?
A physics-informed neural network includes equations, boundary conditions or other physical requirements in its training objective rather than learning only a relationship between example inputs and outputs. For fluid problems, constraints can derive from conservation of mass, momentum or energy. A trained model must still be tested, since adding physical losses does not guarantee a correct numerical solution. Engineering acceptability depends on residual quality, flow regime and independent reference comparisons.
Which product type has the largest commercial position?
Hybrid CFD-AI workflows lead with an estimated ~36% of product revenue because industrial engineering teams can accelerate repeated design questions while preserving conventional solvers for verification. Neural-operator and surrogate platforms represent approximately ~33% of value, while direct PINN solvers account for an estimated ~31%. A numerical surrogate is not necessarily governed by differential-equation losses; the defining constraints and accepted use cases need to be established for every product.
Which application creates the most demand for physics-informed CFD?
Aerospace and defense account for an estimated ~34% of application revenue, reflecting costly aerodynamic and propulsion evaluations, demanding physical test requirements and substantial engineering computing resources. Automotive development follows at an estimated ~24% with repeated external airflow and thermal studies. Energy and turbomachinery contribute around ~20%, including rotating equipment and process flow challenges. The commercial benefit depends on repeated validated tasks rather than the number of projects alone.
Why is North America the leading regional market?
North America has an estimated ~37% share, supported by aerospace research institutions, major software development organizations and access to AI accelerator infrastructure. Europe follows near ~28% through industrial simulation and automotive engineering, with Asia-Pacific around ~23%. A commercial software contract can be placed where the project team operates while training jobs run in a different geography, so customer spending and physical compute location need not coincide.
Do AI fluid-flow models replace traditional CFD solvers?
For many engineering applications they complement rather than replace high-fidelity simulation. A neural model may evaluate familiar variants rapidly, but the most difficult turbulence, transients or newly introduced geometry can require full numerical solutions. Hybrid workflows can automatically identify questionable predictions and route them to established solvers. Teams should assess conservation behavior and benchmark accuracy within a defined operating envelope before incorporating outputs into high-consequence design decisions.
What share of demand uses cloud deployment?
Cloud services represent an estimated ~44% of platform revenue because customers can rent accelerators and distribute intensive training jobs without purchasing the entire compute infrastructure. On-premises installations account for approximately ~30% where protected data or controlled operations are important. Hybrid deployments hold around ~26%, combining local engineering workflows with optional external compute. Total project cost also includes preparation, reference simulation, validation and ongoing model maintenance.
Which organizations are prominent in the competitive environment?
NVIDIA supplies PhysicsNeMo, a framework for physics machine learning; Siemens and Ansys market AI-enhanced industrial simulation platforms, and MathWorks documents equation-informed neural methods within engineering workflows. Open projects such as DeepXDE support development and research. These offerings are not all equivalent: some solve physics-constrained equations directly, others train rapid predictions from CFD examples, and enterprise systems may combine both. Procurement should focus on documented behavior for the exact flow task.
What technical problems slow industrial implementation?
Training can become unstable for turbulent, multiscale or geometry-dependent flow, and a smooth prediction can still violate conservation relations. Reference cases may be expensive to create or limited by confidential project data. Engineers need expertise in both CFD and machine-learning optimization, plus tests for extrapolation and model drift. Safety-sensitive programs can also require formal verification records. These demands increase pilot duration even when individual neural predictions execute quickly.
Where are the strongest future opportunities?
Promising use cases include inverse estimation from sparse industrial sensors, rapid engineering parameter screening, digital-twin state prediction and software services that couple learned models with verified CFD. The most valuable deployments identify a bounded family of physical problems that can be evaluated repeatedly. Providers capable of automating acceptance checks and fallback simulation may win broader industrial trust. A lower computation cost alone is insufficient if unreliable predictions create additional redesign or verification work.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF