Key Statistics
Key Takeaways
- Measured growth: The 2024 publisher anchor of USD 239 million implies a 2025 estimate of USD 247 million and a 2034 value of USD 338 million on a constant endpoint-based growth path.
- Technology mix: Fiber Bragg Grating sensors lead the modeled type allocation with ~46% of 2025 revenue, supported by multiplexed readings and mature packaged strain-gauge families.
- Demand concentration: Civil Engineering holds a publisher-indicated ~35% application share, while Energy represents a modeled ~25% as monitoring installations extend into pipelines and turbines.
- Geographic leader: North America accounts for an estimated ~36% of sales; Asia-Pacific is modeled to grow ~4.8% annually against ~3.0% for North America.
- Measurement challenge: Optical interrogation must distinguish mechanical loading from temperature changes; installation quality and calibration traceability materially affect practical sensor selection.
Optical Strain Sensor Market Overview
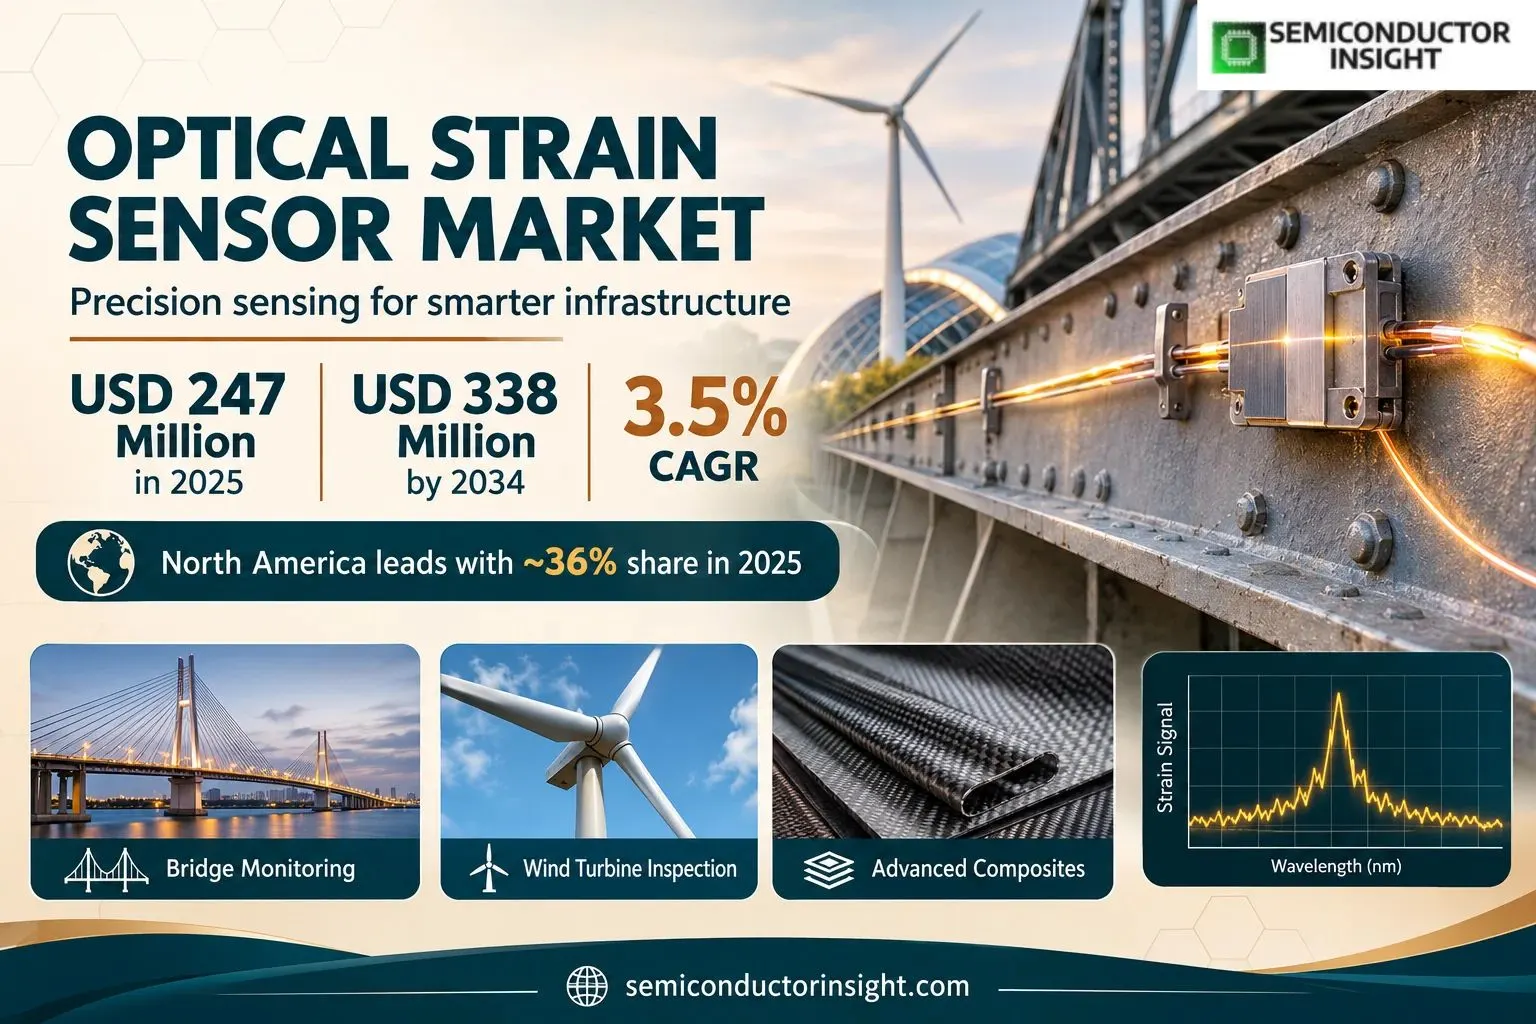
Optical strain sensor market is estimated at USD 247 million in 2025 and projected to reach USD 338 million by 2034, a calculated 3.5% CAGR over 2026–2034. North America retains the leading modeled share at ~36% in 2025. Bridge monitoring, wind-turbine inspection, industrial asset diagnostics and advanced composites create distinct purchasing requirements for optical strain sensing assemblies.
Optical strain measurement interprets a change in light wavelength, phase or backscatter as evidence of deformation. A bonded point gauge measures a localized mechanical response, whereas optical fibers installed along a beam can produce measurements at many positions. The physical packaging matters: a grating bonded with adhesive to a steel component experiences a different transfer path than an element embedded inside a composite laminate. These distinctions give buyers several technically defensible choices rather than a single universal sensor configuration. The endpoint-implied 3.5% trajectory reflects revenue rather than installed sensing-point counts.
The revenue boundary covers finished fiber-optic strain transducers, packaged gratings and optical strain sensing arrangements described by the published Type, Application and End User classifications. Sensors attached to interrogators remain within scope when supplied as strain measurement products. Conventional metallic resistance gauges, general-purpose communications cable without sensing functionality and complete structures containing the sensors are excluded. Instrument interoperability, connector durability and installation engineering influence selling prices without converting the value of the monitored bridge or turbine into sensor market revenue.
North American purchasers use optical instrumentation in infrastructure inspection, aerospace research and energy equipment qualification. A service organization managing bridges generally values durable installations and interpretable long-term time series. An aerospace laboratory may prioritize dense spatial resolution on a composite panel, while an energy operator can need a safe non-electrical measurement method near harsh equipment. The application-led diversity also explains why sensor suppliers often sell hardware together with compatible interrogator specifications and training rather than relying on a commodity-gauge price comparison.
FBGS describes draw-tower gratings written during fiber manufacture and immediately protected by coatings, creating strong continuous sensor arrays. The company markets embedded GFRP assemblies for structures, and Luna offers both distributed Rayleigh-based instruments and multipoint FBG hardware. Packaging and channel selection can influence attainable sensing length, resolution and field serviceability. A grating network may span many instruments in an asset, but its wavelength plan, protection and temperature correction are decided before construction work makes physical access expensive.
Measurement uncertainty is a separate commercial consideration from sensitivity. NIST has documented how very small uncertainties in reflected Bragg wavelength translate into strain measurement differences, while recent studies describe the difficulty of separating thermal and mechanical effects. A monitoring operator must understand the sensor bond, compensation strategy and acquisition system before inferring structural damage from a long-term trend. These engineering obligations support demand for capable interrogation and data interpretation, even where individual sensing elements are inexpensive.
Segment Analysis: By Type
The publisher divides optical strain sensors into Fiber Bragg Grating (FBG), Fabry-Perot Interferometric, Long Period Fiber Grating (LPFG), Michelson Interferometric and Others. The modeled 2025 revenue mix assigns these groups ~46%, ~21%, ~12%, ~9% and ~12%, respectively. The categories describe optical measurement principles rather than merely the sensing cable material, and the range of mechanical installations makes supplier qualification important.
| Type | Underlying measurement considerations | Modeled 2025 market position |
|---|---|---|
| Fiber Bragg Grating (FBG) | An inscribed grating reflects a narrow wavelength band that shifts as the fiber experiences deformation or temperature change. Multiple different Bragg wavelengths can occupy one optical path, which enables distributed-point measurement networks without running an individual wire to every gauge. HBK and FBGS describe fiber sensors that are bonded, welded or embedded according to the asset geometry and strain-transfer requirements. | FBG holds an estimated ~46% of type revenue, with a modeled ~4.1% CAGR. Widely catalogued surface and embedded devices support procurement for civil assets, renewable structures and composite testing. Interrogator compatibility, assembly protection and total installed channel costs influence commercial pricing more than the bare fiber length alone. |
| Fabry-Perot Interferometric | A Fabry-Perot element responds to changes in optical cavity length and interference, which can be engineered for compact point sensing where physical dimensions matter. Designers must control reflectivity, gap stability and thermomechanical behavior to obtain reproducible readings. In specialized testing the device may be chosen because its intrinsic measurement geometry fits a target installation better than a wavelength-multiplexed grating network. | Fabry-Perot units account for a modeled ~21% share and ~2.5% annual expansion. Customers emphasize sensitivity, probe packaging and precision for particular measurement points. Compared with high-channel FBG arrays, specialized configurations often have narrower application boundaries, requiring close collaboration between the transducer vendor and an instrument integrator. |
| Long Period Fiber Grating (LPFG) | Long-period gratings transfer light among propagation modes and create a distinct spectral response to surrounding changes. Their use in mechanical sensing depends on packaging that reduces unintended cross-sensitivity from bending, temperature or the adjacent material. Engineers can use LPFG structures for applications requiring a tailored optical signature, but laboratory calibration and stable attachment become central to reliable long-duration readings. | The LPFG grouping represents an estimated ~12% of 2025 value and modeled ~3.1% CAGR. Its growth is linked to specialized optical designs rather than the broadest bridge-monitoring deployments. Suppliers compete on application-specific grating fabrication, environmental testing and the quality of explanatory calibration data provided with sensors. |
| Michelson Interferometric | Michelson instruments compare optical paths and translate phase differences into a measurement that can be extremely sensitive to physical displacement. The architecture calls for careful management of vibration, thermal drift and reference-path behavior. Engineers may select interferometric elements in laboratory environments or high-sensitivity arrangements where absolute compatibility with standard FBG interrogators is less important than the desired signal resolution. | This method receives ~9% of modeled revenue with a ~2.7% growth path. The commercial niche is influenced by sophisticated optical alignment and customer-specific reference requirements. Integration expenditure can exceed the price of a passive sensing element when laboratory stability, acquisition electronics and noise suppression are important. |
| Others | Other optical strain designs can include Rayleigh-based distributed measurements, Brillouin arrangements and hybrid sensing instruments that sit outside the four named optical categories. A 2026 bridge study demonstrated recovery of structural information using existing telecom fibers rather than purpose-built point sensors. These alternatives expand design options for long structures and difficult-to-access assets without implying that all methods use the same physical observable. | The residual ~12% is modeled at approximately ~2.5% annual growth. Procurement depends on surveillance length, spatial resolution and data processing overhead rather than the headline number of sensors. The group is intentionally limited to optical strain sensing products and excludes unrelated data-communication infrastructure. |
Secondary segmentation: By End User
The publisher identifies Industrial (~40%), Commercial (~25%), Government & Defense (~21%) and Research Institutions (~14%) as end-user groups. The model assigns Industrial customers ~3.4% annual growth based on condition monitoring of operating facilities, while public laboratories and government projects can have more irregular procurement cycles. End users do not map one-to-one onto applications: the same bridge could be operated commercially, financed publicly or used by a research team.
Industrial customers generally emphasize environmental resistance, maintainability and integration with historian or control software. Commercial asset owners evaluate lower-cost monitoring packages and contractor support; Government & Defense buyers may demand traceability and exceptional lifecycle performance; academic facilities often purchase flexible interrogators for repeated experiments. These modeled groups sum to 100% in the 2025 baseline, and none is assigned a revenue share taken from unrelated strain-gauge markets.
Annual regional and segment revenue allocations
Illustrative annual segment revenues in USD million. All figures are analyst-modeled from a 2025 revenue allocation and per-member annual growth rates, not reported supplier sales. The monetary series demonstrates the allocation arithmetic over ten annual observation points and uses the same 2025 baseline for every axis. Rounding to one decimal place may create minor apparent subtotals differences. Country-level or company-level revenue is not inferred from these illustrative numbers.
Region — modeled annual USD million
| Member | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 |
|---|---|---|---|---|---|---|---|---|---|---|
| North America | 89.1 | 91.7 | 94.5 | 97.3 | 100.2 | 103.2 | 106.3 | 109.5 | 112.8 | 116.2 |
| Europe | 61.8 | 63.6 | 65.4 | 67.2 | 69.1 | 71.0 | 73.0 | 75.0 | 77.1 | 79.3 |
| Asia-Pacific | 69.3 | 72.6 | 76.1 | 79.7 | 83.6 | 87.6 | 91.8 | 96.2 | 100.8 | 105.6 |
| South America | 14.8 | 15.3 | 15.8 | 16.4 | 16.9 | 17.5 | 18.0 | 18.6 | 19.2 | 19.9 |
| Middle East & Africa | 12.4 | 12.8 | 13.2 | 13.6 | 14.1 | 14.5 | 15.0 | 15.5 | 16.0 | 16.5 |
Type — modeled annual USD million
| Member | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 |
|---|---|---|---|---|---|---|---|---|---|---|
| Fiber Bragg Grating (FBG) | 113.8 | 118.5 | 123.3 | 128.4 | 133.6 | 139.1 | 144.8 | 150.8 | 156.9 | 163.4 |
| Fabry-Perot Interferometric | 52.0 | 53.3 | 54.6 | 55.9 | 57.3 | 58.8 | 60.2 | 61.8 | 63.3 | 64.9 |
| Long Period Fiber Grating (LPFG) | 29.7 | 30.6 | 31.6 | 32.5 | 33.5 | 34.6 | 35.7 | 36.8 | 37.9 | 39.1 |
| Michelson Interferometric | 22.3 | 22.9 | 23.5 | 24.1 | 24.8 | 25.4 | 26.1 | 26.8 | 27.6 | 28.3 |
| Others | 29.7 | 30.8 | 32.0 | 33.3 | 34.6 | 35.9 | 37.3 | 38.8 | 40.3 | 41.9 |
Application — modeled annual USD million
| Member | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 |
|---|---|---|---|---|---|---|---|---|---|---|
| Civil Engineering | 86.6 | 89.7 | 92.9 | 96.3 | 99.7 | 103.3 | 107.1 | 110.9 | 114.9 | 119.0 |
| Aerospace | 39.6 | 40.8 | 42.2 | 43.5 | 44.9 | 46.3 | 47.8 | 49.3 | 50.9 | 52.6 |
| Energy | 61.8 | 64.3 | 66.8 | 69.4 | 72.1 | 74.9 | 77.8 | 80.8 | 84.0 | 87.3 |
| Automotive | 32.2 | 33.1 | 34.1 | 35.1 | 36.2 | 37.3 | 38.4 | 39.6 | 40.7 | 42.0 |
| Others | 27.2 | 28.1 | 29.1 | 30.1 | 31.1 | 32.1 | 33.2 | 34.3 | 35.5 | 36.7 |
End User — modeled annual USD million
| Member | 2025 | 2026 | 2027 | 2028 | 2029 | 2030 | 2031 | 2032 | 2033 | 2034 |
|---|---|---|---|---|---|---|---|---|---|---|
| Industrial | 99.0 | 102.3 | 105.8 | 109.4 | 113.1 | 117.0 | 120.9 | 125.1 | 129.3 | 133.7 |
| Commercial | 61.8 | 63.8 | 65.9 | 68.0 | 70.2 | 72.4 | 74.7 | 77.1 | 79.6 | 82.1 |
| Government & Defense | 52.0 | 53.8 | 55.8 | 57.8 | 59.8 | 62.0 | 64.2 | 66.5 | 68.9 | 71.4 |
| Research Institutions | 34.6 | 36.1 | 37.6 | 39.2 | 40.9 | 42.6 | 44.4 | 46.3 | 48.2 | 50.3 |
Segment Analysis: By Application
The application classes are Civil Engineering, Aerospace, Energy, Automotive and Others. Civil Engineering has the publisher-indicated ~35% share, and the other modeled 2025 shares are ~16%, ~25%, ~13% and ~11%. Fiber sensor installation economics depend on load spectra, access restrictions and the risk of interference from nearby electrical equipment, making adoption patterns different across these five groups.
| Application | Demand characteristics |
|---|---|
| Civil Engineering | Civil engineering accounts for ~35% of market demand as described by the publisher, with modeled ~3.6% growth. Bridges, tunnels and dams often need long-term records rather than one-time laboratory tests. Embedded gratings can track internal deformation, while surface gauges provide retrievable measurement points. The sensor system must survive concrete curing, weather and irregular maintenance access, so commissioning evidence is as important as high nominal resolution. |
| Aerospace | Aerospace contributes an estimated ~16% share and ~3.2% modeled CAGR. Engineers place lightweight optical fibers on composites and structural joints to evaluate deformation under distributed loading. Luna describes dense sensing along short fiber lengths that can support finite-element model validation. Development work can require high spatial resolution and repeated temperature compensation, whereas installed flight structures place stronger demands on long-life packaging and verification. |
| Energy | Energy is modeled at ~25% of revenue with ~3.9% annual growth. Wind turbines, pipeline structures and offshore assets benefit from the non-electrical nature of passive optical elements. Monitoring networks may combine strain with temperature references and vibration channels, but operators must protect cabling and interrogators against environmental damage. Installation crews also consider whether continuous readings justify the cost of remote data connectivity and alarm interpretation. |
| Automotive | Vehicle and component testing carries an estimated ~13% of spending and a ~3.0% modeled growth rate. Lightweight sensors are useful during prototype evaluation where engineers seek strain-field measurements around joints, composite parts and powertrain structures. Unlike permanent bridge deployments, test programs may reuse instruments among multiple specimens, making rental economics and analysis software more relevant than installing one fixed measurement array for a decade. |
| Others | Other uses account for approximately ~11% of the allocation and a modeled ~2.7% annual expansion. Precision laboratories, specialized machinery, materials research and experimental geotechnical monitoring create projects with unique geometry and data-processing requirements. Procurement can be intermittent, and vendors often rely on application engineers to establish feasible sensor placement, rather than treating all optical measurement requests as repeat orders of standard gauges. |
Applications differ in their response to the same sensing characteristic. A fiber that is safe near high-voltage conductors may appeal to utility equipment operators; a lightweight surface-mounted sensor can be attractive during composite aerospace tests; a distributed sensor on a bridge can reduce the number of individually wired measurement points. However, tensile loading, bending, coating protection and temperature correction remain site-specific. Buyers are therefore likely to compare whole-system measurement uncertainty and operational service commitments before extending a trial to a wider installation.
Regional Analysis
North America leads the modeled 2025 optical strain sensor market with ~36% revenue share and ~3.0% annual expansion. Asia-Pacific follows at ~28% but has a faster ~4.8% modeled trajectory; Europe represents ~25% with ~2.8% yearly growth. South America accounts for ~6% and the Middle East & Africa for ~5%, reflecting smaller installed networks of precision optical sensors. These values are analytical share estimates, not published region-specific financial disclosures.
Where are optical strain monitoring installations most commercially established?
Industrial asset composition matters more than geography alone when interpreting regional demand. North America has extensive aerospace qualification, research facilities and infrastructure inspection programs, while European suppliers contribute grating production and measurement systems for specialized industrial customers. Asia-Pacific combines large new-build construction activity with developing sensing and photonics ecosystems. The modeled five-region allocation distinguishes long-term strain-monitoring deployments from demand for telecommunications equipment, general sensing cable and mechanical structures that do not use optical measurement.
FBGS and HBK illustrate the technically demanding European sensor supply chain, while Luna supplies a broad North American portfolio of distributed and multipoint interrogators. AtGrating offers products designed for embedding in concrete and monitoring wind turbine structures, supporting application projects where local support and supply-chain responsiveness matter. Differences in structural codes and maintenance budgets make national growth rates uncertain; therefore, country narratives describe observable engineering demand drivers instead of presenting unverified country-level sales totals.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| North America | Leader (~36%) | ~3.0% CAGR | Aerospace research and structural monitoring | Long-term accuracy and calibration programs |
| Asia-Pacific | Second (~28%) | ~4.8% CAGR | New infrastructure and sensor fabrication | Qualification cost and project engineering |
| Europe | Third (~25%) | ~2.8% CAGR | Precision instrumentation and wind energy | Materials traceability and sensor durability |
| South America | Fourth (~6%) | ~3.3% CAGR | Energy assets and selected civil projects | Local maintenance and procurement capacity |
| Middle East & Africa | Fifth (~5%) | ~2.7% CAGR | Oilfield installations and public infrastructure | Environmental packaging and local competence |
Optical Strain Sensor Market Competitive Landscape
The industry encompasses dedicated fiber-grating manufacturers, precision transducer suppliers and measurement-system specialists. Procurement differs between a packaged FBG gauge, a distributed optical interrogator and an embedded sensing subassembly. Consequently, a company prominent in sensing components cannot automatically be assumed to lead every end-user category. Supplier positioning is influenced by installation methods, calibration support, compatibility with optical readout equipment and documented performance in civil or industrial assets.
Luna Innovations offers a broad set of high-definition distributed sensing systems and discrete FBG strain gauges. Its ODiSI platforms support densely sampled strain fields, while HYPERION interrogators address multipoint grating arrays and packaged sensor networks. Buyers can choose between continuous spatial information and carefully placed point measurements, with each architecture imposing different software and fiber-routing requirements. Product differentiation therefore includes the speed with which engineers can interpret data as well as optical sensitivity.
HBK provides fiber-optic strain transducers for bonded and welded mounting, and its newLight family addresses applications where measurements must survive long service periods. The company’s product information distinguishes sensor geometry, strain range and environmental rating. This supports a commercial approach based on test-system integration and technical documentation, particularly when a structure must demonstrate compliance with a regulated maintenance process or a research laboratory needs reproducibility across separate test rigs.
FBGS focuses on grating fabrication and OEM components, with draw-tower inscription intended to preserve fiber strength and support high-count sensing arrays. AtGrating also offers packaged surface and embedded strain gauges, temperature-compensated variants and interrogators, making it relevant to infrastructure monitoring integrators. Their supplier strategies emphasize different segments of the value chain, so technical specifications and application fit are more informative than assuming comparable company-wide sensing revenue from their respective catalogues.
Other companies listed by the publisher include Technica Optical Components, Althen, Bestech Australia, SCAIME, Opsens Solutions, Micron Optics, Fibos, FISO Technologies, OSENSA Innovations, Technobis Fiber Technologies and Smart Fibres. Several provide broader measurement, integration or legacy branding capabilities. Company profiles should retain the published list while distinguishing verified optical strain products from adjacent pressure, temperature or sensing services; unverified market shares are not used to assign financial leadership.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Luna Innovations; HBK; FBGS | Broad or technically differentiated optical sensing platforms with established product documentation. |
| Tier 2 | AtGrating Technologies; Technica Optical Components; Technobis Fiber Technologies | Grating fabrication, specialized transducers and customer-specific interrogation arrangements. |
| Tier 3 / profiled | Althen; Bestech Australia; SCAIME; Opsens Solutions; Micron Optics; Fibos; FISO Technologies; OSENSA Innovations; Smart Fibres | Additional profiled companies, integrators and related sensor brands requiring scope-by-scope verification. |
Key companies profiled
- HBK (Hottinger Brüel & Kjær)
- Luna Innovations
- Technica Optical Components
- AtGrating Technologies
- Althen
- Bestech Australia
- SCAIME
- Opsens Solutions
- Micron Optics
- FBGS
- Fibos
- FISO Technologies
- OSENSA Innovations
- Technobis Fiber Technologies
- Smart Fibres
Optical Strain Sensor Manufacturing and Capacity Analysis
Production spans optical-fiber preparation, grating inscription, specialized sensor packaging, mechanical validation and integration with measurement electronics. High-throughput optical fiber drawing is only one part of the process; qualified mounting methods determine whether an installation measures representative structural strain. Capacity is therefore constrained by tested output and application engineering rather than the gross length of glass fiber manufactured. Different formats also require distinct environmental and fatigue testing.
Grating manufacturers use controlled optical-writing processes to create reflective structures with a defined wavelength response. FBGS describes a technique in which gratings are inscribed during draw-tower production before a protective coating is applied, helping retain mechanical integrity. Conventional packaged gauges may instead rely on separate fiber processing and mounting. A production organization must manage wavelength assignment, optical loss, grating uniformity and tensile strength, especially when a buyer expects many independent sensing locations on one array.
Mechanical packaging turns a fragile optical element into a commercial transducer. Weldable designs attach to metallic surfaces, adhesive-mounted patches accommodate laboratory and field locations, and embedded arrays can be incorporated within reinforced composites. HBK specifies a wide strain range for certain patch sensors, while FBGS describes glass-fiber reinforced protection for embedded devices. No single packaging type is optimal for every geometry, and manufacturers must demonstrate that the transfer of strain remains reproducible after installation.
Optical interrogation is a separate bottleneck because passive sensing arrays need reliable light sources, wavelength calibration and readout electronics. Suppliers may offer modular channels, software applications and temperature compensation alongside the sensing elements. The production ability to qualify finished systems matters more than offering an extensive product list when public infrastructure buyers require consistent performance over years. Service partners can also affect practical output by providing installer training and reference checks for networks already deployed.
Optical Strain Sensor Market Dynamics
Asset integrity programs, demand for electrical isolation, distributed fiber sensing and composite materials testing support optical strain adoption. Upfront installed-system cost, calibration difficulty, skilled labor and weather exposure create offsets. The modeled impact allocation totals +6.5 percentage points across five supporting factors and -3.0 percentage points across four restraints, reconciling exactly to the calculated forecast CAGR while describing relative directional influence rather than measured causal attribution.
MARKET DRIVERS
Drivers Impact Analysis*
| Market Drivers | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Long-term structural integrity monitoring | High | +1.90% | High | High | High |
| Electromagnetic immunity in energy assets | Medium-High | +1.50% | High | Medium | Medium |
| Distributed sensing in composites | Medium | +1.30% | Medium | High | High |
| Interrogator integration and data software | Low-Medium | +1.00% | Medium | High | High |
| Others (research and specialized infrastructure) | Low | +0.80% | Low | Medium | Medium |
Infrastructure operators seek strain histories rather than occasional spot checks
Bridges, tunnels and water-retaining structures may experience gradually changing loads that are difficult to diagnose from visual inspection alone. Optical arrays can record deformation trends at selected high-risk locations while keeping electrically sensitive instrumentation away from long cable runs. A 2026 bridge research project showed that existing communications fibers can also contribute to structural analysis. The commercial driver is strongest where asset owners have personnel able to translate the signals into inspection priorities and action thresholds.
Passive optical elements are useful around electrical noise
Strain measurements on power equipment, industrial motors and energy structures can be compromised by electromagnetic interference when conventional conductive leads extend across difficult installations. Fiber sensors provide an electrically passive alternative at the measurement location, allowing strain information to travel through optical links. Customers must still specify suitable readout, environmental protection and data acquisition. The practical advantage grows where an electrical measurement would otherwise demand shielding or extensive isolation arrangements.
Composite fabrication benefits from spatially dense measurements
Aircraft components and wind blades contain geometry that can produce localized loads near joints or changes in material thickness. Luna describes distributed optical strain measurements with fine spatial sampling across compatible fiber lengths, a capability that can help validate mechanical models during design. Embedded fibers must withstand fabrication and repeated fatigue without altering the part’s required structural performance. Researchers can therefore use optical sensing to inform design decisions that a small set of resistance gauges might miss.
Measurement software increases the usefulness of raw optical data
An interferometric trace or shifting reflection wavelength does not itself identify a damaged structure. Instrument software must compensate for temperature, map sensor positions and convert recorded signals into engineering quantities. When data can be connected with inspection records and asset-management thresholds, operators can maintain a consistent history across several seasons. Software and analytics capabilities thus affect sensor purchasing even though the core sensing fiber remains mechanically simple and electrically passive.
Niche scientific projects broaden the addressable customer base
Material laboratories, geotechnical researchers and medical-device developers sometimes need strain measurements where installing a conventional wired gauge is impractical. Fiber sensors can be embedded, routed through constrained spaces or interrogated across multiple positions. Such uses typically start with small trials and bespoke fixtures rather than large production contracts. They support diversification of vendor applications, although specialists still have to demonstrate how a particular optical principle performs under the intended load cycle.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Market Restraints | Impact Rank | CAGR Contribution (%) | 2026–2028 | 2029–2031 | 2032–2034 |
|---|---|---|---|---|---|
| Higher initial integration and system cost | High | -1.10% | High | High | Medium |
| Temperature separation and calibration | Medium-High | -0.80% | High | Medium | Medium |
| Specialist technician and engineering demand | Medium | -0.70% | High | Medium | Medium |
| Others (fiber protection and replacement) | Low | -0.40% | Medium | Low | Low |
Installation engineering can outweigh the sensor unit price
Purchasing a packaged FBG device does not complete a working measurement system. Customers may also need optical interrogation hardware, protected connectors, trained installers and validated surface preparation before commissioning. Retrofitting a finished bridge or energy plant can require access arrangements that are costly compared with the device itself. These expenditures reduce the attractiveness of optical monitoring where periodic inspection or traditional instruments already satisfy operational needs at lower total cost.
Temperature effects complicate claims of stable mechanical performance
The wavelength response of a grating changes with both structural strain and thermal conditions, and the two influences must be separated through reference devices, calibration or sensor configuration. A NIST study showed that small wavelength uncertainty can materially affect interpreted microstrain. Measurements collected over seasons can be misread if thermal drift and sensor attachment changes are overlooked. This reduces confidence in poorly specified field systems despite the underlying sensitivity of the optical method.
Specialist staff remain necessary to interpret data
A high-count optical network generates useful information only when engineers know the sensor positions, channel characteristics and structural behavior being monitored. Operators must investigate sudden signal changes to distinguish actual damage from a broken connector or lost optical path. Training and periodic verification add costs that are particularly visible in small municipal projects. Vendors with good integration support can reduce this burden, but they cannot entirely replace qualified interpretation in safety-critical settings.
MARKET OPPORTUNITIES
Reusable instrument platforms lower barriers to wider monitoring
Organizations that use one interrogator with several calibrated sensing projects can improve utilization of expensive electronic readout equipment. Modular systems may allow additional channels or different sensor types without repeating every procurement decision. This approach can make pilots more economical for research institutions and asset owners with many structures. Suppliers that communicate consistent optical connectors and software compatibility can gain an advantage where procurement committees seek gradual deployment rather than a major immediate capital program.
Distributed measurement enables new asset-management methods
Research on pre-existing telecommunications fibers suggests that structural dynamics can sometimes be investigated without installing a dense bespoke sensor array. The challenge is proving physical coupling and interpreting the recovered signal under real operating conditions. If carefully deployed, such techniques may broaden monitoring beyond a few specially instrumented bridges. They should be treated as adjacent technical opportunities rather than as automatic new sales of dedicated strain sensor hardware.
Improved coatings and compensation widen feasible environments
Sensing elements designed for higher fatigue, harsh temperatures and complicated geometry can reduce the cost of maintaining permanent measurement networks. FBGS publishes mechanical strength and coating information for its draw-tower gratings, while HBK offers several forms of attachment to match structural material. The opportunity lies in choosing compatible components as a system, because a durable optical grating alone cannot prevent failure of adhesives, mechanical mounts or exposed connectors.
Optical Strain Sensor Market Value Chain
The sensing value chain runs from optical glass and coating materials through grating inscription, transducer packaging, interrogation electronics and field integration. Each tier contributes a different type of quality evidence: fiber suppliers establish optical and mechanical characteristics, assembly firms test sensitivity and protection, and integrators verify strain transfer after installation. Monitoring customers ultimately purchase decisions they can rely on, so documentation and calibration services are commercially significant even where the sensing element itself is passive.
Material selection. Fiber type, coating chemistry and bending characteristics influence the feasibility of a mechanical sensing installation. A grating array intended to be embedded in a large composite may require different protection from an exposed sensor bonded temporarily to a laboratory specimen. Suppliers must control optical losses and maintain consistent responses across batches, because a wavelength map can become unusable if deviations exceed the configured measurement channels.
Packaging and acceptance. Manufacturers assemble transducers with connectors, bonded carriers or protective mechanical housings and then characterize them under defined loading. Equipment buyers may request information about temperature sensitivity, fatigue limits and attachment method. Packaging can determine the life of a field device as much as the underlying fiber design. Product validation needs to represent intended operating conditions rather than relying entirely on a short factory functional check.
Installer and distributor role. Specialist integrators plan the layout of sensing positions, provide interrogator commissioning and establish baseline calibration records. They also train maintenance teams to identify optical faults, mechanical changes and data irregularities. A product shipped to a site without these services can fail to produce interpretable engineering evidence, even when its formal component specification is met. Local technical availability therefore affects which suppliers win operational monitoring contracts.
Operations and analytics. Asset owners combine the sensor data with temperature readings, design calculations and inspection histories. A stable installation provides a time series that may support condition monitoring, but an engineering organization must still distinguish ordinary seasonal motion from unusual load conditions. Lifecycle cost depends on the availability of replacement fibers, interrogator service and staff capable of evaluating recorded signals, not just the installation purchase price.
Recent Developments in the Optical Strain Sensor Market
- 16 October 2026 Concrete crack monitoring research
Researchers from Bauhaus-Universität Weimar published experimental work on distributed fiber-optic approaches to crack detection in concrete. The study adds evidence about how sensor attachment and distributed readings can help evaluate damage in structural materials. It represents technical progress for civil monitoring, not a claim that concrete monitoring installations have been adopted throughout the construction industry. Source - 28 September 2026 Broadband strain-resolution investigation
A Photonic Sensors article examined broadband fiber-optic strain measurements with extremely fine resolution. Greater sensitivity opens possibilities for controlled experiments and model validation, but performance in a laboratory should be evaluated separately from ruggedness and calibration drift in permanent outdoor systems. The publication informs potential high-performance instrumentation requirements rather than proving commercial demand volumes. Source - 17 September 2026 Harsh-environment sensing review
A Discover Civil Engineering review assessed signal robustness, thermal correction and long-term reliability for fiber-optic structural monitoring. Its attention to aging and measurement cross-sensitivity explains why vendors must supply more than a nominal sensitivity figure. The review is relevant to asset owners comparing protective housings and calibration strategies under severe operating conditions. Source - 10 September 2026 Building deformation tracking
A research team published a hybrid neuro-fuzzy and wavelet system for FBG-based building shape tracking. The method links optical strain signals with computational interpretation of structural movement. It demonstrates ongoing interest in converting wavelength measurements into useful engineering evidence, although independent field validation remains important before the approach becomes a normal building-management product. Source - 21 August 2026 Bridge monitoring using installed optical fiber
A Nature Communications study tested recovery of dynamic and quasi-static bridge behavior from existing communications cables across six structures in the United States and South Korea. The research highlighted the potential for wider structural sensing without installing separate dense transducer networks. Adoption would still require proof of fiber-to-structure coupling, suitable acquisition systems and long-term operational responsibility. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2020–2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026–2034 |
| Historical Period | 2020–2024 |
| Market Size 2025 | USD 247 million |
| Market Size 2026 | USD 256 million |
| Market Size 2034 | USD 338 million |
| Growth Rate | CAGR of 3.5% from 2026–2034 |
| Unit | Value in USD million, with modeled shares of revenue |
| Segmentation | By Type, Application, End User and Region |
| By Type | Fiber Bragg Grating (FBG) · Fabry-Perot Interferometric · Long Period Fiber Grating (LPFG) · Michelson Interferometric · Others |
| By Application | Civil Engineering · Aerospace · Energy · Automotive · Others |
| By End User | Industrial · Commercial · Government & Defense · Research Institutions |
| By Region | Regional figures are modeled 2025 revenue shares, with region-specific projected growth assumptions North AmericaUnited States, Canada and Mexico EuropeGermany, Belgium, United Kingdom and other European countries Asia-PacificChina, Japan, India and neighboring manufacturing markets South AmericaBrazil, Chile and Argentina Middle East & AfricaSaudi Arabia, United Arab Emirates, South Africa and other regional buyers |
| Key Companies Profiled | HBK, Luna Innovations, Technica Optical Components, AtGrating Technologies, Althen, Bestech Australia, SCAIME, Opsens Solutions, Micron Optics, FBGS, Fibos, FISO Technologies, OSENSA Innovations, Technobis Fiber Technologies, Smart Fibres |
| Customization Scope | Available scope options include grating method, bridge type, surface versus embedded sensor packaging, interrogation technology, industry application and country-level systems demand. |
Frequently Asked Questions
How is the optical strain sensor market valued?
The global industry is estimated at USD 247 million for 2025 and USD 338 million in 2034, based on compounding the reported 2024 and 2032 monetary anchors through the defined planning horizon. This gives an endpoint-derived annual growth rate of 3.5% and includes finished fiber-optic strain sensing products rather than the value of the infrastructure they inspect.
Which type of optical strain sensor has the leading share?
Fiber Bragg Grating technology represents an estimated ~46% of the 2025 type allocation. Its commercial appeal comes from the ability to combine many wavelength-coded measurements within a manageable network. Designers still need to specify calibration, fiber routing and attachment methods when using the sensors in an installed asset. Particular care is required when grating channels are distributed across multiple structural supports.
What are the principal applications of optical strain measurement?
Civil Engineering is the largest application, with the publisher describing a 35% demand share. Energy and aerospace also contribute meaningful purchasing activity through turbine monitoring, pipelines, structural testing and materials research. The appropriate sensor configuration changes with installation geometry, expected mechanical loading and environmental exposure. Inspection teams must identify who will maintain reference readings following project handover.
Why is fiber-optic strain measurement used near electrical equipment?
The passive fiber element does not carry the electrical signal that a resistance-based gauge requires, reducing the risk of electromagnetic interference in demanding energy or industrial locations. Complete monitoring systems still need powered readout equipment, well-protected connectors and proper separation of mechanical strain from environmental drift. Optical isolation alone does not establish the accuracy of an installed sensor network.
Which region has the highest estimated optical strain sensor revenue?
North America has a modeled ~36% share for the 2025 baseline, supported by aerospace engineering, structural asset management and industrial diagnostics. Asia-Pacific is assigned ~28% and faster potential growth because of new infrastructure and developing local sensor-manufacturing capability. These market shares are analytical estimates rather than audited company sales. Their interpretation is limited to the strain sensor revenue boundary.
How does an FBG sensor register deformation?
A Bragg grating reflects a wavelength that changes when the fiber is loaded or its temperature changes. An interrogator observes the reflected signal, and calibration converts the wavelength shift into a mechanical quantity. Temperature compensation and consistent attachment are necessary to avoid confusing environmental changes with structural movement. A reference grating can help quantify thermal drift when installed appropriately.
Which companies supply optical strain sensing products?
The competitive landscape includes Luna, HBK, FBGS and AtGrating among vendors with published optical sensing portfolios, alongside additional specialists listed by the publisher. Their offerings range from compact surface gauges to embedded arrays and optical interrogators. Buyers should verify current product responsibilities and service arrangements before attributing capability to a legacy brand.
What limits the adoption of permanent optical monitoring?
Total deployment expense, specialist installation skills, signal interpretation and long-term maintenance requirements can slow procurement. A low-cost sensing fiber may still require a precise interrogator and dedicated field work. Operators need a clear plan for responding to sensor anomalies and maintaining optical connections throughout the asset lifecycle. A competent service provider can mitigate some implementation uncertainties.
What recent research could change optical monitoring practice?
Studies published in 2026 examined bridge monitoring via installed telecommunications fibers, improved strain resolution and machine-assisted evaluation of structural movement. These developments demonstrate useful technical possibilities but do not establish immediate revenue conversion. Successful commercial systems will depend on field robustness, measurement traceability and the ability to integrate results into inspection procedures.
What forecast years and segmentation are covered?
The baseline year is 2025, the first estimate is 2026 and the forecast concludes in 2034. The report examines the published Type, Application and End User dimensions as well as five geographic regions. Modeled segments reconcile to a full revenue allocation and are differentiated from the publisher’s explicitly reported demand shares.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF