Key Statistics
Key Takeaways
- Market value: The optical heart rate sensor market reached USD 17,562 million in 2026 and is projected at USD 55,931 million by 2036, a 12.3% compound annual growth rate over 2027–2036. The outlook follows demand for qualified optical sensing and application-specific integration, not total consumer electronics or diagnostic industry sales. In headline, for procurement in 2027–2036, customers will test optical heart rate sensor in headline against observed field performance rather than accepting sensor specifications on paper. For headline, Integrators must account for calibration, operating environment and return logistics before technical capabilities translate into recurring revenue.
- Photoplethysmography Sensors: This is the largest type at an estimated ~86% of 2026 revenue, with Photoplethysmography Sensors posting the fastest modeled expansion at ~12.5% CAGR from ~86% share. Different device architectures carry different calibration burdens and monetization opportunities, so shipment volume cannot be used as a direct substitute for optical sensor revenue. In type mix, at an operating level, optical heart rate sensor in type mix cannot be judged solely by component sensitivity. For type mix, The buyer also pays for supporting electronics, repeatability checks and qualified service, with the practical value varying according to where the system is installed and who interprets the resulting signal.
- Smart Watch: This application captures an estimated ~52% of 2026 revenue. Headset is expected to expand at approximately ~13.2% CAGR as customer requirements and installed equipment evolve. Growth depends on performance repeatability and software integration as well as the optical detection element. In application mix, between 2027–2036, stronger adoption depends on the interaction of affordability, verification and device usability. For application mix, A functional laboratory prototype is only one stage in the commercial process; real customers require dependable supply, simple operating procedures and clearly bounded performance claims.
- Asia-Pacific: The largest region accounts for an estimated ~44% of 2026 revenue, while Asia-Pacific has the highest modeled regional growth at ~13.4% CAGR. Its commercial advantages are linked to china offers large electronics assembly and component integration capacity; japan contributes specialized optical semiconductor engineering, while south korea hosts wearable oem design and india supports a price-sensitive smartwatch channel. manufacturing origin and ultimate buyer location must not be confused when interpreting the region.
- Main commercial constraint: Motion artifact and sensor-skin contact instability remains central, because the instrument or wearable must produce an interpretable reading under variable use conditions. Users compare measurement confidence, cost and ease of adoption before replacing existing approaches. This can slow commercialization even when new detectors are more sensitive. In constraints, that distinction matters because revenue in 2027–2036 follows purchasing decisions for qualified devices, readers and consumables, not the number of people potentially benefiting from better sensing. For constraints, Repeat orders depend on practical reliability and the total cost of a successful measurement.
Optical Heart Rate Sensor Market Overview
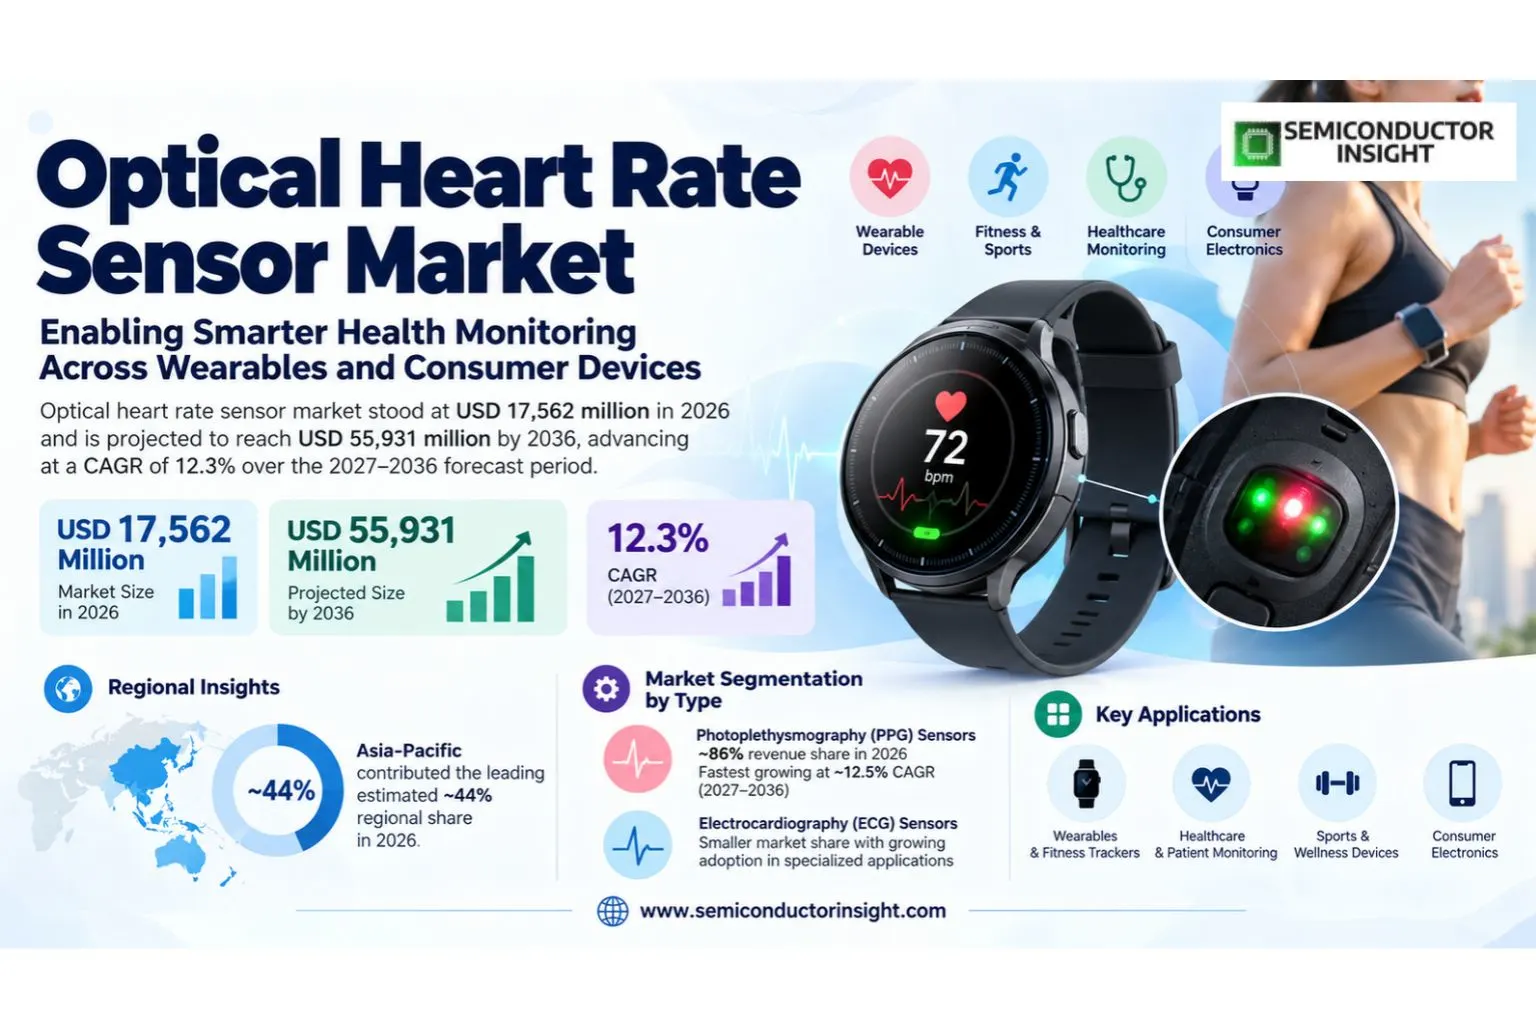
Optical heart rate sensor market stood at USD 17,562 million in 2026 and is projected to reach USD 55,931 million by 2036, advancing at a CAGR of 12.3% over the 2027–2036 forecast period. Asia-Pacific contributed the leading estimated ~44% regional share in 2026. Product demand follows engineering qualification, use-case requirements and the practical economics of optical detection.
Optical heart rate sensing measures a blood-volume pulse through changes in tissue absorption and reflection. Green LEDs and photodiodes are commonly used at the wrist, while infrared and red emitters broaden the available optical responses. Apple Developer documentation distinguishes light paths and emitter wavelengths across watch generations, underlining how optical hardware and signal processing jointly create a useful heart-rate measurement.
Revenue covers optical PPG sensing components and modules sold within smartwatches, bracelets, headsets, phones, and adjacent worn devices. Analog Devices MAX86176 combines a two-channel PPG data path with an ECG interface, illustrating how manufacturers bundle electrical and optical measurements. ECG electrodes alone, however, do not measure light: hybrid products belong here only insofar as their optical channels contribute to value.
The technical architecture connects LED emitters, tissue, photodiode arrays, analog-to-digital conversion and digital algorithms. ROHM specifies a BH1792 optical sensor in a compact package, while Oura Ring 4 employs 18 optical sensing paths to respond to different wearing conditions. Motion, skin contact, ambient light and battery duty cycle create practical performance trade-offs that determine device integration cost.
European adoption provides one measured demand signal. Eurostat reported that 29.9% of individuals used smart wearables in 2024, compared with 70.9% using any connected device. The statistical distinction matters because only a fraction of connected-device spending includes continuous optical heart sensing. Growing software services can enhance user value without adding equivalent optical hardware revenue. In overview 3, for buyers operating under formal specifications, product maturity matters as much as headline accuracy. For overview 3, Changes to the sensing architecture can trigger new software testing, calibration and service requirements, affecting the timing of new purchases during 2027–2036.
New health features raise the strategic importance of sensor quality. Apple Watch Series 11 uses optical heart-sensor data for hypertension notifications assessed over 30-day periods, while Garmin Venu 4 highlights health trends, heart-rate variability and up to 12 days of smartwatch-mode battery life. Neither claim removes the need to distinguish general wellness functionality from a device approved for a defined clinical purpose.
Segment Analysis: By Type
The optical heart rate sensor market is segmented by type into Photoplethysmography Sensors, Electrocardiography Sensors. Photoplethysmography Sensors leads at an estimated ~86% of 2026 revenue, while Photoplethysmography Sensors grows most quickly at ~12.5% CAGR from a base share of ~86%. Applications differ in accuracy requirements, form factor and the cost of continuing to support an installed measurement workflow.
| Type | Function | Market position |
|---|---|---|
| Photoplethysmography Sensors | PPG measures periodic changes in absorbed or reflected light as pulsatile blood volume changes. Green wavelengths around 525 nanometers support wrist measurement, while infrared and red channels can extend use cases. An optical analog front end conditions photodiode currents before algorithms derive rate and rhythm summaries. Technical positioning reflects the interaction between optical design, sample or tissue variability and the accuracy of the finished signal. For photoplethysmography sensors, purchasing occurs when the complete platform can be qualified to its intended operational use. | Estimated ~86% of 2026 revenue; ~12.5% CAGR through 2036. Largest type by value. For photoplethysmography sensors, the expected commercial mix reflects device pricing, installed applications, and how easily manufacturers can scale repeatable output. In 2027–2036, component integration and software services will not contribute in identical proportions across the type classes. In photoplethysmography sensors position, at an operating level, optical heart rate sensor in photoplethysmography sensors position cannot be judged solely by component sensitivity. For photoplethysmography sensors position, The buyer also pays for supporting electronics, repeatability checks and qualified service, with the practical value varying according to where the system is installed and who interprets the resulting signal. |
| Electrocardiography Sensors | ECG is an electrical measurement made through electrodes, so it is not an optical transducer by itself. In a hybrid watch or patch, ECG hardware can complement PPG to resolve ambiguous pulse patterns or evaluate rhythm; only the optical sensing contribution belongs to this narrowly defined market boundary. For screening in electrocardiography sensors integration during 2027, buyers compare optical performance with unit cost, servicing needs and the way operators will interpret measurements throughout 2027–2036. For electrocardiography sensors, purchasing occurs when the complete platform can be qualified to its intended operational use. | Estimated ~14% of 2026 revenue; ~11.0% CAGR through 2036. Specialized product category. For electrocardiography sensors, the expected commercial mix reflects device pricing, installed applications, and how easily manufacturers can scale repeatable output. In 2027–2036, component integration and software services will not contribute in identical proportions across the type classes. In electrocardiography sensors position, these requirements change the route to market for optical heart rate sensor in electrocardiography sensors position. For electrocardiography sensors position, A manufacturer may win an OEM design slot yet still face lengthy acceptance testing, while a hospital or enterprise customer may delay ordering until its existing workflow is ready for a qualified replacement. |
Secondary segmentation: By Technology
By Technology differentiates Green LED Sensors, Red LED Sensors, Infrared Sensors, Multi-Wavelength Sensors. Green LED Sensors is the largest estimated group, representing ~51% of the 2026 axis allocation. Group definitions serve distinct engineering purposes; they should not be added together with the type and application totals because each axis describes a different attribute of the same sale.
| Axis | Members | Commercial role |
|---|---|---|
| By Technology | Green LED Sensors; Red LED Sensors; Infrared Sensors; Multi-Wavelength Sensors | An estimated ~51% of the by technology allocation in 2026 is associated with Green LED Sensors. The remaining named members occupy different price and performance positions. For by technology, instrument qualification, manufacturing yield and intended application decide how rapidly specific technology improvements translate into revenue. This by technology classification covers 100% of its member values but must not be added to a separate segmentation dimension. |
Secondary segmentation: By End User
By End User differentiates Consumer Electronics, Healthcare, Sports & Fitness, Military & Defense, Others. Consumer Electronics is the largest estimated group, representing ~58% of the 2026 axis allocation. For screening in sensor purchasing during 2028, product qualification requires realistic test conditions, supplier support, component stability and a feasible path to reliable recurring orders.
| Axis | Members | Commercial role |
|---|---|---|
| By End User | Consumer Electronics; Healthcare; Sports & Fitness; Military & Defense; Others | An estimated ~58% of the by end user allocation in 2026 is associated with Consumer Electronics. The remaining named members occupy different price and performance positions. For by end user, instrument qualification, manufacturing yield and intended application decide how rapidly specific technology improvements translate into revenue. This by end user classification covers 100% of its member values but must not be added to a separate segmentation dimension. |
Secondary segmentation: PPG sensor subtypes
PPG sensor subtypes differentiates Transmission-type, Reflectance-type, others. Reflectance-type is the largest estimated group, representing ~78% of the 2026 axis allocation. For screening in sensor purchasing during 2029, the commercial outcome depends on usable sensing results, appropriate user training, effective packaging and affordable after-sales support. In ppg sensor subtypes, for buyers operating under formal specifications, product maturity matters as much as headline accuracy. For ppg sensor subtypes, Changes to the sensing architecture can trigger new software testing, calibration and service requirements, affecting the timing of new purchases during 2027–2036.
| Axis | Members | Commercial role |
|---|---|---|
| PPG sensor subtypes | Transmission-type; Reflectance-type; others | An estimated ~78% of the ppg sensor subtypes allocation in 2026 is associated with Reflectance-type. The remaining named members occupy different price and performance positions. For ppg sensor subtypes, instrument qualification, manufacturing yield and intended application decide how rapidly specific technology improvements translate into revenue. This ppg sensor subtypes classification covers 100% of its member values but must not be added to a separate segmentation dimension. |
Secondary segmentation: ECG sensor subtypes
ECG sensor subtypes differentiates Single-lead, Multi-lead, others. Single-lead is the largest estimated group, representing ~66% of the 2026 axis allocation. For screening in sensor purchasing during 2030, operational reliability must survive variations in device placement, specimen quality, calibration and local maintenance expertise. In ecg sensor subtypes, for procurement in 2027–2036, customers will test optical heart rate sensor in ecg sensor subtypes against observed field performance rather than accepting sensor specifications on paper. For ecg sensor subtypes, Integrators must account for calibration, operating environment and return logistics before technical capabilities translate into recurring revenue.
| Axis | Members | Commercial role |
|---|---|---|
| ECG sensor subtypes | Single-lead; Multi-lead; others | An estimated ~66% of the ecg sensor subtypes allocation in 2026 is associated with Single-lead. The remaining named members occupy different price and performance positions. For ecg sensor subtypes, instrument qualification, manufacturing yield and intended application decide how rapidly specific technology improvements translate into revenue. This ecg sensor subtypes classification covers 100% of its member values but must not be added to a separate segmentation dimension. |
Segment Analysis: By Application
Applications comprise Smart Bracelet, Smart Watch, Headset, Smart Phone, Others, led by Smart Watch at an estimated ~52% of 2026 revenue. Headset is the fastest-growing application at ~13.2% CAGR. Differences in the type of operator, sampling frequency, device durability and distribution channel create distinct commercial profiles, even where underlying optical components overlap. In application lead, for buyers operating under formal specifications, product maturity matters as much as headline accuracy. For application lead, Changes to the sensing architecture can trigger new software testing, calibration and service requirements, affecting the timing of new purchases during 2027–2036.
| Application | Demand characteristics |
|---|---|
| Smart Bracelet | Estimated ~20% of 2026 revenue, with ~12.0% CAGR. Low-cost fitness bands require compact green-LED PPG assemblies and algorithms that operate with limited processors. Vendors generally prioritize battery endurance, simplicity and adequate resting-rate performance rather than expensive multi-channel clinical feature sets. The commercial decision in 2027–2036 includes total cost, sensor performance and the ability to maintain a validated workflow over many measurements. |
| Smart Watch | Estimated ~52% of 2026 revenue, with ~12.7% CAGR. Watches remain the primary commercial socket for continuous optical monitoring, with multiple emitters, photodiodes and software supporting workouts, sleep and symptom notifications. Apple and Garmin releases illustrate how product differentiation increasingly depends on interpretation rather than the sensor diode alone. The commercial decision in 2027–2036 includes total cost, sensor performance and the ability to maintain a validated workflow over many measurements. |
| Headset | Estimated ~7% of 2026 revenue, with ~13.2% CAGR. Headset and ear-worn devices can place optical emitters close to relatively perfused tissue, but pressure, positioning and motion change measurement quality. Adoption depends on wearable comfort and whether developers can justify the extra power and processing burden. The commercial decision in 2027–2036 includes total cost, sensor performance and the ability to maintain a validated workflow over many measurements. |
| Smart Phone | Estimated ~8% of 2026 revenue, with ~11.0% CAGR. Phone-based optical pulse measurement uses camera or illumination hardware in selected wellness workflows, but intermittent readings differ from continuous wrist PPG. FDA categorization of camera-based measurement is distinct from ordinary smartwatch optical sensor component approvals. The commercial decision in 2027–2036 includes total cost, sensor performance and the ability to maintain a validated workflow over many measurements. |
| Others | Estimated ~13% of 2026 revenue, with ~11.5% CAGR. Smart rings, adhesive patches and niche athlete monitors form a varied category. Samsung Galaxy Ring includes an optical biosignal element, while Oura Ring 4 uses an 18-path multiwavelength PPG subsystem; each design must solve optical path consistency and charging constraints. The commercial decision in 2027–2036 includes total cost, sensor performance and the ability to maintain a validated workflow over many measurements. |
The principal channel connects smartwatch manufacturers, ring developers, fitness-device OEMs and approved remote-monitoring providers with component vendors, qualified instrument distributors and specialized service partners. OEM design wins differ from repeat orders of consumables or completed diagnostic instruments. Before accepting a product, purchasers assess calibration instructions, documentation, battery or fluidics burden, local service capacity and compatibility with the workflow already in operation.
Regional Analysis
Asia-Pacific is the largest region, with an estimated ~44% of 2026 revenue. North America follows at ~30% and Europe at ~17%. Asia-Pacific has the fastest estimated growth at ~13.4% CAGR. Production location, final device consumption and equipment procurement can differ substantially, so regional profiles depend on the underlying optical-use application. In regional lead, a sustainable supplier position requires compatible components, validated workflows and evidence that the sensing result remains dependable across different operators. For regional lead, This is particularly relevant in 2027–2036, when product releases can advance faster than customer acceptance or replacement cycles.
How do regional growth and optical sensing applications differ?
Asia-Pacific investment is shaped by China offers large electronics assembly and component integration capacity; Japan contributes specialized optical semiconductor engineering, while South Korea hosts wearable OEM design and India supports a price-sensitive smartwatch channel. Manufacturing origin and ultimate buyer location must not be confused when interpreting the region. North American procurement has a different role, including US device platforms emphasize software-defined interpretation of PPG waveforms and integrated health services. The Apple Watch Series 11 optical sensor supports background hypertension notifications, while FDA pathways apply when claims cross from wellness into diagnosis. Canadian distributors and Mexico assembly partners participate in different parts of the value chain. Europe is influenced by privacy and product qualification, while South America and the Middle East and Africa face individual distributor and institution-led purchasing cycles.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~44%) | ~13.4% CAGR | The 2026 demand profile reflects China offers large electronics assembly and component integration capacity; Japan contributes specialized optical semiconductor engineering, while South Korea hosts wearable OEM design and India supports a price-sensitive smartwatch channel. For screening in Asia-Pacific procurement during 2031, equipment selection brings calibration records, replacement-part availability, power requirements and the maturity of software workflows into one decision. Compared with other territories, the timing of purchases is shaped by the local configuration of suppliers, users and technical support. The 2027–2036 growth path is not a simple function of population or general consumer device activity. | Purchasers in Asia-Pacific review instrument reliability, device or assay traceability, service capability and ongoing operating expense before choosing a supplier. Different country procurement rules affect technical documentation, warranties and acceptance testing. A successful 2026 design-in can provide a basis for repeat orders through 2036, but only when field performance remains dependable. In asia-pacific selection, at an operating level, optical heart rate sensor in asia-pacific selection cannot be judged solely by component sensitivity. For asia-pacific selection, The buyer also pays for supporting electronics, repeatability checks and qualified service, with the practical value varying according to where the system is installed and who interprets the resulting signal. |
| North America | Second (~30%) | ~10.8% CAGR | The 2026 demand profile reflects US device platforms emphasize software-defined interpretation of PPG waveforms and integrated health services. For screening in North America procurement during 2032, customers distinguish laboratory sensitivity from deployable optical performance, accounting for training, servicing and a practical economic case. For screening in North America procurement during 2033, OEM designers need reproducible signal acquisition and qualified bill-of-materials changes before a prototype can become a sustained production contract. For screening in North America procurement during 2034, the installed customer base values stable readouts, interpretable software, continued spare supply and a purchasing case based on real use. For screening in North America procurement during 2035, the route from promising photonics to revenue requires verified technical benefits, informed purchasers and reliable service arrangements. | Purchasers in North America review instrument reliability, device or assay traceability, service capability and ongoing operating expense before choosing a supplier. Different country procurement rules affect technical documentation, warranties and acceptance testing. For screening in North America procurement during 2036, procurement during 2027–2036 balances useful detection sensitivity with field constraints, support quality and the cost of replacing existing equipment. In north america selection, at an operating level, optical heart rate sensor in north america selection cannot be judged solely by component sensitivity. For north america selection, The buyer also pays for supporting electronics, repeatability checks and qualified service, with the practical value varying according to where the system is installed and who interprets the resulting signal. |
| Europe | Third (~17%) | ~11.3% CAGR | The 2026 demand profile reflects Eurostat measured smart wearable use by 29.9% of EU individuals in 2024, creating a large installed replacement base. German component engineering, British medical evaluation, and Dutch consumer demand coexist with GDPR-related health-data obligations and differentiated device-regulatory requirements. For qualification in Europe procurement during 2027, buyers compare optical performance with unit cost, servicing needs and the way operators will interpret measurements throughout 2027–2036. For qualification in Europe procurement during 2028, product qualification requires realistic test conditions, supplier support, component stability and a feasible path to reliable recurring orders. | Purchasers in Europe review instrument reliability, device or assay traceability, service capability and ongoing operating expense before choosing a supplier. Different country procurement rules affect technical documentation, warranties and acceptance testing. For qualification in Europe procurement during 2029, the commercial outcome depends on usable sensing results, appropriate user training, effective packaging and affordable after-sales support. In europe selection, for procurement in 2027–2036, customers will test optical heart rate sensor in europe selection against observed field performance rather than accepting sensor specifications on paper. For europe selection, Integrators must account for calibration, operating environment and return logistics before technical capabilities translate into recurring revenue. |
| South America | Fourth (~5%) | ~12.6% CAGR | The 2026 demand profile reflects Brazilian urban customers commonly compare basic PPG fitness bands with premium imported smartwatch models. Chile and Colombia provide selective demand through digital retail and enterprise wellness channels. Import duties, currency movements and after-sales availability shape the actual optical-sensor configuration adopted at retail. For qualification in South America procurement during 2030, operational reliability must survive variations in device placement, specimen quality, calibration and local maintenance expertise. For qualification in South America procurement during 2031, equipment selection brings calibration records, replacement-part availability, power requirements and the maturity of software workflows into one decision. | Purchasers in South America review instrument reliability, device or assay traceability, service capability and ongoing operating expense before choosing a supplier. Different country procurement rules affect technical documentation, warranties and acceptance testing. For qualification in South America procurement during 2032, customers distinguish laboratory sensitivity from deployable optical performance, accounting for training, servicing and a practical economic case. In south america selection, the most successful applications combine a clearly specified measurement, a dependable operating environment and a channel able to resolve faults promptly. For south america selection, This reduces the risk that a theoretically sensitive detector delivers inconsistent outcomes when used by non-specialist personnel. |
| Middle East & Africa | Fifth (~4%) | ~12.8% CAGR | The 2026 demand profile reflects Saudi Arabia and the UAE support premium wearables and smart-health programmes, while South African retail demand is more price and distributor sensitive. High-temperature durability, localized apps and usable charging intervals affect purchasing; clinical deployment depends on validation and a viable remote-care service model. For qualification in Middle East & Africa procurement during 2033, OEM designers need reproducible signal acquisition and qualified bill-of-materials changes before a prototype can become a sustained production contract. For qualification in Middle East & Africa procurement during 2034, the installed customer base values stable readouts, interpretable software, continued spare supply and a purchasing case based on real use. | Purchasers in Middle East & Africa review instrument reliability, device or assay traceability, service capability and ongoing operating expense before choosing a supplier. Different country procurement rules affect technical documentation, warranties and acceptance testing. For qualification in Middle East & Africa procurement during 2035, the route from promising photonics to revenue requires verified technical benefits, informed purchasers and reliable service arrangements. In middle east & africa selection, for buyers operating under formal specifications, product maturity matters as much as headline accuracy. For middle east & africa selection, Changes to the sensing architecture can trigger new software testing, calibration and service requirements, affecting the timing of new purchases during 2027–2036. |
Competitive Landscape
The optical heart rate sensor supplier field includes direct optical-sensing component vendors, finished-device companies and adjacent companies with different transduction technologies. Published corporate revenue cannot be equated to this product boundary. Commercial leadership comes from repeatable optical performance, effective customer qualification and access to specialized integration channels. In competition lead, between 2027–2036, stronger adoption depends on the interaction of affordability, verification and device usability. For competition lead, A functional laboratory prototype is only one stage in the commercial process; real customers require dependable supply, simple operating procedures and clearly bounded performance claims.
Analog Devices, Inc. and ROHM CO., LTD. are important names in the optical sensing supply chain. Their technical or system responsibilities vary, so purchasers compare qualified product families rather than whole-company size. The relevant commercial test is whether a named company can supply the actual optical architecture, maintain calibration and provide compatible replacements during a multiyear production programme.
The wider company list also contains Philips Healthcare, Murata Manufacturing Co., Ltd., Polar Electro Oy. Several participants provide complete devices, clinical platforms or component subsystems rather than identical direct optical detectors. That distinction matters because the pricing and regulatory evidence for a finished consumer health product cannot be used as a proxy for the value of a photodiode or disposable optical sensor.
Supplier consolidation and legacy product labels influence qualification. Maxim Integrated Products, Inc., Seiko Epson Corporation, New Japan Radio Co., Ltd. appear in the broader historical competitive field, but ownership, current product status and whether a product directly uses optical transduction should be checked against relevant datasheets. Purchasing organizations require documented substitution paths before long-term contracts are awarded.
Competition combines optical sensitivity, assay or tissue interference management, supply quality and customer support. A vendor may win early research customers through technical performance while another wins volume OEM purchasing through manufacturability and cost control. These channels respond differently to product obsolescence, firmware revisions and regulatory clearance obligations over the 2027–2036 period. In competitiveness, at an operating level, optical heart rate sensor in competitiveness cannot be judged solely by component sensitivity. For competitiveness, The buyer also pays for supporting electronics, repeatability checks and qualified service, with the practical value varying according to where the system is installed and who interprets the resulting signal.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Direct optical technology suppliers | Analog Devices, Inc., ROHM CO., LTD., AMS AG | These firms sell verified component or analyzer technologies associated with optical sensing, enabling design-in relationships or qualified instrument purchases. Buyers seek optical response performance, integration guidance, reliability data and repair or replacement commitments. Although each vendor operates a broader portfolio, its relevant technical offerings are distinguishable from non-optical technologies. In direct tier, these requirements change the route to market for optical heart rate sensor in direct tier. For direct tier, A manufacturer may win an OEM design slot yet still face lengthy acceptance testing, while a hospital or enterprise customer may delay ordering until its existing workflow is ready for a qualified replacement. |
| Related platform and instrument developers | Philips Healthcare, Murata Manufacturing Co., Ltd., Polar Electro Oy | This group includes companies whose products or industry roles can involve optical components, system-level monitoring and laboratory or healthcare channels. Their competitive position must be interpreted by product and end use. Clinical approval or brand recognition does not imply direct manufacturing of the optical detection subsystem; qualified downstream purchasing responsibilities still matter. In related tier, that distinction matters because revenue in 2027–2036 follows purchasing decisions for qualified devices, readers and consumables, not the number of people potentially benefiting from better sensing. For related tier, Repeat orders depend on practical reliability and the total cost of a successful measurement. |
| Historical and adjacent product ecosystem | Maxim Integrated Products, Inc., Seiko Epson Corporation, New Japan Radio Co., Ltd., Valencell, Inc., PulseOn Oy | Other profiled names encompass acquired portfolios, systems integration and adjacent non-optical sensing. They remain relevant to value-chain assessment and potential channel partnerships, while not all qualify as current independent vendors of directly comparable optical equipment. Technical due diligence distinguishes product availability, measurement modality and long-term service responsibility. In ecosystem tier, equipment vendors and end users weigh the sensitivity of a specific measurement against ease of calibration, lifetime cost and interpretability of its output. For ecosystem tier, The resulting deployment profile in 2027–2036 is more dependent on product qualification than on broad promotional comparisons. |
Key companies profiled
- Analog Devices, Inc.
- ROHM CO., LTD.
- Maxim Integrated Products, Inc.
- Philips Healthcare
- AMS AG
- Murata Manufacturing Co., Ltd.
- Seiko Epson Corporation
- New Japan Radio Co., Ltd.
- Valencell, Inc.
- PulseOn Oy
- Polar Electro Oy
Production Capacity Analysis
Capacity for optical heart rate sensor depends on production of precision LED dies, photodiode arrays, analog-front-end silicon, flexible packages and calibration fixtures. Engineering throughput includes packaging, test yield, controlled calibration and service logistics. Announced factory expansion or full-company revenue does not prove optical-sensor capacity for the specific product and end use. In capacity lead, a sustainable supplier position requires compatible components, validated workflows and evidence that the sensing result remains dependable across different operators. For capacity lead, This is particularly relevant in 2027–2036, when product releases can advance faster than customer acceptance or replacement cycles.
Optical production requires control of detector response, illumination power, mechanical or fluidic interfaces and electrical noise. Component assemblies must be tested across their intended operating conditions. In 2027–2036, supply reliability can matter more than nominal chip wafer throughput when every finished unit requires traceability and final configuration checks. In capacity production, device development therefore involves a commercial trade-off between the cost of acquisition and the ability to deliver repeatable measurements. For capacity production, During 2027–2036, installation support, consumable logistics and long-term product maintenance influence adoption alongside technical improvements.
Manufacturing is geographically distributed between specialized component facilities and customers that integrate the finished optical heart rate sensor function. Outsourcing selected parts can increase flexibility, but it also adds supplier qualification and change-control requirements. A new factory cannot be substituted overnight into a sensitive optical bill of materials without testing the finished signal. In capacity location, for buyers operating under formal specifications, product maturity matters as much as headline accuracy. For capacity location, Changes to the sensing architecture can trigger new software testing, calibration and service requirements, affecting the timing of new purchases during 2027–2036.
Capacity bottlenecks can emerge in high-quality photodiodes, optically active materials, precision coating or specially prepared sample surfaces. Even when ordinary electronic components are plentiful, a narrow qualified-source list can determine shipment timing. Long-term users value predictable device revisions, replacement parts and validated consumables across a full instrument or wearable lifecycle. In capacity bottlenecks, the most successful applications combine a clearly specified measurement, a dependable operating environment and a channel able to resolve faults promptly. For capacity bottlenecks, This reduces the risk that a theoretically sensitive detector delivers inconsistent outcomes when used by non-specialist personnel.
Market Dynamics
Demand is influenced by demand for continuous wrist and finger ppg, while motion artifact and sensor-skin contact instability constrains realization. Growth through 2036 therefore depends on the balance between improved optical signal quality and the time required for product qualification. A technology advance can expand possible use cases without converting all addressable applications into near-term orders.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Demand for continuous wrist and finger PPG | +1.7% | Asia-Pacific | 2027–2030 |
| Low-power optical analog front-end design | +1.3% | North America | 2027–2032 |
| Sleep and recovery analytics in consumer wearables | +0.9% | Europe | 2029–2036 |
| Sensor fusion improving movement resilience | +0.7% | South America | 2028–2034 |
| Demand for continuous wrist and finger PPG | +0.5% | Middle East & Africa | 2027–2036 |
Demand for continuous wrist and finger PPG
Demand for continuous wrist and finger PPG influences demand because improved measurement capabilities can turn a difficult or inconvenient sensing workflow into a practical product feature. Suppliers respond by offering validated modules, supporting software or disposable interfaces and training materials. For optical heart rate sensor, successful commercial uptake requires evidence of real-use consistency, channel fit and a clear purchasing case throughout 2027–2036.
Low-power optical analog front-end design
Low-power optical analog front-end design influences demand because improved measurement capabilities can turn a difficult or inconvenient sensing workflow into a practical product feature. For service in technology investment during 2027, buyers compare optical performance with unit cost, servicing needs and the way operators will interpret measurements throughout 2027–2036. For service in technology investment during 2028, product qualification requires realistic test conditions, supplier support, component stability and a feasible path to reliable recurring orders.
Sleep and recovery analytics in consumer wearables
Sleep and recovery analytics in consumer wearables influences demand because improved measurement capabilities can turn a difficult or inconvenient sensing workflow into a practical product feature. For service in technology investment during 2029, the commercial outcome depends on usable sensing results, appropriate user training, effective packaging and affordable after-sales support. For service in technology investment during 2030, operational reliability must survive variations in device placement, specimen quality, calibration and local maintenance expertise.
Sensor fusion improving movement resilience
Sensor fusion improving movement resilience influences demand because improved measurement capabilities can turn a difficult or inconvenient sensing workflow into a practical product feature. For service in technology investment during 2031, equipment selection brings calibration records, replacement-part availability, power requirements and the maturity of software workflows into one decision. For service in technology investment during 2032, customers distinguish laboratory sensitivity from deployable optical performance, accounting for training, servicing and a practical economic case.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Motion artifact and sensor-skin contact instability | −1.5% | Asia-Pacific | 2027–2036 |
| Battery drain and LED duty-cycle limits | −1.1% | North America | 2028–2032 |
| Clinical validation and regulatory acceptance | −0.8% | Europe | 2027–2034 |
| Legacy component discontinuations | −0.5% | South America | 2029–2036 |
Motion artifact and sensor-skin contact instability
Motion artifact and sensor-skin contact instability can restrain revenue even when the laboratory or demonstration performance of a detector appears promising. Customers must consider conditions outside a controlled test, ongoing operating expenses and the burden of changing a trusted sensing workflow. Manufacturers lower adoption risk by maintaining transparent test data, offering product support and documenting actual intended-use limitations.
Battery drain and LED duty-cycle limits
Battery drain and LED duty-cycle limits can restrain revenue even when the laboratory or demonstration performance of a detector appears promising. For service in technology investment during 2033, OEM designers need reproducible signal acquisition and qualified bill-of-materials changes before a prototype can become a sustained production contract. For service in technology investment during 2034, the installed customer base values stable readouts, interpretable software, continued spare supply and a purchasing case based on real use.
Clinical validation and regulatory acceptance
Clinical validation and regulatory acceptance can restrain revenue even when the laboratory or demonstration performance of a detector appears promising. For service in technology investment during 2035, the route from promising photonics to revenue requires verified technical benefits, informed purchasers and reliable service arrangements. For service in technology investment during 2036, procurement during 2027–2036 balances useful detection sensitivity with field constraints, support quality and the cost of replacing existing equipment.
Legacy component discontinuations
Legacy component discontinuations can restrain revenue even when the laboratory or demonstration performance of a detector appears promising. For scaling in technology investment during 2027, buyers compare optical performance with unit cost, servicing needs and the way operators will interpret measurements throughout 2027–2036. For scaling in technology investment during 2028, product qualification requires realistic test conditions, supplier support, component stability and a feasible path to reliable recurring orders.
MARKET OPPORTUNITIES
Multi-wavelength adaptive PPG designs
Multi-wavelength adaptive PPG designs offers an opportunity where the sensor solution reduces time, provides a more interpretable result or improves end-user convenience. The business case involves sample handling or device integration as well as the optical detector. Suppliers that pair documented performance with affordable systems, compatible software and repeatable field support can serve customers expanding deployments from 2027 through 2036.
Miniaturized smart-ring and ear-worn devices
Miniaturized smart-ring and ear-worn devices offers an opportunity where the sensor solution reduces time, provides a more interpretable result or improves end-user convenience. For scaling in technology investment during 2029, the commercial outcome depends on usable sensing results, appropriate user training, effective packaging and affordable after-sales support. For scaling in technology investment during 2030, operational reliability must survive variations in device placement, specimen quality, calibration and local maintenance expertise.
Remote monitoring integration with clinical teams
Remote monitoring integration with clinical teams offers an opportunity where the sensor solution reduces time, provides a more interpretable result or improves end-user convenience. For scaling in technology investment during 2031, equipment selection brings calibration records, replacement-part availability, power requirements and the maturity of software workflows into one decision. For scaling in technology investment during 2032, customers distinguish laboratory sensitivity from deployable optical performance, accounting for training, servicing and a practical economic case.
Emerging-market affordable wearables
Emerging-market affordable wearables offers an opportunity where the sensor solution reduces time, provides a more interpretable result or improves end-user convenience. For scaling in technology investment during 2033, OEM designers need reproducible signal acquisition and qualified bill-of-materials changes before a prototype can become a sustained production contract. For scaling in technology investment during 2034, the installed customer base values stable readouts, interpretable software, continued spare supply and a purchasing case based on real use.
Supply Chain Analysis
The value chain joins optical components, precise mechanical and electronic assembly, validated instrument or wearable software, OEM qualification and eventual use by smartwatch manufacturers, ring developers, fitness-device OEMs and approved remote-monitoring providers. Consumables and calibration services create distinct recurring business where appropriate. Component origin does not necessarily indicate the location of end-user sales. In supply chain lead, these requirements change the route to market for optical heart rate sensor in supply chain lead. For supply chain lead, A manufacturer may win an OEM design slot yet still face lengthy acceptance testing, while a hospital or enterprise customer may delay ordering until its existing workflow is ready for a qualified replacement.
Upstream. The supply chain starts with precision LED dies, photodiode arrays, analog-front-end silicon, flexible packages and calibration fixtures. In procurement terms, the 2027–2036 outlook depends on traceable supply, realistic maintenance costs and suitability for the application-specific measurement. Suppliers with strong technical support are better placed to convert one initial design win into recurring qualified orders. In upstream chain paragraph, for buyers operating under formal specifications, product maturity matters as much as headline accuracy. For upstream chain paragraph, Changes to the sensing architecture can trigger new software testing, calibration and service requirements, affecting the timing of new purchases during 2027–2036.
Manufacturing. Calibration and controlled packaging determine functional output rather than assembly volume alone. For scaling in component delivery during 2035, the route from promising photonics to revenue requires verified technical benefits, informed purchasers and reliable service arrangements. For scaling in component delivery during 2036, procurement during 2027–2036 balances useful detection sensitivity with field constraints, support quality and the cost of replacing existing equipment. In manufacturing chain paragraph, the most successful applications combine a clearly specified measurement, a dependable operating environment and a channel able to resolve faults promptly. For manufacturing chain paragraph, This reduces the risk that a theoretically sensitive detector delivers inconsistent outcomes when used by non-specialist personnel.
Channel. Sales teams need specific expertise in the intended use and installation of the sensing product. For renewal in component delivery during 2027, buyers compare optical performance with unit cost, servicing needs and the way operators will interpret measurements throughout 2027–2036. For renewal in component delivery during 2028, product qualification requires realistic test conditions, supplier support, component stability and a feasible path to reliable recurring orders. In channel chain paragraph, for procurement in 2027–2036, customers will test optical heart rate sensor in channel chain paragraph against observed field performance rather than accepting sensor specifications on paper. For channel chain paragraph, Integrators must account for calibration, operating environment and return logistics before technical capabilities translate into recurring revenue.
Downstream. Operating buyers include smartwatch manufacturers, ring developers, fitness-device OEMs and approved remote-monitoring providers. For renewal in component delivery during 2029, the commercial outcome depends on usable sensing results, appropriate user training, effective packaging and affordable after-sales support. For renewal in component delivery during 2030, operational reliability must survive variations in device placement, specimen quality, calibration and local maintenance expertise. In downstream chain paragraph, at an operating level, optical heart rate sensor in downstream chain paragraph cannot be judged solely by component sensitivity. For downstream chain paragraph, The buyer also pays for supporting electronics, repeatability checks and qualified service, with the practical value varying according to where the system is installed and who interprets the resulting signal.
Recent Developments
- September 2026 Published
FDA classification documentation continued to distinguish optical camera-based measurement hardware from software-only interpretation. The QOK equipment code and QME software code show how intended use influences regulatory review. For optical heart-rate vendors this matters because a camera-based diagnostic claim is not interchangeable with a wellness-grade wrist PPG feature. In development september 2026, between 2027–2036, stronger adoption depends on the interaction of affordability, verification and device usability. For development september 2026, A functional laboratory prototype is only one stage in the commercial process; real customers require dependable supply, simple operating procedures and clearly bounded performance claims. Source - September 2025 Announced
Garmin introduced the Venu 4 on 17 September 2025, emphasizing 24-hour health trends, heart-rate variability, sleep and up to 12 days of smartwatch-mode battery life. The launch illustrates the commercial need to balance continuous PPG sampling with portable power budgets rather than competing solely on maximum optical acquisition rates. In development september 2025, these requirements change the route to market for optical heart rate sensor in development september 2025. For development september 2025, A manufacturer may win an OEM design slot yet still face lengthy acceptance testing, while a hospital or enterprise customer may delay ordering until its existing workflow is ready for a qualified replacement. Source - September 2025 Announced
Apple introduced Watch Series 11 on 9 September 2025 with optical-sensor-driven hypertension notifications based on responses of blood vessels to heartbeat patterns across 30-day windows. This shows how established sensor modules can support a new software-led use case, although notifications are not identical to cuff blood-pressure measurement. In development september 2025, that distinction matters because revenue in 2027–2036 follows purchasing decisions for qualified devices, readers and consumables, not the number of people potentially benefiting from better sensing. For development september 2025, Repeat orders depend on practical reliability and the total cost of a successful measurement. Source - August 2025 Published
Eurostat reported that 29.9% of individuals in the European Union used smart wearables in 2024, compared with 70.9% using any internet-connected device. The difference clarifies the addressable ecosystem: connected-device prevalence creates potential exposure, but only wearables containing suitable optical physiological sensors translate into PPG device demand. In development august 2025, equipment vendors and end users weigh the sensitivity of a specific measurement against ease of calibration, lifetime cost and interpretability of its output. For development august 2025, The resulting deployment profile in 2027–2036 is more dependent on product qualification than on broad promotional comparisons. Source - October 2024 Announced
Oura introduced Ring 4 on 3 October 2024 with recessed sensors, titanium construction and adaptive Smart Sensing. Its 18-path multiband optical architecture responds to variations in finger anatomy and movement, demonstrating that optical path count, skin contact and signal selection can be central product-design parameters beyond simple heart-rate readout. In development october 2024, a sustainable supplier position requires compatible components, validated workflows and evidence that the sensing result remains dependable across different operators. For development october 2024, This is particularly relevant in 2027–2036, when product releases can advance faster than customer acceptance or replacement cycles. Source - June 2024 Published
WHO reported that roughly 1.8 billion adults, or 31% of the adult population, failed to meet recommended physical activity levels in 2022. This public-health burden creates context for activity monitoring but does not establish sensor shipment volumes; devices must prove daily usability before general wellness motivation becomes repeat purchasing. In development june 2024, device development therefore involves a commercial trade-off between the cost of acquisition and the ability to deliver repeatable measurements. For development june 2024, During 2027–2036, installation support, consumable logistics and long-term product maintenance influence adoption alongside technical improvements. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2036 |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2027–2036 |
| Historical Period | 2021–2025 |
| 2026 Market Size | USD 17,562 million |
| 2027 Estimated Size | USD 19,719 million |
| 2036 Forecast Size | USD 55,931 million |
| Growth Rate | 12.3% |
| Revenue Unit | USD million |
| Market Definition | optical reflectance and transmission photoplethysmography heart-rate sensing assemblies, associated photodiodes, optical analog front ends and finished optical-monitoring subsystems; hybrid ECG-capable products are included only for their optical heart-rate content, excluding stand-alone ECG electrodes and unrelated smartwatch electronics |
| By Type | Photoplethysmography Sensors · Electrocardiography Sensors |
| By Application | Smart Bracelet · Smart Watch · Headset · Smart Phone · Others |
| By Technology | Green LED Sensors · Red LED Sensors · Infrared Sensors · Multi-Wavelength Sensors |
| By End User | Consumer Electronics · Healthcare · Sports & Fitness · Military & Defense · Others |
| PPG sensor subtypes | Transmission-type · Reflectance-type · others |
| ECG sensor subtypes | Single-lead · Multi-lead · others |
| By Region | Regional coverage refers to customer use and purchasing geography rather than merely component fabrication sites. Asia-PacificChina · Japan · India · South Korea North AmericaUnited States · Canada · Mexico EuropeGermany · United Kingdom · Netherlands South AmericaBrazil · Chile · Colombia Middle East & AfricaSaudi Arabia · United Arab Emirates · South Africa |
| Key Companies Profiled | Analog Devices, Inc.; ROHM CO., LTD.; Maxim Integrated Products, Inc.; Philips Healthcare; AMS AG; Murata Manufacturing Co., Ltd.; Seiko Epson Corporation; New Japan Radio Co., Ltd.; Valencell, Inc.; PulseOn Oy; Polar Electro Oy |
| Customization Scope | Detailed optical technology, qualified supplier, regional sales and price-position data for optical heart rate sensor, with subtype and customer-specific growth assumptions through 2036. |
Frequently Asked Questions
How large is the global optical heart rate sensor market?
The optical heart rate sensor market was valued at USD 17,562 million in 2026 and is forecast to reach USD 55,931 million by 2036, corresponding to 12.3% CAGR for 2027–2036. Demand reflects purchasing of relevant optical sensing hardware and integrated subsystems, rather than all electronics or diagnostics associated with the same consumers. An equipment buyer also considers qualification, software and consumable requirements.
Which region has the largest optical heart rate sensor market?
Asia-Pacific has the largest estimated 2026 revenue share at ~44%, followed by North America near ~30% and Europe near ~17%. The ranking reflects local customer purchasing, supplier positioning and application mix. The manufacture of an optical component in one region does not guarantee its sale to a customer in the same region. In faq 1, the most successful applications combine a clearly specified measurement, a dependable operating environment and a channel able to resolve faults promptly. For faq 1, This reduces the risk that a theoretically sensitive detector delivers inconsistent outcomes when used by non-specialist personnel.
Which region is growing most quickly through 2036?
Asia-Pacific has the highest estimated regional growth at ~13.4% CAGR between 2027 and 2036. For renewal in supplier planning for this market during 2031, equipment selection brings calibration records, replacement-part availability, power requirements and the maturity of software workflows into one decision. For renewal in supplier planning for this market during 2032, customers distinguish laboratory sensitivity from deployable optical performance, accounting for training, servicing and a practical economic case. The profile depends on qualification and practical purchasing budgets, which is why the estimated share of a fast-growing region does not simply equal its manufacturing output.
Which sensor type represents the largest revenue share?
Photoplethysmography Sensors represents an estimated ~86% of the 2026 type allocation. For renewal in supplier planning for this market during 2033, OEM designers need reproducible signal acquisition and qualified bill-of-materials changes before a prototype can become a sustained production contract. For renewal in supplier planning for this market during 2034, the installed customer base values stable readouts, interpretable software, continued spare supply and a purchasing case based on real use. For renewal in supplier planning for this market during 2035, the route from promising photonics to revenue requires verified technical benefits, informed purchasers and reliable service arrangements. Revenue depends on genuine optical detection content, product cost and its compatibility with a validated application. Different form factors may use the same optical principle without having identical commercial prices.
Which product type offers the strongest growth?
Photoplethysmography Sensors is expected to expand fastest at ~12.5% CAGR from around ~86% of 2026 revenue. The growth scenario reflects changing use cases and product configurations, subject to reproducible performance and manufacturing economics. Wider adoption requires distribution, support and buyer willingness to qualify a new technical solution. In faq 4, between 2027–2036, stronger adoption depends on the interaction of affordability, verification and device usability. For faq 4, A functional laboratory prototype is only one stage in the commercial process; real customers require dependable supply, simple operating procedures and clearly bounded performance claims.
What is the largest application?
Smart Watch contributes an estimated ~52% of 2026 optical sensor revenue. The largest purchasing channel favours qualified light-emitting and light-detecting sensor designs, stable readings, and supplier integration into finished devices or instruments. Only actual purchases of in-scope optical sensing equipment and associated optical functionality are included in this market; unrelated electronics and software services are outside this boundary.
Which application should expand most rapidly?
Headset is projected to grow at about ~13.2% CAGR from a starting share of ~7%. The forecast reflects technology fit and customer demand rather than a guarantee that every prospective device or assay will become a qualified sale. Pricing, regulatory requirements and supplier capacity remain important constraints. In faq 6, that distinction matters because revenue in 2027–2036 follows purchasing decisions for qualified devices, readers and consumables, not the number of people potentially benefiting from better sensing. For faq 6, Repeat orders depend on practical reliability and the total cost of a successful measurement.
Which companies participate in the competitive landscape?
The profiled supplier and platform list includes Analog Devices, Inc., ROHM CO., LTD., Maxim Integrated Products, Inc., Philips Healthcare, AMS AG, Murata Manufacturing Co., Ltd.. Their commercial roles are not identical: component vendors, finished instrument developers, medical equipment firms and historical product brands should be compared by the actual sensing modality they offer. Revenue from unrelated products is outside the optical detection boundary.
What are the main adoption barriers?
Motion artifact and sensor-skin contact instability and battery drain and led duty-cycle limits can limit the pace of adoption, even as optical detectors improve. In each use case, a customer must obtain measurements that remain useful in realistic operating conditions. Service continuity, total ownership costs and appropriately documented performance are essential to long-term deployment. In faq 8, a sustainable supplier position requires compatible components, validated workflows and evidence that the sensing result remains dependable across different operators. For faq 8, This is particularly relevant in 2027–2036, when product releases can advance faster than customer acceptance or replacement cycles.
What years and segments does this report cover?
The 2026 base year is followed by 2027 as the estimated year and a 2036 forecast endpoint; historical data run from 2021 through 2025. The type segments are Photoplethysmography Sensors, Electrocardiography Sensors. Application coverage includes Smart Bracelet, Smart Watch, Headset, Smart Phone, Others across five geographic regions, supplemented by secondary technical axes and supplier analysis.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF