Key Statistics
Key Takeaways
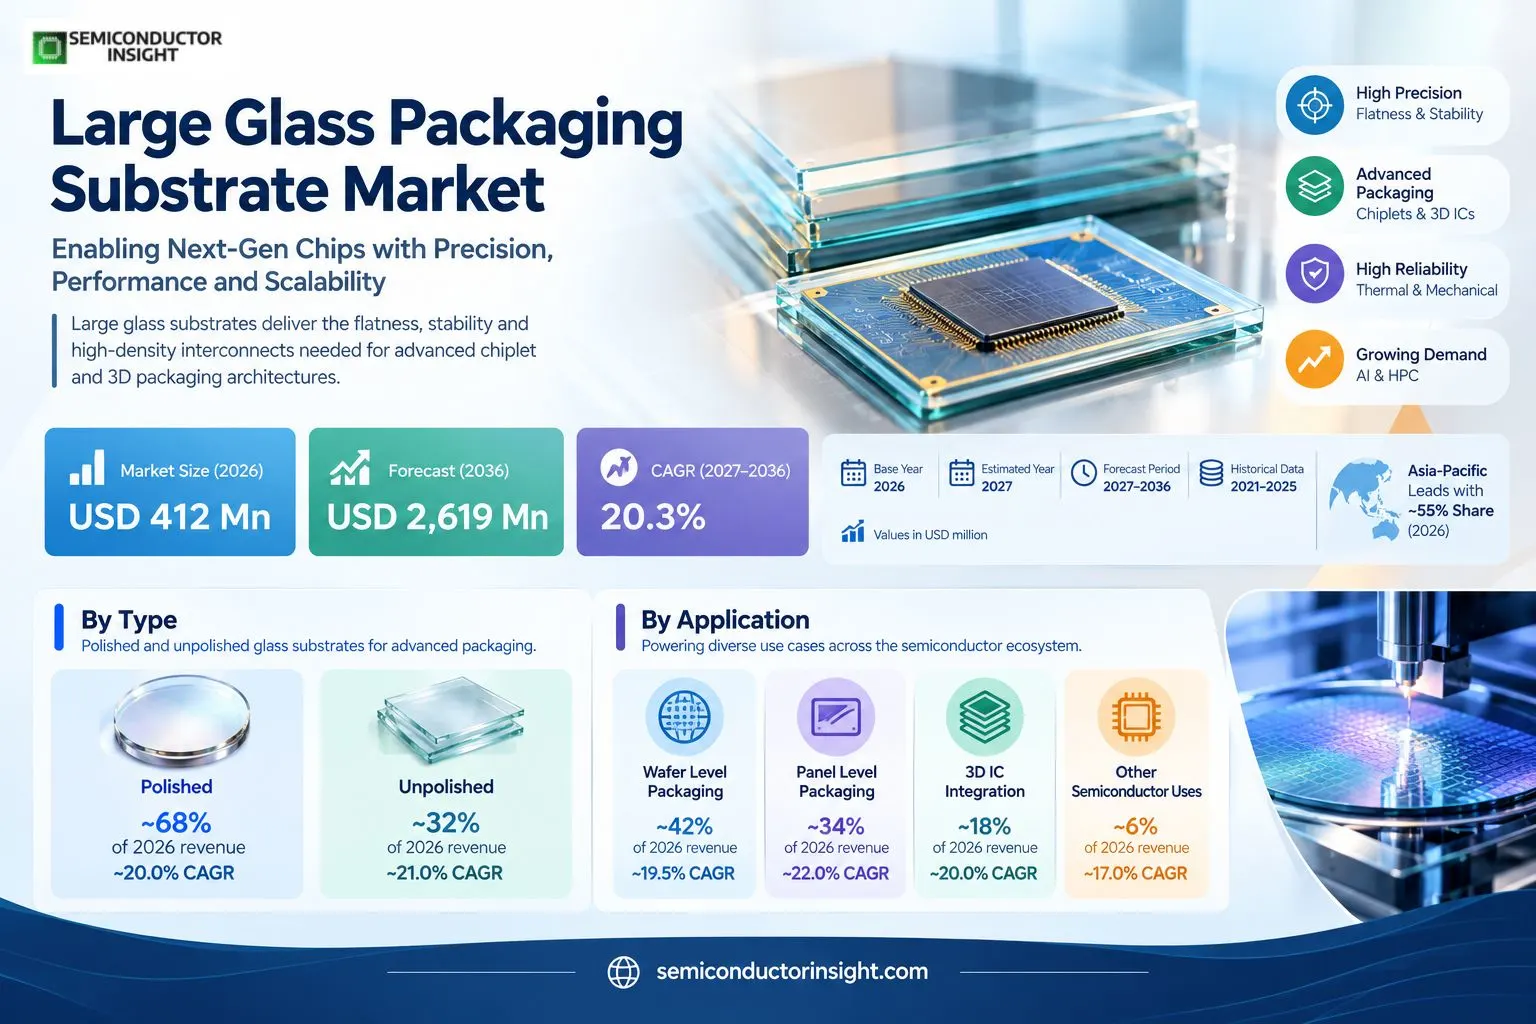
- Market trajectory: Large Glass Packaging Substrate records USD 412 million in 2026 and is projected to reach USD 2,619 million by 2036, equivalent to 20.3% growth during 2027–2036. The revenue opportunity centers on semiconductor package cores and interposers that support fine interconnects, low warpage and heterogeneous chip integration.
- Polished: the largest type with an estimated ~68% of 2026 revenue, reflects high flatness and surface quality for fine redistribution and tgv processing. Its growth path is modeled at ~20.0% CAGR, with process qualification determining realized orders.
- Wafer Level Packaging: the leading application with an estimated ~42% of 2026 revenue, depends on established wafer-format precision processing and chip-scale packaging integration. Adjacent applications have different process requirements, so equipment and material revenue cannot be treated as interchangeable.
- Asia-Pacific: the largest region at an estimated ~55% of 2026 sales, combines materials manufacturing and advanced package supply chains The other four regions differ in manufacturing capacity, investment timing and technical qualification requirements.
- Commercial qualification: Brittle glass handling, high-yield through-glass-via processing and copper metallization remain major commercialization barriers. Buyers distinguish qualified production tools and materials from research demonstrations, and they do not infer market revenue directly from broader semiconductor capital spending.
Large Glass Packaging Substrate Market Overview
Large glass packaging substrate reached USD 412 million in 2026 and is projected to attain USD 2,619 million by 2036, representing a CAGR of 20.3% during 2027–2036. Asia-Pacific accounted for an estimated ~55% of base-year revenue, supported by materials manufacturing and advanced package supply chains. Customer qualification and production integration determine how quickly technical programs become recurring commercial orders.
Large glass packaging substrates are precision-engineered glass cores or interposers used within advanced semiconductor packages to support fine electrical interconnections between chips and boards. The defined market covers permanent glass-based packaging substrates and related qualified substrate fabrication value, excluding beverage containers, cosmetic packaging, architectural glass and temporary process carriers unless explicitly sold as permanent package substrates. This distinction is essential because conventional glass industries have unrelated demand drivers and vastly different pricing units.
Glass offers dimensional stability, low dielectric loss and flatness that can help high-density chiplet packages maintain interconnect alignment. Intel announced advanced glass substrate development in September 2023, describing an order-of-magnitude improvement in design rules compared with organic alternatives. The statement is a technology direction rather than a published revenue forecast for finished glass cores. Commercial adoption requires consistent via formation, metallization and reliability through thermal cycling and assembly.
Through-glass vias provide vertical electrical paths between redistribution layers on the two sides of a glass core. AGC lists TGV substrates in wafer and panel formats, including panels around 510 × 515 mm and via diameters from 20 to 150 micrometers. Nippon Electric Glass disclosed 515 × 510 mm inorganic core development, while LPKF describes laser-based TGV formation. These examples show that material quality and process integration are jointly necessary for production.
Precision glass suppliers and process equipment developers occupy different points in the value chain. SCHOTT markets glass panels, PLANOPTIK describes metallized glass core substrates, Corning supplies advanced packaging glass carriers and semiconductor glass wafers, and LPKF provides laser processing technologies. A glass carrier used temporarily during wafer thinning is not automatically a permanent glass core substrate. Revenue attribution must follow the actual product function and customer application.
The broader semiconductor demand backdrop is strong, with the Semiconductor Industry Association reporting USD 791.7 billion in global semiconductor sales for 2025. That figure is not a measure of glass substrate revenue. Adoption is more directly tied to AI and high-performance computing package architectures, larger chiplet assemblies and the ability to achieve repeatable through-glass-via yields. Large panels can improve processing economics only when crack rates, alignment and metallization remain within production tolerances.
Segment Analysis: By Type
By type, Polished leads at an estimated ~68% of 2026 revenue, while Unpolished represents ~32%. The modeled annual growth rates of ~20.0% and ~21.0% reflect different investment patterns and process requirements. The classification follows the equipment or substrate actually sold and excludes adjacent materials or machinery not performing the defined market function.
| Type | Function | Market position |
|---|---|---|
| Polished | Polished performs precisely finished glass surfaces with controlled total thickness variation and low roughness to support fine-pitch lithography, metallization and reliable bonding. Corning and PLANOPTIK document precision glass processing relevant to these requirements. In the Polished type, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. The Polished process is assessed against the 2026 revenue share estimate of ~68% and the ~20.0% CAGR trajectory. Buyers considering the Polished type compare validated process windows and local service support before committing capital. | An estimated ~68% of 2026 revenue is associated with Polished, with ~20.0% CAGR. Polished substrates command the largest estimated revenue share because advanced package routing and alignment place a premium on flatness, surface integrity and consistent dimensional properties. In Polished procurement, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. For Polished, qualification criteria differ from those of Unpolished and influence how customers evaluate throughput and operating cost. Buyers considering Polished procurement compare validated process windows and local service support before committing capital. |
| Unpolished | Unpolished performs glass blanks or substrates that require further surface finishing before fine-feature processing, depending on the target package architecture. Material composition and dimensional stability remain important even when the initial surface specification is less demanding. In the Unpolished type, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. The Unpolished process is assessed against the 2026 revenue share estimate of ~32% and the ~21.0% CAGR trajectory. Buyers considering the Unpolished type compare validated process windows and local service support before committing capital. | An estimated ~32% of 2026 revenue is associated with Unpolished, with ~21.0% CAGR. The unpolished category serves intermediate processing and selected applications where subsequent grinding or polishing is part of the customer flow; it should not be assumed suitable for every fine-pitch package without qualification. In Unpolished procurement, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. For Unpolished, qualification criteria differ from those of Polished and influence how customers evaluate throughput and operating cost. Buyers considering Unpolished procurement compare validated process windows and local service support before committing capital. |
Polished
Polished is commercially differentiated by high flatness and surface quality for fine redistribution and tgv processing. The Polished technical requirements include stable processing windows and reliable interfaces to adjacent production stages. In Polished process integration, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Its estimated ~68% share should be interpreted as a revenue allocation within the exact market. Buyers considering Polished process integration compare validated process windows and local service support before committing capital.
The growth outlook for Polished is ~20.0% annually from the 2026 base. The Polished production case is assessed through a combination of tool utilization, qualified yield and compatibility with established manufacturing recipes. A supplier of Polished must also demonstrate that equipment maintains process consistency when carrier dimensions, material formulations or package complexity change.
Unpolished
Unpolished is commercially differentiated by cost-sensitive processing paths and selected intermediate substrate uses. The Unpolished technical requirements include stable processing windows and reliable interfaces to adjacent production stages. In Unpolished process integration, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Its estimated ~32% share should be interpreted as a revenue allocation within the exact market. Buyers considering Unpolished process integration compare validated process windows and local service support before committing capital.
The growth outlook for Unpolished is ~21.0% annually from the 2026 base. The Unpolished production case is assessed through a combination of tool utilization, qualified yield and compatibility with established manufacturing recipes. A supplier of Unpolished must also demonstrate that equipment maintains process consistency when carrier dimensions, material formulations or package complexity change.
Segment Analysis: By Application
Applications are led by Wafer Level Packaging at an estimated ~42% of 2026 revenue, followed by Panel Level Packaging at ~34%. Their modeled growth rates are ~19.5% and ~22.0% respectively. Application mix depends on the relative value of qualified process steps rather than the number of finished chips or packages alone.
| Application | Demand characteristics |
|---|---|
| Wafer Level Packaging | Wafer Level Packaging represents an estimated ~42% of 2026 demand and ~19.5% CAGR. Wafer-level use requires glass cores or interposers compatible with precision lithography, fine vias and reliable bonding. Standard wafer formats support existing process tools, but high-density interconnects still require stringent flatness and via quality. In the Wafer Level Packaging application, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. established wafer-format precision processing and chip-scale packaging integration. Buyers considering the Wafer Level Packaging application compare validated process windows and local service support before committing capital. |
| Panel Level Packaging | Panel Level Packaging represents an estimated ~34% of 2026 demand and ~22.0% CAGR. Panel-level glass packaging seeks to scale substrate area beyond conventional wafers. AGC, NEG and LPKF describe panels around 510 × 515 mm, while process engineers must manage glass fragility, via uniformity and registration across large areas. In the Panel Level Packaging application, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. larger rectangular carriers and higher potential area utilization. Buyers considering the Panel Level Packaging application compare validated process windows and local service support before committing capital. |
| 3D IC Integration | 3D IC Integration represents an estimated ~18% of 2026 demand and ~20.0% CAGR. Glass interposers with through-glass vias can provide vertical interconnection paths for complex multi-die packages. Electrical loss, CTE matching and fine redistribution layers determine suitability for advanced compute, memory and RF designs. In the 3D IC Integration application, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. vertical routing and heterogeneous chiplet interconnect density. Buyers considering the 3D IC Integration application compare validated process windows and local service support before committing capital. |
| Other Semiconductor Uses | Other Semiconductor Uses represents an estimated ~6% of 2026 demand and ~17.0% CAGR. Specialty applications include glass-based RF structures, MEMS packaging and precision substrates for niche devices. Volumes are smaller and qualification is application-specific, so a material used as a temporary carrier should not automatically be counted as a permanent package core. |
Wafer Level Packaging is a distinct demand pool because established wafer-format precision processing and chip-scale packaging integration. The modeled base-year share is ~42%, with ~19.5% CAGR through 2036. In Wafer Level Packaging commercialization, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Investment in Wafer Level Packaging is governed by process yield, application-specific reliability and production capacity rather than generic semiconductor market growth. Buyers considering Wafer Level Packaging commercialization compare validated process windows and local service support before committing capital.
Panel Level Packaging is a distinct demand pool because larger rectangular carriers and higher potential area utilization. The modeled base-year share is ~34%, with ~22.0% CAGR through 2036. In Panel Level Packaging commercialization, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Investment in Panel Level Packaging is governed by process yield, application-specific reliability and production capacity rather than generic semiconductor market growth. Buyers considering Panel Level Packaging commercialization compare validated process windows and local service support before committing capital.
3D IC Integration is a distinct demand pool because vertical routing and heterogeneous chiplet interconnect density. The modeled base-year share is ~18%, with ~20.0% CAGR through 2036. In 3D IC Integration commercialization, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Investment in 3D IC Integration is governed by process yield, application-specific reliability and production capacity rather than generic semiconductor market growth. Buyers considering 3D IC Integration commercialization compare validated process windows and local service support before committing capital.
Other Semiconductor Uses is a distinct demand pool because specialty sensors, rf interposers and microelectronic packaging. The modeled base-year share is ~6%, with ~17.0% CAGR through 2036. In Other Semiconductor Uses commercialization, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Investment in Other Semiconductor Uses is governed by process yield, application-specific reliability and production capacity rather than generic semiconductor market growth. Buyers considering Other Semiconductor Uses commercialization compare validated process windows and local service support before committing capital.
Regional Analysis
Asia-Pacific holds an estimated ~55% share of Large Glass Packaging Substrate revenue in 2026, followed by North America (~24%) and Europe (~15%). The remaining regions account for ~3% and ~3%. Regional growth varies with installed semiconductor packaging capacity, customer qualification programs, materials supply and investment in advanced manufacturing. Commercial shipments follow successful product qualification and process integration rather than development announcements alone.
What drives regional demand for large glass packaging substrate?
Asia-Pacific has the largest concentration of glass materials engineering and semiconductor packaging customers. Japan-based AGC and Nippon Electric Glass document panel-capable through-glass-via substrates, while South Korean investment in glass-core commercialization provides another supply-chain path. Taiwan contributes advanced packaging demand. North America supports design and commercialization activity, and Europe contributes specialty glass, laser processing and metallization expertise.
The 2026 allocation assigns Asia-Pacific an estimated ~55% share with ~20.7% CAGR, North America ~24% with ~21.2%, Europe ~15% with ~18.3%, South America ~3% with ~18.2%, and Middle East & Africa ~3% with ~17.3%. These estimates apply only to semiconductor glass packaging substrates. Conventional beverage glass, display glass and temporary carriers are outside the permanent glass-core revenue boundary unless specifically qualified as package substrates.
Glass-core commercialization requires several process steps to work together. Intel’s development announcement, NEG’s large-panel samples and LPKF’s laser processing capabilities indicate technical progress but do not establish the same degree of commercial maturity. Regional demand is therefore shaped by customer qualification, via yield, metallization, warpage, packaging reliability and whether the finished substrate can compete economically with organic or silicon-based alternatives.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Estimated ~55% of 2026 revenue | ~20.7% CAGR | Materials manufacturing and advanced package supply chains | In Asia-Pacific, customers prioritize japan, south korea and china have significant glass and semiconductor packaging expertise, while taiwanese osat activity supports large-carrier process qualification.. The regional share of ~55% and growth rate of ~20.7% reflect qualification and production investment patterns. In Asia-Pacific vendor selection, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Buyers in Asia-Pacific compare process support and the economic return from equipment or substrate procurement. Buyers considering Asia-Pacific vendor selection compare validated process windows and local service support before committing capital. |
| North America | Estimated ~24% of 2026 revenue | ~21.2% CAGR | Advanced packaging R&D and commercialization | In North America, customers prioritize united states chiplet and ai packaging research drives glass-core design work, while substrate manufacturing may be performed domestically or in overseas facilities.. The regional share of ~24% and growth rate of ~21.2% reflect qualification and production investment patterns. In North America vendor selection, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Buyers in North America compare process support and the economic return from equipment or substrate procurement. Buyers considering North America vendor selection compare validated process windows and local service support before committing capital. |
| Europe | Estimated ~15% of 2026 revenue | ~18.3% CAGR | Glass processing technology and materials engineering | In Europe, customers prioritize germany and neighboring european countries contribute specialty glass, laser microstructuring and high-precision substrate processing capabilities.. The regional share of ~15% and growth rate of ~18.3% reflect qualification and production investment patterns. In Europe vendor selection, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Buyers in Europe compare process support and the economic return from equipment or substrate procurement. Buyers considering Europe vendor selection compare validated process windows and local service support before committing capital. |
| South America | Estimated ~3% of 2026 revenue | ~18.2% CAGR | Specialty electronics and imported material demand | In South America, customers prioritize regional demand is early-stage and tied to specialized electronics, research and imported packaging substrates rather than a large domestic glass-core manufacturing base.. The regional share of ~3% and growth rate of ~18.2% reflect qualification and production investment patterns. In South America vendor selection, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Buyers in South America compare process support and the economic return from equipment or substrate procurement. Buyers considering South America vendor selection compare validated process windows and local service support before committing capital. |
| Middle East & Africa | Estimated ~3% of 2026 revenue | ~17.3% CAGR | Emerging research and semiconductor initiatives | In Middle East & Africa, customers prioritize the region is a small base for glass-core substrate demand, with opportunities tied to research, advanced electronics and possible future semiconductor packaging investments.. The regional share of ~3% and growth rate of ~17.3% reflect qualification and production investment patterns. In Middle East & Africa vendor selection, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Buyers in Middle East & Africa compare process support and the economic return from equipment or substrate procurement. Buyers considering Middle East & Africa vendor selection compare validated process windows and local service support before committing capital. |
Competitive Landscape and Supplier Positioning
Competition spans glass material suppliers, core-substrate developers, laser-processing equipment companies and semiconductor package designers. AGC, Nippon Electric Glass, SCHOTT and PLANOPTIK document relevant glass materials or substrates, while LPKF supplies enabling process technology. Intel is a technology developer and potential adopter, not necessarily an independent glass-substrate merchant. Supplier categories must be kept separate when interpreting revenue.
AGC offers through-glass-via substrates with customer-defined via patterns and wafer or panel formats. The company emphasizes flatness, low dielectric loss and CTE properties appropriate for semiconductor packaging. Nippon Electric Glass has developed glass and glass-ceramic core substrates, including 515 × 510 mm formats and alternative via-processing methods. Both suppliers address material and processing constraints that determine whether glass can replace organic cores in production packages.
SCHOTT describes precision glass panels for heterogeneous packaging and through-glass-via metallization. PLANOPTIK documents glass core substrates with TGVs, copper metallization and redistribution-layer processing. Corning supplies semiconductor glass wafers and advanced packaging carriers, including temporary-bonding products. These portfolios overlap technically but not completely commercially, so a carrier wafer used during manufacturing should not automatically be included in permanent core-substrate sales.
LPKF develops laser-induced deep etching and related glass processing systems, while its collaboration with Onto Innovation addresses integration of multiple panel packaging steps. Equipment sales support the glass-core ecosystem but are not the same revenue stream as finished glass substrates. A commercial supply model should distinguish glass blanks, patterned cores, metallized interposers and the tools used to manufacture them.
Intel announced glass substrate technology for future high-performance packages in 2023, and SKC has described Absolics glass-core commercialization investment in the United States. These initiatives indicate customer interest and potential supply expansion, but announced facilities and technical demonstrations do not establish audited annual glass-substrate sales. Adoption depends on substrate reliability, manufacturable fine routing and production economics relative to organic and silicon-based alternatives.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Glass materials and substrates | AGC; Nippon Electric Glass; SCHOTT; PLANOPTIK | Suppliers with documented glass panel, glass core or through-glass-via substrate capabilities for advanced semiconductor packaging. Their products differ in thickness, finishing, via processing and metallization. In Glass materials and substrates competitive tier, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. The Glass materials and substrates distinction separates actual in-scope suppliers from adjacent value-chain participants and customers. Buyers considering Glass materials and substrates competitive tier compare validated process windows and local service support before committing capital. |
| Processing and precision glass | LPKF; Corning | Companies providing enabling laser microstructuring, advanced carriers or precision glass wafers. Some products are process inputs rather than permanent cores, requiring careful revenue classification. In Processing and precision glass competitive tier, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. The Processing and precision glass distinction separates actual in-scope suppliers from adjacent value-chain participants and customers. Buyers considering Processing and precision glass competitive tier compare validated process windows and local service support before committing capital. |
| Technology development and commercialization | Intel; SKC / Absolics | Organizations investing in glass substrate architecture or commercialization. Announced development programs should not be treated as completed substrate sales until commercial supply and qualification are established. In Technology development and commercialization competitive tier, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. The Technology development and commercialization distinction separates actual in-scope suppliers from adjacent value-chain participants and customers. Buyers considering Technology development and commercialization competitive tier compare validated process windows and local service support before committing capital. |
Key companies profiled
- AGC
- Nippon Electric Glass
- SCHOTT
- PLANOPTIK
- Corning
- LPKF
- SKC / Absolics
- Intel
Glass Core Processing, TGVs and Manufacturing Qualification
Glass core substrates require precise material composition, surface finishing, through-glass-via formation and reliable metallization. Large panels add mechanical handling and dimensional uniformity challenges. The main engineering hurdle is maintaining crack-free vias, fine routing and acceptable warpage through subsequent semiconductor package assembly and thermal cycling. Material handling and inspection procedures must also remain stable as substrate dimensions increase.
AGC describes glass with through-glass vias in wafer and panel formats, including 510 × 515 mm panels and 20–150 micrometer hole diameters. The substrate must maintain electrical insulation and dimensional stability while supporting copper routing. Actual manufacturability depends on the selected glass composition, thickness, via aspect ratio and metallization process, not simply the availability of a nominal hole diameter.
Nippon Electric Glass disclosed 515 × 510 mm inorganic cores and later announced two TGV glass-core approaches, including laser modification with etching and CO2 laser processing. The company emphasizes productivity and alternative drilling methods for large substrates. These announcements demonstrate technology development and sample supply, but commercial adoption requires qualified panel yields and customer package reliability testing.
LPKF describes laser-induced deep etching to create precise glass vias without conventional mechanical damage, and its NEXAR systems target wafer and panel automation. PLANOPTIK offers metallized glass cores and precision finishing. Together the disclosures show that a viable product is not just a glass sheet: it requires tightly controlled via sidewalls, metallization adhesion, routing registration and downstream assembly compatibility.
Market Dynamics, Constraints and Opportunities
The main growth drivers are higher-density chiplet packaging, larger substrate formats and demand for low-loss electrical interconnects. Barriers include glass brittleness, via-processing yield, metallization integration and competition from mature organic substrates. Commercial growth depends on successful customer qualification rather than the number of glass technology announcements. Suppliers must demonstrate repeatable process yields at the actual production panel size.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Chiplet interconnect density | +3.4% | Asia-Pacific and North America | 2027–2036 |
| Large-panel process development | +2.6% | Asia-Pacific and Europe | 2027–2034 |
| TGV process improvements | +2.1% | Global | 2027–2036 |
Higher interconnect density
Intel identified glass substrates as a route to much finer interconnect design rules for future high-performance packages. Glass flatness and dielectric characteristics can help complex chiplet assemblies, provided fine routing and vias are manufactured reliably. Demand emerges when customers qualify glass cores for real package architectures, not simply when new AI processors are announced.
Panel-scale manufacturing
AGC and Nippon Electric Glass document panel-capable substrates around 510 × 515 mm, while LPKF describes panel-level processing. Larger formats can improve material utilization and processing economics if yield remains high. The benefit depends on consistent via formation, handling and metallization across the full panel, making equipment and process integration essential.
Through-glass-via innovation
NEG has announced alternative glass via-processing approaches, and LPKF describes laser-induced deep etching for precision features. Better via yield and reduced damage can lower the cost of producing metallized glass cores. Customers still need evidence of electrical performance, long-term reliability and compatibility with redistribution-layer processing before replacing conventional substrates. Long-term testing of the finished semiconductor package is also essential.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Brittle glass and handling | −2.2% | Large-panel production | 2027–2036 |
| TGV yield and metallization | −1.8% | Global | 2027–2035 |
| Organic substrate competition | −1.6% | AI and HPC packaging | 2027–2036 |
Fragility and panel handling
Glass is dimensionally stable but brittle, so scratches, edge defects and microcracks can damage large substrates during processing. Panel-scale manufacturing requires careful handling, inspection and defect control. Suppliers must demonstrate that improved flatness outweighs losses from breakage and that glass can survive bonding, redistribution and package assembly without unacceptable scrap.
Via and metallization yield
Through-glass vias require precise formation and reliable conductive lining or filling. Variations in hole geometry, sidewall condition and metallization adhesion can reduce electrical yield. NEG and LPKF are developing alternative process approaches, but each must be validated on the customer’s actual glass thickness, panel format and package design before commercial deployment.
Competition from established materials
Organic package substrates and silicon interposers have mature manufacturing ecosystems and qualified design flows. Glass must provide a sufficient gain in interconnect density, signal integrity or package stability to justify new processing tools and reliability testing. A laboratory demonstration is not enough if the finished package cost or production yield remains inferior to existing solutions.
MARKET OPPORTUNITIES
AI and chiplet package scaling
Larger multi-die packages for AI and high-performance computing need dense interconnects and stable substrates. Intel’s development work and supplier glass-core programs address this requirement. The opportunity is strongest where organic substrates face warpage or routing constraints, but commercial conversion requires a qualified glass process and a clear total-cost advantage. Package designers must also verify dielectric behavior, thermal cycling and the supply of qualified substrates.
Large glass panels
Panel formats around 510 × 515 mm can support processing of multiple large package substrates in one manufacturing flow. AGC, NEG and LPKF document relevant material and equipment capabilities. Scaling depends on uniformity, via yield, metallization and automated handling, so announced panel dimensions should be treated as capability indicators rather than production volume.
Precision processing partnerships
LPKF and Onto Innovation announced collaboration around panel-level glass-core manufacturing process integration in 2025. Partnerships can help connect via formation, inspection, metallization and other manufacturing steps. Suppliers that shorten qualification cycles and improve reproducibility may capture incremental value, but equipment partnership announcements are not themselves evidence of substrate revenue. Production validation remains necessary before those collaborations translate into qualified glass cores.
Glass Materials, TGV Processing and Packaging Supply Chain
The glass-core value chain starts with specialty glass formulation and sheet production, then surface finishing, via formation, metallization, redistribution and package assembly. Some companies supply temporary carriers or laser equipment rather than permanent substrates. Revenue analysis must follow the actual material sold and its use within the finished semiconductor package.
Material formulation. Glass composition and thermal expansion influence package stress and high-frequency electrical performance. AGC and NEG document non-alkali and engineered inorganic substrate approaches. Customers select material properties against the actual chip and board architecture rather than treating all glass sheets as equivalent. Qualification must cover dielectric performance, rigidity and long-term thermal cycling. In Material formulation supply-chain issue, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Commercial results for Material formulation depend on customer acceptance, materials availability and repeatable production yield. Buyers considering Material formulation supply-chain issue compare validated process windows and local service support before committing capital.
Via processing. Through-glass-via fabrication is a central cost and yield driver. LPKF uses laser-induced modification followed by etching, while NEG has disclosed multiple processing paths including CO2 laser approaches. Each method has different requirements for hole geometry, glass thickness and damage control. Manufacturing economics depend on throughput and reliable metallization after via formation. In Via processing supply-chain issue, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Commercial results for Via processing depend on customer acceptance, materials availability and repeatable production yield. Buyers considering Via processing supply-chain issue compare validated process windows and local service support before committing capital.
Panel finishing and handling. Large glass panels require careful edge quality, flatness and automated transport. Corning describes advanced packaging carriers with controlled thermal expansion and reduced warpage, while NEG reports 515 × 510 mm inorganic cores. Carriers used temporarily during processing should be classified separately from permanent cores in revenue models and supplier comparisons. In Panel finishing and handling supply-chain issue, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Commercial results for Panel finishing and handling depend on customer acceptance, materials availability and repeatable production yield. Buyers considering Panel finishing and handling supply-chain issue compare validated process windows and local service support before committing capital.
Commercial integration. A finished glass substrate must integrate with redistribution layers, chip bonding and downstream package assembly. PLANOPTIK documents copper metallization and TGV processing, and LPKF participates in packaging process integration partnerships. Buyers assess yield and package reliability across the full manufacturing flow, not simply the material supplier’s isolated glass property measurements. In Commercial integration supply-chain issue, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. Commercial results for Commercial integration depend on customer acceptance, materials availability and repeatable production yield. Buyers considering Commercial integration supply-chain issue compare validated process windows and local service support before committing capital.
Recent Developments in Large Glass Packaging Substrate
- January 2026 SEMICONDUCTOR MATERIALS
AGC showcased semiconductor solutions for AI-era packaging at CES 2026, including glass cores and through-glass-via substrates. The exhibition highlights continued investment in advanced glass materials for high-density packaging. It does not establish the revenue of any particular customer program; adoption depends on subsequent material qualification and production integration. In January 2026 SEMICONDUCTOR MATERIALS event, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. The January 2026 SEMICONDUCTOR MATERIALS event provides technology or industry context and does not by itself measure direct market revenue. Buyers considering January 2026 SEMICONDUCTOR MATERIALS event compare validated process windows and local service support before committing capital. Source - 22 May 2025 GLASS CORE SAMPLES
Nippon Electric Glass announced development and sample supply of large through-glass-via glass cores compatible with laser modification and etching or CO2 laser processing. The disclosed formats include 515 × 510 mm panels. The development expands processing options for semiconductor packaging customers, while commercial scaling remains contingent on via yield and assembly reliability. Source - 2 April 2025 PROCESS INTEGRATION
LPKF announced its collaboration with Onto Innovation’s Packaging Applications Center of Excellence, aiming to accelerate glass-core substrate process integration and panel-level packaging commercialization. The partnership addresses the coordination of laser processing with other manufacturing steps. It is an enabling technology development rather than an audited measure of finished glass substrate sales. In 2 April 2025 PROCESS INTEGRATION event, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. The 2 April 2025 PROCESS INTEGRATION event provides technology or industry context and does not by itself measure direct market revenue. Buyers considering 2 April 2025 PROCESS INTEGRATION event compare validated process windows and local service support before committing capital. Source - 15 January 2025 LARGE PANEL
Nippon Electric Glass announced a 515 × 510 mm glass-ceramic GC Core substrate for next-generation semiconductor packages. The larger format was intended to improve processing efficiency and support bigger chiplet assemblies. It demonstrates a material development milestone, but qualification of the complete packaging flow is still needed before announced dimensions translate into volume revenue. Source - 4 December 2024 VIA PROCESS
Nippon Electric Glass announced development of a glass core substrate compatible with CO2 laser via processing. The approach targets a more accessible manufacturing route for fine through-holes in semiconductor packaging cores. The commercial significance depends on avoiding cracks and achieving acceptable via yield at scale, not simply on compatibility with an established laser type. Source - 19 November 2024 JOINT DEVELOPMENT
Nippon Electric Glass announced a joint development agreement with Via Mechanics to accelerate glass and glass-ceramic inorganic core substrate processing. The collaboration addresses equipment and materials integration needed for next-generation packages. The announcement is a development agreement rather than confirmation of a commercial volume production contract or measured substrate market share. In 19 November 2024 JOINT DEVELOPMENT event, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. The 19 November 2024 JOINT DEVELOPMENT event provides technology or industry context and does not by itself measure direct market revenue. Buyers considering 19 November 2024 JOINT DEVELOPMENT event compare validated process windows and local service support before committing capital. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Report title | Large Glass Packaging Substrate Market Trends, Business Strategies 2026–2036 |
| Base year | 2026: USD 412 million |
| Estimated year | 2027: USD 496 million |
| Forecast year | 2036: USD 2,619 million |
| Forecast CAGR | 20.3% during 2027–2036 |
| Revenue boundary | Revenue from permanent large glass cores, metallized glass interposers and qualified semiconductor packaging substrates. Excludes consumer glass containers, display panels, architectural glass, temporary glass carriers when not permanent package substrates, and processing-equipment sales. |
| Study period | 2021–2036, with 2021–2025 historical context and 2027–2036 forecast |
| By Type | Polished · Unpolished |
| By Application | Wafer Level Packaging · Panel Level Packaging · 3D IC Integration · Other Semiconductor Uses |
| By End User | Semiconductor Manufacturers · OSAT Providers · Integrated Device Manufacturers |
| By Manufacturing Process | Thermal Processing · Chemical Strengthening · Mechanical Processing |
| By Region | Five-region 2026 revenue allocation; shares are estimates within the defined market. Asia-PacificJapan, South Korea, Taiwan North AmericaUnited States, Canada, Mexico EuropeGermany, Netherlands, France South AmericaBrazil, Argentina, Chile Middle East & AfricaIsrael, United Arab Emirates, South Africa |
| Key Companies Profiled | AGC · Nippon Electric Glass · SCHOTT · PLANOPTIK · Corning · LPKF · SKC / Absolics · Intel |
| Customization Scope | Glass formulation, TGV geometry, panel sizes, metallization, manufacturing yield, package reliability and regional customer qualification. |
Frequently Asked Questions
How large is the large glass packaging substrate market?
The global semiconductor glass packaging substrate market was USD 412 million in 2026 and is projected to reach USD 2,619 million by 2036, implying 20.3% annual growth. The revenue boundary covers permanent glass package cores and interposers rather than beverage glass, display panels, general glass containers or unrelated processing equipment. In How large is the large glass packaging substrate market?, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. For the question of how large is the large glass packaging substrate market?, the interpretation applies only to the defined large glass packaging substrate revenue boundary and should not be extended to unrelated semiconductor equipment or materials. Buyers considering How large is the large glass packaging substrate market? compare validated process windows and local service support before committing capital.
Which type holds the largest share?
Polished glass substrates lead with an estimated ~68% of 2026 revenue, while unpolished substrates account for ~32%. High-density semiconductor packaging requires controlled surface quality, flatness and thickness variation for fine redistribution and metallization. The classification reflects the state of the substrate supplied and should not be confused with temporary carrier glass used during processing.
Which application leads glass substrate demand?
Wafer Level Packaging accounts for an estimated ~42% of 2026 revenue, followed by Panel Level Packaging at ~34% and 3D IC Integration at ~18%. Wafer formats use established precision processing, while panels can improve area utilization if via uniformity and handling yield remain acceptable. Application shares are modeled revenue allocations rather than shipment counts.
Which region is the largest market?
Asia-Pacific leads with an estimated ~55% of 2026 revenue, supported by Japanese glass suppliers and Asian semiconductor packaging customers. North America accounts for ~24% and Europe ~15%. The distribution reflects glass-core and interposer activity, not conventional flat glass production or total semiconductor equipment spending. In Which region is the largest market?, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. For the question of which region is the largest market?, the interpretation applies only to the defined large glass packaging substrate revenue boundary and should not be extended to unrelated semiconductor equipment or materials. Buyers considering Which region is the largest market? compare validated process windows and local service support before committing capital.
What are through-glass vias?
Through-glass vias are conductive paths formed through a glass substrate to connect redistribution layers on opposite surfaces. AGC documents wafer and panel TGV substrates, while NEG and LPKF describe processing approaches. Commercial success depends on precise hole geometry, reliable metallization, low defect rates and package-level electrical and mechanical reliability. In What are through-glass vias?, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. For the question of what are through-glass vias?, the interpretation applies only to the defined large glass packaging substrate revenue boundary and should not be extended to unrelated semiconductor equipment or materials. Buyers considering What are through-glass vias? compare validated process windows and local service support before committing capital.
Why is glass attractive for chiplet packaging?
Glass offers flatness, rigidity, tunable thermal expansion and favorable high-frequency dielectric properties that can support dense interconnects. Intel announced development of glass substrates for advanced packages in 2023. The material must still compete with mature organic substrates and silicon interposers on manufacturing yield, reliability and total package cost. In Why is glass attractive for chiplet packaging?, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. For the question of why is glass attractive for chiplet packaging?, the interpretation applies only to the defined large glass packaging substrate revenue boundary and should not be extended to unrelated semiconductor equipment or materials. Buyers considering Why is glass attractive for chiplet packaging? compare validated process windows and local service support before committing capital.
What is the role of large panels?
Large glass panels can process multiple package cores with potentially better area utilization than smaller carriers. Nippon Electric Glass announced 515 × 510 mm substrates, and AGC lists similar panel-capable TGV products. Larger area also increases handling, uniformity and crack-control challenges, so commercial advantage depends on yield after all processing steps. In What is the role of large panels?, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. For the question of what is the role of large panels?, the interpretation applies only to the defined large glass packaging substrate revenue boundary and should not be extended to unrelated semiconductor equipment or materials. Buyers considering What is the role of large panels? compare validated process windows and local service support before committing capital.
Which companies supply relevant technology?
AGC, Nippon Electric Glass, SCHOTT and PLANOPTIK document glass substrate or panel capabilities, while LPKF provides enabling processing equipment. Corning supplies precision semiconductor glass and carriers, and Intel has disclosed advanced packaging development. The value chain includes different roles, so not every participant should be classified as a merchant supplier of permanent glass cores.
What limits adoption of glass cores?
Glass brittleness, through-glass-via yield, metallization adhesion and competition from established organic package substrates are major barriers. A supplier must demonstrate stable performance through bonding, thermal cycling and package assembly. Process equipment and material improvements are useful only if they lower the cost of qualified finished substrates at production scale. In What limits adoption of glass cores?, the economic impact depends on qualified throughput, material compatibility, production yield and equipment uptime rather than the nominal capability of a demonstration. For the question of what limits adoption of glass cores?, the interpretation applies only to the defined large glass packaging substrate revenue boundary and should not be extended to unrelated semiconductor equipment or materials. Buyers considering What limits adoption of glass cores? compare validated process windows and local service support before committing capital.
How should customers qualify glass packaging substrates?
Customers should evaluate glass composition, coefficient of thermal expansion, flatness, total thickness variation, via geometry, metallization, electrical loss and mechanical reliability. Pilot runs must reproduce these properties across the intended wafer or panel format. The total-cost assessment should include scrap, handling, processing tools, supplier support and integration with existing chiplet package assembly flows.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF