Key Statistics
Key Takeaways
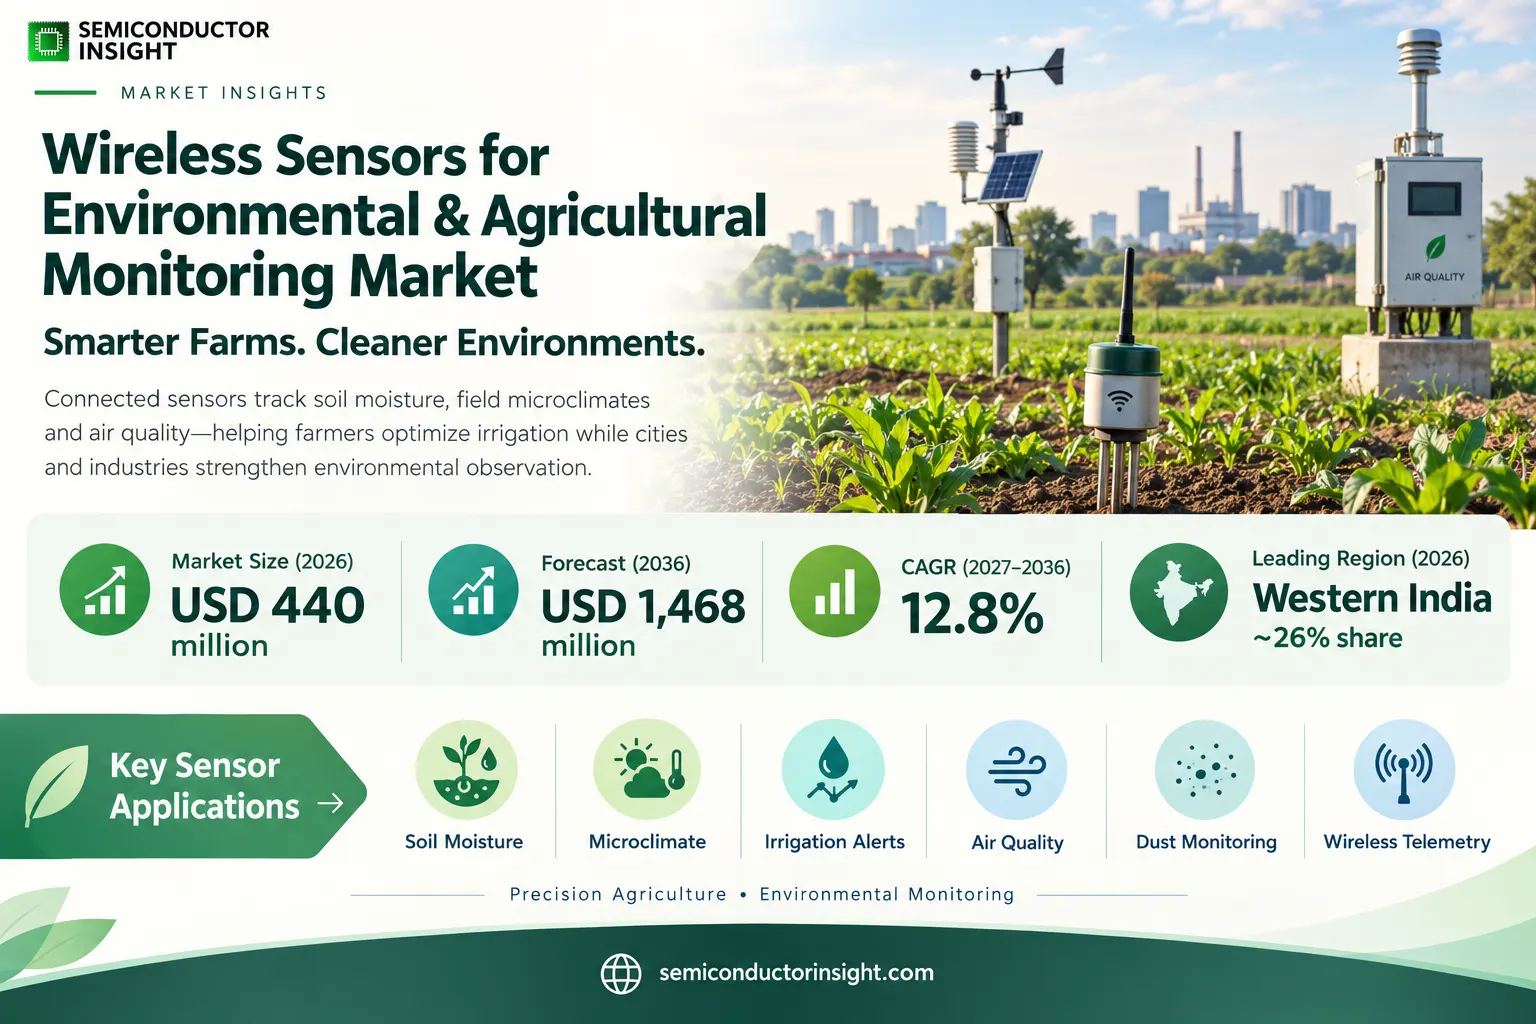
- Market trajectory: The India wireless sensors for environmental and agricultural monitoring market stands at USD 440 million in 2026 and is projected to reach USD 1,468 million by 2036, growing at 12.8% through 2027–2036 as soil-moisture telemetry, irrigation control and distributed air-quality monitoring become more widely deployed across Indian states.
- Monitoring & Control: The largest product class represents an estimated ~56% of 2026 market revenue. Monitoring and control devices generate recurring demand from irrigation, soil telemetry and environmental networks because field data must be converted into reliable operational decisions. Growth rates differ across categories as application requirements change.
- Precision Agriculture: This application contributes an estimated ~61% of 2026 revenue. Precision agriculture purchases prioritize soil moisture, weather and irrigation feedback, supported by field-device platforms and government research on water efficiency. Its commercial role differs from adjacent applications with different purchasing cycles.
- Western India: The leading geographic market accounts for an estimated ~26% of 2026 revenue, with projected growth of ~13.2% CAGR. Western India combines horticulture, irrigation technology and verified urban air-quality deployments, including monitoring networks in Pune and Chiplun.
- Commercial constraints: Small farm budgets, patchy connectivity, calibration burdens and maintenance in dusty or monsoon-exposed locations constrain network scale. These conditions influence qualification, purchasing schedules and the mix of premium versus value-oriented devices.
India Wireless Sensors for Environmental and Agricultural Monitoring Market Overview
The India wireless sensors for environmental and agricultural monitoring market was valued at USD 440 million in 2026 and is projected to reach USD 1,468 million by 2036, growing at a CAGR of 12.8% over 2027–2036. Western India accounted for an estimated ~26% of 2026 revenue, while other geographic markets reflected different application and supply-chain conditions.
Wireless sensors for environmental and agricultural monitoring measure soil moisture, field microclimate, air pollution and related variables before sending data to gateways or cloud applications. In India, these devices serve two distinct purchasing environments: farm irrigation and crop decisions, and urban or industrial environmental observation. Hardware revenue should be distinguished from broad software subscriptions and unrelated smart-city infrastructure.
The Digital Agriculture Mission approved in September 2024 carries a government outlay of INR 2,817 crore and supports digital public infrastructure, geospatial data and farmer services. That programme is an enabling policy context, not an allocation entirely available to sensor suppliers. Actual hardware procurement depends on field trials, crop economics, local deployment partners and data interoperability.
ICAR inaugurated an IoT-enabled soil-monitoring system in Patna in May 2026 in collaboration with BIT Mesra. The institution explicitly described calibration and field-performance evaluation as ongoing, highlighting the difference between an operational research pilot and a scaled commercial deployment. Soil moisture data can guide irrigation only when sensors are calibrated for local soils and placed at meaningful root depths.
Private suppliers offer increasingly integrated systems. Fasal describes a 12-sensor field weather station and a separate soil-moisture unit with mobile alerts, while Semtech documents low-power LoRa connectivity for remote farm telemetry. Such devices must combine sensing, power and actionable agronomy, rather than merely transmit measurements that farmers cannot use. For Private suppliers, procurement depends on soil placement and calibration together with battery maintenance, telemetry and actionable alerts, rather than on an isolated catalogue specification. That combination determines water-use efficiency and farmer adoption for Private suppliers; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order.
Environmental monitoring adds a different commercial channel. Oizom documents 16 custom monitoring stations in Pune in June 2025, 50 instruments in Varanasi, and a January 2025 dust-monitoring project at Raj Transit in Mira Bhayandar. These examples demonstrate distributed air-quality demand, although low-cost sensors complement rather than replace reference-grade regulatory instruments and require ongoing calibration.
Segment Analysis: By Type
The India wireless sensors for environmental and agricultural monitoring market divides into Monitoring & Control, Security & Warning, Diagnosis & Analysis. Monitoring & Control leads with an estimated ~56% of 2026 revenue, while other categories expand at different rates according to specification and application requirements. In deployments involving the India wireless sensors for environmental and agricultural monitoring, a defensible purchasing decision weighs field commissioning and software support alongside subscription economics, radio coverage and device replacement and the conditions at the installation site. Only then can the buyer evaluate repeat purchasing beyond the pilot stage for the India wireless sensors for environmental and agricultural monitoring without mistaking an attractive technical demonstration for sustained operational value.
| Type | Function | Market position |
|---|---|---|
| Monitoring & Control | Monitoring and control nodes measure soil moisture, temperature, humidity, rainfall or air-quality parameters and transmit readings to dashboards or automation systems. Fasal Main Unit 5.0 combines 12 sensors with agronomic alerts, while ICAR Patna has tested field IoT soil monitoring. The commercial importance of Monitoring and control nodes lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For Monitoring and control nodes, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance. | Largest share in 2026 (~56%). Projected category growth is ~12.5% CAGR. This category has the largest estimated 2026 revenue share because repeatable measurements support irrigation scheduling, weather advisories and compliance workflows. Network economics depend on installation density, calibration, battery life and whether the output triggers a concrete field or municipal action. |
| Security & Warning | Warning-oriented wireless sensors flag abnormal dust, pollution, weather or irrigation conditions before they become operational problems. Oizom case studies describe alerts for particulate matter and environmental thresholds, while Fasal sends notifications related to soil and irrigation conditions. When evaluating Warning-oriented wireless sensors flag abnormal dust, pollution, weather or, selection criteria extend beyond initial hardware price to wireless coverage and gateway planning and crop-specific agronomy, power supply and data quality. Those factors influence the ability to turn measurements into irrigation decisions for Warning-oriented wireless sensors flag abnormal dust, pollution, weather or; the supplier must demonstrate that the proposed configuration remains practical over its intended service life. | Estimated share in 2026 (~24%). Projected category growth is ~13.3% CAGR. Buyers value reliable thresholds, low false-alarm rates and fast data delivery. Devices in this category overlap physically with monitoring systems but are classified by their primary commercial purpose: automated warning and response rather than routine measurement or detailed analysis. |
| Diagnosis & Analysis | Diagnosis and analysis systems combine distributed sensor data with trend interpretation, crop-risk models or pollution-source assessment. Fasal offers pest and disease advisories, and Oizom platforms support hyperlocal environmental comparisons. Data quality and appropriate local models are essential to prevent incorrect recommendations. Equipment using Diagnosis and analysis systems requires engineering teams to compare sensor accuracy and environmental exposure with data-platform integration and response thresholds before committing to a device family. The commercial result for Diagnosis and analysis systems depends on the value of a municipal or farm deployment, including acceptance testing and the availability of qualified replacement components or local maintenance. | Estimated share in 2026 (~20%). Projected category growth is ~13.1% CAGR. The category is smaller in hardware revenue but may carry higher value per integrated deployment when sensors, gateway processing and analytical functions are sold together. Standalone cloud subscription revenue should not be treated as device sales without a clearly defined bundled equipment contract. |
Monitoring & Control: technology and purchasing implications
Monitoring nodes are the operational foundation of soil and ambient networks because repeated measurements enable irrigation schedules, pollution mapping and automated equipment control. Their commercial advantage depends on data availability through seasonal weather changes and calibration intervals. Network buyers compare lifetime device service costs with the cost of manual measurement and the value of timely decisions.
Security & Warning: technology and purchasing implications
Warning-focused sensors prioritize the reliability of alerts for abnormal environmental or irrigation conditions. Threshold settings, false alarms, communications latency and escalation workflows determine whether an alert actually improves outcomes. In farm use the response may be pump control or field inspection; in a city it may be a maintenance visit or pollution-source investigation.
Diagnosis & Analysis: technology and purchasing implications
Diagnosis-oriented installations pair sensor readings with interpretation of trends, crop risks or pollution sources. Fasal weather and moisture products illustrate the potential to connect field data with advisory logic, while urban environmental dashboards support comparisons across sites. Hardware value must be separated from subscription analytics when a customer purchases the two on different commercial terms.
Segment Analysis: By Application
Applications include Precision Agriculture, Environmental Monitoring. Precision Agriculture is the largest demand pool with an estimated ~61% share of 2026 revenue; differences in purchase frequency, integration effort and service obligations influence the category outlook. For Applications include Precision Agriculture, Environmental Monitoring, procurement depends on soil placement and calibration together with battery maintenance, telemetry and actionable alerts, rather than on an isolated catalogue specification. That combination determines water-use efficiency and farmer adoption for Applications include Precision Agriculture, Environmental Monitoring; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order.
| Application | Demand characteristics |
|---|---|
| Precision Agriculture | An estimated ~61% of 2026 application revenue with projected growth of ~13.3% CAGR. Farm sensors measure root-zone moisture, microclimate and irrigation conditions to support crop management. ICAR Patna and Goa projects demonstrate research interest, while Fasal offers commercial field stations and moisture units. The purchasing decision depends on water savings, crop value and the availability of installation and agronomy support. |
| Environmental Monitoring | An estimated ~39% of 2026 application revenue with projected growth of ~11.9% CAGR. City and industrial buyers use wireless instruments for air quality, dust, temperature, humidity and related environmental parameters. Oizom documents networks in Pune, Varanasi, Agra and Imphal, and CPCB maintains an industrial continuous ambient monitoring portal. Calibration and reporting requirements differentiate this segment from farm devices. |
Agricultural demand is most compelling when field data changes irrigation behavior. Fasal describes moisture measurements at adjustable root depth, mobile alerts and irrigation automation; an ICAR precision-agriculture technical briefing discussed crop water stress, soil mapping and pest assessment. Farmers may reject a sensor if they must repeatedly maintain it without seeing a credible improvement in irrigation timing or crop performance.
Urban and industrial environmental monitoring has different procurement economics. Pune installed 16 custom Oizom monitoring stations in a smart-city deployment, and Varanasi used 50 ambient instruments. Network value comes from geographic coverage, calibration and usable alerts, not only the number of wireless nodes installed. The commercial importance of Urban and industrial environmental monitoring lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For Urban and industrial environmental monitoring, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance.
The boundary between monitoring hardware and services is commercially important. Wireless field nodes, gateways, solar power units and installation may form a capital purchase, while dashboards, cloud storage and predictive models may be recurring services. Forecasts should allocate revenue consistently rather than counting both the bundled hardware sale and its underlying component purchases.
Regional Analysis
Geographic demand is divided among Western India, Southern India, Northern India, Eastern India, Central and Northeastern India. Western India is the largest at an estimated ~26% of 2026 revenue, while the pace of technology adoption and service availability creates different growth trajectories in each region. When evaluating Geographic demand, selection criteria extend beyond initial hardware price to wireless coverage and gateway planning and crop-specific agronomy, power supply and data quality. Those factors influence the ability to turn measurements into irrigation decisions for Geographic demand; the supplier must demonstrate that the proposed configuration remains practical over its intended service life.
Which geographies drive India wireless sensors for environmental and agricultural monitoring demand?
Western India has a diverse market for precision horticulture, smart irrigation and city air-quality sensing. Oizom documented a June 2025 Pune network of 16 stations and an earlier Chiplun deployment of three instruments. Goa also hosted a 2025 ICAR agreement to evaluate sensor-based decision tools in coastal agriculture. Equipment using Western India requires engineering teams to compare installation economics with site access, training and dependable data before committing to a device family. The commercial result for Western India depends on the durability of a regional deployment, including acceptance testing and the availability of qualified replacement components or local maintenance.
Southern India combines technology suppliers, agricultural research and institutional monitoring needs. Fasal describes sensor and irrigation-automation products for growers, while Oizom documented a January 2025 smart-campus monitoring installation in Hyderabad. These examples reflect different purchasing models: crop productivity and environmental transparency. In deployments involving Southern India, a defensible purchasing decision weighs geographic service constraints alongside component sourcing, acceptance tests and warranties and the conditions at the installation site. Only then can the buyer evaluate regional revenue realization for Southern India without mistaking an attractive technical demonstration for sustained operational value.
Northern, eastern and central states show distinct adoption routes. Oizom reports deployments in Varanasi and Agra; ICAR Patna inaugurated a soil-monitoring pilot in May 2026; and Imphal used smart-city air-quality instrumentation. State-level network scale depends on procurement budgets, technical maintenance and the value of local data. For Northern, eastern and central states, procurement depends on local purchasing conditions together with import lead times, calibration and integrator coverage, rather than on an isolated catalogue specification. That combination determines the pace of repeat equipment orders for Northern, eastern and central states; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Western India | Rank 1/5 · 2026 ~26% | ~13.2% CAGR (2027–2036) | In Western India, buyer selection is shaped by calibration and monsoon reliability, local service arrangements and application qualification. For Western India, the purchasing pattern affects the timing and scope of device orders rather than providing a direct measure of manufacturing capacity. The commercial importance of In Western India, buyer selection lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For In Western India, buyer selection, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance. | Buyers must consider monsoon exposure, service coverage, field calibration and whether an environmental node is required for regulatory reporting or supplementary hotspot mapping. When evaluating Buyers must consider monsoon exposure, service coverage, field calibration, selection criteria extend beyond initial hardware price to wireless coverage and gateway planning and crop-specific agronomy, power supply and data quality. Those factors influence the ability to turn measurements into irrigation decisions for Buyers must consider monsoon exposure, service coverage, field calibration; the supplier must demonstrate that the proposed configuration remains practical over its intended service life. |
| Southern India | Rank 2/5 · 2026 ~24% | ~13.4% CAGR (2027–2036) | In Southern India, buyer selection is shaped by farm service and data integration, local service arrangements and application qualification. For Southern India, the purchasing pattern affects the timing and scope of device orders rather than providing a direct measure of manufacturing capacity. Equipment using In Southern India, buyer selection requires engineering teams to compare sensor accuracy and environmental exposure with data-platform integration and response thresholds before committing to a device family. The commercial result for In Southern India, buyer selection depends on the value of a municipal or farm deployment, including acceptance testing and the availability of qualified replacement components or local maintenance. | Farm deployments must demonstrate water savings and reliable mobile access, while urban customers require integration with dashboards and local reporting systems. Service teams and replacement parts influence repeat orders. In deployments involving Farm deployments, a defensible purchasing decision weighs field commissioning and software support alongside subscription economics, radio coverage and device replacement and the conditions at the installation site. Only then can the buyer evaluate repeat purchasing beyond the pilot stage for Farm deployments without mistaking an attractive technical demonstration for sustained operational value. |
| Northern India | Rank 3/5 · 2026 ~21% | ~12.4% CAGR (2027–2036) | In Northern India, buyer selection is shaped by public procurement and calibration, local service arrangements and application qualification. For Northern India, the purchasing pattern affects the timing and scope of device orders rather than providing a direct measure of manufacturing capacity. For In Northern India, buyer selection, procurement depends on soil placement and calibration together with battery maintenance, telemetry and actionable alerts, rather than on an isolated catalogue specification. That combination determines water-use efficiency and farmer adoption for In Northern India, buyer selection; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order. | Public buyers require calibration, maintenance contracts and data comparability across multiple monitoring locations. Farm systems face different economics and must justify irrigation or crop-management improvements. The commercial importance of Public buyers lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For Public buyers, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance. |
| Eastern India | Rank 4/5 · 2026 ~16% | ~12.7% CAGR (2027–2036) | In Eastern India, buyer selection is shaped by pilot calibration and farm economics, local service arrangements and application qualification. For Eastern India, the purchasing pattern affects the timing and scope of device orders rather than providing a direct measure of manufacturing capacity. When evaluating In Eastern India, buyer selection, selection criteria extend beyond initial hardware price to wireless coverage and gateway planning and crop-specific agronomy, power supply and data quality. Those factors influence the ability to turn measurements into irrigation decisions for In Eastern India, buyer selection; the supplier must demonstrate that the proposed configuration remains practical over its intended service life. | Agricultural pilots must establish soil-specific calibration and maintenance requirements before scaling. Low-income smallholdings and fragmented plots make device-sharing and service models important. Equipment using Agricultural pilots requires engineering teams to compare sensor accuracy and environmental exposure with data-platform integration and response thresholds before committing to a device family. The commercial result for Agricultural pilots depends on the value of a municipal or farm deployment, including acceptance testing and the availability of qualified replacement components or local maintenance. |
| Central and Northeastern India | Rank 5/5 · 2026 ~13% | ~11.9% CAGR (2027–2036) | In Central and Northeastern India, buyer selection is shaped by connectivity and remote service, local service arrangements and application qualification. For Central and Northeastern India, the purchasing pattern affects the timing and scope of device orders rather than providing a direct measure of manufacturing capacity. In deployments involving In Central and Northeastern India, buyer selection, a defensible purchasing decision weighs field commissioning and software support alongside subscription economics, radio coverage and device replacement and the conditions at the installation site. Only then can the buyer evaluate repeat purchasing beyond the pilot stage for In Central and Northeastern India, buyer selection without mistaking an attractive technical demonstration for sustained operational value. | Terrain, mobile coverage, power supply and maintenance travel times can constrain deployment. Buyers may favor low-power radio and solar-powered equipment where conventional connectivity is difficult. For Terrain, mobile coverage, power supply and maintenance travel times, procurement depends on soil placement and calibration together with battery maintenance, telemetry and actionable alerts, rather than on an isolated catalogue specification. That combination determines water-use efficiency and farmer adoption for Terrain, mobile coverage, power supply and maintenance travel times; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order. |
India Wireless Sensors for Environmental and Agricultural Monitoring Competitive Landscape
The Indian wireless monitoring market includes device makers, IoT platform suppliers, field integrators and connectivity semiconductor vendors. Oizom documents deployed environmental instruments; Fasal markets agricultural field stations and moisture units; Semtech provides low-power LoRa technology. The roles differ, so a chip supplier should not be presented as a direct manufacturer of every finished monitoring network.
Oizom publishes concrete Indian air-quality monitoring deployments in Pune, Varanasi, Agra, Imphal and smaller industrial sites. Its commercial offering combines sensor hardware with data visualization and alerts. This portfolio demonstrates an established environmental route to market, where municipal reporting and maintenance may matter more than agricultural advisory features. The commercial importance of Oizom publishes concrete Indian air-quality monitoring deployments in Pune lies in the engineering trade-off between supplier technical differentiation and qualification costs, interfaces and spare parts, which differs across operating environments. For Oizom publishes concrete Indian air-quality monitoring deployments in Pune, the consequence is felt in customer retention after an initial design win, so qualification must address actual installation conditions as well as nominal product performance.
Fasal markets a 12-sensor weather unit, soil-moisture sensing and mobile irrigation automation. These devices serve growers and enterprise farms rather than city pollution regulators. The commercial value is linked to irrigation decisions and crop-risk information, so product adoption depends on agronomic service and the ability to install and maintain devices in fields.
Semtech supplies LoRa connectivity technology used in remote sensing, but it is an upstream semiconductor and networking provider rather than a supplier of every finished Indian field sensor. ICAR research partnerships and the Digital Agriculture Mission create enabling conditions without directly establishing company revenue or procurement awards. When evaluating Semtech supplies LoRa connectivity technology used in remote sensing, selection criteria extend beyond initial hardware price to direct manufacturing capability and camera or gateway integration and field support. Those factors influence the commercial scope of a vendor comparison for Semtech supplies LoRa connectivity technology used in remote sensing; the supplier must demonstrate that the proposed configuration remains practical over its intended service life.
Competition also depends on gateway installation, calibration, cloud interoperability and regional support. Urban monitoring networks require pollutant validation and data consistency, while farm systems prioritize soil placement and practical advice. Comparing suppliers on a single device price therefore misses substantial differences in product scope and recurring service economics. Equipment using Competition also requires engineering teams to compare long-term product support with design changes, calibration and warranty obligations before committing to a device family. The commercial result for Competition also depends on procurement risk for the final system buyer, including acceptance testing and the availability of qualified replacement components or local maintenance.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Environmental devices | Oizom Instruments, SENSEnuts | Wireless air and environmental monitoring devices require pollutant sensing, weather compensation, network uptime and reporting. Verified deployments can demonstrate commercial capability, but installed counts should not be converted into company market shares without revenue evidence. In deployments involving Wireless air and environmental monitoring devices, a defensible purchasing decision weighs engineering specialization alongside volume economics, testing and application knowledge and the conditions at the installation site. Only then can the buyer evaluate the position of a supplier in the value chain for Wireless air and environmental monitoring devices without mistaking an attractive technical demonstration for sustained operational value. |
| Agriculture solutions | Fasal, Ecozen Solutions, Nimble Wireless | Farm sensing and connected equipment depend on irrigation integration, battery performance and field support. These companies have different product scopes; inclusion in a candidate pool does not imply identical direct sensor-manufacturing revenue. For Farm sensing and connected equipment, procurement depends on the exact product layer supplied together with component manufacture, system integration and service, rather than on an isolated catalogue specification. That combination determines whether reported sales reflect the target device market for Farm sensing and connected equipment; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order. |
| IoT technology | Semtech Corporation, Libelium, E-Senza Technologies | Connectivity chips, field sensing platforms and network technologies enable deployments, but their upstream or systems roles must be separated from finished sensor-node sales. Product fit and India-specific commercial activity require verification at the device level. The commercial importance of Connectivity chips, field sensing platforms and network technologies lies in the engineering trade-off between supplier technical differentiation and qualification costs, interfaces and spare parts, which differs across operating environments. For Connectivity chips, field sensing platforms and network technologies, the consequence is felt in customer retention after an initial design win, so qualification must address actual installation conditions as well as nominal product performance. |
Key companies profiled
- Oizom Instruments
- Fasal
- Semtech Corporation
- Libelium
- Ecozen Solutions
- Nimble Wireless
- SENSEnuts
- E-Senza Technologies
India Wireless Sensors for Environmental and Agricultural Monitoring Production and Integration Capacity
Indian wireless monitoring deployments combine sensor modules, protective enclosures, gateways, radio connectivity, field power and calibration services. Oizom and Fasal publish different commercial architectures, while Semtech documents LoRa for remote telemetry. A field node is not commercially ready until its data can be trusted and acted upon. When evaluating Indian wireless monitoring deployments, selection criteria extend beyond initial hardware price to direct manufacturing capability and camera or gateway integration and field support. Those factors influence the commercial scope of a vendor comparison for Indian wireless monitoring deployments; the supplier must demonstrate that the proposed configuration remains practical over its intended service life.
Fasal Main Unit 5.0 combines weather and crop-related sensors with app-based alerts, while its Soil Moisture Unit monitors conditions at adjustable root depth. Farm installation quality affects whether readings represent the relevant root zone. Equipment economics therefore include agronomic setup, connectivity and replacement service. Equipment using Fasal Main Unit 5 requires engineering teams to compare long-term product support with design changes, calibration and warranty obligations before committing to a device family. The commercial result for Fasal Main Unit 5 depends on procurement risk for the final system buyer, including acceptance testing and the availability of qualified replacement components or local maintenance.
Oizom environmental nodes transmit pollutant and meteorological measurements to analysis systems. Pune and Varanasi deployments illustrate multi-site installation, where consistent calibration and central data management matter. Low-cost sensing can extend geographic coverage, but reference-grade monitoring and compliance needs remain distinct. In deployments involving Oizom environmental nodes, a defensible purchasing decision weighs engineering specialization alongside volume economics, testing and application knowledge and the conditions at the installation site. Only then can the buyer evaluate the position of a supplier in the value chain for Oizom environmental nodes without mistaking an attractive technical demonstration for sustained operational value.
LoRa connectivity supports low-power telemetry across large areas, as described by Semtech, but network performance depends on terrain, antenna placement and gateway availability. Remote farms may also need solar power or local buffering during outages. Sensor suppliers must design for actual field conditions rather than nominal radio range. For LoRa connectivity, procurement depends on the exact product layer supplied together with component manufacture, system integration and service, rather than on an isolated catalogue specification. That combination determines whether reported sales reflect the target device market for LoRa connectivity; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order.
India Wireless Sensors for Environmental and Agricultural Monitoring Market Dynamics: Drivers, Restraints and Opportunities
Demand is supported by water-efficiency needs, environmental compliance and expanding IoT capabilities. However, small-farm purchasing constraints, sensor calibration, rural connectivity and the cost of maintaining distributed networks can slow conversion from pilot installations into repeat hardware orders. The commercial importance of Demand is supported by water-efficiency needs, environmental compliance and lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For Demand is supported by water-efficiency needs, environmental compliance and, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Precision irrigation demand | +1.1% | India | 2027–2032 |
| Urban environmental networks | +1.5% | India | 2027–2033 |
| Digital agriculture infrastructure | +1.9% | India | 2027–2034 |
Precision irrigation demand
ICAR Patna established an IoT soil-monitoring pilot in May 2026 to improve irrigation decisions, while Fasal markets root-zone sensing and irrigation alerts. Water-efficiency concerns create a practical use case when measurements can reduce unnecessary pumping and crop stress. Adoption depends on calibration and service economics. When evaluating ICAR Patna established an IoT soil-monitoring pilot in, selection criteria extend beyond initial hardware price to wireless coverage and gateway planning and crop-specific agronomy, power supply and data quality. Those factors influence the ability to turn measurements into irrigation decisions for ICAR Patna established an IoT soil-monitoring pilot in; the supplier must demonstrate that the proposed configuration remains practical over its intended service life.
Urban environmental networks
Oizom documented 16 Pune monitoring stations in June 2025, 50 in Varanasi and 39 in Agra. These installations show how municipal buyers use distributed devices for pollution mapping. Network value depends on validated readings, dashboard integration and maintenance, not only installation count. Equipment using Oizom documented 16 Pune monitoring stations in June 2025 requires engineering teams to compare sensor accuracy and environmental exposure with data-platform integration and response thresholds before committing to a device family. The commercial result for Oizom documented 16 Pune monitoring stations in June 2025 depends on the value of a municipal or farm deployment, including acceptance testing and the availability of qualified replacement components or local maintenance.
Digital agriculture infrastructure
The Government of India approved the INR 2,817 crore Digital Agriculture Mission in September 2024, supporting digital public infrastructure and decision-support systems. This creates an enabling data ecosystem but should not be equated with direct spending on field sensor hardware. In deployments involving the Government of India approved the INR 2,817 crore, a defensible purchasing decision weighs field commissioning and software support alongside subscription economics, radio coverage and device replacement and the conditions at the installation site. Only then can the buyer evaluate repeat purchasing beyond the pilot stage for the Government of India approved the INR 2,817 crore without mistaking an attractive technical demonstration for sustained operational value.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Rural connectivity and power | −0.4% | India | 2027–2032 |
| Calibration and data trust | −0.7% | India | 2027–2033 |
| Affordability and support | −1.0% | India | 2027–2034 |
Rural connectivity and power
Remote fields may lack stable cellular connectivity or grid power. LoRa can reduce power consumption but requires appropriate gateways and coverage. Battery maintenance and environmental protection add ongoing cost, particularly for smallholders and remote terrain. For Remote fields, procurement depends on soil placement and calibration together with battery maintenance, telemetry and actionable alerts, rather than on an isolated catalogue specification. That combination determines water-use efficiency and farmer adoption for Remote fields; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order.
Calibration and data trust
Soil sensors need placement and soil-specific calibration, while air-quality nodes face drift and meteorological interference. ICAR Patna described field evaluation as ongoing. Poor data quality can undermine irrigation decisions or regulatory reporting, limiting willingness to expand a network. The commercial importance of Soil sensors need placement and soil-specific calibration, while air-quality lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For Soil sensors need placement and soil-specific calibration, while air-quality, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance.
Affordability and support
Upfront device, installation and subscription costs can exceed the budgets of individual growers. Municipal buyers also face tendering and service-contract requirements. Shared networks and integrator-led models may improve economics, but cannot eliminate maintenance obligations. When evaluating Upfront device, installation and subscription costs, selection criteria extend beyond initial hardware price to wireless coverage and gateway planning and crop-specific agronomy, power supply and data quality. Those factors influence the ability to turn measurements into irrigation decisions for Upfront device, installation and subscription costs; the supplier must demonstrate that the proposed configuration remains practical over its intended service life.
MARKET OPPORTUNITIES
Coastal and climate-resilient farming
ICAR-CCARI Goa signed a July 2025 agreement to evaluate sensor-driven IoT tools in coastal agriculture. Such research can improve suitability for saline, humid and weather-exposed environments, creating opportunities for devices proven under local field conditions. Equipment using ICAR-CCARI Goa signed a July 2025 agreement to evaluate requires engineering teams to compare sensor accuracy and environmental exposure with data-platform integration and response thresholds before committing to a device family. The commercial result for ICAR-CCARI Goa signed a July 2025 agreement to evaluate depends on the value of a municipal or farm deployment, including acceptance testing and the availability of qualified replacement components or local maintenance.
Hyperlocal pollution mapping
Pune and Agra deployments illustrate how multiple sensor nodes can reveal spatial variation beyond a small number of fixed stations. Municipal and industrial customers may add networks where data quality, transparent reporting and maintenance are contractually defined. In deployments involving Pune and Agra deployments illustrate how multiple sensor nodes, a defensible purchasing decision weighs field commissioning and software support alongside subscription economics, radio coverage and device replacement and the conditions at the installation site. Only then can the buyer evaluate repeat purchasing beyond the pilot stage for Pune and Agra deployments illustrate how multiple sensor nodes without mistaking an attractive technical demonstration for sustained operational value.
Automated irrigation and fertigation
FasalJet and FasalJet Pro connect field observations with remote valve, pump and nutrient control. This can increase value per deployment, but hardware revenue must be separated from ongoing advisory subscriptions and unrelated irrigation infrastructure. For FasalJet and FasalJet Pro, procurement depends on soil placement and calibration together with battery maintenance, telemetry and actionable alerts, rather than on an isolated catalogue specification. That combination determines water-use efficiency and farmer adoption for FasalJet and FasalJet Pro; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order.
India Wireless Sensors for Environmental and Agricultural Monitoring Supply Chain and Integration Analysis
The Indian wireless monitoring value chain spans sensor modules, embedded radio electronics, rugged enclosures, field installation, gateway connectivity and analytics. Commercial success depends on reliable measurements and service continuity. Agricultural and air-quality networks use different calibration regimes and procurement channels even when they share radio technology. The commercial importance of the Indian wireless monitoring lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For the Indian wireless monitoring, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance.
Components. Wireless monitoring products integrate sensing elements, radio modules, power supplies and protective housings. Different crop and pollutant applications require distinct specifications. The supplier base therefore includes semiconductor firms, device assemblers and field-service integrators with different revenue boundaries. The commercial importance of Wireless monitoring products lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For Wireless monitoring products, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance.
Installation. Fasal devices are positioned in the crop root zone or farm microclimate, while Oizom pollution instruments are mounted at selected urban or industrial locations. Correct placement and commissioning determine whether data can support the intended operational decision. When evaluating Fasal devices, selection criteria extend beyond initial hardware price to wireless coverage and gateway planning and crop-specific agronomy, power supply and data quality. Those factors influence the ability to turn measurements into irrigation decisions for Fasal devices; the supplier must demonstrate that the proposed configuration remains practical over its intended service life.
Connectivity. Semtech documents LoRa-based agriculture telemetry for long-range, low-power networks. India deployments still require gateways, backhaul and practical coverage testing. Solar power and local data buffering may improve resilience in locations with unstable electricity. Equipment using Semtech documents LoRa-based agriculture telemetry for long-range, low-power networks requires engineering teams to compare sensor accuracy and environmental exposure with data-platform integration and response thresholds before committing to a device family. The commercial result for Semtech documents LoRa-based agriculture telemetry for long-range, low-power networks depends on the value of a municipal or farm deployment, including acceptance testing and the availability of qualified replacement components or local maintenance.
Service. Sensor drift, battery replacement, cleaning and software updates create recurring maintenance needs. Oizom and Fasal describe monitoring dashboards and alerts, but customers should evaluate who performs calibration and repairs. Long-term network value depends on continuity of trustworthy data. In deployments involving Sensor drift, battery replacement, cleaning and software updates, a defensible purchasing decision weighs field commissioning and software support alongside subscription economics, radio coverage and device replacement and the conditions at the installation site. Only then can the buyer evaluate repeat purchasing beyond the pilot stage for Sensor drift, battery replacement, cleaning and software updates without mistaking an attractive technical demonstration for sustained operational value.
Recent Developments in India Wireless Sensors for Environmental and Agricultural Monitoring
- September 2024 Policy approval
The Government of India approved the Digital Agriculture Mission with an outlay of INR 2,817 crore, including digital public infrastructure and agricultural decision-support systems. This provides an enabling policy environment for precision data applications, but the full programme budget cannot be treated as a sensor procurement allocation. For the Government of India approved the Digital Agriculture Mission, procurement depends on soil placement and calibration together with battery maintenance, telemetry and actionable alerts, rather than on an isolated catalogue specification. That combination determines water-use efficiency and farmer adoption for the Government of India approved the Digital Agriculture Mission; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order. Source - January 2025 Smart campus
Oizom reported installation of a Polludrone monitoring system at Stonecraft in Hyderabad for continuous ambient air-quality observation. The project illustrates demand for on-site environmental transparency and digital reporting, distinct from farm soil-moisture networks and reference-grade regulatory instruments. The commercial importance of Oizom reported installation of a Polludrone monitoring system at lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For Oizom reported installation of a Polludrone monitoring system at, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance. Source - June 2025 City network
Oizom documented deployment of 16 custom air-quality monitoring stations in Pune for hyperlocal pollution mapping. The network targets traffic corridors and industrial areas, showing a practical municipal use for distributed wireless sensing. Continued calibration and data management are necessary to maintain confidence in the measurements. When evaluating Oizom documented deployment of 16 custom air-quality monitoring stations, selection criteria extend beyond initial hardware price to wireless coverage and gateway planning and crop-specific agronomy, power supply and data quality. Those factors influence the ability to turn measurements into irrigation decisions for Oizom documented deployment of 16 custom air-quality monitoring stations; the supplier must demonstrate that the proposed configuration remains practical over its intended service life. Source - July 2025 Research agreement
ICAR-CCARI signed an agreement with Business Kendra to evaluate sensor-based IoT and machine-learning tools for coastal agriculture in Goa. The collaboration aims to improve field decision support and resilience, but the announcement describes evaluation and calibration rather than a quantified commercial sensor rollout. Equipment using ICAR-CCARI signed an agreement with Business Kendra to evaluate requires engineering teams to compare sensor accuracy and environmental exposure with data-platform integration and response thresholds before committing to a device family. The commercial result for ICAR-CCARI signed an agreement with Business Kendra to evaluate depends on the value of a municipal or farm deployment, including acceptance testing and the availability of qualified replacement components or local maintenance. Source - May 2026 Research installation
ICAR-RCER Patna inaugurated an IoT-enabled soil-monitoring system developed with BIT Mesra to study real-time soil moisture and irrigation management. Field calibration and performance evaluation were ongoing at the time of the announcement, making this a verified research installation rather than evidence of nationwide device adoption. In deployments involving ICAR-RCER Patna inaugurated an IoT-enabled soil-monitoring system developed with, a defensible purchasing decision weighs field commissioning and software support alongside subscription economics, radio coverage and device replacement and the conditions at the installation site. Only then can the buyer evaluate repeat purchasing beyond the pilot stage for ICAR-RCER Patna inaugurated an IoT-enabled soil-monitoring system developed with without mistaking an attractive technical demonstration for sustained operational value. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Base Year | USD 440 million |
| Estimated Year | USD 496 million |
| Forecast Size | USD 1,468 million |
| CAGR (2027–2036) | 12.8% |
| Study Period | 2021–2036; forecast period 2027–2036 |
| By Type | Monitoring & Control · Security & Warning · Diagnosis & Analysis |
| By Application | Precision Agriculture · Environmental Monitoring |
| By End User | Soil and Irrigation · Weather and Microclimate · Air Quality · Water Quality and Others |
| By Region | Western India largest in 2026 (~26%); regional growth profiles through 2036 Western IndiaMaharashtra · Goa Southern IndiaKarnataka · Telangana Northern IndiaUttar Pradesh · Delhi NCR Eastern IndiaBihar · West Bengal Central and Northeastern IndiaMadhya Pradesh · Manipur |
| Key Companies Profiled | Oizom Instruments, Fasal, Semtech Corporation, Libelium, Ecozen Solutions, Nimble Wireless, SENSEnuts, E-Senza Technologies |
| Customization Scope | India-only analysis can be customized by state, crop, soil-moisture and weather parameter, air-quality instrument type, wireless technology, deployment scale and end-user procurement. Standalone software subscriptions, satellite imagery and unrelated irrigation machinery are excluded unless directly bundled with the monitored sensing equipment. |
Frequently Asked Questions
What is the size of the India wireless sensors for environmental and agricultural monitoring market?
The market was valued at USD 440 million in 2026 and is projected to reach USD 1,468 million in 2036 at a CAGR of 12.8%. The value covers India-specific wireless sensing devices and integrated monitoring hardware for environmental and agricultural use, not the entire digital agriculture programme or all IoT software. Market growth depends on the conversion of pilots and project tenders into operating field networks.
Which geography leads the India wireless sensors for environmental and agricultural monitoring market?
Western India is the leading market with an estimated ~26% share in 2026. Western India combines verified urban monitoring deployments in Pune and Chiplun with agricultural technology demand. The regional shares are estimated revenue allocations, not a count of installations or an assertion that every device is manufactured within the region.
Which type of product leads India wireless sensors for environmental and agricultural monitoring revenue?
Monitoring & Control is the largest product category at an estimated ~56% of 2026 revenue. The leading type benefits from established integration patterns and a documented set of practical performance requirements. For Monitoring & Control, procurement depends on soil placement and calibration together with battery maintenance, telemetry and actionable alerts, rather than on an isolated catalogue specification. That combination determines water-use efficiency and farmer adoption for Monitoring & Control; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order.
Which application leads demand for India wireless sensors for environmental and agricultural monitoring?
Precision Agriculture leads with an estimated ~61% share in 2026. The leading application has the broadest set of recurring device requirements and procurement pathways. The commercial importance of Precision Agriculture lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For Precision Agriculture, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance.
What is the fastest growing geographic area?
The strongest estimated regional growth is in Southern India at ~13.4% CAGR through 2036. Southern and western states have established agritech and environmental suppliers, while ICAR projects in Bihar and Goa indicate further experimentation. Future regional growth depends on service networks, crop economics and credible field performance rather than nationwide uniform adoption.
What technical constraints affect adoption?
Remote power, monsoon exposure, radio coverage and calibration are significant technical constraints. Soil moisture readings can be misleading when probes are placed incorrectly, and low-cost pollution instruments require correction and comparison against suitable references to support reliable decisions. When evaluating Remote power, monsoon exposure, radio coverage and calibration, selection criteria extend beyond initial hardware price to wireless coverage and gateway planning and crop-specific agronomy, power supply and data quality. Those factors influence the ability to turn measurements into irrigation decisions for Remote power, monsoon exposure, radio coverage and calibration; the supplier must demonstrate that the proposed configuration remains practical over its intended service life.
What differentiates suppliers in this market?
Suppliers compete on sensor accuracy, environmental ruggedness, network uptime, installation support, dashboards and application-specific alerts. A farm irrigation device and a municipal air monitor may use similar radio links but need different calibration, purchasing and service capabilities. Equipment using Suppliers compete on sensor accuracy, environmental ruggedness, network uptime requires engineering teams to compare sensor accuracy and environmental exposure with data-platform integration and response thresholds before committing to a device family. The commercial result for Suppliers compete on sensor accuracy, environmental ruggedness, network uptime depends on the value of a municipal or farm deployment, including acceptance testing and the availability of qualified replacement components or local maintenance.
How do regulations or public programmes affect demand?
India’s Digital Agriculture Mission supports data infrastructure and decision support, while pollution monitoring requirements can motivate municipal and industrial deployments. Neither public initiative guarantees direct sensor orders; actual purchasing depends on budgets, tenders and demonstrated technical performance. In deployments involving India’s Digital Agriculture Mission, a defensible purchasing decision weighs field commissioning and software support alongside subscription economics, radio coverage and device replacement and the conditions at the installation site. Only then can the buyer evaluate repeat purchasing beyond the pilot stage for India’s Digital Agriculture Mission without mistaking an attractive technical demonstration for sustained operational value.
How does product integration affect buyer economics?
A deployment includes nodes, gateways, power, installation and sometimes a recurring platform subscription. Buyers should separate one-time hardware costs from ongoing connectivity and service fees and evaluate the total cost per field, farm or monitoring location. For a deployment, procurement depends on soil placement and calibration together with battery maintenance, telemetry and actionable alerts, rather than on an isolated catalogue specification. That combination determines water-use efficiency and farmer adoption for a deployment; buyers need operating-condition evidence and a service plan before converting an initial evaluation into a repeat order.
What should purchasers evaluate before scaling deployments?
Purchasers should test soil or pollutant accuracy, calibration requirements, wireless coverage, battery life, environmental protection, data export and service response. Pilot results should be evaluated across representative weather and operating conditions before extending a network to more sites. The commercial importance of Purchasers should test soil or pollutant accuracy, calibration requirements lies in the engineering trade-off between field enclosure reliability and monsoon humidity, dust and local servicing, which differs across operating environments. For Purchasers should test soil or pollutant accuracy, calibration requirements, the consequence is felt in the cost of maintaining distributed sensor networks, so qualification must address actual installation conditions as well as nominal product performance.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF