Key Statistics
Key Takeaways
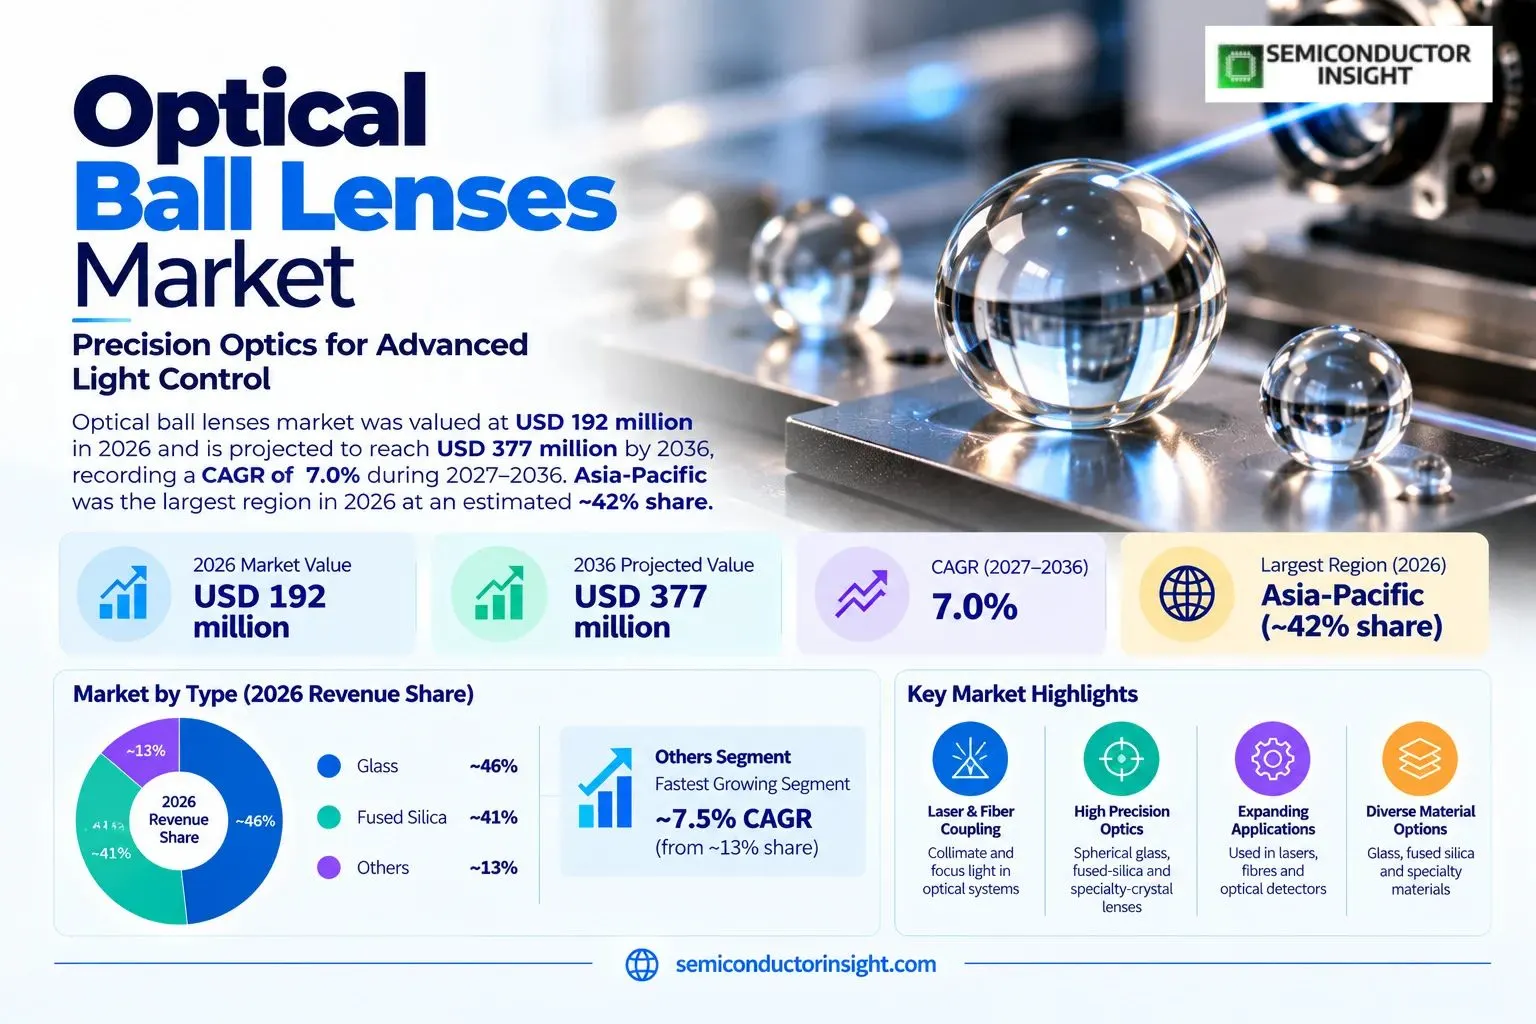
- Market trajectory: The global optical ball lenses market reached USD 192 million in 2026 and is projected to reach USD 377 million by 2036 at 7.0% CAGR over 2027–2036. Demand follows the actual sale of precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors, rather than the full revenue of adjacent digital infrastructure.
- Glass leadership: Glass has the largest estimated type share at ~46% in 2026. The fastest-growing type is Others, at ~7.5% CAGR from an estimated ~13% share. Glass is purchased for a distinct operating envelope in precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. The specification is controlled by optical performance, assembly yield, lifetime and field qualification rather than general electronics expenditure.
- Optical Fibers demand: Optical Fibers leads application revenue at an estimated ~53% in 2026, while Optical Sensors grows most rapidly near ~7.4% CAGR. Optical Fibers purchasers require practical optical-system qualification and performance evidence when evaluating precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. Contract timing, stocking practices and compliance determine actual device shipments; this is narrower than total spending on the end-user industry.
- Asia-Pacific position: Asia-Pacific represents the largest regional revenue pool at an estimated ~42% in 2026. Asia-Pacific has the highest regional modeled growth at ~7.4% CAGR. Optical glass finishing in China, endoscope assembly in Japan and fiber accessory supply chains in India drive a mixture of precision lens grades. For regional competition in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
- Principal constraint: Micron-scale alignment costs is a fundamental restraint. Purchase decisions are also affected by alternative grin and aspheric lenses. Both conditions limit the speed at which a promising optical product can move into enduring installations; careful lifecycle support remains vital. In the adoption barriers setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Optical Ball Lenses Market Overview
Optical ball lenses market was valued at USD 192 million in 2026 and is projected to reach USD 377 million by 2036, recording a CAGR of 7.0% during 2027–2036. Asia-Pacific was the largest region in 2026 at an estimated ~42% share. The market centers on precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors.
Optical Ball Lenses encompasses precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. The optical interaction carries or secures the functional payload, but the device must also include appropriately designed mechanical, electronic and service interfaces. Customers primarily pay for a qualified system that performs consistently in field conditions, rather than a technical principle demonstrated only at prototype level.
The defined commercial boundary includes merchant optical ball-lens components and custom spherical lenses sold by optics suppliers, excluding the value of complete cameras, endoscopes, laser modules or telecom network installations. This distinction prevents a finished datacenter, networking service or unrelated electronic product from being mistaken for direct sales of the specialized component. Supplier comparisons are meaningful only when the invoiced product and its value contribution fall within the stated market boundary.
At the engineering level, precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. Designing this technology for 2026 production requires material and mechanical stability, test coverage, procurement planning and the ability to identify a component that has begun to fail. Qualification routines can be more costly than the core material in demanding installations.
Demand develops through fiber-optic component manufacturers, laser and optical sensor assemblers, miniature endoscope makers and laboratory photonic instrumentation suppliers. Those purchasers differ in the volumes they order, the length of their evaluation cycle and the documentation they require. The leading applications are Optical Fibers, Optical Sensors, Others; their spending patterns cannot simply be extrapolated from wider electronics or digital-storage demand.
Technology priorities are evolving toward more reliable and serviceable optical architectures. For optical ball lenses procurement, glass is purchased for a distinct operating envelope in precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. For optical ball lenses procurement, the specification is controlled by optical performance, assembly yield, lifetime and field qualification rather than general electronics expenditure. The commercial challenge is to turn those technical characteristics into repeat purchasing, while addressing loss of compatibility, changing interfaces and the long-term economics of support.
Segment Analysis: By Type
By type, the optical ball lenses market comprises Glass, Fused Silica, Others. Glass leads with an estimated ~46% revenue share in 2026; Others expands most rapidly at about ~7.5% CAGR from a ~13% share. Different physical designs lead to different suppliers, levels of qualification and possible expansion rates. A commercial evaluation of type overview therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
| Type | Function | Market position |
|---|---|---|
| Glass | The significance for type Glass is the difference between an experimentally functional optical ball lenses device and an optical product accepted for repeated customer shipments. The type Glass purchasing decision for optical ball lenses depends on verifiable optical-device performance, instrument compatibility, and technical approval during 2027–2036. Each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Glass variant affects installation requirements and ongoing service. | Estimated ~46% of 2026 revenue and ~6.4% CAGR. Glass is the largest type by value, with demand linked to the particular requirements of its buyers. For type Glass, customers weigh service response, materials traceability, formal production qualification, and lifetime cost before approving optical ball lenses equipment. Procurement teams evaluate component availability, unit cost and the necessary test records. |
| Fused Silica | Fused Silica is purchased for a distinct operating envelope in precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. For optical ball lenses procurement, each product specification maps to a different material bill, operating environment and qualification procedure. Suppliers therefore need to establish how the Fused Silica variant affects installation requirements and ongoing service. | Estimated ~41% of 2026 revenue and ~7.3% CAGR. Fused Silica is a distinct product category, with demand linked to the particular requirements of its buyers. For optical ball lenses procurement, fused Silica is purchased for a distinct operating envelope in precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. For optical ball lenses procurement, procurement teams evaluate component availability, unit cost and the necessary test records. |
| Others | Others is purchased for a distinct operating envelope in precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. For type Others, customers weigh service response, materials traceability, formal production qualification, and lifetime cost before approving optical ball lenses equipment. Suppliers therefore need to establish how the Others variant affects installation requirements and ongoing service. | Estimated ~13% of 2026 revenue and ~7.5% CAGR. Others is a distinct product category, with demand linked to the particular requirements of its buyers. For optical ball lenses procurement, others is purchased for a distinct operating envelope in precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. |
Secondary segmentation: By Substrate Index
The By Substrate Index classification distinguishes Standard index, High index, Specialty crystal. Standard index leads this separate estimated 2026 allocation at ~52%. Classifications are parallel descriptions of the same sold hardware; they are not additive product revenue pools. The choice among materials and assembly routes affects cost, thermal tolerance, signal characteristics and reliability.
| Axis | Members | Commercial role |
|---|---|---|
| By Substrate Index | Standard index; High index; Specialty crystal | Standard index accounts for an estimated ~52% of by substrate index revenue in 2026. Other members address different procurement specifications. The underlying technology involves precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. The best material or process choice is conditional on the actual optical device, thermal cycle, qualification plan and customer integration cost. |
Secondary segmentation: By Lens Geometry
The By Lens Geometry classification distinguishes Full ball, Half-ball, Custom sphere. Full ball leads this separate estimated 2026 allocation at ~71%. For optical ball lenses procurement, classifications are parallel descriptions of the same sold hardware; they are not additive product revenue pools. For optical ball lenses procurement, the choice among materials and assembly routes affects cost, thermal tolerance, signal characteristics and reliability. This matters for By Lens Geometry segmentation, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
| Axis | Members | Commercial role |
|---|---|---|
| By Lens Geometry | Full ball; Half-ball; Custom sphere | Full ball accounts for an estimated ~71% of by lens geometry revenue in 2026. Other members address different procurement specifications. For optical ball lenses procurement, the underlying technology involves precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. For optical ball lenses procurement, the best material or process choice is conditional on the actual optical device, thermal cycle, qualification plan and customer integration cost. |
Segment Analysis: By Application
Application segments are Optical Fibers, Optical Sensors, Others. Optical Fibers takes the largest estimated 2026 revenue share at ~53%, whereas Optical Sensors is the fastest-growing application at ~7.4% CAGR. Channel structure, end-user servicing needs and purchasing cadence create distinct addressable opportunities despite shared underlying optical technologies. The 2027–2036 opportunity in application overview is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
| Application | Demand characteristics |
|---|---|
| Optical Fibers | Estimated ~53% of 2026 revenue and ~6.6% CAGR. Optical Fibers buyers evaluate functional optical tolerances and system compatibility for precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. For optical ball lenses procurement, contract timing, stocking practices and compliance determine actual device shipments; this is narrower than total spending on the end-user industry. Purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. |
| Optical Sensors | Estimated ~34% of 2026 revenue and ~7.4% CAGR. Optical Sensors buyers evaluate functional optical tolerances and system compatibility for precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. For optical ball lenses procurement, purchasers assess the entire cost of deploying and operating the optical function, including testability, compatible equipment and procurement lead times. |
| Others | Estimated ~13% of 2026 revenue and ~7.1% CAGR. Others buyers evaluate functional optical tolerances and system compatibility for precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. The significance for application Others is the difference between an experimentally functional optical ball lenses device and an optical product accepted for repeated customer shipments. |
The commercial channel is shaped by fiber-optic component manufacturers, laser and optical sensor assemblers, miniature endoscope makers and laboratory photonic instrumentation suppliers. Direct equipment purchase, specialist distributor supply and OEM qualification have different order economics. Volume can be won through stable specifications and documented reliability, while replacement sales depend on spare availability and retained interface compatibility over the 2027–2036 period.
Regional Analysis
Asia-Pacific leads global revenue with an estimated ~42% share in 2026. North America follows at ~26% and Europe at ~22%. Asia-Pacific has the fastest growth at ~7.4% CAGR. Regional purchases and supplier manufacturing footprints must be distinguished for market comparisons. For regional lead in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
How do regional purchasing patterns differ in optical ball lenses?
Asia-Pacific: Optical glass finishing in China, endoscope assembly in Japan and fiber accessory supply chains in India drive a mixture of precision lens grades. North America: U.S. fiber coupling and miniature medical instrument OEMs buy diameter-sorted spheres with metrology certifications and design-support drawings. Europe has distinct qualification and network compliance requirements; South America and the Middle East and Africa rely more heavily on imported products and local distribution service. In the regional comparison setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
| Region | Position | Growth outlook | Demand profile | What decides supplier selection |
|---|---|---|---|---|
| Asia-Pacific | Largest (~42%) | ~7.4% CAGR | For optical ball lenses procurement, optical glass finishing in China, endoscope assembly in Japan and fiber accessory supply chains in India drive a mixture of precision lens grades. Within Asia-Pacific, design wins may be awarded to specialized device manufacturers outside the consuming region even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. For Asia-Pacific regional demand in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. | Buyers in Asia-Pacific require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. For precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
| North America | Second (~26%) | ~6.6% CAGR | U.S. fiber coupling and miniature medical instrument OEMs buy diameter-sorted spheres with metrology certifications and design-support drawings. Within North America, design wins may be awarded to specialized device manufacturers outside the consuming region even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. In the North America regional demand setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. | Buyers in North America require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. For optical ball lenses procurement, for precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors, interface stability and the availability of replacement products can determine whether a promising order proceeds beyond initial evaluation. |
| Europe | Third (~22%) | ~6.4% CAGR | Germany and the United Kingdom emphasize optical metrology, specialty glass chemistry, endoscopy quality procedures and EU material declarations. Within Europe, design wins may be awarded to specialized device manufacturers outside the consuming region even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. This matters for Europe regional demand, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. | Buyers in Europe require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. The significance for five-region comparison is the difference between an experimentally functional optical ball lenses device and an optical product accepted for repeated customer shipments. For Europe, lens importers must confirm refractive-index tolerance, certified substrate composition and return logistics before production-line optical coupling can be qualified. |
| South America | Fourth (~6%) | ~6.9% CAGR | Brazilian instrument integrators need imported optical spheres, stocked replacement assemblies and realistic shipment lead times for imaging systems. Within South America, design wins may be awarded to specialized device manufacturers outside the consuming region even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. A commercial evaluation of South America regional demand therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. | Buyers in South America require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. In five-region comparison, order volumes remain sensitive to validated optical tolerances, installation costs, multi-vendor interoperability, and replacement-part supply for optical ball lenses. For South America, lens importers must confirm refractive-index tolerance, certified substrate composition and return logistics before production-line optical coupling can be qualified. |
| Middle East & Africa | Fifth (~4%) | ~7.1% CAGR | Gulf imaging projects and South African lab instruments depend on distributors that can maintain traceable optical component stocks. Within Middle East & Africa, design wins may be awarded to specialized device manufacturers outside the consuming region even when the finished optical equipment is installed locally, making customer qualification and international logistics decisive commercial factors. The 2027–2036 opportunity in Middle East & Africa regional demand is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. | Buyers in Middle East & Africa require engineering fit, credible warranty conditions, appropriate import arrangements, and a qualified local service path. The five-region comparison purchasing decision for optical ball lenses depends on verifiable optical-device performance, instrument compatibility, and technical approval during 2027–2036. For Middle East & Africa, lens importers must confirm refractive-index tolerance, certified substrate composition and return logistics before production-line optical coupling can be qualified. |
Competitive Landscape
Competition is led by firms with relevant precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. The competitive field includes established manufacturers, original equipment suppliers and historical product brands whose present scope differs. Buyers compare product-specific technical evidence and order terms instead of total corporate turnover, because an optical component represents only part of a finished digital system.
Schott and Union Optic Inc illustrate different capabilities within the sector. Their product portfolios, production locations and support arrangements cannot be assumed identical. Procurement departments typically request specification sheets, samples, aging or thermal data and a long-term sourcing plan before designating a manufacturing source for a multi-year contract. This matters for manufacturer capability, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Doric Lenses, ILLUCO, Tower Optical Corporation, Industrial Technologies, II-VI Incorporated appear in the wider manufacturer and distributor field. The roles of those entities require separation: media production, component housing manufacture, systems integration and distribution do not produce the same category of invoice. Market rivalry occurs at the level of the particular sold device, not across unrelated corporate divisions.
Other suppliers and historical business names include UltiTech Sapphire, Fuzhou Alpha Optics Co, Chengdu Yasi Optoelectronics Co, Shanghai Optics Inc. Legacy corporate names and regional branches may persist in industry directories, while actual current production must be checked against updated company disclosures. Product-life-cycle changes can alter sourcing qualification even if an installed system continues to function with existing spare inventories.
For 2027–2036, vendor differentiation will depend on manufacturing yield, documentation, reliable delivery and compatibility with demanding optical interfaces. Price competition may intensify in mature configurations, whereas new package geometries or specialized optical subassemblies offer specialized margins. A customer switching supplier must weigh requalification, sample validation and operational interruption against lower unit costs. A commercial evaluation of competitive economics therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Tier structure
| Tier | Companies | Basis of competition |
|---|---|---|
| Tier 1 | Schott; Union Optic Inc; Doric Lenses | Direct manufacturers with published optical product or packaging activities differentiate through established process control and established technical catalogs. The first technical gate is the ability to supply precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors in a documented, reproducible format, followed by customer qualification and reliable lead times. |
| Tier 2 | ILLUCO; Tower Optical Corporation; Industrial Technologies; II-VI Incorporated | Regional producers and equipment suppliers compete through specialized configurations, responsive design assistance and local service. Customers generally request traceable quality records and samples in the exact form factor they need. Lower production scale can be balanced by shorter engineering response times or customization of critical interfaces. The 2027–2036 opportunity in tier 2 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. |
| Tier 3 | Swiss Jewel Company; Knight Optical; West Coast Tech Limited; Tecnottica Consonni; Z-Optics; UNI Optics Co; Changchun Sunday Optoelectronics Co; UltiTech Sapphire; Fuzhou Alpha Optics Co; Chengdu Yasi Optoelectronics Co; Shanghai Optics Inc | The broader value chain includes historical participants, distributors, integrators and component companies with adjacent expertise. Their names may appear in sector coverage without establishing that each currently sells an identical qualified device. Product applicability is determined by specific device families, production status and customer approvals. For tier 3 in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. |
Key companies profiled
- Schott
- Union Optic Inc
- Doric Lenses
- ILLUCO
- Tower Optical Corporation
- Industrial Technologies
- II-VI Incorporated
- Swiss Jewel Company
- Knight Optical
- West Coast Tech Limited
- Tecnottica Consonni
- Z-Optics
- UNI Optics Co
- Changchun Sunday Optoelectronics Co
- UltiTech Sapphire
- Fuzhou Alpha Optics Co
- Chengdu Yasi Optoelectronics Co
- Shanghai Optics Inc
Production Capacity Analysis
Production capacity relies on specialized manufacturing and testing for precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. Effective output is constrained by qualified material lots, process yield, equipment availability and completion of electrical, optical and environmental tests. Announced industrial capability should not be equated automatically with installed sales or usable nameplate capacity.
Initial manufacturing operations include precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. Yield is influenced by each fabrication and assembly stage, while changes in materials or process equipment can require formal requalification. Japan, China and other Asia-Pacific manufacturing centers support considerable supplier capacity, although customer purchasing decisions may originate elsewhere.
Diversified capacity can reduce country-of-origin exposure and help supply different qualification requirements. However, transferring tooling and process knowledge between plants takes time, and products made in new locations may require fresh qualification. Strong inventory controls and component traceability are important during a period of changing designs and volatile customer orders. In the capacity diversification setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Upstream constraints include materials, specialized assembly equipment and trained optical manufacturing staff. For optical ball lenses, packaging, testing and maintenance infrastructure shape the ability to convert a technical design into reproducible revenue. Companies should distinguish capacity for direct in-scope products from headline capacity for the much larger adjacent electronics manufacturing market. This matters for capacity bottlenecks, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
Market Dynamics
Demand is driven by fiber-coupling density and miniaturized medical imaging. Growth depends on matching the optical product to qualification requirements, logistics and total ownership cost. Supplier economics also reflect the negative impact of micron-scale alignment costs, particularly when customers require long operational support. A commercial evaluation of dynamics lead therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
MARKET DRIVERS
Drivers Impact Analysis*
| Driver | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Fiber-coupling density | +1.8% | Asia-Pacific | 2027–2036 |
| Miniaturized medical imaging | +1.4% | Global | 2028–2034 |
| High-tolerance sensing components | +1.1% | North America | 2027–2031 |
| Specialized fused-silica applications | +0.9% | Europe | 2029–2036 |
| Optical instruments replacement | +0.7% | Global | 2028–2035 |
Fiber-coupling density
Fiber-coupling density supports specialized purchases for optical ball lenses. precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors must be integrated into customer processes, inspected and supported. The growth effect is directional, not a separate addition to the headline CAGR. Actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
Miniaturized medical imaging
Miniaturized medical imaging supports specialized purchases for optical ball lenses. precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors must be integrated into customer processes, inspected and supported. The growth effect is directional, not a separate addition to the headline CAGR. For optical ball lenses procurement, actual adoption depends on confirmed orders, service requirements and the lifecycle of equipment already installed.
High-tolerance sensing components
High-tolerance sensing components supports specialized purchases for optical ball lenses. precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors must be integrated into customer processes, inspected and supported. The growth effect is directional, not a separate addition to the headline CAGR. In dyn drivers 2, order volumes remain sensitive to validated optical tolerances, installation costs, multi-vendor interoperability, and replacement-part supply for optical ball lenses.
Specialized fused-silica applications
Specialized fused-silica applications supports specialized purchases for optical ball lenses. precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors must be integrated into customer processes, inspected and supported. The growth effect is directional, not a separate addition to the headline CAGR. For dyn drivers 3, customers weigh service response, materials traceability, formal production qualification, and lifetime cost before approving optical ball lenses equipment.
MARKET RESTRAINTS
Restraints Impact Analysis*
| Restraint | (~) % impact on CAGR forecast | Geographic relevance | Impact timeline |
|---|---|---|---|
| Micron-scale alignment costs | −1.5% | Global | 2027–2036 |
| Alternative GRIN and aspheric lenses | −1.1% | Europe and North America | 2027–2034 |
| Substrate grade and yield variation | −0.8% | Asia-Pacific | 2028–2035 |
| Spherical aberration constraints | −0.6% | Global | 2029–2036 |
Micron-scale alignment costs
Micron-scale alignment costs increases the effort required to qualify or replace optical ball lenses. A technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. Suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. The 2027–2036 opportunity in Micron-scale alignment costs restraint is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
Alternative GRIN and aspheric lenses
Alternative GRIN and aspheric lenses increases the effort required to qualify or replace optical ball lenses. For optical ball lenses procurement, a technical disadvantage can translate into delayed procurement, more maintenance work or poorer economics for the user. For optical ball lenses procurement, suppliers that demonstrate stable performance and clear service processes may offset some of this commercial risk, but the constraint remains important for 2027–2036 forecasts. For Alternative GRIN and aspheric lenses restraint in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
Substrate grade and yield variation
Substrate grade and yield variation increases the effort required to qualify or replace optical ball lenses. In dyn restraints 2, order volumes remain sensitive to validated optical tolerances, installation costs, multi-vendor interoperability, and replacement-part supply for optical ball lenses. In the Substrate grade and yield variation restraint setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Spherical aberration constraints
Spherical aberration constraints increases the effort required to qualify or replace optical ball lenses. The significance for dyn restraints 3 is the difference between an experimentally functional optical ball lenses device and an optical product accepted for repeated customer shipments. This matters for Spherical aberration constraints restraint, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
MARKET OPPORTUNITIES
Medical endoscope miniaturization
Medical endoscope miniaturization creates an opportunity to improve deployment or the supplier value proposition. The relevant engineering work concerns precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. Buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. The commercial impact is strongest where those requirements can be standardized across several customers.
Coated high-index micro-lenses
Coated high-index micro-lenses creates an opportunity to improve deployment or the supplier value proposition. For optical ball lenses procurement, the relevant engineering work concerns precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. For optical ball lenses procurement, buyers still require evidence of stable operation, a practical purchasing channel, training and a predictable replacement schedule. For optical ball lenses procurement, the commercial impact is strongest where those requirements can be standardized across several customers.
Traceable precision lens metrology
Traceable precision lens metrology creates an opportunity to improve deployment or the supplier value proposition. For dyn opps 2, customers weigh service response, materials traceability, formal production qualification, and lifetime cost before approving optical ball lenses equipment. In dyn opps 2, order volumes remain sensitive to validated optical tolerances, installation costs, multi-vendor interoperability, and replacement-part supply for optical ball lenses.
Sensor-fibre integrated optical heads
Sensor-fibre integrated optical heads creates an opportunity to improve deployment or the supplier value proposition. The dyn opps 3 purchasing decision for optical ball lenses depends on verifiable optical-device performance, instrument compatibility, and technical approval during 2027–2036. The significance for dyn opps 3 is the difference between an experimentally functional optical ball lenses device and an optical product accepted for repeated customer shipments.
Supply Chain Analysis
The supply chain links specialized raw materials, device fabrication, verification, system integration and servicing for optical ball lenses. A failure at any stage can invalidate the qualified end product. Vendor selection is therefore affected by more than selling price: replacement-component availability, inspection data, lead time and the ability to support legacy interfaces are commercially significant.
Upstream materials. For optical ball lenses procurement, materials and optical substrates required for precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors; inspection before assembly. For optical ball lenses, controlling change across this stage enables traceability, reliability and repeatable delivery. Purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment.
Manufacturing. Fabrication, alignment, sealing or recording operations matched to the market boundary. For optical ball lenses procurement, for optical ball lenses, controlling change across this stage enables traceability, reliability and repeatable delivery. For optical ball lenses procurement, purchasing teams demand technical records that explain product behavior and clarify responsibility if a component fails after deployment. For Manufacturing chain in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
Channels. For optical ball lenses procurement, oEM engineering contracts, technical distributors and integrated storage or optical equipment vendors. For supply paras 2, customers weigh service response, materials traceability, formal production qualification, and lifetime cost before approving optical ball lenses equipment. In the Channels chain setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
Downstream users. For optical ball lenses procurement, fiber-optic component manufacturers, laser and optical sensor assemblers, miniature endoscope makers and laboratory photonic instrumentation suppliers; qualification, deployment and lifecycle support. In supply paras 3, order volumes remain sensitive to validated optical tolerances, installation costs, multi-vendor interoperability, and replacement-part supply for optical ball lenses. For supply paras 3, customers weigh service response, materials traceability, formal production qualification, and lifetime cost before approving optical ball lenses equipment.
Recent Developments
- 14 July 2026 Published
Knight Optical issued updated technical selection guidance for precision lenses covering material properties, surface shape and coatings. For ball-lens OEMs, lens form and refractive-index choices drive achievable coupling efficiency; the commercial effect is stronger tolerance specification during optical system qualification. This matters for Optical Ball Lenses development 14 July 2026, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software. Source - 17 June 2026 Published
The European Commission reviewed European digital connectivity and gaps in fiber networks. This supplies context for optical fiber system demand, not ball-lens market revenue itself; optical-coupler makers may require new alignment components when backbone and access interfaces are redesigned. A commercial evaluation of Optical Ball Lenses development 17 June 2026 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone. Source - 6 February 2026 Published
SIA disclosed 2025 global chip sales, providing an upstream semiconductor production backdrop. As laser and detector manufacturers expand device integration, precision micro-optic buyers seek small lens lots with traceability; broad semiconductor turnover does not represent optical ball-lens demand. The 2027–2036 opportunity in Optical Ball Lenses development 6 February 2026 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics. Source - February 2026 Published
Knight Optical featured ball lenses in its February 2026 product focus, specifying commonly supplied diameters and materials for fiber coupling and endoscopic imaging. The significance is continued standard and custom stocking, with optical alignment and surface finish remaining important differentiators. For Optical Ball Lenses development February 2026 in 2032, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval. Source - 15 October 2025 Published
The International Telecommunication Union estimated six billion worldwide internet users in 2025. Fiber optics investment is an indirect demand driver for coupling micro-optics; the addressable ball-lens opportunity depends on module design choices rather than the aggregate number of internet subscribers. In the Optical Ball Lenses development 15 October 2025 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment. Source - 2018 Published
Knight Optical published a technical guide describing how ball-lens diameter, effective focal length and optical glass index influence fibre coupling. Although older than the 2026 base year, the engineering reference documents long-standing optical design practices and why coupler manufacturers continue to specify lens shape, optical surface precision and substrate performance. The source supports technical context rather than claims of a new 2025 commercial product launch. Source
REPORT SCOPE & SEGMENTATION
| Attribute | Details |
|---|---|
| Study Period | 2021–2036 |
| Base Year | 2026 |
| Estimated Year | 2027 |
| Forecast Period | 2027–2036 |
| Historical Period | 2021–2025 |
| Base Year Market Size | USD 192 million |
| Estimated Year Market Size | USD 205 million |
| Forecast Year Market Size | USD 377 million |
| CAGR | 7.0% |
| Unit | USD million |
| Market Definition | merchant optical ball-lens components and custom spherical lenses sold by optics suppliers, excluding the value of complete cameras, endoscopes, laser modules or telecom network installations |
| By Type | Glass · Fused Silica · Others |
| By Application | Optical Fibers · Optical Sensors · Others |
| By Substrate Index | Standard index · High index · Specialty crystal |
| By Lens Geometry | Full ball · Half-ball · Custom sphere |
| By Region | Five region market segmentation is based on where the final specialized optical equipment is sold, not the location of raw-material fabrication. Asia-PacificChina · Japan · India · South Korea North AmericaUnited States · Canada · Mexico EuropeGermany · United Kingdom · France South AmericaBrazil · Chile · Argentina Middle East & AfricaSaudi Arabia · United Arab Emirates · South Africa |
| Key Companies Profiled | Schott; Union Optic Inc; Doric Lenses; ILLUCO; Tower Optical Corporation; Industrial Technologies; II-VI Incorporated; Swiss Jewel Company; Knight Optical; West Coast Tech Limited; Tecnottica Consonni; Z-Optics; UNI Optics Co; Changchun Sunday Optoelectronics Co; UltiTech Sapphire; Fuzhou Alpha Optics Co; Chengdu Yasi Optoelectronics Co; Shanghai Optics Inc |
| Customization Scope | Supplier, type, application and regional price analysis for optical ball lenses; estimated market shares in 2026 and differentiated growth paths for 2027–2036. |
Frequently Asked Questions
What is the global optical ball lenses market size?
The global optical ball lenses market is valued at USD 192 million in 2026 and is forecast to reach USD 377 million by 2036, with 7.0% CAGR during 2027–2036. The demand boundary is specific to the optical equipment and technology defined here rather than the full revenue of all data-center, media, automotive or electronics systems.
Which geographic region is the largest market?
Asia-Pacific is the leading 2026 regional market with an estimated ~42% of revenue. North America and Europe follow at ~26% and ~22%, respectively. Differences in OEM manufacturing locations and customer purchasing geography can otherwise distort region comparisons. A commercial evaluation of FAQ 2 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Which region has the fastest growth rate?
Asia-Pacific has the highest estimated regional expansion at ~7.4% CAGR through 2036. The rate is linked to equipment deployment, supplier qualification and the technology mix, rather than broad GDP growth alone. The 2027–2036 opportunity in FAQ 3 is linked to deployment timing and customer acceptance, with supplier selection reflecting reliability, supply continuity, interface requirements and actual unit economics.
Which type holds the largest revenue share?
Glass represents an estimated ~46% of the 2026 market. The significance for FAQ 4 is the difference between an experimentally functional optical ball lenses device and an optical product accepted for repeated customer shipments. Buyers need to verify its performance, equipment compatibility and the available delivery chain before treating it as an interchangeable substitute for another optical format.
Which type is projected to expand fastest?
Others carries the strongest estimated type growth at ~7.5% CAGR, from around ~13% of 2026 revenue. The product mix changes as users adopt performance-enhancing configurations, but engineering qualification and lifecycle servicing determine how quickly that potential converts into orders. For FAQ 5 in 2027, the purchase decision depends on explicit equipment compatibility, verifiable component performance and whether the supplier can sustain replacement support throughout the planned service interval.
What is the leading application?
Optical Fibers is the largest application at approximately ~53% of 2026 revenue. For optical ball lenses procurement, optical Fibers buyers evaluate functional optical tolerances and system compatibility for precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. Procurement specifications depend on actual operating conditions; total revenue in the wider user industry is not a direct proxy for the value of optical equipment purchased.
Which application grows fastest?
Optical Sensors is projected to grow at ~7.4% CAGR from approximately ~34% of 2026 revenue. For sensor-head production, certified lens geometries and optical-to-detector alignment must support precision spherical glass, fused-silica and specialty-crystal lenses that collimate or focus light between laser diodes, fibres and optical detectors. Growth is affected by price changes and supplier qualification as well as physical unit demand.
Which companies are included?
The profiled market participants include Schott, Union Optic Inc, Doric Lenses, ILLUCO, Tower Optical Corporation, Industrial Technologies. These companies may operate in different parts of the value chain and in some cases retain historical naming. Comparisons need to distinguish direct in-scope equipment manufacturing from distribution, materials and wider group revenues. In the FAQ 8 setting, an engineering advantage becomes a sale only after procurement teams review validation evidence, inventory risk, maintenance requirements and the operating economics of the intended deployment.
What restrains adoption?
Micron-scale alignment costs is a notable limitation, alongside alternative grin and aspheric lenses. Customers must also examine service cost, quality-control requirements and purchasing terms. Technical improvement will not necessarily produce corresponding annual revenue growth without reproducible production and access to qualified buyers. This matters for FAQ 9, because the technically feasible option must also be installable, serviceable and properly documented across the operating life of the equipment and its supporting software.
What is the study period and segmentation scope?
The base year is 2026, the estimated year is 2027, and the forecast runs through 2036 with historical context from 2021–2025. Segmentation by type covers Glass, Fused Silica, Others and by application covers Optical Fibers, Optical Sensors, Others. Five geographic regions are included. A commercial evaluation of FAQ 10 therefore compares the cost of qualified materials, process yield, lead times, quality assurance and post-installation support rather than product specifications alone.
Research Sources & Evidence Base
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF