Key Statistics
Key Takeaways
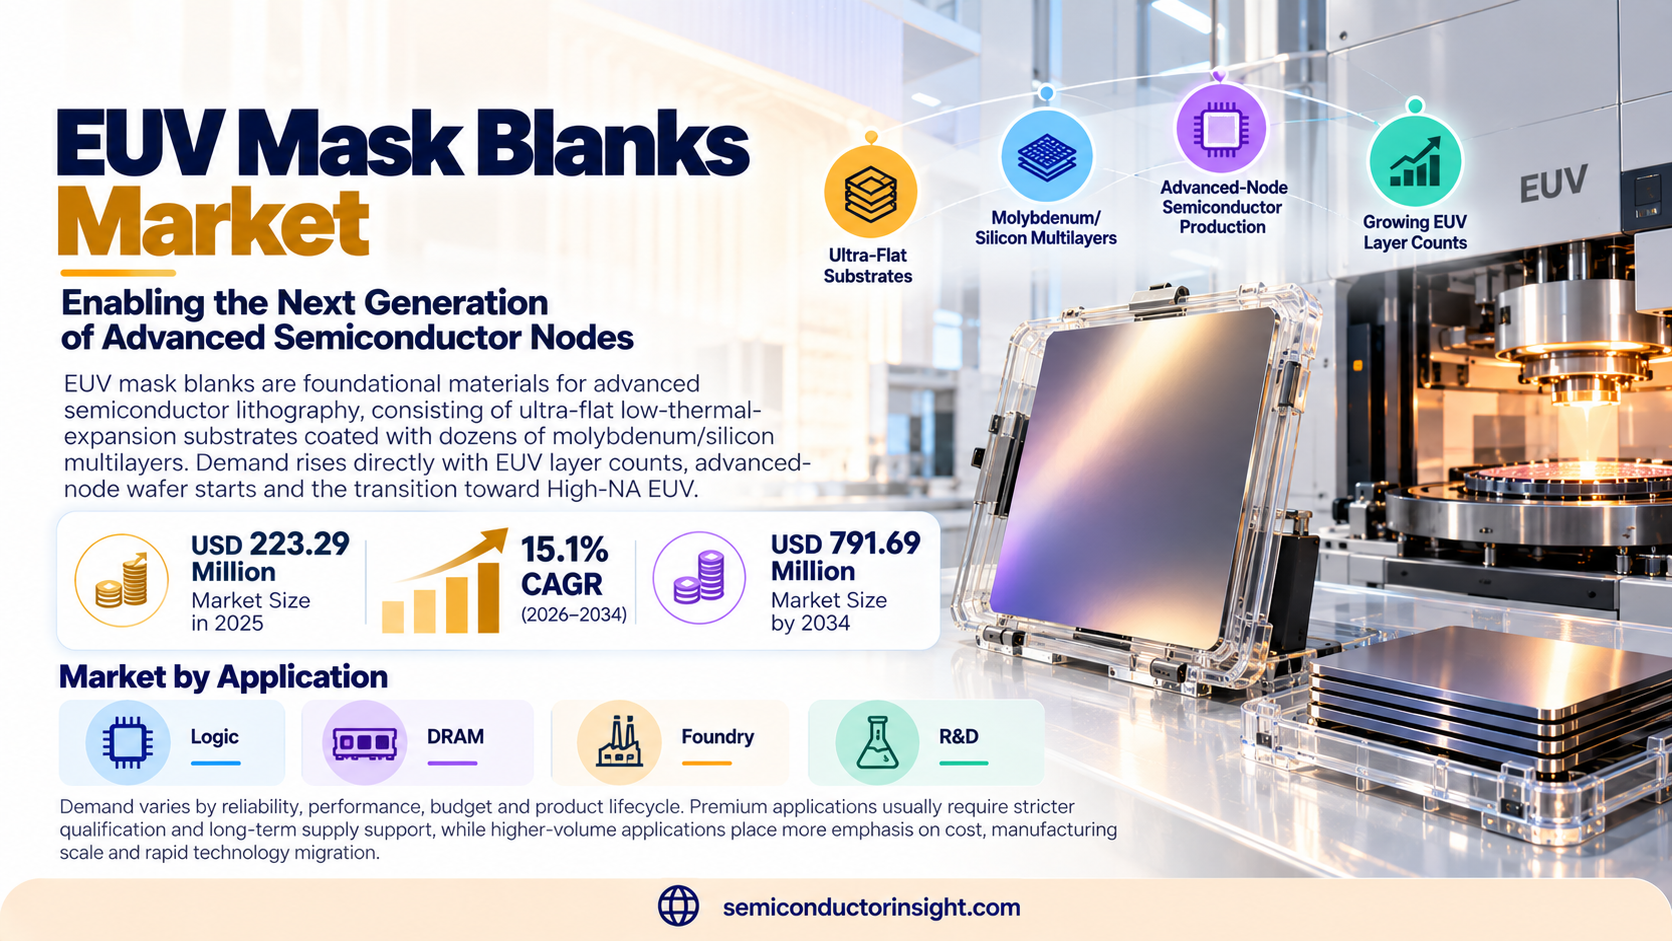
- Market size: The market is valued at USD 223.29 million in 2025 and is projected to reach USD 791.69 million by 2034, representing a 15.1% CAGR during 2026–2034.
- Low-Defect Standard Blanks is a leading segment, reflecting established use across major applications.
- Asia Pacific leads the market, while Asia Pacific provides the strongest growth profile.
- Logic is a major application, supported by rising performance and reliability requirements.
- High-NA EUV readiness, lower defectivity and tighter multilayer uniformity is becoming a central competitive differentiator as customers seek higher performance and lower system-level cost.
EUV Mask Blanks Market Overview
EUV mask blanks market is valued at USD 223.29 million in 2025 and is projected to reach USD 791.69 million by 2034, expanding at a 15.1% CAGR during 2026–2034. The 2026 market level is USD 257.01 million. EUV mask blanks are foundational materials for advanced semiconductor lithography, consisting of ultra-flat low-thermal-expansion substrates coated with dozens of molybdenum/silicon multilayers. Demand rises directly with EUV layer counts, advanced-node wafer starts and the transition toward High-NA EUV.
Supplier concentration is unusually high because blank manufacturing requires extreme defect control, multilayer uniformity and specialized metrology. The underlying evidence indicates AGC and Hoya together hold about 93% share, with AGC alone above 59%, creating significant strategic dependence on a small supplier base. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
High-NA EUV raises requirements for substrate flatness, multilayer reflectivity, defect inspection and absorber-stack compatibility. This increases value per blank while also lengthening qualification cycles and raising capital intensity for suppliers entering the market. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Segment Analysis: By Type
By type, the market is segmented into Low-Defect Standard Blanks, Advanced Low-Defect Blanks, High-NA EUV Blanks. Product selection depends on performance, cost, manufacturing complexity and the target system architecture. Higher-value variants generally offer tighter tolerances, greater integration or improved reliability, while mainstream categories retain volume leadership because of lower cost and broad compatibility.
| Type | Commercial role |
|---|---|
| Low-Defect Standard Blanks | Low-Defect Standard Blanks addresses a distinct requirement set within the EUV Mask Blanks market, with purchasing decisions shaped by performance, qualification, integration and cost. |
| Advanced Low-Defect Blanks | Advanced Low-Defect Blanks addresses a distinct requirement set within the EUV Mask Blanks market, with purchasing decisions shaped by performance, qualification, integration and cost. |
| High-NA EUV Blanks | High-NA EUV Blanks addresses a distinct requirement set within the EUV Mask Blanks market, with purchasing decisions shaped by performance, qualification, integration and cost. |
Additional Segmentation: By Substrate
Substrate segmentation highlights important technical and commercial differences inside the EUV Mask Blanks market. These categories affect pricing, qualification, process requirements and customer fit, making them useful for evaluating where value growth differs from simple unit growth. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Substrate | Demand characteristics |
|---|---|
| LTEM Glass | Commercial low-thermal-expansion substrate for EUV multilayer masks. |
| Quartz / Other Research Substrates | Development platforms for next-generation mask materials and metrology. |
Segment Analysis: By Application
By application, the market covers Logic, DRAM, Foundry, R&D. Demand varies by reliability, performance, budget and product lifecycle. Premium applications usually require stricter qualification and long-term supply support, while higher-volume applications place more emphasis on cost, manufacturing scale and rapid technology migration. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Application | Demand characteristics |
|---|---|
| Logic | Logic is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| DRAM | DRAM is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| Foundry | Foundry is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
| R&D | R&D is a material demand segment where reliability, cost and system performance influence purchasing decisions. |
Additional Segmentation: By End User
End User segmentation clarifies how system architecture and customer requirements reshape product selection. Growth is strongest where the technology delivers a clear performance, cost, reliability or integration advantage relative to incumbent solutions. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| End User | Commercial role |
|---|---|
| Foundries | Leading-edge logic fabs consuming EUV masks at advanced nodes. |
| IDMs | Logic and memory manufacturers with internal mask demand. |
| Mask Shops | Specialized photomask producers serving advanced semiconductor customers. |
| Research Institutes | High-NA EUV and next-generation mask development. |
Regional Analysis
Asia Pacific accounts for about 73% of global demand in the source evidence because leading-edge foundry and memory production is concentrated in Taiwan, South Korea and Japan. North America remains strategically important through advanced logic development and EUV ecosystem investment. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Why does regional demand differ across the EUV Mask Blanks market?
Regional demand mirrors EUV scanner deployment and advanced-node semiconductor capacity. Asia Pacific leads consumption, North America is expanding domestic leading-edge capacity, and Europe is critical through the lithography-tool ecosystem and research base. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
How does Asia Pacific participate in the EUV Mask Blanks market?
Asia Pacific demand is anchored by manufacturing scale, electronics production and growing investment in advanced infrastructure. China, Japan, South Korea, Taiwan and India contribute different mixes of production, end-market demand and technical capability, making the region central to both volume growth and supply-chain development. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
How does North America participate in the EUV Mask Blanks market?
North America remains a high-value market with strong technology development, enterprise spending and specialized industrial demand. The United States is the principal contributor, supported by leading technology companies, research institutions and high-value end markets that adopt premium solutions early. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
How does Europe participate in the EUV Mask Blanks market?
Europe combines advanced manufacturing, healthcare, aerospace, automotive and research demand. Germany, France, the United Kingdom, Italy and other markets emphasize reliability, energy efficiency and regulatory compliance, supporting demand for technically differentiated products with strong lifecycle support. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
How does South America participate in the EUV Mask Blanks market?
South America is a smaller but developing market led by Brazil and selected industrial economies. Demand is concentrated in infrastructure, healthcare, electronics, research and industrial modernization, with import dependence making distributor support, service coverage and pricing important commercial factors. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
How does Middle East & Africa participate in the EUV Mask Blanks market?
Middle East & Africa remains an emerging market where demand is concentrated in infrastructure, healthcare, energy, defense and research projects. Gulf countries account for much of the premium investment, while wider adoption depends on local technical capability, procurement cycles and access to qualified suppliers. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Competitive Landscape
The competitive landscape includes AGC, Hoya, S&S Tech, Applied Materials, Photronics and advanced photomask ecosystem suppliers. Market position is shaped by technical performance, qualification depth, customer support, manufacturing scale and the ability to support product transitions without disrupting customer operations. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Competition is increasingly centered on High-NA EUV readiness, lower defectivity and tighter multilayer uniformity. Larger suppliers benefit from global engineering resources and purchasing scale, while specialized vendors can defend attractive niches through process expertise, customization and faster technical support. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Competitive dimension | What matters |
|---|---|
| Technology | Performance, reliability and roadmap credibility. |
| Qualification | Customer validation, compliance and field history. |
| Supply | Capacity, lead time and regional resilience. |
| Commercial support | Application engineering, service and lifecycle support. |
Production Capacity Analysis
Capacity strategy in the EUV Mask Blanks market is closely linked to demand visibility, qualification cycles and customer concentration. Suppliers add capacity carefully because advanced production often requires specialized equipment, process know-how and extended validation before new lines can serve demanding applications. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Regional capacity decisions increasingly balance cost with resilience. Customers are asking suppliers to diversify critical steps, maintain qualified backup capacity and support shorter lead times. That trend favors manufacturers able to combine scale with consistent process control and regional technical support. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Dynamics
The EUV Mask Blanks market is shaped by simultaneous changes in end-market demand, product architecture, manufacturing economics and qualification requirements. Technology improvements create new use cases, but commercialization depends on whether performance gains translate into measurable system value. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Supply-chain conditions also influence purchasing behavior. Customers increasingly evaluate continuity, regional sourcing and lifecycle support alongside unit price. This shifts competition toward suppliers that can deliver stable quality and technical service through multiple product generations. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Market Drivers
Growth is driven by rising EUV layer counts, 2nm-class logic, DRAM scaling and High-NA EUV adoption. Each new advanced-node generation increases the strategic value of defect-free masks and raises blank performance requirements. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Driver | CAGR impact |
|---|---|
| Technology upgrade cycle | +1.8 percentage points |
| End-market expansion | +1.3 percentage points |
| Higher content per system | +0.9 percentage points |
Market Restraints
Market expansion is constrained by very high barriers to entry, long customer qualification, complex multilayer deposition and stringent defect standards. A single printable defect can invalidate an expensive mask, making yield and inspection capability central to economics. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Restraint | CAGR impact |
|---|---|
| Qualification and replacement cost | -0.8 percentage points |
| Price pressure | -0.6 percentage points |
| Supply or integration complexity | -0.5 percentage points |
Market Opportunities
Opportunities are strongest in High-NA EUV blanks, advanced defect inspection, new absorber stacks and domestic supply-chain localization. Suppliers that achieve lower defectivity and stable high-volume production can capture premium pricing. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Opportunity | Commercial significance |
|---|---|
| High-NA EUV readiness, lower defectivity and tighter multilayer uniformity | Supports premium product mix and new design wins. |
| Regional capacity | Improves lead times and customer resilience. |
| Application engineering | Raises switching costs and deepens customer relationships. |
Supply Chain Analysis
The EUV Mask Blanks supply chain spans upstream materials and components, specialized manufacturing, qualification and integration, distribution or direct sales, and end-use deployment. Value is not distributed evenly: the highest margins generally accrue where process know-how, IP, qualification or application engineering create defensible differentiation. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Stage | Role |
|---|---|
| Upstream inputs | Materials, components, software or specialized process equipment. |
| Manufacturing | Core fabrication, assembly and process control. |
| Qualification & integration | Validation, reliability testing and customer-specific adaptation. |
| End-market deployment | System integration, service and lifecycle support. |
Supply continuity has become strategically important because qualified alternatives may require lengthy validation. Buyers therefore monitor second-source readiness, geographic concentration and supplier financial stability, especially where a single component can delay a high-value system. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
Recent Developments in the EUV Mask Blanks Market
Report Scope & Segmentation
This analysis covers the EUV Mask Blanks market from a 2025 base year through the 2026–2034 forecast period. It evaluates demand by product type, application and two additional segmentation axes, with regional coverage spanning Asia Pacific, North America, Europe, South America, and the Middle East & Africa. Commercial decisions in the EUV Mask Blanks market depend on qualification history, integration effort, operating reliability, lifecycle support and measurable system-level value.
| Scope item | Coverage |
|---|---|
| Base year | 2025 |
| Estimated year | 2026 |
| Forecast period | 2026–2034 |
| By Type | Low-Defect Standard Blanks, Advanced Low-Defect Blanks, High-NA EUV Blanks |
| By Application | Logic, DRAM, Foundry, R&D |
| By Substrate | LTEM Glass, Quartz / Other Research Substrates |
| By End User | Foundries, IDMs, Mask Shops, Research Institutes |
| Key participants | AGC, Hoya, S&S Tech, Applied Materials, Photronics and advanced photomask ecosystem suppliers |
Frequently Asked Questions
What is the EUV Mask Blanks market size in 2025?
The market is valued at USD 223.29 million in 2025.
What is the market forecast for 2034?
The market is projected to reach USD 791.69 million by 2034, with a 15.1% CAGR during 2026–2034.
Which region leads the market?
Asia Pacific leads current market value, while Asia Pacific has the strongest growth profile.
Which type is most important?
Low-Defect Standard Blanks is a leading category, although mix varies by application and performance requirement.
Which applications matter most?
Logic is a major demand segment, alongside DRAM, Foundry.
What technology trend matters most?
High-NA EUV readiness, lower defectivity and tighter multilayer uniformity is a central technology and commercialization trend.
Who are the major suppliers?
Major participants include AGC, Hoya, S&S Tech, Applied Materials, Photronics and advanced photomask ecosystem suppliers.
What drives market growth?
Growth is driven by rising EUV layer counts, 2nm-class logic, DRAM scaling and High-NA EUV adoption. Each new advanced-node generation increases the strategic value of defect-free masks and raises blank performance requi
What limits growth?
Market expansion is constrained by very high barriers to entry, long customer qualification, complex multilayer deposition and stringent defect standards. A single printable defect can invalidate an expensive mask, makin
What will shape the market through 2034?
Technology roadmaps, qualification, supply continuity and High-NA EUV readiness, lower defectivity and tighter multilayer uniformity will shape competitive outcomes.
Research Sources & Evidence Base
View selected external research sources
- ASML — EUV Lithography: Current EUV and High-NA lithography context. Open source
- AGC — Photomask Blanks: Current advanced photomask blank context. Open source
- KLA — Reticle Manufacturing: Current EUV mask inspection and metrology context. Open source
Get Sample Report PDF for Exclusive Insights
Report Sample Includes
- Table of Contents
- List of Tables & Figures
- Charts, Research Methodology, and more...
 Download Sample Report PDF